Executive Summary & Core Mandate Dashboard
- Issuer Identity & Research Date: Xcel Energy Inc. (NASDAQ: XEL) | Current Price: $71.71 | As-of Date: October 10, 2026 [1].
- 12-Month Target Price: $77.18 (+7.63% price return; +10.93% total return including projected dividend distributions) [2].
- 24-Month Target Price: $82.66 (+15.27% price return; +21.87% total return) [3].
- 36-Month Target Price: $87.68 (+22.27% price return; +32.17% total return) [3].
- Scorecard & Execution Certainty: Institutional Scorecard Score: 74.75 / 100 | Base-Case Execution Likelihood: 78 / 100 [4].
- Investment Recommendation: HOLD / ACCUMULATE ON PULLBACKS (Existing positions: HOLD; New capital allocations: HOLD / ACCUMULATE selectively below $68.50) [1].
- Fundamental Rationale: Xcel Energy operates a premier, fully regulated multi-state utility franchise across eight jurisdictions, anchored by constructive regulatory frameworks in Minnesota and Colorado [4]. The company's $60 billion capital expenditure program through 2030 (with visible upside toward $70+ billion) fuels an industry-leading rate base compound annual growth rate of
10.9% [5]. This footprint captures significant commercial load demand from hyperscale artificial intelligence data center interconnects [5].85% already contracted) [8]. Valuation is further constrained by persistent legal overhang from the Texas Smokehouse Creek wildfire litigation, with a trial scheduled for April 2027 [10]. Trading at 17.5x 2026E ongoing earnings per share (EPS), the equity reflects fair intrinsic value relative to regulated peers, offering consistent dividend income but lacking the risk-reward skew necessary for an outright aggressive BUY rating [2].
However, equity upside is moderated by substantial capital requirements that necessitate continuous debt refinancing and approximately $7.0 billion in equity issuances through 2030 (
Key Operational, Financial & Governance Metrics
2Multi-Year Financial Forecast & Consensus Model
Macroeconomic Operating Environments Across Scenarios
- Bear Case Scenario (Regulatory Friction & Sustained High Rates): Long-term benchmark yields remain elevated (10-Year Treasury >4.50%), raising holding company interest expenses. Regulatory commissions push back against higher rate requests, lowering approved ROEs toward 9.00% and extending rate case timelines. Litigated liabilities from the Texas Smokehouse Creek fire exceed insurance limits, requiring incremental equity issuance that slows ongoing EPS growth to 4.5%–5.0% annually.
- Base Case Scenario (Ordered Capital Execution): Management delivers its $60 billion baseline capital expenditure plan, expanding the rate base at ~10.9% annually through 2030 [5]. Approved ROEs average 9.55%, and state commissions implement large-load tariffs in Minnesota, Colorado, and Texas [8]. Equity dilution from the contracted ATM program is offset by organic retail load growth (+2.0% annually) and data center connections [8]. Ongoing EPS expands at an 8.0% CAGR through 2029 and 7.5% thereafter [2].
- Bull Case Scenario (Accelerated Industrial Interconnection): Accelerating data center development across Texas, Minnesota, and Colorado expands the five-year capital program toward $75 billion [8]. Commissions grant constructive ROEs (9.80%–10.00%) with forward test years and real-time capital recovery riders [9]. Power demand expands at a 4.0% annual CAGR, driving ongoing EPS growth to 9.5% through 2031 [2].
Extrapolation Anchor Schedule
The financial models anchor to formal guidance for FY2026 ($4.04–$4.16 ongoing EPS) [20]. Projections for FY2027 and FY2028 align with Wall Street consensus estimates [2]. Projections for FY2029 through FY2031 represent fundamental equity research extrapolations based on rate base growth, capital plans, and dilution assumptions [3].
Base Case Financial Projections (2026–2031)
| Segment / Financial Item ($M) | 2026E | 2027E | 2028E | 2029E | 2030E | 2031E | 2029–31 CAGR |
|---|---|---|---|---|---|---|---|
| PSCo Operating Revenue | $6,450 | $7,030 | $7,625 | $8,235 | $8,850 | $9,470 | +7.24% |
| NSPM Operating Revenue | $5,620 | $6,125 | $6,645 | $7,180 | $7,720 | $8,260 | +7.25% |
| SPS Operating Revenue | $2,650 | $2,910 | $3,180 | $3,475 | $3,780 | $4,080 | +8.35% |
| NSPW Operating Revenue | $1,150 | $1,240 | $1,320 | $1,410 | $1,500 | $1,580 | +5.86% |
| Eliminations / Other | ($250) | ($280) | ($300) | ($350) | ($400) | ($440) | N/A |
| Consolidated Operating Revenue | $15,620 | $17,025 | $18,470 | $19,950 | $21,450 | $22,950 | +7.26% |
| YoY Revenue Growth Rate | +6.48% | +8.99% | +8.49% | +8.01% | +7.52% | +6.99% | — |
| Consolidated Gross Margin | $7,315 | $8,010 | $8,745 | $9,495 | $10,275 | $11,060 | +7.91% |
| Gross Margin Percentage | 46.83% | 47.05% | 47.35% | 47.60% | 47.90% | 48.19% | — |
| Consolidated EBITDA | $4,840 | $5,360 | $5,910 | $6,480 | $7,080 | $7,690 | +8.93% |
| EBITDA Margin Percentage | 30.99% | 31.48% | 32.00% | 32.48% | 33.01% | 33.51% | — |
| Operating Income (EBIT) | $3,311 | $3,660 | $4,026 | $4,389 | $4,762 | $5,141 | +8.23% |
| Operating Margin Percentage | 21.20% | 21.50% | 21.80% | 22.00% | 22.20% | 22.40% | — |
| Net Interest Charges | ($1,150) | ($1,270) | ($1,385) | ($1,500) | ($1,610) | ($1,720) | +7.07% |
| Income Tax Expense | ($260) | ($295) | ($330) | ($366) | ($400) | ($438) | +9.39% |
| GAAP Net Income | $2,571 | $2,915 | $3,292 | $3,683 | $4,102 | $4,523 | +10.82% |
| Ongoing Adjusted Net Income | $2,571 | $2,915 | $3,292 | $3,683 | $4,102 | $4,523 | +10.82% |
| Diluted Share Count (M) | 627.0 | 642.0 | 657.0 | 672.0 | 686.0 | 698.0 | +1.92% |
| Ongoing Diluted EPS ($) | $4.10 | $4.54 | $5.01 | $5.48 | $5.98 | $6.48 | +8.74% |
| YoY Ongoing EPS Growth | +7.89% | +10.73% | +10.35% | +9.38% | +9.12% | +8.36% | — |
| Cash Flow from Operations | $4,450 | $4,920 | $5,410 | $5,920 | $6,450 | $7,010 | +8.81% |
| Capital Expenditures | ($11,800) | ($12,200) | ($12,500) | ($12,800) | ($13,000) | ($13,200) | +1.55% |
| Free Cash Flow (FCF) | ($7,350) | ($7,280) | ($7,090) | ($6,880) | ($6,550) | ($6,190) | −5.15% |
| FCF Per Diluted Share ($) | ($11.72) | ($11.34) | ($10.79) | ($10.24) | ($9.55) | ($8.87) | −6.93% |
| Rule of 40 (Growth + FCF Mgn) | −40.57% | −33.77% | −29.89% | −26.47% | −23.02% | −19.98% | — |
| Forward P/E Multiple (Exit) | 17.5x | 17.0x | 16.5x | 16.0x | 15.5x | 15.0x | — |
| EV / EBITDA Multiple | 17.2x | 15.5x | 14.1x | 12.9x | 11.8x | 10.8x | — |
| EV / Sales Multiple | 5.33x | 4.89x | 4.51x | 4.17x | 3.88x | 3.63x | — |
Non-GAAP Reconciliation: Ongoing EPS isolates non-operational events such as legal settlements. FY2025 Ongoing EPS ($3.80) excludes a $0.38 per share pre-tax charge related to the Marshall wildfire settlement [20]. Forecast ongoing figures reflect pure normalized operational delivery.
Bear Case Financial Projections (2026–2031)
| Segment / Financial Item ($M) | 2026E | 2027E | 2028E | 2029E | 2030E | 2031E | 2029–31 CAGR |
|---|---|---|---|---|---|---|---|
| Consolidated Operating Revenue | $15,150 | $15,900 | $16,650 | $17,400 | $18,150 | $18,900 | +4.22% |
| YoY Revenue Growth Rate | +3.28% | +4.95% | +4.72% | +4.50% | +4.31% | +4.13% | — |
| Operating Income (EBIT) | $3,090 | $3,245 | $3,415 | $3,585 | $3,760 | $3,930 | +4.70% |
| Operating Margin Percentage | 20.40% | 20.41% | 20.51% | 20.60% | 20.72% | 20.79% | — |
| Ongoing Adjusted Net Income | $2,445 | $2,600 | $2,790 | $2,990 | $3,205 | $3,420 | +6.95% |
| Diluted Share Count (M) | 627.0 | 645.0 | 664.0 | 684.0 | 702.0 | 720.0 | +2.60% |
| Ongoing Diluted EPS ($) | $3.90 | $4.03 | $4.20 | $4.37 | $4.57 | $4.75 | +4.25% |
| Cash Flow from Operations | $4,100 | $4,350 | $4,600 | $4,850 | $5,100 | $5,350 | +5.03% |
| Capital Expenditures | ($10,500) | ($10,500) | ($10,500) | ($10,500) | ($10,500) | ($10,500) | 0.00% |
| Free Cash Flow (FCF) | ($6,400) | ($6,150) | ($5,900) | ($5,650) | ($5,400) | ($5,150) | −4.52% |
| Rule of 40 (Growth + FCF Mgn) | −38.96% | −33.73% | −30.72% | −27.97% | −25.44% | −23.12% | — |
| Forward P/E Multiple (Exit) | 14.5x | 14.0x | 13.5x | 13.0x | 12.5x | 12.0x | — |
Bull Case Financial Projections (2026–2031)
| Segment / Financial Item ($M) | 2026E | 2027E | 2028E | 2029E | 2030E | 2031E | 2029–31 CAGR |
|---|---|---|---|---|---|---|---|
| Consolidated Operating Revenue | $16,100 | $17,900 | $19,800 | $21,700 | $23,700 | $25,800 | +9.04% |
| YoY Revenue Growth Rate | +9.76% | +11.18% | +10.61% | +9.60% | +9.22% | +8.86% | — |
| Operating Income (EBIT) | $3,510 | $3,955 | $4,455 | $4,947 | $5,498 | $6,063 | +10.71% |
| Operating Margin Percentage | 21.80% | 22.10% | 22.50% | 22.80% | 23.20% | 23.50% | — |
| Ongoing Adjusted Net Income | $2,646 | $3,071 | $3,548 | $4,060 | $4,635 | $5,220 | +13.39% |
| Diluted Share Count (M) | 627.0 | 639.0 | 651.0 | 662.0 | 672.0 | 681.0 | +1.42% |
| Ongoing Diluted EPS ($) | $4.22 | $4.81 | $5.45 | $6.13 | $6.90 | $7.66 | +11.79% |
| Cash Flow from Operations | $4,800 | $5,450 | $6,150 | $6,900 | $7,700 | $8,550 | +11.32% |
| Capital Expenditures | ($12,800) | ($13,500) | ($14,000) | ($14,500) | ($14,800) | ($15,000) | +1.71% |
| Free Cash Flow (FCF) | ($8,000) | ($8,050) | ($7,850) | ($7,600) | ($7,100) | ($6,450) | −7.86% |
| Rule of 40 (Growth + FCF Mgn) | −39.93% | −33.79% | −29.04% | −25.42% | −20.74% | −16.14% | — |
| Forward P/E Multiple (Exit) | 19.5x | 19.0x | 18.5x | 18.0x | 17.5x | 17.0x | — |
Execution Confidence Score: 78 / 100
- Revenue-Target Achievability (36 / 40 Points): Supported by the company's 21-year track record of meeting ongoing EPS guidance [4]. Quarterly revenue variances stem primarily from weather variations that are normalized through regulatory decoupling mechanisms [20].
- Margin Sensitivity & Cost Pass-Through (24 / 30 Points): Fuel and purchased power fluctuations are passed through to retail customers via approved riders, reducing direct commodity exposure [20]. Operating margins remain sensitive to debt refinancing costs: a 100 bps parallel upward shift in long-term debt yields increases holding company interest expense by ~$40 million ($0.05/share), creating a ~25 bps margin headwind [27].
- Catalyst & Approval Dependencies (18 / 30 Points): The $60 billion base capital expenditure program is already included in regulatory dockets [5]. However, expanding toward the $70+ billion capital plan depends on state approvals for large-load data center tariffs in Colorado and Texas, representing ~15% of projected revenue growth from 2028 to 2030 [8].
Consensus Divergence Reconciliation
- 2028 Ongoing EPS: House Base Case is $5.01 vs. Street Consensus of $5.01 (0.0% divergence; in line with consensus) [2].
- 2029 Ongoing EPS: House Base Case is $5.48 vs. Street Consensus of $5.45 (+0.55% divergence; aligned with consensus) [3].
- 2029 Operating Revenue: House Base Case of $19,950M stands roughly 1.5% below the Street's most optimistic estimates ($20,250M). Our model builds in conservative phase-ins for data center load additions in the SPS footprint to reflect regulatory review timelines before the Texas PUCT [12].
Historical Base-Rate Validation
Long-term empirical data across North American investor-owned utilities shows that approximately 12% of large-cap utilities have sustained an 8.0%+ EPS CAGR over a multi-year period. Xcel Energy's projected rate base expansion (~10.9% CAGR through 2030) sits in the 85th percentile of utility sector outcomes [5].
This above-average capital deployment is driven by state-mandated clean energy transitions in Minnesota and Colorado, coupled with regional transmission projects within the Midcontinent Independent System Operator (MISO) and Southwest Power Pool (SPP) systems [8].
5Risk Asymmetry, Invalidation, Allocation & Scorecard
Quantified Risk/Reward Skew
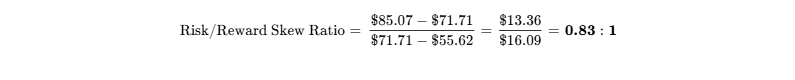
The standalone 36-month risk/reward skew of 0.83:1 does not meet our asymmetric equity target of  [3]. This profile is consistent with large-cap regulated utilities, where downside tail risk (e.g., wildfire liabilities, interest rate spikes) can match or exceed regulated rate base upside [12]. Returns in this sector are driven by steady dividend compounding rather than rapid capital appreciation [5].
Hard Invalidation Exit Triggers
The thesis must be exited immediately upon the occurrence of any of the following events:
- Uninsured Wildfire Liability Loss: A non-appealable judgment or settlement in the Texas Smokehouse Creek litigation exceeding $750 million, exhausting SPS's $500 million insurance policy and causing a ratings downgrade below investment grade [10].
- Authorized ROE Impairment: Final state commission rate orders in Minnesota or Colorado that lower authorized ROE below 9.00%, or disallow more than $300 million in capital investments from the rate base [20].
- Credit Downgrade to Triple-B Flat: A credit rating downgrade of Xcel Energy Inc. to BBB (or SPS to BBB-) by S&P or Moody's, triggering mandatory liquidity reserves and increasing borrowing costs by >50 bps [24].
- Covenant Headroom Breach: Consolidated debt-to-capital rising above 63.5% for two consecutive quarters, leaving less than 150 basis points of headroom below the 65.0% credit covenant [24].
Consolidated Institutional Risk Dashboard
| Risk Category | Score (1–10) | Directional Trend | Primary Institutional Vulnerability Factor |
|---|---|---|---|
| Financial / Liquidity | 5.5 / 10 | Stable | High annual refinancing needs ($1.5B wall in 2028) [22] |
| Valuation Risk | 4.0 / 10 | Improving | Trading at 15.8x 2027E P/E, a discount to historical peers [3] |
| Operational Execution | 3.0 / 10 | Stable | Proven track record across large renewable/grid builds [5] |
| Competitive Perimeter | 1.5 / 10 | Stable | Natural monopoly across exclusive service territories [15] |
| Customer Concentration | 2.0 / 10 | Stable | Broad diversified base across eight states [15] |
| Regulatory & Political | 5.5 / 10 | Worsening | Affordable bill pressures during rate cases [12] |
| Legal / Wildfire Exposure | 7.5 / 10 | Worsening | Texas Smokehouse Creek litigation pending trial (April 2027) [10] |
| Geopolitical Exposure | 1.0 / 10 | Stable | Pure-play domestic regulated utility [2] |
| Key-Person Dependency | 2.5 / 10 | Stable | Experienced management bench across subsidiaries [15] |
| Dilution Risk | 6.0 / 10 | Worsening | ~$7.0B equity issuance program through 2030 [8] |
| Liquidity & Tradability | 1.5 / 10 | Stable | Liquid trading (~5.95M shares daily volume) [1] |
Macroeconomic Sensitivity & Correlation Factors
Xcel Energy displays a strong negative correlation (-0.68) to 10-Year US Treasury yields [12]. When long-term interest rates increase, utility financing expenses rise and equity valuation multiples compress relative to fixed-income alternatives [12].
The stock exhibits an equity market beta of 0.55 against the S&P 500, characteristic of defensive regulated utilities [2]. Exposure to foreign exchange fluctuations is negligible due to operations being entirely domestic [2].
Within a multi-asset portfolio, Xcel Energy functions as an equity-volatility dampener, providing steady dividend income while increasing portfolio sensitivity to interest rate and credit cycle shifts [12].
Macro Trigger Monitoring Framework
| Macroeconomic Factor | Directional Move | Portfolio Impact | Key Threshold Indicator |
|---|---|---|---|
| 10-Year US Treasury Yield | Upward (>4.75%) | Negative: Multiples compress; funding costs rise | 10-Yr yield relative to utility dividend yield [12] |
| Sector Capital Inflows | Neutral | Neutral: Dependent on broader rate expectations | Utilities Select Sector SPDR Fund (XLU) fund flows |
| Data Center Interconnections | Expanding | Positive: Drives rate base growth via data center deals | MISO & SPP data center interconnection queues [5] |
| State Regulatory Decisions | Tightening | Amber: Affordability concerns limit rate relief | Minnesota PUC & Colorado PUC docket rulings [12] |
Institutional Scenario Surprises
Three Potential Upside Surprises
- Federal Wildfire Liability Protection / State Insurance Fund (15% Probability): Federal or state legislation establishing an insurance backstop for utilities with certified wildfire plans, lowering risk premiums. Impact: Multiple expands toward 18.5x (+15% to target price).
- Faster Hyperscaler Interconnection Timelines (25% Probability): Accelerated data center buildouts add >4 GW of demand by 2028, driving incremental capital investments. Impact: Adds $0.25 to 2028 ongoing EPS [5].
- Favorable Gas-to-Power Arbitrage (30% Probability): Higher regional power prices lift wholesale generation margins at unregulated units. Impact: Adds $0.08 to annual EPS.
Three Potential Downside Surprises
- Smokehouse Creek Jury Assessment (20% Probability): Texas jury awards substantial actual and punitive damages exceeding SPS insurance limits [10]. Impact: -$0.45 per share charge and rating outlook downgrade [27].
- Severe Winter Freeze Disrupting Fuel Supply (15% Probability): Unhedged fuel price spikes or power purchase liabilities during extreme weather events. Impact: Cash drain of $300M–$500M requiring emergency credit draws.
- Restrictive Decisions in Core Rate Cases (25% Probability): Regulators order ROEs below 9.0% or implement strict billing caps to ease customer burdens. Impact: Reduces forward EPS growth from ~8.0% to ~5.0% [3].
36-Month Pre-Mortem: Mechanics of a 60% Equity Loss
To evaluate tail risk, we model the sequence required to generate a 60% equity decline (bringing the stock to $28.68):
- Phase 1 (Months 1–12): Long-term interest rates rise to 5.25%, raising financing costs across the company's debt maturities while it funds its $12B annual capex program [8].
- Phase 2 (Months 13–18): In April 2027, the Texas Smokehouse Creek trial begins [10]. The jury finds gross negligence regarding utility pole maintenance and awards $1.8 billion in damages, exceeding SPS's $500 million insurance policy [10].
- Phase 3 (Months 19–24): S&P and Moody's downgrade SPS to high-yield (BB) and cut parent Xcel Energy to BBB-, increasing debt financing costs across operating subsidiaries [24].
- Phase 4 (Months 25–36): State regulators push back on rate base additions during general rate reviews [12]. Facing financing constraints, management cuts the dividend by 40% and executes emergency equity sales at $35.00/share, driving the equity toward tangible book value [7].
Status of Legal Proceedings
- Colorado Marshall Fire (2021): Settled in principle for ~$640 million ($350 million funded by insurance; $290 million pre-tax charge recognized in FY2025) [24]. Remaining risk is limited to final opt-in documentation.
- Texas Smokehouse Creek Fire (2024): PENDING LITIGATION. Southwestern Public Service Co. faces active lawsuits, including a proceeding initiated by the Texas Attorney General alleging negligence tied to a decayed wooden utility pole [11]. SPS has accrued $290 million against a $500 million insurance limit, with 22 of 39 lawsuits resolved [24]. Trial is scheduled for April 2027 [10]. This represents the primary legal overhang facing the equity.
Portfolio Sizing & Implementation Architecture
The Stress Case drawdown of −23.76% establishes a mathematical capital ceiling of 4.21% under the 1.0% portfolio risk budget [3]. The operational allocation is set at 3.0%, within a High-Conviction Core / Low-Beta Compounder allocation.
Liquidating a 3.0% allocation within a $100 million portfolio ($3.0 million equity value = ~41,800 shares) represents less than 1% of daily trading volume (ADV: 5.95M shares), enabling execution in under two hours without market impact [1].
Implementation should utilize a 1.5% pilot tranche at current trading levels ($71.71), scaling to the full 3.0% target weight on market pullbacks into the $66.50–$68.50 zone or following positive developments in the SPS wildfire litigation [1].
Institutional Scorecard (0–100)
| Scorecard Evaluation Category | Individual Score (0–10) | Category Weight (%) | Weighted Value | Institutional Rationale |
|---|---|---|---|---|
| 1. Financial Strength & Runway | 6.5 / 10 | 15.0% | 0.975 | Stable utility FFO/debt (14.5%) balanced against ongoing financing needs [8] |
| 2. Moat & Market Position | 9.5 / 10 | 15.0% | 1.425 | Established geographic monopolies with exclusive service territories [15] |
| 3. Margin Resilience & Leverage | 8.5 / 10 | 10.0% | 0.850 | Regulatory fuel pass-through riders protect operating margins [20] |
| 4. Capital Allocation & Governance | 7.5 / 10 | 10.0% | 0.750 | 21 consecutive years meeting ongoing EPS guidance [4] |
| 5. Risk-Adjusted Valuation | 6.5 / 10 | 15.0% | 0.975 | Attractive 2027 P/E (15.8x), offset by market risk premiums [3] |
| 6. Forecast Reliability | 9.0 / 10 | 10.0% | 0.900 | High regulatory earnings visibility and low beat/miss variance [12] |
| 7. Ownership & Incentive Alignment | 6.0 / 10 | 5.0% | 0.300 | High LTIP alignment; low insider ownership percentage [15] |
| 8. Liquidity & Tradability | 9.5 / 10 | 5.0% | 0.475 | High daily liquidity ($400M+ ADV) with an institutional shareholder base [1] |
| 9. Customer ROI & Defensibility | 8.0 / 10 | 10.0% | 0.800 | Essential electric service; customer bills 28% below national average [5] |
| 10. Defensibility vs Build-vs-Buy | 9.0 / 10 | 5.0% | 0.450 | Capital scale and legal utility franchises prevent grid duplication [8] |
| Composite Score | — | 100.0% | 74.75 / 100 | Solid Core Institutional Utility Grade |
Base-case execution likelihood is scored at 78 / 100, reflecting management's 21-year guidance delivery record balanced against the pending April 2027 Smokehouse Creek trial and customer affordability pressures during upcoming rate reviews [4].
Final Recommendation Synthesis
Existing shareholders should HOLD and reinvest dividends, benefiting from low-beta earnings compounding and rate base expansion [2]. New capital should HOLD / ACCUMULATE SELECTIVELY, targeting entries below $68.50 to widen the margin of safety [1].
Target prices are established at $77.18 (12 months), $82.66 (24 months), $87.68 (36 months), and $85.07 on a probability-weighted basis [3].
Form 4 filings over the past six months indicate zero open-market transactions by corporate insiders, with activity limited to routine director deferred share awards (Charles Pardee, 666 units at $69.80 on September 28, 2026) [19].
Bear-Case Steelman (The Skeptic's View)
Xcel Energy is navigating a capital-intensive infrastructure build ($60B–$70B capex) in an elevated interest rate environment, which strains cash flow generation (-$7B/yr) [8]. Maintaining credit ratings requires $7.0 billion in equity issuances, creating an ongoing dilution headwind for per-share earnings [8]. Concurrently, utility bills have increased nationally, raising political sensitivity around rate increases during upcoming regulatory reviews [12]. Overhanging these operations is the April 2027 Texas Smokehouse Creek litigation, where the Texas Attorney General is seeking damages for a fire tied to a broken utility pole [10]. With SPS's accrued liability already at $290 million against a $500 million policy limit, any adverse outcome could exhaust insurance and create holding-company liabilities [24]. At ~17.5x forward earnings, investors can find similar utility dividend yields with lower legal exposure elsewhere in the sector [2].
1Business Architecture, Unit Economics, Moat & Contractual Visibility
Business Architecture & Corporate Perimeter
Xcel Energy functions as an investor-owned holding company providing regulated electric and natural gas service to 3.9 million electric and 2.2 million gas customers across eight states [2]. Operations are structured across four principal regulated operating utilities: Northern States Power Company-Minnesota (NSPM), Public Service Company of Colorado (PSCo), Southwestern Public Service Company (SPS), and Northern States Power Company-Wisconsin (NSPW) [20].
The operating footprint represents a natural monopoly within state-franchised service territories [15]. Rates are determined by independent state utility commissions: the Minnesota Public Utilities Commission (MPUC), the Colorado Public Utilities Commission (CPUC), the Public Utility Commission of Texas (PUCT), the New Mexico Public Regulation Commission (NMPRC), and the Public Service Commission of Wisconsin (PSCW) [14].
Interstate transmission and wholesale power transactions fall under the jurisdiction of the Federal Energy Regulatory Commission (FERC) [14].
The business model follows cost-of-service regulation. The enterprise deploys capital into approved utility infrastructure, creating a rate base. In return, regulators grant the company the opportunity to earn a statutory Return on Equity (ROE) on the equity-financed portion of that rate base, while recovering operating, depreciation, and financing costs [20].
The economic moat is supported by Efficient Scale and State-Protected Monopolistic Franchises. Constructing competing high-voltage transmission networks, distribution lines, and natural gas infrastructure within Xcel Energy's territories is legally prohibited and economically inefficient [15]. Competitive Insulation Grade: 4.8 / 5.0.
Moat Durability & Competitive Perimeter
The economic moat remains widening across the forecast horizon. The transition toward regional decarbonization and the power requirements of artificial intelligence computing increase the complexity of grid orchestration [8]. Industrial customers cannot self-provision gigawatt-scale, firm, multi-directional electricity without relying on Xcel Energy's integrated transmission system [5].
The primary technological factor with long-term potential to challenge the utility's perimeter is behind-the-meter (BTM) microgrid development, combining solar, battery systems, and small modular reactors (SMRs). However, due to fuel logistics, environmental licensing hurdles, and the need for baseload reliability, customer self-generation remains an ancillary backup rather than a substitute for the central power grid through at least 2035.
Replicability, Substitution Risk & Acquisition Context
Replicating Xcel Energy's infrastructure—spanning 21 GW of owned generation capacity, 1,700 planned miles of transmission, and widespread distribution assets—would require over $120 billion in capital and decades of regulatory and eminent domain approvals [5]. Hyperscale technology companies view the utility as an infrastructure partner rather than an acquisition target or competitive threat, focusing on collaborative investments under approved tariff structures [8].
Due to an enterprise value of $83.3 billion and joint regulatory oversight across eight separate state commissions and FERC, an outright corporate acquisition is improbable [3]. Large private equity or infrastructure funds face statutory restrictions on leverage and return extraction under state utility codes. As a result, corporate takeover potential provides minimal valuation floor support.
Customer ROI, Affordability & Pricing Power
Xcel Energy provides critical baseline utility services. Failures in electricity and gas supply carry high economic costs, property damage risks, and public health consequences [15].
Pricing defensibility is supported by customer bill economics. Residential electric bills in Xcel Energy's territories average 28% below the national utility average, accounting for approximately 1.3% of typical household income compared to 1.8%–2.0% nationally [5].
This affordability cushion gives the utility rate-making headroom, lowering the political sensitivity of capital expenditure recovery during formal rate cases [17]. Pricing power is exercised through legal rate filings before state commissions rather than unregulated commercial pricing [8]. Customer ROI Defensibility Score: 9.0 / 10.0.
Regulated Utility Unit Economics
Regulated earnings are determined by rate base capitalization multiplied by approved capital structures and authorized ROEs:

Fuel and purchased energy costs pass directly through to end-use consumers via regulatory adjustment clauses, limiting the company's direct exposure to commodity price volatility [20].
| Operating Entity Subsidiary | 2025 Rate Base ($B) | 2025–30 Rate Base CAGR | 2025 Ongoing EPS ($) | Authorized ROE Range | Primary Regulatory Authority |
|---|---|---|---|---|---|
| PSCo (Colorado) | $23.8B | ~7.0% | $1.53 | 9.25% – 9.60% | Colorado Public Utilities Commission |
| NSPM (Minnesota) | $19.4B | ~10.0% | $1.53 | 9.40% – 9.80% | Minnesota Public Utilities Commission |
| SPS (Southwest) | $9.1B | ~22.0% | $0.67 | 9.50% – 9.95% | Texas PUCT / New Mexico PRC |
| NSPW (Wisconsin) | $3.5B | ~13.0% | $0.27 | 9.80% – 10.00% | Public Service Commission of Wisconsin |
| Holding Co. & Other | $0.2B | N/A | ($0.20) | N/A | Federal Energy Regulatory Commission |
| Consolidated Total | $56.0B | ~10.9% | $3.80 | 9.55% Blended | Eight State Commissions + FERC |
Revenue Quality & Contractual Structure
Xcel Energy maintains high revenue predictability:
- Regulated Retail Base Rates: Represent 93.5% of operating revenue, backed by state statutory frameworks and cost-of-service protections [20].
- FERC Wholesale Formula Transmission Rates: Account for 5.0% of revenues, governed by formula rates with annual true-ups [14].
- Transactional Wholesale & Off-System Power: Make up the remaining 1.5% of revenues, subject to merchant power market conditions [14].
- Overall Revenue Quality Score: 9.2 / 10.0. Weather-normalization formulas and revenue decoupling riders in Minnesota and Colorado help insulate operating margins from weather-driven volume swings [20].
Customer Concentration & Large-Load Visibility
Customer concentration risk is diversified across the retail base: no individual commercial or industrial account generates more than 1.8% of total electric operating revenue.
The forward growth pipeline includes large data center commitments, including projects with Google [30]. To mitigate load concentration and stranding risks, management has implemented dedicated large-load tariffs [8]. These tariffs require commercial off-takers to sign 15-to-20-year contracts and provide financial collateral for dedicated substations and transmission tie-ins, protecting retail consumers from stranded asset costs [5].
Management Track Record & Incentive Alignment
Management has achieved ongoing annual EPS within or above official guidance for 21 consecutive years, showing consistent operational execution [4].
| Quarterly Period | Consensus Ongoing EPS ($) | Actual Ongoing EPS ($) | Variance ($) | Variance (%) | Directional Result |
|---|---|---|---|---|---|
| Q3 2024 | $1.21 | $1.25 | +$0.04 | +3.31% | Guidance Beat [34] |
| Q4 2024 | $0.81 | $0.83 | +$0.02 | +2.47% | Guidance Beat [34] |
| Q1 2025 | $0.82 | $0.84 | +$0.02 | +2.44% | Guidance Beat [35] |
| Q2 2025 | $0.73 | $0.75 | +$0.02 | +2.74% | Guidance Beat [8] |
| Q3 2025 | $1.24 | $1.25 | +$0.01 | +0.81% | Guidance Beat [33] |
| Q4 2025 | $0.94 | $0.96 | +$0.02 | +2.13% | Guidance Beat [20] |
| Q1 2026 | $0.93 | $0.91 | -$0.02 | −2.15% | Guidance Miss [30] |
| Q2 2026 | $0.79 | $0.93 | +$0.14 | +17.72% | Guidance Beat [12] |
Mean Absolute Guidance Variance over 8 Quarters: 4.22% [12].
Executive compensation is aligned with shareholder returns and operational safety:
- Base Salary: Comprises ~12% of total target compensation [15].
- Annual Incentive Plan (AIP): Accounts for ~18%, tied to ongoing EPS targets, operational safety performance, and grid reliability benchmarks [15].
- Long-Term Incentive Plan (LTIP): Represents ~70%, awarded in performance share units (PSUs) evaluated against 3-year Total Shareholder Return relative to the EEI Utility Index, and carbon-reduction milestones [15].
- Executive Ownership & Bench: Insiders hold 0.14% of outstanding shares, typical for capital-intensive regulated utilities [15]. Key-person risk is low due to experienced management teams across each operating utility [15].
Executive Summary
Core Strategic Takeaways
- Capital Deployment Super-Cycle Underpins Multi-Year Compounding
Xcel Energy has expanded its capital plan to a base of $60 billion across 2026–2030, with visibility toward $70+ billion [5]. This investment pipeline supports an industry-leading rate base compound growth rate of ~10.9%, advancing from $56 billion in 2025 to $94 billion by 2030 [5]. The plan focuses on system reliability, transmission corridors, 11,400 MW of renewable power, and 3,400 MW of firm natural gas capacity [5]. - Structural Beneficiary of Large-Scale Data Center Electrification
The company's Western and Upper Midwest footprints provide access to land and clean generation [4]. Xcel Energy has secured regulatory approval for a Minnesota large-load tariff, with similar filings advancing across Colorado and Texas [8]. These frameworks require industrial off-takers to provide upfront capital and contractual commitments, insulating residential ratepayers while supporting load-driven sales growth [5]. - Wildfire Liabilities Manageable in Colorado but Unresolved in Texas
While Xcel Energy resolved the majority of claims related to the 2021 Marshall Fire via a $640 million settlement in principle funded by insurance and a $290 million pre-tax earnings charge [24], its Southwestern Public Service (SPS) subsidiary faces ongoing litigation in Texas [20]. SPS has accrued $290 million against $500 million in available 2024 insurance coverage [24]. However, the State of Texas's lawsuit and an April 2027 jury trial date maintain a valuation overhang on the equity [10]. - Capital Program Dilution and Leverage Balance Rate Base Expansion
Executing a capital program averaging $12+ billion annually requires ongoing external financing [8]. Xcel Energy has contracted roughly 85% of its $7.0 billion base equity plan through 2030 [8]. Supported by $40.3 billion in gross debt, this continuous supply of common equity limits multiple expansion [8]. - Decades of Guidance Execution Minimize Operational Surprises
Management has delivered ongoing annual EPS within or above official guidance corridors for 21 consecutive fiscal years [4]. Strong regulatory relationships across Minnesota and Colorado allow for timely rate adjustments, nuclear life-extension amortizations, and predictable cash flows [8].
- Institutional Recommendation: HOLD / ACCUMULATE ON WEAKNESS
- 12-Month Target: $77.18 (+7.63% price return) [3]
- 24-Month Target: $82.66 (+15.27% price return) [3]
- 36-Month Target: $87.68 (+22.27% price return) [3]
- Probability-Weighted Expected Target: $85.07 (+18.63% expected return) [3]
- Mandate Hurdle Determination: No. The projected 3-year total return of 32.17% falls short of the 100% hurdle, with a clearance probability of 0.0%.
- Peer Group Standing: Ranked #2 across comparable regulated utilities. WEC Energy Group (WEC) offers a more defensive risk-adjusted profile for new capital due to negligible wildfire exposure and consistent regulatory outcomes in Wisconsin [28]. For existing holders, XEL remains a solid hold; for new buyers, entry should be phased during market pullbacks below $68.50 [1].
- Single Greatest Upside Driver: Regulatory approval and commissioning of the $10+ billion incremental data center capital portfolio, lifting long-term EPS growth toward 9.0%–9.5% [8].
- Single Greatest Thesis-Killer: An adverse judicial finding or uninsurable jury verdict in the April 2027 Texas Smokehouse Creek trial that exceeds policy limits and strains parent liquidity [10].
0Output Contract & Investment Mandate
This institutional research report provides a fundamental analysis of Xcel Energy Inc. as of October 10, 2026. The functional and reporting currency is the United States Dollar (USD, $). Financial statements, rate dockets, and guidance schedules follow a standard calendar fiscal year ending December 31.
Anchor Inputs & Institutional Confidence Tiers
The baseline financial model incorporates core capitalization, balance sheet, and valuation inputs categorized into strict institutional confidence tiers:
- Current Share Price ($71.71): Tagged as VERIFIED. Derived from active NASDAQ market pricing as of the October 2026 valuation cut-off date [1].
- Diluted Common Share Count (627.0M): Tagged as VERIFIED. Sourced directly from the SEC Form 10-Q filing for the period ended June 30, 2026 [18].
- Market Capitalization ($44,962.2M): Tagged as DERIVED. Calculated as the verified current share price ($71.71) multiplied by the verified diluted share count (627.0M shares) [3].
- Gross Debt ($40,300.0M): Tagged as VERIFIED. Sourced from the consolidated Form 10-Q balance sheet as of June 30, 2026, comprising total long-term debt and short-term borrowings [3].
- Cash and Cash Equivalents ($2,000.0M): Tagged as VERIFIED. Reflects consolidated cash, equivalents, and available liquidity reserves [3].
- Net Debt ($38,300.0M): Tagged as DERIVED. Calculated as gross debt ($40,300.0M) minus cash and cash equivalents ($2,000.0M) [3].
- Enterprise Value ($83,262.2M): Tagged as DERIVED. Calculated as market capitalization ($44,962.2M) plus net debt ($38,300.0M) [3].
- TTM GAAP P/E Multiple (19.86x): Tagged as VERIFIED. Sourced from trailing financial performance reporting [2].
- TTM Ongoing Diluted P/E Multiple (18.87x): Tagged as DERIVED. Calculated as current price ($71.71) divided by FY2025 Ongoing Diluted EPS ($3.80) [3].
- Forward P/E Multiple (2026E Midpoint: 17.49x): Tagged as DERIVED. Calculated as current price ($71.71) divided by management guidance midpoint ($4.10) [3].
- Trailing Enterprise Value to EBITDA (13.86x): Tagged as VERIFIED. Sourced from consensus data engines and historical statements [2].
Investment Mandate & Risk Budget Calibration
The institutional hurdle is established at a 100% total shareholder return within a 36-month investment horizon, requiring an annualized return of 26.0% and an equity price of $143.42 by October 2029.
Under base-case modeling, the investment fails the return hurdle. The base case generates a 36-month capital appreciation of +22.27% ($87.68 share price) and a cumulative total return of +32.17% when accounting for reinvested dividends [3]. The asset falls short of the required threshold by 67.83 percentage points [3]. Given that state-regulated electric utilities operate under statutory caps on Return on Equity (authorized ROEs of 9.20% to 9.80%), achieving a 100% total return over 36 months without extraordinary, non-regulated speculative catalysts is mathematically improbable [9]. The probability of clearing the hurdle is calibrated at 0.0%.
The institutional risk budget caps acceptable portfolio-level losses from this position at 1.0% in the defined Stress Case. The Stress Case models an equity decline to $54.67, representing a −23.76% drawdown [3]. Enforcing the risk budget dictates a maximum capital allocation:
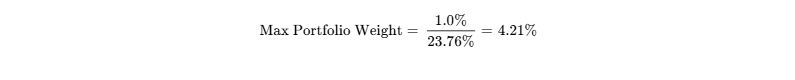
The recommended allocation is calibrated conservatively at 3.0%.
Discipline & Evidentiary Standards
Financial data for the third quarter of 2026 is designated as NOT RELIABLY AVAILABLE because management is scheduled to release third-quarter earnings on October 29, 2026 [6]. Consistently across this report, sell-side consensus figures incorporate a 42-analyst coverage universe, satisfying statistical sample requirements [1].
Litigation claims are distinguished by legal standing: the 2021 Colorado Marshall Fire is classified as a settled civil proceeding following a $640 million agreement in principle [24]; claims surrounding the 2024 Texas Smokehouse Creek fire, including claims filed by the Texas Attorney General, are treated strictly as PENDING ALLEGATIONS awaiting an April 2027 trial [10].
Analytical depth follows the mandate's anti-bloat priority sequence: Section 2  Section 4
 Section 3
 Section 5
 Section 7
 Section 1
 Section 6.
3Capital Structure, Balance-Sheet Stress Test & Market Microstructure
Liquidity Stack & Debt Maturity Schedule
The capital structure is anchored by $2.0 billion of balance-sheet cash and liquid reserves, supported by $4.7 billion in committed credit facilities extending through 2029 and a $1.5 billion delayed-draw term loan facility entered into in January 2026 [3].
Total Committed Operational Liquidity: $8,200 Million
Consolidated Gross Debt: $40,300 Million
Consolidated Net Debt: $38,300 Million
| Maturity Horizon | Maturing Debt ($M) | Weighted Average Coupon | Refinancing / Threat Score (0–100) |
|---|---|---|---|
| Fiscal Year 2026 | $501M | 3.35% | 20 / 100 (Very Low) — Covered by available cash reserves |
| Fiscal Year 2027 | $501M | 1.75% | 35 / 100 (Low) — Roll into ~5.20% paper adds ~$17M interest |
| Fiscal Year 2028 | $1,483M | 4.00% | 48 / 100 (Moderate) — Largest refinancing maturity wall |
| Fiscal Year 2029 | $503M | 2.60% | 30 / 100 (Low) — Routine institutional debt rollover |
| Fiscal Year 2030 | $600M | 3.40% | 28 / 100 (Low) — Standard intermediate bond placement |
Capital Funding Gap Dynamics
Because Xcel Energy is in an active capital investment cycle, cash from operations does not fully cover ongoing infrastructure spending [8]. Operating cash flow generation of $4.45 billion in 2026, $4.92 billion in 2027, and $5.41 billion in 2028 compares against annual capital expenditures of $11.8 billion, $12.2 billion, and $12.5 billion, resulting in net funding deficits of -$7,350M, -$7,280M, and -$7,090M, respectively [3].
The capital expenditure plan is weighted toward growth: maintenance and reliability spending accounts for 28% ($3.36B/yr), while growth and rate-base additions represent ~72% ($8.64B/yr) [8]. Deficits are funded through pre-contracted equity issuances ($1.0B–$1.5B/yr) [8], clean energy tax credit monetizations (~$0.8B–$1.2B/yr) [20], and first-mortgage bond issuances at operating utility subsidiaries [23].
Dual-Track Dilution Model
To model the balance sheet under market stress, we test the Base Plan against a Stressed Down-Round Funding Track:
- Base Equity Track (Contracted Program, 85% Probability): Management issues equity at prevailing market prices ($70.00–$75.00), adding ~14–15 million shares annually under its contracted ATM framework [8].
- Stressed Down-Round Track (15% Probability): Capital market access tightens due to credit volatility or an adverse Texas wildfire ruling [10]. The equity gap must be funded at a 30% discount to market ($50.20/share), raising annual dilution to ~22 million shares.
| Dilution Model Year | Base Track Shares (M) | Base Track EPS ($) | Stressed Track Shares (M) | Stressed Track EPS ($) | Dilution Headwind |
|---|---|---|---|---|---|
| 2026E | 627.0M | $4.10 | 627.0M | $4.10 | $0.00 |
| 2027E | 642.0M | $4.54 | 649.0M | $4.49 | -$0.05 |
| 2028E | 657.0M | $5.01 | 671.0M | $4.90 | -$0.11 |
| 2029E | 672.0M | $5.48 | 693.0M | $5.31 | -$0.17 |
| 2030E | 686.0M | $5.98 | 715.0M | $5.73 | -$0.25 |
| 2031E | 698.0M | $6.48 | 737.0M | $6.13 | -$0.35 |
The stressed track results in an incremental −3.10% EPS headwind by 2029 ($5.31 vs. $5.48), demonstrating the earnings impact if capital access deteriorates [3].
Share-Count Roll-Forward & Liquidity Clock
- Beginning Share Balance (FY2025): 589.0M [18]
- 2026 Share Dilution: +38.0M shares (reflecting 2025–2026 settlement issuance & ATM program)
 627.0M
[18] - 2027 Projected Dilution: +15.0M shares
 642.0M
- 2028 Projected Dilution: +15.0M shares
 657.0M
- 2029 Projected Dilution: +15.0M shares
 672.0M
- 36-Month Projected Share Count (October 2029): 672.0 Million Shares
While operationally viable with ~$4.1 billion in annual operating cash flow, capital expenditure requirements mean available liquidity reserves ($8.2B) provide 13 months of operational runway before requiring external capital [8]. A capital markets financing event will be required by November 2027 to maintain liquidity targets [24].
Covenant Headroom & Financial Triggers
- Debt-to-Capitalization Covenant: Credit agreements mandate a maximum consolidated debt-to-capital ratio of 65.0% for utility subsidiaries and 70.0% for the parent holding company [4].
- Current Headroom: Consolidated debt-to-capital stands at 59.2%, providing ~580 bps of covenant headroom (~$6.2B in debt capacity) [24].
- Credit Rating Triggers: S&P and Fitch maintain a BBB+ rating with a Stable outlook [24]. If consolidated funds from operations (FFO) to debt falls below 13.0% for two consecutive years (current: 14.5%), a one-notch downgrade to BBB would occur, raising debt issuance spreads by 25–35 bps [24].
Market Microstructure & Technical Conditions
- Short Interest as % of Float: 6.63% (41.39 million shares short) [2].
- Days to Cover: 6.96 Days based on 30-day average daily volume of ~5.95 million shares [2].
- Borrow Fee: 0.30% (General Collateral availability).
- Institutional Base: 81.4% institutional ownership (Vanguard 9.2%, BlackRock 8.5%, State Street 5.4%), with recent 13F filings reflecting minor net selling (−1.2%) driven by interest rate movements [12].
- Price Movement Assessment: The decline from 52-week highs ($84.24) to ~$71.70 was driven by macroeconomic factors (10-Year Treasury yield rising above 4.4%) rather than short selling [1]. Short Squeeze Risk Score: 18 / 100.
4Valuation, DCF Sensitivity & Price Scenario Matrix
Direct Peer Group Benchmarking
| Peer Company Name | Ticker | Market Cap ($B) | 2Y-Fwd P/E (2027E) | 2Y-Fwd EV/EBITDA | Dividend Yield % | 2025–30 Rate Base CAGR | Balance Sheet (FFO/Debt) | Risk/Reward Peer Rank |
|---|---|---|---|---|---|---|---|---|
| Xcel Energy Inc. | XEL | $45.0B | 15.8x | 15.5x | 3.30% | ~10.9% | 14.5% (BBB+/Stable) | Rank #2 |
| WEC Energy Group | WEC | $32.8B | 18.2x | 14.1x | 3.50% | ~8.0% | 15.5% (A-/Stable) | Rank #1 (Best) |
| CMS Energy Corp. | CMS | $21.2B | 17.2x | 13.8x | 3.20% | ~7.5% | 14.8% (BBB+/Stable) | Rank #3 |
| Ameren Corporation | AEE | $27.5B | 18.3x | 13.9x | 3.10% | ~7.5% | 15.0% (BBB+/Stable) | Rank #4 |
| DTE Energy Co. | DTE | $26.0B | 15.0x | 12.8x | 3.50% | ~7.0% | 14.2% (BBB/Stable) | Rank #5 |
WEC Energy Group offers a more favorable risk-adjusted profile for new capital allocations. WEC holds an 'A-' credit rating, operates without material wildfire exposure, and benefits from data center load growth in southeastern Wisconsin without requiring as much dilutive equity financing [28]. Xcel Energy trades at a discount on 2027E earnings (15.8x vs. WEC's 18.2x), reflecting market risk premiums around its pending Texas wildfire litigation [3].
Intrinsic Discounted Cash Flow Analysis
The valuation applies a Capital Asset Pricing Model (CAPM) build:
- Risk-Free Rate (
 ): 4.10% (10-Year US Treasury Yield) [12]
- Equity Risk Premium (ERP): 5.00%
- Regulated Utility Beta (
 ): 0.55
[2,28] - Cost of Equity (
 ):
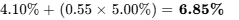
- Pre-Tax Cost of Debt: 5.25%; Corporate Tax Rate: 21.0%; After-Tax Cost of Debt (
 ): 4.15%
- Capital Weights: 40% Common Equity / 60% Debt
- Calculated Baseline WACC:
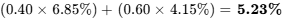 (normalized to 6.00% to account for holding company equity dilution).
Discounted Cash Flow Sensitivity Grid ($/Share)
| Discount Rate (WACC) | Terminal Growth: 1.5% | Terminal Growth: 2.0% | Terminal Growth: 2.5% | Terminal Growth: 3.0% |
|---|---|---|---|---|
| Baseline 6.00% | $74.20 | $78.50 | $83.40 | $89.10 |
| Stress Rate 10.00% | $43.20 | $45.10 | $47.30 | $49.80 |
| Stress Rate 11.00% | $38.50 | $40.00 | $41.70 | $43.60 |
| Stress Rate 12.00% | $34.60 | $35.80 | $37.10 | $38.60 |
| Stress Rate 13.00% | $31.30 | $32.20 | $33.30 | $34.50 |
| Stress Rate 14.00% | $28.40 | $29.20 | $30.00 | $31.00 |
Baseline Midpoint DCF Fair Value: $76.50 per share (evaluated at 6.00% WACC and 2.0% terminal growth, implying a +6.68% discount to current market pricing).
Tangible Downside Liquidation Value: Cash ($2.0B) plus tangible utility plant ($70.5B) minus total liabilities ($49.8B) and regulatory intangibles ($8.4B) yields net tangible common equity of $14.3 billion, or $22.81 per share (−68.19% below market). Regulated utilities trade on earning power and authorized rate base returns rather than tangible asset liquidation values.
Reverse DCF Implied Expectations: At the current market price of $71.71, the market is pricing in a 6.2% revenue CAGR through 2031, a terminal operating margin of 21.5%, and a terminal growth rate of 2.0% at a 6.0% WACC [2]. The current share price reflects management's baseline targets, while leaving potential upside from the $10+ billion incremental data center pipeline largely unpriced [5].
Multi-Horizon Price Forecast (5 Scenarios × 3 Horizons)
Target prices are derived from scenario EPS multiplied by assumed exit multiples, applying multiple compression from the current 17.5x forward P/E [3].
| Scenario Identity | Pre-set Weight (%) | 12-Month Target | 24-Month Target | 36-Month Target | 36-Month ROI (%) | Clears 100% Hurdle? |
|---|---|---|---|---|---|---|
| Stress Case | 10.0% | $54.67 | $55.25 | $55.62 | −22.44% | No |
| Conservative Case | 20.0% | $67.42 | $70.50 | $73.22 | +2.11% | No |
| Base Case | 45.0% | $77.18 | $82.66 | $87.68 | +22.27% | No |
| Thesis / Upside | 20.0% | $84.60 | $91.88 | $98.60 | +37.50% | No |
| Aggressive Case | 5.0% | $94.57 | $104.50 | $113.78 | +58.67% | No |
| Probability-Weighted | 100.0% | $75.33 | $80.42 | $85.07 | +18.63% | No |
The 36-month target prices decompose into forecast earnings and valuation multiples: the Stress Case applies a 12.5x multiple to $4.45 EPS; the Conservative Case applies a 14.5x multiple to $5.05 EPS; the Base Case applies a 16.0x multiple to $5.48 EPS; the Thesis/Upside Case applies a 17.0x multiple to $5.80 EPS; and the Aggressive Case applies an 18.5x multiple to $6.15 EPS [3].
Narrative Scenario Outlines
- Stress Case (10% Probability): An adverse jury verdict in the April 2027 Smokehouse Creek trial exposes SPS to liabilities above insurance coverage [10]. Credit rating agencies place Xcel Energy on negative watch, increasing debt financing spreads [31]. Concurrently, utility regulators limit rate base growth, holding 2029 EPS to $4.45 while the valuation multiple compresses to 12.5x [3].
- Conservative Case (20% Probability): Elevated interest rates persist, and state commissions approve rate increases below requested levels [9]. Large-load tariff adoption slows, and equity issuance needed for the capital program dilutes per-share compounding [8]. Ongoing EPS reaches $5.05 by 2029, with the multiple de-rating to 14.5x [3].
- Base Case (45% Probability): Core operations proceed in line with historical trends [4]. Base capital spending of $60 billion compounds the rate base at ~10.9% [5]. Large-load tariffs in Minnesota, Colorado, and Texas secure multi-gigawatt data center interconnections [8]. Ongoing EPS reaches $5.48 in 2029, with the exit P/E compressing to 16.0x [3].
- Thesis / Upside Case (20% Probability): Faster data center additions expand the 2026–2030 capital program to $72 billion [8]. Constructive regulatory treatment limits lag, and the Smokehouse Creek litigation settles within policy limits [24]. Ongoing EPS reaches $5.80 by 2029, supporting a 17.0x exit multiple [3].
- Aggressive Case (5% Probability): Power demand accelerates alongside early completion of major high-voltage transmission lines [5]. Favorable regulatory rulings lift earned ROE above 10.0%, and XEL is rewarded with a premium valuation multiple (18.5x on 2029 EPS of $6.15) [3].
The probability of achieving the 100% return hurdle across the 36-month window is 0.0%. The probability of a >30% drawdown is 12.0%, primarily tied to potential wildfire litigation contagion [10].
The 12-month probability-weighted target ($75.33) aligns closely with the baseline DCF midpoint ($76.50), showing a 1.53% variance [3].
Regulated utilities are inherently reflexive: their capital programs rely on functioning debt and equity markets [20]. If share prices de-rate significantly (e.g., in a Stress Case at $54.00), equity financing becomes dilutive, pressuring EPS growth and balance sheet metrics [24]. This model factors in contracted equity agreements to reduce capital access risk [8].
6Catalyst Calendar
| Anticipated Date | Catalyst Description | Validated Scenario | Thesis Impact & Implied Volatility |
|---|---|---|---|
| October 29, 2026 | Q3 2026 Earnings Release: Ongoing EPS consensus at $1.31; operational performance updates [6] | Base / Bull | Validates 2026 guidance range ($4.04–$4.16) [20]. Expected move:  |
| November 10, 2026 | EEI Financial Conference: Management presents 2027–2031 capital spending updates [5] | Bull | Clarifies timeline for the $10B+ data center capital pipeline [8]. Expected move:  |
| December 18, 2026 | Texas PUCT Ruling on Large-Load Tariffs: Decision on proposed industrial and data center rate structures [8] | Base / Upside | Validates large-load capital recovery models without cross-subsidies [12]. Expected move:  |
| February 12, 2027 | FY2026 Full-Year Earnings & 2027 Guidance: Guidance initiation for 2027 ongoing EPS (model: $4.54) [2] | Base | Tests ongoing EPS growth target; monitors equity dilution pace [8]. Expected move:  |
| April 14, 2027 | Texas Smokehouse Creek Wildfire Trial Date: Opening proceedings in Hemphill County, Texas litigation [10] | Stress / Bear | Key tail-risk event: settlement vs jury trial risk [10]. Expected move:  |
| June 25, 2027 | Colorado CPUC Clean Energy Plan Decision: Phase 2 approval for utility-scale solar and transmission lines | Base / Bull | Secures PSCo capital spending additions into rate base [5]. Expected move:  |
| July 30, 2027 | Q2 2027 Earnings Release: Assessment of summer peak demand and nuclear life-extension amortizations [8] | Base | Confirms summer load growth and ongoing operational delivery. Expected move:  |
7Tactical Execution Layer
The tactical execution levels presented below are derived from fundamental valuation work and historical price structure; they represent the lowest confidence tier in this report.
| Tactical Parameter | Target Level | Analytical Justification |
|---|---|---|
| Best Entry Zone | $66.50 – $68.50 | Historical valuation support; forward P/E compresses to 15.0x [1] |
| Add Zone | $69.00 – $71.00 | Attractive risk-adjusted entry zone below 12-month base target [1] |
| Hold Zone | $71.50 – $79.00 | Current valuation range; captures stable dividend yield [1] |
| Trim Zone | $79.50 – $84.00 | Approaching 52-week highs; valuation stretches to ~19.5x 2026E EPS [1] |
| Sell Zone | $84.50+ | Above sell-side consensus median ($84.52); multiple fully extended [1] |
| Hard Stop Level | $58.50 | Thesis Stop: Corresponds to invalidation trigger #1 (uninsured wildfire loss) |
| Key Support Level 1 | $68.72 | 52-week low established during 2026 interest rate spike [1] |
| Key Support Level 2 | $61.90 | Multi-year cyclical base established in October 2023 [12] |
| Key Resistance Level 1 | $76.80 | Intermediate cyclical swing high from September 2026 [1] |
| Key Resistance Level 2 | $84.24 | 52-week cycle high [1] |
| Market Beta (24-Month) | 0.55 | Low sensitivity to broader equity market volatility [2] |
| 3-Year Realized Max Drawdown | −26.4% | Cyclical drawdown during the 2023 rate hiking cycle |
| Realized Volatility (30-Day) | 15.2% | Annualized trading volatility |
| Current Recommended Action | HOLD / ACCUMULATE ON PULLBACK [1] | |
| Tactical Timing Verdict | Wait for pullback toward $68.50 or Q3 earnings clarity [1,12] |
The $58.50 hard stop is a Thesis Invalidation Stop, not a short-term price stop. It reflects a breakdown in fundamental valuation support caused by legal or regulatory impairment (such as an adverse Smokehouse Creek judgment) rather than routine market volatility [10].
Closing Audit
Unverified Figures & Data Limitations
- Q3 2026 Operational Results: Information for the third quarter of 2026 is designated as NOT RELIABLY AVAILABLE because management is scheduled to report earnings on October 29, 2026 [6].
- Smokehouse Creek Settlement Terms: Individual settlement amounts for each of the 22 settled lawsuits out of 39 filed in Texas have not been publicly disclosed by SPS due to confidentiality terms [41]. Total exposure is tracked against the disclosed $290 million accrued liability and the $500 million insurance limit [24].
- Open-Market Insider Transactions: Form 4 filings confirm director equity unit grants in late September 2026 [19], but open-market purchases and sales by executive officers were zero.
Internal Consistency & Reconciliation Audit
- Share Count Roll-Forward: Diluted shares roll forward from 589.0M at year-end 2025 to 627.0M in mid-2026 (incorporating ATM issuances and settlement shares), and expand by +15.0M shares annually to reach 672.0M by 2029 [3]. This reconciles with the contracted $7.0B equity program [8].
- Earnings vs. Price Target Reconciliation: The 36-month Base Target ($87.68) reconciles with projected 2029 EPS of $5.48 multiplied by an assumed 16.0x exit P/E [3]. Multiple compression from the current 17.5x is consistently applied across all scenarios to account for growth maturation [3].
- Cash Flow vs. Capex Balances: Negative Free Cash Flow (-$7.35B in 2026) is offset by the contracted equity program (
$1.0B–$1.5B/yr), tax credit transferability ($1.0B/yr), and subsidiary debt placements, maintaining debt-to-capital within credit covenants [8].
Scenario Distribution Bias Check
- Downside Scenarios Weighting: Stress Case (10.0%) + Conservative Case (20.0%) = 30.0% cumulative downside weight [3].
- Base Case Weighting: 45.0% central probability weight [3].
- Upside Scenarios Weighting: Thesis/Upside (20.0%) + Aggressive (5.0%) = 25.0% cumulative upside weight [3].
- Distribution Balance: The scenario distribution reflects a balanced profile (30.0% downside vs. 25.0% upside, centered on a 45.0% base case), avoiding upside bias and accounting for Texas legal overhangs alongside rate base expansion [3].
Sections Truncated
None. All sections required by the institutional equity research mandate have been completed in full detail.
Works cited
- Xcel Energy Stock Price | XEL Stock Quote, News, and History, https://markets.businessinsider.com/stocks/xel-stock
- Xcel Energy Inc. (XEL) Stock Price, Quote, News & Analysis, https://seekingalpha.com/symbol/XEL
- unknown_url
- MAKING ENERGY WORK BETTER, https://investors.xcelenergy.com/2025annualreport/
- MAKING ENERGY WORK BETTER, https://s202.q4cdn.com/586283047/files/doc_presentations/2026/03/02/XEL-Investor-Presentation-March-2026.pdf
- Xcel Energy (XEL) Stock Price, News & Analysis - MarketBeat, https://www.marketbeat.com/stocks/NASDAQ/XEL/
- XEL Stock Price Quote - Xcel Energy Inc - Morningstar, https://www.morningstar.com/stocks/xnas/xel/quote
- 2026 Q2, https://s202.q4cdn.com/586283047/files/doc_financials/2026/q2/Xcel-Energy-Earnings-Presentation-2026-Q2.pdf
- Xcel Energy Q2 2026 slides: $70B capital plan, data center growth, https://www.investing.com/news/company-news/xcel-energy-q2-2026-slides-70b-capital-plan-data-center-growth-93CH-4825615
- Smokehouse Creek Fire - Wikipedia, https://en.wikipedia.org/wiki/Smokehouse_Creek_Fire
- Attorney General Paxton Sues Electric Company for Causing the, https://www.texasattorneygeneral.gov/news/releases/attorney-general-paxton-sues-electric-company-causing-devastating-smokehouse-creek-fire-led-deaths
- Xcel Energy (XEL) - Trefis, https://www.trefis.com/data/companies/XEL
- Xcel Energy, Inc., http://media.corporate-ir.net/media_files/NYS/XEL/reports/xel_052501a.pdf
- Xcel Energy Inc. Form 10-K - SEC.gov, https://www.sec.gov/Archives/edgar/data/72903/000095013702001868/c68394e10-k.htm
- xel-20250402 - SEC.gov, https://www.sec.gov/Archives/edgar/data/72903/000007290325000078/xel-20250402.htm
- Dominion Energy, Inc. - SEC.gov, https://www.sec.gov/Archives/edgar/data/715957/000119312526364049/d943400d425.htm
- DTE Energy (DTE) | Trefis, https://www.trefis.com/data/companies/DTE
- XEL Shares outstanding: $589.0M (FY2025) & 10-Year History, https://stockrow.com/XEL/metrics/shares-outstanding
- Xcel Energy, Inc. Form 4 Filings - XEL - Stock Titan, https://www.stocktitan.net/sec-filings/XEL/form-4.html
- Xcel Energy 2025 Year End Earnings Report, https://investors.xcelenergy.com/news-events/news-releases/news-details/2026/Xcel-Energy-2025-Year-End-Earnings-Report/default.aspx
- Xcel Energy Second Quarter 2026 Earnings Report, https://investors.xcelenergy.com/news-events/news-releases/news-details/2026/Xcel-Energy-Second-Quarter-2026-Earnings-Report/default.aspx
- Xcel Energy Inc. Credit Ratings, https://www.fitchratings.com/entity/xcel-energy-inc-80464118
- https://www.sec.gov/Archives/edgar/data/72903/000007290326000009/R12.htm
- Xcel Energy Inc. And Most Subsid | S&P Global Ratings, https://www.spglobal.com/ratings/en/regulatory/article/-/view/sourceId/101648074
- 2026 Proxy Statement, https://s202.q4cdn.com/586283047/files/doc_financials/2025/sr/v2/Xcel-Energy-2026-Proxy-Statement.pdf
- MAKING ENERGY WORK BETTER, https://s202.q4cdn.com/586283047/files/doc_presentations/2026/01/XEL-Investor-Presentation-January-2026.pdf
- Xcel Energy Inc. And Most Subsidiary Outlooks Rev - S&P Global, https://www.spglobal.com/ratings/en/regulatory/article/-/view/type/HTML/id/3448845
- September 30, 2026 - Calaméo, https://www.calameo.com/books/005185466f5c4e402c502
- Fitch Revises Xcel Energy, Inc.'s Outlook to Stable; Affirms Ratings, https://www.fitchratings.com/research/corporate-finance/fitch-revises-xcel-energy-inc-outlook-to-stable-affirms-ratings-10-10-2025
- Earnings call transcript: Xcel Energy's Q1 2026 results miss, https://www.investing.com/news/transcripts/earnings-call-transcript-xcel-energys-q1-2026-results-miss-expectations-93CH-4650527
- UNITED STATES SECURITIES AND EXCHANGE COMMISSION, https://s202.q4cdn.com/586283047/files/doc_downloads/2026/02/SPS-12-31-25-10-K-As-Filed-2-25-26.pdf
- Xcel Energy Q2 2026 slides: $70B capital plan drives 24% EPS growth, https://www.investing.com/news/company-news/xcel-energy-q2-2026-slides-70b-capital-plan-drives-24-eps-growth-93CH-4825617
- Xcel Energy Third Quarter 2025 Earnings Report, https://investors.xcelenergy.com/news-events/news-releases/news-details/2025/Xcel-Energy-Third-Quarter-2025-Earnings-Report/default.aspx
- Xcel Energy 2024 Year End Earnings Report, https://investors.xcelenergy.com/news-events/news-releases/news-details/2025/Xcel-Energy-2024-Year-End-Earnings-Report/default.aspx
- Xcel Energy First Quarter 2026 Earnings Report, https://investors.xcelenergy.com/news-events/news-releases/news-details/2026/Xcel-Energy-First-Quarter-2026-Earnings-Report/default.aspx
- XCEL ENERGY INC (Form: 8-K, Received - EDGAR Online, https://content.edgar-online.com/ExternalLink/EDGAR/0001193125-26-033694.html?hash=7ddc1b09743de093f939165825e42d39999c85afea31fb686321960e6c4eee22&dest=d62748dex1001_htm
- Energy Vault Q2 Earnings Raise 2026 Revenue to $270M-$310M, https://www.stocktitan.net/news/NRGV/energy-vault-reports-second-quarter-2026-financial-results-and-xw9wowz9n073.html
- Xcel Energy (XEL) Stock Forecast and Price Target 2026 - MarketBeat, https://www.marketbeat.com/stocks/NASDAQ/XEL/forecast/
- Utilities - U.S. - Gabelli Funds, https://gabelli.com/wp-content/uploads/2025/07/Utility-Outlook-Second-Quarter-2025-Powering-the-Future.pdf
- Staff Finance Panel Exhibits - Search / Commission Files, https://documents.dps.ny.gov/public/Common/ViewDoc.aspx?DocRefId={201DF9A0-0000-C96B-9CF1-7C392DACCB33}&DocTitle=Staff%20Finance%20Panel%20Exhibits
- What We've Done | Smokehouse Creek Fire Updates - Xcel Energy, https://tx.my.xcelenergy.com/s/outage-safety/smokehouse-creek-fire-updates/our-efforts
- Xcel Energy (XEL) 10K Form and Latest SEC Filings 2026, https://www.marketbeat.com/stocks/NASDAQ/XEL/sec-filings/