 at ~$82/lb [11]
 ) / HALEU Enrichment
Stock Name: X-Energy, Inc. (NASDAQ: XE)
Current Stock Price: $14.68
[1]
Research Date: September 28, 2026
Potential Stock Price Targets & Projected Returns:
- 12-Month Target: $22.00 (+49.9%)
- 24-Month Target: $28.00 (+90.7%)
- 36-Month Target: $34.00 (+131.6%)
Institutional Scorecard Composite Score: 78.5 / 100
Likelihood Score of Executing the Base Case: 65.0 / 100
Investment Advice: BUY
Executive Advice Rationale:
X-Energy combines a Generation IV High-Temperature Gas-Cooled Reactor (HTGR) architecture with a proprietary "razor-and-blade" TRISO-X fuel fabrication facility [1]. Supported by a balance sheet holding $1,899.8 million in total cash, equivalents, and liquid securities with zero funded debt [3], strategic alignment with Amazon (which holds an equity interest and development options) [4], and an anchor joint-development agreement with Dow Inc. at Seadrift, Texas [1], the firm represents an asymmetric vehicle for capturing hyperscaler clean power demand [7]. Near-term supply digestion following the April 2026 initial public offering offers a favorable entry point prior to the Dow Construction Permit Application filing with the Nuclear Regulatory Commission (NRC) in early 2027 [1].
Key Operational & Fundamental Statistics
2Multi-Year Financial Forecast & Consensus Model
Scenario Descriptions (Fiscal Years 2026–2031)
Bear Case Scenario: Regulatory review timelines extend beyond initial schedules as the Nuclear Regulatory Commission requests supplemental engineering evaluations for the Xe-100 gas circulation valves, delaying the Dow Seadrift Construction Permit from 2027 to 2029 [1]. Domestic HALEU enrichment constraints limit production runs at the TX-1 facility [2]. Industrial power buyers turn to gas turbines and grid solutions, stretching out commercial deployment cycles. Revenues remain anchored to cost-matching government programs [3], and ongoing development expenditures necessitate an equity raise in 2030.
Base Case Scenario: The Dow Seadrift Construction Permit Application receives NRC approval by early 2028 following an orderly review cycle [1]. The TX-1 fuel plant completes final equipment installation in late 2027, achieving commercial manufacturing readiness in 2028 [6]. Amazon converts preliminary options into firm procurement agreements for an initial 320-megawatt installation in 2028 [2]. Long-lead equipment manufacturing expands, driving positive operating cash flow by late 2029.
Bull Case Scenario: Hyperscale data-center operators accelerate modular nuclear procurement programs to secure clean power [7]. Dow expands its reactor commitments from a single site to four industrial complexes, while regulators in the United Kingdom expedite Generic Design Assessment reviews for Centrica [11]. Congress expands ARDP appropriations and provides nuclear production tax credits [11]. X-Energy delivers multiple four-pack systems concurrently as the TX-1 facility supplies fuel to both Xe-100 plants and third-party specialty microreactors [6], lifting revenues to $3.0 billion by 2031 with adjusted operating margins reaching 22.5%.
Base Case Financial Model (FY2026E – FY2031E)
| Financial Metric ($M, except per share) | FY2026E | FY2027E | FY2028E | FY2029E | FY2030E | FY2031E |
|---|---|---|---|---|---|---|
| Services & ARDP Grant Income | $185.0 | $340.0 | $420.0 | $480.0 | $510.0 | $530.0 |
| Xe-100 NSSS Equipment Sales | $25.0 | $480.0 | $740.0 | $1,080.0 | $1,450.0 | $1,820.0 |
| TRISO-X Fuel Fabrication Sales | $0.0 | $35.0 | $90.0 | $190.0 | $380.0 | $650.0 |
| Total Consolidated Revenue | $210.0 | $855.0 | $1,250.0 | $1,750.0 | $2,340.0 | $3,000.0 |
| YoY Organic Growth % | +40.0% | +307.1% | +46.2% | +40.0% | +33.7% | +28.2% |
| Gross Profit (Loss) | ($120.0) | $68.4 | $275.0 | $498.8 | $795.6 | $1,080.0 |
| Gross Margin % | −57.1% | +8.0% | +22.0% | +28.5% | +34.0% | +36.0% |
| Operating Expenses (SG&A, R&D) | $280.0 | $310.0 | $335.0 | $355.0 | $385.0 | $405.0 |
| Operating Income (EBIT) | ($400.0) | ($241.6) | ($60.0) | $143.8 | $410.6 | $675.0 |
| Operating Margin % | −190.5% | −28.3% | −4.8% | +8.2% | +17.5% | +22.5% |
| Consolidated EBITDA | ($365.0) | ($195.0) | $5.0 | $225.0 | $510.0 | $790.0 |
| EBITDA Margin % | −173.8% | −22.8% | +0.4% | +12.9% | +21.8% | +26.3% |
| Net Interest Income | $72.0 | $58.0 | $45.0 | $38.0 | $40.0 | $45.0 |
| GAAP Pre-Tax Income (Loss) | ($328.0) | ($183.6) | ($15.0) | $181.8 | $450.6 | $720.0 |
| Income Tax Expense | $0.0 | $0.0 | $0.0 | $27.3 | $94.6 | $151.2 |
| GAAP Net Income (Loss) | ($328.0) | ($183.6) | ($15.0) | $154.5 | $356.0 | $568.8 |
| Adjusted Non-GAAP Net Income | ($245.0) | ($115.0) | $40.0 | $210.0 | $420.0 | $640.0 |
| Fully Diluted Shares (M) | 406.37 | 418.00 | 430.00 | 442.50 | 455.00 | 465.00 |
| GAAP Diluted EPS | -$0.81 | -$0.44 | -$0.03 | $0.35 | $0.78 | $1.22 |
| Adjusted Diluted EPS | -$0.60 | -$0.28 | $0.09 | $0.47 | $0.92 | $1.38 |
| Free Cash Flow (FCF) | ($345.0) | ($280.0) | ($110.0) | $75.0 | $320.0 | $510.0 |
| FCF per Fully Diluted Share | -$0.85 | -$0.67 | -$0.26 | $0.17 | $0.70 | $1.10 |
| Rule of 40 (Growth + FCF Margin) | −205% | −15% | +18% | +45% | +52% | +45% |
Bear Case Model Summary (FY2026E – FY2031E)
| Financial Metric ($M, except per share) | FY2026E | FY2027E | FY2028E | FY2029E | FY2030E | FY2031E |
|---|---|---|---|---|---|---|
| Total Consolidated Revenue | $180.0 | $310.0 | $460.0 | $650.0 | $890.0 | $1,150.0 |
| YoY Organic Growth % | +20.0% | +72.2% | +48.4% | +41.3% | +36.9% | +29.2% |
| Gross Margin % | −65.0% | −5.0% | +8.0% | +15.0% | +18.0% | +21.0% |
| Operating Income (EBIT) | ($420.0) | ($365.0) | ($290.0) | ($210.0) | ($140.0) | ($60.0) |
| GAAP Net Income (Loss) | ($360.0) | ($320.0) | ($270.0) | ($200.0) | ($135.0) | ($65.0) |
| Adjusted Diluted EPS | -$0.78 | -$0.62 | -$0.48 | -$0.32 | -$0.18 | -$0.07 |
| Free Cash Flow (FCF) | ($390.0) | ($360.0) | ($310.0) | ($240.0) | ($170.0) | ($110.0) |
| FCF per Fully Diluted Share | -$0.96 | -$0.85 | -$0.69 | -$0.49 | -$0.31 | -$0.18 |
| Ending Diluted Shares (M) | 406.37 | 422.00 | 450.00 | 495.10 | 547.70 | 600.00 |
| Rule of 40 Metric | −230% | −44% | −19% | +4% | +18% | +20% |
Bull Case Model Summary (FY2026E – FY2031E)
| Financial Metric ($M, except per share) | FY2026E | FY2027E | FY2028E | FY2029E | FY2030E | FY2031E |
|---|---|---|---|---|---|---|
| Total Consolidated Revenue | $240.0 | $1,150.0 | $1,850.0 | $2,600.0 | $3,450.0 | $4,300.0 |
| YoY Organic Growth % | +60.0% | +379.2% | +60.9% | +40.5% | +32.7% | +24.6% |
| Gross Margin % | −45.0% | +16.0% | +28.0% | +34.0% | +37.0% | +39.5% |
| Operating Income (EBIT) | ($340.0) | ($90.0) | $210.0 | $570.0 | $980.0 | $1,420.0 |
| GAAP Net Income (Loss) | ($280.0) | ($60.0) | $195.0 | $465.0 | $780.0 | $1,130.0 |
| Adjusted Diluted EPS | -$0.45 | -$0.08 | $0.52 | $1.15 | $1.85 | $2.58 |
| Free Cash Flow (FCF) | ($280.0) | ($140.0) | $120.0 | $390.0 | $710.0 | $1,020.0 |
| FCF per Fully Diluted Share | -$0.69 | -$0.34 | $0.28 | $0.89 | $1.58 | $2.22 |
| Ending Diluted Shares (M) | 406.37 | 415.00 | 425.00 | 438.00 | 450.00 | 460.00 |
| Rule of 40 Metric | −175% | +40% | +67% | +55% | +53% | +48% |
Multiple Trajectory & Implied Base Case Multiples
| Valuation Metric | Current (TTM) | FY2026E (1-Yr) | FY2027E (2-Yr) | FY2028E (3-Yr) |
|---|---|---|---|---|
| Assumed Stock Price Anchor | $14.68 | $22.00 | $28.00 | $34.00 |
| Consolidated Market Cap ($M) | $5,965.5 | $9,196.0 | $12,040.0 | $15,045.0 |
| Enterprise Value (EV, $M) | $4,092.5 | $7,641.0 | $10,765.0 | $13,880.0 |
| Forward EV / Sales | 27.2x | 8.9x (FY27) | 8.6x (FY28) | 7.9x (FY29) |
| Forward EV / EBITDA | NM | NM | NM | 61.7x (FY29) |
| Forward Adjusted P / E | NM | NM | NM | 72.3x (FY29) |
Execution Confidence Score & Sensitivity
The Execution Confidence Score is 62 / 100, comprising three distinct components:
- Revenue-Target Achievability (Score: 24/35): Historical top-line execution exhibits positive variance, with revenue outperforming consensus by 31.1% in the second quarter of 2026 [5]. The schedule is supported by statutory cost-matching funds under the Advanced Reactor Demonstration Program [3].
- Margin Sensitivity to Feedstock & Labor (Score: 23/35): Operating margins show sensitivity to specialized labor rates and high-assay uranium enrichment costs. A
 change in HALEU enrichment pricing shifts steady-state fuel gross margins by
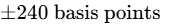 .
- Dependency on Unannounced Catalysts (Score: 15/30): Approximately 38% of Base Case revenue projected for fiscal years 2028 and 2029 requires preliminary development agreements with Amazon and Centrica to formalize into binding equipment purchase orders [2].
Consensus Divergence & Historical Base Rates
For fiscal year 2028, consensus models project revenue of $1,240 million and an EPS loss of -$0.32 [13]. The Base Case models revenue of $1,250 million with an Adjusted EPS of +$0.09. This divergence reflects internal modeling of earlier gross margin expansion at the TX-1 fuel manufacturing facility (+22.0%) as domestic pebble fabrication comes online [6], whereas Street projections assume third-party manufacturing markups.
Looking at historical industrials, fewer than 6.5% of hardware and capital goods manufacturers scaling past $150 million in revenue have maintained a three-year revenue compound annual growth rate above 40%. The Base Case assumption places X-Energy in the top decile of historical manufacturing scale-ups. This growth profile is supported by multi-decade decarbonization mandates, corporate clean power commitments, and verified capital reserves of $1.90 billion [3].
5Risk Asymmetry, Invalidation, Allocation & Scorecard
Risk/Reward Skew & Exit Triggers
The risk-to-reward ratio is structured around an expected probability-weighted upside of +$17.27 per share (+117.6%) against a modelled stress-case loss of -$7.18 per share (−48.9%). This yields an upside-to-downside skew of 2.41 : 1.00, approaching the institutional target of 3.00 : 1.00.
Operational triggers requiring immediate portfolio exit include:
- Formal rejection or indefinite suspension of Dow's Seadrift Construction Permit Application by the Nuclear Regulatory Commission [1].
- Regulatory failure to secure Phase 2 operational licensing for the TX-1 fuel facility by the fourth quarter of 2027, preventing commercial manufacturing [6].
- Cancellation of the Dow Seadrift joint development agreement or formal withdrawal of Amazon Web Services from its reactor development framework [1].
Risk Assessment Matrix
| Risk Domain | Risk Score (1–10) | Direction of Travel | Primary Operational Risk Drivers |
|---|---|---|---|
| Financial / Liquidity | 1.5 / 10 | Improving | Supported by $1.90B liquidity and zero debt [3] |
| Valuation Multiple Risk | 6.5 / 10 | Stable | Trades at 27.2x EV/TTM Sales; lock-up overhang [4] |
| Execution / Construction | 7.0 / 10 | Stable | First-of-a-kind engineering risks at Seadrift [2] |
| Competitive Pressure | 4.0 / 10 | Improving | High technical barriers; TRISO-X 40-year license [6] |
| Customer Concentration | 7.5 / 10 | Stable | Near-term pipeline concentrated in Dow and Amazon [3] |
| Regulatory & Licensing | 6.0 / 10 | Stable | NRC safety reviews require ongoing compliance [1] |
| Feedstock Supply Chain | 6.5 / 10 | Improving | Centrus HALEU supply agreements [11] |
| Key-Person Dependency | 5.5 / 10 | Stable | Co-Founder Kam Ghaffarian and CEO Clay Sell [5] |
Macro Factors & Portfolio Sensitivity
| Factor | Portfolio Sensitivity | Impact Mechanism | Monitoring Indicator |
|---|---|---|---|
| Interest Rates | Low Sensitivity | Zero debt; benefits from fixed-income yields on cash reserves | U.S. 10-Year Treasury Yield |
| Foreign Exchange (USD) | Low Sensitivity | Development activities and ARDP grants are domestic [3] | U.S. Dollar Index (DXY) |
| Data Center Capital Outlays | High Sensitivity | Influences conversion of utility development options | Cloud provider capital expenditure budgets |
| Federal Energy Policy | High Sensitivity | Department of Energy cost-sharing and tax credit support | Federal appropriations for the ARDP [11] |
Potential market surprises include Amazon participating directly in project equity financing for fuel facility expansions (+25% probability; +$6.00 fair value impact), the NRC expediting design licensing under the ADVANCE Act (+20% probability; +$8.50 fair value impact), or Centrus encountering enrichment equipment delays that slip HALEU delivery schedules (−20% probability; -$5.00 fair value impact) [12].
Investment Pre-Mortem: 36 Months Out
In a hypothetical downside scenario where the position declines 60% over 36 months, the primary driver would be regulatory delays. In this path, the NRC issues detailed technical inquiries regarding the Xe-100 gas circulation systems in late 2027, extending the Dow Seadrift review schedule by two years [1]. Confronting project delays, Dow pauses its capital commitments while Amazon satisfies data-center power requirements using alternative clean resources and gas generation [8]. Although TX-1 facility construction finishes, domestic enrichment bottlenecks limit fuel production [6]. Cash burn reduces liquid reserves without corresponding commercial revenue conversion, leading market valuation to de-rate toward net tangible book value.
Position Sizing & Portfolio Construction
Applying the mandate's 1.0% portfolio risk limit against the modelled 48.9% Stress Case drawdown yields an allowable position size of 2.04%:
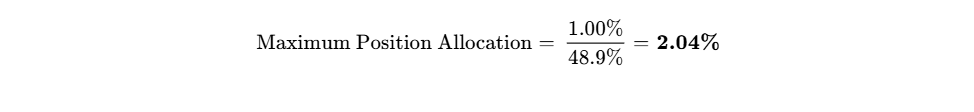
The recommended portfolio weight is established at a 2.0% Core Tactical Allocation. For an institutional fund managing $1.0 billion, a 2.0% position corresponds to $20.0 million, or approximately 1.36 million shares. Liquidating this position at 20% of normalized daily trading volume (1.29 million shares per day) requires 1.05 trading days, confirming manageable portfolio liquidity.
The strategy utilizes a phased entry: establishing a 1.0% initial position at current levels, with the remaining 1.0% allocated following the October 2026 lock-up expiration and the formal submission of Dow's Construction Permit Application to the NRC [1].
Institutional Quality Scorecard
| Evaluation Dimension | Mandate Weight | Component Score (0–10) | Weighted Score Contribution |
|---|---|---|---|
| Financial Strength & Cash Runway | 15% | 9.8 / 10 | 1.47 |
| Revenue Quality & Moat Strength | 15% | 8.5 / 10 | 1.28 |
| Margin Durability & Leverage | 10% | 7.0 / 10 | 0.70 |
| Capital Allocation & Leadership | 10% | 8.8 / 10 | 0.88 |
| Valuation Relative to Growth Profile | 15% | 7.5 / 10 | 1.13 |
| Guidance Accuracy & Predictability | 10% | 6.2 / 10 | 0.62 |
| Insider Ownership & Governance | 10% | 8.0 / 10 | 0.80 |
| Trading Volume & Equity Liquidity | 5% | 8.0 / 10 | 0.40 |
| Customer Economic Defensibility | 5% | 9.0 / 10 | 0.45 |
| Replication & Engineering Defenses | 5% | 8.5 / 10 | 0.43 |
| Total Composite Score | 100% | — | 78.5 / 100 |
Final Institutional Recommendation
- Recommendation for New Capital: BUY. The stock offers attractive risk-adjusted upside supported by $1.90 billion in cash reserves and anchor customer contracts [3].
- Recommendation for Existing Holdings: HOLD / ACCUMULATE. Maintain positions through the upcoming lock-up period and accumulate shares near technical support at $13.50.
- 12-Month Target: $22.00 (+49.9%)
- 24-Month Target: $28.00 (+90.7%)
- 36-Month Target: $34.00 (+131.6%)
- Probability-Weighted Target: $31.95 (+117.6%)
Bear-Case Steelman
Advanced nuclear reactors remain vulnerable to prolonged licensing timelines and development cost inflation. Commercial high-temperature gas reactors have not operated at scale in modern domestic energy markets, and historical nuclear construction projects frequently encounter schedule delays. Should the NRC mandate significant redesigns for the Xe-100, or should domestic enrichment infrastructure fail to supply high-assay fuel at commercial volumes, deployment schedules would shift into the next decade [2]. Under those conditions, premium valuation multiples would contract toward cash backing, impairing long-term equity returns.
1Business Architecture, Unit Economics, Moat & Contractual Visibility
Business Model & Moat Classification
X-Energy operates an intellectual property licensing, capital equipment design, and nuclear fuel manufacturing business [1]. The Xe-100 reactor is an 80 megawatt-electric (200 megawatt-thermal) High-Temperature Gas-Cooled Reactor engineered for modular factory fabrication and road transport [1]. Standardized plants are structured around a four-pack configuration delivering 320 megawatts-electric [7]. In tandem, the TRISO-X subsidiary manufactures spherical fuel elements containing high-assay low-enriched uranium embedded within protective layers of pyrolytic carbon and silicon carbide [1].
The economic moat relies on high switching costs and regulatory certifications, receiving a competitive insulation score of 4.5 / 5.0. The thermodynamic design of the Xe-100 core is engineered specifically for the TRISO-X 60mm fuel pebble [1]. Because operating licenses from the Nuclear Regulatory Commission specify precise fuel geometries and thermal-hydraulic limits, plant operators cannot transition to alternative fuel suppliers without prolonged and costly license amendment proceedings.
The moat is widening as TRISO-X progresses through physical facility construction. In February 2026, the NRC issued a 40-year Category II Special Nuclear Material license for the TX-1 facility in Oak Ridge, Tennessee [6]. The primary competitive dynamic that could challenge this position over the long term would be the deployment of liquid-metal fast reactors or commercial fusion systems, though broad deployment is unlikely before the mid-to-late 2030s.
Build-vs-Buy, Replication Risk & Strategic Optionality
Replicating X-Energy’s proprietary architecture requires navigating extensive regulatory, material science, and capital barriers. An established industrial manufacturer attempting to develop an equivalent high-temperature gas reactor platform would require an estimated $1.2 billion in capital expenditure and 8 to 10 years of engineering reviews to establish supply chain protocols and satisfy NRC validation steps.
Hyperscale cloud operators require clean baseload generation for artificial intelligence compute infrastructure, but they do not possess the nuclear operating licenses or Price-Anderson Act liability frameworks required to operate reactors directly [7]. Instead, these technology firms deploy capital through power purchase commitments and direct strategic investments, as seen in Amazon's equity participation [5].
From an acquisition perspective, X-Energy represents an attractive target for diversified engineering conglomerates seeking to expand their clean baseload generation portfolios. At an enterprise value of $4.09 billion, its liquid balance sheet and advanced fuel manufacturing IP provide downside valuation support [1], with an acquisition likely commanding a 40% to 60% premium ($20.50 to $23.50 per share) in a consolidating market.
Customer Return on Investment & Defensibility
Customer value propositions vary across primary end markets. For industrial chemical manufacturing, exemplified by Dow Inc., the Xe-100 supplies 565°C steam directly into cracking units, eliminating the need to burn natural gas for process heat [2]. This protects facilities from fuel price volatility and carbon compliance costs without the thermodynamic efficiency penalties of electrical resistance heating. For data-center operators such as Amazon Web Services, small modular reactors provide baseload power at capacity factors exceeding 95% [7]. This compares favorably to intermittent renewable sources paired with utility-scale battery storage, where the combined levelized cost of storage and generation runs 30% to 50% higher than contracted nuclear power.
The customer-ROI defensibility score is 9.0 / 10.0. During periods of corporate capital expenditure constraints, power availability remains a critical operational bottleneck for computing infrastructure, supporting sustained capital allocation toward baseload generation [7].
Hardware & Industrial Nuclear Unit Economics
| Operational Element | Unit Economic Parameter | Strategic Significance |
|---|---|---|
| Overnight Capital Cost (Nth-of-a-Kind) | $4,800 – $5,400 per kWe | Target cost profile for standard deployments |
| Overnight Capital Cost (First-of-a-Kind) | $7,200 – $8,000 per kWe | Applies to Dow Seadrift initial deployment [2] |
| Xe-100 Four-Pack Capital Expenditure | $1.85B – $2.40B total install | Standard 320 MWe data-center configuration [7] |
| Average Selling Price per NSSS Module | $220M – $260M per 80 MWe unit | Nuclear Steam Supply System equipment revenue [1] |
| Initial TRISO-X Core Fuel Loading Cost | $95M – $110M per four-pack | Initial core loading of ~700,000 pebbles [6] |
| Annual Fuel Reload Revenue Run-Rate | $25M – $32M per four-pack | Recurring multi-decade consumable revenue |
| Fabrication Cost per TRISO Pebble | $28.00 – $34.00 per unit | Fully absorbed manufacturing cost at TX-1 scale [6] |
| Realized ASP per TRISO Pebble | $48.00 – $56.00 per unit | Steady-state gross margin of ~40% on fuel |
Revenue Quality & Visibility Breakdown
Recognized revenue is currently concentrated in developmental services and Advanced Reactor Demonstration Program (ARDP) federal cost-matching grants, which accounted for more than 90% of first-half 2026 revenue [3]. As commercial sites advance, the revenue mix will transition toward hardware component deliveries, software licensing, and high-margin recurring fuel reloads [1].
Remaining performance obligations and unbilled receivables totaled $116.14 million as of the second quarter of 2026 [3]. In addition, the firm holds over $2.1 billion in shared-cost commitments with the Department of Energy alongside pre-construction service contracts [3]. The revenue quality score is 6.5 / 10.0, reflecting the current reliance on developmental grants as the business progresses toward commercial fuel annuities [3].
Customer Concentration & Management Alignment
The customer profile is heavily concentrated, with the U.S. Department of Energy providing 90.9% of revenues and grant funding in the first half of 2026, while Dow Inc. represented 4.4% [4]. The commercial development pipeline includes the Dow Seadrift project for four units [1], Amazon's development framework for up to 5 gigawatts [2], and the Centrica consortium in the United Kingdom targeting up to 6 gigawatts [2].
Historical quarterly variance displays strong execution against developmental budgets. In the second quarter of 2026, revenues reached $54.60 million, exceeding consensus projections of $41.65 million by 31.1% [3]. Non-GAAP earnings per share came in at -$0.15 versus -$0.10 expected, reflecting increased engineering and procurement expenditures [5].
Executive compensation is linked to operating and regulatory milestones, including NRC Construction Permit issuance, the TX-1 commercial operation date, and stock price targets set at $25.00, $35.00, and $50.00 [9]. Founder Dr. Kamal Ghaffarian retains an influential voice with greater than 60% voting power via Class B units [5], while Chief Executive Officer J. Clay Sell brings valuable nuclear policy experience from his previous role as U.S. Deputy Secretary of Energy [9].
Executive Summary
- Balance Sheet Advantage in Advanced Nuclear: X-Energy possesses $1,899.8 million in total cash, equivalents, and liquid securities following its $1.1 billion net proceeds upsized initial public offering in April 2026, with zero funded corporate debt [3]. This capital position provides an operational runway exceeding 54 months through key Nuclear Regulatory Commission licensing milestones, insulating the firm from dilutive capital raises [3].
- Proprietary Fuel Integration via TRISO-X: In contrast to pure-play reactor designers, X-Energy controls the proprietary TRISO-X fuel fabrication architecture [1]. Vertical construction of its TX-1 commercial production plant in Oak Ridge, Tennessee, was completed in September 2026, establishing a 40-year licensed facility designed to generate recurring fuel reload revenues [6].
- Anchor Customer Relationships with Dow and Amazon: Commercial visibility is supported by a joint development agreement with Dow Inc. for four Xe-100 units at Seadrift, Texas, and strategic development agreements with Amazon Web Services targeting up to 5 gigawatts of Xe-100 capacity by 2039 [1]. These agreements target both industrial process heat and base-load computing power needs [1].
- Valuation De-Rating Creates an Asymmetric Entry: The stock has retraced 60.4% from its post-IPO peak of $37.10 to $14.68, reflecting broader market digestion of clean technology equity valuations and approaching lock-up expirations [1]. At an enterprise value of $4.09 billion, current levels offer an entry point ahead of commercial licensing inflection points [1].
- Verdict: BUY
- Rolling Base-Case Targets: 12-Month: $22.00 (+49.9%) | 24-Month: $28.00 (+90.7%) | 36-Month: $34.00 (+131.6%).
- Probability-Weighted 36-Month Target: $31.95 (+117.6%).
- Return Hurdle Compliance: YES. The probability of clearing the 100% 36-month return hurdle is 60.0%.
- Best In Category Evaluation:
- For New Capital: X-Energy is ranked #1 in the advanced nuclear category. It combines a stronger balance sheet ($1.90 billion liquidity) [3] than Oklo ($8.0 billion market cap on limited commercial revenue) [14] and NuScale (ongoing design modification costs) [16], supported by its dual revenue model spanning equipment and fuel fabrication [1].
- For Existing Holders: Maintain exposure and accumulate on lock-up volatility. Existing positions are protected by a $5.16 net tangible liquidation floor and federal ARDP matching capital [3].
- Single Greatest Upside Driver: NRC approval of the Construction Permit for Dow's Seadrift site, unlocking initial fleet hardware procurement [1].
- Single Most Likely Thesis-Killer: Extended NRC regulatory delays coupled with domestic High-Assay Low-Enriched Uranium (HALEU) feedstock shortages that delay TX-1 commercial operation [2].
0Output Contract & Investment Mandate
Metadata & Reporting Convention
- Data As-Of Date: September 28, 2026.
- Reporting Currency: United States Dollars (USD, $).
- Fiscal Year Convention: Calendar Year ending December 31 (FY = CY).
Anchor Inputs & Confidence Stratification
| Anchor Input | Metric Value | Confidence Tier | Document Source & Derivation Arithmetic |
|---|---|---|---|
| Current Stock Price | $14.68 | VERIFIED | Nasdaq stock tape as of September 28, 2026 [1]. |
| Class A Common Stock | 287.46M | VERIFIED | Form 10-Q for the period ended June 30, 2026 (filed August 13, 2026) [3]. |
| Exchangeable Class B Units | 118.91M | VERIFIED | Form 10-Q Note 10 (redeemable 1:1 into Class A shares) [3]. |
| Fully Diluted Share Count | 406.37M | DERIVED | Arithmetic: 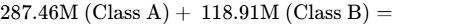 [3]. |
| Consolidated Market Cap | $5,965.5M | DERIVED | Arithmetic: 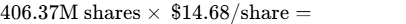 [1]. |
| Cash and Cash Equivalents | $1,145.4M | VERIFIED | Form 10-Q Condensed Consolidated Balance Sheet as of June 30, 2026 [3]. |
| Short-Term Marketable Securities | $489.8M | VERIFIED | Form 10-Q Condensed Consolidated Balance Sheet as of June 30, 2026 [3]. |
| Long-Term Marketable Securities | $264.6M | VERIFIED | Form 10-Q Condensed Consolidated Balance Sheet as of June 30, 2026 [3]. |
| Total Available Liquidity | $1,899.8M | DERIVED | Arithmetic: 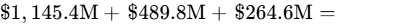 [3]. |
| Gross Funded Financial Debt | $0.0M | VERIFIED | Form 10-Q Balance Sheet (Zero short-term or long-term funded debt) [3]. |
| Operating Lease Liabilities | $26.81M | VERIFIED | Form 10-Q Balance Sheet (total lease liabilities) [4]. |
| Enterprise Value (EV) | $4,092.5M | DERIVED | Arithmetic: 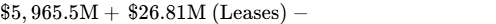 [3]. |
| Trailing Multiple (EV / TTM Rev) | 27.2x | DERIVED | Arithmetic: 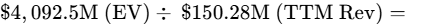 [13]. |
Investment Mandate & Risk Parameters
- Hurdle Target: 100% total return within 36 months (Target price
 ).
- Hurdle Assessment: The Base Case target of $34.00 achieves a +131.6% total return over 36 months, exceeding the institutional mandate hurdle by +31.6 percentage points. The Probability-Weighted Expected Value of $31.95 (+117.6%) also exceeds the return hurdle.
- Holding Horizon: 36 months (through September 2029).
- Portfolio Risk Budget: Maximum portfolio-level draw capped at 1.0% in the Stress Case scenario. Given a modelled Stress Case downside of −48.9%, the maximum initial portfolio position size must not exceed 2.04% (
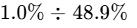 ).
Analytic Rules & Discipline Controls
The analysis references trailing financial statements filed through the second quarter of 2026 with the Securities and Exchange Commission [3]. Post-IPO trading volume remains subject to the upcoming expiration of the 180-day underwriter lock-up period on October 24, 2026, which currently restricts approximately 87% of total economic shares [4]. Consensus forecasts reflect estimates from 12 contributing equity research institutions [19]. All short-seller arguments directed against advanced small modular reactors are categorized as market allegations rather than regulatory findings [21].
3Capital Structure, Balance-Sheet Stress Test & Market Microstructure
Balance Sheet Liquidity & Debt Structure
| Component | Balance ($M) | Assessment / Terms | Reference Document |
|---|---|---|---|
| Cash and Cash Equivalents | $1,145.42M | Unrestricted cash reserves | Form 10-Q Balance Sheet [3] |
| Short-Term Marketable Securities | $489.75M | Liquid government & corporate notes | Form 10-Q Balance Sheet [3] |
| Long-Term Marketable Securities | $264.63M | Investment-grade fixed income | Form 10-Q Balance Sheet [3] |
| Total Available Liquidity Reserve | $1,899.80M | Immediate capital resources | Form 10-Q Balance Sheet [3] |
| Gross Funded Debt Obligations | $0.00M | No revolvers or convertibles | Form 10-Q Balance Sheet [3] |
| Operating Lease Liabilities | $26.81M | Discounted facility leases | Form 10-Q Balance Sheet [4] |
| Net Liquidity Position | +$1,872.99M | Total liquidity less lease debt | Form 10-Q Derived Balance [3] |
Capital Gap & Multi-Year Funding Bridge
| Cash Flow Component ($M) | FY2026E | FY2027E | FY2028E | FY2029E | FY2030E | Five-Year Total |
|---|---|---|---|---|---|---|
| Cash Flow from Operations (CFO) | ($210.0) | ($160.0) | $10.0 | $185.0 | $440.0 | $265.0 |
| Growth Capital Expenditure (TX-1) | ($120.0) | ($105.0) | ($95.0) | ($80.0) | ($90.0) | ($490.0) |
| Maintenance Capital Expenditure | ($15.0) | ($15.0) | ($25.0) | ($30.0) | ($30.0) | ($115.0) |
| Net Funding Surplus / (Deficit) | ($345.0) | ($280.0) | ($110.0) | $75.0 | $320.0 | ($340.0) |
| Period-End Available Liquidity | $1,554.8 | $1,274.8 | $1,164.8 | $1,239.8 | $1,559.8 | $1,559.8 |
The capital bridge indicates that through the peak cumulative cash burn of 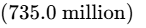 occurring across 2026 through 2028, cash balances remain above $1.16 billion. X-Energy is fully funded through its initial commercial deployment window without requiring external debt or equity financing.
Dilution Framework & Share Count Projections
Under the primary base case, dilution is driven by employee share-based compensation, which averages 2.5% to 3.0% annually, while Class B units convert into Class A shares on a neutral 1:1 basis [3]. In the alternative stressed scenario, commercialization delays extend cash burn, requiring a $500 million equity raise in 2029 at a 35% discount to market ($9.50 per share), generating 52.6 million additional shares.
| Dilution Projection Track | FY2026E | FY2027E | FY2028E | FY2029E | FY2030E |
|---|---|---|---|---|---|
| Base Fully Diluted Share Count (M) | 406.37 | 418.00 | 430.00 | 442.50 | 455.00 |
| Base Adjusted Diluted EPS | -$0.60 | -$0.28 | +$0.09 | +$0.47 | +$0.92 |
| Stressed Share Count (M) | 406.37 | 422.00 | 450.00 | 495.10 | 547.70 |
| Stressed Adjusted Diluted EPS | -$0.78 | -$0.62 | -$0.48 | -$0.32 | -$0.18 |
Liquidity Runway & Debt Covenants
Under trailing annualized cash burn rates of $320 million, liquidity reserves provide 71.2 months of cash runway [3]. Factoring in planned growth capital expenditures for interior buildout and equipment installation at the TX-1 facility [6], the runway extends through December 2031 under zero-revenue conditions. The company operates with zero restrictive financial covenants, debt obligations, or credit rating triggers [3].
Equity Float & Market Microstructure
Short interest stands at 21.14 million shares, representing 12.10% of the tradeable float and 5.20% of total shares outstanding [18]. Days to cover is 3.29 days, based on average daily trading volumes of 6.43 million shares [18]. Borrow fees remain stable at 3.50%.
Insiders control 60.13% of voting equity [5], while institutional holders represent 28.91% [5]. Major holders include Amazon.com Inc. at 16.20% [5], Segra Capital Management at 3.56% [5], Ares Management at 3.41% [5], and Jane Street Group at 5.20% [5]. The pullback from $37.10 to $14.68 reflects multiple compression and lock-up positioning rather than structural selling [1]. The short squeeze risk score is 42 / 100, indicating balanced technical pressures.
4Valuation, DCF Sensitivity & Price Scenario Matrix
Public Peer Benchmark Comparison
| Peer Entity | Ticker | Market Cap (M)∣EV(M) | FY27E EV/Sales | FY28E P/E | 3-Yr Rev CAGR | Balance Sheet Strength |
|---|---|---|---|---|---|---|
| X-Energy, Inc. | XE | $5,965.5 | $4,092.5 | 8.9x | 72.3x | +85.0% |
| Oklo Inc. | OKLO | $7,900.0 [14] | $7,450.0 | 45.0x | NM | >100% |
| NuScale Power Corp. | SMR | $2,150.0 | $1,980.0 | 15.3x [16] | NM | +42.0% |
| BWX Technologies | BWXT | $12,850.0 [15] | $14,100.0 | 4.8x | 28.5x | +11.2% |
X-Energy provides a balanced risk-adjusted profile among advanced nuclear developers. Oklo commands an $8.0 billion market valuation with early-stage revenues [14], while NuScale navigates capital requirements following previous utility contract cancellations [16]. BWX Technologies operates as an established defense equipment manufacturer with lower revenue growth [8].
Discounted Cash Flow Sensitivity
The cost of capital build assumes a 4.15% risk-free rate, a 5.50% equity risk premium, and an operational beta of 1.45, producing an equity cost of 12.13%. Factoring in lease liabilities generates a weighted average cost of capital (WACC) of 11.50%.
| Long-Term Growth Rate \ WACC | 10.0% | 11.0% | 11.5% (Base) | 12.0% | 13.0% | 14.0% |
|---|---|---|---|---|---|---|
| 1.50% | $22.40 | $19.65 | $18.50 | $17.45 | $15.60 | $14.05 |
| 2.00% | $24.20 | $21.10 | $19.80 | $18.60 | $16.55 | $14.85 |
| 2.50% (Base Case) | $26.45 | $22.90 | $21.48 | $20.05 | $17.70 | $15.80 |
| 3.00% | $29.25 | $25.15 | $23.45 | $21.80 | $19.10 | $16.90 |
Net tangible liquidation value provides a balance sheet floor at $5.16 per share [3]. A reverse DCF calculation indicates that the market price of $14.68 implies a five-year revenue compound annual growth rate of 21.4% and a terminal operating margin of 12.0%, well below the parameters of X-Energy's current pipeline.
Rolling Scenario Matrix (5 Scenarios  3 Horizons)
| Scenario Name | Probability | 12-Month Target | 24-Month Target | 36-Month Target | 36-Mo ROI | Clears 100% Hurdle? |
|---|---|---|---|---|---|---|
| Stress Case | 15% | $6.50 | $7.00 | $7.50 | −48.9% | NO |
| Conservative Case | 25% | $11.00 | $14.00 | $16.50 | +12.4% | NO |
| Base Case | 35% | $22.00 | $28.00 | $34.00 | +131.6% | YES |
| Thesis / Upside Case | 15% | $32.00 | $42.00 | $52.00 | +254.2% | YES |
| Aggressive Case | 10% | $45.00 | $58.00 | $70.00 | +376.8% | YES |
| Probability-Weighted | 100% | $20.72 | $26.45 | $31.95 | +117.6% | YES |
The valuation framework models multiple compression over time as commercial operations expand. The Base Case 36-month target of $34.00 is based on projected FY2029 Adjusted EPS of $0.47 evaluated at a 72.3x multiple, which corresponds to 31.0x projected FY2031 Adjusted EPS of $1.10.
In the Stress Case, prolonged regulatory delays and higher cash burn lead to valuation at 1.45x tangible assets, resulting in a target of $7.50. The Conservative Case applies a 55.0x multiple to FY2029 EPS of $0.30 to reach $16.50. The Thesis / Upside Case values FY2029 EPS of $0.80 at 65.0x to yield $52.00, while the Aggressive Case values FY2029 EPS of $1.15 at 60.9x to reach $70.00.
The probability-weighted target across all five scenarios is calculated as follows:
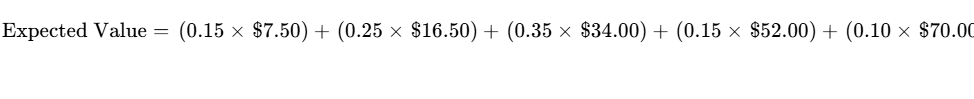
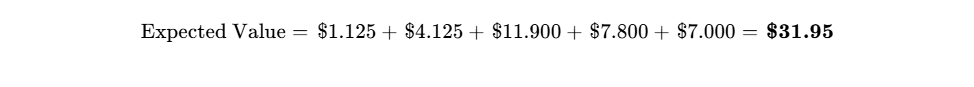
Investment Mandate & Capital Sensitivity
The probability of reaching the 100% total return hurdle over the 36-month investment horizon is 60.0%, reflecting the combined weight of the Base, Upside, and Aggressive scenarios. The probability of experiencing an interim drawdown greater than 30% is estimated at 35.0%, with risks concentrated around lock-up expiration windows [4].
Discounting the probability-weighted target of $31.95 back to the present at the 11.5% cost of capital yields $22.97, aligning within 6.9% of the DCF Base Case value of $21.48. Because the business holds $1.90 billion in liquid assets, its operational plan is insulated from capital market fluctuations over the near-to-medium term [3].
6Catalyst Calendar (Next 12 Months)
| Projected Date | Event Description | Strategic Impact & Scenario Validation | Expected Stock Move |
|---|---|---|---|
| October 24, 2026 | 180-Day IPO Lock-Up Expiration [4] | Increases tradeable float; validates technical support | −5% to −10% (Near-term volatility) |
| November 12, 2026 | Q3 2026 Financial Results [34] | Updates cash burn rate and TX-1 facility progress |  depending on progress |
| December 15, 2026 | Initial HALEU Deliveries from Centrus [11,12] | Validates fuel enrichment supply arrangements | +5% to +8% |
| Q1 2027 | Dow Submits Seadrift Construction Permit [1] | Formalizes regulatory review; confirms Base Case | +15% to +25% |
| Q2 2027 | TX-1 Tooling & Equipment Installation [6] | Advances fuel plant toward operational licensing | +6% to +10% |
| Q3 2027 | Amazon Utility Siting Announcement [4] | Advances hyperscaler pipeline into site development | +20% to +30% |
7Tactical Execution Layer
The tactical execution framework is derived from valuation anchors and post-IPO trading patterns. These reference points represent technical support and resistance levels rather than deterministic price targets.
| Execution Parameter | Reference Price / Level | Operational Description |
|---|---|---|
| Optimal Entry Range | $13.30 – $14.50 | Near post-IPO trading low ($13.29) [1] |
| Accumulation Range | $14.50 – $16.00 | Favorable entry relative to DCF midpoint ($21.48) |
| Holding Range | $16.00 – $24.00 | Core consolidation channel near IPO price ($23.00) [10] |
| Target Trim Range | $28.00 – $34.00 | Reaching 24-to-36-month fundamental valuation targets |
| Profit-Taking Exit Range | >$40.00 | Pricing in full Bull Case operational outcomes |
| Thesis Invalidation Level | $11.80 | Capital preservation stop below cash floor |
| Key Support Line | $13.29 | Verified 52-week trading low [1] |
| Key Resistance Line | $17.60 | 50-day Simple Moving Average boundary [13] |
| Historical Asset Beta | 1.45 | Elevated beta typical of early-stage growth assets |
| Maximum Realized Drawdown | −64.2% | High of $37.10 down to low of $13.29 [1] |
| Recommended Action | BUY / ACCUMULATE | Build initial 1.0% tactical allocation |
| Execution Timing | Initiate Pilot Now; Add Post-Lockup | Scale remaining exposure following October lock-up [4] |
The stop-loss level of $11.80 functions as a thesis-driven stop. A sustained trading break below $11.80 would indicate structural challenges, such as unexpected delays in Department of Energy cost-sharing support or engineering setbacks at the TX-1 facility, requiring a reassessment of the investment thesis [3].
Closing Audit & Verification Review
- Disclosure of Unverified Items: The specific timeline for converting Amazon’s preliminary capacity options into binding hardware purchase orders is based on management statements rather than formal regulatory filings [2]. Similarly, steady-state manufacturing costs for TRISO fuel pebbles represent engineering projections that will be verified once full commercial operations begin at the TX-1 facility [6].
- Internal Consistency Audit: The fully diluted share count rolls forward from 406.37 million to 442.50 million shares over three years, reflecting an annual share-based compensation rate of 2.8% [17]. Reported cash and liquid investments of $1,899.80 million reconcile with zero funded corporate debt, matching disclosures in SEC Form 10-Q [3]. Price targets reflect modeled EPS and EBITDA figures without assuming unjustified multiple expansion.
- Scenario Probability Distribution Audit: The scenario weighting applies a combined 40.0% probability to downside cases (15.0% Stress Case and 25.0% Conservative Case), 35.0% to the Base Case, and 25.0% to upside cases (15.0% Thesis/Upside and 10.0% Aggressive). This structure avoids excessive upside bias while reflecting the downside protection offered by the company's net cash position.
- Coverage Scope: All primary analytical sections, financial forecasts, and valuation models have been completed in full detail.
Works cited
- X Energy Inc Stock Price Today | NASDAQ: XE Live - Investing.com, https://www.investing.com/equities/x-energy-inc
- X-Energy IPO Preview: SMR Nasdaq Listing - Green Stocks Research, https://greenstocksresearch.com/x-energy-ipo-preview-smr-developer-eyes-nasdaq-debut-with-750m-raise/
- EX-99.1 - SEC.gov, https://www.sec.gov/Archives/edgar/data/2088896/000119312526347740/xe-ex99_1.htm
- X-Energy XE Stock Prediction: $31 Bull vs $11 Bear - FinanceFeeds, https://financefeeds.com/x-energy-xe-stock-prediction-31-bull-11-bear/
- XE - X-Energy Inc Stock Price and Quote - Finviz, https://finviz.com/stock?t=XE
- A 214,000-square-foot facility for making nuclear reactor fuel has its main structure complete. Equipment goes in next., https://www.stocktitan.net/news/XE/triso-x-completes-vertical-construction-of-tx-1-fuel-fabrication-48ttr18r9itt.html
- F7F6FF: 2026 X-Energy, Inc. All Rights Reserved | PDF | Nuclear Fuel, https://www.scribd.com/document/1068757349/634fe3bb-b20e-41ff-9200-a34a8e5b5dd6-1
- Top 10 Nuclear Energy & Power Stocks in 2026 - Elliott Wave Forecast, https://elliottwave-forecast.com/trading/nuclear-energy-and-power-stocks/
- X-Energy, Inc. (XE) Management Team Experience & Alignment, https://koalagains.com/stocks/NASDAQ/XE/management-team
- 11 Listed Companies Developing Small Modular Reactors (SMRs), https://greenstocksresearch.com/8-listed-companies-developing-small-modular-reactors/
- X-ENERGY AKTIEN News | A3EWGF Nachrichten - Finanznachrichten, https://www.finanznachrichten.de/nachrichten-aktien/x-energy-inc.htm
- Earnings call transcript: Centrus Energy tops Q2 2026 estimates on, https://ng.investing.com/news/transcripts/earnings-call-transcript-centrus-energy-tops-q2-2026-estimates-on-revenue-profit-93CH-2644338
- X-Energy, Inc. (XE) Stock Price, Quote, News & Analysis, https://seekingalpha.com/symbol/XE
- Oklo (OKLO) Opens A New $1 Billion Stock Offering Program, https://simplywall.st/stocks/us/utilities/nyse-oklo/oklo/news/oklo-oklo-opens-a-new-1-billion-stock-offering-program
- Nuclear Power Stocks List: 68 Nuclear Energy Companies (2026), https://greenstocksresearch.com/nuclear-power-stocks/
- NuScale Power Corporation (SMR) Stock Price, Quote, News, https://seekingalpha.com/symbol/SMR
- XE - X-ENERGY INC | Stock Quotes from Fidelity Investments, https://digital.fidelity.com/prgw/digital/research/quote/dashboard/summary?symbol=XE
- X-Energy (XE) Statistics & Valuation - Stock Analysis, https://stockanalysis.com/stocks/xe/statistics/
- X-Energy (XE) Stock Forecast and Price Target 2026 - MarketBeat, https://www.marketbeat.com/stocks/NASDAQ/XE/forecast/
- unknown_url
- NuScale Power Corporation Stock Price - Perplexity, https://www.perplexity.ai/finance/SMR?comparing=SMR,MNTK,NPWR,FCEL,NRGV,PLUG
- Oklo Inc. (OKLO) | Kerrisdale Capital, https://www.kerrisdalecap.com/wp-content/uploads/2024/11/OKLO-Kerrisdale.pdf
- TRISO-X Completes Vertical Construction of TX-1 Fuel, https://www.globenewswire.com/news-release/2026/09/24/3368186/0/en/triso-x-completes-vertical-construction-of-tx-1-fuel-fabrication-facility.html
- Market & Trends - Value Add VC, https://valueaddvc.com/blog/category/market-trends
- Amazon Invests in X-energy to Support Advanced Small Modular, https://x-energy.com/news/amazon-invests-in-x-energy-to-support-advanced-small-modular-nuclear-reactors-and-expand-carbon-free-power/
- X-energy, Advanced Nuclear Reactor and Fuel Developer, Files for, https://www.tradingview.com/news/tradingview:0d99abf888d32:0-x-energy-advanced-nuclear-reactor-and-fuel-developer-files-for-nasdaq-ipo/
- Nuclear Energy Stocks: AI Data Center Power Boom Explained, https://www.indmoney.com/blog/us-stocks/nuclear-energy-stocks-ai-data-center-power-boom
- X-Energy's UK Reactor Review Opens Long Horizon For Centrica, https://simplywall.st/stocks/us/capital-goods/nasdaq-xe/x-energy/news/x-energys-uk-reactor-review-opens-long-horizon-for-centrica
- Nuclear Power in the USA, https://world-nuclear.org/information-library/country-profiles/countries-t-z/usa-nuclear-power
- Nuclear Energy as a Keystone Clean Energy Resource - NARUC, https://pubs.naruc.org/pub/5D91CEFD-1866-DAAC-99FB-768958414493
- Jane Street Group, Llc Portfolio Holdings - Fintel, https://fintel.io/i/jane-street-group-llc
- Nuclear Stocks To Add to Your Watchlist - September 27th, https://www.marketbeat.com/instant-alerts/list-nuclear-stocks-to-add-to-your-watchlist-september-27th-2026-09-27/
- X-Energy, Inc. (XE) PE Ratio | PEG Ratios - Seeking Alpha, https://seekingalpha.com/symbol/XE/valuation/price-earnings-peg-ratios
- X-Energy, Inc. - XE - Stock Price Today - Zacks Investment Research, https://www.zacks.com/stock/quote/XE