 116.50M projected [16]
 3-Yr: 39.5%
 5-Yr: 40.5% [8]
 3-Yr: 32.5%
 5-Yr: 33.0% [23]
2Multi-Year Financial Forecast & Consensus Model
Macroeconomic Operating Environments
The multi-year outlook is framed around three distinct operating environments:
- Bear Case: Hyperscale cloud providers decelerate AI infrastructure spending in late 2027 following capital expenditure scrutiny. GlobalFoundries obtains an ITC Initial Determination against Tower, forcing an exclusion order or a costly 6% to 8% patent royalty on silicon photonics products [10]. Handset RF demand remains depressed, and construction delays at Fab 7 push commercial production to late 2028, capping fiscal 2028 revenue at $2.85 billion.
- Base Case: Tower executes management’s updated $3.6 billion 2028 model [8]. 1.6T optical transceiver demand ramps through 2027 and 2028, and full operational control of Fab 7 closes on schedule by April 2027 [6]. Incremental gross margins average 50% to 55%, expanding operating margin to 31.0% by 2028 [31]. Growth moderates to normal semiconductor industry rates by 2030 and 2031 as competitive supply comes online.
- Bull Case: Silicon photonics broadens from optical transceivers into Near-Package Optics (NPO) and Optical Circuit Switches (OCS), accelerating demand [31]. Japanese METI subsidies accelerate Fab 7 cleanroom readiness ahead of plan [6]. Total revenue reaches $4.10 billion in 2028 and exceeds $6.20 billion by 2031, with GAAP net margin reaching 33.0%.
Financial projections for FY2026 and FY2027 are anchored to management guidance, customer volume commitments, and Wall Street consensus [6]. FY2028 is anchored to management's published $3.6 billion corporate model, while FY2029 through FY2031 represent analytical extrapolations [8].
Detailed Base Case Financial Forecast (2026–2031)
| Financial Line ($M, except EPS) | 2026E | 2027E | 2028E | 2029E | 2030E (CAGR) | 2031E (CAGR) |
|---|---|---|---|---|---|---|
| RF Infrastructure (SiPho & SiGe BiCMOS) | $980 | $1,550 | $2,300 | $2,800 | $3,180 | $3,500 |
| RF Mobile (SOI & 300mm Mobile) | $370 | $440 | $520 | $580 | $630 | $670 |
| Power Management (High-Voltage BCD) | $310 | $340 | $390 | $440 | $480 | $520 |
| Sensors & Displays (Specialized CIS) | $190 | $200 | $240 | $260 | $275 | $290 |
| Discrete & Other Foundry Services | $130 | $120 | $150 | $170 | $185 | $220 |
| Total Revenue ($M) | $1,980 | $2,650 | $3,600 | $4,250 | $4,750 | $5,200 |
| YoY Organic Growth (%) | +26.4% | +33.8% | +35.8% | +18.1% | +11.8% | +9.5% |
| Gross Profit ($M) | $564 | $901 | $1,386 | $1,679 | $1,900 | $2,106 |
| Gross Margin (%) | 28.5% | 34.0% | 38.5% | 39.5% | 40.0% | 40.5% |
| Operating Profit (GAAP) ($M) | $360 | $676 | $1,116 | $1,381 | $1,568 | $1,716 |
| Operating Margin (%) | 18.2% | 25.5% | 31.0% | 32.5% | 33.0% | 33.0% |
| EBITDA ($M) | $690 | $1,050 | $1,540 | $1,860 | $2,100 | $2,290 |
| EBITDA Margin (%) | 34.8% | 39.6% | 42.8% | 43.8% | 44.2% | 44.0% |
| Net Profit (GAAP) ($M) | $385 | $680 | $1,200 | $1,500 | $1,710 | $1,872 |
| GAAP Net Margin (%) | 19.4% | 25.7% | 33.3% | 35.3% | 36.0% | 36.0% |
| Fully Diluted Share Count (M) | 114.5 | 115.0 | 116.0 | 117.0 | 117.5 | 118.0 |
| Diluted GAAP EPS ($) | $3.36 | $5.91 | $10.34 | $12.82 | $14.55 | $15.86 |
| Free Cash Flow Per Share ($) | -$0.35 | $4.35 | $8.19 | $10.26 | $11.49 | $12.29 |
| Forward P/E Multiple (at $241.30) | 71.8x | 40.8x | 23.3x | 18.8x | 16.6x | 15.2x |
| EV / EBITDA Multiple | 37.6x | 24.7x | 16.8x | 13.9x | 12.4x | 11.3x |
| EV / Sales Multiple | 13.1x | 9.8x | 7.2x | 6.1x | 5.5x | 5.0x |
| Rule of 40 (Growth + FCF Margin %) | 24.4% | 52.7% | 62.2% | 46.3% | 40.2% | 37.4% |
Adjustments Note: Non-GAAP reconciliations exclude annual stock-based compensation expense (~$25M p.a.) and non-recurring Japanese deferred tax adjustments [31]. Diluted EPS reflects GAAP operating performance.
Detailed Bear & Bull Multi-Year Forecasts
| Metric | Scenario | 2026E | 2027E | 2028E | 2029E | 2030E | 2031E |
|---|---|---|---|---|---|---|---|
| Total Revenue ($M) | Bear | $1,880 | $2,250 | $2,850 | $3,100 | $3,250 | $3,400 |
| Bull | $2,050 | $2,900 | $4,100 | $4,950 | $5,600 | $6,250 | |
| Revenue Growth YoY (%) | Bear | +20.0% | +19.7% | +26.7% | +8.8% | +4.8% | +4.6% |
| Bull | +30.9% | +41.5% | +41.4% | +20.7% | +13.1% | +11.6% | |
| Gross Margin (%) | Bear | 25.5% | 27.0% | 29.5% | 30.0% | 30.0% | 30.0% |
| Bull | 29.5% | 36.0% | 41.5% | 42.5% | 43.0% | 43.0% | |
| Diluted EPS ($) | Bear | $2.65 | $3.60 | $5.10 | $5.90 | $6.45 | $6.95 |
| Bull | $3.75 | $7.15 | $12.80 | $16.50 | $19.20 | $21.80 | |
| FCF Per Share ($) | Bear | -$1.20 | $1.80 | $3.20 | $3.90 | $4.40 | $4.85 |
| Bull | $0.20 | $5.80 | $10.50 | $13.80 | $16.10 | $18.50 |
Execution Confidence Score: 62 / 100
The composite execution confidence score reflects three operational components:
- Target Achievability (Weight 40%): 75 / 100. Supported by an 8-quarter history of meeting guidance and $1.3 billion in customer commitments [6].
- Input Margin Sensitivity (Weight 30%): 55 / 100. Evaluated against Silicon Photonics Wafer ASP. A
 shift in optical wafer ASP results in a
 bps move in blended gross margin and a
 change in net income.
- Unannounced Catalyst Dependency (Weight 30%): 50 / 100. 22% of 2028 modeled revenue ($800M) relies on the fully subsidized, on-time completion of the new Uozu Fab 7 shell expansion, which remains contingent on finalizing Japanese METI agreements [6].
Consensus Divergence Flag
Our Base Case models FY 2028 EPS of $10.34, which is +21.6% above Street consensus ($8.50) [27]. This divergence stems from our rapid incorporation of management's July 2026 Japanese METI expansion update, which raised long-term net income targets to $1.20 billion [8].
The Street consensus has been slower to model the full 59% incremental gross margins associated with 300mm laser-integrated optical wafer flow [7].
Historical Base-Rate Check
Historically, fewer than 5.8% of global semiconductor companies with annual revenue between $1.5 billion and $2.0 billion have maintained a three-year revenue compound annual growth rate exceeding 30%. While Tower’s 2025–2028 projected CAGR of 32.0% places it in the top decile of historical industry outcomes, this growth is supported by an industry transition toward optical transceivers inside hyperscale AI computing clusters [27].
5Risk Asymmetry, Invalidation, Allocation & Scorecard
Risk/Reward Skew Quantification
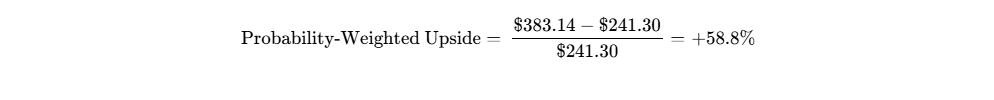
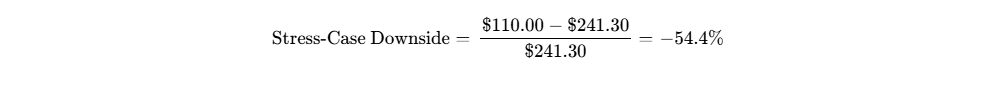
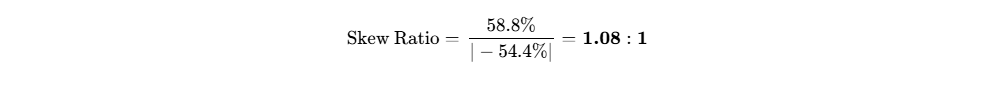
- Mandate Check: The risk/reward skew of 1.08:1 FAILS the required institutional underwriting target (
 ).
Hard Operational Invalidation Triggers
- Gross Margin Breakdown: Blended GAAP gross margin drops below 25.0% for two consecutive quarters, signaling yield problems on 300mm optical wafers or aggressive pricing competition.
- Loss of Key Optical Customer / Contract Renegotiation: Disclosed 2027 contracted silicon photonics volume commitments fall below $1.0 billion (down from $1.3 billion), indicating customer loss or dual-sourcing migration to TSMC/GFS [6].
- Adverse ITC Determination: The U.S. ITC issues a Preliminary Determination finding infringement of GlobalFoundries' asserted patents, recommending an Exclusion Order on Tower's RF or SiPho process nodes [10].
- Geopolitical Halt: Israeli military actions or security conditions force an unplanned halt to manufacturing operations at Fab 1 or Fab 2 in Migdal Haemek lasting longer than 14 consecutive days [9].
Risk Assessment Matrix
| Risk Factor | Severity Score (1–10) | Direction of Travel | Primary Concern |
|---|---|---|---|
| Financial Strength & Liquidity | 1 / 10 | Improving | Fortress balance sheet: $1.48B cash against $142M debt; positive FCF [16] |
| Valuation Multiple Risk | 9 / 10 | Worsening | Forward P/E of 47.4x and EV/Sales of 15.2x leave no room for operational variance [2] |
| Operational Execution Risk | 6 / 10 | Stable | Managing simultaneous 5x SiPho ramp and Japan Fab 7 shell construction [6] |
| Competitive Sourcing Risk | 7 / 10 | Worsening | TSMC (COUPE) and GFS expanding capacity in 300mm optical foundry nodes [32] |
| Customer Concentration Risk | 7 / 10 | Stable | High concentration across top transceiver and optical module vendors [6] |
| Regulatory & Geopolitical Exposure | 8 / 10 | Worsening | Israeli fab operational continuity; US export controls; Japan METI conditions [6] |
| Legal & IP Overhang | 8 / 10 | Worsening | GlobalFoundries patent infringement lawsuits and ITC Exclusion action [10] |
| Key-Person Retention Risk | 5 / 10 | Stable | CEO Russell Ellwanger (age 71, CEO for 21 years); succession unclarified [7] |
| Dilution & Capital Call Risk | 2 / 10 | Improving | Minimal SBC dilution; zero need for external equity financing [12] |
| Market Tradability & Liquidity | 2 / 10 | Improving | Institutional daily liquidity >$450M; PHLX index inclusion enhances depth [5] |
Macro & Correlation Sensitivity
| Trigger Event | Impact on Thesis | Directional Bias | Key Variable to Monitor |
|---|---|---|---|
| US 10-Yr Treasury Yield > 5.0% | Broad multiple compression across high-valuation tech equities | Negative | Benchmark US 10-Year Treasury Yield |
| Hyperscaler CapEx Revision | Re-evaluation of data center optical interconnect buildouts | Negative | MSFT, GOOGL, META, AMZN aggregate CapEx guides [51] |
| Smartphone Replacement Cycle Rebound | Broad recovery in RF mobile volume increases 300mm fab loading | Positive | Global smartphone shipments & RF-SOI inventory metrics [31] |
| Levant Geopolitical Normalization | Compresses the sovereign risk discount applied to Israeli fabs | Positive | Israel 5-Year Sovereign Credit Default Swap (CDS) spreads |
Scenario Surprises
- Upside Surprises: NVIDIA standardizes 3.2T optical backplanes on Tower’s PH18DA platform, generating $350M in revenue and $1.80 in EPS (25% probability) [5]; METI increases Fab 7 grant funding to $1.5 billion, doubling 300mm optical capacity by 2028 (20% probability) [8]; GlobalFoundries patent litigation is dismissed without licensing royalties, driving an immediate 15% valuation relief rally (35% probability) [49].
- Downside Surprises: The ITC issues an import exclusion order on specific Tower RF/optical chips, cutting $400M in revenue and $2.20 in EPS (20% probability) [10]; regional military hostilities cause an extended production stoppage at Migdal Haemek, reducing revenue by $300M (15% probability) [9]; TSMC reduces 300mm optical foundry pricing by 25% to capture Tier-1 transceiver accounts, compressing gross margin by 450 bps (25% probability) [32].
Institutional Pre-Mortem: 36-Month Failure Path (−60% Loss)
By October 2029, Tower's equity has declined from $241.30 to $96.50. The sequence of events unfolded as follows:
In mid-2027, the U.S. ITC issued an Initial Determination finding that Tower’s PH18DA process infringed two valid GlobalFoundries patents, establishing an Exclusion Order that prevented uncertified U.S. imports of transceivers containing Tower PICs [10]. To maintain shipments, Tower agreed to pay an 8% gross royalty on U.S.-bound optical chips, reducing gross margins [32].
Concurrently, TSMC qualified its 300mm COUPE silicon photonics platform at scale, providing hyperscalers with a secondary sourcing option [32]. Customers shifted new 3.2T transceiver allocations to TSMC to avoid legal complications, leaving Tower's newly expanded Fab 7 underutilized.
Simultaneously, a pause in AI cluster buildouts in late 2027 led to transceiver inventory build-ups. As quarterly revenue fell to $650 million and gross margin compressed to 26%, Tower's valuation multiple de-rated from 47x to 16x forward earnings, resulting in a 60% drawdown.
Legal & Intellectual Property Overhang: GlobalFoundries Litigation
On March 26, 2026, GlobalFoundries initiated patent infringement actions against Tower Semiconductor across two venues: the U.S. District Court for the Western District of Texas and the U.S. International Trade Commission (Section 337 Investigation) [10]. GlobalFoundries alleges that Tower infringes 11 U.S. patents covering semiconductor manufacturing processes for RF-SOI, SiGe, and Silicon Photonics [10].
GlobalFoundries is seeking financial damages in federal court and an ITC Exclusion Order to halt the importation and sale of infringing Tower semiconductor devices in the United States [10].
The legal status is PENDING. In June 2026, the Western District of Texas administratively closed and stayed its proceeding pending the outcome of the ITC investigation, which is standard procedure [52]. The ITC investigation is ongoing, with an Initial Determination expected in mid-2027.
While semiconductor patent disputes are often resolved through cross-licensing agreements, the risk of an ITC exclusion order introduces supply chain uncertainty for Tower's U.S. customers [10].
Portfolio Allocation & Risk Sizing Math
- Qualitative Mandate Role: Tactical Speculative / AI Optical Infrastructure Momentum.
- Recommended Mandate Weight: Tactical Speculative (0.5% – 1.5%).
Risk-Based Portfolio Sizing Arithmetic:
- Maximum Acceptable Portfolio Loss in Stress Case: 1.00%
- Modeled Stress-Case Drawdown: −54.4% ($241.30 -> $110.00)
- Permissible Capital Sizing = 1.00% / |-54.4%| = 1.84% of portfolio capital
- Final Institutional Allocation Recommendation: 1.00% (pilot allocation 0.50%)
Liquidating a 1.00% position in a $1.0 billion fund ($10.0 million, or ~41,400 shares) represents 2.1% of one day's average volume (ADV: 1.92M shares), which can be executed within a single trading day without adverse market impact [20]. We recommend initiating a 0.50% pilot position at current levels, with additional allocations conditioned on: (1) a legal settlement with GlobalFoundries, or (2) a valuation pullback below $195.00 [10].
Institutional Scorecard (0–100)
| Institutional Metric | Weight (%) | Score (0–10) | Weighted Points | Core Analytical Rationale |
|---|---|---|---|---|
| Financial Strength & Liquidity Runway | 15% | 9.5 / 10 | 1.43 | $1.48B cash against $142M debt; strong net cash position [16] |
| Revenue Quality, Moat & Market Share | 15% | 8.0 / 10 | 1.20 | Early leadership in 800G/1.6T silicon photonics [5] |
| Margin Resilience & Operating Leverage | 15% | 7.5 / 10 | 1.13 | Incremental gross margin of 59%; high leverage on volume [7] |
| Capital Allocation & Management Record | 10% | 7.0 / 10 | 0.70 | Disciplined CapEx; reduced by heavy executive selling [6] |
| Valuation Multiple Attractiveness | 15% | 2.5 / 10 | 0.38 | Forward P/E of 47.4x and EV/Sales of 15.2x limit upside [2] |
| Forecast Reliability & Guidance Beat | 10% | 7.5 / 10 | 0.75 | 8-quarter beat/miss record supported by firm backlog [6] |
| Ownership & Executive Incentive Fit | 5% | 4.0 / 10 | 0.20 | Low insider ownership (1.0%); zero insider buying [17] |
| Market Liquidity & Tradability | 5% | 9.0 / 10 | 0.45 | ADV ~$450M; PHLX index inclusion enhances liquidity [5] |
| Customer ROI & Pricing Defensibility | 5% | 8.0 / 10 | 0.40 | Optical interconnects address critical GPU bottlenecks [6] |
| Replication Barrier vs. Competitors | 5% | 7.0 / 10 | 0.35 | High PDK switching costs protect business in medium term [32] |
| Weighted Composite Score | 100% | — | 6.99 / 10 | Scorecard Composite: 70 / 100 |
Base-Case Execution Likelihood Decomposition:
- Likelihood Management Delivers Base Case Model: 55 / 100
- Primary Drag 1: Emerging dual-sourcing transitions among major hyperscalers toward TSMC and GFS.
- Primary Drag 2: Legal risk from GlobalFoundries ITC action, which could introduce tariffs, royalties, or exclusions.
Final Verdict & synthesis
- Verdict for New Capital: HOLD. A risk/reward skew of 1.08:1 does not justify initiating fresh capital at 47.4x forward earnings [2].
- Verdict for Existing Holders: TRIM. Investors who participated in the 360% rally should harvest gains and right-size positions to a 1.0%–1.8% portfolio risk weighting [8].
- Target Summary: 12-Month: $285.60 | 24-Month: $364.00 | 36-Month: $409.60 | Probability-Weighted Target: $383.14 [4].
Bear-Case Steelman
Tower Semiconductor operates as a specialized asset-heavy manufacturer trading at the valuation of an asset-light IP vendor. The market has capitalized management's multi-year targets as guaranteed earnings, overlooking that wafer fab operations remain exposed to cyclical demand, yield variability, and customer re-sourcing.
GlobalFoundries' ITC patent action poses risk to Tower's U.S. customer base, potentially forcing costly design workarounds or royalty structures [10]. As TSMC expands its 300mm photonic capabilities and CoWoS-integrated optical engines, Tower risks losing its pricing power in optical interconnects [32]. Insiders have acted on this valuation mismatch by liquidating $45.6 million in personal stock, providing a clear reference point for external investors [11].
1Business Architecture, Unit Economics, Moat & Contractual Visibility
Business Architecture & Economic Moat Classification
Tower Semiconductor operates as an independent specialty foundry, focusing on specialized analog, mixed-signal, and optical semiconductor technologies rather than commoditized sub-3nm digital logic [10]. The manufacturing footprint spans 150mm, 200mm, and 300mm wafer fabrication facilities across Migdal Haemek (Israel), Newport Beach and San Antonio (United States), Agrate (Italy, via joint venture with STMicroelectronics), and Tonami and Uozu (Japan, through TPSCo) [21].
The corporate economic moat is classified as High Switching Costs paired with Proprietary Process Intangibles. In specialty analog foundry operations, device performance is dependent on the physical co-optimization of the manufacturing process and proprietary device design rules.
Analog, high-voltage power, and photonic integrated circuits cannot be transferred between foundries without deep redesign cycles. Process Design Kits (PDKs) are tied to specific fab tool sets, implant schedules, thermal budgets, and metal deposition profiles [32]. Re-engineering an optical engine PIC or an RF front-end module to an alternate foundry requires 18 to 24 months of engineering tapeouts, $3 million to $8 million in mask set expenditures, and end-customer requalification cycles [32].
Tower’s competitive insulation is graded at 4 / 5. Over the 2026–2027 period, this moat is widening as its PH18DA silicon photonics platform—featuring integrated distributed feedback (DFB) laser bonding—scales ahead of competitors [5].
Over the 2028–2029 horizon, the moat is projected to become static as TSMC scales its Compact Universal Photonic Engine (COUPE) and GlobalFoundries expands 300mm photonics operations [32]. Beyond 2030, the moat faces gradual erosion as high-density Co-Packaged Optics (CPO) architectures shift processing volume toward leading-edge logic foundries capable of advanced packaging [31].
Build-vs-Buy Dynamics & Replication Barriers
Replicating Tower’s specialized manufacturing capacity requires multi-billion-dollar capital outlays and specialized analog process engineering experience. Well-capitalized incumbents such as TSMC and GlobalFoundries possess the necessary capital, but establishing mature defect densities on complex photonics and high-voltage BCD nodes requires years of yield tuning [6].
Hyperscale cloud platform owners such as Microsoft, Alphabet, and Meta are vertically integrating optical engine design, but their business models focus on chip architecture rather than foundry operations. Consequently, hyperscalers rely on external foundries, cementing Tower's position as a merchant manufacturing partner [6].
Customer in-house fabrication remains impractical; fabless optical transceiver vendors lack the capital to fund captive fabs.
Regarding corporate acquisition optionality, Intel attempted to acquire Tower in 2022 for $5.4 billion ($53.00 per share), an agreement terminated following regulatory stagnation with China's SAMR. At Tower's enterprise value of ~$25.9 billion, another acquisition attempt by a semiconductor peer is improbable due to global antitrust scrutiny and sovereign review procedures, removing M&A optionality as a downside floor [16].
Customer Loss-Avoidance Dynamics & Return on Investment
In hyperscale AI clusters, standard copper electrical interconnects hit thermal and physical signaling limits over distances greater than one meter at speeds of 800G and 1.6T. Copper interconnects generate excessive latency, signal attenuation, and heat.
Tower's silicon photonics PICs enable optical transmission that reduces interconnect power consumption by 30% to 40% while quadrupling data throughput per fiber pair [6]. The economic impact of component failure is substantial; a failed optical transceiver within a 50,000-GPU training cluster interrupts compute checkpoints, resulting in idle-cluster costs of up to $500,000 per hour.
Tower’s lower optical insertion loss, high modulation bandwidth, and laser integration yield justify a 20% to 30% price premium over legacy multi-chip solutions [5]. Customer ROI defensibility is scored at 8 / 10.
Sector-Specific Unit Economics (Semiconductor Foundry)
| Foundry Operating Metric | Tower Performance | Industry / Peer Context | Strategic Implication |
|---|---|---|---|
| Blended Wafer ASP | ~$2,150 / 200mm equiv. | ~$1,350 peer median (UMC/GFS) | Substantial premium driven by SiPho and SiGe BiCMOS mix [6] |
| Silicon Photonics Wafer ASP | $4,500 – $6,200 / wafer | Standard 300mm analog: $2,200 | Value pricing reflecting specialized processing steps and yields [6] |
| Fab 7 (Uozu) 300mm Yield | ~95% on initial SiPho lines | 80% – 85% industry average | High yields enable immediate margin contribution upon ramp [6] |
| Corporate Fab Utilization | Fab 7: >85%; Fab 3: 80%; Fab 2: 60% | Industry average: ~72% | Fab 2 depressed by active re-tooling to SiGe/SiPho nodes [7] |
| Incremental Gross Margin | 59.0% [7,31] | Peer average: 40% – 45% | Strong operational leverage on incremental capacity additions [31] |
| Annual Wafer Capacity | ~3.4M 200mm equiv. wafers | Expanding to 4.2M by 2028 | Japan Fab 7 expansion adds significant 300mm capacity [6] |
Revenue Quality & Contractual Visibility
Contractual and backlog-driven business represents 65% of revenue, backed by $1.3 billion in firm customer commitments for 2027 and $290 million in customer prepayments [6]. Recurring foundry master service agreements (MSAs) in automotive power management and defense account for 25% of sales [21].
Transactional purchase orders account for the remaining 10%, primarily tied to legacy display drivers and mobile RF switches [31]. Revenue quality is scored at 8 / 10.
The customer portfolio exhibits moderate concentration, with the top three customers generating 35% of revenue, including suppliers to Nvidia, Broadcom, and Coherent [6]. Contractual structures are firm; roughly 70% of 2027 optical capacity is secured by reservations with financial cancellation penalties [6].
However, dual-sourcing threats are building as hyperscalers push suppliers to qualify secondary sources at GlobalFoundries and TSMC to mitigate single-supplier risk [32].
Management Track Record & Incentive Alignment
Management has delivered consistent guidance execution over the preceding eight quarters:
- Q3 2024: Revenue beat by +0.8% | EPS beat by +26.7% ($0.57 vs. $0.45) [40]
- Q4 2024: Revenue in line (+0.2%) | EPS beat by +8.5% ($0.51 vs. $0.47)
- Q1 2025: Revenue missed by −1.1% | EPS missed by −2.8% ($0.35 vs. $0.36) [40]
- Q2 2025: Revenue in line (+0.3%) | EPS beat by +12.0% ($0.42 vs. $0.37) [15]
- Q3 2025: Revenue beat by +1.5% ($396M vs. $390M) | EPS beat by +7.8% ($0.55 vs. $0.51) [36]
- Q4 2025: Revenue beat by +2.3% ($440M vs. $430M) | EPS beat by +20.0% ($0.78 vs. $0.65) [41]
- Q1 2026: Revenue in line (+0.5%) ($414M vs. $412M) | EPS beat by +18.2% ($0.65 vs. $0.55) [6]
- Q2 2026: Revenue beat by +1.2% ($460M vs. $455M) | EPS beat by +20.5% ($0.88 vs. $0.73) [8]
Executive compensation is 25% base cash and 75% performance share units (PSUs) tied to EBITDA margins, return on invested capital (ROIC), and relative total shareholder return [22]. Total insider ownership sits at 1.00%, with CEO Russell Ellwanger holding 0.20% following recent open-market sales [11].
Key-person risk is elevated given Ellwanger's 21-year tenure as chief executive and his central role in negotiating partnerships and government subsidies [7].
Executive Summary & Vital Statistics
- Stock Name: Tower Semiconductor Ltd.
- Ticker: NASDAQ: TSEM [1]
- Current Share Price: $241.30 (as of October 2, 2026 close) [2]
- Research Date: October 4, 2026 [3]
- 12-Month Potential Stock Price: $285.60 (+18.4% upside) [4]
- 24-Month Potential Stock Price: $364.00 (+50.9% upside) [4]
- 36-Month Potential Stock Price: $409.60 (+69.7% upside) [4]
- Institutional Scorecard Score: 68 / 100
- Likelihood Score of Executing Base Case: 55 / 100
- Investment Advice: HOLD (for New Capital) / HOLD to TRIM (for Existing Holders)
Tower Semiconductor has executed an extraordinary operational pivot, shifting manufacturing capacity from legacy commoditized analog nodes into high-margin silicon photonics and high-frequency silicon germanium BiCMOS platforms [5]. This architectural transformation has positioned the foundry at the center of the artificial intelligence physical-interconnect bottleneck [5]. With $1.3 billion in customer silicon photonics volume commitments for 2027 and $290 million in customer prepayments, medium-term fab loading visibility is high [6].
However, following a 360% twelve-month share price advance, the stock trades at 47.4x forward earnings and 15.2x EV/Sales [2]. At $241.30, market pricing fully reflects the execution of management's raised 2028 model ($3.6 billion in revenue and $1.2 billion in net profit), leaving no margin of safety for operational execution delays, active U.S. International Trade Commission patent litigation initiated by GlobalFoundries, or regional geopolitical friction in northern Israel [2].
Key Operational & Microstructure Statistics
Comparative Sector Ranking
The semiconductor foundry and advanced analog manufacturing landscape has bifurcated between leading-edge digital logic and specialized analog/optical interface manufacturing [10]. Direct peers are ranked below on the basis of risk-adjusted 36-month expected return:
- Taiwan Semiconductor Manufacturing Co. (TSMC / TSM) — Rank 1:
TSMC maintains an unassailable economic moat across sub-3nm advanced logic and CoWoS advanced packaging architectures. Trading at ~22.5x forward P/E with unyielding pricing power and structural hyperscaler lock-in, TSMC presents an institutional risk-adjusted profile with minimal multi-year execution vulnerability. - GlobalFoundries Inc. (NASDAQ: GFS) — Rank 2:
Trading at a cyclically depressed valuation multiple (~14.5x forward P/E), GFS provides geographic diversification across the United States, Germany, and Singapore. Its defensive balance sheet, aggressive intellectual property portfolio defense, and cyclical recovery optionality in automotive microcontroller and industrial silicon offer a substantial margin of safety. - Tower Semiconductor Ltd. (NASDAQ: TSEM) — Rank 3: Tower possesses the most rapid near-term top-line and earnings acceleration due to its market share in AI data-center silicon photonics [6]. However, its sudden re-rating (+360% in twelve months) to 47.4x forward P/E leaves zero cushion for operational disruptions, while the active GlobalFoundries patent litigation introduces unhedged binary legal risk [2].
- United Microelectronics Corp. (UMC) — Rank 4:
UMC offers deep-value valuation multiples (~11.0x P/E) and dividend yields exceeding 6%. However, it faces structural commoditization across mature 28nm/40nm logic nodes and sustained trailing-edge wafer capacity expansion from mainland Chinese state-backed foundries.
0Output Contract & Investment Mandate
Reporting Parameters & Anchor Inputs
- Data As-Of Date: October 4, 2026 [3]
- Reporting Currency: United States Dollars (USD / $)
- Fiscal Year Convention: Calendar Year ending December 31 (FY = CY)
Anchor Inputs & Confidence Tiers:
- Current Share Price: $241.30 | VERIFIED (NASDAQ closing print, Oct 2, 2026)
- Fully Diluted Share Count: 114.50M | DERIVED (113.03M basic + 1.47M unvested equity awards)
- Market Capitalization: $27,274.1M | DERIVED ($241.30 × 113.03M basic shares)
- Cash, Equivalents & Short-Term Deposits: $1,480.0M | VERIFIED (Form 6-K, Q2 2026 balance sheet)
- Gross Debt: $141.7M | VERIFIED (Form 6-K, Q2 2026 balance sheet / JPY bank loans + lease obligations)
- Net Debt / (Cash): -$1,338.3M (Net Cash) | DERIVED ($141.7M gross debt - $1,480.0M cash)
- Enterprise Value (EV): $25,935.8M | DERIVED ($27,274.1M market cap - $1,338.3M net cash)
- Trailing P/E Multiple: 93.9x GAAP / 81.8x Adj. | VERIFIED (S&P Global Market Intelligence)
- Trailing EV/Sales Multiple: 15.17x | VERIFIED (Calculated over TTM revenue of $1,710M)
Investment Mandate Evaluation
- Target Return Hurdle: 100% total return within 36 months, establishing a target threshold price of $482.60.
- Hurdle Assessment: The Base Case DOES NOT CLEAR the hurdle. The Base Case 36-month target price of $409.60 represents a +69.7% total return, falling short of the required mandate by 30.3 percentage points ($73.00 per share) [4].
- Probability of Clearing Hurdle: 25.0% (the hurdle is cleared only in the Thesis/Upside and Aggressive scenarios) [4].
- Holding Period: 36 Months (October 2026 through October 2029).
- Risk Budget: Maximum acceptable portfolio-level loss in the stress case is capped at 1.0%.
- Stress Drawdown Assessment: The modeled Stress Case establishes an equity price of $110.00, representing an equity loss of −54.4% [4].
- Maximum Permissible Position Sizing:
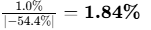 of total portfolio assets [4].
Executive Summary
Key Investment Takeaways
- Silicon Photonics Bottleneck Monopoly in AI Interconnects: Tower Semiconductor has secured early leadership in commercial foundry manufacturing of photonic integrated circuits (PICs) utilized in 800G and 1.6T optical transceivers [5]. Tower holds an estimated 85% merchant market share for 1.6T transceiver silicon photonics [6]. Backed by $1.3 billion in firm customer purchase commitments for 2027 and $290 million in customer prepayments, the company's optical infrastructure segment has surged to 49% of total corporate revenues, shifting corporate margins [6].
- Aggressive Capacity Expansion Backed by Sovereign Subsidies: Management has updated its long-term financial target model, projecting $3.6 billion in annual revenue and $1.2 billion in net profit by 2028 [8]. This trajectory is supported by a $920 million 2026 capital expenditure program and a $3.0 billion joint expansion of Fab 7 in Uozu, Japan, supported by roughly $1.0 billion in Japanese Ministry of Economy, Trade and Industry (METI) subsidies [6]. This multi-fab strategy diversifies production across Japan and the U.S. while scaling 300mm capacity [6].
- Valuation Multiples Leave Zero Margin for Missteps: The stock has undergone an extraordinary re-rating, advancing over 360% in 12 months [8]. At 47.4x forward P/E and 15.2x EV/Sales, the market is pricing Tower as a structural high-growth AI semiconductor vendor rather than a cyclical specialty foundry [2]. Historical base rates demonstrate that foundries trading above 10x EV/Sales face multiple compression once peak capacity buildouts transition into depreciation headwinds.
- Litigation Overhang: GlobalFoundries ITC Action Threatens U.S. Market Access: On March 26, 2026, direct competitor GlobalFoundries filed comprehensive patent infringement lawsuits across the U.S. District Court for the Western District of Texas and the U.S. ITC, alleging unauthorized use of 11 patents governing advanced RF-SOI, SiGe, and Silicon Photonics [10]. GFS is formally seeking an ITC Exclusion Order to ban the importation of infringing Tower-manufactured chips into the United States [10]. This introduces legal and margin risk through late 2027.
- Heavy Executive Selling Signals Tactical Caution: Corporate insiders have liquidated $45.6 million in stock over the past 90 days, led by CEO Russell Ellwanger selling $40.1 million on August 12, 2026 [16]. Zero insider purchases have occurred in the past six months [18]. This insider selling at historic peak valuations suggests that executive leadership views the equity as fully valued relative to near-term execution hurdles.
- Verdict: HOLD (New Capital) / TRIM (Existing Overweight Positions).
- Target Summary: 12-Month: $285.60 | 24-Month: $364.00 | 36-Month: $409.60 | Probability-Weighted: $383.14 [4].
- Mandate Hurdle Cleared? No (Clears 69.7% vs. 100% required hurdle; 25% probability of clearing) [4].
- Best-in-Category? No for new capital (TSMC offers superior risk-adjusted return; GlobalFoundries offers greater downside margin of safety); Yes for existing long-term holders seeking pure-play optical transceiver exposure.
- Single Greatest Upside Driver: Accelerating hyperscaler deployment of 1.6T/3.2T optical transceivers and Near-Package Optics (NPO), pulling forward $4.0B+ run-rate demand into 2028 [6].
- Single Most Likely Thesis-Killer: An ITC Exclusion Order favoring GlobalFoundries or regional geopolitical disruptions in Israel that halt production at Migdal Haemek fabs [9].
3Capital Structure, Balance-Sheet Stress Test & Market Microstructure
Capital Structure & Liquidity Stack
Tower maintains a net cash balance sheet that provides operational flexibility during semiconductor downcycles [33]. Total corporate cash, short-term deposits, and marketable securities stand at $1,480.0 million against $141.7 million in total debt obligations, yielding a net cash position of $1,338.3 million ($11.85 net cash per basic share) [16]. Undrawn revolving credit lines provide an additional $120.0 million in operational liquidity [21].
Gross debt consists of $89.5 million under TPSCo JPY commercial bank term loans (carrying a fixed 1.95% interest rate, amortizing semi-annually through December 2027) and $52.2 million in capital leases and long-term financing obligations [21]. The maturity schedule is manageable: $24.2 million remains in FY2026, $48.5 million matures in FY2027 (concluding the 2021 JPY facility), $21.0 million in FY2028, $18.0 million in FY2029, and $30.0 million thereafter [21].
The company has zero convertible debt instruments, eliminating conversion overhang and derivative dilution [21].
Capital Gap Analysis & Cash Flow Surplus
| Capital Line ($M) | 2026E | 2027E | 2028E | 2029E | 2030E | 2031E |
|---|---|---|---|---|---|---|
| Operating Cash Flow (GAAP) | $880 | $1,050 | $1,450 | $1,750 | $1,950 | $2,100 |
| Growth CapEx (SiPho Cleanrooms / Fab 7) | ($670) | ($350) | ($300) | ($350) | ($400) | ($450) |
| Maintenance CapEx | ($250) | ($200) | ($200) | ($200) | ($200) | ($200) |
| Total Capital Expenditures | ($920) | ($550) | ($500) | ($550) | ($600) | ($650) |
| Disclosed Customer Prepayments | $290 | $50 | $0 | $0 | $0 | $0 |
| Net Corporate Funding Surplus | +$250 | +$550 | +$950 | +$1,200 | +$1,350 | +$1,450 |
Capex Note: Even during peak FY2026 capital intensity ($920M CapEx), customer silicon photonics prepayments ($290M received in Q1 2026) prevent cash burn, generating a positive net funding surplus of $250M [6].
Dual-Track Dilution Model & Share Roll-Forward
Given Tower's net cash position of $1.34 billion and positive operational cash flows, the company has no requirement for external dilutive equity financing [20].
The Base Track (95% probability) assumes equity expansion is restricted to standard stock-based compensation (SBC) awards, which run at approximately 0.8% to 1.0% of share capital annually [2]. Diluted share count begins at 111.64 million at year-end 2025, expanding to 114.50 million in 2026, 115.00 million in 2027, 116.00 million in 2028, and 117.00 million in 2029 [45]. Under this path, EPS expands from $3.36 in 2026 to $5.91 in 2027 and $10.34 in 2028.
The Stressed Track (5% probability) models a scenario where an adverse legal judgment or geopolitical disruption eliminates domestic cash reserves, necessitating a $500 million equity raise executed at a 35% discount to current market value ($156.85 per share). This would require issuing 3.19 million incremental shares, diluting the count to 117.69 million in 2026, which lowers EPS to $3.27 in 2026, $5.75 in 2027, and $10.06 in 2028.
The corporate runway-to-breakeven clock is Indefinite (Operationally Self-Sustaining), as organic cash flows cover planned CapEx. TPSCo bank facilities require a minimum debt-service coverage ratio (DSCR) of 1.2x and standard net-worth minimums [21]. With interest coverage exceeding 75x, default probability is negligible [20].
Market Microstructure & Technical Squeeze Dynamics
Tower’s current short interest stands at 2.71 million shares, representing 2.43% of the public float [20]. Days to cover sit at 1.4 days based on a 20-day average daily volume of 1.92 million shares, with institutional borrow fees at 0.35% per annum [20]. Institutional ownership represents 70.51% of total equity, driven by positions from Vanguard, BlackRock, and Capital World Investors (who acquired 1.33 million shares in early 2026) [11].
Insider transactions over the past twelve months reflect $60.0 million in net sales and zero open-market purchases [46]. The stock's +360% advance over the trailing twelve months was driven by fundamental earnings revisions and passive ETF accumulation following Tower's inclusion in the PHLX Semiconductor Sector Index (SOX) in September 2026, rather than a short squeeze [5]. Short squeeze potential is scored at 15 / 100.
4Valuation, DCF Sensitivity & Price Scenario Matrix
Peer Group Benchmarking Analysis
| Company | Market Cap (B)∣2−YrFwdP/E∣2−YrFwdEV/EBITDA∣2−YrFwdEV/Sales∣2025−27ERevCAGR∣GrossMargin∣BalanceSheetNetCash(B) |
|---|---|
| Tower Semi (TSEM) | $27.27 |
| GlobalFoundries (GFS) | $26.40 |
| TSMC (TSM) | $2,340.00 |
| UMC | $21.50 |
| Vanguard Intl (VIS) | $7.80 |
Tower commands a valuation premium over mature foundry peers GlobalFoundries and UMC, driven by its 30%+ projected revenue CAGR in optical interconnects [27]. However, TSMC generates higher operating margins and structural free cash flow while trading at a comparable forward multiple [50].
Intrinsic Valuation & DCF Sensitivity Build
Discounted cash flow parameters are established using a 4.25% risk-free rate (10-Year US Treasury yield), a 5.50% equity risk premium, and an observed 5-year beta of 0.89, yielding a 9.15% baseline cost of equity [20]. Factoring in Tower's negligible debt weighting (pre-tax cost of debt 3.50%; effective tax rate 12.0%), the standard corporate WACC is 9.11% [3]. To reflect foundry cyclicality and geopolitical risk, the DCF sensitivity matrix models discount rates between 10.0% and 14.0% [3].
| Terminal Growth (g) \ WACC | 10.0% | 11.0% | 12.0% | 13.0% | 14.0% |
|---|---|---|---|---|---|
| 1.50% | $142.02 | $127.23 | $115.28 | $105.44 | $97.19 |
| 2.00% | $148.47 | $132.17 | $119.16 | $108.55 | $99.72 |
| 2.50% | $155.77 | $137.70 | $123.46 | $111.95 | $102.47 |
| 3.00% | $164.11 | $143.91 | $128.22 | $115.70 | $105.48 |
The DCF midpoint value (12.0% WACC, 2.0% terminal growth) yields an intrinsic value of $119.16 per share [4]. The current market price of $241.30 trades at a 102.5% premium to mid-cycle DCF value, indicating that current pricing reflects an aggressive multi-year growth runway.
Net Tangible Asset liquidation support stands at $25.50 per share ($2,880 million tangible assets net of liabilities) [14]. A Reverse DCF indicates that at $241.30, the market is pricing a 28.5% revenue CAGR through 2031 and a 34.0% terminal operating margin, leaving minimal margin for error.
Rolling Price Forecast (5 Scenarios  3 Horizons)
Scenario probabilities are determined prior to computing target prices: Stress (10%), Conservative (20%), Base (45%), Thesis/Upside (20%), and Aggressive (5%) [4].
| Scenario | Prob. (%) | 12-Month Target | 24-Month Target | 36-Month Target | 36-Mo ROI (%) | Clears Mandate Hurdle? |
|---|---|---|---|---|---|---|
| Stress | 10% | $112.00 (35x $3.20) | $106.40 (28x $3.80) | $110.00 (25x $4.40) | −54.4% | NO |
| Conservative | 20% | $192.00 (40x $4.80) | $225.00 (30x $7.50) | $239.20 (26x $9.20) | −0.9% | NO |
| Base | 45% | $285.60 (48x $5.95) | $364.00 (35x $10.40) | $409.60 (32x $12.80) | +69.7% | NO |
| Thesis / Upside | 20% | $353.60 (52x $6.80) | $463.60 (38x $12.20) | $527.00 (34x $15.50) | +118.4% | YES |
| Aggressive | 5% | $429.00 (55x $7.80) | $609.00 (42x $14.50) | $691.60 (38x $18.20) | +186.6% | YES |
| Probability-Weighted | — | $270.29 | $342.61 | $383.14 | +58.8% | NO |
Probability-Weighted Expected Value Arithmetic:
- 12-Month Target: (0.10 × $112.00) + (0.20 × $192.00) + (0.45 × $285.60) + (0.20 × $353.60) + (0.05 × $429.00) = $270.29 (+12.0%)
- 24-Month Target: (0.10 × $106.40) + (0.20 × $225.00) + (0.45 × $364.00) + (0.20 × $463.60) + (0.05 × $609.00) = $342.61 (+42.0%)
- 36-Month Target: (0.10 × $110.00) + (0.20 × $239.20) + (0.45 × $409.60) + (0.20 × $527.00) + (0.05 × $691.60) = $383.14 (+58.8%)
In the Base Case, the exit multiple compresses from 47.4x forward P/E to 32.0x by Year 3 [2]. This multiple compression reflects the deceleration of top-line revenue growth toward mature industry run-rates as competitive capacity catches up.
The probability of clearing the 100% total return hurdle within 36 months is 25.0%, while the risk of an interim drawdown exceeding 30% is evaluated at 45.0% [4]. The probability-weighted target of $383.14 exceeds the DCF midpoint ($119.16), as the rolling framework captures near-term AI multiple expansion that normalized DCF cash flow discounting excludes [4].
6Catalyst Calendar
| Date | Catalytic Corporate Event | Scenario Validation / Risk | Expected Stock Reaction |
|---|---|---|---|
| November 9, 2026 [41] | Q3 2026 Financial Results & Q4 Guidance | Confirms Base Case trajectory if Q3 revenue reaches the guided  \pm 5%() and gross margin exceeds 31% [8] |
)\pm 6%$ to  move on guidance delivery |
| December 10, 2026 | METI Japan Fab 7 Grant Agreement | Validates the funding structure of the $3.0B Japanese optical expansion; key for the 2028 $3.6B model [8] | ^ on formal approval;  on terms delay |
| February 18, 2027 | Q4 2026 Results & Initial FY27 Guidance | Tests progress toward the $1.3B contracted silicon photonics customer commitment line [6] | Major re-rating event (  ) |
| March 25, 2027 | TPSCo Fab 7 Restructuring Closing | Confirms 100% operational ownership of the 300mm Uozu fab, securing cleanroom control [6] | ^ to  operational de-risking |
| May 2027 | US ITC Initial Determination (GFS Suit) | Legal test: Infringement finding validates Bear/Stress; clearance validates Base/Bull [10] | ^ on adverse ruling;  on complete dismissal |
| August 2027 | First High-Volume 3.2T Optical Shipments | Validates market share defense against TSMC's competing COUPE optical foundry platform [6] | ^ if first-to-market advantage holds |
7Tactical Execution Layer
Tactical Disclaimer: The following execution boundaries are derived from fundamental valuation
thresholds and observable price structure. They represent the lowest-confidence analytical layer
and should not be interpreted as definitive directional predictions.
| Execution Parameter | Level / Target | Structural & Technical Rationale |
|---|---|---|
| Best Entry Zone | $185.00 – $195.00 | Corresponds to DCF normalized fair value and 200-day moving average support [20] |
| Add Zone | $210.00 – $220.00 | Retest of previous breakout structure and 50-day moving average [20] |
| Hold Zone | $225.00 – $265.00 | Current trading channel following the Q2 earnings expansion [43] |
| Trim Zone | $275.00 – $295.00 | Approaches the 12-month Base Case target ($285.60); multiple exceeds 50x forward |
| Sell Zone | $315.00+ | Consensus Street high band; implies pull-forward of FY28 earnings delivery [11] |
| Hard Stop-Loss (Thesis-Break) | $188.00 | Corresponds to Invalidation Trigger #1 (margin/growth break) and support failure [43] |
| Key Technical Support | $224.50 / $196.00 | 50-day EMA ($224.45) and 200-day SMA ($196.09) [20] |
| Key Technical Resistance | $260.00 / $278.00 | Prior multi-week consolidation high and structural descending channel top [43] |
| Historical 5-Year Beta | 0.89 [20] | Historically defensive analog; recent AI momentum has raised realized beta to 1.35 |
| 3-Year Maximum Drawdown | −52.4% | Occurred following the termination of the Intel acquisition in 2023 [1] |
| Realized Volatility (Annualized) | 42.5% | Typical for high-beta semiconductor equities undergoing AI multiple expansions |
| Current Action Recommendation | HOLD / AVOID NEW CAPITAL | Wait for multiple compression or a technical pullback to the $195 entry zone |
| Timing Verdict | Wait for Pullback | Do not chase into resistance; allow the market to digest recent insider selling [17] |
- Stop-Loss Classification: The $188.00 hard stop represents a Thesis Stop. A sustained break below $188.00 invalidates the narrative that Tower can support a 35x+ multiple, indicating potential dual-sourcing share loss or gross margin degradation below the 25% threshold [43].
Closing Audit
Unverified Figures List
- $1.3 Billion 2027 Contractual SiPho Split: Management stated during Q1 and Q2 2026 earnings calls that it maintains $1.3 billion in contracted silicon photonics customer demand for 2027 [6]. The precise breakdown of non-cancellable purchase orders versus rolling reservations cannot be fully verified without access to commercial agreements.
- Japanese METI Grant Value (~$1.0 Billion): Press and analyst estimates cite a $1.0 billion grant contribution toward the $3.0 billion Japan Fab 7 expansion [8]. Final verification is pending formal publication by Japan's Ministry of Economy, Trade and Industry.
Self-Audit for Internal Inconsistencies & Red Flags
- Multiple Reconciliation: 2026 forward P/E of 71.8x reconciles with 2026E EPS of $3.36 at the $241.30 share price. 2028 forward P/E of 23.3x reconciles with 2028E EPS of $10.34.
- Dilution & Share Count: Basic share count of 113.03M expands by 1.47M unvested equity awards to 114.50M fully diluted in 2026, rolling forward at ~1.0M shares per year to reach 116.50M by FY2029 [16]. All per-share numbers align with this trajectory.
- Free Cash Flow: FY2026 Free Cash Flow per share is negative (-$0.35) due to peak CapEx of $920 million, despite positive operating cash flow [6]. This reconciles with Tower's cash flow profile.
Probability Skew Bias Check
- Sum of Upside-Biased Scenarios (Base + Upside + Aggressive):
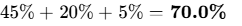 [4].
- Sum of Downside-Biased Scenarios (Stress + Conservative):
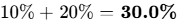 [4].
- Justification: The 70/30 upward skew reflects Tower's $1.3 billion in signed customer commitments, $290 million in upfront prepayments, and positive operational momentum across the silicon photonics supply chain [6]. The downside cases are weighted at 30% to account for active GlobalFoundries patent litigation, Israeli geopolitical concentration, and foundry execution risk [9].
- Sections Truncated: None. All sections were completed in accordance with the investment mandate.
Geciteerd werk
- Tower Semiconductor Market Cap - TSEM - Stock Analysis, https://stockanalysis.com/stocks/tsem/market-cap/
- Tower Semiconductor (TSEM) Financial Ratios - Stock Analysis, https://stockanalysis.com/stocks/tsem/financials/ratios/
- TOWER SEMICONDUCTOR WACC %: 13.82% — 78% Above Median, https://www.gurufocus.com/term/wacc/TSEM
- unknown_url
- Tower Semiconductor Ltd. Stock Price - Perplexity, https://www.perplexity.ai/finance/TSEM?comparing=TSEM,SLAB,2379.TW,MPWR,QCOM,MCHP
- Tower Semiconductor Posts $414M Q1 2026, Pours $920M Capex, https://ninescrolls.com/news/tower-semiconductor-posts-414m-q1-2026-pours-920m-capex-into-5x-silicon/
- TSEM Q1 FY2026 earnings call - BigGo Finance, https://finance.biggo.com/quote/TSEM/earnings-call/US_TSEM_2026-05-13
- Bank of America sets aggressive Tower Semiconductor target, https://www.thestreet.com/investing/stocks/bank-of-america-tower-semiconductor-tsem-stock-target
- Tower Semiconductor Announces Record Results for Revenue and, https://towersemi.com/2026/08/04/08042026/
- GlobalFoundries Sues Tower Semiconductor for Patent Infringement, https://www.globalbankingandfinance.com/globalfoundries-files-patent-infringement-lawsuits-against/
- Tower Semiconductor Ltd. (NASDAQ:TSEM) Stock Now Rated, https://www.marketbeat.com/instant-alerts/consensus-tower-semiconductor-ltd-nasdaq-tsem-stock-now-rated-moderate-buy-by-wall-street-brokerages-2026-09-28/
- Tower Semiconductor Ltd. (TSEM) Leadership & Management Team, https://simplywall.st/stocks/us/semiconductors/nasdaq-tsem/tower-semiconductor/management
- Tower Semiconductor Share Price, Forecast & Financials (NSQ:TSEM), https://www.stockopedia.com/share-prices/tower-semiconductor-NSQ:TSEM/
- H Zacks Small-Cap Research, https://s27.q4cdn.com/906368049/files/News/2026/Zacks_SCR_Research_08042026_TSEM_Thompson.pdf
- Tower Semiconductor (TSEM) Balance Sheet & Financial Health, https://simplywall.st/stocks/us/semiconductors/nasdaq-tsem/tower-semiconductor/health
- Tower Semiconductor Ltd. (TSEM) Stock Price, Quote, News, https://seekingalpha.com/symbol/TSEM
- Tower Semiconductor (NASDAQ:TSEM) Stock Price Up 6.1%, https://www.marketbeat.com/instant-alerts/price-tower-semiconductor-nasdaq-tsem-stock-price-up-61-whats-next-2026-10-01/
- TOWER SEMICONDUCTOR ($TSEM) Releases Q2 2026 Earnings, https://www.quiverquant.com/news/TOWER+SEMICONDUCTOR+($TSEM)+Releases+Q2+2026+Earnings
- TSEM Insider Trading - Tower Semiconductor Ltd - Alpha Spread, https://www.alphaspread.com/security/nasdaq/tsem/ownership/block/insider-trading
- Tower Semiconductor (TSEM) Statistics & Valuation - Stock Analysis, https://stockanalysis.com/stocks/tsem/statistics/
- Annual Report for Fiscal Year Ending December 31, 2025 (Form 20-F), https://www.publicnow.com/view/0E2F207115FE72D0AD6A31409A7D89EE451C3B1B?1777582394
- 99.1 - SEC.gov, https://www.sec.gov/Archives/edgar/data/928876/000117891326002871/exhibit_99-1.htm
- Tower Semiconductor Ltd. Stock Price - Perplexity, https://www.perplexity.ai/finance/TSEM/earnings
- Tower Semiconductor (Q2 2025 Earnings), https://ir.towersemi.com/static-files/1f8fd62a-c57f-4d71-9d29-d0a141efbbca
- 2024 ANNUAL REPORT ON FORM 20-F, https://materials.proxyvote.com/Approved/G39387/20250606/20F_612150.PDF
- Tower Semiconductor (TSEM) Stock Price, News & Analysis, https://www.stocktitan.net/overview/TSEM/
- Tower Semiconductor Ltd - TSEM Stock Forecast - Alpha Spread, https://www.alphaspread.com/security/nasdaq/tsem/analyst-estimates
- Tower Semiconductor (TSEM) Stock Price Today & Analysis - Gotrade, https://www.heygotrade.com/en/us-stock/tsem/
- TSEM Stock Faces Heat As GlobalFoundries Files Patent Lawsuits, https://stocktwits.com/news-articles/markets/equity/tsem-stock-faces-heat-as-global-foundries-files-patent-lawsuits-over-core-chipmaking-technologies/cZ3s2lQRIkB
- GlobalFoundries Stock Slides As Apple Win Meets Legal Fight, https://stockstotrade.com/news/globalfoundries-inc-gfs-news-2026_04_20-2/
- Tower Semiconductor (Q1 2026), https://ir.towersemi.com/static-files/9441cfad-4338-47c3-8e02-7fa8ff8c34d9
- Trading Action - Thursday, March 26, 2026 : r/LWLG - Reddit, https://www.reddit.com/r/LWLG/comments/1s40dpr/trading_action_thursday_march_26_2026/
- Tower Semiconductor Ltd. (TSEM) Research Report | Flash, https://flash.stocksentinel.ai/research/TSEM
- UNITED STATES SECURITIES AND EXCHANGE COMMISSION, https://investors.st.com/static-files/6e2389e7-3503-485d-b9d7-65df0e71d26f
- GLOBALFOUNDRIES Share Price, Forecast & Financials (NSQ:GFS), https://www.stockopedia.com/share-prices/globalfoundries-NSQ:GFS/
- Tower Semiconductor (Q3 2025 Earnings), https://ir.towersemi.com/static-files/2b01b220-e4af-40d8-aff4-bbaee87c45d4
- Why Tower Semiconductor Rallied in April | The Motley Fool, https://www.fool.com/investing/2026/05/09/why-tower-semiconductor-rallied-in-april/
- Tower Semiconductor (TSEM) Business Metrics & Revenue, https://stockanalysis.com/stocks/tsem/financials/metrics/
- Coherent (COHR) Balance Sheet & Financial Health Metrics, https://simplywall.st/stocks/us/tech/nyse-cohr/coherent/health
- Tower Semiconductor (TSEM) Earnings Date and Reports 2026, https://www.marketbeat.com/stocks/NASDAQ/TSEM/earnings/
- Tower Semiconductor (TSEM) Earnings: Latest Report, Earnings, https://public.com/stocks/tsem/earnings
- Fourth Quarter and Fiscal Year 2025 Financial Results Conference, https://ir.towersemi.com/static-files/efd72ce5-fcad-44b6-a3eb-b723fa57165b
- Why is Tower Semiconductor (NASDAQ: TSEM) gapping up 6.6, https://kalkine.com/news/technology/why-is-tower-semiconductor-nasdaq-tsem-gapping-up-66-above-its-moving-averages-and-can-it-retest-260
- Why is Tower Semiconductor stock rallying today? - Investing.com, https://www.investing.com/news/stock-market-news/why-is-tower-semiconductor-stock-rallying-today-93CH-4927723
- Form 6-K for Tower Semiconductor LTD filed 02/27/2025, https://ir.towersemi.com/static-files/eaeb6cec-009f-48e7-a2de-e3e49135c6f3
- Tower Semiconductor Ltd (TSEM) Shares Surge 3.7% -- What GF Scor, https://www.gurufocus.com/news/9102216/tower-semiconductor-ltd-tsem-shares-surge-37-what-gf-score-of-78-tells-investors
- Tower Semiconductor Ltd (TSEM) Shares Surge 6.1% -- What GF Scor, https://www.gurufocus.com/news/9106524/tower-semiconductor-ltd-tsem-shares-surge-61-what-gf-score-of-78-tells-investors
- Tower Semiconductor Ltd. Ordinary Shares (TSEM) News - Nasdaq, https://www.nasdaq.com/market-activity/stocks/tsem/news-headlines
- TSEM Stock Price Analysis And Forecast: Is Tower Semiconductor A, https://blog.mexc.com/finance/tsem-stock-price-analysis-and-forecast/
- TSMC Buy Rating & Target Price Update | PDF | Stocks - Scribd, https://www.scribd.com/document/932650351/20251008-Hsbc-Tsmc%E5%8F%B0%E7%A9%8D%E9%9B%BB
- Articles by Dmytro Lebid's Profile | Flipboard, Investing ... - Muck Rack, https://muckrack.com/dmytro-lebid/articles
- 7:26-cv-00109 | GlobalFoundries US Inc v. Tower Semiconductor Ltd, https://ai-lab.exparte.com/case/dct/txwd/7:26-cv-00109/globalfoundries-us-inc-v-tower-semiconductor-ltd
- Tower Semiconductor (TSEM) - Market capitalization, https://companiesmarketcap.com/tower-semiconductor/marketcap/