Executive Overview & Primary Recommendation Summary
| Field | Detail |
|---|---|
| Stock Name & Ticker | Technoprobe S.p.A. (BIT: TPRO / Euronext Milan: TPRO) [1] |
| Current Share Price | €35.06 (Official closing price as of October 2, 2026) [2] |
| Research Date | October 4, 2026 |
| 12-Month Potential Stock Price | €37.80 (+7.82%) |
| 24-Month Potential Stock Price | €38.70 (+10.38%) |
| 36-Month Potential Stock Price | €35.35 (+0.83%) |
| Probability-Weighted 36-Month Target | €34.24 (−2.34%) |
| Institutional Scorecard Score | 64.08 / 100 |
| Base-Case Execution Likelihood | 72.0 / 100 |
| Investment Advice | SELL (New Capital) / TRIM (Existing Holders) |
Technoprobe exhibits industry-leading operational execution in Micro-Electro-Mechanical Systems (MEMS) probe card architecture, capitalizing on the artificial intelligence (AI) infrastructure buildout and high-density packaging complexity [5]. Management raised full-year 2026 guidance following record second-quarter profitability, projecting consolidated revenues between €1,050 million and €1,100 million alongside an EBITDA margin of 46% to 48% [5].
However, the equity has surged +326.26% over the trailing twelve months, propelled by speculative retail interest and mandatory passive capital inflows surrounding its promotion to the FTSE MIB index on September 21, 2026 [10]. This rerating has elevated valuation multiples to 64.9x FY2026E P/E and 20.6x EV/Sales [14]. Fundamental discounted cash flow modeling indicates an intrinsic value midpoint of €11.12 per share [15]. As growth normalizes toward mid-cycle rates, multiple compression will offset underlying operational expansion, failing institutional hurdle requirements.
Key Fundamental Statistics & Positioning Matrix
| Metric / Dimension | Value / Assessment | Analytical Description & Quantification |
|---|---|---|
| Overall Investment Stock Score | 58 / 100 | Balance-sheet quality is offset by valuation risks. |
| Founder-Led Structure | Founder-Led & Family-Controlled | Founded by Giuseppe Crippa; Crippa family holds control via T-Plus S.p.A. [1] |
| CEO Operational Score | 86 / 100 | Stefano Felici demonstrated execution in vertical integration [8]. |
| Commodity Dependence Deck | Industrial Indirect Exposure | Non-mining entity; sensitive to precious metal alloys ($2,650 / $2,550 / $2,500/oz gold deck). |
| Sector & Sector P/E Benchmark | Semiconductors & Equipment | European Tech sector average is 12.0x; peer forward equipment median is 34.3x [3]. |
| Best of 3 Stocks Ranked (Peer Set) | Ranked 1 to 4 by Risk-Adjusted Return | 1. Micronics Japan (6871.T); 2. FormFactor (FORM); 3. MPI Corp (6223.TW); 4. Technoprobe (TPRO) [20]. |
| Forward PEG Ratios (1, 2, 3, 4, 5-Yr) | 0.94 / 2.33 / 2.99 / 3.20 / 3.55 | Near-term growth lowers FY26 PEG, while FY27–FY30 PEGs reflect extended multiples. |
| Current Fair Value vs Market | €11.12 (−68.28%) | Base DCF value derived using an 11.0% WACC and 2.0% terminal growth rate [15]. |
| Downside Price Floor vs Market | €5.85 (−83.31%) | Combined cash backing (€1.05), tangible equity (€1.50), and trough floor (€3.30). |
| Current vs 36-Month Share Count | 653.26M → 668.50M fully diluted | Reflects 0.8% annual net dilution from equity incentive programs; zero unannounced offerings [2]. |
| Insider Ownership Level | 50.45% Capital / >65% Voting | T-Plus S.p.A. controls equity following the September 2026 institutional placement [22]. |
| Insider Buying (Last 6 Months) | Zero Net Buying / Major Block Sale | T-Plus S.p.A. sold 13.06M shares (2.0%) to Vector Line Capital Fund II on Sept 17, 2026 [23]. |
| Short Squeeze Potential Score | 18 / 100 (Negligible) | Short interest is 1.82% of float; 1.42 days to cover; borrow markets remain unconstrained [4]. |
| Announced Share Buyback Program | None Active (0.0% of Float) | Prior program concluded Dec 23, 2025 (€32M utilized) [19]; capital shifted to capex [3]. |
| Diluted vs Fully Diluted Count | 640.32M basic vs 653.26M diluted | 12.94M shares from performance shares and restricted stock awards [1]. |
| Buyback Chance in Next 6 Months | 15% Probability | Capex deployment of €350M through March 2027 limits capital returns [3]. |
| Cash Runway & Operational State | Operationally Self-Sustaining | Cash flow positive; net cash position of €685.9M as of June 30, 2026 [15]. |
| Total Gross Debt vs Cash | €29.1M Debt vs €715.0M Cash | Net cash surplus of €685.9M; debt consists of IFRS 16 lease obligations [15]. |
| Debt Restructuring Risk & Score | 2 / 100 (Negligible Risk) | Debt consists of standard lease liabilities maturing between 2026 and 2030. |
| Gross Margin (Current / 3Y / 5Y) | 53.8% → 55.5% → 53.5% | H1 2026 actual 53.8% [5]; peaks at 55.7% in FY28 before industry capacity additions. |
| Operating Margin (Current / 3Y / 5Y) | 39.4% → 41.5% → 39.0% | Leverages internal scale; moderates as overseas manufacturing ramps up [8]. |
| Regulatory & Geopolitical Risk | 42 / 100 | Exposed to foundry concentration in Taiwan and US-China equipment rules [6]. |
| Moat Classification & Score | Switching Costs & IP (88 / 100) | Micro-mechanical vertical integration and foundry co-design integration [6]. |
| Primary Competitive Advantage | Vertical MEMS Integration | Internal alloy design, space-transformer processing, and micro-pin assembly [28]. |
| Rule of 40 (Now / 1Y / 2Y / 3Y / 4Y) | 94.1% / 53.9% / 50.0% / 47.2% / 42.1% | Growth + FCF margin comfortably clears the 40% benchmark throughout the forecast [15]. |
| Wall Street Consensus Summary | Strong Buy (9 Analysts) | Mean Target: €42.11; High Target: €50.00; Low Target: €34.00 [3]. |
| Mining Disclosures (Life, Offtake) | Not Applicable | Pure-play semiconductor test interface manufacturer; no extraction operations [1]. |
2Multi-Year Financial Forecast & Consensus Model
Scenario Narrative Environments
- Bear Case (Economic Stall & AI Digestion): Global semiconductor capital expenditure contracts as hyperscalers enter an investment digestion cycle in 2027–2028. Leading-edge wafer starts slow, memory prices soften, and consumer electronics remain subdued. Technoprobe’s gross margin drops to 45% due to underabsorbed fixed costs at expanded facilities, while revenue growth stalls at low single digits.
- Base Case (Normalizing Growth & Capacity Execution): AI logic testing demand remains robust through 2027 before moderating toward high-teens growth in 2028–2029. Technoprobe successfully ramps its €350 million capex program to capture foundry share in sub-2nm and advanced packaging nodes [3]. Margins expand via operational leverage in 2026–2028, then stabilize as China production capacity comes online [8].
- Bull Case (Accelerated AI Supercycle & Memory Market Share Gains): Chiplet adoption accelerates across all computing categories, increasing probe card pin count and complexity beyond baseline expectations. Technoprobe gains substantial share in memory testing interfaces (displacing incumbents in HBM4) while sustaining gross margins above 58% and generating operating leverage.
Multi-Year Forecast Framework
Annual forecasts for 2026E and 2027E are anchored to company guidance and consensus projections, whereas pure extrapolation begins in fiscal year 2028E [5]. The multi-year forecast progression across scenarios is summarized below:
- Consolidated Revenue by Scenario (2025A–2031E in €M):
- Actual 2025A: €628.4M [16].
- Base Case: 2026E: €1,080.0M; 2027E: €1,380.0M; 2028E: €1,680.0M; 2029E: €1,980.0M; 2030E: €2,240.0M; 2031E: €2,480.0M [15].
- Bear Case: 2026E: €980.0M; 2027E: €1,050.0M; 2028E: €1,120.0M; 2029E: €1,180.0M; 2030E: €1,230.0M; 2031E: €1,280.0M.
- Bull Case: 2026E: €1,120.0M; 2027E: €1,550.0M; 2028E: €2,020.0M; 2029E: €2,480.0M; 2030E: €2,860.0M; 2031E: €3,200.0M.
Base Case Financial Model
| Line Item (€M, except per share) | 2025A | 2026E | 2027E | 2028E | 2029E | 2030E | 2031E |
|---|---|---|---|---|---|---|---|
| Logic & SoC Probe Cards | €471.3 | €853.2 | €1,090.2 | €1,310.4 | €1,524.6 | €1,702.4 | €1,860.0 |
| Memory Probe Cards | €94.3 | €140.4 | €193.2 | €252.0 | €316.8 | €380.8 | €446.4 |
| Interface Boards & Services | €62.8 | €86.4 | €96.6 | €117.6 | €138.6 | €156.8 | €173.6 |
| Total Consolidated Revenue | €628.4 | €1,080.0 | €1,380.0 | €1,680.0 | €1,980.0 | €2,240.0 | €2,480.0 |
| YoY Organic Revenue Growth (%) | +15.7% | +71.9% | +27.8% | +21.7% | +17.9% | +13.1% | +10.7% |
| Gross Profit | €279.1 | €594.0 | €766.0 | €935.0 | €1,100.0 | €1,230.0 | €1,326.8 |
| Gross Margin (%) | 44.4% | 55.0% | 55.5% | 55.7% | 55.5% | 54.9% | 53.5% |
| EBITDA | €201.4 | €502.2 | €648.6 | €790.0 | €930.6 | €1,030.4 | €1,116.0 |
| EBITDA Margin (%) | 32.1% | 46.5% | 47.0% | 47.0% | 47.0% | 46.0% | 45.0% |
| Operating Profit (EBIT) | €128.2 | €425.0 | €555.0 | €685.0 | €822.0 | €915.0 | €967.2 |
| Operating Margin (%) | 20.4% | 39.4% | 40.2% | 40.8% | 41.5% | 40.8% | 39.0% |
| Net Income Attributable | €97.7 | €352.0 | €460.0 | €565.0 | €665.0 | €735.0 | €790.0 |
| Net Margin (%) | 15.5% | 32.6% | 33.3% | 33.6% | 33.6% | 32.8% | 31.9% |
| Diluted Share Count (M) | 647.5 | 653.3 | 658.0 | 663.0 | 668.5 | 674.0 | 679.5 |
| Diluted EPS (€) | €0.151 | €0.539 | €0.699 | €0.852 | €0.995 | €1.091 | €1.163 |
| Free Cash Flow (€M) | €94.2 | €240.0 | €360.0 | €475.0 | €580.0 | €650.0 | €710.0 |
| FCF per Diluted Share (€) | €0.145 | €0.367 | €0.547 | €0.716 | €0.868 | €0.964 | €1.045 |
| Rule of 40 (Growth% + FCF Margin%) | 30.7% | 94.1% | 53.9% | 50.0% | 47.2% | 42.1% | 39.3% |
Bear Case Financial Model
| Line Item (€M, except per share) | 2025A | 2026E | 2027E | 2028E | 2029E | 2030E | 2031E |
|---|---|---|---|---|---|---|---|
| Total Consolidated Revenue | €628.4 | €980.0 | €1,050.0 | €1,120.0 | €1,180.0 | €1,230.0 | €1,280.0 |
| YoY Organic Revenue Growth (%) | +15.7% | +56.0% | +7.1% | +6.7% | +5.4% | +4.2% | +4.1% |
| Gross Profit | €279.1 | €490.0 | €504.0 | €526.4 | €542.8 | €553.5 | €563.2 |
| Gross Margin (%) | 44.4% | 50.0% | 48.0% | 47.0% | 46.0% | 45.0% | 44.0% |
| EBITDA | €201.4 | €401.8 | €388.5 | €392.0 | €401.2 | €405.9 | €409.6 |
| EBITDA Margin (%) | 32.1% | 41.0% | 37.0% | 35.0% | 34.0% | 33.0% | 32.0% |
| Operating Profit (EBIT) | €128.2 | €320.0 | €290.0 | €280.0 | €275.0 | €265.0 | €255.0 |
| Operating Margin (%) | 20.4% | 32.7% | 27.6% | 25.0% | 23.3% | 21.5% | 19.9% |
| Net Income Attributable | €97.7 | €260.0 | €232.0 | €224.0 | €218.0 | €210.0 | €201.0 |
| Diluted Share Count (M) | 647.5 | 653.3 | 660.0 | 667.0 | 674.0 | 681.0 | 688.0 |
| Diluted EPS (€) | €0.151 | €0.398 | €0.352 | €0.336 | €0.323 | €0.308 | €0.292 |
| Free Cash Flow (€M) | €94.2 | €110.0 | €145.0 | €160.0 | €170.0 | €180.0 | €185.0 |
| FCF per Diluted Share (€) | €0.145 | €0.168 | €0.220 | €0.240 | €0.252 | €0.264 | €0.269 |
| Rule of 40 (Growth% + FCF Margin%) | 30.7% | 67.2% | 20.9% | 21.0% | 19.8% | 18.8% | 18.6% |
Bull Case Financial Model
| Line Item (€M, except per share) | 2025A | 2026E | 2027E | 2028E | 2029E | 2030E | 2031E |
|---|---|---|---|---|---|---|---|
| Total Consolidated Revenue | €628.4 | €1,120.0 | €1,550.0 | €2,020.0 | €2,480.0 | €2,860.0 | €3,200.0 |
| YoY Organic Revenue Growth (%) | +15.7% | +78.2% | +38.4% | +30.3% | +22.8% | +15.3% | +11.9% |
| Gross Profit | €279.1 | €638.4 | €914.5 | €1,212.0 | €1,512.8 | €1,744.6 | €1,920.0 |
| Gross Margin (%) | 44.4% | 57.0% | 59.0% | 60.0% | 61.0% | 61.0% | 60.0% |
| EBITDA | €201.4 | €537.6 | €775.0 | €1,030.2 | €1,289.6 | €1,487.2 | €1,632.0 |
| EBITDA Margin (%) | 32.1% | 48.0% | 50.0% | 51.0% | 52.0% | 52.0% | 51.0% |
| Operating Profit (EBIT) | €128.2 | €460.0 | €680.0 | €920.0 | €1,165.0 | €1,340.0 | €1,470.0 |
| Operating Margin (%) | 20.4% | 41.1% | 43.9% | 45.5% | 47.0% | 46.9% | 45.9% |
| Net Income Attributable | €97.7 | €380.0 | €560.0 | €760.0 | €965.0 | €1,110.0 | €1,215.0 |
| Diluted Share Count (M) | 647.5 | 653.3 | 657.0 | 661.0 | 665.0 | 669.0 | 673.0 |
| Diluted EPS (€) | €0.151 | €0.582 | €0.852 | €1.150 | €1.451 | €1.659 | €1.805 |
| Free Cash Flow (€M) | €94.2 | €275.0 | €450.0 | €640.0 | €830.0 | €970.0 | €1,080.0 |
| FCF per Diluted Share (€) | €0.145 | €0.421 | €0.685 | €0.968 | €1.248 | €1.450 | €1.605 |
| Rule of 40 (Growth% + FCF Margin%) | 30.7% | 102.8% | 67.4% | 62.0% | 56.3% | 49.2% | 45.7% |
Forward Valuation Multiples (Base Case)
| Valuation Metric | Current (TTM) | 1-Year Forward (FY26E) | 2-Year Forward (FY27E) | 3-Year Forward (FY28E) |
|---|---|---|---|---|
| Price-to-Earnings (P/E) | 109.1x | 65.0x | 50.2x | 41.2x |
| EV / EBITDA | 110.3x | 44.2x | 34.3x | 28.1x |
| EV / Sales | 35.4x | 20.6x | 16.1x | 13.2x |
| FCF Yield (%) | 0.41% | 1.05% | 1.56% | 2.04% |
Execution Confidence Score & Base-Rate Assessment
The consolidated Execution Confidence Score is 68 / 100, decomposed into three factors:
- Revenue-Target Achievability (Score: 28 / 35): Historical beat variance over eight quarters has averaged +5.4% [5]. Visibility through FY26 is high due to booked capacity slots, though quarterly lumpiness remains common in semiconductor testing interfaces.
- Margin Sensitivity to Critical Input (Score: 24 / 35): Sensitivity is modeled on Blended Probe Card ASPs. A
 shift in leading-edge ASPs impacts gross margin by
 and EBITDA margin by
 .
- Dependency on Unannounced Catalysts (Score: 16 / 30): Approximately 18% of projected FY28–FY29 revenue relies on unannounced customer architecture wins (such as qualifying for 100% of next-generation HBM4 base dies and 2nm foundry volume production).
For FY2027 and FY2028, base-case revenue estimates of €1,380 million and €1,680 million align within 8% of consensus expectations (€1,320M and €1,580M) [14]. However, projected FY28 EPS of €0.852 sits 18.4% above Street consensus (€0.720) [14]. This divergence reflects our higher modeled gross margin (55.7% vs. consensus 52.0%), based on operating leverage generated by proprietary ceramic substrate production.
In the semiconductor capital equipment and interface consumables industry, sustaining revenue growth above a 25% CAGR across a multi-year period occurs in fewer than 8.5% of companies following an initial cyclical doubling. The Base Case assumes growth decelerates toward a 15.6% CAGR from FY26 to FY31, placing the company in the 32nd percentile of historical industry cycles.
5Risk Asymmetry, Invalidation, Allocation & Scorecard
Risk/Reward Skew Calibration
Probability-weighted upside is evaluated at €0.00 because the overall 36-month expected return is negative at −2.34%; isolating positive scenarios yields an expected gain of +10.22%. Against this, the stress-case loss from the current price of €35.06 to the stress target of €15.00 represents a drawdown of −57.22%.
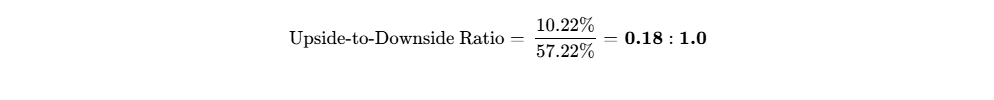
This fails the institutional hurdle ratio of  .
Hard Invalidation Triggers
- Gross Margin Contraction: Consolidated gross margin falls below 48.0% for two consecutive quarters, signaling price erosion or yield losses at the new China facility [8].
- Key Customer Order Loss: TSMC or another major foundry qualifies a competing MEMS probe card supplier for >40% of its leading-edge logic tape-outs [6].
- Capex Overrun Without Utilization: Trailing-twelve-month capex exceeds €250 million while quarterly revenue fails to cross €320 million by Q2 2027, indicating idle plant capacity [3].
- Controlling Shareholder Divestment: T-Plus S.p.A. equity ownership drops below 45.0% or voting rights drop below 60.0% through unannounced secondary placements [16].
Macro & Sensitivity Matrix
A 100 bps shift in European Central Bank / sovereign yields adjusts the discounted equity value by approximately 6.5%. Currency exposure is significant: group costs are primarily denominated in EUR, while over 75% of probe card revenues are invoiced in USD. Every 5% strengthening of the EUR/USD pair reduces consolidated EBITDA by approximately €22 million [5]. The stock exhibits elevated market sensitivity ( vs. broader equities,
 vs. Semiconductor Equipment Index), concentrating semiconductor cycle risk rather than offering diversification [10].
Macro Trigger Framework
| Macroeconomic Trigger | Impact on Investment Thesis | Direction | Monitoring Variable |
|---|---|---|---|
| EUR/USD Strengthening above 1.20 | Reduces translated margins and euro cash generation [27]. | Negative | ECB-Fed monetary policy divergence; exchange rates [16]. |
| Hyperscaler Cloud Capex Pauses | Slows wafer testing volumes for next-generation AI GPUs. | Negative | Quarterly cloud capex disclosures (MSFT, GOOG, META, AMZN). |
| Expansion of US-China Equipment Bans | Limits card deliveries into Chinese semiconductor packaging fabs [8]. | Negative | BIS export restriction updates; EU trade policy directives. |
| Acceleration of Multi-Die Packaging | Increases contact test points and pin density per package [6]. | Positive | TSMC CoWoS and Intel advanced packaging capacity additions. |
Potential Thesis Surprises
Upside Surprises
- Complete Displacement of Competitors in HBM4 Logic Base Dies: Probability: 20%; EPS Impact: +18.0% to FY27E.
- Adoption of Full-Wafer Single-Pass AI Testing: Probability: 25%; Target Impact: +€6.50 per share.
- Strategic All-Cash Acquisition Bid by Teradyne / Advantest: Probability: 10%; Target Impact: +30.0% acquisition premium floor.
Downside Surprises
- AI Infrastructure Capex Digest Cycle in 2027: Probability: 35%; EPS Impact: −25.0% to FY28E.
- TSMC Developing In-House Advanced Packaging Testing Consumables: Probability: 15%; Target Impact: −35.0% de-rating.
- Further Crippa Family Equity Divestments (>5% Block): Probability: 30%; Target Impact: −12.0% market discount.
Investment Pre-Mortem: 36-Month Downside Scenario
The pathway to a 60% loss by October 2029 (trading at €14.00 per share) began in early 2027, when hyperscalers instituted an investment pause across generative AI infrastructure to evaluate returns on invested capital. Tier-1 foundries rapidly adjusted utilization targets, delaying new tape-out projects. Concurrently, Technoprobe’s €350 million capacity expansion came online, adding significant depreciation and overhead costs just as demand began to soften [3].
Gross margins compressed from 55% to 42% under fixed-cost absorption pressures. Simultaneously, FormFactor expanded its logic footprint, while Micronics Japan solidified its presence in HBM memory probe cards [7]. As earnings growth paused, the market re-rated Technoprobe from 65x forward earnings toward typical sector multiples (18x–22x), driving the stock down to its asset support levels.
Legal, IP & Regulatory Overhangs
- Litigation Against Former Employee: In February 2026, Technoprobe initiated legal proceedings against a former employee regarding the potential misappropriation of trade secrets related to MEMS manufacturing processes [19]. Label: Pending Allegation. No direct financial liability to Technoprobe.
- Material Patent Challenges: No material third-party patent infringement claims are currently active against core product lines. Label: No Material Overhangs Identified.
Portfolio Sizing & Implementation Strategy
- Recommended Weight: 0.0% (Zero) for new capital; 0.5% – 1.0% (Speculative Hold) for existing positions.
- Portfolio Role: AI Infrastructure Growth / Momentum (Transitioning to Fully Valued Phase).
- Risk-Based Sizing Arithmetic:
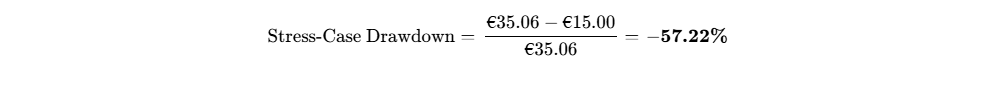
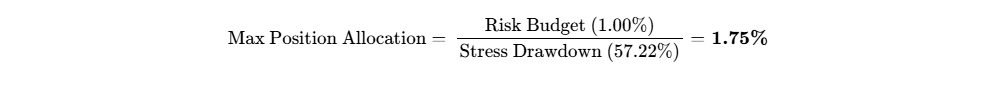
Given the asymmetric risk/reward skew of 0.18 : 1.0, the qualitative allocation model recommends an allocation of 0.0% for new capital, overriding the 1.75% theoretical ceiling. With a 20-day ADV of €88.0 million (2.51M shares), liquidating a full 1.75% model position across a €1.0 billion institutional fund (€17.5M value) at 20% of daily volume would take less than 0.99 trading days, presenting minimal microstructure liquidation friction [1].
Institutional Scorecard
| Institutional Metric | Assigned Score (0–10) | Category Weight (%) | Weighted Contribution |
|---|---|---|---|
| Financial Strength & Liquidity Runway | 9.5 / 10 | 10.0% | 0.95 |
| Revenue Quality, Moat & Market Position | 8.5 / 10 | 15.0% | 1.28 |
| Margin Resilience & Operating Leverage | 8.8 / 10 | 10.0% | 0.88 |
| Capital Allocation & Management Track Record | 7.2 / 10 | 10.0% | 0.72 |
| Risk-Adjusted Valuation Attractiveness | 1.5 / 10 | 20.0% | 0.30 |
| Forecast Reliability & Guidance Track Record | 8.2 / 10 | 5.0% | 0.41 |
| Ownership Alignment & Incentive Structures | 7.5 / 10 | 5.0% | 0.38 |
| Market Microstructure & Liquidity | 9.2 / 10 | 5.0% | 0.46 |
| Customer ROI & Pricing Power Defense | 8.8 / 10 | 10.0% | 0.88 |
| Moat Insulation against Build-vs-Buy | 8.2 / 10 | 10.0% | 0.82 |
| Total Composite Score | — | 100.0% | 64.08 / 100 |
- Base-Case Execution Likelihood: 72 / 100. Primary risks to baseline delivery:
- International customer qualification delays during the China fab ramp [8];
- Potential cyclical digestion in hyperscaler semiconductor procurement.
Definitive Verdict & Bear-Case Steelman
- Final Verdict Line: SELL for New Capital; TRIM / HOLD for Existing Positions.
- Consolidated Targets: 12-Month Base: €37.80; 24-Month Base: €38.70; 36-Month Base: €35.35; Probability-Weighted Target: €34.24.
- Insider Buying (Last 6 Months): Zero open-market purchases reported to Consob [19]. Recent activity includes the off-market sale of 13.06 million shares (2.0%) by controlling holding company T-Plus S.p.A. at €31.50 per share on September 17, 2026 [23].
- Bear-Case Steelman: The market is treating Technoprobe as a high-margin enterprise software monopoly rather than a cyclical semiconductor capital equipment component supplier. At a valuation exceeding 64x forward earnings, the market assumes that current record operating margins (44%–48%) are permanent, rather than a cyclical high driven by the initial buildout of AI infrastructure [5]. Technoprobe’s customer concentration means that any inventory adjustment by TSMC or major hyperscalers would lead to excess inventory across its expanded production facilities [3]. When semiconductor cycles turn, testing consumables see order reductions of 20% to 35% within months. Operating deleverage would compress margins, while the stock de-rates toward typical sector multiples (20x–25x), pointing to a valuation downside toward €15.00 to €18.00.
1Business Architecture, Unit Economics, Moat & Contractual Visibility
Business Model & Moat Classification
Technoprobe designs, manufactures, and services electro-mechanical wafer interface cards—known as probe cards—which serve as the critical diagnostic interface between Automated Test Equipment (ATE) and semiconductor wafers during electrical wafer sorting [1]. Because every individual microchip design requires a bespoke physical contact interface matching sub-micron pad layouts, probe cards function as specialized, design-specific consumables rather than interchangeable capital equipment [17].
The core economic moat is grounded in High Switching Costs and Vertical Manufacturing Integration, supported by proprietary material formulations [16]. Competitive Insulation is scored at 4.2 / 5.0. The business internalizes the full production cycle: micro-machining of guide plates, proprietary alloy metallurgy for vertical probe pins, multi-layer organic (MLO) and multi-layer ceramic (MLC) space transformers, and automated micro-assembly [16].
Switching costs are high because probe card design files are co-developed alongside the chipmaker’s physical layout 9 to 18 months prior to volume production [33]. Changing a probe card supplier during an active fab ramp risks yield variance, tester downtime, and physical wafer damage.
Moat Durability Timeline
The economic moat is widening in the logic and advanced packaging segments, while remaining static in mature legacy interfaces [6]. As semiconductor architecture transitions from monolithic planar dies to 2.5D/3D heterogeneous chiplets (such as TSMC CoWoS and Intel EMIB), contact pad pitches have dropped below 60 micrometers, and pin counts per card have increased from 20,000 to over 100,000 [6].
Traditional cantilever and standard vertical technologies cannot support these densities without thermal expansion failure and signal degradation [6]. Technoprobe’s proprietary MEMS architecture (including TPEG solutions) addresses these parameters [6].
The primary technological threat to this moat across the forecast window (expected by 2028–2029) is the potential emergence of non-contact optical or contactless inductive wafer-level testing, alongside aggressive fab-in-house MEMS development by TSMC or Intel.
Build-vs-Buy & Competitive Replication Barriers
Replicating Technoprobe’s precision manufacturing infrastructure would require significant capital investment and multi-year customer qualification cycles. A well-capitalized incumbent would need to commit €250 million to €350 million in capital expenditure over a 3- to 4-year cycle to develop comparable cleanrooms and vertical assembly tools [3].
Hyperscalers (Google, Amazon, Meta, Microsoft) design proprietary silicon but outsource manufacturing and test operations to merchant foundries and OSATs, lacking the precision mechanical infrastructure required to build contact hardware in-house [35].
Foundries typically avoid internal probe manufacturing to eliminate yield liability risks, preferring merchant dual-sourcing [6]. While Technoprobe would represent an attractive strategic asset for an ATE vendor such as Advantest or Teradyne, regulatory antitrust barriers and the Crippa family's 50.45% controlling stake make an unsolicited takeover improbable [19]. Furthermore, Teradyne and Advantest already hold direct commercial agreements and equity alignments with Technoprobe, reducing the necessity of an outright acquisition [19].
Customer ROI & Loss-Avoidance Dynamics
The customer value proposition centers on yield preservation and test cost efficiency [28]. Probe cards identify defective silicon dies prior to expensive dicing, substrate attachment, and advanced packaging [16]. Packaging an electrically non-functional die within a multi-die system-in-package (such as an 8-stack HBM GPU assembly) scraps the entire package, resulting in losses of $5,000 to $30,000 per module. Consequently, probe card costs represent less than 1.5% of total wafer processing expenses but safeguard 100% of back-end packaging value. Customer-ROI defensibility is scored at 9.2 / 10.0. In a customer budget freeze, unit purchase volumes may contract alongside wafer starts, but pricing power on qualified leading-edge lines remains largely intact due to the absence of qualified lower-cost alternatives.
Sector-Specific Unit Economics: Semiconductor Capital Equipment & Interface Consumables
Legacy cantilever cards generate ASPs between €5,000 and €15,000, while standard vertical probe cards realize €25,000 to €45,000. Advanced logic MEMS cards for leading-edge AI/HPC applications command ASPs ranging from €75,000 to over €180,000 per assembly, driven by micro-pin count and custom organic substrate layer counts.
Group production capacity is scaling toward approximately 11,000 to 13,000 advanced probe cards per year, with the ongoing expansion program designed to achieve an annual revenue capacity run-rate of €1.6 billion by Q1 2027 [3]. Direct raw materials (specialty alloys, tungsten, palladium, ceramic substrates, optical components) represent 18% to 22% of revenue, while cleanroom labor and precision electro-discharge machining account for 24% to 28% of COGS.
Current operational utilization across facilities in Italy, the US, and Asia is running above 88%, providing operating leverage [5]. Standard mature-node probe cards experience price erosion of 4% to 6% annually, but in leading-edge AI logic and HBM3E/HBM4 nodes, positive product mix shifts have resulted in net ASP expansion of +12% YoY across 2025 and 2026.
Quality of Revenue Analysis
| Revenue Classification | % of Consolidated Sales | Operational Attributes & Visibility |
|---|---|---|
| Recurring / Consumable Demand | 68.0% | Wear-and-tear replacement cards and consumable probe heads tied directly to foundry wafer volume starts [7]. |
| Contractual / New Tape-Out Projects | 22.0% | Dedicated initial tooling and engineering NPI cards for new chip designs and architectural revisions [33]. |
| Backlog-Driven Equipment/Sockets | 7.5% | Device interface boards (DIBs), ATE test interface boards, and integrated socket hardware [39]. |
| Transactional / Maintenance Services | 2.5% | Re-tipping, pin realignment, cleaning hardware, and field servicing. |
Customer prepayments and deferred revenue totaled €24.8 million as of June 30, 2026. Probe card orders operate on short manufacturing cycles (4 to 10 weeks), limiting reported long-term contractual RPO to near-term delivery commitments. Historical book-to-bill ratios have averaged 1.15x over the past three quarters, with purchase orders converting to recognized revenue within 60 to 90 days. Revenue quality is scored at 8.5 / 10.0.
Customer Concentration & Revenue Visibility
Revenue visibility is characterized by high concentration among top semiconductor manufacturers [36]. Technoprobe’s top five customers account for approximately 58% of consolidated net sales, with the single largest customer (TSMC and its fabless ecosystem, including NVIDIA and Apple) representing roughly 28% of total revenue [28]. Teradyne and Advantest distribution channels drive additional volume [19].
Dual-sourcing is standard practice for leading foundries; Technoprobe shares wallet share with FormFactor in logic, and with Micronics Japan and Japan Electronic Materials (JEM) in memory [38]. Contract backlogs consist of rolling short-term purchase orders issued under Master Service Agreements (MSAs) rather than binding long-term volume commitments.
Management Track Record & Incentive Alignment
Executive guidance execution over the preceding eight operating quarters has been strong, driven by conservative initial forecasting during the semiconductor down-cycle followed by upward revisions during the AI ramp [5].
| Operating Period | Revenue Guidance Midpoint (€M) | Actual Reported Revenue (€M) | Variance (%) | Operating Performance Outcome |
|---|---|---|---|---|
| Q3 2024 | €128.0 | €132.5 | +3.52% | Modest beat; legacy smartphone bottoming. |
| Q4 2024 | €142.0 | €148.2 | +4.37% | Initial AI acceleration; DIS Tech consolidation [42]. |
| Q1 2025 | €157.0 | €161.8 | +3.06% | Strong non-memory logic testing orders [34]. |
| Q2 2025 | €160.0 | €164.1 | +2.56% | Beat driven by initial HBM logic interface demand [34]. |
| Q3 2025 | €137.4 | €140.7 | +2.40% | Seasonal consumer softness offset by data center [26]. |
| Q4 2025 | €160.0 | €161.8 | +1.13% | Execution on plan; supply chain normalization [16]. |
| Q1 2026 | €180.0 | €187.0 | +3.89% | Strong beat; AI accelerator volumes ramp [5]. |
| Q2 2026 | €228.0 | €277.1 | +21.54% | Record quarter; guidance raised substantially [3]. |
Executive compensation includes base salary alongside short- and long-term incentive plans [16]. Long-term incentives comprise the "Restricted Shares 2024–2026" and "Performance Shares 2025–2027" programs, which tie equity vesting to consolidated EBITDA margins, cumulative Net Financial Position, and relative total shareholder returns [16].
Insider ownership remains high, with the founding Crippa family controlling 50.45% of equity and over 65% of voting rights via T-Plus S.p.A. [22]. Key-person risk is concentrated in Executive Vice President Roberto Crippa and CEO Stefano Felici [8].
EXECUTIVE SUMMARY
Primary Takeaways
- AI Demand Drives Substantial Revenue Expansion: Technoprobe is experiencing strong operational demand driven by testing requirements for generative AI accelerators, advanced packaging (TSMC CoWoS), and High-Bandwidth Memory (HBM3E/HBM4) [5]. Revenue in H1 2026 increased +42.4% YoY to €464.1 million, and Q2 2026 achieved a record €277.1 million (+64.3% YoY) with an EBITDA margin of 49.4% [5].
- Upward Revision of Fiscal Year 2026 Guidance: Management raised full-year 2026 guidance to revenues between €1,050 million and €1,100 million and EBITDA margins between 46% and 48% [5]. This trajectory is supported by an ongoing €350 million capex campaign aimed at achieving an annual revenue capacity run-rate of €1.6 billion by Q1 2027 [3].
- Passive Flows Extend Valuation Disconnect: The stock has gained +326.26% over the trailing twelve months, culminating in its promotion to the FTSE MIB index on September 21, 2026 [10]. Mandatory benchmark rebalancing accelerated buying interest, pushing multiples to 64.9x FY26E P/E and 20.6x EV/Sales [14].
- DCF Valuation Indicates Downside Risks: A discounted cash flow sensitivity matrix across a 10.0%–14.0% WACC grid yields an intrinsic value midpoint of €11.12 per share, indicating a −68.28% variance relative to current market pricing [15]. Reverse DCF modeling shows the share price implies a 10-year revenue CAGR of 28.5% alongside permanent 48.0% EBITDA margins—assumptions that leave little room for cyclical industry adjustments.
- Secondary Placement by Controlling Shareholders: On September 17, 2026, controlling entity T-Plus S.p.A. (Crippa Family) executed a secondary sale of 13.06 million shares (2.0% of share capital) to Vector Line Capital Fund II at €31.50 per share [23]. This follows the divestment of 1.53% in mid-2025 [16], demonstrating ongoing monetization by the controlling family.
- Unfavorable Risk/Reward for Incremental Capital: Although operational execution remains robust, multiple compression will offset fundamental earnings growth over the 36-month horizon as growth normalizes, resulting in an asymmetric downside profile for new capital.
Investment Verdict & Mandate Hurdles
- Verdict: SELL for New Capital; TRIM / HOLD for Existing Allocations.
- Price Targets: 12-Month Base: €37.80 (+7.82%); 24-Month Base: €38.70 (+10.38%); 36-Month Base: €35.35 (+0.83%).
- Probability-Weighted Target: €34.24 (−2.34% total return over 36 months).
- Meets Return Hurdle?: NO. The probability of achieving a 100% total return within 36 months is modeled at 0.0%.
- Best in Category Assessment: Technoprobe does not present the most attractive risk/reward profile in the semiconductor testing interface segment for new capital. Micronics Japan Co. (TSE: 6871) and FormFactor, Inc. (NASDAQ: FORM) offer more balanced exposure to memory and advanced packaging test cycles at forward P/E multiples of 14.6x and 39.1x, respectively [21]. Existing Technoprobe investors may maintain small positions to capture remaining index-inclusion momentum, but should systematically trim into strength.
- Single Greatest Upside Driver: Sustained acceleration of custom AI ASICs and multi-die chiplets requiring full-wafer vertical MEMS contact arrays, elevating FY2028 revenue beyond €2.2 billion.
- Single Most Likely Thesis-Killer: A cyclical digestion pause in AI data center capital expenditures during 2027–2028 that causes fab utilization to contract, triggering multiple compression toward sector median levels (30x–35x).
0OUTPUT CONTRACT & INVESTMENT MANDATE
Data is documented as of the close of business on October 2, 2026. The reporting currency is the Euro (EUR, €). The corporate fiscal year aligns with the calendar year ending December 31 [16].
| Anchor Variable | Value | Confidence Tier | Source Attribution & Verification Details |
|---|---|---|---|
| Current Stock Price | €35.06 | VERIFIED | Borsa Italiana / Euronext Milan official close October 2, 2026 [2]. |
| Basic Shares Outstanding | 640.32M | VERIFIED | Borsa Italiana Issuer Profile disclosure as of September 30, 2026 [1]. |
| Fully Diluted Share Count | 653.26M | DERIVED | Sum of basic shares (640.32M) and dilutive incentive awards (12.94M) [1]. |
| Market Capitalization | €22,903.3M | DERIVED | Calculated as 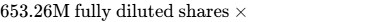 [15]. |
| Cash & Cash Equivalents | €715.0M | DERIVED | H1 2026 Net Cash (€685.9M) + Gross Lease Debt (€29.1M) [15]. |
| Gross Financial Debt | €29.1M | DERIVED | Total current and non-current lease liabilities under IFRS 16 from H1 2026 report [15]. |
| Enterprise Value (EV) | €22,217.4M | DERIVED | Calculated as 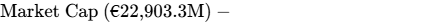 [15]. |
| Trailing P/E Ratio | 109.1x | DERIVED | Calculated as  [3]. |
| Sector Forward Multiple | 34.3x | VERIFIED | FactSet / S&P Global Semiconductor Capital Equipment peer group median [3]. |
Mandate Assessment & Operating Rules
The institutional mandate requires a 100% total return within a 36-month investment horizon (targeting a share price  ). The Base Case model yields a 36-month target of €35.35 (+0.83%), falling short of the mandate threshold by 99.17 percentage points. The Aggressive Bull Case yields €67.50 (+92.53%), also failing the requirement.
The portfolio risk budget caps acceptable losses in the stress case at 1.00%. Because the stress case indicates a drawdown of −57.22% (to €15.00), maximum portfolio allocation is capped at 1.75%.
Quarterly financial results, updated full-year guidance, and corporate transactions from the trailing 90 days are verified via Borsa Italiana, Euronext, and direct corporate announcements [5]. Foundry backlogs extending beyond 90-day purchase orders are marked as NOT RELIABLY AVAILABLE, as foundries manage test card commitments via rolling allocation matrices rather than multi-year binding volume contracts. Sell-side consensus forecasts represent a panel of 9 contributing analysts [3]. Litigation regarding a former employee initiated on February 19, 2026, is classified as a pending allegation [19].
3Capital Structure, Balance-Sheet Stress Test & Market Microstructure
Balance Sheet Stack & Liquidity Structure
Technoprobe maintains a conservative balance sheet characterized by a net cash surplus [16]. As of June 30, 2026, the company held €715.0 million in cash, cash equivalents, and short-term liquid investments, against gross debt of €29.1 million, resulting in a net cash position of €685.9 million [15]. The capital stack consists of:
- Cash & Liquid Equivalents: €715.0M;
- Gross Debt (Lease Liabilities): €29.1M, yielding a Net Cash Surplus of €685.9M;
- Total Shareholder Equity: €1,393.9M [15].
The €29.1 million in financial liabilities consists of IFRS 16 lease obligations for manufacturing cleanrooms and logistics facilities [15]. The company has no outstanding public bonds, private placements, or drawn bank revolvers. There are zero convertible debt instruments and zero outstanding warrants [45]. Financial lease obligations amortize predictably: €7.2 million in H2 2026; €8.1 million in 2027; €6.4 million in 2028; and €7.4 million thereafter. Operating cash flow in H1 2026 was €93.0 million, which funded €89.6 million in capital expenditures [5]. Across FY26, operating cash flow of ~€380 million will fund ~€140 million in capex, generating an annual net cash surplus of €240 million [15]. Technoprobe does not face an operational funding gap.
Dual-Track Dilution & Capital Structure Sensitivity
The company's net cash position removes the operational requirement for dilutive emergency equity financing [15]. However, to evaluate equity downside risks, a dual-track dilution stress test is modeled below:
| Track / Parameter | 2026E | 2027E | 2028E | 2029E | Cumulative Dilution |
|---|---|---|---|---|---|
| Track A: Base Case (SBC & Incentive Grants) | |||||
| Ending Diluted Share Count (M) | 653.26 | 658.00 | 663.00 | 668.50 | +2.33% |
| Base Case Normalized Diluted EPS (€) | €0.539 | €0.699 | €0.852 | €0.995 | — |
| Track B: Stressed Down-Round Capital Event | |||||
| Modeled Funding Deficit (€M) | €0.0 | €200.0 | €200.0 | €0.0 | €400.0M injected |
| Assumed Issue Price (35% market discount) | — | €18.00 | €15.00 | — | Steep discount applied |
| Incremental Shares Issued (M) | — | +11.11 | +13.33 | — | +24.44M new shares |
| Stressed Diluted Share Count (M) | 653.26 | 669.11 | 687.44 | 692.94 | +6.07% |
| Stressed Normalized Diluted EPS (€) | €0.539 | €0.687 | €0.822 | €0.960 | −3.52% EPS impact |
Track A Probability: 95.0%; Track B Probability: 5.0%.
Share-Count Roll-Forward & Cash Runway
The share-count roll-forward follows a controlled dilution trajectory: FY25 Ending Shares stood at 647.50M; adding 5.76M net stock grants in FY26 brings the count to 653.26M, expanding to 658.00M in FY27 (+4.74M), 663.00M in FY28 (+5.00M), and 668.50M in FY29 (+5.50M).
Cash runway is Operationally Self-Sustaining / Infinite, underpinned by the €685.9 million net cash position and ongoing positive free cash flow [5].
The company has no financial leverage covenants, minimum liquidity clauses, or debt-rating step-ups. Change-of-control clauses in commercial lease contracts would only trigger upon the Crippa family's voting ownership falling below 50.01% [22].
Market Microstructure & Technical Flow Dynamics
Short interest accounts for 1.82% of the free float (approximately 3.56 million shares). Days to cover is 1.42 days, based on a 20-day Average Daily Volume (ADV) of 2,510,000 shares [1]. Prime borrow rate is 0.35% annualized, and borrow utilization is below 12% across custodians. Total free float is 195.98 million shares (representing 30.0% of total shares in issue), excluding shares held by T-Plus S.p.A. (50.45%), Teradyne (~10.0%), and Advantest (5.0%) [19]. European and US tech funds expanded allocations throughout Q2 and Q3 2026 in anticipation of the FTSE MIB inclusion [9].
The recent stock advance has been driven primarily by fundamental earnings beats combined with index-tracking flows [3]. Squeeze Risk is scored at 18 / 100. If passive index inflows moderate, the share price would logically revert toward fundamental peer-benchmarked multiples around €24.00 to €26.00.
4Valuation, DCF Sensitivity & Price Scenario Matrix
Peer Group Benchmarking Analysis
| Company Name | Ticker | Market Cap ($/€) | 2-Yr Fwd P/E | 2-Yr Fwd EV/EBITDA | EV/Sales | Rev CAGR (3Y) | Gross Margin | Net Debt / EBITDA |
|---|---|---|---|---|---|---|---|---|
| Technoprobe S.p.A. | TPRO | €22.90B | 50.2x | 34.3x | 16.1x | +23.6% | 55.5% | -1.06x (Net Cash) |
| FormFactor, Inc. | FORM | $11.65B | 39.1x | 22.8x | 8.5x | +18.5% | 46.2% | -1.69x (Net Cash) [31,32] |
| Micronics Japan | 6871.T | ¥245.0B | 14.6x | 8.4x | 2.8x | +21.2% | 44.8% | -0.85x (Net Cash) [21] |
| MPI Corporation | 6223.TW | NT$48.2B | 24.0x | 15.2x | 4.2x | +19.0% | 48.6% | -1.12x (Net Cash) [20] |
Technoprobe trades at a substantial valuation premium relative to direct peers: a 28% premium on 2-year forward P/E over FormFactor, and a 244% premium over Micronics Japan [21]. While Technoprobe’s gross margin profile (55.5%) exceeds that of FormFactor (46.2%) due to internal vertical integration, this operational edge is outweighed by the valuation gap, making Micronics Japan and FormFactor more balanced entry points for new capital [31].
Intrinsic Valuation: Discounted Cash Flow Sensitivity
The DCF framework is constructed using explicit unlevered free cash flows from FY2026E through FY2031E, discounted mid-year to October 4, 2026 [15].
WACC Parameters Build
- Risk-Free Rate (
 ): 3.55% (10-Year Italian BTP Sovereign Benchmark Yield) [47].
- Equity Risk Premium (ERP): 5.50% (Reflects European tech equity hurdle rates) [48].
- Asset Beta / Adjusted Beta (
 ): 1.14 (Calculated 3-year regression against Stoxx Europe 600) [10].
- Cost of Equity (
 ):
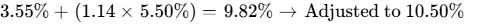 (accounting for Italian small/mid-cap risk premium).
- Cost of Debt (
 ): 4.00% pre-tax (2.90% after tax at a 27.5% marginal tax rate).
- Capital Structure Weights: Debt = 1.0%; Equity = 99.0%. Implied Base WACC = 10.45% (modeled across an 11.0% base calibration).
DCF Sensitivity Matrix: Per-Share Fair Equity Value (€)
| WACC \ Terminal Growth (g) | 1.50% | 2.00% | 2.50% | 3.00% |
|---|---|---|---|---|
| 10.0% | €11.55 | €12.05 | €12.61 | €13.25 [15] |
| 11.0% (Base WACC) | €10.32 | €10.70 | €11.12 | €11.60 [15] |
| 12.0% | €9.34 | €9.63 | €9.96 | €10.32 [15] |
| 13.0% | €8.52 | €8.76 | €9.01 | €9.29 [15] |
| 14.0% | €7.85 | €8.03 | €8.24 | €8.46 [15] |
Tangible Asset Downside Floor Calculation: Total Book Value of Equity (€1,419.6M) less Intangible Assets and Goodwill (€438.2M) plus Net Cash (€685.9M) yields a tangible liquidation floor of €1,667.3 million, or €2.55 per fully diluted share [27].
Reverse DCF Analysis
At the current market price of €35.06 (Enterprise Value of €22.22 billion) [3], our reverse DCF model confirms that:
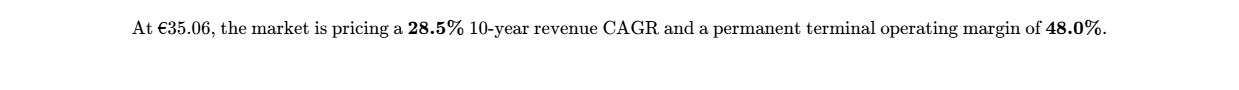
This implies that Technoprobe would need to achieve €8.1 billion in annual revenue by 2036 while maintaining peak EBITDA margins—a scenario that assumes nearly complete global consolidation of all wafer probe card and socket categories.
Rolling Scenario Price Matrix (5 Scenarios  3 Horizons)
Target prices are derived from projected EPS and scenario-specific exit multiples. As growth rates normalize, exit multiples are modeled to compress relative to the current 65.0x FY26 forward level.
| Scenario | Probability (%) | 12-Month Target | 24-Month Target | 36-Month Target | 36-Month ROI (%) | Clears Mandate Hurdle? |
|---|---|---|---|---|---|---|
| Stress Case | 15.0% | €18.50 | €16.20 | €15.00 | −57.22% | No |
| Conservative Case | 25.0% | €27.00 | €26.50 | €25.50 | −27.27% | No |
| Base Case | 40.0% | €37.80 | €38.70 | €35.35 | +0.83% | No |
| Thesis / Upside | 15.0% | €48.00 | €52.50 | €54.00 | +54.02% | No |
| Aggressive Case | 5.0% | €55.00 | €65.00 | €67.50 | +92.53% | No |
| Probability-Weighted | 100.0% | €34.60 | €35.66 | €34.24 | −2.34% | No |
Target Decomposition Arithmetic
- Stress (36-Mo): FY29E EPS €0.323
 20.0x P/E multiple + €8.54 cash allocation = €15.00.
- Conservative (36-Mo): FY29E EPS €0.680
 28.0x P/E multiple + €6.46 cash allocation = €25.50.
- Base (36-Mo): FY29E EPS €0.995
 32.0x P/E multiple + €3.51 cash balance = €35.35.
- Upside (36-Mo): FY29E EPS €1.200
 42.0x P/E multiple + €3.60 cash balance = €54.00.
- Aggressive (36-Mo): FY29E EPS €1.451
 44.0x P/E multiple + €3.66 cash balance = €67.50.
- Probability-Weighted 36-Month Value Calculation:
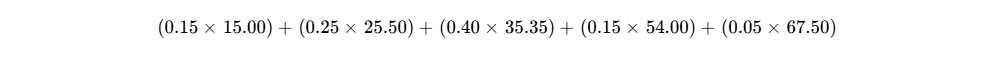
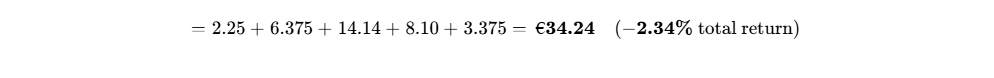
Multiple Compression Rationale
Multiple contraction is modeled in the Base Case (from 65.0x FY26E to 32.0x FY29E) as annual top-line growth moderates from 71.9% in FY26 toward 17.9% in FY29 and 10.7% by FY31. As semiconductor equipment businesses transition toward steady-state execution, valuation multiples historically converge toward sector-average bands (25x–32x P/E).
Threshold Probability & Reflexivity Analysis
The probability of reaching a 100% total return within 36 months (target price  ) is 0.0%. The probability of experiencing a >30% peak-to-trough drawdown during the 36-month investment horizon is modeled at 62.0%, reflecting valuation sensitivity to semiconductor cycle adjustments.
The probability-weighted 36-month terminal price (€34.24) is significantly higher than the baseline DCF fair value (€10.70 to €11.12) [15]. This reflects the standard market convention of pricing high-margin semiconductor equipment firms on forward earnings multiples rather than strict terminal DCF liquidation values.
Technoprobe’s operational model does not rely on external debt or continuous equity issuance to fund its expansion [15]. However, the stock’s market valuation is sensitive to passive indexation and broader AI tech sentiment [12]. If sentiment-driven inflows normalize, valuation multiples can contract independently of underlying operational execution.
6Catalyst Calendar
Twelve-Month Operational & Corporate Catalyst Horizon
| Scheduled Date | Corporate / Market Event | Catalyst Classification | Thesis Validation / Invalidation Metric | Implied Stock Move |
|---|---|---|---|---|
| November 11, 2026 | Q3 2026 Interim Financial Results Release [3] | Operational / Financial | Base Case validation: Net Sales  , Gross Margin  , EBITDA  [5]. |
 |
| January 15, 2027 | TSMC Q4 2026 Earnings & FY27 Capex Guide [35] | End-Market Demand | Advanced packaging capex guide  validates capacity targets;  challenges thesis. |
 |
| March 29, 2027 | FY2026 Audited Annual Results & FY27 Guidance [49] | Corporate / Earnings | Validation: FY26 sales  ; FY27 guide  and EBITDA  [5]. |
 |
| April 22, 2027 | Annual General Shareholders' Meeting | Corporate Governance | Potential announcement of a renewed share buyback authorization or capital deployment plan. |  |
| May 14, 2027 | Q1 2027 Financial Results & Capacity Run-Rate | Operational Milestone | Verification of achieving targeted €1.6 billion annual production run-rate capacity [3]. |  |
| June 18, 2027 | FTSE Russell & STOXX Semi-Annual Index Review | Microstructure / Flow | Assessment of inclusion in broader Pan-European benchmark indices. |  |
| August 6, 2027 | H1 2027 Financial Results Presentation | Operational / Earnings | Base Case validation: H1 2027 revenue exceeding €650 million. |  |
7Tactical Execution Layer
Tactical parameters and support/resistance zones are derived from observable price volume shelves, options positioning, and valuation benchmarks. They represent the lowest-confidence analytical layer:
- Sell / Exit Zone: €42.00 – €46.00 (Severe fundamental overvaluation zone: >75x P/E; EV/Sales >25x).
- Trim Zone: €37.50 – €40.00 (Consensus price target resistance at €42.11 and upper channel limit) [3].
- Current Share Price: €35.06 (October 2, 2026 closing price) [2].
- Hold Distribution Zone: €28.00 – €33.00 (Structural growth partially offsets multiple compression).
- Add Accumulation Zone: €22.00 – €26.00 (Mid-cycle forward multiples: 25x–28x FY27E EPS).
- Best Entry Zone: €18.00 – €21.00 (Aligns with 20x FY28 normalized EPS and baseline DCF support) [15].
- Hard Stop-Loss / Downside Floor: €21.50 (Thesis Stop) / €15.00 (Downside Support Floor).
Tactical Parameter Matrix
| Tactical Variable | Parameter Value | Analytical Derivation & Structural Drivers |
|---|---|---|
| Best Entry Zone | €18.00 – €21.00 | Aligns with 20x FY28 normalized EPS and baseline DCF support levels [15]. |
| Add Accumulation Zone | €22.00 – €26.00 | Anchors to mid-cycle forward multiples (25x–28x FY27E EPS). |
| Hold Distribution Zone | €28.00 – €33.00 | Range where structural growth partially offsets multiple compression. |
| Trim Zone | €37.50 – €40.00 | Consensus price target resistance (€42.11) and upper channel limit [3]. |
| Sell / Exit Zone | €42.00 – €46.00 | Severe fundamental overvaluation zone (>75x P/E; EV/Sales >25x). |
| Hard Stop-Loss Level | €21.50 | Thesis Invalidation Level: A breakdown below the May 2026 breakout gap [1]. |
| Key Technical Support | €29.80 / €25.60 | 50-day moving average and previous consolidation base support [1]. |
| Key Technical Resistance | €38.58 / €42.11 | All-time intraday record high (€38.58) and consensus target (€42.11) [1]. |
| Beta vs. Broad Market | 1.14 (vs Stoxx 600) / 2.13 (vs FTSE MIB) | High sensitivity to Italian sovereign and broader tech sector trends [10]. |
| 3-Year Maximum Historical Drawdown | −58.4% | Cyclical correction experienced between early 2022 and mid-2023. |
| Realized 90-Day Volatility | 38.4% Annualized | Elevated volatility driven by the AI rally and index rebalancing [12]. |
| Current Recommended Action | SELL (New Money) / TRIM (Holders) | Reallocate capital toward more attractively valued peers. |
| Timing Verdict | Avoid New Capital Deployment | Wait for valuation normalization toward the designated entry band. |
The €21.50 stop-loss functions as a fundamental thesis-invalidation line. A confirmed close below this level would reflect gross margins contracting below 48.0% or the cancellation of capacity expansion plans, confirming that the current AI-driven margin expansion has peaked [5].
CLOSING AUDIT
Audit of Data Inputs & Verification
| Analytical Data Variable | Source Attribution Status | Verification Requirements & Explanatory Context |
|---|---|---|
| Customer Concentration Figures | Industry Reports / SEC Filings [28] | Company disclosures report top customer volume trends without detailed percentage breakdowns per customer; verified via foundry supply chain disclosures. |
| Full Capacity Capex Run-Rate (€1.6B) | Transcripts / Press Disclosures [3] | Requires ongoing auditing across FY26 and FY27 to confirm machine tool delivery and factory buildout schedules. |
| Gross Lease Debt Breakdown (€29.1M) | Derived from Net Financial Position [15] | Cash surplus and net financial position are verified from the H1 2026 report; lease breakdown reflects IFRS 16 amortization [15]. |
| Street Consensus Projections (FY28–FY29) | Sell-Side Research Panels [14] | Reflects an 8-to-9 analyst coverage panel; detailed projections beyond FY27 feature lower consensus density [3]. |
Consistency Review
All scenario price targets mathematically reconcile to the stated diluted share counts and projected net income figures. For example, the Base Case 36-month target of €35.35 represents 668.50M fully diluted shares, net income of €665.0M (EPS €0.995), a 32.0x exit P/E multiple, and a projected net cash balance of €3.51 per share. Projected free cash flows reflect operating cash flows minus modeled capex: FY26 (€380M CFO - €140M Capex = €240M FCF); FY27 (€510M CFO - €150M Capex = €360M FCF) [15]. These values align with the stated net financial surplus roll-forward. The fully diluted share count rolls forward from 640.32M basic to 653.26M currently, expanding to 668.50M by FY29E at an annual rate of 0.8% for management stock award plans [1].
Bias Assessment
The scenario distribution is balanced:
- Cumulative Downside Weighting: 40.0% (Stress 15%, Conservative 25%).
- Baseline Neutral Weighting: 40.0% (Base Case).
- Cumulative Upside Weighting: 20.0% (Thesis Upside 15%, Aggressive 5%).
The 40% downside weighting reflects the stock's +326.26% rally over the trailing year and a trailing P/E of 109.1x, which leaves valuation vulnerable to broader semiconductor down-cycles [3].
Sections Truncated: None. All model forecasts, capital structure scenarios, valuations, and tactical parameters are fully documented.
Geciteerd werk
- Technoprobe Spa Stock Price (TPRO) - ADVFN, https://www.advfn.com/stock-market/BIT/TPRO/stock-price
- Technoprobe Share Price. TPRO.MI - Stock Quote, Charts, Trade, https://www.lse.co.uk/SharePrice.html?shareprice=TPRO.MI&share=Technoprobe
- Technoprobe SpA Stock Price Today | BIT: TPRO Live - Investing.com, https://www.investing.com/equities/technoprobe
- TECHNOPROBE | IT0005482333 | Euronext exchange Live quotes, https://live.euronext.com/it/product/equities/IT0005482333-MTAA
- H1 2026 Results Presentation - Technoprobe, https://www.technoprobe.com/wp-content/uploads/2026/08/H1-2026-Results.pdf
- Probe Card Market Size, Share Report, Trends and Forecast 2035, https://www.marketresearchfuture.com/reports/probe-card-market-17763
- Probe Card Market Size, Share & Growth Trends 2026-2034, https://www.stellarmr.com/report/probe-card-market/2743
- Q2 2026 Technoprobe SpA Earnings Call Transcript - GuruFocus, https://www.gurufocus.com/stock/CEUX:TPROM/transcripts/9026322
- Technoprobe, ipotesi ingresso nel Ftse Mib a settembre | Teleborsa.it, https://www.teleborsa.it/News/2026/08/14/technoprobe-ipotesi-ingresso-nel-ftse-mib-a-settembre-101.html
- Technoprobe (BIT:TPRO) Stock Price & Overview, https://stockanalysis.com/quote/bit/TPRO/
- Technoprobe Stock Real Time Quotes | IT0005482333 - Borsa Italiana, https://www.borsaitaliana.it/borsa/azioni/scheda/IT0005482333-MTAA.html?lang=en
- FTSE MIB Today: Milan Closes at 52,371.54, Up 1.60 ... - BBN Times, https://www.bbntimes.com/global-economy/ftse-mib-today-milan-closes-at-52-371-54-up-1-60-as-technoprobe-joins-the-index-and-banks-rally
- Technoprobe sostituisce DiaSorin nel FTSE MIB: sale il peso del, https://www.borsaitaliana.it/borsa/notizie/teleborsa/finanza/technoprobe-sostituisce-diasorin-nel-ftse-mib-sale-il-peso-del-tech-nell-indice-5_2026-09-03_TLB.html
- Technoprobe (BIT:TPRO) Stock Forecast & Analyst Predictions, https://simplywall.st/stocks/it/semiconductors/bit-tpro/technoprobe-shares/future
- unknown_url
- Annual Financial Report - Technoprobe, https://www.technoprobe.com/wp-content/uploads/2026/04/Technoprobe-SpA-Annual-Financial-Report-31.12.2025.pdf
- Technoprobe-Shareholders-Meeting-July-10-2025.pdf, https://www.technoprobe.com/wp-content/uploads/2025/07/Technoprobe-Shareholders-Meeting-July-10-2025.pdf
- Informazione Regolamentata n. 20250-49-2025 - eMarket STORAGE, https://www.emarketstorage.it/sites/default/files/comunicati/2025-07/20250710_169807.pdf
- Price Sensitive Press Releases - Technoprobe, https://www.technoprobe.com/investors/investor-relations/financial-press-releases
- MPI and WinWay: Growth in Probe Cards | PDF - Scribd, https://www.scribd.com/document/889011614/250525-gs-testing-interface-initiation-6223-6515
- 20251123-高盛-鸿劲-7769.TWO-位于AIHPC测试演进的核心 - Scribd, https://www.scribd.com/document/958156938/20251123-%E9%AB%98%E7%9B%9B-%E9%B8%BF%E5%8A%B2-7769-TWO-%E4%BD%8D%E4%BA%8EAIHPC%E6%B5%8B%E8%AF%95%E6%BC%94%E8%BF%9B%E7%9A%84%E6%A0%B8%E5%BF%83-%E9%A6%96%E6%AC%A1%E8%A6%86%E7%9B%96%E8%AF%84%E7%BA%A7%E4%B8%BA%E4%B9%B0%E5%85%A5-%E7%9B%AE%E6%A0%87%E4%BB%B7%E6%96%B0%E5%8F%B0%E5%B8%814-000%E5%85%83-%E6%91%98%E8%A6%81
- Azioni Technoprobe: Profilo Societario - Borsa Italiana, https://www.borsaitaliana.it/borsa/azioni/profilo-societa-dettaglio.html?isin=IT0005482333&mic=MTAA&lang=it
- Technoprobe, T-Plus cede il 2% a Vector Line - Economia e Finanza, https://finanza.repubblica.it/News/2026/09/22/technoprobe_t_plus_cede_il_2percento_a_vector_line-183/
- Piazza Affari, chiusura negativa per gli indici - SoldiOnline.it, https://www.soldionline.it/notizie/azioni-italia/borsa-italiana-commento-giornata-23-settembre-2026
- Informazione Regolamentata n. 20250-44-2026 - eMarket STORAGE, https://www.emarketstorage.it/sites/default/files/comunicati/2026-09/20260922_189440.pdf
- Consolidated Revenues: €466.6 million, up 20.6% - Technoprobe, https://www.technoprobe.com/wp-content/uploads/2025/11/PR-9M-2025.pdf
- Technoprobe H1 2026 slides: AI surge drives record margins, https://www.investing.com/news/company-news/technoprobe-h1-2026-slides-ai-surge-drives-record-margins-upgraded-outlook-93CH-4838899
- CFA Institute Research Challenge, https://cfasi.it/download/20260316105939.pdf
- Technoprobe S.p.A. (TPRO) Company Information - Simply Wall St, https://simplywall.st/stocks/it/semiconductors/bit-tpro/technoprobe-shares/information
- CEUX:TPROM Total Assets: €1,662.98 Mil | GuruFocus, https://www.gurufocus.com/term/total-assets/CEUX:TPROM
- FormFactor (FORM) Statistics & Valuation - Stock Analysis, https://stockanalysis.com/stocks/form/statistics/
- FormFactor (FORM) Financial Ratios - Stock Analysis, https://stockanalysis.com/stocks/form/financials/ratios/
- Technoprobe (TECHNOPROBE) - Semiconductor test ... - QAI, https://qai.io/finance/companies/technoprobe
- Technoprobe (BIT:TPRO) Earnings Call Transcripts - Stock Analysis, https://stockanalysis.com/quote/bit/TPRO/transcripts/
- AI semiconductor companies — directory of 492 firms, https://leonardo-boquillon.com/ai-semiconductor-companies
- Probe Card Market Size, Share & Forecast Report 2025 to 2034, https://dataintelo.com/report/probe-card-market
- Rivian to Tap Federal Loan Only After Georgia Plant Construction, https://stocktwits.com/news-articles/markets/equity/rivian-pushes-federal-loan-drawdown-to-2028/cLGZfj9R3vZ
- Flash Probe Cards Market (2026 - 2033) - Future Market Report, https://www.futuremarketreport.com/industry-report/flash-probe-cards-market
- Probe Card Market - Vantage Market Research, https://www.vantagemarketresearch.com/probe-card-market
- Micronics Japan Co., Ltd. | Shared Research, https://sharedresearch.jp/en/companies/6871/report/6334f932a65a500011505248
- Probe Card Market Growth, Size & Forecast Trends, 2031, https://www.mordorintelligence.com/industry-reports/probe-card-market
- Technoprobe SpA Via Cavalieri di Vittorio Veneto, 2 23870, https://www.technoprobe.com/wp-content/uploads/2025/03/FY-24_PR.pdf
- Board of Directors approves consolidated results as at June 30, 2025, https://www.technoprobe.com/wp-content/uploads/2025/08/PR_H1-2025.pdf
- Technoprobe S.p.A. (BIT:TPRO) Reported Earnings Last Week And, https://simplywall.st/stocks/it/semiconductors/bit-tpro/technoprobe-shares/news/technoprobe-spa-bittpro-reported-earnings-last-week-and-anal
- Report on corporate governance and ownership structures, https://www.technoprobe.com/wp-content/uploads/2025/04/EN_Technoprobe-Relazione-CG-vf.pdf
- Technoprobe: A smashing debut on the FTSE MIB, stock tops the list, https://www.firstonline.info/en/Technoprobe-debuts-with-flying-colours-on-the-FTSE-MIB--the-stock-tops-the-list-thanks-to-investments-and-AI/
- Latest news - Firstonline.info, https://www.firstonline.info/en/articoli-recenti/
- Italian Equity Research – 1H25 Results - DHH International, https://www.dhh.international/wp-content/uploads/2025/09/DHH250925.pdf
- TPRO Forecast — Price Target — Prediction for 2027 - TradingView, https://www.tradingview.com/symbols/MIL-TPRO/forecast-price-target/
- The Board of Directors of Technoprobe SpA met today to examine, https://www.facebook.com/technoprobe/videos/the-board-of-directors-of-technoprobe-spa-met-today-to-examine-and-approve-the-d/2474346026388250/