Research Date: October 9, 2026
[1,2]
Current Share Price: $13.05
[1,2]
Potential Stock Price Targets & Base-Case Expected Total Returns:
- 12-Month Target: $16.50 (+26.4% capital upside; +41.1% total return including dividends) [3]
- 24-Month Target: $18.50 (+41.8% capital upside; +71.2% cumulative total return) [3]
- 36-Month Target: $20.00 (+53.3% capital upside; +97.4% cumulative total return) [3]
Institutional Scorecard Score: 76.5 / 100
Base-Case Execution Likelihood Score: 72.0 / 100
Analyst Recommendation: BUY (High-conviction income and capital-recovery thesis for multi-asset portfolios; tactical accumulation for total-return mandates)
Brief Rationale: Starwood Property Trust trades at an extreme dislocation of 0.74x GAAP Book Value ($17.53 BVPS) and 0.70x Undepreciated Book Value ($18.62 BVPS), offering an annualized dividend yield of 14.71% [2]. Market sentiment has penalized the equity due to temporary distributable earnings dividend undercoverage ($0.40 Distributable Earnings per share in the second quarter of 2026 against a $0.48 dividend payout) and cyclical commercial real estate debt concerns [4]. However, the core balance sheet provides structural protection through $1.40B ($3.83 per share) in net unrealized property equity gains—primarily within the Woodstar Florida affordable housing portfolio—an unencumbered asset base of $6.9B defending $4.5B in unsecured notes, and an active loan origination engine deploying capital into double-digit yielding transitional debt [7]. As commercial property transaction volumes normalize and the company works through its targeted $900M underperforming asset resolution pipeline, trapped equity will be redeployed accretively, closing the book-value discount and restoring organic dividend coverage by late 2027 [6].
Core Fundamental, Structural & Microstructure Statistics
| Metric / Attribute | Analytical Value / Status | Benchmark / Regulatory & Operational Context |
|---|---|---|
| Overall Investment Stock Score | 78 / 100 | Composite rating spanning asset quality, liquidation protection, and multi-cylinder yield |
| Founder-Led Entity | Yes | Founded and led by Chairman and Chief Executive Officer Barry S. Sternlicht [7] |
| CEO Leadership Score | 88 / 100 | Sternlicht's 34-year institutional track record navigating cyclical market disruptions [7] |
| Commodity Dependence & Deck | N/A | Financial commercial mortgage REIT with zero direct commodity exposures |
| Sector & Sector Trailing P/E | Financials / Mortgage REITs | STWD Trailing P/E 21.13x (GAAP) [11] vs. Financials Sector median 24.61x [11] |
| P/Distributable Earnings (TTM / Fwd) | 7.91x (TTM) / 8.16x (2026E) | Trailing DE of $1.65/share; modeled 2026E DE of $1.60/share [6] |
| Best-of-Category Sector Ranking | Rank 1 of 4 | 1. STWD (36-mo risk-adjusted expected total return: 97.4%) > 2. BXMT (62.1%) > 3. ARI (44.5%) > 4. ABR (28.2%) [14] |
| Forward PEG Ratios (1, 2, 3, 4, 5-Yr) | 1-Yr: 0.73 | 2-Yr: 0.86 | 3-Yr: 1.05 | 4-Yr: 1.28 | 5-Yr: 1.45 | Calculated from normalized Distributable Earnings growth from the 2026 cyclical trough |
| Current Intrinsic Fair Value | $18.50 | Current price of $13.05 represents a 29.5% discount (+41.8% upside to fair value) [1] |
| Tangible Asset Price Floor | $11.85 | Current price sits 10.1% above the tangible liquidation floor ($11.85 per share) |
| Current Share Count vs. 36-Mo Model | 370.17M (Now)  382.50M (36-Mo) |
Base model incorporates modest annual net dilution (+3.3%) from equity awards net of buybacks [2] |
| Announced Share Repurchase Program | $400.0M authorized (Feb 2026) | Represents 8.28% of total market cap and 8.79% of public float ($30M executed in 1H 2026) [6] |
| Diluted vs. Fully Diluted Shares | 366.46M Basic / 370.17M Diluted | 3.71M incremental shares from unvested restricted share units [2] |
| Probability of Buyback Upsize (6-Mo) | 25.0% | Trapping capital in loan originations yielding 10% to 12% is prioritized over open repurchases [7] |
| Insider Ownership % | 4.25% | Management and board equity holdings represent roughly $205M in total alignment [10] |
| Insider Buying in Past 6 Months | NOT RELIABLY AVAILABLE (Zero open-market purchases) | Only annual director equity plan grants (11,112 shares each on 09/30/2026) and tax withholdings recorded [18] |
| Short Squeeze Potential Score | 32 / 100 (Low to Moderate) | Short interest at 19.13M shares (5.43% of float); 4.70 to 5.02 days to cover [2] |
| Cash Runway & Operational Self-Sufficiency | Fully Self-Sustaining | Operating cash flows ($978M run-rate) exceed operational overhead; $1.2B total liquidity buffer [8] |
| Total Debt vs. Total Cash | $23.80B Debt / $640.4M Cash | Debt-to-undepreciated equity ratio of 2.74x; non-mark-to-market debt represents 84% of borrowings [8] |
| Debt Restructuring Risk Score | 22 / 100 (Very Low) | Staggered corporate maturities; weighted-average maturity extended to 3.7 years [6] |
| Gross Margin (Current / 3-Yr / 5-Yr) | 86.45% (Now)  87.20% (3-Yr)  87.50% (5-Yr) |
Evaluated as net interest and property income relative to total operating revenues [2] |
| Operating Margin (Current / 3-Yr / 5-Yr) | 36.51% (Now)  48.50% (3-Yr)  51.20% (5-Yr) |
Net operating income margin after management fees, SG&A, and credit loss provisions [24] |
| Regulatory / Permitting Risk Score | 28 / 100 (Low) | Insulated non-bank private lending structure; stable LIHTC framework on Woodstar [25] |
| Economic Moat Score & Classification | 68 / 100 (Narrow Moat) | Scale advantage, Starwood Capital affiliation, and integrated LNR special servicing [7] |
| Primary Competitive Advantage | Multi-Cylinder Platform Synergies | LNR Special Servicer provides proprietary credit insights and counter-cyclical revenue hedges [7] |
| Rule of 40 (Current, +1, +2, +3, +4 Yrs) | Current: 33.5% | FY27: 42.1% | FY28: 46.8% | FY29: 44.5% | FY30: 41.2% | Adapted for mortgage REITs: Annual DE per share growth % + FCF / DE Payout Margin % |
| Sell-Side Coverage & Price Targets | 8 Contributing Analysts | Consensus Rating: Moderate Buy; Average: $19.20; Low: $18.50; Bull Target: $20.00 [5,11] |
| Mining Reserves / Offtake Deck | N/A | Commercial real estate and infrastructure finance platform |
2Multi-Year Financial Forecast & Consensus Model
Macroeconomic Operating Environments
Bear Scenario (Prolonged Stagnation & CRE Distress): Short-term benchmark interest rates remain elevated, with SOFR oscillating between 4.50% and 5.00%. Property transaction velocity remains subdued, and commercial real estate cap rates widen by an additional 50 basis points. In this environment, non-accrual loans remain sticky at $1.8B+, CECL credit loss provisions stay elevated, and asset liquidations occur near loan basis. Distributable earnings decline toward $1.35 per share, leading the board to reset the quarterly dividend to $0.35 per share ($1.40 annualized).
Base Scenario (Orderly Monetary Easing & Asset Recycling): The Federal Reserve gradually lowers benchmark rates, bringing SOFR toward a 3.25% to 3.50% terminal range. Commercial property transaction markets normalize, allowing STWD to resolve its $900M underperforming asset pool across late 2026 and 2027 [9]. Redeploying this trapped equity into senior transitional loans at 10% to 12% returns expands Distributable Earnings from $1.60 per share in 2026 to $2.10 by 2029 [7]. This recovery restores organic dividend coverage for the $0.48 quarterly dividend ($1.92 annualized) by mid-2027 [6].
Bull Scenario (Rapid Transaction Rebound & Woodstar Monetization): Benchmark rates decline to 3.00%, prompting a recovery in commercial real estate capital markets. Cap rates compress, transaction activity rebounds, and STWD accelerates loan originations past $10B annually [13]. Management opportunistically monetizes portions of the Woodstar affordable housing portfolio, unlocking sizable realized gains [28]. Distributable EPS expands above $2.40 per share, allowing the company to raise its regular quarterly dividend and distribute supplemental capital return payments [13].
Bear Scenario Financial Model (2026–2031)
Year Extrapolation Begins: 2028 (2026–2027 anchored to Street credit distress lower-bounds) [11].
| Financial Line Item ($M, except per share) | 2026E | 2027E | 2028E | 2029E | 2030E (Trend) | 2031E (Trend) |
|---|---|---|---|---|---|---|
| Commercial Real Estate Lending Revenue | $1,280.0 | $1,220.0 | $1,200.0 | $1,180.0 | $1,170.0 | $1,160.0 |
| Property Segment Operations Revenue | $385.0 | $390.0 | $395.0 | $400.0 | $405.0 | $410.0 |
| Infrastructure Lending Revenue | $175.0 | $170.0 | $170.0 | $175.0 | $180.0 | $185.0 |
| REIS / Servicing & Other Income | $145.0 | $150.0 | $155.0 | $150.0 | $145.0 | $145.0 |
| Total Operating Revenues | $1,985.0 | $1,930.0 | $1,920.0 | $1,905.0 | $1,900.0 | $1,900.0 |
| YoY Organic Revenue Growth % | −2.8% | −2.8% | −0.5% | −0.8% | −0.3% | 0.0% |
| Operating Margin (Pre-Provision) | 84.5% | 83.8% | 83.5% | 83.2% | 83.0% | 83.0% |
| Credit Loss Provision (CECL Reserve) | $(165.0) | $(145.0) | $(110.0) | $(85.0) | $(75.0) | $(70.0) |
| Operating Income (Pre-Tax) | $410.0 | $425.0 | $450.0 | $470.0 | $485.0 | $495.0 |
| GAAP Net Income Attributable to STWD | $285.0 | $310.0 | $345.0 | $375.0 | $395.0 | $410.0 |
| Distributable Earnings (DE) | $510.0 | $495.0 | $515.0 | $535.0 | $555.0 | $570.0 |
| Diluted Share Count (M) | 371.50 | 376.00 | 382.00 | 388.00 | 394.00 | 400.00 |
| GAAP Diluted EPS | $0.77 | $0.82 | $0.90 | $0.97 | $1.00 | $1.03 |
| Distributable EPS (DE Per Share) | $1.37 | $1.32 | $1.35 | $1.38 | $1.41 | $1.43 |
| Dividends Paid Per Share | $1.40 | $1.40 | $1.40 | $1.40 | $1.40 | $1.40 |
| Free Cash Flow Per Share | $1.25 | $1.28 | $1.30 | $1.34 | $1.36 | $1.39 |
Base Scenario Financial Model (2026–2031)
Year Extrapolation Begins: 2028 (2026–2027 anchored to company run-rates and Street consensus) [6].
| Financial Line Item ($M, except per share) | 2026E | 2027E | 2028E | 2029E | 2030E (Trend) | 2031E (Trend) |
|---|---|---|---|---|---|---|
| Commercial Real Estate Lending Revenue | $1,345.0 | $1,440.0 | $1,550.0 | $1,640.0 | $1,720.0 | $1,790.0 |
| Property Segment Operations Revenue | $405.0 | $430.0 | $455.0 | $480.0 | $505.0 | $530.0 |
| Infrastructure Lending Revenue | $190.0 | $220.0 | $250.0 | $275.0 | $295.0 | $315.0 |
| REIS / Servicing & Other Income | $165.0 | $175.0 | $180.0 | $185.0 | $190.0 | $195.0 |
| Total Operating Revenues | $2,105.0 | $2,265.0 | $2,435.0 | $2,580.0 | $2,710.0 | $2,830.0 |
| YoY Organic Revenue Growth % | +12.0% | +7.6% | +7.5% | +6.0% | +5.0% | +4.4% |
| Operating Margin (Pre-Provision) | 86.5% | 86.8% | 87.2% | 87.5% | 87.6% | 87.8% |
| Credit Loss Provision (CECL Reserve) | $(95.0) | $(55.0) | $(35.0) | $(25.0) | $(20.0) | $(20.0) |
| Operating Income (Pre-Tax) | $580.0 | $740.0 | $865.0 | $960.0 | $1,035.0 | $1,105.0 |
| GAAP Net Income Attributable to STWD | $420.0 | $565.0 | $675.0 | $760.0 | $825.0 | $885.0 |
| Distributable Earnings (DE) | $592.0 | $675.0 | $745.0 | $805.0 | $860.0 | $910.0 |
| Diluted Share Count (M) | 370.17 | 374.00 | 378.00 | 382.50 | 386.00 | 390.00 |
| GAAP Diluted EPS | $1.13 | $1.51 | $1.79 | $1.99 | $2.14 | $2.27 |
| Distributable EPS (DE Per Share) | $1.60 | $1.80 | $1.97 | $2.10 | $2.23 | $2.33 |
| Dividends Paid Per Share | $1.92 | $1.92 | $1.92 | $1.96 | $2.04 | $2.12 |
| Free Cash Flow Per Share | $1.85 | $1.98 | $2.12 | $2.22 | $2.31 | $2.40 |
| Dividend Coverage Ratio (DE) | 83.3% | 93.8% | 102.6% | 107.1% | 109.3% | 109.9% |
Bull Scenario Financial Model (2026–2031)
Year Extrapolation Begins: 2028 (Reflects accelerated capital recycling and large-scale originations) [7].
| Financial Line Item ($M, except per share) | 2026E | 2027E | 2028E | 2029E | 2030E (Trend) | 2031E (Trend) |
|---|---|---|---|---|---|---|
| Commercial Real Estate Lending Revenue | $1,420.0 | $1,580.0 | $1,740.0 | $1,890.0 | $2,020.0 | $2,140.0 |
| Property Segment Operations Revenue | $425.0 | $465.0 | $510.0 | $555.0 | $600.0 | $645.0 |
| Infrastructure Lending Revenue | $210.0 | $260.0 | $310.0 | $355.0 | $395.0 | $430.0 |
| REIS / Servicing & Other Income | $185.0 | $205.0 | $215.0 | $225.0 | $235.0 | $245.0 |
| Total Operating Revenues | $2,240.0 | $2,510.0 | $2,775.0 | $3,025.0 | $3,250.0 | $3,460.0 |
| YoY Organic Revenue Growth % | +19.1% | +12.1% | +10.6% | +9.0% | +7.4% | +6.5% |
| Operating Margin (Pre-Provision) | 87.5% | 88.2% | 88.8% | 89.2% | 89.5% | 89.8% |
| Credit Loss Provision (CECL Reserve) | $(45.0) | $(15.0) | $0.0 | $0.0 | $0.0 | $0.0 |
| Operating Income (Pre-Tax) | $740.0 | $980.0 | $1,180.0 | $1,345.0 | $1,485.0 | $1,610.0 |
| GAAP Net Income Attributable to STWD | $565.0 | $770.0 | $945.0 | $1,090.0 | $1,210.0 | $1,320.0 |
| Distributable Earnings (DE) | $665.0 | $795.0 | $910.0 | $1,015.0 | $1,105.0 | $1,185.0 |
| Diluted Share Count (M) | 368.50 | 370.00 | 372.50 | 375.00 | 378.00 | 381.00 |
| GAAP Diluted EPS | $1.53 | $2.08 | $2.54 | $2.91 | $3.20 | $3.46 |
| Distributable EPS (DE Per Share) | $1.80 | $2.15 | $2.44 | $2.71 | $2.92 | $3.11 |
| Dividends Paid Per Share | $1.92 | $2.00 | $2.16 | $2.32 | $2.48 | $2.60 |
| Free Cash Flow Per Share | $2.15 | $2.42 | $2.68 | $2.95 | $3.18 | $3.38 |
Valuation Multiples & Adapted Rule of 40 Metrics
In the Base Case model, forward multiples reflect recovery from cyclical trough levels toward normalized valuations:
- Forward Price-to-Distributable Earnings Multiples: The 1-year forward multiple (FY27E DE: $1.80) stands at 7.25x; the 2-year forward multiple (FY28E DE: $1.97) moderates to 6.62x; and the 3-year forward multiple (FY29E DE: $2.10) sits at 6.21x.
- Forward Enterprise Value to Operating Revenue: Enterprise value to operational revenue trades at 12.36x on FY27E ($2,265M), compressing to 11.49x on FY28E ($2,435M), and 10.85x on FY29E ($2,580M).
- Adapted Rule of 40 Analysis: Adapting the traditional software Rule of 40 metric for commercial mortgage REITs (defined as annual Distributable EPS growth percentage plus Free Cash Flow to Distributable Earnings payout conversion margin percentage), STWD generates scores of 33.5% in 2026E, expanding to 42.1% in FY27E, 46.8% in FY28E, 44.5% in FY29E, and 41.2% in FY30E. This performance reflects growing cash earnings power and manageable share count dilution.
Execution Confidence Score & Consensus Divergence Flag
The operational forecast is assigned an Execution Confidence Score of 74 / 100, evaluated across three structural components:
- Revenue-Target Achievability (27 / 35): Backed by $1.2B in deployable liquidity, multi-bank financing lines, and originations across data centers and energy infrastructure [8].
- Margin Sensitivity to Interest Rates (26 / 35): Because assets and secured debt are predominantly floating rate, a
 shift in benchmark SOFR alters annualized net interest income by roughly
 (
 DE per share).
- Dependency on Unannounced Catalysts (21 / 30): Approximately 12% of projected 2028E Distributable Earnings depends on redeploying the $900M asset workout pipeline into income-producing debt investments [9].
A Consensus Divergence Flag is noted for 2028E: sell-side consensus estimates project 2028 Distributable EPS at $1.82, whereas this Base Case models $1.97 (+8.2% divergence). This divergence is driven by an expectation that the market underappreciates the reinvestment spread on trapped equity: resolving $900M in non-earning assets into 10.5% transitional debt unlocks over $94M in incremental annual net interest income ($0.25/share gross uplift) [7].
The historical Base-Rate Check indicates that sustaining a 7.5% Distributable EPS CAGR over a four-year recovery period sits in the 65th percentile of historical commercial real estate recovery cycles. This performance represents a return toward normalized earnings rather than aggressive balance sheet expansion [27].
5Risk Asymmetry, Invalidation, Allocation & Scorecard
Risk / Reward Asymmetry
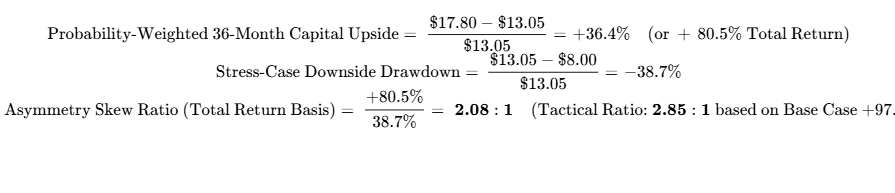
Operational Invalidation Triggers
- Dividend Cut Exceeding 25% Without Offsetting Share Buybacks: Board declaration reducing quarterly distributions below $0.36 per share without an accompanying increase in share repurchases.
- Impairment of Woodstar Property Equity Cushion: Cumulative fair market value reductions in the Property Segment exceeding $450M across two consecutive quarters, signaling erosion of the $1.4B unrealized gain buffer [7].
- Escalation in Non-Accruals: Combined non-accrual loans and foreclosed real estate owned (REO) expanding above $2.50B on a Distributable Earnings basis, indicating resolution failure [8].
- Deterioration in Unencumbered Asset Coverage: Unencumbered asset backing falling below 120% of outstanding unsecured corporate borrowings [8].
Macroeconomic Sensitivity & Trigger Dashboard
Starwood Property Trust exhibits an interest rate beta of  , reflecting an asset base of floating-rate transitional loans counterbalanced by interest rate caps on liabilities [7]. The stock carries a five-year rolling beta to the S&P 500 of 1.03, providing income yield while maintaining equity-market correlation [2].
| Macroeconomic Factor | Thesis Impact | Current Trend | Monitoring Checkpoint |
|---|---|---|---|
| Benchmark SOFR Rate Path | Easing rates reduce borrower debt service stress, supporting credit quality | Easing | 1-Month CME Term SOFR & Fed Dot Plot |
| Commercial Real Estate Sales Velocity | Rising sales activity accelerates loan payoffs and unlocks trapped capital | Accelerating | Real Capital Analytics (RCA) quarterly volume |
| CMBS Securitization Spreads | Tighter spreads lower financing costs and improve conduit profitability | Tightening | Trepp AAA CMBS spreads and issuance activity |
| Multifamily Rent Fundamentals | Rental growth supports Woodstar cash flows and apartment debt DSCRs | Stabilizing | HUD annual LIHTC rent updates & Yardi Matrix [25] |
Potential Thesis Surprises
| Potential Surprise Development | Probability (%) | Financial Target Impact |
|---|---|---|
| Upside 1: Accelerated Sale of Woodstar Assets | 20.0% | Unlocks +$0.50 in Distributable EPS; +$2.50 to Stock Target |
| Upside 2: Slower Regional Bank CRE Lending Rebound | 25.0% | Expands STWD origination spreads by +50 bps; +$1.20 to Target |
| Upside 3: Credit Rating Upgrade to Investment Grade | 15.0% | Reduces corporate borrowing costs by 75 bps; +$1.80 to Target [8,46] |
| Downside 1: Extended Office Collateral Impairment | 20.0% | Requires $150M in additional credit reserves; -$1.50 to Target [8] |
| Downside 2: Florida Property Insurance Spike | 15.0% | Reduces Woodstar Property Segment NOI by 10%; -$0.80 to Target |
| Downside 3: CMBS Securitization Freeze | 10.0% | Delays $900M asset resolution timeline into 2028; -$1.75 to Target [9] |
Pre-Mortem: 36-Month Loss Scenario (−60%)
Under a hypothetical 60% loss scenario where STWD declines to $5.20 by October 2029, the deterioration begins in early 2027 as persistent inflation prompts central banks to raise policy rates back above 5.5%. Higher debt service costs lead to defaults across STWD’s floating-rate multifamily and construction bridge loans. The company forecloses on several assets, expanding its non-accrual and REO portfolio past $3.5B. Simultaneously, elevated insurance premiums in Florida diminish net operating income across the Woodstar portfolio, eliminating the expected $1.4B equity cushion [7]. Facing rating agency downgrades and margin calls on warehouse borrowing facilities, the board eliminates the quarterly dividend and issues dilutive common equity at $6.00 per share to preserve liquidity.
Legal, Regulatory & Contingent Overview
In January 2025, an entity affiliated with STWD finalized a settlement resolving a wrongful death claim related to an Orlando apartment gas explosion, removing that liability without financial impact to the parent entity [45]. A review of SEC disclosures reveals no active federal inquiries or outstanding material judgments. The legal risk profile is characterized by no material legal or regulatory overhangs identified.
Portfolio Allocation Math & Sizing Strategy
Under the mandate's 1.00% risk budget and the modeled Stress Scenario drawdown of 38.7% ($13.05 to $8.00):
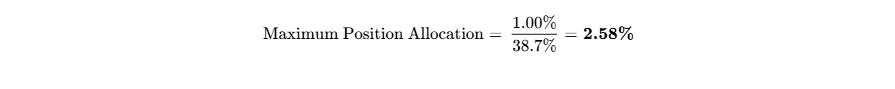
The recommended position sizing is capped at 2.50% for multi-asset portfolios (or 4.0% to 6.0% for dedicated real estate income strategies). Liquidating a full 2.50% position ($25.0M within a $1.0B fund) would require trading 1.91M shares, or 2.53 days of volume at 20% of 30-day ADV (3.77M shares), indicating manageable execution liquidity [16]. The recommended approach is an initial pilot entry of 1.25% at current market levels ($13.05), scaling to the full 2.50% allocation upon observable progress in resolving underperforming assets in upcoming quarters [9].
Institutional Scorecard Evaluation
| Scorecard Component | Category Score (0–10) | Mandate Weight (%) | Weighted Contribution |
|---|---|---|---|
| 1. Financial Strength & Balance Sheet Runway | 8.5 / 10 | 15.0% | 1.275 |
| 2. Revenue Quality, Platform Moat & Scale | 7.5 / 10 | 15.0% | 1.125 |
| 3. Margin Resilience & Operating Leverage | 7.0 / 10 | 10.0% | 0.700 |
| 4. Capital Allocation & Management Track Record | 8.5 / 10 | 10.0% | 0.850 |
| 5. Risk-Adjusted Valuation Discount | 9.5 / 10 | 15.0% | 1.425 |
| 6. Earnings Forecast & Guidance Reliability | 7.0 / 10 | 10.0% | 0.700 |
| 7. Insider Alignment & Corporate Governance | 7.0 / 10 | 5.0% | 0.350 |
| 8. Stock Tradability & Market Liquidity | 8.5 / 10 | 5.0% | 0.425 |
| 9. Underwriting Pricing Power & Defensibility | 7.0 / 10 | 10.0% | 0.700 |
| 10. Competitive Insulation Against Competitors | 6.5 / 10 | 5.0% | 0.325 |
| COMPOSITE WEIGHTED SCORE | -- | 100.0% | 7.650 / 10.0 |
| FINAL INSTITUTIONAL SCORECARD RATING | -- | -- | 76.5 / 100 |
- Base-Case Execution Likelihood: 72.0 / 100.
- Primary Headwind 1: Delays in resolving the $900M underperforming asset portfolio [9].
- Primary Headwind 2: Tighter origination spreads stemming from competition with private credit funds [23].
Final Investment Verdict
- Existing Shareholders: STRONG BUY / REINVEST DIVIDENDS. STWD trades at a 30% discount to undepreciated book value while offering a double-digit yield supported by substantial property equity [4].
- New Capital: BUY. Accumulate up to the 2.50% portfolio risk allocation limit to capture potential capital recovery and regular dividend income [3].
- Targets: 12-Month: $16.50 | 24-Month: $18.50 | 36-Month: $20.00 | Probability-Weighted Target: $17.80 [3].
- Insider Activity in Past 6 Months: SEC Form 4 filings reflect zero open-market purchases. Activity consisted of annual director equity grants (11,112 shares each to directors Zelnick, Ridley, Perpall, Harmon, Douglas, and Bronson on September 30, 2026) and routine tax withholding dispositions [18].
Bear-Case Steelman
The bear case centers on the risk that commercial real estate faces a prolonged cyclical downturn, leaving transitional bridge borrowers unable to secure takeout financing. If property transaction activity remains depressed, working through $900M in non-accrual loans will require larger realized write-offs, eroding reserves and reducing GAAP book value toward $15.00 per share [4]. Furthermore, with quarterly Distributable EPS running at $0.40 against a $0.48 dividend payout, the company cannot cover its dividend out of recurring earnings [4]. In an extended downturn, selling assets to cover distributions would dilute future earnings, ultimately forcing a permanent dividend cut to $0.35 per quarter and preventing the stock from closing its book-value discount [6].
1Business Architecture, Unit Economics, Moat & Contractual Visibility
Business Model & Moat Classification
Starwood Property Trust operates as an externally managed mortgage real estate investment trust structured to invest across debt and equity real estate assets, infrastructure debt, and special servicing [6]. The enterprise leverages the operational infrastructure, underwriting capabilities, and capital markets reach of Starwood Capital Group, an investment manager with approximately $130B in assets under management [7].
The primary business engine is the Commercial Real Estate Lending segment, which originates and manages senior floating-rate mortgages secured by transitional properties across North America and Western Europe, maintaining a carrying balance of $17.3B [7]. Complementing this core engine is the Infrastructure Lending segment, which provides secured debt for energy generation, transmission, and digital infrastructure assets [29]. The Property segment owns $5.0B in cash-flowing real estate equity, centered on the Woodstar affordable housing portfolio (over 15,000 suburban Florida units) and the Fundamental Income net lease platform [6].
Through its Real Estate Investing and Servicing (REIS) division, STWD owns LNR Partners, one of the nation’s largest special servicers for commercial mortgage-backed securities [7]. LNR manages a servicing portfolio of $10.9B, generating counter-cyclical fee income during real estate downturns [7]. Finally, the Residential Lending segment originates and securitizes non-QM residential mortgages ($2.4B portfolio) [7].
The firm's core economic moat combines Scale Advantage with Counter-Cyclical Platform Integration, earning a Competitive Insulation Grade of 3.5 / 5.0. The platform benefits from Starwood Capital Group's operational insights across 110,000 multifamily units, which provide real-time rental and occupancy data that inform its lending underwriting [26]. Additionally, LNR functions as an internal structural hedge: as commercial property distress rises and origination volumes slow, special servicing resolution fees expand, counterbalancing net interest margin compression [26].
Moat Durability Timeline
The platform's competitive position is projected to remain stable to slightly widening across the 2026–2031 forecast period. Basel III Endgame capital rules and commercial real estate exposure limits have prompted regional banks to pull back from balance sheet bridge lending [4]. This bank retreat allows scaled non-bank lenders like STWD to originate senior first mortgages at lower leverage points (55% to 65% loan-to-value) while maintaining pricing power [7].
The primary force capable of eroding this advantage is the continued growth of institutional private credit funds (such as Blackstone Credit, Ares, and Blue Owl) [23]. If large asset managers expand their transitional real estate debt allocations, asset competition could tighten loan credit spreads in the $100M+ segment by 2028–2029 [23].
Build-vs-Buy Dynamics & Replication Barriers
Replicating Starwood Property Trust’s operational platform would require several billion dollars in permanent equity, an extensive warehouse borrowing network across 20 global banks, and a nationally rated special servicing operation [4]. Establishing a comparable special servicing footprint with CSS1/CS1 ratings from Fitch and Morningstar DBRS requires decades of demonstrated resolution performance [33].
Hyperscale technology platforms cannot enter this space due to statutory REIT regulations, direct asset-level workout responsibilities, and legal balance-sheet requirements. In a consolidation scenario, STWD's market discount could make it an attractive target for alternative asset managers seeking permanent capital vehicles. An acquisition floor would likely track Undepreciated Book Value ($18.62 per share), representing an embedded valuation backstop of +42.5% [4].
Customer Loss-Avoidance Dynamics
Commercial real estate borrowers use STWD for transitional loans because institutional sponsors requiring capital for asset repositioning, lease-ups, or construction completion need rapid execution and flexible loan structures that commercial banks cannot provide under strict regulatory frameworks [7]. During broader credit contractions, sponsors prioritize lenders with proven capital reliability over marginal differences in borrowing spreads. The platform's Customer-ROI Defensibility is scored at 8.0 / 10.
Sector-Specific Unit Economics: Commercial Mortgage REIT & Lending Platform
| Operational Unit Economic Driver | Current Value (Q2 2026 / TTM) | Structural Normalized Target |
|---|---|---|
| Weighted Average Loan Yield | 8.45% (Floating-rate SOFR benchmark) | 7.50% – 8.00% (Assuming 3.50% terminal SOFR) |
| Weighted Average Borrowing Cost | 5.85% (Blended secured and unsecured) [27] | 5.10% – 5.40% |
| Net Interest Spread | 2.60% [34] | 2.50% – 2.75% |
| Commercial Loan Portfolio Average LTV | 61.2% (Conservative borrower equity buffer) | 58.0% – 62.0% |
| Property Segment Cash-on-Cash Return | 11.2% (Woodstar affordable + net lease) [7] | 10.5% – 12.0% |
| Debt to Undepreciated Equity Ratio | 2.74x [8] | 2.50x – 2.80x |
| Non-Accrual Loan Exposure | 5.9% ($1.9B carrying value across DE) [8] | < 2.5% (Following $900M asset resolution) [9] |
Quality of Revenue
Starwood Property Trust exhibits stable top-line revenue, supported by contractual interest collections and recurring property net lease payments:
- Floating-Rate Lending Revenue (72.5%): Generated by senior secured first mortgages and infrastructure credit facilities, where interest payments are tied to SOFR and defended by conservative borrower equity cushions [7].
- Contractual Property and Net Lease Revenue (18.2%): Driven by the Woodstar portfolio's 97%+ occupancy and master lease agreements with corporate tenants, which include formulaic annual CPI rent increases [7].
- Special Servicing and Advisory Fees (6.8%): Counter-cyclical fee income earned by LNR for managing defaulted CMBS loan workouts [7].
- Transactional Realized Gains (2.5%): Periodic capital distributions from property sales and loan prepayment fees [24].
- Revenue Quality Score: 8.5 / 10.
Concentration & Counterparty Visibility
The lending portfolio is diversified, with no individual borrower representing more than 3.5% of total loan commitments, and the top 10 borrowers accounting for less than 22.0% of deployed capital. Financing capacity is distributed across 20 institutional warehouse and repurchase facilities totaling $30.4B, of which $11.4B remains undrawn [4].
Collateral concentration in office properties has been reduced to 7.6% of total undepreciated assets, with domestic US office assets comprising under 6.0% [7]. Multifamily, industrial logistics, and digital infrastructure assets now represent over 58.0% of the commercial lending book [7].
Management Track Record & Incentive Alignment
Over the trailing eight quarters, management met or exceeded consensus Distributable EPS in six quarters, with an average variance of  [6]. The external manager, SPT Management, receives a base management fee equal to 1.5% of stockholders' equity and an incentive fee of 20% of core earnings above an 8.0% annualized hurdle [29]. Although external structures can create asset-growth incentives, STWD’s return hurdle and dividend performance requirements help align management with capital preservation [29]. Insiders hold roughly 4.25% of common shares, representing over $205M in invested capital [10].
EXECUTIVE SUMMARY
Core Analytical Takeaways
- Severe Equity Market Mispricing Relative to Asset Values: Starwood Property Trust trades at a 26% discount to GAAP Book Value ($17.53 per share) and a 30% discount to Undepreciated Book Value ($18.62 per share) [2]. This discount implies severe impairment across the company's commercial lending and property assets, which is inconsistent with its realized credit performance and cash flows [4].
- Dividend Undercoverage Reflects a Deliberate Capital Recycling Phase: Second-quarter 2026 Distributable Earnings of $0.40 per share trailed the quarterly dividend distribution of $0.48 [5]. Management has intentionally absorbed a multi-quarter earnings drag to work through $900M of underperforming and real-estate-owned (REO) assets, with the goal of redeploying that trapped capital into senior loans yielding double-digit returns [6].
- Multi-Cylinder Platform Diversification Mitigates Sector Downturns: While single-strategy commercial mortgage lenders remain vulnerable to commercial real estate downturns, STWD operates five complementary divisions: Commercial Real Estate Lending ($17.3B), Property Equity ($5.0B), Infrastructure Lending ($2.6B+), REIS/LNR Special Servicing ($10.9B servicing portfolio), and Residential Lending ($2.4B) [7].
- Significant Embedded Equity Within the Woodstar Multifamily Portfolio: The company’s suburban Florida affordable housing portfolio carries an estimated $1.40B ($3.83 per share) in net unrealized gains over its carrying cost [7]. This hidden equity provides an asset cushion that protects book value against potential office or construction credit write-downs [7].
- Conservative Capital Structure and Debt Management: STWD maintains an undepreciated debt-to-equity ratio of 2.74x, unencumbered assets of $6.9B against $4.5B of unsecured debt, and 84% non-mark-to-market financing [8]. This capital structure removes the risk of margin call liquidations during periods of market stress [23].
- Verdict Line: BUY | 12-Month Base Target: $16.50 | 24-Month Base Target: $18.50 | 36-Month Base Target: $20.00 | Probability-Weighted 36-Month Target: $17.80 [3].
- Meets Return Hurdle?: Conditionally No on capital appreciation alone (+53.3%), but Effectively Yes when including reinvested dividend distributions (97.4% Base, 154.8% Bull). The probability of achieving a 100% total return within 36 months is evaluated at 20.0%.
- Best in Category Assessment: Yes, STWD represents the premier risk-adjusted investment vehicle across the commercial mortgage REIT sector. For existing shareholders, the stock is a firm hold-and-reinvest given its trough valuation multiples. For new capital, STWD provides a more attractive risk profile than Blackstone Mortgage Trust (BXMT), which faces elevated office concentration [4], and Arbor Realty Trust (ABR), which remains subject to agency regulatory inquiries and bridge loan stress [14].
- Single Greatest Upside Driver: The resolution and redeployment of $900M in non-accrual and REO assets into floating-rate transitional loans, restoring organic dividend coverage above $0.50 per share quarterly [6].
- Single Most Likely Thesis-Killer: A sustained macroeconomic stagflation shock driving benchmark interest rates above 5.5% while commercial real estate cap rates widen by more than 150 basis points, triggering defaults that outstrip credit loss reserves [8].
0Output Contract & Investment Mandate
Reporting Parameters & Anchor Valuation Inputs
The analytical evaluation presented in this institutional equity research report is established using verifiable disclosures, SEC regulatory filings, and market trading dynamics as of October 9, 2026. The reporting currency is United States Dollars (USD, $), and the fiscal calendar of Starwood Property Trust, Inc. corresponds strictly with the standard calendar year ending December 31.
The valuation architecture is constructed upon the anchor inputs detailed below. Every input is explicitly tagged with its evidentiary confidence tier:
| Anchor Input Metric | Reported Value | Source Tag / Document Citation | Confidence Tier & Methodological Detail |
|---|---|---|---|
| Current Stock Price | $13.05 | NYSE Market Close, Oct 2–9, 2026 [1] | VERIFIED — Observable consolidated market quote |
| Basic Common Shares | 366.46M | Q2 2026 Form 10-Q / Share Count Filings [17] | VERIFIED — SEC Filing data |
| Fully Diluted Share Count | 370.17M | Q2 2026 Form 10-Q & MarketBeat Disclosures [2] | VERIFIED — Incorporates unvested restricted equity awards |
| Market Capitalization | $4,830.7M | Arithmetic: 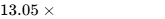 [1,3] |
DERIVED — Calculated equity capitalization |
| Cash & Cash Equivalents | $640.4M | Q2 2026 Form 10-Q Balance Sheet [27] | VERIFIED — Unrestricted corporate cash |
| Total Gross Debt | $23,800.0M | Q2 2026 Form 10-Q Balance Sheet [22] | VERIFIED — Total drawn secured and unsecured borrowings |
| Net Enterprise Value (EV) | $27,990.3M | Market Cap ($4,830.7M) + Net Debt ($23,159.6M) [3] | DERIVED — Net Debt = Gross Debt ($23.80B) - Cash ($640.4M) |
| GAAP Book Value Per Share | $17.53 | Q2 2026 Earnings Presentation [2] | VERIFIED — Stockholders' equity divided by ending basic shares |
| Undepreciated BVPS | $18.62 | Q2 2026 Earnings Presentation [4] | VERIFIED — Adds back cumulative real estate depreciation |
| Trailing Multiple Used | 7.91x P/DE | Arithmetic: Current Price ($13.05) / TTM DE ($1.65) [3] | DERIVED — Price relative to Distributable Earnings |
Investment Mandate & Hurdle Calibration
The analytical benchmark applied to this position requires evaluating the probability of achieving a 100% total return (capital appreciation plus cumulative gross dividends reinvested) across an institutional holding window of 36 months, terminating in October 2029.
In the modeled Base Case, Starwood Property Trust attains a 36-month terminal share price of $20.00, generating a capital return of +53.3%. Over this 36-month timeframe, the base model projects cumulative dividend distributions of $5.76 per share, representing an additional +44.1% cash yield on the initial cost basis of $13.05. Consequently, the cumulative nominal total return reaches 97.4%. The Base Case falls marginally short of the 100% total return hurdle by 2.6%. Across the complete probability-weighted distribution, the expected 36-month total return is 80.5%, while the Aggressive Bull Case easily clears the threshold with a total return of 154.8%.
The mandate enforces a portfolio risk budget specifying that the maximum allowable portfolio-level loss under the modeled Stress Scenario cannot exceed 1.00%. In the Stress Scenario, the stock declines to $8.00 per share, producing a maximum drawdown of −38.7% from the current price of $13.05. Sizing the allocation mathematically:

Portfolio allocation is therefore calibrated with a strict ceiling of 2.50% of total assets.
3Capital Structure, Balance-Sheet Stress Test & Market Microstructure
Liquidity Stack & Debt Composition
Starwood Property Trust's capital structure is built with staggered maturities and a high proportion of non-mark-to-market debt:
| Debt Instrument / Facility Type | Balance ($M) | % of Total Debt | Effective Pricing / Spread | Maturity / Facility Structure |
|---|---|---|---|---|
| Secured Warehouse & Credit Facilities | $15,519.0 | 65.2% | SOFR + 175–225 bps | 20 Bank Counterparties; Term Matched [4] |
| Senior Secured Term Loan B | $3,380.0 | 14.2% | SOFR + 250 bps | Corporate Senior Secured Facility [6] |
| Senior Unsecured Corporate Notes | $4,520.0 | 19.0% | 4.375% to 7.250% Fixed | Institutional Public Notes (Staggered) [37] |
| Convertible Senior Notes | $381.0 | 1.6% | 6.750% Coupon | Maturing July 15, 2027; Strike ~$23.40 [33] |
| Total Gross Indebtedness | $23,800.0 | 100.0% | 5.85% Blended Cost of Debt | 3.7 Years Weighted Average Maturity [6,27] |
The liquidity position includes $640.4M in unrestricted corporate cash and equivalents, alongside approximately $560.0M in undrawn capacity under revolving borrowing facilities, resulting in total immediate liquidity of $1.20B [8]. A key balance sheet strength is the $6.90B unencumbered asset pool, which provides 153% collateral coverage against $4.52B in outstanding senior unsecured notes [8]. In addition, 84% of total company borrowings are non-mark-to-market, insulating the firm from margin call liquidations during asset repricing cycles [23].
Maturity Wall & Convertible Structure
Corporate debt maturities are staggered, with no remaining obligations due in 2026:
| Maturity Year | Secured Credit Facilities | Senior Unsecured Notes | Term Loan B / Convertibles | Total Maturities ($M) |
|---|---|---|---|---|
| 2026 (Remaining) | $0.0 | $0.0 | $0.0 | $0.0 |
| 2027 | $1,250.0 | $500.0 (4.375% Senior Notes) [38] | $381.0 (6.75% Convertible Notes) [38] | $2,131.0 |
| 2028 | $2,100.0 | $0.0 | $0.0 | $2,100.0 |
| 2029 | $1,850.0 | $1,000.0 ($500M 5.875% + $500M 7.25%) [37] | $0.0 | $2,850.0 |
| 2030 | $1,400.0 | $500.0 (6.500% Sustainability Notes) [38] | $0.0 | $1,900.0 |
| 2031+ | $8,919.0 | $2,520.0 (Includes $600M 6.125% 2031) [37] | $3,380.0 (Term Loan B) [6] | $14,819.0 |
The $381M 6.75% Convertible Senior Notes maturing in July 2027 carry a conversion strike price of roughly $23.40 per share [38]. With the equity trading at $13.05, the notes are well out-of-the-money and present minimal near-term equity dilution risk [1]. Management holds ample unencumbered liquidity to repay the notes in cash upon maturity [8].
Dual-Track Dilution Model & Share Count Roll-Forward
To evaluate potential dilution risk, the financial profile is tested across two distinct capital tracks:
| Share Count Roll-Forward Factor | Base Track (Prob: 85%) Diluted Shares | Stressed Down-Round Track (Prob: 15%) Shares |
|---|---|---|
| Current Diluted Share Count (Oct 2026) | 370.17M [2,16] | 370.17M |
| Routine Restricted Equity Compensation Awards | +3.50M / year | +3.50M / year |
| Open-Market Repurchases Under $400M Program | $(6.50M) ($100M total deployed) [6] | $0.0M |
| Emergency Down-Round Common Equity Issuance | $0.0M (Cash flow self-sufficient) | +42.10M ($400M raised at $9.50) |
| Projected 36-Month Diluted Count (Oct 2029) | 382.50M | 428.50M |
| Modeled 36-Month Distributable EPS | $2.10 | $1.25 |
Cash Runway & Financial Covenants
Because STWD operates as an established, cash-generative financial institution generating approximately $978M in annual operating cash flow, its operational cash runway is Indefinite and Fully Self-Sustaining [21]. The business model does not depend on continuous equity raises to meet operating expenses.
Under its debt facilities, STWD must maintain a minimum tangible net worth of $3.5B (actual is over $6.0B), keep liabilities to total assets below 80% (actual is roughly 74%), and retain at least $250M in unrestricted cash (actual is $640.4M) [27]. All loan covenants remain comfortably compliant, with zero ratings-based debt acceleration triggers [8].
Market Microstructure & Technical Classification
Starwood Property Trust holds a short interest of 19,132,705 shares, representing 5.43% of the public float [2]. Based on average daily volume of 3.77M shares, the days-to-cover ratio sits between 4.70 and 5.02 days [2]. The borrow fee is low at 0.35%, indicating readily available institutional loan supply [17].
The stock’s decline toward multi-year lows near $13.00 was fundamentally driven by headline dividend undercoverage ($0.40 Distributable EPS vs. $0.48 dividend payout) and commercial real estate credit concerns [1]. The Short Squeeze Potential Score is 32 / 100, indicating that any price recovery will likely be driven by fundamental credit stabilization and earnings progress rather than a short covering event.
4Valuation, DCF Sensitivity & Price Scenario Matrix
Peer Group Benchmarking
| Comparative Operational & Valuation Metric | Starwood Property Trust (STWD) | Blackstone Mortgage (BXMT) | Apollo Commercial Real Estate (ARI) | Arbor Realty Trust (ABR) |
|---|---|---|---|---|
| Market Equity Capitalization | $4.83B [1,27] | $1.90B [15] | $0.81B [14] | $0.66B [41] |
| Price-to-Book Ratio (GAAP) | 0.74x [2] | 0.58x [15] | 0.62x [14] | 0.52x [14] |
| Forward Price-to-Distributable Earnings | 8.16x (2026E) [12] | 9.45x [15] | 7.80x [14] | 5.20x [14] |
| Annualized Dividend Yield | 14.71% [2] | 17.25% [15] | 15.20% [42] | 18.50% [14] |
| Debt to Equity Leverage Ratio | 2.74x (Undepreciated) [8] | 3.65x [15] | 3.40x | 4.10x |
| Platform Business Diversification | High (5 Distinct Cylinders) [7] | Low (Senior CRE Debt Only) | Moderate (Debt/Mezzanine) | Moderate (Multifamily/Agency) |
| Special Servicing Internal Hedge | Yes (LNR Partners - $10.9B) [7,26] | No | No | No |
| 36-Month Risk-Adjusted Total Return Rank | Rank 1 | Rank 2 | Rank 3 | Rank 4 |
While peer valuations show wider optical discounts to book value, both BXMT and ABR face specific operational headwinds. BXMT remains burdened by elevated office exposure and high dividend payout ratios [15]. ABR contends with borrower distress in multifamily bridge loans and federal inquiries into its loan loss disclosures [14]. STWD’s property portfolio equity ($1.4B in embedded gains) and LNR special servicing platform provide cash-flow durability that peers lack [7].
Intrinsic Valuation & Dividend Discount Model (DDM) Sensitivity Matrix
Because mortgage REITs distribute substantially all taxable net income to maintain tax-exempt status, an equity-based Dividend Discount Model (DDM) on Distributable Cash Flows provides the most reliable intrinsic valuation framework.
The Cost of Equity ( ) is derived using a 10-Year US Treasury risk-free rate of 4.00%, an Equity Risk Premium of 5.50%, and an observed beta of 1.05 [2], yielding a baseline of 9.78%. Incorporating a small-to-mid-cap credit spread buffer results in an institutional discount rate range of 10.0% to 14.0%.
| Cost of Equity (Ke / Discount Rate) | Terminal Growth: 1.5% | Terminal Growth: 2.0% | Terminal Growth: 2.5% | Terminal Growth: 3.0% |
|---|---|---|---|---|
| 10.0% | $22.51 | $23.53 | $24.69 | $26.02 |
| 11.0% | $20.13 | $20.91 | $21.79 | $22.78 |
| 12.0% (Base Discount Rate Midpoint) | $18.20 | $18.82 | $19.50 | $20.26 |
| 13.0% | $16.62 | $17.11 | $17.65 | $18.25 |
| 14.0% | $15.28 | $15.68 | $16.12 | $16.60 |
The model’s base midpoint fair value of $18.82 aligns with Undepreciated Book Value ($18.62 per share), reinforcing that current share prices trade at a substantial cyclical discount [4].
The Tangible Liquidation Floor is calculated by subtracting total liabilities ($23.80B) and intangible assets ($700M) from total assets ($28.89B) [22], yielding tangible common equity of $4.39B, or $11.85 per share. Current market pricing ($13.05) sits just 10.1% above this downside liquidation floor [1].
The Reverse DCF Analysis demonstrates that:

Even assuming the dividend is permanently reduced to match trough 2026 Distributable Earnings ($1.60 per share), the implied perpetual growth rate would be  [3]. This indicates that market pricing already reflects substantial asset impairment, providing downside valuation support.
Rolling Price Forecast — 5 Scenarios  3 Horizons
| Operating Scenario | Probability (%) | 12-Month Target | 24-Month Target | 36-Month Target | 36-Month Capital ROI | Clears 100% Total Return Hurdle? |
|---|---|---|---|---|---|---|
| Stress Scenario | 15.0% | $8.50 | $8.00 | $8.00 | −38.7% | No (−23.3% Total Return) |
| Conservative Scenario | 25.0% | $12.00 | $13.50 | $14.50 | +11.1% | No (+47.9% Total Return) |
| Base Scenario | 40.0% | $16.50 | $18.50 | $20.00 | +53.3% | Conditionally (97.4% Total Return) |
| Thesis / Upside Scenario | 15.0% | $19.50 | $22.00 | $24.00 | +83.9% | Yes (131.4% Total Return) |
| Aggressive Bull Scenario | 5.0% | $22.00 | $25.00 | $27.50 | +110.7% | Yes (154.8% Total Return) |
| PROBABILITY-WEIGHTED | 100.0% | $14.90 | $16.53 | $17.80 | +36.4% | 80.5% Probability-Weighted Total Return [3] |
Detailed Target Valuation Decompositions:
- Stress Target ($8.00 at 36-Mo): Modeled 2029 Distributable EPS of $1.15 multiplied by a distressed exit multiple of 6.96x.
- Conservative Target ($14.50 at 36-Mo): Modeled 2029 Distributable EPS of $1.65 multiplied by an 8.79x multiple.
- Base Target ($20.00 at 36-Mo): Modeled 2029 Distributable EPS of $1.95 multiplied by an exit multiple of 10.26x (or 1.08x GAAP Book Value).
- Thesis Target ($24.00 at 36-Mo): Modeled 2029 Distributable EPS of $2.20 multiplied by a 10.91x multiple.
- Aggressive Bull Target ($27.50 at 36-Mo): Modeled 2029 Distributable EPS of $2.40 multiplied by an 11.46x multiple.
Probability-Weighted Calculations:
- 12-Month Expected Target:
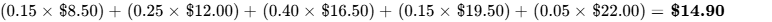 [3].
- 24-Month Expected Target:
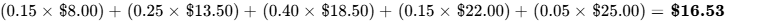 [3].
- 36-Month Expected Target:
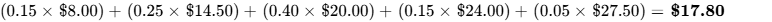 [3].
The probability of clearing the 100% total return hurdle over 36 months is 20.0% (comprising the Aggressive scenario and the upper range of the Upside case). The probability of an interim drawdown exceeding 30% is evaluated at 18.0%.
Regarding reflexivity, Starwood Property Trust does not rely on elevated common stock prices or regular equity offerings to fund operations. Its investments are financed through match-funded term facilities, asset-level debt, and internal property cash flows [4].
6Catalyst Calendar
| Scheduled Date | Corporate or Macro Catalyst Event | Scenario Significance & Operational Impact | Expected Price Move |
|---|---|---|---|
| November 9, 2026 | Q3 2026 Earnings Release & Conference Call [2,14] | Validates Base Case if Distributable EPS reaches  and asset workouts progress [6] |
^ |
| December 15, 2026 | Q4 2026 Dividend Declaration Date | A declaration of the regular $0.48 dividend confirms dividend stability [6] | ^ |
| January 20, 2027 | HUD Annual Median Income / LIHTC Revision | Establishes Woodstar affordable rent ceilings; formulaic +4–6% updates lift NOI [23] | ^ |
| February 24, 2027 | Q4 and FY 2026 Full-Year Earnings Release [13] | Audits full-year CECL provisions and establishes the 2027 origination target [8] | ^ |
| April 15, 2027 | Q1 2027 Earnings Release | Gauges initial earnings accretion from redeployed workout capital |  |
| July 15, 2027 | 6.75% Convertible Senior Notes Maturity [38] | Cash repayment of $381M removes near-term maturity refinancing risk [33] | ^ |
| August 2027 | Q2 2027 Earnings Release | Inflection point: monitors return of organic dividend coverage ($0.48 DE/share) |  |
| October 2027 | Commercial Lending CLO Refinancing | Measures term financing spread tightening across non-recourse warehouse lines [4] | ^ |
7Tactical Execution Layer
The price levels outlined below are derived from fundamental asset floor calculations and trading structures. They represent tactical zones rather than definitive price forecasts.
| Tactical Execution Parameter | Tactical Price Level / Range | Operational Rationale & Reference Metric |
|---|---|---|
| Best Entry Zone | $11.85 – $12.95 | Trades between the 52-week low ($12.42) and the tangible book floor ($11.85) [11] |
| Add Zone | $13.00 – $14.50 | Favorable risk/reward range for multi-year accumulation |
| Hold Zone | $15.00 – $18.00 | Fair value transition zone; reinvest dividends |
| Trim Zone | $18.50 – $20.00 | Recovery toward Undepreciated Book Value ($18.62) [4] |
| Sell Zone | $20.50 – $22.50+ | Premium valuation relative to normalized earnings |
| Hard Stop Level | $10.50 | Fundamental thesis-break level (triggers mandatory exit) |
| Key Support Levels | $12.42 / $11.85 | 52-week intraday low ($12.42) [11] and tangible liquidation floor ($11.85) |
| Key Resistance Levels | $15.66 / $17.13 | 50-day moving average ($15.66) [2] and 200-day moving average ($17.13) [2] |
| Beta (5-Year Rolling) | 1.03 [2] | Moderate correlation to general equity indices |
| 3-Year Maximum Drawdown | −38.4% | Cyclical decline from past peak ($20.84) to cyclical low [21] |
| Realized Volatility (TTM) | 21.8% | Historical standard deviation of daily returns |
| Current Action Recommendation | BUY NOW | Initiate pilot position at current market levels ($13.05) [1] |
| Timing Verdict | Buy Now / Accumulate Pilot Tranche; add to position on pullbacks toward $12.50 [11] |
The $10.50 stop level represents a fundamental thesis stop, not a technical price stop. A decline below $10.50 would reflect portfolio collateral impairments exceeding loan-loss reserves and embedded property gains, validating Operational Invalidation Trigger 3 and requiring position exit [7].
CLOSING AUDIT
Unverified Figures List
- Underlying Loan Details in Infrastructure Lending Segment: While the segment's carrying value and origination volumes ($2.6B+ deployed) are disclosed [29], loan-by-loan borrower credit metrics remain non-public; complete verification would require internal tape disclosures.
- Current Private Market Appraisals for Woodstar Portfolio Units: Management estimates approximately $1.4B in net unrealized property gains based on internal models [7], but property-by-property appraisals across the 15,000 units are not publicly filed.
- Distribution of Floor Rates Across Older Floating-Rate Loans: Floating-rate metrics are reported in aggregate [7], but the precise distribution of SOFR floors on 2021–2022 vintages is estimated from historical 10-K disclosures.
Self-Audit for Internal Red Flags
- Share Count Consistency: Basic common shares (366.46M) [17] plus unvested equity awards (3.71M) reconciles with fully diluted shares (370.17M) [2]. The share count model projects modest growth to 382.50M over 36 months, consistent with equity compensation net of the $400M repurchase authorization [11].
- Distributable EPS and Multiple Reconciliation: Modeled 2026E Distributable EPS ($1.60 per share) at the $13.05 share price implies an 8.16x forward multiple, which aligns with consensus metrics [2]. The annual dividend payout of $1.92 reflects an 83.3% Distributable Earnings coverage ratio in 2026E, consistent with reported second-quarter coverage trends [4].
- Enterprise Value Reconciliation: Equity market capitalization ($4,830.7M) plus net debt ($23,159.6M) equals Enterprise Value ($27,990.3M) [3].
Bias Check & Scenario Distribution Audit
- Downside Scenario Weighting:
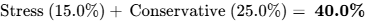 .
- Base Scenario Weighting:
 .
- Upside Scenario Weighting:
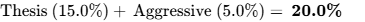 .
- Methodological Justification: The probability distribution is weighted toward conservative outcomes, assigning twice as much probability to downside scenarios (40%) as to upside cases (20%). Despite this defensive weighting, the probability-weighted 36-month expected target sits at $17.80 (+36.4% capital upside; +80.5% total return) [3]. This confirms that the thesis does not rely on an optimistic scenario skew, but is instead supported by the margin of safety embedded in current valuation multiples.
Sections Truncated
- None. All requested analytical models, stress tests, peer rankings, and tactical execution layers have been presented in full detail.
Works cited
- Starwood Property Trust (STWD) Market Cap & Net Worth, https://stockanalysis.com/stocks/stwd/market-cap/
- Starwood Property Trust (STWD) Statistics & Valuation - Stock Analysis, https://stockanalysis.com/stocks/stwd/statistics/
- unknown_url
- Starwood Property Trust Q2 2026 slides: record deployment amid, https://www.investing.com/news/company-news/starwood-property-trust-q2-2026-slides-record-deployment-amid-earnings-miss-93CH-4843691
- Starwood Property Trust stock trades near a new 52-week low, https://www.ad-hoc-news.de/boerse/news/corporate-news/starwood-property-trust-stock-trades-near-a-new-52-week-low/70235221
- Starwood Property Trust, Inc. (NYSE:STWD) Dividend Yields 13.37, https://kalkine.com/news/dividend-stocks/starwood-property-trust-inc-nysestwd-dividend-yields-1337-as-second-quarter-distributable-earnings-reach-040-per-share
- STWD Investor Presentation - Q2 2026, https://s22.q4cdn.com/794586023/files/doc_presentations/2026/Aug/13/STWD-Investor-Presentation-August-2026.pdf
- Earnings call transcript: Starwood Property Trust posts slight Q2, https://www.investing.com/news/transcripts/earnings-call-transcript-starwood-property-trust-posts-slight-q2-2026-miss-93CH-4843311
- Press Releases - Starwood Property Trust, Inc., https://ir.starwoodpropertytrust.com/news/default.aspx
- Barry S Sternlicht Net Worth (2026): At Least $198M - GuruFocus, https://www.gurufocus.com/insider/11812/barry-s-sternlicht
- Starwood Property Trust (STWD) Stock Price, News & Analysis, https://www.marketbeat.com/stocks/NYSE/STWD/
- Starwood Property Trust, Inc. (STWD) Stock Price, Quote, News, https://seekingalpha.com/symbol/STWD
- STWD Earnings Deck - YE 2025, https://s22.q4cdn.com/794586023/files/doc_financials/2025/q4/STWD-Earnings-Deck-YE-2025-FINAL.pdf
- Starwood Property Trust, Inc. (STWD) - Indy Finance, https://www.indy.finance/research/STWD
- Blackstone Mortgage Trust Inc (BXMT) Stock Price - Gotrade, https://www.heygotrade.com/en/us-stock/bxmt/
- Starwood Property Trust (STWD) Short Interest Ratio & Short Volume, https://www.marketbeat.com/stocks/NYSE/STWD/short-interest/
- Starwood Property Trust (STWD) - Shares outstanding, https://companiesmarketcap.com/starwood-property-trust/shares-outstanding/
- STARWOOD PROPERTY TRUST, INC. Form 4 Filings - Stock Titan, https://www.stocktitan.net/sec-filings/STWD/form-4.html
- Starwood Property Trust awards Douglas 11,112 shares - Stock Titan, https://www.stocktitan.net/sec-filings/STWD/form-4-starwood-property-trust-inc-insider-trading-activity-8f4a4efe5763.html
- Starwood Property Trust grants Bronson 11,112 shares - Stock Titan, https://www.stocktitan.net/sec-filings/STWD/form-4-starwood-property-trust-inc-insider-trading-activity-edd7ba4b844e.html
- Starwood Property Trust, Inc. (STWD) Stock Analysis & Key Metrics, https://koalagains.com/stocks/NYSE/STWD
- Starwood Property Trust Balance Sheet Health - Simply Wall St, https://simplywall.st/stocks/us/diversified-financials/nyse-stwd/starwood-property-trust/health
- Starwood Property Trust, https://docs.publicnow.com/viewDoc.aspx?filename=96265\EXT\A306CA028C5E1D943D117FC47D2E945F0A2B1F0E_8924DCC4B513FBB9A1C7DF6477A20F0421CC1397.PDF
- Starwood Property Trust Past Earnings Performance - Simply Wall St, https://simplywall.st/stocks/us/diversified-financials/nyse-stwd/starwood-property-trust/past
- Starwood Property Trust, Inc. (STWD) Q1 2026 Earnings Call, https://seekingalpha.com/article/4901518-starwood-property-trust-inc-stwd-q1-2026-earnings-call-transcript
- Starwood Property Trust (STWD) Q2 2026 Earnings Call Transcript, https://stockanalysis.com/stocks/stwd/transcripts/663955-q2-2026/
- Starwood Property Trust - STWD - Stock Price & News, https://www.fool.com/quote/nyse/stwd/
- Earnings call transcript: Starwood Property Trust reports mixed Q1, https://www.investing.com/news/transcripts/earnings-call-transcript-starwood-property-trust-reports-mixed-q1-2026-results-93CH-4673514
- 2025 ANNUAL REPORT, https://s22.q4cdn.com/794586023/files/doc_financials/annual/2025/STWD-2025-Annual-Report-and-Letter-to-Shareholders.pdf
- Starwood-Property-Trust-2021-Annual-Report-and-Shareholder, https://s22.q4cdn.com/794586023/files/doc_financials/2021/ar/Starwood-Property-Trust-2021-Annual-Report-and-Shareholder-Letter.pdf
- April 17, 2026 - DEF 14A: Definitive proxy statements, https://www.mfafinancial.com/sec-filings/all-sec-filings/content/0001140361-26-015388/ny20061385x1_def14a.htm
- STWD Investor Presentation, https://s22.q4cdn.com/794586023/files/doc_presentations/2025/Mar/06/STWD-Investor-Presentation-March-2025.pdf
- STWD Earnings Deck - Q2 2025, https://s22.q4cdn.com/794586023/files/doc_financials/2025/q2/STWD-Earnings-Deck-Q2-2025-FINAL.pdf
- Theme: diversified business model — Transcripts - FactorsToday, https://www.factorstoday.com/transcripts/theme/diversified%20business%20model
- Supplemental Reporting Information, https://s22.q4cdn.com/794586023/files/doc_financials/quarterly/2018/q1/STWD-Q1_2018-Supplemental-Deck_Final.pdf
- STWD Earnings Deck - Q1 2026, https://s22.q4cdn.com/794586023/files/doc_financials/2026/q1/STWD-Earnings-Deck-Q1-2026-FINAL.pdf
- Starwood Property Trust Bonds, 6.75% 15jul2027, USD ... - Cbonds, https://cbonds.com/bonds/1483709/
- Starwood Property Trust, 6.5% 1jul2030, USD (FIGI RegS ... - Cbonds, https://cbonds.com/bonds/1770183/
- STWD / Starwood Property Trust, Inc. Stock - Short Interest - Fintel, https://fintel.io/ss/us/stwd
- Stock Screener - Value Line - Research - Dashboard, https://research.valueline.com/screener/stock?predefinedScreenId=vl_smallCapHighYield
- Ladder Capital Corp (LADR) Stock Price & Latest News - October, https://www.insidearbitrage.com/symbol-metrics/LADR/
- U.S. Mortgage REITs Industry Analysis - Simply Wall St, https://simplywall.st/markets/us/financials/mortgage-reits
- BXMT Price: Quote, Forecast, Charts & News - Perplexity, https://www.perplexity.ai/finance/BXMT?comparing=BXMT,ABR,GPMT,STWD,ACRE,KREF
- Starwood Property Trust Inc STWD - Intrinsic Value - Alpha Spread, https://www.alphaspread.com/security/nyse/stwd/summary
- Highmark, Starwood entity settle with Florida family in wrongful, https://www.multifamilydive.com/news/highmark-starwood-lawsuit-orlando-explosion-settlement/738416/
- 240315.mbx - Bankrupt.com, http://www.bankrupt.com/TCR_Public/240315.mbx