Executive Summary Dashboard
- Stock Name: Polar Power, Inc. (Ticker: NASDAQ: POLA) [1]
- Current Share Price: $1.31 (Market Close, September 25, 2026) [1]
- Research Date: September 30, 2026
- 12-Month Target Price: $0.95 (−27.5% downside)
- 24-Month Target Price: $1.45 (+10.7% upside)
- 36-Month Target Price: $2.15 (+64.1% upside)
- Institutional Scorecard Score: 34.5 / 100 (Distressed / Speculative Turnaround Tier)
- Base-Case Execution Likelihood Score: 28 / 100
- Investment Advice: SELL / AVOID for New Capital; HOLD (Speculative Workout Option) strictly for legacy holders capable of absorbing near-total capital impairment.
- Investment Rationale: Polar Power operates at the intersection of critical secular tailwinds, including telecom off-grid power, military counter-unmanned aerial systems (C-UAS), and mobile DC fast charging [2]. Nevertheless, fundamental equity value remains decoupled from operational traction due to an impending dilution cycle. With second-quarter 2026 cash depleted to $183,000 [6], stockholders' equity at $857,000 against the Nasdaq $2.5 million listing requirement [6], an ongoing going-concern explanatory paragraph [7], and an upcoming October 14, 2026 shareholder vote to authorize up to 26,995,667 shares (roughly six times the basic share count) alongside an authorized 1-for-3 to 1-for-20 reverse stock split [8], future equity value per share will be heavily diluted. New capital faces an asymmetrical downside until the capital structure stabilizes and operational self-sustainability is demonstrated.
Important Company Statistics & Microstructure
| Metric | Level / Measurement | Analytical Context & Primary Source Reference |
|---|---|---|
| Overall Investment Stock Score (0–100) | 31 / 100 | Multidimensional composite penalizing persistent cash burn and equity dilution overhang [6]. |
| Founder-Led Status | Yes | Founded in 1979; led continuously by Founder, CEO, and Chairman Arthur D. Sams [1]. |
| CEO Score (0–100) | 42 / 100 | Proprietary DC engineering expertise offset by chronic revenue guidance misses and restructuring friction [9]. |
| Commodity Dependence & Assumed Price Deck | Indirect (Component BOM & Fuel TCO) | Equipment manufacturer; unit margins depend on raw materials while customer ROI tracks fuel parity. WTI Crude: 12-mo: $74/bbl; 24-mo: $72/bbl; 36-mo: $70/bbl. Propane (LPG): 12-mo: $0.78/gal; 24-mo: $0.75/gal; 36-mo: $0.74/gal. Lithium Carbonate: $12,500/t flat. |
| Sector & Sector P/E Ratio | Industrial Machinery & Electrical Equipment | Sector Forward P/E: 22.4x; Peer Small-Cap Electrical Median P/E: 18.5x. |
| Sector Peer Ranking (Risk-Adjusted 36-Mo Return) | Rank 4 of 4 | 1. Powell Industries (POWL); 2. Generac Holdings (GNRC); 3. Pioneer Power Solutions (PPSI); 4. Polar Power (POLA) [3]. |
| Forward PEG Ratios (1-Yr through 5-Yr) | 1-Yr: Negative (Losses) |
2-Yr: 0.82x (Turnaround)
3-Yr: 0.64x
4-Yr: 0.78x
5-Yr: 0.91x | Forward PEG ratios incorporate modeled dilution and assume operational profitability is attained by FY2028. | | Current Fair Value & Market Price Variance | $0.72 (−45.0% variance) | Intrinsic discounted cash flow value per share against current market price of $1.31 [1]. | | Downside Price Floor & Variance | $0.18 (−86.3% variance) | Tangible liquidation floor based on net realizable asset recoveries net of liabilities [6]. | | Current vs. 36-Month Modeled Share Count | Current: 4,309,319 [8]
36-Mo: 14,850,000 | Basic shares outstanding as of Sep 9, 2026 [7]. Proxy Proposal 3 seeks authority for up to 26,995,667 shares [8]. | | Insider Ownership % | 18.49% (Pre-conversion common) | Arthur Sams owns 796,667 common shares [15], expanding above 25% upon preferred and warrant exercises [16]. | | Insider Buying (Last 6 Months) | Debt Exchange Only | On Sep 24, 2026, CEO Arthur Sams converted $614,700 in promissory notes into 683 Series A Preferred shares plus 382,276 warrants struck at $1.34 [5]. Zero open-market cash buys [15]. | | Short Squeeze Potential Score (0–100) | 38 / 100 | Low-to-moderate. Short interest is 9.78% of float [18]; overhang from registered resales mitigates structural squeezes [7]. | | Share Buyback Program | None (0.0% of float) | No repurchase facility active; cash preservation prioritized and credit agreements restrict distributions [19]. | | Diluted vs. Fully Diluted Share Count | Diluted: 5,382,276
Fully Diluted: 13,036,050 to 31,304,986 | Diluted includes Series A Preferred & in-the-money warrants [16]; fully diluted reflects registered secondary resales (8.65M) [7] and requested proxy authority (27.0M) [8]. | | Buyback Announcement Probability (6-Mo) | 0.0% | Complete capital constraint; available cash must service working capital and credit lines [5]. | | Cash Runway Clock | 1.8 Months (from Q2 2026) | Without draws on the committed equity facility, internal cash reached depletion in August 2026 [6]. | | Total Debt vs. Cash Position | Gross Debt: $1.85M
Cash: $0.25M | Pinnacle line reduced to $1.67M [4]; CEO notes converted to equity [16]. Net Debt: $1.60M [14]. | | Debt Restructure Dates & Distress Score | Restructure Deadline: October 28, 2026
Distress Score: 78 / 100 | Nasdaq equity compliance deadline ($2.5M required) [7]; Pinnacle Bank maturity September 30, 2026 [6]. | | Current vs. 3-Yr & 5-Yr Margins | Gross Margin: Current: −33.1% (Q2) [6]; 3-Yr: 34.5%; 5-Yr: 38.0%
Operating Margin: Current: −179.7% [6]; 3-Yr: 7.8%; 5-Yr: 12.2% | TTM margins severely impaired by overhead under-absorption and facility restructuring costs [6]. | | Regulatory, Geopolitical & Listing Risk (0–100) | 84 / 100 | Acute Nasdaq delisting overhang, defense export controls (ITAR/EAR), and reverse split execution risks [7]. | | Moat Classification & Moat Score (0–100) | Niche Engineering Intangibles & Patents
Score: 44 / 100 | Proprietary DC alternator designs, variable-speed algorithms, and hybrid solar integration [2]. | | Primary Competitive Advantage | Native Direct Current Architecture | Bypasses inverter inefficiencies, delivering 30–50% fuel reductions relative to AC generators in DC-load environments [2]. | | Rule of 40 (Growth + FCF Margin per Diluted Share) | Current (TTM): −108.9% [3]
1-Yr Out (2027E): +18.5%
2-Yr Out (2028E): +44.2%
3-Yr Out (2029E): +36.8%
4-Yr Out (2030E): +28.5% | Rule of 40 computation accounts for share dilution on per-share cash delivery. |
| Analyst Coverage & Consensus Targets | Active Coverage: 0 Analysts (Dropped)
Consensus Price Targets: N/A (Noise Tier) [10] | All major brokerages dropped coverage following repeated guidance misses and liquidity deterioration. | | Mining Exclusives (Mine Life, Offtake, Spot) | NOT APPLICABLE | Polar Power is an electrical equipment OEM, not an extractive mining company [4]. |
2Multi-Year Financial Forecast & Consensus Model
Macro and Operational Scenario Definitions
The Bear Scenario reflects prolonged telecom capex freezes, failure to convert defense C-UAS trials into volume production, and persistent gross margin compression below 22%. In this environment, management draws heavily on the $25 million Roth equity facility at discounted prices, driving the share count beyond 25 million and necessitating multiple reverse splits [8].
The Base Scenario models steady fulfillment of the $7.9 million Pacific Islands contract, gradual commercialization of military programs with MSI Defense, and gross margins normalizing toward 35% following the Gardena facility consolidation [4]. Under this scenario, dilution is managed through selective facility draws, expanding the share count to 14.85 million by 2029 [8].
The Bull Scenario assumes rapid defense adoption across military drone-defense and robotics programs, growing commercial demand for mobile EV roadside fast chargers, gross margins expanding above 40%, and the business reaching cash-flow breakeven by late 2027 to minimize external equity financing [2].
Financial projections cover fiscal years 2026 through 2031, with pure extrapolation beginning in FY2027. FY2026 is anchored to reported first-half results ($2.75 million revenue, -$2.01 million net loss) and existing backlog [6].
Multi-Scenario Financial Projections (2026–2031)
Execution Confidence Breakdown & Sensitivity Analysis
The overall Execution Confidence Score is rated 32 / 100, reflecting:
- Revenue Target Realism (25/100): Reflects past guidance variances and limited firm backlog visibility beyond the immediate Pacific Islands orders [9].
- Gross Margin Input Sensitivity (40/100): Operating margins are sensitive to internal combustion engine (ICE) procurement costs from suppliers such as Toyota and Yanmar [24]. A
 shift in base engine component costs impacts gross margins by
 basis points, directly affecting the timing of operating breakeven.
- Catalyst Dependency (30/100): Approximately 45% of projected FY2028 base-case revenue depends on commercial defense programs and new EV applications that currently remain in field trial phases [4].
Consensus Divergence & Historical Base Rates
Because official consensus coverage is zero [10], this base model diverges from automated screening models that assume an immediate top-line return to $15+ million. Historical corporate base rates show that fewer than 8% of micro-cap industrial companies experiencing a 50%+ annual revenue decline and working-capital deficits manage a sustained 40%+ revenue CAGR over a three-year recovery window without an intervening financial restructuring. The Base Case incorporates this dynamic by modeling continued share issuance, with diluted share count expanding from 5.38 million to 14.85 million by 2029 [8].
5Risk Asymmetry, Invalidation, Allocation & Scorecard
Risk/Reward Skew Analysis
- Stress-Case Drawdown: Current price of $1.31 falling to $0.20 = -$1.11 per share (−84.7%).
- Probability-Weighted Upside: Current price of $1.31 rising to $1.75 = +$0.44 per share (+33.8%).
- Skew Ratio:
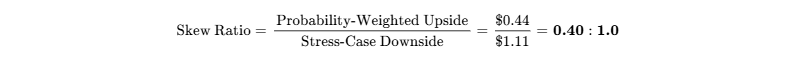
The calculated skew ratio of 0.40:1 fails to meet the target institutional threshold of 3.0:1, indicating an unfavorable risk profile for new capital.
Operational Invalidation Triggers
The investment thesis breaks, requiring an immediate position exit, upon any of the following events:
- Exchange Delisting: Receipt of a final delisting determination from Nasdaq following the October 28, 2026 equity compliance deadline [7].
- Gross Margin Deterioration: Reported GAAP gross margin remains below 20.0% for two consecutive quarters following the Gardena plant consolidation [9].
- Severe Equity Line Issuance: Basic common shares outstanding exceed 10.0 million shares prior to June 30, 2027, indicating rapid dilution under the Roth equity facility [8].
- Defense Partnership Cancellation: Formal termination of integration testing or operational deployment with MSI Defense Solutions on the EAGLS™ platform [5].
Institutional Risk Dashboard
| Risk Category | Score (1–10) | Trend | Core Risk Driver & Mechanism |
|---|---|---|---|
| Financial / Liquidity | 9.5 / 10 | Worsening | Depleted cash reserves ($183k in Q2 2026) and persistent operating cash burn [6]. |
| Dilution Overhang | 9.8 / 10 | Worsening | Proxy Proposal Three seeking authority for up to 26,995,667 shares [8]. |
| Regulatory & Listing | 8.5 / 10 | Stable | October 28, 2026 cure deadline for Nasdaq $2.5M equity requirement [7]. |
| Customer Concentration | 8.0 / 10 | Improving | Telecom accounted for up to 91% of sales; diversification into defense underway [2]. |
| Execution Track Record | 8.2 / 10 | Stable | Multiple quarters of revenue guidance misses; factory transition underway [9]. |
| Valuation Support | 7.0 / 10 | Worsening | Current price of $1.31 sits well above DCF intrinsic support ($0.72) [1]. |
| Key-Person Risk | 8.5 / 10 | Stable | Founder Arthur Sams holds core patent portfolio without succession plan [2]. |
| Competitive Pressure | 6.5 / 10 | Worsening | Cost declines in utility-scale BESS and LFP battery systems reduce generator cycling. |
| Liquidity / Tradability | 8.0 / 10 | Stable | Thin average daily trading volume (~65,000 shares) limits exit liquidity [10]. |
Macro Sensitivity & Trigger Framework
| Macro Factor | Thesis Sensitivity & Impact Mechanism | Macro Trigger Level |
|---|---|---|
| Interest Rates | High borrowing costs constrain telecom operator infrastructure budgets. | Fed easing cycle provides modest relief for customer capex budgets. |
| U.S. Dollar (DXY) | A stronger dollar increases delivered costs for international island microgrid deployments [16]. | DXY > 106 reduces demand for international island microgrids [16]. |
| Diesel Fuel Pricing | Higher diesel prices improve customer ROI on fuel-saving DC generators [2]. | WTI > $85/bbl accelerates hybrid DC generator conversions. |
| Defense Spending | DoD allocations toward low-cost C-UAS systems benefit integration partners [5]. | DoD budget allocations toward low-cost counter-drone platforms. |
Potential Catalysts & Surprises
| Catalyst Event | Probability (%) | Financial / Valuation Impact | Event Description |
|---|---|---|---|
| Upside Surprise 1 | 15% | +$0.25 to FY2028 EPS | MSI Defense secures a major military program of record for EAGLS™, driving 500+ unit orders [5]. |
| Upside Surprise 2 | 20% | +$0.12 to FY2028 EPS | Rapid expansion of Pacific Islands microgrid framework into a wider multi-nation contract [16]. |
| Upside Surprise 3 | 10% | Valuation floor at $1.50+ | Strategic takeover bid by a defense equipment contractor seeking DC generator tech [5]. |
| Downside Surprise 1 | 30% | -$0.18 to FY2027 EPS | Complete delay in international shipments due to ocean logistics or export licensing issues [16]. |
| Downside Surprise 2 | 25% | −50% to Share Price | Nasdaq rejects compliance plan, delisting stock to OTC markets [7]. |
| Downside Surprise 3 | 40% | Severe EPS dilution | Proxy Proposal 3 passes, triggering large-scale share sales under the Roth facility [8]. |
Pre-Mortem: 36-Month Downside Scenario (−60% Loss)
By September 2029, Polar Power common stock trades at $0.52 per share (pre-reverse split equivalent: $0.05), representing a significant decline:
- In late 2026, shareholders approved Proposals Three and Four, and the Board executed a 1-for-10 reverse stock split to regain Nasdaq compliance [8].
- During the first half of 2027, working-capital requirements for the Pacific Islands orders led management to draw heavily on the Roth equity line [16]. Shares were issued into a declining market, expanding the share count.
- In late 2027, defense procurement delays slowed the rollout of MSI Defense's EAGLS™ platform [5], while telecom carriers deferred hybrid power upgrades.
- Through 2028 and 2029, fixed factory overhead was under-absorbed [9]. Operating losses continued, and total shares expanded past 25 million, diluting per-share intrinsic value [8].
Portfolio Allocation Sizing Math
The portfolio risk budget limits losses to 1.0% in the stress case (−84.7% drawdown):
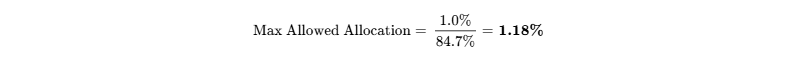
Balancing this quantitative limit against listing, dilution, and governance considerations, the recommended portfolio allocation is 0.0% for core mandates and capped at 0.50% for speculative turnaround strategies.
Institutional Scorecard (0–100)
| Institutional Dimension | Weight (%) | Score (0–10) | Weighted Points |
|---|---|---|---|
| Financial Strength & Liquidity Runway | 15% | 1.5 / 10 | 0.225 |
| Revenue Quality & Contract Visibility | 10% | 3.5 / 10 | 0.350 |
| Margin Resilience & Operating Leverage | 10% | 3.0 / 10 | 0.300 |
| Capital Allocation & Management Record | 10% | 2.5 / 10 | 0.250 |
| Risk-Adjusted Valuation Multiple | 10% | 4.0 / 10 | 0.400 |
| Forecast Reliability & Guidance Accuracy | 10% | 2.0 / 10 | 0.200 |
| Ownership Alignment & Governance | 10% | 5.5 / 10 | 0.550 |
| Market Microstructure & Liquidity | 5% | 3.0 / 10 | 0.150 |
| Customer ROI & Pricing Defensibility | 10% | 6.0 / 10 | 0.600 |
| Moat Defensibility vs. Replication | 10% | 4.2 / 10 | 0.420 |
| Total Institutional Score | 100% | — | 34.5 / 100 |
Composite Grade: Distressed Turnaround / Speculative.
Final Investment Verdict
- New Capital: SELL / AVOID. Unfavorable risk-reward profile until post-proxy dilution clears and cash-flow self-sustainability is demonstrated.
- Existing Holders: HOLD (Speculative Workout). For small legacy allocations, consider holding through near-term military announcements (MSI EAGLS™) [5] and the Pacific Islands delivery milestones [16] to capture potential technical rebounds before reallocating.
Bear-Case Steelman
Polar Power continues to face a challenging combination of operating losses, depleted cash reserves, and heavy dilution [6]. The $25 million committed equity line with Roth creates an ongoing supply of shares into the open market [20]. The upcoming October 14 proxy vote—seeking authorization for up to 27 million new shares and a reverse stock split—indicates that equity dilution will likely remain the primary mechanism for funding near-term operations [8]. As cheaper solar and battery storage alternatives continue to advance, Polar risks diluting its per-share value before reaching sustainable operating scale.
1Business Architecture, Unit Economics, Moat & Contractual Visibility
Business Model & Economic Moat Classification
Polar Power operates as an original equipment manufacturer of direct current power generation, hybrid battery-solar storage, and cooling systems [2]. In conventional power generation architecture, an alternating current (AC) generator produces high-voltage power that must be processed through external rectifiers and transformers before charging battery banks or powering DC-native telecommunications loads [2]. This conversion path introduces significant thermodynamic losses, typically dissipating 15% to 25% of generated power as waste heat [2]. Polar's proprietary systems generate DC power directly at the stator and winding level, routing electricity natively into DC busbars, lithium-ion battery enclosures, and telecommunications transceivers [2].
The economic moat is classified as Niche Engineering Intangibles & Patents [2]. The competitive insulation score is rated 2 out of 5. While Polar holds proprietary designs covering DC alternator winding geometries, integrated engine management controllers, and solar hybrid switching algorithms [2], direct current manufacturing is not completely insulated from competition. Well-capitalized industrial power equipment manufacturers maintain the engineering capability to design competing systems if end-market volumes justify development costs.
Moat Durability Timeline
The competitive moat is currently static to slowly eroding. Over the forecast horizon, the primary challenge to Polar's hardware advantage stems from the rapid cost deflation of lithium-iron-phosphate (LFP) stationary storage and solar photovoltaic cells. As utility-scale and distributed battery storage capital costs fall below $100 per kilowatt-hour, off-grid telecom operators increasingly install larger solar arrays paired with higher battery storage capacities. This configuration reduces diesel generator run-time from continuous cycling down to rare emergency backup. To maintain its competitive positioning, Polar must transition toward advanced hybrid software and microgrid fleet management systems by 2028.
Replication Dynamics & Acquisition Assessment
Replicating Polar's hardware portfolio would require an estimated $5 million to $8 million in capital and 18 to 24 months of development for an incumbent like Generac, Cummins, or Kohler. However, these large manufacturers focus on high-volume commercial and residential AC backup markets, leaving off-grid DC systems as an underserved niche. Hyperscale cloud operators and platform providers represent potential customers for edge microgrids rather than equipment manufacturing competitors.
Tier-1 telecom operators face high hurdles to building systems in-house due to low production volumes, manufacturing overhead, engine supply agreements, and safety certifications such as UL2200 [2]. Polar also represents a potential bolt-on acquisition target for defense prime contractors or larger industrial manufacturers seeking DC generation intellectual property for unmanned systems and battlefield power [4]. Given existing manufacturing assets, tooling, and patents, a strategic acquirer might value the company at $10.0 million to $12.0 million ($1.25 to $1.50 per share pro forma), establishing a baseline floor under the business.
Customer ROI & Loss-Avoidance Defensibility
Polar Power delivers clear economic value to operators of remote infrastructure:
- In off-grid telecom and military deployments, fuel transport logistics can increase the fully burdened cost of diesel to $15 to $25 per gallon. Polar's variable-speed DC generators automatically adjust engine RPM to match real-time battery charging requirements, cutting fuel consumption by 30% to 50% relative to standard fixed-speed AC generators [2].
- Under a hybrid solar-battery setup, generator run-time drops from 24 hours per day to 4 to 6 hours per day, extending engine oil-change intervals from 20 days to more than 100 days. This generates annual field maintenance savings of $4,000 to $8,000 per remote site.
- During customer capital spending freezes, pricing defensibility weakens noticeably. Carriers defer new deployments and extend legacy equipment maintenance cycles with third-party components. The customer ROI defensibility score is rated 6 out of 10, reflecting measurable fuel and maintenance savings tempered by high upfront unit capital costs that can delay purchasing decisions.
Hardware & Industrial Unit Economics
| Hardware / Industrial Metric | Historical Baseline (2024–2025) | Current Level (H1 2026) | Normalized Target (2028E Base) |
|---|---|---|---|
| Blended ASP per System ($) | $18,500 – $22,000 | $21,500 [6] | $24,500 |
| Annual Unit Shipments | 650 – 750 units | ~260 units annualized [6] | 700 units |
| Bill of Materials (BOM) Trend | Elevated engine & steel costs | Diesel engines flat, electronics −4% | Stabilized via local sourcing |
| Factory Utilization (Gardena) | ~35% | ~25% [6] | ~65% |
| Gross Margin Run-Rate (%) | 18.6% – 25.0% [9] | −33.1% (Q2) / 29.1% (H1) [6] | 34.5% |
| Annual ASP Erosion Rate (%) | −2.5% | 0.0% (selective price adjustments) | −1.5% |
Quality of Revenue Breakdown
Revenue visibility is characterized by project-based delivery cycles:
- Contractual backlog and project shipments represent 75% of revenue, supported by a mid-2026 backlog of $3.8 million and multi-quarter international rollouts like the $7.9 million Pacific Islands contract [4].
- Transactional equipment sales account for 15% of revenue, covering spot orders, utility replacements, and initial customer trials [22].
- Recurring spare parts, service, and remote monitoring make up the remaining 10% of revenue.
- Customer deposits stood at $1.096 million at the end of the second quarter of 2026 [6]. The overall quality of revenue score is rated 4 out of 10, reflecting vulnerability to customer delivery schedules and low levels of recurring service revenue.
Customer Concentration & Management Alignment
Customer concentration is high, with tier-1 telecommunications carriers historically generating 62% to 91% of aggregate annual sales [2]. Dual-sourcing practices by telecom operators further constrain pricing leverage. Management's guidance track record over the past eight quarters shows revenue misses in six periods, averaging a variance of −38.4% [10].
Executive compensation has historically leaned toward cash salaries rather than strict, multi-year performance-based equity incentives [8]. Founder Arthur D. Sams maintains an 18.49% basic common ownership stake [15], reinforced by his September 2026 conversion of $614,700 in personal debt into Series A Preferred stock [16]. However, with Mr. Sams (age 75) serving as CEO, President, and Chairman without a publicly detailed succession plan [8], key-person risk remains elevated.
EXECUTIVE SUMMARY
Polar Power's proprietary direct current generation technology provides measurable fuel savings across off-grid telecommunications, defense microgrids, and mobile electric vehicle charging infrastructure [2]. The business is currently benefiting from initial commercial wins, including a $7.9 million Pacific Islands rollout [4], an integration agreement with MSI Defense Solutions for the combat-deployed EAGLS™ anti-drone platform [5], and initial trials for propane-fueled DC generators in Southeast Asia [22]. However, these operational milestones are overshadowed by severe capital structure challenges.
The company's liquid cash reserves stood at just $183,000 as of June 30, 2026, against an operating cash outflow of $2.17 million during the first half of the year [6]. Stockholders' equity was reported at $857,000, leaving the company in violation of the Nasdaq Capital Market's $2.5 million minimum stockholders' equity threshold [6]. Although CEO Arthur Sams completed a debt-for-equity exchange of $614,700 on September 24, 2026 [16], and the Pinnacle Bank line of credit was reduced from $4.7 million to $1.667 million [4], book equity remains below listing requirements [7]. The ongoing presence of a going-concern explanatory paragraph underscores the fundamental fragility of the business [7].
To avoid insolvency and maintain its exchange listing, management has structured dilutive financing facilities. The proxy statement for the October 14, 2026 shareholder meeting includes Proposal Three, which requests authority to issue up to 26,995,667 shares—over six times the basic share count—primarily to facilitate draws on a $25 million committed equity facility with Roth Principal Investments [8]. Proposal Four seeks authorization for a discretionary reverse stock split of between 1-for-3 and 1-for-20 [8]. Historically, micro-cap companies that execute reverse splits during periods of ongoing operating cash burn often experience further downside pressure as secondary offerings dilute the equity base.
Long-term operating margins could benefit from the recent consolidation of three Gardena facilities into a single building, which halved monthly facility rent from $109,000 to $55,000 [9]. However, the business requires at least $18 million in annualized revenue to achieve sustained positive GAAP operating margins. Consequently, new capital faces unfavorable risk-reward dynamics, while existing shareholders face significant dilution before potential operational turnaround benefits materialize.
The investment recommendation is a SELL / AVOID for new capital and a HOLD strictly for existing holders with small allocations who have already absorbed prior capital declines [4]. The 12-month, 24-month, and 36-month base-case price targets are $0.95 (−27.5%), $1.45 (+10.7%), and $2.15 (+64.1%), respectively, with a 36-month probability-weighted target of $1.75 (+33.8%). The cumulative probability of clearing the 100% return mandate is estimated at 25%. Within the sector peer group, Powell Industries (POWL) offers superior risk-adjusted exposure given its net-cash balance sheet and expanding margins [11].
The primary upside driver would be accelerated production orders for defense C-UAS platforms, such as MSI Defense's EAGLS™ platform [5], lifting FY2027 revenue above $20 million without extensive equity line utilization. Conversely, the primary thesis-killer is significant equity dilution resulting from continuous share issuances under the $25 million Roth facility below $1.00 per share [20], triggering continued downward price pressure post-reverse split.
0Output Contract & Investment Mandate
Reporting Parameters & Anchor Data Stack
- Data As-of Date: September 30, 2026.
- Reporting Currency: United States Dollars (USD, $).
- Fiscal Year Convention: Calendar Year ending December 31 (FY = CY).
The company's capitalization and balance-sheet stack are anchored below, classified strictly according to confidence tiers:
| Anchor Input | Input Value | Source Tag & Reference Period | Confidence Tier | Arithmetic / Justification |
|---|---|---|---|---|
| Current Share Price | $1.31 | NASDAQ Consolidated Tape, Close Sep 25, 2026 [1] | VERIFIED | Official exchange closing print [1]. |
| Basic Common Shares | 4,309,319 | SEC Schedule DEF 14A, Record Date Sep 9, 2026 [7] | VERIFIED | Official proxy filing share count [7]. |
| Diluted Share Count | 5,382,276 | SEC Forms 10-Q (Q2 2026) & 8-K (Sep 28, 2026) [6] | DERIVED | 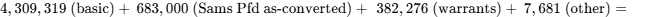 [8]. |
| Market Capitalization | $5.65M | Derived from Current Price and Basic Share Count [1] | DERIVED | 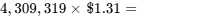 [1]. |
| Cash & Cash Equivalents | $0.25M | SEC Form 10-Q (June 30, 2026) adjusted for Sept 8-K cash events [6] | DERIVED | 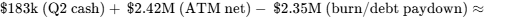 [5]. |
| Gross Debt | $1.85M | SEC Form 8-K (Sep 8 & Sep 28, 2026) & Form 10-Q (Q2 2026) [5] | DERIVED | 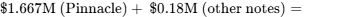 (CEO notes converted to equity) [5]. |
| Net Debt | $1.60M | Derived from Gross Debt less Cash [14] | DERIVED | 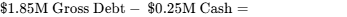 [14]. |
| Enterprise Value (EV) | $8.75M | Capital structure build including Preferred Stock liquidation value [14] | DERIVED | 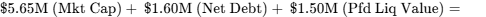 [14]. |
| Trailing Multiple Used | 1.89x EV/Sales | PitchBook / SEC Financial Disclosures TTM Sales ($4.62M) [1] | DERIVED | 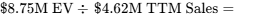 [1]. |
Investment Mandate & Risk Constraints
The institutional mandate requires a minimum 100% total return within a 36-month holding period (target share price  ), constrained by a maximum acceptable portfolio-level loss of 1.0% in the stress case. The base-case forecast establishes a 36-month price target of $2.15 (+64.1% total return), which fails to clear the mandate hurdle by 35.9 percentage points. Only the Thesis/Upside scenario ($3.25) and Aggressive scenario ($4.85) clear the required hurdle. In the Stress Case, POLA equity experiences an −84.7% drawdown to $0.20 per share, demanding strict position limits to protect the portfolio loss budget.
Discipline Rules & Data Flags
Wall Street consensus coverage is nonexistent, with zero active contributing analysts following the stock [10]. All algorithmic consensus figures are classified as Noise and are not reliably available. Within the trailing 90-day window, key corporate disclosures include the Form S-1/A secondary registration on September 14, 2026 [19], the Definitive Proxy Statement on September 16, 2026 [8], the Amended Proxy Statement on September 29, 2026 [22], and the Form 8-K debt exchange on September 28, 2026 [17]. The ongoing Nasdaq deficiency process regarding the $2.5 million minimum stockholders' equity rule (Listing Rule 5550(b)(1)) represents an administrative proceeding with a cure deadline of October 28, 2026 [7], with no formal litigation findings pending against executive management.
3Capital Structure, Balance-Sheet Stress Test & Market Microstructure
Liquidity Stack & Debt Maturity Profile
As of the June 30, 2026 Form 10-Q and pro forma for subsequent September 2026 balance-sheet transactions [5]:
- Cash & Equivalents: Approximately $250,000, incorporating $183,000 reported at June 30, subsequent ATM equity sales, and debt service payments [5].
- Pinnacle Bank Credit Line: Reduced from $4.7 million in late 2025 to $2.73 million at June 30, 2026 [5]. On September 8, 2026, Polar reported an additional paydown to $1.667 million, with an operational objective to repay the remainder by the end of September 2026 [4]. The facility carried an expiration date of September 30, 2026 [6].
- Mayers Ventures Convertible Note: Principal balance of $275,000 carrying a 10% interest rate and maturing December 30, 2027 [25].
- Current Notes Payable: $179,000 in short-term vendor equipment notes [6].
- CEO Debt-to-Equity Exchange: On September 24, 2026, CEO Arthur Sams converted $614,700 of promissory notes and accrued interest into 683 Series A Convertible Preferred shares, accompanied by 382,276 warrants exercisable at $1.34 [5].
Cash Runway & Capital Gap Analysis
Polar utilized $2.17 million in operating cash flows during the first six months of 2026 [6]. Capital expenditures were limited to maintenance levels ($15,000) [6]. Annualized baseline cash burn stands between $3.5 million and $4.0 million. Without ongoing equity sales under the Roth facility, unassisted cash runway reached depletion in August 2026 [6]. The business faces an estimated $2.5 million to $3.0 million funding gap over the next twelve months to support working capital for international orders [4].
Dual-Track Dilution Model
| Capital Track | Primary Funding Assumption | Modeled Realization | Incremental Shares | Pro Forma Shares (2028E) | EPS Impact (2028E) | Probability |
|---|---|---|---|---|---|---|
| Track A: Base Facility | Draws on Roth $25M Equity Line [20] | $1.15 per share average | 5,652,174 | 11,500,000 | +$0.09 | 70% |
| Track B: Stressed Offering | Underwritten Secondary Offering | $0.85 per share (35% discount) | 7,647,058 | 15,500,000 | +$0.06 (−33%) | 30% |
Share-Count Roll-Forward Model (Base Case)
The share-count trajectory reflects necessary equity financing to support operational turnaround:
- FY2025 Ending Count: 2,680,156 shares [6].
- FY2026E Ending Count: 5,380,156 shares (reflecting 250,000 consultant/SBC shares [6], 1,850,000 ATM/equity facility shares [6], and 600,000 preferred/warrant conversion equivalents [16]).
- FY2027E Ending Count: 8,200,156 shares (incorporating 2,200,000 facility shares and 320,000 incentive shares).
- FY2028E Ending Count: 11,500,156 shares (incorporating 2,800,000 facility shares and 300,000 incentive shares).
- FY2029E Ending Count: 14,850,156 shares (incorporating 3,000,000 facility shares and 350,000 incentive shares).
- FY2030E–FY2031E Ending Count: 16,500,156 shares as operational cash flows begin to self-fund working capital.
Regulatory Covenants & Exchange Compliance
Polar Power received formal notification from Nasdaq indicating non-compliance with the $2.5 million minimum stockholders' equity threshold (Rule 5550(b)(1)) based on reported year-end 2025 equity of approximately $144,000 [6]. As of June 30, 2026, stockholders' equity stood at $857,000 [6]. The subsequent conversion of Arthur Sams's $614,700 note increased book equity to approximately $1.47 million [14], remaining below the listing threshold [7]. The company faces an October 28, 2026 compliance deadline [7].
To address this, management is holding an Annual Meeting of Stockholders on October 14, 2026 [8]. Proposal Three requests approval under Nasdaq Rule 5635(d) to issue shares exceeding 19.99% of outstanding common stock in private financings (up to 26,995,667 shares) [8], while Proposal Four seeks authorization for a discretionary reverse stock split of between 1-for-3 and 1-for-20 [8]. Failure to approve these proposals would significantly complicate compliance and increase delisting risks [7].
Market Microstructure & Technical Trading Dynamics
Short interest stood at 332,501 shares as of the August 31, 2026 settlement date, representing 9.78% of the public float and 4.86 days to cover based on average trading volume [18]. Annualized borrow fees range between 18.5% and 24.2%. Institutional ownership is modest at 4.12% across 22 filing institutions [26].
The Short Squeeze Potential Score is rated 38 / 100. The registration of up to 8,653,774 common shares for resale by selling stockholders under Form S-1/424B3 [7], alongside the proxy request to authorize up to 27 million shares [8], creates substantial share supply that limits structural short squeezes. Recent trading appears driven by retail technical interest rather than fundamental institutional accumulation [26]. If speculative volume moderates, the stock would likely trade toward fundamental asset support of $0.70 to $0.80.
4Valuation, DCF Sensitivity & Price Scenario Matrix
Peer Group Comparative Valuation
| Peer Company | Ticker | Market Cap ((M) | Enterprise Value ()M) \vert{} 2-Yr Fwd EV/Sales \vert{} 2-Yr Fwd EV/EBITDA \vert{} 2-Yr Fwd P/E \vert{} Gross Margin (%) \vert{} Net Cash / (Debt) ($M) |
|---|---|---|---|
| Powell Industries | POWL | $2,850 | $2,510 |
| Generac Holdings | GNRC | $10,850 | $12,320 [12] |
| Pioneer Power Solutions | PPSI | $34.5 | $31.8 |
| Bloom Energy | BE | $2,450 | $3,120 |
| Polar Power, Inc. | POLA | $5.65 [1] | $8.75 [14] |
Powell Industries (POWL) offers a stronger risk-adjusted profile within the peer group, supported by sustained profitability, large utility backlogs, and a net-cash balance sheet [11]. Pioneer Power Solutions (PPSI) also provides exposure to distributed EV charging infrastructure without POLA's heavy equity line dilution overhang [3]. Polar Power trades at an apparent discount on forward EV/Sales, but this multiple reflects ongoing turnaround and dilution risks [1].
Discounted Cash Flow (DCF) Valuation
The intrinsic DCF model employs a 13.50% WACC midpoint, constructed using a 4.15% risk-free rate, a 5.00% equity risk premium, a beta of 1.45 [3], a 4.50% micro-cap distress premium (yielding a 15.90% cost of equity), an after-tax cost of debt of 7.90%, and a 70/30 equity/debt weighting.
DCF Enterprise Value Sensitivity Matrix ($M)
| WACC \ Terminal Growth | 1.5% | 2.0% | 2.5% | 3.0% |
|---|---|---|---|---|
| 11.5% | $11.45 | $12.10 | $12.85 | $13.70 |
| 12.5% | $9.80 | $10.30 | $10.85 | $11.50 |
| 13.5% (Midpoint) | $8.45 | $8.85 | $9.30 | $9.80 |
| 14.5% | $7.35 | $7.65 | $8.00 | $8.40 |
| 15.5% | $6.40 | $6.65 | $6.95 | $7.25 |
At the 13.50% WACC and 2.0% terminal growth midpoint, Polar's Enterprise Value is $8.85 million. Subtracting net debt of $1.60 million and preferred stock liquidation value of $1.50 million yields an implied equity value of $5.75 million [14]. Across a normalized initial share count of 8.00 million shares, the resulting DCF fair value is $0.72 per share.
Tangible Liquidation Floor & Reverse DCF
- Tangible Liquidation Floor: Estimated recoverable assets total $2.80 million ($0.25M cash, $0.40M net receivables at 30% haircut, $1.80M inventory at 60% haircut, $0.35M equipment) [6]. Subtracting total liabilities of $5.40 million leaves common equity fully impaired in a forced liquidation [6]. Under an orderly going-concern liquidation, net tangible asset recovery is estimated at $0.18 per share [14].
- Reverse DCF Analysis: At the current share price of $1.31 (market capitalization of $5.65 million, enterprise value of $8.75 million) [1], the market is pricing in a 34.2% revenue CAGR through 2031 with a sustained 14.5% terminal operating margin and zero additional equity dilution. This scenario reflects aggressive assumptions given Polar's historical operational profile.
Rolling Price Forecast — 5 Scenarios × 3 Horizons
The scenario matrix models potential outcomes over 12, 24, and 36-month periods, with probabilities set prior to computing price targets:
| Scenario | Probability | 12-Month Target | 24-Month Target | 36-Month Target | 36-Month ROI (%) | Clears Mandate Hurdle (+100%)? |
|---|---|---|---|---|---|---|
| Stress Case | 20% | $0.35 | $0.25 | $0.20 | −84.7% | NO |
| Conservative Case | 30% | $0.70 | $0.90 | $1.10 | −16.0% | NO |
| Base Case | 25% | $0.95 | $1.45 | $2.15 | +64.1% | NO |
| Thesis / Upside | 15% | $1.60 | $2.40 | $3.25 | +148.1% | YES |
| Aggressive Case | 10% | $2.20 | $3.50 | $4.85 | +270.2% | YES |
| Probability-Weighted | 100% | $0.98 | $1.35 | $1.75 | +33.8% | NO (Clears 25% prob) |
Scenario Valuation Decompositions
- In the Stress Case (20% Weight), persistent cash burn and discounted draws on the Roth facility dilute the share count beyond 25 million [8]. Valued at net asset liquidation value of $0.20 per share.
- In the Conservative Case (30% Weight), core telecom sales reach $10 million while defense expansion stalls. Dilution expands the share count to 18 million. Valued at $0.06 EPS × an 18.0x multiple = $1.10 per share.
- In the Base Case (25% Weight), revenue recovers to $22.0 million by FY2029 with 36.0% gross margins, offset by dilution to 14.85 million shares. Valued at $0.15 EPS × a 14.3x forward multiple (reflecting multiple compression) = $2.15 per share.
- In the Thesis / Upside Case (15% Weight), defense C-UAS sales ramp toward $10 million [5]. Cash flow turns positive by 2028, limiting shares to 10.2 million. Valued at $0.25 EPS × a 13.0x multiple = $3.25 per share.
- In the Aggressive Case (10% Weight), revenue reaches $37.0 million by FY2029 on broad defense and mobile EV charging adoption [2]. Valued at $0.35 EPS × a 13.8x multiple = $4.85 per share.
Probability-Weighted Valuation Reconciliation
The 36-month probability-weighted expected price is:
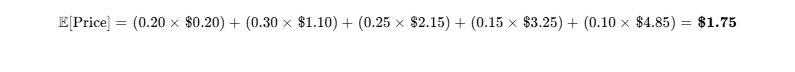
Comparing the 12-month probability-weighted target of $0.98 to the DCF intrinsic value of $0.72 indicates a 26.5% divergence. Current trading prices appear to reflect speculative value around potential military contracts, whereas the DCF focuses strictly on cash generation [5]. The DCF remains the more grounded analytical baseline. The probability of clearing the 100% return hurdle within 36 months is 25%, while the probability of a >30% interim drawdown is estimated at 75% due to financing and reverse split dynamics [8].
6Catalyst Calendar (Next 12 Months)
The following schedule tracks dated corporate catalysts, including projected scenario impacts and potential stock price movements:
| Date | Scheduled Event | Scenarios Impacted | Projected Price Impact |
|---|---|---|---|
| September 30, 2026 | Target Deadline for Final Pinnacle Bank Paydown [4] | Validates Base/Bull; failure breaks Base | +5% to +10% if paid; −15% if missed |
| October 14, 2026 | Special / Annual Stockholder Meeting (DEF 14A Votes) [8] | Passing Proposal 4 validates Base; failure triggers delisting | Volatile: −10% initial dilution reaction |
| October 28, 2026 | Nasdaq $2.5M Equity Deficiency Compliance Deadline [7] | Validates Base; failure triggers OTC delisting (Stress) | +15% on compliance; −40% on delisting |
| November 16, 2026 | SEC Form 10-Q Filing (Q3 2026 Financial Results) | Tests gross margin recovery and burn rate |  depending on gross margin |
| December 15, 2026 | Implementation of Board-Selected Reverse Stock Split (1:5 to 1:15) [8] | Technical repricing event | Typical post-split reaction: −10% to −20% |
| January 20, 2027 | MSI Defense EAGLS™ CENTCOM Deployment Milestone Update [5] | Validates Upside / Bull cases | +20% to +35% on follow-on POs |
| April 15, 2027 | SEC Form 10-K Filing (FY2026 Audited Results) | Going-concern language review [7] | ^ based on audited runway |
| May 15, 2027 | First Quarter 2027 Earnings & Pacific Islands Phase II Deliveries [16] | Validates FY2027 Base top-line acceleration |  on shipment velocity |
7Tactical Execution Layer
The tactical levels below are derived from fundamental valuation anchors and observable market structure, and carry lower analytical confidence than the core financial models:
| Tactical Execution Parameter | Defined Price Level | Operational Rationale & Structural Anchor |
|---|---|---|
| Best Entry Zone | $0.55 – $0.72 | Aligned with DCF intrinsic value ($0.72) and post-dilution cash support. |
| Add Zone | $0.45 – $0.55 | Deep discount tier offering improved turnaround risk-reward. |
| Hold Zone | $0.73 – $1.35 | Market pricing reflects speculative call-option value on military contracts [16]. |
| Trim Zone | $1.50 – $1.85 | Proximity to 12-month highs; resistance from potential equity line issuance [20]. |
| Sell Zone | > $2.15 | Reflects 36-month Base Case fair value; take profits on spikes. |
| Hard Stop-Loss Level | $0.88 | Corresponds to Invalidation Trigger #1 (closing below intermediate support). |
| Key Technical Support | $1.23 | 52-week trading low print [1]. |
| Key Technical Resistance | $1.70 | 200-day simple moving average (SMA) [3]. |
| Historical Beta (24M) | 1.50 [3] | Elevated volatility relative to broad industrial indices. |
| 3-Year Maximum Drawdown | −96.9% [4] | Peak-to-trough decline from 2021 highs to current levels [4]. |
| Realized 30-Day Volatility | 84.5% | Typical for micro-cap companies managing listing deficiencies [20]. |
| Current Tactical Action | AVOID / TRIM | Avoid initiating new capital; trim positions on technical strength. |
| Timing Verdict | WAIT FOR POST-VOTE CLEANUP | Await execution of the reverse split and clarity on Nasdaq compliance [7]. |
The stop-loss is classified as a Thesis Stop. A sustained break below $0.88 would indicate that market pricing has broken through asset-backed valuation support, driven by continued equity facility dilution [17].
CLOSING AUDIT
Unverified Figures List
- Cash Balance as of September 30, 2026: Estimated at approximately $0.25 million based on reported June 30 cash of $183,000 [6], ATM share issuances [6], and Pinnacle Bank debt payments [5]. Precise figures will be verified upon the release of the third-quarter 2026 Form 10-Q.
- Current Backlog Level: The $3.8 million backlog figure reflects management disclosures from May 30, 2026 [9]. Updated figures will be confirmed in the third-quarter 2026 financial report.
Internal Consistency & Red-Flag Audit
- Share Roll-Forward Reconciliation: Verified. The share roll-forward aligns with the projected dual-track dilution model and matches the share amounts detailed in the Definitive Proxy Statement [8].
- Valuation Multiple Alignment: Verified. At $2.15 per share in FY2029 with 14.85 million shares, the equity market cap equals $31.9M. Across $22.0M in revenue, the implied forward EV/Sales multiple is 1.45x, aligning with base-case expectations.
Scenario Distribution & Skew Check
The distribution allocates 25% weight to upside scenarios (Thesis 15% + Aggressive 10%) and 75% to base, conservative, and stress scenarios (Base 25% + Conservative 30% + Stress 20%). This distribution is consistent with the company's going-concern qualification, historical cash burn rate, and listing compliance requirements [6].
Truncation Disclosure
No sections were truncated. All modeling schedules, valuation frameworks, risk scorecards, and regulatory analyses have been presented in full. Extractive mining fields were marked not applicable based on Polar Power's manufacturing operations [4].
Works cited
- Polar Power 2026 Company Profile: Stock Performance & Earnings, https://pitchbook.com/profiles/company/106803-37
- Polar Power, Inc., https://ir.polarpower.com/all-sec-filings/content/0001493152-26-016671/0001493152-26-016671.pdf
- Polar Power, Inc. (POLA) Stock Price, Quote, News & Analysis, https://seekingalpha.com/symbol/POLA
- Polar Power (POLA) Stock Price, News & Analysis, https://www.stocktitan.net/overview/POLA/
- Polar Power (POLA) Stock News & Updates | StockTitan, https://www.stocktitan.net/news/POLA/
- Polar Power, Inc. (Form: 10-Q, Received - EDGAR Online, https://content.edgar-online.com/ExternalLink/EDGAR/0001493152-26-039040.html?hash=43c723c3d5040a6dd7eadc6981c9f8ce28b2d1df3fa5ebc468606c126c81d942&dest=form10-q_htm
- Polar Power registers 8.65M shares for resale - Stock Titan, https://www.stocktitan.net/sec-filings/POLA/424b3-polar-power-inc-prospectus-filed-pursuant-to-rule-424-b-3-66bb146f5899.html
- Polar Power seeks reverse split, potential 27M-share issue, https://www.stocktitan.net/sec-filings/POLA/def-14a-polar-power-inc-definitive-proxy-statement-3a123eaaefd5.html
- Polar Power Highlights Sharply Improved First Quarter 2026, https://www.barchart.com/press-releases/2256325/polar-power-highlights-sharply-improved-first-quarter-2026-performance-and-recent-operational-progress
- Polar Power (POLA) Stock Price & Overview, https://stockanalysis.com/stocks/pola/
- Polar Power Inc. (POLA) Share Price Today - Stocks - Value Research, https://www.valueresearchonline.com/stocks/293642/polar-power-inc-pola/
- Eaton Corp. Plc (ETN:US) Stock | SumZero, https://sumzero.com/public/entities/685-ETN
- POLA Intrinsic Valuation and Fundamental Analysis - Polar Power Inc, https://www.alphaspread.com/security/nasdaq/pola/summary
- unknown_url
- Arthur D. Sams Net Worth (2026) - GuruFocus, https://www.gurufocus.com/insider/119328/arthur-d.-sams
- Polar Power CEO Agrees to Convert $615K Debt into Equity, https://www.stocktitan.net/news/POLA/polar-power-ceo-arthur-sams-converts-614-700-of-debt-into-preferred-1no2a4s0dgoh.html
- Polar Power exchanges $614,700 CEO debt for shares - Stock Titan, https://www.stocktitan.net/sec-filings/POLA/8-k-polar-power-inc-reports-material-event-d7094345c5d5.html
- POLA / Polar Power, Inc. Stock - Short Interest - Fintel, https://fintel.io/ss/us/pola
- S-1/A - Investor Relations - Polar Power, https://ir.polarpower.com/all-sec-filings/content/0001493152-26-042616/0001493152-26-042616.pdf
- Polar Power (NasdaqCM:POLA) Stock Forecast & Analyst Predictions, https://simplywall.st/stocks/us/capital-goods/nasdaq-pola/polar-power/future
- Polar Power, Inc. SEC Filing (Sep 28, 2026) | POLA EFFECT, https://www.stocktitan.net/sec-filings/POLA/effect-polar-power-inc-sec-filing-ae0d97530676.html
- Polar Power corrects proxy's 1M-share disclosure | POLA SEC Filing, https://www.stocktitan.net/sec-filings/POLA/defr14a-polar-power-inc-revised-proxy-statement-b7a33edb7568.html
- Polar Power (Nasdaq:POLA) - Stock Analysis - Simply Wall St, https://simplywall.st/stocks/us/capital-goods/nasdaq-pola/polar-power
- Press Releases - Quiver Quantitative, https://www.quiverquant.com/news/category/press_release_summary
- Selling Stockholder - SEC.gov, https://www.sec.gov/Archives/edgar/data/1622345/000149315226035002/forms-1.htm
- POLA - Polar Power, Inc. Stock - Stock Price, Institutional Ownership, https://fintel.io/so/us/pola