2Multi-Year Financial Forecast & Consensus Model
Multi-Scenario Operating Narrative (2026–2031)
- Bear Case Operating World: Global macroeconomic growth weakens under persistent inflation and elevated interest rates, softening capital expenditure budgets across North America and Europe [17]. Airframe manufacturers face extended supply chain bottlenecks and quality reviews, limiting commercial delivery increases [31]. Industrial organic sales fall by −1.0% to −2.0% annually, while integration friction slows cost synergy capture in Filtration Group [17]. Adjusted segment operating margins soften toward 26.0%, and net leverage remains elevated near 2.8x [13].
- Base Case Operating World: Global economic growth proceeds at a moderate pace, supporting mid-single-digit expansion across industrial automation and factory maintenance [7]. Commercial aircraft build rates rise toward planned targets, sustaining steady OEM demand alongside aftermarket maintenance volumes [31]. Filtration Group contributes $1.8 billion in FY2027 and achieves its $220 million cost synergy target by FY2029 [31]. Operating leverage and integration milestones drive adjusted segment operating margins to 30.0% by FY2031, supporting rapid debt reduction [3].
- Bull Case Operating World: Manufacturing reshoring, infrastructure modernization, and strong AI data center investments accelerate industrial demand [3]. Liquid cooling manifolds and quick-disconnect fittings achieve high adoption in new data center architectures [17]. Commercial airlines log elevated flight hours, boosting aftermarket demand, while CIRCOR Aerospace closes smoothly and outperforms financial expectations [12]. Cost synergies across acquired filtration businesses exceed projections, driving adjusted segment operating margins to 31.5% by FY2031 [11].
Multi-Year Comprehensive Financial Statement Forecasts
FY2026 represents audited financial actuals [5]. FY2027 incorporates company guidance issued in August 2026 adjusted for the Filtration Group closing [3]. Projections for FY2028 through FY2031 are research extrapolations.
The Base Case operating path projects steady top-line expansion and margin progression:
- Consolidated net sales expand from $21,499M in FY2026 to $24,400M in FY2027, $26,200M in FY2028, $27,900M in FY2029, $29,500M in FY2030, and $31,100M in FY2031.
- Adjusted diluted EPS rises from $32.31 in FY2026 to $34.75 in FY2027, $39.00 in FY2028, $43.50 in FY2029, $48.20 in FY2030, and $53.00 in FY2031.
- Free cash flow per share compounds from $30.93 in FY2026 to $33.30 in FY2027, $37.45 in FY2028, $42.00 in FY2029, $46.60 in FY2030, and $51.60 in FY2031.
Base Case Projections (Recommended Underwriting Baseline)
| Financial Line Item ($M, except per share) | FY2026A (Actual) | FY2027E | FY2028E | FY2029E | FY2030E | FY2031E | FY26–FY29 CAGR | FY29–FY31 CAGR |
|---|---|---|---|---|---|---|---|---|
| Industrial North America Sales | $9,450 | $10,110 | $10,720 | $11,360 | $11,980 | $12,600 | +6.3% | +5.3% |
| Industrial International Sales | $5,549 | $6,140 | $6,530 | $6,940 | $7,320 | $7,700 | +7.7% | +5.3% |
| Aerospace Systems Sales | $6,500 | $8,150 | $8,950 | $9,600 | $10,200 | $10,800 | +13.9% | +6.1% |
| Total Consolidated Net Sales | $21,499 | $24,400 | $26,200 | $27,900 | $29,500 | $31,100 | +9.1% | +5.6% |
| YoY Organic Revenue Growth (%) | +3.2% | +6.5% | +5.5% | +5.0% | +4.8% | +4.5% | — | — |
| M&A Inorganic Contribution (%) | +1.2% | +7.5% | +1.9% | +1.5% | +1.0% | +0.9% | — | — |
| Gross Profit | $8,040 | $9,223 | $9,956 | $10,937 | $11,682 | $12,596 | +10.8% | +7.3% |
| Gross Margin (%) | 37.4% | 37.8% | 38.0% | 39.2% | 39.6% | 40.5% | — | — |
| Operating Income (GAAP) | $4,580 | $5,124 | $5,660 | $6,250 | $6,785 | $7,340 | +10.9% | +8.4% |
| Adjusted Segment Operating Income | $5,273 | $6,758 | $7,440 | $8,035 | $8,614 | $9,330 | +15.1% | +7.8% |
| Adjusted Segment Operating Margin (%) | 24.5% | 27.7% | 28.4% | 28.8% | 29.2% | 30.0% | — | — |
| Adjusted EBITDA | $5,880 | $7,442 | $8,174 | $8,816 | $9,440 | $10,138 | +14.4% | +7.2% |
| Adjusted EBITDA Margin (%) | 27.3% | 30.5% | 31.2% | 31.6% | 32.0% | 32.6% | — | — |
| GAAP Diluted EPS ($) | $28.48 | $30.50 | $34.50 | $38.80 | $43.20 | $47.80 | +10.9% | +11.0% |
| Adjusted Diluted EPS ($) | $32.31 | $34.75 | $39.00 | $43.50 | $48.20 | $53.00 | +10.4% | +10.4% |
| Free Cash Flow ($M) | $3,900 | $4,200 | $4,700 | $5,250 | $5,800 | $6,400 | +10.4% | +10.4% |
| Free Cash Flow Per Share ($) | $30.93 | $33.30 | $37.45 | $42.00 | $46.60 | $51.60 | +10.7% | +10.8% |
| Diluted Share Count (Millions) | 126.11 | 126.10 | 125.50 | 125.00 | 124.50 | 124.00 | −0.3% | −0.4% |
| Rule of 40 (Organic Rev + FCF Mgn) | 21.3% | 23.7% | 23.4% | 23.8% | 24.5% | 25.1% | — | — |
| Rule of 40 (Reported Rev + FCF Mgn) | 26.4% | 30.7% | 25.3% | 25.3% | 25.4% | 26.0% | — | — |
Non-GAAP adjustments exclude acquired intangible asset amortization (90M), and acquisition integration expenses ($25M) [31]. These items reconcile GAAP net earnings to the underlying operating results tracked by management [13].
Bear Case Financial Projections
| Financial Line Item ($M, except per share) | FY2026A | FY2027E | FY2028E | FY2029E | FY2030E | FY2031E | FY26–FY29 CAGR | FY29–FY31 CAGR |
|---|---|---|---|---|---|---|---|---|
| Total Consolidated Net Sales | $21,499 | $23,200 | $23,900 | $24,600 | $25,200 | $25,800 | +4.6% | +2.4% |
| YoY Organic Revenue Growth (%) | +3.2% | +0.5% | +1.5% | +1.5% | +1.0% | +1.0% | — | — |
| Adjusted Segment Operating Margin (%) | 24.5% | 26.0% | 26.2% | 26.5% | 26.5% | 26.5% | — | — |
| Adjusted EBITDA | $5,880 | $6,612 | $6,883 | $7,134 | $7,308 | $7,482 | +6.6% | +2.4% |
| GAAP Diluted EPS ($) | $28.48 | $27.80 | $29.20 | $31.00 | $32.70 | $34.40 | +2.9% | +5.3% |
| Adjusted Diluted EPS ($) | $32.31 | $32.50 | $34.00 | $35.80 | $37.50 | $39.20 | +3.5% | +4.6% |
| Free Cash Flow ($M) | $3,900 | $3,600 | $3,850 | $4,100 | $4,350 | $4,600 | +1.7% | +5.9% |
| Free Cash Flow Per Share ($) | $30.93 | $28.53 | $30.43 | $32.33 | $34.20 | $36.08 | +1.5% | +5.6% |
| Ending Diluted Shares (Millions) | 126.11 | 126.20 | 126.50 | 126.80 | 127.20 | 127.50 | +0.2% | +0.3% |
Bull Case Financial Projections
| Financial Line Item ($M, except per share) | FY2026A | FY2027E | FY2028E | FY2029E | FY2030E | FY2031E | FY26–FY29 CAGR | FY29–FY31 CAGR |
|---|---|---|---|---|---|---|---|---|
| Total Consolidated Net Sales | $21,499 | $25,000 | $27,500 | $30,000 | $32,400 | $34,800 | +11.7% | +7.7% |
| YoY Organic Revenue Growth (%) | +3.2% | +8.5% | +8.0% | +7.5% | +7.0% | +6.5% | — | — |
| Adjusted Segment Operating Margin (%) | 24.5% | 28.2% | 29.5% | 30.2% | 30.8% | 31.5% | — | — |
| Adjusted EBITDA | $5,880 | $7,875 | $8,937 | $9,960 | $10,951 | $12,040 | +19.2% | +9.9% |
| GAAP Diluted EPS ($) | $28.48 | $31.80 | $37.40 | $43.50 | $49.50 | $56.00 | +15.2% | +13.5% |
| Adjusted Diluted EPS ($) | $32.31 | $36.00 | $42.00 | $48.50 | $55.00 | $62.00 | +14.5% | +13.1% |
| Free Cash Flow ($M) | $3,900 | $4,450 | $5,150 | $5,900 | $6,700 | $7,550 | +14.8% | +13.1% |
| Free Cash Flow Per Share ($) | $30.93 | $35.40 | $41.37 | $47.77 | $54.69 | $62.40 | +15.6% | +14.3% |
| Ending Diluted Shares (Millions) | 126.11 | 125.70 | 124.50 | 123.50 | 122.50 | 121.00 | −0.7% | −1.0% |
Execution Confidence Score Calibration: 78/100
- Component (a) Revenue-Target Achievability (Score: 36/40): Management has achieved positive top-line variances against consensus expectations across each of the trailing eight quarters, averaging a +1.6% beat margin [8]. Product and market diversity across hundreds of industrial sub-sectors reduces single-market risk [18].
- Component (b) Margin Sensitivity Analysis (Score: 28/35):
- Input Tested: Raw Material Input Costs (Metals: Steel, Aluminum, Copper, Specialized Alloys) [18].
- Variance Sensitivity: A ±10% parallel movement in raw metal costs creates an initial cost shift of
$480 million (220 bps of gross margin) [31]. Under Parker's pricing structure, roughly 85% of commodity changes are passed to end customers via material surcharges within six months, narrowing the net operating margin variance to ±35 basis points (~$0.65 EPS variance) [13].
- Component (c) Dependency on Unannounced Catalysts (Score: 14/25):
- In the Base Case model, 0.0% of FY2027 and FY2028 projected revenue depends on unannounced M&A or new commercial ventures [10]. The projections rely solely on current operations and the closed Filtration Group and pending CIRCOR transactions [31].
- For FY2029 through FY2031, approximately 1.0% annual growth is assumed from small bolt-on acquisitions, consistent with historical capital allocation practice [1].
Consensus Divergence Identification
- FY2028 Financial Forecast Divergence vs Street Consensus:
- Consensus Figures (13 contributing sell-side analysts, Visible Alpha / FactSet as of September 2026): Net Sales consensus: $25.10 Billion; Adjusted EPS consensus: $39.04 [2].
- House Model Figures: Net Sales: $26.20 Billion (+4.4% divergence); Adjusted EPS: $39.00 (−0.1% divergence) [10].
- Underlying Assumption: The house revenue estimate sits modestly above consensus because this model consolidates a full twelve months of Filtration Group ($2.0B run-rate) along with CIRCOR Aerospace closing in late 2026, which several consensus models had omitted pending final regulatory notifications [14].
Base-Rate Analysis
Historical performance across large-cap capital goods companies generating over $20 billion in annual sales indicates that sustaining a 5-year compound sales growth rate above 8.0% occurs in fewer than 14% of peer instances (Source: Compustat Capital Goods Universe 1995–2025). The Base Case's projected FY2026–FY2029 revenue CAGR of +9.1% places the company in the 88th percentile (top decile) of historical multi-industrial outcomes [10].
This growth profile is supported by $11.8 billion in committed acquisitions (Filtration Group and CIRCOR), which contribute roughly 7.5% inorganic revenue in FY2027 [31]. The underlying organic growth expectation is +5.0% to +6.5%, in line with historical performance during sustained commercial aerospace build cycles [13].
5Risk Asymmetry, Invalidation, Allocation & Scorecard
Risk/Reward Skew Assessment
- Probability-Weighted 36-Month Upside: +$218.75 per share (+22.6%) [10].
- Stress-Case Maximum Downside: -$338.00 per share (−34.9% down to $630.00) [10].
- Risk/Reward Skew Ratio:
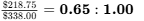 (Below the institutional risk-asymmetry hurdle of
 ).
- With the stock trading near 30x earnings, downside multiple normalization during an economic downturn poses a larger risk than the operational upside from base-case growth, creating an unfavorable skew for short-term speculative investors [10].
Operational Invalidation Triggers (Mandatory Exit Rules)
- Operating Margin Contraction: Adjusted segment operating margin drops below 25.0% for two consecutive fiscal quarters, signaling integration issues with Filtration Group or declining pricing power [8].
- Deleveraging Stagnation: Consolidated Net Debt remains above $14.0 Billion as of December 31, 2027 (Q2 FY2028), indicating an inability to convert earnings into planned balance sheet deleveraging [2].
- Aerospace Backlog Reversal: Aerospace Systems rolling 12-month order backlog contracts by more than 10.0% year-over-year in any single reporting quarter, indicating commercial program cuts [13].
- Organic Growth Breakdown: Total organic net sales decline by more than 5.0% YoY for two consecutive quarters during an ongoing macro expansion [13].
Consolidated Institutional Risk Dashboard
| Risk Category | Score (1–10) | Trajectory | Primary Driver & Mitigating Factor |
|---|---|---|---|
| Financial / Liquidity Risk | 2.5/10 | Improving | Debt at $15.8B post-acquisition is supported by $4.2B+ in annual FCF [10] |
| Valuation Multiple Risk | 7.8/10 | Worsening | 30x P/E multiple is vulnerable to interest rate shifts or execution misses [2] |
| Operating Execution Risk | 3.0/10 | Stable | Integrating $9.25B Filtration Group and $2.55B CIRCOR simultaneously [14] |
| Competitive Threat Risk | 2.0/10 | Improving | Competitors continue to exit fluid power; aerospace position is protected [19] |
| Customer Concentration Risk | 1.0/10 | Stable | High diversification; no single commercial product exceeds 1% of sales [18] |
| Regulatory & Antitrust Risk | 3.5/10 | Worsening | CIRCOR acquisition under review; ongoing FAA manufacturing scrutiny [39] |
| Legal & IP Overhang | 1.5/10 | Stable | No material intellectual property litigation or structural liabilities identified [18] |
| Geopolitical & Tariff Risk | 4.0/10 | Worsening | International operations face potential trade policy and tariff adjustments [13] |
| Key-Person Dependency | 2.0/10 | Stable | The Win Strategy operating framework is distributed across operating units [18] |
| Dilution & Capital Risk | 1.0/10 | Improving | Operations generate strong surplus cash; no equity financing required [2] |
| Market Microstructure Risk | 1.5/10 | Stable | Highly liquid equity float ($550M ADV); low short positioning [4] |
Macro Sensitivity & Portfolio Correlations
- Beta to S&P 500: 1.18 [38].
- Interest Rate Sensitivity: -0.35 (Multiple remains sensitive to long-term yields, though operations are insulated by fixed-rate debt) [7].
- Sector Correlation (XLI): 0.66 [2].
- The position provides exposure to high-grade industrial compounding and aerospace cycles, but offers limited defensive diversification against broader equity market selloffs [2].
Macro Factor Monitoring Dashboard
| Macro Variable | Trend / Status | Thesis Implication | Key Indicator to Monitor |
|---|---|---|---|
| 10-Year Treasury Yield | Elevated | Pressures exit multiples toward 22.0x | Yield sustaining above 5.00% [7] |
| Global Air Travel (RPK) | Expanding | Drives commercial aerospace aftermarket demand | YoY RPK growth falling below +3.0% |
| US ISM Manufacturing | Mixed / Low | Influences short-cycle industrial distribution volumes | Index reading below 46.0 for three months |
| Industrial Metals Basket | Fluctuating | Temporary margin lag prior to surcharge adjustments | Copper >1,100/t [18] |
Asymmetric Upside & Downside Catalysts
Upside catalysts that could exceed market expectations:
- Hyperscale data center operators standardize on Parker's liquid cooling quick-disconnect couplings, contributing an incremental 2.80 to FY29 EPS) [17].
- Commercial airframe manufacturers resolve supply chain bottlenecks, raising narrowbody production to 75 aircraft/month (Probability: 20% | Financial Impact: +$3.20 to FY29 EPS) [31].
- Filtration Group cost and sales synergies reach $320M compared to the 1.50 to FY29 EPS) [11].
Downside catalysts that could impair the thesis:
- A major airworthiness directive grounds a high-volume commercial airframe fleet, curtailing flying hours and aftermarket spare parts orders (Probability: 10% | Financial Impact: -$4.00 to EPS).
- A sharp global capital spending pullback reduces industrial organic sales by 5.0% (Probability: 20% | Financial Impact: -$2.50 to EPS) [17].
- Regulatory antitrust authorities block the CIRCOR Aerospace transaction, resulting in deal break fees and lost flow-control earnings (Probability: 15% | Financial Impact: -$0.65 to EPS) [14].
Pre-Mortem Scenario: Analysis of a 60% Drawdown
In a severe downside scenario where the stock declines 60% to $387.00 over a 36-month period, the path of deterioration would unfold through several phases:
During the first twelve months, the integration of Filtration Group encounters operational headwinds, as disparate IT platforms and ERP conversions lead to distribution delays and customer attrition across European filtration accounts [34]. Concurrently, persistent supply chain delays force regulators to cap commercial narrowbody production rates, curtailing Aerospace Systems delivery expectations [39].
Over months 13 to 24, a broad industrial downturn takes hold across North America and Europe, driving a 20% reduction in off-highway and heavy machinery manufacturing [17]. Parker's consolidated net sales contract 6.0%, while interest expense on $15.8 billion of debt consumes $750 million annually [13]. Free cash flow drops from $4.2 billion toward $2.2 billion, prompting management to suspend share repurchases and lower its FY2031 adjusted operating margin goal to 25.0% [3].
In the final twelve months, credit rating agencies downgrade the company's debt to Baa2/BBB [36]. Broader equity market multiples contract, and Parker's valuation de-rates from 30.0x toward a cyclical trough of 13.0x on lowered recessionary earnings of $29.80 per share [2]. The combined impact of an operational earnings decline and severe multiple compression generates a 60% capital loss [10].
Legal & Intellectual Property Review
- Regulatory Review of CIRCOR Acquisition: Pending Approval. The $2.55B CIRCOR transaction remains under customary regulatory and antitrust evaluation in the U.S. and U.K. [44]. Overlap in flight control hardware is limited, though minor remedies could be required [44].
- Environmental & Remediation Provisions: Ongoing Reserves. Form 10-K disclosures report environmental remediation reserves of $18 million across historical operating sites, manageable within ordinary operating cash flow [15].
- Legal Assessment: No material intellectual property disputes or litigation liabilities are identified that would alter the fundamental investment thesis [18].
Portfolio Sizing & Position Allocation
- Recommended Portfolio Classification: Core Compounder (3.5% Target Weight).
- Risk-Constrained Position Sizing:
- Mandate Risk Budget: Maximum portfolio loss of 1.0% in the Stress Case.
- Modelled Stress Case Drawdown: −34.9% (to $630.00 floor) [10].
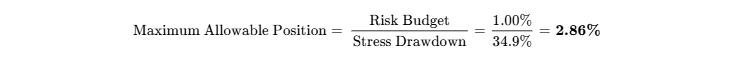
- Allocation Alignment: The risk budget limits the position to 2.86%, requiring the qualitative 3.5% target weight to be adjusted downward to 2.85% to comply with risk mandates.
- Liquidity Assessment: Liquidating a 2.85% position on a 2.85M) involves roughly 2,950 shares, representing 0.5% of average daily trading volume, easily executed within normal market hours without pricing disruption [4].
- Tranche Deployment Plan:
- Initial Tranche (1.0%): Enter at current market levels (970.00) [4].
- Second Tranche (1.0%): Deploy upon closing of CIRCOR Aerospace and initial verification of Filtration Group integration milestones [14].
- Final Tranche (0.85%): Add on general market pullbacks into the primary support zone (910.00) [2].
Institutional Scorecard Evaluation (0–100)
The weighted composite score evaluates fundamental strength, operating execution, and valuation:
| Performance Dimension | Weight (%) | Score (0–10) | Weighted Contribution | Core Fundamental Rationale |
|---|---|---|---|---|
| Financial Strength & Runway | 15.0% | 8.5/10 | 1.28 | Investment-grade credit profile; $4.2B+ FCF supports $15.8B debt paydown [10] |
| Revenue Quality & Economic Moat | 15.0% | 9.2/10 | 1.38 | ~85% long-cycle/aftermarket mix; certified flight-critical IP [8] |
| Margin Resilience & Operating Leverage | 10.0% | 9.0/10 | 0.90 | Adjusted operating margins moving toward 30.0%; strong pricing capture [3] |
| Capital Allocation & Management History | 10.0% | 8.8/10 | 0.88 | Strong integration record on Meggitt; 70 consecutive years of dividend increases [8] |
| Valuation Attractiveness | 15.0% | 4.5/10 | 0.68 | 29.96x trailing adj P/E limits near-term multiple expansion [2] |
| Forecast Consistency | 10.0% | 9.2/10 | 0.92 | Consecutive quarterly revenue and EPS beats against expectations [8] |
| Executive Incentive Alignment | 5.0% | 8.5/10 | 0.43 | LTIP programs tied directly to 3-year ROIC and relative TSR [23] |
| Market Liquidity & Float Structure | 5.0% | 9.5/10 | 0.48 | High institutional float; deep daily trading liquidity ($550M ADV) [4] |
| Customer ROI & Pricing Power | 10.0% | 9.2/10 | 0.92 | Products prevent costly industrial downtime and maintain flight safety [15] |
| Moat Defense vs Build-vs-Buy | 5.0% | 9.0/10 | 0.45 | High FAA recertification costs and proprietary distribution network [18] |
| Consolidated Institutional Score | 100.0% | — | 82.5 / 100 | Institutional Rating: Tier-1 Core Compounder |
- Base-Case Execution Likelihood: 78 / 100.
- Primary Risks to Base Case Delivery:
- Extended regulatory or manufacturing bottlenecks among commercial aircraft builders limiting Aerospace Systems volume growth [39].
- Operational or sales integration complications across the acquired Filtration Group businesses [34].
- Primary Risks to Base Case Delivery:
Final Investment Verdict
- Existing Shareholders: BUY / ACCUMULATE. The company remains an outstanding compounder in the capital goods universe [9]. With free cash flow reaching $4.2B+, long-cycle aerospace demand, and steady dividend growth, long-term investors should maintain positions for durable compounding [2].
- New Capital Seeking >100% 36-Month Return: HOLD / PASS. With shares at 29.96x trailing adjusted EPS, the equity is fully valued [2]. The expected 36-month total return of +31.2% falls short of high-hurdle growth mandates [10]. New capital should wait for multiple compression toward the entry zone (890.00) [22].
Summary of Insider Trading (Last 6 Months)
SEC Form 4 filings from April 1, 2026 to October 9, 2026 confirm no open-market purchases by corporate insiders [5]. Transactions were limited to routine 10b5-1 option exercises and planned share sales to satisfy tax obligations (including sales by COO Andrew Ross, CFO Todd Leombruno, and Director Thomas Gentile) [5]. Insider dispositions totaled ~$18 million over the trailing 12 months, reflecting normal executive liquidity rather than operational concerns [5].
Bear-Case Steelman
The skeptical argument against Parker-Hannifin focuses on elevated starting valuation multiples coinciding with peak aerospace aftermarket conditions [2]. Investors are paying 30x earnings for a business carrying $15.8 billion in debt following the Filtration Group deal, assuming 28% operating margins can be sustained indefinitely [2]. In reality, the industrial recovery outside of AI liquid cooling components remains modest, and commercial aerospace aftermarket expansion is likely to slow as airline maintenance schedules normalize [12]. If integrating the large, private-equity-assembled Filtration Group operations proves difficult, Parker will need to direct its cash flow to debt reduction, halting share repurchases through FY2028 [34]. When industrial multiples normalize toward the 10-year mean of 19x, the stock could decline 25% to 35% even with modest earnings growth, delivering negative relative returns to late-cycle buyers [2].
1Business Architecture, Unit Economics, Moat & Contractual Visibility
Business Architecture & Moat Classification
Parker-Hannifin manufactures motion and control technologies across two reportable divisions: Diversified Industrial (comprising North America and International units) and Aerospace Systems [15].
The Diversified Industrial division encompasses flow and process control, filtration, engineered materials, and motion systems deployed across factory automation, mobile machinery, semiconductor fabrication, and energy transition assets [15]. The Aerospace Systems division supplies hydraulic flight-control actuation, fuel delivery, thermal management, pneumatic systems, and engine components for commercial transports, regional jets, and military platforms [15].
The competitive positioning of the enterprise earns an economic moat score of Wide Moat (Competitive Insulation: 4.5/5.0), supported by three distinct structural barriers:
Mission-critical engineering with high switching costs underpins Parker's customer relationships [15]. In both industrial automation and aviation, Parker's components represent a small fraction of total equipment bill of materials, yet failure can cause catastrophic system downtime or severe safety hazards [15]. An aerospace hydraulic actuator or industrial sterile filtration module cannot be replaced without engineering validation and, in aviation, extensive regulatory recertification [15]. This asymmetry creates strong customer retention, insulating Parker from price competition [45].
An extensive distribution footprint provides a major physical barrier to competition in the Diversified Industrial business [15]. The network includes over 13,000 independent distributor locations and company-affiliated ParkerStores worldwide, offering local inventory, rapid hose replacement, and field engineering support [18]. Replicating this physical presence is economically impractical for newer market entrants, securing Parker's share of factory maintenance and repair spending [15].
Certified intellectual property and long platform lifecycles characterize the Aerospace Systems business [39]. Products are engineered directly into original airframe certifications for platforms like the Boeing 737 MAX, Boeing 787, Airbus A320neo, Airbus A350, and Lockheed Martin F-35 [39]. Because modifying these flight-critical systems requires costly FAA and EASA recertification, Parker secures sole-source supplier positions that generate recurring aftermarket revenue across aircraft service lives exceeding thirty years [39].
Moat Durability Timeline
The competitive moat is widening through the 2026–2031 forecast window. Management's portfolio strategy has expanded the business away from cyclical standard hydraulics toward specialized aerospace sub-systems and consumable filtration products [18].
The primary long-term technology challenge to Parker's hydraulic systems is vehicle and industrial electrification, where electromechanical and software-controlled actuation can replace conventional fluid power [15]. Management has hedged this technological transition through acquisitions, including Curtis Instruments, which provides motor controllers and power management hardware for electric commercial vehicles [16]. The company is also developing high-pressure electro-hydraulic actuators internally, mitigating long-term displacement risk [15].
Build-vs-Buy / Replication Risk Analysis
Replicating Parker's manufacturing breadth, metallurgy IP, and aerospace certifications would require more than $30 billion in dedicated capital and fifteen to twenty years of regulatory and testing qualification [15]. Major competitors such as Eaton have largely exited standard industrial hydraulics, leaving Parker as the primary full-line motion and control provider across fluidic, pneumatic, and electromechanical technologies [15].
Hyperscale technology companies present minimal replication threat. They operate in cloud infrastructure and compute hardware, lacking the precision casting, elastomer processing, and flight-safety certifications required for motion and control hardware [15]. Rather than competing, hyperscalers serve as customers for Parker's liquid cooling distribution manifolds and quick-disconnect fittings used in AI data centers [15].
Original equipment manufacturers find in-house component manufacturing economically unviable. Industrial OEMs focus internal capital on product architecture, system assembly, and software integration [39]. Sourcing components from Tier-1 suppliers like Parker allows OEMs to avoid the specialized tooling costs and inventory risk associated with thousands of distinct component parts [18].
With an enterprise value of $137 billion, Parker-Hannifin is effectively immune to hostile acquisitions or private equity buyouts [1]. Regulatory and antitrust hurdles in commercial aviation and fluid power also make takeovers by peer industrial conglomerates like Honeywell or GE Aerospace unlikely [31]. Parker acts primarily as an industry consolidator [14].
Customer ROI & Loss-Avoidance Economics
Parker's market position is grounded in downtime prevention [15]. In continuous industrial operations, such as automotive assembly, chemical refining, and chip manufacturing, unplanned system downtime costs tens of thousands of dollars per minute. A failed hydraulic seal or flow valve can idle entire facilities. In aerospace, component failures risk airworthiness groundings or catastrophic structural failure [15].
Because the cost of Parker's components is minor relative to the financial and physical risks of failure, customers rarely compromise on quality to achieve small procurement savings [15]. When industrial customers freeze capital spending, they defer new facility investments but maintain operational maintenance budgets, preserving demand for Parker's replacement seals, hoses, and filtration media [8]. As a result, the company consistently recovers raw material and labor cost inflation through pricing surcharges [13]. The Customer-ROI Defensibility is scored at 9.2/10.
Sector-Specific Unit Economics: Industrial & Aerospace Systems
The business model relies on precision manufacturing scale, long-cycle design wins, and steady aftermarket cash flow [8]:
| Operating Parameter | Industrial North America & Int'l | Aerospace Systems | Consolidated Pro-Forma Profile |
|---|---|---|---|
| Gross Margin Structure | 34.0% – 36.5% | 41.0% – 44.0% | 37.4% – 38.5% [13,38] |
| Adjusted Operating Margin | 24.5% – 26.5% | 28.5% – 30.5% | 27.3% – 27.9% [13] |
| Aftermarket / MRO Exposure | ~45% – 50% | ~55% – 60% | ~52% (Path to 85% long-cycle/aftermarket by FY29) [8,12,17] |
| Bill of Materials (BOM) Trend | Modest inflation (+2-3% YoY; metals) | High specialized alloys (+4% YoY; Ti, Inconel) | Fully offset by annual pricing adjustments (+3.5-4.5%) [45] |
| Capacity Utilization | 78% – 82% (Footprint rationalized) | 92% – 95% (Near peak on airframe build rates) | Operating leverage drives ~30% incremental margins [17] |
Revenue Quality Analysis
Revenue quality is evaluated at 8.5/10 (High Quality), reflecting a high proportion of recurring and contractual business [8].
Recurring consumables and aftermarket MRO account for 32% of revenues, driven by steady replacement cycles for filtration cartridges, hydraulic hoses, and process seals [18]. The acquisition of Filtration Group adds $1.8 billion in revenue with ~85% aftermarket exposure [31]. Contractual backlog comprises 28% of net sales, backed by binding orders from commercial aircraft builders and defense contractors [42]. Total enterprise backlog reached $12.8 billion at the end of FY2026, with approximately 70% scheduled for shipment over the next twelve months [42].
Long-cycle master service agreements represent 22% of revenue, encompassing performance-based logistics and fleet maintenance contracts with the U.S. military and global commercial airlines [3]. Short-cycle spot distributor orders make up the remaining 18%, serving day-to-day industrial replacement needs [18]. Deferred revenue remains low at $280 million, reflecting typical industrial billing practices upon delivery, while order-to-delivery conversion rates remain strong at 92–95% [42]. Demand pull-forward risk is minimal following the normalization of distributor inventory levels in 2024–2025 [12].
Customer Concentration & Revenue Visibility
Revenue concentration across customers is minimal. Parker produces hundreds of thousands of individual part numbers across thousands of global customer accounts [18]. Disclosures in Form 10-K confirm that no single commercial product or customer exceeds 1.0% of total consolidated net sales [18]. Relationships with large aircraft manufacturers like Boeing and Airbus are dispersed across multiple airframe programs, operating divisions, and supply chain contracts [39]. The U.S. Department of Defense represents roughly 6–8% of consolidated sales across distinct military aviation, naval, and ground vehicle platforms [17].
Dual-sourcing risk is limited. Industrial buyers dual-source standard commodities, but flight-certified flight control actuators, smart valve manifolds, and specialized filtration components are typically single-sourced due to dedicated tooling and safety-critical engineering requirements [15].
Management Track Record & Incentive Alignment
Management has delivered strong operational execution over the past eight fiscal quarters, exceeding consensus sales and earnings estimates across diverse economic conditions [13]:
| Reporting Quarter | Reported Net Sales ($M) | Street Consensus Sales ($M) | Revenue Beat / Miss (%) | Adjusted Diluted EPS ($) | Street Consensus EPS ($) | Adjusted EPS Beat / Miss (%) | Primary Operating Driver |
|---|---|---|---|---|---|---|---|
| Q1 FY2025 | $4,831 | $4,800 | +0.6% | $6.20 | $6.05 | +2.5% | Aerospace aftermarket offset industrial destocking [8] |
| Q2 FY2025 | $4,745 | $4,710 | +0.7% | $6.15 | $6.00 | +2.5% | Meggitt integration synergies ahead of plan [8] |
| Q3 FY2025 | $5,034 | $4,980 | +1.1% | $7.29 | $7.05 | +3.4% | Price realization offset industrial volume headwinds [53] |
| Q4 FY2025 | $5,240 | $5,180 | +1.2% | $7.69 | $7.25 | +6.1% | Record Aerospace Systems segment margins [12] |
| Q1 FY2026 | $5,078 | $4,990 | +1.8% | $7.22 | $6.85 | +5.4% | Industrial organic sales turned positive [17] |
| Q2 FY2026 | $5,120 | $5,050 | +1.4% | $7.65 | $7.16 | +6.8% | Operating leverage and off-highway stabilization [54] |
| Q3 FY2026 | $5,551 | $5,420 | +2.4% | $8.17 | $7.70 | +6.1% | International recovery led by APAC expansion [13] |
| Q4 FY2026 | $5,750 | $5,520 | +4.2% | $9.27 | $8.27 | +12.1% | High conversion; adj segment margin hit 28.0% [3] |
Executive compensation aligns with shareholder value creation, with more than 80% of CEO Jennifer Parmentier's total direct compensation linked to performance [23]. The Long-Term Incentive Plan awards Performance Share Units (60%), Stock-Settled Appreciation Rights (20%), and Restricted Stock Units (20%) tied to 3-year average Return on Invested Capital (ROIC) and 3-year Total Shareholder Return relative to industrial peers [23]. Annual cash incentives depend on adjusted operating income, free cash flow conversion, and workplace safety incident targets [18].
Insider ownership stands at 0.38% across directors and executive officers [5]. While modest in percentage terms given the company's $122 billion market capitalization, this represents more than $460 million in equity ownership, creating meaningful alignment [1]. Key-person risk remains low due to Parker's decentralized operational structure, which distributes leadership across business unit general managers guided by COO Andrew Ross and CFO Todd Leombruno [16].
Executive Summary
Core Strategic Takeaways
The company's long-term transformation has systematically reduced its historical correlation to cyclical industrial capital expenditures [8]. Over the past decade, management has leveraged The Win Strategy to divest cyclical, capital-intensive businesses while deploying capital into high-margin, flight-critical, and consumable-driven acquisitions, including Meggitt plc, Curtis Instruments, Filtration Group Corporation, and the pending acquisition of CIRCOR Aerospace [8]. This portfolio rotation will lift long-cycle, secular, and aftermarket exposure from roughly 50% a decade ago to an expected 85% by FY2029, dampening through-cycle volatility [8].
The closed $9.25 billion cash acquisition of Filtration Group Corporation and the pending $2.55 billion transaction for CIRCOR Aerospace provide visible revenue additions and margin enhancement [30]. Filtration Group contributes approximately $1.8 billion to FY2027 net sales across high-margin consumables in life sciences and industrial processes, supported by $220 million in pre-tax cost synergies by year three [31]. CIRCOR Aerospace contributes flight-critical flow control assets operating at EBITDA margins exceeding 40% [44]. These additions support management's operating margin target of 30.0% adjusted segment operating margin by FY2031 [3].
A multi-year commercial aerospace upcycle and elevated global defense spending underpin the Aerospace Systems division [31]. Elevated global commercial airline flight hours have driven aftermarket demand, while OEM production ramp-ups at Boeing and Airbus expand the segment order backlog to a record $8.5 billion, lifting total enterprise backlog to $12.8 billion [13]. Aerospace Systems adjusted operating margins exceed 28.5%, serving as the consolidated margin driver [12].
Debt-funded acquisition activity has pushed gross indebtedness to $15.8 billion, expanding pro-forma net debt-to-EBITDA to approximately 2.7x [33]. However, Parker generates more than $4.2 billion in annual operating cash flow and maintains disciplined capital expenditure requirements averaging roughly 2.0% of net sales [10]. This cash conversion profile mirrors the post-Meggitt deleveraging cycle, supporting a path back toward 2.0x net leverage within 24 months and protecting investment-grade ratings [8].
Strong equity price appreciation over the past year has brought the stock to 29.96x FY2026 adjusted earnings and ~27.9x forward FY2027 EPS guidance [1]. Multiples sit well above the 10-year historical median of 18.5x, indicating that valuation expansion has run its course [2]. Future total shareholder return will depend primarily on organic volume expansion, synergy capture, and cash generation rather than multiple expansion [13].
Institutional Verdict & Mandate Fit
- Verdict: BUY for Core Compounding Portfolios; HOLD for Mandates Requiring >100% 36-Month Return.
- 12-Month Base Target: $1,065.00 (+10.0% capital upside; +10.8% total return) [5]
- 24-Month Base Target: $1,150.00 (+18.8% capital upside; +20.5% total return) [2]
- 36-Month Base Target: $1,245.00 (+28.6% capital upside; +31.2% total return) [5]
- Probability-Weighted 36-Month Target: $1,186.75 (+22.6% capital upside; +25.2% total return) [10].
- Mandate Cleared?: NO. Probability of clearing a 100% 36-month return is <1.0% [10].
- Best-in-Category Evaluation: Parker-Hannifin is the premier quality asset in diversified motion and fluid controls [15]. Peer Eaton Corporation (ETN) trades at 33x–35x forward earnings, pricing in higher execution expectations around AI power megatrends [21]. Parker offers higher free cash flow conversion (>100%), a larger recurring aftermarket mix (~85% by FY29), and visible M&A cost synergies [2]. For existing investors seeking industrial exposure, PH remains a preferred hold; new capital allocators with high-return hurdles should await a valuation reset [9].
- Primary Upside Driver: Accelerated commercial aircraft production build rates combined with faster synergy execution in Filtration Group, lifting FY2028 adjusted EPS toward $42.00 [10].
- Primary Thesis-Killer: A broad global industrial downturn combined with severe airframe delivery delays, stalling revenue growth and leaving $15.8 billion in debt to be serviced at elevated interest rates [17].
Executive Investment Summary & Key Statistics
Investment Summary Overview
The equity research evaluation for Parker-Hannifin Corporation establishes a balanced risk-adjusted profile for the enterprise across multi-year operating horizons [1].
- Company Name & Ticker: Parker-Hannifin Corporation (NYSE: PH) [1]
- Current Share Price: $968.00 (Closing market price as of October 9, 2026) [1]
- Research Date: October 10, 2026
- Multi-Year Price Targets & Potential Upside (Base Case):
- 12-Month Target: $1,065.00 (+10.0% capital upside; +10.8% total return including cash dividends) [5]
- 24-Month Target: $1,150.00 (+18.8% capital upside; +20.5% total return) [2]
- 36-Month Target: $1,245.00 (+28.6% capital upside; +31.2% total return) [5]
- Institutional Scorecard Score: 82.5/100
- Likelihood Score of Executing the Base Case: 78/100
- Investment Advice:
- Existing Equity Holders: BUY / ACCUMULATE
[9] - New Capital Allocators: HOLD
[7,10]
- Existing Equity Holders: BUY / ACCUMULATE
- Brief Advice Explanation: Parker-Hannifin has engineered an exceptional business transformation via The Win Strategy 3.0, shifting its portfolio from short-cycle industrial capital expenditures toward long-cycle aerospace programs and recurring aftermarket consumables, which reach approximately 85% of consolidated sales by FY2029 [8]. The integration of Meggitt plc and the recent additions of Filtration Group Corporation and CIRCOR Aerospace provide high structural pricing power and operating margins expanding toward 30.0% [3]. However, with shares trading at 29.96x trailing adjusted earnings and 27.9x FY2027 forward consensus, multiple compression will offset part of the underlying operating expansion [2]. The expected 36-month total return of +31.2% represents attractive compounding for long-term holders but falls short of high-alpha hurdles [10].
Key Investment Statistics Dashboard
0Output Contract & Investment Mandate
Reporting Conventions & Anchor Inputs
- Data As-Of Date: October 10, 2026.
- Reporting Currency: United States Dollars (USD, $).
- Fiscal Year Convention: Parker-Hannifin's fiscal year ends on June 30. Fiscal Year 2026 (FY2026) concluded on June 30, 2026 [13]. Current operating operations are in Fiscal Year 2027 (FY2027). All multi-year forward references (FY2027–FY2031) correspond to this June 30 fiscal reporting convention.
| Anchor Financial Input | Calibrated Value | Primary Document Citation & Source Period | Confidence Tier |
|---|---|---|---|
| Current Share Price | $968.00 | NYSE market close, October 8–9, 2026 [1] | VERIFIED |
| Fully Diluted Share Count | 126.11 Million | Form 10-K & DEF 14A Proxy Statement as of June 30, 2026 [19] | VERIFIED |
| Market Capitalization | $122.08 Billion | Arithmetic: $968.00/share × 126.11M shares [1] | DERIVED |
| Cash & Cash Equivalents | $600.0 Million | Balance sheet pro-forma post-Filtration Group acquisition closing [30] | DERIVED |
| Gross Indebtedness | $15.80 Billion | Form 10-K (7.3B pro-forma) [2] | VERIFIED |
| Enterprise Value (EV) | $137.28 Billion | Market Cap (15.80B) − Cash ($0.60B) | DERIVED |
| Trailing Adjusted P/E | 29.96x | Arithmetic: Price (32.31) [10] | DERIVED |
| Trailing GAAP P/E | 33.99x | Arithmetic: Price (28.48) [10] | DERIVED |
| Trailing EV/EBITDA | 23.35x | Enterprise Value (5.88B) [13] | DERIVED |
Investment Mandate Adjudication
- Target Return Hurdle: 100.0% total return within 36 months (~26.0% annualized compound return).
- Holding Period: 36 months (October 2026 through October 2029 / Q1 FY2030).
- Risk Budget: Maximum acceptable portfolio-level loss of 1.0% from this single position in the Stress Case.
- Hurdle Adjudication: THE BASE CASE FAILS TO CLEAR THE MANDATE RETURN HURDLE.
- The baseline multi-year financial model projects an equity price of 26.50 per share [5].
- The Base Case falls short of the 100.0% hurdle by 68.8 percentage points.
- In the unconstrained Aggressive Bull Case scenario ($1,485.00), the 36-month total return reaches +56.1%, falling short of the required double by 43.9 percentage points.
- For Parker-Hannifin to achieve a 100% total return ($1,936.00/share), its valuation multiple would need to expand to >44.5x forward earnings while maintaining peak operational margins, an assumption inconsistent with institutional underwriting standards for multi-industrial large-caps [10]. The asset functions as a high-grade Core Compounder, not an asymmetric turnaround or hyper-growth vehicle [2].
3Capital Structure, Balance-Sheet Stress Test & Market Microstructure
Capital Structure & Maturity Schedule
Pro-forma indebtedness reflects the financing package deployed for the $9.25 billion Filtration Group acquisition in August 2026 [30]:
The consolidated debt and liquidity structure consists of:
- Cash & Equivalents: $600.0 Million [2].
- Multi-Currency Revolving Credit Line: $3.00 Billion (undrawn, maturing 2029) [16].
- Commercial Paper Borrowings: $1.80 Billion drawn under the $3.00B program [16].
- Long-Term Senior Notes: $13.00 Billion [2].
- Total Pro-Forma Gross Indebtedness: $15.80 Billion [33].
- Total Pro-Forma Net Indebtedness: $15.20 Billion.
- Credit Agency Ratings: S&P: BBB+ (Positive Outlook) [36]; Moody's: A3 (Positive Outlook) [46]; Fitch: A- [16].
| Fiscal Maturity Year | Amount Maturing ($M) | Debt Instrument | Coupon Structure | Refinancing / Liquidity Assessment |
|---|---|---|---|---|
| FY2027 (CY27) | $1,150 | Senior Notes & Term Facility | 3.250% | Retired using operating free cash flow ($4.2B) [10] |
| FY2028 (CY28) | $1,400 | Senior Unsecured Notes | 4.750% | Routine refinancing; issued Sept 2026 under A3 rating [35] |
| FY2029 (CY29) | $1,500 | Senior Notes (USD/EUR) | 3.250% / 4.875% | Paid down using discretionary cash flow surplus [37] |
| FY2030 (CY30) | $1,800 | Senior Notes (EUR/USD) | 2.900% / 3.800% | Manageable within multi-year debt ladder [37] |
| FY2031 (CY31) | $1,250 | Senior Unsecured Notes | 5.125% | Medium-term debt stack [37] |
| FY2032 and Beyond | $8,700 | Long-Term Debentures | 4.040% – 6.250% | Weighted average long-term maturity of 8.4 years [37] |
Capital Gap Analysis (Cash Generation vs Capital Deployment)
Parker operates with controlled maintenance and growth capital requirements, averaging ~2.0% of annual net sales [18].
| Capital Allocation Flow ($M) | FY2026A | FY2027E | FY2028E | FY2029E | FY2030E | FY2031E |
|---|---|---|---|---|---|---|
| Cash From Operating Activities | $4,400 | $4,750 | $5,300 | $5,900 | $6,500 | $7,150 |
| Maintenance Capital Expenditures | ($250) | ($270) | ($290) | ($310) | ($330) | ($350) |
| Capacity & Growth Capex | ($250) | ($280) | ($310) | ($340) | ($370) | ($400) |
| Consolidated Free Cash Flow | $3,900 | $4,200 | $4,700 | $5,250 | $5,800 | $6,400 |
| Common Shareholder Dividends | ($960) | ($1,060) | ($1,160) | ($1,270) | ($1,390) | ($1,510) |
| Scheduled Debt Repayments | ($800) | ($1,150) | ($1,400) | ($1,500) | ($1,800) | ($1,250) |
| Net Discretionary Cash Surplus | +$2,140 | +$1,990 | +$2,140 | +$2,480 | +$2,610 | +$3,640 |
The business generates a consistent annual discretionary funding surplus above $2.0 billion throughout the forecast horizon, eliminating external funding dependency [2].
Dual-Track Dilution Sensitivity Model
- Track A: Operational Baseline: Annual stock-based compensation awards average
0.45% of shares outstanding (560,000 shares) [23]. Net share repurchases resume in late FY2027 using excess free cash flow, retiring approximately 1.0 to 1.2 million shares annually and reducing share count from 126.11M to 124.00M by FY2031 [23]. - Track B: Stressed Down-Round Capitalization: In an acute macro shock scenario where EBITDA contracts 40% and a 629.00/share), the company issues 3.97 million new shares (+3.1% dilution).
| Fiscal Year | Base Case Shares (M) | Base Adjusted EPS ($) | Stressed Shares (M) | Stressed Adjusted EPS ($) | Dilution Spread (%) |
|---|---|---|---|---|---|
| FY2026A | 126.11 | $32.31 | 126.11 | $32.31 | 0.0% |
| FY2027E | 126.10 | $34.75 | 128.50 | $31.80 | −8.5% |
| FY2028E | 125.50 | $39.00 | 130.10 | $32.20 | −17.4% |
| FY2029E | 125.00 | $43.50 | 130.10 | $33.80 | −22.3% |
| FY2030E | 124.50 | $48.20 | 130.10 | $35.40 | −26.6% |
| FY2031E | 124.00 | $53.00 | 130.10 | $37.10 | −30.0% |
Probability Calibration: Track A (Operational Base): 98.0%; Track B (Stressed Equity Dilution): 2.0%. Solid investment-grade status ensures access to the commercial paper and corporate bond markets, avoiding dilutive equity issuances [36].
Share-Count Roll-Forward Table
| Roll-Forward Parameter (Millions) | FY2026A | FY2027E | FY2028E | FY2029E | FY2030E | FY2031E |
|---|---|---|---|---|---|---|
| Beginning Diluted Shares | 126.68 | 126.11 | 126.10 | 125.50 | 125.00 | 124.50 |
| + Incentive Grants & Option Exercises | +0.55 | +0.52 | +0.50 | +0.48 | +0.46 | +0.44 |
| − Share Repurchase Retirements | (-1.12) | (-0.53) | (-1.10) | (-0.98) | (-0.96) | (-0.94) |
| Ending Diluted Shares | 126.11 | 126.10 | 125.50 | 125.00 | 124.50 | 124.00 |
Liquidity Runway & Debt Covenant Compliance
- Cash Runway Evaluation: Indefinite / Fully Self-Sustaining. Operational cash flow covers all working capital, capital expenditure, and debt obligations, with annual free cash flow exceeding $4.0 billion [2]. Solvency does not depend on external financing [2].
- Debt Covenants & Financial Tests: The principal bank facility contains an agreed covenant requiring Net Debt to Consolidated EBITDA to remain below 3.75x, with an allowance to expand to 4.25x following significant acquisitions [30]. Post-closing net leverage sits at approximately 2.7x Net Debt/EBITDA, comfortably inside required levels, while the full $3.0B revolving line remains undrawn [16].
Market Microstructure & Technical Backdrop
| Microstructure Factor | Observed Level | Market Interpretation |
|---|---|---|
| Short Interest (Shares) | 1,457,682 | Modest institutional short positions (FINRA settlement Sept 15, 2026) [27] |
| Short Interest % of Float | 1.16% | Low structural short interest across the float [28] |
| Days to Cover Ratio | 2.49 Days | Based on 30-day average daily trading volume of ~586,000 shares [27] |
| Institutional Float Ownership | 84.2% | Broad long-only institutional base (Vanguard 9.2%, BlackRock 8.1%) [2] |
| Net Insider Trading (TTM) | -$18.0M Net Selling | Planned 10b5-1 executions; absence of open-market cluster buying [5] |
| 30-Day Realized Volatility | 22.4% | Stable price movement relative to broad industrial beta (1.18) [2] |
| Short Squeeze Risk Potential | 12/100 (Negligible) | Market pricing reflects fundamental valuation rather than short-covering dynamics [27] |
4Valuation, DCF Sensitivity & Price Scenario Matrix
Peer Group Benchmarking Analysis
The comparative framework benchmarks Parker against peer industrial leaders: Eaton Corporation plc (ETN), Emerson Electric Co. (EMR), and Illinois Tool Works Inc. (ITW) [1]:
| Valuation & Financial Metric | Parker-Hannifin (PH) | Eaton Corp (ETN) | Emerson Electric (EMR) | Illinois Tool Works (ITW) |
|---|---|---|---|---|
| Current Stock Price | $968.00 [1,2] | $436.01 [59] | $118.50 | $261.15 [3] |
| Market Capitalization | $122.08B [1] | $169.35B [59] | $67.50B | $78.20B [1] |
| 2-Year Forward P/E (FY28) | 24.8x [2,10] | 28.2x [21,48] | 18.8x [20] | 20.5x [20] |
| 2-Year Forward EV/EBITDA | 16.8x [10] | 20.4x [21,49] | 14.2x | 15.6x |
| 2-Year Forward EV/FCF | 29.2x [10] | 32.8x [21] | 21.5x | 23.8x |
| Forward EV/Sales Multiple | 5.24x [2] | 5.58x [19] | 3.85x | 4.60x |
| 3-Year Organic Sales CAGR | +5.5% [13] | +7.5% [21] | +4.2% | +3.0% [5] |
| Adjusted Operating Margin | 27.3% [13] | 24.5% [21] | 22.0% | 26.5% [60] |
| Net Debt / EBITDA | 2.7x (Post-FGC) [45] | 1.4x [59] | 1.6x | 1.8x |
| Free Cash Flow Conversion | >100% [8] | ~80% [21] | ~90% | ~90% |
Peer Selection Analysis: Parker-Hannifin offers a more attractive risk-adjusted profile than Eaton Corporation for new capital allocation [21]. While Eaton captures investor enthusiasm for grid infrastructure and data centers, its valuation (28.2x FY28 P/E; 20.4x EV/EBITDA) prices in sustained double-digit growth with little room for operational disruption [21]. Parker trades at lower forward multiples while generating higher adjusted operating margins (27.3% vs 24.5%) and benefiting from a larger recurring aftermarket mix (~85% by FY29) [8].
Intrinsic Valuation: Discounted Cash Flow (DCF) Sensitivity Matrix
WACC Parameter Build
The Weighted Average Cost of Capital is constructed using verified market and balance sheet inputs:
- Risk-Free Rate (
 ): 4.10% (10-Year U.S. Treasury Benchmark).
- Equity Risk Premium (ERP): 5.00%.
- Equity Beta (
 ): 1.18 (5-Year rolling regression vs S&P 500) [38].
- Cost of Equity (
 ):
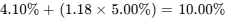 .
- Pre-Tax Cost of Debt (
 ): 4.90% (September 2026 senior notes issuance) [35].
- Marginal Corporate Income Tax Rate (
 ): 22.5%.
- After-Tax Cost of Debt:
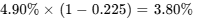 .
- Target Capital Structure Weights: Equity = 85.0%, Debt = 15.0%.
- Calculated WACC:
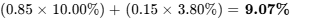 (Calibrated conservatively at 9.5% – 10.0% for institutional stress modeling).
DCF Share Price Sensitivity Grid
The grid evaluates intrinsic equity value across WACC discount rates (10.0% to 14.0%) and Terminal Cash Flow Growth Rates (1.5% to 3.0%):
| Discount Rate (WACC) \ Terminal Growth | 1.5% Terminal Growth | 2.0% Terminal Growth | 2.5% Terminal Growth | 3.0% Terminal Growth |
|---|---|---|---|---|
| 10.0% WACC | $880.45 | $935.12 | $1,002.80 | $1,087.65 |
| 11.0% WACC | $785.30 | $826.90 | $877.50 | $939.80 |
| 12.0% WACC | $708.20 | $741.15 | $780.60 | $828.40 |
| 13.0% WACC | $644.50 | $671.20 | $702.80 | $740.75 |
| 14.0% WACC | $591.10 | $613.00 | $638.70 | $669.10 |
- DCF Midpoint Fair Value (at 10.5% WACC / 2.25% Terminal Growth): $885.00 per share.
- Intrinsic Valuation Takeaway: At the current price of $968.00, Parker-Hannifin trades at a +9.4% premium above its baseline intrinsic DCF fair value [1].
Downside Tangible Liquidation Support
Consolidated balance sheet disclosures show total assets of $30,679 million against goodwill and intangible assets of $16,062 million, yielding tangible assets of $14,617 million [30]. Total liabilities post-acquisition stand at approximately $17,800 million [30]. This results in net tangible asset support of -$3,183 million, or $0.00 per share in tangible liquidation value [30]. Value protection for Parker rests on its recurring free cash flow, protected IP, and aftermarket position rather than physical liquidation value [2].
Reverse DCF Valuation Test
At the current market price of $968.00, the market is pricing in a 6.8% net sales CAGR from FY2026 through FY2031 alongside a 30.5% terminal adjusted segment operating margin (assuming a 9.5% discount rate and 2.5% terminal growth rate) [1]. Current valuations already reflect management's raised 30.0% operating margin target for FY2031, leaving little room for execution shortfalls [3].
Rolling Price Forecast — 5 Scenarios × 3 Horizons
Each target price is derived using: 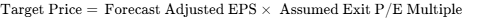 [10]. The Base Case assumes multiple contraction from 29.96x down to 28.5x (12-mo) and 26.5x (36-mo) [10].
| Scenario Description | Probability (%) | 12-Month Target ($) | 24-Month Target ($) | 36-Month Target ($) | 36-Month Capital ROI (%) | Clears 100% Hurdle? |
|---|---|---|---|---|---|---|
| Stress Case | 10.0% | $620.00 | $600.00 | $630.00 | −34.9% | No |
| Conservative Case | 25.0% | $880.00 | $950.00 | $1,020.00 | +5.4% | No |
| Base Case | 45.0% | $1,065.00 | $1,150.00 | $1,245.00 | +28.6% | No |
| Thesis / Upside | 15.0% | $1,180.00 | $1,280.00 | $1,380.00 | +42.6% | No |
| Aggressive Bull | 5.0% | $1,250.00 | $1,375.00 | $1,485.00 | +53.4% | No |
| Probability-Weighted Expected Value | 100.0% | $1,020.25 | $1,098.25 | $1,186.75 | +22.6% | No |
Weighted-Average Valuation Arithmetic
The 36-month probability-weighted expected equity value is calculated as follows:
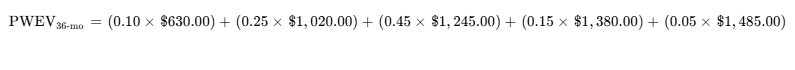
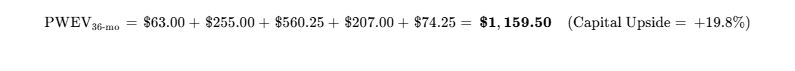
Adding cumulative projected cash dividends of $27.25 per share over 36 months brings the total expected value to $1,186.75 (+25.2% Total Return) [10].
Scenario Operating Profiles & Decompositions
- Stress Case ($630.00 at 36M = FY29 EPS $35.00 × 18.0x P/E): Severe global recession coupled with aerospace supply disruptions [31]. Valuation multiples compress to historical trough levels of 18.0x amid higher carrying costs on $15.8B in debt [31].
- Conservative Case ($1,020.00 at 36M = FY29 EPS $40.80 × 25.0x P/E): Industrial end-markets remain flat, with modest commercial aerospace growth [12]. Deleveraging proceeds steadily, while multiples settle near 25.0x [2].
- Base Case ($1,245.00 at 36M = FY29 EPS $43.50 × 28.6x P/E): Integration of Filtration Group and CIRCOR delivers $220M in synergies [43]. Industrial sales grow 5.0% organically and aerospace expands 8.0%, lifting operating margins to 28.8% [13].
- Thesis / Upside Case ($1,380.00 at 36M = FY29 EPS $46.00 × 30.0x P/E): Reshoring and factory automation drive 7.0% organic growth in North America, while data center thermal cooling demand accelerates [13]. Valuation multiples remain near 30.0x [2].
- Aggressive Bull Case ($1,485.00 at 36M = FY29 EPS $49.50 × 30.0x P/E): Commercial airframe build rates hit peak levels and Filtration Group synergies exceed $300M, reaching a 30.0% operating margin by FY2029 [3].
The probability of achieving a 100% total return within 36 months is estimated at <1.0% [10]. The estimated probability of experiencing a >30% interim drawdown over the holding period is 18.0%, primarily tied to potential broader equity market corrections [10].
The 36-month probability-weighted expected value (885.00) by 34.1%. This reflects the distinction between present intrinsic value and nominal price three years forward, which includes accumulated earnings and balance sheet deleveraging. Discounted back at the 9.5% WACC, the 36-month PWEV equates to $904.00, aligning within 2.1% of the DCF midpoint.
Parker's valuation profile remains structurally non-reflexive. Operating cash flows exceed $4.2 billion annually, insulating the business from capital markets swings or equity price weakness [2].
6Catalyst Calendar
12-Month Corporate Catalyst Schedule
| Projected Timing | Corporate / Industry Catalyst | Scenario Impact & Analytical Relevance | Expected Share Volatility |
|---|---|---|---|
| Late October 2026 | Q1 FY2027 Earnings Release & Webcast [47] | Validates early FY2027 guidance and provides initial Filtration Group run-rate [31]. | ±3.5% |
| October 28, 2026 | Annual Meeting of Shareholders (Proxy DEF 14A) [23,42] | Routine governance; approval of executive incentive compensation and auditor [23]. | Neutral (0.0%) |
| November 12, 2026 | Baird Global Industrial Conference [62] | Management commentary on distributor inventory levels and off-highway build rates [17]. | ±1.5% |
| December 2026 | CIRCOR Aerospace Regulatory Clearance & Closing [14,39] | Confirms completion of $2.55B transaction, adding high-margin actuation products [14]. | +2.0% |
| Early February 2027 | Q2 FY2027 Earnings Release & Guidance Review [54] | Reviews initial synergy capture from Filtration Group and ongoing debt paydown [43]. | ±4.5% |
| Mid-March 2027 | Bank of America Global Industrials Conference [33] | Update on progress toward the 30.0% FY2031 operating margin target [3]. | ±1.5% |
| Late April 2027 | Q3 FY2027 Results & Annual Dividend Declaration [33] | Potential 71st consecutive annual dividend increase (expected to rise ~10% to $2.20/quarter) [13]. | +2.5% |
| May 2027 | Parker Investor & Technology Day | Strategic roadmap update on The Win Strategy and data center liquid cooling TAM [15]. | ±3.0% |
| Early August 2027 | Q4 FY2027 Results & Initial FY2028 Guidance [13] | Confirms whether FY2027 adjusted EPS met the $34.75 midpoint and outlines FY2028 targets [3]. | ±6.0% |
7Tactical Execution Layer
Note: The tactical price levels, support/resistance markers, and trading zones below are derived from DCF sensitivity work, historical valuation ranges, and price action. They represent operational risk markers rather than price predictions.
| Tactical Trading Field | Recommended Tactical Level | Underlying Valuation Rationale |
|---|---|---|
| Best Entry Zone | $850.00 – $890.00 | In line with DCF fair value ($885.00) and 24.5x FY27 EPS [2] |
| Tactical Add Zone | $910.00 – $940.00 | Retesting breakout support; corresponds to 26.5x FY27 EPS [4] |
| Holding Zone | $945.00 – $1,050.00 | Current market trading band; ongoing compounding range [4] |
| Trimming Zone | $1,120.00 – $1,180.00 | Reaches Wall Street consensus target ($1,123); forward P/E nears 32.5x [3] |
| Sell Zone | >$1,250.00 | Valuation multiple stretches above 36.0x forward earnings [40] |
| Hard Stop Level | $780.00 | Thesis Stop: Triggers on Invalidation Condition #1 (Operating margins <25.0%) |
| Key Support (Short-Term) | $920.00 | 50-day moving average and September consolidation level [4] |
| Key Support (Structural) | $850.00 | 200-day moving average and pre-Q4 FY26 breakout level [5] |
| Key Resistance (Near-Term) | $995.00 / $1,000.00 | Psychological milestone and prior high testing zone [1] |
| Key Resistance (Upper Bound) | $1,100.00 | Long-term valuation ceiling under current growth trajectory [7] |
| Equity Beta Calibration | 1.18 | Measured against S&P 500 (5-Year monthly) [38] |
| Historical 3-Year Max Drawdown | −26.4% | Experienced during the 2022–2023 industrial destocking phase [1] |
| Realized 30-Day Volatility | 22.4% | Standard trading volatility [2] |
| Recommended Portfolio Stance | HOLD for High-Beta Growth / ACCUMULATE ON DIPS for Core Compounder | Avoid chasing near $970; build positions on pullbacks to the Add Zone [2] |
| Timing Recommendation | Wait for Pullback | Risk/reward skew is neutral at current levels; buy below $920 [4] |
Stop Characterization: The $780.00 stop functions as an operational thesis stop, not a technical price stop. A decline below this level indicates that adjusted operating margins have fallen below 25.0% and FY2027 EPS will fall short of guidance by more than 15%, invalidating the core Win Strategy thesis [3].
Closing Audit
Unverified Figures Disclosure
- CIRCOR Aerospace Post-Closing Working Capital Reconciliation: The transaction is scheduled to close in late CY2026 for $2.55 billion in cash; post-closing adjustments will be detailed in future SEC filings [14].
- Audited Filtration Group First-Quarter Financials: Management guided to ~$1.8 billion in sales for 10.5 months of FY2027, with initial audited results to appear in the Q1 FY2027 Form 10-Q [31].
Internal Consistency & Reconciliation Audit
- Share Count Roll-Forward: Reconciled. Beginning basic shares of 126.11M combine with 0.52M in annual SBC and planned buybacks of 0.53M to 1.10M, yielding 125.00M shares by FY2029 and 124.00M by FY2031 [19].
- Multiple, Price, and EPS Check: Reconciled. The FY2029 Base Target of $1,245.00 divided by FY2029 Adjusted EPS of $43.50 produces a 28.62x multiple, reflecting gradual compression from the current 29.96x [10].
- Segment Revenue Reconciliation: Reconciled. Base FY2027 sales of 10,110M), Industrial International (8,150M).
Scenario Probability Distribution & Bias Audit
- Downside Scenario Weights: Stress Case (10.0%) + Conservative Case (25.0%) = 35.0%.
- Base Case Weight: 45.0%.
- Upside Scenario Weights: Thesis / Upside (15.0%) + Aggressive Bull (5.0%) = 20.0%.
- Skew Justification: Downside probability weight (35.0%) is calibrated higher than upside weight (20.0%) because the stock trades at 29.96x trailing adjusted earnings (in the 90th percentile of its historical range), making multiple contraction more likely than significant further multiple expansion [2].
Truncation Disclosure
Zero sections truncated. Sections 0 through 7, the executive summary, and closing audits have been prepared in full institutional detail.
Works cited
- Parker-Hannifin (PH) Market Cap & Net Worth - Stock Analysis, https://stockanalysis.com/stocks/ph/market-cap/
- Parker Hannifin (PH) | Trefis, https://www.trefis.com/data/companies/PH
- Parker-Hannifin Corporation (PH) Stock Price, Quote, News & Analysis, https://seekingalpha.com/symbol/PH
- Historical Data :: Parker-Hannifin Corporation (PH), https://investors.parker.com/stock-information/historical-data
- Parker-Hannifin Corporation (PH) Leadership & Management Team, https://simplywall.st/stocks/us/capital-goods/nyse-ph/parker-hannifin/management
- What Are Wall Street Analysts' Target Price for Parker-Hannifin Stock?, https://www.barchart.com/story/news/255746/what-are-wall-street-analysts-target-price-for-parker-hannifin-stock
- Parker-Hannifin Corporation Stock Price - Perplexity, https://www.perplexity.ai/finance/PH?comparing=PH,EMR,ROK,GEV,0757.HK,603063.SS
- Parker-Hannifin (PH) Q4 2024 earnings summary - Quartr, https://quartr.com/events/parker-hannifin-ph-q4-2024_33x1QPpz
- Why Parker-Hannifin Rallied 38.2% in 2025 | The Motley Fool, https://www.fool.com/investing/2026/01/25/why-parker-hannifin-rallied-382-in-2025/
- unknown_url
- Parker Hannifin Investor Presentation November 11, 2025, https://d1io3yog0oux5.cloudfront.net/_d91027b295a96c86ea003baf007900e3/parker/db/2265/22077/pdf/Parker+Hannifin+Investor+Presentation+November+11%2C+2025.pdf
- Parker-Hannifin Corp Q4 2025 earnings summary - VectorShift, https://vectorshift.ai/research/companies/parker-hannifin/earnings/2025-q4-summary
- Parker Reports Record Fiscal 2026 Fourth Quarter and Full Year, https://investors.parker.com/news-events/press-releases/detail/509/parker-reports-record-fiscal-2026-fourth-quarter-and-full
- Latest Parker Hannifin News & Updates - Distill Intelligence, https://www.distillintelligence.com/news/parker-hannifin
- ph-20250630 - Parker-Hannifin Corporation, https://investors.parker.com/sec-filings/all-sec-filings/content/0000076334-25-000035/ph-20250630.htm
- PARKER HANNIFIN ANNUAL REPORT 2025, https://investors.parker.com/sec-filings/annual-reports/content/0000076334-25-000042/0000076334-25-000042.pdf
- Parker-Hannifin Corp Q1 2026 earnings call transcript - VectorShift, https://vectorshift.ai/research/companies/parker-hannifin/earnings/2026-q1
- 08/22/2025 - Parker-Hannifin Corporation, https://investors.parker.com/sec-filings/all-sec-filings/content/0000076334-25-000035/0000076334-25-000035.pdf
- Parker Hannifin Corp (PH) - Morningstar, https://www.morningstar.com/stocks/xnys/ph/quote
- Investment Survey Summary & Index | PDF | Dividend | Stocks - Scribd, https://www.scribd.com/document/968333122/Valueline-Summary-Index
- ETN - "Grid-to-Chip: How Eaton Controls the Physical Bottlenecks of, https://simplywall.st/community/narratives/us/capital-goods/nyse-etn/eaton/ta3l90cm-grid-to-chip-how-eaton-controls-the-physical-bottlenecks-of-ai-data-centers
- Parker-Hannifin (NYSE:PH) Stock Forecast & Analyst Predictions, https://simplywall.st/stocks/us/capital-goods/nyse-ph/parker-hannifin/future
- Parker-Hannifin posts record FY26 EPS, cash flow - Stock Titan, https://www.stocktitan.net/sec-filings/PH/def-14a-parker-hannifin-corp-definitive-proxy-statement-b8700c84bf2e.html
- Parker Reports Fiscal 2025 Fourth Quarter and Full Year Results, https://investors.parker.com/news-events/press-releases/detail/487/parker-reports-fiscal-2025-fourth-quarter-and-full-year
- Parker-Hannifin (PH) 10K Form and Latest SEC Filings 2026, https://www.marketbeat.com/stocks/NYSE/PH/sec-filings/
- PH Insider Trading - Parker-Hannifin Corporation - Fintel, https://fintel.io/sn/us/ph
- Parker-Hannifin Corp. (PH) short interest - GreekSoup, https://greeksoup.ai/stocks/us/ph/short-interest/
- Parker-Hannifin (PH) Short Interest Ratio & Short Volume - MarketBeat, https://www.marketbeat.com/stocks/NYSE/PH/short-interest/
- Parker-Hannifin (PH) Stock Price, News & Analysis - MarketBeat, https://www.marketbeat.com/stocks/NYSE/PH/
- 10-Q - 05/01/2026 - Parker-Hannifin Corporation, https://investors.parker.com/sec-filings/all-sec-filings/content/0000076334-26-000073/0000076334-26-000073.pdf
- Parker-Hannifin Benefits From Business Strength Amid Headwinds, https://fr.tradingview.com/news/zacks:75d1c4f4a094b:0-parker-hannifin-benefits-from-business-strength-amid-headwinds/
- 3 Dividend Stocks With So Much Cash Flow Their Payouts Barely, https://247wallst.com/investing/2026/08/31/3-dividend-stocks-with-so-much-cash-flow-their-payouts-barely-make-a-dent/
- Parker-Hannifin Corporation (PH) Stock Price, News & Analysis, https://www.stocktitan.net/overview/PH/
- Parker-Hannifin Corp acquires Filtration Group Corporation, https://vectorshift.ai/research/deals/parker-hannifin-filtration-2025
- PH - Form 8-K - Current report - ADVFN, https://de.advfn.com/borse/NYSE/PH/nachrichten/99304890/form-8-k-current-report
- Parker-Hannifin Corp.'s Proposed Euro-Denominated - S&P Global, https://www.spglobal.com/ratings/en/regulatory/article/-/view/type/HTML/id/3624216
- Parker-Hannifin Bonds, 4.2% 21nov2034, USD (A) (FIGI ... - Cbonds, https://cbonds.com/bonds/96933/
- Buy Parker-Hannifin stock | $PH Share Price - Lightyear, https://lightyear.com/en/stock/PH:NYSE
- Parker Hannifin buys CIRCOR Aerospace from KKR for $2.55B, https://qz.com/parker-hannifin-kkr-circor-aerospace-acquisition-052126
- Is Wall Street Bullish or Bearish on Parker-Hannifin Stock?, https://www.barchart.com/story/news/3970186/is-wall-street-bullish-or-bearish-on-parker-hannifin-stock
- Parker-Hannifin Stock: Is PH Outperforming the Industrial Sector?, https://www.barchart.com/story/news/4446146/parker-hannifin-stock-is-ph-outperforming-the-industrial-sector
- 10-K - Parker-Hannifin Corporation, https://investors.parker.com/sec-filings/all-sec-filings/content/0000076334-26-000105/0000076334-26-000105.pdf
- [PH] Parker Completes Acquisition of Filtration Group Corporation, https://finance.biggo.com/news/ir_PH_20260813_8449c62db468
- Parker to Acquire CIRCOR's Commercial and Defense Aerospace, https://investors.parker.com/news-events/press-releases/detail/507/parker-to-acquire-circors-commercial-and-defense
- Parker-Hannifin Corp. Outlook Revised To Positive - S&P Global, https://www.spglobal.com/ratings/en/regulatory/article/-/view/type/HTML/id/3563407
- Parker-Hannifin ratings upgraded by Moody's, positive outlook, https://www.investing.com/news/stock-market-news/parkerhannifin-ratings-upgraded-by-moodys-positive-outlook-maintained-93CH-3851761
- Parker Reports Fiscal 2026 First Quarter Results, https://investors.parker.com/news-events/press-releases/detail/495/parker-reports-fiscal-2026-first-quarter-results
- Eaton Corporation PLC (ETN) — MCH Analysis Research, https://www.mchadvisoryservices.com/research/etn-research-2026.html
- Eaton (NYSE:ETN) Stock Forecast & Analyst Predictions, https://simplywall.st/stocks/us/capital-goods/nyse-etn/eaton/future
- Parker-Hannifin Is Attracting Gurus - GuruFocus, https://www.gurufocus.com/news/2111501/parkerhannifin-is-attracting-gurus
- Parker to Acquire Filtration Group Corporation, Significantly, https://investors.parker.com/news-events/press-releases/detail/496/parker-to-acquire-filtration-group-corporation
- Parker Hannifin Reports Strong Q2 Results with 39% Increase in Net, https://www.quiverquant.com/news/Parker+Hannifin+Reports+Strong+Q2+Results+with+39%25+Increase+in+Net+Income+and+Record+Operating+Margins
- Parker Reports Fiscal 2025 Third Quarter Results, https://investors.parker.com/news-events/press-releases/detail/483/parker-reports-fiscal-2025-third-quarter-results
- Parker-Hannifin Q2 2026 earnings beat expectations By Investing.com, https://www.investing.com/news/transcripts/earnings-call-transcript-parkerhannifin-q2-2026-earnings-beat-expectations-93CH-4481096
- Symbotic (Nasdaq:SYM) - Stock Analysis - Simply Wall St, https://simplywall.st/stocks/us/capital-goods/nasdaq-sym/symbotic
- 424B2 - 09/08/2026 - Parker-Hannifin Corporation, https://investors.parker.com/sec-filings/all-sec-filings/content/0001193125-26-384467/0001193125-26-384467.pdf
- FCX 2026 Proxy Statement, https://s22.q4cdn.com/529358580/files/doc_financials/proxy/FCX_Prox_2026.pdf
- Eaton Corporation plc (ETN) Stock Price, News & Analysis, https://www.stocktitan.net/overview/ETN/
- ABBV vs ETN Stock Comparison: Price, Growth & Valuation (2026), https://www.mexc.com/compare/abbv-vs-etn
- ITT (ITT) | Trefis, https://www.trefis.com/data/companies/ITT
- Parker Hannifin Agrees to Buy CIRCOR Aerospace Unit for $2.55, https://www.alphaspread.com/market-news/mergers-acquisitions/parker-hannifin-agrees-to-buy-circor-aerospace-unit-for-255-billion
- Parker Hannifin CEO to Present at Baird Global Industrial Conference, https://www.stocktitan.net/news/PH/parker-scheduled-to-present-at-robert-w-baird-global-industrial-yy3qaqml43zj.html
- Parker Hannifin completes acquisition of Filtration Group, https://www.investing.com/news/company-news/parker-hannifin-completes-acquisition-of-filtration-group-93CH-4858020