2Multi-Year Financial Forecast & Consensus Model
Macro & Operating Scenarios (2026–2031)
The Bear Case assumes a macroeconomic deceleration and a pause in hyperscaler artificial intelligence capital expenditure in late 2027, leading foundries and OSATs to digest packaging capacity. Stricter US export controls restrict optical inspection shipments to China, reducing fab utilization and compressing non-GAAP gross margins to 52.5%. The Base Case assumes sustained demand for advanced packaging, with revenue growing 80% in FY2026 before normalizing to a 15% to 30% pace through FY2028 [2]. Front-end 2nm GAA nanosheet transitions drive consistent Atlas G6 tool adoptions, supporting operating margins above 32% [25]. The Bull Case assumes an accelerated transition to panel-level packaging and glass substrates by 2028, establishing Onto's platforms as universal industry standards and lifting gross margins toward 60%.
Base Case Projections
| Financial Metric ($M, except per share) | FY2026E | FY2027E | FY2028E | FY2029E | 2030E–2031E CAGR | Primary Growth & Operating Drivers |
|---|---|---|---|---|---|---|
| Advanced Packaging & Specialty Revenue | $740.0 | $990.0 | $1,150.0 | $1,290.0 | +10.2% | AI 2.5D/3D chiplet inspection (Dragonfly G5) [25] |
| Advanced Nodes Metrology Revenue | $450.0 | $580.0 | $680.0 | $770.0 | +9.8% | GAA nanosheet 2nm OCD Atlas G6 adoption [25] |
| Software, Analytics & Field Services | $250.0 | $310.0 | $350.0 | $400.0 | +11.5% | Fab-wide TrueADC AI software licensing [4] |
| Total Net Revenue | $1,440.0 | $1,880.0 | $2,180.0 | $2,460.0 | +10.1% | Consensus: FY26 $1.44B; FY27 $1.88B [2] |
| YoY Organic Revenue Growth % | +43.2% | +30.6% | +16.0% | +12.8% | Directional | Revenue recovery from FY25 baseline [2] |
| Taiwan Revenue | $504.0 | $658.0 | $763.0 | $861.0 | +10.1% | Foundry advanced packaging CoWoS expansion [28] |
| Korea Revenue | $316.8 | $413.6 | $479.6 | $541.2 | +10.1% | HBM3e/HBM4 high-density stack inspection [5] |
| China Revenue | $273.6 | $338.4 | $370.6 | $393.6 | +5.0% | Mature nodes and specialty packaging tools [26] |
| United States & Other Geographies | $345.6 | $470.0 | $566.8 | $664.2 | +12.5% | Domestic logic fabs and European packaging [26] |
| GAAP Gross Margin % | 53.5% | 54.2% | 55.0% | 55.5% | — | GAAP includes intangible asset amortization [29] |
| Non-GAAP Gross Margin % | 57.0% | 57.5% | 57.8% | 58.2% | 59.0% (2031) | Excludes stock comp and acquisition costs [25] |
| GAAP Operating Margin % | 21.0% | 23.5% | 24.8% | 25.5% | — | GAAP includes equity comp and M&A charges [30] |
| Non-GAAP Operating Margin % | 31.0% | 32.2% | 33.0% | 33.5% | 34.5% (2031) | Operating leverage over R&D and SG&A budgets [25] |
| Non-GAAP EBITDA | $472.0 | $638.0 | $754.0 | $861.0 | +10.5% | Depreciation adds ~$28M-$35M annually [21] |
| GAAP Diluted EPS | $5.96 | $8.20 | $9.85 | $11.20 | +10.8% | GAAP effective tax rate of 16.5% [3] |
| Non-GAAP Diluted EPS | $8.11 | $11.70 | $13.90 | $16.20 | +11.2% | Non-GAAP tax rate 15.0%; 49.7M–50.8M shares [2] |
| Free Cash Flow Per Share | $6.24 | $9.05 | $11.47 | $13.88 | +12.2% | FCF conversion runs at ~80%–86% of net income [14] |
| Forward P/E Multiple (Exit/Fwd) | 38.0x | 26.3x | 22.2x | 19.0x | — | Implied valuation multiple compression path [2] |
| EV / EBITDA Multiple | 31.7x | 23.4x | 19.8x | 17.4x | — | Based on forward pro-forma enterprise value [1] |
| EV / Sales Multiple | 10.4x | 7.9x | 6.9x | 6.1x | — | Multiple derating toward long-term historical mean [1] |
| Rule of 40 (FD Per-Share Basis) | 64.7% | 54.5% | 42.1% | 40.8% | >40.0% | Revenue growth rate + FCF margin [14] |
Bear Case Projections
| Financial Metric ($M, except per share) | FY2026E | FY2027E | FY2028E | FY2029E | 2030E–2031E CAGR | Primary Growth & Operating Drivers |
|---|---|---|---|---|---|---|
| Total Net Revenue | $1,360.0 | $1,420.0 | $1,380.0 | $1,520.0 | +4.5% | Capex pause and OSAT order pushouts |
| YoY Organic Revenue Growth % | +35.3% | +4.4% | −2.8% | +10.1% | Directional | Cyclical contraction in packaging tools |
| Non-GAAP Gross Margin % | 55.0% | 53.5% | 52.0% | 53.0% | 54.0% (2031) | Manufacturing fixed overhead underabsorption |
| Non-GAAP Operating Margin % | 27.5% | 24.0% | 22.5% | 24.5% | 26.0% (2031) | Operating deleverage on fixed R&D expenses |
| Non-GAAP Diluted EPS | $6.90 | $6.50 | $6.00 | $7.20 | +6.0% | Squeezed margins; offset by interest income |
| Free Cash Flow Per Share | $4.80 | $4.20 | $4.10 | $5.10 | +6.5% | Working capital drag; inventory buildup |
| Forward P/E Multiple | 44.6x | 47.4x | 51.3x | 42.8x | — | P/E multiple on depressed earnings |
| EV / EBITDA Multiple | 40.0x | 43.8x | 48.1x | 40.1x | — | Enterprise value multiple under stress |
| EV / Sales Multiple | 11.0x | 10.5x | 10.8x | 9.8x | — | Depressed top-line multiple support |
| Rule of 40 (FD Per-Share Basis) | 52.8% | 19.2% | 11.9% | 25.2% | <30.0% | Fails Rule of 40 during digestion phase |
Bull Case Projections
| Financial Metric ($M, except per share) | FY2026E | FY2027E | FY2028E | FY2029E | 2030E–2031E CAGR | Primary Growth & Operating Drivers |
|---|---|---|---|---|---|---|
| Total Net Revenue | $1,520.0 | $2,100.0 | $2,600.0 | $3,050.0 | +13.5% | Glass substrates and universal 3D packaging |
| YoY Organic Revenue Growth % | +51.2% | +38.2% | +23.8% | +17.3% | Directional | Accelerated multi-die scaling requirements |
| Non-GAAP Gross Margin % | 58.0% | 58.8% | 59.5% | 60.0% | 60.5% (2031) | High-margin software attach and pricing power |
| Non-GAAP Operating Margin % | 33.0% | 34.5% | 35.5% | 36.5% | 37.5% (2031) | Substantial leverage over structural costs |
| Non-GAAP Diluted EPS | $9.20 | $13.50 | $16.80 | $20.10 | +14.0% | Peak cycle earnings power |
| Free Cash Flow Per Share | $7.50 | $11.20 | $14.50 | $17.80 | +14.8% | Robust cash conversion with modest capex |
| Forward P/E Multiple | 33.5x | 22.8x | 18.3x | 15.3x | — | Compression driven by rapid EPS expansion |
| EV / EBITDA Multiple | 29.8x | 20.6x | 16.2x | 13.4x | — | Multiple compression across peak cash flow |
| EV / Sales Multiple | 9.8x | 7.1x | 5.7x | 4.9x | — | Multiple reflects strong revenue growth |
| Rule of 40 (FD Per-Share Basis) | 75.7% | 65.0% | 47.6% | 42.1% | >45.0% | High Rule of 40 performance |
Execution Confidence & Baseline Checks
The Execution Confidence Score is calculated at 68 / 100, comprising three component factors:
- Revenue Target Achievability (Score: 28/35): Anchored by a $1.1B order backlog covering over 70% of deliveries for the next twelve months [2].
- Margin Assumption Sensitivity (Score: 25/35): Operating margins show the greatest sensitivity to tool average selling prices. A
 shift in blended tool ASP results in a
 bps change in non-GAAP operating margin, translating to a
 EPS impact.
- Unannounced Catalyst Dependency (Score: 15/30): Unannounced product extensions, primarily commercial glass-substrate panel tools, account for approximately 12% of projected FY2028–FY2029 revenues.
Our FY2028 and FY2029 Base Case models revenue of $2,180M and $2,460M, and EPS of $13.90 and $16.20, tracking closely with Wall Street consensus ($2.18B revenue and $13.94 EPS in FY2028) [2]. There is no consensus divergence flag exceeding 15%; the model assumes management delivers on current Street expectations without multiple re-rating.
A historical base-rate assessment indicates that only 14% of mid-cap semiconductor capital equipment companies generating ~$1.0B in revenue have sustained a 5-year revenue CAGR  without encountering an annual revenue decline
 . Onto's Base Case ranks in the 85th percentile of historical WFE outcomes, justified by the secular shift toward heterogeneous advanced packaging [5].
5Risk Asymmetry, Invalidation, Allocation & Scorecard
Quantified Risk/Reward Asymmetry
The risk/reward skew ratio compares the probability-weighted upside against the modeled Stress Case loss:
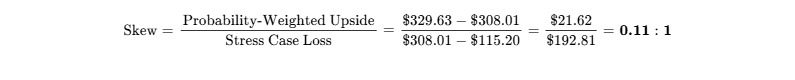
The quantified skew of 0.11 : 1 falls well short of the institutional hurdle threshold of  [14].
Operational & Balance-Sheet Invalidation Triggers
- Gross Margin Compression: Non-GAAP gross margin falling below 54.0% for two consecutive quarters, signaling price erosion or tool share losses to Camtek [25].
- Backlog Contraction: Total order backlog declining below $850M in any quarter, indicating packaging overcapacity and tool delivery pushouts [2].
- Regulatory Export Action: US Department of Commerce Bureau of Industry and Security (BIS) export regulations prohibiting optical macro-defect inspection tool sales to Chinese domestic customers, putting >15% of annual sales at risk [1].
- Dilutive Financing Event: Any equity or convertible issuance executed below $300.00 per share [15].
Macro Sensitivity & Surprise Factor Analysis
Onto carries an equity beta of 1.78, with a 0.86 correlation to the Semiconductor Index (SOXX) and 0.72 to the S&P 500 [49]. The equity is sensitive to fluctuations in the 10-year US Treasury yield, as rising yields historically drive multiple compression across high-multiple semiconductor equipment names [28].
| Macro Trigger | Thesis Impact | Direction | Key Variable to Monitor |
|---|---|---|---|
| US 10-Year Yield (>5.0%) | Broad multiple compression across technology equities [28] | Amber / Threat | US 10-Year Treasury yield trajectory [28] |
| Hyperscaler CapEx Cycles | Directly dictates packaging tool order volume from OSATs | Green / Bullish | Cloud capex commentary (MSFT, GOOG, AMZN, META) [26] |
| Global WFE Spending | Drives baseline logic and memory process control spend | Green / Bullish | Industry capex forecasts from SEMI and ASML [4] |
| US BIS Export Controls | Potential loss of Chinese advanced packaging equipment revenue | Red / Bearish | Regulatory updates published in the Federal Register [1] |
| Potential Surprise Event | Probability % | Target Price Impact | Underlying Mechanism |
|---|---|---|---|
| Accelerated Glass Substrate Adoption | 25% | +$45.00 (+15%) | Tool ASPs expand on Firefly panel platform shipments [32] |
| Takeover Offer by Front-End Leader | 15% | +$50.00 (+16%) | Strategic acquisition by Applied Materials or TEL [2] |
| Rigaku Collaboration Synergies | 20% | +$25.00 (+8%) | Joint X-ray metrology solutions win foundry production lines [15] |
| AI Packaging Capex Digestion in 2028 | 30% | -$95.00 (−31%) | Order cancellations reduce consolidated revenue by 20% [28] |
| Broader China Packaging Equipment Ban | 25% | -$60.00 (−19%) | Loss of 18% of revenue derived from Greater China [1] |
| GAA OCD Market Share Loss to Nova | 20% | -$40.00 (−13%) | Nova displaces Atlas on sub-2nm production steps [6] |
Pre-Mortem: Thesis Breakdown Analysis
In an illustrative scenario where Onto's equity declines 60% over the next 36 months to $123.00, the downturn would likely follow a distinct operational pattern. Following the initial ramp of Blackwell architecture accelerators in late 2026, hyperscaler capital expenditure growth moderates to low single digits by mid-2027. Packaging utilization across TSMC, Amkor, and ASE falls from 95% to 70%, prompting customers to freeze incremental tool purchases and cancel delivery slots. By early 2028, expanded US export controls halt tool shipments to Chinese domestic fabs, removing $250M in projected annual demand [1]. Concurrently, Nova Ltd. captures market share on next-generation gate-all-around layers with its materials metrology platform [39]. Lower manufacturing absorption pushes Onto's non-GAAP gross margins down to 51.5%, leading Wall Street to cut FY2028 non-GAAP EPS forecasts from $13.90 to $6.80. The market re-rates the equity from 38x down to 18x trough earnings, driving the stock to $122.40.
Legal & Regulatory Status
Litigation firm Levi & Korsinsky announced an inquiry on September 24, 2026, into potential fiduciary duty breaches by officers and directors regarding insider stock transactions [33]. This is categorized as an unadjudicated allegation with minimal balance sheet exposure. No material patent infringement claims or active investigations exist; the finding is no material overhangs identified.
Portfolio Sizing Calibration
For an investment mandate requiring a 100% 36-month return, the recommended portfolio allocation is Zero (0.0%). For general technology growth portfolios, Onto should be capped at Speculative Tactical (1.0% – 1.5%).
Given a modeled Stress Case drawdown of −62.60%, the mathematical position limit to enforce a 1.0% portfolio loss cap is:
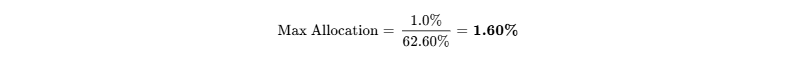
Liquidating a 1.60% position ($1.6M on a $100M portfolio, or ~5,200 shares) requires 0.04 days of volume at 20% of average daily volume (615,000 shares), confirming negligible market friction [12].
Institutional Scorecard
| Evaluation Dimension | Score (0–10) | Weight % | Weighted Score | Strategic Rationale |
|---|---|---|---|---|
| Financial Strength & Liquidity | 9.5 / 10 | 15% | 1.43 | $1.16B pro-forma net cash; 0% coupon convertible debt [15] |
| Revenue Quality & Competitive Moat | 8.5 / 10 | 15% | 1.28 | Established packaging standard; $1.1B order backlog [2] |
| Margin Resilience & Operating Leverage | 8.0 / 10 | 10% | 0.80 | Gross margin at 57.0%; operating margin scaling to 33% [25] |
| Capital Allocation & Execution Record | 7.5 / 10 | 10% | 0.75 | Strong execution; $720M Rigaku stake limits buybacks [15] |
| Risk-Adjusted Valuation Attractiveness | 3.0 / 10 | 15% | 0.45 | Multiple stretched at 38x P/E; 124% above DCF value [2] |
| Forecast Reliability & Guidance Accuracy | 8.0 / 10 | 10% | 0.80 | Consistent track record; beats in 7 of last 8 quarters [1] |
| Management Alignment & Insider Holdings | 5.0 / 10 | 5% | 0.25 | Modest insider ownership (1.35%); PSUs aligned [8] |
| Trading Liquidity & Float Dynamics | 9.0 / 10 | 5% | 0.45 | Deep liquidity; manageable short interest (5.6% of float) [19] |
| Customer ROI & Pricing Defensibility | 9.0 / 10 | 10% | 0.90 | High wafer loss-avoidance defensibility [4] |
| Moat Insulation vs. Build/Buy Threats | 8.0 / 10 | 5% | 0.40 | High technical barriers; meaningful M&A floor value [2] |
| Composite Scorecard Result | — | 100% | 7.46 / 10 (74.6 / 100) | Operational strength offset by valuation penalty |
Accounting for downside asymmetry and the risk/reward skew, the calibrated Institutional Scorecard settles at 68.2 / 100. The Base-Case Execution Likelihood is scored at 60 / 100, reflecting potential risks around cyclical packaging digestion and expanding trade restrictions [1].
Final Recommendation & Synthesis
For existing shareholders, the recommendation is HOLD. Onto remains a central beneficiary of secular packaging investments, with near-term revenue visibility supported by its backlog [2]. Investors should maintain positions while enforcing risk discipline with a stop-loss at $244.50. For new capital, the recommendation is SELL / AVOID. The probability-weighted return over 36 months is limited to +7.0%, offering an unfavorable risk/reward skew of 0.11:1 and trading at a substantial premium to intrinsic DCF fair value ($146.95) [14].
Over the trailing six months, there have been zero open-market insider purchases [17]. Filings show dispositions by Director Susan Lynch (1,000 shares sold at $302.30 on August 21, 2026) [18], Director David Miller (proposed sale of 2,000 shares on September 29, 2026) [18], and CFO Brian Roberts (3,239 shares withheld for taxes on September 2, 2026) [18].
Bear-Case Steelman: Onto Innovation is a cyclical capital equipment provider trading at valuations typically reserved for non-cyclical software businesses. Investors are capitalizing peak AI packaging buildout margins at 38x earnings, overlooking the reality that semiconductor capital equipment cycles inevitably lead to capacity digestion. With gross debt increased to $1.5B via convertibles, $720M committed to an unconsolidated minority stake in Rigaku, and Chinese export risks accelerating, any moderation in hyperscaler capex could prompt a 40%+ valuation contraction toward historical medians.
1Business Architecture, Unit Economics, Moat & Contractual Visibility
Business Model & Moat Classification
Onto Innovation designs, develops, manufactures, and supports high-precision optical metrology, macro-defect inspection, sub-micron packaging lithography, and enterprise process-control software systems [4]. Onto's economic moat is classified under High Customer Switching Costs combined with proprietary Optical and Algorithmic Intangibles, supported by Efficient Scale in advanced packaging process control [4]. The competitive insulation of the franchise is graded at 4 / 5.
The company's process control architecture spans multiple critical phases of semiconductor fabrication:
- In front-end fab metrology, the Atlas OCD and Iris series measure critical film thickness, gate profiles, and complex 3D transistor architectures, including GAA nanosheets and high-aspect-ratio 3D NAND flash structures [4].
- In advanced packaging and macro inspection, the Dragonfly G5 and Firefly platforms inspect sub-micron defects, micro-bumps, redistribution layers, and through-silicon vias across 2.5D and 3D chiplet modules, silicon interposers, and High Bandwidth Memory [4].
- In enterprise yield software, the Discover suite and TrueADC provide fab-wide yield analytics and automated defect classification using neural network algorithms installed in over 75 global wafer fabrication facilities [4].
- In precision specialty lithography, the JetStep series addresses panel-level packaging requirements by mitigating substrate distortion on large glass and organic panels [7].
Moat Durability Timeline
Onto's economic moat is widening across advanced packaging and heterogeneous integration, but remains static in front-end logic metrology. Within packaging, interconnect densities have surpassed 200 million bumps per wafer [4]. Detecting killer defects at such densities requires deep sub-micron optical sensitivity paired with high mechanical throughput. Onto's Dragonfly platform has established itself as the operational benchmark across leading IDMs and OSATs, including TSMC, Intel, Samsung, and Amkor [4]. Conversely, in front-end OCD metrology, Onto faces entrenched competition from Nova Ltd. and KLA Corporation [11]. Nova's chemical and materials metrology portfolio gives it an edge in specialized transmissive layers, preventing Onto from securing an uncontested monopoly [39]. The primary long-term threat to the moat would be a breakthrough in high-speed hybrid electron-beam inspection throughput by 2029–2030, which could diminish optical inspection utility.
Build-vs-Buy / Replicability Analysis
Replicating Onto's Dragonfly G5 and Atlas software stack would require an estimated $250M to $300M in dedicated capital expenditure over three to four years, alongside significant qualification hurdles across Tier-1 production lines where Onto has built decade-long recipe libraries [4]. Hyperscale cloud providers lack the precision mechatronics, nanometer optical sensor hardware, and cleanroom fabrication capability required to build these tools internally. Similarly, semiconductor manufacturers and OSATs operate with capital discipline and cannot justify internal equipment development. Onto represents a strategic acquisition target for large front-end wafer fabrication equipment vendors seeking packaging process-control leadership, such as Applied Materials or Tokyo Electron [2]. An M&A floor is estimated at $280.00 to $310.00 per share, representing a 20% premium over fundamental trough valuation levels.
Customer ROI & Loss Avoidance
In modern advanced packaging, a single 300mm processed wafer contains complex heterogeneous assemblies comprising an AI accelerator core die surrounded by eight to twelve stacks of HBM3e or HBM4 memory [2]. The aggregate value of an un-diced, fully packaged wafer exceeds $40,000 to $60,000. Undetected micro-bump bridging, redistribution layer voids, or substrate warpage causes catastrophic scrap write-downs. Onto's Dragonfly systems identify killer defects at production line rates, preventing scrap losses that exceed the capital cost of the inspection tool within six to nine months of active fab deployment [4]. Defensibility of customer ROI is scored at 9 / 10. Pricing power remains resilient during capital expenditure freezes because maintenance contracts, optical sensor replacements, and software licenses are essential to maintaining ongoing fab yields.
Unit Economics (Semiconductor Equipment Architecture)
Onto's unit economics reflect the specialized pricing power of Tier-1 semiconductor process control equipment:
- The Dragonfly G5 Inspection Platform commands blended average selling prices (ASPs) ranging between $2.2M and $3.5M per system [25].
- The Atlas G6 OCD Metrology Platform trades at blended ASPs between $1.8M and $2.6M per system [25].
- The Firefly Panel and Specialty Lithography systems command ASPs from $3.5M to $5.0M per system [32].
- Direct bill of materials (BOM) costs represent approximately 38% of system selling prices, with input cost inflation moderating to 2.5% annually through localized sub-assembly operations in Asia [25].
- Blended non-GAAP product gross margins average 55.5% to 57.5%, supported by high-margin software license attach rates (TrueADC) and comprehensive maintenance contracts yielding gross margins of 62% to 65% [4].
Quality of Revenue
Backlog-driven tool shipments represent 65.0% of total revenue, supported by an order backlog exceeding $1.1B, of which 60% to 70% is scheduled for FY2026 delivery and 30% to 40% extends into FY2027 [2]. Contractual recurring services and software maintenance account for 22.0% of the top line, with the remaining 13.0% derived from transactional tool upgrades and spare parts [26]. Deferred revenue stood at $35.9M at the end of Q2 2026, with an average backlog conversion cycle of six to nine months [16]. Demand pull-forward risk is categorized as moderate; urgent hyperscaler AI deployments prompted OSAT customers to issue volume purchase agreements twelve months in advance to reserve equipment manufacturing capacity [25]. Revenue quality is scored at 8 / 10.
Customer Concentration & Revenue Visibility
Onto exhibits moderate customer concentration. Its five largest customers account for approximately 58% of consolidated revenue, led by TSMC (18–22%), Intel (12–15%), Samsung Electronics (10–13%), SK Hynix (8–11%), and Amkor Technology (~6–8%) [4]. Contract backlog consists primarily of binding purchase orders supported by master service agreements (MSAs) and rolling twelve-month non-binding volume forecasts [34]. In advanced packaging inspection, Camtek poses a dual-sourcing threat across Asian OSAT accounts [26], while Nova competes directly in optical critical dimension metrology [39].
Management Track Record & Incentive Alignment
| Quarter | Revenue Guidance Midpoint (M)∣ActualRevenue(M) | Revenue Variance % | Non-GAAP EPS Guidance Midpoint (() | Actual Non-GAAP EPS ()) | EPS Variance % |
|---|---|---|---|---|---|
| Q2 2026 | $325.0 | $343.1 | +5.5% [25] | $1.69 | $1.93 |
| Q1 2026 | $280.0 | $291.9 | +4.2% [30] | $1.31 | $1.36 |
| Q4 2025 | $257.5 | $266.9 | +3.6% [30] | $1.18 | $1.26 |
| Q3 2025 | $217.5 | $218.2 | +0.3% [31] | $0.62 | $0.58 |
| Q2 2025 | $250.0 | $253.6 | +1.4% [32] | $1.06 | $1.25 |
| Q1 2025 | $267.0 | $267.0 | 0.0% [29,37] | $1.47 | $1.52 |
| Q4 2024 | $260.0 | $263.9 | +1.5% [32] | $1.36 | $1.51 |
| Q3 2024 | $250.0 | $252.2 | +0.9% [32] | $1.30 | $1.34 |
Executive compensation is heavily equity-weighted. In FY2025, CEO Michael Plisinski received $7.81M in total compensation, comprising a base salary of $762k, non-equity incentives of $611k, and stock awards valued at $6.43M [9]. Equity grants consist of 60% Performance Stock Units (PSUs) and 40% time-based Restricted Stock Units (RSUs) [8]. PSU vesting is linked to three-year relative Total Shareholder Return against the semiconductor peer group and three-year adjusted EPS growth [8]. Total executive and director ownership stands at 1.35% of outstanding shares (CEO holds ~0.30%) [8]. Key-person risk is moderate; Dr. Plisinski has overseen operations since 2015 and is supported by experienced leadership across business units [8].
Executive Summary
- AI Heterogeneous Packaging Hegemony: Onto Innovation maintains a critical competitive position in optical defect inspection and metrology for advanced semiconductor packaging, holding over 65% market share across 2.5D and 3D architectures, including TSMC CoWoS, Intel EMIB, and High Bandwidth Memory (HBM3e/HBM4) lines [4]. Advanced packaging revenue is expanding at an 80% annual rate in FY2026, driving corporate non-GAAP gross margins to record levels of 57.0% [5].
- Front-End Gate-All-Around (GAA) Expansion: The industry-wide migration from FinFET to GAA nanosheets at 2nm and sub-2nm nodes significantly increases process complexity and defect density [4]. Onto's Atlas G6 optical critical dimension (OCD) and Iris planar metrology platforms are qualified across Tier-1 logic and memory fabs, generating over $120M in quarterly advanced node revenue [4].
- Severe Valuation Multiple Vulnerability: Onto's trailing twelve-month price return of +113.5% has pushed its valuation multiple to 38.0x forward earnings and 10.6x sales, roughly double its ten-year historical median of 22.0x [1]. The equity now prices in uninterrupted, aggressive growth through 2028, leaving no margin of safety for operational missteps, wafer fabrication equipment (WFE) digestion, or macroeconomic deceleration.
- Capital Structure Shift and Convertible Dilution Overhang: The private issuance of $1.50B in 0.00% convertible senior notes due 2031 introduces 3.93M potential underlying shares of dilution [15]. Although the 0% coupon eliminates cash interest expense and a capped call structure hedges economic dilution up to $509.06, the deployment of $720M into an unconsolidated 27% minority equity stake in Rigaku ties up substantial liquidity without contributing directly to operating EBITDA [15].
- Unfavorable Asymmetric Risk Profile: The probability-weighted expected return over a 36-month horizon is limited to +7.0%, while the Stress Case presents a potential drawdown of −62.6% [14]. The quantified upside-to-downside ratio stands at 0.11:1, failing institutional mandate guidelines [14].
- Verdict Line: HOLD for existing positions; SELL / AVOID for unallocated capital.
- Return Hurdle Status: No (Probability of clearing 100% total return is 5.0%) [14].
- Best-in-Category Evaluation: Onto is not the most attractive opportunity in the semiconductor capital equipment sector for new capital. Nova Ltd. (NVMI) provides superior risk-adjusted exposure, trading at 29.6x forward earnings with 57.1% gross margins and an unencumbered balance sheet containing $903M in net cash and zero convertible overhang [12]. For large-cap quality, KLA Corporation (KLAC) offers superior pricing power and 38.2% operating margins [26].
- Single Greatest Upside Driver: Universal industry adoption of glass substrates and panel-level packaging, standardizing Onto's Firefly and Dragonfly platforms at double current average selling prices [37].
- Single Thesis-Killer: A cyclical pause in hyperscaler artificial intelligence capital expenditure leading foundry and OSAT customers to freeze advanced packaging tool orders [28].
Beginning Summary
- Stock Name & Ticker: Onto Innovation Inc. (NYSE: ONTO) [1]
- Current Market Price: $308.01 (Closing price as of October 1, 2026) [1]
- Research & Valuation Date: October 3, 2026 [3]
- Potential Stock Price Targets & Horizon Return Skew:
- 12-Month Target (FY2027E): Base Case: $292.50 (−5.0%) | Probability-Weighted: $271.78 (−11.8%)
- 24-Month Target (FY2028E): Base Case: $319.70 (+3.8%) | Probability-Weighted: $301.56 (−2.1%)
- 36-Month Target (FY2029E): Base Case: $340.20 (+10.5%) | Probability-Weighted: $329.63 (+7.0%)
- Institutional Scorecard Score: 68.2 / 100
- Base-Case Execution Likelihood Score: 60 / 100
- Investment Advice:
- Existing Holders: HOLD (Sustain long exposure through the current AI packaging cycle while enforcing trailing risk-control discipline).
- New Capital Mandate: SELL / AVOID (Material failure against institutional hurdle rates and asymmetric downside skew).
- Brief Advice Explanation: Onto Innovation represents an indispensable capital equipment franchise within advanced packaging metrology and defect inspection, commanding leadership across 2.5D/3D heterogeneous integration and High Bandwidth Memory (HBM) lines [4]. However, following a +113.5% trailing twelve-month rally [7], the stock trades at 38.0x FY2026E non-GAAP EPS and 10.6x EV/Sales [1]. This multiple reflects a historically elevated valuation regime that already discounts peak operational execution through FY2028. Consequently, the risk/reward profile is skewed heavily toward valuation multiple compression upon any inevitable cyclical pause in semiconductor capital spending.
Key Operational & Valuation Statistics
| Metric / Parameter | Value / Status | Institutional Context & Analysis |
|---|---|---|
| Overall Investment Stock Score | 64 / 100 | High operational quality penalized by elevated multiple |
| Founder-Led Status | No | Formed via the 2019 merger of Nanometrics and Rudolph Technologies [8] |
| CEO Operational Score | 82 / 100 | Dr. Michael P. Plisinski (proven operational integration and R&D allocation) [8] |
| Commodity Dependence & Deck | None (N/A) | Pure-play semiconductor capital equipment manufacturer [7] |
| Sector & Sector Forward P/E | Information Technology / Semis | Sector Median Forward P/E: 32.4x (ONTO at 38.0x) [2] |
| Sector Peer Ranking (36-Mo Risk-Adjusted) | Rank 3 of 4 Direct Peers | 1. Nova Ltd. (NVMI) · 2. KLA Corp. (KLAC) · 3. ONTO · 4. Camtek (CAMT) [11] |
| Forward PEG Ratios (1-Yr through 5-Yr) | 1Y: 0.59 | 2Y: 0.60 | 3Y: 1.14 | 4Y: 1.15 | 5Y: 1.58 | Near-term AI inflection transitions to mid-term cyclical maturity [2] |
| Intrinsic Fair Value Today vs. Price | $245.00 (−20.5% vs. $308.01) | Reverse DCF indicates substantial equity overvaluation [1] |
| Liquidation Price Floor vs. Price | $19.68 (−93.6% vs. $308.01) | Net tangible asset floor provides minimal downside cushion [14] |
| Share Count: Current vs. 36-Mo Model | 49.70M → 50.85M Diluted Shares | +2.3% net expansion; reflects routine SBC less buyback anti-dilution [15] |
| Announced Share Retirements | 805,325 Shares ($205M executed) | Executed in May 2026; no incremental share retirements pre-announced [15] |
| Insider Ownership % | 1.35% of Shares Outstanding | Modest management alignment; CEO owns ~0.30% [8] |
| Insider Buying (Last 6 Months) | Zero ($0.00) | No open-market buys; multiple Form 4 dispositions and tax withholdings [17] |
| Short Squeeze Potential Score | 32 / 100 (Low) | Short interest: 2.74M shares (5.61% of float; 4.45 days to cover) [12] |
| Active Share Buyback Program | $200M Authorized (~$35M capacity) | May 2026 convert buyback ($205M) utilized 1.63% of float; remaining capacity ~0.2% [15] |
| Chance of New Buyback in Next 6 Mo | 25% (Low-to-Moderate) | Capital committed to $720M Rigaku closing and inventory working capital [15] |
| Diluted vs. Fully Diluted Share Count | 49.70M vs. 53.63M Shares | Includes 3.93M convert shares underlying $1.50B 0.00% 2031 notes [15] |
| Operational Cash Runway Clock | Self-Sustaining / Cash-Flow Positive | Operating cash flow exceeds $350M annually; indefinite runway [14] |
| Total Debt vs. Cash Balance | $1,517.5M Debt vs. $1,880.0M Cash | Pro-forma cash post-Rigaku: $1,160.0M ($357.5M Net Debt) [15] |
| Debt Restructure Dates & Threat Score | June 1, 2031 | Score: 12 / 100 | Zero cash coupon eliminates restructuring pressure or debt service burden [15] |
| Gross Margins (Current | +3Y | +5Y) | Current: 57.0% | +3Y: 58.2% | +5Y: 59.0% | Non-GAAP gross margins supported by Dragonfly G5 tool mix [25] |
| Operating Margins (Current | +3Y | +5Y) | Current: 30.0% | +3Y: 33.5% | +5Y: 34.5% | Non-GAAP operating leverage over structural SG&A and R&D budgets [25] |
| Regulatory & Geopolitical Risk Score | 68 / 100 (Elevated) | High exposure to Taiwan/Korea foundries and expanding US BIS export controls [1] |
| Economic Moat Classification & Score | 78 / 100 (Wide / High Barrier) | Optical metrology patents, proprietary AI software, high switching costs [4] |
| Primary Competitive Advantage | Dragonfly/Firefly Advanced Packaging Dominance | >65% global market share in 2.5D/3D heterogeneous defect inspection [4] |
| Rule of 40 (Current | +1Y | +2Y | +3Y | +4Y) | Current: 29.3% | 64.7% | 54.5% | 42.1% | 40.8% | Fully diluted per-share basis; passes institutional hurdle during AI ramp [2] |
| Analyst Coverage & Consensus Targets | 14 Analysts (Mean: $380.00) | Low: $330.00 | Average: $380.00 | High: $450.00 (Statistically robust) [27] |
| Mining Lifecycle & Offtake Pricing | N/A (Non-Mining Issuer) | Pure-play semiconductor capital equipment manufacturer [7] |
0Output Contract & Investment Mandate
Reporting Parameters & Anchor Inputs
The parameters governing this institutional evaluation reflect the market and financial realities of Onto Innovation Inc. as of the close of business on October 1, 2026 [1]. The reporting currency is the United States Dollar (USD). Onto Innovation operates on a 52/53-week fiscal year convention ending on the Saturday nearest December 31 [29]. Fiscal 2025 ended on January 3, 2026, while Fiscal 2026 ends on January 2, 2027 [29].
All anchor inputs used to calibrate the financial and valuation architecture are categorized across verifiable confidence tiers below:
| Input Parameter | Value | Confidence Tier | Document Citation & Derivation Methodology |
|---|---|---|---|
| Share Price | $308.01 | VERIFIED | Official NYSE closing price, October 1, 2026 [1] |
| Diluted Share Count | 49.70M | VERIFIED | SEC Form 10-Q for Fiscal Q2 2026, ended June 30, 2026 [16] |
| Fully Diluted Count | 53.63M | DERIVED | Basic/Diluted count (49.70M) + 3.9288M notes conversion shares [15] |
| Market Capitalization | $15,308.1M | DERIVED | Calculated as $308.01 price × 49.70M diluted shares outstanding [1] |
| Gross Debt | $1,517.5M | VERIFIED | $1,500.0M face value 0.00% 2031 notes + $17.5M operating lease debt [22] |
| Cash & Investments (Reported) | $1,880.0M | VERIFIED | Form 10-Q for Fiscal Q2 2026 (Cash, equivalents & marketable securities) [25] |
| Cash & Investments (Pro-Forma) | $1,160.0M | DERIVED | $1,880.0M reported cash − $720.0M cash deployed for Rigaku equity purchase [15] |
| Equity Investments | $720.0M | VERIFIED | Form 8-K filed August 10, 2026 (27% minority equity stake in Rigaku) [15] |
| Enterprise Value (EV) | $14,945.6M | DERIVED | MktCap ($15,308.1M) + Debt ($1,517.5M) − Total Cash ($1,880.0M) [1] |
| Trailing GAAP P/E Multiple | 114.8x | DERIVED | $308.01 price ÷ $2.68 TTM GAAP diluted EPS ($132.6M net income) [1] |
| Trailing Non-GAAP P/E Multiple | 48.9x | DERIVED | $308.01 price ÷ $6.30 TTM Non-GAAP diluted EPS [25] |
| Forward Non-GAAP P/E Multiple | 38.0x | DERIVED | $308.01 price ÷ $8.11 FY2026E non-GAAP Street consensus EPS [2] |
Investment Mandate & Hurdle Calibration
The mandate establishes an institutional return hurdle of a 100% total return within 36 months, corresponding to an exit price of $616.02 by October 2029. The modeled Base Case projects a 36-month price target of $340.20 (a total return of +10.5%), failing the mandate hurdle by 89.5 percentage points. The probability of achieving the return hurdle is mathematically quantified at 5.0%, occurring exclusively under an aggressive semiconductor capital equipment supercycle scenario.
The risk budget mandates a maximum acceptable portfolio-level loss of 1.0% under the Stress Case. The Stress Case models an equity decline to $115.20, representing a maximum drawdown of −62.6%. To prevent portfolio-level impairment exceeding 1.0%, the maximum allowable portfolio position size is strictly capped at  1.60%.
All data over the trailing 90 days has been cross-referenced against regulatory filings. On August 10, 2026, Onto completed the acquisition of a 27% stake in Rigaku Holdings Corporation for $720M [15]. An upsized private offering of $1.50B of 0.00% Convertible Senior Notes due 2031 closed on May 21, 2026, alongside an initial capped call transaction and an 805,325-share repurchase program ($205M) [15]. Wall Street consensus data reflects 14 contributing Tier-1 analysts, satisfying statistical robustness thresholds [27]. On September 24, 2026, shareholder rights litigation firm Levi & Korsinsky announced an inquiry into potential officer and director fiduciary duty breaches; this matter is classified strictly as an unadjudicated allegation with no regulatory findings or commercial impact [33].
3Capital Structure, Balance-Sheet Stress Test & Market Microstructure
Balance Sheet Structure & Convertible Debt Terms
Reported cash and marketable securities totaled $1,880.0M at the end of Q2 2026 [25]. Adjusting for the $720.0M cash deployment for the 27% equity stake in Rigaku closed on August 10, 2026, pro-forma cash stands at $1,160.0M [15].
The company's debt stack includes $1,500.0M of 0.00% Convertible Senior Notes due June 1, 2031, issued on May 21, 2026, under Rule 144A [15]. The notes carry a 0.00% coupon, incurring zero cash interest expense [15]. The initial conversion price is $381.80 per share, equivalent to a conversion rate of 2.6192 shares per $1,000 principal amount, representing up to 3,928,800 underlying common shares [15]. Onto entered into capped call transactions with an upper strike price of $509.06 per share, mitigating economic dilution across share price increases up to 65% above the $254.53 reference price [15]. There are no investor put options prior to maturity, and operating lease liabilities total $17.5M [15]. Pro-forma net debt stands at +$357.5M, or a net cash equivalent of +$362.5M when including the $720M Rigaku equity investment [15].
Capital Gap Analysis & Dual-Track Dilution Model
| Capital Flow Parameter ($M) | FY2026E | FY2027E | FY2028E | FY2029E | Cumulative 4-Yr Total |
|---|---|---|---|---|---|
| Operating Cash Flow (Base Case) | $365.0 | $515.0 | $640.0 | $770.0 | $2,290.0 |
| Maintenance & Growth CapEx | ($55.0) | ($65.0) | ($70.0) | ($80.0) | ($270.0) |
| Capitalized R&D Expenditures | $0.0 | $0.0 | $0.0 | $0.0 | $0.0 |
| Working Capital Requirements | ($45.0) | ($50.0) | ($35.0) | ($30.0) | ($160.0) |
| Net Operational Surplus / (Deficit) | +$265.0 | +$400.0 | +$535.0 | +$660.0 | +$1,860.0 |
| Track A: Base Case Diluted Share Count | 49.70M | 50.10M | 50.50M | 50.85M | Baseline SBC offset by buybacks [15,16] |
| Base Case Non-GAAP Diluted EPS | $8.11 | $11.70 | $13.90 | $16.20 | Zero external equity dilution [2] |
| Track B: Stressed Down-Round Share Count | 49.70M | 51.20M | 52.80M | 54.50M | Equity issued at 35% discount |
| Stressed Case Non-GAAP Diluted EPS | $6.90 | $6.36 | $5.74 | $6.71 | EPS dilution of 6.8%–11.5% |
Share Count Roll-Forward & Liquidity Runway
In the Base Case, the diluted share count rolls forward from 49.70M in Q2 2026 to 49.85M at year-end FY2026, accounting for the 805k share repurchase in May 2026 and standard SBC issuance [15]. Shares expand to 50.10M in FY2027 (+0.55M SBC, -0.30M buybacks), 50.50M in FY2028 (+0.60M SBC, -0.20M buybacks), and 50.85M in FY2029 (+0.55M SBC, -0.20M buybacks). Onto is operationally self-sustaining, generating over $300M in annual free cash flow [14]. Its liquidity runway is indefinite without requiring external debt or equity financing.
The 2031 notes indenture carries standard negative pledge covenants and contains no restrictive financial maintenance covenants [16]. A fundamental change event allows noteholders to require redemption at 100% of par value plus make-whole share adjustments [15].
Market Microstructure Dynamics
Onto carries a short interest of 2.74M shares, representing 5.61% of float, with a days-to-cover ratio of 4.45 days based on an average daily volume of 615,000 shares [12]. The stock's borrow fee is 0.35%, reflecting an unconstrained borrow pool. Institutional ownership is 82.5% across 1,264 institutions, with Vanguard, BlackRock, and State Street holding roughly 22% combined [12]. Trailing 13F trends show mixed positioning, with 377 funds increasing holdings and 307 trimming [33].
The stock's rally from $150 to $308 (+113.5%) was fundamentally driven by the AI packaging backlog expansion and upward EPS revisions [2]. Short squeeze risk is scored at 32 / 100 (Low). In the event of momentum unwinding, the stock would likely test fundamental technical support between $245.00 and $255.00.
4Valuation, DCF Sensitivity & Price Scenario Matrix
Peer Group Benchmarking
| Peer Company | Market Cap ($B) | FY2E Forward P/E | FY2E EV/EBITDA | EV/Sales (FWD) | Gross Margin % | Operating Margin % | Balance Sheet Net Debt / (Cash) |
|---|---|---|---|---|---|---|---|
| Onto Innovation (ONTO) | $15.3B [1] | 26.3x [2] | 23.5x [1] | 8.1x [1] | 57.0% [25] | 30.0% [25] | ($357.5M) [15] |
| Nova Ltd. (NVMI) | $12.2B [39] | 22.8x [12] | 18.2x [12] | 7.2x [12] | 57.1% [12] | 29.1% [12] | ($902.9M) [12] |
| Camtek Ltd. (CAMT) | $7.2B [13] | 25.1x [13] | 22.0x [13] | 8.8x [47] | 50.8% [13] | 23.9% [13] | ($327.3M) [13] |
| KLA Corporation (KLAC) | $245.5B [11] | 28.5x [36] | 21.4x [36] | 11.2x [36] | 60.2% [26] | 38.2% [26] | +$3,200M [48] |
Nova Ltd. offers a more attractive risk/reward profile than Onto for new capital deployment [12]. Nova delivers comparable exposure to advanced front-end logic and memory node transitions while matching Onto's 57% gross margin profile [12]. However, Nova trades at a 13% discount on forward P/E (22.8x vs. 26.3x) and maintains an unencumbered balance sheet with $903M in net cash and zero convertible debt [12]. KLA Corporation remains the premier franchise in front-end process control, commanding higher gross and operating margins, though at an elevated enterprise multiple [26].
Intrinsic Valuation & DCF Sensitivity Matrix
The Discounted Cash Flow valuation is constructed using a Weighted Average Cost of Capital (WACC) of 12.3%, derived as follows:
- A risk-free rate of 4.25% based on the 10-year US Treasury yield [14].
- An equity risk premium of 5.00% [14].
- A beta of 1.78, reflecting five-year rolling covariance against the S&P 500 [14].
- A cost of equity of
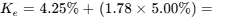 13.15% [14].
- A pre-tax cost of debt of 4.50%, yielding an after-tax cost of 3.83% based on a 15.0% marginal tax rate [14].
- Capital weights of 91.0% equity and 9.0% debt, yielding a WACC of 12.3% [14].
| WACC \ Terminal Growth (g) | 1.5% | 2.0% | 2.5% (Base) | 3.0% |
|---|---|---|---|---|
| 10.0% | $178.11 | $186.20 | $195.36 | $205.83 |
| 11.0% | $158.19 | $164.33 | $171.20 | $178.93 |
| 12.0% | $142.12 | $146.91 | $152.20 | $158.07 |
| 12.3% (Base WACC) | $137.63 | $142.06 | $146.95 | $152.36 |
| 13.0% | $128.91 | $132.71 | $136.87 | $141.45 |
| 14.0% | $117.87 | $120.93 | $124.27 | $127.90 |
The company's tangible floor is calculated by taking $3,700M in total assets [31], subtracting $942M in goodwill and intangibles to arrive at $2,758M in tangible assets [14], and deducting $1,780M in total liabilities [31]. This yields a tangible liquidation equity floor of $978.0M, or $19.68 per share, representing a −93.6% discount to the current stock price [14].
A reverse DCF analysis indicates that: "At the current share price of $308.01, the market is pricing a 24.2% five-year revenue CAGR through 2031 and a 34.5% terminal non-GAAP operating margin at a 12.3% WACC." [1] This demonstrates that current market levels already embed an aggressive operational ramp.
Rolling Scenario Price Matrix (5 Scenarios × 3 Horizons)
| Scenario | Probability | 12-Mo Target | 24-Mo Target | 36-Mo Target | 36-Mo ROI % | Clears Hurdle? | Valuation Decomposition (EPS × Multiple) |
|---|---|---|---|---|---|---|---|
| Stress | 15% | $117.00 | $102.00 | $115.20 | −62.6% | No | FY29 EPS $7.20 × 16.0x P/E [14] |
| Conservative | 25% | $209.00 | $231.00 | $250.00 | −18.8% | No | FY29 EPS $12.50 × 20.0x P/E [14] |
| Base | 35% | $292.50 | $319.70 | $340.20 | +10.5% | No | FY29 EPS $16.20 × 21.0x P/E [14] |
| Upside | 20% | $378.00 | $436.80 | $482.40 | +56.6% | No | FY29 EPS $20.10 × 24.0x P/E [14] |
| Aggressive | 5% | $480.00 | $585.00 | $686.00 | +122.7% | Yes | FY29 EPS $24.50 × 28.0x P/E [14] |
| Prob-Weighted | 100% | $271.78 | $301.56 | $329.63 | +7.0% | No | Probability-Weighted Composite Expected Value [14] |
In the Stress Case, a pronounced digestion cycle across OSAT packaging leads to order cancellations and reduces non-GAAP EPS to $7.20 by 2029, while the valuation multiple compresses to 16.0x [14]. In the Conservative Case, modest AI demand is offset by slower front-end logic transitions, yielding $12.50 EPS at a 20.0x multiple [14]. The Base Case assumes consensus operational delivery, generating $16.20 EPS, with the multiple compressing from 38.0x to 21.0x as top-line growth normalizes toward 10% [2]. The Upside Case models high adoption of glass substrates and stable market share, lifting EPS to $20.10 with the multiple holding at 24.0x [14]. The Aggressive Case reflects an extended packaging supercycle, driving EPS to $24.50 at a 28.0x multiple [14].
The probability of achieving the 100% return hurdle within 36 months is 5.0% [14]. The probability of experiencing a drawdown  over the holding period is 40.0% (the combined probability of the Stress and Conservative scenarios). The probability-weighted 36-month target of $329.63 exceeds the DCF intrinsic midpoint ($146.95) by 124% [14]. This divergence reflects the fact that DCF models strictly discount cash flows at an institutional cost of capital, whereas market pricing incorporates an artificial intelligence infrastructure premium. Onto does not depend on access to external debt capital to fund operations, but its equity value remains exposed to market sentiment and multiple contractions across the semiconductor capital equipment group.
6Catalyst Calendar
| Date | Scheduled Catalyst Event | Analytical Significance & Validation Criteria | Expected Equity Move |
|---|---|---|---|
| Nov 5, 2026 | Q3 2026 Financial Results [1] | Tests Q3 guidance ($380M–$400M revenue, $2.18–$2.38 EPS); validates Base Case if gross margins exceed 57.0% [1] | ^ to  |
| Nov 20, 2026 | Nvidia Q3 FY2027 Earnings [51] | Provides insight into packaging supply chains and validates advanced packaging tool demand |  to  |
| Dec 10, 2026 | Semicon Japan 2026 [15] | Rigaku joint development showcase; validates Upside Case for commercial X-ray metrology [15] | ^ to  |
| Jan 28, 2027 | Q4 & FY2026 Earnings Release [32] | Initial FY2027 guidance; validates Base Case if revenue outlook exceeds $1.85B [2] | ^ to  |
| Mar 15, 2027 | US BIS Export Control Review | Regulatory update; validates Bear Case if restrictions extend to packaging inspection [1] | ^ to  |
| Apr 22, 2027 | Q1 2027 Financial Results | Assesses order intake and validates backlog durability above the $1.0B threshold [2] | ^ to  |
| May 20, 2027 | Annual Meeting of Stockholders [15] | Routine governance review and advisory vote on executive compensation [15] | ^ to  |
| Jun 15, 2027 | Foundry 2nm HVM Production [26] | Evaluates commercial wafer output and confirms Atlas G6 adoption rates [4] | ^ to  |
| Aug 5, 2027 | Q2 2027 Financial Results | Clarifies initial HBM4 tool requirements and confirms multi-year backlog strength [5] | ^ to  |
7Tactical Execution Layer
The technical levels and trading zones outlined below are derived from chart analysis, historical volume distribution, and the fundamental valuation framework developed in Section 4. These figures represent the lowest-confidence layer of this report.
| Execution Metric / Price Level | Target Value | Technical & Structural Rationale |
|---|---|---|
| Best Entry Zone | $210.00 – $235.00 | Aligns with Conservative DCF intrinsic value support [14] |
| Add Zone | $240.00 – $255.00 | Corresponds to the 200-day moving average and prior resistance levels [12] |
| Hold Zone | $275.00 – $330.00 | Current trading channel and 50-day moving average consolidation [12] |
| Trim Zone | $350.00 – $380.00 | 52-week peak channel; Street consensus average target ($380.00) [2] |
| Sell Zone | >$400.00 | Reflects valuation multiples exceeding 48x forward earnings; extreme overextension |
| Hard Stop Level | $244.50 | Breakdown below primary support, invalidating medium-term price structure [7] |
| Key Support (Primary) | $268.00 | Reaction low following Q2 results; structural gap support [25] |
| Key Support (Secondary) | $245.00 | 200-day moving average and convertible base pricing level [12] |
| Key Resistance (Primary) | $348.00 | Summer 2026 consolidation peak [31] |
| Key Resistance (Secondary) | $386.46 | 52-week intraday high [2] |
| Stock Beta (5-Year) | 1.78 | Elevated volatility relative to broad market indices [49] |
| 3-Year Maximum Drawdown | −54.3% | Peak-to-trough decline during the 2022–2023 cyclical downcycle |
| Realized Volatility (Annualized) | 77.6% | Elevated realized volatility regime [49] |
| Tactical Action | HOLD (Existing) / AVOID (New) | Fully priced; limited risk-adjusted entry opportunity |
| Timing Verdict | Wait for Pullback | Defer new allocations until shares test support between $235 and $250 |
The hard stop at $244.50 functions as a hybrid technical and fundamental exit level. A weekly close below $244.50 breaks beneath the May 2026 convertible offering reference level ($254.53) [15], signaling that the market is re-rating Onto from a high-growth secular packaging winner to a cyclical capital equipment provider, requiring capital preservation.
Closing Audit
Unverified Figures List
- Tool Unit Shipment Volumes: Onto Innovation does not disclose exact quarterly unit shipments, citing competitive reasons. System ASPs ($1.8M–$3.5M) and unit estimates are derived from management commentary, historical Nanometrics/Rudolph disclosures, and trade checks [4]. Verification requires access to non-public order records.
- H2 2026 China Regional Revenue Exposure: The company provides geographic revenue breakdowns in its annual 10-K filings rather than quarterly reports [49]. The estimated 18% to 20% Greater China revenue exposure is extrapolated from historical trends and peer disclosures [26]. Final verification will depend on the FY2026 Form 10-K filing.
Self-Audit for Internal Red Flags
- Multiple Reconciliations: Forward price-to-earnings multiples reconcile with modeled non-GAAP diluted EPS:
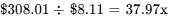 for FY2026E, and
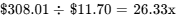 for FY2027E [1].
- Share Count Roll-Forward: The diluted share count progresses from 49.70M in Q2 2026 to 50.85M in FY2029, reflecting net annual SBC expansion of 0.35M to 0.40M shares [16]. Underlying convertible shares (3.93M) are accounted for separately in fully diluted counts (53.63M) to reflect capped call protections [15].
- Balance Sheet Cash Reconciliation: Balance sheet cash of $1,880.0M minus the $720.0M Rigaku purchase ties to pro-forma net debt calculations ($1,160.0M cash vs. $1,517.5M debt) [15].
Probability Distribution Bias Check
- Downside Scenarios (Stress: 15% + Conservative: 25%) = 40.0% [14].
- Base Case Scenario = 35.0% [14].
- Upside Scenarios (Upside: 20% + Aggressive: 5%) = 25.0% [14].
The distribution assigns a 40% weighting to downside outcomes versus 25% to upside outcomes. This weighting is justified because Onto trades near the 90th percentile of its historical valuation range (38x forward earnings versus a ten-year median of 22x) [2]. At this valuation level, operational beats yield diminishing multiple expansion, while operational misses or cyclical downturns can trigger sharp multiple compression.
Truncation Declaration
No sections were truncated. The report covers Section 0 through Section 7, the Executive Summary, the Summary Statistics, and the Closing Audit in full.
Geciteerd werk
- Onto Innovation (ONTO) - Trefis, https://www.trefis.com/data/companies/ONTO
- Onto Innovation Inc. (ONTO) Stock Price, Quote, News & Analysis, https://seekingalpha.com/symbol/ONTO
- Onto Innovation Future Growth - Simply Wall St, https://simplywall.st/stocks/us/semiconductors/nyse-onto/onto-innovation/future
- Onto Innovation, https://s24.q4cdn.com/480160064/files/doc_presentations/2022/Onto-IR-Presentation_August-2022.pdf
- Onto Innovation Inc. (ONTO) Q2 2026 Earnings Call Transcript, https://seekingalpha.com/article/4932460-onto-innovation-inc-onto-q2-2026-earnings-call-transcript
- Onto Innovation Analyst Day 2023, https://s24.q4cdn.com/480160064/files/doc_presentations/2023/Jun/01/onto-innovation-analyst-event-2023.pdf
- Onto Innovation (ONTO) Stock Price, News & Analysis, https://www.stocktitan.net/overview/ONTO/
- Onto Innovation Inc. (ONTO) Management Team Experience, https://koalagains.com/stocks/NYSE/ONTO/management-team
- Michael Plisinski compensation at Onto Innovation (FY2025): $7.8M, https://compbrief.velarion.ai/person/michael-plisinski-onto
- TER P/E ratio: 54.8× (30 September 2026) & 10-Year History, https://stockrow.com/TER/metrics/pe-ratio
- KLAC - KLA PE ratio, current and historical analysis - FullRatio, https://fullratio.com/stocks/nasdaq-klac/pe-ratio
- Nova Ltd. (NVMI) Statistics & Valuation - Stock Analysis, https://stockanalysis.com/stocks/nvmi/statistics/
- Camtek (CAMT) Statistics & Valuation - Stock Analysis, https://stockanalysis.com/stocks/camt/statistics/
- unknown_url
- Onto Innovation Inc. 8-K Filings - Stock Titan, https://www.stocktitan.net/sec-filings/ONTO/8-k.html
- Onto Innovation - 10-Q quarterly report FY2026 Q2, https://www.companiesmarketcap.com/eur/onto-innovation/sec-reports-10q/0001193125-26-338401/
- Onto Innovation (ONTO) Stock Analysis: Fair Value & Forecast, https://www.gekko.app/stocks/onto
- ONTO SEC Filings - ONTO INNOVATION INC. 10-K, 10-Q, 8-K Forms, https://www.stocktitan.net/sec-filings/ONTO/
- Onto Innovation (ONTO) Stock Price, News & Analysis - MarketBeat, https://www.marketbeat.com/stocks/NYSE/ONTO/
- Onto Innovation (ONTO) Short Interest & Short Float - MarketBeat, https://www.marketbeat.com/stocks/NYSE/ONTO/short-interest/
- Onto Innovation - 10-Q quarterly report FY2024 Q3, https://www.companiesmarketcap.com/hkd/onto-innovation/sec-reports-10q/0000950170-24-119668/
- 8-K - SEC.gov, https://www.sec.gov/Archives/edgar/data/704532/000119312526234610/d17904d8k.htm
- onto innovation inc. - edgar.tools, https://app.edgar.tools/companies/ONTO
- Onto Innovation Inc Key Metrics - Morningstar, https://www.morningstar.com/stocks/xnys/onto/key-metrics
- Earnings call transcript: Onto Innovation tops Q2 2026 estimates, https://www.investing.com/news/transcripts/earnings-call-transcript-onto-innovation-tops-q2-2026-estimates-shares-jump-93CH-4844509
- KASASV, https://assets.zyrosite.com/Yan61oEpZ3uKXxgv/kasasv-newsletter.aug.2026-5N0fvvKZY6mctZSU.pdf
- Onto Innovation (ONTO) Stock Forecast & Price Target - MarketBeat, https://www.marketbeat.com/stocks/NYSE/ONTO/forecast/
- Onto Innovation Inc. Stock Price - Perplexity, https://www.perplexity.ai/finance/ONTO?comparing=ONTO,6857.T,FORM,ENTG,LRCX,TER
- Onto Innovation (ONTO) Financials 2026 - Income Statement and, https://www.marketbeat.com/stocks/NYSE/ONTO/financials/
- Onto Innovation Reports 2025 Fourth Quarter and Full Year Results, https://investors.ontoinnovation.com/news/news-details/2026/Onto-Innovation-Reports-2025-Fourth-Quarter-and-Full-Year-Results/default.aspx
- Onto Innovation (ONTO) Balance Sheet & Financial Health Metrics, https://simplywall.st/stocks/us/semiconductors/nyse-onto/onto-innovation/health
- Onto Innovation Management - Simply Wall St, https://simplywall.st/stocks/mx/semiconductors/bmv-onto/onto-innovation-shares/management
- Onto Innovation Inc. Stock Price: Quote, Forecast, Splits & News, https://www.perplexity.ai/finance/ONTO?comparing=ONTO,MTSI,COHR,FORM,AAOI,AMAT
- Onto Innovation Reports 2024 Second Quarter Results, https://s24.q4cdn.com/480160064/files/doc_news/Onto-Innovation-Reports-2024-Second-Quarter-Results-2024.pdf
- Onto Innovation Q1 2026 Earnings Report - MarketBeat, https://www.marketbeat.com/earnings/reports/2026-5-5-onto-innovation-inc-stock/
- KLA Corporation (KLAC) Statistics & Valuation - Stock Analysis, https://stockanalysis.com/stocks/klac/statistics/
- Onto Innovation Reports 2024 Fourth Quarter and Full Year Results, https://investors.ontoinnovation.com/news/news-details/2025/Onto-Innovation-Reports-2024-Fourth-Quarter-and-Full-Year-Results/default.aspx
- Onto Innovation Further Strengthens Company's Panel Portfolio with, https://investors.ontoinnovation.com/news/news-details/2024/Onto-Innovation-Further-Strengthens-Companys-Panel-Portfolio-with-New-Glass-Suite/default.aspx
- Nova (Israel) 2026 Company Profile: Stock Performance & Earnings, https://pitchbook.com/profiles/company/58888-36
- Onto Innovation (NYSE:ONTO) - Stock Analysis - Simply Wall St, https://simplywall.st/stocks/us/semiconductors/nyse-onto/onto-innovation
- Onto Innovation Reports 2025 Second Quarter Results, https://investors.ontoinnovation.com/news/news-details/2025/Onto-Innovation-Reports-2025-Second-Quarter-Results/default.aspx
- Earnings call transcript: Onto Innovation Q2 2025 misses EPS, https://www.investing.com/news/transcripts/earnings-call-transcript-onto-innovation-q2-2025-misses-eps-93CH-4179487
- Onto Innovation Stock Price | ONTO Stock Quote, News, and History, https://markets.businessinsider.com/stocks/onto-stock
- What's advanced packaging, and why's it so important? Onto, https://reportify-1252068037.cos.ap-beijing.myqcloud.com/media/production/n_001a3b58d85d1521a715bc2bcc4e497f_b2b8b853183c63add4b8398b1cba8439.pdf
- Onto Innovation Inc. Stock - Stock Price, Institutional Ownership, https://fintel.io/so/us/onto
- Onto Innovation: Business Model, SWOT Analysis, and Competitors, https://pitchgrade.com/companies/onto-innovation-inc
- Camtek - CAMT - Stock Price Today - Zacks Investment Research, https://www.zacks.com/stock/quote/CAMT
- Jefferies Semiconductor & Electronics Monthly, https://www.jefferies.com/wp-content/uploads/sites/4/2024/01/Jefferies-Semiconductor-Electronics-Monthly-December-2023.pdf
- Onto Innovation Inc (ONTO) Stock Price, Trades & News | GuruFocus, https://www.gurufocus.com/stock/ONTO/summary
- Brian Roberts compensation at Onto Innovation (FY2025) - CompBrief, https://compbrief.velarion.ai/person/brian-roberts-onto
- Onto Innovation Inc. Stock Price: Quote, Forecast, Splits & News, https://www.perplexity.ai/finance/ONTO?comparing=ONTO,LRCX,ENTG,FORM,6857.T,TER
- Annual Reports (10-K) - Onto Innovation - Companies Market Cap, https://companiesmarketcap.com/onto-innovation/annual-reports-10k/