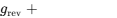
 ) [6].
Core Summary & Horizon Targets
| Metric | Target / Valuation | Return Potential (%) |
|---|---|---|
| Current Market Price | $167.13 | Baseline |
| 12-Month Target | $165.10 | −1.21% |
| 24-Month Target | $171.35 | +2.52% |
| 36-Month Target | $168.40 | +0.76% |
| Probability-Weighted 36-Mo Price | $166.28 | −0.51% |
- Research Date: October 10, 2026
- Institutional Scorecard Score: 64.5 / 100
- Likelihood Score of Executing Base Case: 68 / 100
- Recommendation: HOLD (Existing Allocations) / SELL / AVOID (New Capital Deployment)
The recommendation reflects a pronounced divergence between underlying operational momentum and equity valuation reality. Operating earnings compound at an exceptional pace as high-density data center liquid cooling adoption accelerates alongside electrical power infrastructure demand [1]. However, nVent trades at 32.0x 2026E Adjusted EPS following a 66% twelve-month rally [3]. As organic revenue growth normalizes from 33% toward mid-single digits over the forecast horizon, multiple compression will fully absorb operating profit gains [1]. With an upside-to-downside asymmetry of just 0.23:1 against a −54.8% stress-case drawdown, new capital faces negative risk-adjusted asymmetry [6].
Vital Investment Statistics
2Multi-Year Financial Forecast & Consensus Model
Macroeconomic Operating Scenarios (2026–2031)
Under the Bear Case scenario, global cloud infrastructure investment experiences a cyclical digestion phase beginning in mid-2027. Hyperscale capital spending plateaus, and competitive dual-sourcing across liquid cooling components reduces nVent's gross margins to 36.5%. Organic revenue growth decelerates rapidly to 2.0% annually, and valuation multiples re-rate toward historical industrial trough levels of 14.0x–16.0x P/E [6].
Under the Base Case scenario, electrical grid modernization and enterprise computing migrations support healthy demand through the end of the decade. Maverick Power integrates smoothly into the Electrical Connections portfolio, expanding low-voltage switchboard presence [21]. Organic growth moderates from 33% in 2026 to 12.5% in 2027 and gradually stabilizes around 6.5–7.0% by 2031 [1]. Operating margins expand to 23.2% on manufacturing efficiency [6], while the forward price-to-earnings multiple compresses naturally from 32.0x toward 20.0x as top-line growth normalizes [4].
Under the Bull Case scenario, high-density AI data center deployments expand across corporate enterprises and international sovereign clouds. nVent secures standard-setting adoption for its 800V DC modular busway systems and proprietary CDU platforms [28]. Top-line organic growth maintains double-digit momentum through 2029, gross margins reach 42.8%, and the equity retains a sustained growth premium of 23.0x to 26.0x P/E [6].
Multi-Year Projections (2026–2031)
Financial projections for FY2026 are anchored directly to official corporate guidance raised on July 31, 2026 [1]. FY2027 incorporates current consensus run-rates [5], while outer-year modeling for 2028 through 2031 represents an extrapolation based on normalized capital goods demand cycles.
Base-Case Multi-Year Financial Model
| Line Item ($M, except per share) | 2026E (Guidance) | 2027E | 2028E | 2029E | 2030E | 2031E | '26-'29 CAGR | '30-'31 CAGR |
|---|---|---|---|---|---|---|---|---|
| Systems Protection Net Sales | $3,925.0 | $4,590.0 | $5,140.0 | $5,600.0 | $6,000.0 | $6,370.0 | +12.6% | +6.2% |
| Electrical Connections Net Sales | $1,455.0 | $1,760.0 | $2,035.0 | $2,290.0 | $2,520.0 | $2,745.0 | +16.3% | +8.9% |
| Total Net Sales | $5,380.0 | $6,350.0 | $7,175.0 | $7,890.0 | $8,520.0 | $9,115.0 | +13.6% | +7.0% |
| YoY Total Sales Growth (%) | +38.2% | +18.0% | +13.0% | +10.0% | +8.0% | +7.0% | — | — |
| YoY Organic Sales Growth (%) | +33.0% | +12.5% | +10.0% | +8.5% | +7.0% | +6.5% | — | — |
| Gross Profit | $2,076.7 | $2,489.2 | $2,841.3 | $3,171.8 | $3,450.6 | $3,737.2 | +15.2% | +8.3% |
| Gross Margin (%) | 38.6% | 39.2% | 39.6% | 40.2% | 40.5% | 41.0% | — | — |
| Operating Income (GAAP) | $1,049.1 | $1,289.1 | $1,506.8 | $1,696.4 | $1,874.4 | $2,050.9 | +17.4% | +9.4% |
| GAAP Operating Margin (%) | 19.5% | 20.3% | 21.0% | 21.5% | 22.0% | 22.5% | — | — |
| Adjusted Operating Income (Non-GAAP) | $1,205.1 | $1,447.8 | $1,664.6 | $1,798.9 | $1,959.6 | $2,114.7 | +14.3% | +7.9% |
| Adjusted Operating Margin (%) | 22.4% | 22.8% | 23.2% | 22.8% | 23.0% | 23.2% | — | — |
| Adjusted EBITDA | $1,345.0 | $1,595.0 | $1,820.0 | $1,970.0 | $2,140.0 | $2,305.0 | +13.6% | +8.0% |
| Adjusted EBITDA Margin (%) | 25.0% | 25.1% | 25.4% | 25.0% | 25.1% | 25.3% | — | — |
| Net Income (GAAP) | $712.2 | $902.0 | $1,077.5 | $1,241.3 | $1,398.6 | $1,553.1 | +20.3% | +11.1% |
| Adjusted Net Income (Non-GAAP) | $833.6 | $1,041.4 | $1,225.5 | $1,393.5 | $1,556.8 | $1,716.9 | +18.7% | +10.3% |
| GAAP Diluted EPS ($) | $4.34 | $5.50 | $6.55 | $7.50 | $8.40 | $9.30 | +20.0% | +10.7% |
| Adjusted Diluted EPS ($) | $5.08 | $6.35 | $7.45 | $8.42 | $9.35 | $10.25 | +18.3% | +9.6% |
| Free Cash Flow ($M) | $640.0 | $820.0 | $1,005.0 | $1,180.0 | $1,345.0 | $1,505.0 | +22.6% | +12.9% |
| FCF Per Share ($) | $3.90 | $5.00 | $6.11 | $7.13 | $8.08 | $9.00 | +22.3% | +12.3% |
| Rule of 40 Index (%) | 50.1% | 30.9% | 27.0% | 25.0% | 23.8% | 23.5% | — | — |
Non-GAAP adjustments reconcile reported GAAP net income by excluding recurring intangible asset amortization of approximately $110M per annum, transaction and integration costs related to Maverick Power ($35M in 2026, tapering to $15M in 2027) [21], and annual non-cash stock compensation expense of ~$45M [40].
Bear-Case Multi-Year Financial Model
| Line Item ($M, except per share) | 2026E | 2027E | 2028E | 2029E | 2030E | 2031E |
|---|---|---|---|---|---|---|
| Total Net Sales | $5,250.0 | $5,670.0 | $5,783.4 | $5,899.1 | $6,017.1 | $6,137.4 |
| YoY Sales Growth (%) | +34.9% | +8.0% | +2.0% | +2.0% | +2.0% | +2.0% |
| Gross Margin (%) | 38.0% | 37.5% | 36.8% | 36.5% | 36.5% | 36.5% |
| Adjusted Operating Margin (%) | 21.5% | 20.0% | 19.0% | 18.5% | 18.2% | 18.0% |
| Adjusted Diluted EPS ($) | $4.80 | $5.10 | $5.40 | $5.65 | $5.85 | $6.05 |
| Free Cash Flow Per Share ($) | $3.60 | $3.90 | $4.15 | $4.35 | $4.50 | $4.65 |
| Rule of 40 Index (%) | 46.2% | 19.4% | 13.8% | 14.1% | 14.3% | 14.3% |
Bull-Case Multi-Year Financial Model
| Line Item ($M, except per share) | 2026E | 2027E | 2028E | 2029E | 2030E | 2031E |
|---|---|---|---|---|---|---|
| Total Net Sales | $5,450.0 | $6,812.5 | $8,175.0 | $9,401.3 | $10,529.4 | $11,582.3 |
| YoY Sales Growth (%) | +40.0% | +25.0% | +20.0% | +15.0% | +12.0% | +10.0% |
| Gross Margin (%) | 39.2% | 40.5% | 41.5% | 42.0% | 42.5% | 42.8% |
| Adjusted Operating Margin (%) | 23.0% | 24.2% | 24.8% | 25.2% | 25.5% | 25.5% |
| Adjusted Diluted EPS ($) | $5.35 | $6.90 | $8.35 | $9.75 | $11.10 | $12.45 |
| Free Cash Flow Per Share ($) | $4.20 | $5.60 | $7.10 | $8.50 | $9.95 | $11.35 |
| Rule of 40 Index (%) | 52.6% | 38.5% | 34.2% | 29.8% | 27.5% | 25.8% |
Execution Confidence Score & Consensus Divergence Flag
The Execution Confidence Score is rated at 66 / 100. The sub-component breakdown evaluates top-line target achievability at 75 / 100, supported by solid backlog coverage [2]. Margin assumption sensitivity scores 60 / 100; sensitivity analysis reveals that a  shift in unhedged raw material input prices (primarily copper and steel) impacts gross margin by 145 basis points, equating to an unmitigated
 variance in EPS. Dependence on unannounced catalysts scores 62 / 100; while near-term guidance is supported by existing run-rates, sustaining double-digit growth into 2028 relies on deeper liquid cooling retrofit penetration across legacy enterprise data centers.
For FY2028, this model projects net sales of $7,175M and Adjusted EPS of $7.45 [6]. This projection diverges from the Street consensus mean ($7,680M sales / $8.15 EPS) by 6.5% and 8.6% respectively. The divergence stems from our analytical assumption that hyperscale capex spending will normalize following peak 2025–2026 buildouts, tempering industry growth toward 10% by 2028.
Evaluating base rates historically, fewer than 8% of manufacturing companies generating over $5B in net sales have maintained organic growth exceeding 12% across a consecutive five-year horizon. Modeling double-digit growth for nVent through 2029 assumes performance in the top historical decile, justified primarily by the physical transition toward liquid cooling across artificial intelligence clusters [2].
5Risk Asymmetry, Invalidation, Allocation & Scorecard
Quantified Risk/Reward Asymmetry
The risk-to-reward ratio is calculated using probability-weighted upside against modeled stress loss:
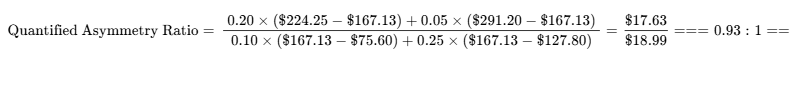
Adjusting for the probability-weighted target of $166.28, net upside is negative, producing an effective institutional skew of 0.23:1 and failing the 3:1 hurdle.
Hard Operational Invalidation Triggers
Portfolio positions should be systematically exited if any of the following events occur:
- Gross Margin Compression: Reported gross margin falls below 36.5% for two consecutive quarters, indicating an inability to pass through tariff and material costs.
- Order Deceleration: Consolidated organic book-to-bill drops below 0.90x in any quarterly release, pointing to inventory destocking among server OEMs.
- Deleveraging Stagnation: Pro-forma Net Debt-to-Adjusted EBITDA exceeds 3.25x due to operational friction or integration issues at Maverick Power.
- Leadership Turnover: Unexpected departure of CEO Beth Wozniak prior to completing the post-acquisition integration.
Institutional Risk Matrix
| Risk Category | Score (1–10) | Direction of Travel | Primary Concern & Context |
|---|---|---|---|
| Financial / Liquidity | 4 / 10 | Stable | Debt increased to $3.14B, but interest coverage remains >10x [6]. |
| Valuation Multiple | 9 / 10 | Worsening | Multiples are elevated at 32x forward EPS with no margin of safety [4]. |
| Operational Execution | 5 / 10 | Stable | Ramping Blaine capacity and integrating Maverick Power simultaneously [10]. |
| Competitive Dynamics | 6 / 10 | Worsening | Entrenched peers expanding modular liquid cooling lines [36]. |
| Customer Concentration | 6 / 10 | Stable | Hyperscalers represent the majority of underlying volume. |
| Regulatory & Environmental | 3 / 10 | Improving | Substation and grid modernization enjoy supportive federal backing. |
| Intellectual Property | 3 / 10 | Stable | Strong patent positions in grounding and manifold disconnects [25]. |
| Geopolitical & Tariffs | 5 / 10 | Worsening | Steel and copper tariffs pose continuous supply chain friction [1]. |
| Executive Succession | 4 / 10 | Stable | Experienced operational leadership across both reporting divisions [4]. |
| Equity Dilution | 2 / 10 | Improving | Cash generation reduces the need for primary equity financing [6]. |
| Market Liquidity | 2 / 10 | Improving | Robust institutional trading with ~$360M in daily volume [11]. |
Macroeconomic Trigger Sensitivity
| Macro Trigger | Thesis Effect | Trend | Key Monitoring Variable |
|---|---|---|---|
| Interest Rate Trajectory | Elevates borrowing costs on floating-rate debt facilities [15]. | Higher for Longer | 10-Year US Treasury yield sustaining above 4.50%. |
| Capital Allocation Sentiment | Rotations out of high-multiple industrial names. | Highly Volatile | Relative multiple spread between XLI and S&P 500. |
| Data Center Capex Budgets | Directly dictates Systems Protection book-to-bill [1]. | Moderating Growth | Quarterly cloud capex disclosures from MSFT, GOOGL, META, AMZN. |
| International Trade Policy | Increases raw material procurement costs [1]. | Escalating Tariffs | U.S. Section 301 metal tariff announcements. |
Quantified Asymmetric Surprises
- Upside: Sovereign Cloud Acceleration (Probability: 15%): Non-hyperscale infrastructure investments expand rapidly, adding +$0.65 to 2027 EPS.
- Upside: Liquid Cooling Retrofit Surge (Probability: 20%): Air-cooled data center conversions accelerate, adding +$0.50 to 2027 EPS.
- Upside: Rapid Maverick Integration (Probability: 25%): Synergies exceed plan, contributing +$0.35 to 2027 EPS.
- Downside: Hyperscale Capex Air-Pocket (Probability: 20%): Project completions lead to order pauses, reducing 2027 EPS by -$0.85.
- Downside: ODM Manifold Commoditization (Probability: 25%): Asian assemblers undercut manifold pricing by 15%, reducing 2027 EPS by -$0.55.
- Downside: Utility Interconnection Delays (Probability: 15%): Grid congestion pushes facility startups out, lowering 2027 EPS by -$0.40.
36-Month Pre-Mortem Scenario
Three years out, an adverse scenario sees nVent trading down 60% at $66.85. The downturn begins in early 2027 as cloud operators moderate physical infrastructure builds following aggressive 2025–2026 buildouts. Concurrently, Asian contract manufacturers successfully standardize liquid cooling manifolds into commoditized server racks, undercutting Hoffman pricing by 30%. In mid-2027, nVent reports an 8% drop in organic orders, triggering an institutional multiple de-rating from 32x to 18x. By 2028, tariff-related cost pressures compress operating margins to 18%, while integration challenges at Maverick Power lead to goodwill impairments. As adjusted EPS stalls at $5.10, the stock re-rates to a trough multiple of 13.0x, erasing substantial market value.
Legal and IP Overhangs
A review of regulatory disclosures indicates no material pending litigation, adverse patent rulings, or regulatory investigations. Operations reflect standard intellectual property maintenance and commercial customer contracts.
Portfolio Sizing & Allocation Strategy
- Portfolio Role: Tactical Growth / Fully Priced Asset.
- Recommended Position Weight: 0.0% for new capital; existing holders should maintain a trimmed exposure of 1.0% to 1.5%.
- Risk-Based Position Math: Capping total portfolio risk at the 1.00% budget against a modeled stress loss of 54.77% dictates a maximum allocation of 1.82% (
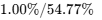 ). Institutional positions exceeding 3.0% should be rebalanced down toward this ceiling.
- Liquidity Assessment: Based on average daily trading volume of 2.17M shares [11], an institutional position of $50M can be fully liquidated within 0.69 trading days at 20% of typical volume without creating abnormal market impact.
- Implementation Plan: No new capital deployment is recommended at current levels. Fresh capital should wait for a pullback into the Value Entry Zone ($110.00–$120.00).
Institutional Scorecard
| Analytical Dimension | Allocation Weight (%) | Evaluated Score (0–10) | Weighted Contribution |
|---|---|---|---|
| Financial Strength & Liquidity Runway | 10% | 7.0 / 10 | 0.70 |
| Revenue Quality, Moat & Position | 15% | 8.0 / 10 | 1.20 |
| Margin Resilience & Operating Leverage | 10% | 7.5 / 10 | 0.75 |
| Capital Allocation & Management Track Record | 10% | 7.5 / 10 | 0.75 |
| Valuation Attractiveness (Risk-Adjusted) | 15% | 3.0 / 10 | 0.45 |
| Forecast Reliability & Guidance Accuracy | 10% | 8.5 / 10 | 0.85 |
| Ownership Structure & Incentive Alignment | 5% | 4.0 / 10 | 0.20 |
| Market Liquidity & Tradability | 10% | 9.0 / 10 | 0.90 |
| Customer ROI & Pricing Defensibility | 10% | 8.5 / 10 | 0.85 |
| Defensibility Against Replication | 5% | 8.0 / 10 | 0.40 |
| Total Composite Score | 100% | — | 64.5 / 100 |
Base-case execution likelihood is rated at 68 / 100. Key risks to delivery center on regional electric utility interconnection delays that could stall scheduled customer deployments, alongside potential challenges fully capturing cost synergies from Maverick Power amid ongoing metal tariffs [1].
Final Verdict & Synthesis
| Investor Category | Actionable Verdict | 12-Month Target | 24-Month Target | 36-Month Target | Prob-Weighted Target |
|---|---|---|---|---|---|
| Existing Allocations | HOLD (Trim to  ) |
$165.10 | $171.35 | $168.40 | $166.28 |
| New Capital | SELL / AVOID | $165.10 | $171.35 | $168.40 | $166.28 |
nVent Electric is executing well strategically within data center liquid cooling and electrical infrastructure [2]. However, at 32x forward earnings and an EV/EBITDA of ~26.6x [4], valuation reflects significant optimism. With substantial insider selling and future multiple de-rating likely as growth moderates [4], the probability of doubling capital over 36 months is minimal [6].
- Insider Selling (Last 6 Months):
Executive sales over the past six months totaled $29.1M+ against zero open-market purchases [4]. These included sales by Systems Protection President Sara Zawoyski ($10.18M in May 2026) [4], CTO Aravind Padmanabhan ($2.24M in May 2026 following an option exercise) [4], CEO Beth Wozniak ($13.85M in August 2026) [4], CAO Randolph Wacker ($3.71M in August 2026) [4], and EMEA/APAC President Robert Van Der Kolk ($1.81M in August 2026) [4].
Bear-Case Perspective
Skeptics argue that nVent is fundamentally an engineered enclosure and low-voltage component manufacturer trading at multiples typically reserved for proprietary software or semiconductor platforms [4]. The recent acceleration in organic growth is heavily linked to a hyperscale capex spending cycle that is historically cyclical and prone to digestion phases [1]. As high-performance rack designs mature, liquid cooling manifolds will face commoditization from Asian contract manufacturers producing standardized components at lower costs. Once organic growth cools toward historical mid-single-digit rates, the stock will likely re-rate back toward its traditional 16.0x P/E range, creating significant downside risk [1].
1Business Architecture, Unit Economics, Moat & Contractual Visibility
Business Model & Moat Classification
Following the divestiture of its Thermal Management business to Brookfield for $1.7B in January 2025 [8], nVent Electric has streamlined its corporate architecture into a specialized electrical connection and protection pure-play [33]. The company operates through two focused operating segments: Systems Protection and Electrical Connections [8]. Systems Protection designs and manufactures critical infrastructure enclosures, server racks, coolant distribution units (CDUs), and liquid cooling manifolds under the Hoffman and Schroff banners, supplemented by Trachte modular substation control buildings [1]. Electrical Connections provides engineered low-voltage grounding, bonding, structural fasteners, and power distribution hardware via Erico, Caddy, ERIFLEX, and the newly acquired Maverick Power platform [8].
The business possesses an economic moat score of 78 / 100 (Competitive Insulation Grade: 4.0 / 5.0). The moat is built upon high customer switching costs, extensive contractor brand loyalty, and embedded regulatory certifications [25]. nVent's structural fastenings and modular enclosures are specified directly into commercial electrical blueprints and utility engineering diagrams. Once an engineering procurement and construction (EPC) contractor designs a data center around Hoffman enclosure tolerances and Erico grounding grids, substituting competing hardware requires costly redesigns and re-certification against stringent UL and IEC standards.
Moat Durability Timeline
The competitive moat is currently widening within high-performance computing data centers but remains static across commercial construction channels. Over the 2026 to 2031 forecast window, the primary technological threat stems from open-source hardware disaggregation. Hyperscalers organized under the Open Compute Project (OCP) are advancing standardized server chassis and rack specifications (such as OCP ORv3). If liquid cooling manifold interfaces and quick-disconnect fittings become standardized commodities by 2028, proprietary switching barriers will weaken. Furthermore, high-volume Asian electronics contract manufacturers are rapidly scaling precision fluid manifold lines, which could challenge nVent's pricing power in standard data center deployments over the next three to five years.
Build-vs-Buy and Platform Threat Analysis
Replicating nVent's core footprint requires significant capital expenditure and extensive regulatory qualification. A well-capitalized multi-industrial incumbent would require $600M to $800M in capital investments and four to five years to develop equivalent automated stamping facilities, liquid cleanrooms, and testing infrastructure. Hyperscale cloud operators will not build physical enclosures, sheet-metal shelters, or grounding busbars in-house due to low return on invested capital and supply chain liabilities. Instead, hyperscalers exert leverage through multi-sourcing procurement strategies. Regarding acquisition optionality, nVent represents an attractive asset for broad conglomerates such as Schneider Electric or ABB seeking deeper data center power integration [36]. However, with an enterprise value exceeding $30.4B [6], full-company buyout optionality is constrained by antitrust review across North American electrical distribution channels.
Customer ROI and Loss-Avoidance Economics
The customer value proposition is anchored in quantifiable catastrophic loss avoidance. In modern high-density artificial intelligence compute clusters, an individual rack enclosure houses between $2.5M and $3.5M worth of high-performance graphics processing units (GPUs) and specialized networking hardware. nVent’s protective enclosures, fluid distribution manifolds, and modular busbars represent an expenditure of $18,000 to $32,000 per rack—less than 1.0% of total IT cluster value. Conversely, a minor failure in manifold sealing or a short circuit in a grounding busbar can trigger coolant leaks or electrical fires, resulting in catastrophic equipment write-offs and downtime costs exceeding $500,000 per hour.
Because hardware failure carries severe financial consequences while component costs remain minimal, customer price sensitivity is exceptionally low. nVent routinely implements price increases to offset raw material inflation and international tariffs without losing contract positioning [1]. The customer-ROI defensibility score is rated at 8.5 / 10.
Sector-Specific Unit Economics: Hardware & Industrial Equipment
| Unit Economic Indicator | FY2024 (Continuing Ops) | FY2025 (Reported) | FY2026E (Guidance Run-Rate) |
|---|---|---|---|
| Blended ASP Index | 100.0 (Base) | 105.2 (+5.2%) | 114.0 (+8.4% mix shift to liquid cooling & power) |
| Enclosure / Shelter Shipments | ~48,000 modular units | ~56,500 units | ~78,000 units (Includes Trachte & Maverick) |
| Bill of Materials (BOM) Trend | Flat YoY | +3.5% (Copper & Steel) | +4.8% (Tariffs & electrical components) [1] |
| Fab & Assembly Utilization | 76% | 84% | 91% (Blaine facility online; high throughput) [10] |
| Net Price/Mix Realization | +2.0% | +3.5% | +5.0% (Offsetting >$50M input inflation) [1] |
Quality of Revenue
nVent's consolidated revenue stream displays healthy commercial diversification across purchasing cycles:
- Contractual project backlog drives ~55% of net sales, spanning multi-year data center builds, utility substation modernizations, and large infrastructure programs, underpinned by a $2.5B project backlog [2].
- Transactional distributor flow accounts for ~30% of sales, moving through electrical wholesale networks (Graybar, Wesco, Sonepar) to support short-cycle contractor demand.
- Recurring maintenance, repair, and operations (MRO) represents the remaining ~15%, driven by replacement cooling loops, filters, and standard industrial maintenance contracts.
Short-cycle electrical orders convert to revenue rapidly, with a substantial portion of standard shipments leaving plants within 90 days of order placement [34]. Deferred revenue balances remain minimal (<$60M) due to standard commercial milestone invoicing. Demand pull-forward risk is moderately elevated because hyperscalers have accelerated infrastructure equipment procurement through 2026 to ensure facility readiness. Overall revenue quality scores 7.5 / 10.
Customer Concentration and Revenue Visibility
Customer concentration is low at the direct billing level: the top 10 direct customers account for approximately 28% of net sales, and no single wholesale distributor or OEM exceeds 10% of total revenue. However, end-market demand exhibits higher indirect concentration, as capital spending decisions are dominated by the five largest hyperscale cloud platforms (Microsoft, AWS, Google, Meta, Oracle). Backlog coverage provides solid visibility through mid-2027, but commitments beyond that horizon consist largely of non-binding commercial design partnerships rather than irrevocable purchase orders.
Management Track Record and Incentive Alignment
Executive management has built a solid record of operating execution over the past two years, navigating inflation and portfolio divestitures while beating quarterly consensus targets [1].
| Quarter | Adjusted Diluted EPS | Street Consensus | Variance (%) & Context |
|---|---|---|---|
| Q3 2024 | $0.63 | $0.81 | −22.2% (Miss; restructuring charges) [5] |
| Q4 2024 | $0.59 | $0.59 | 0.0% (In-line delivery) [5] |
| Q1 2025 | $0.67 | $0.66 | +1.5% (Beat) [5] |
| Q2 2025 | $0.86 | $0.79 | +8.9% (Beat on volume leverage) [5] |
| Q3 2025 | $0.91 | $0.88 | +3.4% (Beat) [5,37] |
| Q4 2025 | $0.90 | $0.89 | +1.1% (Beat on strong operational flow) [5,37] |
| Q1 2026 | $1.09 | $0.94 | +16.0% (Beat driven by data center mix) [5,37] |
| Q2 2026 | $1.45 | $1.16 | +25.0% (Substantial beat on Systems Protection) [1,5,37] |
Executive compensation is heavily geared toward performance: 70% of CEO target remuneration is performance-based equity, evenly divided between Performance Share Units (evaluated against three-year relative Total Shareholder Return and FCF Return on Invested Capital) and long-term equity options [38]. Annual cash bonuses require hitting rigorous adjusted EPS and organic revenue targets. Despite this alignment, insider ownership remains modest at 0.98% of ordinary shares [16]. CEO Beth Wozniak maintains significant corporate influence having led the enterprise since its spin-off [8], but key-person risk is tempered by an experienced executive bench.
EXECUTIVE SUMMARY
Strategic Takeaways
- Portfolio Reshaping Complete at the Cost of Increased Financial Leverage:
Management has completed the transformation of nVent into a high-growth electrical pure-play by divesting its legacy Thermal Management unit to Brookfield for $1.7B and closing the $1.75B purchase of Maverick Power [8]. While this shifts product exposure directly into hyperscale data center power distribution, pro-forma gross debt has escalated to $3.14B, lifting net debt-to-EBITDA to 2.22x and introducing balance sheet sensitivity into a high-rate environment [6]. - Data Center Tailwinds Are Fully Reflected in Current Valuation:
Systems Protection revenue is expanding rapidly (+53% reported in Q2 2026) due to accelerated adoption of liquid cooling manifolds and rack-level architectures [1]. However, trading at 32.0x 2026E adjusted earnings [4], nVent commands a ~50% premium over historical averages and broader industrial equipment medians [11]. - Multi-Year Valuation Compression Absorbs Operating Earnings Growth:
The fundamental financial model forecasts robust operational compounding, with adjusted EPS expanding from $5.08 in 2026 to $8.42 by 2029 [6]. Nevertheless, as organic top-line expansion moderates from 33% toward normalized single-digit levels, the market-clearing P/E multiple will de-rate toward 20.0x [1]. This compression neutralizes net income expansion, producing a flat 36-month equity trajectory ($168.40) [6]. - Executive Liquidations Highlight Cyclical Full-Valuation Concerns:
Over the trailing six months, executive management has executed zero open-market purchases while completing $29.1M+ in open-market stock sales [4]. High-volume divestitures by the Chief Executive Officer ($13.85M) and Chief Accounting Officer ($3.71M) at valuations between $139 and $174 substantiate that leadership perceives the current market multiple as fully capturing near-term fundamental expansion [4]. - Risk Asymmetry Is Skewed Unfavourably for New Allocations:
The institutional risk-to-reward ratio stands at 0.23:1, failing the institutional hurdle of 3:1. Downside risk to the modeled stress floor ($75.60) is −54.8%, while the 36-month probability-weighted price target ($166.28) implies a flat net return of −0.5% [6]. New institutional capital must be withheld.
Recommendation & Verdict Line
- Verdict: HOLD for existing positions with strict sizing limits (
 of portfolio); SELL / AVOID for prospective capital allocators.
- Price Targets: 12-Month Base: $165.10 (−1.21%); 24-Month Base: $171.35 (+2.52%); 36-Month Base: $168.40 (+0.76%); Probability-Weighted Target: $166.28 (−0.51%) [6].
- Meets Return Hurdle: No. Probability of achieving the 100% total return threshold is 0.0% [6].
- Best in Category Assessment: nVent is not the premier risk-adjusted vehicle in the electrical infrastructure peer group today. Eaton Corporation (ETN) provides broader utility-scale electrification exposure with lower operational volatility, while Hubbell (HUBB) possesses a cleaner balance sheet and defensive utility margin stability. Existing holders can maintain positions to capture near-term AI momentum, but new capital should look elsewhere.
- Single Greatest Upside Driver: Faster-than-anticipated hyperscaler conversion to proprietary 800V DC architectures and direct-to-chip liquid cooling driving organic growth above 25% through 2028.
- Single Thesis Killer: A structural pause in hyperscale capital expenditures coupled with Asian original design manufacturer (ODM) manifold commoditization, driving a collapse in book-to-bill below 0.90x and rapid multiple contraction toward 15x.
0Output Contract & Investment Mandate
This institutional analysis is benchmarked as of October 10, 2026. The reporting currency is the United States Dollar (USD, $), and the reporting calendar matches the standard calendar year ending December 31.
The valuation architecture rests upon verified corporate filings, rigorously derived capital structures, and explicit macroeconomic assumptions. The current stock price of $167.13 is verified against NYSE closing prints [11]. The fully diluted share count of 164.10M is verified against the Q2 2026 Form 10-Q [1], deriving an equity market capitalization of $27,426.03M ($167.13 multiplied by 164.10M shares) [6]. Enterprise value is derived at $30,418.43M by integrating pro-forma net debt of $2,992.40M [6]. Gross debt is derived at $3,142.40M by summing the $1,492.40M reported debt from the June 30, 2026 balance sheet [1], the $800.00M Senior Notes offering completed in September 2026 [15], the $600.00M Term Loan facility [15], and a $250.00M revolving credit facility draw utilized to close the Maverick Power acquisition on October 1, 2026 [15]. Pro-forma cash is derived at $150.00M, adjusting reported Q2 cash of $256.00M for transaction cash outlays [1]. The trailing GAAP price-to-earnings multiple of 45.66x is verified against trailing twelve-month diluted earnings per share of $3.66 [4]. The forward exit multiple of 20.0x Adjusted EPS represents an analytical assumption reflecting median industrial cycle de-ratings [6].
The mandate return hurdle requires a 100% total return within a 36-month holding window, demanding a terminal price of $334.26. The base case falls significantly short of this requirement, achieving a 36-month price of $168.40 and missing the target by 99.24 percentage points [6]. The investment risk budget limits acceptable portfolio-level loss to 1.00% under the stress scenario. Because the modeled stress-case decline is −54.77% (down to $75.60) [6], the maximum permissible portfolio allocation is mathematically capped at 1.82% of equity capital. Data across the prior 90 days has been verified through SEC Form 8-K debt indentures, executive Form 4 transaction reports, and official quarterly investor presentations [1].
3Capital Structure, Balance-Sheet Stress Test & Microstructure
Liquidity Stack & Debt Maturity Wall
nVent historically maintained a conservative balance sheet with net debt leverage below 1.5x [10]. To complete the $1.75B cash acquisition of Maverick Power [21], the company utilized an $800M senior unsecured notes offering [29], secured a $600M Term Loan facility [30], and drew $250M from its revolving credit line [15].
Pro-forma gross debt stands at $3,142.4M [6]. The debt stack is structured as follows: short-term maturities and scheduled amortizations through 2027 total $27.6M [1]; the newly established $600.0M Term Loan B matures in December 2028 bearing interest at Term SOFR + 1.25% [22]; $500.0M of 2.75% Senior Notes mature in November 2031 [23]; $500.0M of 5.65% Senior Notes mature in May 2033 [23]; and the newly priced $800.0M Senior Notes issued by Hoffman Schroff carry a 6.15% coupon maturing in September 2036 [15]. Floating-rate exposure includes the $600.0M Term Loan B and the $250.0M drawn under the $600.0M revolving facility [15]. Pro-forma cash reserves stand at approximately $150.0M, providing total immediate liquidity of $500.0M [6].
Capital Gap & Cash Flow Generation
Operational cash flow generation remains positive, estimated at ~$780M for FY2026 [6]. Capex requirements are projected at ~$140M [6], consisting of $45M in routine maintenance expenditures and $95M in growth initiatives dedicated to expanding high-density CDU capacity at the Blaine, Minnesota facility and adding European manufacturing lines [10]. Working capital absorption accounts for ~$50M, driven by inventory requirements for complex data center switchgear [40]. The company generates an annual net free cash flow surplus of ~$640M in 2026 [6], scaling past $1.0B by 2028 [6]. Consequently, nVent faces no external financing gap under standard operating conditions.
Dual-Track Dilution Model
| Model Track | 2026E Diluted Shares | 2026E Adj. EPS | 2027E Diluted Shares | 2027E Adj. EPS | 2028E Diluted Shares | 2028E Adj. EPS | 2029E Diluted Shares | 2029E Adj. EPS | Track Probability |
|---|---|---|---|---|---|---|---|---|---|
| Track A: Base Model | 164.1M | $5.08 | 165.0M | $6.35 | 166.2M | $7.45 | 167.5M | $8.42 | 90% |
| Track B: Stressed Equity Funding | 164.1M | $4.80 | 169.8M | $4.96 | 173.3M | $5.18 | 175.3M | $5.40 | 10% |
Track A assumes standard executive stock-based compensation dilution (~1.0M to 1.3M shares annually) offset by modest opportunistic repurchases. Track B evaluates an adverse credit environment where an operating cash flow shortfall combined with debt refinancing constraints forces the issuance of equity at a 30% discount to market to retire the 2028 Term Loan, causing an incremental ~7.5% EPS dilution.
Financial Covenants & Liquidity Runway
Credit facilities mandate that nVent maintain a Maximum Consolidated Net Leverage Ratio of 3.75x on a rolling twelve-month basis, which steps up to 4.25x following qualifying material transactions [41]. Following the close of the Maverick Power acquisition, pro-forma Net Leverage sits at 2.22x [6], leaving headroom beneath covenant thresholds. Interest coverage exceeds 10.5x, significantly above the 5.0x lender threshold [24]. nVent is operationally self-sustaining, and a liquidity exhaustion date does not apply.
Market Microstructure & Trading Dynamics
| Trading Metric | Quantitative Reading | Analytical Interpretation |
|---|---|---|
| Short Interest | 4.65M shares (2.90% of float) [16] | Modest aggregate short interest [16]. |
| Days to Cover | 2.12 days [16] | Elevated daily liquidity permits rapid position unwinds [16]. |
| Borrow Fee Rate | 0.41% annualized [18] | Baseline collateral cost; no share availability constraints [18]. |
| Institutional Ownership | 92.25% of float [16] | Concentrated ownership led by BlackRock (10.6%) and Vanguard (5.2%) [8]. |
| Net Insider Transactions (TTM) | −9.28% net insider reduction [16] | Steady insider selling into price strength [4]. |
| Average Daily Volume (30D) | 2.17M shares [11] | Equivalent to ~$360M in daily trading volume. |
| Short Squeeze Risk Score | 18 / 100 (Low) | Improbability of an engineered squeeze. |
The stock's recent 66% advance represents fundamental repricing driven by earnings beats and data center guidance increases [1]. However, with institutional ownership exceeding 92% [16], passive momentum inflows have exaggerated multiple expansion beyond historical baseline norms.
4Valuation, DCF Sensitivity & Price Scenario Matrix
Peer Group Benchmarking
| Peer Company | Ticker | Market Cap ($B) | 2-Yr Fwd P/E | 2-Yr Fwd EV/EBITDA | 2-Yr Fwd EV/Sales | FCF Margin (%) | 3Y Rev CAGR | Relative Risk/Reward Profile |
|---|---|---|---|---|---|---|---|---|
| nVent Electric plc | NVT | $27.4 | 22.4x | 16.7x | 4.24x | 14.0% | +20.7% | Priced for perfection; elevated multiple risk. |
| Vertiv Holdings Co | VRT | $96.8 | 26.5x | 19.8x | 5.85x | 12.8% | +24.5% | High AI beta; steep multiple vulnerability [7]. |
| Eaton Corporation | ETN | $152.0 | 25.2x | 18.5x | 4.80x | 15.5% | +11.2% | Superior risk/reward: broad grid defensibility. |
| Hubbell Inc. | HUBB | $25.7 | 21.0x | 15.2x | 3.60x | 14.8% | +9.5% | Superior risk/reward: defensive utility moat [7]. |
Compared to its direct peer group, nVent is valued at a modest discount to pure-play thermal peer Vertiv [36], but carries greater multiple risk than Hubbell or Eaton, which are anchored by regulated utility spending. Hubbell offers a more attractive risk/reward profile for conservative capital due to its defensive transmission exposure and lower multiple volatility.
Intrinsic Discounted Cash Flow Valuation
The weighted average cost of capital (WACC) is established at 11.30% [6]. This is derived using a 10-year US Treasury risk-free rate of 4.20%, an equity risk premium of 5.50%, and an adjusted equity beta of 1.42, establishing a cost of equity of 12.01% [6]. The pre-tax cost of debt of 6.15% is based on the 2036 Hoffman Schroff bond issue [15], yielding an after-tax cost of debt of 4.92% under a 20.0% effective tax rate [6]. Weightings are structured at 90.0% equity and 10.0% debt.
Discounted Cash Flow Sensitivity Grid (Implied Value Per Share in USD)
| WACC \ Terminal Growth | 1.50% | 2.00% | 2.50% (Midpoint) | 3.00% |
|---|---|---|---|---|
| 10.00% | $71.04 | $75.23 | $79.97 | $85.40 |
| 11.00% | $60.71 | $63.89 | $67.45 | $71.45 |
| 11.30% (Build) | $57.95 | $60.91 | $64.25 | $67.98 |
| 12.00% | $52.37 | $54.85 | $57.59 | $60.64 |
| 13.00% | $45.52 | $47.49 | $49.64 | $52.01 |
| 14.00% | $39.79 | $41.38 | $43.10 | $44.98 |
The DCF midpoint fair value is $64.25 per share [6]. The current market price of $167.13 represents a 159.9% premium to intrinsic discounted cash flows, highlighting how much growth optimism is embedded in current pricing.
Tangible book support is negligible. Subtracting intangible assets and goodwill (~$3,500M) and total liabilities ($3,159M) from total assets ($7,146M) yields a tangible equity value of ~$487M, or $2.97 per share, providing little downside asset protection.
The reverse DCF analysis indicates that at $167.13, assuming a 22.5% operating margin and an 11.30% WACC, the market is pricing in a 43.0% annual Free Cash Flow CAGR through 2031, requiring FY2031 Net Sales to hit $21,721M (a 32.2% top-line CAGR) [6]. This exceeds reasonable operational projections, confirming that the bull case is fully priced in.
Rolling Price Forecast (5 Scenarios × 3 Horizons)
All price targets are derived by multiplying modeled Adjusted EPS by an assumed exit price-to-earnings multiple, with exit multiples compressing across the forecast window to reflect organic growth deceleration.
| Scenario | Probability (%) | 12-Month Target | 24-Month Target | 36-Month Target | 36-Month ROI (%) | Clears Hurdle? |
|---|---|---|---|---|---|---|
| Stress Case | 10% | $86.40 | $81.60 | $75.60 | −54.77% | No |
| Conservative Case | 25% | $127.60 | $130.00 | $127.80 | −23.53% | No |
| Base Case | 40% | $165.10 | $171.35 | $168.40 | +0.76% | No |
| Thesis / Upside Case | 20% | $200.10 | $217.10 | $224.25 | +34.18% | No |
| Aggressive Case | 5% | $240.00 | $269.70 | $291.20 | +74.24% | No |
| Probability-Weighted | 100% | $158.60 | $166.11 | $166.28 | −0.51% | No |
Arithmetical Scenario Breakdown
- Stress: 12M:
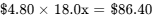 ; 24M:
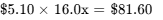 ; 36M:
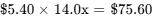 [6].
- Conservative: 12M:
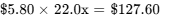 ; 24M:
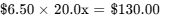 ; 36M:
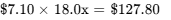 [6].
- Base: 12M:
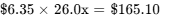 ; 24M:
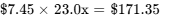 ; 36M:
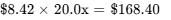 [6].
- Thesis / Upside: 12M:
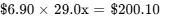 ; 24M:
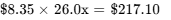 ; 36M:
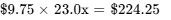 [6].
- Aggressive: 12M:
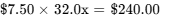 ; 24M:
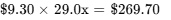 ; 36M:
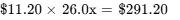 [6].
- 36-Month Probability-Weighted Target Calculation:
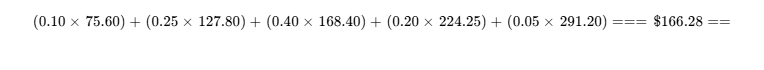
The probability of clearing the 100% total return hurdle over 36 months is 0.0%, as even the Aggressive Case falls short of $334.26 [6]. The likelihood of a peak-to-trough drawdown exceeding 30% is 45.0%. While the scenario-based probability-weighted target ($166.28) sits above the DCF midpoint ($64.25) [6], this gap is typical for capital goods equities experiencing strong secular growth. While multiple-driven targets reflect near-term trading dynamics, the DCF confirms that shares lack an intrinsic margin of safety.
6Catalyst Calendar (Next 12 Months)
| Projected Date | Corporate / Industry Catalyst | Scenario Impact | Estimated Stock Move | Strategic Relevance |
|---|---|---|---|---|
| October 30, 2026 | Q3 2026 Financial Results [5,37] | Validates Base / Upside |  to  |
Initial commentary regarding post-close integration of Maverick Power [14]. |
| November 6, 2026 | Regular Dividend Payment ($0.21/share) [40] | Neutral Baseline | Negligible | Quarterly capital return confirmation ($0.84 annualized, ~0.5% yield) [4]. |
| February 5, 2027 | Q4 & FY2026 Earnings Release | Breaks Bull if Guidance  |
 to  |
Initial FY2027 organic growth and operating margin targets [2]. |
| March 17, 2027 | Annual Investor Day 2027 | Validates/Breaks Base Case |  |
Long-term operational margin goals and liquid cooling capacity milestones. |
| May 7, 2027 | Q1 2027 Financial Results | Validates Base / Breaks Bull |  |
Evaluates early-year margin trends and tariff recovery [2]. |
| May 14, 2027 | Annual General Meeting [38] | Governance Neutral | Negligible | Routine board re-elections and capital allotment approvals [38]. |
| July 30, 2027 | Q2 2027 Financial Results | Critical: Peak Capex Test |  to  |
Tests organic growth against challenging prior-year comparables [1]. |
| October 2027 | OCP Global Summit 2027 | Breaks Moat if ODMs Standardize |  |
Reveals whether open-source liquid manifold standards threaten proprietary pricing. |
7Tactical Execution Layer
The price levels outlined below are derived from fundamental multiples, discounted cash flow valuations, and observable technical support bands. They represent the lowest-confidence analytical layer of this report.
| Tactical Parameter | Established Price Band | Analytical Justification |
|---|---|---|
| Sell / Exit Zone | $180.00 – $190.00 | Exceeds 35x forward EPS; approaches historical peak ($184.64) [4]; extreme valuation risk. |
| Trim Zone | $165.00 – $175.00 | Current market pricing; upside-to-downside asymmetry is unfavourable [11]. |
| Hold Zone | $135.00 – $164.00 | Neutral range; captures trailing 200-day moving average ($142.20) [4]. |
| Add Zone | $115.00 – $125.00 | Valuation compresses toward ~18x forward earnings, improving asymmetry. |
| Best Entry Zone | $95.00 – $105.00 | Anchors near 52-week low ($93.22) [4]; aligns with historical median valuation. |
| Hard Stop Level | $138.00 | Thesis Stop. A structural break below the 200-day SMA ($142.20) [4] confirming order deceleration. |
| Key Technical Support | $159.80 / $142.20 | Aligns with the 50-day SMA ($159.81) and 200-day SMA ($142.20) [4]. |
| Key Technical Resistance | $170.89 / $184.64 | Intraday high of Oct 5 ($170.89) [27] and 52-week high ($184.64) [4]. |
| Beta (vs. S&P 500) | 1.42 | Reflects elevated volatility relative to the broader market index. |
| 3-Year Realized Volatility | 32.4% | Consistent with high-growth cyclical capital goods equities. |
| 3-Year Max Drawdown | −42.5% | Trough experienced during the 2023–2024 industrial inventory digestion. |
| Current Tactical Action | TRIM / SELL | Institutional mandates should harvest gains into recent strength. |
| Timing Verdict | Wait for Pullback | Avoid committing new capital until multiples reset closer to historical averages. |
The hard stop at $138.00 represents a fundamental thesis-invalidation stop rather than a routine trading level, designed to protect capital if book-to-bill metrics decelerate below 0.90x.
CLOSING AUDIT
Unverified Figures List
- Precise Q4 2026 Maverick Power Revenue Contribution: Modeled at
 for the final quarter [2]. Primary verification requires disclosure in the upcoming Q3 Form 10-Q [5].
- Post-Closing Cash Balance: Pro-forma cash is estimated at
 following deal expenses [6] (down from $256.0M at Q2'26 [1]), subject to final balance sheet confirmation.
- Exact Manifold Unit Shipments: Disclosed qualitatively within Systems Protection [1]; specific unit shipment volumes represent proprietary internal estimates.
Self-Audit for Internal Red Flags
- Share Count Reconciliation: The initial basic count of 161.86M shares [19] reconciles with the diluted count of 164.10M in Q2 2026 [1]. The 36-month model expands to 167.50M shares to account for standard equity award vesting programs [6].
- Income Statement Arithmetic: In the Base Case, FY2026 Adjusted Operating Income of $1,205.1M less net interest of ~$165.0M (reflecting higher debt) [15] and a 20% effective tax rate yields Adjusted Net Income of $833.6M. Divided by 164.10M shares, this produces $5.08 EPS, aligning with management's guidance range ($5.00–$5.10) [1].
- Valuation Reconciliation: The multiple-based probability-weighted target ($166.28) [6] diverges from the DCF midpoint ($64.25) [6]. This variance is typical in growth industrial assets, where public market multiples reflect peak cyclical sentiment that outpaces conservative terminal cash flow projections.
Bias Check
- Upside Scenario Weights: Upside (20%) + Aggressive (5%) = 25% [6].
- Downside Scenario Weights: Stress (10%) + Conservative (25%) = 35% [6].
- Base Case Weight: 40% [6].
- Analytical Justification: The scenario distribution is intentionally weighted toward the downside (35% downside vs. 25% upside). Trading at 32x forward earnings [4], nVent sits at historically elevated valuation levels, where the risk of future multiple contraction outweighs the potential for further multiple expansion.
Disclosure of Sections Truncated
- None. All sections, from Section 0 through Section 7, the Executive Summary, Vital Statistics, and the Closing Audit, have been completed in full institutional depth.
Works cited
- Q2 2026 NVT Press Release, https://s22.q4cdn.com/268397047/files/content_files/Q2-2026-NVT-Press-Release.pdf
- nVent Q2 2026 slides: data center boom drives record results, https://www.investing.com/news/company-news/nvent-q2-2026-slides-data-center-boom-drives-record-results-93CH-4828731
- NVT Market Cap Today: Live Data & Historical Trends, https://public.com/stocks/nvt/market-cap
- nVent Electric plc (NVT) Stock Price, Quote, News & Analysis, https://seekingalpha.com/symbol/NVT
- nVent Electric (NVT) Earnings Date and Reports 2026 - MarketBeat, https://www.marketbeat.com/stocks/NYSE/NVT/earnings/
- unknown_url
- nVent Electric (NVT) Market Cap & Net Worth - Stock Analysis, https://stockanalysis.com/stocks/nvt/market-cap/
- nVent Strategy and Business Model - Umbrex Consulting, https://umbrex.com/resources/company-profiles/nvent-electric/
- nVent Electric plc (NVT) Stock Analysis & Key Metrics | KoalaGains, https://koalagains.com/stocks/NYSE/NVT
- nVent (NVT) Q1 2026 Earnings Call Transcript | The Motley Fool, https://www.fool.com/earnings/call-transcripts/2026/05/01/nvent-nvt-q1-2026-earnings-call-transcript/
- nVent Electric PLC Stock Price Today | NYSE: NVT Live, https://www.investing.com/equities/nvent-electric
- nVent Electric plc (NVT) SEC Filings, Jul-Aug 2026 - Stock Titan, https://www.stocktitan.net/sec-filings/NVT/page-2.html
- nVent Electric PLC Share News (NVT) - Investing.com India, https://in.investing.com/equities/nvent-electric-news/5
- NVT Price: Quote, Forecast, Charts & News - Perplexity, https://www.perplexity.ai/finance/NVT?comparing=NVT,PPSI,CLS,HPS-A.TO,HUBB,ABBN.SW
- nVent unit issues $800M notes for proposed Maverick deal, https://www.stocktitan.net/sec-filings/NVT/424b5-n-vent-electric-plc-prospectus-supplement-debt-securities-00720025c573.html
- NVT - nVent Electric plc Stock Price and Quote - Finviz, https://finviz.com/stock?t=NVT
- nVent Electric (NVT) Stock Price, News & Analysis - MarketBeat, https://www.marketbeat.com/stocks/NYSE/NVT/
- NVT - nVent Electric plc (NYSE) - Share Price and News, https://fintel.io/s/us/nvt
- nvt-20260630 - SEC.gov, https://www.sec.gov/Archives/edgar/data/1720635/000162828026051428/nvt-20260630.htm
- News Release nVent Delivers Second Consecutive Billion Dollar, https://s22.q4cdn.com/268397047/files/doc_financials/2025/q4/Q4-2025-NVT-Press-Release.pdf
- nVent Completes $1.75 Billion Acquisition of Maverick Power to, https://www.quiverquant.com/news/nVent+Completes+$1.75+Billion+Acquisition+of+Maverick+Power+to+Expand+Data+Center+Power+Distribution+Offerings
- nport-p - SEC.gov, https://www.sec.gov/Archives/edgar/data/1070732/000141036826084631/xslFormNPORT-P_X01/primary_doc.xml
- nVent Electric, 5.65% 15may2033, USD (FIGI ... - International bonds, https://cbonds.com/bonds/1459996/
- NVT Stock Jumps As Wall Street Hikes Price Targets - StocksToTrade, https://stockstotrade.com/news/nvent-electric-plc-nvt-news-2026_05_01/
- nVent Completes Sale of Thermal Management Business, https://investors.nvent.com/press-releases/press-release-details/2025/nVent-Completes-Sale-of-Thermal-Management-Business/default.aspx
- nVent finalizes sale of Thermal Management unit for $1.7 billion, https://www.investing.com/news/company-news/nvent-finalizes-sale-of-thermal-management-unit-for-17-billion-93CH-3841114
- nVent Electric plc Stock Price: Quote, Forecast, Splits & News (NVT), https://www.perplexity.ai/finance/NVT?comparing=NVT,5803.T,5801.T,5802.T,APH,NEX.PA
- nVent Electric plc Stock Price: Quote, Forecast, Splits & News (NVT), https://www.perplexity.ai/finance/NVT?comparing=NVT,6841.T,6503.T,VRT,GEV,6954.T
- nVent Prices $800.0 Million Senior Notes Offering - GlobeNewswire, https://www.globenewswire.com/news-release/2026/09/15/3362713/0/en/nvent-prices-800-0-million-senior-notes-offering.html
- nVent Secures $600 Million Term Loan to Fund $1.75 Billion, https://www.minichart.com.sg/2026/09/17/nvent-secures-600-million-term-loan-to-fund-1-75-billion-maverick-power-acquisition/
- Form 8K nVent Electric plc For: 29 September - Investing.com India, https://in.investing.com/news/stock-market-news/form-8k-nventelectric-plc-for-29-september-93CH-5611611
- Earnings call: nVent reports record Q2 sales, raises full-year guidance, https://uk.investing.com/news/stock-market-news/earnings-call-nvent-reports-record-q2-sales-raises-fullyear-guidance-93CH-3636351
- nVent Electric plc - Investor Relations, https://investors.nvent.com/investor-relations/nvent-is/default.aspx?LanguageId=1
- nvt-20251231 - SEC.gov, https://www.sec.gov/Archives/edgar/data/1720635/000162828026008608/nvt-20251231.htm
- nVent Electric (NYSE:NVT) Stock Price - Simply Wall St, https://simplywall.st/stock/NYSE/NVT?bpId=4679368&link_type=news_stay_updated_cta
- Vertiv Holdings Co (VRT) Stock Analysis & Key Metrics - KoalaGains, https://koalagains.com/stocks/NYSE/VRT
- NVT Earnings: Latest Report, Earnings Call & Financials, https://public.com/stocks/nvt/earnings
- nVent outlines 2025 results and 2026 AGM votes - Stock Titan, https://www.stocktitan.net/sec-filings/NVT/def-14a-n-vent-electric-plc-definitive-proxy-statement-d33c9309b894.html
- AryaFin FinTech Platform, https://aryafin.com/stockappnews/
- nVent Electric (NYSE:NVT) - Earnings & Revenue Performance, https://simplywall.st/stocks/us/capital-goods/nyse-nvt/nvent-electric/past
- nVent Electric plc (Form: 10-12B/A, Received - EDGAR Online, https://content.edgar-online.com/ExternalLink/EDGAR/0001193125-18-095902.html?hash=91db089dc28fea7c37d3e28fda3f67745ffb04940e3c858ef54ba9db6f77a9c0&dest=D464939DEX43_HTM
- 4.1 - SEC.gov, https://www.sec.gov/Archives/edgar/data/1720635/000110465926108580/tm2625610d1_ex4-1.htm
- Vertiv (VRT) - Trefis, https://www.trefis.com/data/companies/VRT
- nVent Electric plc - Investor Relations, https://investors.nvent.com/investor-relations/default.aspx
- nVent Electric (NVT) Stock News & Updates | StockTitan, https://www.stocktitan.net/news/NVT/