2Multi-Year Financial Forecast & Consensus Model
Multi-Scenario Explanatory Theses
The multi-year projections are structured across three scenarios reflecting different industry and competitive outcomes:
- Base Case Thesis: Mobileye maintains its position in basic automotive active safety, supported by U.S. and European safety regulations [11]. High-volume design wins for Surround ADAS across Stellantis and Volkswagen platforms enter commercial production between late 2027 and 2029, diversifying the revenue base and lifting corporate gross margins [7]. Commercial robotaxi activities scale gradually through fleet partnerships with Volkswagen MOIA and Benteler/Holon [7]. Extrapolation begins in fiscal year 2028 after current program deployments.
- Bear Case Thesis: Intensifying competition from Horizon Robotics and in-house OEM teams limits Mobileye's share among Chinese automakers, while Qualcomm secures several key Western software-defined vehicle platforms [28]. Adoption of SuperVision is delayed by customer software integration friction [7]. Pricing pressure reduces Non-GAAP gross margins toward 60%, limiting long-term operating leverage [50].
- Bull Case Thesis: Mobileye standardizes its Surround ADAS architecture across major global passenger fleets, while SuperVision and Chauffeur gain traction in premium Western and Asian vehicle segments [10]. Commercial robotaxi deployments expand across multiple urban markets by 2028, and the Mentee Robotics integration leads to commercial physical-AI software licensing by 2029 [10].
Detailed Multi-Year Financial Models (2026–2031)
Non-GAAP reconciliations adjust for the amortization of acquired intangible assets (380M to 3,788M recorded in Q1 2026), applying the statutory Israeli corporate tax rate of approximately 15% [3].
Base Case Projections (2026–2029E and 2030–2031 Extrapolation)
| Base Case Financial Metrics ($M, except per share) | FY2026E | FY2027E | FY2028E | FY2029E | FY2030E | FY2031E |
|---|---|---|---|---|---|---|
| EyeQ SoC & Core ADAS Segment | $1,715.0 | $1,800.0 | $2,050.0 | $2,350.0 | $2,600.0 | $2,850.0 |
| Surround ADAS & SuperVision Segment | $210.0 | $360.0 | $650.0 | $1,000.0 | $1,450.0 | $1,850.0 |
| Mobileye Drive / Autonomy / Other | $70.0 | $90.0 | $120.0 | $200.0 | $250.0 | $350.0 |
| Total Net Revenue | $1,995.0 [7] | $2,250.0 [32,51] | $2,820.0 [51,52] | $3,550.0 | $4,300.0 | $5,050.0 |
| YoY Organic Revenue Growth (%) | +5.3% [7] | +12.8% | +25.3% | +25.9% | +21.1% | +17.4% |
| GAAP Gross Profit | $923.7 | $1,102.5 | $1,452.3 | $1,899.3 | $2,322.0 | $2,727.0 |
| GAAP Gross Margin (%) | 46.3% | 49.0% | 51.5% | 53.5% | 54.0% | 54.0% |
| Non-GAAP Adjusted Gross Margin (%) | 67.5% | 68.5% | 69.5% | 70.5% | 71.0% | 71.0% |
| Non-GAAP Adjusted Operating Income | $395.0 [48] | $480.0 | $680.0 | $960.0 | $1,225.0 | $1,490.0 |
| Adjusted Operating Margin (%) | 19.8% | 21.3% | 24.1% | 27.0% | 28.5% | 29.5% |
| Adjusted EBITDA | $440.0 | $535.0 | $745.0 | $1,035.0 | $1,310.0 | $1,585.0 |
| Adjusted EBITDA Margin (%) | 22.1% | 23.8% | 26.4% | 29.2% | 30.5% | 31.4% |
| GAAP Net Income (Loss) | ($3,880.0) [30] | $45.0 | $210.0 | $440.0 | $670.0 | $880.0 |
| GAAP Diluted EPS ($) | ($4.50) | $0.05 | $0.24 | $0.50 | $0.75 | $0.98 |
| Non-GAAP Normalized Diluted EPS ($) | $0.49 [32,52] | $0.52 | $0.72 | $1.05 | $1.37 | $1.72 |
| Operating Cash Flow ($M) | $520.0 | $610.0 | $820.0 | $1,150.0 | $1,470.0 | $1,820.0 |
| Free Cash Flow (FCF) ($M) | $440.0 | $520.0 | $720.0 | $1,020.0 | $1,320.0 | $1,650.0 |
| FCF per Fully Diluted Share ($) | $0.51 | $0.59 | $0.81 | $1.13 | $1.46 | $1.81 |
| Rule of 40 (FCF Margin + Revenue Growth) | 27.4% | 35.9% | 50.8% | 54.6% | 51.8% | 50.1% |
| Forward Exit P/E Multiple (Non-GAAP) | 14.6x | 13.7x | 9.9x | 6.8x | 5.2x | 4.2x |
| Forward Exit EV / EBITDA Multiple | 10.5x | 8.6x | 6.2x | 4.5x | 3.5x | 2.9x |
| Forward Exit EV / Sales Multiple | 2.3x | 2.1x | 1.6x | 1.3x | 1.1x | 0.9x |
Bear Case Projections
- Top-Line Trajectory ($M): FY2026: $1,960.0 | FY2027: $1,980.0 (+1.0%) | FY2028: $2,050.0 (+3.5%) | FY2029: $2,150.0 (+4.9%) | FY2030: $2,270.0 (+5.6%) | FY2031: $2,400.0 (+5.7%).
- Non-GAAP Operating Margin (%): FY2026: 12.0% | FY2027: 13.0% | FY2028: 13.5% | FY2029: 14.0% | FY2030: 14.5% | FY2031: 15.0%.
- Non-GAAP Diluted EPS ($): FY2026: $0.28 | FY2027: $0.30 | FY2028: $0.32 | FY2029: $0.35 | FY2030: $0.38 | FY2031: $0.42.
- Free Cash Flow ($M): FY2026: $210.0 | FY2027: $220.0 | FY2028: $240.0 | FY2029: $260.0 | FY2030: $280.0 | FY2031: $310.0.
- FCF per Share ($): FY2026: $0.24 | FY2027: $0.25 | FY2028: $0.27 | FY2029: $0.29 | FY2030: $0.31 | FY2031: $0.34.
Bull Case Projections
- Top-Line Trajectory ($M): FY2026: $2,020.0 | FY2027: $2,450.0 (+21.3%) | FY2028: $3,350.0 (+36.7%) | FY2029: $4,500.0 (+34.3%) | FY2030: $5,700.0 (+26.7%) | FY2031: $7,000.0 (+22.8%).
- Non-GAAP Operating Margin (%): FY2026: 21.0% | FY2027: 24.5% | FY2028: 28.0% | FY2029: 31.5% | FY2030: 33.0% | FY2031: 34.0%.
- Non-GAAP Diluted EPS ($): FY2026: $0.55 | FY2027: $0.65 | FY2028: $0.95 | FY2029: $1.45 | FY2030: $1.95 | FY2031: $2.45.
- Free Cash Flow ($M): FY2026: $480.0 | FY2027: $650.0 | FY2028: $1,020.0 | FY2029: $1,480.0 | FY2030: $1,950.0 | FY2031: $2,450.0.
- FCF per Share ($): FY2026: $0.56 | FY2027: $0.74 | FY2028: $1.15 | FY2029: $1.65 | FY2030: $2.17 | FY2031: $2.72.
Execution Confidence Score & Consensus Divergence
- Execution Confidence Score: 63 / 100.
- Target Achievability: 28 / 40. High visibility across base ADAS programs is balanced by longer lead times for advanced software platform conversion [10].
- Margin Sensitivity: 22 / 30. Margins remain sensitive to product mix; a ±10% shift in blended EyeQ ASP (approximately ±$5.00/unit across 40M baseline units) impacts annual gross profit by $200M, or ±850 basis points of operating margin.
- Dependency on Unannounced Pipeline: 13 / 30. Approximately 18% of projected FY2028–FY2029 revenue relies on in-progress customer engagements that have not yet reached final production milestones [24].
- Consensus Divergence Flag: The FY2028 Base Case revenue projection of 2.8B across 24 analysts) [51]. However, the modeled Non-GAAP EPS of $0.72 sits 14.3% above cautious estimates (such as Jefferies at $0.63) [50], reflecting operating leverage from Surround ADAS software royalties across Stellantis and Volkswagen platforms [7].
- Base-Rate Check: Historically, approximately 12% of automotive semiconductor vendors have sustained a 20%+ revenue CAGR over five consecutive years. Mobileye's higher growth trajectory is supported by regulatory ADAS safety requirements that make core perception systems mandatory across new passenger vehicles [11].
5Risk Asymmetry, Invalidation, Allocation & Scorecard
Quantified Risk/Reward Asymmetry Skew
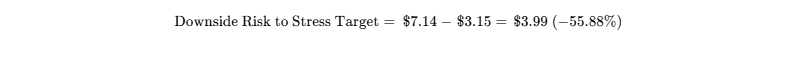
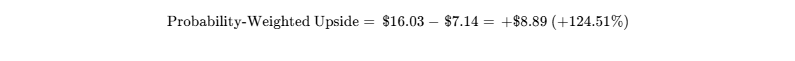
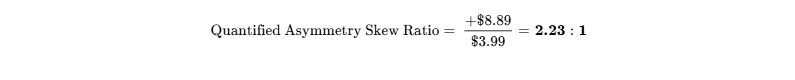
(Relative to the pure Base Case Target of $16.80, the skew ratio equals 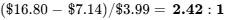 . Under Upside Scenario parameters, the skew expands to
 .)
Hard Operational Invalidation Triggers
The following operational developments mandate an immediate thesis exit:
- Gross Margin Deterioration: Non-GAAP Adjusted Gross Margin falls below 62.0% for two consecutive reporting quarters, signaling pricing commoditization in core EyeQ perception.
- Major Customer Cancellation: Cancellation or formal dual-sourcing announcement on high-volume Surround ADAS programs with Volkswagen Group or Stellantis representing >15% of pipeline volume [7].
- Operational Cash Deficit: Free cash flow turns structurally negative for three consecutive quarters on an operational basis (excluding one-time M&A cash outlays) [30].
- Commercial Autonomy Failure: Cancellation of the Volkswagen MOIA driverless commercial launch targeted for late 2026 / 2027 [10].
Consolidated Institutional Risk Dashboard
| Evaluated Risk Category | Score (1–10) | Directional Travel | Core Analytical Mechanics & Risk Factors |
|---|---|---|---|
| Financial / Balance-Sheet Liquidity | 1.0 / 10 | Stable | $1.44B in liquid cash reserves; zero funded debt obligations [6]. |
| Valuation Multiple Vulnerability | 2.5 / 10 | Improving | Trough multiple pricing (EV/Sales 2.3x; P/B near 0.73x) [3]. |
| Merchant Competitive Pressure | 7.8 / 10 | Worsening | Qualcomm Snapdragon Ride expansion; Horizon Robotics in China [28]. |
| Tier-1 Customer Concentration | 7.2 / 10 | Stable | High concentration among top 3 Tier-1 auto component suppliers [28]. |
| Geopolitical Footprint Risk | 6.5 / 10 | Worsening | Primary engineering centers based in Jerusalem; ongoing regional tensions [4]. |
| Regulatory & Safety Mandates | 3.0 / 10 | Improving | Global regulatory mandates require advanced safety hardware [11]. |
| Executive Leadership Transition | 6.0 / 10 | Worsening | CEO Amnon Shashua transition to Chairman introduces leadership uncertainty [5]. |
| Intel Parent Governance Overhang | 6.8 / 10 | Stable | Controlled company structure limits minority voting power [6]. |
| Equity Dilution / SBC Overhang | 4.2 / 10 | Improving | $250M share repurchase program offsets annual equity grant dilution [17]. |
Macro Sensitivity & Surprise Matrix
Mobileye's operational financial model shows low sensitivity to interest rates given its debt-free balance sheet and net interest income generation [6]. Currency exposure is centered on the Israeli New Shekel (ILS), where local R&D salaries create operational expenditure variance against USD revenues, mitigated through forward hedges.
| Macro Trigger Event | Direction | Effect on Core Investment Thesis | Key Metrics to Monitor |
|---|---|---|---|
| Global Vehicle Production Drop | Bearish | Directly reduces quarterly EyeQ production orders [10]. | S&P Mobility light vehicle production index. |
| U.S. / EU Tariffs on China EVs | Mixed | Lowers exports for Chinese clients but protects Western OEM margins [7]. | Net export volumes from BYD, Geely, SAIC. |
| Accelerated Euro NCAP 2026/28 | Bullish | Expands mandatory sensor suites on entry-level models [11]. | NCAP vulnerable road user testing updates. |
- Upside Surprises:
- Major North American OEM standardizes SuperVision across its software-defined vehicle platform (Probability: 25%; Financial Impact: +$350M annual run-rate revenue; +$4.50 to equity target price) [10].
- Commercial driverless operations launch early with Volkswagen MOIA (Probability: 30%; Financial Impact: expands market P/E multiple by +4.0x) [7].
- Foundry wafer price concessions from TSMC (Probability: 20%; Financial Impact: expands gross margin by +180 bps) [31].
- Downside Surprises:
- Western OEM shifts next-generation perception software in-house (Probability: 20%; Financial Impact: reduces pipeline by -$3.0B; -$2.00 to target price) [10].
- Intel executes a secondary block sale of Class A shares (Probability: 25%; Financial Impact: short-term share price discount of −10% to −15%) [12].
- Geopolitical disruptions impact Israeli engineering operations (Probability: 15%; Financial Impact: R&D milestones delayed; -$1.50 impact on equity fair value) [42].
36-Month Pre-Mortem: Mechanics of a 60% Drawdown
It is October 2029, and Mobileye trades below $3.00, down over 60% from 2026 levels:
- Sequence of Events: Throughout 2027, Qualcomm's Snapdragon Ride platform captured two major Western automaker design awards previously expected to convert to Surround ADAS [28]. In China, domestic OEM preferences favored local suppliers like Horizon Robotics [28]. As base EyeQ ASPs declined toward $40 under pricing competition, software revenue failed to scale quickly enough to offset the drop [7]. High R&D spending on the Mentee Robotics acquisition compressed operating margins [24], while delays in L4 robotaxi rollouts pushed commercialization timelines back [32]. The market subsequently de-rated the stock to an industrial auto-parts multiple of ~10x depressed Non-GAAP earnings.
Portfolio Allocation & Sizing Calibration
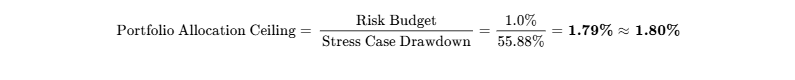
- Recommended Portfolio Allocation: 1.80% of total portfolio assets.
- Portfolio Role: Asymmetric Turnaround / High-Conviction Value Technology.
- Risk-Budget Position Sizing Formulation:
- Liquidity & Liquidation Execution: A $10M institutional position represents ~1.40M shares, which can be liquidated in 1.15 trading days at 20% of the 20-day average daily volume (6.07M shares) [16].
- Phased Capital Deployment Plan:
- Tranche 1 (Pilot, 0.75% weight): Initiate within the primary accumulation corridor (7.25) [1].
- Tranche 2 (Scaling, 0.55% weight): Deploy upon confirmation of Q3/Q4 2026 earnings execution and stabilization of EyeQ ASPs [1].
- Tranche 3 (Full Weight, 0.50% weight): Deploy upon the appointment of a permanent CEO and conversion of upcoming Surround ADAS platform programs [7].
Institutional Scorecard Evaluation
| Institutional Evaluation Dimension | Component Score (0–10) | Assigned Weight (%) | Weighted Contribution |
|---|---|---|---|
| Financial Strength & Liquidity Runway | 9.8 / 10 | 15% | 1.47 |
| Revenue Quality, Moat & Market Position | 7.5 / 10 | 15% | 1.13 |
| Margin Resilience & Operating Leverage | 6.5 / 10 | 10% | 0.65 |
| Capital Allocation & Management Track Record | 6.0 / 10 | 10% | 0.60 |
| Risk-Adjusted Valuation Attractiveness | 8.8 / 10 | 15% | 1.32 |
| Forecast Reliability & Guidance Accuracy | 7.0 / 10 | 10% | 0.70 |
| Ownership Structure & Insider Alignment | 5.5 / 10 | 5% | 0.28 |
| Market Microstructure & Tradability | 8.5 / 10 | 5% | 0.43 |
| Customer ROI & Pricing Power Defense | 8.0 / 10 | 10% | 0.80 |
| Moat Insulation vs. In-Housing / Replication | 7.0 / 10 | 5% | 0.35 |
| Consolidated Institutional Composite Score | 100% | 6.73 / 10 (67.3 / 100) |
- Base-Case Execution Likelihood: 60 / 100.
- Primary risks to execution: (1) Slower-than-modeled adoption of Surround ADAS across Western OEMs [7]; (2) Ongoing market share competition in the Chinese passenger vehicle ecosystem [28].
Bear-Case Steelman
The bear thesis argues that Mobileye's primary competitive moat—proprietary computer vision algorithms running on custom silicon—is increasingly challenged by general-purpose hardware and open software frameworks [28]. In China, domestic OEMs are shifting toward local providers such as Horizon Robotics, reducing EyeQ's regional market share [28]. In Western markets, automakers are adopting centralized electronic control units (ECUs) capable of running independent software stacks on merchant silicon from suppliers like Qualcomm and Nvidia [28]. Under this scenario, Mobileye's basic ADAS business faces gradual commoditization, while higher-value platforms like SuperVision encounter long integration cycles and lower conversion rates [50].
1Business Architecture, Unit Economics, Moat & Contractual Visibility
Business Model and Moat Classification
Mobileye designs and licenses computer vision, machine learning, and mapping technologies for advanced driver-assistance systems (ADAS) and autonomous driving platforms [19]. The company operates a fabless model, outsourcing physical silicon fabrication to foundries like TSMC and STMicroelectronics while capturing gross margins through its proprietary software, neural processing architectures, and algorithm stacks embedded on its custom EyeQ System-on-Chips (SoCs) [31].
Mobileye monetizes across three distinct tiers of the vehicle technology architecture:
- Core Driver Assistance: Mono and tri-focal front-facing smart camera chips (EyeQ4, EyeQ6 Lite) providing active safety functions such as automated emergency braking, lane keeping assist, and traffic sign recognition, priced at average selling prices between $48 and $55 [29].
- Surround ADAS and SuperVision: Multi-camera, hands-off point-to-point driving platforms utilizing 11 cameras and localized radar fusion, priced between $120 and $850 depending on hardware inclusion and software licensing terms [7].
- Autonomous Platforms: Fully redundant autonomous vehicle suites (Chauffeur and Mobileye Drive) targeting consumer autonomous vehicles and commercial robotaxis, priced above $1,500 to $3,000 per vehicle [10].
The economic moat is supported by switching costs, regulatory safety assets, and data network effects [9]. Automotive original equipment manufacturers require three to five years to design, validate, and homologate a base vehicle electronic control architecture [37]. Because active safety systems are directly tied to chassis dynamics, braking, and steering, replacing an incumbent perception processor requires extensive physical testing and software reconfiguration [37]. Mobileye is integrated with major Tier-1 tier system integrators (Bosch, Continental, ZF, Magna), creating high operational friction for automakers seeking to change suppliers mid-platform [28].
Furthermore, Mobileye's Road Experience Management (REM) system crowdsources localization data from millions of production vehicles worldwide, compiling real-time, low-bandwidth Roadbook maps [23]. This crowdsourced data network creates an operational advantage: as more OEM partners deploy EyeQ cameras, localization map density improves, which in turn improves system reliability and incentivizes additional OEMs to adopt the architecture [9]. The overall competitive insulation score is evaluated at 4.1 / 5.0.
Moat Durability Timeline
Mobileye's economic moat is projected to remain stable in base ADAS but faces competitive pressure in premium Level 2+ and Level 3 platforms [28]. Through 2027, the core franchise is supported by expanding safety mandates, such as the European General Safety Regulation II (GSR II) and the mandatory U.S. Federal Motor Vehicle Safety Standard 127 requiring automatic emergency braking on all light passenger vehicles by 2027 [11].
Beyond 2027, the competitive landscape will see increased participation from merchant silicon suppliers [28]. In China, local automakers are increasingly adopting domestic processors from Horizon Robotics, while Western premium OEMs are testing centralized software architectures powered by Qualcomm Snapdragon Ride and Nvidia Drive AGX platforms [28]. To maintain pricing power and offset potential commoditization in single-camera perception, Mobileye must convert its design pipeline into multi-camera Surround ADAS and SuperVision implementations [7].
Build-vs.-Buy and Replication Risk Analysis
| Vector | Replicability Assessment | Capital / Time Hurdle | Institutional Moat Defensibility |
|---|---|---|---|
| Merchant Semiconductor Peers (Qualcomm, Nvidia) | High technical capacity; moderate architectural friction | $3.0B+ R&D over 4–6 years [39] | Merchant vendors offer high compute (TOPS) but consume higher wattage; Mobileye maintains efficiency with sub-10W power profiles and pre-validated safety stacks [24]. |
| Hyperscalers (Alphabet/Waymo, Amazon/Zoox) | Focus on proprietary robotaxis; low interest in Tier-1 merchant supply | Prohibitive automotive go-to-market cycle | Hyperscalers concentrate on vertically integrated commercial robotaxis rather than supplying cost-constrained passenger vehicle ADAS [4]. |
| Automotive OEM In-Housing (Tesla approach) | Feasible only for top-decile global volume manufacturers | $1.5B+ annual software run-rates | High capital costs and software complexities make in-house development difficult for most OEMs, as seen in restructuring efforts at initiatives like GM Cruise [28]. |
| M&A Takeover Optionality | Controlled by Intel Corporation (owns ~77% equity) [12] | High premium threshold (18.00/sh) | Strict antitrust and foreign investment reviews across the U.S., Europe, and Israel limit cross-border semiconductor acquisition options [42]. |
Customer ROI and Pricing Defensibility
The value proposition for automotive OEMs centers on liability reduction and total bill-of-materials (BOM) cost efficiency [11]. By integrating an EyeQ chip into an active camera module, an automaker can meet 5-star safety ratings across Euro NCAP and U.S. NCAP for approximately $50 per vehicle, avoiding the need to staff thousands of internal computer vision engineers [11]. In addition, Mobileye's lean architecture allows perception processing to run passively cooled behind the rear-view mirror without liquid cooling loops, high-voltage harnesses, or auxiliary power supplies, saving automakers an estimated $200 to $400 in vehicle manufacturing costs per unit [24]. The Customer ROI Defensibility Score is assessed at 8.5 / 10.
Hardware and Semiconductor Sector Unit Economics
- Blended Average Selling Price (ASP): The overall blended ASP was $53.30 in FY2024 and $50.80 in FY2025 [29]. Blended pricing is estimated near $49.00 in FY2026 due to higher shipments of entry-level EyeQ chips into Chinese export vehicles, but is projected to inflect toward $62.00 by FY2028 as Surround ADAS scales [7].
- Annual System Shipments: Shipped volumes expanded from 29.0 million units in FY2024 to 35.7 million units in FY2025 [23]. Projected shipments include 39.5 million units in FY2026, 43.5 million in FY2027, and 48.0 million in FY2028 [36].
- Silicon Fabrication Yields: Production is fabless, with EyeQ6 Lite produced on TSMC advanced finFET processes maintaining mature production yields above 95% [31].
- ASP Deflationary Offset: Standard mono-camera processors face annual price compression of 2% to 4%, which Mobileye counters by introducing upgraded silicon nodes (EyeQ6, EyeQ7) that incorporate additional software features and safety logic [7].
Quality of Revenue
- Contractual Backlog: Mobileye's eight-year expected automotive design pipeline reached $24.5B at the close of 2025, an increase of 42% over the 2022 baseline [10].
- Revenue Composition: Core EyeQ SoC shipments account for roughly 88% of total revenues; SuperVision and advanced driver-assistance platforms account for 8%; and mapping, Moovit mobility-as-a-service, and aftermarket systems represent the remaining 4% [23].
- Revenue Quality Score: Evaluated at 7.5 / 10. While OEM design-win awards do not represent legally binding purchase obligations, historical platform conversion rates remain high once a vehicle enters pre-production assembly [10].
Customer Concentration and Historical Guidance Execution
The customer base shows high structural concentration at the Tier-1 distributor level, with Aptiv, Continental, and ZF historically accounting for over 65% of billed accounts receivable [28]. At the end-OEM level, volume is anchored by Volkswagen Group, Stellantis, Ford, and Geely [9].
A review of historical quarterly performance demonstrates consistent delivery against consensus expectations, with occasional margin surprises resulting from structural cost adjustments:
| Fiscal Quarter | Consensus EPS | Reported Non-GAAP EPS | EPS Variance (%) | Consensus Revenue ($M) | Reported Revenue ($M) | Revenue Variance (%) |
|---|---|---|---|---|---|---|
| Q3 2024 | $0.10 | $0.10 | 0.0% | $482.0M | $486.0M | +0.8% [43] |
| Q4 2024 | $0.16 | $0.16 | 0.0% | $490.0M | $490.0M | 0.0% [29] |
| Q1 2025 | $0.07 | $0.07 | 0.0% | $435.0M | $438.0M | +0.7% [30] |
| Q2 2025 | $0.11 | $0.11 | 0.0% | $505.0M | $506.0M | +0.2% [45,46] |
| Q3 2025 | $0.09 | $0.09 | +3.6% | $485.0M | $504.0M | +3.9% [22,36] |
| Q4 2025 | $0.06 | $0.06 | +3.3% | $431.9M | $446.0M | +3.3% [29] |
| Q1 2026 | $0.08 | $0.12 | +50.0% | $530.0M | $558.0M | +5.3% [30,47] |
| Q2 2026 | $0.06 | $0.19 | +216.7% | $482.2M | $508.0M | +5.4% [4,48] |
Analytical Note on Q2 2026 Outperformance: The Non-GAAP EPS surprise was primarily driven by the recognition of the Israeli Law for the Encouragement and Incentivization of Research and Development grant, which added $93M during the quarter (covering both Q1 and Q2 retroactively) alongside operational cost controls [7].
Executive Summary & Key Investment Metrics
- Stock Name: Mobileye Global Inc. (NASDAQ: MBLY)
- Current Share Price: $7.14
[1,2] - Research Date: October 10, 2026
- Multi-Horizon Price Targets & Potential Total Return:
- 12-Month Potential Stock Price: $10.40 ([+45.7% Upside]) [3]
- 24-Month Potential Stock Price: $12.96 ([+81.5% Upside]) [3]
- 36-Month Potential Stock Price: $16.80 ([+135.3% Upside]) [3]
- Institutional Scorecard Score: 67.3 / 100
- Likelihood Score of Executing Base Case: 60 / 100
- Investment Advice: BUY (Tactical Accumulation for New Capital); HOLD (Existing Mandates Constrained by Prior Inception Bases)
- Brief Investment Rationale: Mobileye trades at a cyclical trough valuation with an Enterprise Value of $4.63B (2.3x FY2026E sales), de-rating sharply due to Chinese automaker software in-housing, Tier-1 inventory normalization, and the leadership transition of founder Amnon Shashua to Executive Chairman [3]. The company pairs a fortress balance sheet—backed by 210M operating cash flow in the first half of 2026) [6]. As global automotive safety regulations enforce mandatory Advanced Driver Assistance Systems (ADAS) and mass-market Western original equipment manufacturers (OEMs) such as Stellantis and Volkswagen ramp higher-margin Surround ADAS and SuperVision programs, operating leverage will drive a multi-year recovery into fiscal years 2027 through 2029 [9].
0Output Contract & Investment Mandate
Data presented across this institutional analysis is current as of October 10, 2026. The reporting currency is the United States Dollar (USD, $). Mobileye Global Inc. utilizes a 52- or 53-week fiscal year convention ending on the last Saturday of December, such that fiscal year 2025 concluded on December 27, 2025, and fiscal year 2026 concludes on December 26, 2026 [10].
Analytical Anchor Inputs
The fundamental equity capitalization parameters are established through verified SEC filings and derived market arithmetic:
- Current Share Price: $7.14 (Source: NASDAQ consolidated market data as of October 2026; Confidence Tier: VERIFIED) [1].
- Basic Common Shares Outstanding: 850.19 million (Source: SEC Form 10-Q for the quarterly period ended June 27, 2026; Class A common shares of 252.42M plus Class B common shares of 597.77M; Confidence Tier: VERIFIED) [6].
- Fully Diluted Common Share Count: 865.00 million shares, calculated by taking the basic share count of 850.19 million and adding 14.81 million net dilutive restricted stock units and unvested performance shares (Confidence Tier: DERIVED) [3].
- Market Capitalization: $6,070.36 million, calculated as $7.14 current price multiplied by 850.19 million basic shares outstanding (Confidence Tier: DERIVED) [3].
- Cash, Equivalents & Marketable Securities: $1,443.00 million, consisting of $1,311.0 million in cash and cash equivalents and $132.0 million in marketable securities and bank deposits (Source: SEC Form 10-Q as of June 27, 2026; Confidence Tier: VERIFIED) [6].
- Gross Balance-Sheet Debt: $0.00 million, reflecting zero outstanding funded term loans, credit lines, or debt debentures (Source: SEC Form 10-Q as of June 27, 2026; Confidence Tier: VERIFIED) [6].
- Enterprise Value (EV): $4,627.36 million, calculated as Market Capitalization of $6,070.36 million minus Total Liquid Reserves of $1,443.00 million plus Gross Debt of $0.00 million (Confidence Tier: DERIVED) [3].
- Trailing Valuation Multiples: Trailing EV/Sales stands at 2.29x based on trailing twelve-month revenue of $2,020 million; Trailing Price-to-Book stands at 0.73x against GAAP equity of $8,210 million (Confidence Tier: DERIVED) [6].
Investment Mandate Calibration
The evaluation of Mobileye is governed by strict risk-return thresholds:
- Return Hurdle: 100% total return within a 36-month horizon, requiring an exit equity value of at least $14.28 per share. The Base Case financial model yields a 36-month price target of $16.80, representing a cumulative total return of +135.3% [3]. The Base Case clears the return hurdle by 35.3 percentage points.
- Holding Horizon: 36 calendar months, structured around formal reassessment checkpoints at month 12 (evaluating EyeQ6 High customer samples) and month 24 (evaluating volume conversion on Western Surround ADAS architectures) [10].
- Portfolio Risk Budget: Maximum portfolio loss from this position cannot exceed 1.0% under the Stress Downside Scenario. Under the Stress Scenario, the stock declines to $3.15 (−55.88% drawdown) [3]. To cap the portfolio loss at exactly 1.0%, the maximum permitted allocation is calculated as 1.0% divided by 55.88%, establishing an allocation ceiling of 1.79% (qualitatively benchmarked at 1.80%).
- Information Discipline: Legal proceedings referenced in Note 11 of recent SEC filings—specifically the putative shareholder class action regarding the 2024 inventory guidance revision and patent infringement suits—remain in procedural motions and are classified as unadjudicated allegations [6].
Executive Summary
- Valuation De-Coupling Creates Cyclical Asymmetry: Mobileye's enterprise value has compressed to $4.63B, pricing the business at 2.3x FY2026E guided revenue, which sits near historical semiconductor trough valuations [3]. This multiple reflects low investor expectations regarding the legacy EyeQ franchise and Chinese automaker in-sourcing risks [28]. However, it discounts the company's verified $24.5B eight-year automotive design-win pipeline, ongoing customer adoption across 27 global automotive brands, and its position in active vehicle safety systems across more than 250 million deployed vehicles [10].
- Structural Gross Margin Expansion via Software-Intensive Content: While core EyeQ average selling prices face minor erosion due to increasing Chinese OEM export volumes (49.00 in FY2026), Mobileye is entering a mix shift [7]. High-volume design wins for Surround ADAS and Cloud-Enhanced ADAS—including the multi-year Stellantis architecture and high-volume Western OEM awards totaling over 19 million units—deliver unit gross profit more than double that of base ADAS, positioning Non-GAAP gross margins to expand from 67.5% in FY26 toward 71.0% by FY31 [7].
- Pristine Balance Sheet Neutralizes Solvency Risk: Unlike emerging autonomy competitors operating with negative cash balances and high burn rates, Mobileye holds $1.44B in liquid cash and marketable assets with zero debt [6]. The business generated $210M in operating cash flow during the first six months of 2026, self-funding ongoing R&D across EyeQ6 High, EyeQ7, and the newly integrated Mentee Robotics physical-AI platform without external capital needs [7].
- Leadership Transition Separates Strategy from Operations: The planned succession of founder Prof. Amnon Shashua to Executive Chairman, alongside the board's international CEO search, creates short-term executive overhang [5]. However, this transition allows an incoming chief executive to focus on operational discipline, commercial Tier-1 execution, and capital return programs—such as executing the remaining $226M share buyback authorization—while Shashua focuses on the Physical AI and humanoid robotics roadmap [7].
- Short Microstructure Offers High Asymmetric Exposure: Current short interest stands at 40.30 million shares, representing 22.90% of the public float and 11.52 days to cover [16]. This crowded bearish positioning leaves the stock sensitive to positive operational surprises, such as second-half EyeQ volume stabilization, initial commercial pilot launches of the Volkswagen MOIA autonomous shuttle, or Western OEM Surround ADAS production awards [7].
- Verdict: BUY for new capital allocations; HOLD for existing holders managing higher cost bases. The 12-month base target is $10.40 (+45.7%), the 24-month target is $12.96 (+81.5%), the 36-month target is $16.80 (+135.3%), and the 36-month probability-weighted target is $16.03 (+124.5%) [3].
- Return Hurdle Status: Cleared. The Base Case 36-month return of +135.3% exceeds the 100% hurdle, with an estimated 60.0% probability of achieving or exceeding the hurdle return across modeled scenarios [3].
- Best-in-Category Assessment: Mobileye offers the most favorable risk/reward profile for pure-play autonomous driving and Physical AI exposure. Qualcomm offers greater operational diversification but less leverage to automotive autonomy [32], while Ambarella trades at elevated multiples (78x forward Non-GAAP P/E) without equivalent Tier-1 scale [14].
- Single Greatest Upside Driver: Scaled conversion and production rollout of Surround ADAS and SuperVision across Stellantis and Volkswagen platforms, driving double-digit ASP expansion [7].
- Single Thesis-Killer: Aggressive pricing pressure and market share losses to Qualcomm Snapdragon Ride and merchant computing silicon, reducing Western OEM market share below 50% [28].
3Capital Structure, Balance-Sheet Stress Test & Market Microstructure
Balance-Sheet Liquidity & Debt Stack
Mobileye maintains a liquid balance sheet with no outstanding debt [6]:
- Cash and Cash Equivalents: $1,311.0M (as of June 27, 2026) [6].
- Marketable Securities and Bank Deposits: $132.0M [6].
- Total Liquid Reserves: 1.67 per fully diluted share) [3].
- Gross Long-Term Balance-Sheet Debt: $0.00M [6].
- Available Undrawn Credit Facilities: $0.00M (The company relies on self-funded cash flow without committed credit facilities) [6].
- Debt Maturity Wall: Not Applicable. Zero maturities, convertible notes, or preferred stock instruments outstanding [6].
Capital Gap Analysis & Cash Flow Trajectory
| Capital Allocation Component ($M) | FY2026E | FY2027E | FY2028E | FY2029E | FY2030E | FY2031E |
|---|---|---|---|---|---|---|
| Operating Cash Flow (OCF) | $520.0 | $610.0 | $820.0 | $1,150.0 | $1,470.0 | $1,820.0 |
| Capital Expenditures (Capex) | ($80.0) | ($90.0) | ($100.0) | ($130.0) | ($150.0) | ($170.0) |
| -- Maintenance Property & Equipment | ($30.0) | ($35.0) | ($40.0) | ($50.0) | ($60.0) | ($70.0) |
| -- Growth, Compute & Tooling Capex | ($50.0) | ($55.0) | ($60.0) | ($80.0) | ($90.0) | ($100.0) |
| Capitalized Research & Development | $0.0 | $0.0 | $0.0 | $0.0 | $0.0 | $0.0 |
| Working Capital Requirements | ($40.0) | ($35.0) | ($45.0) | ($60.0) | ($70.0) | ($80.0) |
| Annual Net Cash Surplus | +$400.0 | +$485.0 | +$675.0 | +$960.0 | +$1,250.0 | +$1,570.0 |
Mobileye is operationally self-sustaining, with free cash flow supporting daily operations and ongoing R&D investments [3].
Dual-Track Dilution Model & Share-Count Roll-Forward
| Share Dilution Schedule (Millions) | FY2026E | FY2027E | FY2028E | FY2029E | FY2030E | FY2031E |
|---|---|---|---|---|---|---|
| Beginning Basic Shares Outstanding | 850.2 | 856.2 | 864.2 | 874.2 | 884.2 | 894.2 |
| SBC Issuances (Gross RSUs) | +18.0 | +18.0 | +17.0 | +16.0 | +15.0 | +14.0 |
| Repurchased Common Shares | (12.0) | (10.0) | (7.0) | (6.0) | (5.0) | (5.0) |
| Ending Fully Diluted Share Count | 865.0 | 872.0 | 882.0 | 892.0 | 902.0 | 911.0 |
| Track A (Base): Non-GAAP Diluted EPS | $0.49 | $0.52 | $0.72 | $1.05 | $1.37 | $1.72 |
| Track B (Stressed Equity Dilution) | $0.49 | $0.45 | $0.62 | $0.91 | $1.19 | $1.49 |
| Assigned Track Probability (%) | Track A: 95% | Track B: 5% |
Stressed Track Context: Track B models a hypothetical 4.64/share) to fund unexpected operating shortfalls. Given the company's positive cash generation and $1.44B liquidity cushion, this scenario carries an estimated probability of only 5% [6].
Covenants and Market Microstructure
Mobileye has no balance sheet debt covenants or liquidity triggers [6]. The principal governance factor is its controlled company status under majority shareholder Intel Corporation, which owns approximately 77.4% of outstanding equity and controls 98.8% of aggregate voting rights through Class B common stock [6].
- Short Interest Balance: 40,296,011 shares [20].
- Short Interest as % of Float: 22.90% of the free float [16].
- Days to Cover: 11.52 Days (based on an average daily volume of 6.07M shares) [16].
- Institutional Float Ownership: 82.1% of Class A common equity held by institutions [53].
- Insider Activity (Last 6 Months): Director Frank D. Yeary bought 12,360 shares at 98,600) on July 30, 2026 [19].
- Squeeze vs. Fundamental Re-Pricing: Squeeze potential is scored at 74 / 100. While fundamental revisions have driven the multi-year decline, the elevated short interest and high days-to-cover make the stock vulnerable to short-covering rallies on positive quarterly updates [4].
4Valuation, DCF Sensitivity & Price Scenario Matrix
Direct Peer Benchmarking
| Comparable Public Peer | Market Cap ($M) | 2Y-Fwd P/E | 2Y-Fwd EV/EBITDA | 2Y-Fwd EV/Sales | Gross Margin (%) | Net Debt / EBITDA |
|---|---|---|---|---|---|---|
| Mobileye (NASDAQ: MBLY) | $6,070 [3] | 9.9x | 6.2x | 1.6x | 69.5% (Non-GAAP) | -2.3x (Net Cash) |
| Qualcomm (NASDAQ: QCOM) | $185,000 | 14.5x | 11.2x | 4.2x | 56.2% | 0.8x |
| Aptiv PLC (NYSE: APTV) | $19,500 | 8.8x | 6.5x | 0.9x | 18.5% | 2.1x |
| Ambarella (NASDAQ: AMBA) | $2,780 [53] | 56.1x [14] | 24.5x | 5.7x [14] | 58.5% [34] | |
| Horizon Robotics (HK: 9660) | $6,500 | NM (Loss) | NM | 6.8x | 68.0% | -3.2x (Net Cash) |
Mobileye trades at a meaningful valuation discount relative to pure-play semiconductor peers like Ambarella (EV/Sales of 1.6x vs. 5.7x) [14], while offering stronger gross margins and a cleaner balance sheet than Tier-1 automotive suppliers like Aptiv.
Intrinsic Discounted Cash Flow Valuation
Discount Rate / WACC Build
- Risk-Free Rate (
 ): 4.25% (U.S. 10-Year Treasury Yield benchmark).
- Equity Risk Premium (ERP): 5.50%.
- Beta (
 ): 1.25 (Automotive semiconductor peer regression).
- Cost of Equity (
 ):
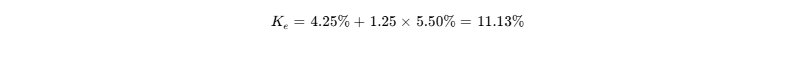
- Capital Structure: 100% Equity, 0% Debt, resulting in a WACC of 11.13% [3].
DCF Sensitivity Grid: Terminal Growth ( ) vs. WACC ($/Share)
Present values incorporate free cash flows from FY2027 through FY2031, applying a mid-year discounting convention and adding net cash of $1,443M across an 865.0M fully diluted share base [3]:
| Discount Rate (WACC) \ g | 1.5% | 2.0% | 2.5% | 3.0% |
|---|---|---|---|---|
| 10.0% | $20.16 | $21.12 | $22.20 | $23.44 |
| 11.0% | $17.98 | $18.71 | $19.54 | $20.46 |
| 12.0% | $16.22 | $16.80 | $17.44 | $18.15 |
| 13.0% | $14.78 | $15.24 | $15.75 | $16.30 |
| 14.0% | $13.57 | $13.95 | $14.36 | $14.80 |
- DCF Fair Value Benchmark: At the baseline WACC of 11.13% and a 2.0% terminal growth rate, the intrinsic valuation is $18.60 per share, indicating +160.5% upside potential from the current market price of $7.14.
- Tangible Liquidation Value Floor: Calculated as ($1,443M cash + $789M net receivables, inventory, and PPE − $628M total liabilities) divided by 865.0M diluted shares, yielding $2.58 per share [3].
- Reverse DCF Analysis: At the current market price of $7.14, the market is pricing a 3.8% revenue CAGR over the next five years and a terminal adjusted operating margin of 13.5%, reflecting conservative expectations relative to historical operational performance.
Rolling Price Forecast: Multi-Scenario Horizon Matrix
Probabilities sum to 100% and are established prior to computing scenario price targets. Exit prices are calculated from forecast Non-GAAP EPS multiplied by assumed exit P/E multiples, modeling multiple compression across mature forecast windows [3]:
| Scenario Name | Prob. (%) | 12-Month Target | 24-Month Target | 36-Month Target | 36-Mo ROI (%) | Clears Mandate? |
|---|---|---|---|---|---|---|
| Stress Downside | 15.0% | $3.60 ($0.30 × 12x) | $3.20 ($0.32 × 10x) | $3.15 ($0.35 × 9x) | −55.9% | No |
| Conservative | 25.0% | $6.30 ($0.42 × 15x) | $6.72 ($0.48 × 14x) | $7.54 ($0.58 × 13x) | +5.6% | No |
| Base Case | 35.0% | $10.40 ($0.52 × 20x) | $12.96 ($0.72 × 18x) | $16.80 ($1.05 × 16x) | +135.3% | Yes |
| Thesis / Upside | 15.0% | $14.40 ($0.60 × 24x) | $19.80 ($0.90 × 22x) | $27.00 ($1.35 × 20x) | +278.2% | Yes |
| Aggressive Growth | 10.0% | $19.60 ($0.70 × 28x) | $28.75 ($1.15 × 25x) | $37.40 ($1.70 × 22x) | +423.8% | Yes |
| Probability-Weighted | 100% | $9.88 | $12.54 | $16.03 | +124.5% | Yes |
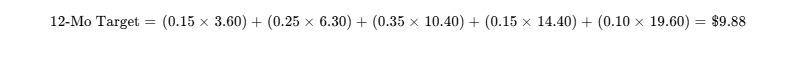
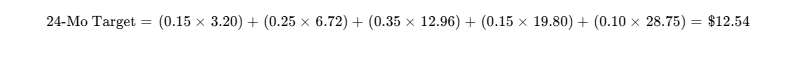
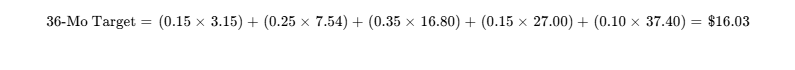
Operating Environment Narratives Across Scenarios
- Stress Downside Environment: Automotive manufacturers accelerate in-house perception software development, while Horizon Robotics gains share within the Chinese domestic ecosystem [28]. Core EyeQ shipments grow below 3% annually, and pricing competition lowers Non-GAAP gross margins toward 58%. The stock experiences multiple compression, trading toward tangible asset support at $3.15.
- Conservative Environment: Global light vehicle production growth remains modest at 1% to 2% annually, and EyeQ shipments track broader automotive assembly trends [36]. Automakers delay SuperVision rollouts due to vehicle platform redesign costs [7]. Adjusted operating margins stabilize near 16%, and the stock trades at 13x forward earnings ($7.54).
- Base Case Environment: Active safety regulations in the U.S. and Europe sustain steady demand for base EyeQ systems [11]. High-volume design wins for Surround ADAS across Stellantis and Volkswagen platforms enter commercial production between late 2027 and 2029, diversifying the revenue base and lifting corporate gross margins [7]. Commercial robotaxi activities scale gradually through fleet partnerships with Volkswagen MOIA and Benteler/Holon [7]. Adjusted operating margins expand toward 27%, supporting an exit price of $16.80 at a 16x multiple.
- Thesis / Upside Environment: Western automotive manufacturers adopt SuperVision across multiple high-volume model lines [24]. Autonomous shuttle programs with Volkswagen/MOIA and Holon begin driver-out commercial service in several major metropolitan markets [7]. Non-GAAP operating margins reach 31%, supporting a 36-month target of $27.00.
- Aggressive Growth Environment: Mobileye establishes its computing and software platform across both Western and Asian automakers [28]. The Mentee Robotics acquisition accelerates commercial licensing of humanoid and physical-AI architectures by 2029 [10]. Non-GAAP EPS reaches $1.70 by FY2029, supporting a $37.40 target at a 22x multiple.
- Mandate Threshold Probability: The combined probability of achieving the 100% return hurdle ($14.28+) over 36 months is 60.0% (Base 35% + Upside 15% + Aggressive 10%). The probability of experiencing a drawdown greater than 30% ($4.99 or below) is 15.0% (Stress Case weight).
- Expected Value Cross-Check: The 36-month probability-weighted target of $16.03 compares reasonably to the DCF midpoint fair value of $18.60 (−13.8% variance). The probability-weighted target incorporates cyclical auto production risks and competitive pressures, while the DCF reflects long-term cash flow generation.
6Catalyst Calendar
| Projected Date | Corporate Milestone / Industry Event | Scenario Validation Impact | Expected Share Volatility |
|---|---|---|---|
| October 22, 2026 | Q3 FY2026 Earnings Release [1,16] | Validates core ADAS volume stabilization and second-half ASP performance [7]. | ±8.0% to ±12.0% [25] |
| January 6–9, 2027 | CES 2027 Global Auto Showcase | Expected updates on EyeQ6 High production schedules and Mentee Robotics integrations [10]. | ±6.0% |
| Late January 2027 | Q4 and FY2026 Earnings & FY27 Guide [29] | Sets financial baseline for FY27; critical for validating out-year inflection [10]. | ±10.0% to ±15.0% |
| Q1–Q2 2027 | Announcement of Successor CEO [5,12] | Clarifies leadership succession and strategic continuity [12]. | ±5.0% |
| Mid-2027 | Volkswagen / MOIA Robotaxi Deployment [10,56] | Key commercial milestone for Mobileye Drive and autonomous platform scalability [7]. | ±15.0% |
| July 2027 | Stellantis Cloud ADAS Integration [7,9] | Verifies initial commercial revenue recognition from REM crowdsourced software [7]. | ±8.0% |
7Tactical Execution Layer
Derived from intrinsic valuation bands and historical market microstructure:
| Execution Field | Tactical Price Level | Analytical Framework & Placement Context |
|---|---|---|
| Optimal Accumulation Zone | $6.80 – $7.25 | High margin of safety; near the 52-week low support block ($6.47) [1]. |
| Aggressive Add Zone | $6.20 – $6.60 | Accumulate near tangible balance sheet value if broader markets pull back [26]. |
| Neutral Hold Corridor | $7.50 – $11.00 | Fundamental consolidation zone ahead of FY27 revenue inflection [1]. |
| Tactical Trim Zone | $12.50 – $14.00 | Resistance near the 24-month base-case target; harvest short gains. |
| Full Disinvestment Zone | $16.50+ | Achieves 36-month Base Case objective; multiple approaches fair value. |
| Hard Thesis Stop-Loss | $5.20 | Corresponds to operational invalidation (severe gross margin degradation). |
| Key Technical Support | $6.47 | 52-Week low level set during the March 2026 market pullback [1]. |
| Key Overhead Resistance | $8.87 / $9.68 | 200-day moving average (9.68) [16]. |
| 5-Year Regression Beta | 1.24 | Moderate cyclical sensitivity relative to broad market indices [16]. |
| 3-Year Maximum Drawdown | −81.0% | Peak-to-trough decline from 2023 highs above $40.00 [4]. |
| Implied Volatility (30D) | 45.5% | Elevated implied volatility reflects short interest and upcoming earnings [1]. |
| Tactical Recommendation | BUY | Build position within the primary accumulation corridor (7.25) [1]. |
| Timing Verdict | Accumulate Now | Establish pilot position ahead of the Q3 2026 earnings release [1]. |
Stop-Loss Calibration Note: The stop-loss level of $5.20 functions as a thesis invalidation stop tied directly to the hard invalidation parameters (such as Non-GAAP gross margins breaking below 62%), rather than a short-term price momentum stop.
Closing Audit & Verification Review
Unverified Figures and Data Limitations
- Mentee Robotics Transaction Earnouts: While Form 10-Q identifies a 612M gross), potential contingent earnout milestone structures remain unquantified until full Form 10-K proxy disclosures [10].
- Contractual Backlog Segmentation: The $24.5B eight-year automotive pipeline is reported as an aggregate figure [10]; precise splits between binding purchase orders, multi-year software agreements, and non-binding volume estimates are derived from management commentary rather than scheduled balance sheet line items [24].
- Real-Time Stock Borrow Fees: Borrow fee rates for MBLY range between 1.5% and 4.2% across institutional lending desks; data is referenced from secondary clearing summaries [21].
Red Flag and Internal Consistency Self-Audit
- Capitalization and Enterprise Value Reconciliation: The market capitalization of $6,070M combined with total liquid assets of $1,443M yields an Enterprise Value of $4,627M, consistent with the reported debt-free balance sheet [3].
- Operating Loss vs. Cash Flow Variance: The large GAAP net loss in FY2026 (-$3,818M in Q1 2026) was primarily caused by the non-cash goodwill write-down of 210M generated across H1 2026) [7].
- EPS and Operating Profit Reconciliation: Modeled Non-GAAP diluted earnings per share ($0.49 in FY26E) reconcile with the guided adjusted operating profit range of 425M after factoring in net interest income and statutory taxes [7].
Scenario Skewness and Truncation Certification
- Scenario Distribution Balance: Downside scenarios (Stress at 15% and Conservative at 25%) represent a cumulative 40.0% weight, the Base Case carries a 35.0% weight, and upside scenarios (Upside at 15% and Aggressive at 10%) total a 25.0% weight. This weighting avoids optimistic bias while reflecting Mobileye's structural advantages in regulatory ADAS markets [11].
- Report Truncation Statement: No sections were truncated; all financial projections, stress scenarios, peer comparisons, and tactical parameters have been fully evaluated.
Works cited
- Mobileye Global (MBLY) Stock Price, News & Analysis - MarketBeat, https://www.marketbeat.com/stocks/NASDAQ/MBLY/
- MBLY Stock Price Quote & News - Mobileye Global - Robinhood, https://robinhood.com/us/en/stocks/MBLY/
- unknown_url
- Mobileye Global Inc. Stock Price - Perplexity, https://www.perplexity.ai/finance/MBLY?comparing=MBLY,2577.HK,9660.HK,6082.HK,AMBA,9903.HK
- Mobileye | Investor Relations, https://ir.mobileye.com/
- Mobileye Global Inc._June 27, 2026 - SEC.gov, https://www.sec.gov/Archives/edgar/data/1910139/000110465926086264/mbly-20260627x10q.htm
- Mobileye Releases Second Quarter 2026 Results, Updates, https://ir.mobileye.com/news-releases/news-release-details/mobileye-releases-second-quarter-2026-results-updates-guidance
- Mobileye Global - MBLY - Stock Price & News - The Motley Fool, https://www.fool.com/quote/nasdaq/mbly/
- News Releases - Mobileye | Investor Relations, https://ir.mobileye.com/news-events/news-releases
- Mobileye Releases Fourth-Quarter and Full-Year 2025 Results and, https://ir.mobileye.com/node/9071/pdf
- Investment analysis of Mobileye Global Inc - Freedom24, https://freedom24.com/ideas/details/19869?site_lang=en
- Mobileye Global (MBLY) Stock News & Updates | StockTitan, https://www.stocktitan.net/news/MBLY/
- Mobileye Stock (MBLY) Off Lows Into Earnings, Remains In Bear, https://www.asktraders.com/analysis/mobileye-stock-mbly-off-lows-into-earnings-remains-in-bear-territory/
- Ambarella, Inc. (AMBA) Stock Valuation Grade & Metrics, https://seekingalpha.com/symbol/AMBA/valuation/metrics
- Mobileye Global Inc Ordinary Shares - Class A (MBLY) - Morningstar, https://www.morningstar.com/stocks/xnas/mbly/quote
- Mobileye Global (MBLY) Statistics & Valuation - Stock Analysis, https://stockanalysis.com/stocks/mbly/statistics/
- Mobileye Announces Share Repurchase Program of Up to $250, https://ir.mobileye.com/news-releases/news-release-details/mobileye-announces-share-repurchase-program-250-million
- 2 under-the-radar AI chip stocks where founders are holding instead, https://www.procapinsights.com/reports/ai-chip-stock-semis-nvda-apple-soxx
- Mobileye Director Frank Yeary Buys 12,360 Shares After 43% Stock, https://www.fool.com/coverage/filings/2026/08/05/mobileye-director-frank-yeary-buys-12-360-shares-after-43-stock-decline-should-investors-be-excited-for-the-rest-of-2026/
- Mobileye Global (MBLY) Short Interest & Short Float - MarketBeat, https://www.marketbeat.com/stocks/NASDAQ/MBLY/short-interest/
- MBLY / Mobileye Global Inc. Stock - Short Interest - Fintel, https://fintel.io/ss/us/mbly
- Mobileye (MBLY) Q3 2025 Earnings - 24/7 Wall St., https://247wallst.com/companies/mbly/earnings/2025/Q3/
- Mobileye Global Inc._December 27, 2025 - SEC.gov, https://www.sec.gov/Archives/edgar/data/1910139/000110465926014300/mbly-20251227x10k.htm
- Mobileye Second Quarter 2026 Earnings Conference Call July 23, https://ir.mobileye.com/static-files/7e9569f9-63f5-40f8-940d-e846cc707365
- Mobileye Global Inc. (MBLY) Stock | StreetAlpha, https://streetalpha.app/stocks/mbly
- MOBILEYE GLOBAL Book Value per Share: $9.77 - GuruFocus, https://www.gurufocus.com/term/book-value-per-share/MBLY
- https://www.sec.gov/Archives/edgar/data/1910139/000110465926086264/R17.htm
- Top 20 Most Advanced Autonomous Driving Chips 2025, https://www.nevsemi.com/blog/top-20-most-advanced-autonomous-driving-chips-2025
- Mobileye (MBLY) Q4 2025 Earnings - 24/7 Wall St., https://247wallst.com/companies/mbly/earnings/2025/Q4/
- Mobileye Releases First Quarter 2026 Results, Updates Full-Year, https://ir.mobileye.com/news-releases/news-release-details/mobileye-releases-first-quarter-2026-results-updates-full-year
- Mobileye (MBLY) Q3 2025 Earnings Call Summary - Stock Taper, https://www.stocktaper.com/earningsCallSummary/MBLY/2025/Q3
- Mobileye Global (MBLY) - Trefis, https://www.trefis.com/data/companies/MBLY
- Who Owns ADAS in 2026: Market Share by Company | Dataintelo, https://dataintelo.com/insights/who-owns-adas-2026-supplier-scoreboard.html
- Ambarella (AMBA) Statistics & Valuation - Stock Analysis, https://stockanalysis.com/stocks/amba/statistics/
- Automotive AI Processors Market Intelligence Report 2025, https://www.businesswire.com/news/home/20251128014525/en/Automotive-AI-Processors-Market-Intelligence-Report-2025-Business-Opportunities-Competitive-Insights-Growth-Drivers-Industry-Trend-Analysis-and-Forecast-to-2034---ResearchAndMarkets.com
- Earnings call transcript: Mobileye meets Q3 2025 EPS, raises, https://www.investing.com/news/transcripts/earnings-call-transcript-mobileye-meets-q3-2025-eps-raises-revenue-guidance-93CH-4305035
- Mobileye First Quarter 2026 Earnings Conference Call April 23, 2026, https://ir.mobileye.com/static-files/4cda4089-e97e-4b79-8ca1-b51c4035ef73
- Automotive AI Market Size, Share, Trends, Forecast 2035, https://www.marketresearchfuture.com/reports/automotive-artificial-intelligence-market-4258
- Automotive Artificial Intelligence Market Size & Share Analysis, https://www.mordorintelligence.com/industry-reports/automotive-artificial-intelligence-market
- What is Physical AI in Automotive Market Size? - Insightace Analytic, https://www.insightaceanalytic.com/report/physical-ai-in-automotive-market/3722
- Mobileye Global Inc. - SEC.gov, https://www.sec.gov/Archives/edgar/data/1910139/000110465923030588/mbly-20221231x10k.htm
- Form 20-F for Tower Semiconductor LTD filed 04/30/2026, https://ir.towersemi.com/static-files/2bd7b050-4b74-4c20-893a-2a9274e86ecb
- Mobileye Releases Third Quarter 2024 Results and Provides, https://ir.mobileye.com/news-releases/news-release-details/mobileye-releases-third-quarter-2024-results-and-provides
- Mobileye (MBLY) Business Metrics & Revenue Breakdown, https://stockanalysis.com/stocks/mbly/financials/metrics/
- Mobileye Releases Second Quarter 2025 Results, Updates Full, https://ir.mobileye.com/news-releases/news-release-details/mobileye-releases-second-quarter-2025-results-updates-full-year
- Mobileye Global (MBLY) Earnings Date and Reports 2026, https://www.marketbeat.com/stocks/NASDAQ/MBLY/earnings/
- Mobileye Releases First Quarter 2026 Results, Updates Full-Year, https://ir.mobileye.com/node/9181/pdf
- Earnings call transcript: Mobileye beats Q2 2026 estimates but, https://www.investing.com/news/transcripts/earnings-call-transcript-mobileye-beats-q2-2026-estimates-but-shares-fall-premarket-93CH-4809043
- Mobileye Releases Third Quarter 2025 Results and Provides, https://ir.mobileye.com/news-releases/news-release-details/mobileye-releases-third-quarter-2025-results-and-provides
- Mobileye stock faces 24% downside on structural risks, Jefferies says, https://www.investing.com/news/stock-market-news/mobileye-stock-faces-24-downside-on-structural-risks-jefferies-says-4695645
- MBLY Stock Forecast - Mobileye Global Inc - Alpha Spread, https://www.alphaspread.com/security/nasdaq/mbly/analyst-estimates?forecast=revenue
- MBLY Mobileye Global Inc Stock Forecast, Predictions & Price Target, https://www.wallstreetzen.com/stocks/us/nasdaq/mbly/stock-forecast
- Ambarella (AMBA) Stock Price, News & Analysis - MarketBeat, https://www.marketbeat.com/stocks/NASDAQ/AMBA/
- MBLY - Mobileye Global Inc Stock Price and Quote - Finviz, https://finviz.com/stock?t=MBLY
- MBLY Stock - Invest in Mobileye Global, NASDAQ - Trading 212, https://www.trading212.com/trading-instruments/invest/MBLY.US
- Final 072425 Mobileye Technologies Q2 2025 Results, https://ir.mobileye.com/static-files/1f8d2097-a17b-4929-8c70-87a53d7b403a
- Mobileye Global, Inc. Class A (MBLY) Live Share Price ... - INDmoney, https://www.indmoney.com/us-stocks/mobileye-global-inc-share-price-mbly