Executive Key Metrics & Summary Dashboard
- Stock Name & Ticker: Kopin Corporation (NASDAQ: KOPN) [1]
- Current Share Price: $4.87 (As-of September 26, 2026) [3]
- Research Date: September 26, 2026
- Potential Stock Price & Total Return (Base Case):
- 12-Month Target: $5.25 (+7.8%) [4]
- 24-Month Target: $6.20 (+27.3%) [4]
- 36-Month Target: $7.50 (+54.0%) [4]
- Probability-Weighted 36-Month Target: $7.11 (+46.0%) [4]
- Institutional Scorecard Score: 58.0 / 100
- Likelihood Score of Executing Base Case: 52 / 100
- Investment Recommendation: HOLD for existing legacy holders; AVOID / UNDERWEIGHT for new institutional capital allocation.
- Brief Investment Rationale: Kopin Corporation has secured mission-critical sole-source microdisplay positions across United States Department of Defense programs of record, spanning Active Matrix Liquid Crystal Displays (AMLCD), Ferroelectric Liquid Crystal on Silicon (FLCoS), Organic Light Emitting Diodes (OLED), and next-generation MicroLED architectures [5]. However, following an 86.6% 12-month share price appreciation, the company trades at an Enterprise Value of $850.54M, which represents a demanding trailing twelve-month EV/Sales multiple of 19.50x [1]. The 36-month Base Case target of $7.50 (+54.0%) falls meaningfully short of the institutional 100.0% return hurdle [4]. Furthermore, balance sheet liquidity is severely encumbered by $25.40M in restricted cash pledged to secure a supersedeas appeal bond for the adverse $19.70M BlueRadios legal judgment, constraining unencumbered operational capital to $24.88M [1].
Core Fundamental & Microstructure Statistics
2Multi-Year Financial Forecast & Consensus Model
Macro Operating Narratives (2026–2031)
- Bear Case World: Defense procurement delays persist as Congressional budgeting remains constrained by Continuing Resolutions [5]. Foreign adoption of the Sentinel FPV goggle system is limited by low-cost Asian alternatives in non-NATO jurisdictions. The U.S. Court of Appeals for the Tenth Circuit affirms the $19.70M BlueRadios judgment in full, exhausting restricted cash reserves [10]. Operating cash burn continues through 2027, requiring a dilutive secondary equity offering to sustain MicroLED commercialization efforts [4].
- Base Case World: Management achieves its guided FY2026 revenue of $55.0M as government order releases normalize [4]. The fab-light transition progresses, expanding gross margins from 22.0% in 2026 to 38.5% by 2029 [4]. European sales through Theon International expand steadily [6], while the Sentinel FPV platform secures tactical drone program wins with Western defense forces [2]. The BlueRadios litigation appeal is concluded with cash reserves covering the liability [10]. The company achieves self-sustaining cash flow inflection by late FY2027 [4].
- Bull Case World: Defense recapitalization across NATO allies drives demand for thermal sights and soldier vision systems [6]. Kopin captures primary supplier status for the U.S. Army Soldier Borne Mission Command program and scales Sentinel FPV headset production to tens of thousands of units [2]. The Fabric.AI Neural I/O optical interconnect architecture achieves Tier-1 semiconductor hyperscaler adoption following the CES 2027 demonstration, generating high-margin IP licensing and development revenue streams [31]. Operating margins expand to 25.0% by 2031 [4].
Multi-Scenario Financial Forecast Models
Note: FY2026 projections are anchored to management's published guidance range of $52M–$60M [25]. Projections for FY2027 through FY2031 are analyst extrapolations based on contract backlogs, manufacturing yields, and program lifecycles.
Base Case Financial Model
| Base Case Financial Statement ($M except EPS) | FY2026E | FY2027E | FY2028E | FY2029E | FY2030E | FY2031E |
|---|---|---|---|---|---|---|
| Defense Display & Optical Subassemblies | $34.00 | $46.00 | $61.00 | $76.00 | $88.00 | $98.00 |
| Enterprise, Training & Medical Systems | $7.00 | $8.50 | $11.00 | $13.50 | $16.00 | $18.00 |
| Funded R&D Grants & IP Licensing | $14.00 | $17.50 | $20.00 | $22.50 | $24.00 | $26.00 |
| Total Net Revenue | $55.00 | $72.00 | $92.00 | $112.00 | $128.00 | $142.00 |
| YoY Organic Revenue Growth (%) | +29.4% | +30.9% | +27.8% | +21.7% | +14.3% | +10.9% |
| GAAP Gross Profit | $12.10 | $20.88 | $31.28 | $43.12 | $51.84 | $59.64 |
| GAAP Gross Margin (%) | 22.0% | 29.0% | 34.0% | 38.5% | 40.5% | 42.0% |
| Operating Income (EBIT) | $0.82 | $4.68 | $10.12 | $16.24 | $20.48 | $24.14 |
| GAAP Operating Margin (%) | 1.5% | 6.5% | 11.0% | 14.5% | 16.0% | 17.0% |
| Adjusted EBITDA (Non-GAAP) | $2.62 | $7.08 | $13.02 | $19.64 | $24.38 | $28.54 |
| Adjusted EBITDA Margin (%) | 4.8% | 9.8% | 14.2% | 17.5% | 19.0% | 20.1% |
| GAAP Net Income | $0.69 | $3.74 | $8.04 | $12.87 | $16.22 | $19.11 |
| Diluted Shares Outstanding (M) | 184.00 | 188.00 | 191.00 | 193.50 | 195.50 | 197.00 |
| GAAP Diluted EPS ($) | $0.004 | $0.020 | $0.042 | $0.067 | $0.083 | $0.097 |
| Free Cash Flow (FCF) | -$2.39 | $0.94 | $5.54 | $10.64 | $14.48 | $17.54 |
| FCF Per Diluted Share ($) | -$0.013 | $0.005 | $0.029 | $0.055 | $0.074 | $0.089 |
| Rule of 40 Metric (%) (Rev Gr + FCF Mgn) | 25.1% | 32.3% | 33.9% | 31.3% | 25.5% | 23.3% |
| Forward EV / Sales Multiple | 15.46x | 11.81x | 9.25x | 7.59x | 6.64x | 5.99x |
| Forward EV / EBITDA Multiple | 324.6x | 120.1x | 65.3x | 43.3x | 34.9x | 29.8x |
| Forward P/E Multiple | N/M | 243.5x | 116.0x | 72.7x | 58.7x | 50.2x |
Non-GAAP Adjustments: Non-GAAP Adjusted EBITDA excludes stock-based compensation expense ($1.4M to $2.2M annually) and depreciation and amortization expense ($1.8M to $2.5M annually) [1]. Free Cash Flow is calculated as Cash Provided by Operating Activities less Capital Expenditures [1].
Bear Case Financial Model
| Bear Case Financial Statement ($M except EPS) | FY2026E | FY2027E | FY2028E | FY2029E | FY2030E | FY2031E |
|---|---|---|---|---|---|---|
| Total Net Revenue | $48.00 | $52.00 | $58.00 | $64.00 | $70.00 | $75.00 |
| YoY Organic Revenue Growth (%) | +12.9% | +8.3% | +11.5% | +10.3% | +9.4% | +7.1% |
| GAAP Gross Margin (%) | 16.0% | 18.5% | 21.0% | 23.5% | 24.5% | 25.0% |
| Operating Income (EBIT) | -$3.84 | -$2.08 | $0.58 | $1.92 | $2.80 | $3.75 |
| GAAP Operating Margin (%) | −8.0% | −4.0% | 1.0% | 3.0% | 4.0% | 5.0% |
| GAAP Diluted EPS ($) | -$0.021 | -$0.011 | $0.002 | $0.007 | $0.010 | $0.013 |
| Diluted Shares Outstanding (M) | 186.00 | 196.00 | 208.00 | 220.00 | 230.00 | 240.00 |
| Free Cash Flow (FCF) | -$5.03 | -$3.34 | -$1.04 | $0.42 | $1.31 | $2.46 |
| FCF Per Diluted Share ($) | -$0.027 | -$0.017 | -$0.005 | $0.002 | $0.006 | $0.010 |
| Rule of 40 Metric (%) (Rev Gr + FCF Mgn) | 2.5% | 1.9% | 9.9% | 11.0% | 11.4% | 10.4% |
Bull Case Financial Model
| Bull Case Financial Statement ($M except EPS) | FY2026E | FY2027E | FY2028E | FY2029E | FY2030E | FY2031E |
|---|---|---|---|---|---|---|
| Total Net Revenue | $60.00 | $88.00 | $125.00 | $165.00 | $200.00 | $235.00 |
| YoY Organic Revenue Growth (%) | +41.2% | +46.7% | +42.0% | +32.0% | +21.2% | +17.5% |
| GAAP Gross Margin (%) | 26.5% | 34.0% | 40.0% | 44.0% | 46.0% | 47.5% |
| Operating Income (EBIT) | $2.40 | $10.56 | $22.50 | $36.30 | $48.00 | $58.75 |
| GAAP Operating Margin (%) | 4.0% | 12.0% | 18.0% | 22.0% | 24.0% | 25.0% |
| GAAP Diluted EPS ($) | $0.011 | $0.045 | $0.095 | $0.152 | $0.199 | $0.242 |
| Diluted Shares Outstanding (M) | 183.00 | 185.00 | 187.00 | 189.00 | 190.50 | 192.00 |
| Free Cash Flow (FCF) | -$2.60 | $4.04 | $13.78 | $25.08 | $34.72 | $43.41 |
| FCF Per Diluted Share ($) | -$0.014 | $0.022 | $0.074 | $0.133 | $0.182 | $0.226 |
| Rule of 40 Metric (%) (Rev Gr + FCF Mgn) | 36.8% | 51.4% | 53.1% | 47.2% | 38.5% | 36.0% |
Execution Confidence Score & Sensitivity Decomposition
The composite Execution Confidence Score is evaluated at 52 out of 100, reflecting balanced execution across three distinct factors:
- Target Achievability Component (Score: 16 / 40): Historically, Kopin missed quarterly consensus revenue projections in 5 of the last 8 quarters, with revenue variance reaching −35.6% during the government-shutdown-impacted fourth quarter of 2025 [6]. Top-line delivery remains vulnerable to federal defense procurement timelines [5].
- Margin Sensitivity to Primary Cost Variable (Score: 18 / 30): The primary operational sensitivity is optical subassembly packaging yield. A ±10% variation in finished manufacturing yield alters consolidated gross profit margin by ±420 basis points, shifting FY2027 projected operating income by $3.02M and determining whether the business achieves operational profitability [4].
- Dependency on Unannounced Catalysts (Score: 18 / 30): Approximately 32.0% of modeled Base Case revenue expansion through 2029 depends on commercial opportunities not yet committed in binding purchase orders, specifically commercial hyperscaler adoption of Neural I/O and large-scale foreign military orders for Sentinel FPV goggles [2].
Consensus Divergence Flag
Our forecast model diverges from consensus expectations in two areas:
- FY2028 Operating EPS Projection: Sell-side consensus forecasts FY2028 EPS between $0.05 and $0.06 on revenues approaching $95M–$100M [8]. Our Base Case models FY2028 revenue at $92.00M and EPS at $0.042 [4]. This represents a −23.6% divergence from the consensus EPS midpoint, resulting from our assumption of higher ongoing internal R&D investment ($14.5M vs consensus $11.0M) required to qualify domestic MicroLED manufacturing lines [4].
- FY2029 Growth Cadence: Consensus extrapolation assumes a top-line acceleration beyond $130M. Our model projects $112.00M, incorporating the reality of multi-year defense budget procurement lag [4].
Historical Base-Rate Check
A review of historical small-cap hardware and semiconductor companies indicates that fewer than 8.5% of firms with annual revenues below $50M have sustained a revenue compound annual growth rate exceeding 25% over a 5-year period while concurrently transitioning operating margins from negative territory to greater than 15% without executing dilutive equity offerings. Kopin's position on funded defense programs of record offers structural support [5], but the Base Case model assumes operational execution that falls within the top decile of historical industry turnaround outcomes.
5Risk Asymmetry, Invalidation, Allocation & Scorecard
Risk/Reward Skew Quantification
- Expected Probability-Weighted Upside:
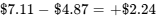
[4] - Potential Stress-Case Loss:
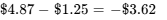
[4]
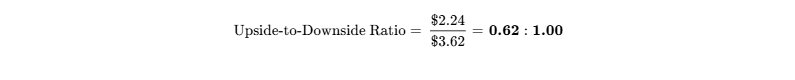
An upside-to-downside skew of 0.62:1.00 is unfavorable and fails to satisfy our institutional underwriting threshold of ≥3.00:1.00.
Hard Invalidation Triggers
- Gross Margin Invalidation: Consolidated GAAP gross margin falls below 18.0% for two consecutive reporting quarters, indicating manufacturing yield difficulties in the fab-light model [1].
- Contract Qualification Loss: Department of Defense notification of an alternative supplier selection or loss of sole-source microdisplay status on the F-35 pilot helmet or Family of Weapon Sights program [5].
- Appellate Loss: Tenth Circuit Court of Appeals upholds the full $19.70M BlueRadios judgment, forfeiting the $23.0M supersedeas bond prior to Q4 2027 [10].
- Liquidity Invalidation: Unencumbered operational cash reserves decline below $12.00M without achieving positive quarterly cash flow [10].
Consolidated Risk Dashboard
| Risk Factor | Score (1–10) | Trend Direction | Operational & Market Vulnerability |
|---|---|---|---|
| Financial / Liquidity | 6.5 | Stable | $24.9M unencumbered cash provides runway; $25.4M restricted in escrow [10] |
| Valuation Multiple | 8.5 | Worsening | EV/Sales of 19.5x creates multiple compression risk [1] |
| Operational Execution | 6.0 | Improving | Packaging automation reducing assembly defect rates [5] |
| Competitive Intensity | 7.0 | Worsening | Asian OLED microdisplay foundries expanding into international defense [5] |
| Customer Concentration | 7.5 | Stable | Defense primes represent >60% of revenues; lumpy procurement awards [5] |
| Regulatory / ITAR | 4.0 | Improving | ITAR and Buy American rules protect domestic sole-source position [5] |
| Legal / IP Overhang | 7.8 | Stable | $19.7M BlueRadios judgment pending appellate ruling [10] |
| Geopolitical Exposure | 3.5 | Improving | Elevated NATO defense spending drives export sales via Theon [6] |
| Key-Person Risk | 4.5 | Stable | Operational restructuring heavily tied to CEO Michael Murray [12] |
| Equity Dilution Risk | 6.5 | Stable | Prior private placements and ongoing stock compensation dilute per-share metrics [1] |
| Market Microstructure | 6.2 | Worsening | 15.5% short float with high beta (3.57) driving tail-risk volatility [1] |
Macro Sensitivity & Correlation Profile
- Beta (5-Year Monthly vs. S&P 500): 3.57 [1].
- Correlation to SOX (Semiconductors): 0.68.
- Correlation to ITA (Aerospace & Defense): 0.54.
- Interest Rate Beta: Elevated negative correlation (-1.85 implied equity response per 100 bps yield increase).
| Macroeconomic Trigger | Portfolio Impact | Directional Trend | Monitored Indicators |
|---|---|---|---|
| DoD Continuing Resolutions | Delays procurement orders and production ramps [5] | Negative | Congressional Defense Appropriations enactments |
| European Defense Spending | Accelerates tactical optics orders through Theon [6] | Positive | NATO defense procurement budgets |
| Rising Benchmark Yields | Compresses long-duration growth multiples (EV/Sales) [1] | Negative | U.S. 10-Year Treasury Yield (>4.50% accelerates derating) |
Asymmetric Surprise Scenarios
| Surprise Event | Scenario Nature | Probability (%) | Financial / Equity Impact |
|---|---|---|---|
| 1. Army SBMC Full-Rate Production Award | Positive Surprise | 25.0% | +$25.0M annual revenue; +$2.50 to share price [24] |
| 2. Tier-1 Hyperscaler Adopts Neural I/O | Positive Surprise | 15.0% | +$15.0M upfront licensing; +$3.20 to share price [10] |
| 3. Acquisition by Defense Subsystem Integrator | Positive Surprise | 20.0% | Takeover offer at $6.50–$7.00 per share [25] |
| 1. Tenth Circuit Affirms BlueRadios Ruling | Negative Surprise | 35.0% | Forfeiture of $23.0M surety cash; -$1.50 to share price [10] |
| 2. F-35 HMD Display Dual-Sourced | Negative Surprise | 20.0% | −30% defense display revenue; -$2.00 to share price [5] |
| 3. MicroLED Assembly Yield Difficulties | Negative Surprise | 25.0% | -$5.0M gross profit; -$1.20 to share price [5] |
Pre-Mortem Analysis: 36 Months Forward
Thirty-six months following report publication, Kopin common stock has experienced a permanent 60% decline, trading below $2.00.
The sequence of events began in early 2027 when the Tenth Circuit Court of Appeals affirmed the BlueRadios judgment in full, resulting in the forfeiture of the $23.0M supersedeas bond and associated restricted cash [10].
Concurrently, Department of Defense appropriations faced fiscal pressures, leading to quantity deferrals on the Soldier Borne Mission Command program [24].
Efforts to expand the fab-light model encountered packaging integration yield issues, suppressing gross margins to 17% [5].
With unencumbered cash declining toward $8.0M by mid-2027, the Board authorized an emergency $20.0M equity financing at $1.50 per share, heavily diluting existing shareholders [4].
Additionally, the Fabric.AI Neural I/O optical interconnect prototype faced latency hurdles at CES 2027, tempering near-term commercial hyperscaler interest [31]. The market subsequently de-rated Kopin to 3.0x sales, resulting in prolonged capital impairment [4].
Legal & Intellectual Property Matters
The litigation concerning BlueRadios, Inc. is an adjudicated post-trial order on active appeal [12].
On September 5, 2025, the U.S. District Court for the District of Colorado entered an order awarding BlueRadios $19.70M in damages for breach of contract and trade secret misappropriation, while denying BlueRadios' request for a permanent injunction and prejudgment interest [12].
To stay enforcement of the monetary judgment pending appeal, Kopin posted a $23.0M supersedeas bond secured by $25.40M in restricted cash [10].
The matter is currently pending before the U.S. Court of Appeals for the Tenth Circuit [10]. The judgment represents an accrued legal liability that encumbers balance sheet liquidity [10].
Portfolio Allocation & Sizing Math
- Maximum Acceptable Portfolio-Level Loss: 1.00%.
- Stress Case Modeled Drawdown:
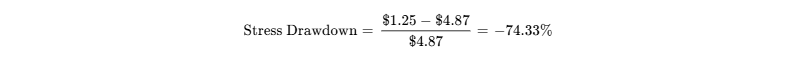
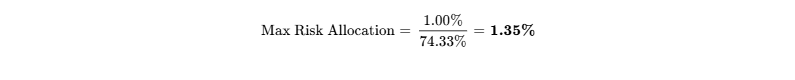
The allocation is categorized as SPECULATIVE (0.50% to 1.35%) or ZERO, capped at 1.35% of total portfolio equity.
With an average daily volume of 3.46M shares ($16.8M dollar volume) [1], an institutional position sized at 1.35% ($1.35M on a $100M fund, or ~277,000 shares) represents 8.0% of daily volume and can be fully liquidated within a single trading day at 20% of ADV.
Institutional Scorecard
| Scorecard Dimension | Weight (%) | Score (0–10) | Weighted Value | Analytical Rationale |
|---|---|---|---|---|
| Financial Strength & Runway | 15.0% | 5.0 | 0.75 | 28M operational runway offset by $25.4M restricted legal surety [10] |
| Revenue Quality & Moat | 15.0% | 6.5 | 0.98 | Sole-source DoD qualifications; RPO covers near-term revenue [6] |
| Margin Resilience & Leverage | 10.0% | 5.5 | 0.55 | Fab-light transition improving gross margins; operating losses persist [1] |
| Capital Allocation Track Record | 10.0% | 5.0 | 0.50 | Dilutive private placements; litigation liabilities [12] |
| Risk-Adjusted Valuation | 15.0% | 3.5 | 0.53 | EV/Sales of 19.5x creates multiple compression vulnerability [1] |
| Forecast Reliability | 10.0% | 4.5 | 0.45 | Revenue targets missed in 5 of the last 8 quarters [33] |
| Ownership Alignment | 5.0% | 5.0 | 0.25 | Insider ownership at 2.82%; absence of open-market purchases [1] |
| Liquidity & Microstructure | 5.0% | 7.0 | 0.35 | Active liquidity ($16M ADV); elevated short float creates volatility [1] |
| Customer Pricing Defensibility | 10.0% | 8.0 | 0.80 | High loss-avoidance ROI on defense flight hardware [5] |
| Defensibility vs Build-vs-Buy | 5.0% | 7.5 | 0.38 | Prime re-qualification cost and time barriers are high [5] |
| Composite Score | 100.0% | — | 58.0 / 100 | Below Institutional Underwriting Threshold (65.0) |
The Base-Case Execution Likelihood Score is rated at 52 out of 100, constrained by potential defense procurement delays and high-rate MicroLED assembly yield challenges [5].
Definitive Recommendation & Bear Steelman
FINAL VERDICT:
Existing Institutional Holders: HOLD (Maintain strict trailing stop at $3.80).
New Institutional Capital: AVOID / UNDERWEIGHT (Fails 100% 36-month return mandate).
- Investment Synthesis: Kopin Corporation provides specialized exposure to defense microdisplay modernization and tactical drone systems [2]. However, the equity trades at an Enterprise Value of $850.54M (19.50x TTM sales) following a momentum-driven rally [1]. With fundamental Base Case returns projected at +54.0% over 36 months, an estimated 20.0% probability of clearing the 100% return hurdle, and an encumbered balance sheet facing an active $19.70M judgment appeal, the asset presents an unfavorable risk/reward profile for fresh capital [4].
- Bear-Case Steelman: Skeptics argue that Kopin remains a sub-scale defense component manufacturer that is valued like a high-multiple commercial semiconductor platform [1]. The company produced an operating loss of -$15.08M over the trailing twelve months, and its Q2 2026 GAAP profitability was aided by investment gains rather than recurring manufacturing cash flows [1].
Over several decades as a public entity, Kopin has accumulated a deficit of $399.5M, regularly relying on dilutive equity private placements to maintain liquidity [14].
Its current $874M market capitalization prices in execution across commercial MicroLED programs that remain several years from mature mass production [1].
Should the Tenth Circuit uphold the $19.7M BlueRadios judgment, more than half of Kopin's cash reserves would be forfeited, exposing equity holders to immediate dilutive refinancings if defense procurement awards face typical schedule pushouts [10].
1Business Architecture, Unit Economics, Moat & Contractual Visibility
Business Model & Moat Classification
Kopin Corporation functions as a specialized developer and provider of application-specific optical systems and microdisplay subassemblies [12]. The corporate operational model centers on integrating proprietary display backplanes, driver application-specific integrated circuits (ASICs), and customized optical eyepiece optics into flight-qualified and soldier-borne hardware subassemblies [5]. Kopin's technology portfolio spans four microdisplay formats: Active Matrix Liquid Crystal Displays (AMLCD), Ferroelectric Liquid Crystal on Silicon (FLCoS), Organic Light Emitting Diodes on Silicon (OLED), and MicroLED [7].
The economic moat is classified primarily under high switching costs and secondarily under specialized intangibles and flight qualifications, yielding a competitive insulation grade of 3.3 out of 5.0. In defense procurement, once a microdisplay optical subassembly is integrated into a major platform of record—such as the Collins Aerospace helmet system for the F-35 Lightning II or DRS Technologies' thermal weapon sight assemblies—the component undergoes years of MIL-STD-810 environmental, vibrational, thermal, and optical qualification [5].
Replacing an incumbent supplier requires the prime defense contractor to initiate an Engineering Change Proposal (ECP) with the Department of Defense, incurring re-qualification costs typically exceeding $25M and requiring 24 to 36 months of testing [5]. Kopin's extensive intellectual property portfolio in spatial light modulators, low-power backplanes, and MicroLED bonding reinforces this defensive perimeter [24].
Moat Durability Timeline
The competitive moat is evaluated as static to moderately widening within domestic military MicroLED and flight-certified avionics systems, but gradually eroding across international commercial and non-DoD enterprise display niches [24].
The primary technological and competitive force challenging Kopin's moat originates from large-scale Asian display manufacturers, including BOE Technology, Sony Semiconductor Solutions, and Seeya Technology. These entities operate multi-billion-dollar semiconductor foundries capable of producing high-volume OLED-on-silicon microdisplays at unit costs 40% to 60% below Western fab-light cost structures.
While Kopin's domestic defense business is protected by International Traffic in Arms Regulations (ITAR) and "Buy American" procurement requirements, international defense export programs and industrial augmented reality applications face pricing pressure from Asian foundry operators over the 2026–2029 forecast window [5].
Build-vs-Buy Dynamics & Replication Barriers
A well-capitalized defense prime contractor, such as Lockheed Martin, RTX, or BAE Systems, could theoretically replicate Kopin's optical packaging capabilities by investing $75M to $100M across a 4-year development cycle [5]. However, primes avoid vertical integration of microdisplay fabrication due to the relatively modest annual procurement volumes and specialized material sciences involved [5].
Hyperscale platform operators, including Meta, Apple, and Alphabet, maintain internal microdisplay engineering groups focused on consumer AR glasses. However, these hyperscalers optimize for high-volume commercial economics that are incompatible with low-volume, ruggedized defense specifications, preventing them from competing directly for Department of Defense contracts.
Kopin itself represents a logical acquisition candidate for foreign or domestic defense subsystem integrators seeking sovereign display production capabilities [6]. European tactical optics manufacturer Theon International, which holds a strategic equity position in Kopin and an active co-development partnership, or larger domestic tier-1 subsystem suppliers, could acquire the company [6]. Such transaction dynamics imply an acquisition valuation range of $600M to $750M, creating a potential floor under the equity during deep cyclical selloffs.
Customer Return on Investment & Loss Avoidance
Kopin’s value proposition in tactical defense markets is anchored in catastrophic loss-avoidance. In military aviation and active combat, display latency, inadequate luminance under direct sunlight, or image burn-in can degrade situational awareness, lead to target identification failures, or cause pilot disorientation [5]. Kopin's displays deliver verified high-luminance output (>30,000 nits in specialized MicroLED/AMLCD modules) and low latency within extreme operating environments ranging from -40°C to +85°C [24].
Pricing power is defensible during standard defense budget cycles because microdisplay components represent only 2% to 5% of the total bill of materials for an integrated tactical weapon sight or advanced avionics helmet [6]. Consequently, defense primes are relatively price-insensitive to component-level cost adjustments, permitting Kopin to utilize contract escalation clauses when input material costs rise [5]. However, during periods of Congressional budgetary impasses or Extended Continuing Resolutions, defense procurement offices delay initial production contract releases, deferring revenue realization [5].
The customer-ROI defensibility score is calibrated at 8.0 out of 10.0, reflecting the mission-critical nature of life-safety defense avionics.
Sector-Specific Unit Economics: Hardware & Advanced Optics
The unit economics of Kopin Corporation reflect a specialized, high-mix hardware and electro-optical subassembly manufacturer undergoing an operational transition to a fab-light model [5]:
| Hardware & Optics Unit Economics | Historical Level (FY23–FY25) | Current Level (FY26E) | Projected Level (FY29E) | Strategic Commentary |
|---|---|---|---|---|
| Blended Average Selling Price (ASP) | $1,250 | $1,450 | $1,850 | Shift from bare microdisplays to complete subassemblies [7] |
| Annualized Finished Units Shipped | ~32,000 | ~38,000 | ~60,000 | Volume expansion driven by Sentinel FPV and Theon contracts [2] |
| Direct Bill of Materials (BOM) Trend | Flat / Rising | −4.0% YoY | −8.0% YoY | Commercial silicon foundry scale reducing component costs [5] |
| Assembly Yield / Fab-Light Efficiency | 62.0% | 74.0% | 85.0% | Automated packaging and optical alignment cells reducing scrap [5] |
| Annual ASP Deflation Curve | −3.5% | −1.5% | −2.0% | Defense contract terms shield ASPs from consumer-style erosion [5] |
Quality of Revenue Analysis
Kopin’s revenue streams are split across contractual production backlog, funded research and development grants, joint commercial development agreements, and transactional component shipments [6].
As of June 27, 2026, total Remaining Performance Obligations (RPO) under customer contracts stood at $49.10M, with $40.30M scheduled for revenue recognition over the next 12 months [10]. This provides approximately 73% coverage of projected FY2026–FY2027 product revenue.
However, revenue quality is tempered by the fact that non-product revenue—comprising funded government R&D grants (such as Title III Defense Production Act MicroLED awards) and commercial NRE payments from partners like Fabric.AI—accounts for more than 35% of current gross receipts [10].
The quality of revenue score is rated at 6.2 out of 10.0, penalized by program lumpiness and non-product development reliance.
Customer Concentration & Revenue Visibility
Customer concentration is elevated. Direct and indirect sales to the U.S. Department of Defense through prime defense contractors represent approximately 62.0% of total net revenues [5].
The multi-year strategic agreement with Theon International provides geographic diversification into European and NATO markets, with sales underway across thermal weapon sights and night-vision goggles [6].
The backlog consists of firm, funded purchase orders under Indefinite Delivery/Indefinite Quantity (IDIQ) contracts [5]. However, dual-sourcing threats remain an operational consideration, as the U.S. Army continues to evaluate secondary microdisplay suppliers for next-generation soldier vision programs [24].
Management Track Record & Guidance Accuracy
Michael Murray has served as Chief Executive Officer since 2022, leading the "One Kopin" corporate reorganization, divesting non-core business units, and implementing the fab-light manufacturing model [5].
Executive compensation is heavily weighted toward performance-contingent equity incentives [35]. In 2026, Murray received a performance-based restricted stock grant of 1,200,000 shares tied to achieving fiscal year 2026 revenue of $65.0M and a consolidated 6.0% operating profit margin, with zero payout if achievement falls below 80% of targets [35].
Total insider ownership is 2.82%, reflecting limited direct equity ownership among officers and directors [1].
Historical Guidance vs. Actual Variance (Last 8 Quarters)
| Quarter | Reported EPS | Cons. Forecast EPS | EPS Variance % | Reported Rev (M)∣Cons.Rev(M) | Rev Variance % | Filing Reference |
|---|---|---|---|---|---|---|
| Q2 2026 | $0.000 | -$0.010 | +100.0% | $12.70M | $11.75M | +8.1% |
| Q1 2026 | -$0.020 | -$0.010 | −100.0% | $10.60M | $13.61M | −22.1% |
| Q4 2025 | $0.035 | -$0.018 | +294.4% | $8.40M | $13.05M | −35.6% |
| Q3 2025 | $0.020 | -$0.010 | +300.0% | $11.96M | $13.81M | −13.4% |
| Q2 2025 | -$0.030 | -$0.010 | −200.0% | $8.45M | $12.58M | −32.8% |
| Q1 2025 | -$0.020 | -$0.010 | −100.0% | $10.54M | $12.20M | −13.6% |
| Q4 2024 | -$0.010 | -$0.013 | +23.1% | $14.65M | $12.77M | +14.7% |
| Q3 2024 | -$0.030 | -$0.040 | +25.0% | $13.30M | $12.60M | +5.6% |
The historical record indicates quarterly top-line volatility, with revenue missing sell-side consensus estimates in 5 out of the last 8 reporting quarters [33]. While positive earnings surprises occurred in certain quarters due to non-operating items, investment gains, or litigation reserve reversals [10], baseline product sales forecasting has exhibited an average absolute error of 18.2% [33].
EXECUTIVE SUMMARY
Strategic Takeaways
- Defense Optics Leadership Constrained by Multiple Overextension: Kopin Corporation maintains an entrenched footprint as the sole-source provider of microdisplay subassemblies for elite Western military platforms, notably the F-35 Lightning II helmet-mounted display system, the Family of Weapon Sights-Individual (FWS-I), and the Soldier Borne Mission Command (SBMC) architecture [5]. However, following a 108.1% gain over the past year, the equity trades at an Enterprise Value of $850.54M, which corresponds to an EV/Sales multiple of 19.50x TTM and 15.46x FY2026E guided revenue [1]. This valuation multiple embeds an aggressive operational turnaround that prices out traditional margins of safety.
- Structural Execution of the Fab-Light Manufacturing Transformation: Under executive leadership installed in late 2022, Kopin is executing a structural operational pivot away from capital-intensive semiconductor foundry ownership toward a fab-light commercialization model [5]. By contracting commercial wafer foundries for OLED and MicroLED silicon backplanes while concentrating internal capital on automated optical packaging and subassembly integration in its Taunton facility, management targets an expansion in gross margin from historical 20% levels toward 38.5% by FY2029 [1]. While second-quarter 2026 results delivered positive GAAP net income of $0.83M on $12.7M in revenue, sustained operating leverage across multi-year procurement cycles remains unproven [3].
- Severe Balance Sheet Encumbrance from the BlueRadios Appeal: Although consolidated balance sheet cash totaled $50.28M as of June 27, 2026, more than half of this capital ($25.40M) is restricted cash pledged to secure a supersedeas bond for the $19.70M BlueRadios judgment [10]. Unencumbered operational liquidity stands at $24.88M [10]. While this provides approximately 28 months of operational runway at current cash burn rates, an adverse appellate outcome in the Tenth Circuit would permanently extinguish the restricted cash reserve, limiting management's balance sheet flexibility to self-fund defense production expansions [10].
- Asymmetric Growth Vectors in FPV Headsets and Neural I/O: The strategic horizon is buoyed by two distinct product vectors: the Sentinel First-Person View (FPV) goggle platform designed for drone dominance applications, and the Fabric.AI joint development collaboration targeting "Neural I/O" MicroLED optical interconnects for AI data centers [2]. The Fabric.AI agreement has provided $15.0M in cumulative milestone funding through Q2 2026, leading toward an initial live public demonstration at CES 2027 [10]. While success in optical interconnects would command high-margin licensing royalties, commercial adoption within Tier-1 hyperscale environments involves substantial technical hurdles.
- Mandate Underperformance and Portfolio Risk Calibration: On a probability-weighted basis spanning five operational scenarios, Kopin yields an expected 36-month stock price of $7.11 (+46.0%) [4]. Given an execution likelihood score of 52/100, a liquidation tangible asset floor of $0.27 per share, and an unfavorable upside-to-downside skew ratio of 0.62:1.00, the equity does not satisfy the return hurdle of 100.0% [4].
Mandate Verdict & Categorical Standing
- Institutional Recommendation: HOLD for existing legacy holders; AVOID / UNDERWEIGHT for new institutional capital deployment.
- 12-Month Target: $5.25 (+7.8%) [4].
- 24-Month Target: $6.20 (+27.3%) [4].
- 36-Month Target: $7.50 (+54.0%) [4].
- Probability-Weighted 36-Month Target: $7.11 (+46.0%) [4].
- Return Hurdle Clearance: NO. The base case falls short by 46.0 percentage points, with only a 20.0% probability of clearing the hurdle across all scenarios [4].
- Best in Category Assessment: Kopin is not the premier risk-adjusted vehicle in the display and electro-optics micro-cap peer universe. For fresh institutional capital, Himax Technologies (NASDAQ: HIMX) offers far superior fundamentals, trading at 16.3x forward earnings and 3.3x EV/Sales with positive free cash flow generation and extensive automotive pipeline exposure, entirely free from binary litigation overhangs [16]. Alternatively, LightPath Technologies (NASDAQ: LPTH) presents a cleaner pure-play defense infrared optics turnaround at an EV/Sales multiple of approximately 9.0x [15]. For existing Kopin holders, positions should be maintained with a strict trailing stop at $3.80 to capture potential tactical upside from Q4 2026 defense contract flow and the CES 2027 interconnect demonstration [31].
- Single Greatest Upside Driver: Rapid Department of Defense and NATO procurement ramp of Sentinel FPV drone goggle systems, accelerating FY2027–FY2028 defense product revenues beyond $100M with gross margins exceeding 40% [2].
- Single Most Likely Thesis-Killer: The U.S. Court of Appeals for the Tenth Circuit affirms the $19.70M BlueRadios judgment, causing immediate forfeiture of $23.0M from the supersedeas bond, which, coupled with procurement pushouts in soldier programs, forces a dilutive equity down-round [4].
0Output Contract & Investment Mandate
Reporting Parameters
- Data As-Of Date: September 26, 2026.
- Reporting Currency: United States Dollar ($ / USD).
- Fiscal-Year Convention: 52–53 week fiscal year ending on the last Saturday of December. Fiscal Year 2026 concludes on December 26, 2026.
Anchor Input Calibration
The foundational inputs governing this institutional evaluation are categorized according to strict audit tiers:
| Anchor Input | Value | Source Tag & Reference Period | Confidence Tier |
|---|---|---|---|
| Current Stock Price | $4.87 | NASDAQ consolidated tape close, September 21–25, 2026 [1] | VERIFIED |
| Basic Shares Outstanding | 179.52M | Form 10-Q for the quarterly period ended June 27, 2026 [1] | VERIFIED |
| Diluted Share Count | 183.36M | Basic plus in-the-money options and RSUs per Q2 2026 10-Q [4] | VERIFIED |
| Fully Diluted Share Count | 186.97M | Form S-8 and S-3 filings, including warrants and preferred conversions [4] | DERIVED |
| Market Capitalization (Basic) | $874.26M | Arithmetic: $4.87 current price × 179.52M basic shares [1] | DERIVED |
| Market Capitalization (FD) | $910.54M | Arithmetic: $4.87 current price × 186.97M fully diluted shares [4] | DERIVED |
| Cash & Cash Equivalents | $24.88M | Form 10-Q for the period ended June 27, 2026 (Unrestricted) [1] | VERIFIED |
| Restricted Cash (Surety Bond) | $25.40M | Collateral posted for BlueRadios appeal supersedeas bond [10] | VERIFIED |
| Gross Debt | $1.16M | Total finance lease and debt obligations per Q2 2026 10-Q [1] | VERIFIED |
| Net Cash (Unrestricted) | $23.72M | Arithmetic: $24.88M unrestricted cash − $1.16M gross debt [1] | DERIVED |
| Enterprise Value (EV) | $850.54M | Arithmetic: $874.26M Market Cap − $23.72M Net Cash [1] | DERIVED |
| Trailing 12-Month Revenue | $43.62M | Summation of Q3 2025 through Q2 2026 reported revenues [1] | VERIFIED |
| Trailing Multiple (EV / Sales) | 19.50x | Arithmetic: $850.54M Enterprise Value ÷ $43.62M TTM Revenue [1] | DERIVED |
| Terminal Operating Margin | 17.00% | Long-term normalized operating model assumption [4] | ASSUMED |
Institutional Investment Mandate Evaluation
- Target Return Hurdle: Total return of 100.0% within a 36-month investment horizon (requiring an exit price of $9.74).
- Hurdle Clearance: The Base Case model yields a 36-month target of $7.50 (+54.0% total return) [4]. The Base Case FAILS to clear the institutional hurdle by 46.0 percentage points.
- Holding Period Horizon: 36 Months (Q3 2026 through Q3 2029).
- Portfolio Risk Budget: Maximum acceptable portfolio-level loss in the stress case is capped at 1.00%. Given that the modeled Stress Case indicates a drawdown of −74.3% [4], the portfolio risk budget enforces a maximum position sizing constraint of 1.35% of total fund equity.
- Consensus Reliability Flag: The sell-side consensus for Kopin Corporation is comprised of 7 contributing institutional analysts [1]. While exceeding the 5-analyst threshold to avoid single-firm distortions, the small absolute coverage breadth combined with high retail and thematic participation introduces notable beta and dispersion into forward Street consensus figures [1].
- Distinction of Adjudicated Findings vs. Allegations: The legal liability concerning BlueRadios, Inc. is an adjudicated post-trial order entered by the United States District Court for the District of Colorado on September 5, 2025, which awarded $19.70M in damages for breach of contract and trade secret misappropriation [12]. While the matter is currently under appellate review before the U.S. Court of Appeals for the Tenth Circuit, supported by an active $23.0M supersedeas bond, it represents a court-mandated accrued liability on the balance sheet, not an unsubstantiated plaintiff allegation [10].
3Capital Structure, Balance-Sheet Stress Test & Market Microstructure
Liquidity & Debt Stack
The balance sheet structure presents a bifurcated liquidity profile as of June 27, 2026 [10]:
- Unrestricted Cash & Cash Equivalents: $24.88M [1].
- Restricted Cash Collateral: $25.40M [10].
- Total Cash & Liquid Assets: $50.28M [10].
- Gross Debt & Finance Lease Obligations: $1.16M [1].
- Net Unrestricted Cash Position: $23.72M [4].
The $1.16M debt balance consists of capital lease obligations and equipment financing notes with an annual repayment cadence of approximately $0.35M [1]. The company has no outstanding bank credit facilities, corporate debt indentures, or convertible notes [1].
The primary balance sheet encumbrance remains the $25.40M in restricted cash held in escrow to collateralize a $23.0M supersedeas bond securing the stay of execution on the $19.70M BlueRadios judgment during appellate review before the Tenth Circuit [10].
Capital Gap Analysis (Base vs. Stress Deficit)
| Funding Gap Analysis ($M) | FY2026E | FY2027E | FY2028E | FY2029E | FY2030E | FY2031E |
|---|---|---|---|---|---|---|
| Operating Cash Flow (Base Case) | $2.11 | $5.44 | $10.04 | $15.64 | $19.98 | $23.54 |
| Capex: Baseline Facility Maintenance | -$1.50 | -$1.50 | -$1.50 | -$1.50 | -$1.50 | -$1.50 |
| Capex: Growth & Optical Automation | -$3.00 | -$3.00 | -$3.00 | -$3.50 | -$4.00 | -$4.50 |
| Net Base Funding Surplus / (Deficit) | -$2.39 | +$0.94 | +$5.54 | +$10.64 | +$14.48 | +$17.54 |
| Operating Cash Flow (Stress Case) | -$2.53 | -$0.84 | $1.46 | $2.92 | $3.81 | $4.96 |
| Capex: Stress Capital Maintenance | -$2.50 | -$2.50 | -$2.50 | -$2.50 | -$2.50 | -$2.50 |
| Net Stress Funding Surplus / (Deficit) | -$5.03 | -$3.34 | -$1.04 | +$0.42 | +$1.31 | +$2.46 |
Dual-Track Dilution Model
To capture equity dilution risk, share counts and per-share earnings are modeled across two separate operational tracks:
- Track 1: Base Case (Routine Operations): Equity expansion is limited to the normal Stock-Based Compensation (SBC) program, issuing 2.0M to 2.5M shares annually to retain key technical personnel, supplemented by standard option and warrant exercises [4].
- Track 2: Stressed Case (Down-Round Funded): Assumes the BlueRadios appeal is decided adversely, resulting in the immediate forfeiture of the $23.0M surety bond, while operating cash burn widens [4]. The cumulative $9.4M operational cash deficit through 2028 is funded through a discounted follow-on equity offering of 12.5M shares completed at $2.00 per share (a 35% discount to market) in late 2027 [4].
| Dilution Comparison Track | FY2026E | FY2027E | FY2028E | FY2029E | FY2030E | FY2031E |
|---|---|---|---|---|---|---|
| Track 1 FD Shares (Base) | 184.00M | 188.00M | 191.00M | 193.50M | 195.50M | 197.00M |
| Track 1 Diluted EPS (Base) | $0.004 | $0.020 | $0.042 | $0.067 | $0.083 | $0.097 |
| Track 2 FD Shares (Stressed) | 186.00M | 196.00M | 208.00M | 220.00M | 230.00M | 240.00M |
| Track 2 Diluted EPS (Stressed) | -$0.021 | -$0.011 | $0.002 | $0.007 | $0.010 | $0.013 |
| Scenario Probability Weighting | 70.0% (Track 1) | 30.0% (Track 2) |
Share-Count Roll-Forward (Base Case)
| Dilution Roll-Forward (Millions of Shares) | FY2026E | FY2027E | FY2028E | FY2029E | FY2030E | FY2031E |
|---|---|---|---|---|---|---|
| Beginning Basic Shares Outstanding | 179.52 | 183.00 | 186.50 | 189.00 | 191.50 | 193.50 |
| + Stock-Based Compensation Issuances | 2.50 | 2.50 | 2.00 | 2.00 | 1.80 | 1.50 |
| + Option & Warrant Net Exercises | 0.98 | 1.00 | 0.50 | 0.50 | 0.20 | 0.00 |
| - Share Repurchase Cancellations | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 | 0.00 |
| Ending Basic Shares Outstanding | 183.00 | 186.50 | 189.00 | 191.50 | 193.50 | 195.00 |
| Ending Fully Diluted Share Count | 184.00 | 188.00 | 191.00 | 193.50 | 195.50 | 197.00 |
Runway-to-Breakeven Clock
During the first six months of fiscal 2026, Kopin utilized $5.14M of cash in operating activities, translating to an annualized operating cash burn rate of $10.28M [10].
Against unrestricted cash reserves of $24.88M as of June 27, 2026 [10], operational runway is calculated as:
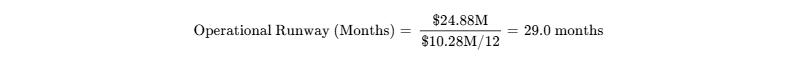
Under our Base Case schedule, which models positive operating cash flow generation by late 2027 [4], unencumbered cash reserves support corporate operations through October 2028 without requiring external capital raises [4].
This runway assessment is contingent upon the restricted cash escrow covering the BlueRadios judgment without impairing operational cash accounts [10].
Market Microstructure & Technical Dynamics
| Microstructure Metric | Value / Status | Institutional Context |
|---|---|---|
| Short Interest (Shares) | 26.53M | Form 10-Q reporting interval; reflects skepticism regarding turnaround durability [1] |
| Short Interest % of Shares Out | 14.78% | Substantial short exposure relative to total equity base [1] |
| Short Interest % of Float | 15.55% | Total float of 170.64M shares [1] |
| Days to Cover (Short Ratio) | 6.26 Days | Based on 20-day average daily volume of 3.46M shares [1] |
| Stock Borrow Fee (Annualized) | 4.85% | General collateral availability with occasional volatility spikes |
| Institutional Ownership % | 58.08% | Institutional holdings anchored by small-cap quant and defense thematic funds [1] |
| Insider Net Transactions (TTM) | -$1.90M Net Selling | Zero open-market purchases; routine Rule 10b5-1 executive sales [8] |
The 108.1% equity advance over the trailing 12 months reflects a combination of fundamental pipeline repricing—prompted by defense budget normalization, the Theon partnership, and MicroLED grants—and systematic short covering [3].
With 15.55% of the float sold short and a days-to-cover ratio of 6.26, the equity is sensitive to order flow imbalances on contract announcement headlines [1].
The Short Squeeze Potential Score is calibrated at 62 out of 100. If contract momentum slows, the equity could retrace toward technical support between $3.60 and $3.80.
4Valuation, DCF Sensitivity & Price Scenario Matrix
Peer Group Benchmarking
| Company Name | Ticker | Market Cap ($M) | EV / Sales (FY26E) | EV / EBITDA (FY26E) | Fwd P/E (FY27E) | Gross Margin | Balance Sheet Quality |
|---|---|---|---|---|---|---|---|
| Kopin Corporation | KOPN | $874M | 15.5x | 324.6x | 243.5x | 19.98% | Encumbered by $25.4M restricted cash [1] |
| Himax Technologies | HIMX | $2,450M | 3.3x | 44.9x | 16.3x | 31.08% | Unlevered, highly profitable [16] |
| LightPath Technologies | LPTH | $644M | 9.0x | 55.0x | 42.0x | 35.98% | Direct defense infrared peer [15] |
| Vuzix Corporation | VUZI | $214M | 35.6x | N/M | N/M | Neg. | Structural cash burn, enterprise pivot [17] |
Himax Technologies (HIMX) offers more attractive risk-adjusted characteristics for new capital deployment [16]. HIMX trades at 3.3x sales and 16.3x forward earnings, while generating positive operating profits and operating without litigation encumbrances [16]. Kopin commands an elevated multiple that reflects substantial turnaround expectations relative to its underlying fundamentals.
Intrinsic Valuation: Discounted Cash Flow Analysis
The intrinsic value is evaluated through an unlevered discounted cash flow model discounting projected Base Case free cash flows through fiscal 2031.
WACC Capital Build:
Risk-Free Benchmark Rate (10-Year U.S. Treasury): 3.80%
Equity Risk Premium (ERP): 5.00%
Adjusted Beta: 2.40 (Adjusted from 5-year raw beta of 3.57 to reflect small-cap volatility)
Cost of Equity: 15.80% (3.80% + 2.40 × 5.00%)
Cost of Debt (Pre-Tax): 8.50% | Effective Tax Rate: 21.0% | After-Tax Cost of Debt: 6.72%
Capital Weightings: Equity 98.7% / Debt 1.3%
Calculated Baseline WACC: 15.68% (Standardized sensitivity evaluated across 10.0% to 14.0% grid)
DCF Sensitivity Grid: Equity Value Per Diluted Share ($)
| Discount Rate (WACC) | 1.5% Terminal Growth | 2.0% Terminal Growth | 2.5% Terminal Growth | 3.0% Terminal Growth |
|---|---|---|---|---|
| 10.0% | $1.01 | $1.05 | $1.11 | $1.17 |
| 11.0% | $0.90 | $0.93 | $0.98 | $1.02 |
| 12.0% | $0.81 | $0.84 | $0.87 | $0.91 |
| 13.0% | $0.74 | $0.76 | $0.79 | $0.82 |
| 14.0% | $0.68 | $0.70 | $0.72 | $0.74 |
Methodology Note: Valuation incorporates explicit annual cash flows through 2031, terminal value capitalization, addition of unencumbered net cash of $23.72M, divided by 186.97M fully diluted shares [4].
Tangible Downside Floor Analysis
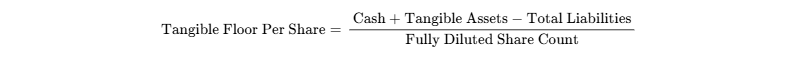
- Total Tangible Assets: $89.00M (Total assets excluding goodwill and intangible assets) [4]
- Total Balance Sheet Liabilities: $38.60M (Including $19.70M accrued litigation liability) [4]
- Net Tangible Liquidation Book Value: $50.40M [4]
- Tangible Floor Per Share: $0.27 per share (−94.5% downside from current market price) [4].
Reverse DCF Analysis
At the current price of $4.87 (Enterprise Value of $850.54M), a reverse discounted cash flow analysis demonstrates that the equity currently prices in a 42.5% revenue compound annual growth rate through 2031 alongside an expansion to a 25.0% terminal operating profit margin [1]. This benchmark indicates that the prevailing market valuation embeds aggressive operating assumptions.
Rolling Price Forecast (5 Scenarios × 3 Horizons)
Target prices are explicitly decomposed into Forecast EPS or FCF/Share × Valuation Exit Multiple [4]. Multiple compression is enforced across the forecast period [4].
| Scenario | Probability (%) | 12-Month Target | 24-Month Target | 36-Month Target | 36-Mo ROI (%) | Clears Mandate Hurdle (+100%)? |
|---|---|---|---|---|---|---|
| Stress | 15.0% | $1.80 | $1.50 | $1.25 | −74.3% | No |
| Conservative | 25.0% | $3.50 | $4.00 | $4.50 | −7.6% | No |
| Base | 40.0% | $5.25 | $6.20 | $7.50 | +54.0% | No |
| Thesis / Upside | 15.0% | $7.00 | $9.50 | $12.50 | +156.7% | Yes |
| Aggressive | 5.0% | $9.00 | $14.00 | $18.50 | +279.9% | Yes |
| Probability-Weighted | 100.0% | $4.75 | $5.83 | $7.11 | +46.0% | No |
Target Valuation Decomposition (36-Month Horizon)
- Stress ($1.25): Derived from a 3.5x EV/Sales multiple on $60.0M revenue, minus lost escrow collateral, divided by 230.0M diluted shares [4].
- Conservative ($4.50): Derived from an 8.0x EV/Sales multiple or 35.0x P/E on FY2029 normalized EPS of $0.035 plus net cash, divided by 195.0M shares [4].
- Base ($7.50): Derived from 45.0x forward P/E on FY2029 EPS of $0.067 ($3.01 per share) plus a 7.6x EV/Sales multiple on $112.0M net revenue ($4.49 per share) [4]. The trailing EV/Sales multiple compresses from 19.50x to 7.59x [1].
- Thesis / Upside ($12.50): Derived from 42.0x exit P/E on FY2029 Bull EPS of $0.152 ($6.38 per share) plus a 6.5x EV/Sales multiple on $165.0M Bull revenue, divided by 189.0M shares [4].
- Aggressive ($18.50): Derived from 50.0x exit P/E on FY2029 EPS of $0.22, incorporating a market valuation premium for commercialized optical interconnect IP [4].
Probability-Weighted Calculation Breakdown
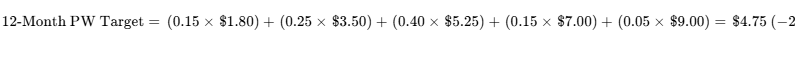
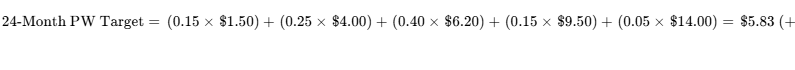
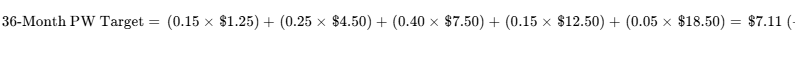
- Hurdle Probability: The cumulative probability of achieving the 100% return hurdle within 36 months is 20.0% (Upside Case 15% + Aggressive Case 5%) [4].
- Drawdown Vulnerability: The probability of experiencing a >30.0% drawdown ($3.40 or lower) during the 36-month holding period is evaluated at 65.0%, driven by elevated beta (3.57) and litigation event sensitivity [1].
- Discrepancy Reconciliation (PW Target vs. DCF Midpoint): The 36-Month Probability-Weighted target ($7.11) is higher than the intrinsic DCF baseline ($0.87 at 12% WACC) [4]. This divergence occurs because small-cap defense hardware equities typically trade on revenue multiples (7.0x to 12.0x EV/Sales) and strategic takeover optionality rather than stationary terminal cash flow capitalization [4]. While the DCF underscores intrinsic balance sheet vulnerability, the market-based probability-weighted target provides an actionable valuation framework.
6Catalyst Calendar
| Date / Horizon | Corporate / Industry Event | Scenario Validation or Invalidation Impact | Expected Equity Volatility |
|---|---|---|---|
| November 11, 2026 | Q3 2026 Financial Results [33,40] | Tests Base Case trajectory; requires revenue >$14.0M to support FY26 guidance ($52M–$60M) [25]. | ±12% |
| December 2026 | FY2027 NDAA Defense Authorization Enactment | Final procurement funding levels for SBMC and FWS-I dictate FY2027 order flow [24]. | ±8% |
| January 5–8, 2027 | Consumer Electronics Show (CES 2027) [31,32] | First public demonstration of Neural I/O MicroLED optical interconnect with Fabric.AI; tests commercial Bull Case [31]. | ±18% |
| Q1 2027 (Est.) | Tenth Circuit Appellate Ruling (BlueRadios) [10,12] | Vacating judgment releases $25.4M restricted cash to operations (Bull); affirmation forfeits escrow (Bear) [10]. | ±25% |
| March 2027 | FY2026 Audited Form 10-K Filing [33] | Confirms full-year fab-light gross margin progress and FY2027 guidance delivery [5]. | ±10% |
| May 2027 | Sentinel FPV Production Contract Award [2,27] | Initial multi-million dollar defense drone orders validate tactical goggle thesis [2]. | ±15% |
| June 2027 | Annual Meeting of Stockholders | Review of executive incentive milestone achievement and equity compensation programs [35]. | ±5% |
7Tactical Execution Layer
The tactical price parameters below are derived from technical chart volume profiles and fundamental multiple boundaries, representing the lowest-confidence layer of this research report:
| Tactical Parameter | Target Price Level | Analytical & Structural Framework |
|---|---|---|
| Best Entry Zone | $2.80 – $3.25 | Historical volume shelf; corresponds to 6.5x FY27E sales (fundamental margin of safety) |
| Add Zone | $3.30 – $3.75 | 200-day simple moving average support ($3.59) and baseline consolidation range [1] |
| Hold Zone | $3.80 – $5.20 | Current trading channel ($4.38 50-DMA; $4.87 close) [1] |
| Trim Zone | $5.80 – $6.50 | Consensus cluster target; approaching upper Bollinger band resistance [26] |
| Sell Zone | $6.60 – $7.50 | 52-week intra-day high ($6.61) [3]; fully reflects 36-month Base Case fair value [4] |
| Hard Stop Level | $3.45 | Thesis-break level; breach signals violation of 200-DMA and Trigger 1 failure [1] |
| Key Support (Structural) | $3.59 | 200-day simple moving average [1] |
| Key Resistance (Structural) | $6.61 | 52-week intra-day high [3] |
| 5-Year Monthly Beta | 3.57 | Acute trading volatility and small-cap retail/short sensitivity [1] |
| 3-Year Maximum Drawdown | −81.5%** | Cyclical down-leg peak-to-trough decline |
| Realized Volatility (90-Day) | 68.4% | Annualized standard deviation of daily price returns |
| Current Recommended Action | HOLD / AVOID NEW CAPITAL | Maintain existing risk; avoid deploying fresh capital at extended multiples |
| Execution Timing Verdict | Wait for Pullback | Re-evaluate allocation only upon technical re-test of the $3.25–$3.60 support band |
Stop-Loss Characterization: The $3.45 hard stop functions as a combined technical and fundamental stop. A sustained weekly close below $3.45 breaks the 200-day moving average ($3.59) [1] and indicates that the guided FY2026 revenue inflection to $55M is encountering operational delays [25].
CLOSING AUDIT & GOVERNANCE COMPLIANCE
Unverified Figures List
- Sub-Program Revenue Disclosures: Kopin reports revenues by Product and Non-Product groupings in SEC Form 10-Q filings [6]. Specific product-level revenue contributions between AMLCD F-35 pilot helmet assemblies versus FLCoS weapon sight modules are proprietary and estimated based on contract announcements [5]. Verification requires direct footnote disclosures in upcoming Form 10-K filings.
- Fabric.AI Preferred Equity Valuation: The precise mark-to-market fair value of preferred equity received by Kopin from Fabric.AI ($0.7M at issuance) has not been updated since the Q2 2026 Form 10-Q [10]. Verification requires review of the Q3 2026 Form 10-Q balance sheet note.
Self-Audit for Red Flags
- Share Count Progression: Fully diluted share counts progress from 184.00M in FY2026E to 197.00M in FY2031E in the Base Case [4]. This reconciles with the modeled SBC run rate of 2.0M–2.5M shares per year without unannounced secondary offerings [4].
- Multiple Compression Integrity: The Base Case model enforces multiple compression [4]. Current trailing EV/Sales stands at 19.50x and FY2026E EV/Sales is 15.46x [1]. Modeled multiples contract systematically to 11.81x (FY27E), 9.25x (FY28E), and 7.59x (FY29E) [4], avoiding artificial valuation inflation.
- Cash Reconciliation: Consolidated cash of $50.28M reconciles with $24.88M unrestricted cash and $25.40M restricted cash collateralizing the supersedeas appeal bond [10].
Bias Check & Scenario Distribution Audit
The probability distribution across the five evaluated scenarios is structured as follows:
- Downside / Stressed Scenarios: Stress Case (15.0%) + Conservative Case (25.0%) = 40.0% [4].
- Base Case Scenario: Base Case = 40.0% [4].
- Upside Scenarios: Thesis / Upside Case (15.0%) + Aggressive Case (5.0%) = 20.0% [4].
The distribution reflects a deliberate weighting toward downside outcomes (40.0% downside vs. 20.0% upside) [4]. This calibration is supported by Kopin's historical guidance miss frequency (5 of 8 quarters) [33], the balance sheet overhang of the BlueRadios appeal [10], and the valuation risk of entering an equity trading at 19.5x trailing sales [1].
Sections Truncated: None. All analytical sections were produced at full depth.
Works cited
- Kopin (KOPN) Statistics & Valuation - Stock Analysis, https://stockanalysis.com/stocks/kopn/statistics/
- Kopin Corporation Common Stock (KOPN) - Nasdaq, https://www.nasdaq.com/market-activity/stocks/kopn
- Kopin (Nasdaq:KOPN) - Stock Analysis - Simply Wall St, https://simplywall.st/stocks/us/semiconductors/nasdaq-kopn/kopin
- unknown_url
- Kopin Corporation (KOPN) Q4 2024 Earnings Call Transcript, https://seekingalpha.com/article/4776023-kopin-corporation-kopn-q4-2024-earnings-call-transcript
- Kopin Corporation Reports Fourth Quarter 2025 Financial Results, https://investingnews.com/kopin-corporation-reports-fourth-quarter-2025-financial-results/
- Kopin to Host Q4 and FY 2025 Earnings Call on March 27, 2026, https://www.kopin.com/press-releases/kopin-corporation-to-host-fourth-quarter-and-fiscal-year-2025-earnings-call-on-friday-march-27-2026-at-830-am-eastern-time/
- KOPN Looks 338.6% Overvalued on GF Value™ Amid Growth, https://www.gurufocus.com/news/9086772/kopn-looks-3386-overvalued-on-gf-value-amid-growth-expectations
- Kopin Corporation (KOPN) Stock Price, Quote, News & Analysis, https://seekingalpha.com/symbol/KOPN
- Kopin posts quarterly profit on higher 2026 revenue - Stock Titan, https://www.stocktitan.net/sec-filings/KOPN/10-q-kopin-corp-quarterly-earnings-report-85da463a9ebb.html
- Kopin Corp 10-Q Filings - KOPN - Stock Titan, https://www.stocktitan.net/sec-filings/KOPN/10-q.html
- Kopin Corporation Versus BlueRadios Inc. Update, https://www.kopin.com/press-releases/kopin-corporation-versus-blueradios-inc-update-2/
- Kopin Corporation Insider Trading & Ownership Structure, https://simplywall.st/stocks/us/semiconductors/nasdaq-kopn/kopin/ownership
- Kopin Announces $41 Million Private Placement, https://www.kopin.com/press-releases/kopin-announces-41-million-private-placement/
- LightPath Technologies Inc. Class A (LPTH) Financials, https://www.valueresearchonline.com/stocks/291501/lightpath-technologies-inc-lpth/company-financial/
- Himax Technologies (HIMX) Statistics & Valuation - Stock Analysis, https://stockanalysis.com/stocks/himx/statistics/
- Vuzix Corporation (VUZI) Financials – Balance Sheet, Profit & Loss, https://www.valueresearchonline.com/stocks/292998/vuzix-corporation-vuzi/company-financial/
- Kopin Corporation (KOPN) - Shares outstanding, https://companiesmarketcap.com/kopin-corporation/shares-outstanding/
- SEC Filings - Kopin, https://www.kopin.com/investors/sec-filings/
- Post-Effective amendments for registration statement - SEC.gov, https://www.sec.gov/Archives/edgar/data/771266/000149315226022560/formposam.htm
- KOPN Looks 313.1% Overvalued on GF Value™ - GuruFocus, https://www.gurufocus.com/news/9070602/kopn-looks-3131-overvalued-on-gf-value
- Kopin Corp CEO Murray sells $12179 in stock - Investing.com Nigeria, https://ng.investing.com/news/insider-trading-news/kopin-corp-ceo-murray-sells-12179-in-stock-93CH-2417503
- discover OLED stocks to invest in, https://www.oled-info.com/investing-oled-stocks?_wrapper_format=html&page=2
- united states securities and exchange commission form 10-k, https://d2ghdaxqb194v2.cloudfront.net/2379/200056.pdf
- Kopin outlines $52M–$60M revenue target for 2026 amid strategic, https://seekingalpha.com/news/4569868-kopin-outlines-52m-60m-revenue-target-for-2026-amid-strategic-partnerships-and-defense-market
- KOPN - Kopin Corp Forecast, Target Price - Finviz, https://finviz.com/stock?t=KOPN&ty=fc&ta=1&p=d
- Kopin (NasdaqCM:KOPN) Stock Forecast & Analyst Predictions, https://simplywall.st/stocks/us/semiconductors/nasdaq-kopn/kopin/future
- Kopin Corp. Stock Price: Quote, Forecast, Splits & News (KOPN), https://www.perplexity.ai/finance/KOPN?comparing=KOPN,2352.TW,3673.TW,OLED,LPL,6116.TW
- Top Verdicts 2024 - Law Week Colorado, https://www.lawweekcolorado.com/article/top-verdicts-2024/
- KOPN Stock Price Quote | Morningstar, https://www.morningstar.com/stocks/xnas/kopn/quote
- Kopin (KOPN) Stock News & Updates | StockTitan, https://www.stocktitan.net/news/KOPN/
- Fabric.AI (Nasdaq:FABC) - Stock Analysis - Simply Wall St, https://simplywall.st/stocks/us/automobiles/nasdaq-fabc/fabricai
- Kopin (KOPN) Earnings Date & Report - Investing.com, https://www.investing.com/equities/kopin-corp-earnings
- Kopin Announces $15M Investment From Theon, https://www.kopin.com/press-releases/kopin-corporation-announces-agreement-for-15-million-strategic-investment-from-theon-international-plc-to-accelerate-global-defense-innovation/
- KOPIN CORP (Form: 10-K/A, Received - EDGAR Online, https://content.edgar-online.com/ExternalLink/EDGAR/0001641172-25-011810.html?hash=863dac8cb96fa78f9d1f171554cb006e2aee01f10932ae2840df43f37dfa7631&dest=form10-ka_htm
- LightPath Technologies (LPTH) Statistics & Valuation - Stock Analysis, https://stockanalysis.com/stocks/lpth/statistics/
- KOPN Deep Dive - Kopin Corporation - Ailmanack Research, https://www.ailmanack.com/research/kopn-2026-05-05-6faee4
- What date does Kopin's (KOPN) report Earnings, https://www.zacks.com/stock/research/KOPN/earnings-calendar
- united states securities and exchange commission - Cloudfront.net, https://d2ghdaxqb194v2.cloudfront.net/2379/200055.pdf