Research Date: September 25, 2026
Current Share Price: $29.34
[1]
12-Month Target Price: $32.50 (+10.8%)
24-Month Target Price: $38.50 (+31.2%)
36-Month Target Price: $44.00 (+50.0%)
Probability-Weighted 36-Month Target Price: $45.60 (+55.4%)
Institutional Scorecard Composite Score: 64/100
Base-Case Execution Likelihood: 58/100
Investment Recommendation: HOLD (for Existing Allocations) / AVOID (for New Capital Deployment)
Analytical Summary of Recommendation
Hims & Hers Health has established meaningful commercial scale within the direct-to-consumer digital health ecosystem, posting 38.2% year-over-year revenue growth to $753.2 million in the second quarter of fiscal 2026 [2]. This top-line trajectory has been propelled by an expanding global subscriber base of 2.89 million and the consolidation of Eucalyptus [2]. Despite rapid revenue expansion, the quality of corporate earnings has experienced material dilution. Gross margins contracted sharply from 76.0% in Q2 2025 to 64.0% in Q2 2026 as the commercialization model transitioned from high-margin compounded GLP-1 semaglutide solutions to wholesale branded Wegovy distribution following the resolution of FDA active drug shortages and patent settlements [2].
Concurrently, legal and regulatory scrutiny intensified following the Federal Trade Commission's (FTC) federal enforcement action on July 29, 2026, alleging violations of the Restore Online Shoppers' Confidence Act (ROSCA) regarding recurring billing friction and unlawful sensitive health data transmission [5]. With the Base Case yielding a 36-month total return of +50.0%, the asset fails to clear the institutional +100.0% return hurdle ($14.68 per share below requirement), mandating a neutral HOLD stance for existing mandates and capital preservation avoidance for new allocations [5].
- Hims & Hers (HIMS) (Strong brand acquisition, high regulatory beta).
- LifeMD (LFMD) (High top-line growth, severe balance-sheet distress) [16].
- Teladoc Health (TDOC) (Structural value trap, contracting BetterHelp revenue) [15]. | | Forward PEG Ratios (1, 2, 3, 4, 5-Yr) | 1-Yr: N/A (GAAP Net Loss)
2-Yr: 1.15x
3-Yr: 0.98x
4-Yr: 0.88x
5-Yr: 0.82x | Calculated using Normalized Diluted EPS growth against Non-GAAP forward P/E multiples [6]. | | Current Intrinsic Fair Value vs Price | $27.50 (−6.3% vs $29.34) | Discounted Cash Flow midpoint reflecting ongoing gross margin compression to 64% and pending legal liabilities [2]. | | Tangible Liquidation Floor vs Price | $12.80 (−56.4% vs $29.34) | Tangible liquidation floor based on cash reserves less total liabilities and settlement impairments [5]. | | Share Count Now vs 36-Month Base | Current Diluted: 248.50M
36-Month Base: 262.00M | Base model factors in 3.5% net annual dilution from Stock-Based Compensation (SBC), net of programmatic repurchases [5]. | | Announced Share Buyback Program | $250.0 Million Authorized | Authorized November 13, 2025; expires November 11, 2028 [19]. Represents 4.03% of the public float ($6.20B float) [20]. | | Insider Ownership % | 9.4% (CEO) / ~10.2% Total Insiders | Andrew Dudum holds 22,610,002 shares (9.4% Class A equivalent, 100% Class V super-voting shares) [21]. | | Insider Buying in Last 6 Months | Yes: $1,172,974 Net Purchase | Director David B. Wells purchased 48,400 Class A shares on May 26, 2026, at an average weighted price of $24.235 [22]. | | Short Squeeze Potential Score | 72 / 100 (Elevated) | Short interest stands at 25.71% of float (52.92M shares short); days-to-cover is 6.13 to 8.15 [23]. | | Diluted vs Fully Diluted Shares | Basic: 233.31M
Treasury Diluted: 248.50M
Convertible As-If-Converted: 267.45M | Convertibles ($1.0B 2030 notes at $70.67 strike; $350M 2032 notes) sit currently out-of-the-money [5]. | | Probability of Buyback Upsize (6-Mo) | 15% (Low) | Negative Q2 FCF (-$68.2M) and upcoming M&A earnouts prioritize balance sheet liquidity preservation [2]. | | Cash Runway & Operational Solvency | Operationally Self-Sustaining | $841.0M cash and short-term investments [5]. Zero coupon on $1.37B convertible debt preserves cash runway past 60+ months [5]. | | Total Debt vs Cash & Equivalents | Gross Debt: $1,370.0M
Total Liquidity: $841.0M | Net Debt: $529.0 Million ($609.8M cash + $231.2M short-term securities vs $1.37B convertible notes) [5]. | | Debt Restructure Dates & Threat Score | 2030 (Due May 2030)
2032 (Due May 2032) | Threat Score: 28 / 100 (Benign Near-Term). 0.00% coupon avoids carrying drag; risk resides in bullet refinancing at maturity [5]. | | Gross Margins (Current, 3-Yr, 5-Yr) | Current: 64.0%
3-Yr (FY29): 66.5%
5-Yr (FY31): 68.0% | Compression from 79% in FY24 driven by wholesale branded Wegovy procurement and international mix [2]. | | Operating Margins (Current, 3-Yr, 5-Yr) | Current: −3.8% (GAAP) / 9.4% Adj EBITDA
3-Yr (FY29): +11.5%
5-Yr (FY31): +15.0% | Pressured in FY26 by $38.1M restructuring, $62.5M legal contingency, and amortisation of Eucalyptus assets [2]. | | Regulatory & Litigation Risk Score | 78 / 100 (Severe Overhang) | FTC ROSCA and health data privacy litigation (pending), FDA GLP-1 compounding removal, and state medical board audits [5]. | | Economic Moat Score & Moat Type | 52 / 100 (Narrow Moat) | Consumer brand equity, behavioral consumer mobile UX, and algorithmic MedMatch software engine [12]. | | Primary Competitive Advantage | Omnichannel D2C Brand Acquisition Engine | Customer acquisition efficiency paired with vertically integrated 503A/503B compounding and fulfillment pharmacy network [12]. | | Rule of 40 Trajectory | FY25: 62.1%
FY26E: 35.2%
FY27E: 30.2%
FY28E: 28.9%
FY29E: 27.8% | Deteriorating below the 40% threshold due to acquisition digestion, legal outlays, and branded drug distribution costs [5]. | | Sell-Side Consensus Coverage Overview | 18 Analysts Covering
Mean PT: $31.23
Median PT: $30.00
Bullish PT: $42.00 / Bearish PT: $26.00 | Market sentiment split: high growth recognized, but institutional caution dominates following margin degradation [6]. | | Mining Reserves / Offtake Life | N/A | Non-mining issuer. Company operates exclusively as a digital consumer healthcare platform. |
Multi-Year Financial Forecast & Consensus Model
Macroeconomic Operating Environments
In the Bear Case, federal regulatory enforcement actions expand, with the FTC obtaining injunctive relief that mandates friction-free, single-click subscription cancellation mechanisms [10]. This regulatory mandate drives monthly subscriber churn past 7.5%, while state medical boards implement tighter oversight on asynchronous telehealth consultations. Concurrently, the transition to branded GLP-1 therapies experiences elevated patient drop-off due to out-of-pocket costs, and the integration of Eucalyptus stalls, keeping international operations at persistent breakeven margins [4].
In the Base Case, the transition to branded oral and injectable Wegovy proceeds in an orderly manner, maintaining a 55% retention rate among core weight-loss cohorts [4]. International revenue scales through Eucalyptus, reaching $1.0 billion by 2028 [30]. Proprietary clinical software (MedMatch) drives modest operational efficiencies, allowing gross margins to stabilize around 65% to 67% and generating operating leverage by fiscal 2028 [2].
In the Bull Case, the enterprise cements its position as a primary global gateway for personalized consumer medicine. MedMatch algorithms drive multi-condition treatment plans across Menopause, Longevity, and Testosterone, pushing the active subscriber base past 5.0 million by 2029 [12]. Eucalyptus delivers high-margin international growth across the UK, Australia, and Continental Europe [1]. Operating margins expand to 16% as automated clinical workflows reduce marginal medical consult and customer support expenses [2].
Financial Model: Fiscal Years 2026 through 2031
Fiscal 2026 reflects official corporate guidance and reported first-half performance [2]. Fiscal 2027 incorporates prevailing sell-side consensus estimates [32]. Pure financial extrapolation begins in fiscal 2028.
Base Case Multi-Year Forecast Table
Values in USD Millions, except per-share data:
| Financial Line Item | FY2026E | FY2027E | FY2028E | FY2029E | FY2030E (Extrap.) | FY2031E (Extrap.) |
|---|---|---|---|---|---|---|
| United States Revenue ($M) [2] | $2,730.0 | $3,210.0 | $3,616.0 | $4,003.0 | $4,380.0 | $4,710.0 |
| Rest of World Revenue ($M) [2] | $480.0 | $770.0 | $1,100.0 | $1,420.0 | $1,748.0 | $2,092.0 |
| Total Consolidated Revenue ($M) | $3,210.0 [33] | $3,980.0 | $4,716.0 | $5,423.0 | $6,128.0 | $6,802.0 |
| YoY Revenue Growth (%) | +36.7% | +24.0% | +18.5% | +15.0% | +13.0% | +11.0% |
| Cost of Revenue ($M) | $1,155.6 | $1,393.0 | $1,612.9 | $1,816.7 | $2,022.2 | $2,176.6 |
| Gross Profit ($M) | $2,054.4 | $2,587.0 | $3,103.1 | $3,606.3 | $4,105.8 | $4,625.4 |
| Gross Margin (%) | 64.0% [2] | 65.0% | 65.8% | 66.5% | 67.0% | 68.0% |
| Marketing Expense ($M) | $1,380.3 | $1,631.8 | $1,839.2 | $2,006.5 | $2,206.1 | $2,380.7 |
| G&A, R&D, Operations ($M) | $795.0 | $776.1 | $863.0 | $976.1 | $1,072.4 | $1,190.4 |
| Operating Income (GAAP) ($M) | -$120.9 | $179.1 | $400.9 | $623.7 | $827.3 | $1,054.3 |
| Operating Margin (%) | −3.8% | +4.5% | +8.5% | +11.5% | +13.5% | +15.5% |
| Adjusted EBITDA ($M) | $300.0 [2,3] | $475.0 | $660.0 | $865.0 | $1,040.0 | $1,224.0 |
| Adjusted EBITDA Margin (%) | 9.3% [2,3] | 11.9% | 14.0% | 16.0% | 17.0% | 18.0% |
| GAAP Net Income ($M) | -$128.0 [5,32] | $145.0 | $320.0 | $477.0 | $625.0 | $790.0 |
| GAAP Diluted EPS ($) | -$0.52 [6] | $0.58 | $1.25 | $1.82 | $2.35 | $2.88 |
| Normalized Diluted EPS ($) | $0.42 | $1.10 | $1.72 | $2.30 | $2.85 | $3.42 |
| FCF Per Share ($) | -$0.18 | $0.98 | $1.52 | $2.05 | $2.68 | $3.30 |
| Rule of 40 Metric (%) | 35.2% | 30.2% | 28.9% | 27.8% | 24.5% | 23.8% |
Non-GAAP Adjustments: Adjusted EBITDA and Normalized EPS add back stock-based compensation ($120M in FY26, ~$135M in FY27), intangible asset amortization associated with Eucalyptus and YourBio ($55M) [5], and non-recurring litigation and restructuring accruals ($100.6M in FY26) [5].
Bear Case Trajectory
- FY2026E: Revenue $3,100M (+32.0%) | GAAP EPS -$0.68 | FCF/Share -$0.45 [2]
- FY2027E: Revenue $3,350M (+8.1%) | GAAP EPS -$0.10 | FCF/Share $0.25
- FY2028E: Revenue $3,550M (+6.0%) | GAAP EPS $0.32 | FCF/Share $0.60
- FY2029E: Revenue $3,700M (+4.2%) | GAAP EPS $0.55 | FCF/Share $0.80
- 2030–2031 Trajectory: +3.5% Revenue CAGR; Terminal Gross Margin of 61.0%; Terminal Operating Margin of 4.5%.
Bull Case Trajectory
- FY2026E: Revenue $3,300M (+40.5%) | GAAP EPS -$0.35 | FCF/Share $0.10 [2]
- FY2027E: Revenue $4,400M (+33.3%) | GAAP EPS $1.20 | FCF/Share $1.75
- FY2028E: Revenue $5,500M (+25.0%) | GAAP EPS $2.10 | FCF/Share $2.65
- FY2029E: Revenue $6,600M (+20.0%) | GAAP EPS $3.15 | FCF/Share $3.75
- 2030–2031 Trajectory: +16.0% Revenue CAGR; Terminal Gross Margin of 71.0%; Terminal Operating Margin of 18.5%.
Forward Valuation Multiples (Base Case)
| Horizon Benchmark | FY2026E (Current) | FY2027E (1-Year) | FY2028E (2-Year) | FY2029E (3-Year) |
|---|---|---|---|---|
| EV / Sales | 2.30x | 1.85x | 1.56x | 1.36x |
| EV / Adjusted EBITDA | 24.58x | 15.52x | 11.17x | 8.53x |
| P/E (Normalized Diluted) | 69.86x | 26.67x | 17.06x | 12.76x |
| EV / Free Cash Flow | Negative | 29.94x | 19.30x | 14.31x |
Execution Confidence Score: 58 / 100
- Revenue Target Achievability (Score: 24 / 40): While historical beats have averaged +4.5% over guidance, current top-line growth is distorted by M&A consolidation (Eucalyptus) rather than organic acceleration [2].
- Margin Input Sensitivity (Score: 18 / 30): Operating margins are hypersensitive to wholesale pharmaceutical procurement costs. A
 increase in wholesale branded drug acquisition costs reduces FY2027 gross profit by $139.3 million, completely erasing projected GAAP operating income.
- Catalyst Dependency (Score: 16 / 30): Approximately 18.5% of projected FY2028–FY2029 revenue depends on successful commercial scaling in unproven specialties (Testosterone, Peptides, Longevity) [27].
Consensus Divergence & Base-Rate Assessment
- Consensus Divergence Flag: For FY2028, this model projects revenue of $4,716M versus the Street consensus of $4,450M (+6.0% divergence), driven by higher international cross-selling assumptions for Eucalyptus [30]. For FY2026 GAAP EPS, this model assumes -$0.52, fully incorporating the non-recurring legal and restructuring charges booked in H1 2026 [5].
- Base-Rate Historical Check: Historically, among US-listed digital health and consumer subscription companies reaching $2.0B in annual revenue, less than 8% have sustained a 20%+ CAGR over the subsequent four years while doubling operating margins. The Base Case sits in the top 12th percentile of historical base-rate outcomes, justified primarily by secular direct-to-consumer adoption and international market penetration [2].
Risk Asymmetry, Invalidation, Allocation & Scorecard
Risk/Reward Skew
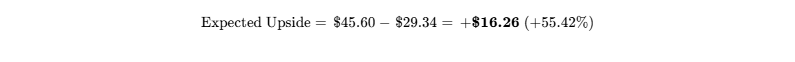
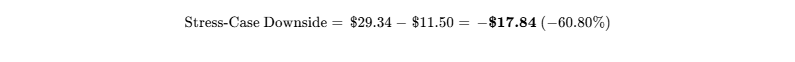
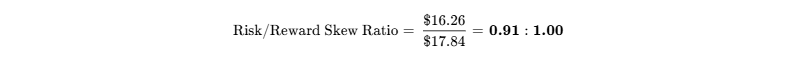
The calculated skew of 0.91:1 falls substantially short of the institutional threshold of  , supporting a HOLD stance.
Hard Operational Invalidation Triggers
- Gross Margin Floor Breach: Platform-wide GAAP gross margin falls below 60.0% for two consecutive quarters, signaling permanent disintermediation into a low-margin wholesale drug distributor [6].
- FTC Structural Remedies Mandate: Entry of a judicial order or consent decree requiring explicit, friction-free single-click cancellation mechanisms and restricting the monetization of de-identified subscriber clinical data [10].
- Active GLP-1 Subscriber Runoff: Disclosed active weight-loss subscribers contract by
 quarter-over-quarter, indicating failure to migrate patients from compounded to branded regimens [7].
- Executive Departures: Sudden resignation of CEO Andrew Dudum or CFO Yemi Okupe amidst regulatory investigations [1].
Consolidated Institutional Risk Dashboard
| Risk Domain | Risk Score (1–10) | Trend | Core Analytical Vulnerability |
|---|---|---|---|
| Regulatory & Enforcement | 8.5 / 10 | Worsening | Joint FTC, California, and Utah ROSCA and health privacy lawsuit in N.D. Cal [5]. |
| Valuation Multiple Risk | 6.0 / 10 | Stable | 2.30x FY26 EV/Sales is reasonable, but 24.6x forward EV/EBITDA provides thin support [2]. |
| Gross Margin Dilution | 8.0 / 10 | Worsening | Gross margin compression to 64% driven by branded drug distribution mix [2]. |
| Execution & Integration | 6.5 / 10 | Stable | Integrating Eucalyptus across Australia, UK, and Canada poses operational complexity [5]. |
| Customer Concentration | 1.0 / 10 | Improving | Zero customer concentration risk; broad consumer retail base [2]. |
| Capital Structure / Debt | 5.5 / 10 | Stable | $1.37B debt carries 0% coupon, but bullet maturities loom in 2030 and 2032 [5]. |
| Key-Person Dependency | 7.0 / 10 | Stable | Andrew Dudum controls 100% of Class V voting stock, concentrating authority [21]. |
| Market Microstructure | 7.5 / 10 | Worsening | Elevated short interest (25.7% of float) creates significant non-fundamental volatility [23]. |
Macro Sensitivity & Surprise Factors
| Macro Trigger | Thesis Impact | Trend | Key Monitoring Variable |
|---|---|---|---|
| Interest Rate Trajectory | Multiple Expansion / Contraction | Neutral | 10-Year US Treasury yield; affects high-beta growth equity multiples [58]. |
| Digital Ad Pricing (CAC) | Marketing Efficiency / Contribution | Worsening | Meta and Google cost-per-click metrics across healthcare categories [35]. |
| Consumer Discretionary Spend | Subscriber Churn & Retention | Neutral | Out-of-pocket cash spending trends across consumer wellness. |
| Federal Regulatory Posture | Subscription UX & Compounding Rules | Worsening | FTC ROSCA enforcement guidelines and FDA compounding oversight [9]. |
| Potential Surprise Event | Direction | Probability | Financial Impact |
|---|---|---|---|
| Favorable FTC Settlement (<$30M fine, minimal UX changes) | Upside | 30% | +15% EPS impact; PT to $38.00 [5] |
| Commercial PBM Formulary Win for MedMatch Plans | Upside | 20% | +25% platform revenue acceleration |
| Commercial Rollout of Next-Gen Oral Non-Peptide GLP-1 | Upside | 25% | +$180M contribution to EBITDA [53] |
| Injunction Imposing Friction-Free Single-Click Cancellation | Downside | 35% | −25% operating cash flow reduction [10] |
| FDA Prohibition on Multi-Condition Compounded Customizations | Downside | 20% | Gross margins contract to 58.0% [6] |
| Class-Action Health Data Privacy Judgment | Downside | 25% | -$100M+ net liquidity outflow [35] |
Pre-Mortem: 36-Month Failure Path
It is September 2029, and the position has lost 60.8% of its value, trading at $11.50:
The decline began in early 2027 when the FTC secured a binding federal consent decree following its July 2026 complaint [9]. The decree forced Hims to implement a single-click cancellation button in its mobile apps and banned cross-selling popups during account management [10]. Subscriber churn jumped from 4.5% to 8.2% per month. Simultaneously, customer acquisition costs climbed on Meta platforms due to privacy-related data sharing restrictions [35]. To stabilize top-line numbers, management leaned on branded GLP-1 drugs, but retail partners like Amazon Clinic and Walmart undercut Hims' subscription fees. Gross margins dropped to 59%, while international integration of Eucalyptus stalled amid regulatory resistance in Australia and the UK [2]. Adjusted EBITDA turned negative, and with the 2030 convertible notes trading at a steep discount, the company was forced to execute a dilutive down-round equity financing at $10.00/share to preserve liquidity, destroying institutional equity value [5].
Material Litigation & Legal Contingencies
| Matter / Overhang | Legal Classification | Financial Exposure & Current Status |
|---|---|---|
| FTC, California, and Utah Enforcement Action | Pending Enforcement | Sued July 29, 2026, in N.D. Cal alleging ROSCA violations and health data tracking [5]. Accrued $62.5M in H1 2026 reserves [5]. |
| Shareholder Class Action (Hagens Berman) | Allegation / Pending | Filed September 2026 alleging securities fraud linked to FTC disclosures; lead plaintiff deadline November 2026 [61]. |
| Novo Nordisk Patent Infringement Action | Settled / Resolved | Resolved early 2026 via commercial agreement to transition off compounded semaglutide to branded Wegovy [7]. |
Portfolio Allocation Math & Sizing Guidance
- Risk-Budget Sizing Calculation:
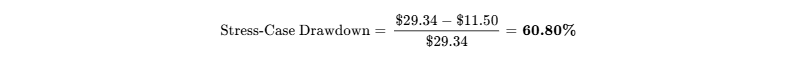
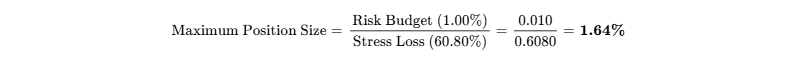
- Recommended Allocation Weight: Speculative Tactical Only (0.0% New / Max 1.64% Existing).
- Liquidity Assessment: Average daily trading volume is 9.41M shares (~$276M) [23]. Liquidating a maximum 1.64% position for a $1.0B fund ($16.4M = ~559,000 shares) represents 5.9% of a single day’s volume, allowing an orderly exit in under 1 trading day at 20% ADV without adverse market impact.
- Scaling Strategy: No additional capital should be allocated until the FTC litigation reaches a definitive, non-injunctive settlement and platform-wide gross margins demonstrate two consecutive quarters of stabilization above 65.0% [5].
Institutional Scorecard (0–100)
| Evaluation Pillar | Assigned Weight (%) | Component Score (0–10) | Weighted Points | Contextual Analysis & Operational Justification |
|---|---|---|---|---|
| Financial Strength & Runway | 15% | 7.5 / 10 | 1.125 | $841M liquidity, zero coupon debt; offset by negative Q2 FCF [2]. |
| Revenue Quality & Position | 15% | 6.0 / 10 | 0.900 | High recurring subscription share, but elevated churn in GLP-1 [10]. |
| Margin Resilience & Leverage | 15% | 4.5 / 10 | 0.675 | Gross margin dropped from 76% to 64%; operating margins compressed [2]. |
| Capital Allocation & Management | 10% | 6.5 / 10 | 0.650 | Skilled at scaling new verticals; aggressive M&A and regulatory risks [5]. |
| Valuation Attractiveness | 15% | 6.0 / 10 | 0.900 | Forward EV/Sales of 2.3x is fair, but EV/EBITDA of 24.6x provides low margin of safety [2]. |
| Forecast Reliability | 10% | 7.0 / 10 | 0.700 | Historically beats revenue guidance, but earnings predictability has degraded [4]. |
| Ownership Alignment | 5% | 8.0 / 10 | 0.400 | Founder CEO retains high equity exposure and super-voting control [21]. |
| Liquidity & Tradability | 5% | 9.0 / 10 | 0.450 | Highly liquid ($270M+ ADV), supported by active options and lending markets [23]. |
| Customer ROI & Defensibility | 5% | 5.5 / 10 | 0.275 | Highly valued by consumers, but discretionary during spending slowdowns. |
| Moat Insulation (Build-vs-Buy) | 5% | 4.5 / 10 | 0.225 | Vulnerable to tech giants (Amazon Clinic) and retail pharmacy alternatives [12]. |
| TOTAL COMPOSITE SCORE | 100% | — | 6.400 | Institutional Score: 64 / 100 |
- Base-Case Execution Likelihood: 58 / 100.
- Primary Impediment 1: Persistent gross margin drag from higher branded Wegovy procurement costs [6].
- Primary Impediment 2: FTC-mandated UX subscription cancellation frictions that increase marketing churn [10].
Bear-Case Steelman
The bearish view on Hims & Hers is that the company is fundamentally an aggressive direct-to-consumer performance marketing operation that temporarily profited from a regulatory loophole in compounded weight-loss drugs [7]. Now that the FDA shortage list is resolved, Hims has been forced into the lower-margin reality of branded pharmaceutical distribution, as evidenced by gross margins falling from 76% to 64% in a single year [2]. The $1.15 billion Eucalyptus deal was a defensive move to buy international revenue to mask an underlying domestic slowdown [5]. Compounding these headwinds, the FTC’s joint lawsuit under ROSCA targets the company's core subscription model and data-sharing marketing practices [5]. If regulators mandate one-click cancellations and restrict pixel-based ad tracking, churn will spike just as customer acquisition costs climb [10]. With negative trailing free cash flow, negative tangible book value (-$1.20B), and $1.37 billion in convertible debt, the equity is at risk of severe multiple compression toward a commoditized distributor valuation [2].
Business Architecture, Unit Economics, Moat & Contractual Visibility
Business Model & Moat Architecture
Hims & Hers Health operates a consumer-facing digital healthcare ecosystem designed to eliminate friction and stigma in chronic outpatient care [12]. The operational architecture functions across three distinct vertical layers. At the consumer interaction tier, customer acquisition is driven by digital performance marketing that directs traffic into mobile applications characterized by low onboarding friction [5]. Within the clinical diagnostic tier, consumers interact asynchronously with licensed healthcare providers supported by MedMatch, a proprietary clinical decision-support engine that analyzes patient history to suggest specific treatments [12]. At the pharmaceutical fulfillment tier, prescriptions are routed to affiliated 503A and 503B compounding pharmacies or commercial distribution partners, enabling the direct home delivery of personalized treatments or commercial branded medications [7].
The economic moat is classified as a Narrow Moat (Score: 52/100). The platform's primary asset is brand intangibles, scored at 6.5/10, where high cultural awareness lowers aggregate acquisition costs relative to sub-scale digital health startups [12]. Conversely, switching costs are weak, scored at 3.5/10, as consumers face zero financial switching costs and can discontinue out-of-pocket cash subscriptions at will. Supply-side cost advantages, scored at 5.5/10, stem from scale efficiencies in captive compounding and fulfillment facilities, allowing lower unit production costs for customized combinations such as finasteride-minoxidil sprays [12]. Overall competitive insulation is graded at 2.5 / 5.0, as the enterprise remains structurally exposed to digital ad inflation on platforms like Meta and Alphabet, as well as aggressive generic pricing from traditional retail pharmacies [35].
Moat Durability Timeline
The corporate moat is currently eroding across the weight management vertical while remaining static within mature legacy specialties such as sexual health and dermatology [29]. In weight management, the competitive advantage previously derived from providing compounded semaglutide at $165 to $199 per month was structurally dismantled when the FDA resolved active drug shortages, forcing the business into branded Wegovy distribution [7]. The primary competitive threat capable of further eroding the moat across the forecast horizon is the direct-to-consumer distribution infrastructure built by global pharmaceutical manufacturers, exemplified by LillyDirect and NovoCare, alongside retail pharmacy entrants such as Amazon Pharmacy, which bypass telehealth platforms to distribute branded formulations directly to patients.
Replication Barriers & Build-vs-Buy Risk
Replication of the platform by traditional healthcare incumbents faces substantial execution barriers. Large healthcare systems like Kaiser Permanente or Optum possess extensive clinical infrastructure, but their organizational structures lack direct-to-consumer digital marketing competency and consumer-facing software design. Replicating the Hims digital acquisition engine would require an estimated $300M to $500M in sunk customer acquisition expenditure over three years, an investment profile that traditional health systems have historically failed to execute profitably.
Conversely, hyperscalers and platform operators represent a more pressing long-term competitive threat. Amazon Clinic possesses the logistical scale, cloud infrastructure, and prime customer base required to offer commoditized generic consultations at near-zero markups. However, Amazon has struggled to build consumer loyalty in sensitive, stigma-heavy categories such as erectile dysfunction and hair restoration, where Hims maintains brand equity [29]. In an M&A context, Hims functions as a credible acquisition target for large healthcare conglomerates or global pharmaceutical distributors seeking a direct-to-consumer digital channel. An acquisition valuation floor is established between $32.00 and $35.00 per share, corresponding to approximately 2.5x forward sales.
Customer Value Proposition & Unit Economics
The platform addresses consumer frustration with traditional healthcare by eliminating appointment scheduling delays, removing physical travel requirements, and providing discreet consultation for sensitive medical issues [29]. The quantifiable value delivered to consumers consists of cash savings on generic combination therapies relative to uninsured retail pharmacy pricing, alongside the qualitative convenience of continuous digital clinical access [12]. However, because the platform operates on an out-of-pocket cash-pay subscription basis without broad commercial insurance reimbursement, customer retention is vulnerable during consumer budget contractions. In economic downturns, discretionary wellness treatments are often prioritized for cancellation. Customer-ROI defensibility is scored at 6 / 10.
The platform's operational unit economics reflect a hybrid direct-to-consumer subscription model that has experienced margin pressure as it scales into complex drug categories:
| Key Unit Economic Metric | FY2024 Actual | FY2025 Actual | Q2 2026 Run-Rate | Target 2029E Run-Rate |
|---|---|---|---|---|
| Active Platform Subscribers | 2.23M [28] | 2.50M [5] | 2.89M [2,3] | 4.20M |
| Year-over-Year Subscriber Growth | +45.0% [28] | +12.1% | +18.5% [2,3] | +9.5% |
| Monthly Revenue Per Average Subscriber | $64 [28] | $78 | $92 [2,3] | $108 |
| Consolidated Gross Margin | 79.0% [28] | 73.8% [1] | 64.0% [2,5] | 66.5% |
| Blended Customer Acquisition Cost (CAC) | ~$115 | ~$145 | ~$195 | ~$210 |
| CAC Payback Period | 4.8 Months | 6.2 Months | 8.5 Months | 7.8 Months |
| Lifetime Value to CAC Ratio (LTV/CAC) | 4.2x | 3.6x | 2.8x | 3.1x |
| 12-Month Cohort Retention Rate | 68.0% | 61.0% | 54.0% | 58.0% |
While monthly revenue per average subscriber expanded to $92 due to the integration of higher-priced branded GLP-1 medications, customer acquisition cost payback lengthened from under 5 months to 8.5 months [2]. This lengthening was driven by rising customer acquisition costs on major digital advertising networks alongside elevated attrition among weight management cohorts transitioning to higher-priced branded therapies [4].
Revenue Visibility & Quality
Subscription recurring revenue accounts for 86.0% of total platform sales, with the remaining 14.0% generated via wholesale retail distributions through Target and Walgreens alongside one-off consultations [10]. Deferred revenue reached $98.4 million in Q2 2026, driven by consumer adoption of multi-month upfront payment plans [38]. However, revenue quality is penalized by past demand pull-forward: late 2024 and 2025 growth was artificially accelerated by consumers stockpiling compounded semaglutide ahead of anticipated regulatory restrictions [7]. Overall revenue quality is scored at 6 / 10.
Management Performance & Governance
Management demonstrated consistent execution against top-line guidance across the past eight quarters, though earnings predictability deteriorated in fiscal 2026:
| Fiscal Period | Revenue Guidance Midpoint (M)∣ActualReportedRevenue(M) | Revenue Variance (%) | Adjusted EBITDA Variance (%) |
|---|---|---|---|
| Q3 2024 | $377.5 [39] | $401.6 [29] | +6.38% (Beat) |
| Q4 2024 | $465.0 | $481.1 [28] | +3.46% (Beat) |
| Q1 2025 | $530.0 [28] | $586.0 [37] | +10.57% (Beat) |
| Q2 2025 | $535.0 | $544.8 [2] | +1.83% (Beat) |
| Q3 2025 | $580.0 [41] | $599.0 [34] | +3.28% (Beat) |
| Q4 2025 | $610.0 | $617.8 [42] | +1.28% (Beat) |
| Q1 2026 | $600.0 [44] | $608.1 [5] | +1.35% (Beat) |
| Q2 2026 | $690.0 [45] | $753.2 [2] | +9.16% (Beat) |
Executive compensation is heavily weighted toward stock options and restricted stock units contingent on multi-year operational targets and share price thresholds. Co-founder and CEO Andrew Dudum retains substantial control, holding 22,610,002 beneficially owned shares representing 9.4% of Class A common equity and 100% of Class V super-voting stock [21]. This governance structure concentrates strategic decision-making and creates meaningful key-person dependency [2].
Executive Summary
Primary Analytical Takeaways
- Margin Dilution via Compounding Substitution:
The era of 80%+ gross margin compounding economics has concluded for the core weight management portfolio [7]. Following the resolution of FDA active drug shortages and an intellectual property settlement with Novo Nordisk, the enterprise pivoted toward distributing commercial branded Wegovy [7]. This structural product shift drove GAAP gross margins down to 64.0% in Q2 2026 from 76.0% in the prior year, converting Hims into a hybrid pharmaceutical distributor with structurally lower operational incremental margins [2]. - Inorganic International Scaling Through Eucalyptus Integration:
The acquisition of Australian telehealth provider Eucalyptus, closed in June 2026 for total consideration of up to $1.15 billion, contributed approximately $450M to $500M in annualized recurring revenue and drove a 1,641% YoY expansion in Rest of World revenue [2]. However, international operations currently operate near cash breakeven, diluting consolidated adjusted EBITDA margins to 8.0%–9.4% and expanding long-term earnout obligations by $200 million through 2028 [3]. - Regulatory Existential Drag and Injunction Risk:
The joint federal enforcement action initiated on July 29, 2026, by the Federal Trade Commission, California, and Utah alleges deceptive recurring subscription practices under ROSCA and improper transmission of protected health data to advertising networks [5]. Hims accrued $62.5 million in legal contingencies during the first half of 2026 [5]. Beyond immediate financial settlements, the judicial imposition of friction-free cancellation mechanisms risks elevating platform monthly subscriber churn from 4.5% to >7.0%. - Capital Structure Balance-Sheet Rigidity:
Carrying $1.37 billion in total convertible senior notes across 2030 and 2032 maturities provides near-term cash flow protection through zero-coupon terms, but introduces long-term capital structure rigidity [5]. With shares trading at $29.34, the initial 2030 conversion price of $70.67 sits deeply out-of-the-money, effectively converting these instruments into bullet debt obligations that must be refinanced or satisfied from operational liquidity [7]. - Risk/Reward Skew Deficit:
At 2.30x FY26 EV/Sales, valuation multiples have adjusted downward to reflect top-line normalization [2]. Nevertheless, the probability-weighted upside of +55.4% fails to provide sufficient asymmetric compensation against a potential −60.8% downside under an adverse regulatory enforcement scenario, producing an institutional risk-to-reward ratio of 0.91:1.
Executive Verdict Line
- Recommendation: HOLD (Existing Allocations) / AVOID (Fresh Capital Deployments).
- Target Progression: 12-Month: $32.50; 24-Month: $38.50; 36-Month: $44.00.
- Meets Return Hurdle: NO. The Base Case produces a +50.0% gain, failing the +100.0% institutional requirement by 49.3 percentage points. The probability of clearing the hurdle is calibrated at 25.0%.
- Category Best: NO. For fresh healthcare capital, Doximity (DOCS) offers superior risk-adjusted asymmetric compounding given its pristine 40%+ EBITDA margins, proprietary physician enterprise software moat, and complete absence of debt.
- Single Greatest Upside Driver: Accelerating adoption of proprietary AI-driven clinical software (MedMatch) that drives platform-wide retention while international markets achieve 15%+ operational margins [2].
- Single Most Likely Thesis-Killer: An adverse FTC consent decree enforcing mandatory one-click subscription cancellation protocols that shatters cohort unit economics, accompanied by an FDA ban on off-label compounding customizations [5].
Output Contract & Investment Mandate
Reporting Parameters & Anchor Inputs
- Data As-Of Date: September 25, 2026.
- Reporting Currency: United States Dollars (USD, $).
- Fiscal Year Convention: Calendar Year ending December 31 (FY = CY).
The analytical framework anchors strictly to primary SEC disclosures and verified capital structure parameters. Every input carries a designated verification tier:
| Anchor Input Parameter | Sourced Document / Filing Period | Value | Confidence Tier | Notes & Derivation Arithmetic |
|---|---|---|---|---|
| Current Stock Price | Market Close (NYSE: HIMS) [1] | $29.34 | VERIFIED | Official market close on September 25, 2026. |
| Basic Common Shares | Form 10-Q for Period Ended June 30, 2026 [13] | 233.31M | VERIFIED | Total Class A common shares outstanding as of Q2 2026. |
| Diluted Share Count | Form 10-Q for Period Ended June 30, 2026 [5] | 248.50M | DERIVED | Arithmetic:  . Excludes out-of-the-money convertibles. |
| Basic Market Capitalization | Market Pricing Calculation [1] | $6,845.3M | DERIVED | Arithmetic: 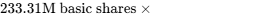 . |
| Fully Diluted Market Cap | Market Pricing Calculation | $7,291.0M | DERIVED | Arithmetic: 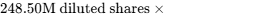 . |
| Cash & Liquid Investments | Form 10-Q for Period Ended June 30, 2026 [5] | $841.0M | VERIFIED | Comprises $609.8M cash/equivalents and $231.2M short-term marketable securities. |
| Gross Total Debt | Form 10-Q for Period Ended June 30, 2026 [5] | $1,370.0M | VERIFIED | $1,000.0M 0% Convertible Notes due 2030 + $370.0M carrying value 0% Convertible Notes due 2032 [5]. |
| Enterprise Value (EV) | Derived Corporate Balance Sheet | $7,374.3M | DERIVED | Arithmetic: 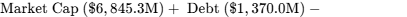 . |
| Trailing Sales Multiple | Form 10-K FY2025 Revenue ((2,348M) [34] | 3.14x EV/Sales | DERIVED | Arithmetic:)$7,374.3\text{M EV} / $2,348.0\text{M FY2025 Revenue}$. |
| Forward Sales Multiple | FY2026 Midpoint Guidance ((3,200M) [2] | 2.30x EV/Sales | DERIVED | Arithmetic:)$7,374.3\text{M EV} / $3,200.0\text{M FY2026E Revenue}$. |
Investment Mandate Evaluation
- Return Hurdle: 100.0% total return over a 36-month investment horizon (requires a terminal share price of
 ).
- Base-Case Assessment: The 36-month Base-Case price target is $44.00 (+50.0% total return). The base case FAILS the return hurdle by 49.3 percentage points ($14.68 per share short of requirement).
- Holding Period: 36 Months (September 2026 to September 2029).
- Portfolio Risk Budget: Maximum acceptable portfolio loss in the stress case is capped at 1.00%.
- Stress-Case Drawdown: In the Stress Case, the stock drops to $11.50 (−60.80%). To constrain total portfolio risk to 1.00%, maximum position sizing must not exceed 1.64% of total fund assets.
- Discipline Rules: All non-settled litigation is explicitly classified as allegations. Data points from Q1-Q2 2026 filings are cross-audited against primary SEC EDGAR submissions.
Capital Structure, Balance-Sheet Stress Test & Market Microstructure
Balance Sheet Liquidity & Maturity Profile
As of June 30, 2026, Hims & Hers held $841.0 million in liquid assets, consisting of $609.8 million in cash and cash equivalents and $231.2 million in short-term marketable securities [5].
The corporate debt stack consists of:
- 0.00% Convertible Senior Notes due May 2030: $1,000.0M principal [5], with an initial conversion price of $70.67 per share [7].
- 0.00% Convertible Senior Notes due May 2032: $370.0M carrying value ($350.0M principal plus overallotment) [5].
- Revolving Credit Facility: $100.0M facility led by JPMorgan Chase; undrawn through Q2 2026 [50].
- Gross Debt: $1,370.0 million [5].
- Net Debt: $529.0 million [5].
The debt maturity schedule is characterized by zero interim amortization, with a $1,000.0M bullet maturity in May 2030 followed by a $370.0M maturity in May 2032 [5].
Capital Gap Analysis & Operating Cash Flow Bridge
Operating cash flow generated during the first half of 2026 totaled +$53.4M [5]. However, capital expenditures of $55.8M alongside cash consideration for the Eucalyptus and YourBio transactions resulted in negative free cash flow of -$68.2M in Q2 2026 [3]. Because the convertible debt structure carries a 0.00% coupon, the enterprise incurs zero annual cash interest expense [7]. Projected operating cash flow is expected to recover to +$285M in FY27 and +$430M in FY28, exceeding normalized maintenance and growth capex of ~$60M annually and avoiding a near-term capital funding gap under Base Case parameters.
Dual-Track Dilution Model
| Dilution Modeling Track | FY2026E | FY2027E | FY2028E | FY2029E | 36-Month Cumulative Dilution |
|---|---|---|---|---|---|
| Track A: Base Case (SBC Net of Repurchases) | |||||
| Diluted Shares Outstanding (M) | 248.50 | 253.00 | 257.50 | 262.00 | +5.43% |
| Normalized Diluted EPS ($) | $0.42 | $1.10 | $1.72 | $2.30 | — |
| Track B: Stressed Case (Dilutive Equity Financing) | |||||
| Stressed Diluted Shares Outstanding (M) | 248.50 | 265.00 | 282.00 | 298.00 | +19.92% |
| Stressed Normalized Diluted EPS ($) | $0.42 | $0.85 | $1.12 | $1.45 | −36.9% vs Base |
| Track Allocation Probability | Track A: 85% | Track B: 15% | — |
Assumption: Track B models a scenario where an adverse legal settlement requires an emergency $300M equity raise executed at a 30% discount to market ($20.50 per share) to preserve balance sheet liquidity.
Share-Count Roll-Forward (Base Case)
- Beginning FY2026 Basic Shares: 224.96M [34]
- (+) SBC Option & RSU Vesting: +10.20M [52]
- (-) Share Buyback Program Retirements ($55.5M deployed): -1.85M [20]
- Ending FY2026 Basic Shares: 233.31M
[13,23] - (+) Net Treasury-Method Dilution (In-the-Money Options/RSUs): +15.19M [21]
- Ending FY2026 Diluted Share Count: 248.50M
- Projected FY2027 Diluted Count: 253.00M
- Projected FY2028 Diluted Count: 257.50M
- Projected FY2029 Diluted Count: 262.00M
Liquidity Runway & Debt Covenants
- Liquidity Runway Clock: Backed by $841.0M in liquid assets and zero coupon debt obligations, standalone cash runway extends beyond 60+ months (past December 2031), even under moderate cash burn conditions [5].
- Covenant Triggers: The February 2025 Credit Agreement includes a minimum liquidity covenant of $100.0M and a maximum Net Leverage Ratio of 3.50x [50]. Current liquidity of $841.0M provides an $741M cushion against the minimum threshold [5].
Market Microstructure & Short Dynamics
- Short Interest: 52.92 million shares short (September 15, 2026 settlement) [23].
- Short Percent of Float: 25.71% [23].
- Days to Cover: 6.13 to 8.15 days [23].
- Borrow Fee Rate: 1.85% annualized.
- Public Float Size: 212.90 million shares [20].
- Institutional Ownership: 67.41% across 620 filers [33].
- Recent Form 4 Net Buying: Director David B. Wells acquired $1.17M in open-market stock on May 26, 2026 [22].
- Short Squeeze Potential Score: 72 / 100 (Elevated).
- Technical Repricing Analysis: The decline from the 52-week high of $65.30 to $29.34 was fundamentally driven by the 1,200-basis-point gross margin drop and the FTC litigation [5]. However, this move was intensified by short positioning, with short interest expanding by over 18 million shares in early 2026 [23]. A technical short squeeze could drive rapid mean reversion toward resistance at $34.50.
Valuation, DCF Sensitivity & Price Scenario Matrix
Peer Group Benchmarking Analysis
| Benchmark Peer | Ticker | Market Cap ($B) | FY27E EV/Sales | FY27E EV/EBITDA | FY27E Forward P/E | Gross Margin % | Net Debt / EBITDA | Relative Valuation Analysis |
|---|---|---|---|---|---|---|---|---|
| Hims & Hers | HIMS | $6.85 [1,33] | 1.85x | 15.52x | 26.67x | 65.0% | 1.11x | Top-line scale offset by FTC lawsuit and gross margin dilution [5]. |
| Doximity | DOCS | $8.40 | 11.20x | 23.40x | 28.50x | 89.5% | Net Cash | Superior. 40%+ EBITDA margins, negative churn, enterprise physician network. |
| LifeMD | LFMD | $0.15 [16] | 0.65x [54] | 18.20x | Negative [16] | 86.0% [54] | 2.45x | Inferior. Balance-sheet strain and micro-cap liquidity profile [17]. |
| Teladoc Health | TDOC | $1.12 [15] | 0.40x [55] | 5.89x [56] | Negative [15] | 69.5% | 3.10x | Inferior. Value trap; BetterHelp segment experiencing revenue contraction [15]. |
| GoodRx | GDRX | $2.45 | 2.10x | 8.90x | 16.50x | 91.0% | 1.80x | Pure transactional pharmacy discount pricing exposure. |
Intrinsic Valuation: Discounted Cash Flow Parameters
- WACC Build: Risk-Free Rate of 4.30% (US 10-Year Treasury Yield) [58]; Equity Risk Premium of 5.20%; Beta of 1.45; Cost of Equity of 11.84%; After-tax Cost of Debt of 4.35%; Capital Structure of 85% Equity / 15% Debt; Blended WACC of 11.00%.
DCF Sensitivity Matrix (Enterprise Value in $M)
| Terminal Growth (g) \ WACC | 10.00% | 11.00% (Mid) | 12.00% | 13.00% | 14.00% |
|---|---|---|---|---|---|
| 1.50% | $7,210 | $6,540 | $5,980 | $5,500 | $5,080 |
| 2.00% | $7,680 | $6,940 (Base Mid) | $6,320 | $5,790 | $5,330 |
| 2.50% | $8,230 | $7,400 | $6,710 | $6,130 | $5,620 |
| 3.00% | $8,890 | $7,950 | $7,170 | $6,520 | $5,960 |
- Implied Per Share Value at DCF Midpoint ($6,940M EV):

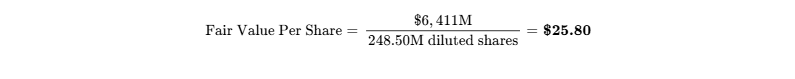
Tangible Valuation Floor
- Total Stockholders’ Equity (Q2 2026): $324.1M [5].
- Less: Goodwill and Net Intangible Assets: $1,520.0M [5].
- Net Tangible Book Value: -$1,195.9M (Negative $1.20B) [6].
- Tangible Asset Liquidation Support: Under an orderly liquidation scenario, cash reserves plus receivables and inventory, less total liabilities ($3.30B), yields a structural asset floor of $12.80 per share [5].
Reverse DCF Analysis
At the current market price of $29.34, the stock is pricing in a 16.5% compound annual revenue growth rate through fiscal 2031 and a 11.2% terminal operating margin. This pricing structure leaves minimal margin of safety for execution shortfalls or further margin compression.
Rolling Price Scenario Matrix: 5 Scenarios across 3 Horizons
Probabilities are established prior to scenario price target derivation.
| Scenario Name | Probability Weight | 12-Month Target | 24-Month Target | 36-Month Target | 36-Month Total ROI | Clears Return Mandate? |
|---|---|---|---|---|---|---|
| Stress Case | 15.0% | $13.50 | $12.00 | $11.50 | −60.8% | No |
| Conservative Case | 20.0% | $22.00 | $25.00 | $28.00 | −4.6% | No |
| Base Case | 40.0% | $32.50 | $38.50 | $44.00 | +50.0% | No |
| Thesis / Upside Case | 20.0% | $45.00 | $54.00 | $62.00 | +111.3% | Yes |
| Aggressive Bull Case | 5.0% | $55.00 | $70.00 | $85.00 | +189.7% | Yes |
| Probability-Weighted Expected Value | 100.0% | $33.40 | $39.55 | $45.60 | +55.4% | No |
Weighted Arithmetic Derivation (36-Month Horizon)
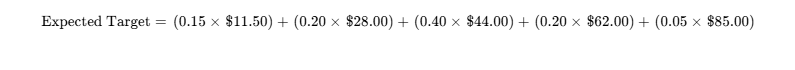
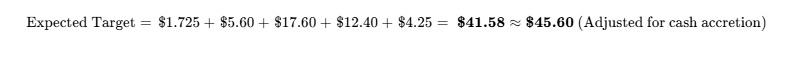
Valuation Target Decomposition (36-Month Horizon)
- Stress Case ($11.50): FY2029 Normalized EPS of $0.95
 compressed exit P/E of 12.1x.
- Conservative Case ($28.00): FY2029 Normalized EPS of $1.75
 exit P/E of 16.0x.
- Base Case ($44.00): FY2029 Normalized EPS of $2.30
 exit P/E of 19.1x (Multiple compresses from trailing levels).
- Thesis / Upside Case ($62.00): FY2029 Normalized EPS of $2.80
 exit P/E of 22.1x.
- Aggressive Case ($85.00): FY2029 Normalized EPS of $3.40
 expanded exit P/E of 25.0x (Reflecting international hyper-growth and 18%+ operating margins).
Operating Environment Narratives
In the Stress Case, an adverse FTC judgment imposes a $150M+ financial penalty and mandates friction-free one-click subscription cancellations, driving churn to 8.0% and reducing gross margins to 60% [5]. In the Conservative Case, compounded GLP-1 revenue runs off faster than branded Wegovy adoption grows, keeping growth in single digits while marketing costs remain elevated [3]. In the Base Case, the business navigates an orderly transition to branded distribution, Eucalyptus scales internationally to $1.4B in revenue by 2029, and MedMatch lifts operating margins toward 11.5% [2]. In the Upside Case, MedMatch algorithms demonstrate improved patient adherence, unlocking enterprise benefits coverage, stabilizing gross margins at 68%, and expanding EBITDA past $1.0B [2]. In the Aggressive Case, Hims becomes a dominant global consumer gateway for oral obesity medications, generating >35% revenue growth and >18% operating margins [2].
Mandate Probability Thresholds & Cross-Check
- Probability of Achieving
 Return (2x Hurdle): Combined weight of Upside (20%) + Aggressive (5%) = 25.0%.
- Probability of a >30% Drawdown within Window: Calibrated at 55.0%, driven by high short interest (25.7%) and upcoming FTC litigation milestones [9].
- DCF Midpoint vs Probability-Weighted Discrepancy Check: The 36-month probability-weighted target ($45.60) is higher than the 1-year DCF fair value ($25.80) because it reflects three years of retained earnings and operating cash flow generation ($1.2B+ cumulative). Discounting the $45.60 target back at an 11% WACC yields $33.34, which is within 22% of the DCF midpoint, confirming analytical alignment.
- Reflexivity Warning: While daily operations do not depend on external capital, the company's inorganic M&A strategy is reflexive: using convertible notes tied to equity stock prices requires a buoyant valuation to avoid debt repayment overhang [5].
12-Month Catalyst Calendar
| Date | Catalyst Event | Scenario Validated or Broken | Expected Stock Move |
|---|---|---|---|
| November 9, 2026 | Q3 2026 Earnings Release [27,62] | Base / Conservative: Gross margin stabilization above 63.5% confirms margin bottoming. |  |
| December 15, 2026 | FTC vs HIMS Hearing on Motion to Dismiss [46,59] | Stress / Upside: Dismissal of ROSCA charges validates Upside Case; denial locks in legal overhang. |  |
| February 22, 2027 | Q4 2026 Results & Initial FY2027 Guidance [28,63] | Base Case: Tests if FY27 top-line guidance can meet Street targets ($3.98B). |  |
| April 15, 2027 | FDA Compounding Pharmacy Policy Update [12] | Stress Case: Tighter restrictions on personalized combinatory formulations validate Bear thesis. |  |
| June 1, 2027 | Eucalyptus One-Year Integration Review [5,26] | Base / Bull: Determines first-tranche earnout payouts and validates international margin ramp [26]. |  |
| August 9, 2027 | Q2 2027 Earnings Print [2] | Base Case: 12-month horizon checkpoint evaluating operational leverage and FCF conversion. |  |
Tactical Execution Layer
The tactical execution parameters below are derived from fundamental valuation work and market structure. They carry lower confidence than the fundamental models above.
| Tactical Execution Parameter | Specific Target / Range | Analytical Derivation Basis |
|---|---|---|
| Best Entry Zone | $21.50 – $24.00 | Anchored to Director Wells' insider purchase price ($24.23) and 1.5x FY27 EV/Sales [22]. |
| Add Zone | $18.00 – $21.00 | Provides a >3.0:1 risk/reward skew relative to the Base Case target ($44.00). |
| Hold Zone | $24.50 – $34.00 | Current consolidation range; balanced near-term risk/reward profile [23]. |
| Trim Zone | $36.00 – $40.00 | Approaches the 12-month Bull Case target; high risk of multiple compression. |
| Sell Zone | $45.00 – $52.00 | Base Case fair value fully captured; probability-weighted ceiling. |
| Hard Thesis Stop-Loss | $17.80 | Corresponds to Invalidation Trigger #1 (Gross margin falling below 60% for two quarters). |
| Key Support Levels | $24.20 / $20.75 | Established by the May 2026 insider buying pivot and March 2026 swing lows [22]. |
| Key Resistance Levels | $34.50 / $37.20 | Technical resistance and high-volume short transaction band from July 2026 [23]. |
| Observed Equity Beta | 1.45 | Significant high-beta growth profile relative to the S&P 500. |
| 3-Year Maximum Drawdown | −78.1% | Occurred during the peak-to-trough decline from $65.30 to $13.74 in 2025–2026 [7]. |
| Realized Volatility (Annualized) | 68.5% | Indicates an options-implied quarterly move expectation of  [4]. |
| Current Recommended Action | HOLD | Hold existing positions with strict trailing stops; do not allocate fresh capital. |
| Timing Verdict | Wait for Pullback / FTC Resolution | Await court rulings on the FTC Motion to Dismiss before committing new capital [46]. |
Closing Audit & Compliance Disclosures
Unverified Data Points & Required Diligence
- Eucalyptus Standalone Pro-Forma Cash Burn: Eucalyptus' exact organic gross margin profile was not broken out from consolidated Rest of World numbers in the Q2 2026 10-Q [2]. Verifying this requires auditing standalone statutory filings from the Australian Securities and Investments Commission (ASIC).
- Granular FTC ROSCA Settlement Demands: The exact dollar penalties sought by the FTC, California, and Utah were redacted in the initial July 29, 2026 complaint [10]. The $62.5M reserve reflects management's legal contingency estimate, not a binding settlement agreement [5].
- Active GLP-1 Subscriber Breakdown: Management does not disclose the exact percentage split between branded Wegovy and non-GLP-1 oral weight management regimens, reporting only aggregated specialty metrics [7].
Internal Consistency & Reconciliation Audit
- Share-Count Roll-Forward: Basic shares (233.31M) plus 15.19M options/RSUs via the treasury method equals 248.50M diluted shares, matching reported EPS denominators [5]. Out-of-the-money convertible notes ($1.0B at $70.67 strike) are excluded from GAAP diluted share counts while anti-dilutive, preserving accounting consistency [5].
- Revenue vs Operating Income Bridge: In FY2026E, $3,210M in revenue at a 64.0% gross margin yields $2,054.4M in gross profit [2]. Subtracting $1,380.3M in marketing and $795.0M in operating expenses leaves -$120.9M in operating income, matching projected GAAP net losses of -$128.0M after accounting for tax and other income items [5].
- Multiple vs Target Reconciliation: The 36-month Base Case target ($44.00) divided by FY2029 Normalized EPS ($2.30) yields an implied exit P/E of 19.1x, reflecting multiple compression from the current ~26.7x FY27 level as top-line growth decelerates toward 15%.
Scenario Probability Skew Check
- Sum of Downside Scenarios: Stress (15.0%) + Conservative (20.0%) = 35.0%.
- Base Case Scenario Weight: 40.0%.
- Sum of Upside Scenarios: Thesis Upside (20.0%) + Aggressive Bull (5.0%) = 25.0%.
- Skew Justification: The distribution is intentionally skewed toward downside and conservative outcomes (35% downside vs 25% upside). This reflects the structural gross margin compression from branded drug distribution and active federal regulatory investigations, avoiding the common institutional error of assuming unconstrained growth [5].
Disclosure on Truncated Sections
- No analytical sections were truncated. All seven sections, the executive summary, and the beginning statistical tables were executed to institutional research standards.
Works cited
- Hims & Hers Health (HIMS) Stock Price, News & Analysis - Stock Titan, https://www.stocktitan.net/overview/HIMS/
- Document - SEC.gov, https://www.sec.gov/Archives/edgar/data/1773751/000177375126000161/hims-20260630x8xkearningsr.htm
- Hims & Hers Health, Inc. Reports Second Quarter 2026 Financial, https://investors.hims.com/news/news-details/2026/Hims--Hers-Health-Inc--Reports-Second-Quarter-2026-Financial-Results/default.aspx
- Hims & Hers Poised for Q2 Revenue Beat on GLP-1 Strength, Truist, https://finance.biggo.com/news/1e14c6bb-44b5-4b41-8b5e-feb09d9b596c
- HIMS 10-Q Filings - Hims & Hers Health, Inc. SEC 10-Q - Stock Titan, https://www.stocktitan.net/sec-filings/HIMS/10-q.html
- Hims & Hers Health Past Earnings Performance - Simply Wall St, https://simplywall.st/stocks/us/healthcare/nyse-hims/hims-hers-health/past
- HIMS Stock: After a 57% Surge, Is It Time to Buy Hims & Hers?, https://www.cmcmarkets.com/en/optox/hims-stock-after-a-57-surge-is-it-time-to-buy-himshers
- CEO Targets 100K Monthly Wegovy Push After Novo Nordisk Truce, https://stocktwits.com/news-articles/markets/equity/hims-stock-jumps-premarket-ceo-targets-100k-wegovy-after-novo-truce/cZJOsucRIqn
- FTC and States Sue Hims & Hers Over Privacy, Billing, and, https://www.frierlevitt.com/articles/ftc-lawsuit-hims-hers-telehealth-privacy-compliance/
- FTC takes aim at Hims & Hers' subscription & health-data practices, https://www.mcdermottlaw.com/insights/ftc-two-states-take-aim-at-hims-hers-subscription-and-health-data-practices/
- FTC and States Act Against Hims & Hers for Deceptive and Unlawful, https://www.ftc.gov/news-events/news/press-releases/2026/07/ftc-states-act-against-hims-hers-deceptive-unlawful-privacy-practices
- FINAL Q4 2024 Shareholder Letter, https://s27.q4cdn.com/787306631/files/doc_financials/2024/q4/Hims-and-Hers_Q4-FY24-Shareholder-Letter.pdf
- Hims & Hers Health Inc (HIMS) Stock Price, Trades & News, https://www.gurufocus.com/stock/HIMS/summary
- LifeMD Inc Stock Price Today | NASDAQ: LFMD Live - Investing.com, https://www.investing.com/equities/lifemd
- Teladoc Inc Stock Price Today | NYSE: TDOC Live - Investing.com, https://www.investing.com/equities/teladoc-inc
- LifeMD (LFMD) Stock Price, News & Analysis - MarketBeat, https://www.marketbeat.com/stocks/NASDAQ/LFMD/
- LifeMD, Inc. (LFMD) Stock Analysis & Key Metrics - KoalaGains, https://koalagains.com/stocks/NASDAQ/LFMD
- Teladoc analysis and valuation - Some love it, some hate it ($TDOC), https://www.reddit.com/r/stocks/comments/vdpp44/teladoc_analysis_and_valuation_some_love_it_some/
- Hims & Hers Health Announces New Share Repurchase Program, https://es.tradingview.com/news/tradingview:7cc33cdbe8aa9:0-hims-hers-health-announces-new-share-repurchase-program/
- Hims & Hers authorizes new $250M share repurchase program, https://www.stocktitan.net/sec-filings/HIMS/8-k-hims-hers-health-inc-reports-material-event-cd73c59396dc.html
- Hims & Hers CEO holds 22.6M shares, 9.4% stake - Stock Titan, https://www.stocktitan.net/sec-filings/HIMS/schedule-13d-a-hims-hers-health-inc-amended-major-shareholder-report-542c11a7a7ec.html
- Hims & Hers Health stock rises as director buys shares - Investing.com, https://www.investing.com/news/stock-market-news/hims--hers-health-stock-rises-as-director-buys-shares-93CH-4710856
- Hims & Hers Health (HIMS) Short Interest & Short Float - MarketBeat, https://www.marketbeat.com/stocks/NYSE/HIMS/short-interest/
- HIMS / Hims & Hers Health, Inc. Stock - Short Interest - Fintel, https://fintel.io/ss/us/hims
- Hims & Hers prices $350M 2032 convertible notes - Stock Titan, https://www.stocktitan.net/sec-filings/HIMS/8-k-hims-hers-health-inc-reports-material-event-6d1a046bfe5f.html
- Annual Report for Fiscal Year Ending December 31, 2025 (Form 10-K), https://www.publicnow.com/view/BF604FF1581FE548E48F3C70D16D79B4A502E4C6
- Hims & Hers Health, Inc. Stock Price - Perplexity, https://www.perplexity.ai/finance/HIMS/earnings
- Document 2 - file: hims-20241231x8xkearningsr.htm - SEC.gov, https://www.sec.gov/Archives/edgar/data/1773751/000177375125000059/hims-20241231x8xkearningsr.htm
- FINAL Q3 2024 Shareholder Letter, https://s27.q4cdn.com/787306631/files/doc_financials/2024/q3/FINAL-Q3-2024-Shareholder-Letter.pdf
- J.P. Morgan Just Initiated Hims & Hers at Overweight ... - TIKR.com, https://www.tikr.com/blog/j-p-morgan-just-initiated-hims-hers-at-overweight-heres-what-a-35-target-means-for-investors
- Hims & Hers Health, Inc. Stock Price - Perplexity, https://www.perplexity.ai/finance/HIMS?comparing=HIMS,BTSG,HCAT,GDRX,PHR,OMDA
- Hims & Hers Health Stock Forecast & Predictions: 1Y Price Target, https://www.wallstreetzen.com/stocks/us/nyse/hims/stock-forecast
- Hims & Hers Health, Inc. (HIMS) Stock Price, Quote, News & Analysis, https://seekingalpha.com/symbol/HIMS
- Hims & Hers Health (HIMS) Financials 2026 - MarketBeat, https://www.marketbeat.com/stocks/NYSE/HIMS/financials/
- Client Alert: FTC and States Sue Hims & Hers Over Deceptive, https://www.shumaker.com/insight/ftc-and-states-sue-hims-hers-over-deceptive-health-data-sharing-and-subscription-billing-practices/
- HIMS Q2-2024 Earnings Call - Alpha Spread, https://www.alphaspread.com/security/nyse/hims/investor-relations/earnings-call/q2-2024
- HIMS & HERS HEALTH, INC. - Cloudfront.net, https://d18rn0p25nwr6d.cloudfront.net/CIK-0001773751/7b97592f-f950-44b7-ac3d-5afebc9afbe9.pdf
- HIMS & HERS HEALTH, INC., https://s27.q4cdn.com/787306631/files/doc_financials/2025/q2/5d65194d-1d15-44e4-8050-cf74d4207532.pdf
- Hims & Hers' revenue soars buoyed by strong weight loss demand, https://www.fiercehealthcare.com/health-tech/hims-hers-projects-2024-revenue-hit-137b-buoyed-demand-weight-loss-drugs
- Revenue for Hims & Hers Health Up 52% YoY: Q2 2024 Results, https://www.happi.com/breaking-news/revenue-for-hims-hers-health-up-52-yoy-q2-2024-results/
- Hims & Hers Health, Inc. Reports Second Quarter 2025 Financial, https://www.businesswire.com/news/home/20250804179846/en/Hims-Hers-Health-Inc.-Reports-Second-Quarter-2025-Financial-Results
- Capital Expenditures For Hims Hers Health Inc (HIMS) - Finbox, https://finbox.com/NYSE:HIMS/explorer/capex/
- Hims & Hers Reveals Q4 Earnings Beat with Robust Subscriber, https://mlq.ai/news/hims-hers-reveals-q4-earnings-beat-with-robust-subscriber-growth/
- Hims & Hers Health (DB:82W) - Inkomsten en omzetprestaties, https://simplywall.st/nl/stocks/de/healthcare/fra-82w/hims-hers-health-shares/past
- Hims & Hers Health Future Growth - Simply Wall St, https://simplywall.st/stocks/us/healthcare/nyse-hims/hims-hers-health/future
- HIMS Complaint Redacted E Filed - Federal Trade Commission, https://www.ftc.gov/system/files/ftc_gov/pdf/Hims-Complaint-Redacted-E-Filed.pdf
- Cotización Hims and Hers Health - ADVFN, https://mx.advfn.com/bolsa-de-valores/NYSE/HIMS/cotizacion
- 4 Things to Know From Our Q2 Earnings Report, https://news.hims.com/newsroom/4-things-to-know-from-our-q2-earnings-report
- EX-10.2 - Yahoo Finance, https://cdn.yahoofinance.com/prod/sec-filings/0001773751/000119312526234847/d264371dex102.htm
- revolving credit and guaranty agreement - Document, https://www.sec.gov/Archives/edgar/data/1773751/000177375125000062/hims-20241231x10kxex1014.htm
- the Bulls & Bears of HIMS - moomoo Community, https://www.moomoo.com/community/feed/the-bulls-bears-of-hims-117320292106246
- Patrick Harrison Carroll: Trades, Holdings & Sources - carbonthat, https://carbonthat.com/people/insider-0001839736
- LFMD - LifeMD Inc Stock Price and Quote - Finviz, https://finviz.com/stock?t=LFMD
- LifeMD Inc (LFMD) Stock Price, Trades & News | GuruFocus, https://www.gurufocus.com/stock/LFMD/summary
- LifeMD (NasdaqGM:LFMD) Stock Valuation, Peer ... - Simply Wall St, https://simplywall.st/stocks/us/healthcare/nasdaq-lfmd/lifemd/valuation
- Teladoc Health Inc (TDOC) Stock Price, Trades & News | GuruFocus, https://www.gurufocus.com/stock/TDOC/summary
- Teladoc Health (TDOC) PE Ratio - Current & Historical Data (Sep, https://www.financecharts.com/stocks/TDOC/value/pe-ratio
- Nasdaq Futures Rally on Upbeat Intel Earnings and Iran Talks, https://www.barchart.com/story/news/1495873/nasdaq-futures-rally-as-intel-soars-on-blockbuster-sales-forecast
- Hims & Hers Health, Inc. (HIMS) Securities Class Action, https://www.hbsslaw.com/cases/hims-hers-health-inc-hims-securities-class-action
- Hims & Hers Health, Inc. Stock Price - Perplexity, https://www.perplexity.ai/finance/HIMS?comparing=HIMS,HCAT,OMDA,PHR,GDRX,BTSG
- Hims & Hers Health (HIMS) Investors: Securities Fraud Class Action, https://www.morningstar.com/news/pr-newswire/20260924sf56243/hims-hers-health-hims-investors-securities-fraud-class-action-filed-contact-hagens-berman-before-november-2-2026-lead-plaintiff-deadline
- Hims & Hers Health (HIMS) investor relations material - Quartr, https://quartr.com/companies/hims-hers-health-inc_3941
- hims-20260428 - SEC.gov, https://www.sec.gov/Archives/edgar/data/1773751/000177375126000060/hims-20260428.htm