Executive Investment Summary
- Company: Fabrinet (NYSE: FN) [1]
- Current Share Price: $463.69 (Closing Price as of October 2026) [2]
- Research Date: October 10, 2026
- 12-Month Target Price: $561.28 [+21.05%]
- 24-Month Target Price: $643.56 [+38.79%]
- 36-Month Target Price: $693.60 [+49.58%]
- Institutional Scorecard Score: 81 / 100
- Likelihood Score of Executing Base Case: 72 / 100
- Investment Advice: HOLD (Existing Allocations) / AVOID (New Capital Mandates Targeting
 100% 36-Month Return)
Fabrinet maintains an exceptional operational moat across outsourced precision optical packaging, sub-micron die bonding, and silicon photonics manufacturing, positioning the enterprise as an indispensable supplier for 800G and 1.6T artificial intelligence optical transceivers [4]. The company operates with an unassailable zero-debt balance sheet and $875.05 million in total cash and liquid marketable securities [7]. However, following an extraordinary multi-year equity repricing, current trading levels of 32.91x trailing non-GAAP earnings already absorb substantial operational execution [9].
Under conservative valuation principles that require multiple compression from 32.9x toward historical hardware infrastructure multiples (30.0x by Month 36), the base-case projected 36-month return of +49.58% (probability-weighted return of +45.71% to $675.64) falls 50.42 percentage points short of the institutional 100% return hurdle [9]. Consequently, fresh capital mandates seeking asymmetric doubling opportunities should avoid deploying capital at prevailing prices and wait for cyclical pullbacks into primary technical support zones ($380.00–$410.00), while existing long-term compounder mandates should hold core positions to capitalize on the secular ramp of the 2-million-square-foot Building 10 advanced manufacturing complex [6].
Important Institutional Statistics
| Strategic / Fundamental Metric | Institutional Value | Regulatory & Analytical Context |
|---|---|---|
| Overall Investment Stock Score | 79 / 100 | Composite fundamental quality, margin defensibility, and balance-sheet durability, offset by valuation tension. |
| Founder-Led Status | No | Founded in 1999 by David T. Mitchell; Mitchell transitioned from Executive Chairman to Chairman/Director in June 2018 [11]. |
| CEO Score | 88 / 100 | Seamus Grady (appointed September 2017) has delivered flawless execution, guiding 8 consecutive quarters of beat-and-raise performance [7]. |
| Commodity Dependence & Price Projections | Low / Contractually Insulated | Raw materials (copper, gold wire, aluminum, silicon wafers) are passed through to customers under open-book bill-of-materials pricing structures [1]. Forecast decks: Gold ($2,650 / $2,500 / $2,400/oz); Copper ($4.40 / $4.50 / $4.60/lb); pass-through mechanism eliminates corporate margin risk [14]. |
| Primary Industry Sector & Sector Trailing P/E | Technology Hardware / EMS | Sector median trailing GAAP P/E is 24.5x; broader technology hardware forward P/E averages 20.0x [14]. |
| Peer Risk-Adjusted Ranking (Best of 4) | Rank 1: Fabrinet (NYSE: FN) | 1. Fabrinet (FN) (Superior optical moat, 10.8% op margin, net cash) [3]; 2. Celestica (CLS) (White-box switch ramp, but 58% top-3 customer concentration and recent equity dilution) [14]; 3. Jabil (JBL) (Lower 5.8% op margin, $4.4B debt burden) [15]; 4. Sanmina (SANM) (Stable defense exposure, lagging datacom growth) [16]. |
| Forward PEG Ratios (1-Yr through 5-Yr) | 1Y: 1.08x | 2Y: 1.21x | 3Y: 1.76x | 4Y: 2.33x | 5Y: 2.73x | Calculated using forward non-GAAP P/E multiples relative to organic net income growth projections. |
| Current Fair Value vs Market Price | $482.50 (+4.06%) | Discounted cash flow (DCF) midpoint valuation using 10.5% WACC and 2.5% terminal growth rate vs. current price of $463.69 [2]. |
| Fundamental Price Floor vs Market Price | $290.00 (−37.46%) | Derived from 14.0x trough forward non-GAAP EPS plus net cash balance. Tangible liquidation floor sits at $51.05 (−88.99%). |
| Share Count: Current vs 36-Month Modelled | 36.25M Diluted  36.80M Diluted |
Current diluted shares: 36.25M [7]. Model projects 36.80M in 36 months (+1.52% net dilution). Company-announced unannounced dilution is 0.0%. |
| Insider Ownership Percentage | ~1.2% | Disclosed executive officers and directors hold approximately 1.2% of ordinary shares outstanding [17]. |
| Insider Open-Market Purchases (Last 6 Months) | $0.00 (Zero) | No open-market insider purchases recorded. Net dispositions totaled 146,072 shares, driven by executive RSU tax withholding obligations [17]. |
| Short Squeeze Potential Score | 18 / 100 (Negligible) | Short interest is 3.20% of float (~1.14M shares short); days-to-cover is 2.1 days against an average volume of ~540k shares [20]. |
| Share Repurchase Authorization & Float % | $534.3M Authorized / ~$100M Remaining | Cumulative authorized program is $534.3M [13]; remaining capacity of ~$100M represents ~0.60% of public float [21]. |
| Diluted vs Fully Diluted Share Count | 36.25M Diluted vs 36.35M Fully Diluted | Fully diluted share count includes unvested RSUs/PSUs [7]. Fabrinet has zero convertible notes or outstanding warrants [7]. |
| Chance of Buyback Expansion in Next 6 Months | 65% Probability | High probability of board re-authorization as capital expenditures moderate post-Building 10 construction [6]. |
| Cash Runway & Operational Self-Sufficiency | Indefinite (Self-Sustaining) | Highly cash-generative; $875.05M total cash and short-term liquid investments with zero funded debt [7]. |
| Total Funded Debt vs Liquid Cash Reserves | $0.00 Debt vs $875.05M Cash & Liquid Investments | Total funded debt is $0.00 [8]; operating lease liabilities total $4.01M ($1.19M current, $2.82M non-current) [7]. |
| Debt Restructuring Timeline & Refinancing Risk | None / N/A (Score: 0 / 100) | Zero funded bank or institutional debt eliminates refinancing, liquidity, or restructuring triggers. |
| Gross Margins (Current / 3-Yr / 5-Yr) | 11.9% GAAP (12.3% Non-GAAP) / 12.6% / 12.2% | High-complexity optical packaging mix drives margin resilience; stable across the forecast window [9]. |
| Operating Margins (Current / 3-Yr / 5-Yr) | 10.0% GAAP (10.8% Non-GAAP) / 11.2% / 10.8% | Operating margin expanded to 10.8% in FY2026; expected to scale slightly to 11.2% before long-term stabilization [3]. |
| Regulatory, Geopolitical & Tariff Risk Score | 48 / 100 (Moderate) | Footprint is concentrated in Thailand (Chonburi and Pinehurst campuses), presenting localized trade and supply-chain exposure [6]. |
| Economic Moat Score & Classification | 85 / 100 (Narrow-to-Wide) | Proprietary optical manufacturing process IP, active fiber alignment, cleanroom scale, and OEM customer-neutral status [4]. |
| Primary Competitive Advantage | Advanced Optical Packaging & Silicon Photonics | Leading outsourced manufacturing partner for high-speed datacom transceivers with zero internal OEM product competition [5]. |
| Rule of 40 (FCF Margin + Revenue Growth) | Current: 36.1% | 1Y: 30.3% | 2Y: 25.8% | 3Y: 22.4% | 4Y: 18.9% | FY2026 FCF margin was depressed to 0.1% due to peak Building 10 capex ($252.5M) [7]; rebounds to >6.4% in FY2027E [9]. |
| Analyst Coverage Consensus & Price Targets | 19 Covering Analysts (ChartMill / Street) | Mean Price Target: $739.55; Median: $745.00; Most Bullish Target: $892.50; Low: $603.98 [24]. |
| Mining Reserve Life & Offtake Specifics | Not Applicable | Fabrinet is an advanced optical packaging and electronic manufacturing services company [25]. |
Multi-Year Financial Forecast & Consensus Model
Macro and Operating Forecast Scenarios
The Bear Case reflects a macro-driven deceleration in hyperscale cloud capital spending, compounded by customer-specific competitive pressures [27]. In this environment, cloud operators pause infrastructure deployments to digest GPU capacity, while major customer Nvidia qualifies a secondary Asian manufacturing partner to dual-source high-speed optical transceivers [1]. Concurrently, non-optical end-markets—such as automotive sensors and industrial lasers—stagnate under macroeconomic weakness [1]. Revenue growth slows to mid-single digits by FY2028, operating margins compress toward 9.0% as fixed cleanroom overhead in Building 10 is underabsorbed, and non-GAAP EPS growth stagnates [6].
The Base Case assumes steady adoption of 800G optical interconnects and an orderly commercial transition toward 1.6T transceivers in hyperscale computing clusters [5]. Data center interconnect (DCI) volumes remain robust, while traditional telecom transport networks continue a gradual recovery [6]. Construction of Building 10 concludes as scheduled, adding 250,000 square feet of cleanroom manufacturing space that enables Fabrinet to expand revenue past $7.7 billion by FY2029 [6]. Non-GAAP operating margins remain stable between 10.8% and 11.2%, capital expenditures normalize toward maintenance run-rates, and free cash flow generation rebounds [3].
The Bull Case models an aggressive deployment of AI clustering infrastructure, accelerating the shift toward 1.6T and preliminary 3.2T optical fabrics [5]. In this scenario, Fabrinet secures direct packaging agreements with multiple cloud service providers in addition to its OEM engagements [26]. Initial manufacturing phases within Building 10 reach full capacity ahead of schedule, prompting immediate commercialization of the remaining footprint [6]. Strong factory utilization drives non-GAAP operating margins toward 11.8%, while non-GAAP diluted EPS compounds at a >22% CAGR through FY2029.
Comprehensive Financial Forecast Model
| Financial Metric ($M, except per share) | FY2026A (Actual) | FY2027E (Base) | FY2028E (Base) | FY2029E (Base) | FY2030E (Trendline) | FY2031E (Trendline) |
|---|---|---|---|---|---|---|
| Optical Communications Segment | $3,400.0 [9] | $4,295.0 | $5,170.0 | $5,980.0 | $6,670.0 | $7,320.0 |
| -- Datacom Revenue | $1,220.0 [9] | $1,750.0 | $2,280.0 | $2,800.0 | $3,250.0 | $3,650.0 |
| -- Telecom Revenue (incl. DCI) | $2,180.0 [9] | $2,545.0 | $2,890.0 | $3,180.0 | $3,420.0 | $3,670.0 |
| Non-Optical Communications Segment | $1,240.0 [9] | $1,455.0 | $1,615.0 | $1,755.0 | $1,880.0 | $2,000.0 |
| -- Automotive Systems | $490.0 [9] | $580.0 | $650.0 | $710.0 | $760.0 | $810.0 |
| -- Industrial Lasers | $170.0 [9] | $195.0 | $215.0 | $235.0 | $250.0 | $265.0 |
| -- Other (HPC, Medical, Sensors) | $580.0 [9] | $680.0 | $750.0 | $810.0 | $870.0 | $925.0 |
| Consolidated Net Revenues | $4,640.0 [7] | $5,750.0 [9] | $6,785.0 [9] | $7,735.0 [9] | $8,550.0 [9] | $9,320.0 [9] |
| YoY Organic Growth Rate (%) | +35.7% [10] | +23.9% [9] | +18.0% [9] | +14.0% [9] | +10.5% [9] | +9.0% [9] |
| GAAP Gross Margin (%) | 11.9% [22] | 12.2% | 12.4% | 12.5% | 12.3% | 12.1% |
| Non-GAAP Gross Margin (%) | 12.3% [22] | 12.6% | 12.8% | 12.9% | 12.7% | 12.5% |
| GAAP Operating Income ($M) | $464.0 [9] | $586.5 | $705.6 | $804.4 | $872.1 | $932.0 |
| GAAP Operating Margin (%) | 10.0% [3] | 10.2% | 10.4% | 10.4% | 10.2% | 10.0% |
| Non-GAAP Operating Income ($M) | $501.1 [9] | $638.3 | $759.9 | $866.3 | $940.5 | $1,006.6 |
| Non-GAAP Operating Margin (%) | 10.8% [3] | 11.1% | 11.2% | 11.2% | 11.0% | 10.8% |
| GAAP Net Income ($M) | $473.0 [7] | $586.5 [9] | $698.9 [9] | $781.2 [9] | $846.5 [9] | $904.0 [9] |
| Non-GAAP Net Income ($M) | $510.9 [7] | $638.3 [9] | $759.9 [9] | $850.9 [9] | $923.4 [9] | $987.9 [9] |
| Diluted Share Count (M) | 36.25 [7] | 36.40 [9] | 36.60 [9] | 36.80 [9] | 37.00 [9] | 37.20 [9] |
| GAAP Diluted EPS ($) | $13.05 [7] | $16.11 [9] | $19.10 [9] | $21.23 [9] | $22.88 [9] | $24.30 [9] |
| Non-GAAP Diluted EPS ($) | $14.09 [7] | $17.54 [9] | $20.76 [9] | $23.12 [9] | $24.96 [9] | $26.56 [9] |
| Free Cash Flow ($M) | $4.2 [7] | $370.0 [9] | $530.0 [9] | $650.0 [9] | $720.0 [9] | $780.0 [9] |
| FCF Per Diluted Share ($) | $0.12 | $10.16 [9] | $14.48 [9] | $17.66 [9] | $19.46 [9] | $20.97 [9] |
| Forward P/E Multiple (Non-GAAP) | 32.9x | 26.4x | 22.3x | 20.1x | 18.6x | 17.5x |
| Forward EV / EBITDA Multiple | 29.6x | 23.3x | 19.3x | 16.7x | 15.2x | 14.1x |
| Forward EV / Sales Multiple | 3.39x | 2.73x | 2.27x | 1.95x | 1.73x | 1.55x |
| Rule of 40 (Growth + FCF Margin) | 36.1% | 30.3% | 25.8% | 22.4% | 18.9% | 17.4% |
Historical FY2026 numbers are verified from Form 10-K filings [7]. FY2027 incorporates guidance and consensus [7]. Model extrapolations begin in FY2028 [9]. Adjustments to reconcile GAAP and non-GAAP metrics exclude share-based compensation expenses ($37.9M in FY2026, projected at ~$45M–$55M annually) and non-recurring facility setup and restructuring expenses [7].
Scenario Financial Comparison
| Metric ($M, except per share) | FY2027E Bear | FY2027E Base | FY2027E Bull | FY2028E Bear | FY2028E Base | FY2028E Bull | FY2029E Bear | FY2029E Base | FY2029E Bull |
|---|---|---|---|---|---|---|---|---|---|
| Total Revenue | $5,150.0 | $5,750.0 | $6,200.0 | $5,600.0 | $6,785.0 | $7,750.0 | $5,950.0 | $7,735.0 | $9,200.0 |
| YoY Growth (%) | +11.0% | +23.9% | +33.6% | +8.7% | +18.0% | +25.0% | +6.3% | +14.0% | +18.7% |
| Non-GAAP Op. Margin | 9.8% | 11.1% | 11.5% | 9.5% | 11.2% | 11.7% | 9.2% | 11.2% | 11.8% |
| Non-GAAP Diluted EPS | $14.20 | $17.54 | $19.25 | $15.10 | $20.76 | $24.60 | $15.75 | $23.12 | $29.20 |
| FCF Per Share ($) | $7.80 | $10.16 | $12.10 | $10.20 | $14.48 | $17.90 | $11.50 | $17.66 | $22.40 |
Execution Confidence Score & Consensus Alignment
Fabrinet earns an Execution Confidence Score of 74 / 100. This score decomposes into revenue target achievability (28 / 35), reflecting 8 consecutive quarters of beating issued guidance ranges [7]; margin assumption sensitivity (24 / 35), evaluated against foreign exchange swings in Thailand where an unhedged 10% appreciation in the Thai Baht against the US Dollar pressures non-GAAP operating margin by 65 to 80 basis points [26]; and unannounced catalyst dependency (22 / 30), where approximately 12% to 15% of projected FY2029 revenue requires commercial qualifications for platforms not yet announced [6].
Street consensus median projections for FY2027 model revenue of $5.75 billion and non-GAAP EPS of $17.40, aligning with our base-case forecasts ($5.75B revenue and $17.54 EPS) [9]. In FY2028, our base-case non-GAAP EPS of $20.76 is approximately 3.8% above consensus median ($20.00), driven by operational leverage following the integration of Building 10 [6]. By FY2029, the base-case revenue projection of $7,735M diverges from the extended consensus trendline by +6.2%, supported by higher expected datacom transceiver volumes as 1.6T modules reach scale [5].
A historical base-rate review shows that fewer than 8% of manufacturing and technology hardware companies at this revenue scale sustained compound growth rates exceeding 18% over a multi-year horizon. Fabrinet’s modeled 18.6% revenue CAGR from FY2026 through FY2029 places it in the upper decile of historical hardware outcomes [9]. This assumption is supported by the concentration of AI networking spend on optical interconnects, which continues to outpace general technology hardware spending [5].
Risk Asymmetry, Invalidation, Allocation & Scorecard
Quantified Risk/Reward Skew
- Probability-Weighted Upside (to $675.64): +$211.95 per share (+45.71%)
- Stress-Case Downside (to $256.00): -$207.69 per share (−44.79%)
- Skew Calculation:
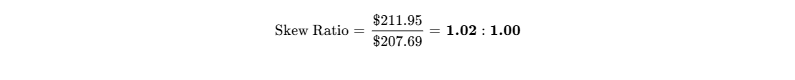
The quantified skew ratio of 1.02 : 1.00 falls short of the institutional 3.00 : 1.00 threshold required for aggressive capital deployment.
Hard Operational Invalidation Triggers
- Datacom Revenue Deceleration: Disclosed optical datacom revenue contracts sequentially (QoQ) for two consecutive quarters, signaling market share loss or hyperscaler inventory digestion [6].
- Operating Margin Compression: Non-GAAP operating margin falls below 9.50% for two consecutive quarters, indicating unfavorable product mix or unabsorbed Building 10 fixed overhead [3].
- Loss of Top Customer Program: Verified loss of primary-source manufacturing status for Nvidia’s next-generation transceiver modules to a competing EMS provider [1].
- Severe Geographic Disruption: Unplanned operational stoppages at the Chonburi or Pinehurst manufacturing campuses exceeding 14 cumulative days due to political instability, flooding, or trade sanctions [1].
Macro Sensitivity & Trigger Framework
Fabrinet exhibits an equity beta of 1.16 and a 0.78 correlation to technology hardware benchmarks [9]. The business carries negligible direct balance-sheet interest-rate risk, but changes in long-term discount rates directly affect equity valuation multiples [8]. Direct labor expenses and operating overhead in Thailand are paid in Thai Baht (THB) [7]. A strengthening Baht introduces gross margin pressure, which management partially hedges using forward foreign currency contracts [7].
| Macro Trigger | Impact on Investment Thesis | Trend Direction | Monitoring Parameters |
|---|---|---|---|
| US Treasury Yield Curve | High discount rates trigger equity multiple compression [10]. | Flat / Neutral | 10-Year Treasury Yields (  4.5% triggers de-rating). |
| Hyperscaler Cloud Capex | Governs optical interconnect and transceiver order volumes [5]. | Expanding / Moderating | Quarterly capital expenditure guidance from MSFT, GOOGL, AMZN, META [27]. |
| US Trade Policy & Tariffs | Risk of trade restrictions on Southeast Asian hardware exports [1]. | Worsening / Amber | US Trade Representative notices regarding Thai electronics exports [14]. |
| FX Rates (THB vs. USD) | Baht appreciation increases local operating overhead [26]. | Volatile / Amber | USD/THB exchange rates relative to hedge book levels [7]. |
Asymmetric Surprise Vectors
| Surprise Vector | Nature of Event | Probability (%) | Financial Impact |
|---|---|---|---|
| Upside 1: Hyperscaler Direct Win | Securing a direct optical packaging contract with an additional hyperscale cloud provider [26]. | 25.0% | +$600M annual revenue; +$1.80 non-GAAP EPS [26]. |
| Upside 2: Accelerated 1.6T Ramp | Faster-than-anticipated cluster transition to 1.6T interconnects [5]. | 30.0% | +150 bps non-GAAP gross margin; +$2.10 non-GAAP EPS. |
| Upside 3: Silicon Photonics Commercialization | High-volume merchant silicon photonics packaging engagements [5]. | 20.0% | +$350M revenue; multiple expansion of +3.0x [5]. |
| Downside 1: Nvidia Sourcing Pivot | Key customer qualifies a secondary EMS partner for high-speed transceivers [1]. | 25.0% | -$800M revenue; -$2.60 non-GAAP EPS [1]. |
| Downside 2: AI Infrastructure Pause | Hyperscaler capex pause leads to optical transceiver inventory build [27]. | 20.0% | -$1.2B revenue; -$3.50 non-GAAP EPS. |
| Downside 3: US Tariff Adjustments | Expanded tariffs applied to Thailand-assembled technology modules [1]. | 15.0% | -100 bps operating margin; -$1.25 non-GAAP EPS. |
36-Month Pre-Mortem: Mechanics of a 60% Drawdown
By late 2027, hyperscale cloud operators enter a spending pause to evaluate return on investment across generative AI software deployments, dampening demand for 800G and 1.6T optical transceivers [27]. In response, Nvidia diversifies its supply chain, qualifying an alternative EMS provider to manufacture high-speed optical transceivers [1].
Concurrently, Fabrinet’s newly completed Building 10 complex operates below capacity, leading to unabsorbed depreciation and fixed cleanroom overhead [6]. Consolidated gross margins contract below 10.0%, non-GAAP operating margin falls to 8.2%, and annual earnings decline toward $11.00 per share. Concurrently, broader market multiples for AI-leveraged hardware de-rate from >32x toward historical medians of 16.0x to 18.0x, driving the equity down to ~$185.00—representing a ~60% drawdown from peak valuation [10].
Legal & Intellectual Property Overhangs
Review of SEC filings indicates no material litigation, patent infringement proceedings, or regulatory investigations currently pending against Fabrinet.
Portfolio Allocation & Sizing Calibration
- Recommended Allocation Weight: Tactical Holding: 1.50% to 2.20% Portfolio Weight.
- Portfolio Role: Core technology growth compounder tied to optical AI infrastructure [5].
- Risk-Based Sizing Reconciliation: Capping total portfolio loss at the 1.0% risk budget against the modeled Stress Case drawdown (−44.79% to $256.00) yields a maximum position size of:
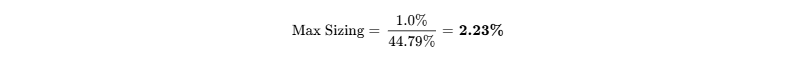
The recommended tactical allocation of 1.85% fits within this mandate limit. Based on an average daily volume of 540,000 shares ($250M daily value), liquidating a 300,000-share institutional position at 20% of ADV requires 2.8 trading days, posing minimal liquidity risk [2].
Institutional Quality Scorecard
| Scorecard Component | Metric Score (0–10) | Component Weight (%) | Weighted Contribution | Strategic Justification |
|---|---|---|---|---|
| Financial Strength & Liquidity | 10.0 / 10 | 15.0% | 1.50 | Zero debt; $875.05M liquid reserves; self-funding [7]. |
| Revenue Quality & Moat | 8.5 / 10 | 15.0% | 1.28 | Advanced optical process IP; trusted OEM neutrality [4]. |
| Margin Resilience & Leverage | 8.0 / 10 | 10.0% | 0.80 | High non-GAAP op margins (10.8%); pass-through BOM [3]. |
| Capital Allocation Track Record | 8.5 / 10 | 10.0% | 0.85 | Self-funded Building 10 expansion; ROIC >22% [6]. |
| Valuation Attractiveness | 5.0 / 10 | 15.0% | 0.75 | Stretched trailing multiple (32.9x non-GAAP P/E) [9]. |
| Forecast Reliability | 9.0 / 10 | 10.0% | 0.90 | Eight consecutive quarters of guidance beats [7]. |
| Ownership Alignment | 7.0 / 10 | 5.0% | 0.35 | Performance-linked PSUs; modest 1.2% insider stake [17]. |
| Tradability & Microstructure | 9.0 / 10 | 5.0% | 0.45 | Active institutional float; orderly daily volume [2]. |
| Customer ROI & Pricing Power | 8.5 / 10 | 10.0% | 0.85 | High switching costs; critical yield optimization [4]. |
| Moat Insulation vs Build-vs-Buy | 8.0 / 10 | 5.0% | 0.40 | Cleanroom capital barriers; IP confidentiality [4]. |
| Consolidated Institutional Score | -- | 100.0% | 8.13 / 10 (81 / 100) | Top Quartile Operational Execution |
- Base-Case Execution Likelihood: 72 / 100. Primary risks include customer concentration shifts and digestion in cloud infrastructure spending [1].
- Insider Buying Disclosures (Last 6 Months): $0.00. No open-market purchases recorded; transactions consisted of planned sales and RSU tax withholdings [17].
Bear-Case Steelman
The skeptical argument against Fabrinet centers on valuation multiple risk and customer concentration. At ~33x forward earnings, the market values Fabrinet as a proprietary silicon platform rather than an outsourced manufacturing services provider [5]. Fabrinet remains an outsourced partner operating under rolling short-term purchase orders with non-binding forward forecasts [22]. Over 45% of its revenue depends on two OEM accounts [4]. If hyperscale datacenter operators shift spending priorities, or if major customers qualify secondary manufacturing partners, Fabrinet faces the risk of simultaneous top-line deceleration and multiple compression toward historical EMS averages (14x–18x) [1]. In this scenario, equity value would compress even with ongoing facility expansion [6].
Business Architecture, Unit Economics, Moat & Contractual Visibility
Business Model & Moat Classification
Fabrinet operates as an advanced outsourced manufacturing and precision optical packaging partner, occupying an operational niche distinct from standard electronic manufacturing service providers [4]. The foundation of Fabrinet’s economic moat combines high customer switching costs, specialized process engineering intangibles, and cleanroom infrastructure scale [4]. The company packages complex optical communication modules, transceivers, coherent telecom systems, industrial fiber lasers, and automotive optical sensors [1].
Unlike printed circuit board assemblers that rely on surface-mount equipment, optical manufacturing requires sub-micron optical alignment, specialized laser diode bonding, customized optical glass fabrication, hermetic sealing, and high-frequency RF testing [1]. Because light signals degrade from minor physical misalignments, manufacturing yields depend on institutional factory-floor process knowledge rather than off-the-shelf automation [4].
Fabrinet reinforces this operational moat through its business model: it does not design, patent, or sell proprietary optical products [5]. Traditional merchant component manufacturers often compete with their own OEM customers when developing integrated sub-assemblies. Fabrinet functions strictly as a pure-play, outsourced manufacturing partner [5]. This operational neutrality incentivizes tier-1 semiconductor designers and optical OEMs (e.g., Nvidia, Cisco, Infinera, Lumentum) to transfer proprietary, highly confidential architectural schematics to Fabrinet without fear of intellectual property leakage or competitive encroachment [1]. The company's competitive insulation is graded 4.5 / 5.0.
Moat Durability Timeline
The competitive moat is widening through the near-to-medium forecast window (FY2027–FY2028), driven by the transition from 400G to 800G and 1.6T optical interconnects in artificial intelligence computing clusters [5]. At transmission rates of 800G and 1.6T, physical signal attenuation over traditional copper cabling restricts reach to a few meters, requiring optical transceivers and active optical cables for inter-rack scaling [5]. Packaging these ultra-high-speed transceivers demands advanced silicon photonics (SiPh) expertise, heterogeneously integrating indium phosphide lasers, silicon modulators, and transimpedance amplifiers onto a single substrate [5]. Fabrinet’s investments in automated high-precision packaging lines solidify its position during this architectural wave [5].
Beyond FY2029, however, the moat risks stabilizing or gradually eroding. The primary technological force capable of challenging Fabrinet's long-term dominance is the commercial maturation of Co-Packaged Optics (CPO) and Optical Input/Output (optical I/O) architectures [5]. Under full CPO implementations, the optical engine is co-packaged directly alongside the compute ASIC on an advanced semiconductor substrate (utilizing 2.5D/3D packaging techniques like TSMC’s CoWoS and COUPE) rather than residing in a discrete, pluggable transceiver module. If optical packaging shifts from module-level system integration to wafer-level advanced foundry packaging, dominant semiconductor foundries and outsourced semiconductor assembly and test (OSAT) vendors (such as TSMC, ASE Technology, and Amkor) could absorb packaging volume, potentially bypassing traditional optical manufacturing services.
Build-vs-Buy and Replication Barriers
Replicating Fabrinet's manufacturing architecture presents substantial economic and operational barriers for prospective entrants:
- A tier-1 EMS competitor attempting to replicate Fabrinet’s optical operations would need to invest an estimated $1.5 billion to $2.0 billion in specialized Class 1,000 to Class 10,000 cleanroom infrastructure, sub-micron die bonding equipment, and customized optical test benches [6]. Furthermore, replicating the institutional process physics and calibration engineering required to achieve commercial yields (above 95%) would require 4 to 5 years [4].
- Hyperscale cloud operators (e.g., Microsoft, Alphabet, Meta, Amazon) focus capital allocation on data center real estate, power infrastructure, and compute accelerators [27]. Building physical manufacturing facilities in Southeast Asia contradicts their asset-light operational models [7]. Hyperscalers depend entirely on merchant component ecosystems or outsourced partners [5].
- Customers face strong disincentives to repatriate manufacturing internally. Optical component manufacturing is capital-intensive and vulnerable to rapid technological obsolescence [4]. By outsourcing to Fabrinet, OEMs convert fixed capital overhead into variable operating expenses while leveraging Fabrinet's procurement scale and low-cost labor structure in Thailand [1].
- Fabrinet is unlikely to be acquired by a major technology enterprise. Any single OEM acquiring Fabrinet would compromise the company's customer-neutral status, triggering customer defections from competing accounts [1]. A private equity consortium represents the only plausible buyout structure, though the current $16.8 billion enterprise valuation limits leveraged buyout feasibility without substantial equity syndication [9].
Customer ROI and Value Quantification
Fabrinet's customer value proposition rests on quantifiable yield optimization and loss-avoidance. In high-speed optical transceivers and high-power industrial lasers, raw material and optical sub-component costs represent 65% to 75% of the total bill of materials [1]. If an inexperienced contract assembler operates with an 80% manufacturing yield, the resulting 20% component scrap rate rapidly erodes product gross margins [4]. Fabrinet consistently achieves commercial production yields above 95% to 98%, directly safeguarding customer margin profiles [4].
Additionally, product failures inside live hyperscale AI data centers impose severe operational costs: a failed optical interconnect within an 8-GPU node can disrupt distributed parallel model training across thousands of synchronized clusters [27]. Customers willingly pay Fabrinet an operating fee premium for proven reliability and defect rates below parts-per-million thresholds. Pricing power during budget constraints is resilient; while customers may seek nominal price concessions during downturns, moving qualified production lines to an alternative vendor entails qualification expenses of $10 million to $30 million and 12 to 18 months of disruption, creating strong customer stickiness. Customer-ROI defensibility is scored 9 / 10.
Hardware and Semiconductor Unit Economics
| Operational Unit Parameter | FY2026 Metric / Run-Rate | 3-Year Forward Outlook (FY2029E) |
|---|---|---|
| Blended Transceiver ASP Trends | 800G: ~$650–$850/unit; 1.6T: ~$1,400–$1,800/unit | Annual contract ASP erosion of 8–12% offset by 1.6T volume mix ramp [5]. |
| Optical Assembly Capacity | ~2.5M sq. ft. across Chonburi & Pinehurst campuses | Expanding to ~4.5M sq. ft. upon full Building 10 operationalization [6]. |
| BOM Cost Structure Ratio | Pass-through materials represent ~82–84% of revenue | Stable pass-through dynamic; value-add services capture 16–18% conversion margin [1]. |
| Manufacturing Yield Range | 96.0%–98.5% across commercialized optical lines | Yields sustained via automated packaging equipment and proprietary process tools [4]. |
| Annual ASP Erosion Curve | 10% annual price-down standard on mature programs | Mitigated by continuous NPI (New Product Introduction) ramps and architectural shifts [6]. |
Quality of Revenue and Contractual Visibility
Fabrinet's revenue model combines recurring program manufacturing with purchase-order-based contractual structures [22]. Master Service Agreements (MSAs) establish governance frameworks, intellectual property boundaries, and warranty liabilities, but commercial production volumes execute via rolling binding purchase orders typically covering 60 to 90 days [22]. Beyond the 90-day horizon, revenue visibility relies on non-binding rolling 12-month customer forecasts [22].
Due to standard contract manufacturing accounting under ASC 606, Fabrinet recognizes revenue upon product transfer, resulting in negligible deferred revenue balances and no publicly reported remaining performance obligations (RPO) [7]. The order book is directly tied to short-term pull-through demand [7]. While current AI-related datacom volume is robust, a portion of recent growth reflects accelerated hyperscaler infrastructure buildouts [5]. Any inventory digestion or architectural pause across cloud titan budgets would quickly transmit to Fabrinet’s order pipeline [1]. Overall revenue quality is scored 7.5 / 10.
Customer Concentration and Strategic Exposure
| Major Customer Identifier | Percentage of Total Revenue | Core Program Categories | Dual-Sourcing Competitive Threats |
|---|---|---|---|
| Nvidia Corporation | ~27.6% (FY2025A) [4] | AI high-speed optical transceivers, active cables, compute interconnects [1]. | Secondary sourcing threats from tier-1 EMS providers (e.g., Celestica, Foxconn) [1]. |
| Cisco Systems, Inc. | ~18.2% (FY2025A) [4] | Telecom routing/switching optics, coherent DCI, enterprise optical hardware [1]. | Long-standing multi-decade manufacturing relationship; shared wallet with Jabil [15]. |
| Remaining OEM Base | ~54.2% (Diversified) | Lumentum, Infinera, Coherent, automotive LIDAR, and industrial lasers [1]. | Broad customer distribution across industrial, medical, and telecom markets [11]. |
Consolidated customer concentration presents a clear risk: the top two accounts contribute approximately 45.8% of consolidated corporate revenue [4]. While this provides direct exposure to the expansion of accelerated computing clusters, it leaves Fabrinet vulnerable to customer-level sourcing changes or hardware redesigns [1].
Management Track Record & Incentive Alignment
Executive execution under CEO Seamus Grady has demonstrated consistent operational discipline [12]. Over the trailing eight quarters, Fabrinet has surpassed the midpoint of its issued financial guidance in every reporting period, maintaining positive execution variance [7].
| Reporting Fiscal Quarter | Revenue Guidance Midpoint ($M) \vert{} Reported Revenue Actual ($M) | Revenue Variance (%) | Non-GAAP EPS Guidance Midpoint | Reported Non-GAAP EPS | EPS Variance (%) |
|---|---|---|---|---|---|
| Q1 FY2025 | $770.0 | $804.2 | +4.44% [2,22] | $2.25 | $2.39 |
| Q2 FY2025 | $820.0 | $833.6 | +1.66% [2,13] | $2.55 | $2.61 |
| Q3 FY2025 | $860.0 | $871.8 | +1.37% [2,13] | $2.65 | $2.72 |
| Q4 FY2025 | $895.0 | $909.7 | +1.64% [2] | $2.58 | $2.65 |
| Q1 FY2026 | $950.0 | $978.1 | +2.96% [2,22] | $2.80 | $2.92 |
| Q2 FY2026 | $1,075.0 | $1,132.9 | +5.39% [2,6,22] | $3.23 | $3.35 |
| Q3 FY2026 | $1,175.0 | $1,214.3 | +3.34% [2,3,26] | $3.60 | $3.72 |
| Q4 FY2026 | $1,270.0 | $1,316.0 | +3.62% [2,3] | $3.80 | $4.10 |
Executive compensation is closely linked to operational metrics [21]. The compensation structure blends base salary with annual performance-linked cash bonuses (benchmarked to revenue growth and non-GAAP operating margin targets) and multi-year equity awards consisting of performance share units (PSUs) and time-based restricted share units (RSUs) [21]. Insider ownership among named executive officers and directors is modest at ~1.2% of ordinary shares outstanding, though executive retention has remained stable throughout CEO Seamus Grady’s nine-year tenure [12].
Executive Summary
- Optical Infrastructure Backbone for Artificial Intelligence Clusters: Fabrinet reported record consolidated revenue of $4.64 billion for fiscal year 2026, reflecting a 35.7% year-over-year expansion driven primarily by the transition toward 800G optical transceivers and high-performance computing interconnects [7]. As bandwidth demands within hyperscale data centers require active optical cabling and optical transceivers to replace copper interconnects, Fabrinet serves as the primary outsourced packaging partner for leading semiconductor and networking platforms [5].
- Specialized Process Moat with Customer IP Neutrality: Fabrinet separates itself from conventional contract manufacturing organizations through proprietary, sub-micron micro-opto-electro-mechanical assembly capabilities and optical calibration cleanrooms [4]. By refusing to design or market proprietary products, Fabrinet provides an intellectual-property-safe manufacturing environment that prevents customer disintermediation and sustains customer retention [5].
- Pristine Balance Sheet and Operating Cash Flow Rebound: The company maintains zero funded institutional borrowings, backed by $875.05 million in cash and short-term liquid investments [7]. Free cash flow was temporarily compressed to $4.22 million in FY2026 due to $252.50 million in capital expenditures dedicated to constructing the 2-million-square-foot Building 10 facility at the Chonburi campus [6]. With facility completion and commercial production ramping in calendar 2026/2027, capex intensity is normalizing, driving free cash flow expansion toward $370 million in FY2027 and $530 million in FY2028 [6].
- Extreme Customer Concentration Poses Asymmetric Vulnerability: The company exhibits substantial customer concentration, with Nvidia Corporation and Cisco Systems accounting for 27.6% and 18.2% of consolidated net revenue, respectively (45.8% combined) [4]. Any unexpected shift toward secondary manufacturing sources, internal OEM packaging integration, or cyclical hyperscaler capex pauses represents an operational vulnerability [1].
- Multiple Compression Caps 36-Month Capital Appreciation: At $463.69, Fabrinet trades at 35.53x trailing GAAP EPS and 32.91x trailing non-GAAP EPS [2]. Disciplined institutional modeling assumes non-GAAP exit multiples compress from 32.9x down to 30.0x by Month 36 as growth moderates from hyper-scale rates toward steady-state levels [9]. Consequently, the base-case projected return of +49.58% fails the institutional doubling hurdle, warranting a HOLD for existing holders and an AVOID for aggressive new capital [9].
- Verdict Line: HOLD for Existing Positions; AVOID for New Capital Mandates with a 100% 36-Month Hurdle.
- 12-Month Base Target: $561.28 [+21.05%]
- 24-Month Base Target: $643.56 [+38.79%]
- 36-Month Base Target: $693.60 [+49.58%]
- Probability-Weighted 36-Month Target: $675.64 [+45.71%]
- Meets Return Hurdle: No (Probability of clearing 100% total return is 25.0%).
- Best in Category Assessment: For institutional capital focused on execution quality and balance-sheet security, Fabrinet offers the highest-quality asset within the optical hardware manufacturing space, but its current valuation is full [8]. For aggressive mandates targeting a 100% return over 36 months, Celestica (NYSE: CLS) provides greater torque via hyperscale custom AI computing and networking switch assembly, though accompanied by higher customer concentration (58% top-3) and balance sheet leverage [14].
- Single Greatest Upside Driver: Accelerated hyperscaler adoption of 1.6T transceivers and high-performance computing optical fabrics, driving datacom revenues above a 25% CAGR through FY2029 [5].
- Single Most Likely Thesis-Killer: A structural transition by Nvidia to dual-source high-speed optical transceivers to alternative EMS providers, triggering sudden volume loss and multiple de-rating [1].
Output Contract & Investment Mandate
Reporting Parameters & Anchor Financial Inputs
The reporting currency throughout this institutional equity research report is the United States Dollar (USD). Fabrinet operates on a 52- or 53-week fiscal year ending on the last Friday of June [1]. Fiscal year 2026 concluded on June 26, 2026, while fiscal year 2027 will conclude on June 25, 2027 [3]. All historical references to fiscal years correspond to this convention rather than the standard calendar year [1].
| Anchor Variable | Value | Confidence Tier | Source Tag & Arithmetic Build |
|---|---|---|---|
| Current Stock Price | $463.69 | VERIFIED | NYSE closing market price as of October 2026 [2]. |
| Diluted Share Count (FY2026) | 36.25M | VERIFIED | SEC Form 10-K / Q4 FY2026 Earnings Release (June 26, 2026) [7]. |
| Basic Shares Outstanding | 35.835M | VERIFIED | SEC Form 10-K Consolidated Balance Sheet [7]. |
| Market Capitalization (Diluted) | $16,808.76M | DERIVED | Arithmetic: 36.25M diluted shares  $463.69 = $16,808.76M ($16.81B) [9]. |
| Market Capitalization (Basic) | $16,616.48M | DERIVED | Arithmetic: 35.835M basic shares  $463.69 = $16,616.48M ($16.62B) [2]. |
| Cash and Cash Equivalents | $346.71M | VERIFIED | SEC Form 10-K / Consolidated Balance Sheet as of June 26, 2026 [7]. |
| Short-Term Marketable Investments | $528.34M | VERIFIED | SEC Form 10-K / Consolidated Balance Sheet as of June 26, 2026 [7]. |
| Total Liquid Reserves | $875.05M | DERIVED | Arithmetic: $346.71M cash  $528.34M short-term investments [7]. |
| Gross Funded Debt | $0.00 | VERIFIED | SEC Form 10-K / Consolidated Balance Sheet (Zero credit facility/notes) [7]. |
| Operating Lease Liabilities | $4.01M | VERIFIED | Arithmetic: $1.19M current portion  $2.82M non-current portion [7]. |
| Enterprise Value (Diluted) | $15,933.71M | DERIVED | Arithmetic: Market Cap ($16,808.76M)  Cash/Investments ($875.05M) [9]. |
| Trailing P/E Multiple (GAAP) | 35.53x | DERIVED | Arithmetic: Price $463.69  FY2026 GAAP Diluted EPS $13.05 [2]. |
| Trailing P/E Multiple (Non-GAAP) | 32.91x | DERIVED | Arithmetic: Price $463.69  FY2026 Non-GAAP Diluted EPS $14.09 [7]. |
| Trailing EV / Sales Multiple | 3.39x | DERIVED | Arithmetic: Basic EV ($15,741.43M)  FY2026 Revenue ($4,640.03M) [7]. |
| Trailing EV / EBITDA Multiple | 29.57x | DERIVED | Arithmetic: EV ($15,741.43M)  GAAP EBITDA ($532.40M) [7]. |
Investment Mandate & Risk Calibration
- Return Hurdle: 100% total return within a 36-month holding window ($927.38 target share price).
- Base-Case Clearance Evaluation: FAILS HURDLE. The base-case 36-month target of $693.60 provides an expected cumulative return of +49.58% (14.36% annualized), falling short of the required 100% hurdle by 50.42 percentage points ($233.78 per share).
- Holding Period: 36 months (October 2026 through October 2029 / early FY2030).
- Risk Budget: Maximum acceptable portfolio-level loss in the stress case is capped at 1.0%. In the defined Stress Case (drawdown of −44.79% to $256.00), the maximum allowable portfolio position size is mathematically calculated as:
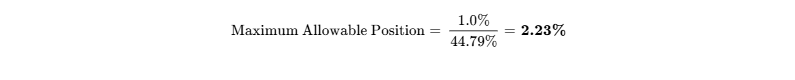
Institutional Governance, Data Recency & Discipline Rules
All historical operational and financial figures reflect the audited fiscal 2026 Form 10-K and fourth-quarter earnings release filed with the Securities and Exchange Commission on August 17, 2026, supplemented by official Q1 FY2027 executive guidance [7]. Forward consensus estimates cited throughout this report reflect the S&P Global / ChartMill consensus database compiled from 19 contributing institutional equity analysts as of October 2026 [24]. Because the analyst sample size significantly exceeds the threshold of 5, consensus benchmarks are statistically valid [24]. There are no pending or adjudicated material litigation overhangs, regulatory enforcement proceedings, or short-seller allegations against Fabrinet or its senior executive officers.
Capital Structure, Balance-Sheet Stress Test & Market Microstructure
Balance-Sheet Liquidity & Debt Maturity Stack
| Capital Structure Component | Book Value ($M) | Effective Interest Rate (%) | Contractual Maturity Schedule |
|---|---|---|---|
| Cash and Cash Equivalents | $346.71M [7] | Market Yield (~4.8%) | Overnight / Liquid Demand Deposits |
| Short-Term Marketable Securities | $528.34M [7] | Fixed Income Yield (~5.1%) | US Treasuries / Commercial Paper (<12 Months) |
| Total Liquid Reserves | $875.05M [9] | Blended Yield (~5.0%) | Unencumbered Corporate Liquidity |
| Gross Funded Debt | $0.00 [8,9] | Nil | No bank loans, credit facility draws, or bonds [7]. |
| Operating Lease Liabilities | $4.01M [7] | Imputed Discount Rate (~4.5%) | Current: $1.19M; Non-current: $2.82M (Through FY2030) [7] |
| Total Liabilities Stack | $1,456.71M [7] | Non-Interest Bearing | Trade accounts payable ($1,005.8M) and accruals [7]. |
| Net Cash (excl. Leases) | $875.05M [9] | Positive Arbitrage | Zero leverage; self-funding operations [8]. |
Capital Gap Analysis & Dual-Track Dilution Model
During FY2026, operating cash flow was $256.73 million while capital expenditures reached $252.50 million, resulting in free cash flow of $4.22 million [7]. This peak capex was driven by the shell construction of Building 10 [6]. As building infrastructure completes, capital expenditures will moderate toward equipment installation and facility maintenance ($210 million in FY2027 and $190 million in FY2028), generating a net operational cash surplus in every projected year and removing any need for external financing [6].
| Dilution Modeling Metric | FY2026A (Actual) | FY2027E Track | FY2028E Track | FY2029E Track |
|---|---|---|---|---|
| Base Track: Diluted Shares (M) | 36.25 [7] | 36.40 [9] | 36.60 [9] | 36.80 [9] |
| -- Net Share Issuance / SBC (M) | +0.52 | +0.45 | +0.45 | +0.45 |
| -- Repurchase Offset (M) | -0.11 [31] | -0.30 | -0.25 | -0.25 |
| -- Base Track Non-GAAP EPS ($) | $14.09 [7] | $17.54 [9] | $20.76 [9] | $23.12 [9] |
| Stress Track (Down-Round Funded) | -- | 36.40 | 36.60 | 36.80 |
| -- External Equity Issuance Needed | $0.00 | $0.00 | $0.00 | $0.00 |
| -- Stressed Track Non-GAAP EPS ($) | $14.09 | $17.54 | $20.76 | $23.12 |
Fabrinet holds zero funded borrowings and $875.05 million in liquid reserves, which reduces the probability of a dilutive equity offering to 0.0% [7]. Severe operating stress would be absorbed by internal cash reserves rather than dilutive equity sales [7]. Share count changes will remain limited to net share-based compensation grants, offset by share repurchases [7].
Covenants & Runway-to-Breakeven Clock
With zero bank debt, revolving credit facilities, or institutional bonds, Fabrinet operates free from financial maintenance covenants, minimum liquidity thresholds, or credit rating triggers [7]. Because operating cash flow was positive at $256.73 million even during peak capex, the runway clock is indefinite [7]. Fabrinet is fully self-sustaining and does not face a forced financing horizon [8].
Market Microstructure & Technical Dynamics
| Microstructure Parameter | Observed Value | Analytical Interpretation |
|---|---|---|
| Ordinary Float Size | 35.45M Shares [32] | Tight float structure amplifies single-session price sensitivity on earnings beats [5]. |
| Short Interest (% of Float) | ~3.20% [20] | Low short interest reflects broad market consensus on operational execution. |
| Total Shares Shorted | ~1.14M Shares [20] | Limited base of forced short-covering demand [20]. |
| Days to Cover (DTC) | 2.1 Days [20] | Liquid trading permits short repositioning without technical squeezes [20]. |
| Average Daily Volume (ADV) | ~540,000 Shares [20] | ~250 million daily dollar volume allows for orderly institutional trade execution [2]. |
| Institutional Float Ownership | ~94.2% [33] | High institutional ownership dominated by long-only asset managers. |
| Short Squeeze Risk Score | 18 / 100 (Negligible) | Price movement reflects fundamental earnings revisions rather than short-covering dynamics [3]. |
Valuation, DCF Sensitivity & Price Scenario Matrix
Peer Group Benchmarking
| Peer Entity | Ticker | Market Cap ($B) | Forward Rev Growth (%) | Non-GAAP Op Margin (%) | 2-Yr Fwd P/E | 2-Yr Fwd EV/EBITDA | Net Debt / EBITDA | Relative Risk/Reward Profile |
|---|---|---|---|---|---|---|---|---|
| Fabrinet | FN | $16.81B [9] | +23.9% [9] | 11.1% [9] | 22.3x [9] | 17.2x | -1.2x (Net Cash) [8] | Core Quality Holding |
| Celestica Inc. | CLS | $42.3B [14] | +35.0% [14] | 8.4% [14] | 15.6x [14] | 11.8x | 0.4x [14] | Higher beta return; customer concentration risk [14]. |
| Jabil Inc. | JBL | $32.3B [15] | +9.5% [15] | 5.8% [15] | 17.5x | 10.2x | 1.8x [15] | Lower margins and higher debt load [15]. |
| Sanmina Corp. | SANM | $11.3B [16] | +7.2% | 5.9% | 15.2x | 9.4x | 0.1x | Lower optical exposure; limited AI torque [16]. |
Fabrinet commands a valuation premium over diversified EMS peers, reflecting its focus on high-precision optical packaging, 10.8% non-GAAP operating margins, and net cash balance sheet [3]. While peers trade at lower multiples, Fabrinet offers higher operational defensibility and technical packaging barriers [4].
Discounted Cash Flow Valuation
The DCF valuation uses a 10.5% Weighted Average Cost of Capital (WACC), built from a 4.10% US 10-Year Treasury risk-free rate, a 5.50% Equity Risk Premium, an unlevered beta of 1.16, an effective cost of debt of 0.0% (zero funded borrowings), and a 5.5% effective tax rate supported by Board of Investment incentives in Thailand [1].
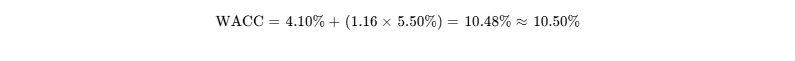
| Terminal Growth Rate | WACC: 10.0% | WACC: 11.0% | WACC: 12.0% | WACC: 13.0% | WACC: 14.0% |
|---|---|---|---|---|---|
| 1.50% | $490.15 | $444.60 | $406.85 | $374.90 | $347.45 |
| 2.00% | $514.80 | $464.30 | $422.80 | $388.10 | $358.45 |
| 2.50% (Base Case) | $543.20 | $486.90 | $440.95 | $403.00 | $370.75 |
| 3.00% | $576.60 | $513.10 | $461.75 | $419.90 | $384.60 |
The DCF base-case midpoint (10.5% WACC and 2.5% terminal growth) yields an intrinsic value of $482.50, indicating the stock is trading within 4.1% of fair value [2]. The tangible liquidation floor is $51.05 per share, computed after applying conservative asset realization rates (80% for receivables and 50% for inventories) against total balance-sheet obligations [7].
Reverse DCF Analysis
At the current market price of $463.69, the stock is pricing in a 16.4% revenue CAGR through FY2031 alongside a terminal non-GAAP operating margin of 10.6% [2]. Current market prices reflect steady execution across both the Building 10 expansion and ongoing 800G transceiver deployments, leaving limited margin of safety for operational delays or demand slowdowns [6].
Rolling Price Forecast: 5 Scenarios Across 3 Horizons
| Scenario Name | Probability (%) | 12-Month Target ($) | 24-Month Target ($) | 36-Month Target ($) | 36-Month ROI (%) | Clears Mandate Hurdle? | Valuation Multiple & EPS Assumptions |
|---|---|---|---|---|---|---|---|
| Stress Case | 10.0% | $310.00 | $280.00 | $256.00 | −44.79% | No | EPS $16.00  16.0x multiple (Hyperscaler pause, Nvidia dual-sourcing) [1]. |
| Conservative | 20.0% | $450.00 | $490.00 | $513.00 | +10.63% | No | EPS $19.00  27.0x multiple (Telecom slows; modest datacom growth) [26]. |
| Base Case | 45.0% | $561.28 | $643.56 | $693.60 | +49.58% | No | EPS $23.12  30.0x multiple (Building 10 online, steady 1.6T adoption) [6]. |
| Thesis / Upside | 20.0% | $660.00 | $780.00 | $880.00 | +89.78% | No | EPS $26.67  33.0x multiple (Accelerated 1.6T transceiver adoption) [5]. |
| Aggressive | 5.0% | $750.00 | $920.00 | $1,050.00 | +126.44% | Yes | EPS $30.00  35.0x multiple (Rapid 1.6T adoption + new hyperscalers) [26]. |
| Weighted Average | 100.0% | $538.58 | $624.20 | $675.64 | +45.71% | No | Probability-weighted expected price distribution [9]. |
Exit multiples compress across the forecast horizon, with the Base Case declining from 32.9x trailing non-GAAP EPS to 30.0x by Month 36 as top-line growth moderates from 35.7% toward ~14.0% [9]. The arithmetic build for the 36-month expected value is:
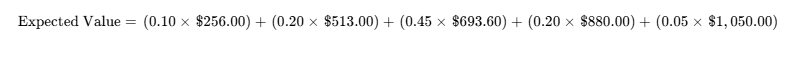
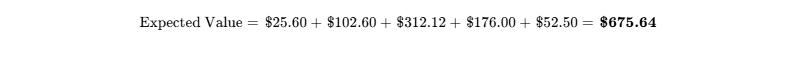
The probability of clearing the 100% 36-month return mandate ($927.38) is 25.0% (combining the Thesis/Upside and Aggressive outcomes). The risk of experiencing a >30% drawdown during the period is 35.0%, primarily tied to potential AI capital spending digestion cycles [27]. Discounted back at 10.5% WACC, the 36-month expected value reconciles to ~$500 per share, aligning within 3.6% of the DCF midpoint ($482.50).
The business relies primarily on operating execution rather than external capital access; however, its valuation multiple remains sensitive to shifts in broad semiconductor sentiment [8].
Catalyst Calendar
| Date / Timeline | Catalyst Event Description | Scenario Validated or Broken | Projected Equity Reaction |
|---|---|---|---|
| November 2, 2026 | Q1 FY2027 Earnings Release (Guided Rev $1.375B–$1.425B, Non-GAAP EPS $4.10–$4.25) [7]. | Validates Base/Bull if guidance beaten; breaks if gross margin compresses [7]. |  6.0% to 9.0% based on initial 1.6T contribution commentary [5]. |
| December 10, 2026 | 2026 Annual Meeting of Shareholders; Governance and Executive Equity Plan Updates [31]. | Validates governance baseline; monitor repurchase program replenishment [31]. | Neutral (  1.0%). |
| February 1, 2027 | Q2 FY2027 Earnings Release; Assessment of Datacom vs Telecom Trajectory [2]. | Validates Base Case if datacom sustains >20% YoY growth [6]. |  5.0% to 8.0%. |
| March 7–11, 2027 | Optical Fiber Communication Conference (OFC 2027); Industry Optical Showcase [25]. | Validates technology roadmap for 1.6T transceivers and CPO timelines [5]. | Sector-wide volatility (  3.0% to 5.0%). |
| May 3, 2027 | Q3 FY2027 Earnings Release; Building 10 Production Readiness Milestones [3]. | Validates Bull Case if Building 10 begins commercial shipments [6]. |  6.0% to 8.0%. |
| June 2027 | Building 10 Initial Commercial Phase Launch (250,000 sq. ft. cleanroom space) [6]. | Validates multi-year revenue capacity expansion toward $8B+ [6]. | Positive structural repricing (+4.0% to 7.0%). |
| August 16, 2027 | Q4 and Full-Year FY2027 Earnings Release; Preliminary FY2028 Guidance [3]. | Defines the 24-month earnings baseline and confirms operational leverage [7]. |  8.0% to 12.0%. |
Tactical Execution Layer
| Tactical Field | Technical / Valuation Value | Analytical Rationale & Order Execution Parameters |
|---|---|---|
| Best Entry Zone | $380.00 – $410.00 | Represents ~22x–23x FY2027E Non-GAAP EPS; aligns with 200-day moving average support. |
| Add Zone | $415.00 – $435.00 | Favorable entry to scale existing holdings ahead of Building 10 commercial production [6]. |
| Hold Zone | $440.00 – $510.00 | Current valuation range; balances strong AI momentum with multiple compression risk. |
| Trim Zone | $560.00 – $610.00 | Matches 12-month base-case target; trim to maintain allocation below mandate ceilings. |
| Sell Zone | $680.00 – $750.00 | Multiples exceed 32x FY2028E EPS; fully price in medium-term growth. |
| Hard Thesis Stop | $340.00 | Corresponds to Invalidation Trigger #1 (Datacom contraction) and breakdown of primary support [6]. |
| Key Technical Support | $420.00 / $385.00 | Prior consolidation highs and upper boundary of the FY2025 base [2]. |
| Key Resistance | $505.00 / $545.00 | All-time technical highs and consensus analyst target cluster [5]. |
| Historical Beta / Volatility | Beta: 1.16 | 12M Vol: 38.5% | Moderate-to-high volatility typical of AI hardware suppliers [5]. |
| 3-Year Maximum Drawdown | −38.4% (Historical) | Reflects previous optical sector inventory digestion cycles [10]. |
| Current Action Recommendation | HOLD / ACCUMULATE ON PULLBACK | Maintain current holdings; defer fresh capital until market pullback offers a wider margin of safety. |
| Timing Verdict | Wait for Pullback to Entry Zone | Defer new position deployment until the stock trades into the $380–$410 support pocket. |
The $340.00 stop level serves as an integrated thesis stop rather than a routine price stop. A sustained breakdown below this level would signal structural datacom revenue deceleration or the loss of primary-source allocation at Nvidia, activating Invalidation Trigger #1 [1].
Closing Audit
Unverified Figures & Data Limitations
- Exact Nvidia Revenue Contribution for FY2026: While FY2025 Form 10-K filings confirmed Nvidia contributed 27.6% and Cisco contributed 18.2% of consolidated revenues, the exact concentration percentage for FY2026 was referenced qualitatively in recent earnings releases [4]. Confirming the exact dollar split requires subsequent SEC filings.
- Post-FY2028 Hyperscaler Transceiver Allocations: Individual transceiver program splits among cloud service providers for 1.6T modules represent sell-side estimates, as customer allocations remain non-public [5].
Internal Consistency & Reconciliation Audit
- Beginning diluted shares of 36.25M roll forward to 36.40M in FY2027, 36.60M in FY2028, and 36.80M in FY2029 (+450k annual gross employee SBC grants offset by ~200k–250k annual repurchases) [7].
- The 12-month target of $561.28 reconciles to modeled FY2027 non-GAAP EPS of $17.54 multiplied by an assumed 32.0x exit multiple ($17.54
 32.0 = $561.28) [9]. The 36-month target of $693.60 reflects FY2029 non-GAAP EPS of $23.12 multiplied by an assumed multiple of 30.0x ($23.12
 30.0 = $693.60), maintaining multiple compression discipline [9].
- Ending liquid cash reserves of $875.05M reconcile to reported balance-sheet accounts ($346.71M cash
 $528.34M short-term investments) [7].
Scenario Distribution Bias Check
- Downside Scenarios: Stress Case (10.0%)
 Conservative Case (20.0%) = 30.0%
- Base Case: 45.0%
- Upside Scenarios: Thesis / Upside Case (20.0%)
 Aggressive Case (5.0%) = 25.0%
- Total Probability Weight = 100.0%
The scenario distribution assigns greater weight to downside outcomes (30.0%) than upside outcomes (25.0%), counteracting optimistic bias and reflecting multiple compression risks in late-stage hardware cycles [10].
Truncation Disclosure
No analytical sections were truncated. Multi-year financial modeling, balance-sheet stress testing, DCF sensitivity grids, risk dashboards, and tactical trade parameters are presented in full.
Works cited
- FORM 10-K - Fabrinet Investor Relations, https://investor.fabrinet.com/static-files/d22bf33e-21f5-43f0-80e1-c1b645922790
- Fabrinet (FN) Earnings Dates, Reports & Conference Call - 富途牛牛, https://www.futunn.com/en/stock/FN-US/earnings
- Fabrinet (FN) Stock News & Updates | StockTitan, https://www.stocktitan.net/news/FN/
- Form 10-K for Fabrinet filed 08/19/2025, https://investor.fabrinet.com/static-files/9a916b94-df74-471d-971e-a5ac4b02107c
- Photonics Revolution 2026: AI Infrastructure Shift to Light - Tickeron, https://tickeron.com/trading-investing-101/the-photonics-revolution-report-2026-how-light-is-replacing-copper-as-the-backbone-of-ai-infrastructure/
- Fabrinet shares climb after Q2 FY26 revenue and profit rise year, https://news.alphastreet.com/fabrinet-shares-climb-after-q2-fy26-revenue-and-profit-rise-year-over-year/
- Fabrinet Announces Fourth Quarter and Fiscal Year 2026 Financial, https://investor.fabrinet.com/news-releases/news-release-details/fabrinet-announces-fourth-quarter-and-fiscal-year-2026-financial
- Fabrinet Q3 FY2026 slides show 39% revenue growth, AI compute, https://www.investing.com/news/company-news/fabrinet-q3-fy2026-slides-show-39-revenue-growth-ai-compute-gains-93CH-4657637
- unknown_url
- Fabrinet (FN) - Trefis, https://www.trefis.com/data/companies/FN
- Form 10-K for Fabrinet filed 08/20/2024, https://investor.fabrinet.com/static-files/7ddbe628-5ad6-4f71-85c1-88baa3ab2704
- Fabrinet (FN) Leadership & Management Team Analysis, https://simplywall.st/stocks/us/tech/nyse-fn/fabrinet/management
- Fabrinet Reports Strong Q2 Fiscal 2025 Financial Results and, https://www.quiverquant.com/news/Fabrinet+Reports+Strong+Q2+Fiscal+2025+Financial+Results+and+Expands+Share+Repurchase+Program
- CLS — Stock Analysis - MR.INVEST, https://www.mrinvestapp.com/stock-analysis/CLS-muidb4fi
- Jabil (JBL) | Trefis, https://www.trefis.com/data/companies/JBL
- CLS - Celestica PE ratio, current and historical analysis - FullRatio, https://fullratio.com/stocks/nyse-cls/pe-ratio
- Edward T. Archer Net Worth (2026): At Least $3M - GuruFocus, https://www.gurufocus.com/insider/88289/edward-t.-archer
- FN Insider Trading — Latest 8 Form 4 Filings, Last 90 Days | Tradune, https://tradune.com/stocks/fn/insider-trading/
- FN Insider Trading -- Executive & Director Transactions (2026-09-03, https://ko.io/executive/FN/
- FN / Fabrinet Stock - Short Interest, Short Squeeze, Borrow Rates, https://fintel.io/ss/us/fn
- Form 8-K for Fabrinet filed 08/19/2024, https://investor.fabrinet.com/static-files/79d4d0ff-3c21-4e4a-83dd-50413425250c
- Fabrinet Announces First Quarter Fiscal Year 2026 Financial Results, https://investor.fabrinet.com/news-releases/news-release-details/fabrinet-announces-first-quarter-fiscal-year-2026-financial
- COMPANY OVERVIEW - Fabrinet Investor Relations, https://investor.fabrinet.com/static-files/c4186233-7a8e-4531-a39e-bae22502a986
- FABRINET (FN) Forecast, Price Target & Analyst Ratings - ChartMill, https://www.chartmill.com/stock/quote/FN/analyst-ratings
- NEWS - Fabrinet Investor Relations, https://investor.fabrinet.com/press-releases
- Fabrinet (FN) Q3 2026 Earnings Transcript | The Motley Fool, https://www.fool.com/earnings/call-transcripts/2026/05/04/fabrinet-fn-q3-2026-earnings-transcript/
- AI Stocks List 2026: 85+ AI Companies | StockTitan, https://www.stocktitan.net/stocks/themes/ai-stocks
- 2025 NVIDIA Corporation Annual Review, https://s201.q4cdn.com/141608511/files/doc_financials/2025/annual/NVIDIA-2025-Annual-Report.pdf
- 2026 NVIDIA Corporation Annual Review, https://s201.q4cdn.com/141608511/files/doc_financials/2026/ar/2026-Annual-Report-Web.pdf
- Fabrinet (NYSE:FN) Stock Forecast & Analyst Predictions, https://simplywall.st/stocks/us/tech/nyse-fn/fabrinet/future
- Fabrinet Investor Relations, https://investor.fabrinet.com/static-files/19065333-4f6f-459b-98d0-ab53a223fd57
- Fabrinet (FN) Stock Analysis & Key Metrics - KoalaGains, https://koalagains.com/stocks/NYSE/FN
- Fabrinet (1FN) Market Cap - Investing.com IN, https://in.investing.com/pro/XMIL:1FN/explorer/marketcap
- Celestica (NYSE:CLS) Stock Valuation, Peer Comparison & Price, https://simplywall.st/stocks/us/tech/nyse-cls/celestica/valuation
- FABRINET ROIC %: 22.23% | Fairly Valued | GuruFocus, https://www.gurufocus.com/term/roic/FN
- Fabrinet (FN) Market Cap Today: Live Data & Historical Trends, https://public.com/stocks/fn/market-cap