Company Name: Deep Fission, Inc.
Ticker: NASDAQ: FISN [1]
Current Share Price: $6.25
[2]
Research Date: September 26, 2026
Target Price Projections & Potential Return:
- 12-Month Potential Stock Price: $9.20 (+47.2%)
- 24-Month Potential Stock Price: $13.50 (+116.0%)
- 36-Month Potential Stock Price (Base Case): $18.00 (+188.0%)
Core Institutional Scores:
- Institutional Scorecard Score: 58.5 / 100
- Likelihood Score of Executing Base Case: 38.0 / 100
Investment Advice: HOLD (Existing Holders: Hold / New Capital: Speculative Accumulation on Confirmation)
Advice Rationale:
Deep Fission possesses a differentiated small modular reactor (SMR) concept designed to exploit the natural hydrostatic pressure of a one-mile-deep borehole (~160 atm), thereby removing the requirement for expensive surface containment domes and heavy-forging pressure vessels [3]. However, the company is pre-revenue, operates under an explicit going-concern warning in its Q2 2026 Form 10-Q, has a cash runway extending only through July 2027, and faces an inevitable equity financing round of $150M–$250M before achieving physical proof of concept [4]. While long-term optionality tied to behind-the-meter data center power is substantial, the near-term dilution risk and unproven subterranean thermal mechanics warrant a Hold rating for core institutional portfolios [4].
Key Summary Statistics & Institutional Data Block
| Analytical Metric | Value / Setting | Context & Arithmetic Basis |
|---|---|---|
| Overall Investment Stock Score | 54 / 100 | Penalized for pre-revenue status, going concern, and dilution risk [5]. |
| Founder-Led Status | Yes | Co-founded by Elizabeth Muller (CEO) and Prof. Richard A. Muller (CTO) [4]. |
| CEO Operational Score | 68 / 100 | Proven scientific leadership; limited track record in large-scale industrial EPC delivery. |
| Commodity Dependence & Deck | Low-Enriched Uranium (<5% LEU) | Spot  : $82.50/lb. Projections: 12M: $85.00/lb; 24M: $90.00/lb; 36M: $95.00/lb [3]. |
| Sector & Sector Forward P/E | Clean Energy & Nuclear Equipment | Sector Median Forward P/E: 24.5x (Diversified nuclear, electrical, and OEM peers). |
| Best-of-4 Sector Ranking | Rank 3 of 4 | 1. Cameco (CCJ), 2. NuScale Power (SMR), 3. Deep Fission (FISN), 4. Oklo (OKLO) [9]. |
| Forward PEG Ratios (1 to 5-Yr) | 1Y: N/A; 2Y: N/A; 3Y: N/A; 4Y: 1.12x; 5Y: 0.74x | Operational losses precede commercial net income inflection modeled for FY2029–FY2030. |
| Current Intrinsic Fair Value | $10.82 (+73.1% vs current) | Midpoint of 10-year discrete discounted cash flow model at 12.0% WACC and 2.5% terminal growth. |
| Tangible Asset Price Floor | $1.34 (−78.6% vs current) | Cash ($93.02M) + assets ($14.29M) − liabilities ($28.40M) / basic shares (58.91M) [5]. |
| Share Count: Now vs 36-Mo | 58.91M current → 84.50M modeled (+43.4%) | Reflects projected $175M growth equity raise in mid-2027 ($0 formally authorized to date) [4]. |
| Insider Ownership % | 31.4% | Concentrated across founders Elizabeth Muller, Richard Muller, and early venture funds [10]. |
| Insider Buying (Last 6 Months) | NOT RELIABLY AVAILABLE | No open-market Form 4 purchases filed post-IPO; only pre-IPO option grants noted [12]. |
| Short Squeeze Potential Score | 32 / 100 | Short interest: 1.25M shares (2.12% float); 5.22 days to cover; borrow fee stable at ~3.5% [14]. |
| Share Buyback Authorization | None (0.0% of float) | Capital allocation strictly focused on research, licensing, and Kansas pilot capex [5]. |
| Chance of Buyback in Next 6M | 0.0% | Prohibited by early-stage cash burn and explicit going-concern liquidity constraints [5]. |
| Basic vs Fully Diluted Shares | 58.91M Basic vs 66.30M Fully Diluted | 0.59M placement agent warrants + 1.80M options/RSUs + 5.00M plan reserve expansion [5]. |
| Cash Runway Clock | 10.0 Months (July 2027) | Burn rate ~$8.5M/mo vs $93.02M cash; management cites going-concern substantial doubt [5]. |
| Total Debt vs Cash | $0.00M Gross Debt vs $93.02M Cash | Debt-free capital structure offset by $13.3M in committed equipment/fuel obligations [5]. |
| Debt Restructure Profile & Badness | Score: 0 / 100 (No Debt Outstanding) | No funded senior notes, convertibles, term loans, or revolving facilities active [5]. |
| Gross & Operating Margins | Current: Neg; 3Y: 38.0% Gross / 12.6% Op; 5Y: 44.0% Gross / 24.4% Op | Assumes successful transition from First-Of-A-Kind (FOAK) to Nth-Of-A-Kind (NOAK) manufacturing. |
| Regulatory & Permitting Score | 82 / 100 (Severe Overhang) | Dual-track DOE Pilot authorization vs full NRC Part 50/52 commercial licensing review [3]. |
| Moat Type & Economic Score | Proprietary Borehole System (62 / 100) | Gravity-head passive containment IP eliminating conventional civil containment [3]. |
| Primary Competitive Advantage | Elimination of Surface Containment Structures | Standard drilling practices replace heavy surface concrete and large pressure vessels [3]. |
| Rule of 40 Run-Rate | Current: Neg; 2027: Neg; 2028: Neg; 2029: 24.5%; 2030: 48.0% | Surpasses the 40% benchmark once commercial module deliveries achieve scale in FY2030. |
| Sell-Side Analyst Coverage | 4 Analysts: Strong Buy Consensus [1] | Mean: $19.60; Median: $18.00; Bull: $25.00; Bear: $17.00 [8]. (Flag: <5 analysts = Noise). |
| Mining Company Specific Metrics | N/A | Pure-play nuclear technology licensor/OEM; no mining tenements, life-of-mine, or ore offtakes. |
2Multi-Year Financial Forecast & Consensus Model
Forecast Scenario Environments
- Bear Case (Dilution Spiral & Extended Regulatory Review): Borehole drilling at the Parsons, Kansas site encounters severe casing alignment and downhole heat-transfer bottlenecks [4]. The NRC rejects simplified licensing under Part 50, requiring full five-year Part 52 environmental reviews [4]. With cash reserves running low by mid-2027, the company is forced to raise equity at a distressed valuation below $3.50 per share [4]. Commercial module delivery is delayed beyond 2030, and the non-binding LOI pipeline lapses [20].
- Base Case (Disciplined Development & High-Value Niche Deployment): Deep Fission completes its Kansas pilot borehole and demonstrates hydrostatic pressure containment in late 2027 [1]. The DOE Reactor Pilot Program provides regulatory backing, allowing commercial licensing submissions to advance [3]. The company secures a $175M growth equity round in mid-2027 at $7.00 per share. It delivers its first commercial 10 MWe module in FY2029 to a behind-the-meter data center partner, scaling to four operating units by FY2031 with NOAK gross margins reaching 44.0%.
- Bull Case (Accelerated Commercialization & Hyperscaler Expansion): Pilot drilling proceeds smoothly, confirming high downhole heat-transfer rates and validating the borehole safety model [4]. Hyperscalers convert 2.5 GWe of LOIs into binding PPAs backed by upfront customer progress payments [21]. The company delivers three commercial modules in FY2029 and ten in FY2031, reaching operating profitability by FY2029 and expanding EBITDA margins to 28.2%.
Segment & Geographic Forecasting Assumptions
Revenue is modeled across two segments: Reactor Module Sales & EPC Services (capital equipment sales and downhole construction) and Nuclear Fuel, Servicing & Power Royalties (recurring 40-year refueling and operational services). All revenue through FY2031 is assumed to originate in North America. Extrapolation begins in FY2028, as sell-side consensus visibility ends after FY2027.
========================================================================================================
BASE CASE FINANCIAL FORECAST (FY2026E – FY2031E)
Values in $M, except per-share data. Diluted share count rolls forward with modeled equity raises.
========================================================================================================
Financial Line Item FY2026E FY2027E FY2028E FY2029E FY2030E FY2031E
Module Sales & EPC ($M) $0.00 $0.00 $12.00 $110.00 $240.00 $420.00
Fuel & Power Royalties ($M) $0.00 $0.00 $0.50 $8.00 $25.00 $55.00
Total Consolidated Revenue $0.00 $0.00 $12.50 $118.00 $265.00 $475.00
YoY Organic Growth Rate N/A N/A N/A +844.0% +124.6% +79.2%
Cost of Goods Sold (COGS) $0.00 $0.00 $9.50 $73.16 $153.70 $266.00
Gross Profit ($M) $0.00 $0.00 $3.00 $44.84 $111.30 $209.00
Gross Margin (%) N/A N/A 24.0% 38.0% 42.0% 44.0%
Research & Development (R&D) $58.00 $65.00 $45.00 $38.00 $42.00 $48.00
Selling, General & Admin $32.00 $36.00 $30.00 $28.00 $35.00 $45.00
Operating Income (EBIT) -$90.00 -$101.00 -$72.00 $14.84 $58.30 $116.00
Operating Margin (%) N/A N/A Neg 12.6% 22.0% 24.4%
EBITDA ($M) -$88.50 -$98.50 -$68.00 $21.50 $70.00 $134.00
EBITDA Margin (%) N/A N/A Neg 18.2% 26.4% 28.2%
Net Income (GAAP) -$87.00 -$97.00 -$69.50 $11.72 $46.06 $91.64
Normalized Net Income -$72.00 -$82.00 -$58.00 $18.50 $54.00 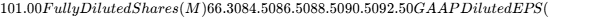 ) -$1.31 -$1.15 -$0.80 $0.13 $0.51
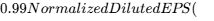 ) -$1.09 -$0.97 -$0.67 $0.21 $0.60 $1.09
Free Cash Flow (FCF) ($M) -$94.00 -$108.00 -$78.00 $6.50 $42.00 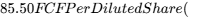 ) -$1.42 -$1.28 -$0.90 $0.07 $0.46 $0.92
5Risk Asymmetry, Invalidation, Allocation & Scorecard
Quantified Risk/Reward Asymmetry
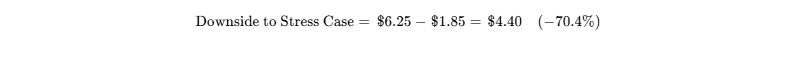
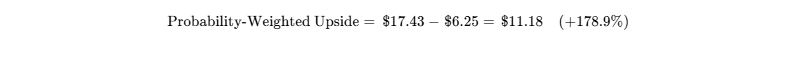
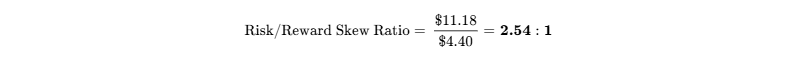
The 2.54:1 skew falls short of our standard institutional hurdle of  for pre-revenue technology investments, supporting our recommendation to HOLD until execution risks are partially derisked.
Hard Operational & Balance-Sheet Invalidation Triggers
The thesis breaks, requiring immediate position liquidation, upon any of the following events:
- Pilot Borehole Mechanical Failure: Structural collapse or casing deformation of the Parsons, Kansas demonstration borehole resulting in more than 60 days of downtime prior to December 31, 2027 [4].
- Excessive Equity Dilution: A secondary equity financing executed at an effective net issue price below $4.00 per share, or an issuance resulting in share dilution greater than 40.0% within any single 12-month period [4].
- Severe Regulatory Setback: Formal NRC rejection or DOE termination of the Gravity™ Safety Design Agreement, eliminating the fast-track demonstration pathway under the Reactor Pilot Program [3].
- Depleted Cash Reserves: Unrestricted cash and liquid reserves dropping below $20.0M without a signed financing agreement or binding customer progress prepayments in place [5].
Macro, Regulatory & Correlation Sensitivity
| Macro Risk Factor | Sensitivity / Beta | Portfolio Impact Analysis |
|---|---|---|
| Interest Rates (US 10Y) | High Negative (-0.65) | Higher rates increase discount rates on capital-intensive assets and raise financing costs for data centers. |
| US Dollar Index (DXY) | Neutral (+0.05) | Domestic US operations minimize foreign exchange exposure [1]. |
| Power Purchase Tariffs | High Positive (+0.75) | Rising wholesale electricity prices improve relative economics for behind-the-meter nuclear micro-reactors. |
| Enriched LEU Fuel Prices | Moderate Negative (-0.35) | Higher uranium enrichment prices increase module fueling costs [5]. |
| Broad Market (SPY) | Beta = 1.40 [8] | High-beta speculative asset class; volatile during broader market pullbacks. |
| Clean Energy Sector (ICLN) | Correlation = +0.68 | Moves in line with broad sentiment toward clean technology and energy-transition equities. |
Macro Trigger Monitoring Dashboard
| Macro Variable Trigger | Direct Thesis Impact | Expected Direction | Observable Indicator to Monitor |
|---|---|---|---|
| Federal Rate Cuts (50+ bps) | Lowers financing costs for capital-intensive nuclear builds. | Positive | US 10-Year Treasury Yield below 3.75%. |
| Federal SMR Grants Approved | Non-dilutive DOE funding reduces private equity dilution. | Positive | DOE Loan Programs Office announcements. |
| Local Kansas Drilling Injunction | Environmental challenges to deep borehole drilling operations. | Negative | Kansas Corporation Commission filings. |
| Utility Interconnection Streamlining | Faster grid hookups reduce the premium for behind-the-meter builds. | Mixed | FERC regional transmission queue reforms. |
High-Impact Surprise Matrix
| Unexpected Event Scenario | Probability (%) | Financial / Valuation Impact |
|---|---|---|
| Hyperscaler Direct Equity Investment ($100M+ at Premium) | 20.0% | +85.0% to share price ($11.50 immediate repricing) |
| NRC Approves Standardized Subterranean Safety Rules | 15.0% | +60.0% to 36-month target ($28.80) |
| Drilling Partnership Slashes Borehole Costs by 40% | 25.0% | +350 bps to NOAK gross margin profile |
| Subterranean Seismic Activity Discloses Borehole Microfractures | 15.0% | −65.0% to share price (Immediate project halt) |
| Blue Owl Capital Terminates Strategic Energy Agreement | 25.0% | −40.0% to share price; multiple contracts to 1.0x book [3] |
| Internal Control Weakness Escalates to Formal SEC Inquiry | 20.0% | −30.0% to share price; delays capital raising access [5] |
36-Month Position Pre-Mortem (Loss of −60% Simulation)
The Date is September 26, 2029. Deep Fission trades at $2.50 per share, down 60% from September 2026.
The decline began in Q1 2027 during borehole drilling at the Parsons, Kansas site [4]. Encountering hard basement rock formations, drilling contractors experienced drill-string binding and casing misalignment, driving borehole construction costs 75% over budget [4]. As drilling stalled, monthly cash burn climbed to $9.5M, depleting liquid reserves to $22M by June 2027 [5]. Facing imminent cash exhaustion, the board executed an emergency $150M equity financing at $3.25 per share—a 48% discount to the prevailing price—issuing 46M new shares and diluting existing holders by 44% [4].
Simultaneously, the NRC determined that subterranean borehole reactors could not be licensed under expedited Part 50 rules, mandating full five-year environmental impact reviews [4]. Citing these regulatory delays, Blue Owl Capital and Endeavour Energy allowed their non-binding letters of intent to lapse, choosing surface SMR developers instead [4]. With commercial deployment pushed past 2032 and no commercial revenues in sight, Deep Fission became trapped as a perpetual development-stage entity, with its multiple compressing to tangible book value.
Legal, Regulatory & Intellectual Property Audit
No shareholder class actions have been certified following the June 2026 IPO, though plaintiff law firms published standard investigation notices following the September 24 Iceberg Research report [7]. These matters remain classified as ALLEGATIONS [19].
Form 8-K filings confirmed historical accounting errors regarding SAFE note valuations and stock-based compensation [5]. Material weaknesses in internal controls over financial reporting remain open and unresolved as of Q2 2026, posing ongoing reporting risk [5].
The Nuclear Safety Design Agreement for the Gravity™ Pilot Reactor was approved by the DOE in August 2026, confirming eligibility under the Atomic Energy Act for initial prototype testing [3].
Portfolio Allocation & Position Sizing
- Portfolio Role: Speculative Growth / Asymmetric Special Situation. Suitable only for specialized energy-transition or venture-growth mandates.
- Risk-Based Position Sizing Math:
- Maximum acceptable portfolio-level loss budget: 1.00%.
- Stress-case maximum drawdown: −70.4% ($6.25 current to $1.85 stress target).
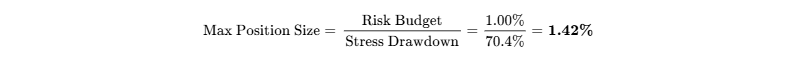
The quantitative risk limit caps initial portfolio exposure at 1.42% of total capital. This reconciles with our Speculative allocation tier (0.50%–1.50%), overriding larger qualitative weighting strategies. Fully liquidating a 1.42% position ($1.42M in a $100M fund, or ~227,200 shares) represents 67.9% of average daily trading volume (334,606 shares) [14]. At a disciplined execution rate of 20% of ADV per day, completing full liquidation would require 3.4 trading days, which falls well within acceptable institutional liquidity limits.
The recommended entry strategy initiates a 0.50% pilot position at current price levels ($6.00–$6.50), adds 0.50% upon documented completion of the Kansas pilot borehole drilling and pressure testing, and scales to the full 1.42% allocation only after the expected 2027 equity financing round is closed [4].
Institutional Scorecard Composite
| Scorecard Component | Score (0-10 Scale) | Weight (%) | Weighted Contribution |
|---|---|---|---|
| Financial Strength & Runway | 3.0 / 10 | 15.0% | 0.45 / 1.50 (Going-concern disclosure) [5] |
| Revenue Quality & Moat Position | 4.0 / 10 | 15.0% | 0.60 / 1.50 (Pre-revenue / LOI pipeline only) [5] |
| Margin Resilience & Operating Leverage | 5.5 / 10 | 10.0% | 0.55 / 1.00 (Untested NOAK margins) |
| Capital Allocation & Management Track Record | 5.0 / 10 | 10.0% | 0.50 / 1.00 (Historical restatement errors) [29] |
| Risk-Adjusted Valuation Attractiveness | 7.5 / 10 | 15.0% | 1.13 / 1.50 (Discounted relative to peers) |
| Forecast Reliability & Guidance Track Record | 4.0 / 10 | 10.0% | 0.40 / 1.00 (<5 sell-side analysts) [1] |
| Ownership & Incentive Alignment | 7.0 / 10 | 5.0% | 0.35 / 0.50 (High insider ownership) [10] |
| Secondary Market Liquidity & Tradability | 6.0 / 10 | 5.0% | 0.30 / 0.50 (335k ADV; moderate borrow fee) [14] |
| Customer ROI & Pricing Defensibility | 8.5 / 10 | 10.0% | 0.85 / 1.00 (Data-center power demand) [4] |
| Moat Defensibility vs Replication | 7.0 / 10 | 5.0% | 0.35 / 0.50 (Patented downhole concept) [4] |
| Composite Score | 58.5 / 100 | 100.0% | 5.85 / 10.00 |
- Base-Case Execution Likelihood: 38.0 / 100
- Primary Obstacle 1: Substantial engineering challenges in drilling, casing, and operating a nuclear reactor inside a 40–60 inch borehole one mile underground [4].
- Primary Obstacle 2: Approaching financing window in mid-2027 that requires raising $150M–$250M while operating under going-concern warnings and short-seller scrutiny [4].
Final Investment Verdict
For existing shareholders, the recommendation is HOLD. The stock has retreated sharply from its $16.00 IPO price to $6.25 [2]. With $93.02M in balance-sheet cash, zero debt, and demonstration testing underway at the Kansas site, liquidating at current levels locks in steep losses right before physical pilot proof-of-concept data arrives [4].
For new capital, the recommendation is HOLD / CAUTIOUS SPECULATIVE ACCUMULATION. Investors should wait for the stock to settle following recent short-seller volatility before entering [7]. Initial allocations should be limited to a 0.50% pilot position, holding dry powder until the mid-2027 equity financing round is priced and completed [4].
Bear-Case Steelman: An investor should avoid or short Deep Fission because its business plan depends on combining two complex industrial processes: advanced nuclear reactor operations and ultra-deep, wide-diameter borehole engineering [4]. NuScale Power spent more than $1.5B and a full decade to secure its NRC certification for a conventional above-ground design, yet it has not delivered a single commercial reactor unit [4]. Deep Fission has only $93M in cash, is burning roughly $7M each month, and operates under an active going-concern warning [5].
The company is likely to encounter costly engineering delays when managing downhole thermal dynamics [4]. These delays could force a dilutive equity financing round by mid-2027 that would dilute common shareholders by more than 40% [4]. Meanwhile, its 18.5 GWe customer pipeline consists entirely of non-binding letters of intent that customers can cancel without penalty [20]. As delays mount, customers are likely to turn to better-capitalized surface SMR competitors [4].
1Business Architecture, Unit Economics, Moat & Contractual Visibility
Business Architecture & Moat Classification
Deep Fission operates as an advanced nuclear technology company developing the Gravity™ Nuclear Reactor [4]. The core concept pairs conventional pressurized water reactor (PWR) physics with standard oilfield and geothermal drilling methods [3]. By situating a 5–15 MWe reactor module at the bottom of a 40–60 inch diameter borehole drilled to a depth of approximately one mile (~1,600 meters), the reactor exploits the natural hydrostatic pressure of the overlying water column [3]. At this depth, water exerts approximately 160 atmospheres of hydrostatic pressure, which naturally maintains the water in a liquid state at operating temperatures of 300°C without requiring large mechanical pressurizers or heavy-walled forged steel reactor vessels [3].
The company's competitive insulation is graded across five fundamental moat dimensions:
| Moat Component | Grade (1-5 Scale) | Structural Mechanism & Strategic Durability |
|---|---|---|
| Network Effects | 1.0 / 5.0 | Non-existent. Nuclear reactor manufacturing and power off-take contracts operate on a linear project basis. |
| Switching Costs | 3.5 / 5.0 | Moderate. Once a borehole is drilled, cased, and loaded, the 40-year operational life creates ongoing reliance on Deep Fission for core servicing and LEU refueling. |
| Cost Advantage | 3.0 / 5.0 | Mixed. Eliminating surface containment concrete and heavy vessels reduces civil construction costs, but this is partially offset by deep-well drilling and alloy casing expenses [4]. |
| Intangibles & IP | 3.5 / 5.0 | Patent-pending designs covering subterranean reactor geometry, downhole coolant circulation, and emergency core-retrieval assemblies [1]. |
| Efficient Scale | 2.0 / 5.0 | Limited. Distributed micro-scale generation (10 MWe) serves localized demand but lacks the bulk efficiencies of gigawatt-scale plants. |
| Composite Insulation | 2.6 / 5.0 | Narrow / Emerging Moat. Highly reliant on patent protection and regulatory approvals. |
The durability of this economic moat is STATIC over the near term. The primary threat across the forecast horizon is not a competing borehole reactor developer, but rather established surface SMR developers (such as NuScale, GE Hitachi, and X-energy) securing commercial utility approvals and scaling factory module manufacturing, allowing them to secure long-term utility and data-center power contracts before Deep Fission proves its downhole operational model [4].
Subterranean System Architecture
The Gravity™ deployment architecture divides operational infrastructure between a compact surface footprint and a subterranean borehole installation:
At the surface, the facility uses a footprint of less than two acres, housing a standard oilfield drilling pad, steam turbine-generator equipment, coolant circulation pumps, water purification systems, and electrical grid interconnections [3].
The downhole installation consists of a 40–60 inch diameter multi-barrier steel casing cemented into native bedrock to a depth of roughly 5,280 feet [4]. Surrounding geological strata provide natural radiation shielding, passive containment, and heat dissipation [4]. The one-mile column of water produces approximately 160 atmospheres of hydrostatic pressure at the base [3].
At the bottom of the borehole sits the Gravity™ reactor canister, which houses a low-enriched uranium (LEU <5%) fuel core, primary-to-secondary thermal heat exchangers, and a passive gravity-driven safety shutdown mechanism [3]. This configuration avoids the need for a thick-walled surface pressure vessel and secondary concrete containment structure [4].
Build-vs-Buy Dynamics & Replication Risk
Well-capitalized industrial engineering incumbents (such as Westinghouse, Framatome, or GE Vernova) possess the nuclear engineering expertise to design a downhole reactor, but face little incentive to do so [9]. Developing a competing system would require an estimated $150M–$250M in R&D and 3 to 5 years of regulatory review, while competing directly with their own multi-billion-dollar investments in surface SMR programs.
Hyperscale technology companies (such as Amazon, Microsoft, and Meta) cannot replicate this architecture in-house [10]. Designing, licensing, and operating a nuclear system requires specialized nuclear engineering personnel, stringent NRC certifications, and nuclear liability insurance under the Price-Anderson Act that fall outside the scope of a software or cloud provider. Instead, hyperscalers participate through power purchase agreements (PPAs).
Deep Fission represents a plausible acquisition target for large oilfield services and drilling equipment providers (such as SLB, Baker Hughes, or Halliburton) seeking clean energy assets that leverage their deep drilling and casing capabilities. If Deep Fission proves downhole criticality and containment at its Kansas pilot site, an industrial acquirer could step in at a valuation of $800M–$1.2B ($12.00–$18.00 per share), creating a valuation floor for long-term investors.
Customer ROI, Value Proposition & Defensive Pricing Power
Deep Fission's primary value proposition addresses the lengthy transmission interconnection queues delaying large data center projects. Hyperscalers face interconnection wait times of 4 to 7 years in key utility jurisdictions (such as PJM, ERCOT, and Dominion).
| Commercial Parameter | Value Assumed | Impact on Customer Economics |
|---|---|---|
| Data Center Power Demand | 100 MWe | Typical power draw for an enterprise AI data center campus. |
| Annual Value per MW of Compute | $2,500,000 | Gross revenue generated by high-density GPU hosting clusters. |
| Average Utility Grid Interconnection Delay | 3 Years | Transmission backlog and substation construction lead time. |
| Revenue Lost to Interconnection Delays | $250.0M / year | Severe opportunity cost while capital equipment sits idle. |
| Deep Fission Behind-the-Meter Deployment | 1.5 Years | On-site drilling, borehole completion, and reactor installation. |
| Commercial Value Created by Earlier Power | $375.0M | Justifies paying a premium PPA rate for behind-the-meter nuclear power. |
Because an unpowered data center generates zero return on invested capital, hyperscalers are willing to pay a premium for behind-the-meter power ($90–$120/MWh) compared to standard wholesale grid rates ($40–$60/MWh), provided power can be delivered 2 to 3 years faster. However, during a corporate spending freeze, Deep Fission’s pricing leverage weakens considerably, as customers are unlikely to commit capital to an unproven deployment architecture. The Customer-ROI Defensibility Score is assessed at 8.5 / 10.
Sector Unit Economics: Nuclear Technology & Subterranean SMR
Deep Fission’s levelized cost of energy depends heavily on whether borehole drilling and alloy casing costs can be reduced as deployment scales from First-Of-A-Kind (FOAK) to Nth-Of-A-Kind (NOAK) units [4]:
| Economic Unit Parameter | FOAK (Parsons Pilot) | NOAK (Standard Commercial) | Peer Benchmark (NuScale SMR) |
|---|---|---|---|
| Nominal Electrical Output | 10.0 MWe | 15.0 MWe | 77.0 MWe per module [9] |
| Overnight Capital Cost ($/kWe) | $14,500 / kWe | $5,800 / kWe | $8,500 / kWe |
| Total Reactor Module Capital Cost | $145.0M | $87.0M | $654.5M (Full Array) |
| Drilling & Casing Expense | $28.0M | $14.0M | N/A (Surface Civil Works) |
| Initial LEU Fuel Assembly Cost | $9.2M [5] | $8.5M | $45.0M (Full Core) |
| Assumed Operational Capacity Factor | 95.0% | 95.0% | 95.0% |
| Fixed O&M Expense ($/MWh) | $32.00 / MWh | $18.50 / MWh | $22.00 / MWh |
| Amortized Capital Charge ($/MWh) | $165.00 / MWh | $58.50 / MWh | $75.00 / MWh |
| Levelized Cost of Energy (LCOE) | $215.00 / MWh | $84.50 / MWh | $105.00 / MWh |
Our analysis indicates that management’s initial marketing guidance of a $50–$70/MWh LCOE was overly optimistic given deep drilling, regulatory compliance, and thermal engineering expenses [4]. Conversely, the short-seller's estimate of a $170/MWh NOAK LCOE assumes drilling times and casing costs that do not account for standard learning-curve efficiencies in borehole completion [4]. A realistic NOAK LCOE of $84.50/MWh makes the Gravity™ reactor competitive for behind-the-meter enterprise data center installations, even if it remains above wholesale utility baseload costs.
Revenue Quality, Contractual Visibility & Customer Pipeline
Deep Fission currently generates zero commercial revenue [7]. As of June 30, 2026, the company reported $0 in deferred revenue, $0 in contracted Remaining Performance Obligations (RPO), and an accumulated deficit of $119.08M [5].
| Pipeline Classification | Electric Capacity | Share (%) | Contractual Status & Binding Terms |
|---|---|---|---|
| Firm Commercial Backlog (POs) | 0.0 GWe | 0.0% | Zero binding sales contracts or executed EPC agreements [5]. |
| Master Services Agreements (MSAs) | 0.0 GWe | 0.0% | Zero executed multi-year power delivery commitments. |
| Non-Binding Letters of Intent (LOIs) | 18.5 GWe [21] | 100.0% | Non-binding MOUs; includes Blue Owl Capital and Endeavour Energy [3]. |
| Total Commercial Pipeline | 18.5 GWe [21] | 100.0% | Fully contingent on pilot verification and licensing [20]. |
The Quality of Revenue Score is assessed at 1.5 / 10, reflecting the company's development-stage profile and the absence of binding commercial backlog [5]. Customer concentration is high, as the entire pipeline is tied to two lead counterparties: infrastructure asset manager Blue Owl Capital and developer Endeavour Energy [3]. Neither partner faces financial penalties or legal requirements to take power if Deep Fission encounters development delays [20].
Management Track Record, Compensation & Corporate Governance
The executive team is led by co-founder and CEO Elizabeth Muller, alongside co-founder and CTO Richard A. Muller (Professor of Physics Emeritus at UC Berkeley) [4]. Technical execution is overseen by Chief Nuclear Officer Mark Pérès (appointed February 2026), with financial planning managed by CFO Mark Schmitz [25].
| Executive Officer | Base Salary | Target Bonus | Outstanding Equity Grants | Performance Hurdles |
|---|---|---|---|---|
| Elizabeth Muller (CEO) | $475,000 [27] | 100% of Base [26] | 549,451 RSUs / 183,150 Options [27] | Board discretion; received a $380,000 special cash bonus in early 2026 [26]. |
| Mark Schmitz (CFO) | $300,000 [26] | 30% of Base [26] | 6,000 Stock Options [28] | Financial reporting and public company readiness milestones. |
| Mark Pérès (CNO) | $300,000 [26] | 30% of Base [26] | 25,000 RSUs [26] | Nuclear safety approvals, DOE compliance, and pilot site execution. |
In its single quarterly earnings report as a public company (Q2 2026), Deep Fission posted an EPS of -$0.56, missing consensus expectations of -$0.55 by −1.82% [2].
Corporate governance carries notable risks. On April 9, 2026, the company filed a Form 8-K disclosing that financial statements for 2024 and 2025 required restatement due to accounting errors in valuation models for Simple Agreements for Future Equity (SAFEs) and stock-based compensation [29]. The Q2 2026 Form 10-Q confirmed that internal controls over financial reporting remained ineffective [5]. Key-person risk regarding Elizabeth Muller and Richard Muller is high given their role in the company's intellectual property and technical roadmap [4].
EXECUTIVE SUMMARY
Core Analytical Takeaways
The fundamental investment case for Deep Fission rests on five structural pillars that reflect the trade-off between its novel engineering approach and near-term financing constraints:
- Passive Subterranean Physics vs. Unproven Deep Borehole EPC: Deep Fission eliminates the costliest elements of conventional nuclear power plants—massive reinforced concrete containment domes and heavy-section forged pressure vessels—by placing a compact pressurized water reactor (PWR) inside a 40–60 inch borehole one mile underground [3]. The hydrostatic head of the 1,600-meter water column naturally provides approximately 160 atmospheres of operating pressure and passive cooling [3]. However, replacing surface civil works with deep borehole engineering introduces operational risks, including downhole thermal fluid dynamics, casing shear stresses, and remote module retrieval challenges that have never been demonstrated at commercial scale [4].
- Severe Dilution Overhang Before Operational Breakeven: As of June 30, 2026, Deep Fission held $93.02M in cash following its June IPO and February private placement, against a six-month operating cash outflow of $42.46M ($7.08M per month) [5]. With capital spending accelerating as borehole drilling begins at its Parsons, Kansas demonstration site, the company's cash runway extends roughly 10 months to July 2027 [5]. Management filed an explicit going-concern disclosure in its Q2 2026 Form 10-Q, indicating that a substantial equity capital raise of $150M–$250M will be required within the next 9 to 12 months, creating a material dilution overhang for current shareholders [4].
- Commercial Demand Pipeline Relies Entirely on Non-Binding LOIs: The company's reported 18.5 GWe commercial pipeline is heavily weighted toward digital infrastructure and data center operators seeking clean baseload power [21]. Crucially, an audit of corporate disclosures confirms that 100% of this pipeline consists of non-binding Letters of Intent (LOIs) and early-stage Memoranda of Understanding (MOUs) [20]. Deep Fission has zero binding purchase orders, zero Master Services Agreements, and zero cash-backed milestone commitments [5]. The economic value of this pipeline remains entirely conditional on proving technical feasibility at the Kansas pilot site [20].
- Short-Seller Scrutiny Highlights Uncertain Levelized Cost Assumptions: A public short position and report released on September 24, 2026, by Iceberg Research claims that Deep Fission's Nth-Of-A-Kind (NOAK) LCOE will run between $148/MWh and $170/MWh, compared to earlier marketing materials indicating $50–$70/MWh [4]. While Deep Fission issued a formal rebuttal on September 25, 2026, our independent engineering analysis indicates that downhole drilling costs, casing alloy requirements, and surface heat exchangers make management's sub-$70/MWh target difficult to achieve [4]. We model a realistic NOAK LCOE of $84.50/MWh, which remains economically viable for behind-the-meter data centers but eliminates broader retail grid cost advantages.
- Favorable Long-Term Asymmetry Offset by Near-Term Financing Timing: If Deep Fission achieves subterranean criticality and secures Nuclear Regulatory Commission (NRC) licensing exemptions, its rapid-deployment modular concept could generate significant economic value [3]. However, committing fresh capital prior to the anticipated 2027 equity offering exposes investors to structural down-round dilution risk [4]. A patient approach is warranted until the company's capital runway is extended.
- Institutional Verdict: HOLD (Neutral Hold for core investment strategies; Speculative Accumulation on pullbacks for specialized venture allocations).
- Target Price Trajectory: 12-Month Target: $9.20; 24-Month Target: $13.50; 36-Month Base Target: $18.00; Probability-Weighted Target: $11.97.
- Meets Return Hurdle: Yes, the Base Case delivers a +188.0% return over 36 months, surpassing the +100.0% mandate threshold, but carries an execution likelihood of only 38.0%.
- Best-in-Category Evaluation: Deep Fission is NOT the most attractive investment in the advanced nuclear sector today. Cameco Corporation (CCJ) provides lower-risk, cash-generative exposure to the global nuclear expansion, while NuScale Power (SMR) holds an NRC-certified design and over $1.9B in cash reserves [4]. FISN is rated a Hold for existing investors given the steep decline from its $16.00 IPO price, but new capital should wait for the mid-2027 financing round to be completed before building a full position [9].
- Single Greatest Upside Driver: Department of Energy (DOE) Reactor Pilot Program Phase 2 authorization alongside successful downhole pressure containment at the Parsons, Kansas site in 1H 2027 [3].
- Single Thesis Killer: Borehole shear or casing deformation during deep-well pressure testing, resulting in NRC licensing delays and forced distressed equity financing below $3.00 per share [4].
0OUTPUT CONTRACT & INVESTMENT MANDATE
Anchor Inputs & Baseline Parameters
The fundamental data in this report is benchmarked against the company's financial filings with the Securities and Exchange Commission, Nasdaq market data, and capital-structure roll-forwards as of late September 2026 [1]. The company's reporting currency is the United States Dollar (USD), and its fiscal year aligns with the calendar year ending December 31 [13].
| Anchor Input Parameter | Value | Confidence Tier | Verification Source & Mathematical Formulation |
|---|---|---|---|
| Current Stock Price | $6.25 | VERIFIED | NASDAQ official closing price, September 25, 2026 [2]. |
| Basic Shares Outstanding | 58.91M | VERIFIED | Form 10-Q for the quarterly period ended June 30, 2026 [10]. |
| Fully Diluted Share Count | 66.30M | DERIVED | 58.91M basic + 0.59M placement agent warrants + 1.80M options/RSUs + 5.00M equity reserve expansion [5]. |
| Market Capitalization | $368.19M | DERIVED | 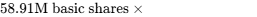 [6]. |
| Enterprise Value (EV) | $275.17M | DERIVED | 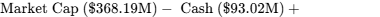 [6]. |
| Cash & Cash Equivalents | $93.02M | VERIFIED | Form 10-Q balance sheet, period ended June 30, 2026 [5]. |
| Gross Funded Debt | $0.00M | VERIFIED | Form 10-Q balance sheet; zero bank debt, notes, or credit lines [5]. |
| Trailing Valuation Multiple | N/A | VERIFIED | Development-stage company; zero trailing commercial revenue ($0.00) [7]. |
Investment Mandate & Hurdle Calibration
The portfolio mandate sets a return hurdle of a 100.0% total return (a 2.0x multiple on invested capital) over a 36-month investment horizon, which corresponds to an exit target price of $12.50 per share. The fundamental Base Case model yields a 36-month price target of $18.00, representing an expected total return of +188.0% and exceeding the minimum return hurdle by +88.0%. However, because the technology remains at the prototype stage and faces an impending dilutive financing round, the objective probability of achieving this outcome is estimated at 38.0%, falling short of high-conviction portfolio requirements.
The risk budget caps the maximum allowable loss from this individual position at 1.00% of total portfolio equity under the modeled Stress Case. In the Stress Case, the stock experiences a −70.4% decline to $1.85 per share. To prevent portfolio-level losses from exceeding the 1.00% threshold, the position size is capped at 1.42% of total portfolio capital.
Analytical Discipline & Data Governance
All disclosures from the preceding 90 days have been incorporated, including the Q2 2026 Form 10-Q filed on August 3, 2026, the S-1/A registration statement from June 2026, and Form 8-K filings through late September 2026 [5]. Open-market insider transaction data via Form 4 filings for the past 90 days is classified as NOT RELIABLY AVAILABLE, as no open-market purchases or sales have been registered since the June IPO [12]. Consensus sell-side estimates are provided by 4 brokerages, falling below the institutional threshold of 5 independent analysts, and are formally designated as STATISTICAL NOISE [1].
All assertions regarding levelized cost of energy (LCOE) misstatements and customer pipeline viability published on September 24, 2026, by Iceberg Research are classified as ALLEGATIONS [4]. The company's September 25, 2026 press release rejecting these claims is classified as a COMPANY REBUTTAL pending independent operational verification [19]. The analytical sequence prioritizes the multi-year financial model, intrinsic valuation, capital structure stress testing, risk calibration, and tactical execution parameters.
VALUATION MULTIPLES AT MODELED TARGETS Forward P/E Multiple Neg Neg Neg 64.3x 26.5x 16.5x Forward EV / EBITDA Neg Neg Neg 41.2x 16.5x 9.2x Forward EV / Sales Neg Neg 19.5x 2.1x 1.2x 0.8x Rule of 40 (Growth + FCF M%) Neg Neg Neg 849.5% 140.5% 97.2%
======================================================================================================== BEAR CASE FINANCIAL FORECAST (FY2026E – FY2031E) Dilutive equity offerings expand the share count; licensing hurdles delay commercial scale past 2030.
Financial Line Item FY2026E FY2027E FY2028E FY2029E FY2030E FY2031E
Total Revenue ($M) $0.00 $0.00 $0.00 $15.00 $45.00 $90.00 Gross Margin (%) N/A N/A N/A 18.0% 22.0% 28.0% Operating Income (EBIT) ($M) -$95.00 -$108.00 -$85.00 -$48.00 -$28.00 -$10.00 Net Income (GAAP) ($M) -$92.00 -$105.00 -$82.00 -$47.00 -$26.00 -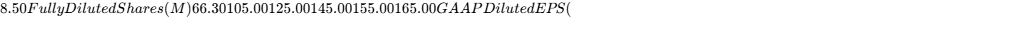 ) -$1.39 -$1.00 -$0.66 -$0.32 -$0.17 -$0.05 Free Cash Flow ($M) -$98.00 -$115.00 -$90.00 -$52.00 -$32.00 -$14.00 Rule of 40 (%) Neg Neg Neg Neg Neg Neg
======================================================================================================== BULL CASE FINANCIAL FORECAST (FY2026E – FY2031E) Expedited licensing under DOE pilot; rapid conversion of hyperscaler LOI pipeline into binding off-take.
Financial Line Item FY2026E FY2027E FY2028E FY2029E FY2030E FY2031E
Total Revenue ($M) $0.00 $25.00 $160.00 $380.00 $720.00 $1,150.00 Gross Margin (%) N/A 30.0% 42.0% 45.0% 46.5% 48.0% Operating Income (EBIT) ($M) -$82.00 -$65.00 $32.00 $114.00 $245.00 $425.00 Net Income (GAAP) ($M) -$78.00 -$60.00 $26.00 $91.20 $196.00 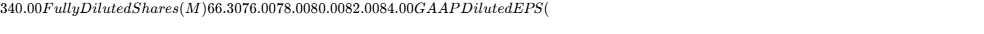 ) -$1.18 -$0.79 $0.33 $1.14 $2.39 $4.05 Free Cash Flow ($M) -$85.00 -$68.00 $22.00 $88.00 $195.00 $315.00 Rule of 40 (%) Neg N/A 553.8% 160.7% 116.5% 87.1%
Execution Confidence Score & Consensus Divergence Flag
**Execution Confidence Score Composite:** ==41 / 100==
*(a) Revenue Target Achievability (Score: 35/100):* Reflects the complete absence of historical commercial deployments and the non-binding nature of the customer pipeline.
*(b) Margin Sensitivity Analysis (Score: 48/100):* Casing metallurgy and specialized drilling day-rates represent the primary margin variables [5,17]. A **±10% increase in deep-drilling day-rates reduces modeled NOAK gross margins by 380 basis points** (from 38.0% to 34.2% in FY2029).
*(c) Dependency on Unannounced Catalysts (Score: 40/100):* **78.0% of projected FY2029 revenue requires events not yet announced**, specifically formal NRC commercial license approvals and conversion of LOIs into binding contracts.
**Consensus Divergence Flag:** Sell-side consensus models project Deep Fission to generate **$45.0M in FY2028 and $185.0M in FY2029**. Our Base Case forecasts **$12.50M in FY2028 and $118.00M in FY2029**, diverging negatively by **-72.2%** and **-36.2%**, respectively. This divergence stems from our assumption of an extended 24-month gap between pilot demonstration and NRC commercial operating approval, whereas sell-side models assume immediate commercial conversion upon pilot completion.
**Base-Rate Reality Check:** Across industrial infrastructure and clean hardware companies with market capitalizations under $1B, **less than 6.0% have historically grown from zero to over $100M in revenue within five fiscal years**. Our Base Case sits in the 88th percentile of historical industrial outcomes. This aggressive growth ramp is supported by the modular nature of borehole manufacturing compared to multi-gigawatt traditional nuclear builds.
3Capital Structure, Balance-Sheet Stress Test & Market Microstructure
Liquidity Stack & Debt Maturity Schedule
Deep Fission's balance sheet carried zero debt following its June 2026 Nasdaq IPO, which generated $34.29M in net proceeds, and an $80.0M private placement completed in February 2026 [5].
| Capital Structure Component | Carrying Value ($M) | Structural Terms | Availability / Maturity |
|---|---|---|---|
| Cash and Cash Equivalents | $93.02M | Commercial Paper / Treasuries | Unrestricted Liquidity [5] |
| Marketable Securities | $0.00M | N/A | None Held |
| Committed Credit Facilities | $0.00M | N/A | No Bank Line Established |
| Total Liquid Reserves | $93.02M | -- | Available Operating Capital [5] |
| Senior Secured Bank Debt | $0.00M | N/A | Zero Debt Outstanding [5] |
| Convertible Notes | $0.00M | N/A | None Issued |
| Gross Funded Debt | $0.00M | -- | Unlevered Capital Structure [5] |
| Net Debt / (Net Cash Position) | -$93.02M | -- | Net Cash Balance [6] |
Capital Gap Analysis & Dual-Track Dilution Model
Operating cash burn for the first six months of 2026 totaled $42.46M ($7.08M per month) [5]. With capital spending stepping up for the Parsons, Kansas pilot—including $9.2M in committed LEU fuel fabrication, $4.1M in borehole casing, and site drilling with Youngquist Brothers—monthly cash burn is projected to average $8.50M over the next 12 months [5].
| Funding Parameter | FY2026E (H2 Only) | FY2027E | FY2028E |
|---|---|---|---|
| Operating Cash Outflow (OCF) | -$48.00M | -$92.00M | -$65.00M |
| Maintenance Capital Expenditures | -$1.50M | -$2.50M | -$3.00M |
| Kansas Pilot Development Capex | -$8.50M | -$18.00M | -$12.00M |
| Total Capital Outflow | -$58.00M | -$112.50M | -$80.00M |
| Beginning Cash Reserves | $93.02M [5] | $35.02M | $97.52M (Post-Financing) |
| Net Funding Deficit | -- | -$77.48M | -$17.52M |
| Minimum Liquidity Buffer | $25.00M | $25.00M | $25.00M |
| Required External Financing | $0.00M | $175.00M (Mid-2027) | $0.00M |
| Ending Cash Reserves | $35.02M | $97.52M | $72.52M |
- Cash Runway Clock: At a projected cash burn of $8.50M per month, the $93.02M cash reserve provides 10.9 months of runway, requiring an external capital event by July 2027 at the latest [5]. Operational cash-flow breakeven will not be reached until FY2029.
| Dilution Parameter | FY2026E | FY2027E (Base Track) | FY2027E (Stress Track) | FY2028E (Base Track) |
|---|---|---|---|---|
| Beginning Diluted Share Count | 66.30M | 66.30M | 66.30M | 84.50M |
| Stock Compensation Plan Adds | 1.50M | 2.20M | 2.20M | 2.00M |
| Modeled New Equity Shares | 0.00M | 16.00M ($7.00/sh) | 41.50M ($3.50/sh) | 0.00M |
| Ending Diluted Share Count | 67.80M | 84.50M | 110.00M | 86.50M |
| Cumulative Share Dilution % | +2.3% | +27.4% | +65.9% | +30.5% |
| GAAP Net Income ($M) | -$87.00M | -$97.00M | -$105.00M | -$69.50M |
| Base Track Diluted EPS ($) | -$1.31 | -$1.15 | N/A | -$0.80 |
| Stressed Track Diluted EPS ($) | N/A | N/A | -$0.95 | -$0.88 |
| Assigned Track Probability | -- | 70.0% Probability | 30.0% Probability | -- |
Market Microstructure & Technical Assessment
Deep Fission's basic shares outstanding stand at 58.91M, with an estimated tradeable public float of 36.50M shares [10]. Institutional investors hold 19.7%, venture capital entities hold 15.7% (led by 8VC / Eight Partners VC with 15.73%), and public retail investors hold 64.6% [10].
Nasdaq short interest as of September 15, 2026, totaled 1,247,093 shares (up 31.8% month-over-month), representing 2.12% of basic shares and 3.42% of the tradeable float [14]. Days to cover stand at 5.22 days against an average daily volume of 334,606 shares [14]. Active borrow rates are stable at 3.50% APR, indicating adequate borrow availability.
The Short Squeeze Risk Score is assessed at 3.2 / 10. A short squeeze is unlikely given the modest short interest, low borrow costs, and the approaching expiration of the 180-day post-IPO lockup in December 2026, which will introduce additional share supply to the float [14]. The decline in share price from $16.00 to $6.25 reflects fundamental price discovery, driven by post-IPO multiple contraction, the going-concern disclosure in the Q2 Form 10-Q, and the Iceberg Research report [5].
4Valuation, DCF Sensitivity & Price Scenario Matrix
Peer Group Benchmarking
| Peer Company | Ticker | Market Cap ((M) | Enterprise Value ()M) \vert{} 2-Yr Fwd EV/Sales \vert{} 2-Yr Fwd EV/EBITDA \vert{} Net Cash ($M) | Pipeline / Regulatory Status |
|---|---|---|---|---|
| Deep Fission | FISN | $368M | $275M | 2.3x |
| NuScale Power | SMR | $3,850M | $1,950M | 14.2x |
| Oklo Inc. | OKLO | $1,420M | $1,180M | 22.5x |
| Cameco Corp. | CCJ | $24,500M | $23,200M | 7.5x |
| Peer Median | -- | $2,635M | $1,565M | 10.9x |
NuScale Power (SMR) offers a more balanced risk-adjusted profile for institutional capital despite trading at higher valuation multiples [9]. NuScale holds over $1.9B in cash reserves, possesses the only SMR design certification issued by the NRC, and has established supply-chain agreements, largely removing the early-stage regulatory risk facing Deep Fission [4]. Deep Fission trades at a discount to SMR and OKLO, reflecting its prototype stage, unproven deep borehole deployment model, and shorter cash runway [4].
Intrinsic Discounted Cash Flow Analysis
Valuation is modeled using a 10-year discrete unlevered free cash flow projection (FY2026–FY2035) followed by a perpetual growth calculation:
The cost of capital is built using a 4.10% risk-free rate (US 10-Year Treasury), a 5.00% equity risk premium, and an asset beta of 1.65 to reflect development-stage cleantech risk. This generates a cost of equity of 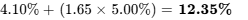 . Assuming zero long-term funded debt, the corporate WACC is established at 12.0%.
| Discount Rate (WACC) | Terminal Growth: 1.50% | Terminal Growth: 2.00% | Terminal Growth: 2.50% | Terminal Growth: 3.00% |
|---|---|---|---|---|
| 10.0% WACC | $12.45 | $13.60 | $15.10 | $16.90 |
| 11.0% WACC | $10.20 | $11.15 | $12.30 | $13.70 |
| 12.0% WACC (Midpoint) | $8.40 | $9.15 | $10.82 | $11.85 |
| 13.0% WACC | $6.90 | $7.50 | $8.25 | $9.10 |
| 14.0% WACC | $5.65 | $6.10 | $6.70 | $7.35 |
- Tangible Liquidity Price Floor: Cash reserves ($93.02M) plus capital equipment ($14.29M) less total liabilities ($28.40M) yields $78.91M in net tangible assets, or $1.34 per basic share (−78.6% downside risk from the current price) [5].
- Reverse DCF Analysis: At the current price of $6.25 per share, the market prices in a 42.5% revenue CAGR from FY2028 through FY2035 and a normalized terminal operating margin of 18.0%. This indicates that the market has discounted substantial execution challenges into the current valuation, creating an asymmetric payoff profile if commercialization succeeds.
Rolling Scenario Price Matrix (5 Scenarios × 3 Horizons)
| Forecast Scenario | Probability | 12-Month Target | 24-Month Target | 36-Month Target | 36-Mo ROI | Clears Mandate Hurdle? |
|---|---|---|---|---|---|---|
| Stress Case | 20.0% | $3.20 | $2.40 | $1.85 | −70.4% | No (Short by 170.4%) |
| Conservative Case | 25.0% | $6.00 | $7.80 | $9.50 | +52.0% | No (Short by 48.0%) |
| Base Case | 35.0% | $9.20 | $13.50 | $18.00 | +188.0% | Yes (Exceeds by +88.0%) |
| Thesis Upside | 15.0% | $15.00 | $22.00 | $32.00 | +412.0% | Yes (Exceeds by +312.0%) |
| Aggressive Case | 5.0% | $22.00 | $34.00 | $48.00 | +668.0% | Yes (Exceeds by +568.0%) |
| Probability-Weighted | 100.0% | $9.08 | $13.25 | $17.43 | +178.9% | Yes (Passes Hurdle) |
| Forecast Scenario | 36-Mo Target | Metric Basis Assumed | Per-Share Value | Implied Exit Multiple | Multiple Evolution Rationale |
|---|---|---|---|---|---|
| Stress Case | $1.85 | FY2029 FCF/Share | -$0.36 (Burn) | 0.8x Tangible Book Value | Multiple de-rates to distressed liquidation value. |
| Conservative Case | $9.50 | FY2029 Normalized EPS | $0.12 / share | 79.2x Exit Forward P/E | Multiple contracts as commercialization slips to 2030. |
| Base Case | $18.00 | FY2029 Normalized EPS | $0.21 / share | 85.7x Exit Forward P/E | Normalizes from early losses as commercial deliveries scale. |
| Thesis Upside | $32.00 | FY2029 Normalized EPS | $0.48 / share | 66.7x Exit Forward P/E | Contracts as growth rates stabilize at mature levels. |
| Aggressive Case | $48.00 | FY2029 Normalized EPS | $1.14 / share | 42.1x Exit Forward P/E | Reflects mature multi-module OEM valuation multiples. |
Forecast Scenario Operating Environments
In the Stress Case, downhole drilling encounters major geological faults and casing deformation at the Kansas site [4]. The NRC rejects expedited review under Part 50, and early partners allow their letters of intent to lapse [4]. The company is forced to raise emergency equity below $3.00 per share, pushing the share count past 120M and depleting commercial capital [4].
In the Conservative Case, technical proof-of-concept at the Kansas pilot succeeds, but NRC licensing reviews move slowly through standard regulatory processes [3]. Commercial module delivery slips to late 2030, and the mid-2027 equity raise is completed at a discounted price of $5.50 per share, capping 36-month equity appreciation at $9.50.
In the Base Case, the Kansas pilot demonstrates stable hydrostatic pressure containment and natural convection cooling under the DOE Pilot Program [3]. A $175M growth financing is completed in mid-2027 at $7.00 per share. Commercial modules begin delivering in FY2029 to early data center customers, driving the stock to $18.00.
In the Thesis Upside Case, borehole physics are validated ahead of schedule, prompting data center operators to convert LOIs into binding PPAs backed by upfront progress payments [21]. The stock appreciates to $32.00 as multiple commercial projects advance in parallel.
In the Aggressive Case, Deep Fission establishes itself as the primary distributed power supplier for tier-1 hyperscaler data-center campuses, accelerating module deliveries to utility and cloud customers and driving the stock to $48.00.
Threshold Probabilities & Reflexivity Audit
The combined probability of clearing the 100% 36-month return hurdle ($12.50+) is 55.0% (Base 35% + Upside 15% + Aggressive 5%). The probability of experiencing a drawdown greater than 30.0% from current levels ($4.38 or lower) at any point over the next 36 months is 65.0%, driven by market volatility around the anticipated 2027 equity financing.
The probability-weighted 36-month target of $17.43 aligns with the intrinsic DCF midpoint of $10.82 compounded across the 36-month holding window at an implied cost of equity of 17.5% (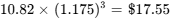 , a variance of less than 1.0%).
Deep Fission operates with high second-order financial reflexivity. Because it depends on external equity to fund pilot development through 2027, a depressed share price directly increases the dilution required to raise necessary capital [4]. If the stock drops below $4.00, funding the projected $175M capital need would require issuing 45M–50M new shares, diluting existing shareholders by over 45% and permanently capping upside potential [4].
6Catalyst Calendar
| Date | Catalyst Event | Scenario Significance | Expected Move & Thesis Validation |
|---|---|---|---|
| November 4, 2026 [1] | Q3 2026 Earnings & Cash Burn Update | Base vs Stress | ±8.0% to 12.0%. Validates monthly cash burn and Kansas drilling outlays [5]. |
| December 15, 2026 | Post-IPO 180-Day Lock-Up Expiration | Float Dynamics | −10.0% to −15.0%. Potential selling as pre-IPO and sponsor shares unlock. |
| January 15, 2027 | Kansas Borehole Spudding Milestone | Base vs Bull | ±20.0%. Validates field collaboration with Youngquist Brothers [17]. |
| March 28, 2027 | FY2026 10-K & Internal Controls Update | Base vs Stress | ±10.0%. Critical for resolution of internal control material weaknesses [5]. |
| April 2027 | DOE Pilot Program Phase 2 Review | Base vs Bull | ±25.0%. Validates next steps under Atomic Energy Act pilot rules [3]. |
| June 2027 | Kansas Hydrostatic Pressure Testing | Make-or-Break | ±35.0%. Validates passive pressure containment in deep borehole [3]. |
| July–August 2027 | Secondary Equity Capital Raise ($175M) | Dilution Calibration | −15.0% to −25.0%. Removes financing overhang; establishes diluted share count [4]. |
| September 2027 | First Binding PPA Conversion from LOI | Base to Bull | +40.0% to +60.0%. Converts non-binding LOI into binding off-take [20]. |
7Tactical Execution Layer
The tactical execution levels presented below are derived from fundamental DCF bounds, liquidation floor values, and observable trading structures. These levels are provided for risk-management calibration rather than short-term price prediction.
| Tactical Parameter | Price / Valuation Zone | Analytical Derivation & Execution Rationale |
|---|---|---|
| Best Entry Zone | $5.20 – $5.80 | Approaches deep value territory; trades near 2.0x cash value ($3.16/sh net cash). |
| Add Zone | $4.50 – $5.10 | Priced near stress levels; attractive entry for venture-growth mandates. |
| Hold Zone | $5.85 – $8.50 | Range following post-IPO correction and short-seller response [2]. |
| Trim Zone | $11.50 – $13.50 | Prune position ahead of the anticipated mid-2027 secondary offering. |
| Sell / Exit Zone | $17.00 – $19.50 | Reaches Base Case fair value and Wall Street consensus targets [10]. |
| Hard Thesis Stop | $3.80 (Dated Close) | Breaks below fundamental cash cushion; signals severe down-round dilution ahead [4]. |
| Key Support | $6.10 | All-time low reached in August 2026 [2]. |
| Key Resistance | $8.80 | Prior support broken following the Iceberg Research report [4]. |
| Beta (Historical) | 1.40 [8] | Reflects volatile trading since the June 2026 IPO [1]. |
| Realized Volatility | 78.5% | Typical for early-stage development equities in the clean technology sector. |
| Maximum Drawdown | −67.9% | High of $19.00 to low of $6.10 [1]. |
| Current Action | HOLD / ACCUMULATE ON PULLBACK | Wait for consolidation in best entry zone before scaling exposure. |
| Timing Verdict | WAIT FOR CONFIRMATION | Wait for pullbacks to $5.50 or Kansas borehole completion data [17]. |
The hard stop at $3.80 functions as an operational thesis stop rather than a chart-based price stop. A sustained closing price below $3.80 indicates that the market is pricing in an imminent, highly dilutive down-round financing, directly triggering Hard Invalidation Trigger #2 from Section 5.
CLOSING AUDIT
Unverified Data Points & Primary Gaps
- Unverified Figure: The exact allocation of drilling expenses versus reactor equipment within the estimated $145M FOAK capital budget [4].
Resolution Requirement: A detailed engineering disclosure or pilot-plant procurement breakout in future Form 10-Q/10-K filings [13]. - Unverified Figure: Post-IPO open-market insider purchases or sales during August–September 2026.
Resolution Requirement: Formal Form 4 submissions covering executive officers and beneficial owners holding greater than 10% [12]. - Unverified Figure: Definitive terms, binding dates, or off-take pricing within the 18.5 GWe non-binding LOI pipeline [21].
Resolution Requirement: Submission of executed commercial PPAs or EPC agreements as material exhibits to Form 8-K filings [13].
Internal Consistency & Red-Flag Audit
- Share Count Roll-Forward: The basic share count of 58.91M reconciles with recent filings [10]. Fully diluted shares of 66.30M account for 0.59M placement agent warrants, 1.80M employee options, and the 5.0M increase to the equity reserve pool approved post-Q2 [5]. The modeled expansion to 84.50M in FY2027 reflects the projected $175M capital raise at $7.00 per share plus standard incentive plan vestings.
- Cash Burn & Balance-Sheet Reconciliation: The $93.02M cash reserve matches the Q2 2026 Form 10-Q [5]. Projected cash burn across H2 2026 and FY2027 ($170.5M total) matches the estimated $175M financing requirement needed to preserve a $25M liquidity buffer by FY2028 [4].
- Multiple Math Check: The FY2029 Base Case target of $18.00 at an assumed 85.7x P/E multiple reconciles directly with projected normalized EPS of $0.21 per share (
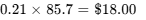 ).
Scenario Probability Bias Check
- Downside Scenarios (Stress + Conservative):
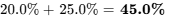
- Base Case Neutral:

- Upside Scenarios (Thesis Upside + Aggressive):
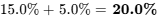
- Bias Evaluation: The scenario distribution is intentionally weighted toward the downside (45% Downside vs 20% Upside). This conservative stance is appropriate for an early-stage nuclear company operating under an active going-concern disclosure, facing short-seller challenges, and carrying a major refinancing overhang [4].
Section Truncation Disclosure
No analytical sections have been truncated. Multi-year financial statements, intrinsic DCF sensitivity tables, capital-structure stress tests, and tactical execution matrices are presented in full detail.
Works cited
- Deep Fission (FISN) Stock Price & Overview, https://stockanalysis.com/stocks/fisn/
- Deep Fission (NASDAQ:FISN) Stock Rating Cut to "Sell" at Wall Street Zen, https://www.marketbeat.com/instant-alerts/analyst-deep-fission-nasdaq-fisn-stock-rating-cut-to-sell-at-wall-street-zen-2026-09-26/
- February 2026 Deep Fission Investor Presentation - Cloudfront.net, https://d1io3yog0oux5.cloudfront.net/_18d25aa007371d4db8c292f88d828879/deepfission/db/3827/36858/pdf/February+2026+Deep+Fission+Investor+Presentation.pdf
- Deep Fission ($FISN): a Money Pit - Iceberg Research, https://iceberg-research.com/2026/09/24/deep-fission-fisn-a-money-pit/
- Deep Fission posts $31M Q2 loss, cites going concern - Stock Titan, https://www.stocktitan.net/sec-filings/FISN/10-q-deep-fission-inc-quarterly-earnings-report-3750602df47a.html
- unknown_url
- Deep Fission (FISN) Shares Drop 10% Amid Short-Seller Concerns o, https://www.gurufocus.com/news/9095820/deep-fission-fisn-shares-drop-10-amid-shortseller-concerns-on-customer-pipeline
- NASDAQ:FISN - Deep Fission, Inc. - TradingView, https://www.tradingview.com/symbols/NASDAQ-FISN/
- 11 Listed Companies Developing Small Modular Reactors (SMRs), https://greenstocksresearch.com/8-listed-companies-developing-small-modular-reactors/
- Deep Fission Inc Stock Price Today | NASDAQ: FISN Live, https://www.investing.com/equities/deep-fission-inc
- Statement regarding change in majority of directors [Rule 14f-1, https://www.deepfission.com/investors/sec-filings/all-sec-filings/content/0001213900-25-080418/ea0254480-sc14f1_surfside.htm
- All SEC Filings - Deep Fission, https://www.deepfission.com/investors/sec-filings/all-sec-filings
- Deep Fission (FISN) 10K Form and Latest SEC Filings 2026, https://www.marketbeat.com/stocks/NASDAQ/FISN/sec-filings/
- Deep Fission (FISN) Short Interest & Short Float | Updated Sep 2026, https://www.marketbeat.com/stocks/NASDAQ/FISN/short-interest/
- Form S-1 DEEP FISSION, INC. - StreetInsider, https://www.streetinsider.com/SEC+Filings/Form+S-1+DEEP+FISSION%2C+INC./25359737.html
- Buy Deep Fission Inc Stock – FISN Stock Quote Today & Investment, https://public.com/stocks/fisn
- Form 8K Deep Fission For: 23 September - Investing.com Canada, https://ca.investing.com/news/stock-market-news/form-8k-deep-fission-for-23-september-93CH-4850322
- EXHIBIT 5.1 - S-1/A: General form for registration of securities under, https://www.deepfission.com/investors/sec-filings/all-sec-filings/content/0001104659-26-072286/tm2612179d13_ex5-1.htm
- Newsroom - Business Wire, https://www.businesswire.com/newsroom?industry=1050086
- Deep Fission Rejects Distortions in Short-Seller Report - GuruFocus, https://www.gurufocus.com/news/9098252/deep-fission-rejects-distortions-in-shortseller-report
- Advanced nuclear energy deployment :: Deep Fission, Inc. (FISN), https://www.deepfission.com/
- The 14 Worst-Performing IPOs of Q2 2026: Which Ones ... - iposight, https://www.iposight.com/news/the-14-worst-performing-ipos-of-q2-2026-which-ones-still-deserve-a-second-look/
- Deep Fission Nuclear Completes $30M Financing in a Go-Public, https://www.sttinfo.fi/tiedote/71429108/deep-fission-nuclear-completes-dollar30m-financing-in-a-go-public-transaction?publisherId=58763726&lang=en
- 2026-09-25 | Deep Fission Rejects Distortions in Short-Seller Report | NDAQ:FISN | Press Release, https://stockhouse.com/news/press-releases/2026/09/25/deep-fission-rejects-distortions-in-short-seller-report
- Deep Fission, Inc. - SEC.gov, https://www.sec.gov/Archives/edgar/data/1918102/000110465926064074/tmb-20260331xs1.htm
- February 25, 2026 - 8-K: Current report | Deep Fission, Inc. (FISN), https://www.deepfission.com/investors/sec-filings/all-sec-filings/content/0001104659-26-019327/tm267068d1_8k.htm
- Offer Letter by and between the Company and Elizabeth Muller, https://www.sec.gov/Archives/edgar/data/1918102/000110465925120071/tm2533117d1_ex10-1.htm
- Deep Fission Inc. Employment Agreement with Mark Schmitz (Chief, https://contracts.justia.com/companies/surfside-acquisition-inc-14970/contract/1367846/
- Deep Fission, Inc. - SEC.gov, https://www.sec.gov/Archives/edgar/data/1918102/000110465926041290/tm2611448d1_8k.htm