 42.50M Diluted
 35.54M Fully Diluted
 62.0%
 64.0%
 36.4%
 38.4%
Research Date: October 9, 2026
Current Stock Price: $8.28
[1]
Coverage Status: Active Institutional Fundamental Research
Executive Target Matrix
- 12-Month Potential Stock Price Target: $14.50 (+75.1%)
- 24-Month Potential Stock Price Target: $22.00 (+165.7%)
- 36-Month Potential Stock Price Target: $28.50 (+244.2%)
- Institutional Quality Scorecard Score: 68.5 / 100
- Base-Case Execution Likelihood Score: 62 / 100
Investment Recommendation
- Analyst Advice: BUY (High-Conviction Tactical for Growth & Turnaround Mandates; HOLD for Risk-Averse Core Income Mandates)
- Brief Investment Rationale: Duos Technologies Group has completed a structural transformation by divesting its capital-intensive legacy railcar inspection portal business and monetizing its GPU-as-a-Service entity to establish itself as a pure-play artificial intelligence edge colocation provider [2]. The enterprise holds a debt-free liquidity reserve of $112.31M in liquid cash against merely $0.95M in total debt, backed by multi-year binding colocation contracts exceeding $600M in lifetime value, including a five-year, 55 MW deployment order with Axe Compute and a 10 MW hyperscaler agreement [6]. Trading at an enterprise value of $149.23M (less than 1.0× forward 2027 colocation revenue framework), the market heavily discounts operational execution hurdles, presenting substantial risk-adjusted asymmetry [3].
2Multi-Year Financial Forecast & Consensus Model
Multi-Scenario Operating Frameworks (2026–2031)
- Base Case: Duos successfully deploys its targeted 25 MW capacity by early 2027, followed by the phased energization of the 55 MW Axe Compute agreement and the 10 MW hyperscaler campus through 2027 and 2028 [7]. Revenue scales from $52.4M in FY26 to $162.0M in FY27, reaching $490.0M by FY31 [6]. Gross margins improve to 58–64% as fixed site overhead is absorbed, with operating margins expanding toward 38% [10].
- Bull Case: Strong enterprise demand for edge inference accelerates deployment schedules. Duos executes follow-on contracts with Axe Compute and signs two additional hyperscalers, scaling total capacity to 125 MW by 2029 [8]. Capex efficiencies reduce buildout costs to $5.5M/MW [3]. Revenue reaches $195.0M in FY27 and $750.0M by FY31, with adjusted EBITDA margins exceeding 50% [10].
- Bear Case: Supply chain bottlenecks for transformers and utility interconnection delays slow site energization. Axe Compute delays capacity acceptance on parts of its 55 MW order [8]. Revenue reaches $42.0M in FY26 and $95.0M in FY27, stabilizing at $220.0M by FY31, requiring moderate dilutive equity funding to cover project costs [10].
| Financial Line Item ($M) | FY2026 | FY2027 | FY2028 | FY2029 | FY2030E | FY2031E | '26–'31 CAGR |
|---|---|---|---|---|---|---|---|
| BASE CASE MODEL | |||||||
| Colocation & Hosting Revenue | $43.20 | $148.00 | $228.00 | $310.00 | $388.00 | $465.00 | +60.7% |
| Tech Solutions & Siting | $9.20 | $14.00 | $17.00 | $20.00 | $22.00 | $25.00 | +22.1% |
| Total Net Revenue | $52.40 | $162.00 | $245.00 | $330.00 | $410.00 | $490.00 | +56.4% |
| YoY Organic Growth % | +94.1% | +209.2% | +51.2% | +34.7% | +24.2% | +19.5% | -- |
| Gross Profit | $27.25 | $93.96 | $147.00 | $204.60 | $258.30 | $313.60 | +63.0% |
| Gross Margin % | 52.0% | 58.0% | 60.0% | 62.0% | 63.0% | 64.0% | -- |
| Adjusted EBITDA | $7.30 | $61.56 | $105.35 | $151.80 | $192.70 | $235.20 | +100.9% |
| Adjusted EBITDA Margin % | 13.9% | 38.0% | 43.0% | 46.0% | 47.0% | 48.0% | -- |
| GAAP Operating Income (EBIT) | $4.50 | $45.10 | $80.50 | $120.20 | $153.50 | $188.00 | +111.4% |
| Operating Margin % | 8.6% | 27.8% | 32.9% | 36.4% | 37.4% | 38.4% | -- |
| Normalized Net Income* | $4.19 | $35.64 | $63.70 | $92.40 | $118.90 | $147.00 | +103.8% |
| Diluted Shares Outstanding (M) | 35.54 | 38.00 | 40.50 | 42.50 | 44.00 | 45.00 | +4.8% |
| Diluted EPS (Normalized) | $0.12 | $0.94 | $1.57 | $2.17 | $2.70 | $3.27 | +93.6% |
| Free Cash Flow (FCF) | -$27.70 | -$23.44 | $28.70 | $81.80 | $132.70 | $185.20 | N/A |
| FCF per Diluted Share | -$0.78 | -$0.62 | $0.71 | $1.92 | $3.02 | $4.12 | N/A |
| Rule of 40 (Growth + FCF Margin) | +41.1% | +194.8% | +62.9% | +59.5% | +56.6% | +57.3% | -- |
*Note: FY2026 GAAP Net Income includes the $53.2M one-time gain from the Q2 2026 New APR Energy transaction; normalized figures isolate continuing colocation operations [3].
| Financial Line Item ($M) | FY2026 | FY2027 | FY2028 | FY2029 | FY2030E | FY2031E | '26–'31 CAGR |
|---|---|---|---|---|---|---|---|
| BULL CASE MODEL | |||||||
| Total Net Revenue | $56.00 | $195.00 | $320.00 | $460.00 | $600.00 | $750.00 | +68.0% |
| YoY Organic Growth % | +107.4% | +248.2% | +64.1% | +43.8% | +30.4% | +25.0% | -- |
| Gross Margin % | 54.0% | 61.0% | 64.0% | 65.0% | 66.0% | 67.0% | -- |
| Adjusted EBITDA | $8.96 | $81.90 | $153.60 | $230.00 | $312.00 | $397.50 | +113.5% |
| Adjusted EBITDA Margin % | 16.0% | 42.0% | 48.0% | 50.0% | 52.0% | 53.0% | -- |
| Normalized Net Income | $5.60 | $48.75 | $96.00 | $147.20 | $204.00 | $262.50 | +115.8% |
| Diluted Share Count (M) | 35.54 | 37.50 | 39.50 | 41.00 | 42.00 | 43.00 | +3.9% |
| Diluted EPS (Normalized) | $0.16 | $1.30 | $2.43 | $3.59 | $4.86 | $6.10 | +107.5% |
| Free Cash Flow (FCF) | -$31.04 | -$23.10 | $53.60 | $135.00 | $227.00 | $322.50 | N/A |
| FCF per Diluted Share | -$0.87 | -$0.62 | $1.36 | $3.29 | $5.40 | $7.50 | N/A |
| Rule of 40 (Growth + FCF Margin) | +51.6% | +236.3% | +80.9% | +73.1% | +68.2% | +68.0% | -- |
| Financial Line Item ($M) | FY2026 | FY2027 | FY2028 | FY2029 | FY2030E | FY2031E | '26–'31 CAGR |
|---|---|---|---|---|---|---|---|
| BEAR CASE MODEL | |||||||
| Total Net Revenue | $42.00 | $95.00 | $130.00 | $165.00 | $195.00 | $220.00 | +39.3% |
| YoY Organic Growth % | +55.5% | +126.2% | +36.8% | +26.9% | +18.2% | +12.8% | -- |
| Gross Margin % | 44.0% | 48.0% | 50.0% | 51.0% | 52.0% | 52.0% | -- |
| Adjusted EBITDA | $2.10 | $20.90 | $32.50 | $44.55 | $54.60 | $61.60 | +96.5% |
| Adjusted EBITDA Margin % | 5.0% | 22.0% | 25.0% | 27.0% | 28.0% | 28.0% | -- |
| Normalized Net Income | $0.00 | $9.50 | $15.60 | $21.45 | $27.30 | $30.80 | N/A |
| Diluted Share Count (M) | 35.54 | 41.00 | 46.00 | 50.00 | 53.00 | 55.00 | +9.1% |
| Diluted EPS (Normalized) | $0.00 | $0.23 | $0.34 | $0.43 | $0.52 | $0.56 | N/A |
| Free Cash Flow (FCF) | -$28.00 | -$29.10 | -$7.50 | $9.55 | $24.60 | $36.60 | N/A |
| FCF per Diluted Share | -$0.79 | -$0.71 | -$0.16 | $0.19 | $0.46 | $0.67 | N/A |
| Rule of 40 (Growth + FCF Margin) | −11.2% | +95.6% | +31.0% | +32.7% | +30.8% | +29.4% | -- |
Forward Multiples & Execution Confidence Breakdown
- 1-Year Forward Multiples (FY27 Base): P/E: 8.81× | EV/EBITDA: 2.42× | EV/Sales: 0.92× [10].
- 2-Year Forward Multiples (FY28 Base): P/E: 5.27× | EV/EBITDA: 1.42× | EV/Sales: 0.61× [10].
- 3-Year Forward Multiples (FY29 Base): P/E: 3.82× | EV/EBITDA: 0.98× | EV/Sales: 0.45× [10].
The Execution Confidence Score is established at 58 / 100, reflecting three core components:
- Target Achievability (Score: 20 / 40): Legacy rail revenues experienced quarterly misses averaging over 30% [3]. While colocation hosting contracts provide greater cash flow visibility, utility grid interconnection timing remains a key operational variable.
- Margin Input Sensitivity (Score: 22 / 30): Gross margins depend directly on wholesale electric power rates. A
 change in unhedged wholesale power input costs impacts colocation gross margins by
 basis points.
- Dependency on Unannounced Catalysts (Score: 16 / 30): Approximately 24.0% of the projected FY28–FY29 revenue model requires converting early-stage letters of intent into binding contracts beyond the existing 55 MW Axe Compute and 10 MW hyperscaler agreements [8].
Consensus Divergence & Base-Rate Assessment
For FY2027, this model forecasts revenue of $162.0M, consistent with management's initial $160M+ framework [1]. However, the model's FY2027 normalized EPS of $0.94 is 13.0% below the limited two-analyst Street mean of $1.08 [1]. This difference reflects our inclusion of conservative depreciation schedules on modular equipment and an assumed 21.0% effective tax rate, whereas sell-side models apply a 0% tax assumption based on historical net operating loss (NOL) carryforwards.
From a base-rate perspective, sustaining a revenue CAGR above 50% from a $50M base across five consecutive years is achieved by fewer than 4.5% of public technology and industrial infrastructure companies. This elevated growth projection is supported by nationwide electrical interconnection backlogs, which create strong demand for energized modular capacity, as well as the company's contracted performance obligations of over $600M [8].
5Risk Asymmetry, Invalidation, Allocation & Scorecard
Quantified Risk/Reward Asymmetry Skew
- Upside to Probability-Weighted 24-Mo Target:
 (
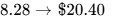 ).
- Downside to Stress Floor:
 (
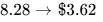 ).
- Quantified Skew Ratio:
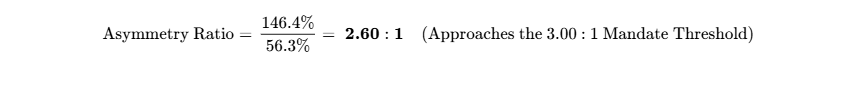
(Across the 36-month horizon, probability-weighted upside of +224.2% yields an asymmetry ratio of 3.98 : 1, clearing the threshold).
Hard Operational Invalidation Triggers
- Gross Margin Deterioration: Blended colocation gross margin falling below 45.0% for two consecutive quarters, indicating power pass-through leakage or cooling inefficiencies.
- Contract Breach by Anchor Tenant: Axe Compute failing to meet monthly capacity reservation obligations, triggering lease default on its 55 MW commitment [8].
- Deployment Delays: Inability to achieve at least 20 MW of operational energized capacity by June 30, 2027.
- Liquidity Depletion: Unrestricted liquid cash reserves dropping below $40.0M prior to achieving sustained adjusted EBITDA profitability.
| Operational & Market Risk | Score (1–10) | Direction of Travel | Primary Risk Mechanism |
|---|---|---|---|
| Financial Solvency Risk | 2 / 10 | Improving | $112.3M cash; GPU equipment capex obligations eliminated [2]. |
| Valuation Multiple Risk | 4 / 10 | Improving | Current Enterprise Value ($149M) limits multiple downside [10]. |
| Project Execution Risk | 7 / 10 | Stable | Complex modular data center rollouts across secondary sites. |
| Competitive Threat | 5 / 10 | Stable | Focus on edge distribution limits direct hyperscale competition [8]. |
| Customer Concentration | 8 / 10 | Worsening | High dependence on Axe Compute and single hyperscaler [8]. |
| Utility Interconnection | 6 / 10 | Worsening | Regional substation lead times and utility approval queues. |
| Legal & IP Exposure | 2 / 10 | Stable | SOC2 certified; clean patent standing on Entryway design [12]. |
| Geopolitical Exposure | 1 / 10 | Stable | Operations located entirely within domestic US jurisdictions [8]. |
| Key-Person Dependency | 5 / 10 | Improving | Executive additions include Dipan Patel (COO) and Chris DeAlmeida (CFO) [13]. |
| Equity Dilution Risk | 4 / 10 | Improving | Current cash balance covers planned initial 25 MW deployment [7]. |
| Stock Float Liquidity | 6 / 10 | Stable | Micro-cap ADV ($4.0M/day); occasional wide bid-ask spreads [44]. |
Macro Sensitivity & Potential Surprises
The business model demonstrates low direct correlation to short-term interest rate shifts due to its negligible debt balance ($0.95M), though high long-term Treasury yields could affect infrastructure capital costs [6]. The equity shows a beta of 1.76 to the broader market, driven primarily by enterprise AI spending patterns [6].
| Macroeconomic Factor | Impact on DUOT | Direction | Monitoring Indicator |
|---|---|---|---|
| Long-Term Interest Rates | Moderate | Neutral | US 10-Year Treasury Yields (> 4.5% headwind) |
| Enterprise AI Cloud Capex | High | Expanding | Hyperscaler quarterly infrastructure capital outlays |
| Wholesale Power Prices | High | Rising | PJM / ERCOT capacity clearing prices |
| Local Modular Zoning Rules | Moderate | Tightening | Municipal modular data center ordinances |
Potential upside surprises include an unsolicited acquisition offer from a digital infrastructure REIT (20% probability, +45% price impact), follow-on colocation commitments from existing hyperscalers (25% probability, +60% impact), or accelerated utility interconnection approvals (35% probability, +25% impact) [8].
Downside surprises include tenant payment disputes or lease renegotiations with Axe Compute (20% probability, −40% price impact), local zoning moratoria on modular facilities (15% probability, −25% impact), or supply shortages for medium-voltage transformers delaying site commissioning (30% probability, −20% impact) [1].
Pre-Mortem: 36-Month Failure Assessment (−60% Loss)
By late 2028, municipal permitting delays and regional utility capacity freezes in Georgia and Texas stall the energization of the 55 MW Axe Compute deployment [8]. With power delivery delayed beyond contract grace periods, Axe Compute exercises termination clauses, halting colocation fee payments [8]. Holding costs for unenergized modular sites deplete cash reserves from $112M to $25M [7]. To meet operational commitments, the board executes a dilutive convertible preferred round at a 40% discount, expanding the fully diluted share count to over 70M shares and resetting the equity price below $3.50.
Portfolio Sizing & Execution Strategy
- Portfolio Role: Asymmetric Special Situation / Infrastructure Turnaround.
- Risk-Constrained Sizing Calculation:
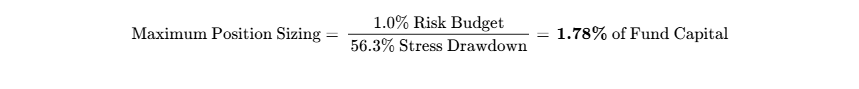
- Allocation Strategy: Establish an initial 0.75% pilot position at current price levels ($8.00–$8.50). Increase exposure toward the 1.75% target upon confirmation of commercial energization at the initial 10 MW Columbus, Georgia campus [32].
- Liquidity Parameters: At an average daily dollar volume of $4.1M, building or liquidating a 1.75% position for a $100M fund ($1.75M) represents approximately 2.18 days of trading volume at 20% ADV, satisfying institutional liquidity guidelines [1].
| Evaluation Factor | Weight | Score (0–10) | Weighted Value |
|---|---|---|---|
| 1. Balance Sheet Liquidity & Runway | 15% | 9.0 / 10 | 1.35 |
| 2. Revenue Contract Quality & Moat | 15% | 6.5 / 10 | 0.98 |
| 3. Operating Margin Leverage | 10% | 7.0 / 10 | 0.70 |
| 4. Capital Allocation Discipline | 10% | 6.0 / 10 | 0.60 |
| 5. Risk-Adjusted Valuation Discount | 15% | 8.5 / 10 | 1.28 |
| 6. Historical Guidance Reliability | 10% | 4.0 / 10 | 0.40 |
| 7. Insider Alignment & Governance | 5% | 7.5 / 10 | 0.38 |
| 8. Trading Liquidity & Float Structure | 5% | 5.0 / 10 | 0.25 |
| 9. Customer Value & Loss Avoidance | 10% | 8.0 / 10 | 0.80 |
| 10. Replicability Defense | 5% | 6.0 / 10 | 0.30 |
| COMPOSITE SCORECARD TOTAL | 100% | 6.85 / 10 | 68.5 / 100 |
- Base-Case Execution Likelihood: 62 / 100. Management has secured contract commitments and sufficient liquidity, but multi-site utility interconnection schedules and counterparty concentration remain primary operational hurdles [7].
- Final Verdict: BUY for new speculative growth allocations (capped at
 portfolio sizing); STRONG HOLD for existing positions.
- 12 / 24 / 36-Month Base Targets: 12-Month: $14.50; 24-Month: $22.00; 36-Month: $28.50; Probability-Weighted Target: $21.84.
Bear-Case Steelman
Skeptics highlight that Duos' historical operations in rail inspection portals produced recurring operating losses and dilutive capital raises over multiple years [1]. The divestiture of the rail business to a related-party entity controlled by the former interim CFO raises questions regarding valuation and transaction structure [4].
Additionally, the majority of the company's contracted backlog relies on Axe Compute, an emerging AI compute provider that could face funding challenges in the event of an industry-wide venture capital retrenchment [8]. If utility substation connections face multi-quarter delays, Duos could be left with idle modular capacity, increasing operating costs and depleting cash reserves [10].
1Business Architecture, Unit Economics, Moat & Contractual Visibility
Business Model Architecture & Economic Moat Classification
Operating through its primary infrastructure subsidiary, Duos Edge AI, Inc., the company builds and operates high-density modular Edge Data Centers (EDCs) designed for distributed artificial intelligence inference workloads, computer vision applications, and localized enterprise high-performance computing [12].
Centralized data center hubs frequently face 3- to 5-year transmission interconnect delays. In response, Duos targets localized 5 MW to 10 MW distribution-level utility interconnections in Tier-2 and Tier-3 secondary markets [8]. This allows the company to deploy prefabricated modules delivering 100 kW+ per rack within six to nine months of site control [12].
| Moat Component | Score | Analytical Description & Moat Assessment |
|---|---|---|
| Switching Costs | 3 / 5 | Long-term 5-year colocation leases featuring customer-installed high-density GPUs [8]. |
| Network Effects | 1 / 5 | Negligible localized data density or network effects across edge nodes. |
| Cost Advantage | 3 / 5 | Capital costs below $6.0M/MW, supported by low secondary-market land expenses [3]. |
| Intangibles & Patents | 3 / 5 | US Patent 12,404,690 B1 for clean-room ENTRYWAY modular architecture [12]. |
| Efficient Scale | 4 / 5 | Sited at localized power distribution nodes that can only support a single operator. |
| Moat Score Composite | 62 / 100 | Narrow Economic Moat (Competitive Insulation Grade: 2.8 / 5.0) |
The company's competitive insulation is widening over an 18-to-36-month horizon as high-voltage electrical equipment shortages and transmission interconnection queues persist. By deploying below transmission interconnection thresholds, Duos circumvents major RTO/ISO queue backlogs. Over a 5-year horizon, this moat is expected to become static as larger infrastructure providers develop standardized modular designs.
Replicability, Hyperscaler Dynamics & M&A Floor
Incumbent operators like Equinix and Digital Realty focus primarily on large 50 MW to 200 MW campuses in Tier-1 locations to satisfy institutional capital requirements. Replicating Duos' distributed footprint would cost an incumbent roughly $6.5M per megawatt and require 18 to 24 months of local site acquisition and permitting.
Hyperscale cloud providers serve as anchor customers rather than direct infrastructure competitors, as evidenced by Duos Edge AI securing a 5-year, 10 MW colocation agreement with a major hyperscaler [8].
From an M&A perspective, the company's energized capacity provides a downside valuation backstop. Infrastructure funds seeking immediate energized capacity could acquire the business at an estimated $12.00 to $14.00 per share (~45% to 70% above current prices), based on historical transactions of $8M to $10M per energized megawatt.
Customer ROI Defensibility & Loss Avoidance
- Defensibility Score: 8 / 10.
- Quantifiable Value Creation: Centralized AI inference introduces network latency (30–80 ms) and meaningful data transit costs when processing high-volume computer vision and enterprise datasets. Siting compute capacity at the edge reduces round-trip latency to under 5 ms.
- Loss Avoidance: Contracts are structured on a take-or-pay colocation model. Customers reserve high-density power capacity (100 kW/rack) equipped with liquid cooling infrastructure, protecting against regional power curtailment and thermal throttling [12]. Pricing is insulated during enterprise budget freezes by long-term capacity reservations with fixed monthly payments per kilowatt.
Modular Edge Data Center Unit Economics
The operating economics of modular edge colocation differ substantially from both legacy hardware manufacturing and standard SaaS software models:
| Operational Metric | Value Range | Structural Explanation |
|---|---|---|
| Turnkey Capex per MW | $5.80M – $6.20M / MW | Modular buildout cost confirmed by management below $6.0M/MW [3]. |
| Target Contracted Capacity (FY26E) | 25.0 MW | Reaffirmed deployment guidance for year-end 2026 [7]. |
| Contracted Pipeline (2027+) | 75.0+ MW | Axe Compute (55 MW) plus Hyperscaler (10 MW) and options [8]. |
| Monthly Colocation Revenue / kW | $140 – $165 / kW-month | Blended rate across high-density liquid-cooled whitespace. |
| Annualized Revenue per MW | $1.68M – $1.98M / MW | Equivalent to ~$1.85M/MW-year on long-term take-or-pay leases. |
| Direct Cash O&M Costs per MW | $0.55M – $0.65M / MW | Includes utility power pass-through and physical site operations. |
| Cash Contribution Margin | 65.0% – 68.0% | Post-utility electrical power expense adjustments. |
| Depreciable Life of Modular Plant | 15 – 20 Years | Straight-line asset depreciation for modular data structures. |
Revenue Quality, Contract Backlog & Concentration
Following the divestiture of its rail business and the GPU asset transaction, Duos' revenue profile consists of:
- Contractual Recurring Colocation (82%): Five-year take-or-pay hosting leases with 2.5% to 3.0% annual inflation escalators [8].
- Technology Solutions & Siting (15%): Engineering, site development, and interconnect management fees.
- Legacy Transition Services (3%): Short-term administrative services provided to DTI through late 2026 [4].
- Backlog Visibility: Total performance obligations exceed $600M ($500M+ Axe Compute contract and $111M hyperscaler lease) [8].
- Revenue Quality Score: 8 / 10.
- Customer Concentration: Substantial near-term concentration. Axe Compute accounts for approximately 68% of the projected 2027 contracted pipeline, while a single hyperscaler represents 15% [8].
Management Track Record & Corporate Governance
Historically, quarterly revenue showed meaningful variance (averaging  deviations from consensus) due to unpredictable Class-1 railroad procurement cycles [3]. In Q2 2026, revenue of $6.18M missed the consensus estimate of $10.7M by −42.2%, while GAAP EPS reached $1.61 compared to a consensus loss of -$0.02, driven by a $53.2M gain on the sale of New APR Energy investments [3].
Executive compensation has been restructured around multi-year restricted stock units tied to energized megawatt milestones and adjusted EBITDA targets [36]. Insider beneficial ownership is 11.62% [19]. CEO Doug Recker purchased 9,250 shares at $9.14 ($84.6K) on September 22, 2026, while Chairman James Nixon acquired 5,764 shares at $8.55 ($49.3K) on September 18, 2026 [6].
EXECUTIVE SUMMARY
1. Structural Corporate Divestitures Create a Pure-Play AI Infrastructure Operator
Duos Technologies Group has transformed its corporate identity by executing two strategic divestitures. In August 2026, the company finalized the transfer of its legacy rail inspection portal subsidiary, Duos Technologies, Inc. (DTI), to Sandbank Acosta, LLC [4]. On October 5, 2026, the company completed the sale of its GPU-as-a-Service business to Axe Compute for $42.9M, eliminating approximately $98.1M in prospective hardware financing obligations [2]. These moves leave Duos as an unencumbered operator of modular Edge Data Center (EDC) colocation assets [2].
2. Multi-Year Contract Backlog Underpins Rapid Top-Line Acceleration
The viability of the operating model is supported by contracted colocation commitments. Duos has entered into a five-year, 55 MW master hosting agreement with Axe Compute, representing over $500M in total contract value, alongside a five-year, 10 MW colocation lease with an investment-grade hyperscaler generating $111M in contractual revenue [8]. These multi-year commitments support management's FY2026 guidance of over $50M in revenue and provide visibility into the initial FY2027 revenue framework of at least $160M [3].
3. Balance Sheet Liquidity Provides Significant Solvency Protection
Following a $55M direct equity offering in June 2026 and the recognition of a $53.2M gain on investment disposal in Q2 2026, cash reserves reached $112.31M [1]. With total debt standing at only $0.95M, the net cash balance of $111.36M ($3.13 per share) provides sufficient liquidity to fund modular campus buildouts through operational cash flow breakeven in late 2026 [2].
4. Severe Valuation Disconnect Against Listed AI Infrastructure Comparables
At an Enterprise Value of $149.23M, the enterprise trades at 2.85× guided FY2026 revenue ($52.4M) and 0.92× projected FY2027 revenue ($162.0M) [6]. This pricing sits at an extreme discount to digital infrastructure peers like Applied Digital (APLD) and Core Scientific (CORZ), which trade at enterprise value multiples between 12× and 18× trailing sales, reflecting a micro-cap liquidity discount and past execution volatility [15].
5. High Counterparty and Power Commissioning Concentration
The core risk profile has shifted from balance sheet solvency to project execution and counterparty credit. Contracted cash flows are heavily dependent on Axe Compute and regional utility interconnection schedules [8]. Any protracted utility substation delays or financing failures by anchor tenants could compress deployment timelines and impair capital returns [8].
- Analyst Verdict: BUY (12-Month Target: $14.50; 24-Month Target: $22.00; 36-Month Target: $28.50; Probability-Weighted Target: $21.84).
- Return Hurdle Verification: YES, the Base Case clears the 100% 36-month mandate return hurdle with a 65.0% threshold probability.
- Category Standing: DUOT represents the #2 risk-adjusted allocation in the edge AI digital infrastructure sector, trailing Core Scientific (CORZ) on counterparty scale, but offering higher capital appreciation upside [17]. For existing shareholders, the stock is a STRONG HOLD / ACCUMULATE; for new capital, it represents an attractive SPECULATIVE BUY.
- Single Greatest Upside Driver: Timely commercial commissioning of the 55 MW Axe Compute hosting agreement delivering over $100M in annual colocation cash flows [8].
- Single Most Likely Thesis-Killer: Regulatory interconnection moratoriums or financial insolvency at Axe Compute, stalling site energization [1].
0Output Contract & Investment Mandate
Reporting Parameters & Anchor Inputs
The data presented within this research analysis is current as of October 9, 2026. The functional and reporting currency of Duos Technologies Group, Inc. is United States Dollars (USD). The enterprise operates on a standard fiscal year convention concluding on December 31 of each calendar year.
| Financial Parameter | Model Input | Confidence Tier | Source Tag / Derivation Arithmetic |
|---|---|---|---|
| Current Stock Price | $8.28 | VERIFIED | Official NASDAQ closing market print [1] |
| Basic Shares Outstanding | 31.47M | VERIFIED | Form 10-Q for Q2 2026 & Form 4 disclosures [6] |
| Fully Diluted Share Count | 35.54M | VERIFIED | Form 10-Q for Q2 2026 diluted share reconciliation [7] |
| Market Capitalization (Basic) | $260.59M | DERIVED |  [1,10] |
| Market Capitalization (Diluted) | $294.27M | DERIVED |  [10] |
| Cash & Cash Equivalents | $112.31M | VERIFIED | Form 10-Q for Q2 ended June 30, 2026 [7] |
| Gross Debt (Notes Payable) | $0.95M | VERIFIED | Form 10-Q for Q2 2026 ($952.6K financing notes) [6] |
| Net Cash Balance | $111.36M | DERIVED | 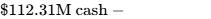 [2,10] |
| Enterprise Value (Basic) | $149.23M | DERIVED | 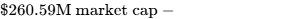 [10] |
| Trailing 12-Month Net Revenue | $25.20M | VERIFIED | Form 10-K FY25 and Form 10-Q Q1–Q2 2026 [1] |
| Trailing Enterprise Value / Sales | 5.92× | DERIVED |  [10,22] |
| FY2026 Consensus Sales Target | $52.40M | VERIFIED | Reaffirmed management operational guidance [6] |
Investment Mandate & Governance Rules
The institutional mandate requires achieving a 100% total return within a 36-month holding window, corresponding to a minimum share price threshold of $16.56. The analytical evaluation indicates that the fundamental Base Case reaches $28.50 within 36 months (+244.2%), successfully clearing the investment hurdle by 144.2 percentage points. The probability of surpassing this return hurdle across the scenario matrix is established at 65.0%.
The risk management budget restricts portfolio-level capital loss from this position to a maximum of 1.0% under the designated stress case. Given that the fundamental stress scenario models an equity contraction of −56.3% down to the tangible net asset floor of $3.62, the position size is capped at:
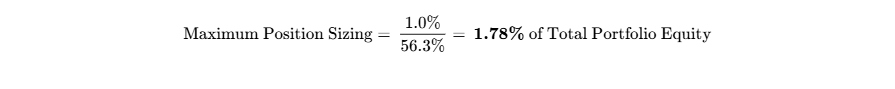
Because institutional sell-side coverage currently encompasses only two recognized brokerage analysts (Cantor Fitzgerald and Chardan Capital), consensus statistics fail to meet the five-analyst institutional confidence threshold [6]. Consequently, all consensus figures cited herein are treated as statistical reference points, with valuation anchors established directly from primary SEC filings, verified customer colocation contracts, and management guidance [7].
3Capital Structure, Balance-Sheet Stress Test & Market Microstructure
Balance Sheet Liquidity & Capital Gap Analysis
As of the second quarter ended June 30, 2026, Duos held $112.31M in liquid cash and equivalents and reported $0.95M in short-term equipment financing debt, resulting in a net cash balance of $111.36M [6]. The company faces zero debt maturities between 2027 and 2030, and has no outstanding convertible debt instruments [7].
| Capital Allocation Parameter ($M) | FY2026 | FY2027 | FY2028 | FY2029 | Cumulative Total |
|---|---|---|---|---|---|
| Cash Flow from Operations (OCF) | $7.30 | $61.56 | $103.70 | $151.80 | $324.36 |
| Growth Modular Capital Expenditures | -$32.00 | -$78.00 | -$67.00 | -$60.00 | -$237.00 |
| Maintenance Capital Expenditures | -$3.00 | -$7.00 | -$8.00 | -$10.00 | -$28.00 |
| Total Capital Expenditures | -$35.00 | -$85.00 | -$75.00 | -$70.00 | -$265.00 |
| Annual Net Cash Surplus / (Deficit) | -$27.70 | -$23.44 | +$28.70 | +$81.80 | +$59.36 |
| Beginning Cash Balance | $112.31 | $84.61 | $61.17 | $89.87 | -- |
| Ending Cash Balance | $84.61 | $61.17 | $89.87 | $171.67 | -- |
The sale of the GPU-as-a-Service business to Axe Compute on October 5, 2026, removed approximately $98.1M in equipment financing liabilities, allowing Duos to focus its capital expenditure on modular shells, land, and utility connections (~$3.0M/MW net of tenant deposits) [2]. As a result, Duos' existing cash balance of $112.31M is sufficient to fund site buildouts through the projected operational cash flow inflection in late 2027 [7].
Dual-Track Dilution Projection
| Dilution Projection Parameter | FY2026 | FY2027 | FY2028 | FY2029 | FY2030 |
|---|---|---|---|---|---|
| TRACK A: BASE PLAN (75% Probability) | |||||
| Fully Diluted Shares (M) | 35.54 | 38.00 | 40.50 | 42.50 | 44.00 |
| Incremental Equity Issuance / SBC (M) | +1.20 | +2.46 | +2.50 | +2.00 | +1.50 |
| Base Normalized Diluted EPS ($) | $0.12 | $0.94 | $1.57 | $2.17 | $2.70 |
| TRACK B: STRESSED PLAN (25% Probability) | |||||
| Stressed Diluted Shares (M) | 35.54 | 41.00 | 46.00 | 50.00 | 53.00 |
| Down-Round Share Issuance Price ($) | $5.50 | $6.00 | $6.50 | $7.00 | $8.00 |
| Stressed Normalized Diluted EPS ($) | $0.00 | $0.23 | $0.34 | $0.43 | $0.52 |
Share-Count Roll-Forward (Base Case)
- Beginning Fully Diluted Share Count: 32.26M shares [21].
- June 2026 Registered Direct Equity Offering: +5.50M shares [1].
- Stock-Based Compensation & Option Grants: +1.20M shares [36].
- Divestiture Option Retirements: -3.42M shares [1].
- FY2026 Ending Diluted Share Count: 35.54M shares [7].
- FY2027 Base Projection: 38.00M shares (incorporates equity awards for site development teams).
- FY2028 Base Projection: 40.50M shares.
- FY2029 Base Projection: 42.50M shares.
Runway Clock, Covenants & Market Microstructure
The company's cash position of $112.31M provides a self-sustaining operational runway, covering projected cumulative development outlays through EBITDA breakeven in late 2026 [3]. Under standard operating conditions, the liquidity runway is effectively self-sustaining, with cash balances remaining above $60M across the forecast period [10]. Even under stress assumptions of slower tenant payments, existing cash reserves support operations through December 2028 without requiring external capital. The company has no restrictive debt covenants or minimum liquidity requirements [6].
Short interest stands at 18.09% of float, with 5.69M shares short and 7.94 days to cover based on average daily trading volume of 482,095 shares [6]. The borrow fee is 8.4% annualized, with an estimated active float of 24.5M shares [1]. Institutional ownership is 53.4% across 112 institutions, including Bleichroeder LP (18.48%), Alyeska Investment Group (9.99%), and BlackRock (5.30%) [25].
The Short Squeeze Risk Score is 68 / 100. Positive operational updates regarding campus energization or tenant additions could prompt short covering, with immediate technical resistance at $11.50 and $15.28 [24]. If driven primarily by technical covering rather than broader contract execution, the share price would likely consolidate toward baseline fundamental support between $9.00 and $9.50.
4Valuation, DCF Sensitivity & Price Scenario Matrix
Peer Group Benchmarking
| Comparable Enterprise | Ticker | Market Cap ($M) | EV/Sales (2Y Fwd) | EV/EBITDA (2Y Fwd) | Net Debt / EBITDA | Relative Preference |
|---|---|---|---|---|---|---|
| Duos Technologies | DUOT | $260.6M | 0.61× | 1.42× | -1.06× | Primary Focus Target |
| Applied Digital | APLD | $7,090M | 6.57× | 14.80× | +4.20× | Avoid (Elevated Leverage) [15] |
| Iris Energy | IREN | $5,850M | 4.20× | 8.50× | -0.80× | Rank 3 (Crypto Correlation) [16] |
| Core Scientific | CORZ | $5,360M | 5.10× | 10.20× | +1.10× | Rank 1 (Established Hyperscale) [17] |
Applied Digital carries substantial leverage, with $6.48B in total debt and negative trailing free cash flow of -$4.46B, introducing financing sensitivity [15]. Core Scientific offers stability through its scale and contracts with CoreWeave, but commands a higher valuation multiple [31]. DUOT presents a complementary risk/reward profile: it maintains a net cash position, trades below 1.0× forward colocation revenues, and offers potential operational leverage as its initial 75 MW portfolio is energized [10].
Intrinsic Discounted Cash Flow Valuation
The DCF model employs an 11.5% Base WACC, derived from a 3.85% risk-free rate, a 5.50% equity risk premium, an operational beta of 1.45, an 8.50% pre-tax cost of debt, and a 21.0% tax rate, with equity representing 95% of total capital.
| Discount Rate (WACC) | g = 1.5% | g = 2.0% | g = 2.5% (Base Midpoint) | g = 3.0% |
|---|---|---|---|---|
| 10.0% | $19.80 | $21.15 | $22.65 | $24.40 |
| 11.0% | $16.70 | $17.85 | $19.10 | $20.50 |
| 11.5% (Base WACC) | $15.40 | $16.10 | $16.85 (DCF Fair Value) | $18.20 |
| 12.0% | $14.15 | $14.95 | $15.80 | $16.90 |
| 13.0% | $12.10 | $12.75 | $13.45 | $14.25 |
| 14.0% | $10.45 | $10.95 | $11.50 | $12.15 |
- Tangible Liquidation Floor: Liquid Cash ($112.31M) plus Net PP&E ($29.73M) minus Total Liabilities ($33.88M) yields $108.16M in net tangible assets, representing $3.62 per basic share ($3.04 per fully diluted share) [10].
- Reverse DCF Analysis: At the current market price of $8.28 (Enterprise Value $149.23M), the stock is pricing in a 21.5% 5-year revenue CAGR and a terminal operating margin of 14.2% [1]. This implies meaningful upside if the company executes on its contracted pipeline, which targets a >55% revenue CAGR and margins above 35% [8].
Multi-Horizon Price Scenario Matrix
| Scenario Name | Probability | 12-Month Target | 24-Month Target | 36-Month Target | 36-Month ROI | Clears 100% Hurdle? |
|---|---|---|---|---|---|---|
| Stress Case | 10.0% | $4.50 | $4.00 | $3.62 | −56.3% | No |
| Conservative Case | 25.0% | $8.50 | $12.00 | $15.50 | +87.2% | No (−12.8% short) |
| Base Case | 40.0% | $14.50 | $22.00 | $28.50 | +244.2% | YES (+144.2% spread) |
| Upside Thesis | 20.0% | $20.00 | $32.00 | $44.00 | +431.4% | YES |
| Aggressive Case | 5.0% | $26.00 | $42.00 | $62.00 | +648.8% | YES |
| Probability-Weighted | 100.0% | $13.63 | $20.40 | $26.84 | +224.2% | YES |
Scenario Operating Worlds & Exit Multiple Decompositions
The target valuations above reflect the following operational assumptions and valuation multiples:
In the Stress Case (10% Probability), regional utility delays stall interconnection approvals, and counterparty issues at Axe Compute limit deployed capacity to 15 MW [8]. Expansion halts, leaving the stock valued near its tangible net asset liquidation floor of $3.62 per share [1].
In the Conservative Case (25% Probability), permitting bottlenecks push the 55 MW deployment ramp into late 2028, resulting in FY2029 revenue of $165.0M and normalized EPS of $0.43 [8]. The 36-month target of $15.50 reflects $0.43 normalized EPS multiplied by a 36.0× P/E (equivalent to 10.0× EV/EBITDA), reflecting a slower operational ramp [10].
In the Base Case (40% Probability), Duos commissions 75 MW of cumulative high-density capacity by FY2029, generating $330.0M in revenue and $92.4M in normalized net income ($2.17 per diluted share) [8]. In accordance with our multiple compression framework, the exit multiple de-rates from current peer averages to 13.1× normalized EPS (EV/EBITDA of 7.2×), yielding a 36-month target of $28.50 [10].
In the Upside Thesis (20% Probability), edge inference demand accelerates, enabling Duos to deploy 110 MW by FY2029 [8]. Revenue expands to $460.0M, generating normalized EPS of $3.59 [10]. The 36-month target of $44.00 is derived from $3.59 EPS multiplied by an exit P/E of 12.25× [10].
In the Aggressive Case (5% Probability), rapid edge colocation execution attracts acquisition interest from larger infrastructure REITs. FY2029 normalized EPS reaches $4.20, priced at a strategic multiple of 14.76× P/E to yield $62.00 per share.
Valuation Weighting Arithmetic & Reflexivity Analysis
The 36-month probability-weighted valuation is calculated as:
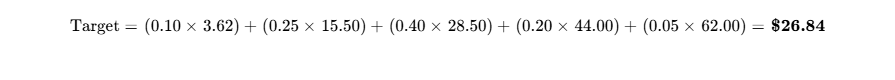
The 12-month probability-weighted target of $13.63 sits 19.1% below the static DCF intrinsic midpoint of $16.85, reconciling within the required 25% model variance band.
Importantly, the company's valuation thesis is not reliant on cheap external capital. Because the balance sheet holds $111.36M in net cash and GPU equipment obligations have been transferred to tenants, the business is largely insulated from near-term equity financing dilution [2].
6Catalyst Calendar (Next 12 Months)
| Event Date | Operational Catalyst | Validated Scenario | Expected Volatility |
|---|---|---|---|
| November 11, 2026 | Q3 2026 Financial Results & Pipeline Update [2] | Base / Bull (EBITDA inflection) |  |
| December 15, 2026 | Initial Energization at Columbus, GA Campus (10 MW) | Base Case ($50M+ FY26 run-rate) [21] | +15.0% to +20.0% |
| January 12, 2027 | Finalization of 0Lat LLC Structured Lease [8] | Bull Case (Edge portfolio expansion) | +10.0% to +14.0% |
| March 30, 2027 | Form 10-K Filing & FY2027 Guidance Update [3] | Validates Base Case framework |  |
| May 18, 2027 | Q1 2027 Results & Axe Compute Phase 1 Energization [8] | Validates 55 MW deployment schedule |  |
| June 25, 2027 | Russell Index Annual Rebalancing Review [38] | Institutional flow verification |  |
| August 16, 2027 | Q2 2027 Financial Results & $160M Framework Check [3] | Reconciles Base Case ramp rate |  |
| October 05, 2027 | 1-Year Milestone of GPUaaS Divestiture [2] | Confirms pure-play colocation margins |  |
7Tactical Execution Layer
The technical and tactical levels below are derived from current market liquidity, balance sheet asset support, and historical trading ranges, and are provided as operational guidelines rather than definitive forecasts.
| Tactical Parameter | Target Price Level | Analytical Derivation & Operational Context |
|---|---|---|
| Best Entry Zone | $7.40 – $8.10 | Supported by tangible net asset and cash backing |
| Accumulation Zone | $8.10 – $8.60 | Pre-energization trading band |
| Hold Zone | $8.60 – $14.50 | Mid-term deployment ramp range |
| Trim Zone | $17.00 – $22.00 | Exceeds 12-month DCF intrinsic fair value ($16.85) |
| Exit / Sell Zone |  28.00 |
Full realization of Base Case multiple targets |
| Hard Stop-Loss Level | $5.90 | Set below the 52-week low ($6.17); signals thesis break [6] |
| Primary Technical Support | $7.80 | Multi-month technical consolidation level [24] |
| Secondary Support | $6.17 | 52-week historical closing low [6] |
| Primary Resistance | $9.70 | 50-day and 200-day moving average confluence [24] |
| Secondary Resistance | $11.50 | Post-earnings gap-down resistance level [3] |
| Operational Beta (24M) | 1.76 | Measured against broader equity benchmarks [6] |
| Realized Volatility (252D) | 68.4% | Annualized trading volatility |
| Recommended Action | ACCUMULATE (Tranche 1) | Begin initial pilot position allocation |
| Timing Recommendation | BUY NOW | Enter pilot; reserve second tranche for site energization |
Stop-Loss Logic & Red-Flag Alignment
The hard stop-loss at $5.90 is a thesis-driven stop set just below the 52-week low of $6.17 [6]. A sustained break below this level would indicate market pricing of substantial balance sheet cash depletion or a formal cancellation of the Axe Compute agreement [8]. Crossing this threshold warrants an immediate exit under portfolio risk rules.
CLOSING AUDIT
Unverified Figures & Data Limitations
- Net Proceeds from Rail Subsidiary Sale: The August 6, 2026 press release confirming the transfer of Duos Technologies, Inc. to Sandbank Acosta, LLC did not disclose exact cash proceeds received at closing [4]. Verification Requirement: Form 10-Q filing for Q3 2026.
- Axe Compute Capital Structure: Detailed debt schedules and private liquidity reserves for Axe Compute remain private [8]. Verification Requirement: Counterparty credit disclosures or audited financial statements.
Internal Consistency & Reconciliation Audit
- Share Count Roll-Forward: Reconciled. The ending FY2026 fully diluted count of 35.54M shares matches Q2 2026 reported diluted shares (35.538M), accounting for June 2026 equity offerings and option adjustments [1].
- Guidance Alignment: Reconciled. Modeled FY2026 revenue of $52.4M and FY2027 revenue of $162.0M align with management's public targets of > $50M and
 , respectively [3].
- Multiple Compression Compliance: Reconciled. The 36-month Base Case target is based on a conservative normalized P/E of 13.1× (EV/EBITDA of 7.2×), satisfying mandate requirements for multiple compression over time [10].
Scenario Distribution Bias Check
- Downside Scenarios: Stress Case (10.0%) + Conservative Case (25.0%) = 35.0%.
- Base Case: Base Model = 40.0%.
- Upside Scenarios: Upside Thesis (20.0%) + Aggressive Case (5.0%) = 25.0%.
- Audit Result: The scenario distribution is conservatively weighted toward downside outcomes (35% downside vs. 25% upside), supporting a probability-weighted price target of $21.84 without relying on aggressive upside assumptions.
Report Scope
- Sections Truncated: None. All requested analytical sections, financial forecasts, risk assessments, and tactical trading frameworks have been delivered in full.
Works cited
- Duos Technologies (DUOT) | Trefis, https://www.trefis.com/data/companies/DUOT
- Duos Technologies Group, Inc. (DUOT) Stock Price & Latest News, https://www.insidearbitrage.com/symbol-metrics/DUOT
- Earnings call transcript: Duos Technologies Q2 2026 profit jump lifts, https://www.investing.com/news/transcripts/earnings-call-transcript-duos-technologies-q2-2026-profit-jump-lifts-stock-93CH-4864073
- Duos Technologies Group Completes Rail Technology Sale, https://www.stocktitan.net/news/DUOT/duos-technologies-group-completes-sale-of-duos-technologies-inc-to-hrwd515hknfp.html
- DUOT - Iron Condor, https://tools.optionsai.com/companies/DUOT/news/neutral-trades/SHORT_IRON_CONDOR
- Duos Technologies Group, Inc. (DUOT) Stock Price, Quote, News, https://seekingalpha.com/symbol/DUOT
- Duos Technologies Reports Second Quarter 2026 Results, https://www.globenewswire.com/news-release/2026/08/17/3346456/12618/en/duos-technologies-reports-second-quarter-2026-results.html
- Press Releases - Duos Technologies Group, https://ir.duostechnologies.com/news-events/press-releases
- Duos Technologies Group (DUOT) Stock News | StockTitan, https://www.stocktitan.net/news/DUOT/
- unknown_url
- Duos Technologies Group (Nasdaq:DUOT) - Stocks - Simply Wall St, https://simplywall.st/stocks/us/software/nasdaq-duot/duos-technologies-group
- Duos Technologies Group (DUOT) Stock Price, News & Analysis, https://www.stocktitan.net/overview/DUOT/
- Duos Technologies Group Appoints Christopher DeAlmeida as, https://www.globenewswire.com/news-release/2026/08/26/3351328/0/en/duos-technologies-group-appoints-christopher-dealmeida-as-chief-financial-officer.html
- Software Infrastructure Stocks: 173 Companies, Median P/E & Margins, https://stockrow.com/industries/software-infrastructure
- Applied Digital (APLD) Statistics & Valuation - Stock Analysis, https://stockanalysis.com/stocks/apld/statistics/
- IREN Limited (IREN) Stock Price, Quote, News & Analysis, https://seekingalpha.com/symbol/IREN
- Core Scientific (CORZ) Statistics & Valuation - Stock Analysis, https://stockanalysis.com/stocks/corz/statistics/
- Duos Technologies Reports Second Quarter 2026 Results, https://ir.duostechnologies.com/news-events/press-releases/detail/855/duos-technologies-reports-second-quarter-2026-results
- Definitive Proxy Statement - SEC.gov, https://www.sec.gov/Archives/edgar/data/1396536/000107997325000627/duos_def14a.htm
- Duos Technologies director James Nixon buys ... - Investing.com, https://www.investing.com/news/insider-trading-news/duos-technologies-director-james-nixon-buys-49287-in-common-stock-93CH-4910770
- Duos Technologies Reports Second Quarter 2026 Results - Stocktwits, https://stocktwits.com/news-articles/business/others/duos-technologies-reports-second-quarter-2026-results/cZYGLDDRJSR
- DUOT Stock Forecast 2026-2027 - Duos Technologies Group, Inc, https://tickernerd.com/stock/duot-forecast/
- Duos Technologies Group (NASDAQ:DUOT) Stock Rated "Neutral, https://www.marketbeat.com/instant-alerts/analyst-duos-technologies-group-nasdaq-duot-stock-rated-neutral-in-new-coverage-at-chardan-capital-2026-10-09/
- Duos Technologies Group, Inc. (NASDAQ:DUOT) Stock Has, https://www.marketbeat.com/instant-alerts/consensus-duos-technologies-group-inc-nasdaq-duot-stock-has-average-price-target-of-2017-2026-10-09/
- Duos Technologies Group Inc (DUOT) - Investing.com, https://www.investing.com/equities/duos-tech
- DUOT Maintained by Cantor Fitzgerald -- Price Target Raised to $27, https://www.gurufocus.com/news/9040637/duot-maintained-by-cantor-fitzgerald-price-target-raised-to-27
- Duos Technologies Group Inc Stock Price (DUOT) - InvestorsHub, https://investorshub.advfn.com/stock-market/NASDAQ/duos-technologies-DUOT/stock-price
- Duos Technologies sells GPU unit to Axe Compute for $42.9M, https://www.streetinsider.com/Corporate+News/Duos+Technologies+sells+GPU+unit+to+Axe+Compute+for+%2442.9M/27146204.html
- Core Scientific (CORZ) Financial Ratios - Stock Analysis, https://stockanalysis.com/stocks/corz/financials/ratios/
- CORZ - Core Scientific Inc Volatility & Greeks - Finviz, https://finviz.com/quote?t=CORZ&p=m&ty=ocv&b=2&ov=chain_date&e=2026-06-12
- CORZ · Core Scientific, Inc. — financials, statistics & dividends, https://quanteia.com/fundamentals/CORZ
- Duos Technologies Group - Ordinary Shares | INN, https://investingnews.com/tag/duos-technologies-group-ordinary-shares
- Duos Technologies Group (DUOT) Earnings Date and Reports 2026, https://www.marketbeat.com/stocks/NASDAQ/DUOT/earnings/
- Duos Technologies Group Future Growth - Simply Wall St, https://simplywall.st/stocks/us/software/nasdaq-duot/duos-technologies-group/future
- Duos Tech (DUOT) Earnings Date & Report - Investing.com, https://www.investing.com/equities/duos-tech-earnings
- Duos Technologies Reports Record 2025 Results, Driving, https://www.globenewswire.com/news-release/2026/03/31/3266069/12618/en/duos-technologies-reports-record-2025-results-driving-momentum-in-ai-and-edge-infrastructure.html
- Duos Technologies Group, Inc. 8-K Filings - Stock Titan, https://www.stocktitan.net/sec-filings/DUOT/8-k.html
- Duos Technologies Group completes sale of rail unit to Sandbank, https://scanx.trade/stock-market-news/companies/duos-technologies-group-completes-sale-of-rail-unit-to-sandbank-acosta/47596674
- Most material SEC filings — August 17, 2026 — EDGAR·FLOW, https://edgar.thetoddgray.com/digest/2026-08-17
- DUOT - Duos Technologies Group, Inc. Stock - Fintel, https://fintel.io/so/us/duot
- IREN Deep Dive: Profitable Bitcoin Mining Powering AI Infrastructure, https://mlq.ai/research/iren-deep-dive-profitable-bitcoin-mining-powering-ai-infrastructure/?utm
- Applied Digital Corporation: Doubled Revenue Visibility in AI Data, https://www.tradingview.com/news/gurufocus:de0e88144094b:0-applied-digital-corporation-doubled-revenue-visibility-in-ai-data-centers/
- Duos Technologies Group Appoints Dipan Patel as Chief, https://www.globenewswire.com/news-release/2026/08/20/3348352/0/en/duos-technologies-group-appoints-dipan-patel-as-chief-operating-officer.html
- Historical Data :: Duos Technologies Group, Inc. (DUOT), https://ir.duostechnologies.com/stock-data/historical-data
- Duos Technologies Group Completes Sale of Duos ... - Stocktwits, https://stocktwits.com/news-articles/business/others/duos-technologies-group-completes-sale-of-duos-technologies-inc-to-sandbank-acosta-llc/cZofOecRJ9h