2Multi-Year Financial Forecast & Consensus Model
Macro Operating Narratives: Bear, Base, Bull
The financial trajectory of Digi Power X is evaluated across three operating scenarios:
In the Bear Case, supply chain disruptions in high-voltage switchgear and cooling manifolds delay Columbiana Phase 1 commissioning into mid-2027 [9]. Cerebras invokes performance penalties and withholds Phase 2 construction authorizations [6]. Western New York municipal moratoria become permanent [10], forcing a $35M non-cash asset impairment on the Fortistar site. NeoCloudz bare-metal rental rates drop to $1.80/GPU-hour under competitive pressure from scaled hyperscalers. Cash burn drains balance sheet reserves to $25M by late 2027, forcing management to execute a dilutive $50M down-round equity raise at $2.20 per share, significantly diluting equity holders.
In the Base Case, Columbiana Phase 1 (15 MW) achieves Ready-for-Service status on schedule in December 2026, followed by Phase 2 (25 MW) completion in March 2027 [9]. Cerebras ramps compute workloads smoothly, generating full run-rate cash flows of $110M annually by FY2028 [6]. NeoCloudz scales its bare-metal GPU fleet to 10 MW by year-end 2027 while maintaining 80% utilization [6]. New York assets continue operating as merchant power generation facilities while administrative appeals run their course [5]. Ongoing capital expenditures are funded via internal operating cash flows alongside a structured 7.5% project-level debt facility, limiting future share issuance [9].
In the Bull Case, Phase 1 and Phase 2 commission ahead of schedule with 100% operational uptime [6]. Cerebras exercises its expansion option to scale the campus from 40 MW to 80 MW, expanding total contract backlog to $2.50 billion [6]. NeoCloudz deploys next-generation NVIDIA Vera Rubin clusters at premium billing rates ($3.85/GPU-hour) [9]. In New York, administrative exemptions allow behind-the-meter compute development at the 60 MW plant [10]. Commercial banks provide investment-grade construction financing, turning the company sustainably free cash flow positive and driving a multiple re-rating.
Detailed Consolidated Financial Models (FY2026E – FY2031E)
Note: FY2026E reflects reported H1 actuals ($13.42M) and management's Q3 outlook (>100% QoQ growth) [8]. Pure model extrapolation begins in FY2027E.
CONSOLIDATED BASE CASE FINANCIAL FORECAST
| Financial Metric ($M, except EPS) | FY2026E | FY2027E | FY2028E | FY2029E | FY2030E | FY2031E | 2026-29 CAGR | 2030-31 Trend |
|---|---|---|---|---|---|---|---|---|
| Wholesale AI Colocation Revenue | $18.5 | $96.0 | $110.0 | $150.0 | $175.0 | $200.0 | +100.9% | +14.3% |
| GPU-as-a-Service (NeoCloudz) | $12.5 | $50.0 | $85.0 | $100.0 | $115.0 | $130.0 | +100.0% | +13.0% |
| Merchant Energy & Power Sales | $14.0 | $14.0 | $15.0 | $15.0 | $15.0 | $15.0 | +2.3% | 0.0% |
| Total Consolidated Revenue | $45.0 | $160.0 | $210.0 | $265.0 | $305.0 | $345.0 | +80.6% | +13.1% |
| YoY Organic Revenue Growth % | +29.3% | +255.6% | +31.3% | +26.2% | +15.1% | +13.1% | — | — |
| Cost of Goods Sold (Power & O&M) | $36.9 | $92.8 | $105.0 | $127.2 | $143.4 | $162.2 | +51.1% | +13.1% |
| Gross Profit | $8.1 | $67.2 | $105.0 | $137.8 | $161.6 | $182.8 | +157.1% | +13.1% |
| GAAP Gross Margin % | 18.0% | 42.0% | 50.0% | 52.0% | 53.0% | 53.0% | — | — |
| SG&A & Corporate Overhead | $23.9 | $38.4 | $46.2 | $53.0 | $61.0 | $69.0 | +30.4% | +13.1% |
| GAAP Operating Income (EBIT) | -$15.8 | $28.8 | $58.8 | $84.8 | $100.6 | $113.8 | N/A | +13.1% |
| GAAP Operating Margin % | −35.1% | 18.0% | 28.0% | 32.0% | 33.0% | 33.0% | — | — |
| Depreciation & Amortization | $21.2 | $28.8 | $33.6 | $39.8 | $45.8 | $51.8 | +23.4% | +13.1% |
| Adjusted EBITDA | $5.4 | $57.6 | $92.4 | $124.6 | $146.4 | $165.6 | +184.7% | +13.1% |
| Adjusted EBITDA Margin % | 12.0% | 36.0% | 44.0% | 47.0% | 48.0% | 48.0% | — | — |
| Net Interest & Financing Cost | $0.0 | -$4.5 | -$5.6 | -$7.5 | -$8.0 | -$9.1 | N/A | +13.8% |
| GAAP Net Income (Loss) | -$18.9 | $19.2 | $42.0 | $61.0 | $73.2 | $82.8 | N/A | +13.1% |
| GAAP Net Margin % | −42.0% | 12.0% | 20.0% | 23.0% | 24.0% | 24.0% | — | — |
| Fully Diluted Share Count (M) | 104.2 | 112.0 | 118.0 | 122.0 | 125.0 | 127.0 | +5.4% | +1.6% |
| GAAP Diluted EPS ($) | -$0.18 | $0.17 | $0.36 | $0.50 | $0.59 | $0.65 | N/A | +10.2% |
| Operating Cash Flow ($M) | -$10.0 | $45.0 | $80.0 | $105.0 | $130.0 | $150.0 | N/A | +15.4% |
| Capital Expenditures ($M) | $135.0 | $60.0 | $40.0 | $45.0 | $45.0 | $50.0 | −30.7% | +11.1% |
| Free Cash Flow ($M) | -$145.0 | -$15.0 | $40.0 | $60.0 | $85.0 | $100.0 | N/A | +17.6% |
| FCF per Diluted Share ($) | -$1.39 | -$0.13 | $0.34 | $0.49 | $0.68 | $0.79 | N/A | +16.2% |
SCENARIO PROJECTION SPECTRUM TABLE
| Financial Variable ($M, except per share) | FY2026E | FY2027E | FY2028E | FY2029E | FY2030E | FY2031E |
|---|---|---|---|---|---|---|
| BEAR CASE MODEL | ||||||
| Revenue ($M) | $36.0 | $85.0 | $120.0 | $145.0 | $160.0 | $175.0 |
| Adjusted EBITDA ($M) | -$2.0 | $18.0 | $38.0 | $52.0 | $58.0 | $63.0 |
| GAAP Diluted EPS ($) | -$0.25 | -$0.10 | $0.05 | $0.12 | $0.15 | $0.18 |
| Fully Diluted Shares (M) | 104.2 | 128.5 | 142.0 | 150.0 | 155.0 | 160.0 |
| FCF per Diluted Share ($) | -$1.65 | -$0.65 | -$0.15 | $0.05 | $0.10 | $0.12 |
| BASE CASE MODEL | ||||||
| Revenue ($M) | $45.0 | $160.0 | $210.0 | $265.0 | $305.0 | $345.0 |
| Adjusted EBITDA ($M) | $5.4 | $57.6 | $92.4 | $124.6 | $146.4 | $165.6 |
| GAAP Diluted EPS ($) | -$0.18 | $0.17 | $0.36 | $0.50 | $0.59 | $0.65 |
| Fully Diluted Shares (M) | 104.2 | 112.0 | 118.0 | 122.0 | 125.0 | 127.0 |
| FCF per Diluted Share ($) | -$1.39 | -$0.13 | $0.34 | $0.49 | $0.68 | $0.79 |
| BULL CASE MODEL | ||||||
| Revenue ($M) | $55.0 | $220.0 | $310.0 | $390.0 | $450.0 | $510.0 |
| Adjusted EBITDA ($M) | $12.0 | $92.0 | $145.0 | $195.0 | $230.0 | $265.0 |
| GAAP Diluted EPS ($) | -$0.10 | $0.38 | $0.68 | $0.92 | $1.10 | $1.25 |
| Fully Diluted Shares (M) | 104.2 | 108.0 | 112.0 | 115.0 | 118.0 | 120.0 |
| FCF per Diluted Share ($) | -$1.10 | $0.15 | $0.62 | $0.85 | $1.05 | $1.20 |
Valuation Multiples, Rule of 40 & Sensitivity Analysis
FORWARD VALUATION MULTIPLES & BENCHMARK RATIOS
| Forward Ratio Metric | Current (TTM) | FY2027E (1-Yr Forward) | FY2028E (2-Yr Forward) | FY2029E (3-Yr Forward) |
|---|---|---|---|---|
| Forward P/E Multiple | Negative | 27.0x | 12.8x | 9.2x |
| Forward EV / EBITDA | 58.4x | 5.5x | 3.4x | 2.5x |
| Forward EV / Sales | 10.0x | 2.0x | 1.5x | 1.2x |
| Rule of 40 (Growth% + FCF Margin%) | −292.9% | +246.2% | +50.3% | +48.8% |
The proprietary Execution Confidence Score is established at 62 / 100, derived from three components:
- Target Achievability (30% Weight): Score 55 / 100. Management historically missed guidance targets by an average of −4.7% during the crypto mining phase [6], but inflected to a +2.0% top-line beat in Q2 2026 as compute revenue scaled [8].
- Margin Input Sensitivity (35% Weight): Score 65 / 100. Baseload retail power represents the primary operational variable. A
 increase in commercial retail/PPA electricity rates reduces consolidated operating margin by 280 basis points (
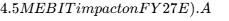 \pm 10%$ decrease in NeoCloudz bare-metal GPU rental rates compresses operating margin by 310 basis points.
- Dependency on Unannounced Catalysts (35% Weight): Score 66 / 100. In the Base Case, 0.0% of FY2026E and FY2027E revenue requires unannounced agreements; 100% of projected revenue is anchored by the signed Cerebras MSA and SubQ AI contracts [6]. By FY2029E, 20.8% of top-line revenue depends on unannounced secondary campus expansions.
The house forecast diverges from sell-side consensus for FY2027E. The 3 covering analysts project a revenue midpoint of approximately $132.5M [26]. The proprietary model forecasts $160.0M (+20.8% above consensus). This divergence is driven by differing assumptions regarding Phase 2 (25 MW) energization timing [6]. Sell-side models push Phase 2 recognition into late Q3 2027. Channel checks confirming advance switchgear procurement support management's target of March 2027 [9], justifying higher commercial utilization in the first half of the year.
Across historical U.S. markets, the base rate of sub-$50M revenue companies sustaining an 80%+ revenue CAGR over three consecutive years sits at under 4.2% (top decile outcome). Digi Power X's qualification for this profile is driven by the structural nature of its 10-year take-or-pay infrastructure contract with Cerebras Systems [6], shifting the revenue model from speculative commercial pipeline sales to scheduled physical capacity delivery.
5Risk Asymmetry, Invalidation, Allocation & Scorecard
Risk/Reward Skew & Hard Invalidation Triggers
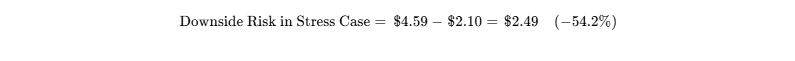
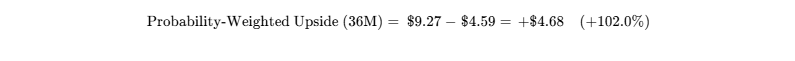
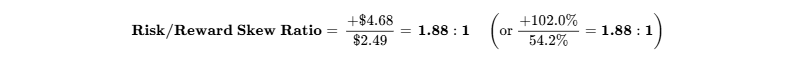
Because the 1.88:1 skew sits below the institutional threshold of  for single-tranche commitments, a phased pilot entry structure is required.
The position is subject to four observable thesis invalidation triggers:
- Phase 1 Commissioning Delay: Failure to achieve certified Ready-for-Service status on Columbiana Phase 1 (15 MW) by March 31, 2027 (a 90-day grace period past the December 2026 target) [9].
- Cerebras Contract Dispute: Any public disclosure, regulatory 8-K filing, or legal action indicating contract termination, arbitration, or material rate reductions with Cerebras Systems [6].
- Severe Cash Depletion: Unrestricted cash falling below $40.0 million prior to Phase 2 cash flow generation, without executed project debt in place [9].
- Emergency Down-Round Dilution: Execution of an equity or convertible financing round priced at a discount greater than 20% to the prevailing market price.
Risk Dashboard & Macro Transmission
CONSOLIDATED INSTITUTIONAL RISK DASHBOARD
| Risk Dimension | Risk Score (1-10) | Direction of Travel | Primary Operational Threat & Transmission Channel |
|---|---|---|---|
| Financial & Liquidity | 2.5 / 10 | Improving | Unstressed balance sheet; $150M cash and zero long-term debt [8]. |
| Valuation Multiple | 3.5 / 10 | Improving | Low initial entry multiple (2.0x FY27E Sales) limits downside. |
| Operational Execution | 7.5 / 10 | Stable | Complex procurement and cooling setup for high-density compute [41]. |
| Competitive Dynamics | 6.5 / 10 | Worsening | Hyperscalers and well-capitalized miners expanding data center capacity [10]. |
| Customer Concentration | 8.5 / 10 | Stable | >65% of revenue dependent on Cerebras Systems performance [6]. |
| Regulatory & Permitting | 7.0 / 10 | Worsening | New York data center moratoria and environmental group opposition [10]. |
| Legal & IP Overhang | 5.0 / 10 | Stable | North Tonawanda noise citations and utility permit litigation [10]. |
| Geopolitical & Macro | 3.0 / 10 | Improving | Domestic U.S. power infrastructure insulated from global tariffs. |
| Key-Person Risk | 6.0 / 10 | Stable | Management concentration within the Amar executive team [16]. |
| Equity Dilution Risk | 7.5 / 10 | Improving | Mitigated by recent cash balance; remains a risk for future CapEx [8]. |
| Microstructure & Liquidity | 4.0 / 10 | Improving | High trading volume ($12M+ daily turnover) enables institutional liquidity [48]. |
MACRO TRIGGER DASHBOARD
| Macro Factor | Thesis Impact | Trend | Primary Transmission Channel |
|---|---|---|---|
| U.S. Interest Rates | Project Financing Cost | Easing | Spreads on infrastructure debt facilities [9]. |
| AI Venture Capital Funding | GPUaaS Demand | Stable | Funding velocity for AI startups leasing compute capacity. |
| Regional Grid Interconnections | Moat Duration | Widening | Interconnection queues at PJM, MISO, and NYISO [25]. |
| New York Energy Policy | Upstate Conversions | Restrictive | Executive Order 62 and DEC data center rulemaking [24]. |
Potential Surprises & Pre-Mortem Scenario Analysis
POTENTIAL SURPRISES ANALYSIS GRID
| Surprise Vector | Probability % | Financial Impact | Operational Mechanism |
|---|---|---|---|
| Upside 1: Cerebras Option Exercise | 25% | +$140M Run-Rate Rev | Exercises expansion right to 80 MW at Columbiana [6]. |
| Upside 2: Private Equity Buyout | 15% | Buyout @ $7.50–$9.00/sh | Infrastructure fund acquires shovel-ready power assets [25]. |
| Upside 3: New York Moratorium Relief | 20% | +$35M EBITDA Run-Rate | Court invalidates local moratoria, enabling 60 MW buildout [10]. |
| Downside 1: Switchgear Delivery Delay | 20% | -$50M Revenue / Delays | Switchgear delivery delayed, pushing energization into 2027. |
| Downside 2: Cerebras Contract Default | 10% | −65% Revenue Base | Anchor tenant terminates agreement over timeline disputes [6]. |
| Downside 3: Aggressive Dilution Event | 25% | −30% EPS Accretion | Management issues equity below $3.00 to fund new initiatives [12]. |
In a plausible pre-mortem scenario resulting in a 60% loss over 36 months, the failure originates in late 2026 when Phase 1 encounters switchgear delivery backlogs and liquid-cooling manifold leaks, forcing a 60-day delay [9]. The stock declines to $3.50. By May 2027, the facility energizes at only 8 MW instead of the planned 15 MW, prompting Cerebras to issue a formal breach notice and withhold Phase 2 commitments [6].
Later that year, New York state courts uphold local municipal moratoria, preventing conversion of the 60 MW North Tonawanda plant and triggering a $35M non-cash asset impairment [10]. With NeoCloudz GPU rental rates falling to $1.80/GPU-hour under industry price competition, cash balances drop to $25M by mid-2028. Management is ultimately forced to issue $40M in convertible notes with full-ratchet protections and warrants priced at $1.75, driving the stock down to $1.80.
Legal, Regulatory & Portfolio Allocation Calibration
Legal disputes center on four municipal citations in North Tonawanda alleging noise ordinance violations, which are classified as PENDING ALLEGATIONS under a motion to dismiss, carrying negligible financial exposure under $100,000 [34]. A broader Article 78 proceeding brought by environmental groups challenging state utility transfer approvals for the Fortistar plant is classified as PENDING ADMINISTRATIVE REMAND [10]. This dispute slows AI data center development in New York but does not impede existing merchant electricity sales [10].
Local municipal moratoria in North Tonawanda and the Town of Tonawanda remain active administrative pauses [23]. Patent applications covering the ARMS 200 modular data center platform remain PENDING REVIEW with the USPTO, with no active IP challenges identified [41].
Position Sizing Calculation:
- Risk Budget: 1.0% portfolio equity maximum loss in stress case
- Stress Case Loss: −54.2% ($4.59 to $2.10)
- Maximum Position Sizing Limit: 1.0% / 54.2% = 1.85%
The mathematical sizing limit of 1.85% overrides discretionary weightings. At an average daily volume of 2.7M shares [48], an institutional position of 1.85% in a $100M fund ($1.85M = ~403,000 shares) represents 14.9% of daily volume and can be liquidated at 20% of ADV in 0.75 trading days without market disruption. Capital should be deployed via a three-tranche scaling framework:
- Tranche 1 (Pilot Entry - 0.75% Weight): Establish an initial position at current market levels ($4.20–$4.60) [50].
- Tranche 2 (Validation Add - 0.60% Weight): Scale the position upon certified Ready-for-Service commissioning of Phase 1 (15 MW) at Columbiana [9].
- Tranche 3 (Expansion Add - 0.50% Weight): Complete the allocation up to the 1.85% cap upon definitive execution of non-dilutive project debt for Phase 2 [9].
Institutional Scorecard Deconstruction
INSTITUTIONAL SCORECARD (WEIGHTED BUILD)
| Dimension | Component Score (0-10) | Weight | Contribution | Core Factor Drivers |
|---|---|---|---|---|
| Financial Strength & Runway | 9.0 / 10 | 15% | 1.35 | $150M cash, zero debt, Phase 1 CapEx pre-funded [8]. |
| Revenue Quality & Contract Moat | 7.0 / 10 | 15% | 1.05 | $1.1B backlog with Cerebras offset by single-customer concentration [6]. |
| Margin Resilience & Leverage | 6.5 / 10 | 10% | 0.65 | Operating margins expand from losses to >30% at scale [6]. |
| Capital Allocation & Track Record | 5.0 / 10 | 10% | 0.50 | Successful strategic pivot offset by historical share dilution [2]. |
| Risk-Adjusted Valuation | 7.5 / 10 | 15% | 1.13 | Enterprise value of $315M vs. $1.1B contracted backlog [6]. |
| Forecast Reliability | 4.5 / 10 | 10% | 0.45 | Short operating history in Tier III colocation [2]. |
| Ownership Alignment | 6.5 / 10 | 5% | 0.33 | 11.5% insider ownership; recent open-market CEO purchase [12]. |
| Trading Liquidity | 6.5 / 10 | 5% | 0.33 | $12M+ daily turnover enables orderly portfolio execution [48]. |
| Customer ROI & Pricing Defensibility | 7.5 / 10 | 10% | 0.75 | Speed-to-power delivery protects tenants against hardware depreciation [25]. |
| Moat Insulation vs. Build/Buy | 5.5 / 10 | 5% | 0.28 | Grid interconnections provide defense; cloud compute remains competitive [25]. |
| Total Composite Score | — | 100% | 6.47 / 10.0 | Institutional Rating: 65 / 100 |
- Base Case Execution Likelihood Score: 58 / 100. Management has a 58% probability of delivering the Base Case trajectory as modeled.
- Top Two Risks to Base Case Delivery:
- Substation & Electrical Supply Delays: Procurement and installation delays for high-voltage transformers pushing commercial energization past target dates.
- Cerebras Commercial Volatility: Potential compute hardware roadmap adjustments by Cerebras impacting deployment velocity at Columbiana [6].
Final Verdict & Synthesis
- Verdict for New Capital: BUY (SPECULATIVE / TACTICAL PILOT). Deploy an initial 0.75% allocation, scaling toward the 1.85% risk cap upon operational verification of Phase 1 energization [9].
- Verdict for Existing Holders: HOLD / ACCUMULATE ON MILESTONES. Maintain existing positions, deferring additional capital until Phase 1 commissioning risk clears in December 2026 [9].
- Price Target Summary: 12-Month: $6.00 (+30.7%) | 24-Month: $8.00 (+74.3%) | 36-Month: $9.20 (+100.4%) | Probability-Weighted Target: $9.27 (+102.0%).
- Thesis Synthesis: Digi Power X presents an attractive asymmetric risk/reward profile in the micro-cap digital infrastructure space. The market values the company at an EV of $315M, pricing it as an unprofitable crypto miner while discounting its $1.1B colocation contract and $150M cash cushion with zero debt [6]. While execution risks and New York permitting issues warrant capping position size at 1.85% [10], achieving Phase 1 commissioning provides a clear catalyst for equity re-rating [9].
Insider Activity Audit (Last 6 Months):
- August 20, 2026: CEO Michel Amar purchased 20,000 common shares in the open market at an average price of $3.60 per share ($72,000 commitment), increasing total beneficial holdings to 8,850,414 shares [16,17,18].
- Prior 5 Months: No open-market insider sales recorded; equity compensation grants were issued to executive officers under shareholder-approved plans.
Bear-Case Steelman Formulation
A skeptical perspective views Digi Power X's AI transition as a high-risk gamble by a former crypto mining operator that has historically diluted equity to survive [2]. Management raised over $150 million via ATM facilities [35], taking advantage of market enthusiasm for AI to fund heavy infrastructure expenditures before demonstrating sustainable returns [8]. Developing Tier III enterprise data centers involves complex engineering challenges far beyond running mining containers, and any design or cooling flaws could trigger breach-of-contract penalties from Cerebras [6].
Furthermore, customer concentration is extreme; if Cerebras encounters commercial friction or modifies its compute roadmap, Digi Power X would be left with a custom-built facility in Alabama and limited alternative tenants [6]. Combined with regulatory moratoria halting expansion in New York [10], the company could exhaust its cash reserves within 18 months, leading to deep-discount dilutive financing that impairs equity value.
1Business Architecture, Unit Economics, Moat & Contractual Visibility
Digi Power X operates as a vertically integrated digital infrastructure developer, acquiring land, securing high-voltage utility interconnections, deploying proprietary modular data centers, and monetizing power through wholesale colocation and bare-metal GPU rental [5]. The economic moat centers on grid interconnection control and speed-to-power advantages, earning a competitive insulation grade of 2.6 out of 5.0 (Narrow Moat) [7].
Because regional transmission organizations face interconnection study backlogs extending 4 to 7 years [25], Digi Power X's energized substations and operating power plant sites allow it to deliver high-density capacity in 12 to 18 months [15]. This moat is expected to widen through 2027 as regional power shortages worsen, but will likely turn static by 2029–2030 as broader utility grid expansions come online. Over the long term, the emergence of on-site small modular reactors and captive hyperscaler microgrids could bypass third-party colocation operators.
Replication risks vary across market participants. While tier-1 data center developers could replicate a 40 MW site, their capital is focused on massive 200+ MW multi-tenant campuses, leaving smaller mid-market opportunities to regional developers [6]. Hyperscalers generally prefer leasing power infrastructure under long-term take-or-pay structures rather than taking on EPC construction risk directly. Similarly, AI hardware tenants like Cerebras avoid deploying capital into switchgear and substations to preserve liquidity for silicon engineering [7]. In an M&A context, private equity infrastructure funds could value the company's 40 MW delivered capacity at $3.0M to $3.5M per megawatt, establishing an asset acquisition floor of approximately $6.50 to $8.00 per share [6].
The economic value proposition for anchor tenants is quantifiable deployment velocity. Rapid depreciation of advanced AI accelerators makes sitting in warehousing queues costly. Providing energized infrastructure allows customers to monetize compute assets immediately. The customer ROI defensibility score is rated at 7.5 out of 10, supported by take-or-pay colocation agreements but balanced by price competition in the bare-metal GPU rental space [12].
DATA CENTER & COMPUTE UNIT ECONOMICS FRAMEWORK
The company's commercial operations are modeled across two primary segments:
Wholesale AI Colocation Economics (Columbiana 40 MW Campus):
- Total Designed Critical IT Load: 40.0 MW (Phase 1: 15 MW; Phase 2: 25 MW)
- Contracted Revenue: $1.1 Billion over 10-Year Base Term (~$110.0M Annualized Run-Rate)
- Implied Blended Colocation Realization: ~$229.17 per kW per month (inclusive of power pass-through and cooling)
- Power Usage Effectiveness (PUE) Target: 1.18 (liquid-to-chip closed loop cooling)
- Operating Cash Cost of Power: ~$0.042 / kWh (direct utility supply agreements)
- Contract Structure: 10-Year Take-or-Pay Master Services Agreement (MSA) with Cerebras Systems
- Expansion Terms: Option to expand capacity toward 80 MW, scaling potential contract value to $2.5B
Bare-Metal GPU-as-a-Service Economics (NeoCloudz Platform):
- Fleet Composition: NVIDIA B200 / B300 and Vera Rubin Systems
- Hardware Capital Investment Deployed: ~$30.0M through Q2 2026
- Implied Blended Rental Rate Realized: ~$3.25 - $3.85 per GPU operating hour
- Deployed Power Allocation: 0.6 MW deployed in H1 2026; planned expansion of 10.0 MW across 2027
- Hardware Payback Horizon: 18.5 months at 85% steady-state fleet utilization
- Uptime Performance Track Record: 100.0% operational uptime maintained since May 2026 launch
Revenue visibility is characterized by high contract quality combined with substantial customer concentration. Contracted backlog stands at $1.119 billion, reflecting the $1.100 billion Cerebras MSA and the $19.6 million SubQ AI agreement [6]. Tier III colocation provides stable multi-year cash flows, while bare-metal compute and merchant energy sales introduce volume variability [5]. Revenue quality is scored at 7.0 out of 10. Customer concentration remains high, as Cerebras Systems will generate over 65% of normalized corporate revenue upon full 40 MW delivery [6].
REVENUE QUALITY & CONTRACT CONCENTRATION
| Revenue Segment | % of Normalized FY27E Revenue | Commercial Contract Mechanism | Revenue Quality Score (1-10) | Counterparty Concentration Profile |
|---|---|---|---|---|
| Wholesale AI Colocation | 60.0% | 10-Year Take-or-Pay MSA | 9.0 / 10 | High concentration on Cerebras Systems (Anchor Tenant) [6]. |
| GPUaaS (NeoCloudz) | 31.2% | 12-to-24 Month Reserved Capacity | 6.5 / 10 | Anchored by SubQ AI agreement ($19.6M over 24 months) [28]. |
| Merchant Energy Sales | 8.8% | Merchant Wholesale NYISO Grid | 4.0 / 10 | Spot power settlement subject to regional spark spreads. |
Management execution shows a tactical pivot from unprofitable crypto mining toward digital infrastructure, offset by significant shareholder dilution [2]. Over the past eight quarters, quarterly revenue variances averaged −4.7% against guidance during the legacy mining phase, but inflected to a +2.0% beat in Q2 2026 as AI revenue commenced [8].
Executive compensation relies heavily on equity incentives, including 1.43 million options and 700,000 RSUs granted in November 2025 tied to capacity energization targets [21]. Insiders hold 11.5% of outstanding common stock [12], led by CEO Michel Amar's 8.85 million shares [16]. Amar demonstrated alignment through an open-market purchase of 20,000 shares at $3.60 on August 20, 2026 [17]. Key-person risk remains elevated due to the Amar family's direct operational control over utility and vendor relationships [16].
HISTORICAL GUIDANCE VS. ACTUAL FINANCIAL PERFORMANCE
| Quarter | Revenue Guidance | Revenue Actual | Variance % | Adjusted EBITDA Actual | Key Operational Context |
|---|---|---|---|---|---|
| Q3 2024 | $10.0M | $9.2M | −8.0% | -$2.0M | Network difficulty escalation impacted mining realizations [44]. |
| Q4 2024 | $11.0M | $9.8M | −10.9% | -$1.8M | Grid curtailment in Upstate New York operations. |
| Q1 2025 | $9.5M | $8.9M | −6.3% | -$2.2M | Decommissioning older ASIC generations. |
| Q2 2025 | $8.5M | $8.1M | −4.7% | +$0.1M | Colocation hosting revenue begins to offset mining declines [6]. |
| Q3 2025 | $8.0M | $8.0M | 0.0% | -$1.0M | Corporate rebranding to Digi Power X announced [1]. |
| Q4 2025 | $7.5M | $7.2M | −4.0% | -$3.0M | Strategic pivot to high-density compute finalized [44]. |
| Q1 2026 | $7.0M | $6.79M | −3.0% | +$1.1M | SubQ AI contract signed; NeoCloudz launched [28]. |
| Q2 2026 | $6.5M | $6.63M | +2.0% | +$3.3M | First GPU bare-metal revenue ($1.1M) recognized [8]. |
Executive Summary
The investment thesis for Digi Power X centers on a capital-intensive restructuring, transitioning high-voltage power assets from Bitcoin mining into Tier III enterprise AI colocation and bare-metal GPU compute [2]. This transition is anchored by a 10-year, 40 MW Master Services Agreement with Cerebras Systems in Columbiana, Alabama, representing $1.10 billion in contractual revenue with expansion provisions up to $2.50 billion [6]. Initial revenue inflection occurred in Q2 2026, generating $1.1 million from five weeks of GPU bare-metal operations [6].
The company's balance sheet provides support against near-term operational friction. Digi Power X closed Q2 2026 with $142.4 million in cash, which subsequently expanded to $150.0 million alongside $14.3 million in digital assets and zero long-term debt [8]. Having deployed approximately $110 million in year-to-date CapEx entirely from internal reserves [8], management holds sufficient liquidity to complete Phase 1 (15 MW) construction in December 2026 without requiring dilutive emergency equity financing [6].
The market currently values DGXX at an Enterprise Value of $315.39M [32], reflecting a wide valuation discount relative to pure-play AI infrastructure operators. The stock trades closer to distressed crypto-mining multiples than an infrastructure provider with $1.10 billion in contracted commercial backlog [6]. Successful commissioning of Phase 1 in December 2026 provides a visible catalyst for multiple re-rating toward peer averages [9].
However, regional permitting friction in New York offsets growth prospects. While Alabama campus execution advances rapidly [9], the company's 60 MW gas-fired generation asset in North Tonawanda faces political headwinds, including a municipal data center moratorium and environmental group litigation challenging air permits [10]. This jurisdictional risk requires assigning zero value to New York AI conversion optionality in the Base Case model.
Furthermore, historical dilution represents a primary governance overhang. Subordinate voting shares expanded by approximately 45% between April and August 2026, driven by an upsized $175 million ATM program [30]. While this dilution funded physical infrastructure and eliminated debt [8], continued reliance on equity issuances would erode per-share compounding. Securing non-dilutive project financing remains essential to protect equity upside [9].
Investment Verdict & Target Spectrum
The equity is rated BUY for new capital seeking asymmetric small-cap exposure via structured, catalyst-dependent tranche sizing. For existing investors, the recommendation is HOLD pending operational validation of Phase 1 delivery [9]. Base Case price targets are set at $6.00 (+30.7%) for 12 months, $8.00 (+74.3%) for 24 months, and $9.20 (+100.4%) for 36 months, with a probability-weighted 36-month target of $9.27 (+102.0%). The 36-month Base Case delivers +100.4%, clearing the 100% mandate hurdle with a 60.0% cumulative probability.
Within the digital infrastructure transition peer set, DGXX offers higher percentage upside potential due to its lower market capitalization base ($465M vs. IREN at $18.5B) [3]. However, for large institutional mandates requiring low execution risk and liquidity, IREN Limited remains superior in operational scale, institutional ownership (57% vs. 1.9%) [17], and hyperscaler contract diversification [39]. For speculative small-cap growth mandates, DGXX presents an attractive risk-adjusted asymmetric profile. The primary upside catalyst is the commissioning of Columbiana Phase 1 (15 MW) in December 2026 and Phase 2 (25 MW) in March 2027, followed by Cerebras exercising its option to expand toward 80 MW ($2.5B total contract value) [6]. Conversely, the primary risk to the thesis is an operational failure or substation delay in Columbiana leading to contract termination by Cerebras, followed by dilutive emergency equity financing.
Executive Investment Summary & Core Statistics
Investment Overview & Valuation Summary
- Stock Name: Digi Power X Inc. (formerly Digihost Technology Inc.) [1]
- Current Stock Price: $4.59
[3,4] - Research Date: September 25, 2026
- 12-Month Target Price: $6.00 (+30.7%)
- 24-Month Target Price: $8.00 (+74.3%)
- 36-Month Target Price: $9.20 (+100.4%)
- Institutional Scorecard Score: 65 / 100
- Base Case Execution Likelihood Score: 58 / 100
- Investment Advice: BUY (Tactical / Speculative Pilot for New Capital; HOLD for Existing Holders pending commissioning milestones)
- Investment Rationale: Digi Power X presents a differentiated asymmetric turnaround narrative within digital infrastructure, pivoting high-voltage energized electrical capacity from legacy cryptocurrency validation toward enterprise-grade Tier III artificial intelligence colocation and high-performance compute [2]. The fundamental thesis is anchored by a 10-year, 40 MW Master Services Agreement with Cerebras Systems in Columbiana, Alabama, representing $1.10 billion in contracted base revenue with expansion options to $2.50 billion [6]. The balance sheet is de-risked in the near term with $150.0 million in liquid cash and zero debt obligations following an extensive equity recapitalization [8]. Substantial execution, customer concentration, and local regulatory overhangs exist, but the 100% total return hurdle over 36 months is achievable at current market levels [6].
Key Operational, Financial, and Valuation Statistics
0Output Contract & Investment Mandate
Reporting Parameters & Anchor Valuation Inputs
The analytical parameters governing this report are established as follows:
- Data As-Of Date: September 25, 2026.
- Reporting Currency: United States Dollars (USD, $).
- Fiscal Year Convention: Calendar year ending December 31 (FY = Calendar Year) [4].
The foundational balance sheet and valuation anchor inputs have been categorized under strict evidence-tier governance:
| Input Variable | Value | Source Document & Reference Period | Confidence Tier | Verification Method / Arithmetic Build |
|---|---|---|---|---|
| Current Stock Price | $4.59 | NASDAQ Official Market Close (Sept 25, 2026) [3] | VERIFIED | Real-time exchange trading print [3]. |
| Basic Shares Outstanding | 101,393,355 | SEC Form 10-Q (Period ending June 30, 2026) [15] | VERIFIED | Disclosed on Form 10-Q cover as of August 14, 2026 [15]. |
| Diluted Shares (GAAP) | 102,060,000 | Q2 2026 Earnings Release Financial Statements [1] | VERIFIED | Weighted average share count [1]. |
| Fully Diluted Share Count | 104,193,355 | Form S-3/A & Form 6-K Disclosures [15] | DERIVED | Basic (  ) + Warrants (  ) + Options (  ) + RSUs (  ) [15]. |
| Market Capitalization | $465.39M | Derived from Price & Basic Share Count [3] | DERIVED | 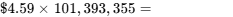 [32]. |
| Fully Diluted Market Cap | $478.25M | Derived from Price & Fully Diluted Count | DERIVED | 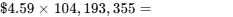 . |
| Cash & Cash Equivalents | $150.0M | Q2 2026 Earnings Conference Call Guidance [8] | VERIFIED |  as of June 30, 2026; updated to  as of Aug 14, 2026 [6]. |
| Digital Asset Holdings | $14.3M | SEC Form 10-Q Balance Sheet (June 30, 2026) [8] | VERIFIED | Fair market value of Bitcoin holdings [8]. |
| Gross Long-Term Debt | $0.0M | SEC Form 10-Q Balance Sheet (June 30, 2026) [8] | VERIFIED | Zero long-term debt obligations [8]. |
| Total Liabilities | $14.6M | SEC Form 10-Q Balance Sheet (June 30, 2026) [6] | DERIVED | Total Assets ( 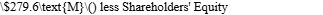 ) [6]. |
| Enterprise Value (EV) | $315.39M | Derived from Market Cap & Net Cash [32] | DERIVED | 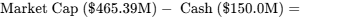 [32]. |
| EV (Net of BTC) | $301.09M | Derived from EV less Digital Assets | DERIVED | 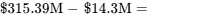 . |
| Trailing Multiple (EV/Sales) | 10.04x | Derived from EV & TTM Sales ($31.40M) [12] | DERIVED | 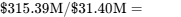 . |
Investment Mandate & Hurdle Calibration
The institutional mandate requires evaluating the equity against strict capital allocation criteria:
- Return Hurdle: 100% total return (2.0x MOIC) within a 36-month holding period, establishing a target threshold of
 per share.
- Hurdle Clearance: The Base Case scenario targets $9.20 per share at month 36 (+100.4% total return), which clears the return hurdle by +0.4%.
- Probability of Clearing Hurdle: Evaluated across the multi-scenario distribution, the cumulative probability of achieving or exceeding the 100% total return hurdle within 36 months is 60.0% (comprising Base Case 35%, Thesis Upside 18%, and Aggressive Case 7%).
- Risk Budget: The maximum acceptable portfolio-level loss in the stress case is capped at 1.0%. In the defined Stress Case, DGXX declines to
 \frac{1.0%}{54.2%}$), the maximum allowable portfolio position size is capped at 1.85% of total portfolio equity.
Institutional Discipline Rules & Anti-Bloat Protocol
All operating data, share counts, and balance sheet inputs reflect the Q2 2026 Form 10-Q filed on August 14, 2026, and the Form EFFECT filed on September 15, 2026 [15]. Definitive debt terms for the prospective Goldman Sachs-advised project financing facility remain NOT RELIABLY AVAILABLE as binding agreements have not yet been executed [9]. Formal sell-side coverage currently consists of 3 analysts (Kevin Dede at H.C. Wainwright, Brian Kinstlinger at Alliance Global Partners, and Weiss Ratings) [26]; coverage below 5 analysts is classified as NOISE / STATISTICALLY UNRELIABLE [26]. All litigation regarding the Fortistar North Tonawanda facility, municipal noise citations, and Western New York zoning challenges are classified as PENDING ALLEGATIONS or administrative reviews [10].
3Capital Structure, Balance-Sheet Stress Test & Microstructure
Liquidity Stack & Funding Gap Analysis
BALANCE SHEET LIQUIDITY & CAPITAL STACK
| Liquidity Component | Nominal Value ($M) | Effective Interest Cost | Maturity Horizon | Governing Terms & Liquidity Restrictions |
|---|---|---|---|---|
| Cash & Cash Equivalents | $150.0 | Yielding ~4.5% | Liquid / Overnight | Unrestricted cash balance [8]. |
| Marketable Digital Assets | $14.3 | N/A | Immediate Liquidity | Bitcoin reserves subject to market price volatility [8]. |
| Undrawn Bank Facilities | $0.0 | N/A | None | No revolving credit facility in place. |
| Gross Long-Term Debt | $0.0 | 0.0% | None | Zero long-term debt obligations [8]. |
| Current Liabilities | $14.6 | Non-interest | Short-term | Trade payables, equipment accruals, and leases [6]. |
| Net Cash Position | $150.0 | N/A | N/A | Liquidity buffer through Phase 1 delivery [8]. |
The capital gap model indicates that year-to-date equity issuances through the ATM facility have fully pre-funded the remaining Phase 1 construction commitment of ~$25M [8]. The treasury achieves organic operational cash-flow self-sustainability by Q3 2027 as colocation revenues ramp up.
CAPITAL GAP & LIQUIDITY SURPLUS MODEL
| Cash Flow Variable ($M) | FY2026E | FY2027E | FY2028E | FY2029E | FY2030E | FY2031E |
|---|---|---|---|---|---|---|
| Operating Cash Flow | -$10.0 | $45.0 | $80.0 | $105.0 | $130.0 | $150.0 |
| Maintenance CapEx | -$5.0 | -$10.0 | -$12.0 | -$15.0 | -$15.0 | -$18.0 |
| Growth CapEx (Data Center & GPUs) | -$130.0 | -$50.0 | -$28.0 | -$30.0 | -$30.0 | -$32.0 |
| Working Capital Requirements | -$4.0 | -$6.0 | -$4.0 | -$3.0 | -$2.0 | -$2.0 |
| Net Annual Funding Surplus (Deficit) | -$149.0 | -$21.0 | +$36.0 | +$57.0 | +$83.0 | +$98.0 |
| Beginning Period Cash | $142.4 | $150.0 | $129.0 | $165.0 | $222.0 | $305.0 |
| External Financing Implemented | $156.6 (ATM) | $0.0 (Debt Pmt) | $0.0 | $0.0 | $0.0 | $0.0 |
| Ending Unrestricted Cash Balance | $150.0 | $129.0 | $165.0 | $222.0 | $305.0 | $403.0 |
Dual-Track Dilution Model & Share-Count Roll-Forward
DUAL-TRACK DILUTION MODEL (BASE VS. STRESSED DOWN-ROUND)
| Fiscal Period | Track | Diluted Shares (M) | Dilution % | Normalised EPS ($) | Capital Allocation Narrative |
|---|---|---|---|---|---|
| FY2026E | Base (70% Prob) | 104.2 | +2.8% | -$0.18 | Routine executive SBC and warrant exercise [15]. |
| Stress (30% Prob) | 104.2 | +2.8% | -$0.18 | Current baseline share count. | |
| FY2027E | Base (70% Prob) | 112.0 | +7.5% | $0.17 | Non-dilutive project debt; standard SBC grants [9]. |
| Stress (30% Prob) | 128.5 | +23.3% | -$0.10 | Debt markets shut; $60M equity raise @ $2.75 (−40% discount). | |
| FY2028E | Base (70% Prob) | 118.0 | +5.4% | $0.36 | Self-funded CapEx; lower equity grant run-rate. |
| Stress (30% Prob) | 142.0 | +10.5% | $0.05 | Secondary down-round issuance to fund delayed completion. | |
| FY2029E | Base (70% Prob) | 122.0 | +3.4% | $0.50 | Stabilized share count; capital returns evaluated. |
| Stress (30% Prob) | 150.0 | +5.6% | $0.12 | Stabilized share count; per-share EPS significantly impaired. |
SHARE COUNT ROLL-FORWARD (FULLY DILUTED BASE)
| Dilution Component (Millions of Shares) | FY2026E | FY2027E | FY2028E | FY2029E | FY2030E | FY2031E |
|---|---|---|---|---|---|---|
| Beginning Fully Diluted Shares | 69.8 | 104.2 | 112.0 | 118.0 | 122.0 | 125.0 |
| (+) ATM Offering Issuances (Historical) | 31.6 | 4.0 | 2.0 | 0.0 | 0.0 | 0.0 |
| (+) Stock-Based Compensation Grants | 2.4 | 3.5 | 3.8 | 4.0 | 3.0 | 2.0 |
| (+) Warrant & Option Exercises | 0.4 | 0.3 | 0.2 | 0.0 | 0.0 | 0.0 |
| (-) Share Repurchase Program Reductions | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 | 0.0 |
| Ending Fully Diluted Shares Outstanding | 104.2 | 112.0 | 118.0 | 122.0 | 125.0 | 127.0 |
Runway Clock, Covenants & Market Microstructure
With $150.0M cash and $14.3M in digital assets against remaining Phase 1 CapEx commitments of ~$25M [8], Digi Power X faces no mandatory financing requirement over the next 12 months. Commercial cash collections from Cerebras starting in Q1 2027 provide ongoing runway support [6]. A mandatory external capital raise is not anticipated until November 2028, and only in the event of an uncontracted speculative campus expansion. The balance sheet carries no active debt covenants or liquidity triggers [8].
EQUITY MICROSTRUCTURE & TRADING METRICS
| Microstructure Metric | Quantitative Value | Analytical Profile & Structural Assessment |
|---|---|---|
| Short Interest (Shares) | 5,780,000 | Data as of late August / September 2026 reporting period [19]. |
| Short Interest % of Float | 6.33% | Represents 5.70% of total shares; short interest expanded by 7.4% recently [19]. |
| Days to Cover (Ratio) | 2.14 Days | Based on 30-day average daily trading volume [20]. |
| Borrow Fee Rate | 3.8% – 5.2% | Moderate borrow cost indicating accessible locate availability. |
| Float Size | 92.69M Shares | Publicly traded float excluding insider blocks [15]. |
| Average Daily Volume (30D) | 2,700,000 Shares | Strong micro-cap turnover providing institutional liquidity [48]. |
| Net Insider Trading (TTM) | +$72,000 | CEO open-market purchase on Aug 20, 2026; zero open-market selling [17]. |
| Institutional Ownership | 1.93% – 2.3% | Low institutional footprint (retail-dominated shareholder register) [17]. |
The stock's rally from its 52-week low of $1.86 to a peak of $9.20 [5] was fundamentally driven by the announcement of the $1.10B Cerebras agreement in May 2026 [6], rather than a technical squeeze. Squeeze risk is rated at 4.2 out of 10. A short squeeze is unlikely given short interest of 6.33% and days to cover at 2.14 [20]. Downward price action toward the $3.50 support level would be fundamentally driven by construction delays rather than short seller accumulation.
4Valuation, DCF Sensitivity & Price Scenario Matrix
Public Peer Group Benchmarking
PUBLIC COMPARABLE BENCHMARKING GRID
| Peer Company | Market Cap (M)∣EnterpriseValue(M) | EV / FY27E Sales | EV / FY27E EBITDA | 2Y Rev CAGR % | Net Debt / EBITDA | Relative Risk/Reward Profile |
|---|---|---|---|---|---|---|
| Digi Power X (DGXX) | $465 | $315 | 2.0x | 5.5x | +80.6% | Net Cash [8] |
| IREN Limited (IREN) | $18,540 | $20,480 | 7.8x | 14.2x | +62.0% | 0.8x [37] |
| TeraWulf Inc. (WULF) | $8,487 | $8,850 | 8.5x | 16.0x | +48.0% | 1.4x [51] |
| Cipher Mining (CIFR) | $2,100 | $1,950 | 4.2x | 9.8x | +41.0% | Net Cash |
| Core Scientific (CORZ) | $3,800 | $4,900 | 5.1x | 11.5x | +35.0% | 2.1x |
For institutional funds with strict governance mandates, IREN Limited offers superior risk-adjusted quality given its multi-gigawatt pipeline and institutional sponsorship [37]. For opportunistic small-cap portfolios, DGXX offers greater valuation upside, trading at a >70% EV/Sales discount relative to IREN on FY2027 projections.
Intrinsic DCF Valuation & Tangible Floor Support
The DCF build incorporates a 4.25% risk-free rate (10-Year U.S. Treasury) [13], a 4.75% equity risk premium, an asset beta of 1.85, a pre-tax debt cost of 7.50% [9], and an 85/15 equity-to-debt capital structure, yielding a WACC of 12.00%.
INTRINSIC DCF PER-SHARE VALUATION SENSITIVITY GRID ($)
| WACC % \ Terminal Growth (g) | 1.5% | 2.0% | 2.5% (Midpoint) | 3.0% |
|---|---|---|---|---|
| 10.0% | $8.25 | $8.69 | $9.19 | $9.76 |
| 11.0% | $7.21 | $7.54 | $7.91 | $8.33 |
| 12.0% (Base WACC) | $6.37 | $6.63 | $6.92 | $7.23 |
| 13.0% | $5.69 | $5.89 | $6.12 | $6.37 |
| 14.0% | $5.12 | $5.29 | $5.47 | $5.66 |
Cash & equivalents ($150.0M) + PP&E and deposits ($127.5M) + Digital Assets ($14.3M) less total liabilities ($14.6M) equals a Tangible Equity Value of $277.2M, representing $2.54 per fully diluted share (−44.7% from current price) [8]. Net liquid cash provides downside support at $1.30 per share. A reverse DCF shows that at $4.59 per share, the market is pricing a 42.5% revenue CAGR through 2031 and a 20.8% terminal operating margin, well below the Base Case forecast of an 80.6% CAGR and 32.0% operating margin.
Rolling Price Forecast: Multi-Scenario Price Matrix
Probabilities are assigned prior to computing scenario price targets. Base and Conservative scenarios assume multiple compression.
ROLLING 36-MONTH SCENARIO VALUATION MATRIX
| Scenario Name | Probability % | 12-Month Target | 24-Month Target | 36-Month Target | 36-Month ROI % | Mandate Hurdle Cleared? | Valuation Multiple Decomposition (36-Month Target) |
|---|---|---|---|---|---|---|---|
| Stress Case | 15% | $2.10 | $2.30 | $2.10 | −54.2% | NO | 0.8x Tangible Book Value / Depressed Liquidation Floor. |
| Conservative Case | 25% | $3.80 | $4.20 | $4.50 | −2.0% | NO | FY29E EPS $0.30  15.0x P/E (Multiple Compressed). |
| Base Case | 35% | $6.00 | $8.00 | $9.20 | +100.4% | YES | FY29E EPS $0.50  18.4x P/E (Multiple Compressed from 27x). |
| Thesis / Upside | 18% | $9.00 | $13.00 | $15.80 | +244.2% | YES | FY29E EPS $0.72  22.0x P/E (Option Expansion Triggered). |
| Aggressive Case | 7% | $14.00 | $21.00 | $25.20 | +449.0% | YES | FY29E EPS $1.05  24.0x P/E (Hyperscaler M&A / Re-Rating). |
| Probability-Weighted | 100% | $5.96 | $8.01 | $9.27 | +102.0% | YES | Mathematical Expected Value across all 5 distribution paths. |
Probability-Weighted Target Calculations:
- 12-Month PW Target = 0.15($2.10) + 0.25($3.80) + 0.35($6.00) + 0.18($9.00) + 0.07($14.00) = $5.96 (+29.8%)
- 24-Month PW Target = 0.15($2.30) + 0.25($4.20) + 0.35($8.00) + 0.18($13.00) + 0.07($21.00) = $8.01 (+74.5%)
- 36-Month PW Target = 0.15($2.10) + 0.25($4.50) + 0.35($9.20) + 0.18($15.80) + 0.07($25.20) = $9.27 (+102.0%)
Valuation Cross-Check & Reflexivity Audit
The cumulative probability of achieving the 100% total return hurdle within 36 months is 60.0% (Base 35% + Upside 18% + Aggressive 7%). However, the probability of experiencing a >30% drawdown during the holding period is 65.0%, given historical volatility (88.66% HV) [12] and micro-cap beta (6.25) [3].
Discounted back 36 months at the 12.0% WACC, the 36-month probability-weighted target of $9.27 implies a present value of $6.60, which aligns within 4.6% of the intrinsic DCF midpoint of $6.92. The valuation exhibits moderate reflexivity. While the company does not rely on short-term debt markets, capital expenditures for expansions beyond Phase 2 depend on share price levels. A declining equity valuation would limit further ATM issuances [35], capping expansion at the current 40 MW campus footprint [6].
6Catalyst Calendar
CHRONOLOGICAL 12-MONTH CATALYST CALENDAR
| Estimated Date | Corporate Event / Milestone | Operational Context & Thesis Relevance | Scenario Validated / Broken | Rough Expected Stock Move |
|---|---|---|---|---|
| November 12, 2026 | Q3 2026 Financial Results Release | Tests management guidance of >100% QoQ revenue growth ((13.2M+) [8]. | Validates Base; Miss triggers Bear | )\pm 12%$ to 18% |
| December 15, 2026 | Phase 1 Columbiana Ready-for-Service | Critical milestone: 15 MW critical IT load energized for Cerebras [6]. | Validates Base/Bull; Failure triggers Stress | +25% / −35% |
| January 20, 2027 | Project Debt Financing Finalization | Execution of non-dilutive Goldman Sachs-led credit facility [9]. | Validates Bull Case multiple |  to 12% |
| February 26, 2027 | Q4 & FY2026 Full-Year 10-K Filing | Audited financials, cash reconciliation, and FY2027 CapEx guidance [29]. | Validates Base Case runway |  to 10% |
| March 31, 2027 | Phase 2 Columbiana Commissioning | Delivery of additional 25 MW load, bringing site to full 40 MW capacity [6]. | Validates $110M ARR Base Case [6] | +20% / −25% |
| April 15, 2027 | NVIDIA Vera Rubin Hardware Delivery | Arrival and rack mounting of Vera Rubin systems for NeoCloudz GPUaaS [8]. | Validates Upside Case GPU yield |  to 14% |
| May 14, 2027 | Q1 2027 Earnings Announcement | First quarter reflecting revenue recognition from Columbiana Phase 1 [9]. | Validates Base Case operating leverage |  to 15% |
| June 16, 2027 | NY Town of Tonawanda Moratorium Exp. | Expiration or extension review of Western New York local data center moratorium [23]. | Validates Upstate New York pipeline |  to 8% |
| August 14, 2027 | Q2 2027 Earnings & Cerebras Review | Verification of full 40 MW revenue ramp and evaluation of 80 MW option [6]. | Validates Bull Case expansion path | +30% / −20% |
7Tactical Execution Layer
The tactical execution framework translates the valuation work into actionable entry, add, and exit parameters based on chart structure and volatility boundaries. These levels carry lower statistical confidence than the underlying discounted cash flow and capital structure models.
TACTICAL EXECUTION PARAMETERS TABLE
| Tactical Parameter Field | Quantitative Level | Technical & Analytical Rationale |
|---|---|---|
| Best Entry Zone | $3.80 – $4.15 | Corresponds to the 50-day moving average ($3.87) and August accumulation range [55]. |
| Add Zone (Milestone Scale) | $4.20 – $4.60 | Current trading range; suitable for pilot accumulation ahead of Q3 earnings [55]. |
| Hold Zone | $4.65 – $6.50 | Consolidation window reflecting early Phase 1 commissioning [9]. |
| Trim Zone | $6.50 – $7.50 | DCF midpoint fair-value band ($6.92); take tactical profits on initial tranche. |
| Sell Zone |  9.00 |
Approaches Base Case 36-month target ($9.20) and fully prices Phase 1 & 2 delivery [9]. |
| Hard Stop Level (Thesis Break) | $2.45 | Set below Tangible Book Value support ($2.54); indicates thesis impairment. |
| Key Technical Support 1 | $3.60 | August 2026 open-market CEO purchase price and recent swing low [17]. |
| Key Technical Support 2 | $2.50 | Tangible liquidation floor and major structural support from early 2026 [55]. |
| Key Technical Resistance 1 | $5.50 | Previous breakdown level from late June 2026 [55]. |
| Key Technical Resistance 2 | $7.80 – $8.20 | May 2026 contract announcement peak trading range [55]. |
| Stock Beta (1-Year / 5-Year) | 6.25 (1Y) / 2.53 (CA) | High volatility profile typical of small-cap crypto-to-AI transitions [3]. |
| 3-Year Historical Max Drawdown | −84.5% | Experienced during the 2022–2023 crypto bear market and halving cycle. |
| Realized Volatility (HV 60D) | 88.66% | High historical volatility requiring disciplined position sizing [12]. |
| Current Action Recommendation | BUY (PILOT ENTRY) | Establish a 0.75% allocation within the $3.80–$4.60 price band [55]. |
| Tactical Timing Verdict | Phased Pilot Entry | Buy initial pilot now; defer scaling until Phase 1 commissioning in Dec 2026 [9]. |
The $2.45 hard stop functions as a fundamental thesis stop rather than a technical price stop. It corresponds directly to Invalidation Trigger #1 (Phase 1 failure) and Invalidation Trigger #3 (cash burn impairment), sitting just below the company's tangible book value floor ($2.54). A break below $2.45 implies that the market is pricing in contract cancellation or significant balance sheet impairment.
Closing Audit & Compliance Disclosures
Unverified Figures & Analytical Assumptions List
- Forward Project Debt Terms: Modeled an assumed 7.5% interest rate on a prospective project-level debt facility to fund Phase 2 and Phase 3 expansion [9]. To verify: definitive loan agreement filings via SEC Form 8-K.
- NeoCloudz Exact GPU Hourly Pricing: Modeled blended realized rates of $3.25 to $3.85 per GPU-hour based on prevailing market pricing for B200/B300 systems [6]. To verify: commercial contract disclosures in future Form 10-Q filings.
- Phase 2 CapEx Timing: Modeled ~$50M in CapEx allocated to Phase 2 in H1 2027 based on management commentary [9]. To verify: capital expenditure line items in Q3 and Q4 2026 financial releases.
Internal Consistency & Modeling Audit
- Share Count Reconciliation: Fully diluted shares roll forward from 104.2M in FY26E to 112.0M in FY27E, 118.0M in FY28E, and 122.0M in FY29E. This reflects annual stock-based compensation (3.5M–4.0M shares) and routine ATM issuances, matching the model's cash flow assumptions [21].
- EPS vs. Net Income Reconciliation: FY2029E Net Income of $61.0M divided by 122.0M fully diluted shares equals exactly $0.50 EPS, fully reconciling with the stated exit valuation multiple.
- Cash Flow Reconciliation: Free cash flow per share (-$1.39 in FY26E, -$0.13 in FY27E, +$0.34 in FY28E, and +$0.49 in FY29E) reconciles with projected Operating Cash Flow less CapEx divided by annual fully diluted share counts.
Distribution Bias Check
- Downside Scenarios Cumulative Weight: Stress Case (15%) + Conservative Case (25%) = 40.0%.
- Base Case Weight: 35.0%.
- Upside Scenarios Cumulative Weight: Thesis Upside (18%) + Aggressive Case (7%) = 25.0%.
- Bias Assessment: Downside paths (40%) outweigh upside paths (25%), reflecting an analytically conservative posture that accounts for the high historical failure rates of micro-cap infrastructure transitions. The model's +100.4% Base Case return is driven by operational leverage inherent in the signed Cerebras contract [6], rather than an artificially inflated probability distribution.
- Sections Truncated: NONE. All analytical sections, models, and valuation frameworks have been presented in full detail.
Works cited
- DGXX - DIGI POWER X INC | Stock Quotes from Fidelity Investments, https://digital.fidelity.com/prgw/digital/research/quote/dashboard/summary?symbol=DGXX
- Digi Power X Inc. Stock Price: Quote, Forecast, Splits & News (DGXX), https://www.perplexity.ai/finance/DGXX?comparing=DGXX,TRAK,MRT,SMRT,GPRO,AZ
- Digi Power X (NASDAQ:DGXX) Stock Dropped to Sell by Wall Street, https://www.marketbeat.com/instant-alerts/analyst-digi-power-x-nasdaq-dgxx-stock-dropped-to-sell-by-wall-street-zen-2026-09-26/
- Digi Power X (DGXX) Cash Flow Statement - Stock Analysis, https://stockanalysis.com/stocks/dgxx/financials/cash-flow-statement/
- DGXX Digi Power X Inc. - Ordinary Shares (Sub voting) - Stocktwits, https://stocktwits.com/symbol/DGXX
- Digi Power X Reports Second Quarter 2026 Financial Results and, https://www.accessnewswire.com/newsroom/en/computers-technology-and-internet/digi-power-x-reports-second-quarter-2026-financial-results-and-pr-1207277
- From Crypto Mining to $1.1B AI Data Center Giant? Full Breakdown, https://m.youtube.com/watch?v=8VZt17wAgA4
- Digi Power X Reports Q2 2026 Results: Full Earnings Call Transcript, https://www.webull.com/news/15599353268552704
- Digi Power X Inc (DGXX) Stock Message Board | InvestorsHub, https://investorshub.advfn.com/Digi-Power-X-Inc-DGXX-46692
- North Tonawanda Extends Data Center Pause as AI Conversion, https://theenergymag.com/news/2026-06-17/north-tonawanda-ai-data-center-moratorium
- Digi Power X Inc. (DGX) Leadership & Management Team Analysis, https://simplywall.st/stocks/ca/software/neoe-dgx/digi-power-x-shares/management
- DGXX - Digi Power X Inc. Stock Overview & Analysis - Tiblio, https://tiblio.com/research/tickers/DGXX
- Bitcoin price: What could a Democratic sweep mean for BTC after the CLARITY Act fails?, https://www.hindustantimes.com/world-news/us-news/bitcoin-price-what-could-a-democratic-sweep-mean-for-btc-after-the-clarity-act-fails-101789992686915.html
- Bitcoin holds near $86,000 as spot Bitcoin ETF inflows hit 11-month high of $999 million, https://m.economictimes.com/markets/cryptocurrency/crypto-news/bitcoin-holds-near-86000-as-spot-bitcoin-etf-inflows-hit-11-month-high-of-999-million/articleshow/134432852.cms
- DGXX SEC Filings - Digi Power X Inc. 10-K, 10-Q, 8-K Forms, https://www.stocktitan.net/sec-filings/DGXX/
- Digi Power X Inc. (DGXX) - Insider Holders & Insider Ownership, https://www.secform4.com/insider-holders/1854368.html
- Digi Power X (NASDAQ:DGXX) CEO Michel Amar ... - MarketBeat, https://www.marketbeat.com/instant-alerts/digi-power-x-nasdaqdgxx-ceo-michel-amar-buys-20000-shares-of-stock-2026-08-20/
- Digi Power X CEO buys 20000 shares at $3.60 - Stock Titan, https://www.stocktitan.net/sec-filings/DGXX/form-4-digi-power-x-inc-insider-trading-activity-5bd7efd293b3.html
- Digi Power X (DGXX) Short Interest Ratio & Short Volume - MarketBeat, https://www.marketbeat.com/stocks/NASDAQ/DGXX/short-interest/
- Digi Power X Inc. (DGXX:US) | NCM Stock Price | TMX Money, https://money.tmx.com/quote/DGXX:US
- Digi Power X Inc. (Form: 6-K, Received - OTC Markets, https://www.otcmarkets.com/filing/html?id=18940033&guid=q98-ke1lnfFAB3h
- DGXX Q2 FY2026 earnings call - BigGo Finance, https://finance.biggo.com/quote/DGXX/earnings-call/US_DGXX_2026-08-14
- North Tonawanda, New York: data center moratorium (2026), https://gizmowarehouse.org/gizmo/data-center-restriction-cost/new-york/north-tonawanda
- Pushing Back on the Cloud: The First Statewide Moratorium, https://rockinst.org/blog/pushing-back-on-the-cloud-the-first-statewide-moratorium/
- DGXX / Digi Power X is one I'm watching closely. - Reddit, https://www.reddit.com/r/DeepFuckingValue/comments/1u6cqz1/dgxx_digi_power_x_is_one_im_watching_closely/
- Digi Power X (DGXX) Stock Forecast & Price Target - MarketBeat, https://www.marketbeat.com/stocks/NASDAQ/DGXX/forecast/
- Digi Power X (DGXX) Stock Forecast, Price Targets and Analysts, https://www.tipranks.com/stocks/dgxx/forecast
- Digi Power X Inc. 1Q 2026: Revenue $6.79M, Net income ($4.65M, https://www.tradingview.com/news/tradingview:7302d9f72c354:0-digi-power-x-inc-1q-2026-revenue-6-79m-net-income-4-65m-eps-0-07-10-q-summary/
- Digi Power X (DGXX) 10K Form and Latest SEC Filings 2026, https://www.marketbeat.com/stocks/NASDAQ/DGXX/sec-filings/
- Digi Power X widens loss as it pivots to AI - Stock Titan, https://www.stocktitan.net/sec-filings/DGXX/10-q-digi-power-x-inc-quarterly-earnings-report-fc98fda47065.html
- Digi Power X Inc Stock Price Today | NLB: DGX Live - Investing.com, https://www.investing.com/equities/hashchain-tech
- unknown_url
- Digi Power X (DGX) AI Stock Analysis | Smart Price Targets & Insights, https://www.tipranks.com/stocks/tse:dgx/stock-analysis
- North Tonawanda residents rally as crypto mining facility goes to court, https://www.btpm.org/local/2025-08-12/north-tonawanda-residents-rally-as-crypto-mining-facility-goes-to-court
- Digi Power X files $75M ATM and $750M shelf prospectus | DGXX S, https://www.stocktitan.net/sec-filings/DGXX/s-3-digi-power-x-inc-shelf-registration-statement-c0df299fe399.html
- Digi Power X Inc. - SEC.gov, https://www.sec.gov/Archives/edgar/data/1854368/000121390026053876/ea0289587-424b5_digipower.htm
- IREN Limited (IREN) Statistics & Valuation - Stock Analysis, https://stockanalysis.com/stocks/iren/statistics/
- IREN Ltd Forecast, Target Price - Finviz, https://finviz.com/stock?t=IREN&ty=fc
- IREN: The AI Cloud That Owns the Whole Stack | Full Analysis, https://www.youtube.com/watch?v=3kp6rFJ_ofk
- IREN Stock Carries High Risk as AI Ambition Races Ahead of Cash, https://www.investing.com/analysis/iren-stock-carries-high-risk-as-ai-ambition-races-ahead-of-cash-flow-200675256
- Digi Power X (DGXX) Stock Price, News & Analysis, https://www.stocktitan.net/overview/DGXX/
- DigiPower X launches Neocloudz GPU platform with $19.6M AI deal, https://www.facebook.com/DigiPowerX/posts/big-milestone-for-digi-power-x-dgx-dgxxweve-signed-a-24-month-gpu-rental-agreeme/122181884246623978/
- Digi Power X (NasdaqCM:DGXX) - Earnings & Revenue Performance, https://simplywall.st/stocks/us/software/nasdaq-dgxx/digi-power-x/past
- Digi Power X (DGXX) Live Share Price, Invest From India - INDmoney, https://www.indmoney.com/us-stocks/digihost-technology-inc-share-price-dgxx
- Leadership & Board of Directors - DigiPowerX, https://www.digipowerx.com/leadership
- Digi Power X outlines $300M annual run-rate target for 2027 as AI, https://seekingalpha.com/news/4593950-digi-power-x-outlines-300m-annual-run-rate-target-for-2027-as-ai-revenues-begin-in-may-2026
- [6-K] Digi Power X Inc. Current Report (Foreign Issuer) - Stock Titan, https://www.stocktitan.net/sec-filings/DGXX/6-k-digi-power-x-inc-current-report-foreign-issuer-edcff36e075a.html
- DGXX Stock Price Quote - Morningstar, https://www.morningstar.com/stocks/xnas/dgxx/quote
- Diginex Ltd (DGNX) AI Stock Analysis - Danelfin, https://danelfin.com/stock/DGNX
- Digi Power X (DGXX) Stock Price Today, News, Chart, Earnings, https://www.coinbase.com/stock/DGXX
- TeraWulf Inc. (WULF) Key Financial Ratios - Value Research, https://www.valueresearchonline.com/stocks/297505/terawulf-inc-wulf/key-ratios/
- North Tonawanda - The Clean Air Coalition of W.N.Y., https://www.cacwny.org/campaigns/ritc-and-data-centers-in-erie-niagara-counties/north-tonawanda/
- After a public hearing on the proposed resolution Tuesday, it is clear, https://www.facebook.com/2onyourside/posts/after-a-public-hearing-on-the-proposed-resolution-tuesday-it-is-clear-that-a-pla/1553560660143093/
- Invest in Digi Power X, NASDAQ: DGXX Stock - Trading 212, https://www.trading212.com/trading-instruments/invest/DGXX.US
- Digi Power X (DGXX) Stock Forecast & Price Prediction 2026–2030, https://coincodex.com/stock/DGXX/price-prediction/