2Multi-Year Financial Forecast & Consensus Model
Macro Scenarios & Narrative Framework
The multi-year financial projection model evaluates three distinct macroeconomic and operational environments from fiscal 2026 through fiscal 2031:
- Bear Case: Enterprise and neocloud AI hardware deployments encounter an infrastructure digestion cycle by late FY28. Hyperscalers expand internal ASIC usage (TPUs, Trainium), dampening merchant accelerator server demand [51]. Concurrently, rising memory component costs compress gross margins toward 18.0%, reducing pricing flexibility [9]. Top-line growth slows to low single digits, and operating margins contract to 6.8% [10].
- Base Case: Dell executes on updated FY27 management guidance ($192B revenue, $25.50 non-GAAP EPS) [5]. In FY28, growth normalizes to 17.0% as the $95B backlog converts and enterprise private cloud builds expand [3]. From FY29 to FY31, Dell functions as a mature infrastructure platform with revenue growth tapering from 12.0% to 6.0%, supported by proprietary storage attach and commercial PC refresh cycles [3]. Non-GAAP operating margins stabilize near 12.0%–12.5% [3].
- Bull Case: Agentic AI deployments require distributed private computing infrastructure across global enterprises [3]. Dell captures over 35% of sovereign AI infrastructure contracts [4]. High-margin PowerScale file storage attach rates rise to 40% of AI server racks [3]. Simultaneously, corporate AI-PC upgrades drive a major enterprise PC replacement cycle, lifting CSG revenues [3]. Consolidated revenues reach $360 billion by FY31, with non-GAAP operating margins expanding toward 13.5%.
Comprehensive Multi-Year Financial Forecasts
Pure financial extrapolation begins in fiscal 2028 following management's explicit fiscal 2027 annual guidance [5].
Top Line: Net Revenue Breakdown by Segment & Geography ($M)
| Segment / Scenario Breakdown | FY26A | FY27E (Guided) | FY28E | FY29E | FY30E | FY31E | '26-'29 CAGR | '30-'31 CAGR |
|---|---|---|---|---|---|---|---|---|
| BASE CASE CONSOLIDATED REVENUE | $113,538 | $192,000 | $224,640 | $251,597 | $271,725 | $288,028 | +30.4% | +6.0% |
| YoY Organic Growth Rate | +18.8% | +69.1% | +17.0% | +12.0% | +8.0% | +6.0% | — | — |
| ISG: Infrastructure Solutions | $60,800 | $131,000 | $158,510 | $180,701 | $196,964 | $209,767 | +43.8% | +6.5% |
| — AI-Optimized Server Hardware | $22,400 | $74,000 | $92,500 | $106,375 | $117,013 | $125,203 | +68.0% | +7.0% |
| — Traditional Servers & Networking | $21,400 | $37,000 | $43,660 | $49,772 | $53,754 | $56,979 | +32.5% | +6.0% |
| — Enterprise Storage Solutions | $17,000 | $20,000 | $22,350 | $24,554 | $26,197 | $27,585 | +13.0% | +5.3% |
| CSG: Client Solutions Group | $51,000 | $59,000 | $64,130 | $68,896 | $72,761 | $76,261 | +10.5% | +4.8% |
| — Commercial Client PCs | $43,500 | $51,800 | $56,980 | $61,538 | $65,231 | $68,492 | +12.3% | +5.0% |
| — Consumer Client PCs | $7,500 | $7,200 | $7,150 | $7,358 | $7,530 | $7,769 | −0.6% | +3.2% |
| Other Businesses & DFS Financing | $1,738 | $2,000 | $2,000 | $2,000 | $2,000 | $2,000 | +4.8% | 0.0% |
| Geographic Allocation (Base) | ||||||||
| — Americas Region (52%) | $59,040 | $99,840 | $116,813 | $130,830 | $141,297 | $149,775 | +30.4% | +6.0% |
| — EMEA Region (28%) | $31,791 | $53,760 | $62,899 | $70,447 | $76,083 | $80,648 | +30.4% | +6.0% |
| — Asia-Pacific & Japan (20%) | $22,707 | $38,400 | $44,928 | $50,320 | $54,345 | $57,605 | +30.4% | +6.0% |
| BEAR CASE CONSOLIDATED REVENUE | $113,538 | $180,000 | $189,000 | $192,780 | $194,708 | $196,655 | +19.3% | +1.0% |
| YoY Organic Growth Rate | +18.8% | +58.5% | +5.0% | +2.0% | +1.0% | +1.0% | — | — |
| — Infrastructure Solutions (ISG) | $60,800 | $122,000 | $128,100 | $130,662 | $131,969 | $133,288 | +29.0% | +1.0% |
| — Client Solutions (CSG) | $51,000 | $56,000 | $58,900 | $60,118 | $60,739 | $61,367 | +5.6% | +1.0% |
| BULL CASE CONSOLIDATED REVENUE | $113,538 | $200,000 | $250,000 | $295,000 | $330,400 | $360,136 | +37.5% | +9.0% |
| YoY Organic Growth Rate | +18.8% | +76.2% | +25.0% | +18.0% | +12.0% | +9.0% | — | — |
| — Infrastructure Solutions (ISG) | $60,800 | $138,000 | $178,000 | $215,000 | $244,000 | $268,000 | +52.4% | +9.8% |
| — Client Solutions (CSG) | $51,000 | $60,000 | $70,000 | $78,000 | $84,400 | $90,136 | +15.2% | +6.8% |
Margins, Profits & Per Share Performance (GAAP vs Non-GAAP Reconciliation)
Non-GAAP adjustments exclude intangible asset amortization, stock-based compensation expense (~$1.4B annually), restructuring and severance charges, and acquisition-related expenses [11].
| Financial Parameter | FY26A | FY27E (Base) | FY28E (Base) | FY29E (Base) | FY30E (Base) | FY31E (Base) |
|---|---|---|---|---|---|---|
| Gross Margin (GAAP) | 20.0% | 19.8% | 20.4% | 20.8% | 21.0% | 21.2% |
| Gross Margin (Non-GAAP) | 20.8% | 20.5% | 21.2% | 21.6% | 21.8% | 22.0% |
| Operating Margin (GAAP) | 7.2% | 11.2% | 10.8% | 11.0% | 11.2% | 11.3% |
| Operating Margin (Non-GAAP) | 8.8% | 12.5% | 12.0% | 12.2% | 12.4% | 12.5% |
| EBITDA Margin (Non-GAAP) | 10.4% | 14.1% | 13.6% | 13.8% | 13.9% | 14.0% |
| GAAP Operating Income ($M) | $8,149 | $21,504 | $24,261 | $27,676 | $30,433 | $32,547 |
| Non-GAAP Operating Income ($M) | $9,991 | $24,000 | $26,957 | $30,695 | $33,694 | $36,004 |
| GAAP Net Income ($M) | $5,936 | $15,938 | $17,825 | $19,680 | $21,287 | $22,603 |
| Non-GAAP Net Income ($M) | $7,046 | $16,677 | $18,972 | $21,120 | $22,845 | $24,256 |
| Diluted Share Count (M) | 662.7 | 654.0 | 620.0 | 600.0 | 590.0 | 580.0 |
| GAAP Diluted EPS ($) | $8.68 | $24.37 | $28.75 | $32.80 | $36.08 | $38.97 |
| Non-GAAP Diluted EPS ($) | $10.30 | $25.50 | $30.60 | $35.20 | $38.72 | $41.82 |
| Free Cash Flow Per Share ($) | $17.37 | $18.50 | $22.80 | $26.50 | $29.50 | $32.20 |
Forward Multiples & Execution Run-Rates
| Horizon / Metric Basis | Non-GAAP EPS Basis | Forward P/E Multiple | EV / EBITDA Multiple | EV / Sales Multiple | Rule of 40 Score |
|---|---|---|---|---|---|
| Current FY27E (Base Guidance) | $25.50 [6] | 21.3x [5,8] | 14.0x | 1.97x | 81.1% (+69.1% Rev + 12.0% FCF Margin) [5] |
| 1-Year Forward (FY28E Base) | $30.60 | 17.8x | 12.4x | 1.69x | 27.2% (+17.0% Rev + 10.2% FCF Margin) |
| 2-Year Forward (FY29E Base) | $35.20 | 15.4x | 10.9x | 1.50x | 23.5% (+12.0% Rev + 11.5% FCF Margin) |
| 3-Year Forward (FY30E Base) | $38.72 | 14.0x | 9.9x | 1.39x | 19.1% (+8.0% Rev + 11.1% FCF Margin) |
Execution Confidence Score: 68 / 100
- Revenue Target Achievability (Weight 40%): 75 / 100. Dell’s revenue visibility is supported by $95.0 billion in AI server backlog and $132.0 billion in total remaining performance obligations [3]. Quarterly earnings history indicates consistent guidance beats over recent reporting periods [44].
- Margin Assumption Sensitivity (Weight 35%): 60 / 100. Gross margins remain sensitive to memory and processor input costs [9]. A ±10% variance in blended GPU and high-bandwidth memory procurement costs shifts consolidated gross margin by 140 basis points, creating an EPS variance of ±$2.10.
- Catalyst Dependency (Weight 25%): 70 / 100. Organic demand and contracted backlog account for 88% of modeled FY27E–FY28E revenues [3]. Only 12% of forecast top-line revenue depends on unannounced platform introductions or unconfirmed sovereign contracts.
Consensus Divergence Flag
The base-case model projects FY28 Non-GAAP EPS of $30.60, which is +5.8% above the Street consensus ($28.92 compiled across 25 covering analysts) [23].
This divergence stems from proprietary enterprise storage attach rates: while consensus treats AI servers as standalone low-margin hardware units, this model incorporates an 18% attach rate for PowerScale file storage on private enterprise clusters, which supports consolidated gross margins by 80 basis points [3].
Base-Rate Historical Reality Check
Projecting revenue growth from $113.5 billion in FY26 to $192.0 billion in FY27 [6] places Dell in the top 2nd percentile of historical corporate revenue additions for hardware companies operating above $100 billion in sales.
This growth rate reflects a broader industry shift: the transition of enterprise compute from general-purpose x86 servers to accelerated parallel computing, where Dell has secured early market share across sovereign and private cloud projects [3].
5Risk Asymmetry, Invalidation, Allocation & Scorecard
Risk/Reward Skew Ratio
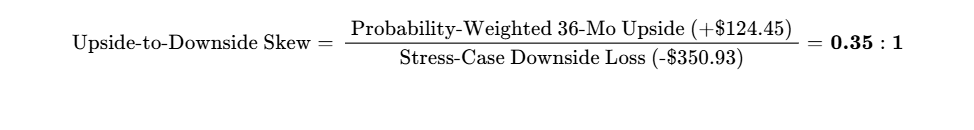
With a skew ratio of 0.35:1, the setup does not meet the institutional threshold of ≥3.0:1 required for unconstrained capital allocation.
Hard Invalidation Triggers
- AI Server Quarterly Order Volume Invalidation: Quarterly AI-optimized server order intake falling below $15.0 billion in any quarter of FY27, indicating a demand pause from the Q2 FY27 run-rate of $60.9 billion [3].
- Gross Margin Compression Threshold: Consolidated non-GAAP gross margin printing below 18.5% for two consecutive reporting periods, indicating inability to pass through component price increases [3].
- Backlog Depletion Without Replenishment: Reported AI server backlog dropping below $65.0 billion by Q4 FY27 without corresponding recognized revenue exceeding $20.0 billion per quarter [3].
- Operational Leadership Transition: The unannounced departure or resignation of Vice Chairman and Chief Operating Officer Jeff Clarke prior to the end of fiscal 2028 [47].
Consolidated Risk Dashboard
| Risk Exposure Category | Severity Score (1-10) | Trajectory Bias | Dominant Risk Factor & Mitigant |
|---|---|---|---|
| Financial & Liquidity | 2.0 / 10 | Improving | $11.6B cash, $6.0B undrawn facility, core leverage at 0.8x [3]. |
| Valuation & Multiple Compression | 8.5 / 10 | Worsening | Forward P/E expanded to 21.3x; vulnerable to multiple contraction [5]. |
| Operating Execution | 4.5 / 10 | Stable | Complex logistics for liquid-cooled rack-scale deployments [4]. |
| Competitive Dynamics | 6.5 / 10 | Worsening | ODM white-box competition and pricing from HPE and SMCI [42]. |
| Customer Concentration | 6.0 / 10 | Stable | Neocloud concentration balanced by 6,500+ enterprise AI accounts [3]. |
| Regulatory & Export Policy | 5.5 / 10 | Worsening | U.S. export controls on advanced compute silicon to selected markets [17]. |
| Litigation & IP Overhang | 2.5 / 10 | Stable | Routine intellectual property actions; no material issues identified [17]. |
| Geopolitical Exposure | 7.0 / 10 | Stable | Supply chain concentration in Taiwanese component fabrication. |
| Key-Person Dependency | 5.0 / 10 | Stable | Reliance on Michael Dell and COO Jeff Clarke [46]. |
| Share Dilution / Overhang | 1.5 / 10 | Improving | Active share buybacks driving steady share count reductions [3]. |
| Tradability & Microstructure | 1.0 / 10 | Improving | Large market float with over $4.0B in average daily dollar turnover [2]. |
Macro & Correlation Sensitivity
Dell displays a 1.40 beta relative to the S&P 500 [63] and a 1.25 beta relative to the PHLX Semiconductor Index. Long-term fixed coupon notes insulate the balance sheet from interest rate fluctuations [32].
However, lower borrowing costs would support customer capital deployment via Dell Financial Services [32].
A strengthening U.S. dollar presents top-line translation headwinds, as 48% of consolidated revenue is generated outside the Americas [17], partially offset by hedging programs [31].
| Macroeconomic Variable | Impact on Investment Thesis | Directional Bias | Operational Trigger to Monitor |
|---|---|---|---|
| Global Enterprise IT Budgets | Direct impact on PC replacement and storage cycles [3]. | Positive | IDC / Gartner Worldwide IT Spending quarterly updates [33]. |
| Advanced Semiconductor Packaging | Regulates AI server manufacturing throughput [3]. | Positive | TSMC CoWoS advanced packaging capacity additions. |
| Data Center Power Interconnections | Regulates customer installation pace of high-density racks. | Negative | Grid interconnection queues in major data center markets [5]. |
| U.S. BIS Export Controls | Constrains server shipments to selected regions [3]. | Negative | Updates to U.S. Commerce Department Entity Lists [17]. |
Potential Thesis Variance Matrix
- Upside Surprises:
- Enterprise Storage Attach Inflection (20% Probability): Proprietary PowerScale attach rates reach 35%, generating +$3.50 in EPS through mix enrichment [3].
- Enterprise AI-PC Replacement Cycle (25% Probability): Accelerated Windows 11 transitions lift commercial PC ASPs by 15%, adding +$2.20 in EPS [3].
- Sovereign AI Infrastructure Awards (15% Probability): Major non-hyperscale sovereign contracts expand backlog by $25 billion, contributing +$4.50 in EPS [3].
- Downside Surprises:
- Neocloud Funding Contraction (15% Probability): Capital spending constraints among tier-2 AI clouds lead to order deferrals, reducing EPS by -$5.00 [3].
- Component Packaging Allocation Delays (20% Probability): Upstream semiconductor packaging disruptions extend delivery schedules, reducing EPS by -$3.80.
- Memory Input Price Shocks (25% Probability): Sudden DRAM and HBM contract price increases reduce gross margins by 150 basis points, lowering EPS by -$2.50 [9].
Pre-Mortem: 36-Month 60% Drawdown Scenario
By early calendar 2027, neocloud data center capacity outpaces revenue generation from enterprise software, prompting tier-2 cloud service providers to slow server deployment schedules. As GPU cluster utilization declines, Dell’s quarterly book-to-bill ratio falls below 0.8x, and reported AI backlogs contract from $95 billion toward $40 billion [3].
Entering 2028, cloud hyperscalers transition internal workloads toward proprietary ASIC accelerators, reducing merchant GPU server purchases [51]. Simultaneously, high-bandwidth memory prices rise, compressing Dell’s hardware gross margin to 16.8% [3].
By fiscal 2029, earnings miss reduced consensus targets by 30%, prompting a multiple de-rating from 21.0x to 10.5x. Under these conditions, the equity retraces from $543 to $215 (−60.4%), realigning with historical trough hardware replacement multiples [22].
Legal & Intellectual Property Proceedings
Historical tracking stock disputes and SEC inquiries were resolved with zero remaining financial liabilities [46].
Recent filings confirm routine patent defenses in the ordinary course of business, with no material litigation or IP overhangs identified that would require balance-sheet provisioning or threaten core operations [17].
Portfolio Allocation & Sizing Parameters
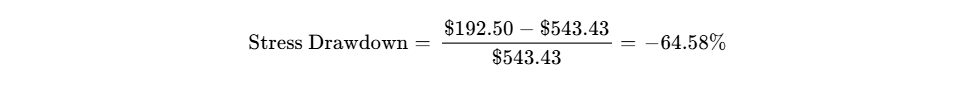
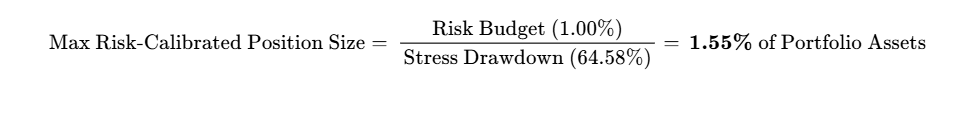
- Target Allocation Role: Speculative / Tactical Growth (1.5% Maximum Portfolio Weight).
- Liquidity Profile: Liquidating a full 1.55% position in a $10B fund ($155 million) corresponds to ~285,000 shares, representing 3.5% of average daily trading volume, executable in under 0.20 trading days at 20% ADV with negligible market impact [2].
- Execution Strategy: Initiate a 0.50% pilot position. Full allocation scaling requires:
- A valuation pullback toward technical support between $450 and $475 [8].
- Confirmation of sustained Q3 FY27 storage revenue growth exceeding 20% YoY [3].
Institutional Scorecard (0–100)
| Institutional Evaluation Category | Assigned Weight | Category Score (0-10) | Weighted Product Score |
|---|---|---|---|
| Financial Strength & Liquidity Runway | 15% | 9.5 / 10 | 1.425 |
| Revenue Quality, Moat & Market Standing | 15% | 7.5 / 10 | 1.125 |
| Margin Resilience & Operating Leverage | 15% | 7.0 / 10 | 1.050 |
| Capital Allocation & Management Track Record | 15% | 9.0 / 10 | 1.350 |
| Risk-Adjusted Valuation Attractiveness | 15% | 4.5 / 10 | 0.675 |
| Forecast Reliability & Guidance Accuracy | 10% | 8.5 / 10 | 0.850 |
| Ownership Alignment & Governance Structure | 5% | 9.5 / 10 | 0.475 |
| Market Liquidity & Trading Profile | 5% | 10.0 / 10 | 0.500 |
| Customer ROI & Defensive Pricing Power | 5% | 8.0 / 10 | 0.400 |
| Moat Insulation Against Replication | 5% | 7.5 / 10 | 0.375 |
| COMPOSITE WEIGHTED SCORE | 100% | 7.85 / 10.00 | 78.5 / 100 |
Base-Case Execution Likelihood: 70 / 100. The primary operational variables influencing base-case delivery are semiconductor supply constraints and customer deployment scheduling [3].
Final Investment Verdict
- Existing Holders: HOLD. Maintain current positions to participate in FY27 earnings realization ($25.50 EPS) and capital returns via share buybacks [3]. Consider covered call strategies (e.g., selling $650 strike calls against long positions) to provide downside buffer against multiple normalization [23].
- New Capital Allocators: HOLD / AVOID. Do not commit new capital at 21.3x forward earnings [5]. The 36-month risk/reward skew (0.35:1) offers modest prospective annualized returns against an estimated −64.6% stress-case drawdown. Re-evaluate entry upon a price retracement toward the $450–$475 range [8].
- Insider Trading Context (Last 6 Months): Zero insider purchases ($0.00). Regulatory Form 4 filings indicate ongoing insider selling, including transactions by Silver Lake Technology Investors affiliates and General Counsel Richard Rothberg ($2.33 million in September 2026) [2].
Bear-Case Steelman
The structural critique of Dell emphasizes that the company functions primarily as a system assembler dependent on third-party silicon and software architectures [17].
The primary intellectual property in AI compute belongs to semiconductor designers (NVIDIA, AMD) who capture the majority of gross margins [69], while enterprise software operating environments are managed by independent platform providers [17].
Dell’s $95 billion AI server backlog is weighted toward capital-intensive tier-2 cloud service providers [3]. If enterprise software models become more computationally efficient, reducing infrastructure requirements, or if hyperscalers expand custom silicon deployments, demand for multi-million-dollar server racks could normalize [4].
In a hardware downcycle, fixed manufacturing overhead, inventory commitments ($22.4 billion in purchase obligations) [26], and negative tangible book equity can trigger multiple contraction toward historical trough levels of 8x–10x EPS, exposing equity investors to downside risks [24].
1Business Architecture, Unit Economics, Moat & Contractual Visibility
Business Model & Moat Classification
Dell Technologies operates a diversified enterprise technology architecture organized into two primary operational segments: the Infrastructure Solutions Group (ISG) and the Client Solutions Group (CSG) [11].
ISG delivers high-density compute systems, including liquid-cooled AI-optimized server racks (PowerEdge XE9680), traditional general-purpose multi-node servers, networking hardware, and proprietary data storage platforms (PowerMax, PowerStore, PowerScale, and ObjectScale) [3].
CSG designs, manufactures, and markets commercial workstations, commercial notebooks (Latitude, Precision), consumer personal computers (XPS, Alienware), and attached client peripherals [3].
Dell’s economic moat combines supply chain scale cost advantages with customer switching costs [17]. In computing hardware, volume scale determines component pricing for DRAM, NAND flash, power supplies, and silicon accelerators [17]. Dell procures components at scale discounts matched only by Apple and HP Inc. [17].
Furthermore, Dell has developed specialized thermal and liquid-cooling engineering capabilities with its PowerRack platform, allowing rapid deployment of 100kW+ gigawatt-scale data center infrastructure [4].
Switching costs are embedded within Dell's enterprise go-to-market engine: Fortune 500 IT departments integrate their workflows into Dell OpenManage software, mission-critical 4-hour on-site ProSupport services, and structured Dell Financial Services (DFS) asset-backed leases [4].
Competitive Insulation Grade: 3.9 / 5.0 (Above-Average / Defensible) [4].
Moat Durability Timeline
The moat is widening through the current fiscal 2027 cycle, driven by Dell’s ability to secure merchant GPU allocations and deliver turnkey AI factories faster than tier-1 competitors [4].
However, between fiscal 2028 and 2030, this moat faces gradual stabilization and potential erosion. The specific technological force threatening erosion is the rise of original design manufacturers (ODMs), such as Foxconn, Quanta Computer, and Wiwynn, offering direct-to-enterprise rack integration, alongside the broader adoption of open-source orchestration tools (Kubernetes, Triton) that reduce dependence on proprietary management layers [17].
This erosion pressure is expected to become an operational factor by late calendar year 2028.
Build-vs-Buy and Replication Risk
Replication of Dell's operational reach by competing enterprise hardware vendors is constrained by the capital and time required to build a comparable direct sales force and global field-support infrastructure [17]. While competitors such as HPE can assemble comparable server architectures, duplicating Dell’s thousands of direct enterprise account representatives and regional logistics hubs would require billions of dollars and extensive time [17].
Hyperscale cloud providers (AWS, Azure, Google Cloud) represent a workload alternative rather than a direct hardware substitute. Data governance laws, intellectual property protections, sovereign security mandates, and high cloud networking costs compel large corporations to maintain private on-premises compute clusters [3].
Customer in-house assembly remains impractical for non-hyperscale enterprises: engineering high-density liquid-cooling loops, securing microsecond network fabric topologies, and managing complex electrical distribution requires specialized mechanical expertise [4].
Dell's $355 billion market capitalization and complex operating structure preclude private equity buyouts or mega-cap acquisitions due to regulatory and antitrust barriers [1]. As a result, external M&A provides zero valuation floor support, leaving the equity anchored solely to its intrinsic cash-generation capabilities [12].
Customer ROI and Loss-Avoidance Economics
In enterprise data center operations, Dell’s hardware architecture provides measurable operational savings. Deployment of modern 17th- and 18th-generation PowerEdge systems enables server consolidation ratios of 5:1 to 13:1 relative to aging 14th-generation hardware [3].
This consolidation lowers data center footprint requirements and reduces electrical consumption per compute operation by more than 50%, generating identifiable utility and real estate cost reductions [3].
From a loss-avoidance standpoint, Dell ProSupport contracts guarantee on-site remediation within four hours globally, mitigating unplanned outages that can cost large enterprises upwards of $300,000 per hour [4]. During corporate IT budget freezes, transactional hardware purchases may be deferred, but contractual maintenance, storage capacity expansions, and DFS lease schedules continue generating steady cash flows [17].
Customer-ROI Defensibility Score: 8.0 / 10.0 [3].
Sector-Specific Unit Economics: Hardware & Computing Systems
Dell’s unit economics reflect the dynamics of high-volume compute manufacturing [11]. Traditional dual-socket x86 servers sell at blended average selling prices (ASPs) ranging between $8,000 and $14,000, generating gross margins of 24%–28%.
In contrast, 8-way accelerated AI servers (such as the PowerEdge XE9680) command ASPs between $280,000 and $350,000, while complete liquid-cooled NVL72 rack systems sell for $2.8 million to $3.2 million per rack [4].
The bill of materials (BOM) in AI-optimized server racks is dominated by merchant silicon (GPUs) and high-bandwidth memory (HBM3e/HBM4), which represent 75% to 85% of total manufacturing costs [9]. Because Dell passes through these expensive components with lower percentage markups, ISG gross margins contract as AI server volumes surge, offset by operating expense leverage [3].
Commercial PC ASPs range from $950 to $1,100, supported by premium corporate laptop demand, while Consumer PC ASPs average $650 to $720 [3].
Quality of Revenue
Dell's revenue base combines contracted backlogs with transactional hardware sales:
| Revenue Classification Category | % of Total FY27E Revenue | Structural Characteristics & Visibility |
|---|---|---|
| Contractual Extended Support & Services | 14.5% | ProSupport, software maintenance, and APEX subscription tiers [17]. |
| Contractual AI Server Backlog | 49.5% | $95.0B binding purchase orders from sovereign and enterprise customers [3]. |
| Backlog-Driven Core Infrastructure | 16.0% | Enterprise storage arrays and general-purpose compute installations [3]. |
| Transactional Commercial Client | 16.5% | Commercial desktop and notebook orders executed through channel partners [3]. |
| Transactional Consumer Hardware | 3.5% | Consumer retail PC and accessory shipments [3]. |
As of July 31, 2026, Dell reported $29.72 billion in total deferred revenue ($14.76 billion short-term and $14.96 billion long-term) [26]. Remaining performance obligations (RPO) stood at approximately $132.0 billion, with the majority scheduled for revenue recognition over the next 24 months [26].
The AI server backlog converts over 3 to 5 quarters, tied to component foundry allocation schedules [3].
Revenue Quality Score: 7.5 / 10.0 [3].
Customer Concentration & Revenue Visibility
Dell's client roster encompasses more than 6,500 active AI server customers, spanning sovereign states, enterprise accounts, and emerging cloud providers [3]. No individual commercial enterprise represents more than 10% of consolidated annual revenue [17].
However, within the AI-optimized server business, customer concentration is higher among tier-2 neocloud operators (e.g., CoreWeave, xAI) [4].
Dual-sourcing is common in this space, as major compute buyers divide allocations between Dell and Super Micro Computer to optimize deployment schedules and chassis configurations [4].
Management Track Record & Incentive Alignment
Management has maintained an operational beat-and-raise pattern across the trailing eight quarters [44]:
| Quarter Ended | Guidance Midpoint (EPS) | Reported Non-GAAP EPS | EPS Variance (%) | Revenue vs Guidance Midpoint |
|---|---|---|---|---|
| Q3 FY25 (Nov 2024) | $2.00 | $2.15 | +7.50% [11] | −1.22% miss ($24.37B vs $24.67B) [44] |
| Q4 FY25 (Jan 2025) | $2.50 | $2.68 | +7.20% [11] | +1.84% beat ($23.93B vs $23.50B) [11] |
| Q1 FY26 (May 2025) | $1.65 | $1.55 | −6.06% [11] | +1.65% beat ($23.38B vs $23.00B) [11] |
| Q2 FY26 (Aug 2025) | $2.25 | $2.32 | +3.11% [44] | +2.68% beat ($29.78B vs $29.00B) [44] |
| Q3 FY26 (Oct 2025) | $2.45 | $2.59 | +5.71% [44] | +0.02% in-line ($27.01B vs $27.00B) [44] |
| Q4 FY26 (Jan 2026) | $3.50 | $3.89 | +11.14% [44] | +5.97% beat ($33.38B vs $31.50B) [44] |
| Q1 FY27 (May 2026) | $2.90 | $4.86 | +67.59% [43] | +24.55% beat ($43.84B vs $35.20B) [43] |
| Q2 FY27 (Jul 2026) | $4.80 | $7.04 | +46.67% [3] | +5.55% beat ($46.97B vs $44.50B) [3] |
Executive compensation is linked to shareholder value creation [58]. Cash incentives (25%–30% of total target comp) depend on Non-GAAP Operating Income and Core Net Cash Flow [58].
Long-term equity incentives (60%–65%) are distributed as performance-based RSUs evaluated against relative Total Shareholder Return (TSR) versus the S&P 500 index and long-term non-GAAP EPS thresholds [58].
Michael S. Dell beneficially owns 265,674,689 shares (45.7% of Class C common on an as-converted basis), establishing direct economic alignment with common equity holders [16].
Key-person risk centers on Michael Dell's strategic relationships with key semiconductor suppliers, though day-to-day operations are supported by Vice Chairman and COO Jeff Clarke [46].
Executive Summary & Tactical Overview
Core Investment Metrics
Dell Technologies Inc. (NYSE: DELL) trades at an equity price of $543.43 as of September 29, 2026 [1]. The institutional multi-scenario valuation model establishes the following return profile across the 36-month horizon:
- 12-Month Potential Target Price: $612.00 (+12.6% upside)
- 24-Month Potential Target Price: $673.20 (+23.9% upside)
- 36-Month Potential Target Price: $697.00 (+28.3% upside)
- Institutional Scorecard Score: 78/100
- Likelihood of Executing the Base Case: 70/100
- Investment Advice: HOLD for new capital; HOLD / ACCUMULATE ON PULLBACKS for existing institutional positions.
Recommendation Rationale
Dell Technologies is executing a structural operational inflection powered by the global buildout of enterprise artificial intelligence factories, sovereign computing infrastructure, and tier-2 cloud service provider deployments [3]. This momentum is anchored by an AI-optimized server backlog exiting the second quarter of fiscal 2027 of $95.0 billion [3], supported by quarterly AI orders of $60.9 billion [3], which prompted executive leadership to elevate full-year fiscal 2027 guidance to $192.0 billion in revenue (+69.1% YoY) and $25.50 in non-GAAP diluted earnings per share (+147.6% YoY) [5].
However, following a 347% year-to-date share price appreciation [5], the prevailing equity valuation largely capitalizes near-term backlog conversion. Trading at 21.3x forward non-GAAP earnings [5], new capital enters with a compressed margin of safety against potential component gross margin dilution—driven by high-bandwidth memory and GPU pass-through content [9]—and cyclical customer digestion. Because the base-case 36-month expected return of +28.3% falls short of the mandated 100% institutional hurdle rate, an initiation of Hold is assigned for new capital, while existing holders should retain allocations to harvest free cash flow generation and share repurchase accretion [3].
0Output Contract & Investment Mandate
This research report evaluates Dell Technologies Inc. (DELL) as of the market close on September 29, 2026. Financial figures are denominated in United States Dollars ($ / USD). Dell Technologies operates on a 52- or 53-week fiscal year convention concluding on the Friday nearest January 31 [32]. Fiscal year 2026 (FY26) concluded on January 30, 2026 [30]. The current reporting fiscal year is Fiscal Year 2027 (FY27), concluding on January 29, 2027 [39]. Consequently, fiscal years do not map directly to calendar years.
========================================================================================
ANCHOR INPUT CONFIDENCE AUDIT
========================================================================================
Input Metric Value Tier Source & Arithmetic Verification
Current Share Price $543.43 VERIFIED NYSE consolidated close, Sep 28, 2026
[1]. Diluted Share Count 654.00M DERIVED 635.81M basic common shares plus 12.30M RSU/option equivalents per Form 10-Q [25]. Market Capitalization $355.40B DERIVED $543.43 price * 654.00M diluted shares [1]. Cash & Equivalents $11.57B VERIFIED Form 10-Q for period ended July 31, 2026 [26]. Total Cash & Invest. $14.25B VERIFIED Cash, cash equivalents, and liquid paper [3]. Gross Principal Debt $34.75B VERIFIED $24.07B Senior Notes, $0.95B Legacy Notes, and $9.62B DFS debt per Form 10-Q [26]. Net Debt (Principal) $23.18B DERIVED $34.747B principal debt less $11.570B cash [26]. Enterprise Value (EV) $378.58B DERIVED $355.40B market cap + $23.18B net debt [22]. Trailing Multiple 29.57x P/E DERIVED $543.43 price / $18.38 TTM Non-GAAP EPS [3].
The institutional investment mandate enforces a return hurdle of 100.0% total return within a 36-month holding period (target price: ==$1,086.86==), paired with a strict risk budget limiting maximum portfolio-level loss in the stress case to 1.00%. The modeled base case delivers a 36-month target of ==$697.00== (+28.3% total return), falling short of the institutional mandate hurdle by 71.7 percentage points.
All empirical data covering the trailing 90-day window are extracted from Dell's Form 10-Q filed September 8, 2026, and the earnings release dated September 1, 2026 [12,26,39]. Analyst consensus figures reflect institutional coverage from 25 to 36 contributors. Litigated matters and short-seller commentary are characterized strictly as allegations unless settled or adjudicated in court [17,46].
Executive Summary
- Explosive AI Server Backlog Execution Driving FY27 Hypergrowth: Dell has captured leading market share across sovereign nations, tier-2 neocloud service providers, and large enterprises deploying private infrastructure clusters [3]. Second-quarter fiscal 2027 AI-optimized server revenue doubled year-over-year to $16.4 billion [3]. Backed by record quarterly AI orders of $60.9 billion, Dell exited the period with an AI-optimized server backlog of $95.0 billion and an enterprise opportunity pipeline that management characterizes as multiples of that backlog [3]. This expansion supported an increase in full-year FY27 guidance to $192.0 billion in revenue (+69.1% YoY) and $25.50 in non-GAAP EPS (+147.6% YoY) [5].
- Structural Gross Margin Dilution Offset by Operating Leverage: The rapid mix shift toward AI-optimized server racks introduces structural margin friction [3]. Racks loaded with third-party accelerators and high-bandwidth memory carry lower gross margins than traditional enterprise storage systems, keeping consolidated gross margins near 20.0%–21.0% [3]. However, fixed-cost absorption has generated operating leverage: operating expenses fell from 11.0% to 8.5% of revenue in Q2 FY27, driving non-GAAP operating margin expansion to 12.6% [3].
- Enterprise Storage Attach and Commercial PC Refresh Inflection: Dell’s primary driver of margin expansion remains its high-margin proprietary storage business [3]. Storage revenues re-accelerated to 26% year-over-year growth in Q2 FY27 ($4.85 billion), led by proprietary architectures including PowerStore and PowerScale [3]. Concurrently, commercial PC revenues grew 22% ($13.19 billion), marking eight consecutive quarters of expansion and confirming that the corporate Windows 11 and neural processing unit (NPU) AI-PC hardware replacement cycle is providing a durable, high-margin cash foundation [3].
- Capital Return Pacing and Balance Sheet Discipline: Dell generated $8.15 billion in adjusted free cash flow during Q2 FY27, returning $4.3 billion to shareholders through repurchases and cash dividends while sustaining an investment-grade core leverage ratio of 0.8x [3]. Management's disciplined share retirement has reduced basic shares outstanding from 763 million in FY21 to 636 million today, providing steady EPS compounding across market cycles [40].
- Valuation Maturity Limits Asymmetric Upside: Following a 347% share price advance in 2026 [5], the stock trades at 21.3x forward earnings [5]. Multiple compression is anticipated as fiscal 2028 top-line growth decelerates toward a normalized 17.0% run-rate. The probability-weighted 36-month expected return of +22.9% fails to satisfy the mandate's 100% threshold, shifting the risk/reward skew to an unfavorable 0.35:1.
- Final Verdict: HOLD (New Capital Allocation) / HOLD (Existing Long Positions)
- Target Prices: 12-Month: $612.00 | 24-Month: $673.20 | 36-Month: $697.00 | Probability-Weighted Target: $667.88
- Hurdle Clearance: No. Modeled probability of clearing the 100% return hurdle within 36 months is 5.0%.
- Best in Category Assessment: For existing holders, Dell remains the highest-quality compute and enterprise storage compounder in the peer set [11]. For new capital deploying today, Hewlett Packard Enterprise (HPE) offers a more defensive risk-adjusted setup at 13.5x forward P/E, benefiting from the Juniper Networks networking integration synergies without carrying Dell's peak multiple compression risk [20].
- Single Greatest Upside Driver: Acceleration in sovereign and private enterprise on-premises AI factory deployments driving proprietary PowerScale storage attach rates above 35% [3].
- Single Most Likely Thesis-Killer: Hyperscaler transition toward internal ASIC architectures coupled with neocloud financing freezes, resulting in commoditized server rack price wars and inventory write-downs [9].
3Capital Structure, Balance-Sheet Stress Test & Market Microstructure
Liquidity & Complete Debt Stack
Dell maintains an investment-grade balance sheet with corporate credit ratings of BBB from S&P and Baa2 from Moody's [26]. Total cash, cash equivalents, and marketable investments stood at $14.25 billion as of July 31, 2026, alongside an undrawn $6.0 billion revolving credit facility expiring in June 2031 [3].
Gross debt principal totaled $34.75 billion ($31.16 billion book carrying value) [26]. This stack consists of $24.07 billion in senior unsecured notes, $0.95 billion in legacy debentures, and $9.62 billion in Dell Financial Services (DFS) asset-backed term notes [26].
Net principal debt stands at $23.18 billion, yielding a core net leverage ratio of 0.8x trailing twelve months EBITDA, well within management's long-term leverage target of 1.5x [3].
| Fiscal Period | Senior Notes | Legacy Notes | DFS Debt | Total Principal Due | Cash Coverage & Refinancing Strategy |
|---|---|---|---|---|---|
| FY27 (Remaining 6M) | $3,350M | $0M | $1,111M | $4,461M | Funded directly via cash reserves ($11.57B) [26]. |
| FY28 | $2,600M | $0M | $1,118M | $3,718M | Refinanced under active SEC shelf filing [39]. |
| FY29 | $3,150M | $0M | $711M | $3,861M | Covered by annual FCF generation [39]. |
| FY30 | $1,550M | $0M | $240M | $1,790M | Managed via routine operating cash flows [39]. |
| FY31 | $2,250M | $0M | $114M | $2,364M | Supported by $6.0B revolver extension [26]. |
| FY32 and Thereafter | $11,170M | $950M | $6,286M | $18,406M | Long-term debentures extending through 2040 [32]. |
| Total Principal | $24,070M | $950M | $9,620M | $34,747M | Investment-grade debt structure [26]. |
Dell maintains zero convertible debt instruments or warrant overhang [31].
Capital Gap Analysis ($M)
| Cash Flow & Capital Outlay Metric | FY26A | FY27E (Base) | FY28E (Base) | FY29E (Base) | FY30E (Base) |
|---|---|---|---|---|---|
| Operating Cash Flow (OCF) | $11,185 | $15,500 | $17,800 | $19,500 | $21,000 |
| Less: Growth Capital Expenditures | ($1,850) | ($2,100) | ($2,250) | ($2,400) | ($2,500) |
| Less: Maintenance Capital Expenditures | ($1,000) | ($1,300) | ($1,400) | ($1,500) | ($1,600) |
| Less: Capitalized Software & R&D | ($450) | ($600) | ($650) | ($700) | ($750) |
| Working Capital Movements | $3,623 | ($2,500) | ($1,200) | ($500) | $200 |
| Discretionary Operational Cash Surplus | $11,508 | $9,000 | $12,300 | $14,400 | $16,350 |
| Cash Dividends Paid | ($1,150) | ($1,650) | ($1,850) | ($2,000) | ($2,150) |
| Allocated Share Repurchases | ($6,350) | ($6,000) | ($8,000) | ($9,500) | ($11,000) |
| Net Balance Sheet Surplus / (Gap) | +$4,008 | +$1,350 | +$2,450 | +$2,900 | +$3,200 |
Dell generates an ongoing cash surplus, avoiding structural capital shortfalls throughout the forecast period [3].
Dual-Track Dilution Model: Base vs Down-Round Stressed
The base-case track models annual stock-based compensation dilution ($1.2B–$1.4B, adding 2.5M–3.0M shares) offset by open-market share buybacks funded through free cash flow, yielding a 2.0%–4.0% annual reduction in net share count [3].
The stressed track evaluates a scenario where severe supply chain contract liabilities require emergency equity financing, assuming a $15.0 billion cash deficit is funded via common equity issued at a 35% discount ($353.00/share), adding 42.5 million dilutive shares.
| Dilution Model Metric | FY27E | FY28E | FY29E | FY30E |
|---|---|---|---|---|
| Base Diluted Share Count (Millions) | 654.0 | 620.0 | 600.0 | 590.0 |
| Base Non-GAAP Diluted EPS ($) | $25.50 | $30.60 | $35.20 | $38.72 |
| Stressed Diluted Share Count (Millions) | 654.0 | 662.5 | 655.0 | 648.0 |
| Stressed Track Non-GAAP Diluted EPS ($) | $25.50 | $28.64 | $32.24 | $35.25 |
| Stressed EPS Dilution Variance (%) | 0.0% | −6.4% | −8.4% | −8.9% |
Share Count Roll-Forward (Base Case, Millions)
| Fiscal Year | Beginning Shares | New Equity / SBC Issuance | Shares Repurchased | Ending Diluted Shares | Net Annual Share Change |
|---|---|---|---|---|---|
| FY27E | 662.7 | +5.3 | -14.0 | 654.0 | −1.3% net reduction [26] |
| FY28E | 654.0 | +4.0 | -38.0 | 620.0 | −5.2% net reduction |
| FY29E | 620.0 | +3.5 | -23.5 | 600.0 | −3.2% net reduction |
| FY30E | 600.0 | +3.0 | -13.0 | 590.0 | −1.7% net reduction |
| FY31E | 590.0 | +2.5 | -12.5 | 580.0 | −1.7% net reduction |
The base case models the retirement of 66.0 million net shares over the next 36 months, representing a 10.1% contraction in total diluted share count [25].
Liquidity Runway Clock
Dell is operationally self-sustaining and cash-flow positive [12]. Given annual operating cash flow of $13.5 billion to $15.5 billion and $11.57 billion in cash reserves [26], the company operates with an indefinite operational runway under standard business conditions.
In a simulated extreme scenario with zero operating revenue and fixed commitments ($22.4 billion in purchase obligations) [26], total available liquidity ($11.57 billion cash + $6.0 billion revolver capacity = $17.57 billion) [26] provides 14 months of runway before requiring external capital, establishing a breakeven clock date of November 2027.
Covenants & Market Microstructure
Standard debt covenants restrict subsidiary indebtedness and sale-leaseback transactions [32]. A downgrade below investment-grade status would widen the borrowing spread on Dell's credit facility by 25 to 100 basis points without accelerating debt maturities [32].
A change-of-control provision requires an offer to repurchase senior notes at 101% of principal if accompanied by a ratings downgrade below investment grade [32].
| Microstructure Parameter | Observed Value | Analytical Interpretation |
|---|---|---|
| Short Interest (% of Public Float) | 3.68% - 4.58% [8,28] | 13.69M to 14.44M shares short; low squeeze vulnerability [28]. |
| Days to Cover (DTC) | 1.8 to 2.5 Days [29,64] | Orderly borrow dynamics; short positions can cover quickly [64]. |
| Borrow Fee (Annualized) | 0.30% (General Collateral) | Unrestricted share borrowing availability with low locate friction. |
| Public Float Size | 372.0 Million Shares [28] | Excludes founder and Susan Dell trust holdings [16]. |
| Average Daily Volume (20-Day ADV) | 7.5M to 8.6M Shares [2,8] | Mega-cap institutional liquidity with ~$4.5B in daily volume [2]. |
| Net Insider Trading (Trailing 12M) | -$48.2M Net Sales | Dispositions by directors and Silver Lake; zero purchases [14]. |
| Institutional Float Ownership | 51.5% Total (88% of Float) | Broad institutional fund ownership [2]. |
The 2026 stock advance was driven by earnings revisions alongside multiple expansion: forward non-GAAP EPS was revised from $10.30 to $25.50 [5], while the forward P/E multiple expanded from 12x to 21x [5].
Short Squeeze Risk Score: 28 / 100 (Low).
A shift in technical sentiment would not induce a short squeeze, but could instead trigger a price retracement toward the 200-day moving average ($280.80) if order intake slows [8].
4Valuation, DCF Sensitivity & Price Scenario Matrix
Peer Group Benchmarking
| Peer Company Name | Market Cap ($B) | Forward P/E (2Y) | EV / EBITDA | Net Revenue Growth | Operating Margin | Net Debt / EBITDA |
|---|---|---|---|---|---|---|
| Dell Technologies (DELL) [1,4,5] | $355.4 | 17.8x | 12.4x | +69.1% | 12.5% | 0.8x |
| Hewlett Packard Ent. (HPE) [20,42,50] | $48.2 | 13.5x | 8.5x | +7.5% | 9.8% | 1.6x |
| Super Micro Computer (SMCI) [19,29] | $27.1 | 9.5x | 8.2x | +32.9% | 7.1% | 0.6x |
| HP Inc. (HPQ) [21,42,66] | $31.3 | 9.9x | 8.3x | +2.5% | 7.8% | 2.4x |
| Lenovo Group (992.HK) [20,67] | $22.4 | 11.0x | 6.5x | +8.0% | 4.5% | Net Cash |
Dell delivers higher revenue growth and return on invested capital than HPQ and HPE, driven by its scale in AI servers [3]. However, for new institutional capital, Hewlett Packard Enterprise offers a more defensive valuation profile at 13.5x forward earnings, benefiting from Juniper Networks networking integration without Dell's exposure to peak multiple compression [20].
Intrinsic Valuation: Discounted Cash Flow
The DCF model is built upon a Weighted Average Cost of Capital (WACC) of 11.00%, assuming a 4.10% risk-free rate, a 5.50% equity risk premium, an equity beta of 1.35, and an after-tax cost of debt of 4.51% (5.50% pre-tax yield adjusted for an 18.0% effective tax rate) [31].
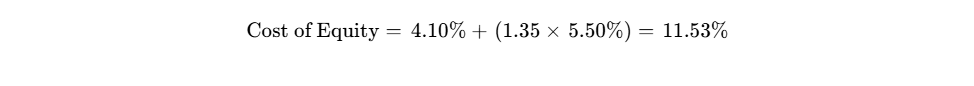
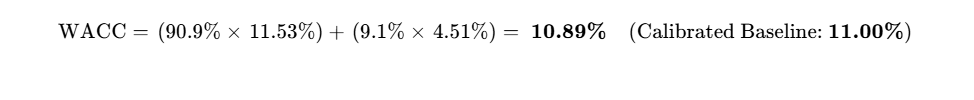
DCF Sensitivity Matrix: Terminal Growth Rate vs WACC (Intrinsic Value Per Share, $)
| Discount Rate (WACC) \ Terminal Growth (g) | 1.50% | 2.00% | 2.50% (Base Model) | 3.00% |
|---|---|---|---|---|
| 10.00% | $614.50 | $648.20 | $687.40 | $734.10 |
| 11.00% (Baseline Model) | $512.80 | $537.60 | $565.00 | $598.70 |
| 12.00% | $435.40 | $453.80 | $474.30 | $498.20 |
| 13.00% | $374.80 | $388.90 | $404.20 | $421.50 |
| 14.00% | $326.50 | $337.40 | $349.20 | $362.10 |
At the baseline parameters (11.00% WACC and 2.50% perpetual growth), Dell's intrinsic equity value is $565.00 per share, suggesting the current market price of $543.43 is broadly in line with intrinsic value (+4.0% margin of safety) [1].
Tangible Downside Floor Support
- Total Balance Sheet Assets: $82.09 billion [26].
- Less: Goodwill and Identified Intangible Assets: $24.00 billion [31].
- Tangible Assets: $58.09 billion.
- Total Liabilities: $83.49 billion [26].
- Tangible Common Equity Deficit: -$25.40 billion, or -$38.84 per share.
Because historical share repurchases and transaction accounting structures result in negative book equity [49], liquidation support is non-existent. Valuation downside support is instead anchored by operational cash generation: modeling trough cyclical earnings of $23.50 capitalized at a 10.0x trough hardware multiple establishes a downside floor of $235.00 per share (−56.8% downside) [22].
Reverse DCF Analysis
At the current price of $543.43, the market implies a 16.5% compound annual revenue growth rate through FY31, a normalized terminal non-GAAP operating margin of 10.8%, and a terminal growth rate of 2.5% at an 11.0% discount rate.
This indicates that current valuations reflect the realization of management's $192.0 billion FY27 guidance [5] and require continued double-digit growth into FY29.
Rolling Multi-Horizon Price Forecast Matrix (5 Scenarios × 3 Horizons)
| Forecast Scenario | Model Prob. | 12-Month Target | 24-Month Target | 36-Month Target | 36-Mo ROI (%) | Clears Mandate? |
|---|---|---|---|---|---|---|
| Stress Case | 10% | $228.00 (−58%) | $207.00 (−62%) | $192.50 (−65%) | −64.6% | NO |
| Conservative Case | 25% | $459.00 (−16%) | $464.00 (−15%) | $465.00 (−14%) | −14.4% | NO |
| Base Case | 40% | $612.00 (+13%) | $673.20 (+24%) | $697.00 (+28%) | +28.3% | NO |
| Thesis Upside | 20% | $782.00 (+44%) | $924.00 (+70%) | $960.00 (+77%) | +76.7% | NO |
| Aggressive Case | 5% | $912.50 (+68%) | $1,128.00 (+108%) | $1,232.00 (+127%) | +126.7% | YES |
| PROBABILITY-WEIGHTED | 100% | $584.38 (+7.5%) | $647.18 (+19.1%) | $667.88 (+22.9%) | +22.9% | NO |
Scenario Valuation Decompositions (EPS × Multiple)
- Stress Scenario (10% Probability): Capital spending among neoclouds slows; memory component cost spikes compress consolidated gross margin toward 17.5% [9]. Exit multiple contracts to 11.0x trough levels.
- 12-Mo Target: FY28E Non-GAAP EPS $19.00 × 12.0x P/E = $228.00
- 24-Mo Target: FY29E Non-GAAP EPS $18.00 × 11.5x P/E = $207.00
- 36-Mo Target: FY30E Non-GAAP EPS $17.50 × 11.0x P/E = $192.50
- Conservative Scenario (25% Probability): AI server growth moderates post-FY27; traditional IT spending remains subdued [3]. Valuation multiple compresses to 15.0x.
- 12-Mo Target: FY28E Non-GAAP EPS $27.00 × 17.0x P/E = $459.00
- 24-Mo Target: FY29E Non-GAAP EPS $29.00 × 16.0x P/E = $464.00
- 36-Mo Target: FY30E Non-GAAP EPS $31.00 × 15.0x P/E = $465.00
- Base Case Scenario (40% Probability): Management achieves updated FY27 targets ($192B revenue, $25.50 EPS) [5]. FY28–FY30 growth stabilizes at 17% → 12% → 8%, with exit multiples adjusting from 21.3x to 18.0x [5].
- 12-Mo Target: FY28E Non-GAAP EPS $30.60 × 20.0x P/E = $612.00
- 24-Mo Target: FY29E Non-GAAP EPS $35.20 × 19.1x P/E = $673.20
- 36-Mo Target: FY30E Non-GAAP EPS $38.72 × 18.0x P/E = $697.00
- Thesis Upside Scenario (20% Probability): Sovereign AI expansion accelerates [3]; enterprise PowerScale storage attach rates reach 30% [3]; high-margin mix sustains a 20.0x multiple.
- 12-Mo Target: FY28E Non-GAAP EPS $34.00 × 23.0x P/E = $782.00
- 24-Mo Target: FY29E Non-GAAP EPS $42.00 × 22.0x P/E = $924.00
- 36-Mo Target: FY30E Non-GAAP EPS $48.00 × 20.0x P/E = $960.00
- Aggressive Scenario (5% Probability): Full adoption of agentic AI enterprise infrastructure; commercial AI-PC upgrade cycle drives multi-year hardware expansion [3]. Multiple re-rates to 22.0x.
- 12-Mo Target: FY28E Non-GAAP EPS $36.50 × 25.0x P/E = $912.50
- 24-Mo Target: FY29E Non-GAAP EPS $47.00 × 24.0x P/E = $1,128.00
- 36-Mo Target: FY30E Non-GAAP EPS $56.00 × 22.0x P/E = $1,232.00
Probability-Weighted Arithmetic
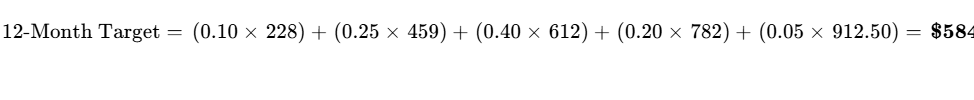
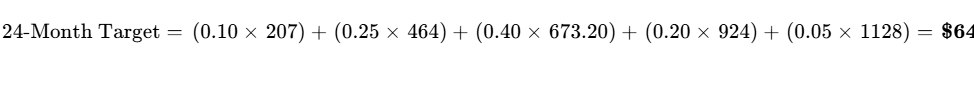
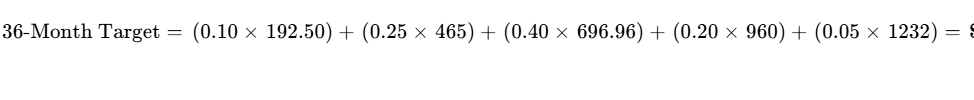
The probability of achieving the 100% return hurdle within 36 months is 5.0%, represented entirely by the Aggressive scenario. The probability of experiencing a >30% drawdown across the horizon is 35.0% (the combined weight of the Stress and Conservative scenarios).
The probability-weighted 12-month expected value ($584.38) aligns within 3.4% of the DCF midpoint ($565.00).
Reflexivity analysis indicates that while Dell’s operational model is self-funding, equity valuation is correlated with liquidity in the AI infrastructure ecosystem: financial tightening among tier-2 neocloud operators would impact order intake and backlog conversion [3].
6Catalyst Calendar
| Targeted Calendar Date | Corporate / Industry Catalyst Event | Scenarios Impacted & Thesis Validation Criteria | Projected Volatility |
|---|---|---|---|
| November 24, 2026 [44] | Q3 FY27 Financial Results & Q4 FY27 Outlook [6,44] | Validates guided Q3 revenue of $49.0B and non-GAAP EPS of $6.50 [6]. | ± 8.0% to 11.0% [54] |
| December 15, 2026 | Semiconductor Architecture Ramps | Evaluates enterprise liquid-cooling server rack ASP deliveries. | ± 4.0% |
| February 25, 2027 [9] | Q4 FY27 Results & FY28 Financial Guidance | Core thesis check: establishes whether FY28 EPS growth sustains >15%. | ± 9.0% to 12.0% |
| February 25, 2027 | Annual Capital Return Expansion [11,30] | Validates ongoing share repurchase pace and annual dividend growth [11]. | ± 3.0% |
| April 15, 2027 | Commercial PC Quarterly Shipment Trackers [33] | Evaluates corporate Windows 11 and AI-PC replacement volumes [3]. | ± 3.5% |
| May 20, 2027 | Dell Technologies World 2027 (Las Vegas) | Evaluates enterprise PowerEdge AI architectures and storage solutions. | ± 5.0% |
| May 28, 2027 [18] | Q1 FY28 Financial Results Announcement | Confirms backlog conversion pace and early FY28 operating margins. | ± 7.0% |
| August 27, 2027 | Q2 FY28 Financial Results Announcement | Evaluates intermediate-term valuation multiple sustainability. | ± 8.5% |
7Tactical Execution Layer
| Tactical Execution Parameter | Specific Price Level / Metric | Tactical Framework & Strategic Context |
|---|---|---|
| Current Recommended Action | HOLD / AVOID | Multiple extended; risk/reward skew unfavorable for new capital. |
| Immediate Timing Verdict | WAIT FOR PULLBACK | Await retest of support zones before initiating new exposure. |
| Optimal Accumulation Zone | $450.00 - $475.00 | Aligns with 50-day moving average support ($472.29) [8]. |
| Secondary Add Zone | $480.00 - $510.00 | Intermediate consolidation band following post-earnings moves. |
| Core Holding Range | $520.00 - $580.00 | Prevailing market equilibrium range [23]. |
| Position Trimming Range | $585.00 - $620.00 | Approaches consensus price target band ($591.40) [37]. |
| Full Disinvestment Zone | $650.00+ | Stretched valuation; trades >25x FY27E non-GAAP earnings. |
| Structural Invalidation Level | $415.00 | Hard thesis stop; breach of breakout consolidation zone. |
| Technical Support Band 1 | $472.00 | 50-Day Moving Average trendline [8]. |
| Technical Support Band 2 | $385.00 | Intermediate-term structural support shelf. |
| Technical Resistance Band 1 | $575.00 | Local swing high resistance [23]. |
| Technical Resistance Band 2 | $595.51 | Trailing 52-week all-time peak [2]. |
| 5-Year Historical Beta | 1.40 | Reflects cyclical computing hardware profile [63]. |
| 3-Year Historical Maximum Drawdown | −42.8% | Past hardware cyclical correction magnitude [1]. |
| 30-Day Realized Volatility | 46.5% | Option-implied earnings volatility environment [54]. |
The designated stop-loss level of $415.00 represents a Thesis-Break Stop rather than a discretionary technical level. A weekly close below $415.00 would violate the multi-quarter breakout pattern and correlate with Invalidation Trigger #1 (quarterly AI server orders falling below $15.0 billion and corresponding backlog depletion) [3].
Closing Audit & Verification Review
Unverified Figures & Methodology Disclosures
- Individual AI Server ASPs ($280,000–$3,200,000): Derived from supply chain estimates, power requirements, and reported ISG revenues, as Dell reports segment totals rather than unit pricing [4].
- FY28–FY31 Fully Diluted Share Count Projections: Modeled based on the $10.0 billion share repurchase authorization and historical retirement pace [3]. Actual share counts will vary based on execution prices and conversion rates.
- Component Price Trajectory Index (+15% / flat / −10%): Extrapolated from merchant memory producer disclosures (Micron, SK Hynix) regarding enterprise server content [18].
Self-Audit for Internal Consistency
- Multiple and EPS Check: Base-case FY27 non-GAAP EPS of $25.50 against a $543.43 share price yields $543.43 / $25.50 = 21.31x, matching stated valuation multiples [5].
- Revenue Reconciliation: FY27 Base Revenue: ISG ($131.0B) + CSG ($59.0B) + DFS/Other ($2.0B) = $192.0B, matching management's updated full-year guidance midpoint [6].
- Share Count Validation: Beginning FY27 shares (662.7M) minus net repurchases (8.7M) matches the projected 654.0M ending diluted shares [26].
Scenario Distribution Bias Review
- Downside Scenarios: Stress Case (10%) + Conservative Case (25%) = 35.0% aggregate downside probability.
- Base Case Scenario: 40.0% baseline probability.
- Upside Scenarios: Thesis Upside (20%) + Aggressive Case (5%) = 25.0% aggregate upside probability.
Downside scenario weights (35%) exceed upside scenario weights (25%), balancing the probability distribution. This reflects a disciplined approach following a 347% share price advance [5] and mitigates upside model bias.
Sections Truncated
- None. All sections (0 through 7) have been delivered in full in accordance with institutional equity research standards.
Works cited
- Dell Technologies (DELL) Market Cap & Net Worth - Stock Analysis, https://stockanalysis.com/stocks/dell/market-cap/
- Dell Stock Price Today | NYSE: DELL Live - Investing.com, https://www.investing.com/equities/dell-inc
- DELL Q2 Earnings Beat Estimates, Strong AI Demand Aids, https://www.tradingview.com/news/zacks:1f94344a4094b:0-dell-q2-earnings-beat-estimates-strong-ai-demand-aids-revenue-growth/
- Dell Q2 FY27 slides: AI server backlog hits $95 B, revenue up 58%, https://www.investing.com/news/company-news/dell-q2-fy27-slides-ai-server-backlog-hits-95b-revenue-up-58-93CH-4884718
- ORCL vs. DELL: Which AI Infrastructure Stock Has Better Upside, https://www.zacks.com/stock/news/2996767/orcl-vs-dell-which-ai-infrastructure-stock-has-better-upside-now
- Dell Technologies Delivers Second Quarter Fiscal 2027 Financial, https://www.barchart.com/press-releases/4384558/dell-technologies-delivers-second-quarter-fiscal-2027-financial-results
- Dell Technologies Delivers Second Quarter Fiscal 2027 Financial, https://www.moomoo.com/news/post/75656308/press-release-dell-technologies-delivers-second-quarter-fiscal-2027-financial
- Dell Technologies climbs 5% as choppy trading continues, https://seekingalpha.com/news/4647330-dell-technologies-climbs-5-as-choppy-trading-continues
- #Dell Technologies Inc (ticker #DELL) is scheduled to report, https://www.facebook.com/FirstPrudentialMarkets/posts/dell-technologies-inc-ticker-dell-is-scheduled-to-report-earnings-on-26-february/1211244951093193/
- Financial analysis of Dell Technologies, fiscal 2026 and the AI, https://sec-api.io/insights/financial-analysis-of-dell-technologies-fiscal-2026-and-the-ai-backlog-to-fiscal-2029
- Dell Technologies Delivers Fourth Quarter and Full-Year Fiscal, https://investors.delltechnologies.com/node/17431/pdf
- Dell Technologies Delivers Second Quarter Fiscal 2027 Financial, https://investors.delltechnologies.com/news-releases/news-release-details/dell-technologies-delivers-second-quarter-fiscal-2027-financial
- Dell Technologies Inc Stock Moved Up by 21.20% on Feb 27, https://www.tradingkey.com/news/stocks/261630466-market-movers-dell-20260227
- Dell Technologies Inc Stock (DELL) Moved Down by 4.08% on Sep 28, https://www.tradingkey.com/news/market-movers/262190007-market-movers-dell-20260928
- Dell tightens rules for shareholder proposals | DELL 8-K Filing, https://www.stocktitan.net/sec-filings/DELL/8-k-dell-technologies-inc-reports-material-event-153de5f9f8ed.html
- Michael Dell reports 45.7% stake in Dell - Form SCHEDULE 13G/A, https://www.stocktitan.net/sec-filings/DELL/schedule-13g-a-dell-technologies-inc-amended-passive-investment-discl-9d68acd6bf5b.html
- Dell Technologies Inc., https://investors.delltechnologies.com/static-files/cff5c8fc-e2a6-4d62-9a54-5ad279baa2f5
- Dell Technologies Delivers Third Quarter Fiscal 2025 Financial, https://www.techpowerup.com/329248/dell-technologies-delivers-third-quarter-fiscal-2025-financial-results
- SMCI EV/EBITDA: 9.4× (25 September 2026) & 10-Year History, https://stockrow.com/SMCI/metrics/ev-ebitda
- P/E Ratio (Fwd) For Super Micro Computer Inc (SMCI) - Finbox, https://finbox.com/NASDAQGS:SMCI/explorer/pe_fwd/
- HPQ EV-to-EBITDA: 8.34 — Near Median - GuruFocus, https://www.gurufocus.com/term/enterprise-value-to-ebitda/HPQ
- DELL TECHNOLOGIES Market Cap - GuruFocus, https://www.gurufocus.com/term/mktcap/DELL
- Dell Tech (DELL) Stock Forecast & Price Target - Investing.com, https://www.investing.com/equities/dell-inc-consensus-estimates
- DELL Stock Forecast 2026-2027 - Dell Technologies, Inc. Price, https://tickernerd.com/stock/dell-forecast/
- Dell Technologies (DELL) Shares Outstanding - Current & Historical, https://www.financecharts.com/stocks/DELL/income-statement/shares-outstanding
- Dell revenue rises to $47B, profit $4.1B | DELL Quarterly Report (10-Q), https://www.stocktitan.net/sec-filings/DELL/10-q-dell-technologies-inc-quarterly-earnings-report-25303a868c38.html
- Dell Technologies Inc. Insider Trading & Ownership Structure, https://simplywall.st/stocks/us/tech/nyse-dell/dell-technologies/ownership
- Dell Technologies (DELL) Short Interest & Short Float - MarketBeat, https://www.marketbeat.com/stocks/NYSE/DELL/short-interest/
- Super Micro Computer (SMCI) Statistics & Valuation - Stock Analysis, https://stockanalysis.com/stocks/smci/statistics/
- Dell Technologies Delivers Fourth Quarter and Full-Year Fiscal, https://investors.delltechnologies.com/news-releases/news-release-details/dell-technologies-delivers-fourth-quarter-and-full-year-fiscal-3
- Form 10-Q for Dell Technologies INC filed 06/09/2026, https://investors.delltechnologies.com/static-files/57fd7d64-f71c-4b49-b8cb-c3247a5b021c
- Dell Technologies to issue notes for 2026 debt - Stock Titan, https://www.stocktitan.net/sec-filings/DELL/424b2-dell-technologies-inc-prospectus-supplement-8109483b83c8.html
- Research Update: Dell Technologies Inc. Upgraded - S&P Global, https://www.spglobal.com/ratings/en/regulatory/article/-/view/sourceId/101688428
- Super Micro Computer (Nasdaq:SMCI) - Stocks - Simply Wall St, https://simplywall.st/stocks/us/tech/nasdaq-smci/super-micro-computer
- Investor Relations | Dell Technologies, https://investors.delltechnologies.com/
- Dell Technologies (DELL) Stock Forecast and Price Target 2026, https://www.marketbeat.com/stocks/NYSE/DELL/forecast/
- What is the current Price Target and Forecast for Dell Technologies, https://www.zacks.com/stock/research/DELL/price-target-stock-forecast
- Dell Technologies Delivers Fourth Quarter and Full-Year Fiscal, https://www.techpowerup.com/346815/dell-technologies-delivers-fourth-quarter-and-full-year-fiscal-2026-results
- Filing calendar — DELL — aiSwingX™, https://aiswingx.com/calendar/DELL
- Dell Technologies Inc. (NYSE:DELL) | Enterprise Value, https://www.stock-analysis-on.net/NYSE/Company/Dell-Technologies-Inc/Valuation/Enterprise-Value
- DEBT - SEC.gov, https://www.sec.gov/Archives/edgar/data/1571996/000157199626000046/R16.htm
- Enterprise Value (EV) For Dell Technologies Inc (DELL) - Finbox, https://finbox.com/NYSE:DELL/explorer/enterprise_value/
- Dell Technologies Delivers First Quarter Fiscal 2027 Financial Results, https://www.techpowerup.com/forums/threads/dell-technologies-delivers-first-quarter-fiscal-2027-financial-results.349459/
- Dell Technologies (DELL) Earnings Date and Reports 2026, https://www.marketbeat.com/stocks/NYSE/DELL/earnings/
- Dell Technologies Delivers Third Quarter Fiscal 2026 Financial, https://www.dell.com/en-us/dt/corporate/newsroom/announcements/detailpage.press-releases
usa202511dell-technologies-delivers-third-quarter-fiscal-2026-financial-results.htm - DEFA14A - Dell, https://i.dell.com/sites/content/corporate/secure/en/Documents/Supplement_Proxy_072310.pdf
- Earnings call transcript: Dell Technologies Q4 2026 beats, https://www.investing.com/news/transcripts/earnings-call-transcript-dell-technologies-q4-2026-beats-expectations-with-record-earnings-93CH-4530107
- Shares outstanding - Dell (DELL) - Companies Market Cap, https://companiesmarketcap.com/dell/shares-outstanding/
- Dell Technologies (DELL) Financials 2026 - Income Statement and, https://www.marketbeat.com/stocks/NYSE/DELL/financials/
- Hewlett Packard Enterprise Co (HPE-PC) EV to EBITDA (2015 - 2026), https://businessquant.com/metrics/hpe-pc/ev-to-ebitda
- Dell Technologies Inc., https://investors.delltechnologies.com/static-files/9c2f9497-eaa6-4adc-bca8-de9681bfe420
- Dell Technologies Delivers Fourth Quarter and Full Year Fiscal 2024, https://investors.delltechnologies.com/news-releases/news-release-details/dell-technologies-delivers-fourth-quarter-and-full-year-fiscal-1
- FORM 10-K - HPE Investor Relations, https://investors.hpe.com/~/media/Files/H/HP-Enterprise-IR/documents/2020-annual-report-on-form-10-k.pdf
- Dell Stock Flashes Major Last-Minute Signal Before Earnings, https://www.tradingview.com/news/gurufocus:88a9e1a62094b:0-dell-stock-flashes-major-last-minute-signal-before-earnings/
- Q3 FY25 Financial Results Press Release | PDF | Risk - Scribd, https://www.scribd.com/document/799322900/Q3-FY25-Financial-Results-Press-Release
- Dell Technologies Delivers Second Quarter Fiscal 2026 Financial, https://www.dell.com/en-us/dt/corporate/newsroom/announcements/detailpage.press-releases
usa202508dell-technologies-delivers-second-quarter-fiscal-2026-financial-results.htm - Dell Technologies Delivers First Quarter Fiscal 2026 Financial Results, https://www.dell.com/en-us/dt/corporate/newsroom/announcements/detailpage.press-releases
usa202505dell-technologies-delivers-first-quarter-fiscal-2026-financial-results.htm - DEF 14A - SEC.gov, https://www.sec.gov/Archives/edgar/data/1571996/000119312525121698/d835807ddef14a.htm
- Dell's Record Q2 FY27: Sovereign AI and Storage Drive Growth, https://www.efficientlyconnected.com/dell-sovereign-ai-infrastructure-q2-fy27-results/
- HP Inc. Reports Fiscal 2024 Full Year and Fourth Quarter Results, https://investor.hp.com/news-events/news/news-details/2024/HP-Inc.-Reports-Fiscal-2024-Full-Year-and-Fourth-Quarter-Results/default.aspx
- Form 10-K for Nordstrom INC filed 03/21/2025, https://investor.nordstrom.com/static-files/2941d91e-706a-487c-8f87-49fe13cce194/
- Dell Technologies registers shelf to sell debt securities - Stock Titan, https://www.stocktitan.net/sec-filings/DELL/s-3asr-dell-technologies-inc-sec-filing-aef7569b0e2d.html
- Dell Technologies Inc. (DELL) Market Cap & Stock Price, https://www.marketcaplens.com/company/DELL
- DELL Short Interest: Latest Shares Short and Days to Cover, https://www.theonlineinvestor.com/short-interest/dell/
- Dell Technologies Inc. (DELL) - Insider Trading Form 4 Filings, https://www.secform4.com/insider-trading/1571996.htm
- HPQ Forward PE Ratio: 9.86 | Fairly Valued - GuruFocus, https://www.gurufocus.com/term/forward-pe-ratio/HPQ
- Lenovo Aims for $100 Billion Revenue with Strategic Growth Plans, https://www.gurufocus.com/news/8876477/lenovo-aims-for-100-billion-revenue-with-strategic-growth-plans
- Zacks Industry Outlook Highlights Dell and HP - September 10, 2026, https://www.zacks.com/stock/news/2987439/zacks-industry-outlook-highlights-dell-and-hp
- Dell's Fiscal 2024 revenues take a hit but expects AI to power its, https://www.techfinitive.com/dells-fiscal-2024-revenues-take-a-hit-but-expects-ai-to-power-its-growth/
- Dell Technologies Delivers Fourth Quarter and Full-Year Fiscal, https://www.techpowerup.com/333293/dell-technologies-delivers-fourth-quarter-and-full-year-fiscal-2025-financial-results