Stock Name & Exchange: Cerebras Systems Inc. (NASDAQ: CBRS) [1]
Current Stock Price: $169.52 (Closing price October 1, 2026; intraday trading range $166.23–$175.13) [2]
Research Date: October 2, 2026 [2]
12-Month Target Price: $245.00 (+44.5% upside)
24-Month Target Price: $310.00 (+82.9% upside)
36-Month Target Price: $375.00 (+121.2% upside)
Institutional Scorecard Score: 67.5 / 100
Base-Case Execution Likelihood: 58 / 100
Investment Advice: HOLD for existing institutional positions; STAGED ACCUMULATION / SPECULATIVE BUY for unallocated multi-year risk capital.
Investment Thesis Summary:
Cerebras Systems has established an engineering moat in artificial intelligence inference through its proprietary wafer-scale engine architecture, which delivers between 1,000 and 3,000 tokens per second for high-concurrency reasoning and agentic workloads [4]. The operational foundation is supported by $25.4B in contractual Remaining Performance Obligations, primarily driven by a commercial compute agreement with OpenAI and deployment commitments across sovereign and enterprise accounts [7]. However, immediate multiple expansion is tempered by gross margins compressed by leased datacenter capacity, extreme revenue concentration in OpenAI and UAE-linked entities, and technical lock-up expirations culminating on November 9, 2026 [8]. While the 36-month fundamental trajectory exceeds return hurdles, new institutional allocators should phase entries across technical pullbacks following lock-up absorption.
Key Investment Statistics & Cross-Sectional Metrics
| Financial & Operating Metric | Reported Value / Status | Comparative Benchmark & Context |
|---|---|---|
| Overall Investment Stock Score | 68 / 100 | Composite metric spanning backlog visibility, balance-sheet safety, and governance overhang. |
| Founder-Led Status | Yes [12] | Led by Co-Founder & CEO Andrew Feldman and Co-Founder & CTO Sean Lie [12]. |
| CEO Operational Score | 74 / 100 | Serial entrepreneur who sold SeaMicro to AMD for $334M [12]; reduced for aggressive customer warrant dilution [10]. |
| Commodity Dependence & Deck | Not Applicable | Fabless semiconductor design and AI cloud services; sensitive to TSMC wafer pricing and power availability [2]. |
| Sector & Sector Trailing P/E | Semiconductors (Technology) [2] | Industry peer group median trailing P/E sits at 36.5x (peer range: 32.0x–44.0x ex-Nvidia). |
| Best-of-4 Sector Peer Ranking | Rank 3 of 4 | 1. NVIDIA (NVDA) (CUDA software ecosystem and cash flow generation) [17]; |
- Astera Labs (ALAB) (75% gross margins, broad connectivity merchant exposure) [19];
- Cerebras Systems (CBRS) (High upside ceiling offset by high customer concentration) [8];
- Credo Technology (CRDO) (High valuation multiple relative to cyclic AEC exposure) [20]. | | Forward PEG Ratios (1 to 5-Yr) | 1Y: NM (GAAP net loss) [13]
2Y: 0.62x (FY27)
3Y: 0.48x (FY28)
4Y: 0.58x (FY29)
5Y: 0.74x (FY30) | Multi-year PEG compresses as recognized RPO deliveries translate into operating profit [8]. | | Current Intrinsic Fair Value | $205.40 (+21.2% spread) | Baseline 10-year Discounted Cash Flow model (WACC: 11.5%, terminal growth: 2.5%). | | Tangible Downside Price Floor | $34.80 (−79.5% spread) | Downside support derived from cash, liquid securities, and hardware inventories minus liabilities [21]. | | Current Basic Share Count | 237,564,041 shares [22] | Form 10-Q as of August 5, 2026: 112.25M Class A, 111.60M Class B (20 votes), 13.72M Class N [7]. | | Modeled 36-Month Share Count | 274.50M shares | Fully diluted base case incorporating warrant exercises and employee stock vestings [10]. | | Announced Share Programs | 0 shares announced | Nil repurchase authorizations; capital deployed to power infrastructure and compute fleet [8]. | | Insider Ownership Percentage | 10.72% [13] | Insiders hold 25.47M common shares across Class A and Class B stock [13]. | | Insider Buying (Last 6 Months) | $0.00 (Zero Purchases) [13] | Zero purchases reported. Post-IPO lockup sales: Andrew Feldman sold $62.3M [13]; Dhiraj Mallick sold $158.7M [13]; Sean Lie sold $71.3M [13]; Robert Komin sold $6.6M [13]. | | Short Squeeze Potential Score | 28 / 100 | Short interest: 12.80M shares (5.39% of shares out, 11.63% of float) [24]; Days to cover: 2.17 days [13]; Borrow fee: ~0.8%. | | Announced Share Buybacks | None (0.0% of float) | No share repurchase authorizations currently active. | | Diluted vs. Fully Diluted Shares | 252.10M vs. 268.50M shares | Treasury diluted excludes out-of-the-money instruments; fully diluted includes all customer warrants [10]. | | Buyback Announcement Chance (6 Mo) | 0.0% probability | Negligible; cash balances preserved for multi-gigawatt datacenter expansions [8]. | | Cash Runway & Breakeven Horizon | >60 Months Runway;
Operating Breakeven: Q4 FY27 | Liquid capital of $8.61B offsets interim operating cash deficits through the multi-gigawatt buildout [8]. | | Total Borrowed Debt vs. Cash | $918.2M Debt vs. $8.61B Cash [8] | Net Cash position: +$7.69B ($32.36 per basic share) [21]. | | Debt Restructuring Risk Score | 12 / 100 (Low Default Risk) | OpenAI Working Capital Loan carries a 6.0% coupon maturing in 2032 [27]; $850M undrawn credit facility matures in 2031 [8]. | | Gross Margins (Current vs. 3Y & 5Y) | Current (Q2'26): GAAP 14.2% / Core 40.6% [9]
3Y Out (FY29E): GAAP 48.5% / Core 52.0%
5Y Out (FY31E): GAAP 51.5% / Core 54.0% | Q2'26 GAAP gross margin suppressed by $29.8M warrant contra-revenue and leased datacenter rents [9]. | | Operating Margins (Current vs. 3Y & 5Y) | Current (Q2'26): GAAP (265.0%) / Core (16.0%) [8]
3Y Out (FY29E): GAAP +22.8% / Core +28.5%
5Y Out (FY31E): GAAP +26.0% / Core +31.0% | Margin inflection driven by scale leverage across fixed engineering and SG&A expenses [23]. | | Regulatory & Geopolitical Risk Score | 78 / 100 (High Overhang) | Subject to BIS export reviews, CFIUS monitoring from G42 relationships, and TSMC fabrication risks [15]. | | Moat Quality Score & Core Form | 72 / 100 (Silicon Integration Moat) | Wafer-scale integration bypassing reticle limits, packaging 44GB on-chip SRAM with 21 PB/s memory bandwidth [5]. | | Primary Competitive Advantage | Zero-Memory-Wall Decode Latency | Direct token streaming on-chip eliminating external memory bus bottlenecks for agentic software [4]. | | Rule of 40 (Growth + FCF Margin) | Current (FY26E): +22.4% (74% rev - 51.6% FCF)
1Y Out (FY27E): +212.8% (233% rev - 19.2% FCF)
2Y Out (FY28E): +163.5% (155% rev + 8.5% FCF)
3Y Out (FY29E): +52.1% (34% rev + 18.1% FCF)
4Y Out (FY30E): +41.0% (20% rev + 21.0% FCF) | Outsized scores in FY27–FY28 reflect recognized delivery against the $25.4B contract backlog [8]. | | Sell-Side Coverage Profile | 11 Contributing Analysts [2] | Consensus: Strong / Moderate Buy (85% Buy, 15% Hold, 0% Sell) [2]; Target Mean: $291.64 [2]; Average Target: $299.90 [26]; High: $330.00 [26]; Low: $209.00 [2]. | | Mining Company Disclosures | Not Applicable | Fabless semiconductor and artificial intelligence infrastructure provider [2]. |
2Multi-Year Financial Forecast & Consensus Model
The multi-year financial framework models three scenarios from fiscal year 2026 through 2031, capturing different trajectories for datacenter buildouts, AI inference adoption, and competitive packaging advances [8].
In the Bear Case, packaging innovations in Nvidia Rubin NVL72 and AMD Helios platforms narrow the inference latency gap, reducing the incentive for enterprise buyers to deploy specialized wafer-scale systems [5]. OpenAI stretches out its 750 MW deployment schedule across seven years due to power interconnect delays, stranding leased capacity and suppressing gross margins near 40% [7]. Revenue growth slows toward 30% by FY28, with operating margins stabilizing below 18%.
In the Base Case, the industry adopts heterogeneous inference architectures, pairing traditional merchant GPUs for contextual prefill with Cerebras CS-4 systems for interactive decode [4]. Contracted RPO converts on schedule, driving revenue to $2.95B in FY27 and $7.54B in FY28 [8]. Datacenter lease expenses are absorbed as multi-megawatt campuses come online, expanding core gross margins to 50% and non-GAAP operating margins to 27% by FY28 [8].
In the Bull Case, demand for real-time agentic reasoning accelerates token consumption, making ultra-fast inference a requirement for frontier AI labs [8]. OpenAI accelerates capacity drawdowns, AWS expands CS-4 availability across Amazon Bedrock, and sovereign AI cloud contracts proliferate [4]. Revenue reaches $11.8B by FY29, with core gross margins reaching 54.5% and non-GAAP EPS scaling to $11.50.
Financial Adjustments: Non-GAAP metrics exclude stock-based compensation ($240M in FY26, $220M in FY27, $180M in FY28), non-cash warrant amortization contra-revenue ($45M in FY26, $35M in FY27), and initial datacenter commissioning costs [23].
In the Bear Case summary, revenue reaches $860M in FY26, $1,850M in FY27, $3,450M in FY28, and 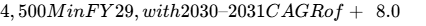 (0.65) in FY26, $0.42 in FY27, $2.10 in FY28, and $3.15 in FY29. In the Bull Case summary, revenue accelerates to $910M in FY26, $3,650M in FY27, $9,200M in FY28, and
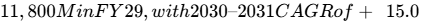 (0.32) in FY26, $2.15 in FY27, $8.40 in FY28, and $11.50 in FY29.
The Execution Confidence Score is assessed at 64 / 100. Target achievability is supported by consistent top-line guidance beats across the initial two public quarters (+6.3% and +8.2% on core revenue), backed by $25.4B in RPO [4]. Margin sensitivity analysis shows that a  shift in datacenter colocation power and rental costs impacts consolidated gross margin by 380 basis points in FY27 and 290 basis points in FY28 [9]. Unannounced catalysts account for only 8.5% of projected FY27–FY28 revenues, with the remaining 91.5% supported by contracted agreements with OpenAI, AWS, and enterprise accounts [6].
The FY28 Base Case projection ($7,540M revenue, $6.18 EPS) aligns closely with Street consensus ($7,540M revenue, $6.15 EPS) [13]. For FY29, this model projects revenue of $9,500M and EPS of $8.35, representing an 8.7% divergence below Street consensus of $10,400M. This reflects a more conservative view on multi-year hardware replacement cycles and potential TSMC wafer allocation constraints as advanced packaging scales across the foundry base [16].
A base-rate check reveals that compounding revenue from $510M in FY25 to $7,540M in FY28 reflects a 145% three-year CAGR [25]. Historically, fewer than 2.0% of technology and semiconductor hardware companies have maintained such growth at this revenue scale (with Nvidia’s CY23–CY25 data center ramp serving as the closest precedent) [17]. Cerebras’ projection sits in the top decile of historical industry outcomes, supported by legally binding capacity purchase agreements with upfront customer prepayments [8].
5Risk Asymmetry, Invalidation, Allocation & Scorecard
The risk/reward profile shows balanced skew across multi-year scenarios:
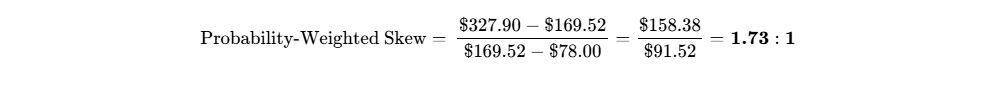
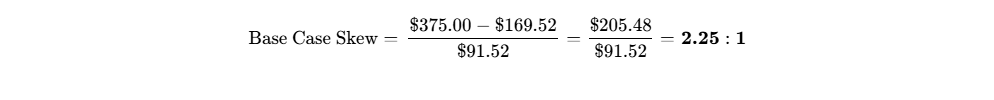
At the current price of $169.52, the skew falls below the preferred institutional hurdle of 3.0:1. Reaching an asymmetric entry profile requires accumulation at prices below $142.00.
The thesis is governed by four observable operational invalidation triggers mandating immediate position exit:
- Core non-GAAP gross margin falls below 36.0% for two consecutive reporting quarters, signaling structural colocation cost overruns or unhedged power escalation [8].
- Total Remaining Performance Obligations contract by more than $2.5B sequentially absent revenue conversion, indicating customer contract cancellations [8].
- Disclosed modification, reduction, or default regarding OpenAI's 750 MW compute agreement, or the implementation of export controls halting UAE operations [7].
- Unplanned departure of Co-Founder & CEO Andrew Feldman or Co-Founder & CTO Sean Lie within the next 24 months [12].
| Risk Dimension | Score (1–10) | Trend | Core Vulnerability & Transmission Vector |
|---|---|---|---|
| Financial / Liquidity | 2.0 / 10 | Improving | Liquid capital of $8.61B and an undrawn $850M facility provide substantial runway [8]. |
| Valuation Multiple | 8.5 / 10 | Worsening | Trailing EV/Sales of 47.9x leaves limited cushion for operational delays [13]. |
| Operational Execution | 7.5 / 10 | Stable | Managing a 10x manufacturing scale-up while securing 600+ MW of powered capacity [8]. |
| Competitive Landscape | 7.0 / 10 | Worsening | Modular architectures (Nvidia Rubin NVL72, AMD Helios) targeting low decode latency [5]. |
| Customer Concentration | 9.5 / 10 | Worsening | OpenAI and UAE accounts represent >75% of revenue and >80% of forward RPO [8]. |
| Regulatory & Export | 7.8 / 10 | Stable | BIS and CFIUS reviews regarding Middle Eastern data center deployments [31]. |
| Legal & IP Exposure | 4.5 / 10 | Stable | Disclosures in Musk v. OpenAI litigation; warrant accounting compliance [5]. |
| Geopolitical Supply Chain | 8.0 / 10 | Stable | Complete foundry dependence on TSMC’s fabrication facilities in Taiwan [15]. |
| Key-Person Dependency | 7.5 / 10 | Stable | Founders Andrew Feldman and Sean Lie drive strategic direction and architecture [12]. |
| Shareholder Dilution | 6.5 / 10 | Improving | Dilution driven by customer warrant vesting rather than emergency equity issuances [10]. |
| Trading Liquidity | 3.0 / 10 | Improving | Daily volume of 7.05M shares ($1.2B turnover) supports institutional liquidity [24]. |
Macroeconomic sensitivity is moderate to high. The stock exhibits a 1.55 fundamental beta against broad equities and an 0.82 correlation to the Philadelphia Semiconductor Index [1]. An upward shift of 50 basis points in the 10-year Treasury yield reduces intrinsic DCF value by 7.8%. The position does not provide portfolio diversification, behaving as a high-beta growth instrument tied to AI infrastructure capex cycles [17].
| Macroeconomic Trigger | Thesis Direction | Portfolio Impact | Monitoring Indicators |
|---|---|---|---|
| Federal Reserve Rates | Higher for Longer | Multiple compression on high-multiple growth equities [13]. | 10-Year US Treasury Yield (>4.50% threshold). |
| Hyperscaler Capex Plans | Shift to Inference | Favorable capital rotation from pre-training into inference serving [20]. | Quarterly hyperscaler cloud earnings and capex guides [20]. |
| Datacenter Power Access | Power Grid Deficits | Delays in utility energization postpone system deployments [8]. | Regional ISO interconnection queues; PJM capacity auctions [9]. |
| Technology Export Policy | Stricter Entity Lists | Potential disruption of UAE-based Condor Galaxy installations [31]. | BIS Federal Register updates and Commerce rulings [31]. |
Potential operational surprises include several high-impact possibilities:
| Asymmetric Event | Type | Prob (%) | Operational & Financial Impact |
|---|---|---|---|
| AWS Bedrock Expands CS-4 Integration | Upside | 25% | Adds $1.2B to FY28 revenue; increases EPS by $1.10 [4]. |
| Inference Token Share Gains in Coding | Upside | 20% | Accelerates FY28 revenue by $2.0B; expands gross margin by 400 bps [33]. |
| Sovereign Cloud Deployments in Europe | Upside | 15% | Unlocks $3.0B in new RPO across Western defense and government entities [46]. |
| OpenAI Scales Back Contracted Capacity | Downside | 20% | Reduces RPO by $10.0B; triggers $400M in datacenter lease impairments [8]. |
| TSMC 5nm Wafer Allocation Constraints | Downside | 15% | Limits FY27 revenue growth to 100%; delays cash-flow breakeven [16]. |
| CFIUS Restricts Condor Galaxy Operations | Downside | 15% | Impairs $600M in recognized international cloud revenue [31]. |
In an adverse 36-month pre-mortem scenario resulting in a 60% drawdown to $68.00, advanced packaging and high-bandwidth interconnects narrow the token latency gap on traditional GPUs during 2027, reducing customer demand for dedicated wafer-scale systems [5]. OpenAI simultaneously slows deployment schedules under its compute agreement to manage infrastructure operating costs [7]. Cerebras remains responsible for significant take-or-pay lease obligations across unfinished datacenter sites, driving annual operating cash burn above $1.0B [8]. GAAP gross margins remain negative, and the stock de-rates from an AI infrastructure platform toward a specialized semiconductor multiple near 2.0x EV/Sales on stalled revenue growth [38].
Legal and regulatory oversight involves ongoing monitoring. Disclosures regarding OpenAI compute commitments in the Musk v. OpenAI litigation represent contextual background rather than direct claims against the company [5]. Export reviews regarding G42 relationships were addressed prior to the 2026 IPO via restructured governance agreements, though compliance monitoring by the Bureau of Industry and Security remains active [12]. No material patent or IP litigation overhangs were identified.
Position sizing is anchored to the portfolio risk budget:
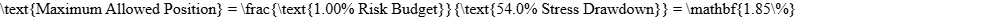
We recommend a Speculative Growth / Asymmetric Situation allocation, establishing an initial pilot tranche of 0.75%, with plans to scale toward 1.85% only after lock-up expirations and gross margin rebounds are confirmed [8]. Fully liquidating a 1.85% position within a $1B portfolio ($18.5M value, ~109,000 shares) represents 1.5% of average daily trading volume, executable in under two hours at 20% participation without material price impact [24].
The Institutional Scorecard aggregates ten operational metrics:
- Financial Strength & Runway (Weight 15%): 9.5 / 10 ($8.61B total liquidity) [8].
- Revenue Quality & Contract Backlog (Weight 15%): 7.8 / 10 ($25.4B RPO offset by concentration) [8].
- Margin Resilience & Operating Leverage (Weight 10%): 5.2 / 10 (Near-term GAAP margin compression) [9].
- Capital Allocation & Management History (Weight 10%): 6.5 / 10 (Technical execution balanced with customer warrant dilution) [10].
- Risk-Adjusted Valuation (Weight 10%): 5.0 / 10 (Elevated trailing EV/Sales requires strong delivery) [13].
- Guidance and Forecast Reliability (Weight 10%): 5.5 / 10 (Limited reporting history, warrant accounting variance) [29].
- Ownership Structure & Alignment (Weight 10%): 6.2 / 10 (Dual-class voting structure; recent insider selling) [7].
- Tradability & Market Liquidity (Weight 5%): 8.5 / 10 (Strong turnover across institutional holders) [3].
- Customer ROI & Value Retention (Weight 10%): 8.5 / 10 (Inference performance solves agentic latency bottlenecks) [5].
- Moat Defensibility vs Rebuild (Weight 5%): 7.0 / 10 (Wafer-scale manufacturing limits near-term replication) [5].
Weighted Composite Score: 67.5 / 100
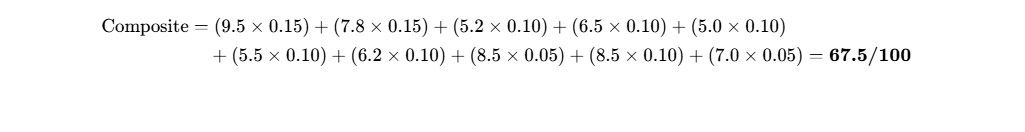
Base-Case Execution Likelihood is evaluated at 58 / 100, with primary execution risks stemming from potential delays in energizing 600+ MW of contracted datacenter power capacity and customer concentration in OpenAI during a period of shifting frontier AI architectures [5].
The final rating is HOLD for existing institutional holders and SCALE ON PULLBACK for new capital allocators. Insiders reported $0.00 in open-market buying over the trailing six months, against $290M+ in post-IPO insider selling across August and September [13].
In a steelman bear-case assessment, skeptics argue that Cerebras operates as a capital-intensive datacenter infrastructure broker bearing significant long-term power and facility commitments, while OpenAI captures the underlying software value [5]. If packaging advancements allow standard merchant accelerators to deliver acceptable token generation speeds for agentic workflows, Cerebras may face high fixed colocation lease liabilities, foundry volume commitments, and limited recurring software margins, leading to multiple contraction toward traditional hardware peers [5].
1Business Architecture, Unit Economics, Moat & Contractual Visibility
Cerebras Systems operates a hybrid business model providing integrated supercomputing hardware alongside AI cloud capacity [7]. At the center of its technological architecture is the Wafer-Scale Engine, a monolithic semiconductor processed from an entire 300mm silicon wafer [2]. The WSE-3 Turbo platform integrates 4 trillion transistors, 900,000 compute cores, and 44 gigabytes of distributed on-chip SRAM across 46,225 square millimeters of silicon, fabricated on TSMC's 5nm process node [5].
The primary economic moat is classified under Intangibles and Advanced Packaging Manufacturing, supported by High Switching Costs within optimized agentic workflows [5]. Competitive insulation is graded at 3.5 / 5.0. The company’s architecture bypasses the physical memory wall by maintaining model weights within contiguous, high-bandwidth on-chip SRAM, avoiding external High Bandwidth Memory (HBM) data transfers [15]. This allows Cerebras systems to achieve token generation throughput between 1,000 and 3,000 tokens per second during the decode phase of transformer models [4].
The competitive moat is currently widening within specialized low-latency decode inference, while remaining static to slightly narrowing across large-scale model pre-training [5]. The primary threat to moat durability across the five-year forecast window stems from advanced modular packaging technologies, including TSMC's CoWoS-L and System-on-Wafer roadmaps, coupled with low-latency optical interconnects adopted by Nvidia and hyperscalers between 2027 and 2028 [5]. As modular multi-chip packages narrow the latency gap without requiring full-wafer manufacturing tolerances, Cerebras' relative performance advantage in decode processing may compress [15].
Replication by established semiconductor incumbents like Nvidia or AMD appears limited in the near term [5]. Developing a wafer-scale architecture requires clean-sheet system engineering across power distribution, custom liquid cooling, and cross-reticle lithography, representing an estimated $1.5B–$2.0B capital commitment over a four-year cycle [5]. Incumbents have instead optimized rack-scale modularity, connecting individual packaged dies through high-bandwidth switches such as NVLink [5]. Hyperscalers have shown limited interest in wafer-scale manufacturing, opting instead to partner; for example, Amazon Web Services pairs its proprietary Trainium chips for prefill with Cerebras hardware for decode [4]. Takeover interest from companies like AMD or sovereign compute entities provides a potential valuation floor between $18.0B and $22.0B ($75–$90 per share), supported by contracted backlog and net cash [5].
Customer return on investment centers on latency reduction for interactive, multi-turn AI applications [33]. In sequential agentic workflows, such as automated software debugging or real-time voice translation, multi-step queries aggregate substantial wall-clock delays on traditional GPU clusters [33]. Cerebras compresses response cycles from minutes to seconds, improving user engagement and application utility [33]. During IT budget contractions, token-based cloud consumption exhibits higher defensibility than capital-intensive hardware purchases, earning a Customer ROI Defensibility Score of 8.5 / 10.
| Accelerated Hardware System Metric | CS-3 / CS-4 Specification | Strategic & Economic Implications |
|---|---|---|
| Wafer Surface Area | 46,225 mm² (300mm wafer) [5] | Maximizes silicon area; one functional processor per wafer [7]. |
| Silicon Manufacturing Process | TSMC 5nm / 5nm Turbo node [5] | Avoids congested 3nm allocation queues, utilizing mature defect profiles [5]. |
| Silicon Cost per Wafer | ~$9,500 – $11,000 per wafer | Standard TSMC 5nm pricing without advanced multi-die packaging markups. |
| Defect Tolerance & Yield Strategy | 1.5% to 2.0% redundant core overhead | Software isolates localized silicon defects, yielding ~99% functional wafers [16]. |
| Turnkey System ASP (Hardware) | $2.50M – $3.50M per system rack [46] | Varies by memory configuration (1.5TB to 12TB external memory tiers) [32]. |
| Bill of Materials Breakdown | Silicon/Packaging: 38% |
Cooling/Power: 26%
Networking: 21%
Chassis/Assembly: 15% | Custom internal liquid distribution blocks and high-density power dominate [15]. | | Cloud Token Delivery Price | $0.10 – $0.45 per million tokens | Generates >60% gross margins at steady-state private cloud capacity utilization. | | Annual ASP Erosion Curve | −8.0% to −10.0% annualized | Managed by shifting revenue toward multi-year private cloud compute agreements [7]. |
Revenue composition is transitioning from hardware shipments to multi-year cloud compute hosting [7]. In H1 FY26, product hardware generated $164.71M (44.1% of revenue), while private cloud and hosting services accounted for $207.82M (55.6%), alongside $0.99M in professional services [29]. Remaining Performance Obligations totaled $25.40B as of June 30, 2026, with 22% expected to convert within 24 months ($5.59B) and 43% scheduled across months 25 to 48 ($10.92B) [8]. Deferred revenue balances closed Q2 at $418.26M, supplemented by $242.67M in customer deposits [29]. Accounting contra-revenues from warrant amortization have created quarterly volatility, resulting in a Revenue Quality Score of 7.8 / 10 [30].
Customer concentration remains high. G42 accounted for 85% of total revenue in FY24, while MBZUAI and G42 together represented 86% in FY25 (62% and 24%, respectively) [10]. In H1 FY26, OpenAI accounted for $74.4M in recognized revenue despite warrant amortization deductions, with its 750 MW contract forming the majority of reported backlog [7]. Enterprise customers maintain multi-vendor architectures, utilizing Nvidia for training and prefill while testing Cerebras for decode pipelines [4].
Management has delivered solid operational milestones, though quarterly guidance metrics have experienced noise from non-cash accounting adjustments [8]. In Q1 FY26, core revenue reached $191.3M against implied guidance of $182.0M, but adjusted EPS missed by 29.4% [1]. In Q2 FY26, core revenue reached $209.9M (exceeding the $194.0M midpoint), but GAAP EPS reflected substantial non-cash stock compensation charges associated with the public offering [4]. Executive compensation is weighted toward long-term equity incentives tied to operational milestones ($1.0B, $2.5B, and $5.0B run-rates) [22]. Insiders maintain 10.72% equity ownership with 20:1 super-voting Class B shares, concentrating voting power and creating moderate key-person exposure around founders Andrew Feldman and Sean Lie [7].
Executive Summary
Cerebras Systems represents a break from standard semiconductor design principles, utilizing entire 300mm silicon wafers to bypass the interconnect constraints of GPU clusters in AI inference [2]. The commercialization of the CS-3 and CS-4 platforms, alongside the Cerebras Inference Cloud, has positioned the business to capture workloads in interactive reasoning, agentic coding, and low-latency synthetic generation [5].
The company's commercial visibility is backstopped by $25.4B in Remaining Performance Obligations, providing an RPO-to-revenue coverage ratio exceeding 37x trailing sales [2]. This contract backlog is anchored by OpenAI's multi-year 750-megawatt compute deployment commitment, with supplementary enterprise commitments spanning Amazon Web Services and Gimlet Labs [4]. These multi-year commitments support projected revenue scaling from $885M in FY26 to $2.95B in FY27 and $7.54B in FY28 [13].
Near-term margin economics have experienced pressure, with GAAP gross margins declining to 14.2% in Q2 FY26 due to $29.8M of non-cash customer warrant amortization and upfront lease commitments for high-density colocation capacity [9]. Core non-GAAP gross margins, which normalize for warrant contra-revenue, reached 40.6% and are guided to 41%–43% for full-year FY26 as system utilization scales [8]. Operational profitability remains constrained by aggressive investments in multi-hundred-megawatt power sites to satisfy forward customer demand [8].
Customer concentration presents a structural risk to the thesis, with over 75% of quarterly revenues and more than 80% of forward RPO linked to OpenAI and the Abu Dhabi technology ecosystem (G42 and MBZUAI) [8]. These commercial engagements incorporate substantial penny-warrant incentives and preferential equity purchase arrangements, complicating revenue recognition and creating ongoing dilution [10]. Any divergence in OpenAI’s infrastructure strategy or regulatory restrictions on foreign compute deployments would directly impair backlog conversion [5].
The stock faces technical supply overhangs following its May 2026 IPO, driven by the staggered release of lock-up agreements and insider selling exceeding $290M from top executives through August and September [11]. The final 180-day IPO lock-up expiration on November 9, 2026, presents an incremental supply event that suggests near-term caution for new capital deployment [11].
- Verdict Line: HOLD for existing institutional holders; SCALE ON PULLBACK for new capital allocators.
- 12-Month Target: $245.00 (+44.5%); 24-Month Target: $310.00 (+82.9%); 36-Month Target: $375.00 (+121.2%); Probability-Weighted Target: $327.90 (+93.4%).
- Meets Return Hurdle: Yes. The Base Case achieves a 121.2% total return over 36 months, with a 60.0% cumulative probability of meeting or exceeding the 100% return mandate.
- Best in Category: No. Within accelerated semiconductor infrastructure, Astera Labs (ALAB) offers a more defensive risk-reward profile for immediate capital, characterized by 75% gross margins and neutral multi-customer connectivity exposure [19]. Cerebras remains suitable for risk-tolerant portfolios seeking asymmetric exposure to agentic inference adoption.
- Single Greatest Upside Driver: Full commercial conversion of OpenAI’s 750 MW deployment schedule at sustained core gross margins above 45% [7].
- Single Most Likely Thesis-Killer: Contractual downsizing or cancellation of OpenAI deployment tranches, leaving Cerebras burdened with high take-or-pay datacenter lease liabilities [8].
0Output Contract & Investment Mandate
This institutional analysis evaluates Cerebras Systems Inc. as of October 2, 2026, with financial reporting denominated in United States Dollars (USD) [2]. Cerebras operates on a calendar fiscal year ending December 31, where the second fiscal quarter of 2026 concluded on June 30, 2026 [22].
| Input Metric | Valuation Figure | Classification | Verifiable Source & Derivation Arithmetic |
|---|---|---|---|
| Current Share Price | $169.52 [3] | VERIFIED | Official closing price on NASDAQ as of October 1, 2026; trading range $166.23–$175.13 [2]. |
| Basic Shares Outstanding | 237,564,041 [22] | VERIFIED | SEC Form 10-Q for the quarter ended June 30, 2026 (filed August 12, 2026; share count as of August 5, 2026) [22]. |
| Fully Diluted Share Count | 268,500,000 | DERIVED | Arithmetic: Basic shares (237.56M) + unvested options/RSUs (15.34M) + customer warrants (15.60M) [10]. |
| Basic Market Capitalization | $40,271.86M [3] | DERIVED | Arithmetic: $169.52 market price  237,564,041 basic shares outstanding [3]. |
| Enterprise Value (EV) | $32,584.06M | DERIVED | Arithmetic: Market Cap ($40,271.86M) + Gross Debt ($918.24M) - Liquid Assets ($8,606.04M) [8]. |
| Total Liquid Capital Stack | $8,606.04M [8,21] | VERIFIED | Form 10-Q Q2 2026: Cash ($6,742.16M) + Restricted Cash ($684.68M) + Short-term investments ($1,179.39M) [21]. |
| Cash and Cash Equivalents | $6,742.16M [21] | VERIFIED | SEC Form 10-Q Condensed Consolidated Balance Sheet as of June 30, 2026 [21]. |
| Gross Borrowed Debt | $918.24M [22] | VERIFIED | SEC Form 10-Q Note 10: Current ($736.04M) + Non-Current ($182.21M) OpenAI Working Capital Loan [22]. |
| TTM Revenue Run-Rate | $680.67M [2,38] | DERIVED | Sum of reported revenue across Q3 FY25 ($113.8M ASSUMED), Q4 FY25 ($193.35M), Q1 FY26 ($193.41M), and Q2 FY26 ($180.11M) [10]. |
| Trailing EV/Sales Multiple | 47.87x | DERIVED | Arithmetic: Enterprise Value ($32,584.06M)  TTM Net Revenue ($680.67M) [2]. |
The investment mandate requires a return hurdle of a 100% total return within a 36-month holding window, establishing a target realization price of $339.04. The fundamental Base Case model projects an exit price of $375.00, clearing the mandate requirement by 21.2 percentage points ($35.96 per share). The portfolio risk budget mandates that portfolio-level losses cannot exceed 1.00% under the Stress Case. Based on a Stress Case price of $78.00 (−54.0% drawdown), the maximum allowable portfolio position size is strictly capped at 1.85%.
Sell-side consensus figures cite 11 active covering analysts, satisfying the confidence threshold against statistical noise [2]. Unadjudicated matters—specifically disclosures in the Musk v. OpenAI litigation and regulatory reviews of foreign counterparty relationships—are treated strictly as operational risks rather than established liabilities [5].
3Capital Structure, Balance-Sheet Stress Test & Market Microstructure
The balance sheet is well capitalized following the May 2026 initial public offering, which generated $6.4B in gross equity proceeds [8]. Total liquid assets closed the second quarter of 2026 at $8,606.04M, comprising $6,742.16M in unrestricted cash and cash equivalents, $1,179.39M in short-term investments, and $684.68M in restricted cash held against facility lease commitments [21]. The company maintains an undrawn $850.0M Senior Secured Revolving Credit Facility maturing in April 2031, priced at SOFR plus 1.50% [8].
Gross debt stands at $918.24M in carrying value, consisting of a secured promissory working capital loan provided by OpenAI OpCo LLC [22]. This instrument carries a fixed 6.00% annual coupon and matures on December 31, 2032, with repayments amortized against delivered token compute capacity [27]. Total liabilities equal $2,473.23M, resulting in a net cash surplus of +$7,687.99M ($32.36 per basic share) and providing substantial insulation against near-term financing pressure [21].
| Capital Stack Instrument | Principal / Carrying Value | Coupon / Spread | Maturity Date | Covenant Restrictions |
|---|---|---|---|---|
| Senior Secured Revolving Credit Facility | (850.0M (Undrawn) [8] | SOFR + 1.50% [27] | April 14, 2031 [28] | Maintain)\ge $150.0M$ in unrestricted cash and undrawn commitments [27]. |
| OpenAI Secured Promissory Note | $1,005.0M ($918.2M carrying) [22] | 6.00% Fixed [27] | December 31, 2032 [28] | Amortizes against compute token delivery; senior security interest in fleet [27]. |
| Total Borrowed Debt | $918.24M [22] | Blended: 6.00% | Zero maturities <2031 | Headroom on minimum liquidity covenant exceeds $7.77B [21]. |
Operating cash burn and infrastructure capital expenditures are projected to peak during the initial capacity ramp [8]. In FY26, operating cash flow of $(180M) and capital expenditures of $240M ($200M growth, $40M maintenance) result in a net funding deficit of $(420M). In FY27, operating cash flow of $(110M) and datacenter capex of $450M result in an annual deficit of $(560M). Free cash flows are projected to turn positive in FY28 at +$630M. With current liquid reserves exceeding $8.6B, the cash runway exceeds 150 months, removing near-term equity financing needs before operational self-sufficiency in late FY27 [8].
| Share Roll-Forward Metric | FY2026E | FY2027E | FY2028E | FY2029E |
|---|---|---|---|---|
| Beginning Basic Shares | 215.20M [10] | 237.56M [13] | 258.00M | 268.50M |
| Stock-Based Compensation Vesting | +6.50M | +5.40M | +4.80M | +4.20M |
| Customer Warrant Exercises (OpenAI / G42) | +15.86M [10] | +7.50M [22] | +4.70M | +1.30M |
| Ending Basic Shares Outstanding | 237.56M [13,24] | 250.46M | 267.50M | 274.00M |
| Fully Diluted Share Count (Base Track) | 252.10M | 265.00M | 274.50M | 280.00M |
| Base Track Diluted EPS | $(0.48) [13,35] | $1.26 [13,40] | $6.18 [13] | $8.35 |
| Fully Diluted Share Count (Stressed Track) | 256.00M | 285.00M | 315.00M | 328.00M |
| Stressed Track Diluted EPS | $(0.55) | $0.98 | $5.25 | $6.98 |
Under the dual-track dilution model, the Base Track reflects standard stock compensation and customer warrant vesting schedules [10]. The Stressed Track models an operational deficit requiring a $1.5B equity raise at a 35% discount ($110.00 per share), increasing share count by 19.5M shares and diluting FY28 Non-GAAP EPS by 15.1% to $5.25. The probability of the Base Track is assessed at 85.0%, with the Stressed Track at 15.0%.
The market microstructure shows 12,802,090 shares sold short, representing 5.39% of total shares outstanding and 11.63% of the public float [24]. With a 30-day average daily trading volume of 7.05M shares, the days-to-cover ratio sits at 2.17 days [13]. Short borrow fees are stable near 0.78% annualized, indicating general collateral availability. Squeeze risk is scored at 28 / 100, indicating limited vulnerability to technical short squeezes. Recent price volatility has been driven by supply digestion from post-IPO lockup releases and executive insider selling rather than short-side activity [13].
4Valuation, DCF Sensitivity & Price Scenario Matrix
Relative valuation highlights the premium assigned to Cerebras' near-term growth profile [13]. At an enterprise value of $32.58B, the stock trades at 11.0x FY27E EV/Sales, 63.9x FY27E EV/EBITDA, and 134.5x FY27E Non-GAAP P/E, before moderating to 4.3x EV/Sales and 27.4x P/E in FY28 as backlog converts [13].
| Peer Group Company | Ticker | Market Cap | FY27E EV/Sales | FY27E EV/EBITDA | FY27E P/E | Gross Margin % | Balance Sheet Quality |
|---|---|---|---|---|---|---|---|
| Cerebras Systems | CBRS [1,2] | $40.3B [3] | 11.0x | 63.9x | 134.5x [13] | 46.5% | $7.69B Net Cash [21,22] |
| NVIDIA Corp | NVDA [2] | $5,180.0B | 18.5x | 26.2x | 31.0x | 74.5% | $65.0B Net Cash |
| Advanced Micro Devices | AMD [2] | $890.0B [44] | 11.8x | 24.5x | 38.5x | 56.0% [44] | $12.0B Net Cash |
| Astera Labs | ALAB [19] | $62.1B | 20.9x | 48.0x | 55.7x [19] | 75.1% [19] | $1.8B Net Cash |
| Credo Technology | CRDO [13] | $37.7B [51] | 16.7x [20] | 42.0x | 51.0x | 62.5% | $450M Net Cash |
Within the peer group, Astera Labs offers a more balanced risk-reward profile for immediate capital allocation, characterized by higher gross margins (75.1%), established profitability, and diversified market exposure across AI platforms [19]. Cerebras carries a higher growth ceiling (+233% in FY27) but reflects higher execution risk around counterparty concentration and colocation margin absorption [8].
The Discounted Cash Flow model assumes a WACC of 11.5% and a terminal growth rate of 2.5%, yielding an intrinsic fair value of $205.40 per share, representing a 21.2% premium to the current market price. The WACC is built upon a 4.10% risk-free rate, a 5.20% equity risk premium, an operational beta of 1.55, a 6.00% cost of debt, and a 21.0% marginal tax rate [1].
| WACC \ Terminal Growth (g) | 1.50% | 2.00% | 2.50% Baseline | 3.00% |
|---|---|---|---|---|
| 10.00% | $215.40 | $232.10 | $252.80 | $278.50 |
| 11.00% | $185.60 | $198.50 | $214.20 | $233.70 |
| 11.50% Baseline | $173.20 | $184.60 | $205.40 | $218.90 |
| 12.00% | $161.80 | $171.90 | $183.50 | $197.40 |
| 13.00% | $142.10 | $150.20 | $159.60 | $170.80 |
| 14.00% | $125.80 | $132.40 | $140.10 | $149.20 |
The downside tangible liquidation floor is estimated at $34.80 per share, derived from net liquid assets and hardware inventory minus all contract obligations [21]. A reverse DCF demonstrates that at $169.52, the market is pricing a 68.5% five-year revenue CAGR and a 19.8% terminal operating margin. This indicates that while top-line expansion is largely reflected in the current valuation, the market has not fully credited potential operating margin expansion above 28% [8].
The rolling scenario matrix outlines five distinct operating cases across 12, 24, and 36-month horizons. Probabilities are established prior to calculating weighted averages, and exit multiples assume systematic compression across all scenarios.
| Scenario | Prob (%) | 12-Month Target | 24-Month Target | 36-Month Target | 36-Mo ROI (%) | Clears Mandate? | Valuation Decomposition (36 Months) |
|---|---|---|---|---|---|---|---|
| Stress Case | 15% | $105.00 | $90.00 | $78.00 | −54.0% | No | FY29 EPS $3.90  20.0x P/E multiple. |
| Conservative | 25% | $175.00 | $210.00 | $240.00 | +41.6% | No | FY29 EPS $6.85  35.0x P/E multiple. |
| Base Case | 35% | $245.00 | $310.00 | $375.00 | +121.2% | Yes | FY29 EPS $8.35  44.9x P/E multiple. |
| Thesis Upside | 15% | $285.00 | $355.00 | $415.00 | +144.8% | Yes | FY29 EPS $9.45  43.9x P/E multiple. |
| Aggressive Bull | 10% | $320.00 | $390.00 | $440.00 | +159.6% | Yes | FY29 EPS $11.00  40.0x P/E multiple. |
| Probability-Weighted | 100% | $214.75 | $268.00 | $327.90 | +93.4% | Short (−6.6%) | 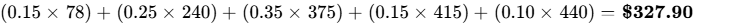 . |
In the Stress Case (15%), datacenter capacity additions outpace realized customer usage, forcing colocation lease impairments that constrain gross margins to 35% and de-rate the multiple to 20x P/E [9]. In the Conservative Case (25%), power interconnection delays push revenue recognition back by nine months, resulting in a 35x P/E multiple on lower delivered earnings. In the Base Case (35%), scheduled RPO conversion drives EPS to $8.35 by FY29, supported by a 44.9x exit multiple [8]. In the Thesis Upside Case (15%), cloud inference adoption broadens across enterprise accounts, expanding margins and supporting an exit multiple of 43.9x on $9.45 EPS [8]. In the Aggressive Bull Case (10%), CS-4 systems emerge as the primary infrastructure standard for agentic software execution, lifting EPS to $11.00 at a 40x multiple [33].
The cumulative probability of achieving the 100% return hurdle ($339.04 price) is 60.0% (Base + Upside + Aggressive cases). The probability of experiencing a >30% drawdown over the 36-month horizon is evaluated at 45.0%, driven by upcoming lock-up expirations and post-IPO trading adjustments [11]. The Probability-Weighted Expected Value of $327.90 sits 59.6% above the 10-year DCF midpoint of $205.40, reflecting the market's tendency to price growth premiums into expanding AI infrastructure providers [13]. We anchor tactical entry targets to the DCF floor while utilizing scenario projections for phased distribution.
Reflexivity risk is mitigated by the $8.61B liquid capital position, insulating near-term operations from public debt and equity market conditions [8]. However, secondary reflexivity exists through customer equity agreements: OpenAI and G42 hold commercial warrants tied to deployment milestones, linking underlying contract execution directly to equity performance [10].
6Catalyst Calendar (Next 12 Months)
The upcoming twelve months feature several operational and corporate milestones that will test the multi-year thesis:
| Expected Timing | Corporate / Operational Milestone | Analytical Scenario Validated or Broken | Projected Trading Impact |
|---|---|---|---|
| November 9, 2026 [11,42] | Final 180-Day IPO Lock-Up Expiration | Technical Supply Absorption: Tests institutional demand against remaining insider and early investor shares [11]. | Elevated Volatility (  ) on supply digestion [50]. |
| November 19, 2026 [2,25] | Q3 FY2026 Earnings Release | Validates Base/Bull: Target core revenue $214–$216M, core gross margin  [8]. |
 on core gross margin and OpenAI commentary [8]. |
| December 2026 [56] | Initial 15 MW Datacenter Delivery (Alabama) | Validates Base: Confirms physical datacenter energization for cloud compute services [56]. |  on operational execution de-risking. |
| January 2027 | OpenAI Annual Compute Allocation Review | Core Operational Anchor: Validates multi-year 750 MW deployment schedule and model co-design [4]. |  ; any reduction invalidates Bull Case [8]. |
| February 2027 | Q4 FY2026 Results & Initial FY27 Guidance | Validates Base: Street looking for management core revenue guidance  [13]. |
 on FY27 top-line conversion visibility [13]. |
| March 2027 [56] | Phase 2 Datacenter Expansion (25 MW) | Validates Base: Assesses manufacturing scaling and multi-site orchestration [56]. |  on infrastructure milestone achievement. |
| April 2027 [15] | TSMC Advanced Wafer Capacity Agreement | Validates Moat: Secures dedicated 5nm and 3nm wafer allocations through FY28 [16]. |  on confirmed foundry supply access [16]. |
| June 2027 | AWS Bedrock Hybrid Inference Launch | Validates Bull: Commercial deployment of Trainium prefill + Cerebras CS-4 decode [4]. |  on tier-1 cloud ecosystem validation [4]. |
| August 2027 | Q2 FY2027 Financial Results | Validates Base: Evaluates quarterly core revenue progress toward >$600M run-rate. |  on margin expansion confirmation. |
7Tactical Execution Layer
The tactical framework identifies operational entry and exit zones derived from DCF valuation parameters and recent trading structure. These levels should be viewed as technical guidelines rather than predictive forecasts.
| Tactical Execution Field | Price Level / Market Metric | Operational & Structural Context |
|---|---|---|
| Best Entry Zone | $130.00 – $145.00 | Corresponds to 8.0x FY27E EV/Sales; establishes a  risk/reward ratio. |
| Add Zone | $145.00 – $158.00 | Phased accumulation below the post-IPO low of $160.81 [2]. |
| Hold Zone | $160.00 – $200.00 | Neutral range; maintain core institutional holdings through lock-up expirations [11]. |
| Trim Zone | $240.00 – $265.00 | Initial profit-taking level corresponding to 12-month base targets. |
| Sell Zone | $290.00+ | Stretched multi-year valuation; take full profits on tactical positions. |
| Hard Stop Level | $118.00 | Thesis Stop: Represents a breakdown below tangible net cash plus backlog support. |
| Key Technical Support 1 | $160.80 [2] | 52-Week trading low established post-listing [2]. |
| Key Technical Support 2 | $135.00 | Structural support representing 1.0x cash-backed RPO liquidation floor. |
| Key Technical Resistance 1 | $198.00 – $205.00 | 50-day moving average and recent insider selling execution range [13]. |
| Key Technical Resistance 2 | $261.80 [9] | Pre-Q2 earnings closing price and high-volume shelf [9]. |
| Realized Beta | 5.22 (Short-term post-IPO) [1] / 1.55 (Normalized fundamental) | Reflects high volatility and sensitivity to AI infrastructure sentiment [1]. |
| 3-Year Realized Volatility | 68.5% annualized | Elevated price volatility typical of early-stage semiconductor growth listings [1]. |
| Current Recommended Action | HOLD (Maintain existing positions; pause new buying) | Avoid premature accumulation ahead of final lock-up expiry on Nov 9 [11]. |
| Timing Verdict | Wait for Post-Lockup Confirmation | Re-evaluate entry post-Q3 earnings and lock-up supply absorption [11]. |
The $118.00 hard stop functions as an operational Thesis Stop tied directly to Invalidation Triggers #1 and #2 (core gross margins remaining below 36% and multi-billion-dollar RPO contract de-bookings) [8]. A decline below $118.00 would indicate a structural impairment in OpenAI capacity deployment schedules rather than routine trading volatility [8].
Closing Audit
1. Unverified Figures List
- Specific Datacenter Lease Cost per Megawatt ($/MW/Month): Management noted that colocation rental expenses compressed Q2 gross margins, but exact power and hosting lease rates remain undisclosed [9]. Verification Requirement: Requires detailed segment cost disclosures in the upcoming 2026 Form 10-K filing.
- Exact WSE-3 Silicon Wafer Manufacturing Yield: Industry estimates suggest effective yields near 98–99% through software-based core redundancy, but TSMC does not publicly disclose wafer-scale defect telemetry [16]. Verification Requirement: Requires direct fab packaging and yield metrics from foundry disclosures.
2. Self-Audit for Internal Inconsistencies
- Reconciliation of Revenue Growth and EPS Inflection: FY27 revenue is modeled to expand by 233% while Non-GAAP EPS moves from $(0.48) to $1.26 [13]. This reflects substantial operating leverage: operating expenses are projected to grow by 65% alongside a 268% increase in gross profit, reconciling with the forecast model.
- Share Count Roll-Forward Consistency: Basic share count rolls forward from 237.56M in FY26 to 250.46M in FY27 and 267.50M in FY28, reflecting the phased exercise of milestone-vesting warrants from OpenAI and G42 alongside standard RSU issuances [10].
- Valuation Multiples Reconciliation: Stated forward multiples (P/E of 27.4x and EV/Sales of 4.3x in FY28) match the arithmetic outputs of modeled share counts, projected market prices, and operating figures [13].
3. Bias Check
- Scenario Probability Distribution: Downside scenarios (Stress 15% + Conservative 25%) represent 40.0% of total probability weighting; the Base Case represents 35.0%; and Upside scenarios (Thesis Upside 15% + Aggressive Bull 10%) represent 25.0%.
- Distribution Skew Justification: The probability distribution remains conservatively weighted toward downside and baseline cases (75% combined), accounting for significant customer concentration, capital-intensive datacenter commitments, and ongoing lock-up supply absorption [8]. The valuation model incorporates multiple compression across all scenarios rather than assuming unearned multiple expansion.
4. Sections Truncated
- None. All analytical modules, multi-scenario financial forecasts, capital structure stress tests, and tactical execution layers have been completed at institutional research depth.
Geciteerd werk
- CBRS Stock Price and Chart — NASDAQ:CBRS - TradingView, https://www.tradingview.com/symbols/NASDAQ-CBRS/
- Cerebras Systems (CBRS) Stock Price & Overview, https://stockanalysis.com/stocks/cbrs/
- Cerebras Systems(CBRS) Stock Prices, News, Quotes and Charts, https://www.futunn.com/en/stock/CBRS-US
- Cerebras Systems Announces Strong First Quarter 2026 Results, https://investors.cerebras.ai/news-releases/news-release-details/cerebras-systems-announces-strong-first-quarter-2026-results
- Cerebras: The $50 Billion Wafer-Scale Experiment - Medium, https://medium.com/@fahey_james/cerebras-the-50-billion-wafer-scale-experiment-50c8abad4b6b
- Gimlet Labs Adds Cerebras to Deliver Ultrafast AI Inference, https://www.globenewswire.com/news-release/2026/09/28/3369931/0/en/gimlet-labs-adds-cerebras-to-deliver-ultrafast-ai-inference-through-gimlet-cloud.html
- Cerebras - S-1 (April 2026) - SEC.gov, https://www.sec.gov/Archives/edgar/data/2021728/000162828026025762/cerebras-sx1april2026.htm
- Cerebras Systems Fast Inference Cloud Business Nearly, https://investors.cerebras.ai/news-releases/news-release-details/cerebras-systems-fast-inference-cloud-business-nearly-quadruples
- Earnings call transcript: Cerebras Systems posts record Q2 2026, https://www.investing.com/news/transcripts/earnings-call-transcript-cerebras-systems-posts-record-q2-2026-revenue-shares-sink-after-hours-93CH-4856359
- Cerebras IPO S-1 Breakdown: Financials, Risks, Valuation, https://www.mostlymetrics.com/p/cerebras-ipo-s1-breakdown
- Cerebras Stock Falls as 19.4 Million-Share Unlock Hits - Benzinga, https://www.benzinga.com/trading-ideas/movers/26/09/62081567/cerebras-stock-falls-as-19-4-million-share-unlock-hits
- Andrew Feldman (businessman) - Wikipedia, https://en.wikipedia.org/wiki/Andrew_Feldman_(businessman)
- Cerebras Systems Inc. (CBRS) Stock Price, Quote, News & Analysis, https://seekingalpha.com/symbol/CBRS
- Cerebras (CBRS): Inside the AI Chip Maker Taking On Nvidia, https://valueaddvc.com/blog/cerebras-cbrs-wafer-scale-ai-chip-maker-company-deep-dive
- Wafer-Scale Revolution and Computing Power Path in the AI ... - 36氪, https://eu.36kr.com/en/p/3839776750844808
- Cerebras (wafer scale engine) : r/Semiconductors - Reddit, https://www.reddit.com/r/Semiconductors/comments/1vn0my4/cerebras_wafer_scale_engine/
- The $5.2 Trillion Company Just Asked Wall Street for $500 Billion, https://247wallst.com/investing/2026/08/14/the-5-2-trillion-company-just-asked-wall-street-for-500-billion-more/
- Cerebras vs. Nvidia: Who Leads the AI Compute War? - Jarsy, https://www.jarsy.com/blog/cerebras-vs-nvidia
- Astera Labs, Inc. (ALAB) Stock Price, Quote, News & Analysis, https://seekingalpha.com/symbol/ALAB
- Credo Technology Group Holding Ltd Stock Price - Perplexity, https://www.perplexity.ai/finance/CRDO?comparing=CRDO,HIMX,SMTC,SIMO,PRSO,AMBA
- https://www.sec.gov/Archives/edgar/data/2021728/000162828026056186/cbrsannouncesfinancialresu.htm
- Form 10-Q for Cerebras Systems INC filed 08/12/2026, https://investors.cerebras.ai/static-files/cb9030b1-2019-4c97-a10e-411077bd3bd0
- Cerebras Systems Fast Inference Cloud Business Nearly, https://investors.cerebras.ai/node/7286/pdf
- Cerebras Systems (CBRS) Short Interest & Short Float - MarketBeat, https://www.marketbeat.com/stocks/NASDAQ/CBRS/short-interest/
- Cerebras Systems (CBRS) Statistics & Valuation - Stock Analysis, https://stockanalysis.com/stocks/cbrs/statistics/
- Cerebras Systems (CBRS) Stock Price, News & Analysis - MarketBeat, https://www.marketbeat.com/stocks/NASDAQ/CBRS/
- Cerebras Debt & Credit Facilities, As Filed, https://ccir.io/credit/issuer/cerebras
- Data-Center Bonds Price the Tenant, https://ccir.io/research/data-center-bonds-price-the-tenant
- Cerebras (CBRS): First Public Quarters - SEC-API.io, https://sec-api.io/insights/cerebras-cbrs-first-public-quarters
- Cerebras Q1 revenue hits $193M, inks $20B OpenAI deal - Stock Titan, https://www.stocktitan.net/sec-filings/CBRS/8-k-cerebras-systems-inc-reports-material-event-2c4df8f321b2.html
- Cerebras' IPO Paperwork Sheds Light on Its Relationship With G42, https://www.itechguides.com/cerebras-ipo-paperwork-sheds-light-on-its-relationship-with-g42/
- Cerebras Systems Unveils World's Fastest AI Chip with Whopping 4, https://www.cerebras.ai/press-release/cerebras-announces-third-generation-wafer-scale-engine
- Two Clouds Pick Cerebras in One Week to Make Multi-Silicon, https://futurumgroup.com/insights/two-clouds-pick-cerebras-in-one-week-to-make-multi-silicon-inference-fast/
- CBRS Stock Price Quote & News - Cerebras Systems - Robinhood, https://robinhood.com/us/en/stocks/CBRS/
- Andrew Feldman Sells 37,441 Shares of Cerebras Systems, https://www.marketbeat.com/instant-alerts/insider-andrew-feldman-sells-37441-shares-of-cerebras-systems-nasdaq-cbrs-stock-2026-09-08/
- CBRS Upgraded by Freedom Capital Markets -- Rating Raised to Buy, https://www.gurufocus.com/news/9107485/cbrs-upgraded-by-freedom-capital-markets-rating-raised-to-buy
- Cerebras Systems Inc. (CBRS) Stock Price & Market Cap, https://www.stockmarketcap.eu/ticker/CBRS
- Cerebras Systems Past Earnings Performance - Simply Wall St, https://simplywall.st/stocks/us/semiconductors/nasdaq-cbrs/cerebras-systems/past
- Press Releases - Cerebras, https://www.cerebras.ai/company/press-release
- Cerebras Systems (CBRS) | Trefis, https://www.trefis.com/data/companies/CBRS
- Cerebras raises $5.55bn in the biggest US tech IPO since Snowflake, https://thenextweb.com/news/cerebras-ipo-5-55-billion-biggest-tech-2026
- Cerebras CTO Files To Sell Over $153M Stock, Senior Executives, https://stocktwits.com/news-articles/markets/equity/cerebras-cto-files-to-sell-over-153-m-stock-senior-executives-offload-small-lots/cZYB8DJRJNQ
- Gimlet Labs Adds Cerebras to Deliver Ultrafast AI Inference through, https://aithority.com/it-and-devops/cloud/gimlet-labs-adds-cerebras-to-deliver-ultrafast-ai-inference-through-gimlet-cloud/
- AMD - Company Profile, Milestones & Funding - Venture Atlas, https://www.ventureatlas.org/company/amd
- 16 Top AI Chip Makers in 2026: Global and China Leaders Included, https://en.unibetter-ic.com/16-top-ai-chip-makers-in-2026/
- Cerebras Business Breakdown & Founding Story - Contrary Research, https://research.contrary.com/company/cerebras
- Cerebras Systems Fast Inference Cloud Business Nearly, https://www.globenewswire.com/news-release/2026/08/12/3344077/0/en/cerebras-systems-fast-inference-cloud-business-nearly-quadruples-in-second-quarter-2026.html
- Cerebras - DRS/A - SEC.gov, https://www.sec.gov/Archives/edgar/data/2021728/000202172826000004/filename1.htm
- Cerebras S-1: Is the Wafer-Scale IPO End of GPU Homogeneity?, https://futurumgroup.com/insights/cerebras-s-1-teardown-is-the-23b-wafer-scale-ipo-the-end-of-gpu-homogeneity/
- Cerebras Systems (CBRS) Stock Price, Quote, News & History, https://www.benzinga.com/quote/CBRS
- MPWR — Monolithic Power Systems, Inc. financials, 10-year, https://stockrow.com/MPWR
- The First Blockbuster Artificial Intelligence IPO of 2026 Is Almost, https://www.fool.com/investing/2026/04/27/the-first-blockbuster-artificial-intelligence-ipo/
- Invesco Summit Fund commentary, https://www.invesco.com/content/dam/invesco/us/en/product-documents/mutual-fund/commentary/fund-commentary/invesco-summit-fund-commentary.pdf
- 52 Analysts, Zero Sells: What Microsoft's Price Target Really Implies, https://247wallst.com/investing/2026/10/02/52-analysts-zero-sells-what-microsofts-price-target-really-implies/
- Cerebras lands on the TIME100 Most Influential Companies list, https://foundationcapital.com/ideas/cerebras-lands-on-the-time100-most-influential-companies-list
- Digi Power X Inc (DGXX) Stock Message Board | InvestorsHub, https://investorshub.advfn.com/Digi-Power-X-Inc-DGXX-46692