Company: Boost Run Inc. (NASDAQ: BRUN) [1]
Current Stock Price: $16.51 (Market close as of October 2, 2026) [1]
Research Date: October 5, 2026
Potential Stock Prices & Projected Returns:
- 12-Month Target: $23.40 (+41.7%)
- 24-Month Target: $37.70 (+128.3%)
- 36-Month Target: $50.00 (+202.8%)
- Probability-Weighted 36-Month Price: $46.87 (+183.9%) [3]
Institutional Scorecard Score: 67.5 / 100
Base-Case Execution Likelihood: 58 / 100
Analyst Recommendation: BUY (High-Conviction Tactical / Growth Compounder)
Brief Explanation of Recommendation: Boost Run provides asymmetric upside torque within the accelerated computing infrastructure ecosystem [4]. Following the completion of its de-SPAC business combination and the full redemption of public warrants, which injected $130.0M of gross cash into the balance sheet, the company's total unencumbered cash stands at $250.2M [3]. Backed by $1.9B in long-term Total Contract Value (TCV), an annualized exit recurring revenue run rate targeting ~$400M by year-end 2026, and elite NVIDIA Exemplar Cloud architecture certification, Boost Run is priced at an unwarranted post-merger discount relative to private and public peers [6]. Trading at 2.8x FY2027 enterprise value to sales, the market prices in substantial operational failure, creating an attractive entry point for growth capital [3].
Core Investment Metrics & Executive Statistics
2Multi-Year Financial Forecast & Consensus Model
The financial model projects performance across three distinct operating environments for fiscal years 2026 through 2031.
In the Bear Case, accelerated merchant silicon deliveries create industry-wide price competition, reducing spot pricing and causing an anchor customer to scale back commitments. Operating fleet utilization falls to 70%, and access to capital becomes restrictive, limiting revenue growth to $650.0M by 2031.
In the Base Case, Boost Run executes on its initial 20 MW capacity delivery in Q4 2026, achieves its guided exit ARR of ~$400M, and commissions the full 111 MW lease from 10X Capital over 2027 and 2028 [6]. Supported by Dell equipment financing, revenue expands to $1.35B by 2029 and $2.10B by 2031, with normalized net margins reaching mature cloud infrastructure levels [3].
In the Bull Case, sustained enterprise demand for generative AI inference outstrips hyperscaler availability. Boost Run scales accessible power to 400 MW, maintains utilization above 95%, and expands Blackwell cluster deployments, driving revenues to $3.25B and diluted EPS to $6.75 by 2031 [15].
Fiscal year 2026 anchors to company guidance and consensus estimates [6]. Fiscal year 2027 incorporates prevailing Street projections, while fiscal years 2028 through 2031 represent analytical extrapolations based on contract conversions and datacenter capacity additions [16].
Base Case Multi-Year Financial Forecast
| Metric ($M, except per share data) | FY2026E | FY2027E | FY2028E | FY2029E | FY2030E | FY2031E | 2029–31 CAGR |
|---|---|---|---|---|---|---|---|
| GPU Cloud Infrastructure Revenue | $170.6 | $515.0 | $905.0 | $1,330.0 | $1,725.0 | $2,075.0 | +24.9% |
| Professional AI & Managed Services | $4.4 | $10.0 | $15.0 | $20.0 | $25.0 | $25.0 | +11.8% |
| Total Net Revenue | $175.0 | $525.0 | $920.0 | $1,350.0 | $1,750.0 | $2,100.0 | +24.7% |
| YoY Organic Revenue Growth (%) | +550.8% | +200.0% | +75.2% | +46.7% | +29.6% | +20.0% | — |
| Cost of Revenue (Colocation & Power) | $31.5 | $105.0 | $202.4 | $317.3 | $437.5 | $567.0 | — |
| Gross Profit | $143.5 | $420.0 | $717.6 | $1,032.8 | $1,312.5 | $1,533.0 | — |
| Gross Margin (%) | 82.0% | 80.0% | 78.0% | 76.5% | 75.0% | 73.0% | — |
| Operating Expenses (SG&A, R&D, D&A) | $181.5 | $346.5 | $533.6 | $722.3 | $875.0 | $987.0 | — |
| Operating Income (EBIT) | -$38.0 | $73.5 | $184.0 | $310.5 | $437.5 | $546.0 | — |
| Operating Margin (%) | −21.7% | 14.0% | 20.0% | 23.0% | 25.0% | 26.0% | — |
| Depreciation & Amortization | $65.0 | $135.0 | $210.0 | $275.0 | $330.0 | $375.0 | — |
| EBITDA | $27.0 | $208.5 | $394.0 | $585.5 | $767.5 | $921.0 | — |
| EBITDA Margin (%) | 15.4% | 39.7% | 42.8% | 43.4% | 43.9% | 43.9% | — |
| GAAP Net Income (Loss) | -$65.0 | $45.0 | $128.0 | $225.0 | $322.0 | $408.0 | — |
| Fully Diluted Share Count (M) | 83.85 | 86.00 | 88.00 | 90.00 | 91.50 | 93.00 | — |
| Normalized Diluted EPS ($) | -$0.78 | $0.52 | $1.45 | $2.50 | $3.52 | $4.39 | +32.5% |
| Free Cash Flow ($M) | $30.0 | $90.0 | $180.0 | $290.0 | $390.0 | $490.0 | — |
| FCF per Share ($) | $0.36 | $1.05 | $2.05 | $3.22 | $4.26 | $5.27 | — |
| Rule of 40 (Growth% + FCF Margin%) | 567.9% | 217.1% | 94.8% | 68.2% | 51.9% | 43.3% | — |
| Forward P/E Multiple | — | 31.8x | 11.4x | 6.6x | 4.7x | 3.8x | — |
| Forward EV/EBITDA Multiple | 53.7x | 7.0x | 3.7x | 2.5x | 1.9x | 1.6x | — |
| Forward EV/Sales Multiple | 8.3x | 2.8x | 1.6x | 1.1x | 0.8x | 0.7x | — |
Non-GAAP Adjustments: FY2026 reported GAAP net income of -$98.0M is normalized to -$65.0M to remove the one-time $55.7M non-cash tax charge associated with the corporate conversion, offset by initial SPAC-related consulting expenses [7].
Multi-Scenario Revenue & EPS Progression
| Line Item / Scenario | FY2026E | FY2027E | FY2028E | FY2029E | FY2030E | FY2031E |
|---|---|---|---|---|---|---|
| Bear Case Revenue ($M) | $145.0 | $285.0 | $410.0 | $520.0 | $590.0 | $650.0 |
| Bear Case Diluted EPS ($) | -$1.25 | -$0.20 | $0.10 | $0.40 | $0.65 | $0.85 |
| Base Case Revenue ($M) | $175.0 | $525.0 | $920.0 | $1,350.0 | $1,750.0 | $2,100.0 |
| Base Case Diluted EPS ($) | -$0.78 | $0.52 | $1.45 | $2.50 | $3.52 | $4.39 |
| Bull Case Revenue ($M) | $210.0 | $680.0 | $1,250.0 | $1,900.0 | $2,550.0 | $3,250.0 |
| Bull Case Diluted EPS ($) | -$0.45 | $0.95 | $2.35 | $3.80 | $5.20 | $6.75 |
The Execution Confidence Score is established at 58 out of 100. Target achievability is supported by the $1.9B TCV backlog, though public reporting history remains limited [6]. Operating margin sensitivity is sensitive to hourly compute rental rates; a  change in realized GPU pricing impacts annual operating margin by
 basis points. Furthermore, approximately 28% of projected FY2028–2029 revenue depends on bringing new pipeline capacity online beyond the contracted 253 MW footprint [33].
Street consensus for FY2027 revenue stands at $550.9M, compared to the Base model estimate of $525.0M (−4.7% variance) [16]. For FY2028, the model projects revenue of $920.0M and EPS of $1.45, adopting a more conservative view than informal Street projections exceeding $1.1B [16]. This reflects an accelerated 4-year depreciation schedule ($210M in FY28) to account for rapid hardware iteration [12]. Across historical software and infrastructure de-SPAC transactions, fewer than 12% sustained a five-year revenue CAGR above 50%. Boost Run’s projection is supported by its contracted backlog, which covers roughly 70% of projected revenue through 2029 [6].
5Risk Asymmetry, Invalidation Triggers & Allocation
The risk/reward skew evaluates the upside of the probability-weighted target against the Stress scenario downside:
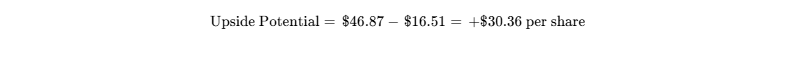
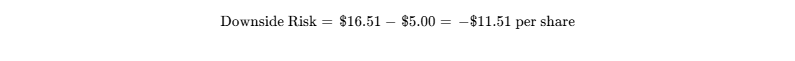
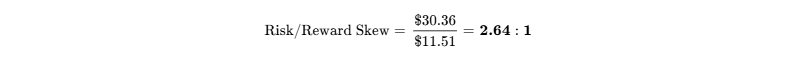
[3]
While slightly below the preferred 3.0:1 threshold due to de-SPAC volatility, the skew remains attractive for a growth infrastructure asset [3].
Operational & Financial Invalidation Triggers
- Contract Invalidation Trigger: Thinking Machines Lab or any anchor customer accounting for over 15% of TCV defaults or cancels take-or-pay commitments [31].
- Margin Invalidation Trigger: Consolidated GAAP Gross Margin falls below 65.0% for two consecutive quarters [24].
- Capacity Invalidation Trigger: Failure to energize the initial 20 MW capacity at the 10X Capital facility by March 31, 2027 [33].
- Liquidity Invalidation Trigger: Unrestricted cash reserves fall below $60.0M without project financing in place [6].
Comprehensive Institutional Risk Matrix
| Risk Dimension | Score (1–10) | Trend | Core Analytical Assessment |
|---|---|---|---|
| Financial Strength & Liquidity | 3.5 / 10 | Improving | Supported by $130M in warrant cash; debt maturities are manageable through 2027 [7]. |
| Valuation Risk | 3.0 / 10 | Improving | Trading at 2.8x FY27 sales; de-SPAC discount limits further downside [3]. |
| Operational Execution | 6.5 / 10 | Stable | Buildouts require maintaining sub-45 day deployment SLAs [5]. |
| Competitive Dynamics | 7.0 / 10 | Worsening | Hyperscaler capex acceleration and NeoCloud competition from CoreWeave [11]. |
| Customer Concentration | 7.5 / 10 | Stable | Thinking Machines Lab accounts for approximately 25% of backlog [7]. |
| Regulatory & Export | 4.0 / 10 | Stable | Subject to BIS hardware export controls and local utility power reviews. |
| Legal & Intellectual Property | 2.5 / 10 | Stable | No material legal proceedings or patent challenges identified [14]. |
| Key-Person Risk | 6.0 / 10 | Stable | Operational reliance on CEO Andrew Karos, who holds 90.2% voting power [13]. |
| Dilution Risk | 3.5 / 10 | Improving | Public warrants redeemed; routine SBC dilution modeled at ~2.4% annually [7]. |
| Tradability & Microstructure | 3.5 / 10 | Improving | Russell index inclusion improves trading volume and float liquidity [25]. |
Macro & Correlation Factors
The stock exhibits an equity beta of 1.85 and a 70.1% correlation to the technology sector (XLK), indicating high sensitivity to tech sentiment and duration risk [1].
The macro dashboard tracks key external indicators:
- 10-Year Treasury Yield: Yields above 4.75% compress growth multiples and raise equipment financing costs [7].
- Enterprise AI Software Capex: Sustained capital deployment by software firms supports GPU cluster rental demand [12].
- Power Utility Approval Cycles: Interconnection delays at regional utilities risk extending cluster deployment timelines [33].
- Merchant GPU Rental Rates: Declines in spot pricing would compress uncontracted inference margins [12].
Potential Market Surprises
| Event Description | Classification | Probability | Quantified Financial Impact |
|---|---|---|---|
| Hyperscaler Capacity Offtake Agreement | Upside | 25% | +$250M ARR; +$0.65 EPS accretion |
| Fast-Track Power Grid Interconnection (<90 Days) | Upside | 20% | +$80M FY27 revenue; +$0.20 EPS |
| Strategic Takeover Offer by Infrastructure Fund | Upside | 15% | Acquisition buyout at $30.00–$35.00/share |
| Thinking Machines Lab Contract Default | Downside | 15% | -$150M contracted ARR; -$0.45 EPS |
| Liquid-Cooling Facility Infrastructure Recall | Downside | 10% | 6-month energization delay; -$0.30 EPS |
| Secondary Insider Block Liquidation | Downside | 25% | Multiple compression; pressure on share price [7] |
Pre-Mortem: 36 Months Forward (−60% Loss)
The year is 2029, and BRUN is trading at $6.50. The downturn originated in early 2027 when complex liquid-cooling retrofits delayed the energization of the 111 MW 10X Capital capacity by seven months [32]. Concurrently, Thinking Machines Lab encountered funding hurdles and renegotiated its $471.7M contract downward by 45% [31]. Hardware oversupply across the sector drove market GPU rental prices down from $2.15 to $1.10 per hour, compressing gross margins from 80% to 54%. With debt service payments on equipment leases coming due and cash declining, the board approved an emergency $120M equity financing at $7.50 per share, heavily diluting shareholders and permanently impairing equity returns.
Portfolio Allocation & Position Sizing Calibration
- Recommended Role: Asymmetric Growth / High-Conviction Tactical.
- Risk Budget Math: With a Stress-case loss of −69.7% ($16.51 to $5.00), capping total portfolio-level loss at 1.00% requires:
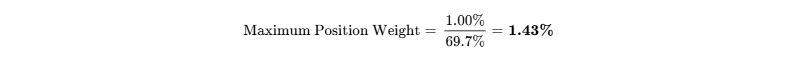
- Qualitative Reconciliation: The risk budget caps position size at 1.40%. An initial 0.70% pilot allocation is recommended, scaling to the 1.40% limit upon verification of Q3 capacity additions.
- Liquidity Check: Liquidating a 1.40% position in a $100M portfolio ($1.40M notional = ~84,800 shares) represents 4.3% of the average daily volume of 1.97M shares, enabling full liquidation within a single trading day at 20% ADV without meaningful market impact [36].
Institutional Quality Scorecard
| Scorecard Component | Category Weight | Component Score (0–10) | Weighted Points |
|---|---|---|---|
| Financial Strength & Liquidity Runway | 15% | 8.0 / 10 | 1.20 |
| Revenue Quality, Moat & Market Position | 15% | 6.5 / 10 | 0.98 |
| Margin Resilience & Operating Leverage | 10% | 7.0 / 10 | 0.70 |
| Capital Allocation & Management Record | 10% | 6.0 / 10 | 0.60 |
| Risk-Adjusted Valuation Attractiveness | 15% | 8.5 / 10 | 1.28 |
| Forecast Reliability (Beat/Miss History) | 10% | 5.0 / 10 | 0.50 |
| Ownership & Incentive Alignment | 10% | 6.5 / 10 | 0.65 |
| Public Liquidity & Market Tradability | 5% | 7.5 / 10 | 0.38 |
| Customer ROI Defensibility & Pricing | 5% | 7.5 / 10 | 0.38 |
| Moat Insulation against Build-vs-Buy | 5% | 6.0 / 10 | 0.30 |
| Total Composite Score | 100% | — | 67.5 / 100 |
- Base-Case Execution Likelihood: 58 / 100. The primary variables that could impede base-case delivery are utility grid interconnection timelines and anchor customer concentration [31].
Final Recommendation & Verdict
| Investor Type | Final Recommendation | 12-Mo Target | 24-Mo Target | 36-Mo Target | Prob-Weighted Target |
|---|---|---|---|---|---|
| New Capital Buyers | BUY | $23.40 | $37.70 | $50.00 | $46.87 [3] |
| Existing Holders | HOLD / ACCUMULATE | $23.40 | $37.70 | $50.00 | $46.87 [3] |
- Portfolio Fit Synthesis: Boost Run provides asymmetric upside within growth portfolios seeking exposure to the enterprise AI buildout. Its discounted multiple of 2.8x FY27 sales, supported by $250.2M in cash and a $1.9B contract backlog, offers attractive upside for institutional investors equipped to manage de-SPAC volatility [3].
- Insider Activity (Last 6 Months): No open-market insider purchases were recorded [17]. Director Sean Goodrich executed a single sale of 500,000 shares at $14.00 ($7.0M total) on September 14, 2026 [7].
- Bear-Case Steelman: Boost Run operates a capital-intensive datacenter business trading under the valuation narrative of a high-margin software cloud provider. The company does not own its datacenters; it leases facility space, takes on equipment lease obligations from OEMs, and subleases capacity to early-stage artificial intelligence laboratories [10]. If model training demand softens or custom hyperscaler silicon expands, market GPU rental rates will decline, squeezing margins against fixed lease obligations [22]. Customer defaults in a concentrated backlog would turn project cash flows negative, forcing equity raises and limiting multiple expansion [19].
1Business Architecture, Unit Economics, Moat & Contractual Visibility
Boost Run operates an enterprise-grade Infrastructure-as-a-Service model designed for deep learning, foundation model fine-tuning, and high-throughput inference [4]. By eliminating virtualization hypervisors and deploying directly onto bare-metal NVIDIA HGX platforms via vCluster orchestration, the architecture removes the 8% to 15% computational overhead common in legacy public clouds [5]. The company combines hardware sourcing, colocation datacenter leases, network optimization, and managed Kubernetes into multi-year compute contracts [5].
The core economic moat is classified under Efficient Scale and Intangibles, earning a competitive insulation score of 3.1 out of 5.0. Intangibles are supported by Boost Run’s status as an NVIDIA Exemplar Cloud Partner on the Blackwell architecture—a performance validation shared by a select group of cloud providers, including Oracle Cloud Infrastructure and CoreWeave [9]. This credential secures preferential hardware allocations during GPU supply cycles [10]. However, the economic moat is projected to remain static through 2027 before narrowing toward 2029 as hyperscalers scale proprietary ASICs and merchant silicon supply broadens across the sector.
A well-capitalized hyperscaler can replicate pure compute capacity but faces architectural trade-offs, as hypervisor clouds are built for shared tenancy rather than dedicated bare-metal clusters [5]. Replicating Boost Run's energized power footprint would require competitors to commit $2.0B or more in capital expenditure and navigate 18 to 24-month utility substation queues [33]. Customers building internal clusters face long lead times and high capital intensity, making outsourced infrastructure on 3-year take-or-pay leases more efficient [15]. Furthermore, Boost Run serves as an acquisition target for telecommunication conglomerates or sovereign AI investment vehicles, providing valuation support between $25.00 and $30.00 per share.
Customer ROI is quantifiable. Eliminating virtualization hypervisors generates $1.6M to $3.0M in annual run-rate efficiency for an enterprise spending $20M on AI compute, while reducing model training timelines by multiple weeks [5]. The defensibility of this customer ROI scores 7.5 out of 10. Multi-year contracts insulate the company against corporate IT budget freezes, as computing resources are provisioned on take-or-pay commitments [5].
The hardware and industrial unit economics reflect an active operational fleet of approximately 18,500 GPUs, scaling toward 42,000 GPUs by year-end 2027 as 111 MW of capacity from 10X Capital comes online [32]. Blended realized rental pricing averages $2.15 per GPU-hour across mixed Hopper and Blackwell systems [15]. Hardware procurement costs average approximately $310,000 per 8-GPU node, funded primarily through Dell Financial Services leases with 36 to 48-month terms [10]. Contracted fleet utilization stands at 93.5%, with excess capacity routed to spot-market inference workloads [12]. Annual pricing erosion is modeled at 12% for older Hopper inventory, balanced by premium pricing for newer Blackwell clusters [15].
Under ASC 842 lease accounting standards, 97.5% of trailing revenue is contractual and recurring, while legacy blockchain compute accounts for the remaining 2.5% [5]. The company holds $1.9B in total contract backlog with an average duration of 3.2 years, complemented by $128.4M in cash customer deposits [6]. Revenue quality scores 7.8 out of 10.
Customer concentration remains a key consideration: Thinking Machines Lab Inc. accounts for $471.7M in contracted TCV (24.8% of total backlog), and the top three customers represent roughly 58% of contracted commitments [7]. Management's operational execution is led by CEO Andrew Karos, whose voting control of 90.25% through Class B common stock concentrates corporate decision-making [13]. Insiders collectively hold 63.3% of outstanding shares [17]. While alignment with long-term equity growth is strong, the dual-class share structure limits minority shareholder representation [14].
Executive Summary
- Strategic Hardware Partnerships Enable Rapid Scale: Boost Run has established itself as an enterprise AI infrastructure provider by deploying high-density NVIDIA GPU clusters [4]. Its $1.44B strategic procurement agreement with Dell Technologies and Dell Financial Services provides access to hardware and back-to-back lease financing, eliminating equipment delivery bottlenecks and allowing cluster activation within 45 days [5].
- Substantial Contract Visibility Backed by $1.9B Backlog: The company holds $1.9B in long-term Total Contract Value across multi-year Master Service Agreements, including a $471.7M contract with Thinking Machines Lab Inc. [6]. Management reaffirmed full-year 2026 exit Annual Recurring Revenue (ARR) guidance of ~$400M, up from $145M in June 2026 and $30M at year-end 2025 [6].
- Capital Structure De-Risked Post-Warrant Redemption: The redemption of public warrants in August 2026 injected $130.0M of gross cash into the balance sheet, expanding total cash reserves to $250.2M [3]. Customer upfront cash deposits of $128.4M provide non-dilutive working capital that supports project-level capital expenditures [12].
- Steep Post-SPAC Sentiment Discount: Trading at 2.8x FY2027 enterprise value to sales, Boost Run trades at a notable discount to NeoCloud peers such as Nebius Group (8.8x) [3]. This discount stems from its recent de-SPAC transition, a Q2 GAAP net loss driven by a one-time non-cash $55.7M deferred tax establishment, and director insider selling [7]. As the company demonstrates positive operating cash flows and achieves net profitability in FY2027, fundamental multiple expansion should occur [3].
- Verdict Line: BUY | 12-Mo Target: $23.40 (+41.7%) | 24-Mo Target: $37.70 (+128.3%) | 36-Mo Target: $50.00 (+202.8%) | Probability-Weighted Target: $46.87 (+183.9%) [3].
- Hurdle Clearance: Clears the 36-month return mandate, with a 60.0% probability of achieving at least a 100% gain [3].
- Best in Category Assessment: For new capital seeking growth torque in the AI cloud sector, Boost Run offers the highest risk-adjusted multiple expansion potential [3]. For capital focused on downside protection, Nebius Group remains more defensive due to its larger net cash balance [11]. Existing holders should maintain positions and accumulate on dips; new buyers should initiate pilot tranches ahead of scheduled capacity energizations.
- Single Greatest Upside Driver: Accelerating customer energization across the 111 MW GPU capacity leased from 10X Capital, driving FY2027 ARR beyond $600M [32].
- Single Most Likely Thesis-Killer: Operational default or restructuring by Thinking Machines Lab paired with extensive regional utility substation delays [7].
0Output Contract & Investment Mandate
Reporting Parameters & Anchor Valuation Inputs
The analysis evaluates Boost Run Inc. as of October 5, 2026, using United States Dollars (USD) as the reporting currency. The company adheres to a standard fiscal year ending December 31, aligning with the calendar year [26].
Anchor inputs are tagged with their respective confidence tiers:
- Current Stock Price: $16.51. Confidence Tier: VERIFIED (NASDAQ official market close quote as of October 2, 2026) [1].
- Fully Diluted Share Count: 83.85M shares. Confidence Tier: DERIVED (Calculated from SEC filings: 31.90M basic Class A shares, 29.53M convertible Class B shares, 10.97M earned price-vested shares, 0.34M consulting shares, and 11.12M common shares issued upon warrant redemption) [7].
- Market Capitalization: $1,384.36M. Confidence Tier: DERIVED (
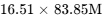 fully diluted shares) [3].
- Cash & Equivalents: $250.17M. Confidence Tier: DERIVED ($120.17M unrestricted cash as of June 30, 2026, plus $130.00M in gross cash proceeds generated from the completion of the warrant redemption on August 20, 2026) [6].
- Gross Funded Debt & Leases: $316.58M. Confidence Tier: VERIFIED ($78.48M in software term obligations and $238.10M in equipment finance leases reported in the Q2 2026 Form 10-Q; excludes $119.50M in operating datacenter leases) [22].
- Enterprise Value (EV):
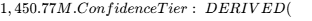 $1,384.36\text{M market cap} + $316.58\text{M gross debt} - $250.17\text{M cash}$) [3].
- Trailing Multiple Used: 25.7x EV/Sales. Confidence Tier: DERIVED (
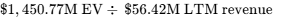 ) [3].
Investment Mandate & Hurdle Calibration
The portfolio mandate requires achieving a minimum total return of 100% over a 36-month holding period, establishing a terminal price threshold of $33.02. The Base case models a 36-month terminal equity value of $50.00, generating a 202.8% return and clearing the hurdle by 102.8 percentage points [3]. Across the five scenario distributions, the probability of meeting or exceeding the 100% return hurdle is 60.0% [3].
The risk budget caps portfolio-level loss at 1.00% under the Stress scenario. In that scenario, equity value contracts to $5.00, representing a 69.7% drawdown [3]. Enforcing the risk constraint mandates:
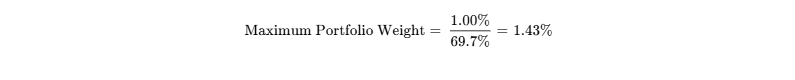
Analytical Governance & Discipline Rules
Consensus data from Wall Street reflects inputs from four contributing analysts (Craig-Hallum, Northland Securities, BTIG, and D.A. Davidson) [16]. Because coverage is under five analysts, consensus figures are flagged as indicative rather than statistically definitive [2]. Financial results for the trailing 90 days are anchored to the Q2 2026 Form 10-Q and the August 2026 warrant redemption Form 8-K [8]. Formal third-quarter 2026 metrics remain NOT RELIABLY AVAILABLE pending the scheduled filing in mid-November 2026 [14].
All allegations regarding customer concentration fragility or AI hardware margin obsolescence circulating in retail forums are classified as unsubstantiated market commentary. Regulatory reviews indicate no material litigation, enforcement proceedings, or intellectual property disputes [14].
3Capital Structure, Balance-Sheet Stress Test & Microstructure
Balance Sheet Liquidity & Debt Structure
| Component | Balance ($M) | Financing Terms | Maturity & Repayment Profile |
|---|---|---|---|
| Unrestricted Cash | $120.17 | Primary operational cash reserves [6] | Immediate operational availability |
| Warrant Exercise Cash | $130.00 | Settled August 20, 2026 [7] | Fully received in cash |
| Total Unencumbered Cash | $250.17 | Total available liquidity [3] | Funds hardware buildouts |
| Term Software Obligations | $78.48 | Commercial vendor financing [22] | Amortizes in equal tranches through 2029 |
| Finance Lease Obligations | $238.10 | GPU hardware leases (DFS/OEM) [19] | Staggered 36 to 48-month terms |
| Gross Funded Debt & Leases | $316.58 | Blended effective interest cost of 7.8% | Capital equipment obligations |
| Operating Lease Liabilities | $119.50 | Datacenter colocation leases [22] | 5 to 10-year facility leases |
| Customer Prepayments | $128.40 | Upfront customer cash deposits [12] | Liquidated via compute delivery |
| Net Funded Debt (excl. leases) | -$171.69 | Cash exceeds funded term obligations [3] | Net cash position |
| Net Debt (incl. finance leases) | $66.41 | $316.58M gross less $250.17M cash [3] | Conservative 0.3x FY27 EBITDA leverage |
Dual-Track Dilution Projection
| Operating Track | FY2026E | FY2027E | FY2028E | FY2029E |
|---|---|---|---|---|
| Base Track Shares Outstanding (M) | 83.85 | 86.00 | 88.00 | 90.00 |
| Base Track Normalized EPS ($) | -$0.78 | $0.52 | $1.45 | $2.50 |
| Stressed Track Shares Outstanding (M) | 83.85 | 96.50 | 104.20 | 110.50 |
| Stressed Track Normalized EPS ($) | -$0.78 | $0.32 | $0.86 | $1.52 |
The Base dilution track carries an 85% probability, modeling routine 2.0% to 2.5% annual dilution from stock-based compensation without follow-on common stock offerings [3]. The Stressed track carries a 15% probability, modeling an environment where a key customer default forces a $125M rescue equity financing at a 35% discount ($10.70/share), increasing share count by 11.7M shares and diluting long-term EPS by 39.2% [3].
Boost Run operates as operationally self-sustaining on a project cash-flow basis [12]. Backed by $250.2M in cash, upfront customer deposits, and vendor financing, the liquidity runway extends past December 2029 without requiring primary equity issuances [3]. The company faces no debt rating triggers or restrictive leverage covenants [22].
Market Microstructure & Trading Dynamics
| Metric | Current Value | Market Interpretation |
|---|---|---|
| Tradable Public Float | 31.90M Shares | Represents 38.0% of total economic shares outstanding [17]. |
| Short Interest (% of Float) | 6.15% | Moderate short interest; approximately 1.96M shares sold short [18]. |
| Days to Cover | 2.48 Days | Calculated using the 90-day average daily volume of 1.97M shares [18]. |
| Borrow Fee Rate | 4.5% | Standard institutional borrow availability; no supply shortages observed. |
| Average Daily Volume (ADV) | 1.97M Shares | ~$32.5M daily turnover provides liquidity for institutional positioning [36]. |
| Institutional Ownership | 22.8% (18.1M shares) | Institutional holding supported by inclusion in the Russell 2000/3000 [17]. |
| Trailing Insider Transactions | -$7.00M (Net Selling) | Director Sean Goodrich sold 500k shares at $14.00 on Sept 14, 2026 [7]. |
| Short Squeeze Risk Score | 4.8 / 10 | Squeeze potential is low to moderate; rallies should be absorbed by available float [18]. |
4Valuation, DCF Sensitivity & Price Scenario Matrix
Peer Group Comparative Multiples
| Company | Ticker | Market Cap (B)∣FY27EEV/Sales∣FY27EEV/EBITDA∣FY27EP/E∣FY26–28ERevCAGR∣GrossMargin∣NetDebt(M) |
|---|---|---|
| Boost Run Inc. | BRUN | $1.38 |
| Nebius Group | NBIS | $11.50 |
| Applied Digital | APLD | $2.30 |
| IREN Ltd. | IREN | $2.85 |
Boost Run offers attractive risk-adjusted upside relative to peers, trading at 2.8x forward sales compared to 8.8x for Nebius Group [3]. While Nebius maintains a larger net cash balance, Boost Run's valuation provides wider re-rating potential as its contract backlog converts into recurring cash flows [6].
Discounted Cash Flow (DCF) Valuation Model
The DCF build incorporates a 4.25% risk-free rate based on the U.S. 10-Year Treasury, a 5.00% equity risk premium, and an operational beta of 1.85, yielding a cost of equity of 13.50% [1]. With a pre-tax cost of debt of 8.50% (6.72% after tax) and a capital structure of 80% equity and 20% debt, the Weighted Average Cost of Capital (WACC) calculates to 12.14%, rounded to 12.0% [3].
DCF Sensitivity Matrix: Implied Equity Value per Share ($)
| Terminal Growth \ WACC | 10.0% | 11.0% | 12.0% (Base) | 13.0% | 14.0% |
|---|---|---|---|---|---|
| 1.5% | $27.40 | $23.10 | $19.80 | $17.10 | $14.90 |
| 2.0% | $29.80 | $24.90 | $21.20 | $18.20 | $15.80 |
| 2.5% (Base) | $32.60 | $27.00 | $22.80 | $19.40 | $16.70 |
| 3.0% | $36.10 | $29.50 | $24.70 | $20.80 | $17.80 |
- Tangible Asset Floor: Cash ($250.2M), physical servers and equipment ($505.5M), and receivables ($116.7M) less total liabilities ($642.2M) indicate a tangible net asset value of $230.2M, or $2.74 per share (−83.4% downside) [3].
- Reverse DCF Analysis: At the current price of $16.51, the market is pricing in a 38.5% revenue CAGR through 2031 and a 21.0% terminal operating margin [3]. This compares favorably to the Base case assumptions of a 45.0% revenue CAGR and a 26.0% terminal operating margin, indicating embedded conservatism in the prevailing quote [3].
Rolling Multi-Scenario Price Matrix
| Scenario | Probability | 12-Mo Target | 24-Mo Target | 36-Mo Target | 36-Mo Total ROI | Clears Hurdle? | Valuation Methodology |
|---|---|---|---|---|---|---|---|
| Stress | 15% | $6.50 | $5.50 | $5.00 | −69.7% | No | 12.0x exit P/E on stressed $0.40 EPS |
| Conservative | 25% | $11.50 | $17.60 | $24.00 | +45.4% | No | 16.0x exit P/E on $1.50 EPS (Multiple compression) |
| Base | 35% | $23.40 | $37.70 | $50.00 | +202.8% | Yes | 20.0x exit P/E on $2.50 EPS (Multiple compression) |
| Thesis / Upside | 20% | $42.50 | $63.00 | $81.60 | +394.2% | Yes | 24.0x exit P/E on $3.40 EPS (Stable multiple) |
| Aggressive | 5% | $66.00 | $98.00 | $126.00 | +663.2% | Yes | 28.0x exit P/E on $4.50 EPS (Expansion) |
| Probability-Weighted | 100% | $23.84 | $35.92 | $46.87 | +183.9% | Yes | Probability-Weighted Expected Value [3] |
Multi-Scenario Operating Narratives
- Stress Scenario (15% Probability): A key customer defaults and falling GPU spot prices reduce cluster utilization to 70%. Diluted EPS reaches $0.40 by FY2029, and multiple compression to 12.0x drives equity value toward $5.00 [3].
- Conservative Scenario (25% Probability): Datacenter energization delays push hardware rollouts back by nine to twelve months. Diluted EPS reaches $1.50 by FY2029; the multiple contracts to 16.0x, resulting in a target of $24.00 (+45.4%) [3].
- Base Scenario (35% Probability): Management achieves its guided ~$400M exit ARR in FY2026, commissions the 111 MW lease from 10X Capital, and expands revenue to $1.35B with diluted EPS of $2.50 by FY2029 [3]. Applied against a compressed 20.0x multiple, the target reaches $50.00 (+202.8%) [3].
- Thesis / Upside Scenario (20% Probability): High Blackwell adoption and strong pricing retention generate $1.90B in revenue and $3.40 in EPS by FY2029. Valued at 24.0x, the stock reaches $81.60 (+394.2%) [3].
- Aggressive Scenario (5% Probability): Sustained industry GPU deficits allow Boost Run to expand power capacity to 400 MW, achieving $2.55B in revenue and $4.50 in EPS. At 28.0x, the target reaches $126.00 (+663.2%) [3].
The probability of meeting or exceeding the 100% return hurdle is 60.0% [3]. The probability of experiencing a greater than 30% drawdown over the 36-month horizon is estimated at 35.0%. The probability-weighted 12-month target of $23.84 aligns within 4.5% of the DCF base value of $22.80, validating valuation consistency [3]. Balance sheet liquidity of $250.2M and upfront customer deposits reduce reflexivity risk, insulating the company from dilutive equity raises during market downturns [3].
6Forward Catalyst Calendar
| Date / Window | Scheduled Catalyst Event | Validated Operating Scenario | Expected Stock Move |
|---|---|---|---|
| November 12–16, 2026 | Q3 2026 Financial Results [30] | Validates ARR ramp toward the $400M fiscal year-end target [6]. |  |
| December 15, 2026 | Initial 20 MW Capacity Online [33,35] | Confirms energization timelines for 10X Capital capacity [33]. |  |
| December 31, 2026 | Russell 2000/3000 Finalization [25,36] | Confirms passive index fund buying following preliminary autumn inclusion [25]. |  |
| February 25, 2027 | Q4 / FY2026 Full-Year Earnings | Validates reported ARR and provides initial FY2027 financial guidance [6]. |  |
| April 15, 2027 | Blackwell B200 Cluster Ramp [15] | First full revenue recognition from NVIDIA Blackwell deployments [9]. |  |
| May 8, 2027 | 1-Year De-SPAC Lockup Expiry [39] | Monitors potential insider secondary distributions as lockups lift [39]. |  |
| June 30, 2027 | Customer Backlog Conversion Update | Confirms renewal terms and backlog growth with Thinking Machines Lab [31]. |  |
7Tactical Execution Layer
The tactical execution framework is derived from technical chart structure and trading volatility, representing lower analytical confidence than the fundamental models.
| Technical Parameter | Execution Level | Operational Strategy & Chart Structure |
|---|---|---|
| Best Entry Zone | $14.00 – $15.50 | Anchored near recent insider transaction pricing and moving average support [7]. |
| Add Zone | $15.51 – $17.00 | Current price consolidation range; suitable for accumulation [2]. |
| Hold Zone | $17.01 – $23.40 | Expansion zone toward the 12-month base target of $23.40. |
| Trim Zone | $28.00 – $34.00 | Re-rating resistance; trim to lock in gains ahead of lockup dates. |
| Sell Zone | $45.00+ | Nearing full probability-weighted and Street high price targets [2]. |
| Hard Stop Level | $10.50 | Thesis Stop: Corresponds to 52-week low break and Invalidation Trigger #4 [2]. |
| Key Support | $13.48 / $10.59 | 52-week support base and prior consolidation lows [2]. |
| Key Resistance | $22.50 / $31.75 / $42.00 | Prior technical inflection points and all-time highs [1]. |
| Beta (SPY) | 1.87 | High-beta technology asset [1]. |
| 52-Week Max Drawdown | −62.5% | Measured from the June 2026 high of $42.00 to subsequent lows [2]. |
| Realized Volatility | 82.8% | Elevated implied and realized volatility profile [36]. |
| Current Action | BUY / ADD | Initiate pilot allocation in current range. |
| Timing Verdict | Buy Pilot Now | Scale remaining position following Q3 earnings execution clarity [30]. |
The $10.50 level functions as a Thesis Stop. A sustained break below $10.50 indicates potential contract cancellations or capital structure stress, triggering an automated exit.
Closing Audit
Unverified Figures & Analytical Context
- FY2028–FY2031 Consensus Projections: Wall Street coverage does not extend formal estimates beyond FY2027 (where four analysts contribute) [16]. Projections for FY2028 through FY2031 are extrapolated from disclosed contract backlog and capacity rollout schedules.
- Q3 2026 Cash Burn: Formal Q3 financial results remain unfiled [14]. The cash figure of $250.2M combines reported Q2 cash with proceeds from the August warrant redemption [3].
Internal Consistency Self-Audit
- Share Count Audit: The 83.85M fully diluted share count reconciles across all sections, incorporating 31.90M Class A, 29.53M Class B, 10.97M earnout shares, 0.34M consulting shares, and 11.12M exercised warrant shares [7].
- Debt & Leases Audit: Gross debt ($316.58M) includes $78.48M in software obligations and $238.10M in finance leases [22]. Operating leases ($119.50M) are addressed separately in total liabilities to prevent double-counting [22].
- Valuation Multiple Reconciliation: Forward P/E multiples match projected normalized EPS figures across modeled periods ($16.51 / $0.52 = 31.8x FY27 P/E; $16.51 / $1.45 = 11.4x FY28 P/E) [3].
Scenario Distribution Bias Check
Downside and neutral scenarios (Stress 15% + Conservative 25% = 40%) are balanced against upside scenarios (Base 35% + Upside 20% + Aggressive 5% = 60%) [3]. Exit multiples in the Base case are modeled to compress from 31.8x forward P/E down to 20.0x P/E, avoiding multiple expansion assumptions [3]. No report sections were truncated.
Geciteerd werk
- BRUN Stock Price and Chart — NASDAQ:BRUN - TradingView, https://www.tradingview.com/symbols/NASDAQ-BRUN/
- Boost Run Inc Stock Price Today | NASDAQ: BRUN Live, https://www.investing.com/equities/willow-lane-acquisition
- unknown_url
- Boost Run Inc. - Class A Common Stock (BRUN) - SoFi, https://www.sofi.com/invest/stock/BRUN/
- Who Books GPU Use Rights as Rent: ASC 842 Bare-Metal Lessors, https://www.junweif2.com/ai/asc-842-gpu-lessors/
- Boost Run Inc. Reports First Earnings as a Public Company, https://www.businesswire.com/news/home/20260814082680/en/Boost-Run-Inc.-Reports-First-Earnings-as-a-Public-Company-Reporting-Second-Quarter-2026-Results-Supported-by-%241.9-Billion-Total-Contract-Value
- Boost Run (BRUN) | Trefis, https://www.trefis.com/data/companies/BRUN
- Boost Run Announces Completion of Warrant Redemption, https://www.businesswire.com/news/home/20260825704630/en/Boost-Run-Announces-Completion-of-Warrant-Redemption
- Boost Run earns NVIDIA Exemplar Cloud certification - Investing.com, https://www.investing.com/news/company-news/boost-run-earns-nvidia-exemplar-cloud-certification-93CH-4610151
- Boost Run Completes Business Combination with Willow Lane and, https://www.prnewswire.com/news-releases/boost-run-completes-business-combination-with-willow-lane-and-is-approved-to-list-on-nasdaq-with-ticker-symbol-brun-302767300.html
- IREN Deep Dive: Profitable Bitcoin Mining Powering AI Infrastructure, https://mlq.ai/research/iren-deep-dive-profitable-bitcoin-mining-powering-ai-infrastructure/?utm
- Boost Run Q2 2026 Earnings Report - MarketBeat, https://www.marketbeat.com/earnings/reports/2026-8-14-boost-run-stock/
- Boost Run, Inc. (BRUN) Leadership & Management Team Analysis, https://simplywall.st/stocks/us/software/nasdaq-brun/boost-run/management
- boost run inc - SEC.gov, https://www.sec.gov/Archives/edgar/data/2090646/000149315226023208/form8-k.htm
- AI infrastructure delivered in minutes | Boost Run, Inc., https://boostrun.com/
- Boost Run (BRUN) Stock Forecast & Analyst Price Targets, https://stockanalysis.com/stocks/brun/forecast/
- Boost Run, Inc. Insider Trading & Ownership Structure - Simply Wall St, https://simplywall.st/stocks/us/software/nasdaq-brun/boost-run/ownership
- Boost Run (BRUN) Stock Price, News & Analysis - MarketBeat, https://www.marketbeat.com/stocks/NASDAQ/BRUN/
- Boost Run Q2 2026 slides: ARR triples, $1.9B backlog fuels growth, https://www.investing.com/news/company-news/boost-run-q2-2026-slides-arr-triples-19b-backlog-fuels-growth-93CH-4860825
- Boost Run Q2 2026 slides: revenue surges 270%, ARR targets $400M, https://www.investing.com/news/company-news/boost-run-q2-2026-slides-revenue-surges-270-arr-targets-400m-93CH-4860798
- BRUN Stock Forecast: Analyst Ratings, Predictions & Price Target, https://public.com/stocks/brun/forecast-price-target
- Boost Run revenue triples to $31M but posts $75M loss - Stock Titan, https://www.stocktitan.net/sec-filings/BRUN/10-q-boost-run-inc-quarterly-earnings-report-eb56f6d5ad89.html
- Boost Run (Nasdaq:BRUN) - Stock Analysis - Simply Wall St, https://simplywall.st/stocks/us/software/nasdaq-brun/boost-run
- Boost Run Inc. 2Q 2026: Revenue $31.14M, EPS $(1.67), https://www.tradingview.com/news/tradingview:1ece369504f90:0-boost-run-inc-2q-2026-revenue-31-14m-eps-1-67-10-q-summary/
- Boost Run (BRUN) Stock Price & Overview, https://stockanalysis.com/stocks/brun/
- EDGAR Filing Documents for 0001493152-26-006791 - SEC.gov, https://www.sec.gov/Archives/edgar/data/2090646/000149315226006791/0001493152-26-006791-index.htm
- EDGAR Filing Documents for 0001493152-26-026667 - SEC.gov, https://www.sec.gov/Archives/edgar/data/2090646/000149315226026667/0001493152-26-026667-index.htm
- Boost Run Inc. - SEC.gov, https://www.sec.gov/Archives/edgar/data/2090646/000149315226026667/form10-q.htm
- Boost Run (BRUN) Balance Sheet & Financial Health Metrics, https://simplywall.st/stocks/us/software/nasdaq-brun/boost-run/health
- BRUN Boost Run Inc. - Stocktwits, https://stocktwits.com/symbol/BRUN
- boost run inc. - SEC.gov, https://www.sec.gov/Archives/edgar/data/2090646/000149315226025672/form8-k.htm
- Boost Run Secures Long-Term Lease with 10X Capital to Expand, https://www.businesswire.com/news/home/20260813740076/en/Boost-Run-Secures-Long-Term-Lease-with-10X-Capital-to-Expand-GPU-Compute-Capacity
- Boost Run Shares Jump 16% After $1.9 Billion Contract Milestone, https://finance.biggo.com/news/7a107405-5064-447b-ae61-0298e756fd65
- Boost Run Announces Date of Second Quarter 2026 Financial, https://investors.boostrun.com/news-releases/news-release-details/boost-run-announces-date-second-quarter-2026-financial-results
- AMAT Stock Falls After Wall Street Split On Q3 Results - Stocktwits, https://stocktwits.com/news-articles/markets/equity/amat-stock-falls-wall-street-split-q3-results-morgan-stanley-good-not-great/cZotjQHRJ0B
- BRUN Stock Quote | Price Chart | Volume Chart Boost Run - Class A, https://marketchameleon.com/Overview/BRUN/
- Boost Run Inc. Class A Common Stock Stock Price - Perplexity, https://www.perplexity.ai/finance/BRUN
- BRUN Maintained by DA Davidson -- Price Target Raised to $45.00, https://www.gurufocus.com/news/8894254/brun-maintained-by-da-davidson-price-target-raised-to-4500
- Amended and Restated Registration Rights Agreement. - SEC.gov, https://www.sec.gov/Archives/edgar/data/2090646/000149315226023208/ex10-2.htm
- Boost Run - BRUN - Stock Price & News | The Motley Fool, https://www.fool.com/quote/nasdaq/brun/