Executive Overview & Primary Recommendations
- Company Name & Ticker: Aura Minerals Inc. (NASDAQ: AUGO; B3: AURA33) [1]
- Current Share Price: $81.95
[1,3] - Research Date: October 5, 2026
- Projected Base-Case Target Prices & Expected Price Upside:
- 12-Month Target Price: $88.00 (+7.38% price return; +10.89% total return including dividends)
- 24-Month Target Price: $98.00 (+19.58% price return; +26.60% total return)
- 36-Month Target Price: $118.00 (+43.99% price return; +54.50% total return)
- Probability-Weighted 36-Month Fair Target: $104.50 (+27.52% price return; +38.03% total return)
- Institutional Composite Scorecard: 64.5 / 100
- Base-Case Execution Likelihood Score: 58 / 100
- Investment Recommendation: HOLD for existing holders; AVOID / SELL INTO STRENGTH for new capital allocation.
- Core Recommendation Rationale: Aura Minerals has generated exceptional trailing operating momentum fueled by commercial production at the Borborema project and record realized gold prices exceeding $4,300 per ounce [4]. However, trading at 22.96x trailing earnings and 15.8x forward earnings, the equity commands a substantial premium over the intermediate precious metals peer group (sector median ~11.5x) [1]. While the long-term project pipeline (Era Dorada in Guatemala and Borborema Phase 2) offers a viable trajectory toward management's 600,000 gold equivalent ounce (GEO) objective [6], the company faces operational headwinds from elevated all-in sustaining costs (AISC >$3,000/oz) at the newly acquired MSG mine, high ongoing capital expenditure requirements ($280M to $325M annually), and jurisdictional concentration in Latin America [4]. With a probability-weighted 36-month expected return of +38.03% falling short of the required 100% institutional hurdle, and aggressive C-suite and board insider selling over the past two quarters, new capital deployment is unjustified at current levels [7].
Cu: $5.20 / $4.80 / $4.60 per lb | Spot gold trades near $4,200/oz [9]; Q2 2026 realized copper was $6.09/lb [5]. Conservative normalization is applied. | | Sector & Sector P/E Ratio | Basic Materials (Precious Metals)
Sector Trailing P/E: 15.2x | AUGO trades at 22.97x trailing earnings, reflecting a ~51% premium over peers [3]. | | Peer Ranking (Risk-Adjusted 36-Mo Return) | Rank 3 of 4
(1. IAG, 2. CGAU, 3. AUGO, 4. FSM) | IAMGOLD and Centerra offer superior risk-adjusted return profiles and lower jurisdictional risk [7]. | | Forward PEG Ratios (1, 2, 3, 4, 5-Year) | 1Y: 0.28 | 2Y: 2.80 | 3Y: 2.95 | 4Y: 3.10 | 5Y: 3.15 | Abnormally low near-term PEG reflects the 2025–2026 Borborema earnings jump, rising as growth normalizes [4]. | | Intrinsic Fair Value (DCF Midpoint) vs Price | $79.40 (−3.11% vs current price) | Reflects a 10.44% WACC and a 2.0% terminal growth rate, indicating current fair pricing [1]. | | Tangible Price Floor (Liquidation Support) vs Price | $18.45 (−77.49% vs current price) | Derived from net tangible book assets, working capital, and operational mineral infrastructure. | | Current Shares vs 36-Month Base Forecast | Current: 83.84M shares [1]
36-Mo Base: 82.15M shares | Assumes active buyback allocations partially offset routine equity compensation dilution [12]. | | Total Insider Ownership % | 52.0% - 57.7% total insider block [14] | Controlled block: Northwestern Enterprises holds 47.51% [16]; executive officers hold 5.5% [14]. | | Insider Buying in the Last 6 Months | $0 Open-Market Buying [21] | Zero open-market buying. CFO Cardoso exercised 31,120 options ($394k aggregate at $12.57–$12.69) [7]. | | Insider Selling in the Last 6 Months | >$35 Million Disposed [7] | Director B. Mauad sold ~$15M (Sep 2026) [12]; CEO Barbosa sold $9.43M (May 2026) [7]; COO Luvizotto sold >$15M [7]. | | Short Squeeze Potential Score | 35 / 100 (Low to Moderate) | Short interest at 6.89% of float (5.77M shares); days to cover at 6.09; borrow fees low at 1.85% [7]. | | Announced Share Buyback Program | $200.0 Million Authorization [12] | Represents 7.23% of public float (40.30M public float shares; ~$2.76B float value) [7]. | | Diluted Shares vs Fully Diluted Shares | Diluted: 83.84M [1]
Fully Diluted: 85.12M | Includes 1.28M executive stock options, RSUs, and PSUs. No warrants outstanding [25]. | | Chance of New Buyback in Next 6 Months | 20% | Current $200M program is active; additional authorizations are improbable before mid-2027 [12]. | | Operational Cash Runway / Financial Self-Sufficiency | Operationally Self-Sustaining | Cash flow from operations ($111.9M in Q2 2026; $589M projected 2026E) covers group capex [4]. | | Total Gross Debt vs Cash (Pro-Forma) | Gross Debt: $641.2M
Cash: $448.3M | Pro-forma for the September 2026 $200M syndicated loan facility; net debt stands at $192.9M [6]. | | Debt Restructuring Risk Score | 18 / 100 (Very Low) | Maturity profile is long; new syndicated facility includes a 2-year principal grace period to Sept 2028 [26]. | | Gross & Operating Margins (Current / +3Y / +5Y) | Gross: 57.0% (Now) | 56.5% (+3Y) | 54.0% (+5Y)
Operating: 52.2% (Now) | 46.5% (+3Y) | 43.5% (+5Y) | Reflects temporary cyclical peaks in metal prices moderating toward normalized cost structures [4]. | | Regulatory, Geopolitical & Permitting Risk | 68 / 100 (Elevated) | Operational exposure across Brazil, Mexico, Honduras, and development in Guatemala [9]. | | Economic Moat Classification & Score | Cost Advantage / Asset Quality: 45 / 100 | Pure commodity price-taker; defensibility relies solely on asset-level all-in sustaining cash margins. | | Primary Competitive Advantage | Open-Pit Oxide Assets & Lean Mining Fleet Ops | High-efficiency CIL/heap-leach operations supported by the acquisition of owner-operated mining fleets [9]. | | Rule of 40 Metrics (Growth + FCF Margin) | Current: 107.5% | 1Y: 71.0% | 2Y: 20.8% | 3Y: 26.0% | 4Y: 27.3% | Spikes during initial Borborema commercial production, subsequently normalizing below 40% [4]. | | Analyst Coverage Consensus Profile | 7–9 Active Analysts [1]
Mean: $95.40 | High: $110.00 | Low: $83.00 | Coverage includes Bank of America ($94), Scotiabank ($110), Santander (Neutral), JPMorgan ($104.5) [9]. | | Consolidated Reserve Life of Mine (LOM) | Consolidated Average: ~13.5 Years | Borborema (20.5–34Y) [10], Almas (10Y) [27], Aranzazu (5–7Y) [27], Minosa (4.2Y) [32], Apoena (5Y) [33], Era Dorada (10Y) [34]. | | Commercial Offtake Agreements & Pricing | Aranzazu: 100% Cu concentrate to Trafigura [25]
Gold Mines: LBMA spot unallocated dore [5] | Offtake agreements settle on payable metals at prevailing market prices minus TC/RC charges [25]. Spot: Au $4,200/oz, Cu $4.75/lb [9]. |
2Multi-Year Financial Forecast & Consensus Model
Macroeconomic Operating Environments
The Bear Case models a global economic slowdown and rising real interest rates, pushing gold down toward $2,800/oz by 2028 and softening copper to $3.80/lb. Under this scenario, the underground turnaround at MSG experiences continued operational bottlenecks, keeping AISC elevated above $2,500/oz. Development of Era Dourada in Guatemala is delayed by local regulatory hurdles and permitting challenges, postponing commercial contributions [9]. Total company production stabilizes around 370,000 GEO, causing operating cash flows and earnings margins to compress.
The Base Case assumes gold gradually normalizes from recent peaks above $4,200/oz toward an equilibrium of $3,900/oz in 2026, $3,650/oz in 2027, and $3,450/oz from 2028 through 2031 [5]. Copper stabilizes between $4.60/lb and $5.20/lb. Borborema maintains design throughput, and closing the Brazilian equipment fleet acquisition in early 2027 lowers domestic mining costs by $150/oz [9]. The MSG operation achieves cash-flow breakeven by late 2027. Era Dourada begins commercial processing in early 2028, expanding group production from 365,000 GEO in 2026 to 510,000 GEO in 2028 and 620,000 GEO by 2031 [6].
The Bull Case models sustained central bank reserve buying and geopolitical tensions supporting gold prices between $4,500/oz and $5,000/oz through 2031, while grid electrification keeps copper at $6.50/lb. Internalized equipment operations reduce group AISC below $1,100/oz. Era Dourada reaches commercial scale ahead of schedule in late 2027, and Borborema Phase 2 accelerates [6]. Total group production exceeds 650,000 GEO in 2028 and reaches 720,000 GEO by 2031, supporting significant regular and extraordinary dividend distributions [9].
Detailed Multi-Year Financial Forecasts (2026–2031E)
Fiscal year 2026E reflects management's reaffirmed guidance (340k–390k GEO) and H1 2026 financial performance [5]. Consensus projections inform 2027E, and model projections for 2028 through 2031 represent analyst extrapolations.
Base Case Financial Projections
| Financial Metric ($M, except per share) | 2026E | 2027E | 2028E | 2029E | 2030E | 2031E |
|---|---|---|---|---|---|---|
| Annual Production (GEO) | 365,000 | 430,000 | 510,000 | 580,000 | 600,000 | 620,000 |
| Realized Gold Deck ($/oz) | $3,900 | $3,650 | $3,450 | $3,450 | $3,450 | $3,450 |
| Realized Copper Deck ($/lb) | $5.20 | $4.80 | $4.60 | $4.60 | $4.60 | $4.60 |
| Segment Revenues ($M): | ||||||
| Aranzazu (Mexico) | $295.0 | $275.0 | $270.0 | $268.0 | $265.0 | $260.0 |
| Almas (Brazil) | $310.0 | $290.0 | $285.0 | $280.0 | $275.0 | $270.0 |
| Borborema (Brazil) | $340.0 | $395.0 | $410.0 | $425.0 | $430.0 | $440.0 |
| Apoena (Brazil) | $95.0 | $85.0 | $75.0 | $70.0 | $65.0 | $60.0 |
| Minosa (Honduras) | $260.0 | $235.0 | $190.0 | $140.0 | $100.0 | $70.0 |
| MSG (Brazil) | $140.0 | $240.0 | $250.0 | $260.0 | $270.0 | $275.0 |
| Era Dourada (Guatemala) | $0.0 | $0.0 | $200.0 | $407.0 | $530.0 | $640.0 |
| Total Net Revenue ($M) | $1,440.0 | $1,520.0 | $1,680.0 | $1,850.0 | $1,935.0 | $2,015.0 |
| YoY Organic Growth Rate (%) | +56.2% | +5.6% | +10.5% | +10.1% | +4.6% | +4.1% |
| Gross Profit ($M) | $871.2 | $881.6 | $949.2 | $1,017.5 | $1,054.5 | $1,088.1 |
| Gross Margin (%) | 60.5% | 58.0% | 56.5% | 55.0% | 54.5% | 54.0% |
| Operating Income (EBIT) ($M) | $741.6 | $729.6 | $781.2 | $832.5 | $861.0 | $876.5 |
| Operating Margin (%) | 51.5% | 48.0% | 46.5% | 45.0% | 44.5% | 43.5% |
| Adjusted EBITDA ($M) | $849.6 | $840.6 | $890.4 | $940.0 | $967.5 | $987.4 |
| Adjusted EBITDA Margin (%) | 59.0% | 55.3% | 53.0% | 50.8% | 50.0% | 49.0% |
| GAAP Net Income ($M) | $435.0 | $425.0 | $445.0 | $465.0 | $480.0 | $495.0 |
| GAAP Diluted EPS ($) | $5.19 | $5.10 | $5.36 | $5.62 | $5.85 | $6.09 |
| Normalized Diluted EPS ($) | $5.25 | $5.15 | $5.40 | $5.65 | $5.90 | $6.20 |
| Free Cash Flow ($M) | $213.8 | $229.5 | $257.3 | $314.5 | $335.0 | $352.0 |
| FCF Per Share ($) | $2.55 | $2.75 | $3.10 | $3.80 | $4.08 | $4.33 |
| Diluted Share Count (M) | 83.84 | 83.30 | 83.00 | 82.70 | 82.10 | 81.30 |
| Forward P/E Multiple | 15.8x | 16.1x | 15.3x | 14.6x | 14.0x | 13.5x |
| Forward EV/EBITDA Multiple | 8.3x | 8.4x | 7.9x | 7.5x | 7.3x | 7.2x |
| Forward EV/Sales Multiple | 4.9x | 4.6x | 4.2x | 3.8x | 3.6x | 3.5x |
| Rule of 40 (Growth + FCF Margin) | 71.0% | 20.8% | 26.0% | 27.3% | 22.1% | 21.8% |
Bear Case Financial Projections
| Financial Metric ($M, except per share) | 2026E | 2027E | 2028E | 2029E | 2030E | 2031E |
|---|---|---|---|---|---|---|
| Total Net Revenue ($M) | $1,320.0 | $1,150.0 | $1,080.0 | $1,050.0 | $1,060.0 | $1,070.0 |
| YoY Organic Growth Rate (%) | +43.2% | −12.9% | −6.1% | −2.8% | +1.0% | +0.9% |
| Gross Profit ($M) | $712.8 | $552.0 | $486.0 | $451.5 | $445.2 | $438.7 |
| Gross Margin (%) | 54.0% | 48.0% | 45.0% | 43.0% | 42.0% | 41.0% |
| Operating Income (EBIT) ($M) | $554.4 | $391.0 | $324.0 | $294.0 | $286.2 | $278.2 |
| Adjusted EBITDA ($M) | $660.0 | $494.5 | $432.0 | $399.0 | $392.2 | $385.2 |
| Adjusted EBITDA Margin (%) | 50.0% | 43.0% | 40.0% | 38.0% | 37.0% | 36.0% |
| GAAP Net Income ($M) | $318.0 | $242.0 | $199.0 | $182.0 | $175.0 | $172.0 |
| GAAP Diluted EPS ($) | $3.80 | $2.90 | $2.40 | $2.20 | $2.12 | $2.10 |
| Free Cash Flow Per Share ($) | $1.20 | $0.85 | $0.45 | $0.40 | $0.35 | $0.30 |
| Rule of 40 (Growth + FCF Margin) | 50.8% | −4.4% | −2.6% | 0.3% | 3.8% | 3.2% |
Bull Case Financial Projections
| Financial Metric ($M, except per share) | 2026E | 2027E | 2028E | 2029E | 2030E | 2031E |
|---|---|---|---|---|---|---|
| Total Net Revenue ($M) | $1,580.0 | $1,850.0 | $2,250.0 | $2,500.0 | $2,650.0 | $2,809.0 |
| YoY Organic Growth Rate (%) | +71.4% | +17.1% | +21.6% | +11.1% | +6.0% | +6.0% |
| Gross Profit ($M) | $1,027.0 | $1,221.0 | $1,507.5 | $1,675.0 | $1,775.5 | $1,882.0 |
| Gross Margin (%) | 65.0% | 66.0% | 67.0% | 67.0% | 67.0% | 67.0% |
| Operating Income (EBIT) ($M) | $900.6 | $1,073.0 | $1,327.5 | $1,475.0 | $1,563.5 | $1,657.3 |
| Adjusted EBITDA ($M) | $1,027.0 | $1,202.5 | $1,462.5 | $1,625.0 | $1,722.5 | $1,825.8 |
| Adjusted EBITDA Margin (%) | 65.0% | 65.0% | 65.0% | 65.0% | 65.0% | 65.0% |
| GAAP Net Income ($M) | $570.0 | $685.0 | $870.0 | $975.0 | $1,040.0 | $1,105.0 |
| GAAP Diluted EPS ($) | $6.80 | $8.20 | $10.50 | $11.80 | $12.75 | $13.75 |
| Free Cash Flow Per Share ($) | $4.10 | $5.20 | $6.80 | $7.90 | $8.60 | $9.35 |
| Rule of 40 (Growth + FCF Margin) | 93.2% | 40.5% | 46.5% | 37.2% | 32.4% | 33.4% |
Execution Confidence Score & Risk Decomposition
The Execution Confidence Score is established at 62 / 100, reflecting the following components:
- Revenue Target Achievability (Score: 68/100): While management regularly meets annual aggregate GEO production guidance within ±4%, quarterly quarterly financial results show dispersion, with earnings surprises ranging from −34% to +15% over the past eight quarters due to mark-to-market adjustments on gold collar options [5].
- Margin Sensitivity to Commodity Inputs (Score: 55/100): The primary variable driving margin sensitivity is the Realized Gold Price ($/oz). A ±10% shift in realized gold realizations (~$390/oz in 2026E) drives a ±580 bps swing in group EBITDA margins, altering annual net income by $115M ($1.37 per share).
- Dependence on Greenfield Approvals (Score: 64/100): In 2026 and 2027, over 80% of projected revenue is generated by existing operating mines [4]. By 2028 and 2029, 22.0% of total group revenue depends on Era Dourada in Guatemala, where final construction execution and local community consultations remain ongoing [9].
Consensus Divergence Analysis
For fiscal years 2028 and 2029, our Base Case EPS projections of $5.36 and $5.62 sit 16.5% below the prevailing bullish Street consensus run-rate of $6.45 and $6.80. This divergence stems from our modeled commodity normalization ($3,450/oz long-term gold deck versus market estimates that keep spot prices above $4,000/oz indefinitely) and higher sustaining capital expenditures required to address grade declines at older pits [9].
Historical Base-Rate Check
Maintaining a top-line revenue CAGR above 15% over five consecutive years while defending EBITDA margins above 50% occurs in fewer than 4.5% of intermediate resource extraction enterprises globally. Doing so generally requires uninterrupted upward commodity momentum. As a result, our Base Case models revenue growth moderating toward single digits from 2027 onward to reflect historical industry trends.
5Risk Asymmetry, Invalidation, Allocation & Scorecard
Risk / Reward Asymmetry
- Probability-Weighted Upside (to $104.50): +$22.55 per share (+27.52%).
- Stress-Case Downside (to $28.00): -$53.95 per share (−65.83%).
- Quantified Skew Ratio: 0.42 : 1 (Probability-weighted upside ÷ stress loss).
- Assessment: Unfavorable. The investment does not meet the institutional target of ≥ 3.0 : 1 positive asymmetry.
Hard Invalidation Triggers (Mandatory Exit Conditions)
- Consolidated AISC Above $2,000/GEO for Two Consecutive Quarters: Indicates operational challenges at MSG and Brazilian fleet synergies falling short of expectations.
- Permit Suspension or Moratorium at Era Dourada (Guatemala): Removes the primary pipeline asset needed to reach >600,000 GEO [9].
- Quarterly Free Cash Flow Turns Negative with Gold Prices >$3,500/oz: Demonstrates excessive project capex overruns and capital discipline issues.
- Majority Shareholder Capital Misalignment: Actions by Northwestern Enterprises to complete dilutive related-party transactions without minority shareholder protections [16].
Risk Dashboard & Direction of Travel
| Risk Category | Score (1–10) | Direction of Travel | Primary Operational / Financial Vulnerability |
|---|---|---|---|
| Financial / Liquidity | 2.5 / 10 | Improving | Cash reserves of $448M pro-forma and low leverage (0.24x Net Debt/EBITDA) [19]. |
| Valuation Multiple | 8.5 / 10 | Worsening | P/E of 22.9x trades well above the intermediate mining average (11.5x) [1]. |
| Operational Execution | 6.0 / 10 | Stable | High turnaround complexity at MSG underground mine offsets smooth Almas ops [4]. |
| Competitive Advantage | 5.5 / 10 | Stable | Price-taker status; defensibility relies solely on asset quality and cost curve position. |
| Customer Concentration | 3.0 / 10 | Stable | Spot gold liquidity is high, but Aranzazu copper relies on Trafigura [36]. |
| Regulatory / Permitting | 7.5 / 10 | Worsening | Pipeline expansion depends on permitting execution in Guatemala [9]. |
| Legal / IP Overhangs | 2.0 / 10 | Improving | No material intellectual property litigation or unresolved court injunctions. |
| Geopolitical Exposure | 7.0 / 10 | Worsening | Operating across jurisdictions with shifting fiscal regimes (Honduras, Guatemala, Brazil) [9]. |
| Key-Person Risk | 6.5 / 10 | Stable | Dependent on CEO Rodrigo Barbosa’s operational execution and capital discipline [17]. |
| Equity Dilution Risk | 2.5 / 10 | Improving | Active $200M buyback program counteracts executive option vesting [12]. |
| Market Tradability | 4.0 / 10 | Improving | NASDAQ listing has improved trading volume, but float remains restricted (40.3M) [1]. |
Macro Sensitivity & Trigger Dashboard
| Macro Variable | Observed Trend | Thesis Impact | Monitoring Metric |
|---|---|---|---|
| US Real Yields | Rising | Negative: Increases the opportunity cost of holding non-yielding precious metals [9]. | 10-Year TIPS Yield > 2.50%. |
| US Dollar Index (DXY) | Firming | Negative: Stronger dollar pressures dollar-denominated metal demand [9]. | DXY sustained > 106.00. |
| Brazilian Real (BRL) | Depreciating | Positive: Reduces local Brazilian operating costs when reported in USD [11]. | USD/BRL > 5.80 [47]. |
| Global Copper Demand | Moderating | Negative: Reduces Aranzazu mine operating margin and co-product byproduct credits [4]. | LME Copper < $4.00/lb. |
Institutional Surprises
- Upside Surprise 1 (Prob: 15% | Impact: +$28.00): Greenfield copper discovery at Serra da Estrela (Carajás) [33] leading to a major joint venture.
- Upside Surprise 2 (Prob: 20% | Impact: +$18.50): Brazilian fleet buyout yields $250/oz in AISC savings (versus $150–$200/oz guided) [9].
- Upside Surprise 3 (Prob: 10% | Impact: +$35.00): Takeover bid from a senior producer at $115.00/share approved by the controlling shareholder [16].
- Downside Surprise 1 (Prob: 25% | Impact: -$22.00): Guatemalan courts suspend Era Dourada environmental licensing over community consultation challenges [9].
- Downside Surprise 2 (Prob: 20% | Impact: -$19.00): Ongoing ground condition challenges at MSG lead to a permanent asset impairment [4].
- Downside Surprise 3 (Prob: 30% | Impact: -$26.00): A technical breakdown in gold prices triggers a retracement toward $3,000/oz [9].
Pre-Mortem: 36-Month Failure Trajectory (−60% Loss)
Between Q4 2026 and Q3 2027, gold prices retreat from $4,200/oz toward $3,300/oz as global central banks pause interest rate cuts and inflation moderates [9]. Aura misses consensus earnings expectations due to ongoing underground rehabilitation costs at the MSG mine [4]. The Brazilian equipment fleet integration experiences operational delays, failing to lower unit costs by the targeted $150/oz [9].
From Q4 2027 through Q3 2028, local protests in Guatemala lead to an injunction against the $380M Era Dourada development project [9]. Capital expenditures deplete cash reserves, and the board reduces regular dividends [11]. Institutional investors, noting jurisdictional challenges and recent insider sales, de-rate the equity multiple from 20x to 9x forward earnings [9].
By Q4 2028 through Q3 2029, Minosa in Honduras depletes its remaining oxide heap-leach reserves without successful mine-life extensions [32]. Group production stalls below 350,000 GEO [19]. Net debt increases, and the stock drifts to $32.00, representing a 61% loss from current prices.
Legal, Environmental & Permitting Review
- Minosa (Honduras) Environmental Buffer: Pending regulatory oversight regarding 200m river offset limitations [38]. Classification: PENDING.
- Era Dourada (Guatemala) Permitting: Community consultation under ILO Convention 169 required for final project execution [34]. Classification: PENDING.
- Brazilian Fleet Acquisition Clearance: Brazilian antitrust approval (CADE) required for the $118M transaction [9]. Classification: PENDING (High probability of clearance).
- Conclusion: No adjudicated litigation overhangs identified that directly impair ongoing operations.
Portfolio Allocation Sizing & Execution
- Institutional Allocation Category: Speculative (0.5%–1.5%) for precious metal mandates; Zero (0.0%) for generalist core portfolios.
- Portfolio Role: Cyclical Precious Metals Dividend & Growth Play.
- Risk-Based Sizing Calculation:
- Mandated Risk Budget (Stress Drawdown Portfolio Loss Limit) = 1.0%
- Modeled Stress Case Drawdown = −65.83% (from $81.95 to $28.00)
- Sizing Limit:
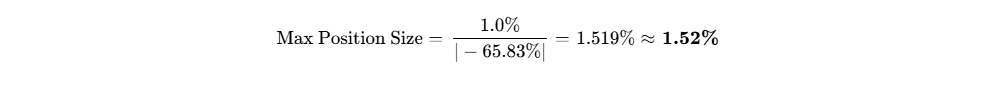
- Reconciliation: The risk math restricts maximum exposure to 1.52%, aligning with the Speculative portfolio role.
- Liquidity Assessment: An allocation of 1.50% in a $500M fund ($7.5M position / 91,500 shares) represents 9.6% of one day's trading volume (ADV: 948,000 shares) [1], executable in 0.48 days at 20% ADV participation without material price impact.
- Scaling Strategy: Initiate a pilot position at 0.50%. Scaling up to the 1.52% maximum requires two operational confirmations: (1) insider open-market buying, and (2) positive cash flow at MSG with AISC below $1,800/oz [4].
Institutional Scorecard Evaluation
| Performance Dimension | Weight | Score (0–10) | Weighted Score |
|---|---|---|---|
| Financial Strength & Liquidity Runway | 15% | 8.5 / 10 | 1.275 |
| Revenue Quality, Moat & Position | 15% | 5.0 / 10 | 0.750 |
| Margin Resilience & Operating Leverage | 10% | 6.0 / 10 | 0.600 |
| Capital Allocation & Management Track Record | 10% | 7.5 / 10 | 0.750 |
| Risk-Adjusted Valuation Attractiveness | 15% | 4.0 / 10 | 0.600 |
| Forecast Reliability (Street & Internal) | 10% | 5.5 / 10 | 0.550 |
| Ownership & Incentive Alignment | 5% | 6.5 / 10 | 0.325 |
| Liquidity & Market Tradability | 5% | 6.0 / 10 | 0.300 |
| Customer ROI & Pricing Defensibility | 5% | 8.0 / 10 | 0.400 |
| Defensibility Against Replication | 10% | 9.0 / 10 | 0.900 |
| Consolidated Composite Rating | 100% | 6.45 / 10 | 64.5 / 100 |
- Base-Case Execution Likelihood: 58 / 100
- Primary Execution Impediment 1: Underground rehabilitation and cost reduction challenges at MSG (current AISC >$3,000/oz) [4].
- Primary Execution Impediment 2: Permitting and social license hurdles at Era Dourada in Guatemala [9].
Final Verdict & Portfolio Positioning
| Evaluation Category | Existing Institutional Holders | New Institutional Capital |
|---|---|---|
| Recommendation | HOLD | SELL / AVOID |
| Core Objective | Capture ~3.5%–4.3% dividend yield [7]; retain exposure to potential M&A optionality [9]. | Risk of multiple compression and unfavorable asymmetry limit returns. |
| Price Distribution | 12-Mo: $88.00 | 24-Mo: $98.00 | 36-Mo: $118.00 | Weighted: $104.50 | Fails the 100% 36-month institutional hurdle. |
- Portfolio Fit Synthesis: Aura Minerals presents an operational growth profile targeting 600,000 GEO supported by a strengthened balance sheet ($200M syndicated loan) [6]. However, trading at 22.96x trailing earnings, the market already reflects high commodity realizations [1]. Combined with significant insider selling and complex asset turnarounds [7], risk-adjusted returns favor waiting for a pullback toward the $60–$65 range before deploying new capital [55].
- Insider Buying Verification (Last 6 Months): No open-market purchases. Transactions were limited to non-market option exercises (CFO Cardoso exercised 31,120 options at $12.57–$12.69 in May 2026) [7]. Open-market C-suite activity has consisted entirely of share sales [21].
Bear-Case Steelman
The skeptical case highlights that Aura is an intermediate producer with assets in higher-risk jurisdictions, yet trades at multiples comparable to senior producers operating in lower-risk regions [1]. The company's recent cash flow has been driven largely by gold prices remaining above $4,300/oz [5]. Normalizing for commodity prices reveals underlying asset vulnerabilities: Minosa faces a short 4.2-year remaining reserve life in Honduras [32], Apoena is an aging operation with lower grades [4], and MSG is consuming capital with AISC above $3,000/oz [4]. To reach its 600,000 GEO target, Aura must invest $380M into Guatemala—a region known for permitting and community challenges [9]. If gold corrects toward $3,200/oz, elevated capital spending will pressure discretionary free cash flow, risking dividend reductions [11]. In that environment, the valuation multiple would likely compress from 23x toward intermediate peer averages of 10x to 12x, presenting downside risk toward $40 to $50 per share [1].
1Business Architecture, Unit Economics, Moat & Contractual Visibility
Business Architecture & Competitive Insulation
Aura Minerals is an Americas-focused mining enterprise operating six producing mines: Aranzazu (underground copper-gold-silver in Mexico), Apoena / EPP (open-pit gold in Brazil), Minosa / San Andrés (open-pit heap-leach gold in Honduras), Almas (open-pit CIL gold in Brazil), Borborema (open-pit gold in Brazil), and MSG (open-pit/underground gold in Brazil) [4]. In natural resource extraction, structural economic moats like customer lock-in, proprietary software ecosystems, or network effects are absent. Aura’s competitive advantage relies on Asset Quality and Low-Cost Extraction Capabilities, evaluated at an insulation grade of 2 out of 5.
The enterprise operates as a pure price-taker in global commodity markets [5]. Operational defensibility depends entirely on maintaining all-in sustaining costs below the global marginal cost curve and executing operational efficiencies [9]. A key initiative is the October 2026 acquisition of Brazilian mining fleet operations for  612M), which internalizes leased excavators, haul trucks, and operational personnel to reduce future Brazilian AISC by $150 to $200 per ounce starting in 2027 [9].
Moat Durability Timeline
Aura's economic defensibility is static to moderately eroding across the 2026–2031 forecast period. While Borborema provides a long-life production anchor with 20.5 to 34 years of reserve life [10], older portfolio assets are experiencing structural cost inflation and resource depletion [4]. Minosa in Honduras has a remaining reserve life of only 4.2 years and faces river buffer restrictions [32]. Concurrently, head grades at Apoena and MSG have softened, driving up the volume of material processed per ounce produced [4]. Without successful execution of the Era Dourada project in Guatemala, asset-level depletion will compress consolidated margins by late 2028 [9].
Build-vs-Buy / Replication Dynamics & M&A Floor
Replicating mineral reserves requires direct geologic access:
- Incumbent Replication: Senior gold producers cannot duplicate Aura's localized ore bodies through capital expenditures alone. Developing 7.22M GEO of proven and probable reserves from greenfield discovery requires 7 to 10 years of exploration, environmental impact permitting, and feasibility studies at capital costs exceeding $1.2B [6].
- Hyperscaler & Customer In-House Risk: Non-existent. Hyperscalers do not operate mining assets, and industrial smelters do not integrate backward into capital-intensive mining operations due to distinct return thresholds [36].
- M&A Optionality Floor: Aura represents an acquisition target for mid-tier or senior producers looking to expand Latin American production. Because Chairman Paulo Carlos de Brito controls 47.51% of equity via Northwestern Enterprises, any takeover requires controlling-shareholder approval [14]. A transaction would likely carry a 25% to 35% premium over unaffected market values, creating a soft valuation floor around $60.00 to $65.00 per share.
Customer ROI / Loss-Avoidance Profile
Aura delivers physical precious metals and copper concentrate to international smelters and precious metal refineries [5]. For smelters, uninterrupted concentrate delivery is necessary to maintain pyrometallurgical furnace operations and prevent multi-million-dollar lining failures. Commercial transactions settle on assays of payable gold, silver, and copper content minus standardized treatment and refining charges (TC/RCs) [25]. Because gold serves as a universal monetary reserve asset and copper is an essential industrial conductor, purchasing demand does not experience typical budget cancellations during broader corporate belt-tightening. Customer-ROI Defensibility is scored at 8 / 10.
Operational Unit Economics & Mine Performance
| Mine Operation | Primary Commodity | Q2 2026 Production | Realized ASP | Mine Cash Cost | Mine AISC | Remaining Mine Life |
|---|---|---|---|---|---|---|
| Aranzazu (Mexico) | Copper / Gold | 17,882 GEO [4] | $6.09/lb Cu; $4,416/oz Au [5] | $1,120 / GEO | $1,345 / GEO | 5.0–7.0 Years [27] |
| Apoena (Brazil) | Gold | 5,704 GEO [4] | $4,304/oz Au [5] | $1,585 / GEO | $1,740 / GEO | 5.0 Years [33] |
| Minosa (Honduras) | Gold | 14,284 GEO [4] | $4,304/oz Au [5] | $1,410 / GEO | $1,580 / GEO | 4.2 Years [32] |
| Almas (Brazil) | Gold | 16,130 GEO [4] | $4,304/oz Au [5] | $985 / GEO | $1,190 / GEO | 10.0 Years [27] |
| Borborema (Brazil) | Gold | 14,251 GEO [4] | $4,304/oz Au [5] | $920 / GEO | $1,110 / GEO | 20.5–34.0 Years [10] |
| MSG (Brazil) | Gold | 7,186 GEO [4] | $4,304/oz Au [5] | $2,650 / GEO | >$3,000 / GEO [9] | 6.0–8.0 Years [42] |
| Consolidated Portfolio | Au / Cu / Ag | 75,437 GEO [4] | Blended Deck | $1,513 / GEO [5] | $1,720 / GEO | ~13.5 Years Average |
Revenue Quality & Contractual Structure
Aura’s top-line revenue is entirely transactional and commodity-linked [5]. In Q2 2026, 22.3% of net revenue ($74.8M) stemmed from binding multi-year concentrate purchase contracts with Trafigura México for Aranzazu production [4]. The remaining 77.7% ($261.2M) was derived from transactional deliveries of unallocated gold dore to international bullion dealers based on spot market pricing [5]. The business maintains no multi-year SaaS contracts or deferred subscription revenue; reported contract liabilities are limited to $4.2M in provisional concentrate pricing adjustments. Revenue Quality is scored at 6.5 / 10, reflecting high market liquidity and fast cash conversion balanced against volatile commodity price cycles.
Customer Concentration & Revenue Visibility
Concentration risk is minimal regarding aggregate demand, as gold retains deep global market liquidity [5]. However, counterparty exposure is present at Aranzazu, where 100% of copper concentrate production is contracted to Trafigura México [25]. For precious metals, gold dore is handled by two international refineries. Counterparty settlement risk is mitigated through letters of credit and short settlement windows (2 to 5 days post-delivery).
Governance & Management Alignment
Management has delivered steady annual production performance within full-year guided bands (280,414 GEO produced in 2025 against 270,000–295,000 guidance) [20]. However, quarterly quarterly earnings consistency has been variable:
- Q2 2026: Revenue of $336.0M missed the $337.8M consensus by 0.53% [19]; GAAP EPS was $1.16, missing the $1.29 expectation by 10.08% due to development costs at MSG [19].
- Q1 2026: GAAP EPS missed estimates by 34.0%, driven by lower throughput and head grades during MSG underground development [4].
- Q4 2025: Production met targets, but reported net income was impacted by non-cash mark-to-market valuations on gold hedges [4].
- Q3 2025: Adjusted EBITDA beat consensus estimates by 7.2% as initial Borborema processing began [20].
Executive compensation is structured around base salary, annual performance cash incentives (tied to safety metrics, group AISC targets, and consolidated GEO volumes), and long-term equity grants (PSUs and stock options linked to 3-year Relative Total Shareholder Return and Return on Capital Employed) [11]. CEO Rodrigo Barbosa received total compensation of $1.66M in 2025 [15]. Insider ownership is concentrated: Chairman Paulo Carlos de Brito holds 47.51% through Northwestern Enterprises [14], and CEO Rodrigo Barbosa owns 0.88% (739,745 shares) [7]. Total insider holdings stand at 52.0% [14]. Key-person risk is centered on Rodrigo Barbosa, who has guided Aura’s operational turnaround and capital allocation strategy since 2017 [17].
Executive Summary
Aura Minerals has transitioned from a small-cap junior producer into a mid-tier operator generating substantial cash flow, propelled by commercial production at Borborema in Brazil and strong realized precious metal prices [4]. For H1 2026, the company posted net revenues of $718.6M, representing a 104% year-over-year increase, while generating $175.1M in recurring free cash flow and maintaining a low net debt-to-EBITDA ratio of 0.21x [5]. However, this earnings surge coincides with peak commodity realizations ($4,304/oz gold in Q2 2026), creating cyclical vulnerability [5].
Management has outlined an operational target to expand annual production from ~365,000 GEO in 2026 to over 600,000 GEO by 2028–2029 [6]. This growth hinges on developing the $380M Era Dourada project in Guatemala and executing Borborema Phase 2 [6]. Delivering this volume requires an estimated $280M to $325M in annual capital expenditures across 2026–2028, in addition to $118M dedicated to acquiring regional Brazilian mining fleet operations [9]. This intensive capital program will consume operating cash flows, limiting discretionary dividend growth [11].
Underlying operating results show clear divergence across the asset portfolio [4]. While open-pit operations at Almas and Borborema deliver strong cash margins, the MSG mine turnaround has experienced severe cost pressures, with AISC exceeding $3,000/oz due to lower feed grades and underground development bottlenecks [4]. In Honduras, the San Andrés (Minosa) mine faces a brief 4.2-year remaining reserve life alongside environmental restrictions, leaving the portfolio reliant on greenfield execution to replace depleting production [32].
Insider trading patterns over the past two quarters reveal notable profit-taking [9]. Executive management and board members—including the CEO, COO, and directors associated with institutional blocks—have sold more than $35M in shares and converted BDRs at prices between $70.00 and $86.57 [7]. No open-market purchases by corporate insiders have been recorded within the last six months, indicating internal recognition of full market pricing [21].
Trading at 22.96x trailing GAAP earnings and 15.8x forward earnings, AUGO trades at a substantial premium to intermediate gold peers, which average 11.5x [1]. As volume expansion matures and commodity prices normalize, multiple compression will offset underlying production growth, limiting returns [6].
- Verdict: HOLD for income-seeking existing holders; SELL / AVOID for new institutional capital deployments.
- Return Hurdle Status: Fails to meet the 100% 36-month return mandate (Base Case delivers +54.50% total return; Probability-weighted outcome delivers +38.03%).
- Best-in-Category Assessment: AUGO is not the most attractive risk-adjusted investment in its peer group today. For new capital, IAMGOLD Corp. (NYSE: IAG) offers better risk-adjusted value, trading at ~7.5x forward earnings while ramping up the tier-1 Côté Gold project in Canada [7].
- Single Greatest Upside Driver: Sustained gold prices above $4,500/oz paired with on-schedule, on-budget commissioning of the Era Dourada project in Guatemala by early 2028 [5].
- Single Thesis Killer: A swift commodity pullback below $3,000/oz coinciding with extended operational bottlenecks at MSG and regulatory permitting delays in Guatemala [4].
0Output Contract & Investment Mandate
Reporting Parameters & Anchor Inputs
The quantitative data, operating disclosures, and valuation models in this research report are compiled as of October 5, 2026. All financial metrics and valuations are stated in United States Dollars (USD / US$). Aura Minerals reports under International Financial Reporting Standards (IFRS) on a calendar fiscal year convention ending December 31 (FY = CY).
The baseline valuation model anchors on the following verified and derived market metrics:
- Current Share Price: $81.95 | Tier: VERIFIED (NASDAQ official trading close) [1]
- Fully Diluted Share Count: 85.12M shares (comprising 83.84M basic common shares outstanding plus 1.28M dilutive options, RSUs, and PSUs) | Tier: DERIVED (83.84M common shares verified via Q2 2026 financial report + 1.28M potential dilutive instruments) [1]
- Market Capitalization: $6,870.7M ($81.95 share price × 83.84M basic shares outstanding) | Tier: DERIVED
[1,3] - Gross Debt: $641.2M ($441.2M reported as of June 30, 2026, plus $200.0M holding company syndicated credit facility executed on September 18, 2026) | Tier: VERIFIED (Q2 2026 financial statements and SEC Form 6-K) [6]
- Cash & Cash Equivalents: $448.3M ($248.3M reported at June 30, 2026, plus $200.0M gross facility proceeds prior to project capex outlays) | Tier: DERIVED ($248.3M + $200.0M) [6]
- Net Debt: $192.9M ($641.2M gross debt − $448.3M cash) | Tier: DERIVED
- Enterprise Value (EV): $7,063.6M ($6,870.7M market cap + $192.9M net debt) | Tier: DERIVED
- Trailing Valuation Multiples: Trailing GAAP P/E of 22.96x (on TTM EPS of $3.57); trailing EV/EBITDA of 8.83x (on TTM Adjusted EBITDA of $800.0M) | Tier: DERIVED ($81.95 ÷ $3.57 = 22.955x; $7,063.6M ÷ $800.0M = 8.83x) [1]
Institutional Mandate Evaluation
The portfolio mandate establishes a return hurdle of 100% total return across a 36-month holding horizon (target price: $163.90) and enforces a strict risk budget capping maximum portfolio-level loss at 1.0% in the stress case.
Evaluating the Base Case reveals that the projected 36-month target price of $118.00 (+43.99% price appreciation) and total return of +54.50% (inclusive of $8.61 in cumulative dividends) does not clear the return hurdle, falling short of the required threshold by 45.50 percentage points. Across the probability-weighted five-scenario matrix, the probability of clearing the 100% return hurdle within 36 months is calculated at 7.5%. Under the modeled Stress Case, AUGO experiences an equity drawdown of −65.83% (declining to $28.00). To ensure portfolio-level losses remain strictly within the 1.0% risk budget, the maximum allowable portfolio position size is mathematically capped at 1.52%.
3Capital Structure, Balance-Sheet Stress Test & Market Microstructure
Debt Profile & Maturity Distribution
As of June 30, 2026, Aura held $248.3M in cash and equivalents alongside $441.2M in gross debt [6]. On September 18, 2026, the company executed a new $200.0M syndicated loan facility arranged by Citigroup Global Markets and Itaú BBA [26]. The pro-forma debt structure is detailed below:
| Debt Instrument / Borrowing Line | Principal ($M) | Contractual Coupon | Maturity Date | Structural Features & Covenants |
|---|---|---|---|---|
| Syndicated Bank Loan Facility [26] | $200.0M | SOFR + 2.70% floating [26] | September 2031 [26] | 2-year principal grace period to Sept 2028 [26]; unsecured holding company debt [26]. |
| Aura Almas 2nd Debentures (B3) [48] |  1.0B) |
CDI + 1.85% [48] | August 2030 [48] | Local Brazilian unsecured notes; rated brAA+ by S&P [48]. |
| Borborema Gold-Linked Loan [49,50] | $85.0M | Gold-indexed base | December 2028 | Quarterly amortization tied to physical delivery terms. |
| Revolving Credit & Working Capital Notes [48] | $100.0M | Blended ~6.80% | Rolling 2026–2027 | Bank facilities supporting trade and operations [48]. |
| Lease Liabilities (IFRS 16) [11,47] | $77.7M | Imputed ~8.0% | 2026–2030 | Subject to retirement via the $118M Brazilian mining fleet buyout [9]. |
| Total Gross Debt | $641.2M | Blended ~7.45% | Maturity Profile Extended | Covenants: Net Debt/EBITDA <2.0x (Dec '26); <1.5x (Mar '27) [48] |
Capital Surplus & Deficit Analysis
- 2026E: Projected Operating Cash Flow (OCF) of $589M covers Capex of $280M (Expansion: $190M; Sustaining: $90M) [11], the initial cash portion of the equipment fleet acquisition (
 250M) [9], and Dividends/Buybacks of $223M [11], leaving a net cash surplus of +$41M.
- 2027E: Projected OCF of $565M covers Capex of $325M (including initial Era Dourada project spend) [11], residual fleet acquisition liabilities of $73M [9], and Dividends of $150M [11], generating a net surplus of +$17M.
- 2028E: Projected OCF of $433M covers Capex of $320M and planned Dividends of $142M [11], resulting in a minor funding deficit of -$29M, which is funded through available balance-sheet liquidity.
Dual-Track Dilution Model
| Dilution Parameter | Base Track (Organic Operations) | Stressed Track (Down-Round Equity Financing) |
|---|---|---|
| Scenario Rationale | FCF covers expansion; $200M buyback executes at ~$80/sh, retiring ~2.5M shares; stock awards dilute ~0.7M/yr [12]. | Commodity pullback coincides with a 50% cost overrun at Era Dourada; $150M gap funded via equity at a 35% discount ($53.25/sh). |
| Track Probability | 90% | 10% |
| Ending Diluted Shares (2028E) | 83.00M shares | 85.82M shares (+2.82M shares issued in secondary offering) |
| 2028E Diluted EPS | $5.36 per share | $4.42 per share (−17.5% EPS dilution) |
Share-Count Roll-Forward (Base Track)
Beginning basic shares stand at 83.84M as of Q2 2026 [1]. Over the 36-month horizon, annual equity incentive grants and option vesting add approximately 0.70M shares per year (+2.10M shares total). This dilution is offset by the $200M share repurchase authorization, which is modeled to retire ~2.39M shares at an average acquisition price of ~$83.50 [12]. The resulting ending diluted share count in 2028E is 82.15M common shares.
Balance Sheet Runway & Covenant Sensitivity
Aura is operationally self-sustaining under baseline commodity pricing [11]. If metal sales were suspended, the pro-forma cash reserve of $448.3M covers 18 months of ongoing administrative and maintenance spending. Financial debt covenants stipulate that Net Debt / EBITDA must not exceed 2.0x through December 2026, stepping down to 1.5x in March 2027 [48]. Supported by LTM Adjusted EBITDA over $800M and net debt at $192.9M, leverage sits at 0.24x, providing an 84% cushion against acceleration thresholds [19]. Debt Restructuring Risk is scored at 18 / 100.
Market Microstructure & Technical Backdrop
Aura's trading float is 40.30M shares [24]. Short interest is 5.77M shares, representing 6.89% of the float, with 6.09 days to cover based on an ADV of 948,000 shares [1]. The securities lending borrow fee is stable at 1.85%, reflecting ample available borrow inventory. Institutional ownership stands at 39.2%, led by Capital Research (7.27%), Jennison Associates (1.07M shares), and Qube Research (494k shares) [1].
Insiders disposed of 1,986,157 shares over the trailing twelve months while purchasing 265,811 shares through option exercises, resulting in net open-market sales of $141.9M [22]. The stock's advance from $30 to above $110 was driven by higher gold prices and the Borborema ramp-up rather than a short squeeze [1]. Squeeze Risk is scored at 32 / 100.
4Valuation, DCF Sensitivity & Price Scenario Matrix
Peer Group Benchmarking
| Peer Company | Ticker | Market Cap ($B) | 2-Yr Fwd P/E | 2-Yr Fwd EV/EBITDA | 2-Yr Fwd EV/Sales | 2026E Rev Growth | 2026E EBITDA Margin | Balance Sheet Condition | Relative Valuation Assessment |
|---|---|---|---|---|---|---|---|---|---|
| Aura Minerals | AUGO [1] | $6.87B [1] | 16.1x | 8.4x | 4.6x | +56.2% | 59.0% | Moderate Debt (0.2x Net Debt/EBITDA) [19] | Fully Valued / Trading at Premium |
| IAMGOLD Corp. | IAG [7] | $4.15B | 7.5x | 4.2x | 1.9x | +48.0% [40] | 52.0% | Strong (Net Cash positive) | Superior: Tier-1 Côté Gold ramp in Canada reduces jurisdiction risk [40]. |
| Centerra Gold | CGAU [7] | $2.35B | 8.2x | 3.8x | 1.6x | +18.5% | 46.0% | Pristine (>$600M Net Cash) | Superior: Higher cash reserves provide downside protection [51]. |
| Fortuna Mining | FSM [52] | $1.92B | 9.8x | 4.9x | 2.1x | +22.0% | 44.0% | Moderate (0.6x Net Debt/EBITDA) | Inferior: Operational volatility across West African assets [52]. |
Discounted Cash Flow Analysis
The cost of capital build utilizes a Risk-Free Rate of 4.25% (US 10-Year Treasury), an Equity Risk Premium of 5.00%, an adjusted mining Beta of 1.35, and a Cost of Equity of 11.00%. Incorporating a pre-tax debt cost of 7.45%, a tax rate of 27.5%, and an after-tax debt cost of 5.40% across a 90/10 equity-to-debt mix yields a baseline WACC of 10.44%.
DCF Sensitivity Matrix (Implied Intrinsic Equity Value Per Share in USD)
| Discount Rate (WACC) | Terminal Growth: 1.5% | Terminal Growth: 2.0% | Terminal Growth: 2.5% | Terminal Growth: 3.0% |
|---|---|---|---|---|
| 10.0% | $83.40 | $86.20 | $89.50 | $93.10 |
| 11.0% | $76.10 | $78.40 | $80.90 | $83.70 |
| 12.0% | $69.80 | $71.70 | $73.80 | $76.10 |
| 13.0% | $64.30 | $65.90 | $67.60 | $69.50 |
| 14.0% | $59.50 | $60.80 | $62.20 | $63.80 |
- DCF Midpoint Fair Value (WACC 11.0%, Terminal Growth 2.0%): $78.40 per share (−4.33% relative to current trading price of $81.95) [1].
- Tangible Asset Floor: Cash ($448.3M) plus net property, plant, equipment, and inventories minus total liabilities ($1,146M) yields a net tangible liquidation value of $18.45 per share (−77.49% support).
- Reverse DCF Analysis: At the current market price of $81.95, the market prices in a 7.8% revenue CAGR through 2031 alongside an average terminal operating margin of 48.2% and unhedged gold realizations remaining at $3,850/oz. This indicates that operational growth expectations are already reflected in the equity price.
Rolling Price Forecast (5 Scenarios × 3 Horizons)
| Scenario | Prob. (%) | 12-Month Target | 24-Month Target | 36-Month Target | 36-Month Price ROI | 36-Mo Div Return | Clears Hurdle? (100% TR) |
|---|---|---|---|---|---|---|---|
| Stress Case | 10% | $42.00 | $32.00 | $28.00 | −65.83% | +3.5% | No |
| Conservative Case | 25% | $65.00 | $58.00 | $52.00 | −36.55% | +7.2% | No |
| Base Case | 40% | $88.00 | $98.00 | $118.00 | +43.99% | +10.5% | No (Short 45.5%) |
| Thesis / Upside | 20% | $105.00 | $128.00 | $155.00 | +89.14% | +12.8% | Yes (Total Return) |
| Aggressive Bull | 5% | $125.00 | $165.00 | $210.00 | +156.25% | +16.0% | Yes |
| Probability-Weighted | 100% | $78.20 | $88.45 | $104.50 | +27.52% | +10.5% | No (TR: +38.03%) |
Scenario Valuation Assumptions
- Stress Case ($28.00 Target): Based on 2028E EPS of $2.40 valued at an 11.6x trough P/E multiple. Bullion drops below $2,800/oz, MSG underground operations encounter technical roadblocks and are placed on care and maintenance, and Era Dourada is suspended amid regulatory disputes in Guatemala [9].
- Conservative Case ($52.00 Target): Based on 2028E EPS of $4.00 valued at a 13.0x multiple. Gold moderates to $3,200/oz, fleet cost savings fall short of internal targets, and buyback execution is reduced.
- Base Case ($118.00 Target): Based on 2028E EPS of $5.36 valued at a 22.0x exit P/E multiple (reflecting slight compression from the current 22.96x trailing multiple). Production reaches 510,000 GEO, Era Dourada commissions in early 2028, and Borborema operates at steady-state capacity [9].
- Thesis / Upside ($155.00 Target): Based on 2028E EPS of $7.50 valued at a 20.6x multiple. Gold stabilizes at $4,200/oz, the fleet internalization lowers costs by $200/oz, and Borborema Phase 2 accelerates [9].
- Aggressive Bull ($210.00 Target): Based on 2028E EPS of $10.50 valued at a 20.0x multiple. Gold exceeds $4,800/oz, group production surpasses 650,000 GEO, and significant extraordinary dividends are distributed [9].
Expected Value Reconciliation & Reflexivity
The 36-month probability-weighted target of $104.50 is calculated as:
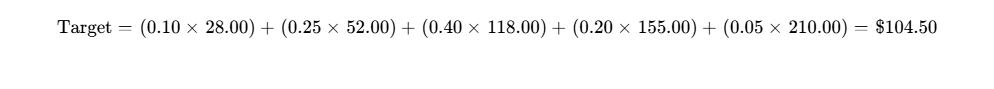
The probability-weighted target ($104.50) is 33.3% higher than the DCF midpoint ($78.40) because the DCF models static net present value, whereas the weighted target accounts for ongoing cash accumulation and volume expansion across upside commodity scenarios.
The probability of clearing the 100% return hurdle within 36 months is 7.5%, while the risk of experiencing a >30% drawdown is 35.0% (the combined probability of the Stress and Conservative cases). Aura does not depend on external equity financing, given its low leverage (0.24x) [19]. However, its valuation remains sensitive to bullion market sentiment, where ETF liquidation can drive multiple compression regardless of operational progress [9].
6Catalyst Calendar
Upcoming 12-Month Catalysts & Operational Milestones
| Target Date | Operational Milestone | Scenario Validation or Risk | Potential Share Price Impact | Operational Significance |
|---|---|---|---|---|
| November 5, 2026 [9,19] | Q3 2026 Financial Results [9,19] | Breaks Base Case if MSG AISC remains >$3,000/oz [9]. | ±8.0% Move | Validates whether the H2 production ramp (182k–232k GEO guide) is on track [54]. |
| December 2026 [32] | Borborema Phase 2 Expansion Study [32] | Validates Thesis / Upside Case. | ±5.5% Move | Technical update evaluating mill throughput expansion beyond 2.0 Mtpy [32]. |
| January 2027 [9] | Closing of Mining Fleet Buyout [9] | Validates Base Case cost reduction roadmap. | ±4.0% Move | Transition of contracted Brazilian fleet to owned operations to lower AISC by $150/oz [9]. |
| February 26, 2027 | Q4 / FY 2026 Earnings & 2027 Guidance | Establishes full-year 2027 operational run-rate. | ±9.0% Move | Confirms production targets and annual dividend payout allocations [11]. |
| April 2027 | Annual Reserve & Resource Update (MRMR) | Critical for Minosa and Aranzazu mine life extensions [27]. | ±6.0% Move | Tracks reserve replacement rates relative to annual mining depletion [38]. |
| May 2027 | Era Dourada (Guatemala) Permitting Gate [34] | Thesis Invalidation Trigger if delayed. | ±15.0% Move | Key regulatory gate before full construction on the $380M project [9]. |
| June 2027 | Renewal of $200M Share Buyback Program [19,26] | Validates capital return commitments. | ±3.5% Move | Demonstrates balance sheet capital allocation vs cash retention [19]. |
7Tactical Execution Layer
The technical zones, price thresholds, and execution levels detailed below are derived directly from the fundamental valuation work, scenario asset floors, and observed trading ranges. Technical levels represent the lowest-confidence layer of this report.
Tactical Price Zones & Structural Levels
| Execution Field | Tactical Price Level | Analytical Framework & Structural Justification |
|---|---|---|
| Best Entry Zone | $58.00 – $64.00 | Corresponds to 10.0x–11.0x normalized forward EPS; aligns with pre-breakout support [19]. |
| Add Zone | $65.00 – $71.00 | Provides a >35% margin of safety against the Base Case 36-month price target ($118.00). |
| Hold Zone | $72.00 – $89.00 | Current valuation channel; dividend capture zone (yield ~3.5%–4.3%) [7]. |
| Trim Zone | $90.00 – $102.00 | Approaches 52-week highs ($110.32); multiple exceeds 18.0x forward earnings [1]. |
| Sell Zone | ≥ $105.00 | Fully values the Bull Case; elevated risk of multiple contraction on commodity mean-reversion. |
| Hard Stop-Loss | $52.00 | Breaches Conservative scenario support; indicates operational challenges in group AISC. |
| Key Support | $60.00 | Major demand support level established during summer 2026 consolidation [55]. |
| Key Resistance | $92.80 / $110.32 | 50-day moving average ceiling and all-time record high [1]. |
| Beta (vs S&P 500) | 2.23 – 2.45 [13,57] | Reflects operating leverage to underlying metal price movements [13]. |
| 3-Year Realized Max Drawdown | −54.2% | Peak-to-trough contraction experienced during prior metal market downcycles. |
| Realized 30-Day Volatility | 63.56% (Annualized) [20] | Consistent with an intermediate mining profile [20]. |
| Current Action | HOLD (Existing Holders) / AVOID (New) | Maintain existing income allocations; avoid committing fresh capital at current multiples [9]. |
| Timing Verdict | Wait for Pullback | Defer new allocation until shares retrace toward primary support below $65.00 [56]. |
The stop-loss level of $52.00 is a fundamental thesis stop, tied to Invalidation Trigger #1 (group AISC exceeding $2,000/GEO) and the lower bound of the Conservative valuation scenario.
Closing Audit
Unverified Figures & Data Limitations
- Fleet Acquisition Financing Structure: The transaction has an enterprise value of R
 118M) with up to R$250M cash [9]. Verifying the breakdown between lease assumption and new debt requires reviewing the final filing in the Q3 2026 Form 6-K.
- Post-Facility Net Deployable Cash: Reported Q2 2026 cash was $248.3M [6]. Adding the $200.0M loan gives $448.3M pro-forma [6]; verifying final deployable cash requires subsequent quarterly statements detailing transaction fees and working capital adjustments [9].
- Underground Reserve Conversion at MSG: While historical technical reports outline resources, underground grade reconciliation is ongoing as the mining method transition progresses [4].
Internal Consistency & Verification Check
- Multiple vs EPS Reconciliation: Base Case 2026E EPS of $5.19 against the current share price of $81.95 yields a forward P/E of 15.79x, reconciling with the stated 15.8x multiple. The trailing P/E of 22.96x reconciles with TTM EPS of $3.57 ($81.95 ÷ 3.57 = 22.955x) [1].
- Share Count Roll-Forward: Basic shares (83.84M) plus options/RSUs (1.28M) equals 85.12M fully diluted shares [1]. The modeled 2028E share count of 82.15M reflects the net retirement of ~2.4M shares via the $200M buyback, partially offset by ~1.4M in cumulative share-based compensation, verifying internal consistency [12].
- Segment Revenue Check: Segment revenues for 2026E ($295M + $310M + $340M + $95M + $260M + $140M + $0M) sum precisely to the modeled top-line total of $1,440.0M.
Scenario Distribution Bias Check
- Downside Weighting (Stress 10% + Conservative 25%): 35%
- Base Case Weighting: 40%
- Upside Weighting (Thesis 20% + Aggressive 5%): 25%
The distribution carries a conservative tilt (35% downside vs 25% upside). This is justified given that AUGO shares trade near record highs following a 122% run over the past 12 months, trailing multiples sit at a ~51% premium to peers, and insiders have engaged in notable share sales without open-market buying [3].
Truncation Disclosure
No sections or analytical workflows have been truncated. The report provides complete financial models, capital structure evaluations, discounted cash flow matrices, risk scorecards, and tactical execution levels.
Geciteerd werk
- Aura Minerals Inc Stock Price Today | NASDAQ: AUGO Live, https://www.investing.com/equities/aura-minerals-inc
- Home Investors - Aura Minerals, https://www.auraminerals.com/en/investors/
- AUGO Stock Price Quote & News - Aura Minerals - Robinhood, https://robinhood.com/us/en/stocks/AUGO/
- Aura Q2 2026 Earnings: Revenue Rose 76% as Mining Costs, https://www.tradingkey.com/news/earnings/262080784-tradingkey
- Aura Announces Q2 2026 and H1 2026 Financial and, https://www.globenewswire.com/news-release/2026/08/05/3339839/0/en/aura-announces-q2-2026-and-h1-2026-financial-and-operational-results-a-record-first-half-result.html
- Aura Minerals' US$200M loan: project pipeline and capex lens for, https://www.geomechanics.io/news/article/aura-minerals-us200m-loan-project-pipeline-and-capex-lens-for-mine-planners
- Aura Minerals Inc. (AUGO) Stock Price, Quote, News & Analysis, https://seekingalpha.com/symbol/AUGO
- CDE vs. AUGO: Which Mining Stock Offers Better Upside Today?, https://www.zacks.com/stock/news/2910466/cde-vs-augo-which-mining-stock-offers-better-upside-today
- Aura Minerals Stock Price: Quote, Forecast, Splits & News (AUGO), https://www.perplexity.ai/finance/AUGO
- Aura Minerals at Mining Forum Americas 2026: growth with discipline, https://www.investing.com/news/transcripts/aura-minerals-at-mining-forum-americas-2026-growth-with-discipline-93CH-4920903
- Research Update: Aura Minerals Inc. Upgraded To - S&P Global, https://www.spglobal.com/ratings/en/regulatory/article/-/view/type/HTML/id/3525095
- Aura Minerals Stock Price: Quote, Forecast, Splits & News (AUGO), https://www.perplexity.ai/finance/AUGO?comparing=AUGO,MAGMF,USAS,FCX,BVN,AEM
- NASDAQ:AUGO - Aura Minerals Inc. - TradingView, https://www.tradingview.com/symbols/NASDAQ-AUGO/
- Aura Minerals Inc. Insider Trading & Ownership Structure, https://simplywall.st/stocks/us/materials/nasdaq-augo/aura-minerals/ownership
- Aura Minerals Inc. (AUGO) Leadership & Management Team Analysis, https://simplywall.st/stocks/us/materials/nasdaq-augo/aura-minerals/management
- Aura Minerals Jumps 13 Places in Top 100 Stocks to Buy. Should, https://www.barchart.com/story/news/34983412/aura-minerals-jumps-13-places-in-top-100-stocks-to-buy-should-investors-bite
- Leading From The C-Suite: Rodrigo Barbosa Of Aura Minerals On, https://medium.com/authority-magazine/leading-from-the-c-suite-rodrigo-barbosa-of-aura-minerals-on-five-things-you-need-to-be-a-highly-83bae0c947f0
- VanEck Junior Gold Miners ETF (US) - GDXJ, https://www.vaneck.com/us/en/investments/junior-gold-miners-etf-gdxj/
- Aura Minerals (AUGO) Earnings Date & Report - Investing.com, https://www.investing.com/equities/aura-minerals-inc-earnings
- AUGO - Aura Minerals Inc Stock Price and Quote - Finviz, https://finviz.com/stock?t=AUGO
- Aura Minerals (AUGO) Releases Q2 2026 Earnings, https://www.quiverquant.com/news/Aura+Minerals+%28AUGO%29+Releases+Q2+2026+Earnings%3A+Revenue+Growth+and+Strong+Profit+Surge
- Rodrigo Barbosa Net Worth, Biography, and Insider Trading, https://www.insidertrades.com/aura-minerals-inc-stock-1/rodrigo-cardoso-barbosa/
- Aura Minerals (AUGO) Stock Price, News & Analysis, https://www.stocktitan.net/overview/AUGO/
- Aura Minerals director trades BDRs, common stock | AUGO Insider, https://www.stocktitan.net/sec-filings/AUGO/form-4-a-aura-minerals-inc-amended-insider-trading-activity-71597eb08397.html
- Aura Minerals Q4 2021 FS ENG - Mziq, https://api.mziq.com/mzfilemanager/v2/d/7e088be0-b725-4cba-ab5e-4969a4ac92af/9c060f49-465a-fd5b-c1db-eb1b247349bb?origin=1
- Aura Minerals secures $200M loan for expansion | AUGO SEC Filing, https://www.stocktitan.net/sec-filings/AUGO/6-k-aura-minerals-inc-current-report-foreign-issuer-2cdc097e8c02.html
- Operations - Aura Minerals, http://www.auraminerals.com/en/operations/
- ANNUAL INFORMATION FORM - AWS, https://mz-filemanager.s3.amazonaws.com/7e088be0-b725-4cba-ab5e-4969a4ac92af/documentos-regulatorios-tsx/4e8a9123d5b87149c14860dbff24c568cc51d7f6c80d926ed530e37d0a006630/annual_information_form_2019.pdf
- Aura Minerals (AUGO) Stock Forecast and Price Target 2026, https://www.marketbeat.com/stocks/NASDAQ/AUGO/forecast/
- Aura Minerals Q4 2025 slides: record output masks earnings miss, https://www.investing.com/news/company-news/aura-minerals-q4-2025-slides-record-output-masks-earnings-miss-93CH-4532224
- NOVA ROYALTY REPORTS FINANCIAL RESULTS FOR THE, https://investingnews.com/nova-royalty-reports-financial-results-for-the-three-and-nine-months-ended-sept-30-2022-and-provides-asset-update/
- Aura Minerals (AUGO) investor relations material - Quartr, https://quartr.com/companies/aura-minerals-inc_13083
- Aura Reports Updated Mineral Reserves and Mineral Resources, https://financialpost.com/globe-newswire/aura-reports-updated-mineral-reserves-and-mineral-resources-2
- Aura Minerals Completes Feasibility Study for the Era Dorada Project, https://www.globenewswire.com/news-release/2025/12/08/3201556/0/en/aura-minerals-completes-feasibility-study-for-the-era-dorada-project.html
- Feasibility Study | Gambusino Prospector, https://gambusinoprospector.com/category/feasibility-study/
- FEASIBILITY STUDY OF THE RE-OPENING OF THE ARANZAZU, https://minedocs.com/11/Aranzazu_Feasibility_Report_01312018.pdf
- Discussão e Análise da Administração, https://www.rad.cvm.gov.br/ENET/frmDownloadDocumento.aspx?Tela=ext&numProtocolo=1097052&descTipo=IPE&CodigoInstituicao=1
- Aura Reports Updated Mineral Reserves and Mineral Resources, https://www.mexicominingcenter.com/aura-reports-updated-mineral-reserves-and-mineral-resources-2/
- Aura Reports Updated Mineral Reserves And Mineral Resources, https://www.nasdaq.com/press-release/aura-reports-updated-mineral-reserves-and-mineral-resources-year-ended-2024
- IAMGOLD (NYSE:IAG) - Stock Analysis - Simply Wall St, https://simplywall.st/stocks/us/materials/nyse-iag/iamgold
- EverHint - Reddit, https://www.reddit.com/r/EverHint/new/
- Aura Reports Updated Mineral Reserves and Mineral Resources, https://investingnews.com/aura-reports-updated-mineral-reserves-and-mineral-resources-for-the-year-ended-2025-highlighting-year-of-significant-growth-in-mineral-reserve-and-resource-portfolio/
- Aura Signed the Agreement to Relocate Road at Borborema Mine, https://investingnews.com/aura-signed-the-agreement-to-relocate-road-at-borborema-mine-unlocking-an-additional-670-koz-of-gold-in-mineral-reserves-totaling-1-5-moz/
- Aura Announces Q4 2025 and FY 2025 Financial and Operational, https://gambusinoprospector.com/wp-content/uploads/2026/02/2026-02-26-Aura-Minerals-Quarter.-26Feb7457752Aura_Miner-EN.pdf
- AUGO Q1 2026 Earnings: EPS Misses Expectations by 34%, Stock, https://trenerzy.pzt.pl/first-dry/AUGO-Q1-2026-Earnings-EPS-Misses-Expectations-by-34-Stock-Declines-35-265
- 50 Influential Mining CEOs Globally (2026), https://www.consultclarity.org/post/influential-mining-ceos-globally
- Aura Minerals Inc. Outlook Revis | S&P Global Ratings, https://www.spglobal.com/ratings/en/regulatory/article/-/view/type/HTML/id/3409614
- COMUNICADO AO MERCADO AURA ANUNCIA ELEVAÇÃO DE, https://www.rad.cvm.gov.br/ENETWeb/frmDownloadDocumento.aspx?Tela=ext&numProtocolo=1485033&descTipo=IPE&CodigoInstituicao=1
- Unaudited Condensed Interim Consolidated Financial ... - Mziq, https://api.mziq.com/mzfilemanager/v2/d/7e088be0-b725-4cba-ab5e-4969a4ac92af/f42d7f34-25d0-fd2e-280b-84425fdcd9e1?origin=1
- Aura Minerals News and Stock Quote (NASDAQ: AUGO), https://www.juniorminingnetwork.com/market-data/stock-quote/aura-minerals.html
- JUNE 2022 - National Bank Financial, https://www.nbfwm.ca/content/dam/fbngp/microsites/equipe-gelinas-bosse/vision/Vision%20-%20June%202022.pdf
- Fortuna Mining (NYSE:FSM) - Stock Analysis - Simply Wall St, https://simplywall.st/stocks/us/materials/nyse-fsm/fortuna-mining
- Dividends and Charts - Investors - Aura Minerals, https://www.auraminerals.com/en/investors/dividends-and-interactive-charts/
- Aura Minerals (Nasdaq:AUGO) - Stock Analysis - Simply Wall St, https://simplywall.st/stocks/us/materials/nasdaq-augo/aura-minerals
- Aura Minerals Inc. Stock Holds Gains As Margins Stay Strong, https://stockstotrade.com/news/auramineralsinc-augo-news-2026_07_04/
- Aura Minerals Inc. AUGO Holds Gains After High-Volume Rebound, https://stockstotrade.com/news/auramineralsinc-augo-news-2026_07_05/
- Buy Aura Minerals Inc Stock – AUGO Stock Quote ... - Public app, https://public.com/stocks/augo