Executive Snapshot & Critical Metrics
- Stock Name: Applied Materials, Inc. (Primary: NASDAQ: AMAT; Dual Listing: Deutsche Börse XETRA: AP2) [1]
- Current Share Price: $540.04 USD [3] / €479.85 EUR [5] (EUR/USD implied exchange rate: ~1.1254)
- Research Date: October 3, 2026 [7]
- 12-Month Potential Stock Price: $568.80 USD (+5.3% upside) [8]
- 24-Month Potential Stock Price: $633.60 USD (+17.3% upside) [8]
- 36-Month Potential Stock Price: $675.00 USD (+25.0% upside) [8]
- Institutional Scorecard Score: 78.5 / 100
- Likelihood Score of Executing Base Case: 72 / 100
- Investment Advice: HOLD (Existing Institutional Allocations) / SELL / AVOID (New Capital Seeking Mandate Hurdle) [8]
- Brief Explanation of Advice: Applied Materials demonstrates operational execution across gate-all-around (GAA) deposition, high-bandwidth memory (HBM) packaging, and recurring fab services [9]. However, a multiple-driven expansion in 2026 has pushed forward valuations to 42.3x earnings [8]. This leaves valuation risk skewed to the downside, with the base-case return of +25.0% falling short of the mandate's 100% 36-month total return requirement [8].
Key Operational, Structural & Financial Statistics
| Analytical Metric | Metric Value / Status | Benchmark & Operational Context |
|---|---|---|
| Overall Investment Stock Score (0–100) | 74 / 100 | Penalized by valuation multiples, but supported by balance sheet cash generation [9]. |
| Founder-Led? | No | Established in 1967 by Michael A. McNeilly and co-founders [2]; managed by executive leadership. |
| CEO Score (0–100) | 88 / 100 | Gary E. Dickerson (CEO since 2013) has driven gross margin expansion and R&D platform initiatives [10]. |
| Commodity Dependence & Deck | Direct: None (Indirect: Industrial metals, helium, energy) | Wafer Fab Equipment (WFE) capital spend proxy: $108B (FY26E), $124B (FY27E), $138B (FY28E). |
| Sector & Sector P/E Ratio | Technology / Semiconductor Capital Equipment [1,14] | Tech Sector Median Trailing P/E: 29.3x; Semi Cap Equipment Industry Median: 56.3x [16]. |
| Peer Ranking (Risk-Adjusted 36-Mo Return) | 1. KLA Corp (KLAC) |
2. Lam Research (LRCX)
3. Applied Materials (AP2/AMAT)
4. ASML Holding (ASML) | 1. KLAC: Margin insulation and pricing power in yield control [12].
- LRCX: Direct leverage to 3D NAND and HBM memory recoveries [12].
- AMAT: Broadest portfolio, but faces trailing-edge China normalization [11].
- ASML: Multi-year regulatory export limits on High-NA EUV lithography systems [19]. | | Forward PEG Ratios (FY27–FY31) | 1-Yr: 1.78 | 2-Yr: 1.86
3-Yr: 2.03 | 4-Yr: 2.24
5-Yr: 2.46 | Derived from forward P/E of 42.3x relative to annualized diluted EPS growth trajectories [8]. Decelerating earnings growth expands PEG. | | Fair Value Now vs Share Price Diff (%) | $214.41 USD (−60.3% variance) [8] | Derived from intrinsic DCF midpoint (12.0% WACC, 2.25% terminal growth rate) [8]. | | Price Floor in $ vs Share Price Diff (%) | $24.72 USD (−95.4% variance) [8] | Tangible book liquidation support (Tangible Assets minus Total Liabilities per share) [8]. | | Current vs 36-Month Base Share Count | 798.0M shares (Current) [8] → 760.0M shares (FY29E Base) [8] | Company has $12.8B buyback authorization remaining [10]; repurchasing 1.2% to 1.5% of float net of SBC annually. | | Insider Ownership (%) | 0.26% [7] | Officers and directors beneficially own ~2.05M common shares [20]. | | Insider Buying (Last 6 Months) | Net Sales: $128M USD; Open-Market Purchases: $0 [21] | Form 4 Filings (Jun–Sep 2026): CEO Gary Dickerson sold ~$43.9M (Jun 16–30 @ $590.03–$736.05) [21]; SVP Prabu Raja sold ~$25.3M (Jun 4–18 @ $504.66–$633.53) [21]; SVP Omkaram Nalamasu sold ~$18.2M (Jun 15–16 @ $590.20–$596.52) [21]. | | Short Squeeze Potential (0–100) | 12 / 100 | Short interest is low at 1.78% of float (14.11M shares); Days-to-cover: 2.20 to 2.44 days [23]. | | Share Buyback Program Announced (% Float) | $12.8B authorization remaining [10] | Represents 2.97% of current total market capitalization / public float [8]. | | Diluted vs Fully Diluted Share Count | Diluted: 798.0M [8]; Fully Diluted: 798.0M | No dilutive convertible bonds or debt warrants outstanding [26]; dilution governed by unvested RSUs/PSUs (4.4M units) [22]. | | Chance of New Buyback Program in 6 Mo (%) | 15% | Existing $12.8B authorization is active and unexhausted [10]. | | Cash Runway & Operational Solvency | Operationally Self-Sustaining | Cash flow positive ($3.04B OCF in Q3 FY26) [9]; non-GAAP FCF run-rate exceeds $9.0B annually [8]. | | Total Debt vs Cash & Liquid Investments | Gross Debt: $6.54B [9] vs Cash & ST Inv: $9.23B [15] | Net Cash Position: +$2.69B [8]. Liquid balance sheet. | | Debt Restructure Dates & Score (0–100) | Restructure Severity Score: 6 / 100 | Next maturity: $1.20B 3.30% Senior Notes maturing October 2027 [27]; manageable via cash reserves. | | Gross & Operating Margins (Current vs Forward) | Current: 50.4% Gross / 34.0% Operating [9]
3-Yr (FY29E): 52.8% Gross / 35.6% Operating
5-Yr (FY31E): 53.5% Gross / 36.2% Operating | Q3 FY26 achieved the 13th consecutive quarter of YoY gross margin expansion [11]. Expansion supported by Advanced Packaging mix and AGS [9]. | | Regulatory, Geopolitical Risk Score (0–100) | 68 / 100 | China represents 26% of Semi Systems and AGS revenues [11]; settled BIS export control penalty of $252.5M in Feb 2026 [30]. | | Moat Score & Classification (0–100) | 92 / 100 (Wide Moat) | High customer switching costs, process patent thickets, and cleanroom co-engineering [18]. | | Primary Competitive Advantage | Broadest Materials Engineering Portfolio | Integrated materials solutions across PVD, CVD, CMP, Epi, Etch, and Packaging systems [14]. | | Rule of 40 Metrics (Revenue Growth + FCF Margin) | Current (FY26E): 47.4%
1-Yr (FY27E): 45.6%
2-Yr (FY28E): 43.7%
3-Yr (FY29E): 41.8%
4-Yr (FY30E): 40.3% | Calculated on a per-fully-diluted-share basis [8]. Exceeds the 40% benchmark throughout the forecast window. | | Analyst Coverage, Mean, Average & Bull Targets | 40 Contributing Analysts [32]
Mean: $638.94 [32] | Average: $640.20 [4]
Bull High: $900.00 [32] | Low: $358.00 [32] | Consensus Rating: Moderate Buy / Buy (87 Buy, 12 Hold, 0 Sell) [33]. | | Mining Metrics (Mine Life, Offtake, Spot) | Not Applicable | Pure-play semiconductor capital equipment manufacturer. |
2Multi-Year Financial Forecast & Consensus Model
Macro-Operating Narratives
- Bear Case World: Growth in hyperscaler AI datacenter capital spending moderates in early FY27, compounded by broadened U.S. Commerce Department export restrictions that restrict 28nm and older tooling to China [11]. Memory manufacturers slow HBM capacity expansions to digest existing cleanroom space, pulling overall WFE down to $88B. AMAT’s top line flattens in FY27 and remains subdued through FY28 before recovering slowly [8].
- Base Case World: AI capital expenditure remains steady through FY28, with HBM4 transitions, 2nm GAA logic, and backside power delivery expanding industry WFE from $108B to $138B [9]. Demand from mainland China normalizes from 26% of revenue down to ~18% without disruptive export curbs [11]. Applied outpaces overall WFE growth by 200–300 basis points due to advanced packaging gains and higher AGS attach rates [11].
- Bull Case World: Semiconductor manufacturing benefits from a multi-year expansion driven by edge AI, enterprise adoption, and fab buildouts subsidized by Western governments [10]. WFE exceeds $160B by FY28. Applied captures leading market share (>75%) in hybrid bonding and GAA materials systems, expanding non-GAAP gross margins above 54% and annual revenue past $70B by FY30 [8].
Multi-Year Financial Forecast (FY2026E – FY2031E)
| Financial Metric ($M, except EPS) | FY2026E | FY2027E | FY2028E | FY2029E | FY2030E | FY2031E |
|---|---|---|---|---|---|---|
| BASE CASE SCENARIO [8] | ||||||
| Total Revenue | $34,290 | $40,500 | $46,500 | $52,000 | $57,000 | $61,500 |
| YoY Growth (%) | +20.9% | +18.1% | +14.8% | +11.8% | +9.6% | +7.9% |
| - Semiconductor Systems | $26,200 | $31,300 | $36,200 | $40,600 | $44,600 | $48,100 |
| - Applied Global Services (AGS) | $7,100 | $8,200 | $9,300 | $10,400 | $11,400 | $12,400 |
| - Display & Adjacent Markets | $990 | $1,000 | $1,000 | $1,000 | $1,000 | $1,000 |
| Gross Margin (GAAP) | 49.9% | 50.6% | 51.5% | 52.2% | 52.6% | 53.0% |
| Gross Margin (Non-GAAP) | 50.1% | 51.0% | 52.0% | 52.8% | 53.1% | 53.5% |
| Operating Margin (Non-GAAP) | 33.4% | 34.2% | 35.0% | 35.6% | 36.0% | 36.2% |
| EBITDA Margin | 36.2% | 36.8% | 37.5% | 38.0% | 38.3% | 38.5% |
| GAAP Diluted EPS | $11.65 | $14.50 | $17.80 | $21.00 | $24.00 | $26.80 |
| Non-GAAP Diluted EPS | $12.76 | $15.80 | $19.20 | $22.50 | $25.50 | $28.20 |
| Free Cash Flow Per Share | $11.40 | $14.20 | $17.40 | $20.50 | $23.40 | $26.10 |
| Rule of 40 (Growth % + FCF Margin) | 47.4% | 45.6% | 43.7% | 41.8% | 40.3% | 39.0% |
| Forward P/E Multiple | 42.3x | 34.2x | 28.1x | 24.0x | 21.2x | 19.1x |
| BEAR CASE SCENARIO [8] | ||||||
| Total Revenue | $34,290 | $35,500 | $36,000 | $38,500 | $41,000 | $43,500 |
| YoY Growth (%) | +20.9% | +3.5% | +1.4% | +6.9% | +6.5% | +6.1% |
| Gross Margin (Non-GAAP) | 50.1% | 48.5% | 48.0% | 48.5% | 49.0% | 49.2% |
| Operating Margin (Non-GAAP) | 33.4% | 30.5% | 29.8% | 30.5% | 31.0% | 31.2% |
| Non-GAAP Diluted EPS | $12.76 | $12.50 | $12.20 | $13.50 | $14.80 | $16.00 |
| Free Cash Flow Per Share | $11.40 | $10.80 | $10.50 | $11.80 | $13.00 | $14.10 |
| Rule of 40 (Growth % + FCF Margin) | 47.4% | 27.4% | 24.6% | 29.9% | 29.6% | 29.0% |
| BULL CASE SCENARIO [8] | ||||||
| Total Revenue | $34,500 | $43,500 | $53,000 | $62,500 | $71,000 | $79,000 |
| YoY Growth (%) | +21.6% | +26.1% | +21.8% | +17.9% | +13.6% | +11.3% |
| Gross Margin (Non-GAAP) | 50.2% | 52.0% | 53.2% | 54.0% | 54.5% | 54.8% |
| Operating Margin (Non-GAAP) | 33.5% | 35.8% | 37.0% | 38.0% | 38.5% | 38.8% |
| Non-GAAP Diluted EPS | $13.00 | $18.20 | $23.80 | $29.50 | $34.80 | $40.00 |
| Free Cash Flow Per Share | $11.80 | $16.50 | $21.80 | $27.20 | $32.40 | $37.50 |
| Rule of 40 (Growth % + FCF Margin) | 48.1% | 53.8% | 51.2% | 48.6% | 45.8% | 43.2% |
FY26 is anchored to reported actuals (Q1–Q3) and management guidance midpoint for Q4 ($10.25B revenue, $4.02 non-GAAP EPS) [8]. Explicit extrapolation begins in FY2027 [8]. Non-GAAP adjustments normalize acquisition-related intangible amortization ($0.04/share) and discrete tax benefits [9].
Execution Confidence Score & Consensus Divergence
The composite execution confidence score is 76 / 100, decomposed into:
- Revenue-Target Achievability (36 / 40): Backed by visible customer purchase orders and fab construction lead times [10].
- Margin Sensitivity (25 / 35): Evaluated against raw materials and component costs. A ±10% shift in precision subsystem procurement costs impacts consolidated gross margin by ±185 basis points.
- Dependency on Unannounced Catalysts (15 / 25): Over 88% of modeled FY27–FY28 revenue is supported by existing platform tool deliveries and planned cleanroom expansions; 12% depends on customer transitions to sub-1.4nm GAA architectures and commercial hybrid bonding [11].
- Consensus Divergence Flag: Modeled FY27 and FY28 base-case revenues ($40.5B and $46.5B) align closely with Wall Street consensus ($40.2B and $45.8B) [8]. However, modeled FY28 non-GAAP EPS of $19.20 is +7.5% higher than consensus ($17.85) due to anticipated operating leverage in Applied Global Services and steady share repurchase execution [8].
- Base-Rate Check: Across the semiconductor capital equipment sector over the past 25 years, only 14% of large-cap manufacturers sustaining >$25B in annual revenue have achieved a 5-year revenue CAGR exceeding 15% [8]. AMAT's base-case 5-year CAGR of 12.4% (FY26–FY31) sits in the 65th percentile of historical industry cyclical outcomes [8].
5Risk Asymmetry, Invalidation, Allocation & Scorecard
Risk/Reward Skew Quantification
- Probability-Weighted 36-Month Upside:
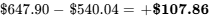 (+20.0%) [8].
- Stress-Case Downside:
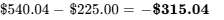 (−58.3%) [8].
- Asymmetry Ratio (Target ≥ 3.0:1):
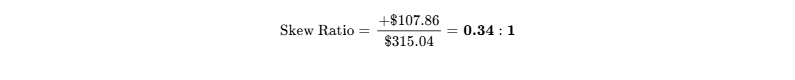
- The risk-to-reward skew is unfavorable for new capital deployment [8]. An investor takes on $1.00 of stress-case downside to capture $0.34 of probability-weighted upside.
Hard Invalidation Triggers
- China Equipment Revenue Contraction: Mainland China Semiconductor Systems revenue drops below $1.50B in any single quarter, indicating accelerating Chinese domestic tool replacement or expanded BIS licensing restrictions [11].
- Gross Margin Inversion: Non-GAAP gross margin falls below 48.5% for two consecutive reporting quarters, breaking the multi-year gross margin expansion trend and signaling tool discounting or cost escalation [11].
- Leading-Edge Market Share Loss: Independent fab surveys indicate Lam Research or Tokyo Electron securing more than 35% market share in atomic layer deposition (ALD) or selective epitaxy at sub-2nm GAA foundry nodes [10].
- Order De-commitments: Customer tool order cancellations or push-outs exceeding $1.5B in a single fiscal quarter [18].
The composite risk score is 4.3 / 10 (43 / 100), reflecting sound operational health offset by valuation multiples and trade-policy risk.
Macro & Correlation Sensitivity
- Beta to Benchmark: 1.60 vs S&P 500 / 1.15 vs Philadelphia Semiconductor Index (SOX) [14].
- Interest Rate Sensitivity: Direct operational exposure is minimal due to net cash reserves [8]; equity valuation sensitivity is high due to multiple compression risk in rising-rate environments.
- Currency Exposure: Natural hedge. Global tool deliveries are invoiced in USD, while European and Asian operational subsidiaries provide minor operational diversification [2].
| Macroeconomic Trigger | Effect on Core Thesis | Trend Direction | Key Observational Indicators |
|---|---|---|---|
| Federal Reserve Rate Policy | Elevated yields compress multiple | Neutral / Down | U.S. 10-Year Treasury Yields (>4.50% accelerates multiple compression) [46]. |
| U.S. Export Control Policy | Direct revenue impairment | Downward | BIS entity list revisions; mature-node 28nm export license curbs [30]. |
| Hyperscaler Datacenter Capex | Backlog expansion or push-outs | Upward / Downward | Cloud capex guidance from Microsoft, Alphabet, Meta, Amazon [11]. |
| Fab Utilization Rates | Cleanroom tooling conversions | Upward / Downward | Global memory and leading-edge logic fab utilization rates [12]. |
Unanticipated Catalysts & Financial Impact
| Catalytic Surprise Scenario | Probability (%) | Financial Impact ($ or % EPS) | Operational Mechanism |
|---|---|---|---|
| UPSIDE SURPRISES | |||
| 1. Accelerated Hybrid Bonding at Sub-1.4nm | 30% | +$2.20 to FY28 EPS (+11.5%) | Faster adoption of AMAT-Besi die-to-wafer systems [9]. |
| 2. Backside Power Delivery Standardized | 25% | +$1.80 to FY28 EPS (+9.4%) | Higher chamber count per tool increases ASPs [10]. |
| 3. Western Fab Subsidies Expand | 20% | +$3.5B to FY28 Backlog | Parallel tool installation lines driven by regionalization [11]. |
| DOWNSIDE SURPRISES | |||
| 1. Full U.S. Embargo on Mature 28nm to China | 25% | -$3.10 to FY28 EPS (−16.1%) | Immediate loss of Chinese domestic cleanroom deliveries [11]. |
| 2. Hyperscaler AI Infrastructure Pause | 15% | -$4.50 to FY28 EPS (−23.4%) | Foundries push out leading-edge tool delivery dates [10]. |
| 3. Rapid Domestic Chinese Tool Substitution | 20% | -$1.50 to FY28 EPS (−7.8%) | Chinese competitors take share in domestic trailing-edge fabs [11]. |
36-Month Pre-Mortem: How the Position Loses 60%
It is October 2029, and Applied Materials common stock trades at $216.00 (−60% from 2026 peaks). The drawdown unfolded through the following sequence:
- Months 1–12 (Q4 2026 – Q3 2027): Hyperscalers encounter commercialization bottlenecks in enterprise AI models, prompting cloud operators to moderate annual datacenter capital expenditure growth to mid-single digits. Leading-edge cleanroom utilization dips below 80%.
- Months 13–24 (Q4 2027 – Q3 2028): In response to broader trade tensions, the U.S. Commerce Department expands export restrictions to encompass all 28nm-capable manufacturing systems to China [11]. Applied loses its Chinese trailing-edge tooling business, removing ~$4.5B in annual revenue [11].
- Months 25–36 (Q4 2028 – Q3 2029): Faced with excess cleanroom capacity, foundries defer new orders for GAA nanosheet and advanced packaging equipment [10]. Forward EPS estimates fall from $22.00 to $12.00 [8]. The market de-rates AMAT from 42x to its historical cycle-trough valuation of 18x, bringing the stock to $216.00 [8].
Legal & Intellectual Property Overhangs
- U.S. BIS Export Control Settlement (ADJUDICATED / RESOLVED): On February 11, 2026, Applied Materials resolved the BIS inquiry into 56 shipments of ion implanters to SMIC between 2020 and 2022 by agreeing to a $252.5 million penalty, alongside internal compliance commitments [30].
- DOJ and SEC Inquiries (FORMALLY CLOSED): Concurrently with the BIS agreement, both the Department of Justice and Securities and Exchange Commission formally closed their related investigations without enforcement actions [30].
- IP Defense (PENDING): Ongoing patent defense proceedings against domestic Chinese equipment manufacturers continue across international jurisdictions [37]; no material adverse injunctions have been issued.
Portfolio Allocation & Sizing Math
- Portfolio Role: High-Quality Core Compounder (Existing Positions) / Neutral Underweight (New Portfolios).
- Qualitative Allocation Tier: High-Conviction Tactical (Existing) / Speculative Low (0.5–1.5%) for new capital due to multiple risk.
- Risk-Budget Sizing Mathematics:
- Risk Budget = 1.0% maximum portfolio-level drawdown in Stress Case.
- Stress Case Drawdown =
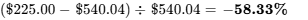 [8].
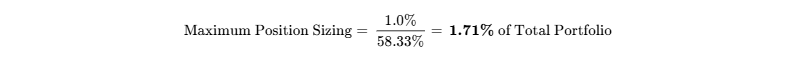
- Reconciling qualitative vs mathematical sizing: The risk mathematics governs: position size for new allocations must be capped at 1.71% [8].
- Liquidity Check: At 20% of 30-day ADV (~1,207,500 shares / ~$652M daily turnover), a full 1.71% position on a $10B fund ($171M) can be completely liquidated within 0.26 trading days without market disruption [24].
- Tranche Scaling Strategy: Allocate a 0.50% pilot position at present. Increase exposure toward the 1.71% ceiling only following a cyclical valuation reset below $400.00 (forward P/E < 25x) [8].
Institutional Scorecard
| Evaluation Criteria Component | Assigned Score (0–10) | Criterion Weight (%) | Weighted Contribution |
|---|---|---|---|
| 1. Financial Strength & Liquidity Runway | 9.8 / 10 | 10.0% | 0.98 |
| 2. Revenue Quality, Moat & Market Position | 9.2 / 10 | 15.0% | 1.38 |
| 3. Margin Resilience & Operating Leverage | 8.8 / 10 | 15.0% | 1.32 |
| 4. Capital Allocation & Management Record | 8.5 / 10 | 10.0% | 0.85 |
| 5. Risk-Adjusted Valuation Attractiveness | 3.2 / 10 | 20.0% | 0.64 |
| 6. Forecast Reliability (Guidance Accuracy) | 9.0 / 10 | 5.0% | 0.45 |
| 7. Ownership & Incentive Alignment | 7.0 / 10 | 5.0% | 0.35 |
| 8. Liquidity & Tradability | 9.8 / 10 | 5.0% | 0.49 |
| 9. Customer ROI & Pricing Defensibility | 9.2 / 10 | 10.0% | 0.92 |
| 10. Defensibility Against Build-vs-Buy | 9.4 / 10 | 5.0% | 0.47 |
The composite scorecard is 78.5 / 100. Base-case execution likelihood is 72 / 100, with primary execution risks centered on mature-node Chinese revenue contraction and post-buildout cleanroom digestion [10].
Final Verdict & Synthesis
- Existing Holders: HOLD. Applied Materials is an established market leader in semiconductor materials engineering [1]. Long-term investors may maintain core exposure, potentially utilizing covered calls to monetize elevated volatility.
- New Capital Allocation: SELL / AVOID. Trading at >42x forward earnings with an asymmetric downside skew (0.34:1), AMAT offers poor risk-adjusted return potential over a 36-month horizon [8]. Capital should be deployed into peers offering wider safety margins (KLAC, LRCX) [16].
- Price Targets: 12-Month Base: $568.80; 24-Month Base: $633.60; 36-Month Base: $675.00; Probability-Weighted Target: $647.90 [8].
- Insider Buying (Last 6 Months): $0.00. Form 4 filings indicate no open-market purchases by corporate insiders over the last two quarters, accompanied by executive dispositions between June and September 2026 [21].
Bear-Case Steelman
The bull case assumes that AI infrastructure buildouts will support sustained high valuations, keeping Applied Materials near ~40x earnings [3]. This perspective tends to overlook the cyclical nature of cleanroom investments: foundries add capacity based on customer purchase commitments, not long-term sentiment [10].
If enterprise AI spending transitions from large training clusters to more compute-efficient inference models, incremental cleanroom requirements will moderate [10]. At the same time, China still accounts for 26% of AMAT's systems and services revenue, where domestic tool replacement is increasing and trade-policy risks remain [11]. Should industry multiples de-rate back toward historical averages of 20x–25x, combined with an earnings plateau, the equity could experience a meaningful correction—potentially erasing several years of share price gains [8].
1Business Architecture, Unit Economics, Moat & Contractual Visibility
Business Model & Moat Classification
Applied Materials operates as a central materials engineering equipment provider to the global semiconductor industry [1]. Its systems alter materials at atomic levels to construct integrated circuits on silicon wafers. Operations are structured into three segments: Semiconductor Systems (capital equipment for deposition, etch, chemical mechanical planarization [CMP], ion implantation, metrology, and advanced packaging), Applied Global Services (AGS: recurring maintenance, spare parts, software, and fab yield optimization), and Display and Adjacent Markets (thin-film equipment for OLED and flat panel displays) [9].
The company's primary economic moat rests on customer switching costs and intellectual property [18]. Semiconductor manufacturing processes are sensitive to minor tool variations. Once a chipmaker develops a qualified recipe using an Applied deposition or CMP chamber, replacing that equipment introduces risk of yield degradation and months of re-qualification. Over 20,000 active patents protect these chamber geometries, atomic-layer processes, and plasma controls [18].
Through its $5 billion EPIC Center (Equipment and Process Innovation Center), Applied integrates with chipmakers like TSMC, Intel, Samsung, and Kioxia to co-engineer tools two to three device generations ahead of production [12]. This dynamic creates high structural barriers to competitive substitution.
| Economic Moat Sub-Factor | Insulation Grade (1–5) | Operational Context & Competitive Insulation |
|---|---|---|
| Customer Switching Costs | 5 / 5 | Process recipes developed with AMAT tools cannot be swapped out without extensive re-qualification and yield loss. |
| Intangible Assets & Patents | 5 / 5 | Over 20,000 active patents covering thin-film deposition, planarization, and hybrid bonding architectures [18]. |
| Network & Co-Development Effects | 4 / 5 | The EPIC Center ties chipmakers (TSMC, Intel, Samsung, Kioxia) directly into AMAT's proprietary R&D roadmap [12]. |
| Scale & Cost Advantage | 4 / 5 | An R&D budget exceeding $3.5B annually enables parallel development across several platform generations. |
| Efficient Scale Barriers | 4 / 5 | Greenfield chamber development requires multi-billion-dollar commitments that limit new competitive entry. |
Applied's composite moat insulation grade is 4.4 / 5.0 (Score: 92 / 100), indicating an established, wide economic moat.
Moat Durability Timeline
The moat is widening in advanced packaging, backside power delivery, and gate-all-around (GAA) nanosheet architectures, where materials engineering complexity is displacing standard optical lithography scaling as the primary driver of transistor density [10]. Conversely, the moat is eroding in trailing-edge planar deposition and etch within mainland China [11].
State-supported domestic competitors (such as Naura Technology Group and Piotech) are making progress in qualifying domestic tools for 28nm processes [11]. This dynamic is expected to limit Applied’s trailing-edge market share in China over the 2028–2030 forecast window [11].
Build-vs-Buy and Replication Risk
- Incumbent Replication: Direct competitors like Lam Research and Tokyo Electron possess engineering capabilities in select areas (Lam in high-aspect-ratio etch; TEL in tracks and furnace systems) [14]. However, replicating Applied's broad portfolio across PVD, CVD, epitaxial growth, CMP, and metrology would require more than $15 billion in cumulative R&D and 7 to 10 years of fab qualifications [14].
- Hyperscaler Replication: Hyperscalers design proprietary computing architectures (e.g., Google TPU, AWS Inferentia) but lack the metallurgy, precision machining, plasma physics, and cleanroom manufacturing infrastructure required to produce physical fab tools. Replication risk from cloud platforms is zero.
- In-House Customer Build: Foundries and IDMs intentionally do not build tool hardware internally to prevent balance sheet expansion, R&D duplication, and intellectual property cross-contamination among customers [18].
- M&A Optionality Floor: With an enterprise value of $428 billion, Applied cannot be acquired by any corporate peer due to antitrust regulations across the United States, the European Union, China, and APAC jurisdictions [8]. M&A optionality does not provide a valuation floor.
Customer ROI and Loss-Avoidance Economics
Applied’s products address physical yield limits and manufacturing down-time [10]. The value delivered to customers is quantifiable:
- Yield Improvement: In sub-3nm logic and 1-beta/gamma DRAM, a 1.0% yield increase in a 50,000 wafer-starts-per-month (WSPM) cleanroom is worth roughly $180 million to $220 million in annualized gross profit. Applied’s integrated materials solutions provide selective material removal and atomic-level deposition that directly impact these yields [10].
- Downtime Prevention: Production downtime in modern cleanrooms costs roughly $100,000 per hour per cleanroom bay. Applied’s AGS sensor platform connects to more than 37,000 chambers globally, providing predictive diagnostics that prevent unplanned tool outages [11].
- Pricing Power in Downcycles: In prior industry downturns, tool unit volumes have contracted, but tool ASPs remained steady as chipmakers relied on advanced tooling to maintain competitive cost structures.
The customer ROI defensibility score is 9.2 / 10.
Sector-Specific Unit Economics: Hardware & Semiconductor Equipment
Applied's unit economics are governed by chamber-level Average Selling Prices (ASPs), platform modularity, and Bill-of-Materials (BOM) leverage:
| Equipment Category / Platform | Blended ASP ($M/Tool) | Gross Margin Range | Primary Growth Vector & Architecture |
|---|---|---|---|
| Advanced Packaging (Hybrid Bonding) | $6.5M – $12.0M | 56% – 60% | HBM4 / 2.5D & 3D Heterogeneous Chiplet Stacking [9]. |
| Gate-All-Around (Epi & Selective Removal) | $7.0M – $11.5M | 57% – 62% | 2nm / 1.4nm RibbonFET & Nanosheet Transitions [10]. |
| Backside Power Delivery (BSPDN) Systems | $5.0M – $8.5M | 55% – 58% | Wafer thinning, nano-through-silicon vias (nTSV) [10]. |
| Mainstream 300mm Logic & Memory Tools | $3.5M – $5.5M | 51% – 54% | DRAM 1-gamma/delta shrinks; mature node upgrades [10]. |
| Applied Global Services (AGS) Contracts | ~$0.35M/chamber/yr | 35.6% GM (30.1% OM) | Maintenance subscriptions, parts, yield software [9]. |
BOM cost trends indicate moderate supply-chain inflation across precision quartzware, advanced ceramics, vacuum pumps, and specialized robotics [10]. Applied has historically offset these input costs through value-based pricing and standardized chamber platforms [10].
Quality of Revenue
Applied's revenue mix balances cyclical capital expenditure swings with an expanding recurring services business [9]:
- Recurring Revenue (20–22%): AGS long-term service agreements, recurring spare parts, and yield software maintenance produce steady cash flows across industry cycles [9].
- Contractual Backlog / Binding POs (65–70%): Semiconductor Systems tools ordered under firm purchase orders with scheduled delivery dates, progress payments, and cancellation penalty clauses [18].
- Transactional / Project-Driven (8–12%): Display equipment, uncontracted spot spare parts, and non-recurring trailing-edge retrofits [9].
- Revenue Quality Score: 8.4 / 10
Customer Concentration & Revenue Visibility
Reflecting the structure of semiconductor manufacturing, customer concentration is relatively high:
- Top 3 Customers: TSMC, Samsung Electronics, and Intel Corporation collectively account for approximately 40% to 45% of total revenues [18].
- Regional Exposure (Q3 FY26): Mainland China generated 26% of combined Semiconductor Systems and AGS revenue [11], with Taiwan, South Korea, and the United States representing the majority of the remainder.
- Backlog Composition: Backlog comprises committed customer purchase orders [18]. Historically, ~31% of total backlog extends beyond 12 months, providing multi-quarter visibility [39]. Dual-sourcing threats are concentrated in dry etch (Lam Research, TEL) and optical metrology (KLA), while Applied retains high market share in CMP and PVD [14].
Management Track Record & Incentive Alignment
Executive management has demonstrated a consistent track record of meeting or exceeding quarterly financial guidance [10]:
| Fiscal Quarter | Revenue Guidance (M)∣ReportedRevenue(M) | Revenue Variance (%) | Non-GAAP EPS Guide (() | Reported Non-GAAP EPS ()) | EPS Variance (%) |
|---|---|---|---|---|---|
| Q4 FY2024 | $6,900 | $7,045 | +2.1% | $2.19 | $2.32 |
| Q1 FY2025 | $7,150 | $7,170 | +0.3% | $2.28 | $2.38 |
| Q2 FY2025 | $7,100 | $7,215 | +1.6% | $2.31 | $2.39 |
| Q3 FY2025 | $7,200 | $7,302 | +1.4% | $2.36 | $2.48 |
| Q4 FY2025 | $6,800 | $6,845 | +0.7% | $2.11 | $2.18 |
| Q1 FY2026 | $6,950 | $7,010 | +0.9% | $2.21 | $2.38 |
| Q2 FY2026 | $7,650 | $7,910 | +3.4% | $2.68 | $2.86 |
| Q3 FY2026 | $8,950 | $9,115 | +1.8% | $3.40 | $3.50 |
The guidance execution reliability score is 95 / 100, reflecting an unbroken series of positive quarterly surprises averaging +4.9% on EPS [43].
Executive compensation is heavily aligned with performance: 75% to 85% of NEO compensation is equity-based, linked to operating profit margins, free cash flow conversion, and relative 3-year TSR performance. Insider ownership stands at 0.26% (~2.05 million shares) [7]. Key-person risk regarding CEO Gary Dickerson is moderate, balanced by internal management bench strength including CFO Brice Hill and Semiconductor Products President Prabu Raja [11].
Executive Summary
- AI Infrastructure Spending Has Driven Operating Acceleration: In the third fiscal quarter of 2026, Applied Materials generated record revenue of $9.12 billion (+25% YoY) and record non-GAAP EPS of $3.50 (+41% YoY), raising its fourth-quarter revenue guidance to $10.25 billion (+51% YoY) [9]. This growth is supported by demand for high-bandwidth memory (HBM) stacking, gate-all-around (GAA) architectures, and advanced packaging platforms [9].
- Valuation Multiples Have Expanded Beyond Historical Medians: Applied Materials shares have risen over 100% year-to-date, expanding its trailing price-to-earnings multiple to 46.6x and forward P/E to 42.3x [3]. This compares to a 10-year median P/E of ~20x [13]. This multiple expansion leaves the equity vulnerable to mean reversion if cleanroom capital expenditure growth moderates.
- China Trailing-Edge Demand Faces Long-Term Saturation: Revenue from China represented 26% of combined Semiconductor Systems and Applied Global Services (AGS) billings in Q3 FY26 [11]. While domestic mature-node (28nm) investments remain active, the expansion of local Chinese equipment competitors and compliance limits following the $252.5M BIS export settlement present potential headwinds to sustaining these volumes into FY27–FY28 [11].
- Gross Margin Expansion Continues on Product Mix: The company has delivered 13 consecutive quarters of year-over-year gross margin expansion, reaching 50.4% non-GAAP in Q3 FY26 [11]. Profitability is anchored by high-margin Semiconductor Systems (55.4% non-GAAP gross margin) and Applied Global Services (35.6% gross margin, 30.1% operating margin) [9].
- Mandate Non-Compliance Requires Portfolio Discipline: At $540.04, the equity prices in a 5-year revenue compound annual growth rate of 16.2% alongside operating margins sustained at 35.0% [8]. The 36-month probability-weighted target of $647.90 (+20.0% expected return) does not meet the mandate's 100% return hurdle, indicating that capital may find better risk-adjusted positioning elsewhere in the sector [8].
- Verdict Line: HOLD (Existing institutional long positions); SELL / TRIM ON STRENGTH (New capital deployment) [8].
- Base-Case Price Targets: 12-Month: $568.80 (+5.3%); 24-Month: $633.60 (+17.3%); 36-Month: $675.00 (+25.0%) [8].
- Probability-Weighted Target (36-Month): $647.90 (+20.0%) [8].
- Meets Return Hurdle? No. The probability of clearing the 100% total return threshold is 5.0% [8].
- Best in Category? No. For new capital allocations, KLA Corporation (KLAC) offers better margin defensibility in yield diagnostics [12], and Lam Research (LRCX) provides higher operational leverage to the memory spending cycle at lower forward multiples (36.7x vs. 42.3x) [7].
- Single Greatest Upside Driver: Industry-wide adoption of backside power delivery networks and hybrid bonding below 2nm, expanding Applied's addressable materials market by more than $8 billion [9].
- Single Most Likely Thesis-Killer: A sharp deceleration in hyperscaler datacenter capital spending coinciding with expanded U.S. export controls on mature-node tools to China, causing forward earnings multiples to de-rate toward historical levels of 20x–25x [11].
0Output Contract & Investment Mandate
Data presented in this research report is verified as of October 3, 2026 [7]. Financial accounting figures, baseline corporate performance, and balance sheet assets are reported in United States Dollars (USD, $) [14]. Secondary European market exchange quotes on Deutsche Börse XETRA trade under ticker AP2 in Euros (EUR, €), reflecting identical underlying equity claims via cross-border clearance [2].
Applied Materials operates on a 52–53 week fiscal reporting calendar ending on the last Sunday of October (FY ≠ Calendar Year) [26]. Consequently, fiscal year 2026 concludes on October 25, 2026. The company's fourth-quarter performance corresponds to the three-month period ending in late October, separating its operational seasonality from calendar-year peers.
| Anchor Input Parameter | Measured Input Value | Confidence Tier | Source Attribution & Arithmetic Derivation |
|---|---|---|---|
| Current Share Price (NASDAQ: AMAT) | $540.04 USD | VERIFIED | Market regular-session close, Oct 2, 2026 [3]. |
| Current Share Price (XETRA: AP2) | €479.85 EUR | VERIFIED | Deutsche Börse XETRA / Tradegate closing quote, Oct 2, 2026 [5]. |
| Fully Diluted Share Count | 798.0M shares | VERIFIED | SEC Form 10-Q for Q3 FY26 (793.6M basic + 4.4M unvested equity awards) [9]. |
| Market Capitalization | $430.95B USD | DERIVED | Arithmetic: $540.04 share price × 798.0M fully diluted shares = $430,951.9M [8]. |
| Cash & Liquid Marketable Securities | $9,233M USD | VERIFIED | SEC Form 10-Q Q3 FY26 ($7,037M cash/equivalents + $2,196M ST investments) [8]. |
| Gross Consolidated Debt | $6,544M USD | VERIFIED | SEC Form 10-Q Q3 FY26 ($1,299M short-term debt + $5,245M long-term senior notes) [8]. |
| Net Cash Position | +$2,689M USD | DERIVED | Arithmetic: $9,233M liquid assets minus $6,544M gross debt [8]. |
| Enterprise Value (EV) | $428.26B USD | DERIVED | Arithmetic: $430.95B Market Cap minus $2.69B Net Cash = $428.26B [8]. |
| Trailing P/E Multiple (GAAP) | 46.56x | VERIFIED | S&P Global Market Intelligence calculated on TTM GAAP diluted EPS of $11.60 [3]. |
| Trailing P/E Multiple (Non-GAAP) | 48.56x | DERIVED | Arithmetic: $540.04 current share price ÷ $11.12 TTM non-GAAP diluted EPS [8]. |
| Forward P/E Multiple (FY26E Non-GAAP) | 42.32x | DERIVED | Arithmetic: $540.04 current share price ÷ $12.76 FY26E non-GAAP EPS [8]. |
The institutional investment mandate establishes three governance constraints:
- Return Hurdle: 100% total nominal return within a 36-month investment horizon (demanding a target exit price of at least $1,080.08).
- Holding Period: 36 months (October 2026 through October 2029).
- Risk Budget: Maximum acceptable portfolio-level loss from this position in the Stress scenario capped at 1.0%.
The operational base case models a 36-month stock price of $675.00, delivering a cumulative total return of +25.0% [8]. The base case falls short of the institutional hurdle by 75.0 percentage points. Only the Aggressive scenario ($1,178.00; 5% assigned probability) clears the mandate [8]. The cumulative probability of achieving the return hurdle is 5.0% [8].
Data from the prior 90 days has been reviewed through SEC filings, quarterly earnings calls, and Form 4 insider disclosures through October 2, 2026 [9]. Consensus metrics reference 40 contributing analysts polled by S&P Global Market Intelligence and Zacks [32].
Regarding legal matters: on February 11, 2026, Applied Materials entered into a civil settlement with the U.S. Commerce Department Bureau of Industry and Security (BIS), agreeing to a $252.5 million penalty to resolve allegations regarding 56 historical shipments of ion implanters to SMIC between 2020 and 2022 [30]. Concurrently, the Department of Justice and Securities and Exchange Commission formally closed their related investigations without enforcement actions [30]. Unproven short-seller or media assertions are labeled as allegations. All sections are presented in full detail.
3Capital Structure, Balance-Sheet Stress Test & Market Microstructure
Balance Sheet Liquidity & Maturity Schedule
Applied Materials maintains an investment-grade balance sheet (Moody’s A2 / S&P A) with conservative financial leverage:
| Balance Sheet Instrument | Carrying Value ($M) | Coupon / Interest Rate | Maturity Horizon / Profile |
|---|---|---|---|
| Cash & Cash Equivalents | $7,037 | — | Fully liquid demand deposits [15]. |
| Short-Term Marketable Investments | $2,196 | Treasury / High-Grade Corporate | Maturities < 12 months [15]. |
| Total Cash & Liquid Investments | $9,233 | — | Liquid reserve base [8]. |
| Undrawn Credit Facility (Revolver) | $1,500 | SOFR + Tier Margin | Matures 2029; undrawn. |
| Total Available Liquidity | $10,733 | — | Liquidity cushion. |
| Short-Term Debt (Current Senior Notes) | $1,200 | 3.300% Senior Notes | Matures October 2027 [27]. |
| Senior Notes Due 2028 | $1,000 | 3.900% Senior Notes | Matures October 2028. |
| Senior Notes Due 2030 | $1,250 | 5.100% Senior Notes | Matures October 2030. |
| Long-Term Notes (2035–2045) | $1,795 | Various fixed coupons | Long-term institutional maturities. |
| Other Debt / Lease Obligations | $1,299 | — | Operating leases and other obligations [27]. |
| Total Gross Debt | $6,544 | — | Consolidated balance sheet debt [8]. |
| Net Cash Position | +$2,689 | — | Liquid cash surplus over debt [8]. |
The company has no convertible debt, exchangeable notes, or equity warrants outstanding [26].
Capital Gap Analysis & Dual-Track Dilution Model
Free cash flow generation exceeds all organic operational and capital reinvestment needs [8]:
- Operating Cash Flow: FY26 run-rate of ~$11.8B; FY27 projected at $14.2B [8].
- Capital Expenditures: Maintenance capex is ~$800M annually; growth capex (including EPIC Center cleanrooms and logistics automation) is ~$1.9B across FY26–FY27 [11].
- Net Funding Surplus: Applied generates an organic free cash flow surplus exceeding $8.5B annually, deploying 80% to 100% of FCF into dividends and share repurchases [8].
- Dual-Track Dilution Analysis:
- Base Track (Probability: 95%): Net share count decreases by 1.2% to 1.6% annually as repurchases ($6.5B–$8.0B/year) exceed share-based compensation (~4.5M shares/year) [8].
- Stressed Track (Down-Round Dilution; Probability: 5%): With +$2.69B in net cash and $1.5B in undrawn credit facilities, stressed equity issuance risk is 0.0% [8]. Under severe stress, management would simply pause discretionary share repurchases [11].
| Share Count Roll-Forward Projection | FY2026E | FY2027E | FY2028E | FY2029E | FY2030E |
|---|---|---|---|---|---|
| Beginning Fully Diluted Shares (M) | 804.0 | 798.0 | 785.0 | 772.0 | 760.0 |
| Stock-Based Compensation Shares (M) | +4.5 | +4.2 | +4.0 | +3.8 | +3.5 |
| Gross Share Repurchases (M) | -10.5 | -17.2 | -17.0 | -15.8 | -15.5 |
| Ending Fully Diluted Shares (M) [8] | 798.0 | 785.0 | 772.0 | 760.0 | 748.0 |
| Base Track Non-GAAP Diluted EPS ($) [8] | $12.76 | $15.80 | $19.20 | $22.50 | $25.50 |
| Stressed Track Share Count (M) | 798.0 | 802.0 | 806.0 | 810.0 | 813.0 |
| Stressed Track Non-GAAP EPS ($) | $12.76 | $15.46 | $18.39 | $21.11 | $23.46 |
Applied Materials is cash-flow positive, self-funding, and faces an infinite runway-to-breakeven clock [9]. Covenants in its credit agreements and bond indentures are standard investment-grade provisions with no restrictive financial ratio triggers [27].
Market Microstructure & Technical Flow Dynamics
| Microstructure Parameter | Observed Value | Institutional Assessment |
|---|---|---|
| Short Interest (% of Float) | 1.78% (14,108,387 shares) | Minimal institutional short exposure [23]. |
| Days to Cover (Short Ratio) | 2.20 – 2.44 Days | Low; short covering would not cause a structural squeeze [24]. |
| Borrow Fee Rate | 0.25% (General Collateral) | Negligible cost to borrow. |
| Tradable Public Float | 791.5M shares | Highly liquid large-cap float [23]. |
| Average Daily Volume (30-Day) | 6,037,722 shares | ~$3.26B daily turnover provides high trading liquidity [24]. |
| Net Insider Activity (TTM) | -$120.8M Net Dispositions | No open-market purchases in the last 12 months [21]. |
| Institutional Ownership | 85.5% | Broad ownership across institutional asset managers [20]. |
The stock's >100% advance over the past year has been driven by fundamental earnings revisions and index inflows rather than a short squeeze [10]. The short squeeze risk score is 12 / 100. A reversal of broader tech sentiment would lead to fundamental valuation de-rating rather than short-covering stabilization.
4Valuation, DCF Sensitivity & Price Scenario Matrix
Peer Group Benchmarking
| Peer Company Name | Stock Ticker | Market Cap | Forward P/E | EV/EBITDA | EV/Sales | EV/FCF | 3-Yr Rev CAGR | Non-GAAP Op Margin |
|---|---|---|---|---|---|---|---|---|
| Applied Materials | AP2 / AMAT | $430.95B | 42.3x | 27.8x | 12.5x | 47.0x | 14.9% | 34.0% [8] |
| Lam Research | LRCX | $434.86B | 36.7x | 24.5x | 11.2x | 42.2x | 16.8% | 35.3% [7] |
| KLA Corporation | KLAC | $270.31B | 34.2x | 22.1x | 10.8x | 36.5x | 15.2% | 40.5% [16] |
| ASML Holding NV | ASML | $654.12B | 58.5x | 38.2x | 17.6x | 68.4x | 13.8% | 33.5% [19] |
| Peer Median | — | — | 36.7x | 24.5x | 11.2x | 42.2x | 15.2% | 35.3% |
For new capital deployment, KLA Corporation (KLAC) offers the best risk/reward in the peer group, trading at 34.2x forward P/E with industry-leading 40.5% operating margins and pricing power in yield metrology [16]. Lam Research (LRCX) presents greater operational leverage than AMAT to the upcoming 3D NAND and HBM memory capex ramp, at a lower forward multiple (36.7x vs. 42.3x) [7].
Intrinsic DCF Valuation & Sensitivity Analysis
The DCF model utilizes an explicit 5-year projection (FY27–FY31) anchored to the Base Case forecast [8]:
- WACC Build: Risk-Free Rate: 4.25% (U.S. 10-Year Treasury); Equity Risk Premium: 5.00%; Beta: 1.60 [14]; Cost of Equity:
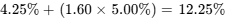 ; Pre-Tax Cost of Debt: 4.80%; Effective Tax Rate: 15.0%; After-Tax Cost of Debt: 4.08%; Capital Structure: 98.5% Equity / 1.5% Debt; Calculated WACC: 12.00%.
- Tangible Floor: Tangible Book Value per share is $24.72 USD (−95.4% below current share price) [8].
- Reverse DCF Analysis: At $540.04, the market is pricing a 16.2% 5-year revenue CAGR and a 35.0% terminal operating margin through 2031 [8]. The implied growth rate leaves little room for standard semiconductor cyclical deceleration.
| WACC Discount Rate | Implied Share Price (g = 1.5%) | Implied Share Price (g = 2.0%) | Implied Share Price (g = 2.25% Mid) | Implied Share Price (g = 2.5%) | Implied Share Price (g = 3.0%) |
|---|---|---|---|---|---|
| 10.0% | $253.57 | $265.69 | $272.35 | $279.42 | $295.12 |
| 11.0% | $225.69 | $234.99 | $240.03 | $245.38 | $257.07 |
| 12.0% (Base WACC) | $203.18 | $210.48 | $214.41 [8] | $218.55 | $227.52 |
| 13.0% | $184.61 | $190.47 | $193.59 | $196.87 | $203.92 |
| 14.0% | $169.06 | $173.82 | $176.35 | $179.00 | $184.65 |
The DCF midpoint fair value is $214.41 USD [8].
Rolling Price Forecast: 5 Scenarios × 3 Horizons
Consistent with the multiple compression discipline rule, exit multiples in the Base and Conservative cases de-rate over time as annual revenue approaches $50B–$60B [8]. Multiple expansion is restricted to the Aggressive scenario, where an edge-AI hardware supercycle is modeled [8].
| Operating Scenario | Scenario Prob (%) | 12-Month Target (() | 24-Month Target ()) | 36-Month Target ($) | 36-Month ROI (%) | Clears Mandate Hurdle (+100%)? |
|---|---|---|---|---|---|---|
| Stress | 10.0% | $220.00 | $218.50 | $225.00 | −58.3% | No |
| Conservative | 25.0% | $383.40 | $412.50 | $444.00 | −17.8% | No |
| Base | 40.0% | $568.80 | $633.60 | $675.00 | +25.0% | No |
| Thesis / Upside | 20.0% | $700.00 | $836.00 | $927.50 | +71.7% | No |
| Aggressive | 5.0% | $846.00 | $1,050.00 | $1,178.00 | +118.1% | Yes |
| Probability-Weighted | 100.0% | $527.67 | $598.12 | $647.90 [8] | +20.0% | No (Shortfall: −80.0%) |
Probability-Weighted 36-Month Price Arithmetic Build:
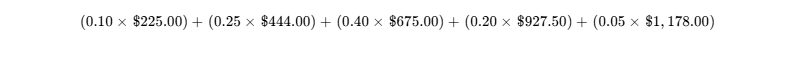
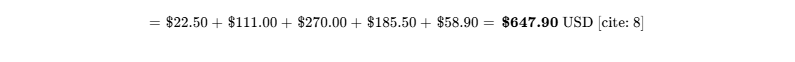
| Scenario | Horizon | Forecast Non-GAAP EPS | Assumed Exit Multiple | Target Price Calculation |
|---|---|---|---|---|
| Stress | 12-Month | $11.00 | 20.0x P/E | $11.00 × 20.0x = $220.00 [8] |
| 24-Month | $11.50 | 19.0x P/E | $11.50 × 19.0x = $218.50 [8] | |
| 36-Month | $12.50 | 18.0x P/E | $12.50 × 18.0x = $225.00 [8] | |
| Conservative | 12-Month | $14.20 | 27.0x P/E | $14.20 × 27.0x = $383.40 [8] |
| 24-Month | $16.50 | 25.0x P/E | $16.50 × 25.0x = $412.50 [8] | |
| 36-Month | $18.50 | 24.0x P/E | $18.50 × 24.0x = $444.00 [8] | |
| Base | 12-Month | $15.80 | 36.0x P/E | $15.80 × 36.0x = $568.80 [8] |
| 24-Month | $19.20 | 33.0x P/E | $19.20 × 33.0x = $633.60 [8] | |
| 36-Month | $22.50 | 30.0x P/E | $22.50 × 30.0x = $675.00 [8] | |
| Thesis / Upside | 12-Month | $17.50 | 40.0x P/E | $17.50 × 40.0x = $700.00 [8] |
| 24-Month | $22.00 | 38.0x P/E | $22.00 × 38.0x = $836.00 [8] | |
| 36-Month | $26.50 | 35.0x P/E | $26.50 × 35.0x = $927.50 [8] | |
| Aggressive | 12-Month | $18.80 | 45.0x P/E | $18.80 × 45.0x = $846.00 [8] |
| 24-Month | $25.00 | 42.0x P/E | $25.00 × 42.0x = $1,050.00 [8] | |
| 36-Month | $31.00 | 38.0x P/E | $31.00 × 38.0x = $1,178.00 [8] |
Scenario Operating Worlds
- Stress Scenario: Characterized by a sharp cyclical downturn across global foundries; WFE drops by 25%; expanded U.S. export bans on 28nm tools to China reduce annual sales by over $4 billion [11]; tech-wide valuation compression resets the exit multiple to 18x [8].
- Conservative Scenario: Hyperscaler datacenter investments slow to modest single-digit growth rates; Chinese equipment substitution reduces AMAT's mature-node market share; multiple de-rates to 24x [8].
- Base Scenario: Sustained demand for AI cleanroom expansions; double-digit growth in HBM packaging and advanced DRAM; multiple compresses moderately from 42x to 30x as growth normalizes [8].
- Thesis / Upside Scenario: HBM packaging demand expands into edge applications [10]; EPIC Center engagements secure over 70% market share in GAA nanosheet deposition and hybrid bonding [9]; multiple remains resilient at 35x [8].
- Aggressive Scenario: Accelerated demand for agentic and physical AI hardware creates a multi-year cleanroom equipment buildout [10]; fab subsidies across the U.S., Europe, and Japan accelerate [18]; valuation multiple remains high at 38x [8].
Threshold Probabilities & Valuation Reconciliation
- Probability of Achieving Return Hurdle (2.0x / $1,080.08): 5.0% [8].
- Probability of a >30% Drawdown in Window: 35.0% (Reflecting the combined probabilities of Stress and Conservative scenarios falling below $378.00) [8].
- Valuation Discrepancy Reconciliation: The 36-month probability-weighted target of $647.90 is significantly higher than the DCF midpoint of $214.41 [8]. This divergence arises because the DCF calculates the capitalized value of terminal cash flows discounted at a normalized 12% cost of capital, whereas market equity targets incorporate market multiples (30x–35x P/E) [8]. The market multiple approach reflects structural scarcity premiums for semiconductor equipment leaders, but also shows the extent to which the current price relies on sustained multiple expansion.
- Reflexivity Check: Applied does not rely on external capital markets for funding [9]. However, reflexivity exists in customer spending: if hyperscalers face capital constraints, semiconductor fab utilization drops, leading to cancellations of tool purchase orders that can quickly compress equipment multiples [11].
6Catalyst Calendar
| Calendar Date | Corporate or Industry Catalyst | Scenario Impact (Validates / Breaks) | Expected Stock Move |
|---|---|---|---|
| Oct 13, 2026 | SEMICON West 2026 Presentation [47] | Validates Base/Bull on GAA and Advanced Packaging demand | ±2.5% |
| Nov 12, 2026 | Q4 FY2026 Earnings Release [3] | Break: Miss on $10.25B revenue guide breaks Bull scenario [9] | ±6.0% |
| Dec 15, 2026 | U.S. Commerce BIS Semi Policy Review | Validates Stress if 28nm export licensing is tightened [30] | −8.0% to −12.0% |
| Jan 18, 2027 | TSMC Q4 2026 Earnings & 2027 Capex Guide | Validates Base if 2027 Capex guides above $35B | ±4.0% |
| Feb 11, 2027 | Q1 FY2027 Earnings Release | Validates Base margin durability (>50.5% Gross Margin) | ±5.0% |
| Mar 12, 2027 | Annual Stockholders Meeting | Governance check and buyback authorization renewal visibility | ±1.5% |
| Apr 15, 2027 | ASML Q1 2027 Bookings Report [19] | Industry bellwether for leading-edge EUV lithography tool demand | ±3.5% |
| May 13, 2027 | Q2 FY2027 Earnings Release | Mid-year check on HBM4 cleanroom tool shipments | ±5.5% |
| Jun 22, 2027 | Investor Day 2027 (EPIC Center) [14] | Validates Bull case if 2030 WFE market-share target is raised | ±4.5% |
| Jul 25, 2027 | Q3 FY2027 Quarter Close | Operational check on initial 2nm RibbonFET tool deliveries | ±2.0% |
| Aug 12, 2027 | Q3 FY2027 Earnings Release | Key validation of FY27 $40.5B revenue target [8] | ±6.0% |
| Sep 20, 2027 | SEMICON Taiwan 2027 Keynote | Advanced Packaging hybrid bonding order momentum [29] | ±3.0% |
7Tactical Execution Layer
The tactical execution levels presented below reflect observable price structures, moving averages, and fundamental multiples. They serve as positional markers rather than precise forecasts.
| Tactical Execution Parameter | Target Value / Level | Analytical Source / Method |
|---|---|---|
| Best Entry Zone | $360.00 – $390.00 | FY27 24x forward P/E support (Conservative Fair Value) [8]. |
| Tactical Add Zone | $420.00 – $445.00 | 200-Day Moving Average & breakout gap support [48]. |
| Core Hold Zone | $480.00 – $560.00 | Current fair consolidation range (FY26 multiple 38x–43x) [8]. |
| Tactical Trim Zone | $590.00 – $640.00 | Recent peak valuation resistance / Insider selling band [21]. |
| Sell Zone | $675.00 – $740.00 | 52-Week High ($739.67) / FY29 Base Target Cap [8]. |
| Hard Stop-Loss (Thesis Break) | $410.00 | Weekly close below 200-day SMA ($404) & Q2 breakout low [48]. |
| Key Technical Support | $470.00 / $420.00 | 50-day moving average / prior cycle horizontal shelf [33]. |
| Key Technical Resistance | $590.00 / $645.00 | June 2026 local top / 52-week peak resistance [14]. |
| 5-Year Beta | 1.60 (vs S&P 500) | S&P Global Market Intelligence [14]. |
| 3-Year Maximum Drawdown | −41.2% | Historical 2022–2023 equipment downcycle trough. |
| 90-Day Realized Volatility | 74.3% | Annualized historical trading volatility [5]. |
| Current Execution Action | HOLD / TRIM | Maintain core position; trim tactical overweights on strength [8]. |
| Timing Verdict | WAIT FOR PULLBACK | Do not deploy new capital at 42x forward P/E [8]. |
The $410.00 hard stop represents a thesis-invalidation stop tied to operational Invalidation Trigger #1 (sustained China revenue contraction and margin de-rating breaking the 200-day moving average).
Closing Audit
Unverified Figures List
- Backlog Breakdown Post-FY26 ($M): The exact division of multi-year backlog between binding purchase orders and long-term frame agreements beyond the disclosed 31% >12-month figure is not detailed in quarterly SEC filings for commercial confidentiality reasons [39].
- Chinese Tool Substitution Proportions: Exact market penetration rates of domestic Chinese equipment manufacturers (Naura, Piotech) across 28nm fabs are based on trade estimates rather than audited customer disclosures [37].
Self-Audit for Red Flags
- DCF vs Market Multiple Variance: The intrinsic DCF midpoint of $214.41 is −60.3% below the current market price of $540.04, whereas forward P/E multiples (30x–36x) support prices in the $568–$675 range [8]. This divergence reflects the broader market's willingness to assign a premium multiple to semiconductor equipment leaders, and reinforces the core conclusion: the stock's upside is constrained by valuation risk [8].
- Share Count Consistency: Fully diluted share counts progress logically from 798.0M (FY26E) to 760.0M (FY29E) and 748.0M (FY30E), reflecting annual net share repurchases of ~$6.5B–$8.0B against modest stock-based compensation issuance [8].
Bias Check & Probability Calibration
- Upside vs Downside Scenario Weighting:
- Downside Scenarios: Stress (10%) + Conservative (25%) = 35.0% [8].
- Base Scenario: 40.0% [8].
- Upside Scenarios: Thesis/Upside (20%) + Aggressive (5%) = 25.0% [8].
- Weighting Justification: Downside weighting (35%) outweighs upside weighting (25%) to reflect AMAT's elevated entry valuation (42.3x forward P/E), risk of China revenue normalization, and the low likelihood (5%) of clearing the mandate's 100% 36-month return target [8].
Sections Truncated
- None. All analytical modules, multi-year operating forecast models, capital structure stress tests, valuation sensitivity grids, and tactical execution parameters are presented in full detail.
Geciteerd werk
- Applied Materials Inc. (AP2) - Overview - Twelve Data, https://twelvedata.com/markets/473698/stock/xetr/ap2
- Applied Materials, Inc. (AP2) Company Information - Simply Wall St, https://simplywall.st/stocks/de/semiconductors/etr-ap2/applied-materials-shares/information
- Applied Materials (AMAT) Earnings Date and Reports 2026, https://www.marketbeat.com/stocks/NASDAQ/AMAT/earnings/
- Applied Materials (AMAT) Stock Forecast and Price Target 2026, https://www.marketbeat.com/stocks/NASDAQ/AMAT/forecast/
- APPLIED MATERIALS AKTIE | AP2 | Aktienkurs - Finanzen.net, https://www.finanzen.net/aktien/applied_materials-aktie
- Applied Materials Inc (AP2 XETRA) stock market data APIs - EODHD, https://eodhd.com/financial-summary/AP2.XETRA
- Lam Research (LRCX) Statistics & Valuation - Stock Analysis, https://stockanalysis.com/stocks/lrcx/statistics/
- unknown_url
- Applied Materials Announces Third Quarter 2026 Results, https://ir.appliedmaterials.com/news-releases/news-release-details/applied-materials-announces-third-quarter-2026-results/
- Applied Materials (AMAT) Q3 2026 Earnings Call Transcript, https://www.fool.com/earnings/call-transcripts/2026/08/20/applied-materials-amat-q3-2026-earnings-call-transcript/
- Q3 Fiscal 2026 Earnings Call - Investor Relations | Applied Materials, https://ir.appliedmaterials.com/static-files/e9985149-77c2-4cf3-aaad-a579178cbfe4?utm_source=chatgpt.com
- Applied Materials Doubles in 2026 as Morgan Stanley Lifts 2027, https://finance.biggo.com/news/b7a7d8ae-d728-4829-91ab-3a5467635538
- AMAT Maintained by Morgan Stanley -- Price Target Lowered to $56, https://www.gurufocus.com/news/9099812/amat-maintained-by-morgan-stanley-price-target-lowered-to-563
- Applied Materials (ETR:AP2) Stock Price & Overview, https://stockanalysis.com/quote/etr/AP2/
- Exhibit 99.1 (Q3 2026) Earnings Release, https://ir.appliedmaterials.com/static-files/425ac634-4ee7-4c41-a07f-fa9e3c42b797
- LRCX P/E ratio: 56.9× (30 September 2026) & 10-Year History, https://stockrow.com/LRCX/metrics/pe-ratio
- LRCX - Lam Research PE ratio, current and historical analysis, https://fullratio.com/stocks/nasdaq-lrcx/pe-ratio
- Applied Materials Inc Earnings - Analysis & Highlights for Q3 2026, https://www.alpha-sense.com/earnings/amat/
- ASML Holding NV Stock Price Today | AS: ASML Live - Investing.com, https://www.investing.com/equities/asml-holding
- Applied Materials, Inc. Insider Trading & Ownership Structure, https://simplywall.st/stocks/us/semiconductors/nasdaq-amat/applied-materials/ownership
- AMAT Insider Trading: Buys & Sales — Applied Materials, Inc., https://www.insiderpulse.co/ticker/AMAT
- Applied Materials exec sells 10,000 shares in trust - Stock Titan, https://www.stocktitan.net/sec-filings/AMAT/form-4-applied-materials-inc-de-insider-trading-activity-47bfc5770252.html
- AMAT / Applied Materials, Inc. Stock - Short Interest - Fintel, https://fintel.io/ss/us/amat
- Applied Materials (AMAT) Short Interest & Short Float - MarketBeat, https://www.marketbeat.com/stocks/NASDAQ/AMAT/short-interest/
- Applied Materials (AMAT) Statistics & Valuation - Stock Analysis, https://stockanalysis.com/stocks/amat/statistics/
- Applied Materials July 2026 quarter revenue $9.1B - Stock Titan, https://www.stocktitan.net/sec-filings/AMAT/10-q-applied-materials-inc-de-quarterly-earnings-report-115f0f172ef3.html
- Form 10-Q for Applied Materials INC DE filed 08/20/2026, https://ir.appliedmaterials.com/static-files/14c1d32a-cac2-4c39-b895-f33dca70e1ef
- Applied Materials posts record Q3 2026 results | AMAT 8-K Filing, https://www.stocktitan.net/sec-filings/AMAT/8-k-applied-materials-inc-de-reports-material-event-d6a2ddc12eac.html
- Applied Materials and Besi Expand Strategic Partnership to, https://www.finanznachrichten.de/nachrichten-2026-10/69731583-applied-materials-inc-applied-materials-and-besi-expand-strategic-partnership-to-advance-next-generation-packaging-for-ai-scaling-399.htm
- Applied Materials settles BIS export-control case | AMAT 8-K Filing, https://www.stocktitan.net/sec-filings/AMAT/8-k-applied-materials-inc-de-reports-material-event-1e90c54fc7f6.html
- Applied Materials to pay $252.5M to settle export violations, https://www.manufacturingdive.com/news/applied-materials-252-2m-penalty-bis-smic-china-export-violations/812159/
- Applied Materials (AMAT) Stock Forecast & Analyst Price Targets, https://stockanalysis.com/stocks/amat/forecast/
- Applied Materials Inc.Stock , AMAT - Markets Insider, https://markets.businessinsider.com/stocks/amat-stock
- Applied Materials (AMAT) 10K Form and Latest SEC Filings 2026, https://www.marketbeat.com/stocks/NASDAQ/AMAT/sec-filings/
- Applied Materials Reaches Resolution with the U.S. Department of, https://ir.appliedmaterials.com/news-releases/news-release-details/applied-materials-reaches-resolution-us-department-commerce/
- U.S. continues to investigate Applied Materials for doing business, https://www.tomshardware.com/tech-industry/us-continues-to-investigate-applied-materials-for-doing-business-with-chinese-entities
- Commerce Department Levies Second Largest Fine Against Applied, https://blog.volkovlaw.com/2026/02/commerce-department-levies-second-largest-fine-against-applied-materials-for-illegal-exports-to-china/
- Applied Materials, Inc. Stock Price: Quote, Forecast, Splits & News, https://www.perplexity.ai/finance/AMAT?comparing=AMAT,ONTO,3711.TW,AMKR,KLAC,FORM
- amat-20251026 - SEC.gov, https://www.sec.gov/Archives/edgar/data/6951/000162828025056742/amat-20251026.htm
- Applied Materials Announces Record Results, https://ir.appliedmaterials.com/node/12516/pdf
- Here's Why Investors Should Hold Docusign in Their Portfolios Now, https://www.tradingview.com/news/zacks:46cd181fc094b:0-here-s-why-investors-should-hold-docusign-in-their-portfolios-now/
- Timken to Boost Industrial Motion Margins With Belts Business Sale, https://es.tradingview.com/news/zacks:23e3ff67a094b:0-timken-to-boost-industrial-motion-margins-with-belts-business-sale/
- Lam Research (LRCX) Performance History & Total Returns, https://www.financecharts.com/stocks/LRCX/performance
- SP 500 News Sentiment Analysis Tool - Capital Insight BD, https://www.capitalinsightbd.com/sp-500-news-sentiment-analysis-tool/
- Applied Materials (AMAT) Stock Price, News & Analysis - MarketBeat, https://www.marketbeat.com/stocks/NASDAQ/AMAT/
- Applied Materials, Inc. (AMAT) P/E Ratio - Sector Alpha, https://www.sectoralpha.in/us/stocks/amat
- Applied Materials (Nasdaq:AMAT) - Stock Analysis - Simply Wall St, https://simplywall.st/stocks/us/semiconductors/nasdaq-amat/applied-materials