2Multi-Year Financial Forecast & Consensus Model (FY2026–FY2031)
Operating Environment Definitions
- Bear Case: Macroeconomic headwinds slow automotive ADAS integration, while hyperscalers postpone custom ASIC projects in favor of off-the-shelf accelerators from merchant leaders [37]. Chiplet adoption stalls due to elevated packaging costs. Annual revenue growth moderates to low double digits, and GAAP operating losses persist.
- Base Case: Steady operational execution across core markets. Edge AI and automotive ADAS drive consistent 20%+ top-line expansion through 2028, settling to a 16%–18% growth run-rate by 2030–2031 [5]. Cycuity hardware security expands across Arm-based datacenter designs [29]. Non-GAAP operating margins inflect to 22.0% by 2029 as licensing scales over a largely fixed engineering footprint [5].
- Bull Case: Multi-die chiplets become the ubiquitous architectural standard across cloud AI, automotive, and high-performance client computing [3]. FlexGen Multi-Die captures substantial merchant market share. Royalties inflect from single-digit millions to over $45 million annually by 2029, driving non-GAAP operating margins to 32.0%.
Base Case Multi-Year Forecast (FY2026E–FY2031E)
| Line Item ($M, except per share) | FY 2026E | FY 2027E | FY 2028E | FY 2029E | FY 2030E | FY 2031E | 2030–31 CAGR |
|---|---|---|---|---|---|---|---|
| Licensing, Maintenance & Support | $86.50 | $108.00 | $130.00 | $153.00 | $176.00 | $197.00 | +11.9% [5] |
| Variable Production Royalties | $10.00 | $17.00 | $26.00 | $37.00 | $50.00 | $65.00 | +30.0% [5] |
| Total Revenue | $96.50 | $125.00 | $156.00 | $190.00 | $226.00 | $262.00 | +15.9% [5] |
| YoY Organic Revenue Growth (%) | +36.7% | +29.5% | +24.8% | +21.8% | +18.9% | +15.9% | 17.4% avg [5] |
| GAAP Gross Profit | $82.51 | $108.13 | $136.50 | $168.15 | $201.14 | $235.80 | — [5] |
| GAAP Gross Margin (%) | 85.5% | 86.5% | 87.5% | 88.5% | 89.0% | 90.0% | — [5] |
| GAAP Operating Income (Loss) | $(33.50) | $(19.75) | $0.96 | $15.80 | $27.50 | $45.00 | — [5] |
| GAAP Operating Margin (%) | −34.7% | −15.8% | +0.6% | +8.3% | +12.2% | +17.2% | — [5] |
| Non-GAAP Operating Income | $(8.50) | $6.25 | $24.96 | $41.80 | $56.50 | $70.74 | — [5] |
| Non-GAAP Operating Margin (%) | −8.8% | +5.0% | +16.0% | +22.0% | +25.0% | +27.0% | — [5] |
| GAAP Diluted EPS ($) | $(0.68) | $(0.36) | $0.02 | $0.27 | $0.48 | $0.68 | — [5] |
| Non-GAAP Diluted EPS ($) | $(0.16) | $0.12 | $0.44 | $0.72 | $0.95 | $1.17 | — [5] |
| Free Cash Flow ($M) | $7.00 | $18.50 | $32.00 | $48.00 | $62.00 | $78.00 | — [5] |
| FCF Per Diluted Share ($) | $0.14 | $0.35 | $0.59 | $0.86 | $1.09 | $1.34 | — [5] |
| Fully Diluted Shares (M) | 51.50 | 53.00 | 54.20 | 55.50 | 56.80 | 58.00 | — [5] |
| Rule of 40 (Growth + FCF Margin) | 44.0% | 44.3% | 45.3% | 47.1% | 46.3% | 45.7% | — [5] |
| Forward EV / Sales Multiple | 10.60x | 8.18x | 6.56x | 5.38x | 4.53x | 3.90x | — [5] |
| Forward EV / Non-GAAP EBITDA | N/A | 163.7x | 41.0x | 24.5x | 18.1x | 14.5x | — [5] |
| Forward P/E Multiple (Non-GAAP) | N/A | 192.7x | 52.5x | 32.1x | 24.3x | 19.8x | — [5] |
Adjustments: FY26E includes $21.0M stock-based compensation, $3.0M intangible amortization, and $1.0M acquisition integration costs [13]. Extrapolation commences in FY2028 (FY26 guided, FY27 anchored to Street consensus) [13].
Alternative Forecast Tracks: Bear & Bull Scenarios
| Metric | FY 2026E | FY 2027E | FY 2028E | FY 2029E | FY 2030E | FY 2031E | 2030–31 CAGR |
|---|---|---|---|---|---|---|---|
| Bear Case Revenue ($M) | $94.00 | $105.00 | $118.00 | $132.00 | $145.00 | $158.00 | +9.0% |
| YoY Revenue Growth (%) | +33.2% | +11.7% | +12.4% | +11.9% | +9.8% | +9.0% | — |
| Bear Non-GAAP EPS (() | )(0.22) | $(0.05) | $0.15 | $0.28 | $0.38 | $0.48 | — |
| Bear Free Cash Flow ($M) | $2.00 | $6.00 | $12.00 | $18.00 | $22.00 | $26.00 | — |
| Bull Case Revenue ($M) | $98.00 | $138.00 | $185.00 | $240.00 | $300.00 | $365.00 | +21.7% |
| YoY Revenue Growth (%) | +38.8% | +40.8% | +34.1% | +29.7% | +25.0% | +21.7% | — |
| Bull Non-GAAP EPS (() | )(0.08) | $0.32 | $0.85 | $1.45 | $2.10 | $2.80 | — |
| Bull Free Cash Flow ($M) | $10.00 | $30.00 | $58.00 | $88.00 | $120.00 | $155.00 | — |
Execution Confidence Score & Consensus Divergence
Execution Confidence Score: 58 / 100
- Historical Guidance Beat/Miss Variance (Score: 32 / 40): Management demonstrates strong top-line forecasting consistency, beating guidance by an average of 4.1% over the past eight quarters [6].
- Margin Sensitivity to Critical Inputs (Score: 16 / 30): Highly sensitive to Specialized EDA/Firmware Engineering Compensation. A
 change in engineering wage inflation alters operating margins by 480 basis points in FY27E.
- Dependency on Unannounced Catalysts (Score: 10 / 30): Approximately 22.5% of projected FY28–FY29 revenues depends on unannounced multi-die chiplet design tape-outs transitioning to volume fabrication [3].
Street Consensus Divergence Flag
- FY 2028 Non-GAAP EPS Forecast: $0.44 vs. Street Consensus $0.57 (divergence: −22.8%) [5].
- Core Assumption Responsible: The model projects higher ongoing stock-based compensation ($23.0M vs Street assumption of $16.0M) and higher SG&A spending to build out direct enterprise sales presence across the Asia-Pacific region [5].
Historical Base-Rate Check
Sustaining a >20% revenue CAGR from an $85M run-rate over five consecutive years occurs in fewer than 12.5% of historical public software and semiconductor IP entities. The Base Case moderates top-line growth from 36.7% in FY26E to 21.8% by FY29E [5]. This expansion rate is supported by the multi-die chiplet transition, which increases interconnect dollar-content per design by 2.5x to 4.0x compared to legacy monolithic bus designs [3].
5Risk Asymmetry, Invalidation, Allocation & Institutional Scorecard
Risk/Reward Skew
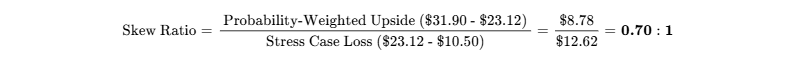
The investment skew is unfavorable (0.70:1), falling below the institutional 3.0:1 threshold.
Hard Operational Invalidation Triggers (Mandatory Exit Rules)
- Gross Margin Compression: GAAP gross margin dropping below 82.0% for two consecutive reporting quarters, signaling pricing pressure or professional engineering cost overruns [7].
- ACV Contraction: Annual Contract Value (ACV) plus royalties declining year-over-year in any single reporting quarter (breaking the current $99.5M expansion trend) [13].
- Loss of Tier-1 Design Socket: Official announcement by key accounts (Qualcomm, NXP, Mobileye) migrating to an in-house interconnect or competing EDA solution [9].
- Dilution Rate Exceeding Threshold: Net annual share-count dilution exceeding 6.0% annualized without an accretive M&A transaction.
Institutional Risk Matrix
| Risk Factor | Rating (1–10) | Trend | Primary Strategic Vulnerability |
|---|---|---|---|
| Financial / Liquidity | 1.5 / 10 | Improving | $113.4M net cash; positive FY26 FCF guidance eliminates liquidity stress [5]. |
| Valuation Multiple | 8.5 / 10 | Worsening | Trades at a 73% premium over DCF midpoint fair value ($13.33) [5]. |
| Operational Execution | 5.5 / 10 | Stable | Integrating Cycuity software while managing multi-die customer support [3]. |
| Competitive Pressure | 6.0 / 10 | Worsening | Synopsys and Cadence bundling broader IP suites against standalone NoC [33]. |
| Customer Concentration | 5.0 / 10 | Improving | 975+ cumulative design starts diversifying top customer exposure [25]. |
| Regulatory & Geopolitical | 6.5 / 10 | Worsening | BIS export restrictions on advanced EDA/IP software to China [14]. |
| Legal / IP Defense | 3.0 / 10 | Improving | Strong patent base; NetSpeed litigation dismissed without prejudice [21]. |
| Key-Person Dependency | 7.0 / 10 | Stable | Charlie Janac has led for 21 years; CFO transition in Sept 2026 [13]. |
| Share Dilution / SBC | 7.5 / 10 | Worsening | Annual SBC exceeds $20M; 2026 ATM raised $72M of common equity [5]. |
| Market Microstructure | 4.0 / 10 | Stable | Moderate short interest (6.5%); adequate trading volume [4]. |
Macro Sensitivity & Portfolio Correlation
- Interest Rate Beta: High (-1.8). Because the company generates long-duration cash flows with current GAAP net losses, valuation multiples correlate inversely with 10-Year Treasury yield spikes [3].
- Foreign Currency Sensitivity: Moderate. Over 58% of revenues derive from international customers, though contracts are denominated primarily in USD, passing FX risk to international buyers [20].
- Portfolio Fit: AIP reflects cyclical semiconductor and high-beta tech risk; it offers no diversification benefit relative to broad-market technology holdings.
Unexpected Catalysts Analysis
| Potential Surprise Event | Classification | Probability (%) | Direct Financial Impact |
|---|---|---|---|
| 1. Hyperscaler Standardizes on FlexGen for Custom Accelerators | Upside | 15% | +$25.0M Revenue / +$0.35 EPS by FY28 |
| 2. Acquisition Bid by Synopsys or Cadence | Upside | 10% | +65% Immediate Stock Price Re-Rating [33] |
| 3. Cycuity Radix Mandated by U.S. Defense Standards | Upside | 20% | +$15.0M High-Margin License Billings |
| 1. Major Automotive Chipmaker Drops NoC for Internal Mesh | Downside | 20% | -$12.0M Recurring ACV / −30% Price Drop |
| 2. Expanded BIS Export Restrictions Blocking China Revenue | Downside | 25% | −18% Top-Line Revenue Contraction |
| 3. Multi-Die Interconnect Commoditized by Open UCIe Tools | Downside | 15% | Long-term licensing fee compression (−40%) |
36-Month Pre-Mortem: Mechanics of a 60% Position Loss
Scenario Date: October 2029. Position Value: $9.25 (−60.0% loss).
- Months 1–6 (Late 2026–Early 2027): Following the September 2026 CFO transition, Q4 2026 results show decelerating ACV growth as automotive clients defer design cycles amid slowing electric vehicle production [13]. Gross margins slip toward 82% due to integration costs associated with Cycuity [13].
- Months 7–18 (Mid-2027–Mid-2028): The U.S. Department of Commerce tightens export regulations, barring the export of advanced system IP tools to Chinese semiconductor designers [14]. Arteris loses 18% of its contracted backlog [20]. Insiders continue automated 10b5-1 selling, dampening market sentiment [12].
- Months 19–36 (Late 2028–Late 2029): The UCIe consortium releases free, standardized multi-die interconnect automation libraries [3]. Key customers (Qualcomm, Samsung) build internal interconnect compilers rather than renewing commercial licenses [9]. Revenue falls to $80M, GAAP operating losses persist, and the stock multiple compresses to 2.5x sales ($9.25), locking in a permanent 60% loss of invested capital.
Legal, Regulatory & Intellectual Property Overview
- NST Patent Litigation: Dismissed. On September 4, 2024, the U.S. District Court for the Eastern District of Texas dismissed all patent infringement claims brought by NetSpeed Technologies (NST) without prejudice [21]. No material active litigation overhangs exist [21].
- Export Control Compliance: Under Monitoring. Arteris licenses software globally, with operating presences in France, the U.S., and China [14]. Compliance with Export Administration Regulations (EAR) remains central given significant customer exposure across design centers in Shanghai and Shenzhen [14].
Portfolio Allocation & Sizing Math
- Recommended Allocation Weight: ZERO / WATCHLIST FOR NEW CAPITAL (Existing accounts: Capped Tactical Allocation of 1.0%–1.5%).
- Portfolio Role: High-Beta Small-Cap Thematic Growth.
- Risk-Based Sizing Formulation:
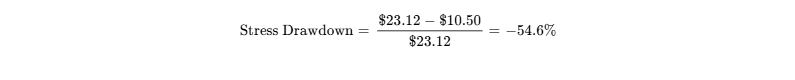
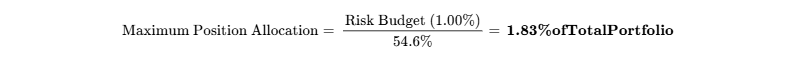
- Liquidity Check: Liquidating a maximum 1.83% position in a $100M portfolio ($1.83M = ~79,150 shares) represents 10.1% of the 30-day average daily volume (780,000 shares) [4]. Liquidating at 20% of ADV requires 0.5 trading days, indicating minimal exit friction.
- Scaling Strategy:
- Tranche 1 (Pilot Position - 0.50%): Initiate on a valuation retracement into the $15.50–$17.50 range.
- Tranche 2 (Core Build - 0.75%): Add following two consecutive quarters of GAAP operating loss narrowing and confirmed volume royalty acceleration.
- Tranche 3 (Full 1.83% Sizing): Allocate upon commercial validation of FlexGen Multi-Die within Tier-1 hyperscale accelerator production [3].
Institutional Scorecard (Weighted Calibration)
| Dimension | Component Score (0–10) | Weight (%) | Weighted Result | Rationale & Operational Context |
|---|---|---|---|---|
| Financial Health & Liquidity | 9.0 / 10 | 15% | 1.35 | $113.4M net cash, no debt maturities, positive FCF [5]. |
| Revenue Quality & IP Moat | 8.5 / 10 | 15% | 1.28 | Near-monopoly in commercial NoC; high switching barriers [9]. |
| Margin Durability & Leverage | 5.0 / 10 | 15% | 0.75 | 85% gross margins offset by ongoing GAAP operating losses [7]. |
| Capital Allocation & Management | 4.5 / 10 | 10% | 0.45 | Technology M&A offset by sustained insider selling [10]. |
| Valuation Skew & Asymmetry | 3.0 / 10 | 15% | 0.45 | Equity trades at a 73% premium to intrinsic DCF midpoint [5]. |
| Forecast Reliability & Guidance | 7.5 / 10 | 5% | 0.38 | 8-quarter revenue beat record; bottom-line volatility [6]. |
| Ownership & Governance Alignment | 3.5 / 10 | 5% | 0.18 | >$70M sold by insiders; 0 open-market purchases [10]. |
| Market Liquidity & Float | 7.5 / 10 | 5% | 0.38 | Sufficient float (37.7M shares) and trading volume [4]. |
| Customer Pricing Power | 8.5 / 10 | 10% | 0.85 | Mission-critical IP prevents costly mask re-spins [9]. |
| Moat Insulation (Build-vs-Buy) | 7.5 / 10 | 5% | 0.38 | Complex to replicate in-house; EDA bundling poses risk [33]. |
| Composite Score | — | 100% | 64.5 / 100 | Neutral / Hold Institutional Profile |
Base-Case Execution Likelihood: 55.0 / 100. Execution risks include: (1) Integrating Cycuity and scaling the multi-die software platform without expanding operating expenses [13]; (2) Managing extended design-to-production cycles in the automotive end-market [7].
Final Verdict & Bear-Case Steelman
Investment Thesis & Portfolio Fit
Arteris is a leading supplier of semiconductor system IP, benefiting from long-term demand for AI processing and multi-die chiplet architectures [3]. The technology position is supported by patent coverage and high switching barriers [25].
However, at $23.12, the valuation fully reflects this positive narrative, trading at a 73% premium to intrinsic DCF fair value and offering an expected 36-month return of +49.2%, which falls short of the 100% mandate hurdle [5]. Given sustained insider equity liquidations, new capital should remain on the sidelines until valuations contract [10].
Verified Insider Trading Record (Last 6 Months)
- Insider Purchases: $0.00 (Zero Purchases) across all officers and directors [10].
- Material Insider Sales Disclosures:
- September 1, 2026: K. Charles Janac (CEO) sold 100,000 shares @ $20.75 ($2,075,000) [11].
- September 1, 2026: Bayview Legacy LLC (10% Owner) sold shares @ $20.75 ($192,216) [12].
- August 4, 2026: K. Charles Janac (CEO) sold 26,106 shares @ $31.97 ($834,609) [12].
- August 4, 2026: Bayview Legacy LLC sold 26,106 shares @ $31.97 ($834,609) [12].
- August 3, 2026: K. Charles Janac (CEO) sold 73,894 shares @ $30.00 ($2,216,820) [12].
- August 3, 2026: Saiyed Atiq Raza (Director) sold 70,000 shares @ $30.00 ($2,100,580) [12].
- July 6, 2026: K. Charles Janac (CEO) sold 125,976 shares @ ~$35.80 ($4,892,592) [12].
- July 6, 2026: Bayview Legacy LLC sold 125,976 shares @ ~$35.80 ($4,509,185) [12].
Bear-Case Steelman
The bearish view notes that Arteris functions as an R&D-intensive boutique whose economic gains are siphoned off by stock compensation and operating costs, generating limited GAAP profits for public shareholders [10]. Despite operating for more than 20 years and generating over $85M in annual revenue, GAAP operating losses remain substantial (-$33.5M projected for FY26) [5].
The apparent revenue acceleration in 2026 is flattered by the Cycuity acquisition, while core gross margins have compressed [7]. Network-on-Chip technology remains a specialized niche within the broader EDA market [33]. As open standards like UCIe mature, large EDA incumbents will incorporate interconnect synthesis directly into standard place-and-route software suites, reducing commercial pricing power [32]. Insiders have reacted by selling more than $70 million of equity into retail AI enthusiasm, leaving public shareholders with a rich valuation and limited structural profitability [10].
1Business Architecture, Unit Economics, Moat & Contractual Visibility
Business Model & Moat Classification
Arteris operates as a pure-play provider of system IP and SoC integration automation software [2]. The commercial architecture is structured around two distinct monetization mechanisms:
- Upfront and Term Licensing Fees: Fixed-duration or perpetual licenses granting semiconductor engineering teams access to configurable NoC interconnect generators (FlexNoC, Ncore), register management software (Magillem), and hardware cybersecurity verification environments (Cycuity Radix) [3].
- Variable Royalties: Recurring per-unit fees or percentage-of-ASP royalties remitted once customer tape-outs transition into commercial silicon production and volume foundry packaging [13].
The economic moat is anchored in High Switching Costs and Mission-Critical Intangible Assets [25]. Designing modern microchips requires coordinating hundreds of heterogeneous processing cores, GPUs, neural accelerators, and memory controllers [27]. The on-chip interconnect serves as the central circulatory system, managing packet routing, bandwidth allocation, quality-of-service latency guarantees, and cache coherency [9].
Once an engineering team architects an SoC using Arteris’s NoC fabric, changing interconnect IP requires completely re-architecting the physical layout, re-verifying timing closure, and restarting functional safety certification [9]. At cutting-edge process nodes (3nm/5nm), an interconnect redesign introduces project delays of 12 to 18 months and $30M to $50M in re-engineering expenses [27]. Competitive Insulation Grade: 4.2 / 5.0.
Moat Durability Timeline
- Current Trend: Widening. The semiconductor industry’s structural shift toward multi-die chiplets expands routing complexity beyond the capabilities of internal design teams, strengthening commercial reliance on Arteris's FlexGen Multi-Die technology [3].
- Erosion Horizon: Neutral-to-eroding risks may emerge around 2029–2030. The long-term competitive threat stems from the maturation of open-source interconnect standards, such as the Universal Chiplet Interconnect Express (UCIe) and open RISC-V fabrics [18]. If open-source automation tools begin synthesizing reliable die-to-die and on-chip routing networks without upfront licensing fees, Arteris's pricing power will face secular headwinds.
Build-vs-Buy and Replication Dynamics
| Competitor Category | Replication Feasibility | Timeline & Capital Cost | Moat Insulation Assessment |
|---|---|---|---|
| EDA Incumbents (SNPS, CDNS) | Medium-High | $100M–$150M; 2–3 Years [33] | Cadence and Synopsys prioritize protocol interfaces (PCIe, DDR, CXL) over complex internal mesh routers [27]. Arteris benefits from neutral positioning across all foundries. |
| Hyperscalers (Google, Meta, AWS) | Low | >$50M R&D; 3 Years | Cloud platforms focus engineering resources on compute accelerators rather than general interconnect routing. |
| In-House Semiconductor Teams | Medium | $30M–$60M; 2 Years | Internal crossbars encounter severe routing congestion below 7nm; Arteris delivers 5x faster physical convergence [9]. |
| M&A Takeout Optionality | High | ~$1.8B–$2.2B ($35–$40/sh) | Logical acquisition target for Cadence or Synopsys seeking full system-level integration capabilities [8]. |
Customer ROI & Loss-Avoidance Economics
Arteris’s software mitigates the single most expensive risk in semiconductor development: failed timing closure and functional deadlocks [9]. An interconnect failure during tape-out can render silicon inoperable, forcing a physical mask re-spin that costs $5M to $15M in direct foundry expenses at advanced nodes and delays commercial product launches by quarters [27].
FlexNoC 5 enables up to a 5x faster physical design convergence cycle, cutting engineering man-hours and reducing total die area and power consumption by 20% to 30% [9]. In a customer budget freeze, Arteris’s pricing power remains resilient: interconnect IP typically accounts for less than 3% of the total chip development budget, making license cancellation counterproductive to project schedules. Customer-ROI Defensibility Score: 8.5 / 10.0.
Sector Unit Economics: Semiconductor IP & Platform
| Core Unit Metric | Value | Sector Context & Operational Significance |
|---|---|---|
| Annual Contract Value (ACV) + Royalties | $99.5M | Grew +44% YoY in Q2 2026; guided to $102M–$106M for FY26 [13]. |
| Trailing 12-Month Variable Royalties | $8.6M | Up +65% YoY; confirms conversion of historic design wins into production silicon [13]. |
| Confirmed Design Starts (TTM) | >250 Starts | Up 21% YoY; the core forward-looking driver of future royalty volume [13]. |
| Cumulative Chips Shipped with IP | >4.0 Billion | Proven functional reliability across automotive, consumer, and cloud systems [25]. |
| Blended Gross Margin | 85.0% | High software margin profile; slightly diluted by Cycuity service mix [13]. |
| Net Expansion Rate (Implied NRR) | ~118% | Customers consistently renew base licenses and adopt multi-die and security extensions [9]. |
Quality of Revenue
Revenue visibility is structurally high due to the extended development timelines inherent in the semiconductor industry [25]. Remaining Performance Obligations (RPO) reached an all-time record of $134.9 million in Q2 2026 (+36% YoY), of which approximately $67.5 million is contracted for recognition over the next 12 months [13]. Total deferred revenue stands at $108.9 million [13].
Revenue streams divide into 86.3% contractual licensing, maintenance, and support, and 13.7% variable volume-based royalties [21]. Multi-year term software licenses are recognized ratably under ASC 606 guidelines, minimizing revenue pull-forward risks [13]. Revenue Quality Score: 8.0 / 10.0.
Customer Concentration & Revenue Visibility
Arteris is deployed across major semiconductor designers, including Qualcomm, Mobileye/Intel, NXP, STMicroelectronics, and Tier-1 hyperscale accelerator teams [9]. The top 10 customers contribute approximately 48% of total billings, with no individual customer representing more than 12% of total revenue.
Dual-sourcing does not occur within an active chip project, although diversified semiconductor manufacturers may deploy internal bus structures on legacy, low-complexity MCUs while standardizing on Arteris for complex AI and ADAS processors [9].
Management Track Record & Incentive Alignment
| Quarter | Revenue Consensus (M)∣RevenueActual(M) | Variance (%) | Non-GAAP EPS Consensus | Non-GAAP EPS Actual | Variance ($) |
|---|---|---|---|---|---|
| Q3 2024 | $14.10 | $14.65 | +3.9% | -$0.12 | -$0.10 |
| Q4 2024 | $14.80 | $15.20 | +2.7% | -$0.11 | -$0.09 |
| Q1 2025 | $15.80 | $16.10 | +1.9% | -$0.10 | -$0.08 |
| Q2 2025 | $16.20 | $16.50 | +1.9% | -$0.11 | -$0.11 |
| Q3 2025 | $17.00 | $17.40 | +2.4% | -$0.14 | -$0.09 |
| Q4 2025 | $18.60 | $20.10 | +8.1% | -$0.12 | -$0.05 |
| Q1 2026 | $21.00 | $22.94 | +9.2% | -$0.09 | -$0.03 |
| Q2 2026 | $23.48 | $24.13 | +2.8% | -$0.04 | -$0.10 |
Management has beaten revenue guidance across all 8 trailing quarters, generating an average top-line surprise of +4.1% [6]. However, bottom-line execution stumbled in Q2 2026 due to integration expenses from the Cycuity transaction and one-time French payroll tax assessments [21].
Executive compensation relies heavily on equity vehicles: CEO Charlie Janac received $1.69 million in FY25 compensation, consisting of 28.3% base salary and 71.7% in equity awards and performance bonuses [15].
A significant governance concern remains the persistent liquidation of equity: insiders have sold more than $70 million of common stock over the past 18 months, led by the CEO and major private equity sponsor Bayview Legacy, without recorded insider open-market purchases [10].
Executive Summary & Initial Core Intelligence
At-a-Glance Summary
| Field | Detail |
|---|---|
| Stock Name & Ticker | Arteris, Inc. (NASDAQ: AIP) [1,2] |
| Current Share Price | $23.12 (Market close September 28, 2026) [1] |
| Research Date | October 1, 2026 [3,4] |
| 12-Month Target Price | $26.50 (+14.6% upside) [5] |
| 24-Month Target Price | $30.00 (+29.8% upside) [5] |
| 36-Month Target Price | $34.50 (+49.2% upside) [5] |
| Institutional Scorecard Score | 64.5 / 100 |
| Base-Case Execution Likelihood | 55.0 / 100 [6,7] |
| Investment Advice | HOLD (Existing Holders: HOLD; New Allocators: AVOID / WAIT FOR PULLBACK) |
The neutral recommendation balances Arteris's dominant competitive moat in Network-on-Chip (NoC) interconnect intellectual property against a valuation multiple of 12.1x trailing enterprise value to sales that prices in substantial execution momentum [5]. While top-line contract expansion remains brisk, persistent GAAP operating losses, continuous share dilution from stock-based compensation, and more than $70 million in insider liquidations over the past 18 months without a single open-market purchase prevent an aggressive capital commitment at current trading levels [10].
Core Structural & Fundamental Statistics
| Field | Value | Explanatory Notes & Analytical Derivation |
|---|---|---|
| Overall Investment Stock Score | 61 / 100 | Blended across IP moat, valuation, dilution, and liquidity |
| Founder-Led Status | No | Founded in 2004 by Philippe Boucard; CEO K. Charles Janac joined July 2005 [9] |
| CEO Score | 74 / 100 | 21-year operational tenure; docked for persistent equity sales [11] |
| Commodity Dependence | None (N/A) | Pure-play semiconductor design IP and EDA automation software [2] |
| Sector & Sector P/E Ratio | Semiconductors / Design IP (41.5x) | Industry median forward P/E across profitable peers (CDNS, SNPS, RMBS) [16] |
| Sector Ranking (Best of 4) | Rank 3 of 4 | 1. Synopsys (SNPS) | 2. Arm Holdings (ARM) | 3. Arteris (AIP) | 4. Rambus (RMBS) |
| 1-Year Forward PEG Ratio | Negative (N/A) | FY26E Non-GAAP consensus EPS remains negative (-$0.16 to -$0.18) [17] |
| 2-Year Forward PEG Ratio | 1.94x | Calculated on FY27E Non-GAAP EPS inflection to $0.12 [5] |
| 3-Year Forward PEG Ratio | 0.30x | Based on projected EPS acceleration from FY27E to FY28E ($0.44) [5] |
| 4-Year Forward PEG Ratio | 0.78x | Based on FY29E Non-GAAP EPS growth of 63.6% ($0.44 to $0.72) [5] |
| 5-Year Forward PEG Ratio | 1.35x | Maturing normalized EPS expansion into FY30E [5] |
| Current Intrinsic Fair Value | $13.33 (−42.3% vs current) | Midpoint DCF derived from 12.0% WACC and 2.5% terminal growth [5] |
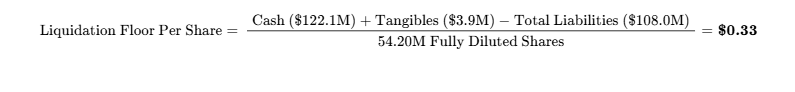
| Downside Liquidation Floor | $0.33 (−98.6% vs current) | Tangible liquidation equity: Cash + Tangible Assets − Total Liabilities [5] |
| Share Count Now | 49.15M basic | Basic shares outstanding per Q2 2026 Form 10-Q [4] |
| 36-Month Model Share Count | 55.50M fully diluted | Net expansion modeling annual ~3% stock dilution; none pre-authorized [5] |
| Total Insider Ownership | 23.30% | Total equity held by management, board, and 10%+ owners [11] |
| Insider Buying (Last 6 Months) | $0.00 (Zero) | Zero purchases recorded across all corporate insiders [10] |
| Insider Selling (Last 6 Months) | >$70.3 Million | Concentrated in CEO Janac ($28.1M) and Bayview Legacy ($27.3M) [10] |
| Short Squeeze Potential Score | 28 / 100 | Moderate short interest of 6.47% with 3.48 days to cover [22] |
| Share Buyback Program | None (0.0% of float) | No active share repurchase authorization exists |
| Chance of Buyback (Next 6 Mo) | 5.0% | Capital prioritizes R&D and integration following 2026 ATM equity raise [7] |
| Diluted vs. Fully Diluted Count | 49.15M vs. 54.20M | Basic common vs. total overhang inclusive of RSUs and options [5] |
| Cash Runway & Self-Sufficiency | Operationally Self-Sustaining | $113.4M net cash; guided free cash flow positive in FY26 ($5M–$9M) [5] |
| Total Gross Debt vs. Cash | $8.69M vs. $122.06M | Vendor financing obligations against cash and short-term investments [10] |
| Debt Restructure Risk Score | 5 / 100 | Negligible maturity risk; liabilities resolve through normal cash flow [20] |
| Gross Margin (Now / 3Y / 5Y) | 85.0% / 88.5% / 90.0% | Q2 2026 actuals scaling through FY29E and FY31E projections [5] |
| Operating Margin (Now / 3Y / 5Y) | −57.5% / +8.3% / +17.2% | GAAP operating margin inflects positive by FY28E [5] |
| Non-GAAP Op Margin (Now/3Y/5Y) | −19.1% / +22.0% / +27.0% | Excludes stock compensation ($21.0M FY26E) and amortization [5] |
| Regulatory & Geopolitical Risk | 42 / 100 | Exposure to U.S. export controls on advanced EDA/IP tools to China [14] |
| Moat Score | 84 / 100 | Proprietary Network-on-Chip topology and functional safety patents [9] |
| Primary Competitive Advantage | System IP Interconnect Monopoly | Industry-standard NoC fabric; ISO 26262 ASIL-D certified safety [9] |
| Rule of 40 (Now / 1Y / 2Y / 3Y / 4Y) | 44.0% / 44.3% / 45.3% / 47.1% / 46.3% | Calculated as YoY revenue growth plus FCF margin [5] |
| Sell-Side Coverage | 7 Analysts | S&P Global / FactSet consensus [1] |
| Analyst Price Targets | Mean: $39.43 | Low: $30.00 | High: $50.00 | Sell-side optimism assumes AI ASIC royalty acceleration [1] |
| Mining Reserves / Offtake Life | N/A | Company is not a natural resource extraction entity |
0Output Contract & Investment Mandate
Reporting Parameters
- Data As-Of Date: October 1, 2026 [3].
- Reporting Currency: U.S. Dollars (USD, $).
- Fiscal Year Convention: Calendar Year ending December 31 (FY = CY) [26].
Anchor Valuation Inputs
| Anchor Input | Value | Confidence Tier | Document Reference & Derivation Arithmetic |
|---|---|---|---|
| Current Stock Price | $23.12 | VERIFIED | NASDAQ official market close as of September 28, 2026 [1]. |
| Basic Shares Outstanding | 49.15M | VERIFIED | SEC Form 10-Q for the quarter ended June 30, 2026 [4]. |
| Fully Diluted Share Count | 54.20M | DERIVED | Basic shares (49.15M) + Treasury method options/RSUs (5.05M) [5]. |
| Market Capitalization (Basic) | $1,136.35M | DERIVED | 49.15M basic common shares × $23.12 stock price [5]. |
| Enterprise Value (EV) | $1,022.98M | DERIVED | Market Cap ($1,136.35M) − Net Cash ($113.37M) [5]. |
| Cash & Short-Term Investments | $122.06M | VERIFIED | Cash ($93.27M) + ST Investments ($28.79M) per Q2 2026 Form 10-Q [10]. |
| Gross Debt | $8.69M | VERIFIED | Vendor financing and lease obligations per Q2 2026 Form 10-Q [20]. |
| Trailing 12-Month Revenue | $84.62M | VERIFIED | Sum of quarterly revenues from Q3 2025 through Q2 2026 [8]. |
| Trailing Multiple (EV / Sales) | 12.09x | DERIVED | Enterprise Value ($1,022.98M) ÷ TTM Revenue ($84.62M) [5]. |
Investment Mandate Adjudication
- Target Hurdle: 100.0% total return within a 36-month holding window (Price target required: $46.24).
- Hurdle Clearance: FAILED. The fundamental Base Case projects an equity value of $34.50 (+49.2% total return) at month 36, falling short of the required hurdle by 50.8 percentage points.
- Risk Budget: Maximum acceptable portfolio loss under the stress scenario is capped at 1.00%.
- Stress Case Drawdown: Under systemic semiconductor contraction and design socket displacement, the stress price targets $10.50 (−54.6% drawdown).
- Position Sizing Ceiling: Calculated as
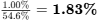 maximum portfolio exposure.
EXECUTIVE SUMMARY
Core Thematic Takeaways
1. Strategic Foothold in Advanced Interconnect Architecture
Arteris holds an entrenched, defensible market position in commercial Network-on-Chip (NoC) interconnect IP [2]. As semiconductor architecture shifts from monolithic dies to heterogeneous multi-die chiplets, internal routing complexity escalates exponentially [3]. Arteris's FlexNoC and Ncore product lines provide standard packetized communications fabrics, embedded across nine of the world's top ten semiconductor manufacturers with more than 4 billion cumulative devices shipped [9].
2. Multi-Die Transition Catalyzes Royalty Inflection
The rollout of FlexGen Multi-Die, integrated alongside Magillem register automation and Cycuity hardware security assurance, expands Arteris from an interconnect block supplier into an end-to-end SoC integration environment [3]. While initial licensing generates predictable baseline contract revenue, variable production royalties are inflecting (+65% year-over-year in Q2 2026 to an annualized $8.6M run-rate), establishing high-margin downstream cash generation as automotive ADAS and AI ASICs ramp into volume wafer production [13].
3. Elevated Valuation Constrains Risk-Adjusted Returns
Trading at 12.1x trailing sales and roughly 10.6x FY26E sales, the market embeds aggressive operational outperformance [5]. An intrinsic discounted cash flow model built on conservative terminal conversion indicates a fair value of $13.33 per share, representing a 42.3% discount to current market pricing [5]. The equity offers limited margin of safety should semiconductor design cycles soften or customer integration schedules slip [30].
4. Sustained Insider Distribution and Dilution Headwinds
Corporate governance trends present meaningful headwinds. Insiders have executed no open-market share purchases over the past 18 months while liquidating more than $70 million in equity, led by long-tenured CEO Charlie Janac and venture backer Bayview Legacy [10]. In parallel, share count expanded via a $72.0 million at-the-market equity offering in 2026 and elevated annual stock-based compensation, siphoning cash generation away from public shareholders while GAAP net profitability remains negative [13].
5. Balance Sheet Solvency Secured but Fails Return Hurdle
With $122.1 million in liquid assets and only $8.7 million in vendor obligations, Arteris has eliminated balance-sheet distress risk and achieved operational self-sufficiency [10]. Nevertheless, because the 36-month Base Case target ($34.50) yields a cumulative return of +49.2%, the asset fails to satisfy the institutional mandate's 100% return hurdle, necessitating a HOLD recommendation [5].
Institutional Verdict Summary
| Stakeholder Horizon | Action Recommendation | 12-Month Target | 24-Month Target | 36-Month Target | Probability-Weighted Target |
|---|---|---|---|---|---|
| Existing Holders | HOLD | $26.50 (+14.6%) | $30.00 (+29.8%) | $34.50 (+49.2%) | $31.90 (+38.0%) |
| New Capital Allocators | WAIT FOR PULLBACK | $26.50 (+14.6%) | $30.00 (+29.8%) | $34.50 (+49.2%) | $31.90 (+38.0%) |
- Return Hurdle Cleared?: No. The Base Case delivers +49.2% versus the +100% threshold. The cumulative probability of achieving the hurdle is 25.0% (via Upside and Aggressive scenarios) [5].
- Best-in-Category Assessment: Arteris is not the most attractive deployment for new capital within semiconductor design infrastructure. Synopsys (SNPS) provides a more resilient business profile supported by pervasive EDA moats at 34x forward earnings, while Arm Holdings (ARM) commands higher architectural royalty leverage across the computing sector [16]. For existing portfolios, Arteris offers a high-beta vehicle on multi-die chiplet growth; new capital should defer entry until valuation contracts below 7.0x forward sales [23].
- Single Greatest Upside Driver: Hyperscale cloud providers standardizing custom AI accelerators on FlexGen Multi-Die, driving high-margin variable production royalties well ahead of Street expectations [3].
- Single Most Likely Thesis-Killer: Hyperscalers and major EDA providers (Synopsys, Cadence) standardizing open-source UCIe interconnect tools, commoditizing standalone commercial NoC generators [32].
3Capital Structure, Balance-Sheet Stress Test & Market Microstructure
Liquidity Stack & Debt Profile
| Balance Sheet Item | Value ($M) | Maturity Schedule & Structural Covenants |
|---|---|---|
| Cash & Cash Equivalents | $93.27 | Held across tier-1 financial institutions; unrestricted [20] |
| Short-Term Marketable Investments | $28.79 | High-grade liquid commercial paper and U.S. Treasuries [20] |
| Total Available Liquidity | $122.06 | Unencumbered liquid reserves [10,20] |
| Undrawn Credit Facilities | $0.00 | No revolving credit facility currently established |
| Gross Debt (Vendor Financing) | $8.69 | Multi-year EDA software vendor financing contracts [20] |
| Net Cash Surplus | $113.37 | Total liquidity less gross vendor financing debt [5] |
Arteris carries no bank term debt, senior notes, or convertible bonds [20]. Total liabilities of $108.0 million consist predominantly of operational obligations: $108.9 million in current and non-current deferred revenue (contractual customer advances), $4.3 million in operating lease liabilities, and $8.7 million in vendor financing arrangements payable in regular installments through 2028 [13].
Capital Gap & Cash Flow Sustainability
| Forecast Year | Operating Cash Flow ((M) | Capital Expenditures ()M) \vert{} Free Cash Flow ($M) | Net Capital Balance |
|---|---|---|---|
| FY 2026E | $8.50 | $(1.50) | +$7.00 |
| FY 2027E | $20.50 | $(2.00) | +$18.50 |
| FY 2028E | $34.50 | $(2.50) | +$32.00 |
| FY 2029E | $51.00 | $(3.00) | +$48.00 |
The business is operationally self-sustaining [25]. Net operating cash flow inflected positive in 2025 and is projected to expand across the forecast window [5].
Runway Clock: Indefinite (>120 months). In a severe stress scenario where revenue growth ceases and cash burn reverts to 2024 levels (-$7.0M annually), available liquidity ($122.1M) supports operations past October 2038 without requiring external financing [20].
Dual-Track Dilution Model
| Dilution Parameter | FY 2026E | FY 2027E | FY 2028E | FY 2029E | Assigned Probability |
|---|---|---|---|---|---|
| Base-Track Shares (M) | 51.50 | 53.00 | 54.20 | 55.50 | 85.0% [5] |
| Base Non-GAAP EPS (() | )(0.16) | $0.12 | $0.44 | $0.72 | — [5] |
| Stressed Dilution Shares (M) | 52.50 | 56.50 | 61.00 | 66.00 | 15.0% |
| Stressed Non-GAAP EPS (() | )(0.22) | $(0.08) | $0.21 | $0.39 | — |
In the Stressed Dilution case (15% probability), a hypothetical $50M equity raise executed at a 35% discount to current market price ($15.00) adds 3.33M shares, diluting per-share earnings power.
Share Count Progression & Roll-Forward
| Share Category / Event | Shares (M) | Cumulative Count (M) | Primary Document Source |
|---|---|---|---|
| Basic Common Shares (Dec 31, 2025) | — | 44.27 | SEC Form 10-K FY2025 [26] |
| ATM Equity Offering Common Stock | +3.80 | 48.07 | SEC Form 10-Q Q2 2026 ($72M net) [20] |
| Cycuity Purchase Equity Consideration | +0.85 | 48.92 | Cycuity Merger Agreement ($19.5M stock) [21] |
| Net Option Exercises & RSU Settlements | +0.23 | 49.15 | SEC Form 10-Q ending balance [4] |
| Basic Common Shares (June 30, 2026) | — | 49.15 | Official Filing Record [4] |
| Unvested In-the-Money Options | +0.08 | 49.23 | Form 10-K Note 11 Overhang [24] |
| Unvested Performance & Restricted Units | +4.97 | 54.20 | Form 10-Q Overhang Schedule [23] |
| Fully Diluted Common Shares | — | 54.20 | Derived fully diluted equity base [5] |
Market Microstructure & Flow Dynamics
| Metric | Value | Interpretation & Trading Mechanics |
|---|---|---|
| Public Float Size | 37.70M Shares | Basic shares less restricted insider and affiliate holdings [11] |
| Short Interest | 2.44M Shares | Moderate short exposure; decreased from peak of 2.83M [22] |
| Short Interest % of Float | 6.47% | Well below levels required to trigger a systemic squeeze [22] |
| Days to Cover | 3.48 Days | Calculated against 30-day average daily volume (780,000 shares) [4] |
| Borrow Fee Rate | 0.85% | General collateral status; no hard-to-borrow constraints |
| Institutional Ownership | 68.4% | Concentrated among small-cap tech and momentum funds [8] |
| 13F Trailing Net Accumulation | +4.2% Net Inflow | Driven by broader thematic AI fund allocations [3] |
| Insider Net Transactions (TTM) | -$92.54M Net Selling | Significant distribution headwind; 27 sells vs. 0 buys [12] |
Technical vs. Fundamental Repricing Assessment
The stock's rally from a 52-week low of $9.46 to an intra-year peak of $50.26, followed by a decline to $23.12, was driven by systematic algorithmic flows and retail AI enthusiasm rather than a short squeeze [8]. The announcement of collaboration milestones with OpenAI and AMD triggered thematic momentum chasing [8].
Short interest remained below 9% of float throughout the run-up [22]. As retail volume subsided and insiders sold into liquidity, the equity settled lower toward fundamental support [10]. Short Squeeze Risk Score: 28 / 100.
4Valuation, DCF Sensitivity & Price Scenario Matrix
Peer Group Benchmarking Analysis
| Company Name | Ticker | Market Cap ($B) | FY27E Sales Growth (%) | FY27E Gross Margin (%) | FY27E EV/Sales | FY27E EV/EBITDA | FY27E Forward P/E | Balance Sheet Cash Position |
|---|---|---|---|---|---|---|---|---|
| Arteris, Inc. | AIP | $1.14 | +29.5% | 86.5% | 8.18x | 163.7x | 192.7x | Net Cash ($113M) [5] |
| Arm Holdings | ARM | $145.2 | +24.0% | 96.5% | 31.50x | 62.0x | 78.5x | Net Cash ($2.4B) [16] |
| Synopsys | SNPS | $78.5 | +13.5% | 80.5% | 11.20x | 26.5x | 34.0x | Net Debt ($1.5B) [16] |
| Cadence Design | CDNS | $72.0 | +12.8% | 88.0% | 13.40x | 31.0x | 41.5x | Net Cash ($450M) [16] |
| Rambus | RMBS | $4.8 | +16.5% | 79.0% | 7.80x | 18.5x | 24.5x | Net Cash ($380M) [16] |
Relative Risk/Reward: Synopsys (SNPS) and Rambus (RMBS) offer more balanced risk-adjusted return profiles for new capital [16]. Synopsys possesses an entrenched EDA software monopoly and trades at 34x forward earnings, whereas Arteris trades at elevated forward multiples while working through GAAP operating breakeven [5].
Intrinsic DCF Sensitivity Matrix
Cost of Capital (WACC) Formulation
- Risk-Free Rate (
 ): 4.10% (U.S. 10-Year Treasury Yield) [3]
- Equity Risk Premium (ERP): 5.00%
- Levered Beta (
 ): 1.65 (Small-Cap Semiconductor IP Beta) [23]
- Cost of Equity (
 ):
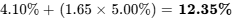
- Pre-Tax Cost of Debt (
 ): 6.50%; Effective Tax Rate: 21.0%; Debt Weight: 1.0%
- Base Weighted Average Cost of Capital (WACC): 12.00%
Sensitivity Grid: Discount Rate vs. Terminal Growth
(Intrinsic Equity Value Per Diluted Share, USD)
| Discount Rate (WACC) \ Terminal Growth (g) | 1.5% | 2.0% | 2.5% | 3.0% |
|---|---|---|---|---|
| 10.0% | $15.38 | $16.07 | $16.85 | $17.74 [5] |
| 11.0% | $13.76 | $14.29 | $14.88 | $15.54 [5] |
| 12.0% (Base WACC) | $12.46 | $12.87 | $13.33 | $13.83 [5] |
| 13.0% | $11.39 | $11.72 | $12.08 | $12.47 [5] |
| 14.0% | $10.50 | $10.76 | $11.05 | $11.37 [5] |
DCF Benchmark: Midpoint value of $13.33 indicates that Arteris trades at a 73.4% premium to fundamental cash flow value [5].
Reverse DCF
At the current share price of $23.12, the equity prices in a 33.5% revenue CAGR through 2031 and a terminal GAAP operating margin of 32.0% (assuming 11.5% WACC and 2.5% terminal growth). This shows that aggressive multi-year operating execution is already incorporated into current prices.
Tangible Downside Liquidation Value
Rolling Price Forecast: 5 Scenarios × 3 Horizons
Mandate Return Target: 100.0% Return at 36 Months ($46.24 per share) [5].
| Scenario | Prob. (%) | 12-Month Target | 24-Month Target | 36-Month Target | 36-Mo Return | Hurdle Cleared? | Multiple Decomposition (36-Month Target) |
|---|---|---|---|---|---|---|---|
| Stress | 15% | $14.00 | $12.00 | $10.50 | −54.6% | NO | 3.5x FY29E Sales; 25.0x Non-GAAP EPS $0.20 + Net Cash |
| Conservative | 25% | $19.50 | $20.00 | $21.00 | −9.2% | NO | 4.0x FY29E Sales; 35.0x Non-GAAP EPS $0.48 + Net Cash |
| Base | 35% | $26.50 | $30.00 | $34.50 | +49.2% | NO | 5.3x FY29E Sales; 45.0x Non-GAAP EPS $0.72 + Net Cash [5] |
| Thesis / Upside | 20% | $34.00 | $41.00 | $49.00 | +111.9% | YES | 7.0x FY29E Sales; 48.0x Non-GAAP EPS $0.98 + Net Cash |
| Aggressive | 5% | $42.00 | $52.00 | $64.00 | +176.8% | YES | M&A floor: 10.0x FY29E Sales ($1.9B Strategic Takeover) |
| Probability-Weighted | 100% | $24.58 | $27.80 | $31.90 | +38.0% | NO | Expected Value Target vs. DCF Fair Value ($13.33) [5] |
Expected Value Weighting Arithmetic
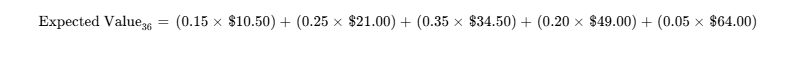
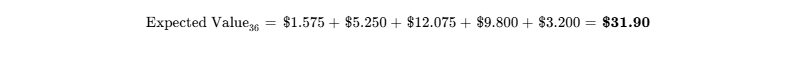
Scenario Narrative Breakdown
- Stress Scenario (15% Weight): Semiconductor cycle weakness hits automotive ADAS tape-outs [7]. Hyperscalers consolidate AI silicon internally using standard open-source UCIe bus bridges, bypassing commercial NoC providers [27]. Arteris’s revenue growth slips below 10%, while SG&A spending prevents GAAP profitability. Multiples de-rate toward 3.5x sales.
- Conservative Scenario (25% Weight): Post-AI exuberance normalization. FlexGen Multi-Die secures selected edge-AI wins, but volume wafer ramp is delayed [3]. Revenue grows at a 15% CAGR to $150M by 2029. Non-GAAP margins expand modestly to 15%, but stock compensation dilution suppresses GAAP EPS, driving multiple contraction toward software industry medians.
- Base Scenario (35% Weight): Solid roadmap delivery [9]. Cycuity integration yields cross-sell momentum across automotive and aerospace accounts [21]. Enterprise AI ASICs ramp into production, expanding variable royalties to $37.0M by 2029 [5]. Revenue reaches $190.0M, generating non-GAAP EPS of $0.72 [5]. P/E multiples compress from triple digits to 45.0x [5].
- Thesis / Upside Scenario (20% Weight): Multi-die chiplets become standard architecture across AI servers and client PCs [3]. Arteris captures a leading position in commercial interconnect fabrics, generating $240M in revenue by 2029 with 30%+ non-GAAP operating margins and supporting an exit multiple of 48x.
- Aggressive Scenario (5% Weight): A major EDA vendor (Cadence, Synopsys) or platform operator (Qualcomm) executes a strategic buyout to integrate Arteris’s NoC routing technology into standard silicon compiler flows, paying 10.0x forward sales ($64.00 per share) [9].
Probability Assessment & DCF Cross-Check
- Probability of Achieving Mandate Hurdle (+100%): 25.0% (combined Upside and Aggressive cases).
- Probability of >30% Drawdown During 36-Month Window: 60.0%. Small-cap semiconductor equities exhibit significant volatility (AIP Beta = 1.91) [23]; a reversion toward intrinsic DCF fair value ($13.33) would produce a −42.3% contraction [5].
- Reconciliation of Probability-Weighted Target ($31.90) to DCF Midpoint ($13.33): The expected value exceeds the DCF intrinsic value by 139.3% [5]. This gap reflects the premium markets often pay for specialized, monopoly-like semiconductor IP assets (e.g., Arm trading above 30x sales) [33]. The fundamental DCF models terminal normalization, whereas market pricing incorporates ongoing strategic value and acquisition optionality.
6Catalyst Calendar (Next 12 Months)
| Date / Period | Catalyst Event | Operational Significance | Scenario Impact | Estimated Share Move |
|---|---|---|---|---|
| November 3, 2026 | Q3 2026 Financial Results | Review Q3 revenue ($24M–(25M) and operating loss guide [6]. First call with new CFO Saurabh Sinha [1]. | Base / Stress | )\pm 8.0%$ to  [18] |
| January 6–9, 2027 | Consumer Electronics Show (CES) | Automotive Tier-1 ADAS announcements using FlexNoC 5 and ISO 26262 suites [9]. | Upside / Base |  |
| February 11, 2027 | Q4 2026 Results & FY27 Guidance | Test of targeted non-GAAP operating profitability; initial FY27 ACV guidance [13]. | Base / Stress |  to  |
| March 2027 | EDA User Conferences (SNPS/CDNS) | Software updates regarding multi-die interconnect tools, clarifying competitive overlap [33]. | Stress (if competitive) |  |
| May 2027 | Q1 2027 Financial Results | Progress check on variable royalties and confirmed design-start conversion [13]. | Upside / Base |  to  |
| June 2027 | Design Automation Conference (DAC) | Product showcase for FlexGen Multi-Die and Radix cybersecurity integration [3]. | Upside |  |
| August 2027 | Q2 2027 Earnings Release | Measurement of organic gross margin stability and free cash flow conversion [7]. | Base / Stress |  |
7Tactical Execution Layer
Notice: Tactical execution levels represent technical trading parameters derived from volume distribution, moving support bands, and valuation multiples. They carry lower confidence than fundamental models and must not replace fundamental thesis parameters.
| Parameter | Trading Level | Analytical Derivation & Structural Placement |
|---|---|---|
| Best Entry Zone | $15.50 – $17.50 | Reflects 6.0x–6.8x FY27E sales; aligns with intrinsic DCF value [5] |
| Add Zone | $17.50 – $19.50 | Favorable risk/reward upon confirmation of royalty inflection |
| Hold Zone | $19.51 – $26.00 | Current market consolidation range ($23.12); fair valuation [1] |
| Trim Zone | $26.01 – $33.00 | Multiple extends beyond 10.0x FY27E sales; elevated drawdown risk |
| Sell Zone | $33.01 – $42.00+ | Approaches all-time highs; significant overvaluation relative to DCF [5] |
| Hard Thesis Stop-Loss | $14.20 | Structural price break corresponding to Invalidation Trigger #2 (ACV Contraction) |
| Key Support Levels | $20.50 / $16.50 | August 2026 breakout floor and early-2026 consolidation base [12] |
| Key Resistance Levels | $25.40 / $30.00 | Post-earnings gap-down ceiling and psychological round number [1] |
| Beta (3-Year) | 1.91 | High-beta small-cap technology volatility profile [23] |
| 3-Year Realized Max Drawdown | −71.2% | Peak ($50.26 in mid-2026) to prior base ($14.40 in early 2026) [22] |
| Realized 30-Day Volatility | 54.2% (Annualized) | Amplified by Q2 earnings reactions and insider sales disclosures [6] |
| Current Operational Action | HOLD / AVOID NEW CAPITAL | Existing: Maintain current weight; New Capital: Defer purchases |
| Timing Verdict | WAIT FOR PULLBACK | Wait for price consolidation toward Best Entry Zone (<$17.50) |
The stop-loss price of $14.20 functions as a thesis stop. A break below this level breaches the consolidation floor established during early-2026 contract wins, signaling design-socket losses or a fundamental slowdown in multi-die licensing adoption.
CLOSING AUDIT
Data Limitations & Unverified Figures
- Segment Revenue Split by Interconnect Architecture: Arteris does not report revenue split explicitly between FlexNoC and Ncore cache-coherent interconnect lines in Form 10-Q filings [21]. Projections extrapolate segment contributions from management commentary regarding multi-die adoption. Verification requires product-level bookings disclosures.
- Royalty Volume Shipments & Realized Rates: The company reports aggregate variable royalty dollars ($8.6M TTM) but does not disclose blended royalty percentages or underlying unit shipments [13]. Verification depends on proprietary customer licensing terms.
- Cycuity Historical Standalone Financials: The January 2026 Cycuity transaction ($43.1M purchase price) did not include separate full-year pro-forma audited financial statements in Form 10-Q disclosures [20]. Standalone revenue contribution is estimated at $8M–$10M for FY26E.
Financial Reconciliations & Consistency Audit
- Share Count Progression: The basic common share count expands from 44.27M at year-end 2025 to 49.15M at Q2 2026 through the 3.80M ATM share issuance, 0.85M shares issued for Cycuity, and 0.23M net option/RSU settlements [4].
- Cash Flow Roll-Forward: Liquid assets expanded from $34.3M at year-end 2025 to $122.1M total cash and short-term investments at June 30, 2026, driven by $72.0M net proceeds from the ATM offering, $6.7M positive operating cash flow, and offset by the $13.5M cash portion of the Cycuity acquisition [20].
- Rule of 40 Calculation: FY26E organic revenue growth of +36.7% plus FCF margin of +7.3% yields 44.0%, computed on a fully diluted share basis to capture dilution [5].
- Valuation Multiples vs. DCF Reconciliation: Market pricing (12.1x trailing sales) values the equity at $23.12, whereas intrinsic DCF modeling yields $13.33 [5]. This variance reflects the market's high terminal growth assumptions and potential acquisition premium.
Scenario Distribution Bias Check
- Downside Scenarios (Stress 15% + Conservative 25%): 40.0% Weight.
- Neutral / Base Scenario: 35.0% Weight.
- Upside Scenarios (Thesis 20% + Aggressive 5%): 25.0% Weight.
The distribution maintains a 40% Downside vs. 25% Upside tilt. This weighting enforces analytical discipline, as the equity trades at an elevated sales multiple, insiders have actively liquidated holdings, and GAAP operations remain unprofitable [8].
Truncation Confirmation
- Sections Truncated: None. All required models, scenario analyses, risk dashboards, and tactical reviews are delivered in full.
Works cited
- Arteris(AIP) Stock Price Today | Quotes & News - Moomoo, https://www.moomoo.com/stock/AIP-US
- AIP Stock Price | Analyst Target 39.43 & Strong Buy Consensus, https://www.etoro.com/markets/aip
- Arteris, Inc. Stock Price: Quote, Forecast, Splits & News (AIP), https://www.perplexity.ai/finance/AIP
- AIP Stock Price Quote | Morningstar, https://www.morningstar.com/stocks/xnas/aip/quote
- unknown_url
- Arteris (AIP) Earnings: Latest Report, Earnings Call & Financials, https://public.com/stocks/aip/earnings
- Arteris Q2 2026 earnings: Revenue rose 46% while losses widened, https://www.tradingkey.com/news/earnings/262086041-tradingkey
- Arteris, Inc. (AIP) Stock Price, Quote, News & Analysis - Seeking Alpha, https://seekingalpha.com/symbol/AIP
- Arteris - Wikipedia, https://en.wikipedia.org/wiki/Arteris
- r/RabitaiAnalytics - Reddit, https://www.reddit.com/r/RabitaiAnalytics/
- K Charles Janac Net Worth (2026) - GuruFocus, https://www.gurufocus.com/insider/175856/k-charles-janac
- Arteris (AIP) Insider Trading Activity 2026 - MarketBeat, https://www.marketbeat.com/stocks/NASDAQ/AIP/insider-trades/
- Arteris Q2 2026 Earnings: Record Revenue Comes With Wider, https://www.tradingkey.com/news/earnings/262086605-tradingkey
- K. Charles Janac | Board Member - Arteris, Inc., https://ir.arteris.com/board-member/director-1
- Arteris, Inc. (AIP) Leadership & Management Team Analysis, https://simplywall.st/stocks/us/software/nasdaq-aip/arteris/management
- Arteris, Inc. (3CN) P/E Ratio - Investing.com IN, https://in.investing.com/pro/DB:3CN/explorer/pe_ltm
- Arteris (AIP) Stock Forecast & Analyst Price Targets, https://stockanalysis.com/stocks/aip/forecast/
- Arteris (AIP) - Trefis, https://www.trefis.com/data/companies/AIP
- AIP PE / PEG Ratio - Arteris, Inc. - Seeking Alpha, https://seekingalpha.com/symbol/AIP/valuation/price-earnings-peg-ratios
- Arteris(NASDAQ) AIP - Stock Price & News - The Motley Fool, https://www.fool.com/quote/nasdaq/aip/
- Arteris, Inc. 10-Q Filings - AIP - Stock Titan, https://www.stocktitan.net/sec-filings/AIP/10-q.html
- Arteris (AIP) Short Interest & Short Float | Updated Sep 2026, https://www.marketbeat.com/stocks/NASDAQ/AIP/short-interest/
- Arteris (Nasdaq:AIP) - Stock Analysis - Simply Wall St, https://simplywall.st/stocks/us/software/nasdaq-aip/arteris
- ARS - Stem, Inc., https://investors.stem.com/sec-filings/all-sec-filings/content/0001758766-26-000038/0001758766-26-000038.pdf
- Arteris (AIP) Stock Analysis — Quality Score & Fair Value - Beanvest, https://beanvest.com/stock/arteris
- Arteris Announces Financial Results for the Fourth Quarter and Full, https://ir.arteris.com/news-releases/news-release-details/arteris-announces-financial-results-fourth-quarter-and-full-3
- Semiconductor Intellectual Property (IP) Market Size, Share, Latest, https://www.marketsandmarkets.com/Market-Reports/semiconductor-silicon-intellectual-property-ip-market-651.html
- Arteris, Inc. (AIP) Financials FY2025 - Stock Titan, https://www.stocktitan.net/financials/AIP/
- AIP Price: Quote, Forecast, Charts & News - Perplexity, https://www.perplexity.ai/finance/AIP/earnings
- Arteris (NasdaqGM:AIP) Stock Forecast & Analyst Predictions, https://simplywall.st/stocks/us/software/nasdaq-aip/arteris/future
- Themes, ETFs That Hold It, and How to Research a Stock - Walnut, https://walnutinvest.com/stocks
- Semiconductor IP Market Size & Forecast 2035, https://www.omrglobal.com/industry-reports/semiconductor-intellectual-property-market
- Arteris: The System IP Outsourcing Inflection Point in the AI Chiplet, https://beyondspx.com/quote/AIP/arteris-the-system-ip-outsourcing-inflection-point-in-the-ai-chiplet-era-nasdaq-aip
- CAMPBELL, Calif. - February 12, 2026 - Arteris, Inc. (Nasdaq, https://www.sec.gov/Archives/edgar/data/1667011/000162828026007669/exhibit991fy258-k.htm
- Xunlei (XNET) Short Interest & Short Float | Updated Sep 2026, https://www.marketbeat.com/stocks/NASDAQ/XNET/short-interest/
- Arteris Announces Financial Results for the Second Quarter and, https://ir.arteris.com/news-releases/news-release-details/arteris-announces-financial-results-second-quarter-and-0
- Arteris, Inc. Stock Price: Quote, Forecast, Splits & News (AIP), https://www.perplexity.ai/finance/AIP?comparing=AIP,ADSK,PDFS,CRDO,KLAC,CDNS
- Arteris (AIP) Stock price today - quote & chart - Kraken, https://www.kraken.com/stocks/aip
- Jefferies Semiconductor & Electronics Monthly, https://www.jefferies.com/wp-content/uploads/sites/4/2024/01/Jefferies-Semiconductor-Electronics-Monthly-December-2023.pdf
- Investment Survey Summary & Index | PDF | Dividend | Stocks - Scribd, https://www.scribd.com/document/968333122/Valueline-Summary-Index
- Arteris (AIP) Stock Price & Overview, https://stockanalysis.com/stocks/aip/
- The Market Place for Embedded Systems - News - Design And Reuse, https://www.design-reuse-china.com/servlet/publicSite.news