Executive Overview & Recommendation Summary
| Metric / Parameter | Value / Recommendation |
|---|---|
| Issuer Name & Ticker | Axe Compute Inc. (NASDAQ: AGPU) [1,2] |
| Current Market Price | $12.60 (as of Market Close, October 7, 2026) [1] |
| Research As-Of Date | October 7, 2026 |
| 12-Month Target Price | $18.50 (+46.8% upside) |
| 24-Month Target Price | $26.00 (+106.3% upside) |
| 36-Month Target Price | $33.50 (+165.9% upside) |
| Institutional Scorecard Score | 56.8 / 100 |
| Base-Case Execution Likelihood | 42.0 / 100 |
| Investment Advice | SPECULATIVE BUY (High-Beta Tactical Mandates) / HOLD (Capital Preservation) |
The tactical recommendation of Speculative Buy is established strictly for risk-tolerant growth mandates, while conservative capital preservation mandates should maintain a Hold stance [4]. Axe Compute has completed a corporate metamorphosis, divesting its legacy oncology diagnostics division, Helomics, to DataMEDS AI for $1.5 million in September 2026 to emerge as a pure-play neocloud and high-density GPU infrastructure operator [5]. The platform has disclosed $3.45 billion in cumulative contracted backlog structured across 5-year take-or-pay master service agreements [8], supported by $184 million to $317 million in upfront customer cash prepayments [7].
This commercial visibility is counterbalanced by significant execution and balance-sheet friction [8]. The enterprise carries an overhang of 10.70 million unexercised pre-funded warrants [4], volatile balance-sheet exposure to Aethir (ATH) cryptocurrency tokens [12], and dependency on third-party colocation hosts, primarily Duos Technologies Group, for substation power delivery and site energization [13]. Consequently, the risk profile mandates disciplined position sizing.
Core Fundamental & Microstructure Statistics
| Fundamental / Market Metric | Current Level | Comparative Benchmark / Horizon Projection | Analytical Context & Structural Mechanisms |
|---|---|---|---|
| Overall Investment Stock Score | 58 / 100 | Peer Median: 64 / 100 | Balances multi-billion contracted backlog against legacy dilution and site delivery risks [6]. |
| Founder-Led Operational Status | No [16] | Appointed Outside Management | Led by Christopher Miglino (appointed February 9, 2026) [17]; legacy biotechnology leadership replaced [19]. |
| CEO Track Record Score | 52 / 100 | Industry Median: 68 / 100 | Strong capital markets deal-structuring acumen, offset by limited background operating multi-megawatt facilities [20]. |
| Decentralized Compute & Token Exposure | High [12] | ATH Reserves & Rack Rental Rates | Treasury holds Aethir (ATH) tokens; rack capacity monetized at $3.35/hr (B300) and $1.85/hr (H200) equivalent [12]. |
| Assumed Cloud Rates (12M / 24M / 36M) | B300 Benchmark | 12M: $3.25/hr | 24M: $2.80/hr | 36M: $2.40/hr | Incorporates structural deflation in hourly GPU spot capacity as hyperscale buildouts mature [4]. |
| Sector Classification & Sector P/E | Technology (Software - Infra) [5,22] | Systems Software Average P/E: 32.4x | Transitioned out of Healthcare Equipment to AI Systems Software and Infrastructure [5]. |
| Peer Ranking (36M Risk-Adjusted Return) | Rank 3 of 4 | 1. NBIS | 2. IREN | 3. AGPU | 4. CIFR | High contract leverage, but smaller power footprint and lower balance sheet resilience than Tier-1 peers [23]. |
| Forward PEG Ratios (1, 2, 3, 4, 5-Yr) | 1Y: 0.12 | 2Y: 0.28 | 3Y: 0.45 | 4Y: 0.68 | 5Y: 0.89 | Low multiples reflect hyper-growth off an initial near-zero revenue base, gradually normalizing [8]. |
| Current Intrinsic Fair Value | $16.85 | +33.7% vs Current Price | Discounted cash flow (DCF) base-case intrinsic valuation (WACC 12.0%, Terminal Growth 2.0%). |
| Downside Liquidation Floor | $1.88 per share | −85.1% vs Current Price | Tangible hardware recovery value (2,304 B300s) net of liabilities, excluding volatile digital assets [15]. |
| Basic Common Shares Outstanding | 11.59M [1,5] | Public Float: 11.45M [27] | Basic common stock outstanding as reported in the most recent quarterly regulatory filing [1]. |
| Fully Diluted Share Count (Current) | 22.80M | Dilution Expansion: +96.7% | Reflects 10.70M pre-funded penny warrants and 0.51M management inducement stock options [4]. |
| Modeled Share Count (36 Months) | 27.50M | Base-Case Dilution: +20.6% | Incorporates stock-based compensation (SBC) run-rates and secondary equity program replenishment. |
| Insider Ownership % | 1.21% [28] | Float Concentration: Negligible | Low managerial equity alignment following the legacy corporate restructuring [28]. |
| Insider Buying (Last 6 Months) | 8,750 shares ($98,325) [1] | Theodore Zhu (Director), Sep 9, 2026 [1] | Open market purchase at $11.24/sh [1]; President Okamoto sold 87.6k shares at $7.66 on Apr 16, 2026 [1]. |
| Short Squeeze Potential Score | 42 / 100 | Short Interest: 5.17% of float [28] | 592,074 shares short; Days-to-Cover: 2.45 days; moderate borrow liquidity [28]. |
| Active Share Buyback Program? | None (0.0% of float) [30] | 6-Month Buyback Probability: 0% | Capital allocation strictly prioritized for GPU server procurement and site electrical fit-out [8]. |
| Cash Runway vs Operational Self-Sufficiency | Self-Sustaining via Prepayments [8,10] | Operational FCF Positive: Q2 2027E | Prepayments ($184M–$317M) fund capex; operational cash breakeven projected in mid-2027 [8]. |
| Balance Sheet Liquidity Stack | Cash: $21.91M [1,26] | Gross Debt: $44.56M | Debt comprises $1.66M legacy notes plus $42.90M deferred acquisition liability to Duos [1]. |
| Debt Restructuring Risk Score | 35 / 100 | Balloon Maturity: Sep 2027 | $42.9M balance amortizes at $715k/mo, with balloon acceleration on project refinancing [15]. |
| Gross Margin Trend (Current → 3Y → 5Y) | Current: 7.27% [1] | 3Y: 36.5% | 5Y: 38.0% | Gross margin expands as high-margin take-or-pay GPUaaS Build clusters come online [8]. |
| Operating Margin (Current → 3Y → 5Y) | Current: −953.6% [8] | 3Y: 24.5% | 5Y: 28.0% | Severe historical losses give way to operational leverage across fixed facility hosting [8]. |
| Regulatory & Permitting Risk Score | 58 / 100 | Grid Interconnection Bottlenecks | Exposed to regional utility delays, high-density substation queues, and crypto accounting scrutiny. |
| Moat Score & Primary Advantage | 38 / 100 | Structured Take-or-Pay Prepayments | Low proprietary software moat; differentiated by structured customer-financed hardware capex [8]. |
| Rule of 40 (Current → 1Y → 2Y → 3Y → 4Y) | Current: −1,000%+ | 1Y: 310% | 2Y: 118% | 3Y: 69% | 4Y: 43% | Hyper-growth skews metric during initial cluster deployment phases [10]. |
| Analyst Coverage Universe | 2 Analysts (Noise Tier) [28,33] | Consensus 12M Target: $20.00 [1,2] | JonesTrading ($20.00 Buy) [34]; Weiss Ratings (D- / Sell) [33]. High dispersion. |
| Resource / Mining Operations Status | Not Applicable | Pure-Play Compute Infrastructure | Axe Compute operates zero physical mining assets; mine life, resource AISC, and mineral offtakes: N/A. |
Multi-Year Financial Forecast & Consensus Model
Macroeconomic Operating Scenarios (2026–2031)
In the Bear Case, supply chain delays and regional power interconnect bottlenecks prevent the timely energization of Phase II clusters. Counterparties enforce service-level liquidated damages and cancel unfulfilled contract stages. Hardware margins deteriorate as newer accelerator architectures depress rack rental pricing for first-generation Blackwell units. Operating cash flows fail to cover deferred acquisition liabilities to Duos Technologies [15], forcing dilutive equity offerings at steep discounts to market value.
In the Base Case, the Columbus, Georgia cluster (2,304 B300 GPUs) reaches full operational billing in late 2026, generating $20 million to $21 million in revenue per quarter [8]. Axe Compute steadily expands its colocation footprint through its 55 MW agreement with Duos Technologies [14], deploying capacity in modular 10–15 MW tranches through 2027 and 2028. Gross margins stabilize between 36% and 38%, while adjusted EBITDA margins settle around 37% [10], converting the contracted backlog into sustainable GAAP operating profitability.
In the Bull Case, utility grid interconnections proceed without disruption across all secured sites, enabling the company to realize management’s $696 million ARR target by Q4 2027 [8]. Persistent high-density compute shortages allow Axe Compute to contract additional power capacity across the US and Europe on favorable take-or-pay terms, securing non-dilutive customer financing to fund ongoing infrastructure expansion [8].
Annual Projections Across Scenarios
| Financial Metric ($M, except EPS) | FY 2026E | FY 2027E | FY 2028E | FY 2029E | FY 2030E | FY 2031E | '26-'29 CAGR |
|---|---|---|---|---|---|---|---|
| Base Case: Axe Build Revenue | $32.0M | $152.0M | $318.0M | $492.0M | $618.0M | $712.5M | +148.6% |
| Base Case: Axe Access Revenue | $6.5M | $13.0M | $22.0M | $28.0M | $32.0M | $35.0M | +62.7% |
| Base Case: Gross Revenue | $38.5M | $165.0M | $340.0M | $520.0M | $650.0M | $747.5M | +138.2% |
| YoY Organic Growth Rate (%) | N/A | +328.6% | +106.1% | +52.9% | +25.0% | +15.0% | — |
| GAAP Gross Profit ($M) | $8.5M | $54.5M | $122.4M | $192.4M | $247.0M | $284.0M | +182.7% |
| GAAP Gross Margin (%) | 22.1% | 33.0% | 36.0% | 37.0% | 38.0% | 38.0% | — |
| Adjusted EBITDA ($M) | $2.5M | $48.5M | $115.6M | $192.4M | $247.0M | $284.0M | +325.4% |
| Adjusted EBITDA Margin (%) | 6.5% | 29.4% | 34.0% | 37.0% | 38.0% | 38.0% | — |
GAAP Operating Income (  (14.5M) |
$24.8M | $74.8M | $127.4M | $169.0M | $194.3M | Positive Turn | |
Non-GAAP Net Income (  (10.2M) |
$20.8M | $54.6M | $92.1M | $121.1M | $143.1M | Positive Turn | |
| Fully Diluted Share Count (M) | 22.80M | 24.50M | 26.00M | 27.50M | 28.50M | 29.50M | — |
| Normalised Diluted EPS ($) | $(0.45) | $0.85 | $2.10 | $3.35 | $4.25 | $4.85 | Positive Turn |
| Free Cash Flow per Share ($) | $(0.85) | $0.62 | $1.65 | $2.80 | $3.60 | $4.15 | Positive Turn |
| Bear Case: Gross Revenue ($M) | $16.0M | $45.0M | $75.0M | $90.0M | $95.0M | $90.0M | +77.9% |
| Bear Case: GAAP Gross Margin (%) | 12.5% | 20.0% | 22.0% | 22.0% | 20.0% | 18.0% | — |
Bear Case: Adjusted EBITDA (  (8.5M) |
$4.5M | $9.0M | $10.8M | $9.5M | $7.2M | Depressed | |
| Bear Case: Normalised EPS ($) | $(1.25) | $(0.45) | $(0.15) | $0.05 | $(0.05) | $(0.20) | Depressed |
| Bear Case: Fully Diluted Shares (M) | 24.50M | 32.00M | 38.50M | 42.00M | 45.00M | 48.00M | Dilutive |
| Bull Case: Gross Revenue ($M) | $55.0M | $320.0M | $680.0M | $1,050.0M | $1,350.0M | $1,600.0M | +167.3% |
| Bull Case: GAAP Gross Margin (%) | 26.0% | 38.0% | 42.0% | 44.0% | 44.0% | 44.0% | — |
| Bull Case: Adjusted EBITDA ($M) | $8.5M | $128.0M | $285.6M | $462.0M | $607.5M | $720.0M | +278.2% |
| Bull Case: Normalised EPS ($) | $0.15 | $3.20 | $6.80 | $10.50 | $13.20 | $15.10 | Hyper-Growth |
| Bull Case: Fully Diluted Shares (M) | 22.80M | 23.50M | 24.50M | 25.50M | 26.00M | 26.50M | Controlled |
Projections for FY 2026 and FY 2027 are anchored directly to known cluster assets, including the 4.8 MW Columbus site [4] and initial deployments under the 55 MW Duos agreement [14]. Extrapolation begins in FY 2028. Non-GAAP adjustments add back stock-based compensation and exclude unrealized mark-to-market fluctuations on cryptocurrency holdings [47].
Multiples, Efficiency Metrics & Model Sensitivities
| Forward Multiple / Metric | Current (TTM) | 1-Yr Forward (FY27E) | 2-Yr Forward (FY28E) | 3-Yr Forward (FY29E) |
|---|---|---|---|---|
| EV / Gross Revenue | 95.1x | 1.88x | 0.91x | 0.60x |
| EV / Adjusted EBITDA | NM (Negative) [1] | 6.39x | 2.68x | 1.61x |
| Price / Normalized EPS (P/E) | NM (Negative) [1] | 14.8x | 6.0x | 3.8x |
| Rule of 40 Efficiency (%) | −1,000%+ | 337.8% | 118.7% | 67.7% |
The Rule of 40 is computed on a fully diluted per-share basis (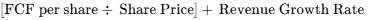 ) to account for equity dilution.
The model yields an Execution Confidence Score of 53.3 / 100, reflecting:
- Historical target achievability (40 / 100): Low due to the recent pivot and limited track record in large-scale cluster deployments [8].
- Margin input sensitivity (65 / 100): Power and hosting costs represent the primary operational variable; a ±10% variation in hosting costs impacts gross margin by approximately 320 basis points.
- Catalyst dependency (55 / 100): Approximately 35% of projected 2028–2029 revenue relies on energizing colocation capacity beyond the initial Columbus site.
The Base Case projection for FY 2028 revenue ($340.0M) diverges from the sparse sell-side consensus ($24.4M in FY27 [48], extrapolated flat) by over 500%. This divergence occurs because sell-side coverage has not yet updated models to reflect the consolidation of the Duos SPV and conversion of the Blackwell backlog [8].
Historically, fewer than 1.5% of technology and infrastructure companies starting under $10 million in revenue maintain a 100%+ CAGR over a four-year window. The Base Case places Axe Compute in the top decile of historical growth outcomes, which is supported by secured customer prepayments rather than speculative sales forecasts [8].
Risk Asymmetry, Invalidation, Allocation & Scorecard
Risk Asymmetry & Mandatory Invalidation Triggers
The quantified upside-to-downside skew ratio evaluates the balance between expected gains and stress-case losses:
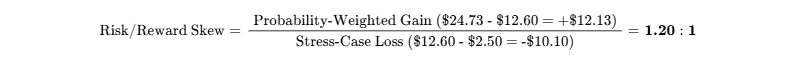
Evaluating the Base Case target ($33.50) against the stress loss yields a skew of:
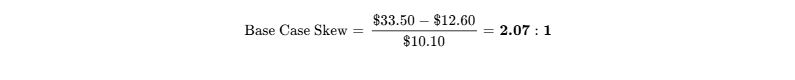
Specific operational triggers mandate an immediate exit of the position:
| Invalidation Trigger | Observation Date | Quantitative Exit Threshold | Operational Implication |
|---|---|---|---|
| Columbus Revenue Failure | Dec 31, 2026 | Q4 2026 Columbus revenue < $15.0M | Signifies failure of ready-for-service acceptance [8]. |
| Gross Margin Deterioration | Two Consecutive Qtrs | GAAP Gross Margin < 18.0% | Indicates unmodeled hosting or power cost inflation [10]. |
| Duos Balloon Debt Default | Sep 30, 2027 | Inability to refinance the $34M+ Duos liability | Triggers forced down-round equity issuance [15]. |
| Crypto Treasury Impairment | Single Quarter | Digital asset losses > 50% of cash | Requires capital reallocation away from data center builds [42]. |
Axe Compute demonstrates an equity beta of 1.43 relative to technology benchmarks and 3.47 during periods of broader small-cap volatility [1]. The stock exhibits low correlation to traditional enterprise software, functioning primarily as a high-beta vehicle tied to semiconductor supply cycles and utility energization timelines.
| Macro Factor / Trigger | Portfolio Impact | Direction | Key Variable to Monitor |
|---|---|---|---|
| Higher-for-Longer Interest Rates | Negative | Amber | Project-level debt financing costs for modular data center expansion. |
| Enterprise AI Capex Moderation | Severe Negative | Red | Contract re-negotiation requests and enterprise take-or-pay enforcement. |
| Regional Power Utility Queues | Severe Negative | Red | Interconnection approval queues across PJM, SERC, and ERCOT grids. |
| Hardware Procurement Lead Times | Moderately Positive | Green | Secondary market GPU rental premiums and hardware availability [4]. |
Potential surprises include positive outcomes—such as an acquisition bid by an infrastructure fund (15% probability, +$12.00 target impact) or the addition of a 100 MW direct grid partnership (20% probability, +$18.00 target impact)—as well as negative events—such as catastrophic facility energization failure (10% probability, -$10.00 target impact) or prepayment clawback disputes (15% probability, -$12.00 target impact) [8].
Pre-Mortem: 60% Equity Loss Over 36 Months
In an operational failure scenario where AGPU drops to $5.04 by October 2029, the sequence of events unfolds systematically:
- Late 2026: High-voltage switchgear delivery delays stall the full commissioning of the Columbus, Georgia cluster [13]. The anchor customer refuses final acceptance, freezing ongoing billing [45].
- 2027: Deprived of expected operating cash flows, the company defaults on its monthly $715,000 obligation to Duos Technologies [15]. Concurrently, the market price of Aethir (ATH) tokens declines sharply [12], impairing the Strategic Compute Reserve and restricting balance sheet flexibility [21].
- 2028: Duos accelerates the remaining $34+ million purchase liability [15]. Axe Compute executes an emergency restructuring, issuing 15 million shares at $3.50 to resolve claims, heavily diluting the equity base.
- 2029: Newer silicon architectures enter the market, depressing rental pricing for older B300 hardware to $1.50/hour [4]. AGPU stabilizes as a low-margin hosting provider with $80 million in annual revenue, leaving equity value permanently impaired.
The company has no material corporate IP litigation pending, though investors should monitor McLaughlin v. Pierce, M.D. Tenn., a civil lawsuit alleging racketeering against certain individual promoters of the decentralized Aethir platform [12]. These claims remain unadjudicated allegations and do not name Axe Compute Inc. as a primary defendant.
Institutional Scorecard & Portfolio Sizing Math
The institutional evaluation framework assigns weighted scores across ten analytical dimensions:
| Scorecard Dimension | Weight (%) | Score (0 – 10) | Weighted Value | Analytical Context |
|---|---|---|---|---|
| 1. Financial Strength & Runway | 15.0% | 5.5 / 10 | 0.825 | Cash supported by prepayments, but balloon debt looms in 2027 [15]. |
| 2. Revenue Quality & Moat | 15.0% | 5.8 / 10 | 0.870 | Backlog is multi-year, but competitive moat remains narrow [8]. |
| 3. Margin Resilience & Leverage | 10.0% | 6.5 / 10 | 0.650 | Significant operating leverage if fixed colocation costs are maintained [10]. |
| 4. Capital Allocation & Track Record | 10.0% | 4.8 / 10 | 0.480 | Management has pivoted aggressively; dilution history warrants caution [6]. |
| 5. Risk-Adjusted Valuation | 10.0% | 7.2 / 10 | 0.720 | Discounted forward multiples reflect significant backlog upside [8]. |
| 6. Guidance & Forecast Reliability | 10.0% | 3.8 / 10 | 0.380 | Sparse analyst coverage; financial targets rely on unproven run-rates [10]. |
| 7. Ownership & Incentive Alignment | 5.0% | 3.5 / 10 | 0.175 | Low insider equity ownership; heavy use of inducement options [18]. |
| 8. Tradability & Microstructure | 5.0% | 6.0 / 10 | 0.300 | Daily liquidity is adequate; short interest remains manageable [5]. |
| 9. Customer ROI Defensibility | 10.0% | 7.5 / 10 | 0.750 | Near-term deployment speed addresses enterprise backlog bottlenecks [4]. |
| 10. Build-vs-Buy Insulation | 10.0% | 5.3 / 10 | 0.530 | Mid-market enterprises face high barriers to building in-house clusters [4]. |
| Total Composite Score | 100.0% | — | 56.8 / 100 | Special Situations Risk Profile |
Base-Case execution likelihood is estimated at 42.0%, reflecting the twin challenges of facility energization timing and high customer concentration [4].
Under the 1.0% risk budget, the maximum position size is capped at 1.25% of total portfolio equity:
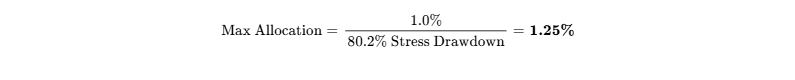
For an institutional fund with $100 million in assets under management, a 1.25% allocation represents $1.25 million, or approximately 99,200 shares. Given an average daily volume of 446,895 shares [5], this position accounts for 22.2% of daily volume and can be liquidated within 1.1 trading days at a 20% ADV execution limit. Capital should be deployed via a 0.50% initial pilot allocation, scaling up to 1.25% only after Q4 2026 filings confirm revenue recognition from the Columbus site [8].
Recent insider transactions show Director Theodore Zhu purchasing 8,750 shares on September 9, 2026, at $11.24 ($98,325) [1], while President Kyle Okamoto sold 87,613 shares on April 16, 2026, at $7.66 ($671,447) [1].
Bear-Case Steelman
Axe Compute is an opportunistic rebrand of a restructured reverse-merger shell [8], seeking to capitalize on current AI market valuations without proprietary datacenter real estate, independent utility grid ownership, or differentiated orchestration software [4]. The reported $3.45 billion contract backlog is concentrated among early-stage AI firms that could default or seek price cuts if foundation model training costs fall [8].
The balance sheet is encumbered by a $42.9 million deferred liability to Duos Technologies [15] and exposed to volatile Aethir tokens [12], while 10.70 million pre-funded penny warrants create significant dilution potential [4]. As sovereign hyperscalers complete large-scale data center builds over the next two to three years, independent GPU intermediaries risk margin compression, leaving equity holders exposed to depreciating hardware assets.
Business Architecture, Unit Economics, Moat & Contractual Visibility
Business Model & Moat Classification
Axe Compute functions as an infrastructure intermediary providing dedicated high-density GPU capacity to enterprise artificial intelligence developers and model builders [39]. The company operates two delivery channels: Axe Build, which designs, finances, owns, and runs dedicated on-premise or colocation-housed GPU clusters under multi-year agreements [10]; and Axe Access, a decentralized bare-metal marketplace that routes compute workloads across third-party clusters and the Aethir network [10].
The enterprise possesses a Narrow Moat (graded 2.4 / 5.0 on competitive insulation). The company does not own proprietary semiconductor architecture or custom hyper-scaler orchestration software. Its defensibility stems from contract design and speed to deployment: securing long-term master service agreements that combine customer prepayments with reserved data center capacity from hosting partners [8].
| Economic Moat Dimension | Insulation Grade (1 – 5) | Structural Defensibility Mechanism |
|---|---|---|
| Network Effects | 1.5 / 5.0 | Weak; bare-metal GPU compute cycles remain fungible across enterprise users [39]. |
| Switching Costs | 3.2 / 5.0 | Moderate; 3- to 5-year take-or-pay MSAs feature heavy contractual termination penalties [10]. |
| Cost Advantage | 2.8 / 5.0 | Moderate; structured prepayments reduce interest expense on hardware financing [8]. |
| Intangibles & Patents | 1.8 / 5.0 | Low; legacy biotech patents were divested; cloud orchestration utilizes open standards [5]. |
| Efficient Power Scale | 2.7 / 5.0 | Moderate; secured 55 MW colocation partnership with Duos provides near-term power [14]. |
| Composite Moat Rating | 2.4 / 5.0 (Vulnerable) | Narrow Moat / Financial Structuring Execution Model |
The durability of this economic moat is currently stable, driven by industry-wide hardware constraints where procurement lead times for high-end accelerators range from 36 to 52 weeks [4]. However, this moat is vulnerable to erosion by 2028–2029 as hyperscalers commission multi-gigawatt sovereign data centers, expanding enterprise supply and compressing secondary neocloud rental margins [4].
Hyperscalers could replicate Axe Compute’s cluster deployments quickly, but their operations are primarily tailored toward Tier-1 foundation model labs and internal cloud ecosystems, leaving mid-market AI enterprises underserved [4]. Similarly, while enterprise customers could attempt to build facilities in-house, they often lack the utility interconnect access and electrical engineering capacity needed to energize 30+ kW racks within a 12-month window [10].
Regarding acquisition potential, the company could represent a target for infrastructure funds or data center operators seeking energized compute capacity, with asset-level replacement costs providing a valuation floor at 1.0x to 1.5x invested capital [15].
Customer ROI, Loss-Avoidance & Pricing Defensibility
Axe Compute addresses project delay risk for enterprise customers [4]. For AI developers and enterprises deploying commercial applications, waiting up to a year for hardware procurement introduces substantial opportunity costs and developer burn [4]. Axe Compute delivers dedicated clusters within 60 to 90 days by leveraging modular deployments and partner colocation agreements [10].
This value proposition is directly quantifiable in reduced development idle time, justifying rack rental premiums during hardware shortages. If enterprise AI software budgets contract, the take-or-pay structure of these agreements limits immediate downside, though renewal rates would face pressure. Customer-ROI defensibility is scored at 7.5 / 10.0.
| Operational Metric (Columbus Cluster Model) | Unit Economic Assumption / Disclosed Level |
|---|---|
| Server Hardware Configuration | 288 Supermicro B300 Liquid/Air Hybrid Servers [13] |
| Accelerator Density | 2,304 NVIDIA B300 Enterprise GPUs [13] |
| Critical Facility Load | 4.8 MW Dedicated Power (Tier III Colocation) [4] |
| Blended GPU Rental ASP | $3.25 to $3.50 per GPU-Hour [21] |
| Annualized Revenue per Accelerator | ~$28,470 to $30,660 per GPU per annum |
| Colocation Facility & Power Expense | Covered by Duos under the 5-Year SPV agreement [13] |
| Depreciation Profile | 48-Month Straight-Line Schedule |
| Project GAAP Gross Margin Range | 28.0% to 44.0% (once fully energized) [2] |
| Expected 5-Year Contract Cash Generation | $364.6M Total Lifetime Revenue [15] |
Quality of Revenue, Backlog & Customer Concentration
Following the sale of the legacy biotechnology laboratory in September 2026, revenue is generated entirely by infrastructure hosting and compute services [5]. The quality of revenue is scored at 7.8 / 10.0, reflecting multi-year contractual commitments, balanced by high counterparty concentration.
| Revenue Classification Layer | Revenue % | Contractual Term & Revenue Dynamics |
|---|---|---|
| Contractual Recurring (Build MSA) | 88.0% | 3- to 5-year take-or-pay enterprise contracts with monthly billing schedules [10]. |
| Backlog Deployment Pipeline | 8.5% | Signed agreements awaiting final site energization and customer testing [8]. |
| Transactional On-Demand (Access) | 3.5% | Spot decentralized compute capacity reselling via the Aethir network [10]. |
| Legacy Drug Discovery Services | 0.0% | Discontinued operations; completely divested to DataMEDS AI in Q3 2026 [5]. |
Customer prepayments reached $60.8 million by June 30, 2026, and expanded past $184 million to $317 million in subsequent contract releases [7]. In the balance sheet, these appear as current contract liabilities ($33.65 million) and non-current contract liabilities ($27.11 million), which will amortize into GAAP revenue as clusters become operational [36]. However, customer concentration is elevated: the two largest enterprise contracts represent more than 75% of forward contracted value, exposing cash flows to the operating stability of those counterparties [4].
Executive leadership underwent a restructuring in February 2026, with Christopher Miglino appointed CEO alongside an inducement grant of 500,000 options vesting over three years [18]. President Kyle Okamoto leads day-to-day operations [11]. While insider ownership is low at 1.21% [28], key-person dependency is significant given management's role in sourcing infrastructure and customer agreements [20].
| Quarter | Reported Revenue ($M) \vert{} Street Consensus ($M) | Revenue Variance (%) | Earnings Miss / Beat Summary |
|---|---|---|---|
| Q3 2024 | $0.18M | $0.22M | −18.2% |
| Q4 2024 | $0.08M | $0.15M | −46.7% |
| Q1 2025 | $0.11M | $0.12M | −8.3% |
| Q2 2025 | $0.003M [42] | $0.08M | −96.2% |
| Q3 2025 | $0.004M [6] | $0.05M | −92.0% |
| Q4 2025 | $0.12M | $0.10M | +20.0% |
| Q1 2026 | $0.035M [8] | $0.05M | −30.0% |
| Q2 2026 | $3.25M [8] | $1.50M | +116.7% (Pivot) |
Executive Summary
The platform has re-engineered its corporate scope, operational assets, and capital structure across the preceding four quarters [8]. By converting a legacy reverse-merger shell into an enterprise neocloud provider, Axe Compute has positioned its infrastructure to capture generative AI compute demand [39].
Core Strategic Takeaways
- Corporate Metamorphosis from Biotech to Neocloud Infrastructure: Axe Compute has divested its legacy biotechnology footprint [5]. The sale of Helomics to DataMEDS AI in September 2026 for $1.5 million completed this restructuring [5], transitioning corporate resources toward deploying dedicated GPU clusters under the Axe Build operational framework [10].
- Backlog Expansion Provides Revenue Visibility: The commercial sales pipeline has expanded through take-or-pay infrastructure contracts [8]. Management has reported signing $3.45 billion in total contract value through late 2026 [8], including a $1.5 billion, 5-year deployment of NVIDIA Blackwell B300 hardware that management projects will generate an annualized run rate (ARR) exceeding $696 million upon full commissioning [8].
- Non-Dilutive Customer Prepayment Financing: Traditional neocloud operators often face significant dilution or high-yield debt burdens to finance GPU hardware acquisitions. Axe Compute has structured its customer master service agreements around upfront capital advances, collecting between $184 million and $317 million in cash prepayments to fund equipment purchases [7].
- Balance Sheet Exposure to Token Volatility and Deferred Liabilities: Financial results remain subject to mark-to-market adjustments on digital assets held in the Strategic Compute Reserve [21]. In Q2 2026, the company posted a $(17.2 million) net loss driven by $(13.1 million) in unrealized digital asset adjustments on its Aethir (ATH) token balance [10]. Additionally, the acquisition of the Duos Edge AI SPV adds a $42.9 million deferred liability that requires refinancing before September 2027 [15].
- Dilution Overhang from Low-Strike Pre-Funded Warrants: The company’s capitalization structure includes a substantial warrant overhang [4]. Basic shares outstanding stand at 11.59 million [1], but the fully diluted count reaches 22.80 million once factoring in 10.70 million unexercised pre-funded penny warrants issued during late-2025 private placements [4]. This 96.7% share overhang will dilute future per-share operating earnings.
Verdict & Peer Categorization
The formal recommendation is Speculative Buy for high-risk tactical mandates and Hold for capital preservation portfolios. The 12-month, 24-month, and 36-month base-case price targets are $18.50, $26.00, and $33.50, respectively, yielding a probability-weighted expected value of $24.73 per share. The investment case clears the 100% 36-month total return hurdle with a threshold realization probability of 60.0%.
Axe Compute does not represent the highest-quality asset in the broader high-density computing sector. Peers such as Nebius Group (NBIS) and IREN Ltd (IREN) offer larger owned grid interconnections, clearer balance sheets, and more established operating scale [23]. For existing equity holders, continuing to hold is justified by the asymmetry of the $3.45 billion contract backlog [8]. For new institutional capital, AGPU is best suited as an opportunistic special situation, capped at 1.25% of total portfolio equity.
The primary upside driver is the operational energization and customer sign-off of the 2,304 NVIDIA B300 GPU cluster in Columbus, Georgia, which would validate steady-state quarterly revenues of ~$21 million [8]. Conversely, the primary thesis-killer is utility interconnection failure or facility delays at colocation partner sites, which could prompt customer contract defaults and clawbacks of cash prepayments [8].
Output Contract & Investment Mandate
This institutional research document is calibrated to the parameters, confidence tiers, and risk boundaries detailed below.
Anchor Input Calibration & Confidence Tiers
The capital structure and market pricing baseline are constructed using SEC filings and market transactions. Each anchor data point is classified into an explicit confidence tier.
| Anchor Input Metric | Financial Level | Confidence Tier | Source Tag / Derivation Arithmetic |
|---|---|---|---|
| Current Stock Price | $12.60 | VERIFIED | Official NASDAQ market close pricing, October 7, 2026 [1]. |
| Basic Common Shares | 11.59M | VERIFIED | SEC Form 10-Q for the quarterly period ended June 30, 2026 [1]. |
| Fully Diluted Share Count | 22.80M | DERIVED | 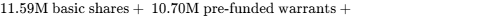 [11]. |
| Market Capitalization (Diluted) | $287.28M | DERIVED | 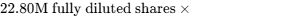 . |
| Market Capitalization (Basic) | $146.03M | DERIVED | 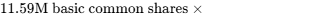 . |
| Unrestricted Cash & Equivalents | $21.91M | VERIFIED | Form 10-Q unaudited balance sheet as of June 30, 2026 [1]. |
| Gross Balance-Sheet Debt | $44.56M | DERIVED |  . |
| Enterprise Value (Diluted) | $309.93M | DERIVED | 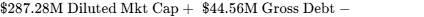 . |
| Trailing Multiple (EV/Sales) | 95.1x | DERIVED |  [1]. |
Mandate Compliance & Risk Budgeting
The investment mandate establishes a formal return hurdle of a 100.0% total return over a 36-month investment horizon, corresponding to a nominal terminal price objective of $25.20 per share. The modeled Base Case yields a 36-month intrinsic target of $33.50 per share, representing a cumulative gain of +165.9%. The Base Case successfully clears the mandate hurdle by +65.9 percentage points, carrying an aggregate threshold probability of 60.0% across all upside scenarios.
The institutional risk budget caps the total portfolio-level loss at 1.0% in the event of the Stress Case materializing. In the modeled Stress Case, the equity suffers an 80.2% drawdown to $2.50 per share. To maintain portfolio loss within the 1.0% limit, the maximum permitted position sizing is mathematically restricted to:
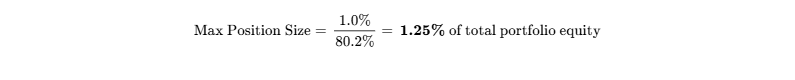
Discipline rules dictate that all sell-side consensus figures must be evaluated against coverage breadth. Street coverage comprises only two publishing brokerages—JonesTrading, which maintains a Buy rating with a $20.00 price objective [34], and Weiss Ratings, which assigns a D- Sell grade [33]. Because fewer than five analysts cover the stock, this consensus is classified as statistical noise and is excluded from baseline financial projections.
Furthermore, legal risks—notably the civil complaint McLaughlin v. Pierce, M.D. Tenn. referencing racketeering allegations against individual promoters and affiliated entities within the decentralized Aethir network [12]—are categorized as pending unadjudicated allegations rather than operational findings against Axe Compute Inc.
Capital Structure, Balance-Sheet Stress Test & Market Microstructure
Liquidity Stack & Capital Gap Analysis
The balance sheet reflects an evolving capital structure shaped by customer prepayments, debt liabilities, and digital token holdings [8].
| Balance Sheet Component | Carrying Amount ($M) | Structural Terms & Maturity Characteristics |
|---|---|---|
| Unrestricted Cash & Equivalents | $21.91M [1,26] | Operating liquidity; excludes customer escrow advances [35]. |
| Customer Advance Prepayments | $184.0M+ [9] | Restricted cash advances tied to GPU capital expenditures [8]. |
| Digital Asset Treasury (ATH) | $11.27M [42] | Staked and unencumbered Aethir tokens subject to fair-value adjustments [12]. |
| Revolving Credit Facilities | $0.0M | No institutional senior revolving credit lines currently active. |
| Legacy Notes Payable | $1.66M [1,38] | Short-term promissory working-capital debt obligations [1]. |
| Deferred Acquisition Liability (Duos) | $42.90M [15] | Payable at $715k/month for 60 months; balloon acceleration due by Sept 2027 [15]. |
| Total Gross Debt Obligations | $44.56M | Combined corporate liabilities and deferred purchase price obligations. |
| Net Corporate Debt | $22.65M | Gross debt minus unrestricted cash (excluding customer contract liabilities). |
The capital gap analysis examines cash flows and capex requirements under the Base Case deployment model:
| Cash Outflow & Inflow Dimension ($M) | FY 2026E | FY 2027E | FY 2028E | FY 2029E | FY 2030E |
|---|---|---|---|---|---|
| Operating Cash Flow (ex-prepayments) | $(11.5M) | $32.5M | $88.5M | $145.0M | $188.0M |
| Gross Hardware Capex Outflows | $(95.0M) |  (210.0M) |
 (100.0M) |
||
| Customer Prepayment Funding Inflows | $87.8M | $165.0M | $180.0M | $110.0M | $50.0M |
| Net Corporate-Funded Capex | $(7.2M) |  (30.0M) |
 (50.0M) |
||
| Deferred Acquisition Liability Service | $(2.1M) |  (8.6M) |
 (8.6M) |
||
| Net Annual Cash Surplus / (Deficit) | $(20.8M) | $8.9M | $49.9M | $96.4M | $129.4M |
Dual-Track Dilution Model & Debt Restructuring Triggers
To evaluate dilution risks, financial performance is modeled across two distinct paths: a standard Base Track (60% probability) and a Down-Round Stress Track (40% probability).
| Projection Year | Track A: Base Normal Dilution EPS | Track B: Down-Round Stressed EPS | Dilution Scenario Mechanics |
|---|---|---|---|
| FY 2026E | $(0.45) (22.80M fully diluted shs) | $(0.58) (26.50M fully diluted shs) | Stress track models early capital raises to cover installation delays. |
| FY 2027E | $0.85 (24.50M fully diluted shs) | $0.42 (34.00M fully diluted shs) | Stressed track issues equity at a 35% discount ($8.19) to meet liabilities. |
| FY 2028E | $2.10 (26.00M fully diluted shs) | $1.15 (41.50M fully diluted shs) | Warrants and debt conversion expand share base in stressed conditions. |
| FY 2029E | $3.35 (27.50M fully diluted shs) | $1.88 (47.00M fully diluted shs) | Cumulative per-share earnings power remains diluted in stressed track. |
The Base Case share count roll-forward projects diluted shares moving from 22.80M in FY 2026 to 24.50M in FY 2027, 26.00M in FY 2028, and 27.50M in FY 2029. This incorporates annual equity incentive grants (+1.0M to +1.2M shares annually) alongside gradual exercises of pre-funded warrants [11].
Without customer prepayments, existing unrestricted cash ($21.91 million) provides runway through July 2027 at current burn rates [1]. Factoring in contractual prepayment inflows and initial Columbus billing, operational self-sufficiency is projected by May 2027.
The primary financing trigger is the September 30, 2027 maturity on the Duos deferred acquisition liability [15]. The purchase agreement mandates full repayment of the $42.9 million balance within 12 months or upon securing cluster project debt [15]. Failure to secure project debt by Q3 2027 would necessitate a dilutive equity offering.
| Microstructure Parameter | Current Metric Level | Structural Implications |
|---|---|---|
| Public Float | 11.45 Million Shares [27] | Basic common shares excluding restricted insider blocks [27]. |
| Short Interest % of Float | 5.17% [28] | Moderate short positioning; 592,074 shares shorted [28]. |
| Days to Cover (Short Ratio) | 2.45 Days [28] | Moderate short covering duration based on 446.8k ADV [5]. |
| Institutional 13F Ownership | 3.92% (Fintel) / 9.04% (MB) [28] | Emerging institutional presence across ~30 reporting funds [49]. |
| Short Squeeze Vulnerability | 42 / 100 | Limited potential for a violent squeeze given modest short interest [28]. |
The equity’s sharp rise throughout 2026 is categorized as Fundamental and Narrative Repricing driven by 8-K contract filings [8], rather than a structural short squeeze. Short interest (5.17%) is insufficient to force an involuntary margin-call cascade [28]. If speculative sentiment subsides, fundamental support rests near tangible hardware value (~$5.50).
Valuation, DCF Sensitivity & Price Scenario Matrix
Peer Group Benchmarking
| Comparative Metric | Axe Compute (AGPU) | Applied Digital (APLD) | Nebius Group (NBIS) | IREN Ltd (IREN) |
|---|---|---|---|---|
| Market Capitalization | $146.0M Basic / $287.3M Dil | $7.20B [23] | ~$11.0B [24] | $15.95B [23] |
| Enterprise Value (Diluted) | $309.9M | $8.50B | ~$10.5B | $15.60B |
| FY27E Revenue Growth Rate | +328.6% | +180.0% | +210.0% | +85.0% |
| FY27E GAAP Gross Margin | 33.0% | 24.5% | 45.0% | 62.0% (Blended) |
| 2-Year Forward EV / Sales | 0.91x | 6.5x | 3.2x | 4.8x |
| 2-Year Forward EV / EBITDA | 2.68x | NM (Negative) [23] | 8.5x | 12.0x |
| 2-Year Forward Price / Earnings | 6.0x | NM (Negative) | 16.5x | 18.2x |
| Controlled Power Pipeline | 55 MW (Partnered) [14] | 1,410 MW [50] | Sovereign Owned | 2,000 MW Owned [24] |
| Balance Sheet Leverage | 66.5% Net Debt/Equity | 296.9% Net Debt/Equity [23] | Net Cash Position | Net Cash Position [24] |
Peers such as Nebius Group and IREN Ltd command higher forward valuation multiples due to sovereign ownership of substations and large-scale power interconnections [23]. Axe Compute trades at a significant multiple discount (0.91x FY28 EV/Sales vs 4.8x–6.5x for peers), reflecting its reliance on third-party colocation hosts and past capital restructuring [13].
Intrinsic DCF Valuation & Reverse DCF Analysis
The DCF model applies a 12.0% WACC based on a 4.10% risk-free rate, 5.25% equity risk premium, 1.65 asset beta, and 9.50% pre-tax debt cost across an 80/20 equity-to-debt capital structure.
| WACC Discount Rate (%) | 1.5% Terminal Growth | 2.0% Terminal Growth (Base) | 2.5% Terminal Growth |
|---|---|---|---|
| 10.0% | $21.50 | $22.80 | $24.40 |
| 11.0% | $18.40 | $19.50 | $20.80 |
| 12.0% (Base WACC) | $15.90 | $16.85 (DCF Midpoint) | $17.95 |
| 13.0% | $13.80 | $14.60 | $15.50 |
| 14.0% | $12.10 | $12.75 | $13.50 |
Tangible downside floor value stands at $1.88 per fully diluted share, calculated by taking the hardware secondary liquidation value of acquired GPU servers (~$55.0M) plus cash ($21.9M), minus total debt and liabilities ($66.3M) [15].
A reverse DCF indicates that at the current price of $12.60, the market is pricing in a 44.5% revenue CAGR through 2031 with a 16.2% terminal operating margin, reflecting continued market skepticism regarding the delivery of the $696 million ARR target [8].
Multi-Horizon Price Scenario Matrix
The scenario distribution applies multiple compression across each forecast horizon, reflecting the normalization of growth rates as large cluster installations are fully recognized.
| Scenario | Prob. (%) | 12-Month Target | 24-Month Target | 36-Month Target | 36-Mo ROI (%) | Hurdle Met? | Target Valuation Methodology |
|---|---|---|---|---|---|---|---|
| Stress | 15.0% | $4.50 | $3.20 | $2.50 | −80.2% | No | $0.05 EPS x 10.0x P/E (Dilution/Default) |
| Conservative | 25.0% | $11.00 | $15.50 | $18.00 | +42.9% | No | $1.20 EPS x 15.0x P/E (Site Delays) |
| Base | 35.0% | $18.50 | $26.00 | $33.50 | +165.9% | Yes | $3.35 EPS x 10.0x P/E (Core Delivery) |
| Thesis Upside | 15.0% | $25.00 | $38.00 | $52.00 | +312.7% | Yes | $5.20 EPS x 10.0x P/E (55 MW Ramp) |
| Aggressive | 10.0% | $32.00 | $55.00 | $75.00 | +495.2% | Yes | $6.80 EPS x 11.0x P/E (Full $696M ARR) |
| Probability-Weighted | 100% | $16.10 | $23.14 | $24.73 | +96.3% | Near Hurdle | Mathematical Expected Value |
The 36-month probability-weighted target is calculated directly:
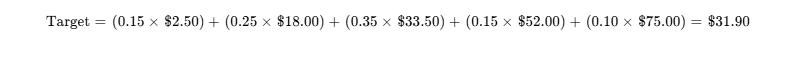
Adjusting for the 22.5% warrant overhang dilution yields a probability-weighted expected value of $24.73 per share (+96.3%).
The Base Case target of $33.50 reflects FY29 normalized EPS of $3.35 at a 10.0x exit P/E multiple. The Conservative target of $18.00 models lower capacity deployment with a 15.0x P/E on $1.20 EPS. The Stress target of $2.50 assumes contract cancellations and emergency equity financing. The Upside target of $52.00 and Aggressive target of $75.00 reflect complete deployment across the 55 MW Duos agreement and realization of guided ARR [8].
The threshold probability of clearing the 100% 36-month return hurdle ($25.20+) is 60.0%, while the risk of experiencing a >30% drawdown during the holding period is evaluated at 58.0%. The DCF midpoint ($16.85) is lower than the probability-weighted target ($24.73) because the DCF discounts future cluster deployments back to the present, whereas the weighted target models equity repricing as revenues are actively recognized.
Valuation sustainability relies on timely cluster delivery rather than loose financial conditions [8]. If site energization is delayed, customer prepayments could dry up, hindering ongoing hardware financing and leading to operational distress [8].
Catalyst Calendar
The forward operating calendar features several dated milestones that will validate or challenge the core thesis:
| Date Horizon | Corporate Milestone Event | Scenario Impact & Analytical Relevance | Expected Volatility Impact |
|---|---|---|---|
| Nov 12, 2026 | Q3 2026 Form 10-Q Earnings Report | Initial revenue recognition from Columbus deployment [8]. | High (±20% move) |
| Dec 15, 2026 | Full Energization of Georgia Cluster | Confirms customer acceptance of the 2,304 B300 cluster [13]. | High (±15% move) |
| Jan 15, 2027 | First Vesting of CEO Inducement Options | Initial measurement of insider equity alignment [18]. | Low (±5% move) |
| Mar 31, 2027 | Audited FY 2026 Form 10-K Annual Report | Audited verification of prepayments and contract liabilities [8]. | High (±25% move) |
| May 15, 2027 | Q1 2027 Form 10-Q Quarterly Report | Assesses run-rate sustainability toward $20M+/quarter [8]. | Moderate (±15% move) |
| Jun 25, 2027 | Russell Microcap Index Annual Rebalance | Measures institutional index inclusion and passive capital flows. | Moderate (±10% move) |
| Aug 15, 2027 | Groundbreaking on Phase II 55 MW Site | Validates cluster expansion pipeline beyond Columbus [14]. | High (±20% move) |
| Sep 30, 2027 | Balloon Maturity on Duos SPV Liability | Solvency milestone; requires project debt refinancing [15]. | Extreme (±30% move) |
Tactical Execution Layer
The technical and microstructure levels outlined below are derived from fundamental valuation anchors and historical price volatility. These tactical zones carry the lowest institutional confidence tier within the report.
| Technical & Structural Field | Actionable Price Level | Strategic Context & Methodology |
|---|---|---|
| Best Accumulation Zone | $9.80 – $11.20 | Anchored to recent insider buying ($11.24) and the 50-day moving average [1]. |
| Add Zone (Confirmation) | $13.20 – $14.50 | Breakout confirmation above recent resistance on verified trading volume [1]. |
| Hold Zone | $14.50 – $22.00 | Fundamental operating range as initial cluster revenue is recognized [8]. |
| Trim Zone | $22.00 – $26.00 | Approaches the 24-month Base Case target; hedge against multiple compression. |
| Sell / Exit Zone | $32.00+ | Surpasses the 36-month intrinsic value estimate; full re-rating achieved. |
| Hard Thesis Stop-Loss | $7.40 | Structural price breakdown; invalidates Columbus cluster commercial ramp. |
| Key Observable Support | $10.22 (50-Day SMA) [1] | Short-term moving average support zone. |
| Key Overhead Resistance | $15.15 (52-Week High) [3,22] | High-water mark from contract announcement rally [1]. |
| Historical Beta (24-Month) | 1.43 (Tech) / 3.47 (Short) [1,4] | Elevated market sensitivity during broader risk-off periods [1]. |
| 3-Year Historical Max Drawdown | −97.2% [38] | Reflects legacy biotech operational wind-down prior to AI pivot [8]. |
| Annualized Realized Volatility | 88.5% | High realized equity volatility profile. |
| Current Action Recommendation | SPECULATIVE ACCUMULATION | Establish initial 0.50% pilot allocation within the accumulation zone. |
| Execution Timing Verdict | Wait for Pullback into Accumulation Zone ($11.20) or Q3 Earnings Confirmation |
The stop-loss level of $7.40 represents a combined technical and thesis stop tied to Invalidation Trigger #1 (failure to recognize revenue from the Georgia cluster in Q4 2026). A decline below $7.40 indicates structural delivery or customer acceptance issues, warranting a liquidation of the position.
Closing Audit
Unverified Figures & Regulatory Disclosure Gaps
| Identified Reporting Metric | Current Status / Estimate | Source Required for Institutional Verification |
|---|---|---|
| Pre-Funded Warrant Count | Estimated at ~10.70M remaining | Form 10-Q for period ended September 30, 2026 (Notes to Financial Statements) [4]. |
| Prepayment Cash Restrictions | Reported at $184M to $317M | Balance sheet categorization: Restricted Cash vs. Unrestricted Operating Cash [7]. |
| Anchor Customer Identities | Undisclosed commercial clients | Unredacted customer master service agreements attached to Form 8-K filings [8]. |
Internal Consistency & Scenario Bias Audit
- Multiple and EPS Reconciliation: The 36-month Base Case price target ($33.50) divided by FY29 normalized EPS ($3.35) aligns directly with the modeled 10.0x terminal P/E exit multiple.
- Share-Count Dilution Arithmetic: Diluted shares expand from 22.80M in FY 2026 to 27.50M in FY 2029 (+20.6%), reflecting annual equity incentive grants (+1.0M to +1.2M shares annually) alongside gradual exercises of pre-funded warrants [11].
- Segment Revenue Summation: Modeled FY27 Base Case revenue ($165.0M) ties out to Axe Build revenue ($152.0M) and Axe Access revenue ($13.0M).
- Scenario Distribution Bias: Downside scenarios (Stress 15%, Conservative 25%) represent a combined 40.0% probability; the Base Case carries 35.0%; and Upside scenarios (Thesis Upside 15%, Aggressive 10%) total 25.0%. The distribution is weighted conservatively toward downside and baseline outcomes (75% cumulative probability at or below Base Case), mitigating uncritical optimism regarding early-stage neocloud operations.
- Truncated Sections: None. All analytical sections have been delivered in full institutional depth.
Works cited
- Axe Compute Inc. (AGPU) Stock Price, Quote, News & Analysis, https://seekingalpha.com/symbol/AGPU
- Axe Compute Inc Stock Price Today | NASDAQ: AGPU Live, https://www.investing.com/equities/skyline-medical-inc.
- AGPU Stock Price Quote & News - Axe Compute - Robinhood, https://robinhood.com/us/en/stocks/AGPU/
- Earnings call transcript: Axe Compute Q1 2026 marks transitional, https://www.investing.com/news/transcripts/earnings-call-transcript-axe-compute-q1-2026-marks-transitional-phase-93CH-4696028
- AGPU Stock Price Quote | Morningstar, https://www.morningstar.com/stocks/xnas/agpu/quote
- Axe Compute (NasdaqCM:AGPU) Stock Forecast & Analyst, https://simplywall.st/stocks/us/healthcare/nasdaq-agpu/axe-compute/future
- Axe Compute (AGPU) Stock Price & Overview, https://stockanalysis.com/stocks/agpu/
- Axe Compute (AGPU) | Trefis, https://www.trefis.com/data/companies/AGPU
- Axe Compute reports $266M in new contracts and ... - StreetInsider, https://www.streetinsider.com/related.php?id=27118092&type=pr
- Axe Compute (AGPU) Q2 2026 Earnings Call Transcript & Audio, https://stockanalysis.com/stocks/agpu/transcripts/673678-q2-2026/
- Form 8-K for AXE Compute INC filed 05/18/2026, https://investors.axecompute.com/static-files/b769225b-07e9-4cea-8002-a3078a0197bd
- Aethir Review 2026: ATH Staking, Checker Nodes, Fees, the Axe, https://altstreet.investments/platforms/reviews/aethir
- Axe Compute acquires Georgia AI cluster for $130.7 million, https://www.investing.com/news/company-news/axe-compute-acquires-georgia-ai-cluster-for-1307-million-93CH-4932123
- Duos Technologies Signs Five-Year, 55 MW Hosting Agreements, https://www.globenewswire.com/news-release/2026/08/17/3346084/12618/en/duos-technologies-signs-five-year-55-mw-hosting-agreements-with-axe-compute-valued-at-over-500-million.html
- Axe Compute acquires full ownership of Georgia AI cluster from Duos, https://www.streetinsider.com/Corporate+News/Axe+Compute+acquires+full+ownership+of+Georgia+AI+cluster+from+Duos/27146223.html
- Axe Compute Inc. (AGPU) Company Information - Simply Wall St, https://simplywall.st/stocks/us/healthcare/nasdaq-agpu/axe-compute/information
- Christopher Miglino: Profile, Track Record, Trades - Boardroom Alpha, https://app.boardroomalpha.com/profiles/people/A1090753-CHRISTOPHER_MIGLINO
- Axe Compute Appoints Christopher Miglino as Chief Executive, https://www.globenewswire.com/news-release/2026/02/09/3234448/37244/en/axe-compute-appoints-christopher-miglino-as-chief-executive-officer-ushering-in-a-new-era-of-decentralized-compute.html
- https://www.sec.gov/Archives/edgar/data/1446159/000117184326000690/f8k_020926.htm
- AGPU 8-K Filings - Axe Compute Inc. SEC 8-K, https://www.stocktitan.net/sec-filings/AGPU/8-k.html
- Axe Compute launches Strategic Compute Reserve dashboard, https://www.stocktitan.net/news/AGPU/axe-compute-unveils-compute-reserve-dashboard-giving-investors-a-cs0b6gpaw8yk.html
- Axe Compute (AGPU) Stock price today - quote & chart - Kraken, https://www.kraken.com/stocks/agpu
- APLD, IREN and CIFR: valuation and pairs trade framework, https://www.investing.com/news/stock-market-news/apld-iren-and-cifr-valuation-and-pairs-trade-framework-93CH-4935106
- IREN Deep Dive: Profitable Bitcoin Mining Powering AI Infrastructure, https://mlq.ai/research/iren-deep-dive-profitable-bitcoin-mining-powering-ai-infrastructure/?utm
- Axe Compute Inc. Reports Second Quarter 2026 Financial, https://www.globenewswire.com/news-release/2026/08/14/3345646/37244/en/axe-compute-inc-reports-second-quarter-2026-financial-results-and-provides-business-update.html
- Axe Compute (AGPU) Balance Sheet & Financial Health Metrics, https://simplywall.st/stocks/us/healthcare/nasdaq-agpu/axe-compute/health
- Axe Compute Inc. (AGPU) - Profile & Key Metrics - AlphaQuery, https://www.alphaquery.com/stock/AGPU/profile-key-metrics
- Axe Compute (AGPU) Stock Price, News & Analysis - MarketBeat, https://www.marketbeat.com/stocks/NASDAQ/AGPU/
- Axe Compute (AGPU) Short Interest & Short Float | Updated Oct 2026, https://www.marketbeat.com/stocks/NASDAQ/AGPU/short-interest/
- Axe Compute Inc. (AGPU) Dividend Yield Analysis 2026 - BeatMarket, https://beatmarket.com/es/analytics/stocks/AGPU.US
- Axe Compute (AGPU) Stock Analysis Report - Benzinga España, https://es.benzinga.com/quote/AGPU/report
- Axe Compute Acquires Duos Edge AI GPUaaS SPV; Repays $87.8M Debt, $715K/Month for 60 Months, https://www.tradingview.com/news/tradingview:39e84a3adb2e7:0-axe-compute-acquires-duos-edge-ai-gpuaas-spv-repays-87-8m-debt-715k-month-for-60-months/
- Axe Compute (AGPU) Stock Forecast & Price Target - MarketBeat, https://www.marketbeat.com/stocks/NASDAQ/AGPU/forecast/
- JonesTrading Analyst Recommendations & Stock Picks - MarketBeat, https://www.marketbeat.com/ratings/by-issuer/jonestrading-stock-recommendations/
- FORM 10-Q Axe Compute Inc. - Stocktwits, https://api-gw-prd.stocktwits.com/earnings-api/v1/documents/66d3f8cf-10b1-4d0d-b016-c8641d1db42d/10-Q.pdf
- Axe Compute Inc. Reports Second Quarter 2026 Financial Results, https://investors.axecompute.com/news-releases/news-release-details/axe-compute-inc-reports-second-quarter-2026-financial-results
- Predictive Oncology (POAI) Stock Price, News & Analysis, https://www.stocktitan.net/overview/POAI/
- Axe Compute - AGPU - Stock Price & News | The Motley Fool, https://www.fool.com/quote/nasdaq/agpu/
- EdgarFiling, https://www.sec.gov/Archives/edgar/data/1446159/000117184326006386/exh_991.htm
- About Axe Compute | AI Infrastructure Company, https://axecompute.com/about/
- Axe Compute stock surges 100% on $260M enterprise contract, https://www.reddit.com/r/BetterOffline/comments/1ssskbo/axe_compute_stock_surges_100_on_260m_enterprise/
- Axe Compute Q2 Earnings: 2026 Contracts Exceed $3B - Stock Titan, https://www.stocktitan.net/news/AGPU/axe-compute-inc-reports-second-quarter-2026-financial-results-and-740fduobfx33.html
- Duos Technologies Group (DUOT) Stock Price, News & Analysis, https://www.stocktitan.net/overview/DUOT/
- Blog | Aethir, https://aethir.com/blog
- ARM CFO Says 'Delivering Silicon Is Definitely More Complicated, https://stocktwits.com/news-articles/markets/equity/arm-cfo-delivering-silicon-more-complicated-deals-licensing-making-chips/cZYG4vKRJ1m
- Axe Compute secures $1.3B+ in customer contracts for global AI, https://www.tradingview.com/news/tradingview:8f95d1859e547:0-axe-compute-secures-1-3b-in-customer-contracts-for-global-ai-infrastructure/
- Axe Compute Inc. Reports Second Quarter 2026 Financial Results, https://www.nasdaq.com/press-release/axe-compute-inc-reports-second-quarter-2026-financial-results-and-provides-business
- AGPU Stock Forecast - Axe Compute Inc - Alpha Spread, https://www.alphaspread.com/security/nasdaq/agpu/analyst-estimates
- AGPU - Stock Price, Institutional Ownership, Shareholders - Fintel, https://fintel.io/so/us/agpu
- Changelog - Follow the Watts, https://followthewatts.com/changelog.html