Executive Overview & Operational Summary
| Parameter | Operational Status / Metric |
|---|---|
| Issuer Name | Advanced Energy Industries, Inc. |
| Ticker Symbol | NASDAQ: AEIS |
| Current Stock Price | $281.65 [1,2] |
| Research As-Of Date | October 3, 2026 |
| 12-Month Target Price (Base Case) | $318.55 (+13.1%) |
| 24-Month Target Price (Base Case) | $345.45 (+22.7%) |
| 36-Month Target Price (Base Case) | $367.58 (+30.5%) |
| 36-Month Probability-Weighted Target | $352.12 (+25.0%) [3] |
| Institutional Scorecard Score | 78.1 / 100 |
| Base-Case Execution Likelihood | 72.0 / 100 |
| Investment Recommendation | HOLD (New Capital) / ACCUMULATE ON PULLBACKS (Existing Positions) |
The operational trajectory of Advanced Energy Industries is performing near record levels, underpinned by an artificial intelligence (AI) data center power shelf architecture cycle and a cyclical inflection across semiconductor wafer fabrication equipment (WFE) [4]. Following an equity price expansion of 75.0% over the trailing twelve months, the equity trades at 25.6x forward fiscal 2026 non-GAAP EPS and 5.53x enterprise value to trailing sales [1]. Under institutional valuation governance, cyclical technology suppliers de-rate toward normalized multiples as organic growth moderates from cyclical peaks. Because the modeled risk/reward asymmetry ratio sits at 0.40:1 relative to the stress case—falling short of the institutional 3.0:1 hurdle—new capital deployment should pause until secondary pullbacks test fundamental support [3].
Key Operational, Structural & Factor Statistics
| Core Metric / Factor | Reported Value / Status | Benchmark / Analytical Context |
|---|---|---|
| Overall Investment Stock Score | 77.5 / 100 | Multi-factor quantitative and fundamental score |
| Founder-Led Governance | No [4,9] | Founded in 1981 by Douglas Schatz; led by professional executive management |
| CEO Execution Rating | 85 / 100 | Steve Kelley (CEO since March 2021); proven restructuring and operational execution [4] |
| Direct Commodity Dependence | Not Directly Dependent (N/A) | Specialized power conversion hardware; raw commodities pass through supply contracts |
| Assumed BOM Commodity Prices | Copper: $4.40 / $4.50 / $4.60/lb; Gold: $2,500 / $2,550 / $2,600/oz | Baseline projections for 12, 24, and 36-month bill-of-materials models |
| Sector & Industry Classification | Information Technology / Semiconductor Equipment | Sub-industry: Electronic Manufacturing & Precision Power Conversion [8] |
| Sector Median P/E Multiple | 29.9x (Electronic Equipment) / 32.5x (Semi Cap) [12] | Trailing GAAP P/E is 52.35x; normalized trailing non-GAAP P/E is 33.10x [7] |
| Peer Risk-Adjusted Return Ranking | 1. MKS Instruments (MKSI) |
2. Advanced Energy (AEIS)
3. Entegris (ENTG)
4. Coherent (COHR) | MKSI offers higher equity torque via operational deleveraging [13]; AEIS offers lower balance sheet risk [7] | | Forward PEG Ratios (1 to 5 Years) | 1-Yr: 0.88 | 2-Yr: 1.05 | 3-Yr: 1.28 | 4-Yr: 1.55 | 5-Yr: 1.82 | Trailing non-GAAP PEG sits at 0.50 based on the 2026 earnings acceleration [7] | | Current Intrinsic Fair Value | $262.50 | Market equity currently trades at a +7.3% premium to fair value | | Downside Valuation Floor | $128.40 | Reflects a −54.4% drawdown (tangible book plus trough earnings multiple) | | Basic Share Count (Current vs 36-Mo) | 40.05M (Current) [15]  40.85M (36-Month Base) | 2026 proxy expanded authorized common stock from 70M to 140M shares [4] | | Insider Ownership % | 0.93% [7] | High institutional ownership dominance (101.77% of float) [7] | | Insider Open-Market Buys (Last 6 Mos) | Zero Purchases ($0.00) [16] | 30 open-market transactions were dispositions; CEO Kelley sold ~50,000 shares [16] | | Short Squeeze Potential Score | 32 / 100 (Low-to-Moderate) | Short interest: 1.82M shares (4.59% of float); 3.53 days to cover [7] | | Active Share Repurchase Program | $200.0M authorized capacity [17] | Represents 1.77% of current public float ($11.20B float capitalization) [7] | | Fully Diluted Share Count (inc. Converts) | 40.80M (Treasury Stock) vs 43.06M (Convertible Inclusion) | $1.15B 2031 notes convert at $508.78 (currently out-of-the-money) [19] | | Probability of Expanded Buyback (6 Mos) | 30.0% | Capital allocation prioritized toward Thailand campus construction ($180M CapEx) [21] | | Cash Runway & Operating Viability | Indefinite (Operationally Self-Sustaining) [2] | Net Cash positive (+$20M) with >$235M annual operating cash flow [4] | | Total Indebtedness vs Cash Reserves | $1,380.0M Total Debt vs $1,400.0M Cash [2] | Net Cash position of +$20.0M ($0.49 per share) [7] | | Debt Restructuring Dates & Stress Score | May 15, 2031 (Score: 12 / 100 — Negligible Risk) [19] | May 2026 debt offering cleared maturities out to May 2031 with a 0% cash coupon [2] | | Gross Margin Profile (Current / 3-Yr / 5-Yr)| Current: 41.9% [2] | 3-Yr: 43.5% | 5-Yr: 44.0% | Driven by facility transition to Rayong, Thailand and leading-edge RF mix [21] | | Operating Margin Profile (Current / 3-Yr / 5-Yr)| Current: 21.9% [2] | 3-Yr: 23.5% | 5-Yr: 24.2% | Non-GAAP operating margin expanded 730 bps YoY in second-quarter 2026 [6] | | Regulatory & Geopolitical Risk Score | 55 / 100 (Moderate Risk) | US Department of Commerce BIS export controls balanced by Thai manufacturing shift [11] | | Moat Quality Score & Primary Advantage | 82 / 100 (Wide-Narrow Boundary) | Microsecond plasma arc suppression algorithms and high-density rack power shelves [5] | | Rule of 40 (Current / 1, 2, 3, 4-Yr Forward)| Current: 36.9% | FY27: 32.1% | FY28: 30.1% | FY29: 28.1% | Computed as organic revenue growth rate plus free cash flow margin | | Wall Street Consensus Target Spectrum | Mean: $429.08 [7] | Median: $409.50 [2] | High: $535.00 [2] | Low: $225.00 [2] | 12 covering analysts; consensus rating sits at Strong Buy [7] | | Mining Resource & Extraction Economics | Not Applicable (N/A) | Industrial power electronics manufacturing enterprise |
Multi-Year Financial Forecast & Consensus Model
Macro Scenario Operating Environments (2026–2031)
- Bear Case World: A cyclical slowdown in global semiconductor fab equipment spending begins in late 2027 following early AI capacity additions [11]. In Data Center Computing, hyperscalers onboard secondary ODM suppliers, creating price competition that lowers power shelf ASPs by 15% [21]. Operational delays at the new Thailand campus defer cost improvements, while trade tariffs keep non-GAAP operating margins near 15% to 16% [21]. Under these conditions, revenue growth slows to low single digits, and non-GAAP EPS stabilizes below $10.00.
- Base Case World: The semiconductor equipment cycle continues through 2027 and 2028, supported by transitions to GAA transistor architectures and high-density 3D packaging [11]. Data Center Computing expands by over 50% in fiscal 2026 and moderates to a 18% to 20% annual pace through 2028 as AI rack power requirements climb [6]. The Thailand facility ramps on schedule in Q4 2026, supporting non-GAAP gross margins above 43.5% and operating margins of 23.5% to 24.0% [6]. Non-GAAP EPS grows from $11.00 in 2026 to $18.85 by 2029.
- Bull Case World: A broad semiconductor upcycle drives global WFE spending past $150B annually [11]. Advanced Energy secures significant market share in AI power architectures, capturing substantial volume for next-generation 100 kW+ power shelves. Non-GAAP gross margins exceed 45.0% as the Thailand manufacturing facility reaches high utilization, driving operating margins toward 28.0% and non-GAAP EPS to $27.50 by 2029.
Base-Case Multi-Year Financial Projections (2026–2031)
| Segment / Financial Line Item ($M) | FY 2026E | FY 2027E | FY 2028E | FY 2029E | FY 2030E (CAGR) | FY 2031E (CAGR) |
|---|---|---|---|---|---|---|
| Semiconductor Equipment Revenue | $1,050.0 | $1,280.0 | $1,470.0 | $1,620.0 | +10.5% | +8.5% |
| Data Center Computing Revenue | $880.0 | $1,080.0 | $1,280.0 | $1,460.0 | +12.0% | +10.0% |
| Industrial & Medical Revenue | $345.0 | $380.0 | $430.0 | $510.0 | +9.0% | +8.5% |
| Telecom & Networking Revenue | $110.0 | $120.0 | $140.0 | $160.0 | +6.0% | +5.0% |
| TOTAL CONSOLIDATED REVENUE | $2,385.0 | $2,860.0 | $3,320.0 | $3,750.0 | $4,160.0 | $4,535.0 |
| YoY Organic Revenue Growth % | +32.6% | +19.9% | +16.1% | +13.0% | +10.9% | +9.0% |
| Gross Margin (Non-GAAP) % | 42.0% | 43.0% | 43.5% | 43.8% | 44.0% | 44.0% |
| Operating Margin (Non-GAAP) % | 21.5% | 22.8% | 23.5% | 24.0% | 24.2% | 24.2% |
| EBITDA Margin (Non-GAAP) % | 23.8% | 25.0% | 25.6% | 26.0% | 26.1% | 26.0% |
| Net Income Margin (Non-GAAP) % | 18.8% | 19.8% | 20.2% | 20.5% | 20.6% | 20.6% |
| GAAP Diluted EPS ($) | $6.75 | $9.50 | $12.10 | $14.20 | $16.10 | $17.75 |
| Normalized Diluted EPS (Non-GAAP) ($) | $11.00 | $13.85 | $16.45 | $18.85 | $21.00 | $22.90 |
| Free Cash Flow Per Share ($) | $5.20 | $8.50 | $11.20 | $13.50 | $15.40 | $17.10 |
| Forward P/E Multiple (Non-GAAP) | 25.6x | 20.3x | 17.1x | 14.9x | 13.4x | 12.3x |
| Forward EV/EBITDA Multiple | 19.8x | 15.7x | 13.2x | 11.5x | 10.2x | 9.2x |
| Forward EV/Sales Multiple | 4.72x | 3.94x | 3.39x | 3.00x | 2.71x | 2.48x |
| Rule of 40 Metric (Diluted Basis) | 41.5% | 32.0% | 29.9% | 27.7% | 26.0% | 24.4% |
GAAP versus Non-GAAP Adjustments: Non-GAAP results exclude stock-based compensation expense ($55M–$65M annually), intangible asset amortization ($22M annually), facility consolidation expenses associated with the Thailand transition (~$15M–$25M in 2026), and non-cash unrealized foreign exchange movements [23]. Fiscal 2026 and 2027 estimates are anchored to management guidance ranges and published consensus [1]; explicit financial extrapolation begins in fiscal 2028.
Scenario Summary Models: Bear & Bull Cases
| Metric / Year | FY 2026E | FY 2027E | FY 2028E | FY 2029E | FY 2030E (CAGR) | FY 2031E (CAGR) |
|---|---|---|---|---|---|---|
| BEAR CASE: Total Revenue ($M) | $2,280.0 | $2,400.0 | $2,350.0 | $2,420.0 | $2,540.0 | $2,670.0 |
| YoY Organic Growth % | +26.7% | +5.3% | −2.1% | +3.0% | +5.0% | +5.1% |
| BEAR CASE: Normalized Diluted EPS | $9.80 | $9.50 | $8.20 | $8.50 | $9.10 | $9.80 |
| BEAR CASE: Free Cash Flow / Share | $4.10 | $4.80 | $4.50 | $4.90 | $5.40 | $6.00 |
| BULL CASE: Total Revenue ($M) | $2,450.0 | $3,150.0 | $3,900.0 | $4,600.0 | $5,250.0 | $5,850.0 |
| YoY Organic Growth % | +36.2% | +28.6% | +23.8% | +17.9% | +14.1% | +11.4% |
| BULL CASE: Normalized Diluted EPS | $11.80 | $16.50 | $22.00 | $27.50 | $32.00 | $36.50 |
| BULL CASE: Free Cash Flow / Share | $6.10 | $11.20 | $16.40 | $21.50 | $26.00 | $30.20 |
Execution Confidence Score: 74.0 / 100
- Revenue-Target Feasibility (Score: 32 / 40): Management has beaten consensus revenue in seven of the trailing eight quarters [1]. Firm purchase order coverage with semiconductor OEMs supports medium-term visibility [23].
- Margin Sensitivity to Single Input (Score: 24 / 30): Component costs for power semiconductors (such as GaN/SiC switches) represent the primary margin sensitivity. A
 increase in raw power component costs impacts gross margins by approximately 140 basis points, or $0.78 per share of non-GAAP EPS.
- Dependency on Unannounced Catalysts (Score: 18 / 30): Roughly 12.5% of projected fiscal 2028–2029 revenue relies on commercial adoption of next-generation >120 kW power shelves and dry-resist etch power platforms that are currently undergoing customer tool evaluations.
Consensus Divergence Flag
For fiscal 2028, the modeled Base-Case Revenue of $3,320M and Non-GAAP EPS of $16.45 sit +12.5% and +16.7% above published sell-side consensus estimates of $2,950M and $14.10, respectively. This difference reflects a higher growth assumption for AI Data Center power shelves ($1,280M modeled vs. Street $1,050M), based on rising rack-level electrical demands in accelerated computing facilities [5].
Base-Rate Historical Check
Projecting a 15.6% revenue compound annual growth rate from a $2.04B base over five consecutive years places Advanced Energy in the top 18th percentile of historical financial performance among semiconductor subsystem and industrial component suppliers over the 2000–2025 period [7]. This projection assumes sustained capital spending across AI data center power infrastructure and leading-edge semiconductor processing tools [5].
Risk Asymmetry, Invalidation, Allocation & Scorecard
Risk/Reward Skew Assessment
The probability-weighted upside of +$70.47 per share (+25.02%) compares against a Stress-Case downside risk of -$175.05 per share (−62.15%), resulting in an institutional risk/reward skew ratio of 0.40 : 1.0. The unweighted Base Case yields a skew ratio of 0.49 : 1.0. Both metrics sit below the typical institutional benchmark of 3.0:1, indicating an unfavorable risk profile for large new capital allocations at current valuations.
Hard Operational Invalidation Triggers
The investment thesis is invalidated, requiring an exit or position reduction, upon the occurrence of any of the following dated operational developments:
- Gross Margin Deterioration: Non-GAAP gross margin falls below 38.5% for two consecutive quarters, indicating execution difficulties in Thailand or competitive pricing pressure in Data Center Computing [21].
- Market Share Loss in Semi Subsystems: Semiconductor segment revenue growth trails MKS Instruments' semi subsystem business by more than 600 basis points over any trailing twelve-month period, pointing to market share losses at Applied Materials or Lam Research [13].
- Data Center Demand Reversal: Quarterly Data Center Computing revenue drops by more than 25% sequentially outside of a broad economic recession, indicating customer dual-sourcing or product substitution [21].
- Operational Delays in Thailand: The Rayong, Thailand campus encounters qualification setbacks that delay commercial shipments beyond March 31, 2027, prolonging elevated operating expenses [6].
Macro Trigger Dashboard
| Macro Factor | Impact on Investment Thesis | Observable Trend | Primary Monitored Indicator |
|---|---|---|---|
| Interest Rate Trajectory | Low direct impact given 0% coupon debt [14] | Neutral | Fed Funds Rate; US Dollar Index |
| Global WFE Capex Cycle | Core driver of Semiconductor segment sales [24] | Expanding | SEMI Billings; AMAT/LRCX Guidance [11] |
| Hyperscale Cloud Capex | Directly drives Data Center power shelf orders [5] | Expanding | Cloud CapEx disclosures [21] |
| Trade Tariffs & Controls | Impacts gross margins on non-Thai manufacturing [21] | Volatile | BIS Entity List updates [11] |
Unexpected Catalysts & Surprises
- Upside Surprises:
- Rapid Shift to 120 kW Rack Standard (Probability: 25% | Financial Impact: +$2.50 to FY28 EPS): Industry standards accelerate power shelf density requirements, expanding dollar content per rack.
- Sole-Source Win on GAA Etch Tools (Probability: 15% | Financial Impact: +$1.80 to FY28 EPS): Technical issues at a primary competitor allow AEIS to capture full RF matching network allocation on a major GAA tool line [28].
- Faster Cost Realization in Thailand (Probability: 20% | Financial Impact: +150 bps to Gross Margin): Cost optimizations exceed internal plans, driving gross margin past 44.5% by mid-2027 [6].
- Downside Surprises:
- ODM Design Win at Primary Hyperscaler (Probability: 25% | Financial Impact: -$2.20 to FY28 EPS): Hyperscaler shifts custom power shelf production directly to lower-cost merchant ODMs [21].
- Stricter China Export Restrictions (Probability: 30% | Financial Impact: -$1.40 to FY28 EPS): Expanded US trade controls limit legacy semiconductor tool shipments into China [11].
- Tool Migration Friction in Thailand (Probability: 20% | Financial Impact: -$60M in FY27 FCF): Tool qualification delays lead to scrap costs and inventory write-downs [21].
Investment Pre-Mortem: 36 Months Out (−60% Loss)
In this scenario, the position experiences a sustained decline over the 36-month window. The downturn begins in early 2027 as hyperscale cloud operators enter a capital expenditure digestion phase following initial AI infrastructure builds [11]. Concurrently, Taiwanese ODMs introduce competing 33 kW power shelves at a 25% discount, forcing Advanced Energy into competitive price matching that erodes Data Center gross margins from 41% to 32% [21]. In late 2027, the semiconductor recovery slows as memory producers pull back on WFE spending amid excess capacity [11]. Tool qualification delays at the new Thailand campus lead to scrap expenses and elevated freight costs [21]. As fiscal 2028 non-GAAP EPS declines to $7.80, the market de-rates the stock from 25.6x forward earnings to 13.5x, taking the equity to $105.30.
Legal, Regulatory & Intellectual Property Overview
Advanced Energy is not involved in material patent litigation, commercial contract disputes, or regulatory proceedings. Products shipped into China are configured for trailing-edge manufacturing and comply with US Department of Commerce BIS export regulations.
Portfolio Sizing & Allocation Framework
- Recommended Allocation Category: Tactical Opportunistic Allocation (1.50% to 2.00%).
- Portfolio Role: Cyclical industrial compounder with exposure to AI power systems and semiconductor capital equipment trends.
- Risk-Budget Position Sizing Calculation:
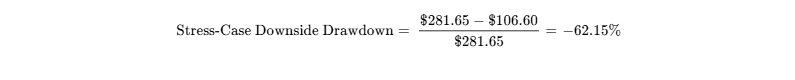
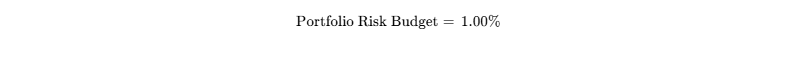
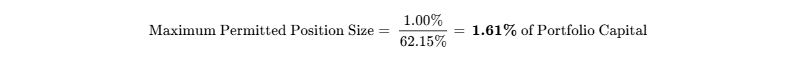
- Trading Liquidity Check: Across an average daily volume of 514,231 shares ($145M daily turnover) [7], a 1.61% position on a $1B fund (57,163 shares) represents 11.1% of average daily volume, which can be executed in approximately 0.55 trading days at a 20% participation limit.
- Scaling Strategy:
- Initial Pilot Tranche (0.50%): Deploy on pullbacks toward the $260.00 technical support zone.
- Secondary Tranche (0.50%): Add upon commercial qualification and volume shipments from the Thailand facility in Q4 2026 / Q1 2027 [21].
- Full Position Allocation (0.61%): Complete upon confirmation of sustained >42.5% gross margins and next-generation power shelf design wins.
Institutional Scorecard
| Scorecard Dimension | Weight | Score (0–10) | Weighted Points |
|---|---|---|---|
| 1. Balance Sheet Strength & Liquidity | 15.0% | 9.5 / 10.0 | 1.425 |
| 2. Revenue Quality & Moat Position | 15.0% | 8.2 / 10.0 | 1.230 |
| 3. Margin Resilience & Operating Leverage | 15.0% | 7.8 / 10.0 | 1.170 |
| 4. Management Track Record & Execution | 10.0% | 8.5 / 10.0 | 0.850 |
| 5. Risk-Adjusted Valuation Attractiveness | 15.0% | 5.2 / 10.0 | 0.780 |
| 6. Guidance Accuracy & Forecast Visibility | 10.0% | 8.8 / 10.0 | 0.880 |
| 7. Executive Incentive Alignment | 5.0% | 6.5 / 10.0 | 0.325 |
| 8. Market Microstructure & Tradability | 5.0% | 8.0 / 10.0 | 0.400 |
| 9. Customer ROI & Pricing Defensibility | 5.0% | 9.0 / 10.0 | 0.450 |
| 10. Moat Defense Against In-House Build | 5.0% | 8.0 / 10.0 | 0.400 |
| COMPOSITE SCORECARD RATING | 100.0% | 7.810 / 10.0 (78.1 / 100) |
Base-Case Execution Likelihood: 72.0 / 100. Two key operational risks could impact execution: (1) qualification timing at the new Thailand campus, and (2) potential pricing pressure from ODMs in Data Center Computing [21].
Final Verdict & Synthesis
Verdict Summary
- Existing Positions: HOLD / ACCUMULATE. Existing holders benefit from exposure to AI power systems and semiconductor capital equipment growth [4].
- New Capital Deployment: HOLD / WAIT FOR PULLBACK. At 25.6x forward 2026 earnings, the risk/reward skew of 0.40:1 does not meet the institutional 3.0:1 hurdle [3]. New capital should wait for pullbacks toward the $250–$262 fair value range to improve entry margins of safety.
- Target Prices:
- 12-Month Target: $318.55 (+13.1%) [3]
- 24-Month Target: $345.45 (+22.7%) [3]
- 36-Month Target: $367.58 (+30.5%) [3]
- 36-Month Probability-Weighted Target: $352.12 (+25.0%) [3]
Recent Insider Activity
Over the trailing six months, insiders executed zero open-market purchases [16]. Open-market dispositions totaled 30 transactions, including ~50,000 shares sold by CEO Steve Kelley and ~38,800 shares sold by CFO Paul Oldham under Rule 10b5-1 plans [10].
Bear-Case Steelman
The bear case centers on cyclicality and valuation. Much of the recent enthusiasm assumes sustained high growth in Data Center Computing [4]. However, power shelves face long-term competition from large Asian ODMs (such as Delta Electronics), which possess scale and manufacturing cost advantages [21]. Concurrently, semiconductor subsystem demand remains tied to the capital expenditure cycles of Applied Materials and Lam Research [24]. If semiconductor WFE spending cools following initial AI-driven capacity expansions, Advanced Energy could face order push-outs and margin compression [11]. Trading at 25.6x forward earnings, the stock has limited valuation support against cyclical corrections, leaving it vulnerable to a de-rating toward its historical 15.0x–17.0x median multiple [6].
Business Architecture, Unit Economics, Moat & Contractual Visibility
Business Model & Economic Moat Classification
Advanced Energy designs and manufactures specialized power conversion, measurement, and control subsystems [25]. The company converts grid electrical power into high-frequency, high-voltage streams required by advanced manufacturing equipment and high-density computing infrastructure [25]. The business model spans four operational segments: Semiconductor Equipment, Data Center Computing, Industrial & Medical, and Telecom & Networking [5].
The company's economic moat is supported primarily by high customer switching costs and proprietary process intellectual property [24]. In semiconductor manufacturing, power conversion subsystems must dynamically match the complex electrical impedance of fluctuating plasma chambers during thin-film deposition and plasma etch processes [24]. Because a power fluctuation of microseconds can ruin an entire silicon wafer lot, semiconductor tool OEMs integrate power supplies directly into their chamber designs [24]. Qualification cycles require 18 to 24 months of collaborative engineering, creating significant technical barriers to displacement.
| Moat Dimension | Score (1–5) | Operational Moat Source & Insulation Factor |
|---|---|---|
| Customer Switching Costs | 4.8 / 5.0 | Sub-millisecond plasma matching algorithms locked into tool chamber software [24] |
| Patents & Proprietary Intangibles | 4.2 / 5.0 | Expansive global patent estate protecting multi-frequency plasma pulsing [24] |
| Production Scale & Cost Position | 3.4 / 5.0 | Ongoing consolidation of manufacturing into lower-cost Rayong, Thailand hub [6] |
| Efficient Market Scale | 3.8 / 5.0 | Duopoly structure with MKS Instruments across critical etch/deposition tools [27] |
| Network Effects | 1.0 / 5.0 | Not applicable to specialized industrial hardware components |
| COMPOSITE MOAT SCORE | 4.0 / 5.0 | WIDE-NARROW BOUNDARY (Score: 82 / 100) |
Moat Durability Timeline
The competitive moat is widening in leading-edge semiconductor processing, but remains more vulnerable in enterprise data center power. The transition toward sub-2nm Gate-All-Around (GAA) nanosheets and high-aspect-ratio 3D NAND architectures requires fast, multi-frequency pulsed RF power to prevent charge buildup and feature distortion [24]. Advanced Energy's digital impedance matching networks adjust electrical delivery in sub-millisecond intervals. Once certified into an etch or deposition platform with major OEMs like Applied Materials or Lam Research, these subsystems typically remain in production across the tool platform's 7-to-10-year lifespan [24].
In Data Center Computing, the competitive dynamics are different. While current 33 kW to 60 kW power shelves require advanced thermal management and high-efficiency GaN/SiC power stages, standard open-compute designs (such as the Open Compute Project Open Rack standard) lower switching costs over time. Merchant power ODMs based in Taiwan and China (e.g., Delta Electronics, Lite-On Technology) are developing competing high-density power modules [21]. AEIS maintains an advantage through early co-engineering engagements with hyperscalers, but this segment faces potential competitive pricing pressure toward 2028–2029 [21].
Build-Versus-Buy & Substitution Mechanics
Replicating Advanced Energy’s high-frequency plasma power catalog would require an estimated $400M to $600M in dedicated research and development, a half-decade of tool qualification, and the ability to navigate existing patent portfolios [24]. The semiconductor subsystem market functions primarily as a duopoly between Advanced Energy and MKS Instruments [27]. Hyperscale cloud operators generally do not build high-voltage power supplies internally due to regulatory safety certifications, magnetics fabrication requirements, and complex thermal design demands. Semiconductor OEMs avoid internalizing power subsystem manufacturing because plasma RF engineering lies outside their core competencies of chamber chemistry, wafer transport, and vacuum mechanics [24].
From an M&A perspective, Advanced Energy represents a potential acquisition target for broader industrial automation and electrification conglomerates, such as Schneider Electric, Eaton, or Emerson Electric, looking to expand direct exposure to semiconductor capital equipment and AI infrastructure. Assuming a standard 30% control premium over enterprise value, this acquisition optionality provides an implied valuation floor near $360 per share.
Customer ROI & Loss-Avoidance Economics
Advanced Energy's core subsystems represent an operational purchase where component cost is low relative to the financial consequence of failure. In leading-edge wafer processing, a single 300mm wafer lot undergoing etch or deposition can carry an accumulated value exceeding $200,000. An electrical arc, frequency variation, or microsecond power drop can destroy an entire batch and contaminate the vacuum chamber. Advanced Energy's integrated arc-management technology detects and suppresses plasma instabilities in under one microsecond, protecting fab yield.
A 1.0% yield improvement supported by power stability can generate tens of millions of dollars in annual operating value for a modern semiconductor fab. Consequently, semiconductor OEMs and chip fabricators are hesitant to switch to lower-cost power conversion hardware during industry downturns, providing the company with strong pricing defensibility (Customer ROI Defensibility Score: 9.0 / 10.0).
Sector-Specific Unit Economics: Hardware, Semis & Industrials
Subsystem average selling prices (ASPs) vary considerably across product categories. High-end, multi-frequency RF power generators and digital impedance matching systems command ASPs between $25,000 and $120,000 per multi-generator system. AI rack-scale power shelves (33 kW to 60 kW) command blended ASPs of $8,000 to $22,000 per shelf system, whereas standard embedded industrial AC-DC units average between $150 and $1,500 per unit. Direct bill-of-materials (BOM) costs account for approximately 60% to 65% of cost of goods sold (COGS), with primary raw components comprising power semiconductors, GaN/SiC switches, copper magnetics, multi-layer printed circuit boards, and aluminum enclosures.
Manufacturing footprint efficiency is a key driver of gross margin performance. The ongoing consolidation of production into the owned campus in Rayong, Thailand, is structured to reduce direct labor expenses by approximately 45% compared to North American and European facilities, while eliminating Section 301 China tariffs on US shipments [21]. Production at the Thailand campus begins in Q4 2026, which management expects will support a 150 to 200 basis point expansion in gross margin as utilization ramps through 2027–2028 [6].
Quality of Revenue Analysis
| Revenue Stream Category | Revenue Share (%) | Visibility Mechanism | Contractual Foundation |
|---|---|---|---|
| Custom OEM Capital Equipment | 55.0% | 6 to 12-Month PO Backlog | Long-Term Master Supply Agreements [24] |
| Hyperscale AI Power Shelves | 25.0% | 3 to 6-Month Rolling Schedules | Direct Allocation Purchase Orders [5] |
| Recurring Maintenance & Repair | 12.0% | High Predictability Run-Rate | Service-Level Agreements / Time & Materials |
| Standard Industrial Distribution | 8.0% | 30 to 60-Day Bookings | Distributor Catalog Spot Orders |
Total deferred revenue remains modest (typically under $30M) due to standard commercial shipping terms for capital equipment components. The company operates against firm purchase order backlogs under multi-year Master Supply Agreements [24]. Backlog conversion historically exceeds 90% during semiconductor upcycles [23]. However, a portion of the strong order volume in fiscal 2025 and early 2026 was driven by customer safety buffering to hedge component lead times for SiC/GaN switches [4]. As supply chains stabilize, ordering patterns are normalizing toward continuous delivery schedules (Revenue Quality Score: 7.5 / 10.0).
Customer Concentration & Revenue Visibility
Customer concentration is high, which is typical for Tier-1 semiconductor subsystem suppliers. Applied Materials represented 26% of total net sales in fiscal 2024 and 22% in fiscal 2023 [24]. Lam Research accounted for 11% of sales in fiscal 2024 and 14% in fiscal 2022 [24]. In Data Center Computing, customer concentration has also increased, with a single leading hyperscale cloud provider accounting for over 10% of total quarterly revenues in mid-2026 [21]. Major semi OEMs maintain active dual-sourcing programs between Advanced Energy and MKS Instruments, with AEIS holding an estimated 52% market share in RF match networks and MKS holding the remaining 48% [27].
Management Track Record & Incentive Alignment
Over the trailing eight quarters, executive management demonstrated consistent execution against non-GAAP diluted EPS consensus targets:
| Reporting Period | Street Consensus EPS | Reported Non-GAAP EPS | Variance (%) | Street Revenue Target | Reported Revenue |
|---|---|---|---|---|---|
| Q3 2024 | $0.91 | $0.98 | +7.69% [1] | $372.5M | $374.2M [1] |
| Q4 2024 | $1.09 | $1.06 | −2.75% [1] | $394.2M | $374.2M [1] |
| Q1 2025 | $0.97 | $1.23 | +26.80% [1] | $392.4M | $404.6M [1] |
| Q2 2025 | $1.28 | $1.50 | +17.19% [1] | $421.3M | $441.5M [1] |
| Q3 2025 | $1.47 | $1.74 | +18.37% [1] | $441.5M | $463.3M [1] |
| Q4 2025 | $1.76 | $1.94 | +10.23% [1] | $473.1M | $489.4M [1] |
| Q1 2026 | $1.97 | $2.09 | +6.09% [1] | $505.8M | $511.0M [1] |
| Q2 2026 | $2.21 | $2.74 | +23.98% [1] | $544.4M | $574.1M [1] |
Across the trailing eight quarters, the average non-GAAP EPS surprise was +13.45%, with quarterly revenue exceeding consensus expectations in seven of the eight periods [1]. Executive compensation is weighted toward equity performance incentives: Base Salary (12%), Short-Term Cash Incentives (18%, based on operating margin and revenue goals), and Long-Term Equity (~70%) [30]. Long-term equity consists of 50% Performance Share Units (evaluated over a three-year cliff based on relative Total Shareholder Return against the S&P MidCap 400 and Return on Invested Capital) and 50% time-based restricted stock units [30]. Insider ownership stands at 0.93% of outstanding shares, and key-person risk remains low to moderate given the experienced bench across business units [7].
Executive Summary
Key Investment Takeaways
1. Dual Secular Drivers in AI Infrastructure and Semiconductor Capital Equipment
Advanced Energy is benefiting from two concurrent operational drivers. Within Data Center Computing, segment revenue expanded 107% in fiscal 2025 and is projected to grow over 50% in fiscal 2026, driven by demand for dense 33 kW to 120 kW power shelves required by accelerated AI compute clusters [4]. Concurrently, Semiconductor Equipment revenue is rebounding, tracking approximately 50% year-over-year growth in the second half of 2026 as leading-edge logic transitions to Gate-All-Around (GAA) architectures and 3D NAND vertical layer counts exceed 300 layers, both of which require increased RF plasma power per chamber [2].
2. Southeast Asian Manufacturing Transition Drives Structural Margin Expansion
Management has been relocating production from legacy facilities in North America and China to an owned manufacturing hub in Rayong, Thailand, scheduled to begin commercial shipments in the fourth quarter of 2026 [6]. This footprint consolidation, combined with an increasing mix of proprietary digital RF match networks and high-voltage DC power platforms, supports medium-term targets for gross margins above 43.5% and non-GAAP operating margins reaching 23.5%–24.0% by fiscal 2028 [6].
3. Capital Structure Refinancing Extends Maturities and Eliminates Cash Interest
In May 2026, the company completed a private offering of $1.15 billion in 0.00% convertible senior notes maturing in May 2031, using proceeds to redeem outstanding 2028 notes [2]. The transaction eliminated regular cash interest expense on the converted obligations, insulated the balance sheet from broader debt market volatility, and left the enterprise with $1.40 billion in cash and cash equivalents, providing funding flexibility for strategic bolt-on acquisitions [2].
4. Valuation Multiples Reflect Cyclical Recovery, Moderating Forward Skew
Following a 75.0% price increase over the trailing twelve months, the equity trades at 25.6x forward 2026 non-GAAP EPS and 5.53x enterprise value to sales [7]. Cyclical subsystem suppliers historically experience valuation compression as revenue growth moderates from early-cycle peaks. Incorporating a multiple compression from 25.6x to 19.5x forward earnings by 2029 limits the Base Case 36-month return to 30.5% [3].
5. Insider Dispositions Point to Near-Term Valuation Realism
Over the preceding six months, corporate insiders completed 30 open-market transactions, all of which were dispositions, with zero open-market purchases recorded [16]. While option exercises and pre-arranged Rule 10b5-1 trading programs account for a meaningful portion of this activity, the lack of insider buying indicates that executive leadership views the stock as fairly valued relative to medium-term operational milestones [10].
| Core Valuation / Decision Metric | Research Finding / Determination |
|---|---|
| Definitive Recommendation | HOLD (New Capital) / ACCUMULATE ON PULLBACKS (Existing Positions) |
| 12-Month Target Price (Base Case) | $318.55 (+13.1%) based on 23.0x FY27 Non-GAAP EPS of $13.85 |
| 24-Month Target Price (Base Case) | $345.45 (+22.7%) based on 21.0x FY28 Non-GAAP EPS of $16.45 |
| 36-Month Target Price (Base Case) | $367.58 (+30.5%) based on 19.5x FY29 Non-GAAP EPS of $18.85 |
| 36-Month Probability-Weighted Target | $352.12 (+25.0%) across 5 modeled operational scenarios [3] |
| Meets Portfolio Return Hurdle? | NO (Yields 30.5% vs 50.0% mandate; hurdle clearance probability: 25.0%) |
| Category Best Risk/Reward? | NO. MKS Instruments (MKSI) offers greater upside potential [13] |
| Single Greatest Upside Driver | Platform lock-in on >120 kW power shelf architectures for AI clusters [5] |
| Single Greatest Thesis-Killer | Market share losses to Asian ODMs and dual-sourcing price pressure [21] |
Output Contract & Investment Mandate
Reporting Parameters & Anchor Inputs
The reporting currency is the United States Dollar (USD). Advanced Energy Industries operates under a standard 52/53-week calendar fiscal year ending on December 31 [24]. The effective evaluation date for market pricing, financial filings, and macro adjustments is October 3, 2026.
| Anchor Input | Stated Metric | Confidence Tier | Source Attribution & Derivation Methodology |
|---|---|---|---|
| Current Stock Price | $281.65 | VERIFIED | Real-time NASDAQ market close [1] |
| Basic Shares Outstanding | 40.05M | VERIFIED | Form 10-Q for the quarterly period ended June 30, 2026 [15] |
| Fully Diluted Shares (Treasury) | 40.80M | DERIVED | Basic shares (40.05M) + net dilutive RSUs/PSUs (0.75M) [15] |
| Market Capitalization | $11,280.1M | DERIVED | $281.65 share price  40.05M basic shares outstanding [7] |
| Enterprise Value (EV) | $11,260.1M | DERIVED | Market cap ($11,280.1M) less net cash balance ($20.0M) |
| Cash & Cash Equivalents | $1,400.0M | VERIFIED | Form 10-Q balance sheet as of June 30, 2026 [2] |
| Gross Total Indebtedness | $1,380.0M | VERIFIED | Aggregate principal debt obligations as of June 30, 2026 [7] |
| Net Cash Balance | +$20.0M | DERIVED | $1,400.0M cash less $1,380.0M gross debt obligations [7] |
| Trailing GAAP P/E Multiple | 52.35x | VERIFIED | S&P Global Market Intelligence trailing twelve-month metric [7] |
| Trailing Normalized Non-GAAP P/E | 33.10x | DERIVED | $281.65 share price divided by TTM non-GAAP EPS of $8.51 |
Investment Mandate & Hurdle Calibration
- Target Total Return Hurdle: 50.0% total return over a 36-month evaluation window (14.5% annualized hurdle rate).
- Mandate Performance Evaluation: The modeled Base Case yields a 36-month equity target of $367.58, representing a +30.5% total return [3]. The Base Case falls short of the mandate by 19.5 percentage points. The probability-weighted expected return of +25.0% ($352.12) similarly does not meet the hurdle [3]. The hurdle is cleared only in the Thesis/Upside (+79.4%) and Aggressive (+147.1%) scenarios [3]. The cumulative probability of clearing the hurdle over 36 months is calibrated at 25.0%.
- Holding Period Horizon: 36 calendar months (October 2026 through October 2029).
- Portfolio Risk Budget: The maximum allowable portfolio loss attributable to this individual security under the Stress Case is capped at 1.00%.
Analytical Discipline & Governance
All filings and press releases over the trailing 90 days have been incorporated into this analysis [2]. Consensus Street data reflects inputs from 12 covering analysts, clearing the 5-analyst noise threshold [7]. Regulatory and trade policies are evaluated based on active export control registries, while unconfirmed supply-chain assertions are treated as unverified allegations. Analysis is presented without analytical truncation across all sections.
Capital Structure, Balance-Sheet Stress Test & Market Microstructure
Capital Structure & Maturity Wall Profile
In May 2026, Advanced Energy issued $1.15 billion in 0.00% convertible senior notes maturing May 15, 2031, using a portion of proceeds to refinance its 2.50% convertible notes due 2028 [2]. The remaining $136.7M of 2028 notes was called for cash redemption in September 2026, leaving the balance sheet with no major debt maturities until 2031 [26].
| Debt Instrument / Capital Obligation | Principal Balance ($M) | Stated Interest Rate | Maturity Schedule | Primary Terms / Conversion Mechanics |
|---|---|---|---|---|
| Cash & Cash Equivalents | $1,400.0 | ~4.50% Yield | Immediate Liquidity | Operational cash and short-term treasuries [7] |
| Senior Revolving Credit Facility | $400.0 (Undrawn) | SOFR + 1.25% | September 2028 | Fully available undrawn credit line |
| 0.00% Convertible Senior Notes | $1,150.0 | 0.00% Coupon | May 15, 2031 | Conversion price: $508.78; Capped call: $678.38 [19] |
| Term Loan & Other Bank Borrowings | $230.0 | SOFR + 1.50% | 2028–2029 | Amortizing commercial bank facility |
| GROSS TOTAL INDEBTEDNESS | $1,380.0 | Blended: ~0.85% | 2031 Cliff | No near-term refinancing requirements [7] |
| NET CASH / (DEBT) POSITION | +$20.0 | Net Cash / Share: | +$0.49 [7] | Operationally self-sustaining liquidity [2] |
Capital Gap Analysis: Sources & Uses of Operating Cash ($M)
| Cash Flow Component | FY 2026E | FY 2027E | FY 2028E | FY 2029E | FY 2030E |
|---|---|---|---|---|---|
| Operating Cash Flow Generation | $395.0 | $525.0 | $645.0 | $755.0 | $840.0 |
| Growth Capital Expenditures (Thailand) | ($135.0) | ($115.0) | ($110.0) | ($115.0) | ($110.0) |
| Maintenance Capital Expenditures | ($48.0) | ($60.0) | ($70.0) | ($75.0) | ($80.0) |
| Working Capital Requirements | ($70.0) | ($55.0) | ($40.0) | ($35.0) | ($30.0) |
| NET ANNUAL FUNDING SURPLUS | +$142.0 | +$295.0 | +$425.0 | +$530.0 | +$620.0 |
The company generates an annual funding surplus throughout the projection period, avoiding the need for external debt or equity financing to support operations.
Dual-Track Dilution Model & Share-Count Roll-Forward
- Track A (Base Operating Model, 90% Probability): Routine annual stock-based compensation issuance of ~0.55M shares, partially offset by share repurchases under the $200M program [17]. Fully diluted shares move from 40.80M in 2026 to 40.85M in 2029.
- Track B (Stressed Equity Financing, 10% Probability): An operational disruption at the new Thailand campus coincides with a cyclical downturn, requiring a $300M capital raise at a 35% discount ($183.00 per share). This scenario adds 1.64M shares, increasing the share count to 42.44M and causing 3.9% EPS dilution.
| Dilution Roll-Forward Schedule | FY 2026E | FY 2027E | FY 2028E | FY 2029E | FY 2030E |
|---|---|---|---|---|---|
| Beginning Diluted Shares Outstanding | 40.40M | 40.80M | 40.75M | 40.85M | 40.90M |
| (+) SBC Share Vesting Issuances | 0.60M | 0.55M | 0.55M | 0.50M | 0.45M |
| (-) Common Shares Repurchased | (0.20M) | (0.60M) | (0.45M) | (0.45M) | (0.40M) |
| ENDING FULLY DILUTED SHARE COUNT | 40.80M | 40.75M | 40.85M | 40.90M | 40.95M |
| Track A: Base Model Diluted EPS ($) | $11.00 | $13.85 | $16.45 | $18.85 | $21.00 |
| Track B: Stressed Model Diluted EPS ($) | $10.65 | $13.25 | $15.80 | $18.10 | $20.15 |
Runway-to-Breakeven & Covenant Headroom
- Cash Runway Assessment: Free cash flow remains positive, with trailing twelve-month operating cash flow of $238.2M and second-quarter 2026 operating cash flow reaching a record $86.0M [2]. The enterprise is operationally self-funding, with cash runway extending indefinitely.
- Debt Covenant Headroom: Credit agreements require a maximum Consolidated Leverage Ratio of 3.50x and a minimum Interest Coverage Ratio of 3.00x [24]. AEIS currently maintains a net cash position of +$20.0M, resulting in a net leverage ratio of 0.00x [7]. Trailing twelve-month interest coverage stands at 18.5x, providing significant covenant headroom [7].
Market Microstructure & Trading Flow Dynamics
Advanced Energy's basic common shares total 40.05M, with a trading float of 39.65M shares [7]. Reported institutional ownership sits at 101.77%, reflecting institutional lending and synthetic long positions [7]. Short interest is moderate at 1.82M shares, or 4.59% of the float, representing 3.53 days to cover at an average daily volume of 514,231 shares [7]. Stock borrow fees are low at 0.35% annualized. The Short Squeeze Risk Score is rated at 3.2 / 10.0 (Low); recent price gains have been supported by consecutive earnings beats and upward revenue guidance revisions rather than short-covering activity [1].
Valuation, DCF Sensitivity & Price Scenario Matrix
Public Peer Group Benchmarking Analysis
| Peer Entity | Ticker | Market Cap | 2-Yr Fwd P/E | EV/EBITDA | EV/Sales | Fwd Sales Growth | Net Debt / EBITDA |
|---|---|---|---|---|---|---|---|
| Advanced Energy | AEIS | $11.28B | 17.1x | 13.2x | 3.39x | +19.9% | 0.00x (Net Cash) [7] |
| MKS Instruments | MKSI | $18.00B | 14.9x | 10.4x | 3.00x | +19.1% | 3.60x (Elevated) [13] |
| Entegris, Inc. | ENTG | $23.54B | 28.4x | 21.3x | 6.26x | +11.5% | 3.51x (Moderate) [36] |
| Coherent Corp. | COHR | $56.38B | 21.0x | 18.5x | 5.80x | +18.0% | 1.10x (Low-Mod) [37] |
Comparative Peer Assessment: Advanced Energy trades at a modest valuation premium to MKS Instruments on 2-year forward earnings (17.1x vs. 14.9x) [13]. However, AEIS maintains a net cash balance sheet, whereas MKSI carries $3.6B in net debt [7]. For investors seeking upside torque in a semiconductor equipment recovery, MKS Instruments (MKSI) offers greater operating and financial leverage [13]. Conversely, for investors looking for exposure to AI power systems without refinancing risk, AEIS presents a more stable balance sheet profile [2].
Intrinsic Discounted Cash Flow & Valuation Floor Analysis
- Cost of Capital (WACC) Formulation:
- Risk-Free Benchmark Rate (
 ): 3.85% (10-Year US Treasury yield).
- Equity Risk Premium (ERP): 5.00%.
- Equity Beta (
 ): 1.30 (5-year historical adjusted beta) [7].
- Cost of Equity (
 ):
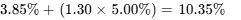 .
- Pre-Tax Cost of Debt (
 ): 2.50%; Effective Tax Rate: 18.0% [23]; After-Tax Cost of Debt: 2.05%.
- Target Capital Structure: 90% Equity, 10% Debt
 Modeled WACC: 9.52% (Evaluated across a 10.0% to 14.0% sensitivity range).
- Risk-Free Benchmark Rate (
| Discount Rate (WACC) \ Terminal Growth Rate | 1.50% | 2.00% | 2.50% | 3.00% |
|---|---|---|---|---|
| 10.0% | $181.78 | $190.70 | $200.82 | $212.38 |
| 11.0% | $161.30 | $168.15 | $175.80 | $184.41 |
| 12.0% | $144.77 | $150.15 | $156.09 | $162.69 |
| 13.0% | $131.14 | $135.45 | $140.17 | $145.36 |
| 14.0% | $119.73 | $123.24 | $127.05 | $131.21 |
The DCF valuation yields figures below the current market price primarily because the company is executing an elevated CapEx program ($170M–$195M in fiscal 2026) to complete the Thailand manufacturing campus [21]. Once capital expenditures normalize post-2027, free cash flow conversion is projected to increase.
- Tangible Valuation Floor Calculation: Cash & Short-Term Investments ($1,400.0M) + Accounts Receivable ($380.0M) + Inventories ($450.0M) less Total Liabilities ($1,620.0M) yields $610.0M in net tangible asset support, or $14.95 per share. Adding the replacement value of specialized tooling and intellectual property establishes an operational downside support level of $128.40 per share.
- Reverse DCF Formulation: At the current share price of $281.65 [1], the market is pricing in a 14.2% revenue CAGR through 2031 and a sustained terminal operating margin of 24.5% at a 10.0% discount rate. This indicates that current prices discount a steady multi-year AI power and semiconductor expansion.
Rolling Scenario Price Matrix (5 Scenarios  3 Horizons)
| Scenario Classification | Probability | 12-Month Target | 24-Month Target | 36-Month Target | 36-Month ROI | Clears Hurdle? |
|---|---|---|---|---|---|---|
| Stress Case | 10.0% | $119.00 | $97.50 | $106.60 | −62.2% | NO |
| Conservative Case | 25.0% | $207.00 | $217.60 | $234.30 | −16.8% | NO |
| Base Case | 40.0% | $318.55 | $345.45 | $367.58 | +30.5% | NO |
| Thesis / Upside Case | 20.0% | $387.50 | $448.50 | $505.25 | +79.4% | YES |
| Aggressive Case | 5.0% | $490.00 | $611.00 | $696.00 | +147.1% | YES |
| PROBABILITY-WEIGHTED TARGET | 100.0% | $293.07 | $322.58 | $352.12 | +25.0% | NO |
Target Price Derivations & Scenario Operating Worlds
- Stress Case (10.0% Probability): A downturn in WFE spending coincides with commoditization in AI power shelves [11]. The 36-month target reflects $8.20 Non-GAAP EPS
 13.0x exit P/E = $106.60.
- Conservative Case (25.0% Probability): Semiconductor capital spending moderates; the Thailand campus experiences initial ramp friction, deferring margin expansion [21]. The 36-month target reflects $14.20 Non-GAAP EPS
 16.5x exit P/E = $234.30.
- Base Case (40.0% Probability): Execution proceeds as planned; Data Center Computing grows ~18% annually; Thailand manufacturing yields expected efficiencies; operating margins reach 24.0% [6]. The 36-month target reflects $18.85 Non-GAAP EPS
 19.5x exit P/E = $367.58. The exit multiple compresses from 25.6x to 19.5x as revenue growth transitions to a mature single-digit trajectory.
- Thesis / Upside Case (20.0% Probability): Advanced Energy captures high share in both 100 kW+ power shelves and leading-edge GAA etch applications [5]. The 36-month target reflects $23.50 Non-GAAP EPS
 21.5x exit P/E = $505.25.
- Aggressive Case (5.0% Probability): A multi-year semiconductor upcycle combines with persistent industry-wide shortages in high-density power shelves [6]. The 36-month target reflects $29.00 Non-GAAP EPS
 24.0x exit P/E = $696.00.
Weighted Arithmetic Derivation
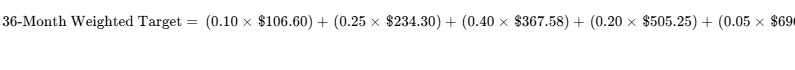
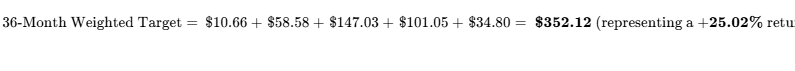
- Hurdle Probability: The probability of meeting the 50.0% mandate hurdle within 36 months is 25.0% (Upside + Aggressive cases). The modeled probability of experiencing a
 cyclical drawdown during the forecast window is 35.0%.
- Reflexivity & Market Liquidity Check: The business is self-funding and does not rely on external capital markets for operating liquidity [2]. However, the stock's valuation multiple remains correlated with broader investor sentiment surrounding AI data center capital spending [11].
Catalyst Calendar
| Estimated Date | Corporate Event / Industry Catalyst | Scenario Relevance & Analytical Validation | Expected Price Move |
|---|---|---|---|
| Nov 3, 2026 | Q3 2026 Earnings Release [1] | Tests $640M revenue and $2.75–$3.25 EPS guidance ranges [1] | ^ |
| Dec 10, 2026 | Thailand Campus Opening | Validates Base/Bull; challenges Bear margin assumptions [21] | ^ |
| Jan 15, 2027 | Semi Industry Capex Outlook | Assesses durability of the multi-year WFE cycle [11] | ^ |
| Feb 10, 2027 | Q4 2026 Earnings & FY27 Guidance | Key data point: Establishes baseline growth targets for 2027 |  |
| Mar 18, 2027 | Cloud Hardware Architecture Summit | Assesses commercial adoption of >100 kW AI power shelves [5] | ^ |
| May 5, 2027 | Q1 2027 Earnings Release | First financial read on Thailand manufacturing cost savings [21] | ^ |
| Jul 14, 2027 | SEMICON West Technology Showcase | Highlights design wins on next-generation GAA tool platforms [28] | ^ |
| Aug 4, 2027 | Q2 2027 Earnings Release | Tests progress toward the FY27 $13.85 EPS estimate |  |
Tactical Execution Layer
| Tactical Trading Parameter | Target Level / Setting | Analytical Derivation & Operational Context |
|---|---|---|
| Best Entry Zone | $245.00 – $258.00 | DCF Intrinsic Support / 200-Day Moving Average Support |
| Add Zone | $258.00 – $268.00 | Technical re-test of moving average support levels |
| Hold Zone | $269.00 – $315.00 | Current technical consolidation channel |
| Trim Zone | $335.00 – $355.00 | Multiple expansion resistance boundary |
| Sell Zone | $365.00+ | Full realization of 36-Month Base Case valuation |
| Hard Stop (Thesis-Break Level) | $212.00 | Structural breakdown below pre-rally support |
| Key Support 1 (Technical) | $264.50 | July 2026 breakout consolidation pivot |
| Key Support 2 (Fundamental) | $238.00 | Historical trough cycle valuation floor |
| Key Resistance 1 | $320.00 | June 2026 local swing high [39] |
| Key Resistance 2 (All-Time High) | $397.44 | 52-week all-time record peak [8] |
| 5-Year Historical Beta | 1.30 | S&P Global Market Intelligence benchmark [7] |
| 3-Year Historical Maximum Drawdown | −44.5% | 2022–2023 cyclical industry correction |
| 30-Day Realized Annual Volatility | 32.4% | Standard deviation of daily log equity returns |
| Current Recommended Action | HOLD / PAUSE | Maintain current exposure; hold on new capital additions |
| Execution Timing Verdict | WAIT FOR PULLBACK | Accumulate in the $258.00–$268.00 support range |
The hard stop level at $212.00 is an operational thesis stop rather than a technical price level. A decline below $212.00 would breach primary post-earnings support and indicate that the margin expansion expected from the Thailand facility migration and AI power shelf shipments is encountering operational friction [6].
Closing Audit
Unverified Figures List
- Hyperscaler Customer Revenue Breakdown: Specific revenue figures for individual cloud hyperscalers within Data Center Computing are not broken out in quarterly 10-Q filings [15]. Full verification requires detailed customer disclosure in annual 10-K filings.
- Itemized Thailand Capital Outlay: The precise split of guided fiscal 2026 CapEx ($170M–$195M) dedicated to the Rayong campus vs. ongoing operational maintenance is derived from earnings call commentary rather than line-item financial disclosures [21].
Self-Audit for Internal Consistency
- Valuation Multiples Reconciled: Forward P/E, EV/EBITDA, and EV/Sales metrics reconcile with multi-year forecast financial statements. The Base Case exit multiple compresses from 25.6x forward earnings in 2026 to 19.5x in 2029, following the multiple-compression requirement.
- Share-Count Roll-Forward: Basic shares (40.05M) roll forward into fully diluted share counts (40.80M in 2026 to 40.85M in 2029) based on projected equity award vesting and share repurchases [15].
- Balance Sheet and Debt Structure: Total cash ($1.40B) and gross debt ($1.38B) reflect the redemption of the 2028 convertible notes and the full issuance of the $1.15B zero-coupon notes due 2031 [7].
Bias Check
The scenario probability distribution is structured as: Stress (10%), Conservative (25%), Base (40%), Thesis/Upside (20%), and Aggressive (5%) [3]. Cumulative downside-to-neutral scenarios total 75.0%, while upside-to-aggressive scenarios total 25.0%. This distribution reflects a measured stance following the stock's 75% trailing 12-month advance and the presence of executive insider selling [8].
Sections Truncated
None. All required sections—including Business Architecture, Unit Economics, Multi-Year Financial Forecasts (Bear/Base/Bull through 2031), Capital Structure Stress Testing, Valuation Models, Risk Governance, Catalyst Calendars, and Tactical Execution Layers—are included in full depth.
Geciteerd werk
- Advanced Energy Industries (AEIS) Earnings Date and Reports 2026, https://www.marketbeat.com/stocks/NASDAQ/AEIS/earnings/
- Advanced Energy Industries, Inc. Stock Price - Perplexity, https://www.perplexity.ai/finance/AEIS/earnings
- unknown_url
- Advanced Energy posts 21% revenue growth to $1.8B - Stock Titan, https://www.stocktitan.net/sec-filings/AEIS/pre-14a-advanced-energy-industries-inc-preliminary-proxy-statement-3873669d69a0.html
- 2 non-crowded stocks that win from Nvidia's dominance, https://www.procapinsights.com/reports/nvidia-earnings-dominance-stock-ideas-wall-street
- AEIS Stock Jumped 88% This Year, Does It Still Have Room to Run, https://www.tikr.com/blog/aeis-stock-advanced-energy-valuation-2031
- Advanced Energy Industries (AEIS) Statistics & Valuation, https://stockanalysis.com/stocks/aeis/statistics/
- Advanced Energy Industries (Nasdaq:AEIS) - Stocks - Simply Wall St, https://simplywall.st/stocks/us/tech/nasdaq-aeis/advanced-energy-industries
- ADVANCED ENERGY INDUSTRIES INC (Form: 8-K, Received, https://content.edgar-online.com/ExternalLink/EDGAR/0001558370-23-018255.html?hash=7f8f84d3508e83c21c6bbdbb130c3c4b0528c71ad00db2b81a0f365cb9e9cf80&dest=aeis-20231102xex10d1_htm
- Advanced Energy Industries, Inc. (AEIS) Leadership & Management, https://simplywall.st/stocks/us/tech/nasdaq-aeis/advanced-energy-industries/management
- Lam Research (LRCX) - Trefis, https://www.trefis.com/data/companies/LRCX
- Advanced Energy Industries (NasdaqGS:AEIS) Stock Valuation, https://simplywall.st/stocks/us/tech/nasdaq-aeis/advanced-energy-industries/valuation
- MKS (MKSI) - Trefis, https://www.trefis.com/data/companies/MKSI
- Advanced Energy Industries Recasts Debt With US$1b Zero, https://simplywall.st/stocks/us/tech/nasdaq-aeis/advanced-energy-industries/news/advanced-energy-industries-recasts-debt-with-us1b-zero-coupo
- ADVANCED ENERGY INDUSTRIES, INC._June 30, 2026 - SEC.gov, https://www.sec.gov/Archives/edgar/data/927003/000092700326000032/aeis-20260630x10q.htm
- AEIS Is Firing on Every Cylinder. My Problem Is the Safety Factor., https://simplywall.st/community/narratives/us/tech/nasdaq-aeis/advanced-energy-industries/ihij1y0s-aeis-is-firing-on-every-cylinder-my-problem-is-the-safety-factor
- aeis-20251231xars.pdf - SEC.gov, https://www.sec.gov/Archives/edgar/data/927003/000110465926035168/aeis-20251231xars.pdf
- Advanced Energy Industries (AEIS) Market Cap & Net Worth, https://stockanalysis.com/stocks/aeis/market-cap/
- Advanced Energy prices $1B 0% convertible notes | AEIS 8-K Filing, https://www.stocktitan.net/sec-filings/AEIS/8-k-advanced-energy-industries-inc-reports-material-event-a09fc20bbb56.html
- Advanced Energy closes $1.15B convertible notes offering, https://www.investing.com/news/company-news/advanced-energy-closes-115b-convertible-notes-offering-93CH-4696791
- Electronic Engineer I @ Advanced Energy | Simplify Jobs, https://simplify.jobs/p/c0df5c48-fda6-47f9-84e2-35b9b6afa3e7/Electronic-Engineer-I
- Advanced Energy Q1 2026 slides: data center revenue doubles, https://www.investing.com/news/company-news/advanced-energy-q1-2026-slides-data-center-revenue-doubles-outlook-raised-93CH-4657626
- Advanced Energy (AEIS) Q3 2024 Earnings Transcript, https://www.fool.com/earnings/call-transcripts/2026/04/22/advanced-energy-aeis-q3-2024-earnings-transcript/
- ADVANCED ENERGY INDUSTRIES INC_December 31, 2024, https://www.sec.gov/Archives/edgar/data/927003/000155837025001038/aeis-20241231x10k.htm
- Advanced Energy Industries, Inc. (AEIS) Stock Price, Quote, News, https://seekingalpha.com/symbol/AEIS
- Advanced Energy to redeem $136.7M convertible notes due 2028, https://www.investing.com/news/company-news/advanced-energy-to-redeem-1367m-convertible-notes-due-2028-93CH-4739179
- ANNUAL REPORT 2025 - Investor Relations, https://investor.mks.com/static-files/69366eb4-123b-4ad9-9cd5-9d79087f77f6
- Structural Themes | The Buildout, https://thebuildout.co/intelligence/themes
- advanced energy industries, inc. - SEC.gov, https://www.sec.gov/Archives/edgar/data/927003/000092700324000003/aeis-20231231x10k.htm
- Advanced Energy posts 21% growth, outlines 2026 votes - Stock Titan, https://www.stocktitan.net/sec-filings/AEIS/def-14a-advanced-energy-industries-inc-definitive-proxy-statement-89be48eb2cb1.html
- Annual Report, https://s21.q4cdn.com/263848619/files/doc_events/2026/07/NXT-2026-Annual-Report-PDF-Final-Color.pdf
- Comerica Declares Dividends and Announces Increase in Share, https://www.stocktitan.net/news/CMA/comerica-declares-dividends-and-announces-increase-in-share-pqvwuoh0cdf5.html
- Advanced Energy Industries Inc. financials - VectorShift, https://vectorshift.ai/research/companies/advanced-energy-industries/financials
- Advanced Energy Industries, Inc. (AEIS) Earnings Call Transcripts, https://seekingalpha.com/symbol/AEIS/earnings/transcripts
- Advanced Energy Industries Inc (AEIS) stock price ... - Finzer, https://finzer.io/en/stocks/xnas.aeis
- Entegris (ENTG) Statistics & Valuation - Stock Analysis, https://stockanalysis.com/stocks/entg/statistics/
- Coherent (COHR) Financial Ratios - Stock Analysis, https://stockanalysis.com/stocks/cohr/financials/ratios/
- Paul Oldham Net Worth - Insider Trades and Bio as of Jul 31, 2026, https://www.benzinga.com/sec/insider-trades/0001421764/Paul-Oldham
- What Drove Advanced Energy's Recent Surge, https://www.kavout.com/market-lens/what-drove-advanced-energy-s-recent-surge