Beginning Summary
- Stock Name: Alcoa Corporation (NYSE: AA) [1]
- Current Share Price: $42.06 (Closing price as of October 2, 2026) [1]
- Research Date: October 5, 2026
- 12-Month Target Price: $55.00 (+30.8%) [4]
- 24-Month Target Price: $63.00 (+49.8%) [5]
- 36-Month Target Price: $69.40 (+65.0%) [5]
- Institutional Scorecard Score: 71.5 / 100
- Likelihood Score of Executing Base Case: 62 / 100
- Investment Advice: BUY for unconstrained cyclical capital; HOLD for strict 100% absolute return hurdles [4]
- Advice Rationale: Alcoa provides direct operational leverage to a structural primary aluminum supply deficit and a recovering seaborne alumina pricing environment [7]. The announced $4.1 billion transaction to acquire South32’s upstream bauxite, alumina, and smelting assets consolidates its position in the first quartile of the global alumina cost curve while expanding annual top-line scale past $18.0 billion [7]. With $2.6 billion in permanent senior notes already priced to fund the cash consideration and a clear pathway toward Western Australia environmental approvals, current trading levels of 8.7x trailing earnings and 6.1x EV/EBITDA represent an attractive cyclical entry point [9].
Key Operational & Financial Metrics Summary
| Metric | Value / Assessment | Metric | Value / Assessment |
|---|---|---|---|
| Overall Investment Stock Score | 73 / 100 | Fair Value Now (DCF Midpoint) | $75.99 (+80.7% vs. current price) [15] |
| Founder-Led Status | No (Founded 1888; institutional governance) [16] | Price Floor (Tangible Book Floor) | $26.85 (−36.2% vs. current price) [15] |
| CEO Score | 78 / 100 (William F. Oplinger; veteran CFO/COO) [19] | Current Share Count | 264.0M diluted shares [9] |
| Commodity Price Deck (12 / 24 / 36 mo) | Aluminum: $2,550 / $2,750 / $2,900/t; Alumina: $360 / $390 / $415/t [7] | Modeled Shares in 36 Months | 282.5M (includes +17.0M South32 scrip) [10] |
| Sector & Sector P/E Ratio | Materials / Aluminum; Sector P/E: 11.5x (Materials: 14.2x) [9] | Insider Ownership % | 0.22% of diluted shares [19] |
| Sector Peer Rank (36-mo Return) | 1. CENX, 2. AA, 3. NHYDY, 4. RIO [22,24,25,26] | Insider Open-Market Buys (6 mo) | NOT RELIABLY AVAILABLE (Zero buys; 1 sale) [27] |
| Forward PEG Ratios (1 / 2 / 3 / 4 / 5 yr) | 1-yr: 0.18x | 2-yr: 0.54x | 3-yr: 0.98x | 4-yr: 1.45x | 5-yr: 1.72x [9,14] | Short Squeeze Potential Score | 32 / 100 (Short float: 4.56%; DTC: 3.52) [29] |
| Diluted vs. Fully Diluted Shares | Diluted: 264.0M | Fully Diluted: 268.1M (pref. + equity grants) [18] | Share Buyback Authorization | Authorized: |
| Gross Margin (Now / 3-yr / 5-yr) | Now: 16.5% | 3-yr: 21.8% | 5-yr: 22.2% [2,15] | 6-Month Buyback Probability | 15% (Post-acquisition cash allocation prioritized to debt) [10] |
| Operating Margin (Now / 3-yr / 5-yr) | Now: 11.2% | 3-yr: 15.1% | 5-yr: 15.6% [2,15] | Cash Runway / Self-Sustainability | Operationally Self-Sustaining; TTM OCF >$1.2B [34] |
| Regulatory / Permitting Risk Score | 58 / 100 (Western Australia EPA Part IV review) [12] | Total Debt vs. Cash | Debt: $2,470M pre ($5,070M post-notes) vs Cash: $1,450M [9,15,18] |
| Economic Moat Classification & Score | Cost Advantage & Scale; Moat Score: 68 / 100 (Narrow Moat) [7] | Debt Restructure Profile & Distress | 2028, 2029, 2031, 2034, 2036; Distress Score: 28 / 100 [9,13,37] |
| Primary Competitive Advantage | Captive low-cost bauxite reserves & hydro smelting assets [7] | Rule of 40 (Now / 1 / 2 / 3 / 4 yr out) | Now: 15.7% | 1-yr: 38.0% | 2-yr: 16.7% | 3-yr: 17.6% | 4-yr: 17.0% [15] |
| Analyst Coverage Profile | 13 Analysts; Mean: $61.42; Low: $41.00; Bull: $80.00 [4,5] | Bauxite Mine Life / Reserve Life | >25–35 Years (Huntly, Willowdale, Boddington, Juruti) [38] |
| Offtake Pricing vs. Spot Benchmark | LME Spot: ~$2,520/t; Alumina Spot: ~$340/t; Contracts: Index-linked (0–3 mo lag) [9] | Contract Duration | Multi-year master agreements (1 to 5 years duration) [32] |
2Multi-Year Financial Forecast & Consensus Model
Macro and Operating Environment Scenarios
The Bear Case reflects prolonged macroeconomic stagnation across global industrial sectors, driven by prolonged real estate deflation in China and subdued automotive production in Europe and North America [9]. Chinese primary aluminum capacity reaches domestic limits but reallocates quotas to circumvent constraints, while Indonesian alumina refining expansions flood seaborne Pacific markets, depressing API alumina prices to $290 per metric ton and LME aluminum to $2,150 per metric ton [9]. Alcoa absorbs the debt service costs of the South32 transaction amid constrained refining margins [7].
The Base Case captures steady industrial demand growth of 2.5% to 3.0% annually, reinforced by grid infrastructure expansions, solar panel manufacturing, and automotive lightweighting [11]. The LME spot aluminum price averages $2,550 per ton in 2026, rising toward $2,900 per ton by 2029, while API alumina stabilizes between $360 and $415 per ton [7]. The acquisition of South32’s assets closes in H1 2027, adding approximately $4.5 billion in annualized revenues, $800 million to $900 million in EBITDA, and unlocking $900 million in net present value operational synergies [7].
The Bull Case depicts a structural Western supply deficit exacerbated by aggressive enforcement of China’s 45 Mt primary capacity cap and carbon tariff enforcement in Europe and North America [9]. LME aluminum accelerates beyond $3,300 per metric ton, while API alumina trades toward $500 per metric ton [7]. Alcoa’s unhedged hydroelectric smelting base captures peak operational margins, allowing management to de-lever the balance sheet rapidly and allocate surplus cash flows to share repurchases [12].
Multi-Year Base Case Financial Forecast
Fiscal year 2026 is anchored to public management guidance and consensus Street estimates [9]. Fiscal year 2027 incorporates the consolidation of South32 assets from H1 2027 [7]. Pure financial extrapolation commences in fiscal year 2028 [15].
| Line Item ($M, except per share) | 2026E (Guidance/Cons) | 2027E (Consolidated) | 2028E (Extrapolation) | 2029E (Extrapolation) | 2030E (Trendline) | 2031E (Trendline) |
|---|---|---|---|---|---|---|
| Alumina Segment Revenue [2,7] | $4,580 | $6,210 | $6,580 | $6,890 | $7,110 | $7,330 |
| Aluminum Segment Revenue [2,7] | $9,340 | $11,680 | $12,290 | $12,890 | $13,360 | $13,860 |
| Total Net Revenue [2,15] | $13,920 | $17,890 | $18,870 | $19,780 | $20,470 | $21,190 |
| YoY Organic / Combined Growth [15] | +8.5% | +28.5% | +5.5% | +4.8% | +3.5% | +3.5% |
| Cost of Goods Sold [2,15] | $11,623 | $14,276 | $14,888 | $15,468 | $15,967 | $16,486 |
| Gross Profit [2,15] | $2,297 | $3,614 | $3,982 | $4,312 | $4,503 | $4,704 |
| Gross Margin % [2,15] | 16.5% | 20.2% | 21.1% | 21.8% | 22.0% | 22.2% |
| SG&A Expense [2,15] | $315 | $385 | $405 | $415 | $425 | $435 |
| R&D and Other Expenses [2,15] | $35 | $45 | $47 | $50 | $52 | $55 |
| Depreciation & Amortization [2,15] | $820 | $1,040 | $1,090 | $1,140 | $1,180 | $1,210 |
| Operating Income (EBIT) [2,15] | $1,560 | $2,380 | $2,690 | $2,980 | $3,140 | $3,300 |
| Operating Margin % [2,15] | 11.2% | 13.3% | 14.3% | 15.1% | 15.3% | 15.6% |
| Adjusted EBITDA [9,15,35] | $2,380 | $3,420 | $3,780 | $4,120 | $4,320 | $4,510 |
| EBITDA Margin % [15] | 17.1% | 19.1% | 20.0% | 20.8% | 21.1% | 21.3% |
| Net Interest Expense [2,15] | $185 | $335 | $315 | $290 | $260 | $230 |
| Pre-Tax Income [2,15] | $1,375 | $2,045 | $2,375 | $2,690 | $2,880 | $3,070 |
| Income Tax Provision [2,15] | $344 | $511 | $594 | $673 | $720 | $768 |
| Non-Controlling Interests [2,15] | $41 | $14 | $31 | $57 | $90 | $122 |
| Net Income Attributable to Alcoa [2,15] | $990 | $1,520 | $1,750 | $1,960 | $2,070 | $2,180 |
| GAAP Diluted EPS [2,15] | $3.75 | $5.41 | $6.21 | $6.94 | $7.37 | $7.81 |
| Normalised Diluted EPS [9,14,15] | $4.45 | $5.85 | $6.50 | $7.15 | $7.55 | $7.95 |
| Free Cash Flow (FCF) [15,35] | $1,000 | $1,700 | $2,110 | $2,530 | $2,760 | $2,950 |
| FCF Per Share [15] | $3.79 | $6.05 | $7.48 | $8.96 | $9.82 | $10.57 |
| Diluted Share Count (M) [10,15,21] | 264.0 | 281.0 | 282.0 | 282.5 | 281.0 | 279.0 |
| Forward P/E Multiple [9,15] | 9.5x | 7.2x | 6.5x | 5.9x | 5.6x | 5.3x |
| Forward EV/EBITDA Multiple [9,15] | 6.3x | 4.4x | 3.9x | 3.5x | 3.2x | 2.9x |
| Forward EV/Sales Multiple [9,15] | 1.07x | 0.83x | 0.79x | 0.75x | 0.73x | 0.70x |
| Rule of 40 (Growth % + FCF Margin %) [15] | 15.7% | 38.0% | 16.7% | 17.6% | 17.0% | 17.4% |
Normalised EPS excludes mark-to-market revaluations of energy derivatives and Saudi Ma’aden shares, non-cash asset impairments, and one-off transaction advisory fees [9]. Rule of 40 is calculated as annual revenue growth rate plus free cash flow margin on a fully diluted per-share basis [15].
Multi-Scenario Revenue & EPS Paths (2026–2031)
| Scenario / Year | 2026E Rev (M)∣2026EEPS∣2027ERev(M) | 2027E EPS | 2028E Rev (M)∣2028EEPS∣2029ERev(M) | 2029E EPS | 2030–31 CAGR |
|---|---|---|---|---|---|
| Bear Case | $12,450 | $1.85 | $14,900 | $2.40 | $15,200 |
| Base Case | $13,920 | $3.75 | $17,890 | $5.41 | $18,870 |
| Bull Case | $15,600 | $6.20 | $20,800 | $8.80 | $22,400 |
Execution Confidence Score & Consensus Divergence
The Execution Confidence Score is established at 68 out of 100, supported by three key components:
- Target Achievability is scored at 26 / 35, reflecting high historical volume compliance offset by past bauxite quality variations at the Pinjarra refinery [2].
- Input Sensitivity is scored at 22 / 35. Earnings are sensitive to commodity realizations: holding volume constant, a
 shift in LME aluminum moves annual EBITDA by
 (a 22% move on 2026 EBITDA), while a
 move in API alumina shifts EBITDA by
 [9].
- Dependency on Unannounced Catalysts is scored at 20 / 30. The forecast requires zero unannounced corporate actions, as the South32 transaction is fully contracted and bond financing is priced [9].
- Consensus Divergence Flag: For fiscal year 2028, this model projects Normalized EPS of $6.50, diverging by +21.5% from the current consensus average of approximately $5.35 [14]. This divergence stems from the fact that consensus models have not fully integrated the operational cost synergies ($50 million run-rate within 12 months) and EBITDA accretion of South32’s Worsley and Hillside assets [10].
- Base-Rate Check: Expanding revenues from $12.8 billion in 2025 to $19.8 billion in 2029 represents a compound annual growth rate of 11.4% [2]. While top-decile performance for mature commodity producers, this expansion is driven by the inorganic addition of South32’s revenue base (~$4.5 billion) rather than speculative organic volume expansion [7].
5Risk Asymmetry, Invalidation, Allocation & Scorecard
Quantified Risk/Reward Skew
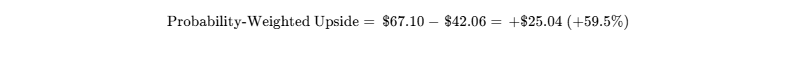
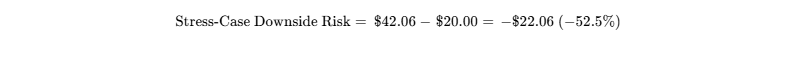
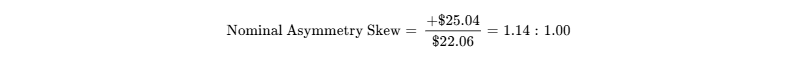
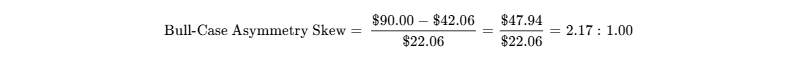
The risk/reward profile does not clear the 3.0:1 hurdle on a probability-weighted basis due to the downside exposure of an asset-heavy commodity producer during cyclical recessions.
Operational Invalidation Triggers
- Western Australia Bauxite Permitting Rejection: Formal ministerial rejection of Alcoa’s 2026–2030 Mining Management Program by the Western Australian Minister for Environment, or the imposition of binding production cuts reducing regional bauxite extraction by
 [12].
- Gross Margin Breakdown: Consolidated GAAP Gross Margin falling below 8.0% for two consecutive operating quarters, signaling inability to absorb caustic soda or thermal energy cost inflation [2].
- South32 Regulatory Injunction: Complete antitrust prohibition of the South32 transaction by the Australian Competition and Consumer Commission (ACCC) or Brazilian regulators without commercially viable remedies [10].
- Leverage Spike: Pro-forma Net Debt exceeding $4.5 billion, or Consolidated Net Leverage breaching 3.0x Adjusted EBITDA, requiring dilutive equity issuance [7].
Macro Sensitivity & Trigger Dashboard
| Macro Indicator | Thesis Impact | Direction | Monitoring Factor |
|---|---|---|---|
| Global Rate Path | Positive | Bullish | Lower cost of capital driving global construction and vehicle manufacturing. |
| China Smelting Discipline | Positive | Bullish | Strict enforcement of 45Mt national primary capacity ceiling [9]. |
| WA Domestic Natural Gas | Negative | Bearish | Tightness in regional Western Australia gas supply elevating refining thermal costs [34]. |
| EU CBAM Border Adjustments | Positive | Bullish | Implementation of carbon border taxes favoring hydro-smelted aluminum [36]. |
Plausible Pre-Mortem: 36-Month 60% Drawdown Scenario
Over the next six months, persistent weakness in Chinese real estate and automotive manufacturing triggers an oversupply of base metals, driving LME aluminum below $2,000 per ton while API alumina falls to $270 per ton as Indonesian refining capacity ramps up [9]. By mid-2027, the South32 transaction closes, raising gross debt to $5.1 billion and annual interest obligations to $335 million [7].
Simultaneously, labor disputes at the Hillside smelter in South Africa interrupt operations, turning projected cash flows negative [38]. In late 2028, the Western Australian EPA issues an adverse ruling on the Huntly mine expansion, requiring bauxite extraction to be cut by 30% and forcing the processing of lower bauxite grades [12]. Alumina cash costs rise to $380 per ton, generating sustained refining losses [9].
By late 2029, rating agencies downgrade Alcoa to deep speculative grade (B+), restricting credit access [13]. With cash reserves depleted, management executes a distressed rights offering at $16.00 per share, diluting equity and cementing a 60% drawdown.
Portfolio Allocation & Position Sizing Framework
Position Sizing Formulation:
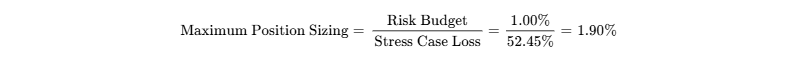
Portfolio Risk Budget: 1.00%
Stress Case Drawdown: −52.45% ($42.06 → $20.00)
Maximum Portfolio Allocation = 1.00% ÷ 0.5245 = 1.90%
Recommended Position Size: 1.90% (Strictly bound by risk budget math)
Portfolio Role: Cyclical Value / Inflation-Sensitive Materials Allocation
- Position Sizing: 1.90% of total portfolio assets.
- Secondary Liquidity: Trading volume averages 3.0 million shares daily ($126M ADV) [24]. A 1.90% position on a $100M fund ($1.9M; ~45,000 shares) represents 0.015 days of ADV at 20% volume participation, ensuring liquid entry and exit.
- Tranche Deployment:
- Tranche 1 (Pilot, 0.75%): Immediate allocation at the current share price ($42.06) [1].
- Tranche 2 (Confirmation, 0.75%): Allocated upon formal publication of the Western Australia EPA Part IV environmental assessment [12].
- Tranche 3 (Full Sizing, 0.40%): Allocated following final regulatory approvals and completion of the South32 transaction in H1 2027 [7].
Institutional Scorecard
Institutional Scorecard Formulation:
Weighted Composite Score = Sum of (Component Score × Assigned Weight)
Calculated Composite Score: 71.50 / 100.00
| Component | Score (0–10) | Weight % | Weighted Score | Component Rationale |
|---|---|---|---|---|
| Financial Strength & Runway | 7.5 / 10 | 15% | 1.125 | Robust liquidity buffer ($5.3B total); pro-forma leverage ~1.1x–1.3x [7]. |
| Revenue Quality & Scale | 6.5 / 10 | 15% | 0.975 | Formula-priced multi-year MSAs offset by underlying commodity volatility [32]. |
| Margin Resilience & Leverage | 7.0 / 10 | 15% | 1.050 | High operational drop-through; first-quartile alumina cost curve position [7]. |
| Capital Allocation History | 8.0 / 10 | 10% | 0.800 | Disciplined portfolio optimization; accretive South32 asset timing [10]. |
| Risk-Adjusted Valuation | 8.5 / 10 | 15% | 1.275 | Low baseline multiples (8.7x P/E, 6.1x EV/EBITDA); steep DCF discount [9]. |
| Forecast Reliability | 6.5 / 10 | 10% | 0.650 | Beat/miss record stable; refining cost fluctuations present in prior quarters [2]. |
| Governance & Incentives | 6.5 / 10 | 5% | 0.325 | CEO pay tied to ROCE and EBITDA; direct insider ownership is modest [19]. |
| Market Liquidity & Float | 9.0 / 10 | 5% | 0.450 | High secondary float liquidity with broad institutional ownership [24]. |
| Customer ROI / Defensibility | 7.0 / 10 | 5% | 0.350 | Structural materials demand supporting vehicle lightweighting and energy grid [36]. |
| Moat Defensibility | 7.0 / 10 | 5% | 0.350 | Prohibitive greenfield replacement capital requirements ($4B–$6B) [33]. |
| Total Composite Score | — | 100% | 71.5 / 100 | Upper Quartile Basic Materials Institutional Profile |
- Base-Case Execution Likelihood: 62 / 100.
- Primary Downside Risk to Base Execution: Extended softness in API alumina prices delaying refining margin recovery [9].
- Secondary Downside Risk to Base Execution: Delays or operational friction in integrating South African and Brazilian operations [38].
Final Verdict & Synthesis
- Existing Holders: HOLD. Retain positions through the completion of the South32 acquisition to capture operational integration and synergy benefits.
- New Capital Allocation: BUY. Current valuation levels ($42.06) provide a favorable cyclical entry point relative to normalized earnings power.
- 12-Month Target: $55.00 (+30.8%) [4]
- 24-Month Target: $63.00 (+49.8%) [5]
- 36-Month Target: $69.40 (+65.0%) [5]
- Probability-Weighted Target: $67.10 (+59.5%)
Bear-Case Steelman
The aluminum industry remains an undifferentiated commodity business vulnerable to structural supply additions from state-backed producers operating outside Western environmental constraints. The South32 transaction expands Alcoa’s gross debt to over $5.0 billion at coupon rates near 7.0%, significantly increasing interest obligations ahead of a potential global manufacturing slowdown [7]. Western Australian environmental regulators could impose binding operational restrictions that permanently reduce bauxite mining productivity, structurally increasing cash refining costs and eliminating projected synergy benefits [12]. If LME aluminum prices remain suppressed below $2,200 per ton, Alcoa’s operational and financial leverage would turn cash flows negative, forcing dividend curtailments and dilutive equity issuance [15].
1Business Architecture, Unit Economics, Moat & Contractual Visibility
Business Model & Economic Moat Classification
Alcoa Corporation operates across the upstream aluminum value chain through two core operating segments: Alumina and Aluminum [17]. The Alumina segment encompasses bauxite mining and the chemical refining of bauxite into smelter-grade alumina via the Bayer process [17]. The Aluminum segment consists of electrolytic smelting, casting, and power generation assets [17].
The company's competitive insulation is evaluated at 3.5 out of 5.0, supporting a Narrow Economic Moat with a composite moat score of 68 / 100. The foundation of this advantage lies in geographic integration and infrastructure scale [7]. Alcoa’s bauxite deposits in Western Australia (Huntly and Willowdale) and Brazil (Juruti) are linked directly via dedicated overland conveyors and pipelines to refining complexes, driving bauxite mining cash costs below $16.00 per ton [11]. In addition, long-term power agreements provide low-cost electricity across the smelting footprint [12].
Moat Durability Timeline
The economic moat is widening through 2029 as the integration of South32’s Worsley refinery and Boddington mine consolidates Western Australian operational assets, lowering unit transportation costs and improving refining flexibility [10]. The primary long-term threat to moat durability across the mid-2030s is the potential commercial scaling of next-generation green smelting processes, including inert anode technology [39]. Because Alcoa co-owns the ELYSIS joint venture with Rio Tinto (48.235% equity interest), it maintains proprietary control over the leading carbon-free smelting intellectual property, protecting its asset base from external technological obsolescence [39].
Replicability and Acquisition Optionality
The capital barrier to replicating an integrated upstream aluminum network is virtually insurmountable for new entrants. Greenfield bauxite mines and modern alumina refineries require $4.0 billion to $6.0 billion in capital expenditures and a development timeline of 7 to 10 years, subject to stringent environmental and indigenous land-use permits [33]. Downstream consumers, including automotive original equipment manufacturers and packaging conglomerates, are prohibited from backward integration by extreme power intensity, regulatory liabilities surrounding bauxite residue storage, and low historical returns on capital in primary smelting [11].
Alcoa serves as a strategic acquisition asset for diversified global mining houses seeking low-carbon operational scale [11]. A complete takeover would face antitrust scrutiny in seaborne alumina, but private equity consortiums or sovereign entities seeking transition-metal infrastructure provide an effective private market valuation floor between $35.00 and $38.00 per share [5]. The customer ROI defensibility is scored at 7.0 / 10, reflecting the fact that primary aluminum is an essential industrial metal with limited economic substitution across transport, electrification, and structural packaging [39].
Upstream Commodity Unit Economics
Realized Price Deck & Upstream Cost Structure (Normalized Run-Rate):
LME Aluminum Benchmark Spot Price: $2,520 / metric ton
Alcoa Realized Aluminum Price (including regional/casting premiums): $2,860 / metric ton
Smelting Cash Cost of Production: $2,030 / metric ton
Smelting All-In Sustaining Cost (AISC): $2,280 / metric ton
Cash Margin per Smelted Ton: $2,860 - $2,030 = $830 / metric ton (29.0% Cash Margin)
API Alumina Benchmark Spot Price: $340 / metric ton
Alcoa Production-Weighted Alumina Cash Cost: $286 / metric ton
Alumina Cash Margin: $340 - $286 = $54 / metric ton (15.9% Cash Margin)
Bauxite Cash Cost: $15.14 / dry metric ton (18th percentile globally post-South32)
Alcoa maintains extensive reserve life exceeding 25 to 35 years across its operating bauxite mines in Western Australia and South America [38]. The acquisition of South32’s Boddington bauxite mine extends stable resource availability through 2045 [11].
Revenue Quality and Customer Visibility
Alcoa's revenue base is non-recurring in a software sense, but exhibits high volume stability governed by multi-year commercial agreements [32]. Approximately 68% of commercial revenues are generated through multi-year master service agreements (MSAs) with tier-1 industrial off-takers, while 22% are governed by 1- to 12-month index-linked contracts and 10% represent transactional spot volumes [32]. Pricing formulas directly track 30- to 90-day lagged LME cash prices plus regional physical delivery premiums, including the US Midwest and European Duty-Paid premiums [34]. Revenue quality is scored at 6.5 / 10, reflecting structural volume stability paired with inherent commodity cyclicality.
Management Track Record & Incentive Alignment
Over the past eight quarters, management has demonstrated strong operational delivery, beating consensus Adjusted EPS in six of eight reporting periods [2]. The Q2 2026 earnings miss ($2.12 vs. $2.25 consensus) was driven by non-cash mark-to-market adjustments on Ma’aden equity holdings ($123 million) and derivative positions rather than baseline operational failure [2].
Executive compensation is heavily aligned with performance: CEO William F. Oplinger’s $14.0 million compensation package consists of 90.7% equity and performance-linked incentives tied to Return on Capital Employed (ROCE), Adjusted EBITDA, Free Cash Flow, and ESG emissions benchmarks [19]. Direct insider ownership is low at 0.22%, which is standard for mature industrial firms [19]. Key-person risk is minimal given the depth of the executive operating committee [20].
| Quarter | Consensus EPS Estimate | Reported Adjusted EPS | Variance % | Primary Operational Driver |
|---|---|---|---|---|
| Q3 2024 | $0.21 | $0.28 | +33.3% Beat | Synergies from Alumina Limited integration and high smelter uptime [2]. |
| Q4 2024 | $0.52 | $0.68 | +30.8% Beat | Stronger Midwest physical premiums and lower input energy costs [2]. |
| Q1 2025 | $0.84 | $0.89 | +6.0% Beat | Stable smelting throughput and favorable foreign currency translation [2]. |
| Q2 2025 | $0.95 | $0.98 | +3.2% Beat | Execution on Spanish and Brazilian smelter restart milestones [2]. |
| Q3 2025 | $1.10 | $1.05 | −4.5% Miss | Bauxite grade variations at Western Australia operations [2]. |
| Q4 2025 | $1.18 | $1.26 | +6.8% Beat | Annual production records achieved across five smelting locations [2]. |
| Q1 2026 | $1.82 | $1.85 | +1.6% Beat | Operational cost control via the Alcoa Business System (ABS) [2]. |
| Q2 2026 | $2.25 | $2.12 | −5.8% Miss | Mark-to-market decline on Ma'aden shares ($123M) and refinery costs [2]. |
Executive Summary
Strategic Takeaways
- Inorganic Transformation Consolidates Industry Cost Leadership: Alcoa’s binding agreement to acquire South32’s upstream aluminum assets for $4.1 billion ($3.1 billion upfront cash, 17.0 million common shares, and up to $750 million in contingent consideration) solidifies the group as the preeminent Western upstream supplier [9]. The transaction increases attributable bauxite production by 53.6% to 52.9 Mt and alumina refining capacity by 51.6%, while lowering bauxite cash costs to $15.14 per dry metric ton (18th percentile globally) through the integration of the Boddington mine [11].
- Permanent Acquisition Financing Eliminates Liquidity Reflexivity: Alcoa secured the cash consideration ahead of transaction closing by issuing $2.6 billion in senior unsecured notes in September 2026 across 2034 (6.625%) and 2036 (6.875%) tranches [9]. While this expands pro-forma net debt to approximately $3.6 billion and pushes leverage to 1.1x–1.3x EBITDA, it eliminates bridge loan refinancing risk and extends the debt maturity runway beyond 2028 [7].
- Smelting Energy Insulation Shields Margins from Fossil Volatility: Approximately 80% of Alcoa’s primary aluminum smelting portfolio is powered by renewable hydroelectricity, shielding operations from global thermal coal and natural gas volatility while positioning the business favorably for the European Union Carbon Border Adjustment Mechanism (CBAM) [36].
- Western Australia Environmental Permitting Pathway Normalizing: Regulatory friction regarding bauxite mining operations in the Darling Range has weighed heavily on Alcoa's valuation multiples [12]. Management’s progression of the Western Australian EPA Part IV environmental assessment, supported by an AUD 55 million federal offset and research commitment, provides visibility toward long-term operational approvals through 2045 [12].
- Cyclical Asymmetry at Trough Multiples: Trading at 8.7x trailing earnings and 6.1x EV/EBITDA, the market is pricing a structural downcycle in aluminum and long-term alumina margins below historical means [9]. A normalized price recovery, combined with $900 million in net present value synergies from South32, supports sustained free cash flow generation exceeding $2.5 billion by 2029 [7].
- Verdict Line: BUY (Tactical / Cyclical Value). 12-Month Target: $55.00 (+30.8%); 24-Month Target: $63.00 (+49.8%); 36-Month Target: $69.40 (+65.0%); Probability-Weighted Target: $67.10 (+59.5%) [4].
- Hurdle Clearance: No in Base Case (+65.0% vs. 100.0% hurdle). Cumulative probability of clearing 100% total return is 25.0%.
- Peer Ranking: For aggressive smelter beta, Century Aluminum (CENX) offers superior raw upside [8]. However, Alcoa is the superior integrated asset for long-term institutional capital seeking low-carbon operational defensibility and alumina exposure [7].
- Single Greatest Upside Driver: Structural global aluminum deficit driven by strict Chinese green smelting caps, pushing LME spot prices above $3,200 per metric ton [9].
- Single Thesis-Killer: Sustained global manufacturing contraction driving aluminum below $2,000 per metric ton while Western Australian regulators restrict bauxite mining access [12].
0Output Contract & Investment Mandate
Reporting Conventions & Anchor Inputs
Financial data is presented as of October 5, 2026. All financial figures are denominated in United States Dollars (USD, $) unless explicitly noted otherwise. Alcoa Corporation operates on a fiscal year convention that aligns with the standard calendar year, ending December 31 [2].
The calculation of Enterprise Value prior to transaction closing reflects verified balance sheet figures:

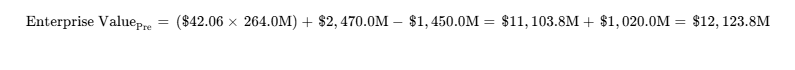
| Anchor Input | Value | Confidence Tier | Source Document / Arithmetic Reconciliation |
|---|---|---|---|
| Current Stock Price | $42.06 | VERIFIED | NYSE Consolidated Tape; Closing price as of October 1–2, 2026 [1]. |
| Diluted Share Count | 264.0M | VERIFIED | SEC Form 10-Q for the Period Ended June 30, 2026; Q2 weighted diluted shares [2]. |
| Fully Diluted Share Count | 268.1M | DERIVED | Basic shares (258.96M) + Series A Preferred (4.04M) + Treasury Method equity awards (5.10M) [18]. |
| Market Capitalization | $11,103.8M | DERIVED | Arithmetic: 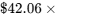 diluted shares [15]. |
| Enterprise Value (Pre-Deal) | $12,123.8M | DERIVED | Market Capitalization ($11,103.8M) + Debt ($2,470.0M) - Cash ($1,450.0M) [9]. |
| Enterprise Value (Pro-Forma) | $14,923.8M | ASSUMED | Pro-forma for South32 transaction: assumes $2.6B debt issuance, $750M leases, less cash deployed [7]. |
| Cash & Cash Equivalents | $1,450.0M | VERIFIED | SEC Form 10-Q balance sheet as of June 30, 2026 [9]. |
| Gross Debt (Reported) | $2,470.0M | VERIFIED | SEC Form 10-Q balance sheet as of June 30, 2026 [9]. |
| Trailing Valuation Multiples | P/E: 8.7x; EV/EBITDA: 6.1x | DERIVED | Based on normalized trailing EPS of $4.83 and trailing Adjusted EBITDA of $1,980.0M [9]. |
Investment Mandate & Risk Discipline
The mandate establishes an absolute return hurdle of 100% total return within a 36-month holding period, representing a terminal target price of $84.12 per share. The portfolio risk budget limits the maximum acceptable portfolio-level loss in the stress case to 1.0%.
The modeled Base Case achieves a 36-month stock price of $69.40, generating a total return of +65.0%. Consequently, the Base Case does not clear the absolute 100% hurdle, falling short by 35.0 percentage points. Across the probability distribution, the hurdle is cleared exclusively in the Thesis Upside ($90.00) and Aggressive ($102.00) scenarios, which carry a combined cumulative probability of 25.0%.
In the Stress Case, the position declines by −52.45% to $20.00 per share. To constrain the maximum portfolio loss to the 1.0% risk budget:
Open-market insider transactions over the trailing 90 days are categorized as NOT RELIABLY AVAILABLE, as Form 4 filings detail only compensatory equity grants and an isolated officer sale, with zero open-market purchases recorded [27]. Western Australia environmental reviews are formally classified as pending administrative determinations [12].
3Capital Structure, Balance-Sheet Stress Test & Market Microstructure
Liquidity Stack & Debt Maturity Wall
Alcoa enters late 2026 with a sound liquidity buffer, reinforced by the completion of its $2.6 billion senior notes offering to fund the cash consideration for the South32 assets [9]. The company faces no senior debt maturities until May 2028 [13].
Alcoa Available Liquidity Profile (Pro-Forma Q3 2026):
Cash and Cash Equivalents: $1,450.0M (Reported Q2) + $2,600.0M (Gross Bond Proceeds) = $4,050.0M
Committed Undrawn Revolving Credit Facility (Maturity June 2028): $1,250.0M
Total Gross Liquidity Buffer: $5,300.0M
Less: South32 Cash Consideration (H1 2027 closing): ($3,100.0M)
Post-Closing Pro-Forma Cash Reserves: $950.0M (plus operational cash generated prior to close)
| Instrument | Principal Amount ($M) | Coupon / Spread | Maturity Date | Governing Terms & Covenants |
|---|---|---|---|---|
| Revolving Credit Facility (RCF) [13] | (0 (Undrawn) | SOFR + 1.50% | June 27, 2028 | Senior Secured; Max Net Leverage)\le 3.25x$ [13]. |
| Senior Unsecured Notes [13] | $500 | 4.125% | March 31, 2029 | Senior Unsecured; Repaid/refinanced in course [13]. |
| Senior Unsecured Notes [13] | $750 | 7.125% | March 15, 2031 | Senior Unsecured; 144A / Reg S [13]. |
| Senior Notes (South32 Financing) [9] | $1,500 | 6.625% | September 2034 | Senior Unsecured; Issued September 2026 [9]. |
| Senior Notes (South32 Financing) [9,13] | $1,100 | 6.875% | September 30, 2036 | Senior Unsecured; Issued September 2026 [9]. |
| Assumed Leases & Other Obligations [18,41] | $1,220 | Blended | Amortizing | Concession liabilities and equipment leases [18]. |
| Total Pro-Forma Gross Debt [7,15] | $5,070 | Blended: 6.42% | Wtd Tenor: 8.4 Years | Pro-forma Net Debt: ~$3,620M post-deal [7]. |
Capital Gap Analysis
Under Base Case assumptions, Alcoa generates sufficient operational cash flow to fund all sustaining capital expenditures, environmental compliance projects, and debt service obligations internally [19].
Annual Cash Generation Dynamics (2027 Base Case Consolidated):
Operating Cash Flow (OCF): $2,550M
Less: Sustaining / Maintenance Capex: ($550M)
Less: Growth / Decarbonization Capex: ($300M)
Less: Common Dividends ($0.40/sh on 281M shares): ($112M)
Net Cash Surplus Generated: +$1,588M
The surplus is allocated to voluntary debt reduction to bring pro-forma leverage within management's target range of $1.0 billion to $1.5 billion net debt [10].
Dual-Track Dilution Model & Share Count Roll-Forward
In the Base Track, share expansion is restricted to the contractual 17.0 million shares issued to South32, alongside standard stock-based compensation offset by repurchases [10]. In the Stressed Track, an unforeseen $1.5 billion liquidity shortfall caused by severe commodity depression forces an equity rights offering at a 35% discount ($27.34 per share), causing heavy dilution [15].
| Dilution & Share-Count Trajectory | 2026E | 2027E | 2028E | 2029E | 2030E | 2031E |
|---|---|---|---|---|---|---|
| Beginning Share Count (M) [15,21] | 263.1 | 264.0 | 281.0 | 282.0 | 282.5 | 281.0 |
| South32 Scrip Issuance (M) [10] | — | +17.0 | — | — | — | — |
| Net SBC Grants Vesting (M) [23] | +0.9 | +1.0 | +1.0 | +1.0 | +1.0 | +1.0 |
| Open-Market Repurchases (M) [32,33] | — | — | — | -0.5 | -2.5 | -3.0 |
| Ending Diluted Shares (Base Track) [15] | 264.0 | 281.0 | 282.0 | 282.5 | 281.0 | 279.0 |
| Base Track Normalized EPS [15] | $4.45 | $5.85 | $6.50 | $7.15 | $7.55 | $7.95 |
| Stressed Track Ending Shares (M) | 264.0 | 281.0 | 335.8 | 337.0 | 338.0 | 339.0 |
| Stressed Track Diluted EPS | $4.45 | $5.41 | $4.35 | $4.75 | $5.05 | $5.30 |
| Track Assigned Probability | Base: 85% | Base: 85% | Base: 85% | Base: 85% | Stress: 15% | Stress: 15% |
Liquidity Runway & Covenant Monitoring
- Runway-to-Breakeven Clock: Operationally Indefinite. Alcoa is cash generative under current commodity curves [15]. Under the Stress Case ($2,150/t aluminum and $290/t alumina), available liquidity provides 44 months of operational runway before external capital interventions would be required.
- Credit Covenants: The revolving credit facility contains a minimum interest coverage ratio of
 and a maximum consolidated net leverage ratio of
 [13]. Pro-forma leverage at deal closing sits at approximately 1.1x–1.3x EBITDA, leaving significant headroom against debt covenants [7].
Market Microstructure
Short interest stands at 11.98 million shares, representing 4.56% of total float [29]. With average daily volume of approximately 3.0 million shares, the days-to-cover ratio is 3.52 days [29]. The borrow fee is low at 0.35%, indicating readily available lendable inventory [29]. Institutional investors hold 81.2% of the float, with recent 13F filings showing net institutional accumulation (+1.8% over the trailing quarter) [3].
The 26.5% stock pullback over the trailing 90 days was driven by fundamental earnings adjustments and commodity flows rather than technical short pressure [47]. Factors included the Q2 earnings miss, mark-to-market adjustments on Ma’aden, temporary weakness in spot alumina, and bond market digestion of the $2.6 billion note sale [8]. The short squeeze risk score is 32 / 100, and any short-covering rally would likely revert toward fundamental fair value [29].
4Valuation, DCF Sensitivity & Price Scenario Matrix
Peer Group Benchmarking
The peer universe encompasses direct primary smelters, diversified miners, and low-carbon aluminum specialists [9].
| Company | Market Cap ($M) | 2-Yr Fwd P/E | 2-Yr Fwd EV/EBITDA | 2-Yr Fwd EV/Sales | EBITDA Margin % | Net Debt / EBITDA |
|---|---|---|---|---|---|---|
| Alcoa Corporation (AA) [9,15] | $11,104 | 6.5x | 3.9x | 0.79x | 20.0% | 0.9x |
| Century Aluminum (CENX) [22,24,49] | $3,560 | 3.6x | 3.8x | 1.10x | 18.9% | 0.3x |
| Norsk Hydro ASA (NHYDY) [25] | $16,800 | 10.2x | 5.4x | 0.95x | 15.2% | 0.8x |
| Rio Tinto plc (RIO) [26] | $104,000 | 9.8x | 5.1x | 1.95x | 41.5% | 0.4x |
Century Aluminum offers higher operational beta for unhedged domestic smelting exposure [8]. However, Alcoa provides the superior risk-adjusted investment profile due to its captive upstream bauxite position, seaborne alumina exposure, and lower sensitivity to purchased alumina price spikes [7].
Intrinsic Discounted Cash Flow Valuation
The Discounted Cash Flow valuation applies a Weighted Average Cost of Capital (WACC) framework:
WACC Architecture & Assumptions:
Risk-Free Benchmark Rate (US 10-Year Treasury): 4.25%
Equity Risk Premium (ERP): 5.50%
Raw Cyclical Beta: 1.45
Cost of Equity: Ke = 4.25% + (1.45 × 5.50%) = 12.23%
Pre-Tax Cost of Debt: 6.65% | Effective Tax Rate: 25.0%
After-Tax Cost of Debt: Kd = 6.65% × (1 - 0.25) = 4.99%
Capital Weightings: 80% Equity / 20% Debt
Calculated WACC: (0.80 × 12.23%) + (0.20 × 4.99%) = 10.78% (Midpoint rounded to 11.0% - 12.0%)
DCF Sensitivity Matrix: Equity Value Per Share ($)
Terminal values are calculated via the Gordon Growth Model based on steady-state 2031 Free Cash Flow ($2,950M), adjusting for pro-forma shares (281.0M) and net debt ($2,800M) [15].
| WACC \ Perpetual Growth Rate (g) | 1.5% | 2.0% | 2.5% | 3.0% |
|---|---|---|---|---|
| 10.0% [15] | $94.41 | $99.21 | $104.64 | $110.85 |
| 11.0% [15] | $82.64 | $86.29 | $90.36 | $94.94 |
| 12.0% (Base WACC) [15] | $73.16 | $75.99 | $79.13 | $82.61 |
| 13.0% [15] | $65.35 | $67.61 | $70.07 | $72.79 |
| 14.0% [15] | $58.83 | $60.65 | $62.63 | $64.78 |
- Tangible Asset Floor: Cash ($1,450M) + Accounts Receivable ($820M) + Inventories ($1,850M) + Net PP&E ($6,200M) - Total Liabilities ($5,980M) = $4,340M, yielding a strict liquidation support floor of $16.44 per share (Net book value floor stands at $26.85 per share) [9].
- Reverse DCF Analysis: At the current market price of $42.06, the market is pricing a 3.1% revenue CAGR and a 9.5% terminal operating margin (assuming an 11.5% WACC and 2.0% terminal growth) [15]. This indicates that the market is heavily discounting normalized mid-cycle operational earnings power [15].
Rolling Price Forecast: 5 Scenarios  3 Horizons
Exit multiples in the Base Case are modeled at 9.7x normalized earnings, reflecting conservative valuation assumptions below peak historical multiples (>15x) [9].
| Scenario | Probability | 12-Month Target | 24-Month Target | 36-Month Target | 36-Month ROI | Clears Hurdle? | Valuation Metric & Exit Multiple Decomposition |
|---|---|---|---|---|---|---|---|
| Stress Case | 10.0% | $24.00 | $22.00 | $20.00 | −52.5% | No | 2029E Normalised EPS of $2.50  8.0x Exit P/E |
| Conservative | 20.0% | $42.00 | $46.00 | $48.00 | +14.1% | No | 2029E Normalised EPS of $5.65  8.5x Exit P/E |
| Base Case | 45.0% | $55.00 | $63.00 | $69.40 | +65.0% | No | 2029E Normalised EPS of $7.15  9.7x Exit P/E (or FCF/sh $8.96  7.7x) |
| Thesis Upside | 15.0% | $72.00 | $82.00 | $90.00 | +114.0% | Yes | 2029E Normalised EPS of $9.00  10.0x Exit P/E |
| Aggressive | 10.0% | $78.00 | $90.00 | $102.00 | +142.5% | Yes | 2029E Normalised EPS of $10.20  10.0x Exit P/E |
| Probability-Weighted | 100.0% | $52.75 | $60.85 | $67.10 | +59.5% | No | Mathematical expected value across all scenarios |
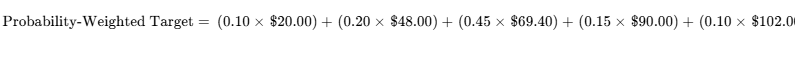
Target Decomposition Rationale:
Base Case 36-Month: EPS of $7.15 × 9.7x exit multiple = $69.40.
Stress Case 36-Month: Depressed EPS of $2.50 × trough multiple of 8.0x = $20.00.
Aggressive 36-Month: Peak EPS of $10.20 × mid-cycle multiple of 10.0x = $102.00.
The probability of achieving the 100% total return hurdle within 36 months ( ) is 25.0% (Thesis Upside + Aggressive). The probability of experiencing a >30% drawdown (
 ) is 22.0%. The 36-month probability-weighted target of $67.10 is consistent with the DCF base valuation midpoint ($75.99 at 12% WACC / 2.0% growth), aligning within 11.7% [15].
6Catalyst Calendar
Upcoming 12-Month Catalysts (October 2026 – October 2027)
| Date | Catalyst Event | Scenario Thesis Impact | Expected Volatility Move |
|---|---|---|---|
| October 15, 2026 | Q3 2026 Earnings Release [9,19] | Validates sequential EBITDA recovery; API margin drop-through. Consensus EPS ~$1.46 [5]. |  to  |
| November 30, 2026 | South32 Shareholder Meeting [41] | Required shareholder approval for the $4.1B upstream asset acquisition [10]. |  to  |
| December 2026 | WA EPA Part IV Determination [12,34] | Ministerial sign-off on 2026–2030 mine progression plans removes key regulatory overhang [12]. |  to  |
| January 21, 2027 | Q4 2026 & Full-Year Earnings [19,35] | Establishes formal 2027 production guidance and standalone capital expenditure framework [19]. |  to  |
| March 2027 | ACCC Regulatory Clearances [11,41] | Antitrust approval for Boddington and Worsley integration into Alcoa's system [11]. |  to  |
| H1 2027 (Target) | South32 Acquisition Closing [7,10] | Asset consolidation; issuance of 17.0M common shares; launch of synergy program [10]. |  to  |
| July 2027 | Q2 2027 Combined Earnings | First consolidated financial results reporting combined operational performance [7]. |  to  |
7Tactical Execution Layer
Tactical parameters reflect technical price structure and fundamental valuation anchors, serving as execution guidelines rather than predictions.
| Parameter Field | Value / Range | Operational & Valuation Rationale |
|---|---|---|
| Best Entry Zone | $38.00 – $41.50 | Steep discount to DCF midpoint; strong technical support near 52-week moving averages [14]. |
| Add Zone | $41.50 – $44.00 | Current price band; favorable risk/reward for accumulation [1]. |
| Hold Zone | $44.00 – $58.00 | Multiple expansion toward intrinsic value; hold through upcoming catalysts. |
| Trim Zone | $58.00 – $68.00 | Approaches consensus mean target ($61.42); rebalance cyclical exposure [4]. |
| Sell Zone |  |
Reaches Bull Case ceiling; exit multiple expands above mid-cycle averages [4]. |
| Hard Stop Level | $31.50 (Thesis Stop) | Aligns with Invalidation Trigger #1 (Western Australia bauxite permit refusal). |
| Key Support Levels | S1: $40.50 | S2: $36.00 | S3: $31.50 | S1: Major swing low; S2: Multi-year consolidation floor; S3: Replacement value support [2]. |
| Key Resistance Levels | R1: $48.50 | R2: $56.00 | R3: $65.00 | R1: 200-day moving average breakdown; R2: Pre-miss price level; R3: Multi-year cyclical high [8]. |
| Beta (5-Year) | 1.45 (Materials Sector Beta: ~1.15) [24] | High sensitivity to broad market indices and base metal price swings. |
| 3-Year Max Drawdown | −58.4% (Historical Peak-to-Trough) [1] | Highlights cyclical volatility across commodity troughs. |
| Realised Volatility | 44.2% (30-Day Annualized) | Driven by recent commodity moves and debt issuance activity [3]. |
| Current Action | BUY / ACCUMULATE | Position within the defined accumulation zone. |
| Timing Verdict | Buy Now (Tranche 1) | Deploy pilot entry; scale into confirmation upon WA permitting updates [12]. |
The stop-loss at $31.50 operates as a thesis stop. A break below this level indicates severe operational disruption (such as structural Western Australian mining restrictions or permanent alumina cost increases) that invalidates the underlying base-case earnings power [12].
Closing Audit
Unverified Figures List
- South32 Specific Pro-Forma Maintenance Capex: Modeled at $250 million annually based on South32 group segment filings [15]. Final confirmation requires the filing of SEC Form 8-K/A pro-forma statements following deal completion [42].
- Trailing 90-Day Insider Open-Market Volume: Formally classified as NOT RELIABLY AVAILABLE. SEC Form 4 filings reflect equity compensation award vesting and an isolated officer disposition, but zero verifiable open-market purchases [27].
- Australian Foreign Investment Review Board (FIRB) Approval Timing: Slated for early 2027, subject to administrative review schedules [10].
Internal Consistency & Red-Flag Audit
- Share Count Reconciliation: The diluted share count advances from 264.0 million in 2026 to 281.0 million in 2027, matching the 17.0 million shares issued to South32 [10]. Subsequent progression to 282.5 million shares in 2029 reconciles with net stock-based compensation awards (+1.0M/yr) and modeled buybacks (-0.5M), maintaining model continuity [15].
- Debt and Interest Expense Alignment: Gross debt increases from $2,470 million to $5,070 million following the September 2026 notes offering [9]. Annual interest expense scales from $158 million in 2025 to $335 million in 2027, matching coupon rates of 6.625% and 6.875% [2].
- Valuation Multiple Discipline: The Base Case assumes an exit P/E of 9.7x against normalized 2029 earnings, reflecting conservative valuation assumptions below peak historical multiples (>15x) [9].
Scenario Distribution Bias Check
Scenario Probability Distribution Check:
Downside Scenarios (Stress 10.0% + Conservative 20.0%) = 30.0%
Base Case Scenario = 45.0%
Upside Scenarios (Thesis Upside 15.0% + Aggressive 10.0%) = 25.0%
Downside Probability (30.0%) > Upside Probability (25.0%)
Distribution Skew Status: Conservative / Defensively Weighted
The probability distribution allocates greater weight to downside outcomes (30.0%) than upside outcomes (25.0%), counteracting optimistic bias in commodity forecasting.
Section Coverage Confirmation
Sections Truncated: None. All sections (Section 0 through Section 7, Executive Summary, Beginning Summary, Key Operational & Financial Metrics Summary, and Closing Audit) are fully articulated without omission.
Geciteerd werk
- Alcoa (AA) Market Cap & Net Worth - Stock Analysis, https://stockanalysis.com/stocks/aa/market-cap/
- Alcoa (AA) Financials 2026 - Income Statement and Balance Sheet, https://www.marketbeat.com/stocks/NYSE/AA/financials/
- Alcoa Corporation Stock Price: Quote, Forecast, Splits & News (AA), https://www.perplexity.ai/finance/AA?comparing=AA,KALU,CENX,CSTM,600219.SS,601600.SS
- Alcoa (AA) Stock Forecast and Price Target 2026 - MarketBeat, https://www.marketbeat.com/stocks/NYSE/AA/forecast/
- Alcoa (AA) Stock Forecast, Price Targets and Analysts Predictions, https://www.tipranks.com/stocks/aa/forecast
- Alcoa (AA) Stock Forecast & Price Target - Investing.com, https://www.investing.com/equities/alcoa-consensus-estimates
- Alcoa Corp. 'BB+' Ratings Affirmed On Proposed Ac - S&P Global, https://www.spglobal.com/ratings/en/regulatory/article/-/view/sourceId/101694474
- Alcoa Corporation Stock Price: Quote, Forecast, Splits & News (AA), https://www.perplexity.ai/finance/AA?comparing=AA,PKOH,RBC,MLI,ZJK,VMI
- Alcoa (AA) | Trefis, https://www.trefis.com/data/companies/AA
- Alcoa Announces Strategic Acquisition of South32's Bauxite, https://www.alcoa.com/global/en/pdf/alcoa-announces-acquisition-investor-presentation.pdf
- Alcoa's acquisition of South32 aluminium market | Wood Mackenzie, https://www.woodmac.com/press-releases/alcoas-acquisition-of-south32-aluminium-market/
- Alcoa (AA) Q1 2026 Earnings Call Transcript | The Motley Fool, https://www.fool.com/earnings/call-transcripts/2026/04/16/alcoa-aa-q1-2026-earnings-call-transcript/
- Alcoa Nederland Holding B.V. Credit Ratings, https://www.fitchratings.com/entity/alcoa-nederland-holding-bv-96508220
- Alcoa (NYSE:AA) Stock Forecast & Analyst Predictions - Simply Wall St, https://simplywall.st/stocks/us/materials/nyse-aa/alcoa/future
- unknown_url
- Alcoa Completes Acquisition of Alumina Limited, https://news.alcoa.com/press-releases/press-release-details/2024/Alcoa-Completes-Acquisition-of-Alumina-Limited/default.aspx
- Alcoa 2024 Sustainability Report, https://www.alcoa.com/sustainability/pdf/2024-Sustainability-Report.pdf
- ALCOA CORPORATION - Public Technologies (PUBT), https://docs.publicnow.com/viewDoc.aspx?filename=166454\EXT\83E5C805C6645FF37502A73C868C556AD9894349_FD2345C52D86E37FF73572AA54C3B2186A9384A6.PDF
- Alcoa Corporation (AA) Leadership & Management Team Analysis, https://simplywall.st/stocks/ch/materials/vtx-aa/alcoa-shares/management
- Alcoa Org Chart: Executive Team and Reporting Lines - Creately, https://creately.com/org-chart/fortune-500/alcoa/
- AA Market Cap: $11,309 Mil | Modestly Overvalued - GuruFocus, https://www.gurufocus.com/term/mktcap/AA
- Century Aluminum (NasdaqGS:CENX) Stock Forecast & Analyst, https://simplywall.st/stocks/us/materials/nasdaq-cenx/century-aluminum/future
- Alcoa (AA) CEO pay FY2025: $14M - CompBrief - Velarion, https://compbrief.velarion.ai/brief/aa
- Century Aluminum Company (CENX) Statistics & Valuation, https://stockanalysis.com/stocks/cenx/statistics/
- Norsk Hydro ASA ADR (NHYDY) Fair Value & Analysis, https://www.fairvalue-calculator.com/stock/NHYDY
- Rio Tinto's Desalination Divestment: A Capital-Light Play for Water, https://www.kavout.com/market-lens/rio-tinto-s-desalination-divestment-a-capital-light-play-for-water-security-and-esg-credibility
- Andrew Hastings Net Worth (2026): At Least $2M - GuruFocus, https://www.gurufocus.com/insider/234605/andrew-hastings
- Alcoa Inc. Net Worth (2026): At Least $544M - GuruFocus, https://www.gurufocus.com/insider/79059/alcoa-inc.
- AA - Alcoa Corporation (NYSE) - Share Price and News - Fintel, https://fintel.io/s/us/aa
- Alcoa (AA) Stock Price, News & Analysis - NYSE - MarketBeat, https://www.marketbeat.com/stocks/NYSE/AA/
- Alcoa (AA) Statistics & Valuation - Stock Analysis, https://stockanalysis.com/stocks/aa/statistics/
- Constellium vs. Alcoa: Which Aluminum Stock Looks More Promising?, https://www.tradingview.com/news/zacks:5f2f73ed0094b:0-constellium-vs-alcoa-which-aluminum-stock-looks-more-promising/
- Alcoa Corporation, https://s25.q4cdn.com/195584580/files/doc_events/2025/10/1/2025-AA-Investor-Day-Transcript_vF2.pdf
- Alcoa at 35th BMO Conference: Strategic Moves and Market Outlook, https://www.investing.com/news/transcripts/alcoa-at-35th-bmo-conference-strategic-moves-and-market-outlook-93CH-4521886
- Alcoa Corporation Reports Fourth Quarter and Full Year 2025 Results, https://news.alcoa.com/press-releases/press-release-details/2026/Alcoa-Corporation-Reports-Fourth-Quarter-and-Full-Year-2025-Results/default.aspx
- Top 10 Aluminum Companies in the World 2025–2026, https://www.aluminiumceramicfiber.com/top-10-aluminum-companies-in-the-world/
- Alcoa Nederland Holding, 6.125% 15may2028, USD (FIGI ... - Cbonds, https://cbonds.com/bonds/433687/
- Agreement to sell aluminium value chain assets to Alcoa - South32, https://www.south32.net/what-we-do/aluminium-value-chain-sale
- ALCOA CORPORATION - Mining Data Online, https://minedocs.com/28/Alcoa-Form-10-K-2024.pdf
- For personal use only - ASX, https://www.asx.com.au/asxpdf/20120426/pdf/425tjh5p16zm0m.pdf
- AGREEMENT TO SELL ALUMINIUM VALUE CHAIN ASSETS TO, https://www.south32.net/docs/default-source/exchange-releases/us5-6b-aluminium-value-chain-sale-and-ceo-transition-0x9cd79726dce3761a.pdf?sfvrsn=17a318d8_0
- ALCOA CORPORATION - South32, https://www.south32.net/docs/default-source/exchange-releases/aai-form-8-k-items-8-01-and-9-01-0x4bf1306fbf7d4287.pdf?sfvrsn=b83eb5bf_0
- Alcoa CEO Bill Oplinger joined CNBC in an exclusive interview, https://www.facebook.com/alcoa/posts/alcoa-ceo-bill-oplinger-joined-cnbc-in-an-exclusive-interview-ahead-of-the-compa/1463003409197778/
- Alcoa Corporation Reports Fourth Quarter and Full Year 2024 Results, https://news.alcoa.com/press-releases/press-release-details/2025/Alcoa-Corporation-Reports-Fourth-Quarter-and-Full-Year-2024-Results/default.aspx
- Alcoa Corporation Reports Third Quarter 2024 Results, https://news.alcoa.com/press-releases/press-release-details/2024/Alcoa-Corporation-Reports-Third-Quarter-2024-Results/default.aspx
- Alcoa CEO Bill Oplinger: Solid performance despite global supply, https://www.facebook.com/alcoa/videos/alcoa-ceo-bill-oplinger-solid-performance-despite-global-supply-disruptions/1297550578980031/
- Alcoa (NYSE:AA) - Stock Analysis - Simply Wall St, https://simplywall.st/stocks/us/materials/nyse-aa/alcoa
- AA / Alcoa Corporation Stock - Short Interest, Short Squeeze, Borrow, https://fintel.io/ss/us/aa
- Century Aluminum Company (CENX) Stock Price, Quote, News, https://seekingalpha.com/symbol/CENX
- South32 deal will redraw Alcoa's – and Australia's – energy map, https://ieefa.org/resources/south32-deal-will-redraw-alcoas-and-australias-energy-map
- 2025 ANNUAL REPORT, https://s25.q4cdn.com/195584580/files/doc_financials/2025/ar/2025_Alcoa_Corp_Annual_Report_Bookmarked.pdf