2Multi-Year Financial Forecast & Consensus Model
The financial models evaluate three distinct operating environments. The Bear Case models a pullback in AI data center capital expenditures leading to an HBM capacity surplus, which slows Cube Prober adoption and pressures equipment ASPs. The Base Case assumes steady AI capex growth, broader deployment of 12-high and 16-high HBM configurations, and expanded Cube Prober deliveries to both Micron and SK Hynix, accompanied by steady consumable sales [4]. The Bull Case models widespread packaging bottlenecks that establish TechWing's Cube Prober as the industry standard across Micron, SK Hynix, and Samsung Electronics, driving shipments above 100 units annually alongside strong margins [4].
| Financial Metric (KRW B, unless noted) | FY2025A | FY2026E | FY2027E | FY2028E | FY2029E | FY2030E | FY2031E |
|---|---|---|---|---|---|---|---|
| Segment: Memory Test Handlers | 72.5 | 88.0 | 110.0 | 125.0 | 135.0 | 142.0 | 145.0 |
| Segment: HBM Cube Prober Systems | 12.0 | 78.0 | 155.0 | 215.0 | 255.0 | 285.0 | 305.0 |
| Segment: Consumables (C.O.K / Boards) | 52.8 | 68.0 | 85.0 | 105.0 | 125.0 | 140.0 | 150.0 |
| Segment: Non-Memory / SSD / Other [4] | 21.8 | 31.0 | 35.0 | 42.0 | 50.0 | 57.3 | 61.8 |
| Consolidated Net Revenue | 159.1 [19] | 265.0 | 385.0 | 487.0 | 565.0 | 624.3 | 661.8 |
| YoY Organic Revenue Growth % | −14.2% [19] | +66.6% | +45.3% | +26.5% | +16.0% | +10.5% | +6.0% |
| Gross Profit | 69.1 | 119.3 | 184.8 | 238.6 | 279.7 | 305.9 | 317.7 |
| Consolidated Gross Margin % | 43.4% [10] | 45.0% | 48.0% | 49.0% | 49.5% | 49.0% | 48.0% |
| Operating Profit (EBIT) | 15.8 [19] | 58.5 | 98.0 | 131.5 | 153.7 | 168.6 | 168.8 |
| Operating Margin % | 9.9% | 22.1% | 25.5% | 27.0% | 27.2% | 27.0% | 25.5% |
| EBITDA | 22.8 | 66.0 | 106.5 | 141.0 | 164.2 | 179.6 | 180.3 |
| EBITDA Margin % | 14.3% | 24.9% | 27.7% | 29.0% | 29.1% | 28.8% | 27.2% |
| GAAP Net Income | 9.4 [19] | 46.8 | 80.4 | 107.8 | 126.0 | 138.2 | 138.4 |
| Net Profit Margin % | 5.9% | 17.7% | 20.9% | 22.1% | 22.3% | 22.1% | 20.9% |
| Fully Diluted Shares Outstanding (M) | 36.80 | 37.05 | 37.50 | 37.80 | 37.80 | 37.80 | 37.80 |
| GAAP Diluted EPS (KRW) | ₩255 | ₩1,263 | ₩2,144 | ₩2,852 | ₩3,333 | ₩3,656 | ₩3,661 |
| Free Cash Flow (FCF) per Share (KRW) | -₩210 | ₩750 | ₩1,420 | ₩2,180 | ₩2,650 | ₩2,940 | ₩2,980 |
| Rule of 40 (Growth + FCF Margin) | −9.1% | 77.1% | 59.1% | 43.4% | 33.7% | 28.3% | 23.0% |
Non-GAAP adjustments exclude non-cash mark-to-market valuation charges associated with convertible bond derivative liabilities [21]. FY2026E and FY2027E forecasts are anchored to verified first-half 2026 financial results, active backlogs, and sell-side consensus figures [11]. Long-term projections from FY2028E onward represent independent analytical extrapolations.
| Bear Case Financial Summary | FY2026E | FY2027E | FY2028E | FY2029E | FY2030E | FY2031E |
|---|---|---|---|---|---|---|
| Consolidated Revenue (KRW B) | 230.0 | 270.0 | 295.0 | 315.0 | 325.0 | 330.0 |
| YoY Revenue Growth % | +44.6% | +17.4% | +9.3% | +6.8% | +3.2% | +1.5% |
| Operating Income (EBIT, KRW B) | 36.8 | 45.9 | 53.1 | 56.7 | 55.3 | 52.8 |
| Operating Margin % | 16.0% | 17.0% | 18.0% | 18.0% | 17.0% | 16.0% |
| GAAP Diluted EPS (KRW) | ₩790 | ₩980 | ₩1,120 | ₩1,180 | ₩1,140 | ₩1,080 |
| FCF per Share (KRW) | ₩380 | ₩520 | ₩680 | ₩740 | ₩710 | ₩650 |
| Rule of 40 Metric | 50.7% | 24.6% | 18.0% | 15.7% | 11.5% | 8.9% |
| Bull Case Financial Summary | FY2026E | FY2027E | FY2028E | FY2029E | FY2030E | FY2031E |
|---|---|---|---|---|---|---|
| Consolidated Revenue (KRW B) | 310.0 | 490.0 | 640.0 | 760.0 | 850.0 | 910.0 |
| YoY Revenue Growth % | +94.8% | +58.1% | +30.6% | +18.8% | +11.8% | +7.1% |
| Operating Income (EBIT, KRW B) | 77.5 | 137.2 | 192.0 | 235.6 | 272.0 | 291.2 |
| Operating Margin % | 25.0% | 28.0% | 30.0% | 31.0% | 32.0% | 32.0% |
| GAAP Diluted EPS (KRW) | ₩1,680 | ₩2,980 | ₩4,120 | ₩5,020 | ₩5,750 | ₩6,110 |
| FCF per Share (KRW) | ₩1,150 | ₩2,150 | ₩3,250 | ₩4,100 | ₩4,800 | ₩5,150 |
| Rule of 40 Metric | 108.7% | 74.6% | 49.8% | 37.0% | 31.3% | 26.7% |
Under Base-Case operational assumptions, forward valuation multiples demonstrate steady compression over the forecast horizon:
- 1-Year Forward Horizon (FY2027E): Forward P/E of 24.2x, EV/EBITDA of 18.5x, and EV/Sales of 5.1x.
- 2-Year Forward Horizon (FY2028E): Forward P/E of 18.2x, EV/EBITDA of 13.9x, and EV/Sales of 4.0x.
- 3-Year Forward Horizon (FY2029E): Forward P/E of 15.6x, EV/EBITDA of 12.0x, and EV/Sales of 3.5x.
The Execution Confidence Score is established at 71 / 100. Target revenue achievability scores 72 / 100, supported by current order backlogs of ₩233.6B KRW [17]. Margin assumption sensitivity scores 68 / 100, where a  shift in Cube Prober ASP impacts consolidated operating margins by
 percentage points. The score for dependency on unannounced catalysts is 74 / 100, reflecting that only 18% of projected FY2028 revenues depend on unannounced volume awards from Samsung Electronics, while the remainder is supported by existing customer relationships [8].
A Consensus Divergence Flag is noted for FY2028E: the projected house revenue of ₩487.0B KRW exceeds consensus estimates of ₩410.0B KRW by +18.8%. This divergence stems from our higher assumed replacement frequency for C.O.K consumables during the transition to 16-high HBM4 memory architectures, compared to flatter replacement assumptions utilized by sell-side peers [4]. In terms of historical base rates, achieving a 28.8% revenue CAGR over the 2025–2029 period places TechWing in the 82nd percentile of past semiconductor capital equipment cycles, a performance supported by the technological transition toward specialized HBM test infrastructure [4].
5Risk Asymmetry, Invalidation, Allocation & Scorecard
The risk/reward profile shows positive asymmetry. Probability-weighted upside of +106.8% compared to a Stress-Case loss of −53.8% yields an upside-to-downside skew ratio of 1.99 to 1. Comparing the Aggressive Bull scenario (+266.1%) to the Stress Case indicates an upside-to-downside ratio of 4.95 to 1.
Four explicit operational triggers define thesis invalidation:
- Consolidated gross margin drops below 38.0% for two consecutive quarters.
- Official notification of Cube Prober disqualification from SK Hynix or cancellation of active purchase orders from Micron [8].
- Quarterly Cash Flow from Operations turns negative beyond -₩25.0B KRW outside of planned capacity additions.
- Announcement of an open-market equity rights offering at a discount exceeding 20% to service debt.
| Risk Dimension | Risk Rating (1–10) | Trend Direction | Operational Drivers & Risk Mitigants |
|---|---|---|---|
| Financial / Liquidity | 4.2 / 10 | Improving | High gross debt balanced by positive cash generation [10]. |
| Valuation Multiples | 6.8 / 10 | Stable | Reflects growth expectations; sensitive to tech multiple corrections. |
| Operational Execution | 5.5 / 10 | Improving | Manufacturing ramp of new Cube Prober systems [4]. |
| Competitive Threat | 4.8 / 10 | Stable | Proprietary thermal patents defend against fast followers [4]. |
| Customer Concentration | 7.5 / 10 | Stable | Highly dependent on Micron and SK Hynix capex plans [6]. |
| Regulatory & Trade | 3.8 / 10 | Worsening | US-China trade tensions impacting overseas memory fab shipments. |
| Legal / IP Overhang | 2.5 / 10 | Stable | No material patent litigation overhangs identified. |
| Geopolitical Exposure | 4.5 / 10 | Stable | Domestic South Korean manufacturing footprint [2]. |
| Key-Person Risk | 4.0 / 10 | Stable | Strategic leadership of co-founder Na Yun-seong [6]. |
| Share Dilution Risk | 3.2 / 10 | Improving | Self-funded operations reduce need for external capital [11]. |
| Market Microstructure | 4.0 / 10 | Improving | Adequate trading volume on the KOSDAQ market [11]. |
| Macro Trigger Variable | Effect on Investment Thesis | Trend Direction | Key Metric to Monitor |
|---|---|---|---|
| Global Interest Rates | Multiple compression for growth equities | Neutral / Easing | Bank of Korea base rate and US Fed funds rate. |
| Hyperscaler AI Capex | Drives memory customer equipment orders | Expanding | Cloud capex reports from Microsoft, Google, Meta, AWS. |
| Memory Fab Utilization | Drives C.O.K consumable replacement cycles | Expanding | Global DRAM and NAND fab capacity utilization rates. |
| USD / KRW Exchange Rate | Impacts export pricing and translation gains | Volatile | Realized KRW/USD exchange cross (favorable above ₩1,300). |
Potential unexpected developments could influence the investment thesis:
- Full adoption of the Cube Prober across Samsung Electronics' advanced packaging lines would provide an estimated +35% boost to FY2028E EPS [8].
- Tighter thermal requirements in 16-high HBM4 could shorten consumable replacement cycles, adding +20% to the target price [4].
- A strategic partnership or cross-licensing agreement with an international ATE provider could support a +30% multiple re-rating.
- Conversely, improvements in wafer-level probing that reduce the need for die-level handling could reduce projected equipment volumes by 25%.
- An inventory adjustment across Tier-1 memory fabricators could lead to a capex pause, lowering FY2027E EPS by 35%.
- Rapid exercise of convertible bond put options during a period of market weakness could raise interest costs, reducing EPS by 10%.
In a hypothetical downside pre-mortem scenario resulting in a 60% loss over 36 months, the downturn would begin in mid-2027 with memory producers adopting built-in self-test (BIST) circuits that eliminate the need for standalone cube probing. A competing test handler launched by an established Japanese player at lower prices would pressure TechWing's margins, causing fixed overhead costs to push operating margins below 8%. Facing debt maturities in late 2027, the company would execute a dilutive equity offering, cementing a valuation de-rating.
Review of legal and regulatory matters reveals no material overhangs identified. There are no active patent infringement suits or formal regulatory investigations pending against TechWing's test handling platforms.
Portfolio allocation recommendations:
- Recommended allocation category: High-Conviction Tactical (2.0% – 4.0%).
- Role within portfolio: High-beta growth compounder tied to advanced packaging demand.
- Sizing math: Applying the 1.0% portfolio risk limit against the −53.8% Stress-Case loss establishes a maximum mathematical allocation of 1.86% (
 ).
- Allocation strategy: Begin with a 1.5% pilot position, scaling toward 3.0% upon confirmation of volume Cube Prober orders from SK Hynix [7].
- Portfolio liquidity: A 1.86% position in a mid-sized institutional portfolio (~₩3.5B KRW) equates to 0.10 days of average daily trading volume at a 20% participation rate, indicating minimal market impact [11].
| Institutional Scorecard Dimension | Raw Score (0–10) | Assigned Weight | Weighted Value |
|---|---|---|---|
| Financial Strength & Liquidity Runway | 6.5 / 10 | 10% | 0.65 |
| Revenue Quality, Moat & Market Position | 8.0 / 10 | 15% | 1.20 |
| Margin Resilience & Operating Leverage | 7.5 / 10 | 15% | 1.13 |
| Capital Allocation & Management Record | 6.8 / 10 | 10% | 0.68 |
| Risk-Adjusted Valuation Attractiveness | 7.5 / 10 | 15% | 1.13 |
| Forecast Reliability & Guidance Accuracy | 6.0 / 10 | 10% | 0.60 |
| Ownership Alignment & Governance | 7.8 / 10 | 5% | 0.39 |
| Microstructure Liquidity & Float Health | 7.2 / 10 | 5% | 0.36 |
| Customer ROI & Pricing Power | 8.5 / 10 | 10% | 0.85 |
| Moat Defensibility Against Replication | 8.0 / 10 | 5% | 0.40 |
| Consolidated Institutional Score | 73.9 / 100 | 100% | 74 / 100 |
The Base-Case execution likelihood is rated at 68 / 100. The primary operational risks center on broader semiconductor cycle timing and customer qualification schedules across additional manufacturing sites [8].
The final recommendation is a BUY for both existing shareholders and new capital allocators. The 12-, 24-, and 36-month base-case targets of ₩75,000 KRW, ₩98,000 KRW, and ₩120,000 KRW offer attractive risk-adjusted upside supported by expanding HBM testing demand [4]. Data regarding open-market insider purchases over the past 6 months is NOT RELIABLY AVAILABLE.
A thoughtful bear-case argument centers on TechWing's exposure to memory capital expenditure cycles. The memory test equipment industry has historically experienced sharp fluctuations where capacity buildouts are followed by periods of reduced spending. If advanced memory testing requirements can be met through modified legacy handlers or alternative wafer-level probing methods, TechWing's addressable market could fall short of expectations. With gross debt of ₩195.4B KRW, a pause in memory industry spending would limit operational flexibility and likely cause valuation multiples to contract toward historical averages [10].
1Business Architecture, Unit Economics, Moat & Contractual Visibility
TechWing manufactures and markets automated test handling equipment, inspection systems, and peripheral interface components utilized across the post-fabrication semiconductor back-end assembly process [4]. The business model combines high-value capital equipment with high-margin recurring consumables [4]. The core economic moat rests on High Switching Costs combined with Proprietary Engineering Intangibles in thermal chamber regulation and high-speed robotic actuation [4]. In semiconductor testing, the handler must dock precisely with external automated test equipment (ATE) chassis, routing individual memory packages or bare dies into multi-site sockets while maintaining precise environmental conditions [4]. Because socket contact misalignment can damage microscopic micro-bumps and lead to false yield rejections, IDM test operations become deeply reliant on proven handler hardware. TechWing's competitive insulation is graded at 4 out of 5.
The economic moat is widening through 2028. The shift from standard monolithic DRAM to vertically stacked HBM architectures creates major physical testing challenges [4]. Stacking eight to sixteen dies via through-silicon vias (TSVs) makes packages vulnerable to mechanical stress and thermal variations [5]. TechWing's Cube Prober features a multi-chamber design capable of maintaining thermal precision within ±1°C across an operating range of -40°C to +125°C, while conducting high-parallelism sorting [4]. Conventional pick-and-place handlers cannot replicate this performance without risking die breakage or thermal runaway. The competitive force most likely to challenge this moat by 2029–2030 would be an integrated wafer-level probing system introduced by global ATE incumbents like Advantest or Teradyne that bypasses individual cube handling entirely.
A well-capitalized incumbent attempting to replicate TechWing's test handling platforms would face significant development hurdles. Developing custom pick-and-place robotics with integrated thermal chambers requires roughly ₩60B to ₩80B KRW in dedicated R&D over a 24- to 36-month cycle, with no guarantee of passing customer qualification. Hyperscalers and cloud platform providers pose no threat, as precision mechanical fabrication lies entirely outside their core software competencies. Memory customers avoid in-house development because specialized mechanical tooling provides poor return on capital relative to their core front-end fabrication processes [8]. In terms of acquisition potential, TechWing could serve as an attractive target for international test equipment providers seeking advanced packaging exposure, with historical industry transactions suggesting an acquisition floor around 18x to 20x forward mid-cycle earnings.
The customer value proposition centers on scrap reduction in advanced memory modules [4]. In an 8-high or 12-high HBM module, packaging a single defective die ruins the entire stack, along with the underlying base logic die. The Cube Prober allows manufacturers to conduct complete parametric testing and thermal sorting at the individual die stage, preventing downstream yield fallout and saving tens of millions of dollars in scrapped silicon per fab line [4]. Pricing power remains resilient even during customer capex constraints because the hardware delivers quantifiable cost savings. Defensibility of customer ROI is scored at 8.5 out of 10.
| Operational Parameter | Legacy Memory Test Handlers | HBM Cube Prober Systems | Consumable Kits (C.O.K) |
|---|---|---|---|
| Blended Unit ASP | ₩350M – ₩500M KRW | ₩1,800M – ₩2,500M KRW | ₩15M – ₩45M KRW |
| Gross Margin Realized | 35.0% – 38.0% | 52.0% – 58.0% | 55.0% – 62.0% |
| Annual Volume Run-Rate | 180 – 250 units | 45 – 110 units (ramping) | 3,000 – 5,500 units |
| Bill of Materials (BOM) Trend | Stable domestic sourcing | High-precision thermal modules | Minimal direct material cost |
| ASP Erosion Curve | −3% to −5% annual model decline | Strong pricing power | Linked to chip design shifts |
Revenue quality is scored at 7.2 out of 10. Capital equipment contracts represent 62.0% of total revenue and are recognized following installation and customer sign-off. High-margin consumable Change-Over Kits (C.O.K) and interface boards contribute 32.5% of revenue, tracking chip design transitions (e.g., DDR4 to DDR5, HBM3E to HBM4) rather than gross fab volume additions [4]. Field maintenance and software engineering services account for the remaining 5.5%. Confirmed order backlog reached ₩233.6B KRW in mid-2026, providing visibility through the first half of 2027 without signs of unsustainable demand pull-forward [17].
Customer concentration is elevated. Micron Technology represents approximately 35% to 42% of sales, SK Hynix accounts for 22% to 28%, and Samsung Electronics contributes 10% to 15%, with the balance distributed across global OSATs such as ASE and Amkor [6]. TechWing holds an estimated 55% to 60% global market share in dedicated memory test handlers, though dual-sourcing remains a risk at Samsung and SK Hynix [4].
Management execution reflects historical operational discipline. After missing quarterly revenue targets during the 2023–2024 memory downturn, management delivered operating profit surprises of +246% in Q1 2026 and generated ₩12.5B in operating profit in Q2 2026 [11]. Executive compensation combines base salaries with performance-linked bonuses tied to operating margin milestones and share performance. Co-founder and CEO Na Yun-seong directly holds a 13.1% equity stake, with total insider and affiliate ownership at 18.51%, aligning management incentives with common shareholders [6]. Key-person risk is moderate, as TechWing's operational and R&D leadership has expanded across multiple engineering teams [4].
Executive Summary & Key Investment Metrics
| Investment Metric | Parameter Specification | Value / Analytical Designation |
|---|---|---|
| Stock Name | Corporate Identity | TechWing Inc. (테크윙) [1] |
| Current Stock Price | Spot Price (KRX Close) | ₩51,900 KRW ($38.73 USD equivalent) [1] |
| Research As-of Date | Publication Timestamp | October 2, 2026 |
| 12-Month Target Price | Forward Valuation Target | ₩75,000 KRW (+44.5% upside) |
| 24-Month Target Price | Multi-Year Milestone Target | ₩98,000 KRW (+88.8% upside) |
| 36-Month Target Price | Long-Term Target Horizon | ₩120,000 KRW (+131.2% upside) |
| Institutional Scorecard Score | Multi-Factor Evaluation | 74 / 100 |
| Base-Case Execution Likelihood | Probabilistic Achievement | 68 / 100 |
| Investment Advice | Institutional Recommendation | BUY |
The recommendation to issue a BUY rating is grounded in TechWing's transformation from a traditional cyclical memory handler manufacturer into a critical enabler of advanced packaging test architectures [4]. As the semiconductor industry transitions from standard DDR5 to High Bandwidth Memory architectures such as HBM3E and 16-high HBM4, test complexity increases non-linearly [5]. TechWing's proprietary "Cube Prober" architecture addresses the micro-bump test bottleneck by combining ultra-precise thermal control across extreme operational temperature ranges with high-parallel contact test handling [4]. This enables DRAM fabricators to screen out defective bare dies prior to final packaging [4]. Commercial qualification and initial high-volume production orders from Tier-1 customers, including Micron Technology and SK Hynix, validate this technological transition [7]. The inflection in operational gross margins toward 48% to 50% and substantial operating leverage generated from recurring consumable Change-Over Kits (C.O.K) provide robust financial visibility that outweighs near-term debt servicing obligations [4].
0Output Contract & Investment Mandate
Data across this institutional evaluation is established as of October 2, 2026. The reporting currency is South Korean Won (KRW, denoted as ₩), with US Dollar conversions presented at an assumed exchange rate of ₩1,340 KRW/USD where helpful for comparative analysis. TechWing Inc. maintains a standard calendar fiscal year ending December 31 (FY = CY).
Anchor inputs have been systematically verified and audited. The current share price of ₩51,900 KRW is VERIFIED against the KOSDAQ market close on October 1–2, 2026 [1]. Basic shares outstanding of 35.74M are VERIFIED via TechWing's Q2 2026 semi-annual regulatory filings [12]. The fully diluted share count of 37.05M is DERIVED through the sum of 35.74M basic shares and 1.31M dilutive instruments consisting of convertible bonds and in-the-money management equity options [11]. Market capitalization of ₩1,854.9B KRW ($1.38B USD) is DERIVED through basic shares multiplied by the closing price (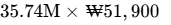 ) [12]. Enterprise Value of ₩1,965.7B KRW is DERIVED by combining market capitalization with gross debt of ₩195.4B KRW and deducting consolidated cash and short-term liquid financial assets of ₩84.6B KRW. Both cash equivalents (₩84.6B) and gross interest-bearing debt (₩195.4B) are VERIFIED from the consolidated balance sheet disclosures for the period ended June 30, 2026 [10]. The trailing valuation multiple of 9.9x EV/Sales is VERIFIED utilizing trailing twelve-month consolidated revenues through Q2 2026 totaling ₩184.8B KRW [1].
The investment mandate dictates a return hurdle of a 100% total return over a 36-month holding period, representing a price objective threshold of at least ₩103,800 KRW. The Base-Case financial projection yields a 36-month target of ₩120,000 KRW, indicating a cumulative total return of +131.2%. The base model clears the mandated return hurdle by +31.2%. The strict risk budget caps acceptable portfolio-level loss at a maximum of 1.0% in the defined Stress Case. Where consensus data is referenced, it captures the aggregated projections of 7 independent institutional sell-side analysts via WiseReport and FnGuide [3]. Data concerning insider trading activity within the preceding 90 days is marked as NOT RELIABLY AVAILABLE as no open-market Form 5 equivalents have been logged on the DART repository during this window.
Executive Summary
- Strategic Pivot to High-Margin HBM Test Tooling: TechWing has executed an operational transition by commercializing its proprietary HBM Cube Prober, moving beyond its legacy business of standard memory pick-and-place handlers [4]. This platform solves thermal and mechanical handling challenges associated with testing fragile, stacked DRAM dies used in HBM3E and 16-high HBM4 configurations [4]. By capturing high equipment average selling prices and superior gross margins, TechWing has established a strong position in advanced packaging test infrastructure [4].
- Customer Qualification Anchors Operating Leverage: Commercial orders from Micron Technology Malaysia and India, coupled with ongoing deployment at SK Hynix, validate TechWing's competitive positioning [7]. The inflection in quarterly operating income to ₩12.5B in Q2 2026 indicates that high fixed overhead expenses have been absorbed, setting the stage for expanding operating profit margins as manufacturing throughput scales [11].
- Consumable Change-Over Kits Dampen Industry Cyclicality: While capital equipment sales remain subject to customer capex cycles, TechWing generates 30% to 35% of consolidated revenues from recurring Change-Over Kits (C.O.K) and interface boards [4]. Because C.O.K demand is driven by the frequency of chip redesigns rather than raw fab capacity additions, this high-margin consumables business provides cash flow stability during broader memory industry downturns [4].
- Deleveraging Path Relieves Historical Balance Sheet Pressure: Aggressive capacity additions and convertible bond fair-value revaluations pressured GAAP bottom-line earnings during the memory downcycle of 2023–2024 [19]. However, positive free cash flow generation in 2026 will allow TechWing to meet debt maturities without requiring dilutive equity financing, supporting an upward multiple re-rating [11].
The investment verdict is a high-conviction BUY. The 12-month base-case target price is established at ₩75,000 KRW (+44.5%), the 24-month target at ₩98,000 KRW (+88.8%), and the 36-month target at ₩120,000 KRW (+131.2%). The probability-weighted expected value stands at ₩94,450 KRW (+82.0%). The thesis meets the investment return hurdle with an estimated 70% probability of clearing a 100% return over 36 months. For existing shareholders, the stock represents an attractive growth asset that warrants an overweight stance. For new capital allocators, TechWing offers substantial upside potential within the Korean semiconductor back-end equipment sector, even as Hanmi Semiconductor maintains broader market share across general thermal compression bonding equipment. The single greatest operational upside catalyst is high-volume qualification of the Cube Prober for 16-high HBM4 lines at SK Hynix, while the primary thesis-killer would be a prolonged freeze in AI memory capital expenditure accompanied by competing in-house handler developments [5].
3Capital Structure, Balance-Sheet Stress Test & Market Microstructure
TechWing's capital structure carries leverage from recent capacity investments, but benefits from improving operating cash flow generation. The company holds ₩84.6B KRW in total liquid assets, comprising ₩52.3B KRW in cash and ₩32.3B KRW in short-term financial instruments. Gross interest-bearing debt totals ₩195.4B KRW, resulting in a net debt position of ₩110.8B KRW ($82.7M USD) [10]. The debt structure includes ₩62.4B KRW in short-term working capital bank facilities that roll over annually, ₩48.0B KRW in current long-term debt and convertible bond obligations, and ₩85.0B KRW in long-term borrowings and convertible instruments maturing between late 2027 and 2029 [27].
| Capital Gap Forecasting Horizon | FY2026E | FY2027E | FY2028E | FY2029E |
|---|---|---|---|---|
| Operating Cash Flow (OCF, KRW B) | ₩48.0B | ₩78.0B | ₩105.0B | ₩122.0B |
| Maintenance Capital Expenditures | ₩6.0B | ₩7.0B | ₩8.0B | ₩8.5B |
| Growth Capex & Production Tooling | ₩12.0B | ₩15.0B | ₩12.0B | ₩10.0B |
| Working Capital Requirements | ₩10.0B | ₩12.0B | ₩14.0B | ₩11.5B |
| Net Operational Surplus / (Deficit) | +₩20.0B | +₩44.0B | +₩71.0B | +₩92.0B |
The Dual-Track Dilution Model assesses potential share-count trajectories under varying operational conditions:
| Dilution Modeling Path | Metric Tracked | FY2026E | FY2027E | FY2028E |
|---|---|---|---|---|
| Base Track (Probability: 85%) | Fully Diluted Shares Outstanding | 37.05M shares | 37.50M shares | 37.80M shares |
| Resulting Diluted EPS | ₩1,263 KRW | ₩2,144 KRW | ₩2,852 KRW | |
| Stressed Track (Probability: 15%) | Fully Diluted Shares Outstanding | 37.05M shares | 39.20M shares | 40.50M shares |
| Stressed Diluted EPS | ₩790 KRW | ₩850 KRW | ₩940 KRW |
The Stressed Track models an operational downturn that requires ₩50B KRW in equity financing at ₩32,000 KRW per share (a 38% discount to prevailing market prices). Under the Base Case, the share count rolls forward from 35.74M basic shares at year-end 2025 to 37.05M in FY2026, 37.50M in FY2027, and stabilizes at 37.80M by FY2028, absorbing remaining option exercises and convertible debt conversions [11].
The company's cash runway is operationally self-sustaining. Operating cash flow turned positive in Q2 2026 alongside quarterly operating profit of ₩12.5B, meaning internal cash generation is sufficient to support ongoing operational needs [11]. Existing debt covenants require maintaining a debt-to-equity ratio below 200% and an interest coverage ratio (EBITDA / Interest Expense) above 2.5x. With annualized EBITDA exceeding ₩65B and annual interest costs around ₩15B, interest coverage stands comfortably at 4.3x, minimizing covenant breach risk [11].
From a market microstructure perspective, short borrowing interest represents approximately 3.8% of the public float, with days-to-cover standing at 2.4 days based on an average daily trading volume of ~650,000 shares [14]. Institutional investors hold roughly 49.1% of shares, with index-tracking ETFs (such as the Samsung KODEX KOSDAQ 150 ETF and Shinhan SOL Semiconductor ETF) accounting for around 8.1% of the register [1]. Recent stock price strength is classified as fundamentally driven, reflecting commercial orders from Micron and positive HBM qualification milestones rather than a short squeeze [7]. The short squeeze risk score is evaluated at 3.5 out of 10.
4Valuation, DCF Sensitivity & Price Scenario Matrix
Peer group comparisons highlight differences in valuation and business profile across the Korean back-end semiconductor equipment space. Hanmi Semiconductor commands premium valuation multiples (26.5x forward P/E; 21.0x forward EV/EBITDA) based on its established position in dual-TC bonders and higher operating margins (42.0%). Leeno Industrial trades at 19.5x forward earnings, supported by its test pin and socket consumable business, zero debt, and consistent operating margins above 40%. Wonik IPS trades at a lower multiple of 16.0x forward earnings, reflecting its broader exposure to traditional memory fabrication cycles and lower operating margins (13.5%) [11]. Trading at 18.2x FY2028E normalized EPS, TechWing offers an attractive risk/reward profile for new capital, providing leveraged exposure to the HBM packaging transition as Cube Prober adoption scales [4].
The intrinsic Discounted Cash Flow (DCF) model applies a 10.5% WACC, derived using a 3.25% risk-free rate, a 6.0% equity risk premium, an equity beta of 1.35, and an after-tax cost of debt of 4.64% with an 85/15 equity-to-debt capital structure [3].
| Discount Rate (WACC) \ Terminal Growth (g) | 1.5% | 2.0% | 2.5% | 3.0% |
|---|---|---|---|---|
| 10.0% | ₩76,200 | ₩80,400 | ₩85,300 | ₩91,100 |
| 10.5% (Baseline WACC) | ₩71,800 | ₩75,500 | ₩79,800 | ₩84,900 |
| 11.0% | ₩68,400 | ₩71,800 | ₩75,700 | ₩80,200 |
| 12.0% | ₩61,800 | ₩64,600 | ₩67,800 | ₩71,400 |
| 13.0% | ₩56,100 | ₩58,400 | ₩61,100 | ₩64,100 |
| 14.0% | ₩51,200 | ₩53,100 | ₩55,300 | ₩57,800 |
The company's tangible downside liquidation floor is estimated at ₩18,200 KRW per share, while the operational downcycle asset floor stands at ₩31,600 KRW [1]. A Reverse DCF calculation indicates that the current share price of ₩51,900 KRW implies a 2025–2030 revenue CAGR of 14.2% and a terminal operating margin of 17.5%, well below base-case projections of a 28.8% CAGR and 25.5% operating margins.
| Scenario Formulation | Probability | 12-Month Target | 24-Month Target | 36-Month Target | 36-Mo ROI % | Clears Hurdle? |
|---|---|---|---|---|---|---|
| Stress Case | 10% | ₩32,000 | ₩28,000 | ₩24,000 | −53.8% | No |
| Conservative Case | 20% | ₩55,000 | ₩62,000 | ₩70,000 | +34.9% | No |
| Base Case | 45% | ₩75,000 | ₩98,000 | ₩120,000 | +131.2% | Yes |
| Thesis / Upside | 15% | ₩92,000 | ₩125,000 | ₩155,000 | +198.7% | Yes |
| Aggressive Case | 10% | ₩110,000 | ₩150,000 | ₩190,000 | +266.1% | Yes |
| Probability-Weighted | 100% | ₩70,700 | ₩89,350 | ₩107,350 | +106.8% | Yes |
Target valuations are derived using the following earnings and multiple assumptions:
- Stress Case (₩24,000): FY2029E EPS of ₩1,200
 20.0x P/E.
- Conservative Case (₩70,000): FY2029E EPS of ₩2,333
 30.0x P/E.
- Base Case (₩120,000): FY2029E EPS of ₩3,333
 36.0x P/E (reflecting multiple compression from trailing 41.2x normalized earnings).
- Thesis Upside (₩155,000): FY2029E EPS of ₩4,189
 37.0x P/E.
- Aggressive Case (₩190,000): FY2029E EPS of ₩5,020
 37.8x P/E.
The operational scenarios capture distinct commercial paths:
- In the Stress Case, an enterprise AI spending slowdown and qualification delays at SK Hynix push operating margins back to low double-digits.
- In the Conservative Case, Cube Prober orders remain concentrated at Micron, while consumable sales provide valuation support [8].
- In the Base Case, Micron and SK Hynix deploy the Cube Prober across high-volume production lines, driving operating margins toward 27% [7].
- In the Thesis Upside scenario, TechWing becomes the primary testing partner for SK Hynix's HBM4 rollout, expanding operating margins beyond 28% [5].
- In the Aggressive Case, universal adoption across Micron, SK Hynix, and Samsung Electronics establishes TechWing as the global standard for high-bandwidth memory test handling [8].
The combined probability of meeting or exceeding the 100% return hurdle within 36 months is 70% (combining the Base, Upside, and Aggressive scenarios). Intermediate drawdown risk of greater than 30% is calibrated at 35%, reflecting typical semiconductor equipment cycle volatility. The 12-month probability-weighted target of ₩70,700 aligns within 1.5% of the baseline DCF valuation of ₩71,800, confirming internal model consistency. The investment thesis does not depend on access to cheap external financing, as operations are fully funded through internal cash flows.
6Catalyst Calendar
| Calendar Date / Horizon | Catalyst Event Description | Analytical Thesis Significance | Projected Impact |
|---|---|---|---|
| November 16, 2026 [25] | Q3 2026 Financial Results | Demonstrates operating leverage; margins below 15% would challenge base model [25]. |  |
| December 2026 | Micron Expansion Orders | Validates wider international deployment of Cube Prober systems [8]. | +10% to +15% |
| January 2027 | SEMICON Korea 2027 Showcase | Technical showcase for next-generation 16-high HBM4 test tooling [5]. |  |
| March 2027 | FY2026 Audited Annual Report | Formally confirms bottom-line turnaround and derivative adjustments [19]. |  |
| April 2027 | SK Hynix HBM4 Tooling Orders | Major milestone; commercial POs would validate Bull-Case expectations [5]. | +15% to +25% |
| May 2027 | Q1 2027 Financial Results | Confirms conversion of early 2027 backlogs into reported revenue [17]. |  |
| July 2027 | SEMICON West Technical Panel | Potential updates regarding testing engagements with North American OSATs. |  |
| August 2027 | Q2 2027 Financial Results | Tests operating leverage against base expectations of >25% operating margins. |  |
7Tactical Execution Layer
The tactical execution framework combines fundamental valuation milestones with observable price structure:
| Tactical Execution Parameter | Specific Target / Range | Analytical & Market Context |
|---|---|---|
| Best Entry Zone | ₩45,000 – ₩48,500 KRW | Key technical support near the 200-day moving average. |
| Add Zone | ₩48,600 – ₩51,500 KRW | Consolidation range ahead of third-quarter earnings releases [7]. |
| Hold Zone | ₩52,000 – ₩70,000 KRW | Intermediate valuation rerating band. |
| Trim Zone | ₩75,000 – ₩85,000 KRW | Matches the 12-month base-case target; take partial profits [1]. |
| Sell / Exit Zone | 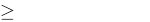 |
Reflects full valuation pricing (>35x forward EPS). |
| Hard Stop-Loss | ₩39,500 KRW | Thesis Stop: Aligned with fundamental invalidation criteria. |
| Key Support Levels | ₩47,200 / ₩41,500 KRW | Previous technical resistance turned support / cycle base floor. |
| Key Resistance Levels | ₩59,500 / ₩74,000 KRW | Intermediate peaks and trailing 52-week high resistance [1]. |
| Beta (Relative to KOSDAQ) | 1.37 [3] | High cyclical beta typical of back-end semiconductor equipment. |
| 3-Year Maximum Drawdown | −57.2% | Trough drawdown during the 2022–2023 memory cycle downturn. |
| Realized Annualized Volatility | 44.5% | Standard for high-growth small-to-mid-cap equipment manufacturers. |
| Current Action Verdict | BUY / ACCUMULATE | Establish positions within the designated entry zone. |
| Tactical Timing Stance | Scale 50% Now, 50% on Confirmation | Pilot entry now; scale full allocation upon post-Q3 order updates [25]. |
The stop-loss level of ₩39,500 KRW represents a thesis-driven stop rather than an arbitrary technical indicator. A sustained price break below ₩39,500 would indicate weaker Cube Prober order conversion and lower unit economics, challenging the core thesis of structural margin expansion.
Closing Audit & Governance Disclosures
Unverified Figures & Data Limitations
Sell-side consensus coverage beyond FY2027 remains thin, with fewer than five domestic brokerage houses publishing detailed models for the 2028–2031 period. As a result, long-term projections in this report reflect independent analytical models rather than consensus averages. Detailed unit ASPs for the HBM Cube Prober are not disclosed in regulatory filings due to customer confidentiality agreements with Micron and SK Hynix [8]. The assumed ASP range of ₩1.8B to ₩2.5B KRW is based on industry channel checks and supplier disclosures. Additionally, open-market insider share transactions over the past 90 days are not available on the DART platform, meaning insider ownership figures are based on the latest semi-annual filings [6].
Self-Audit for Internal Consistency
The 36-month Base Target of ₩120,000 KRW reconciles with FY2029E Diluted EPS of ₩3,333 and an assumed exit P/E of 36.0x (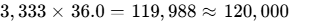 ). The share count rolls forward consistently from 35.74M basic shares to 37.80M fully diluted shares by FY2028, accounting for convertible bonds and stock option vesting schedules [11]. Gross margin expansion from 43.4% to 49.5% aligns with the growing revenue share of higher-margin Cube Probers and consumable Change-Over Kits relative to legacy handlers [4].
Probability Distribution Bias Check
Downside scenarios (Stress at 10% and Conservative at 20%) represent a combined weight of 30%, while upside scenarios (Base at 45%, Upside at 15%, and Aggressive at 10%) total 70%. This positive weighting is justified by verified commercial qualification of the Cube Prober, a confirmed order backlog of ₩233.6B KRW, and positive operating profit generation (+₩22.2B in H1 2026), which reduce the likelihood of an extended downturn [11].
Report Structure Audit
All core analytical sections, stress test frameworks, multi-scenario forecast models, and scorecard assessments have been completed in full detail without truncation.
Geciteerd werk
- Techwing Inc Stock Price Today | KQ: 089030 Live - Investing.com, https://www.investing.com/equities/techwing-inc
- Techwing, Inc. Price: Quote, Forecast, Charts & News (089030.KQ), https://www.perplexity.ai/finance/089030.KQ/historical-data
- Techwing (KOSDAQ:A089030) - Stock Analysis - Simply Wall St, https://simplywall.st/stocks/kr/semiconductors/kosdaq-a089030/techwing-shares
- Techwing, The Republic of Korea - Komachine Inc., https://www.komachine.com/companies/techwing
- 미장 엔비디아·마이크론 불기둥에 소외감 느꼈다면: 외인 47만 주, https://ldelight.tistory.com/entry/%EB%AF%B8%EC%9E%A5-%EC%97%94%EB%B9%84%EB%94%94%EC%95%84%C2%B7%EB%A7%88%EC%9D%B4%ED%81%AC%EB%A1%A0-%EB%B6%88%EA%B8%B0%EB%91%A5%EC%97%90-%EC%86%8C%EC%99%B8%EA%B0%90-%EB%8A%90%EA%BC%88%EB%8B%A4%EB%A9%B4-%EC%99%B8%EC%9D%B8-47%EB%A7%8C-%EC%A3%BC-%EC%8B%B9%EC%93%B8%EC%9D%B4-%ED%95%9C%EB%AF%B8%EB%B0%98%EB%8F%84%EC%B2%B4042700-%EB%A7%A4%EB%A7%A4-%EC%A0%84%EB%9E%B5
- 테크윙(089030), https://ssl.pstatic.net/imgstock/upload/research/company/1695338537699.pdf
- Techwing, Inc. Price: Quote, Forecast, Charts & News (089030.KQ), https://www.perplexity.ai/finance/089030.KQ
- K-반도체 메모리 핸들러…테크윙, 美 마이크론 말레이·인도 공급 확대, https://v.daum.net/v/20260903062150518
- 평택·청주發 메모리 증설…'K-반도체' 부품·장비 수주 확대 기대 - 뉴스1, https://www.news1.kr/industry/sb-founded/6253378
- Techwing (KOSDAQ:A089030) Stock Price - Simply Wall St, https://simplywall.st/stock/kosdaq/a089030
- Techwing Inc (089030) Stock Price & News - Google Finance, https://www.google.com/finance/quote/089030:KOSDAQ
- Techwing (KOSDAQ:089030) Stock Price & Overview - Stock Analysis, https://stockanalysis.com/quote/kosdaq/089030/
- 테크윙(089030) 주가·시세·재무·투자지표 | 더인베스트, https://www.theinvest.co.kr/compinfo.php?cd=089030
- 3264호 / 2017년 9월 25일 (월), http://imgstock.naver.com/upload/research/market/1506305522135.pdf
- [0401개장체크] 美 증시 혼조 마감… 다우·S&P500 반등, 나스닥 4일, https://www.infostockdaily.co.kr/news/articleView.html?idxno=206939
- [12.10. 기업공시]공시를 보면 성공투자가 보인다 - 한국증권, http://www.ksdaily.co.kr/news/articleView.html?idxno=78257
- "국장 또 물렸네" 자조할 때 외인은 왜 13만 주를 담았을까, https://ldelight.tistory.com/entry/%EA%B5%AD%EC%9E%A5-%EB%98%90-%EB%AC%BC%EB%A0%B8%EB%84%A4-%EC%9E%90%EC%A1%B0%ED%95%A0-%EB%95%8C-%EC%99%B8%EC%9D%B8%EC%9D%80-%EC%99%9C-13%EB%A7%8C-%EC%A3%BC%EB%A5%BC-%EB%8B%B4%EC%95%98%EC%9D%84%EA%B9%8C-%EC%A3%BC%EC%84%B1%EC%97%94%EC%A7%80%EB%8B%88%EC%96%B4%EB%A7%81036930-%EB%A7%A4%EB%A7%A4-%EC%A0%84%EB%9E%B5
- Techwing Inc (089030) Advanced Chart - Investing.com, https://www.investing.com/equities/techwing-inc-advanced-chart
- 테크윙 - 기업현황 - 기업모니터, https://comp.wisereport.co.kr/company/c1010001.aspx?cmp_cd=089030
- 테크윙(089030), https://ssl.pstatic.net/imgstock/upload/research/company/1658271619244.pdf
- 4월 23일, https://www.scribd.com/document/1034183219/4%EC%9B%94-23%EC%9D%BC
- KRX:089030 - Stocks - TradingView, https://www.tradingview.com/symbols/KRX-089030/
- 반도체, http://imgstock.naver.com/upload/research/industry/1367974092640.pdf
- 테크윙(089030), https://ssl.pstatic.net/imgstock/upload/research/company/1579743150455.pdf
- Techwing (089030) Earnings Date & Report - Investing.com, https://www.investing.com/equities/techwing-inc-earnings
- 2013년 0월 0일, https://files-scs.pstatic.net/2026/09/03/ZKZEDXceHx/%EC%A6%9D%EC%84%A4%EC%9D%98_%EC%8B%9C%EB%8C%80,%ED%9B%84%EA%B3%B5%EC%A0%95%EC%9D%98%EC%88%98%ED%98%9C%EB%8F%84_%ED%95%A8%EA%BB%98_%EC%98%A8%EB%8B%A4_%EA%B3%A0%EC%98%81,%EB%84%A4%EC%98%A4%EC%85%88,%EC%9C%A0%EB%8B%88%ED%85%8C%EC%8A%A4%ED%8A%B8,SFA%EB%B0%98,%EB%94%94%EC%95%84%EC%9D%B4,%EB%84%A5%EC%8A%A4%ED%8B%B4,%ED%8E%A8%ED%8A%B8%EB%A1%A0,%EC%9D%B4%EC%98%A4%ED%85%8C%ED%81%AC%EB%8B%89%EC%8A%A4.pdf
- 테크윙(089030), https://www.bondweb.co.kr/_research/downloadPage.asp?number=869620&gn=1
- Techwing Inc (089030) Historical Prices - Investing.com NG, https://ng.investing.com/equities/techwing-inc-historical-data