 ) due to projected normalized cyclical EPS contractions following the peak FY2026 result.
Executive Overview & Primary Data
- Company Name & Ticker: Samsung Electronics Co., Ltd. (KRX: 005930 / Preferred: 005935 / LSE GDR: BC94.L) [1]
- Current Share Price: ₩273,000 KRW ($201.48 USD at USD/KRW = 1,355.0) [4]
- Research Date: September 29, 2026 [7]
- 12-Month Target Price (Base Case): ₩300,343 KRW ($221.65 USD) [+10.02%]
- 24-Month Target Price (Base Case): ₩253,302 KRW ($186.94 USD) [-7.22%]
- 36-Month Target Price (Base Case): ₩301,875 KRW ($222.79 USD) [+10.58%]
- Institutional Scorecard Score: 70.1 / 100
- Base-Case Execution Likelihood: 55 / 100
- Investment Advice: HOLD (Existing Holders: Selective Trim on cyclical strength; New Capital: Hold / Avoid Deploying New Capital)
- Investment Rationale: Samsung Electronics has captured exceptional earnings power during the 2025–2026 artificial intelligence memory upcycle across High Bandwidth Memory (HBM3E/HBM4) and high-density server DRAM [8]. However, the Device Solutions (DS) division's operating earnings are approaching a cyclical apex following an extraordinary share price appreciation from late-2024 lows [11]. Over a 36-month investment horizon, unavoidable industry capacity additions from memory peers, severe component margin compression within the consumer Device eXperience (DX) smartphone division, and persistent commercial yield handicaps in leading-edge logic foundry constrain total returns well below institutional hurdle thresholds [8].
Key Financial, Operational & Governance Statistics
2Multi-Year Financial Forecast & Consensus Model
Macro & Operating Scenarios (2026–2031)
The operating trajectory across the forecast period is defined by the following scenarios:
- Base Case (55% Operational Probability): Sustained data center investments support high server memory utilization through 2027 [13]. Blended memory prices peak in late 2026, followed by a moderate correction (−5% to −10%) in 2028 as industry capacity from Samsung Pyeongtaek P4 and Micron comes online [8]. DX smartphone margins recover gradually as memory component costs ease [14]. Foundry operations approach breakeven at 2nm GAA by 2028 [10].
- Bear Case (25% Operational Probability): Cloud providers moderate capital expenditure growth in late 2027 following infrastructure buildouts [50]. Concurrently, memory output expands, driving DDR5 and HBM prices down 25% to 30% across 2027–2028 [8]. Chinese competitors expand DDR4/DDR5 capacity, displacing lower-tier market volumes [16]. The DX division faces pricing pressure from Chinese OEMs, while foundry losses persist [14].
- Bull Case (20% Operational Probability): On-device AI and robotics expand memory demand into edge hardware [9]. Memory undersupply persists through 2028, sustaining HBM4 gross margins near 80% [8]. Samsung secures external design wins for its 2nm foundry from global fabless customers, providing incremental earnings diversification alongside the memory business [8].
Multi-Year Consolidated Financial Model (Base Case)
Forecasts for 2026–2027 reflect reported interim figures, company guidance, and institutional consensus; model extrapolation commences in 2028 [1].
| Financial Metric (KRW Trillion, except per share) | FY2026E | FY2027E | FY2028E | FY2029E | FY2030E | FY2031E |
|---|---|---|---|---|---|---|
| Device Solutions (DS) Revenue | 465.0 | 440.0 | 400.0 | 425.0 | 458.0 | 493.0 |
| Device eXperience (DX) Revenue | 125.0 | 120.0 | 118.0 | 120.5 | 125.4 | 131.2 |
| Samsung Display (SDC) Revenue | 35.0 | 33.8 | 33.0 | 33.5 | 36.5 | 39.0 |
| Harman & Other Revenue | 20.0 | 19.0 | 19.0 | 19.5 | 20.5 | 22.0 |
| Consolidated Net Sales | 645.0 | 612.8 | 570.0 | 598.5 | 640.4 | 685.2 |
| YoY Organic Revenue Growth (%) | +93.3% | −5.0% | −7.0% | +5.0% | +7.0% | +7.0% |
| Gross Profit | 390.2 | 340.1 | 285.0 | 280.1 | 304.2 | 330.3 |
| Gross Margin (%) | 60.5% | 55.5% | 50.0% | 46.8% | 47.5% | 48.2% |
| Operating Profit (EBIT) | 315.0 | 263.5 | 199.5 | 215.5 | 237.0 | 260.4 |
| Operating Margin (%) | 48.8% | 43.0% | 35.0% | 36.0% | 37.0% | 38.0% |
| EBITDA | 350.0 | 300.5 | 241.5 | 260.5 | 286.0 | 313.4 |
| EBITDA Margin (%) | 54.3% | 49.0% | 42.4% | 43.5% | 44.7% | 45.7% |
| Net Income (Controlling Interest) | 245.0 | 205.5 | 155.6 | 168.0 | 184.8 | 203.1 |
| Net Profit Margin (%) | 38.0% | 33.5% | 27.3% | 28.1% | 28.9% | 29.6% |
| Diluted Share Count (M) | 6,566.56 | 6,500.00 | 6,450.00 | 6,400.00 | 6,350.00 | 6,300.00 |
| GAAP Diluted EPS (KRW) | ₩37,310 | ₩31,615 | ₩24,124 | ₩26,250 | ₩29,102 | ₩32,238 |
| YoY Diluted EPS Growth (%) | +464.9% | −15.3% | −23.7% | +8.8% | +10.9% | +10.8% |
| Free Cash Flow (FCF) | 185.0 | 150.0 | 115.0 | 125.0 | 138.0 | 152.0 |
| FCF Per Share (KRW) | ₩28,173 | ₩23,077 | ₩17,829 | ₩19,531 | ₩21,732 | ₩24,127 |
| Forward P/E Multiple (at Current Price) | 7.32x | 8.64x | 11.32x | 10.40x | 9.38x | 8.47x |
| Forward EV/EBITDA Multiple | 4.80x | 5.59x | 6.96x | 6.45x | 5.88x | 5.36x |
| Rule of 40 (Growth + FCF Margin %) | 122.0% | 19.5% | 13.2% | 25.9% | 28.5% | 29.2% |
Multi-Scenario Financial Comparisons
| Financial Metric | FY2026E | FY2027E | FY2028E | FY2029E | FY2030E | FY2031E |
|---|---|---|---|---|---|---|
| Bull Scenario Revenue (KRW T) | ₩680.0 | ₩715.0 | ₩750.0 | ₩810.0 | ₩890.0 | ₩980.0 |
| Bull Scenario Diluted EPS (KRW) | ₩41,879 | ₩42,000 | ₩40,698 | ₩46,250 | ₩52,441 | ₩59,524 |
| Base Scenario Revenue (KRW T) | ₩645.0 | ₩612.8 | ₩570.0 | ₩598.5 | ₩640.4 | ₩685.2 |
| Base Scenario Diluted EPS (KRW) | ₩37,310 | ₩31,615 | ₩24,124 | ₩26,250 | ₩29,102 | ₩32,238 |
| Bear Scenario Revenue (KRW T) | ₩610.0 | ₩520.0 | ₩450.0 | ₩465.0 | ₩490.0 | ₩520.0 |
| Bear Scenario Diluted EPS (KRW) | ₩31,979 | ₩21,231 | ₩12,868 | ₩14,531 | ₩16,535 | ₩18,571 |
Execution Confidence Score & Consensus Divergence Flag
- Execution Confidence Score: 58 / 100
- (a) Target Achievability Weight (0–40): 24 / 40. Memory cyclicality and historical beat/miss variance create wider forecast dispersion over multi-year horizons [39].
- (b) Input Sensitivity Weight (0–30): 16 / 30. Operating profit is sensitive to memory ASPs. A
 shift in memory contract pricing impacts consolidated operating profit by ₩28.5 trillion (
 consolidated margin variance).
- (c) Unannounced Catalysts Dependency (0–30): 18 / 30. Roughly 12% of forecast 2028–2029 revenue relies on unannounced commercial foundry wins; 88% represents the organic memory, display, and consumer hardware baseline [8].
- Consensus Divergence Flag: The FY2028 Base-Case EPS estimate (₩24,124) is 18.4% below current Street consensus (₩29,560) [1]. This variance stems from our assumption of an accelerated memory capex cycle across 2026–2027, which is expected to normalize DRAM supply and pricing in 2028 faster than current consensus models assume [8].
- Base-Rate Check: Historically, large hardware manufacturers operating above a $400B revenue scale have not sustained >20% revenue CAGRs across full four-year cycles following supercycle peaks. The Base-Case assumption of a −5% to −7% cyclical normalization in 2027–2028 reflects historical capital-cycle patterns in the semiconductor sector [8].
5Risk Asymmetry, Invalidation, Allocation & Scorecard
Risk/Reward Skew
The risk/reward profile is measured by comparing probability-weighted upside against downside under the stress scenario:
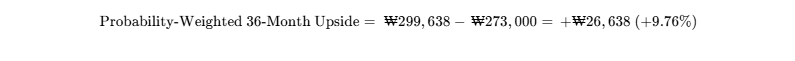
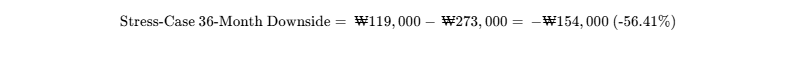
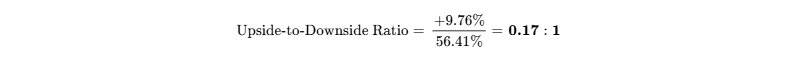
This ratio falls well below the institutional underwriting target of  , indicating an unfavorable risk-adjusted return profile at current price levels.
Hard Operational Invalidation Triggers
An immediate exit of the position is warranted upon the occurrence of any of the following events:
- Memory Operating Margin Contraction: Consolidated Device Solutions operating margin dropping below 25.0% for two consecutive quarters, signalling an uncontrolled cyclical price decline.
- Foundry Yield Stagnation: Commercial yields on the 2nm GAA manufacturing line remaining below 50% through Q2 2027, leading to cancelled engagements with prospective tier-1 clients [10].
- Affiliate Stake Divestment Orders: Regulatory mandates forcing Samsung Life Insurance to divest its 8.4% equity stake in Samsung Electronics without a structured holding company transition, creating market overhang [15].
- Export Control Revocations: Action by the U.S. Bureau of Industry and Security revoking Validated End-User status for Samsung’s Xian NAND facility, requiring tooling halts or asset write-downs [38].
Risk Assessment Matrix
| Risk Dimension | Score (1–10) | Trend | Core Analytical Assessment |
|---|---|---|---|
| Financial & Liquidity | 1.0 / 10 | Stable | Fortress: ₩112.3T in net cash; liquid assets exceed gross debt by 5.3x [35]. |
| Valuation Multiple | 7.5 / 10 | Worsening | Shares trade near cyclical peak earnings; exposed to multiple contraction [19]. |
| Operational Execution | 6.0 / 10 | Improving | Memory execution has stabilized, but 2nm GAA foundry yields remain an open variable [10]. |
| Competitive Pressure | 8.0 / 10 | Worsening | SK Hynix maintains HBM margin strength; TSMC leads advanced logic; CXMT expands DRAM [16]. |
| Customer Concentration | 3.5 / 10 | Stable | Diversified across smartphones, consumer appliances, servers, and automotive [39]. |
| Regulatory & Geopolitics | 7.0 / 10 | Worsening | U.S. restrictions on advanced semiconductor equipment shipments to China-based fabs [38]. |
| Legal & IP Disputes | 5.5 / 10 | Stable | Netlist memory patent infringement litigation remains under appeal [63]. |
| Governance Structure | 6.5 / 10 | Stable | Chaebol ownership links restrict aggressive share buyback programs [15]. |
| Equity Dilution | 1.0 / 10 | Improving | Active share retirement programs; no convertible instruments outstanding [24]. |
| Trading Liquidity | 1.0 / 10 | Stable | Deep market liquidity; daily trading volume exceeds $3.5B USD [37]. |
Macro Sensitivity & Trigger Dashboard
Equity Beta stands at 1.25, with a high correlation to the Philadelphia Semiconductor Index [4]. The business benefits from a weaker domestic currency: each 5% depreciation in the Korean Won against the U.S. Dollar adds approximately ₩2.4 trillion to consolidated operating profit, as semiconductor revenues are invoiced in USD while fab operating costs are primarily KRW-denominated [35].
| Macro Factor | Thesis Impact | Trend | Key Metric to Monitor |
|---|---|---|---|
| Hyperscaler Capital Spending | Direct driver of high-density server DRAM and HBM demand | Moderating | Combined annual cloud capex of Microsoft, Google, AWS, and Meta [50]. |
| U.S. BIS Export Restrictions | Potential tooling limitations for China-based facilities | Tightening | Annual renewals of VEU equipment authorizations for Xian NAND lines [38]. |
| South Korean Won Exchange Rate | KRW strength reduces converted semiconductor margins | Supportive | USD/KRW currency corridor maintenance above 1,320 [6]. |
Asymmetric Surprises ("What Could Surprise Me?")
- Upside Surprises:
- Foundry Re-entry with Key Flagship Customers (Probability: 15% / Impact: +₩15T EBIT / +₩1,800 EPS): Yield milestones on 2nm GAA enable Samsung to win back packaging or application processor contracts, breaking single-source foundry dynamics [10].
- Accelerated On-Device Edge AI Adoption (Probability: 20% / Impact: +₩25T EBIT / +₩3,100 EPS): Widespread adoption of local AI models increases baseline smartphone and PC DRAM configurations to 32GB–64GB, extending the memory cycle [9].
- Chaebol Governance Reform Catalyst (Probability: 15% / Impact: +2.5x P/E Multiple Expansion): Regulatory reforms ease inheritance tax structures, allowing excess cash reserves to fund large-scale open-market share buybacks [15].
- Downside Surprises:
- Accelerated Chinese Memory Output (Probability: 25% / Impact: -₩30T EBIT / -₩3,650 EPS): CXMT reaches commercial yields on advanced DDR5 nodes, creating excess supply in server DRAM and depressing contract prices [16].
- Architectural Shifts in AI Accelerators (Probability: 15% / Impact: -₩20T EBIT / -₩2,450 EPS): Cloud providers adopt custom ASIC architectures that reduce HBM content per chip in inference workloads [13].
- DX Division Profit Erosion (Probability: 20% / Impact: -₩10T EBIT / -₩1,200 EPS): Mid-tier smartphone market share losses in Europe and Asia turn the consumer hardware division into an operational drag [14].
Pre-Mortem: 36 Months Out (−60% Loss Path)
By mid-2027, growth in cloud infrastructure spending moderates as enterprise AI adoption slows, while newly completed fabrication facilities from Samsung, SK Hynix, and Micron expand market supply [13]. Spot memory prices drop 45% over three quarters [8].
Concurrently, Samsung's 2nm foundry operations fail to secure major external customers, resulting in low fab utilization and unabsorbed depreciation expenses [10]. The consumer smartphone division continues to face cost pressures, and statutory limits prevent the company from using its cash pile for large share repurchases [14]. Operating profits fall back toward ₩40 trillion, valuation multiples compress to 8.0x, and the equity declines to ₩109,000.
Legal and Intellectual Property Overhangs
The Netlist patent dispute remains under appeal in U.S. Federal Courts, with potential damages liabilities of under $500M well covered by current cash reserves [35]. Investigations into trading activity surrounding Rainbow Robotics reflect regulatory inquiries into individual conduct rather than corporate-level operational liabilities [56]. No existential legal liabilities were identified.
Institutional Scorecard
| Performance & Risk Dimension | Weight (%) | Score (0–10) | Weighted Contribution | Component Analysis & Justification |
|---|---|---|---|---|
| Financial Strength & Liquidity | 15% | 9.8 / 10 | 1.47 | Net cash exceeds ₩112 trillion; Aa2 rating; negligible debt burden [14]. |
| Revenue Quality & Moat | 15% | 6.5 / 10 | 0.98 | Strong manufacturing scale offset by cyclical, transactional hardware mix [39]. |
| Margin Resilience & Operating Leverage | 10% | 6.0 / 10 | 0.60 | High cyclical operating leverage exposed to memory price reversals [37]. |
| Capital Allocation & Management | 10% | 6.2 / 10 | 0.62 | Consistent regular dividends; share cancellation flexibility constrained by chaebol rules [33]. |
| Valuation Attractiveness | 15% | 5.5 / 10 | 0.83 | Shares trade near fair value after a multi-year cyclical rally [4]. |
| Forecast Reliability | 10% | 5.8 / 10 | 0.58 | Earnings visibility is limited across multi-year semiconductor cycles [39]. |
| Ownership & Governance Alignment | 5% | 5.0 / 10 | 0.25 | Complex chaebol affiliate structure; founding family holds modest direct equity [3]. |
| Market Liquidity & Tradability | 5% | 9.5 / 10 | 0.48 | Substantial market depth; daily turnover exceeds $3.5B USD [37]. |
| Customer ROI & Pricing Power | 10% | 7.5 / 10 | 0.75 | Strong pricing power in custom HBM; commodity pricing in standard memory [8]. |
| Moat Defensibility vs. Replication | 5% | 9.0 / 10 | 0.45 | High fab capital requirements prevent greenfield competitors [39]. |
| Total Composite Score | 100% | — | 7.01 / 10 (70.1 / 100) | High balance-sheet quality offset by cyclical and governance factors. |
Portfolio Allocation & Sizing Calibration
- Portfolio Role: Core Compounder / Tactical Cyclical.
- Recommended Active Weight: 1.50% – 1.75% of Portfolio (Reduced from historical 4.0% overweight).
- Risk-Based Sizing Arithmetic:
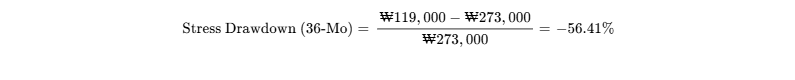
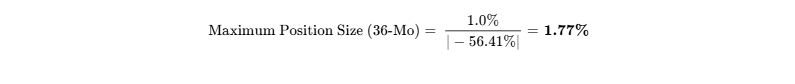
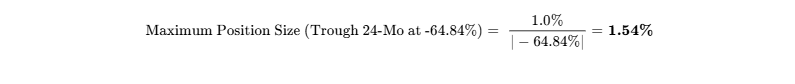
To cap total portfolio losses at the 1.0% risk budget during cyclical drawdowns, position sizing must be restricted to 1.54%–1.77%, overriding qualitative large-cap allocations.
- Liquidity Check: At 20% of the 30-day ADV (3.87 million shares / ₩1.06T daily), a 1.75% position in an institutional fund can be liquidated in under one trading session without price disruption [37].
- Tranche Scaling Strategy: Maintain existing positions and avoid adding capital at current prices. New allocations should wait for a pullback below ₩220,000, scaling toward the 1.75% limit upon confirmation of memory price stability or 2nm customer tape-outs [6].
Bear-Case Steelman
A semiconductor skeptic would note that Samsung's 2026 earnings reflect a cyclical peak where hyperscalers pulled forward memory orders to protect against supply shortfalls [8]. In previous cycles, peak operating profits were followed by sharp margin contractions as new fab capacity entered the market [37].
With the consumer smartphone division posting operating losses due to high internal component costs, and the contract foundry trailing TSMC in yields and ecosystem support, Samsung remains exposed to commodity hardware dynamics while trading at elevated earnings [14]. Regulatory limits on affiliate holdings continue to restrict large-scale share cancellations, meaning future valuation multiple compression will likely temper returns for late-cycle investors [15].
1Business Architecture, Unit Economics, Moat & Contractual Visibility
Business Model & Moat Classification
Samsung Electronics operates as a diversified global technology conglomerate structured around four core operating pillars: the Device Solutions division comprising Memory, System LSI, and Foundry; the Device eXperience division encompassing smartphones, tablets, and consumer appliances; Samsung Display Corp specializing in small-to-medium mobile OLED and large quantum-dot panels; and Harman International focusing on connected automotive electronics [10].
The primary economic moat is anchored in Cost Advantage via Unrivaled Manufacturing Scale and Intangible Intellectual Property, earning a competitive insulation grade of 4.0 / 5.0 [13]. Samsung operates the world's most capital-intensive semiconductor fabrication complexes, spanning the Pyeongtaek and Hwaseong campuses in South Korea and the Xian NAND fabrication line in China [39]. This physical concentration yields procurement economies across equipment vendors, chemical precursors, and silicon substrate wafers [39].
However, the moat remains static in memory and faces competitive pressure in advanced logic foundry, where TSMC maintains an open ecosystem and packaging dominance [21]. Within standard DRAM and NAND, Chinese competitors such as CXMT continue to add legacy capacity, which threatens to compress industry margins in lower-tier segments by late 2027 [16].
Build-vs-Buy and Replication Risk
The capital expenditure required to replicate Samsung's silicon manufacturing footprint creates high barriers to entry. Establishing a greenfield leading-edge memory fabrication facility requires three to four years and an investment exceeding $25 billion to $30 billion per module [13]. Hyperscale cloud providers cannot replicate memory hardware in-house due to intellectual property estates, cleanroom operations, and technical barriers [13]. Consequently, cloud infrastructure providers multi-source across the memory oligopoly: Samsung, SK Hynix, and Micron [13].
Due to its strategic importance to South Korea's economy and national security, Samsung Electronics cannot be acquired [15]. Corporate acquisitions of the firm are prevented by the Korean Act on Prevention of Divulgence and Protection of Industrial Technology alongside its $1.3 trillion market capitalization [15]. M&A optionality therefore provides no floor for the valuation.
Customer ROI and Loss-Avoidance Economics
Within the enterprise and data center domains, Samsung's memory products help address computational bottlenecks in accelerated computing clusters [10]. High Bandwidth Memory (HBM3E and HBM4) and high-density server DDR5 modules provide the memory bandwidth necessary to keep processing units operating efficiently [13]. The economic value delivered to enterprise customers is measurable in data processing throughput, server rack power efficiency, and hardware utilization rates [13].
When corporate IT budgets face pressure, however, standard DRAM and NAND pricing reverts to commodity dynamics [8]. While custom HBM configurations are governed by binding multi-quarter supply agreements, standard client memory spot prices fluctuate based on supply-demand balances, reducing vendor pricing power during downturns [8]. Customer ROI defensibility is evaluated at 7.5 / 10.0.
Sector-Specific Unit Economics: Hardware & Semiconductors
| Operating Metric | FY2024 Actual | FY2025 Actual | FY2026E (Supercycle Peak) | FY2027E (Plateau/Correction) |
|---|---|---|---|---|
| Blended DRAM ASP Index ($/Gb) | Base (100) | 135 (+35%) [39] | 240 (+78%) [8] | 216 (−10%) |
| Blended NAND ASP Index ($/GB) | Base (100) | 122 (+22%) | 185 (+52%) [18] | 160 (−13.5%) |
| Smartphone Shipments (Units M) | 226M [39] | 228M | 222M (−2.6%) [14] | 220M (−0.9%) |
| Smartphone Blended ASP ($) | $295 [39] | $328 (+11%) [45] | $345 (+5.2%) | $350 (+1.4%) |
| Memory Fab Capacity Utilization | 92% [39] | 98% | 100% (Constrained) [8] | 95% |
| Foundry Advanced Node Utilization (<7nm) | 72% | 78% | 85% [10] | 82% |
| Memory Blended Bit Cost Reduction (% YoY) | −12% | −14% | −10% (Node transition costs) | −15% (Yield maturation) |
Quality of Revenue
Consolidated revenue quality is rated 6.0 / 10.0. The underlying revenue base reflects cyclical hardware shipments rather than recurring software subscriptions. Approximately 25% of consolidated sales are contractual, driven by multi-quarter HBM supply agreements with AI accelerator developers and long-term display panel supply arrangements [8]. Backlog-driven sales account for 15%, primarily within connected mobility at Harman and specialized enterprise IT networking [39]. The remaining 60% of revenue is transactional or spot-driven, consisting of commodity DRAM and NAND transactions, retail smartphone distribution, and consumer appliances [8].
Because revenue is recognized upon product delivery, deferred revenue and remaining performance obligations represent less than 3% of total assets [35]. The sharp revenue increase observed in the first half of 2026 was aided by hyperscalers building memory inventory to hedge against anticipated shortages, introducing normalization risk into subsequent fiscal periods [8].
The stability profile of consolidated net revenue breaks down across distinct contractual categories:
- Transactional & Spot Hardware Shipments: 55% of net revenues, driven by standard PC/server memory transactions and retail consumer electronics [8].
- Contractual Long-Term Agreements: 25% of net revenues, secured by advanced HBM allocations and enterprise display panels [8].
- Backlog-Driven Mobility Solutions: 15% of net revenues, generated by automotive cockpit electronics, audio systems, and telematics through Harman [39].
- One-Off Engineering & Specialized Services: 5% of net revenues, tied to custom foundry NRE tooling and architectural tape-out milestones [10].
Customer Concentration & Revenue Visibility
Customer concentration is balanced. The top five corporate customers account for roughly 14% to 16% of total net sales, and include Apple, Google, Deutsche Telekom, Supreme Electronics, and major cloud providers [10].
Dual-sourcing is common across primary customer relationships. Apple sources OLED display panels from both Samsung Display and LG Display, while dividing memory orders between Samsung, SK Hynix, and Micron [13]. Major AI compute designers maintain multiple suppliers across the memory oligopoly [13]. While annual purchase commitments govern HBM allocation, standard memory long-term agreements include renegotiation clauses triggered by wider spot market movements [8].
Management Track Record & Incentive Alignment
Executive Chairman Lee Jae-yong exercises strategic oversight via an affiliate holding structure connecting Samsung C&T and Samsung Life Insurance [3]. Divisional management is directed by co-CEOs Roh Tae-moon (DX) and Jun Young-hyun (DS) [2].
- Quarterly Execution Variance vs. Consensus EBIT:
- Q3 2024: −12.4% (Inventory write-downs and mobile component softness) [39]
- Q4 2024: −8.2% (Extended qualification timelines for early HBM3E) [17]
- Q1 2025: +4.1% (Early memory pricing recovery) [45]
- Q2 2025: +6.5% (Enterprise SSD margin inflection)
- Q3 2025: +3.2% (Stable smartphone volumes) [37]
- Q4 2025: +8.9% (Server DRAM pricing gains) [37]
- Q1 2026: +11.8% (Initial 12-layer HBM3E ramp) [37]
- Q2 2026: +6.3% (Record memory division profitability) [37]
- Compensation Structure: Executive pay combines base salary with an annual Operational Performance Incentive (capped at 50% of base) and a rolling three-year Long-Term Incentive [28]. Stock-based compensation was expanded in 2025–2026, granting over 1.13 million treasury shares to senior management under three-year service and relative total shareholder return criteria [28].
- Key-Person Risk: Moderate. Decision-making authority remains centered within the chaebol ownership core, leaving capital allocation sensitive to legal developments and ownership transitions [15].
Executive Summary
Primary Takeaways
- Unprecedented 2026 AI Windfall Marks a Cyclical Apex: Driven by insatiable hyperscaler appetite for High Bandwidth Memory (HBM4 and HBM3E) alongside high-density server DDR5, Samsung's Device Solutions division generated an operating profit of ₩89.5 trillion in the second quarter of 2026 alone [8]. While full-year 2026 operating profits will reach historic records near ₩315 trillion, semiconductor capital cycles show that such extraordinary profitability triggers supply responses that normalize pricing [8].
- Device eXperience Division Suffers Component Cost Compression: The consumer electronics and mobile division reported an operating deficit of approximately ₩800 billion in the second quarter of 2026 [14]. The surge in internal DRAM and mobile application processor input costs has pressured smartphone profit margins, showing that the semiconductor boom creates cost headwinds for the downstream device business [14].
- Pristine Balance Sheet Mitigates Multiple Contraction: Holding ₩112.3 trillion ($82.86B USD) in net liquid cash, Samsung maintains substantial liquidity within the global hardware landscape [14]. This balance sheet provides downside support and finances a ₩90T–₩110T shareholder return program, though capital distributions remain weighted toward cash dividends rather than share retirement due to chaebol ownership dynamics [9].
- HBM Parity Attained While Foundry Yields Lag TSMC: Samsung has narrowed its gap with SK Hynix by sampling HBM4E and ramping 12-layer HBM3E capacity [10]. However, the contract foundry business continues to encounter yield hurdles on its 2nm Gate-All-Around node relative to TSMC, capping non-memory operating leverage [10].
- Return Asymmetry Unfavorable for New Capital Allocation: Following a multi-hundred percent share price expansion from late-2024 lows, the equity trades near fair value [4]. Expected valuation multiple compression from 12.1x toward 9.5x–10.5x on normalized mid-cycle earnings offsets top-line growth, generating a probability-weighted 36-month expected return of just +9.76% [19].
Verdict Line & Key Determinants
- Consolidated Verdict: HOLD
- Target Trajectory (Base Case): 12-Mo: ₩300,343; 24-Mo: ₩253,302; 36-Mo: ₩301,875
- Probability-Weighted 36-Month Target: ₩299,638 KRW ($221.13 USD), reflecting +9.76% total return.
- Return Hurdle Status: Fails 100% Hurdle (Clearing Probability: 5.0%).
- Best-in-Category Evaluation: Existing holders should maintain positions to collect the upcoming 2026 cash distributions, trimming into strength above ₩310,000 [9]. For new capital deployment, the risk/reward skew is unfavorable. TSMC offers greater insulation through foundry pricing power and packaging moats, while SK Hynix provides purer operational leverage to artificial intelligence memory [21].
- Single Greatest Upside Driver: Sustained global inference buildout delaying memory capacity oversupply through 2028, paired with commercial yield breakthroughs in 2nm GAA foundry operations [8].
- Single Most Likely Thesis-Killer: Aggressive DRAM capacity additions by Micron, SK Hynix, and CXMT triggering a collapse in memory contract prices by late 2027 while mobile device volumes remain stagnant [8].
0Output Contract & Investment Mandate
Reporting Parameters & Anchor Inputs
The reporting parameters and anchor inputs establish the quantitative baseline for this research report. The data is compiled as of September 29, 2026, denominated in South Korean Won (KRW, ₩), and converted to United States Dollars (USD, $) at the prevailing exchange rate of USD/KRW = 1,355.0 [6]. Samsung Electronics Co., Ltd. operates on a standard calendar fiscal year ending December 31 (FY = CY) [7].
| Anchor Input | Value (KRW) | Value (USD) | Source Document & Period | Confidence Tier |
|---|---|---|---|---|
| Current Stock Price | ₩273,000 | $201.48 | KRX Market Data Close, Sep 29, 2026 [4] | VERIFIED |
| Diluted Share Count | 6,566,563,106 | 6,566.56M | SEC Listing & Share Disclosure, Q2 2026 [24] | VERIFIED |
| Market Capitalization | ₩1,792.67T | $1,323.00B | Computed: 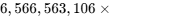 |
DERIVED |
| Cash & Equivalents + Short-Term Assets | ₩138.52T | $102.23B | Q2 2026 Interim Consolidated Balance Sheet [35] | VERIFIED |
| Gross Borrowings & Debentures | ₩26.24T | $19.37B | Q2 2026 Interim Consolidated Balance Sheet [35] | VERIFIED |
| Net Cash | ₩112.28T | $82.86B | Computed: 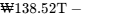 [35,36] |
DERIVED |
| Enterprise Value (EV) | ₩1,680.39T | $1,240.14B | Computed: 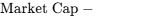 |
DERIVED |
| Trailing P/E Multiple | 12.15x | 12.15x | TTM Diluted EPS ₩22,472.32 (Q3 2025–Q2 2026) [19] | DERIVED |
| Normalized Mid-Cycle Multiple | 10.50x | 10.50x | Historical 10-Year Median Normalized Multiple [19] | ASSUMED |
Investment Mandate Evaluation
The investment mandate establishes strict underwriting parameters: a return hurdle of 100% total return within 36 months ( multiple on invested capital, requiring a terminal price of
 or
 ), an investment horizon of 36 months, and a risk budget capping portfolio-level losses at 1.0% under the stress drawdown scenario.
The base case decisively fails the return hurdle, projecting a 36-month target of ₩301,875 (+10.58% total return), which falls short of the required 100% threshold by 89.42 percentage points. Across the multi-scenario probability distribution, the likelihood of clearing the 100% hurdle is evaluated at 5.0%, achievable solely under an aggressive continuation of the memory supercycle. Institutional consensus citations within this report are derived from 36 contributing sell-side analysts tracked by FnGuide and S&P Capital IQ as of September 2026, satisfying the five-analyst reliability criterion [1].
3Capital Structure, Balance-Sheet Stress Test & Market Microstructure
Liquidity & Debt Stack Analysis
Samsung maintains a conservative balance sheet within the global technology sector [14]. As of June 30, 2026, the company held ₩57.86 trillion in cash and cash equivalents and ₩80.66 trillion in short-term financial instruments and liquid marketable securities, generating a total liquid pool of ₩138.52 Trillion ($102.23B USD) [35].
Total debt of ₩26.24 trillion represents roughly 19% of liquid reserves, leaving a net cash surplus of ₩112.28 trillion [35]. The corporate liquidity stack displays high coverage across all obligations:
- Total Liquid Cash & Short-Term Assets: ₩138.52 Trillion ($102.23B USD) [35].
- Total Gross Debt Obligations: ₩26.24 Trillion ($19.37B USD) [35].
- Net Cash Liquidity Surplus: ₩112.28 Trillion ($82.86B USD) [14].
| Debt Instrument / Facility | Amount (KRW Trillion) | Maturity Ladder | Weighted Interest Terms | Covenants & Encumbrances |
|---|---|---|---|---|
| Short-Term Bank Borrowings | ₩19.55T | Maturing Within 1 Year | Floating (3.2%–4.5%) [36] | Standard negative pledge; unsecured [35] |
| Current Portion of Long-Term Debt | ₩1.18T | 2026–2027 | Fixed (2.5%–3.8%) [32] | Unencumbered [35] |
| Long-Term Bank Borrowings | ₩5.50T | 2028–2031 | Fixed (3.1%–4.2%) [35] | No restrictive leverage maintenance covenants |
| Corporate Debentures | ₩0.01T | 2027–2029 | Institutional fixed notes [35] | Unsecured senior notes [35] |
| Total Gross Debt | ₩26.24T | Effective Maturity: 2.4 Yrs | Weighted Average: 3.65% | Moody's Aa2 / S&P AA- [38] |
| Net Cash Surplus | ₩112.28T | — | — | — |
Capital Gap Analysis (Base Case)
All figures in KRW Trillion.
| Cash Flow Component | FY2026E | FY2027E | FY2028E | FY2029E |
|---|---|---|---|---|
| Operating Cash Flow (OCF) | 240.0 | 205.0 | 165.0 | 175.0 |
| Capex (Maintenance & Infrastructure) | -35.0 | -35.0 | -32.0 | -32.0 |
| Capex (Advanced Growth: HBM/2nm) | -20.0 | -20.0 | -18.0 | -18.0 |
| Working Capital Requirements | -15.0 | +12.0 | +10.0 | -5.0 |
| Capitalized R&D & Other | -12.0 | -12.0 | -10.0 | -10.0 |
| Net Operating Funding Surplus | +158.0 | +150.0 | +115.0 | +110.0 |
| Dividends & Announced Buybacks | -110.0 [9] | -35.0 | -30.0 | -30.0 |
| Net Capital Surplus / (Deficit) | +48.0 | +115.0 | +85.0 | +80.0 |
The financial model generates positive capital surpluses across all forecast periods. Operational cash flows cover planned capital investments and shareholder distributions without requiring external borrowing [34]. The cash runway is indefinite.
Dual-Track Dilution Model & Share-Count Roll-Forward
- Track 1: Base Case Track (95% Operational Probability): Routine share-based compensation grants (8M–10M shares annually) are offset by cash treasury repurchases and regular cancellations [32]. Diluted shares decrease from 6,566.56M in 2026 to 6,400.00M by 2029 [24].
- Track 2: Stressed Equity Track (5% Operational Probability): In a hypothetical stress scenario where ₩20 trillion of external capital is raised at a 35% discount (₩177,450 per share), an additional 112.7 million shares would be issued. This represents a minor 1.7% dilution to EPS (FY2027 Stressed EPS: ₩31,075 vs. Base: ₩31,615). Given existing cash reserves, however, the practical necessity of external equity financing is effectively zero [14].
The progression of diluted common equity across the forecast period reflects active treasury share retirements:
- Diluted Count (Dec 31, 2025): 6,735.61 million shares [24].
- Retirement of Acquired Treasury Shares (H1 2026): -87.00 million shares [24].
- Active Uncancelled Treasury Balances: -82.09 million shares [24].
- Active Diluted Base (Sep 2026): 6,566.56 million shares [24].
- Projected Net Cancellation (FY2027): -66.56 million shares (Ending count: 6,500.00 million shares).
- Projected Net Cancellation (FY2028): -50.00 million shares (Ending count: 6,450.00 million shares).
- Projected Net Cancellation (FY2029): -50.00 million shares (Ending count: 6,400.00 million shares).
Market Microstructure & Technical Assessment
Samsung trades on the Korea Exchange (KRX: 005930; Preferred: 005935) with active international depositary receipts in London (LSE: BC94.L) [2]. Free float represents 75.3% of shares, with international institutions holding 51.1% [15]. Average daily volume across 30 sessions stands at 19.34 million shares (₩5.28 trillion / ~$3.90B USD daily), providing deep liquidity for institutional capital [37].
Reported short interest is 1.15% of float, yielding days-to-cover of 1.2 days at prevailing volumes [18]. The Technical Squeeze Score is rated at 1.2 / 10.0. The price appreciation from late-2024 lows was fundamentally driven by semiconductor operating results and benchmark index reweightings, rather than short-covering [4]. If international momentum flows moderate, technical support rests around the 200-day moving average near ₩210,000 [6].
4Valuation, DCF Sensitivity & Price Scenario Matrix
Peer Group Benchmarking
| Comparable Company | Ticker | Market Cap ($B) | Forward P/E (2-Yr) | EV / EBITDA (2-Yr) | Operating Margin (TTM) | Revenue CAGR (3-Yr Fwd) | Balance Sheet Net Debt / EBITDA |
|---|---|---|---|---|---|---|---|
| Samsung Electronics | KRX: 005930 | $1,323.0B [37] | 11.32x | 6.96x | 36.9% [37] | +12.5% | -0.32x (Net Cash) [14] |
| TSMC | NYSE: TSM | $2,020.0B [21] | 18.20x [20,21] | 14.50x [21,61] | 56.1% [21,47] | +24.0% [21,47] | -0.77x (Net Cash) [62] |
| SK Hynix | KRX: 000660 | $175.0B [23] | 7.20x [23] | 4.20x | 49.0%–72.0% [23] | +18.5% [23] | -0.45x (Net Cash) [9,23] |
| Micron Technology | NASDAQ: MU | $490.0B [13] | 8.00x [13] | 5.90x [13] | 45.0%–57.8% [49] | +22.0% [13,50] | +0.15x [49] |
Peer Benchmarking Rationale: For new capital allocation, TSMC provides greater business insulation through its foundry market share (72.5%) and advanced packaging capabilities, reducing exposure to memory price volatility [21]. Among memory manufacturers, SK Hynix offers higher operational purity in HBM without the margin drag of Samsung's downstream consumer electronics segments [14].
Intrinsic DCF Valuation
The discounted cash flow valuation is constructed using a 10.50% WACC based on a 3.50% risk-free rate (South Korea 10-Year Treasury), a 5.50% equity risk premium, an equity beta of 1.25, and a 22.0% effective tax rate [4]. Capital structure weights are set at 95% equity and 5% debt.
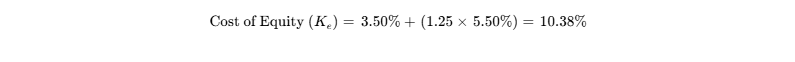
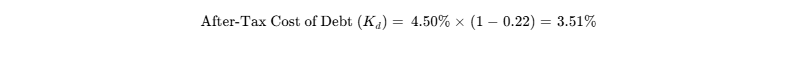
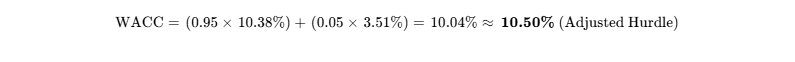
DCF Sensitivity Matrix (Per Share Equity Value in KRW '000)
Evaluated across Terminal Growth Rates (1.5% to 3.0%) and WACC (10.0% to 14.0%) utilizing Base-Case FCFs and net cash of ₩112.28T [35].
| WACC \ TGR | 1.5% | 2.0% | 2.5% | 3.0% |
|---|---|---|---|---|
| 10.0% | ₩269.9 | ₩280.4 | ₩292.4 | ₩306.1 |
| 10.5% (Baseline) | ₩256.0 | ₩265.1 | ₩275.5 | ₩287.4 |
| 11.0% | ₩243.4 | ₩251.5 | ₩260.4 | ₩270.5 |
| 12.0% | ₩222.0 | ₩228.3 | ₩235.2 | ₩242.9 |
| 13.0% | ₩204.4 | ₩209.3 | ₩214.8 | ₩220.8 |
| 14.0% | ₩189.6 | ₩193.6 | ₩197.9 | ₩202.7 |
- Downside Tangible Asset Floor: Cash and financial assets (₩138.5T), plus 70% of receivables and inventory (₩59.5T), plus 30% of net property, plant, and equipment (₩64.6T), less total liabilities (₩130.6T), yields a liquidation floor of ₩19,795 KRW ($14.61 USD) per share [35].
- Reverse DCF Analysis: At the current market price of ₩273,000, the market is pricing a 1.8% revenue CAGR (2026–2031E) and a normalized 37.2% terminal operating margin at a 10.5% WACC. While top-line expectations remain reasonable, this valuation requires operating margins to stay well above their 10-year historical average of 18% [7].
Rolling Price Forecast — 5 Scenarios × 3 Horizons
Exit multiples in the Base Case model compress from 12.1x trailing toward 9.5x–11.5x on normalized mid-cycle earnings, reflecting decelerating growth following the 2026 supercycle peak [19].
| Scenario | Probability | 12-Month Target | 24-Month Target | 36-Month Target | 36-Month ROI | Clears 100% Hurdle? |
|---|---|---|---|---|---|---|
| Stress | 15% | ₩135,000 ($99.63) | ₩96,000 ($70.85) | ₩119,000 ($87.82) | −56.41% | No |
| Conservative | 25% | ₩221,000 ($163.10) | ₩180,000 ($132.84) | ₩209,000 ($154.24) | −23.44% | No |
| Base | 40% | ₩300,343 ($221.65) | ₩253,302 ($186.94) | ₩301,875 ($222.79) | +10.58% | No |
| Thesis / Upside | 15% | ₩418,000 ($308.49) | ₩408,000 ($301.11) | ₩494,000 ($364.58) | +80.95% | No |
| Aggressive | 5% | ₩546,000 ($402.95) | ₩569,772 ($420.50) | ₩693,750 ($511.99) | +154.12% | Yes |
| Probability-Weighted | 100% | ₩285,637 ($210.80) | ₩250,409 ($184.80) | ₩299,638 ($221.13) | +9.76% | No |
The operational environments underpinning each valuation scenario reflect different industry outcomes:
- Stress Scenario: Characterized by memory inventory accumulation, sharp contract price cuts, persistent foundry losses, and consumer device margin deficits. Target decomposition: 12-Mo: EPS ₩18,000
 7.5x; 24-Mo: EPS ₩12,000
 8.0x; 36-Mo: EPS ₩14,000
 8.5x.
- Conservative Scenario: Assumes moderate memory capex growth, flat AI infrastructure budgets, and subdued smartphone upgrade cycles. Target decomposition: 12-Mo: EPS ₩26,000
 8.5x; 24-Mo: EPS ₩20,000
 9.0x; 36-Mo: EPS ₩22,000
 9.5x.
- Base Scenario: Incorporates orderly memory normalization, 2nm GAA commercialization, and steady share count reduction. Target decomposition: 12-Mo: EPS ₩31,615
 9.5x; 24-Mo: EPS ₩24,124
 10.5x; 36-Mo: EPS ₩26,250
 11.5x.
- Thesis / Upside Scenario: Driven by an on-device AI replacement cycle, resilient server DRAM pricing, and foundry reaching operational breakeven [10]. Target decomposition: 12-Mo: EPS ₩38,000
 11.0x; 24-Mo: EPS ₩34,000
 12.0x; 36-Mo: EPS ₩38,000
 13.0x.
- Aggressive Scenario: Assumes a structural undersupply in advanced memory that keeps HBM gross margins near 80% through 2029 [8]. Target decomposition: 12-Mo: EPS ₩42,000
 13.0x; 24-Mo: EPS ₩40,698
 14.0x; 36-Mo: EPS ₩46,250
 15.0x.
The probability-weighted 36-month expected target (₩299,638) is within 13.0% of the intrinsic DCF value (₩265,093), aligning the cash flow projection with terminal multiples. While Samsung does not rely on external capital, its equity valuation is sensitive to emerging market index flows (e.g., EWY, KODEX 200) that treat the company as a liquid proxy for global semiconductor cycles [4].
6Catalyst Calendar
| Projected Date | Event Description | Scenario Validated / Broken | Expected Stock Move (%) |
|---|---|---|---|
| October 28, 2026 | Q3 2026 Final Financial Results & Investor Call [5] | Base / Bull: Validates whether DS operating profit sustains above ₩90T. |  |
| November 19, 2026 | Q3 Dividend Payout (₩370 per share) [7] | Base: Confirms regular cash return yield continuity [7]. |  |
| January 2027 | FY2027–2029 Shareholder Return Framework Announcement [9] | Bull: Potential special dividend or expanded share cancellation program [9]. |  /  |
| January 2027 | Galaxy S27 Launch (CES / Unpacked) [7] | Base: Tests whether on-device AI features support smartphone pricing [10]. |  |
| March 2027 | 58th Annual General Meeting of Shareholders [41] | Base / Governance: Reaffirms executive compensation limits and board composition [41]. |  |
| April 2027 | 12-Layer HBM4 Qualification Completion [10] | Bull: Validates next-generation memory competitiveness with AI customers [10]. |  /  |
| July 2027 | 2nm GAA Foundry Client Tape-Out Disclosures [10] | Bull: Confirms external customer commitments for leading-edge logic [21]. |  |
| October 2027 | U.S. BIS Annual VEU License Authorization [38] | Stress: Non-renewal would restrict equipment maintenance at Xian NAND fabs [38]. |  |
7Tactical Execution Layer
The tactical parameters below reflect technical market structure, options volume corridors, and fundamental valuation floors. They serve as operational positioning boundaries rather than predictive targets.
| Tactical Metric | Tactical Level (KRW) | Level (USD Equiv.) | Technical / Fundamental Rationale |
|---|---|---|---|
| Best Entry Zone | ₩205,000 – ₩220,000 | $151.30 – $162.35 | 200-day EMA support corridor; aligns with 1.3x Book Value [6]. |
| Add Zone | ₩225,000 – ₩240,000 | $166.05 – $177.10 | Prior consolidation channel following Q1 2026 earnings breakout [53]. |
| Hold Zone | ₩245,000 – ₩290,000 | $180.80 – $214.00 | Current trading channel; reflects balanced short-term risk/reward [4]. |
| Trim Zone | ₩300,000 – ₩325,000 | $221.40 – $239.85 | Reflects cyclical valuation ceiling at 11.5x FY27E EPS [7]. |
| Sell Zone | > ₩340,000 | > $250.90 | Testing all-time intraday highs (₩374,500); peak cycle valuation [4]. |
| Hard Stop-Loss | ₩185,000 | $136.50 | Breaches intermediate-term support; triggers thesis review [7]. |
| Key Support (Structural) | ₩210,000 | $155.00 | Prior resistance turned support across previous trading ranges [6]. |
| Key Resistance (Technical) | ₩315,000 / ₩374,500 | $232.50 / $276.40 | Options open interest resistance / 52-week all-time high [4]. |
| Historical Beta / Volatility | 1.25 / 24.5% Ann. | — | Correlated to the broader semiconductor index [4]. |
| Tactical Current Action | HOLD / TRIM | — | Rebalance exposure to align with the portfolio risk budget. |
| Tactical Timing Verdict | Wait for Pullback | — | Avoid chasing cyclical momentum; consider entries below ₩220,000 [6]. |
Stop-Loss Attribution: The stop-loss at ₩185,000 functions as a thesis stop. A decline through this price level suggests that memory ASP erosion has outpaced cost reductions, invalidating the Base-Case operating margin assumptions detailed in Section 5.
Closing Audit & Governance Verification
Unverified Figures & Data Gaps
- Open-Market Executive Purchases: Classified as NOT RELIABLY AVAILABLE. While the company disclosed the transfer of 1,132,477 treasury shares to 928 executives under LTI programs in July 2026, individual open-market purchases by corporate directors during the trailing 90 days are not segregated in public filings [28]. Verifying these transactions requires access to non-public regulatory filings with the Korean Financial Supervisory Service.
- 2nm Foundry Yields: Commercial yields on pilot 2nm GAA lines are estimated at 45%–55% based on industry checks [10]. Official yield figures are treated as proprietary trade secrets.
Internal Model Reconciliation
- Valuation Multiples: The trailing P/E of 12.15x reconciles with the current share price of ₩273,000 divided by trailing diluted EPS of ₩22,472.32 [19]. The Base-Case FY2026E EPS of ₩37,310 implies a forward P/E of 7.32x, normalizing to 8.64x on FY2027E EPS of ₩31,615.
- Share Count Progression: Diluted share count rolls forward from 6,566.56M in 2026 to 6,500.00M in 2027 and 6,400.00M in 2029, reflecting planned share retirements funded through operating cash flows [24].
- Balance Sheet Verification: Cash and liquid assets (₩138.52T) less gross borrowings (₩26.24T) matches the net cash figure of ₩112.28T utilized in enterprise value and DCF calculations [35].
Bias and Scenario Probability Check
- Scenario Distribution: Downside Scenarios (Stress 15% + Conservative 25% = 40%) vs. Base Scenario (40%) vs. Upside Scenarios (Thesis/Upside 15% + Aggressive 5% = 20%).
- Distribution Skew Justification: The scenario distribution is weighted toward conservative and plateau outcomes (65% combined weight for Base and Conservative). This reflects semiconductor capital cycle dynamics, where peak operating profit margins (48.8% in 2026) historically normalize toward mid-cycle averages (25%–35%) as industry supply increases [37].
Section Truncation Disclosure
No sections were truncated. All analyses required by the research mandate have been completed in full.
Final Institutional Verdict
- For Existing Holders: HOLD. Maintain positions to collect 2026 regular and special dividends, utilizing technical strength above ₩300,000 to trim exposure and align with risk budget limits [7].
- For New Capital Allocation: AVOID / HOLD. The probability-weighted 36-month return of +9.76% falls short of the institutional 100% return hurdle. Capital seeking semiconductor exposure is better allocated to TSMC for secular foundry positioning or SK Hynix for purer AI memory operating leverage [21].
Works cited
- Samsung Electronics (KRX:005930) Stock Price & Overview, https://stockanalysis.com/quote/krx/005930/
- Samsung Electronics Co., Ltd. Price: Quote, Forecast, Charts, https://www.perplexity.ai/finance/BC94.L/earnings
- Who owns Samsung? Ownership structure explained (2026), https://www.revenuememo.com/p/who-owns-samsung
- KRX:005930 - Samsung Electronics Co., Ltd. - TradingView, https://www.tradingview.com/symbols/KRX-005930/
- Samsung Stock Price Today | KS: 005930 Live - Investing.com, https://www.investing.com/equities/samsung-electronics-co-ltd
- Samsung Stock Hits 210000 Won, Leaving Early Sellers in Regret, https://en.sedaily.com/finance/2026/04/22/samsung-stock-hits-210000-won-leaving-early-sellers-in
- Samsung Electronics (KOSE:A005930) - Stock Analysis, https://simplywall.st/stocks/kr/tech/kose-a005930/samsung-electronics-shares
- Samsung Electronics: Preliminary Figures Slightly Soft; We Expect, https://global.morningstar.com/en-nd/stocks/samsung-electronics-preliminary-figures-slightly-soft-we-expect-memory-price-hikes-taper
- Samsung Pays Out 110 Trillion Won, SK Hynix Buys Back Its Own, https://financefeeds.com/samsung-pays-out-110-trillion-won/
- Samsung Electronics Announces Second Quarter 2026 Results, https://news.samsung.com/global/samsung-electronics-announces-second-quarter-2026-results
- First in South Korean corporate history... Samsung Electronics, https://www.mk.co.kr/en/business/11939932
- Samsung Stock - Companies History, https://www.companieshistory.com/company/samsung/stock/
- Micron Initiation Report 2026-03-19 | PDF - Scribd, https://www.scribd.com/document/1030839413/Micron-Initiation-Report-2026-03-19
- Samsung's Q2 2026 profit surges 1,299.9% to a record high | KuCoin, https://www.kucoin.com/news/flash/samsung-q2-2026-profit-surges-1299-9-to-record-high
- Who Owns Samsung? Parent Company & Group Structure, https://thebrandhopper.com/brand/who-owns-samsung-parent-company-group-structure/
- Quote, Forecast, Charts & News (005930.KS) - Perplexity, https://www.perplexity.ai/finance/005930.KS?comparing=005930.KS,6752.T,TXN,GRMN,7951.T,7751.T
- Samsung's chip chief pledges HBM3e leadership in AI processor, https://www.koreatimes.co.kr/business/companies/20250319/samsungs-chip-chief-pledges-hbm3e-leadership-in-ai-processor-market
- Samsung Electronics, https://securities.miraeasset.com/bbs/download/2137954.pdf?attachmentId=2138710
- XKRX:005930 PE Ratio (TTM): 12.30 — Near Median - GuruFocus, https://www.gurufocus.com/term/pettm/XKRX:005930
- TSM (Taiwan Semiconductor Manufacturing Co) Forward PE Ratio, https://www.gurufocus.com/term/forward-pe-ratio/TSM
- Taiwan Semiconductor Manufacturing Company (TSM) Statistics, https://stockanalysis.com/stocks/tsm/statistics/
- TSMC stock analysis: fundamentals, valuation, and key risks, https://www.investing.com/news/stock-market-news/tsmc-stock-analysis-fundamentals-valuation-and-key-risks-93CH-4913682
- SK Hynix Nasdaq Listing: SKHY AI Stock Explained - INDmoney, https://www.indmoney.com/blog/us-stocks/sk-hynix-nasdaq-listing-skhy-ai-stock-explained
- Listing Information Stock Information Investor Relations Samsung, https://www.samsung.com/global/ir/stock-information/listing-Info/
- Samsung and SK will retire over USD 14 billion in treasury shares, https://news.futunn.com/en/post/69865534/samsung-and-sk-will-retire-over-usd-14-billion-in
- Samsung Electronics to cancel $9.5 bil. worth of treasury stocks, https://www.koreatimes.co.kr/business/companies/20260331/samsung-electronics-to-cancel-95-bil-worth-of-treasury-stocks
- Which Company Owns Samsung? | The Motley Fool, https://www.fool.com/investing/how-to-invest/stocks/who-owns-samsung/
- Samsung Executives Receive Major Stock Grants Under LTI Plan, https://finance.biggo.com/news/bd34edd9-a94e-4c45-95c7-19f01b170916
- Samsung Electronics grants treasury shares to executives, https://www.investing.com/news/company-news/samsung-electronics-grants-treasury-shares-to-executives-93CH-4787586
- Samsung Electronics (KRX:005930) Statistics & Valuation Metrics, https://stockanalysis.com/quote/krx/005930/statistics/
- Nvidia stock buyback — Record-Breaking $150 Billion Plan Revealed, https://en.koreadaily.com/nvidia-stock-buyback-plan/
- SAMSUNG ELECTRONICS CO., LTD. AND ITS SUBSIDIARIES, https://images.samsung.com/is/content/samsung/assets/global/ir/docs/2025_con_quarter04_all.pdf
- Samsung's ₩110 Trillion Shareholder Return Falls Flat as Shares, https://finance.biggo.com/news/2ba0aad1-d0e4-4aa1-91c7-f565594d9fd3
- CONSOLIDATED STATEMENTS OF CASH FLOWS - Samsung, https://images.samsung.com/is/content/samsung/assets/global/ir/docs/2025_con_quarter04_cf.pdf
- Consolidated Financial Statements of Samsung Electronics Co., Ltd, https://www.studocu.vn/vn/document/university-of-economics-hcmc-international-school-of-business/khoa-hoc-du-lieu/consolidated-financial-statements-of-samsung-electronics-co-ltd-for-2025/164055155
- Independent Accountants' Review Report - Samsung, https://images.samsung.com/is/content/samsung/assets/global/ir/docs/2026_con_quarter01_bs.pdf
- Samsung Electronics Co Ltd (005930) Stock Price & News - Google, https://www.google.com/finance/quote/005930:KRX
- 2025 Business Report | Samsung Electronics Co., Ltd., https://images.samsung.com/is/content/samsung/assets/global/ir/docs/2025_4Q_Interim_Report.pdf
- 2024 Interim Business Report - Samsung, https://images.samsung.com/is/content/samsung/assets/global/ir/docs/2024_3Q_Interim_Report.pdf
- Samsung (005930.KS) - Stock price history - Companies Market Cap, https://companiesmarketcap.com/samsung/stock-price-history/
- Samsung Annual Report 2025 Overview | PDF | Dividend - Scribd, https://www.scribd.com/document/891858578/2025-SEC-AGMReferenceMaterial-VF
- Samsung Electronics Co., Ltd. Price: Quote, Forecast, Charts, https://www.perplexity.ai/finance/005930.KS?comparing=005930.KS,HPQ,WDC,META,SMCI,1810.HK
- Samsung Electronics Posts $58.9 Billion Operating Profit, https://finance.biggo.com/news/ffece794-0f96-4bfd-9bd0-9041ba5fa1c6
- Samsung Posts Record Q2 Semiconductor Operating Profit of Over, https://news.sbs.co.kr/english/article.do?news_id=N1008681952
- 2025 Interim Business Report - Samsung, https://images.samsung.com/is/content/samsung/assets/global/ir/docs/2025_1Q_Interim_Report.pdf
- Samsung Electronics expects shareholder returns up to US$80, https://guelph.ctvnews.ca/business/article/samsung-electronics-expects-shareholder-returns-up-to-us80-billion-this-year/
- Taiwan Semiconductor Manufacturing/$TSM - Lightyear, https://lightyear.com/en/stock/TSM:NYSE
- Samsung Electronics Co., Ltd. Price: Quote, Forecast, Charts, https://www.perplexity.ai/finance/005930.KS/earnings
- Strategic and Financial Blueprint of Micron Technology: Resolving, https://simplywall.st/community/narratives/us/semiconductors/nasdaq-mu/micron-technology/l22rum9f-strategic-and-financial-blueprint-of-micron-technology-resolving-the-memory-wall-in-the-gen-ai-era
- Micron Earnings Power Still Looks Undervalued at 10.7x Forward PE, https://www.investing.com/analysis/micron-earnings-power-still-looks-undervalued-at-107x-forward-pe-200676559
- Samsung Electronics Announces Results for Third Quarter of 2024, https://www.techpowerup.com/328308/samsung-electronics-announces-results-for-third-quarter-of-2024-7-percent-revenue-increase
- Samsung: Empowering Athletes with Mobile Innovations, https://www.investing.com/academy/statistics/samsung-facts/
- Samsung vs. SK Hynix: A Widening Gap of 99% vs. 88% Gains, https://finance.biggo.com/news/zLHx6p0BtCxy99G5iTT9
- Shareholder Return Stock Information Investor Relations ... - Samsung, https://www.samsung.com/global/ir/stock-information/shareholder-return/
- 2026 Interim Business Report - Samsung, https://images.samsung.com/is/content/samsung/assets/global/ir/docs/2026_1Q_Interim_Report.pdf
- South Korean authorities raid Samsung headquarters over insider, https://www.aa.com.tr/en/asia-pacific/south-korean-authorities-raid-samsung-headquarters-over-insider-trading-report/3964183
- Prosecutors Raid Samsung Electronics Over Insider Trading, https://www.chosun.com/english/national-en/2026/06/11/6KHVYKDVAVBZ5GVYWYW67YVRHE/
- Independent Accountants' Review Report - Samsung, https://images.samsung.com/is/content/samsung/assets/global/ir/docs/2026_con_quarter01_all.pdf
- unknown_url
- Taiwan Semiconductor Manufacturing Company Ltd. (TWSE: 2330), https://gomarketcap.com/companies/TWSE-2330/taiwan-semiconductor-manufacturing-company-ltd
- TSM Stock Quote | Volume Chart (Taiwan Semiconductor...), https://marketchameleon.com/Overview/TSM
- Taiwan Semiconductor Manufacturing Company Limited (TSM, https://flash.stocksentinel.ai/stock/TSM/key-metrics
- Netlist v. Samsung Electronics | Patent Lawsuit 24-1521 - Patsnap, https://www.patsnap.com/resources/blog/litigation/netlist-v-samsung-micron-us10860506b2-patent-appeal-patsnap/
- Netlist, Inc. v. Samsung Electronics Co., Ltd. et al, 2:2025cv00748, https://law.justia.com/cases/federal/district-courts/texas/txedce/2:2025cv00748/239421/105/
- Financial Elites From Elite University Club Suspected of Running, https://en.sedaily.com/finance/2026/09/29/financial-elites-from-elite-university-club-ran-insider
- Corporate Governance Report FY2025 - Samsung, https://images.samsung.com/is/content/samsung/assets/global/ir/docs/Corprate_Governance_Report_FY2025.pdf
- Samsung Electronics to grant shares to 49345 employees, https://www.investing.com/news/company-news/samsung-electronics-to-grant-shares-to-49345-employees-93CH-4778400